Small Cap Value Report (Mon 16 Sept 2024) - SNX, TTG, ADF

Good morning from Paul & Graham!
I had an interesting email from Paul Hill over the weekend, making some really interesting points about if/when/why various valuation measures should or can be used (eg price to sale, EV/EBITDA). I'm thinking this is an interesting topic that would make a good discussion, so I'll ask him if he wants to do a podcast on it.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
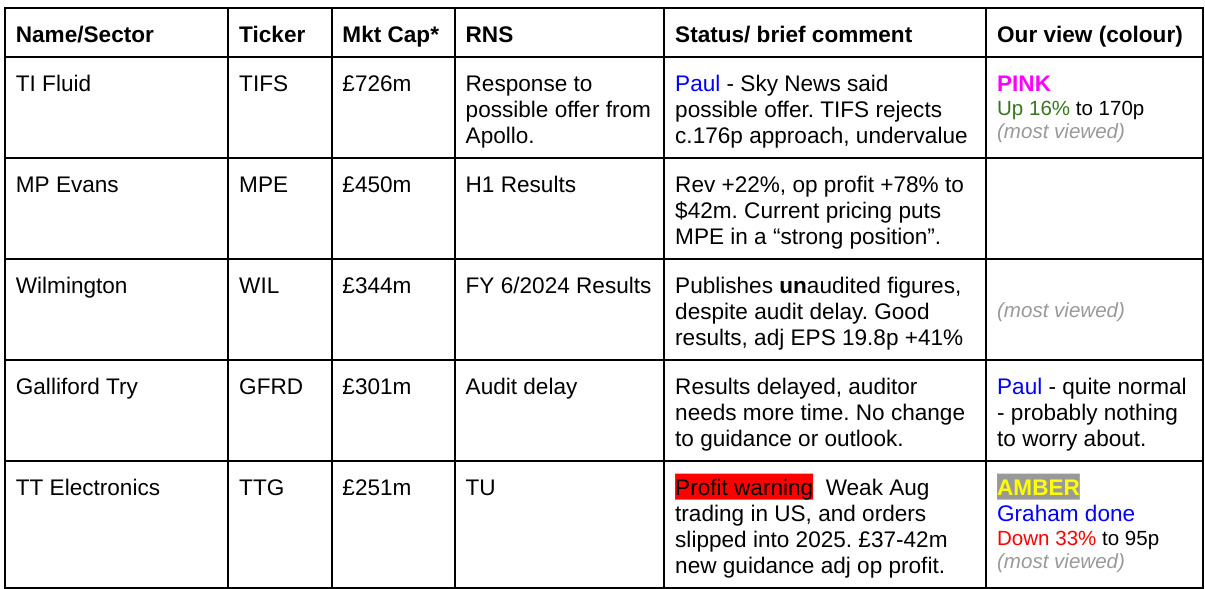
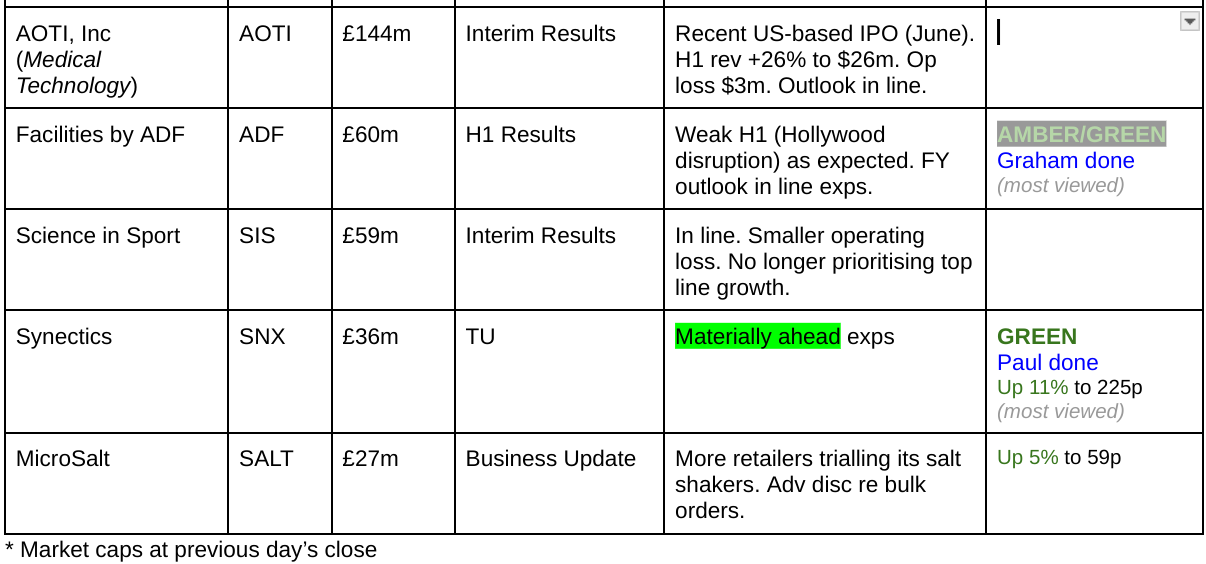
Synectics (LON:SNX) - up 11% to 225p (£40m) - Trading Update [ahead exps] - Paul - GREEN
An ahead of expectations update drives a useful broker upgrade. Taking into account that 20% of its market cap is supported by net cash, and good performance & outlook, I think this share remains cheap. However, it relies on large & lumpy orders, so future performance can't be guaranteed. If it meets ambitious forecasts, then I could see this share continuing to rise, c.300p looks doable providing the news remains positive.
TT electronics (LON:TTG) - down 36% to 91.4p (£162m) - Trading Update - Graham - AMBER
An awful profit warning from this component manufacturer which seems to be the company’s own fault, as it suffers from operational issues in North America. I’ve been positive on this one as it has deleveraged in recent years, but today’s update has severely affected my trust in the story and so I’m switching to a neutral stance. Perhaps I can turn GREEN again in the future, if they can fix these problems.
Facilities by ADF (LON:ADF) - down 2.5% to 53.9p (£58m) - Half year results - Graham - AMBER/GREEN
The outlook from this provider of film/TV production facilities is in line with expectations. The H1 results in isolation are poor but they do reflect an industry affected by highly unusual strike activity and the company is now enjoying positive momentum as it integrates a significant acquisition announced last month.
Paul’s Section:
Synectics (LON:SNX)
Up 11% to 225p (£40m) - Trading Update [ahead exps] - Paul - GREEN
I should start by saying how sorry I was to hear of the recent sudden death of CEO Paul Webb. Our condolences to his family, friends, and colleagues.
“Synectics plc (AIM: SNX), a leader in advanced security and surveillance systems, provides an update on trading for the year ending 30 November 2024 ("FY 2024"), following the conclusion of its third quarter, ended 31 August 2024.”
Trading is going well -
“Continued positive trading in the third quarter - FY 2024 now expected to be materially ahead of market expectations”
“*Prior to this announcement, FY 2024 market expectations were revenue of £52.9m and adjusted PBT of £3.5m”
Materially ahead usually means at least 10% above (profit). Shore Capital helpfully updates us, raising adj PBT estimate from £3.5m to £3.9m. This is 18.6p adj EPS (previously 16.8p). I’m not sure that justifies an 11% increase in the value of the company. On the new forecast, the PER is 12.1x, which looks about right to me for this type of business.
Note that Shore is pencilling in quite large further increases in EPS to 23.9p and 29.0p in FY 11/2025 & 26 respectively. If it achieves those (and Shore points out SNX has established a track record of meeting/beating expectations recently) then I suspect a share price nearer 300p would be likely - quite good upside. Although you never really know, as it all depends on what contracts it is able to win, and on what terms - which depends on a wide range of factors that as investors we cannot predict.
Outlook -
“Continued momentum across its key markets”
Good order intake -
“Order intake remains strong and recent contract wins have included a $1.2m contract for the installation of a new security and surveillance system at a casino resort in the Philippines, further contract wins with Saudi Aramco, and a strategically important order for the Company's first installation, of a new security and surveillance system for a casino resort, in Cambodia.”
“The Company continues to focus on further strengthening its already healthy FY 2025 order book.”
Paul’s opinion - I see Graham reviewed its 11/2023 results back in February, concluding he liked it, so GREEN, at 187p/share. We’re now higher at 225p/share, and I think it still looks good value, due to the forecasts having risen, and trading/outlook comments today being good.
So I’ll stick with GREEN. There’s always the risk that a gap could appear in the order book, so you can never really sleep soundly with this type of company (with mostly non-recurring revenues). Hence why investors don’t tend to be prepared to pay a high rating (rightly so).
It pays smallish divis, and has a nice solid debt-free balance sheet that included £6.4m net cash at 31/5/2024, c.20% of the market cap.
All looks good to me, GREEN it is!
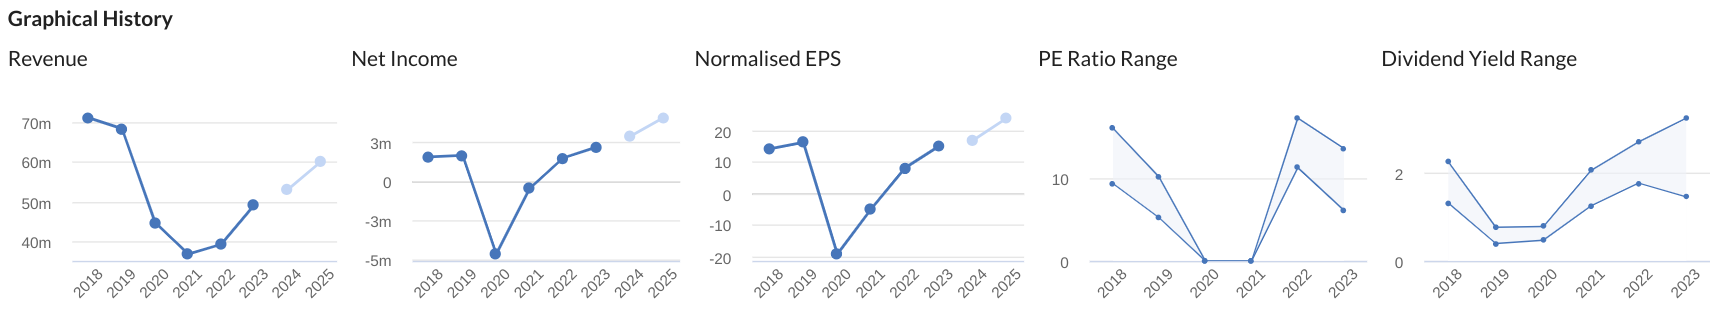
It's quite surprising how much this share has gone up recently. Just shows that there are plenty of decent companies on the UK market at attractive prices, despite all the doom & gloom.It's established a nice recovery in EPS since the pandemic -
TT electronics (LON:TTG)
Down 36% to 91.4p (£162m) - Trading Update - Graham - AMBER
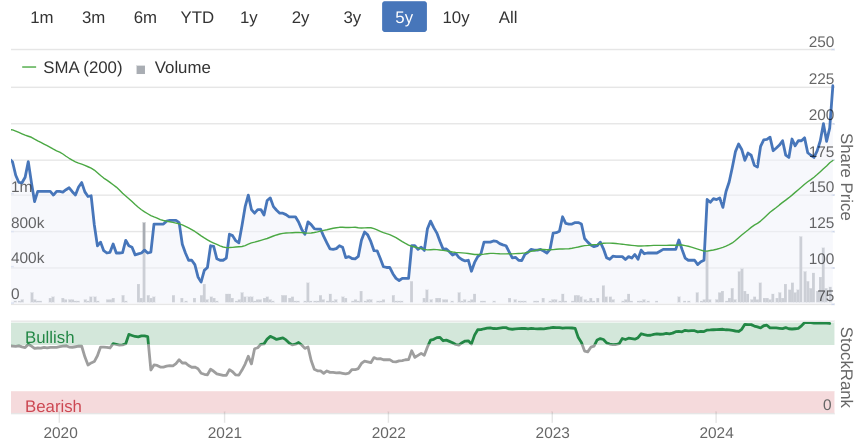
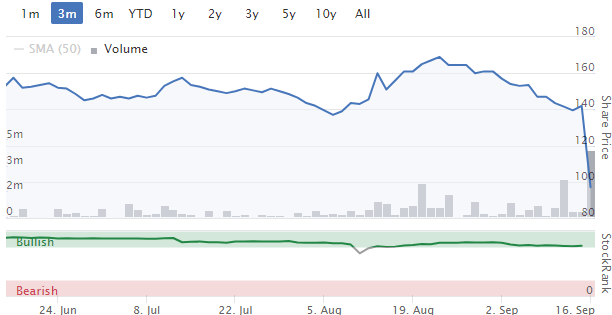
This is a horrible trading update from a company I’ve been “GREEN” on, and the share price has crashed this morning on heavy volumes:
Here is the bad news:
August trading results are weak due to “operational efficiency issues in two North American sites”. These issues are causing both delays and higher production costs. Plans are in place to rectify the issues “during the remainder of the year and potentially into Q1 2025”. It seems that the issues are entirely the company’s own fault and flow from problems to do with “factory planning and factory layout”.
Aside from the financial impact, this really makes me question management and if the right people are in charge.
Additionally, recent order intake in the higher-margin North American components business has been for delivery in 2025, not 2024 as expected. Perhaps it’s to be expected that customers would not want to send in more orders for short-term delivery, if the company is struggling to execute current orders?
The result is that TTG’s H2 revenue will be c. £15-20m lower than expected, and operating profit will be lower by £13-18m.
The rest of the group is trading “broadly in line” but we still have a big hit to group profitability; full-year operating profit will now be £37-42m (last year: £53m, previous year: £47m).
Leverage is now expected to finish 2024 “around or marginally above” the target range of 1-2x.
(Context: leverage had fallen from 2x (at the end of 2022) to 1.7x (at the end of 2023), so this is a step backwards).
Medium-term targets are unchanged, including a 12% operating margin in 2026, but it’s understandably difficult for investors to look past the poor performance in the current year.
Graham’s view
With a hit to profitability of up to 35%, it makes sense that the share price would fall by this amount or more, especially considering that there are balance sheet implications.
A leverage multiple of 2x is not where the company ought to be; it has worked very hard to reduce leverage and this backward step is a big blow to the investment thesis.
I wouldn’t question the company’s solvency at this degree of leverage, but the big attraction for me has been the deleveraging story and so it’s very frustrating to see it going in the wrong direction..
I’m therefore inclined to switch to a neutral stance on this share. This may be a poorly-timed change of stance. But when I’ve been wrong, sometimes it’s best to take the hint that the market is giving me!
For what it’s worth, here are the multiples/ratios the company was trading at as of last night:
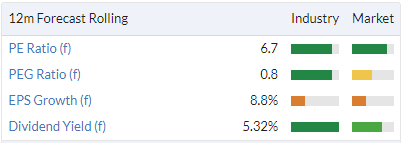
I thought this cheap valuation should have been sufficient to price in some bad news, but a surprise 35% hit to profitability is beyond what I thought was possible.
Could this be the low? Perhaps. Leverage (i.e. net debt divided by adj. EBITDA) is returning to the top end of the range but I think this is almost entirely because of lower EBITDA/profitability, not because of an adverse movement in net debt. And as the issues that are causing lower profitability get resolved, the leverage multiple and the valuation of TTG should hopefully recover.
However, I can’t confidently build an investment thesis here, after the company has disappointed me like this. I no longer trust it, so I can’t stay GREEN. I’m going back to a neutral stance.
Facilities by ADF (LON:ADF)
Down 2.5% to 53.9p (£58m) - Half year results - Graham - AMBER/GREEN
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV") announces its unaudited half year results for the six months ended 30 June 2024 (H1-FY24).
These results suffered from the knock-on effects of the Hollywood strikes. It posts a large drop in year-on-year revenues and a loss, but maintains its dividend:
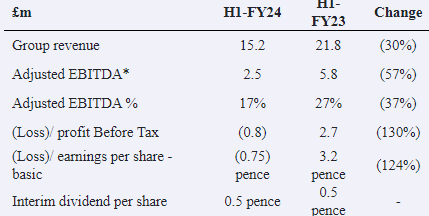
The performance is described as “resilient” and as an improvement from H2 2023 (but not from H1).
ADF supported “38 high-profile productions” during the period. Checking last year’s interim report, I see that they supported 46 then.
Last month (only a few weeks ago really), ADF announced the £21m acquisition of Autotrak that was covered by Paul in superb detail here. Paul had a positive view of that deal.
Outlook statement: in line with market expectations. H1 “finished strongly” with the order book for H2 “building well across the summer months as momentum returns across the market following the Strikes”.
CEO comment:
"We are proud of the performance delivered in H1-FY24, demonstrating the Group's resilience and leading market position as the Film and HETV [high-end television] industry continues to recover from the impact of last year's strike disruptions. With the market normalising, we continue to be well-positioned to achieve our goal of becoming a One-Stop-Shop…
"As we continue to invest in our fleet and explore further acquisition opportunities, alongside the increased investment anticipated across the industry in the UK in the coming years, we remain confident in achieving our aim of generating £100m revenue in the medium-term."
Dividend: it’s a little cheeky of the company to say that their unchanged dividend of 0.5p “is reflective of the Group's progressive dividend policy”.
The share count has gone up after the recent fundraising, and the unchanged interim dividend (per share) will therefore cost the company more in total than it did last year.
But in my book, a dividend is defined in terms of its per-share payment, not in terms of its total cost to the company. So I see this as a dividend that is currently flat, not one that is progressively increasing!
However, I acknowledge that the company must have quite a lot of confidence if it is willing to make this payment, given the loss-making circumstances it finds itself in.
Net debt excluding leases was £13m at the end of June. The Autotrak acquisition was funded by a £10m placing for the upfront £10m cost, with the rest of the cost spread out in future periods.
Graham’s view
We have interim results that are as expected, an in-line trading update, and a confident outlook statement. So I am happy to leave Paul’s AMBER/GREEN on this unchanged.
That said, I think reporting here could be more straightforward - why does the company bother giving us adj. EBITDA when depreciation is one of the most important charges, and is clearly a real cost to the business?
The depreciation charge was £2.6m in H1, similar to previous periods, and should not be ignored.
I tend to agree that the Hollywood strikes were very rare events that should not repeat for many years, so that ADF should be in the clear for the foreseeable future.
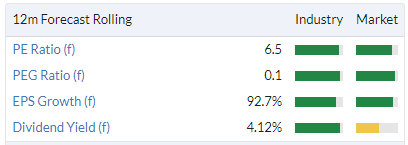
Rightly or wrongly, the market doesn’t seem to be pricing in too much success:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Harworth (LON:HWG)
Up 7.25% on very high volume at 192p, other than the recent results that were from my perspective very positive I am unaware of any reason for the price movement, which is a post-covid high.
The company is in my view an enticing bid target given where we are in the cycle, heading up insofar as property/real estate is concerned as interest rates fall, but I suspect the share price movement is just the usual gyrations of the market.
It has been held in 2 family ISAs well before covid and added to in the interim.
fste 250 entry soon 80% shareholding across 10 holders big 2 hold 52%
Investors Chronicle reiterates its BUY rating for buildtech software developer Eleco (LON:ELCO) .
Disclosure: I've owned shares in #ELCO for almost 10 years.
https://www.investorschronicle...
One thing I noted when looking at Wilmington (LON:WIL) earlier is that it has a main market listing and market cap of £340m, but for some reason is not included in the FTSE Small Cap index. Anyone know why that is?
TI Fluid Systems (LON:TIFS)
Are they a genuine target for Apollo or just victims of another of their opportunistic offers? If I recall correctly Apollo walked away from two separate businesses they had tabled offers for last year. One was John Wood (LON:WG.) and I was a holder. Then Sidara did the same there so maybe not unreasonable. Don't remember who the other outfit was but makes me question whether Apollo are signalling value or really interested in buying and building. I suspect the former.
MPE Thought I'd give it a little mention since no-one else has. I hold, but I'm down 8% on it so far. I bought when palm oil was high, so not one of my more masterful investments.
What's interesting is that EPS has been growing by about 24% pa (using a bizarre formula I cooked up based on Ben Graham's formulation in Intelligent Investor). That's more than a little impressive. Mind you, palm oil prices have doubled in the last 10 years, which most certainly helps.
Could prices revert? Sure. But consider this. Eyeballing the chart, prices were around $300 per metric ton in 1990-94, $400 in 1994-2007, $600 in 2015-2021 and $1000 from 2022. https://fred.stlouisfed.org/se...
You could argue that inflation (and let's be honest, there's been a lot of that) is unlikely to see prices drop to those $600 levels, at least over the long term. So for your money you get a company on a PE of 10 (EV/EBITDA of 6.2), very comfortable debt levels and a management that is steadily investing in the business.
Commodity prices are going to play an important factor.
It's hardly the most exciting business in the world, but management seems competent enough and try to do the right thing.
Morning (just).
Cavendish Financial (LON:CAV) dished out an AGM statement at 9:09am this morning, 51 minutes in advance of their AGM starting. Ample time to digest it, I'm sure we all agree.
Although it didn't really say anything, except maybe preparing the ground for a profit warning by saying nothing's changed since the general election. This is both deeply unhelpful in judging the current year's financial performance against expectations, and also doesn't really explain the current 10% discount. But then the market is quite illogical at the best of times.
Anyway, I am a holder and will continue to hold. Unless the UK market just slowly dies, the listings market will eventually come back and Cavendish will make a load of money (and a small fraction of that will come back to shareholders ;p ).
Cheers
Chris
Chris hi. Cavendish Financial (LON:CAV)
i noticed this drop as it was on my watchlist and i got a notification... it goes EX Div in a few days tooo..
Can anyone answer a question... Why does it not appear in the list of "Decliners" on the "Today" page at 8% in should be second in the list... any wisdom or do i green button it...
Cavendish Financial (LON:CAV) Is in my top 5 holdings, been a bit of a damp squib since the merger though.
So much potential but there doesn't seem to be any ooomph in the business, or communication with retail, which is a shame really as assessing and communicating with the market what they are supposed to be good at....
Top Risers/Decliners are main market. Cavendish Financial (LON:CAV) is AIM
TY. P-O-T
If you click on the FTSE AIM allshare box it shows advancers and decliners for that market
Something else new learned today, thanks.
thank you, didn't know!
Don't think they can do a profit warning as they don't have any forecasts...
I actually read it more.poaitively re the IPOs in the pipeline but I think some investors are getting impatient.
Not a small-cap, but Phoenix group (LON:PHNX) reported their HY24 results this morning. Late for the sector - they're the last of the large insurers (life or otherwise) to report HY IFRS 17 numbers. And this is partly explained by them subtly disclosing that they got their FY2023 IFRS numbers wrong - the first year of implementation of IFRS 17, and they (a) had to suddenly delay their results, and (b) now fess up 6 months later to having got them wrong after all that. (albeit they got them wrong in the "right" way - they've increased their equity by £0.2bn).
Outside of that, I'm not thrilled with the results. I'l doubtless find the good points (which I think will centre around new business inflows, OCG and dividends) once I've had my morning coffee... but the negatives I saw were:
- low SII ratio compared to peers - they must be the lowest in the sector
- massive disconnect between SII basis and IFRS basis - again, way larger than other peers
- size of IFRS loss is excessive compared to the move in interest rates in the year - I know they hedge to SII rather than to IFRS but I suspect there's something else going on there beneath the surface
- Discontinuation of the Sun Life sale process sounds like they can't get a buyer at the price they want. Which implies they value it higher than anyone else does - doesn't sound great if you read that through to their assumptions and judgements, implies that they are likely not conservative.
FWIW, I still hold, as the dividend is just too good to pass up... but need to dig into figures more to understand perhaps a more balanced and nuanced view of things...
The trouble with insurers is being able to get your head round their accounts - and I reckon £PHNX is the most complicated set of figures out there, having taken over the old business from Standard Life / Aberdeen a few years ago - It was trading north of 700p a few years ago - yes its a big fat divi but not for me.
Good morning all, has anyone got any views about Harworth (LON:HWG)?
I would value all your opinions.
Nice chart.
Harworth
Great land bank .
Lots of wind farm / solar potential
Harworth (LON:HWG) - serviced residential and commercial plots, ready to build : just what the government need to get homes built and businesses to expand, with rental and generation royalty income balancing capital and income. Management come across well with clear goals. Back at pandemic highs.
Watched presentation last week by CEO & FD. Most impressive ladies.
Have held share for some time, been depressed by rising interest rates.
Company USP is purchasing land and obtaining planning permission. Highly successful.
They sell off residential land and retain some of commercial land and are building a Grade A landbank.
Have very low LTV
They are currently building out a large site, which they sold to HA last year and as a result have increased their building team as well as building a factory on a site they sold to Microsoft.
As they build up their rental income they intend to increase their dividend.
Both CEO and FD bought additional shares on open market last week. That announcement helped sentiment on shares to day. It is shortly to move to FTSE250.
Most impressive outfit DYOR.
fste 250 bound safe boring company?
TT electronics (LON:TTG)
i had this on my watch list (lucky for me it was only on watch list) - todays update is a complete stinker bearing in mind the prior update just over 5 weeks ago. Have things deteriorated that badly in 5 weeks ? seems ridiculously implausible , so thats an F from me for management and their ability to tell it like it is. Is the drop this morning an over reaction? i know not - they have advised debt might now be above the top of their target range and that was one of the risks here that the debt is chunky. I kinda feel like anyone who has invested here since the trading date has been seriously let down here by management.
TT electronics (LON:TTG)
I had this on my watch list (lucky for me it was only on watch list) - todays update is a complete stinker bearing in mind the prior update just over 5 weeks ago.
I’m a victim of this disingenuous messaging and have sold at open. It’s a golden rule that I won’t stay with companies that can’t forecast more than a fortnight in advance. TTD was one of a basket of cyclicals that I bought in Dec 23/Jan 24, most of which have done well, especially in the building materials sector. But I’ve dialled down the cyclical exposure recently and now only hold Robert Walters (LON:RWA) Luceco (LON:LUCE) RS (LON:RS1) Brickability (LON:BRCK) and Alumasc (LON:ALU) in the most cyclically exposed category. There are plenty of other industrials in my fund, including other recruiter SThree (LON:STEM, but their peak to trough earnings spread is much lower.
TTG "advised debt might now be above the top of their target range"
Ouch. Debt already looked fairly high relative to net profits, and it has an interest cover of 0.29. Yikes. Mean 5-year ROCS is 2.5% and the best it every managed since 2018 is 4.4%. It's a very weak business.
I don't know how long the directors have been at the helm, but if it's been a long time, then they need to get booted.
TT electronics (LON:TTG)
I don't know how long the directors have been at the helm, but if it's been a long time, then they need to get booted.
Its tricky one - someone has pointed out on the other place that the CEO was only appointed last July (and that they came witha good reputation )i havent fact checked that statement but they seem to have a pretty decent list of places they worked at previously.
So is 12 months short enough that they can be blaming prior incumbents ? - perhaps i will be generous and say the company may have perhaps had weaknesses that are not easy for one person at the top to fix. IMHO the financial projections and news that comes from the board is one where the whole team needs to take responsibility - i see little excuse after 12 months as to ehy they would be caught with their pants down. Perhaps the new guy has had enough and its throwing the FD under the bus if its more than they can deal with - either way the facts its such a sudden jump to debt targets being exceeeded it reflects poorly on management - is this kitchen sinking by the new guy so later news is better - i know not.
I dont know the company well enough to add much useful -they historical numbers looked poor and i am new to the company the only thing that really looked decent was tehn future and thats not so bright now.
TTG According to bulletin boards posters elsewhere, it seems to be a product issue and are still trying to find out the underlying cause, possibly. Hmm. Make of that what you will.
What we can say for sure is that the charts over 5-, 10- and 20- years are down. Not good.
I pulled up Stockopedia's report from 21.10.17 out of curiosity (please, never ditch that facility!) and saw that their average ROE over the preceding 5 years was also pretty weak, at 4.1%. Operating cashflows had also declined.
Stocko's report on 30.9.13 painted a similar picture.
With such weak returns on equity it's not surprising that the share price has shown such poor performance. I notice that they've have different directors on each report. It seems that the new guy has quite the challenge ahead of him.Agreed rmillaree. I don't like to blame management too hastily but in this case it seems that change is needed. How could they get their N American operations and forecasts so badly wrong? It doesn't add up. Somebody has messed up. G
US corporation tax: Paul you mentioned on your podcast that Kamala Harris is proposing to increase the top rate of corporation tax in the US by 7 percentage points.
Does anyone have an educated guess at what the effect might be on UK based companies trading in the US? I am wondering if it partly explains the recent price weakness at IG Design (LON:IGR) for example - which is probably also down on worries about the US economy. I tried to google an answer but it's not quick and easy to work out so wondering if any experts here have an understanding!
Re:IG Design (LON:IGR) - investors spooked by possible withdrawal of IHT relief in the budget? Company has been silent on ballooning freight costs, so assume no major impact from that. £ strong too at the moment.
Seldom can there have been such a divergence between price action and the Stocko rating.
Lookkng forward to seeing your take on Synectics (LON:SNX) this morning Paul, I'm pleased to see Stocko's risk rating fall from highly speculative to merely speculative and I have increased my trailing stop loss by 20 pence accordingly both with this and today's rise in share price. SNX is also dividend-paying so I'm happy to hold shres in the company.
RE: VERTU - EV sales in UK
Some comment in the weekend press. Robert Forrester Vertu's CE has reportedly written to Jonathan Reynolds the Business Secretary saying that customers are being "coerced" into going electric.
He reportedly adds..
"The targets in the United Kingdom are far more aggressive than any other western country. Frankly, the industry cant get there without significant collateral damage"
Stellantis (Vauxhall) are also reported as saying that they are being forced to slash EV prices to unsustainable levels to sell enough EVs to comply
Plexus Holdings (LON:POS) is this one of those sale bargains all the volatility is throwing up.
Looking at the major shareholders no sells all buys, however as I have more shares than the bottom 4 shareholders, not sure how valid this screen is currently.
Falling knife or bargain?, time to deploy the fun money maybe.
Hi GloucesterBob, what are your thoughts this could be because of new govt anticipated changes in energy mix? Eg the same way that Enquest (LON:ENQ) has sold down a lot since the change in party?
Hi ttt,
First off Plexus Holdings (LON:POS) is not a high conviction holding for me, I am in my second session of holding it, having watched from the sidelines when Paul first mentioned it, saw it go to around 28p, watched it drop to around 11p before I jumped in. Sold out around 18p and then watched it all the way down to sub 11p today.
All this drop on barely any news. I think the Gov't energy policy though mad (IMHO) may actually help Plexus Holdings (LON:POS) if I understand the business. If the Gov't is keen on shutting down the North Sea, then I assume, there are a few well-heads that will need capping off, so there may be a short but fruitful future here in the North Sea, along with their other world wide business.
The problem with Plexus Holdings (LON:POS) [I hold] is that it hasn't told the market anything in 6 months! That's a ludicrous length of time without any trading updates, so we have no idea what's going on. I've lodged complaints about this, as it's just not right for a public company to go totally silent for 6 months! The rules are that they have to inform the market immediately if they're going to miss forecasts, so hopefully nothing untoward. Small shareholders naturally drift away in the absence of news, which becomes self-reinforcing as the price keeps falling. There has been a changeover of management, with internal promotions over the summer.
I remain of the view that POS has proven tech (it was a growth company, and profitable, with a market cap that peaked c.£300m up to its market almost closing down in 2015). Biggest ever contract won in 2023, which is what got me interested, and one-off sale of surplus IP at end 2023 gave it a one-off year of bumper profitability for FY 6/2024 (numbers not yet published). That also resolved cash position for now.
The missing bit is - everything else! How is it trading now, what is the outlook like? Historically POS has done well with only 2-3 large deals each year, because it's specialist engineering. It has large opportunities, as the £8m rental deal in the last year showed, but it needs to win more business, not just the occasional one-off deal. If that happens, then we're onto a serious multibagger, last year gave a glimpse of that.
Regards, Paul.
Looks more like a normal micro/smallcap that's sold off because it's in between trading updates and has typical smallcap lower volume and some folk as usual selling small amounts knocking the slowly price down to buy something with positive momentum, perhaps hitting a stop loss or 2 on the way to me.And without the arbitrageurs of larger caps to support the price.It's been selling off for a while bar a brief 'spike' or 2.Market needs an update imo.
Only a break above 15 would I consider imho.
Don't quite understand why Paul's list and Mr Contrarian's have omitted Wilmington (LON:WIL) this morning? On a day of few results this is probably the highest quality small cap that is reporting. I sold a short while back after the sale of the UK healthcare business on poor terms (low price and most of the proceeds deferred by four years!) However, today's results are strong and I would welcome some further analysis.
Don't quite understand why Paul's list and Mr Contrarian's have omitted Wilmington (LON:WIL) this morning?
Refresh your page!!! ;-)
Ahh! Thank you
Don't quite understand why Paul's list and Mr Contrarian's have omitted Wilmington (LON:WIL) this morning? On a day of few results this is probably the highest quality small cap that is reporting. I sold a short while back after the sale of the UK healthcare business on poor terms (low price and most of the proceeds deferred by four years!) However, today's results are strong and I would welcome some further analysis.
I think Paul would do well to drink several cups of strong coffee before looking at Wilmington (LON:WIL) FY results. So many moving parts it has just made my head hurt! Overall looks ok but in terms of outlook we are only left with:
"We have had a good start to the current financial year, with revenues and profits in line with expectations."
So not much reason to get too excited.
All the best, Si
Does anyone know what % of revenues the gambling sector represents for Synectics (LON:SNX)? I’ve tried to find the answer but not sure it’s disclosed.
Recent contract wins seem pretty heavy in this area and it’s beginning to feel like a bit of a sin stock via the back door.
Recently been furious (and powerless to stop) seeing my 18 year old get seduced by the advertising and lure of free bet offers from the gambling companies. I hate this sector, really do.
Hello M48,
I read a report a few months back that stated Gaming was 20% of sales.
The remainder was made up from Oil & Gas 26%, Vehicle 14%, Security 23% and Public Space, Transport & Infrastructure 17%.
Not sure if the recent win, or upgraded guidance will distort any of those figures.
Hope that helps you.
Also, if you want to get back at the gambling companies for their introductory offers have a look at Team Profit. Nice little way of getting money from them. Waring, they will ban you after a while of doing this !!
Thank you, that’s helpful. Suspect the 20% will be growing somewhat. Not one for me then!
dont kid yourself the stock market is a form of gambling
Fair challenge. I agree it can be in some situations. But think I’ll park that discussion or it risks going down a rabbit hole like some other topics do on here occasionally.
It pays to be patient with UK equities
Everyone knows the UK equity market is cheap and unloved, but is anyone buying it yet?
Most institutional investors have been selling down over the past decade or more and now the UK is a mere pimple on the face of global equities. In fact, it is only companies buying their own shares that seemingly want the UK today.
https://www.ftadviser.com/equi...
Sensible and interesting narrative eParo. I certainly agree, nothing stands still and the only constant is change. UK small caps will at some point have their day in the sun. One just needs a little good fortune and decent research in choosing the right shares.
Jonno "One just needs a little good fortune and decent research in choosing the right shares" Really?
Just look at the Aim charts over a long period. It is very easy to lose a small fortune - buying Aim shares should come with severe health warnings, and helpline numbers. Only half joking because it is a place with sharks, liars, lounge lizards and con artists (even if never prosecuted) lurking everywhere. If inheritance tax exemptions are withdrawn the Aim indices will hit all time lows, and all "Investors" will realise they have actually been gamblers for years. Of course there are good, increasingly profitable Aim companies and nuggets of gold, but their shares will tend to be relatively expensive, which is to be expected, However it is truly amazing how many companies which have never made any money or paid any dividends, still manage to issue new shares, year after year, which may be deeply discounted, so diluting all the long term holders year after year. Don't forget all the time we invest in "researching" in the name of our hobbies, encouraging the rising stars of future British Industry. Actually we all know it makes more sense to just pick 10 solid , steady, large companies and tweak the portfolio every 6 months or so, getting rid of dead wood. Buyer beware. Tata for now.
PS I know all this is obvious and off topic, but it is late in the evening, tommorow is another day, so nobody will read this anyway, and I just felt like having a good whinge.
PS, Jonno writes lots of great stuff on here, which I usually agree with ..............but I think the above statement could mislead potential new investors. 12 years ago I was that confident, wet-behind-the ears "newbie", even though I had spent a few years working back office in a stockbrokers.
My morning smallcap tweet: It's a chill wind
TT electronics (LON:TTG) Kromek (LON:KMK) MaxCyte (LON:MXCT) Kinovo (LON:KINO) MicroSalt (LON:SALT) Volex (LON:VLX) Synectics (LON:SNX) Netcall (LON:NET) £Made Tribe Technology (LON:TRYB), Science in Sport (LON:SIS)
◄TT Electronics (TTG)► warns H2 rev miss of £15-20m and FY op profit only £37-42m. Blames delayed orders and operational efficiency issues in North America. [SP=141.21 Cap=251m]
◄Kromek (KMK)► wins £2m ordre for nuclear radiation detectors and ancillary products. Delivery thus FY. [SP=5.4 Cap=35m]
◄MaxCyte (MXCT)► signs 'strategic' (natch') platform license agreement with Kamau Therapeutics to accelerate the development of cell therapies. [SP=300 Cap=424m]
◄Kinovo (KINO)► wins £12m 18 month contract for Net Zero Carbon works. Also £400k max PA 3 year contract for repairs to council dwellings and common areas. [SP=67.98 Cap=42m]
◄MicroSalt (SALT)► gets products into more American stores. Also "advanced discussions with major food manufacturers, with volume commitments of approximately 350,000 lbs., received in Q3 with more commitments anticipated in Q4 2024, from companies in both Mexico and the US". [SP=56.37 Cap=27m]
◄ValiRx (VLX)► subsidiary Inaphaea BioLabs signs co-marketing agreement with US contract research organisation Netoids Rx Laboratories. [SP=335 Cap=609m]
◄Synectics (SNX)► guides FY-Nov U/L pretax materially ahead of market expectations of £3.5m. [SP=206 Cap=37m]
◄Netcall (NET)► buys Smart & Easy (trading as Parble), a provider of intelligent document processing software, for €4.7m plus €4m max contingent. Expected to be immediately earnings enhancing. [SP=87.85 Cap=144m]
◄(Made Tech (MTEC)► wins 4 year £13.2m contract from the Department for Education. [SP=NA Cap=NA]
◄Tribe Technology (TRYB)► first autonomous RC Drill Rig delivered to Australia. [SP=4.47 Cap=11m]
In line: SIS
ValiRx (LON:VAL) not Volex (LON:VLX)
Welcome back Alun
Tiddler Made Tech (Mkt Cap £23.7m) awarded £13.2m contract with the Department for Education
Made Tech, a leading provider of digital, data, and technology services to the UK public sector, is pleased to announce that it has been awarded a contract with the Department for Education ("DfE"), worth c. £13.2m over a four-year period, with an option for the DfE to extend for a fifth year, valued at c. £3.3m. The initial contribution from this contract is expected to be recognised in the current financial year.
The Group will provide digital, data, and managed service capabilities to support the Standards and Testing Agency (STA), an arm's-length body within the DfE, in launching national curriculum assessments for pupils in primary school. The initial focus of this contract is the delivery of the Reception Baseline Assessment, a new government initiative to monitor pupil progress, scheduled for rollout in April 2025.
Thought of the day
Chinese ecommerce giants Shein & Temu have for years been flooding the West (see chart) with cheap low value imports (re thresholds: $800 US, £135 UK & €150 EU) that are sent direct-to-the-consumer and hence avoid paying VAT/sales tax.
This is perfectly legal, yet unfortunately it is killing domestic rivals who have to charge 20% VAT/sale tax on each item sold. Just look at results from Boohoo, DollarGeneral & THG as evidence.
However, what might happen if both the US and UK chose to close these perceived ‘unfair’ tax loopholes?
Well the good news is that Britain and America might raise more than £2bn and $7bn respectively by equalising such tax regimes. Much better than a poke in the eye for their depleted coffers.
But that’s not all.
The tax changes would also help boost the fortunes (& jobs) of domestic online and physical retailers. Without materially increasing inflation either, as many consumers would simply switch to buying more items locally, whose prices wouldn’t be affected.
Meaning in the event UK chancellor Rachel Reeves did ultimately decide to ‘level the playing field’ and push the VAT button on low value foreign (non EU) imports.
Then for investors, it could materially boost the prospects of listed retailers like Next, M&S, Boohoo, Shoezone & many others. Now that sounds like a bargain…. Roll on the 30th October Budget.
Interestingly an older direct to consumer Chinese retailer Ali Express already introduced VAT on sales to UK consumers a couple of years ago. I had thought that there had been UK government pressure to achieve this but I don’t know the history .
Not a new idea. Singapore already closed this 'loophole' a while back and all imports have been taxed with GST (their VAT equivalent) even for lower value goods below the previous import threshold amount for quite some time already. The bigger retailers (Amazon etc.) are all over this and it gets automatically added to your payment cart when you check out so you can immediately see the total cost. Customers ordering from smaller operators who miss this may end up with a 'surprise' when their good don't arrive and are held by customs pending payment of the GST as a separate charge. In Singapore everyone took this on the chin and it was a very smooth transition process without fuss (and the collection process for missing GST also efficient and very easy to navigate). If this comes to pass in the UK prepare yourself for (i) several months of a barrage of complaining consumers who 'had no idea' they were going to be hit with a 20% uplift on their orders from abroad, and miles of newspaper column space devoted to the injustice of it all... *eyeroll* and (ii) a massive backlog of parcels and a shambolic period of trying to collect VAT on orders with a system that isn't ready for it ... What's the betting that the extra manpower and systems upgrades needed to administer it all ends up costing the amount of the extra VAT raised?! Ahhhh, gotta love our green and pleasant land here in Blighty...
Here is a story found under Walmart (NYQ:WMT) which might be of interest...
US lawmakers urge Biden to close tariff 'loophole' for Chinese small package imports
What I found interesting is that they say Amazon.com (NSQ:AMZN) and Walmart (NYQ:WMT) also benefit from the ‘deminimus loophole’ . I did a bit of digging to try understand how they benefit and came across this link which explains it and that Amazon.com (NSQ:AMZN) and the United Parcel Service (NYQ:UPS) and FedEx (NYQ:FDX) lobbied for it. The Loophole That Lets Amazon Deliver Uninspected Imports to Your Door
Hi Paul, Really enjoyed the podcast (as always) and think that your idea to discuss ratios with Paul Hill is a really good idea.
Yes, great idea Scotty. Definitely up for discussing the various valuation metrics that investors might wish to use.
Our next big podcast is scheduled for 2pm Wednesday 2nd October - so only 16 days' time. We'll slot a 10-20 mins section into the interview to cover the topic, alongside taking questions from the audience.
Remember however valuation is an art & science - re 'Beauty is in the eye of the beholder'.
Facilities by ADF (LON:ADF)
Before today's interims some research I did following Paul's detailed report on the acquisition and placing here:
https://www.stockopedia.com/co...
He commented on the placing by individuals:
Paul also had a go at the phrase "selling in order to meet strong institutional demand" which I agree is an untrue nonsense trotted out time and again and should be banned.
So why did they sell?. My guess is fear of the next budget re CGT and possibly IHT. As far as CGT is concerned they paid just £100 between them for those shares.
Andrew Dixon and Stephen Haines created CAD Services Ltd in 2002 each putting £50 in for 50 shares. At the end of 2021 they sold the company to ADF just before its flotation and it was for a while ADF's only trading subsidiary. Remarkably they never increased the share capital so the balance sheet at the end of 2021 shows:
The sale was an all share exchange. If I was sitting on those capital gains I would be worried about the forthcoming budget!!
If Starmer and Reeves are smart, which they should be, the scary words will be followed by a budget which is less aggressive than people feared.....
Or it could be a case of ‘kitchen sinking’ performed by new CEOs …