Small Cap Value Report (Mon 17 Dec 2018) - ASC, BOO, SOS, SFE, PHTM

Good morning, it's Paul here.
I knew it was going to be a bad day today, at approximately 06:52, when I knocked a tumbler of water all over my iPhone, trying to turn off the alarm. My late grandmother always told me that bad things happen in threes - which always struck me as possibly not the most soothing thing you can say to someone who has just experienced their first bad thing of the day.
Thankfully, I have since accidentally poured cold water into my cafetiere, and spilt a carton of milk all over the kitchen floor. Therefore my quota of 3 bad things is now complete, and today should just get better from here.
Or so I thought, until looking at my share prices. Let's hope that doesn't constitute the start of a second batch of 3.
A profit warning from perennially over-priced Asos seems to have caused some problems this morning. Therefore, despite being a larger cap, I'll check out what Asos is saying, looking for sector read-across. I'll also later look at the update this morning from Boohoo (LON:BOO) .
There seems to be a pattern emerging of (some) clothing retailers saying that November trading was poor - e.g. Sports Direct said that trading was "unbelievably bad" in Nov. Bonmarche Holdings (LON:BON) put out a horrible profit warning recently. As did Superdry (LON:SDRY) .
Therefore it seems likely that others could be following suit with profit warnings. Hence why it's carnage in the whole sector at the moment, re share prices. The market tends to shoot first, and ask questions later.
ASOS (LON:ASC)
Share price: 2539p (down 39% today, at 11:27)
No. shares: 83.87m
Market cap: £2,129.5m
Trading update (profit warning)
This online fashion retailer announces a slowdown in Q1 (Sep-Nov 2018) sales growth.
Last year (ending 08/2018) Asos achieved +24% revenue growth. This growth rate has slowed to +13% (at constant currency, or +14% as reported) in Q1. Note that;
- November was particularly difficult (as others have reported) - not helped by unseasonably mild weather (which does genuinely have an impact, as people don't buy higher value outerwear)
- Conventional retailers would die for revenue growth of +14%, so this is still a good performance, just not as good as the market was expecting - hence the share price being clobbered, as expectations are lowered
- The UK is actually the strongest market segment, with +19% revenue growth. So nobody can blame this on Brexit! (although no doubt some people still will, as generally I find that people tend to believe what they want to believe)
- EU sales growth is +14% (at CC), with France & Germany being difficult, but the rest of Europe better (at +24%)
- Margins also down, by 160 bps - which is often the case (revenue growth & gross margins tend to move in tandem, because lower sales then require price discounting to shift slow-moving inventories)
Asos has a relatively low gross margin to start with, as it shifts a lot of third party inventories (lower than own-buy product).
Higher costs
Put that lot together, and the EBIT margin (which wasn't good to start with) has halved. Revised guidance for this year;
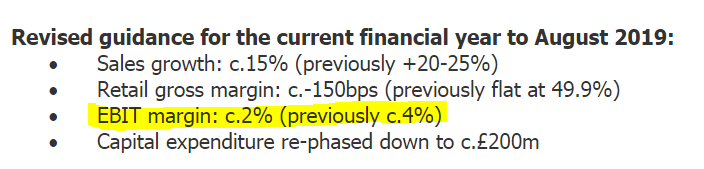
Other points;
- Capex is being reduced - but is still enormous, at £200m this year - being warehouse automation mainly
- Significant headroom on banking facilities - the fact this is mentioned at all is a worry
- H1/H2 profit weighting is usually 30%/70% - will be even more pronounced this year (thus increasing risk H2 could disappoint further)
My opinion - Asos doesn't generate any free cashflow, and has never paid dividends. So what exactly is the point of it? Mind you, people have been saying that about Amazon's cashflow for years too, and that hasn't held it back.
At this size, the business should be highly cash generative, but isn't. That's concerned me for a long time. The market didn't worry about this, whilst growth was stellar, but it's coming more info focus now that growth is slowing down.
The key question is whether this is a temporary dip, or whether online sales growth has now peaked? I saw an article recently which suggested that online is levelling off in Germany, as everyone who wants to buy online is possibly now doing so. Whereas in the UK, consumer appetite for online purchases shows no signs of abating.
In the past, a pre-Xmas wobble in retailing shares has, selectively, been a buying opportunity. My experience (admittedly now becoming historic) was that Xmas sales always happen, they just get later & later every year. I think Black Friday has been a terrible American cultural import (aren't they all?!) - it just incentivises customers to hold back on spending in Oct & Nov, to anticipate Black Friday discounts.
Large eCommerce companies like Asos (and increasingly BooHoo) become so large, that their warehouses become inefficient. Therefore both are spending lots of capex on automation. Whilst expensive short term, that should give considerable efficiency and cost savings, once up & running. So there should be upside to come through in due course for both companies.
With slower growth at Asos, it is likely that investors will focus more on conventional valuation measures, principally PER. That could see Asos shares potentially tumble a lot further.
Are the problems closer to home with Asos, as opposed to industry-wide, or a bit of both? An update from BooHoo this morning seems to indicate that Asos could be making some of its own problems, or just isn't competitive enough any more, maybe?
Boohoo (LON:BOO)
Share price: 156.6p (down 14.4% today)
No. shares: 1,149.5m
Market cap: £1,800m
This is another online fashion retailer, with 3 brands: BooHoo, PrettyLittleThing, and Nasty Gal.
No doubt in response to Asos's profit warning, BooHoo rushed out at 8:08 this morning a brief update on its own trading. Everything's fine basically;
Boohoo group plc (AIM: BOO), a leading online fashion group, is pleased to confirm that the group's trading performance remains strong, with record Black Friday sales across the group and continues to trade comfortably in line with market expectations.
The group will provide an update for the four month trading period to December 31st on January 15th 2019.
So why on earth is its share price down over 14% today? That doesn't seem to make sense to me.
Why is BooHoo not being affected by the sector slowdown? Probably because it's so aggressive on price. BooHoo's strategy has always been to lead the charge against conventional retailers, by under-cutting them on price, and achieving better speed to market, with the test & repeat business model.
Hence I can see why BooHoo would weather the current storm better than others.
Read across to other retailers
This is very difficult to determine. The share price of Marks and Spencer (LON:MKS) is plumbing new lows, so my previous enthusiasm for the turnaround story there has obviously waned somewhat. There's no point standing in front of an express train, hoping that it will stop before it hits you, so I've had to bow to market forces and close my long position there, for now. Although the (I believe safe) dividend yield is now highly attractive.
Similarly, and as mentioned at Mello, I've been looking for a point to re-enter Next (LON:NXT) but it really doesn't feel like the right time there either.
As regards Sosandar (LON:SOS) the share price fall today of 15% to 29p doesn't make any sense at all. We've heard from management very recently (in interim results & presentations) that business is booming, across all product sectors. They're very upbeat about how things are going, and broker revenue forecast have been raised recently from £3.9m to £4.15m for y/e 03/2019.
Given the incorrect market read-across, I think it would make sense for SOS to follow the example of BOO, and also put out a brief update. Crunching the numbers myself, and looking at how quickly many lines sell out on Sosandar's website at full price, I reckon they should be on track for a substantial beat against broker forecast revenues of £4.15m. They achieved £1.85m revenues in H1, and the H2 seasonal uplift should be huge. Therefore I'd be surprised if anything under £5m revenues for the full year are reported.
SOS is achieving these big sales increases on 55% gross margins, way ahead of the 48.4% gross margin being achieved by Asos. That's because SOS product sells through very fast, at full price - an extremely bullish indicator that the company is designing products which are highly attractive to its core customer, and that demand exceeds supply.
Another point to bear in mind, is that a tiny eCommerce fashion business like SOS can carve out a niche in a gigantic market, irrespective of market conditions, if the product is right. Whereas it's more difficult for bigger players to buck macro trends.
Incidentally, if you've not seen it, there is an excellent video here from 3 Dec 2018, briefing private investors on Sosandar's recent interim results. This is well worth a look, for people interested in deepening your understanding of the company. I had a more detailed meeting with management a couple of weeks earlier, which was also very upbeat in tone. There's no read-across at all to Sosandar, from today's Asos profit warning, in my opinion.
Therefore overall, my view is that I'll be avoiding Asos, even after this big plunge. Whereas both BOO and Sosandar (in which I have a long position) look like buying opportunities to me. I'm also minded to avoid all conventional retailers for now. There might well be some bargains out there, but we just don't really know which ones are bargains, and which ones are disasters waiting to happen.
So much business is leaking away online, that conventional retailers with a small/poor online offering are looking very vulnerable indeed.
Whereas niche & online retailers continue to do well. Joules (LON:JOUL) was an example of a business that is bucking the trend, with a positive recent update.
Isn't it annoying when waiters try to memorise your order, instead of writing it down? There's literally zero upside for the customer from this annoying practice. There's only downside risk, that something will go wrong, which it very often does.
I ordered 3 items, solo dining today, for a late lunch. Guess how many arrived? One! Yes, the waiter managed to forget 2 of the 3 items I ordered. There were only about 4 other people in the restaurant, so it wasn't like he was rushed off his feet.
Although 2 of those other people were a couple of very attractive Italian young ladies. (I was going to say "birds", but apparently that's not allowed these days). The waiter was also Italian, and let's just say that I've noticed Italian waiters' blood tends to flow away from their brains, when attractive women are in the vicinity.
Which restaurant was it, I hear you ask? Franco Manca! (in which I hold a long position - part of Fulham Shore (LON:FUL) ). The gluten-free pizza base was awful too, so they haven't got that right either. Never mind, usually it's much better, so I can forgive them one mishap.
Safestyle UK (LON:SFE)
Share price: 85p (up 4.3% today, at market close)
No. shares: 82.8m
Market cap: £70.4m
What a bizarre year, this PVCu replacement windows & doors company has had. Trading fell off a cliff, when a founder & a load of staff left, to set up in competition. Then, they were enticed back with a mixture of carrot & stick.
Things now seem to be picking up;
Since the Commercial Agreement announced on 22 October 2018, the Group has experienced a significant increase in its contracted workforce across its canvass, sales, surveying and installations operations. This has resulted in an improved sales order intake that is in line with the same six week period last year.
Higher short term costs, and lost business earlier this year, has resulted in a thumping great loss for this year (today forecast by the company at between £8.2-8.6m pre-tax loss). This looks to be in roughly the same ballpark as Stockopedia's (post tax) forecast loss of -£6.5m.
Outlook - this sounds more promising;
... the Board is confident that the recovery and performance in 2019 will be ahead of current market expectations.
The only figures I have, are £4.5m after tax profit in 2019, which equates to 4.62p EPS. That's the Thomson Reuters data shown on Stockopedia.
There are 2 new broker updates out today, available on Research Tree. These move up 2019 EPS forecasts to a range of 4.9p to 6.4p, with a further increase pencilled in for 2020.
My opinion - it sounds as if the business is getting back on track.
However, for me, the damage is done. The events of the last year have demonstrated how fragile the business model is. Key staff can up sticks at any time, set up in competition (there are not many barriers to entry), and quickly wreck the business they came from. I suppose there's a risk of that happening in many areas, but normally staff are more loyal, and the key ones are locked in through appropriate bonus schemes, share options, etc.
For me it has all been a good reminder of why I'll never invest in anything to do with double glazing ever again. There isn't any kind of moat. Staff do not appear to be loyal. Business practices can often be at the sharp end of acceptable (high pressure selling, etc). It's highly cyclical. Profits can vanish very quickly, the list goes on & on.
Photo-Me International (LON:PHTM)
Share price: 88p
No. shares: 377.7m
Market cap: £332.4m
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces its results for the six months ended 31 October 2018.
Figures from this photo booth & other booths group, slipped through the net last week. So this is a catch-up section.
The most striking feature from the StockReport is the forecast 9.5% dividend yield. Anything over the borderline range of 6-7% is usually a sign that there may be trouble ahead - i.e. that a dividend cut could be in the offing. 9.5% yield is well into danger territory. In recent years, the market has actually been very good at predicting dividend cuts (through excessive dividend yields). So amber lights are already flashing in my mind.
Key features from PHTM's interims;
Adjusted profit before tax down 7.9% to £26.7m in H1
Seasonality - it's good to see this spelled out clearly in note 3 (all companies should do this);
Historically, the first half of the financial year is seasonally the strongest for the Group in terms of profits, and this is expected to be the case again for the current year ending 30 April 2019.
Outlook - sounds OK, with a proviso;
The Group maintains its guidance for the FY2019 and expects to report profit before tax of £44 million, net of restructuring costs in Japan and excluding any movement in the value of Max Sight Holdings.
The Group's ability to meet guidance will be reliant on normalised trading conditions in its key markets.
Balance sheet - I'm scratching my head over this. The cash pile has grown tremendously, to £88.6m. Yet is has bank debt too - of £57.1m. Why?
I don't understand it. You could argue that big dividends are being paid (at least partially) from bank borrowings. Yet bank borrowings seem to be more than covered by cash balances. That doesn't make sense to me.
My opinion - I rarely (if ever, actually) flag the risks section of the narrative, in results statements. Maybe we should collectively look more closely at these?
In this case, perhaps PHTM shares might be cheap because European Governments might try to undermine this UK-based company post-Brexit? s it's involved with Govt ID, that's not as daft as it sounds.
That's me done for now.
Another year goes by, and it's been a pleasure! I'd like to thank Graham for being such a pleasure to work with, and of course the team at Stockopedia who put up with me being me - as always, hopefully the positives out-weigh the negatives - that's what it's all about, none of us are perfect!
Above all, thanks to the 3/4 of all SCVR readers who are Stockopedia subscribers! It's very much appreciated. To the other 1/4 - what's the matter with you, why do you think you should get our lovely insights free? Cheapskates!
The rest of this week is mainly fun-filled lunches & parties for me, so I'll leave you in the capable hands of our Graham! Then into January of course, it's the grim winter period of Dry January. Doctors orders this year, I've got to do Dry February too, to grow some new liver cells. Well it's for the best!
See you on the other side :-)
Love, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
This is the season for hostile takeovers, shares being so low-priced by a nervous market, that if I were a susceptible company I would load up with debt just to keep predators away. Does this answer Paul's question about PHTM?
Interesting view to take into account. Would it also be fair to consider a tax offset. with interest rates still quite historically low, one could argue it would be more economical to pay interest on debt rather than a higher tax bill?
I think this is conflating two different things - online penetration of users (being the percentage of all consumers who have recently bought something online) and online retail sales penetration (being online sales as a percentage of total retail sales).
Germany's online user penetration is indeed pretty flat at around 80%, but this translates into online sales of around 15% of total retail sales, which suggests to me that there is ample room for growth even if user penetration stays flat and even if some categories of retail sales remain resistant to the shift to online. (I think the corresponding figures for the UK are around 80% and 18% respectively).
Over the weekend I was watching a video of Benedict Evans (of Andreessen Horowitz) making this very point. He included this chart to make the point that "most people are online but most of the money is not":
For anyone prepared to take the long view and look past any short term weak consumer sentiment, there is still plenty of money to be made in online retail, but whether ASOS (LON:ASC), Boohoo (LON:BOO), Sosandar (LON:SOS) or none of the above will be long term winners, I have no idea.
Amazon it is then! :D
No (direct) holding in amzn or other shares mentioned. Can't handle the multiples
Many thanks for your great analysis Paul. I look forward to your Photo-Me International (LON:PHTM) review as it will be interesting to read other views and if the price is fair or the share has been beaten down too much on trading results and general stock market action.
The retail sector is certainly battered today. As a holder in French Connection (LON:FCCN) in light of their transformation plans and the up for sale sign I was a little surprised to see their price pushed down strongly today too. It leaves me pondering whether to increase my stake since with 4 potential suitors a nice bidding war could emerge. And it has very little to do with ASOS!
Seemed to be retail-carnage-day today !
I sold 40% of my Boohoo (LON:BOO) holding on 16th Nov for just over 200p, and didn't expect to be able to rebuy those for sub 160p so soon. Back up to my main holding level for BOO, and hope the 15th Jan T/U isn't a disappointment.
Also had a small dabble with two other retailers today. After my purchases, one dropped a further 5% and the other finished up 5%, so cancelled each other out.
Having sold part of a core holding to make these purchases, my trades today (4) exceed my average monthly number of trades (3) !
With retailing on my mind, and whilst chatting to an avid Marks and Spencer (LON:MKS) shopper, I decided to have a quick look, and was quite surprised at their 5-year summary. Turnover has remained in the £10b region, but PBT for 2014-18 has been £580m, £600m, £489m, £176m, £67m - quite a dramatic downturn. Without checking, I presume there are other B&M retailers showing the same (or worse).
Boohoo (LON:BOO) looks to be worth a punt at this price following their positive trading statement and considering the track record for profitable growth.
I thought the question to ask about £ASOS is why on earth the price was so high before. A market cap in the region of 7bn, for a retailer with sales in the region of 2.5bn, just seemed divorced from reality. After today's "shocker" we are still seeing a business with revenue growth of 14%, and an underlying forward PER somewhere around 35. Still expensive, but there must be a decent business in there, once the current heavy capex winds down.
On the negative side, why are their operating margins half those at £BOO? Suggests Boohoo (LON:BOO) is the better business - as obviously a lot of other people think.
I don't own any retailers, but starting to wonder whether I should.
ASOS (LON:ASC) sells branded goods therefore paying for the privilege. Boohoo (LON:BOO) sells their own high fashion range - fast, cheap, responsive to demand. I sold Superdry (LON:SDRY), ASOS (LON:ASC) and Sosandar (LON:SOS) a while ago. Long term holder of Boohoo (LON:BOO) and Next (LON:NXT). I see Next (LON:NXT) and their excellent management adapting to the retailing market using their established distribution networks. They serve different markets - one very young, the other middle-aged but both fairly neutral on branding. I would never invest in branded gear now, fashion is moving way too fast . I'm not convinced about Sosandar (LON:SOS) as I don’t like their merchandise and can’t identify their target market. They are not profitable so I'm steering clear for now.
Hi SundayTrader,
Thanks for your comments. I have been saying for, literally years, that Boohoo (LON:BOO) is a better business than ASOS (LON:ASC) - because BOO is run by astute rag traders, who know how to make a margin. Asos isn't. Hence why it doesn't make any real profit or cashflow.
Nice to be vindicated. Even though I sold my 500k Asos shares at 9p for a nice profit, and then shorted it (numerous times!) from 350p up to 7000p, losing money almost every time. LOL! ;-)
Equally, BOO made me a few hundred £K, but could have been millions, if I'd just sat tight, from the massively positive comments here when it was 24p.
Such is life! Nobody can time the lows (buys) and the highs (sells) every time. Anyone who claims they do so, is a fraud!!
Best wishes, Paul.
Many thanks to Paul (in his " read across to other retailers" section for the link to the 30mins Sosandar video posted on you tube. First time I had seen Julie Lavington perform . Clearly understands her consumer and she was in command of both her people and the business data. Very positive impression. Well worth watching
Talk was uploaded on 6th Decand included lots of graphs showing eg marketing spend separate from logistics and other admin My favourite was a classic 2x2 grid showing top left young fast fashion brands for 20 year olds (Zara, Top Shop, Asos) and bottom right "Mumsy Middle Ground). Of course, Sosansdar was unopposed in top right!
Julie said Nov 18 was a new record (no surprise for new business) but gave no indication of anything other than rapid growth with products selling out and going on wait list and expansion to new categories like scarves flying.
Since they are so small they can grow X50 before worrying about the market; they just need to find their natural customers. My only query will come when the business has grown so much the co-founders can no longer directly supervise the design side and the business will have to go more corporate. However, this is probably when urnover is >£100Mn vs current run rate of around £4mn pa annualised
I already had a small position but gifted by today's pullback, I am buying more.
According to the met office (https://www.metoffice.gov.uk/climate/uk/summaries)
"The provisional UK mean temperature [for November] was 7.3 °C, which is 1.1 °C above the 1981-2010 long-term average."
Hi HHR,
That's interesting, your data;
"The provisional UK mean temperature [for November] was 7.3 °C, which is 1.1 °C above the 1981-2010 long-term average."
I spend my time between London, and the South coast. So to me, it never really feels properly cold, until we get a cold snap, and some snow. The rest of the time, I just go around in t-shirts, and my red gilet from Primark, and maybe in Dec & Jan I might put on some fingerless gloves from Primark, and a beanie.
That's about it.
So I've never really understood why people buy winter coats, etc.
I spend about 10 minutes outside, and Mum asks me why my arms are not cold, wearing just a gilet. I reply of course that it keeps my rotund torso warm, and hence continues to supply my arms with hot blood. My arms would only go cold if the supply of warm blood stopped. Which of course would be terminal anyway, so cold arms would be least of my worries in that scenario.
Bottom line then? Winter coats are not necessary if you don't care about fashion, and maintain a BMI of 25-30 over the winter - which is similar to what penguins do, I believe.
OK, I'll stop now.
Best wishes, PaUL.
RE: Gillet, I've never been in a situation where my body is cold but not my arms. Please can someone explain the point of this garment?
So Marks and Spencer (LON:MKS) is down in sympathy this morning but it should not be a surprise. Normally the two weeks before Christmas see peak prices but not this year. M&S is offering me 20% off everything except food and drink until Thursday. Last week I shopped in Tesco with an £8 off £40 voucher and found that they had a 25% off 6 bottles or more of wine promotion.
This is worth reading as a reminder:
https://www.theguardian.com/business/2018/dec/13/retailers-dont-need-mike-ashley-tell-them-how-bad-november-trading-worst-record
I know I'm not the right demographic by I've watched the boohoo various adverts in the last month or so and have no idea what the are advertising. Retail is detail.
Asos is a real shocker. It is the bellwether of online. I walked past a Quiz shop last week...empty. It is as if many folk are thinking we don’t know what will happen next year so let’s have a skinny Xmas and reduce or not increase debt and wait and see. I know mortgage applications are being rejected all over the place. I read an interesting article last night where a professor said that he did not think the mkts had priced in the impact of a no deal. Some of the smartest private investors I know are sitting at 90 per cent cash. I reckon the mkt is reasonably cheap but I think it is going to get a lot cheaper. Both in terms of the stock mkt and property mkt. toughest thing I find is to sit on my hands and do nothing....but I know I must. Cash won’t run away. January and February could be really dire and I just cannot see stocks higher esp if poor results start to be issued.
M&S will no doubt post some awful figures but we all exepected that long ago.
(Fashion) Brands seem to have a lifecycle and on the internet it seems to be faster.
Asked some young (under 25) people about asos.
One said her mum shops there.
This is why the boo purchase of prettylittlething etc is a good move.
But it does speak to a lack of 'loyalty'
I have the feeling that internet years are like dog years.
Wow ASOS down 40 % and SOS down 13%. Would love to know your thoughts Paul......
QUIZ (LON:QUIZ) looks very cheap on these prices.
I seem to remember Paul speculating that their recent woes of bad trading were at least partially down to a poor performing autumn range of clothes. Given that retailers are saying that November has been unseasonably warm (and it looks as if December might go that way too), this might not be so good news for Quiz, and the next trading update could be bad as well.
I feel that the likes of the small firms like Bonmarche and Quiz might end up being obsolete in a few years without a massive change in fortunes. Is the target market for Quiz that much different than ASOS or Next? I feel they are powerless to repel them - a hot selling item by Quiz would just see it replicated by Next, which also then might be replicated by Primark.
Will be interesting the next Sosandar update - apparently November went really well for them, so they could be immune some of these issues.
My gut feeling is that for the 16-30 segment of the market, value is going to become more important. Cannot imagine disposable incomes increasing here, so looking further afield makes sense. At least ASOS have the money to do it, the others will have to ride it out.
Remember QUIZ (LON:QUIZ) has already reported on sales for the majority of November:
"Since the end of H1 2019 we have continued to grow Group sales. In the eight weeks to 24 November 2018, sales (excluding international franchise sales which are wholesale in nature and therefore, can fluctuate from month to month) are up 10% year on year. This growth has been underpinned by particularly strong sales growth through the brand's own websites of 62%."
QUIZ (LON:QUIZ) particularly focuses on occasion clothing (e.g. parties, weddings) so may be slightly more insulated from the negative impact on warmer clothing that we're seeing.
Would be great to have some thoughts on the retail space..as per many of the above posts. QUIZ (LON:QUIZ) looks very cheap -famous last words
Interesting on ASOS revenue miss from RoW -3% (UK +19%, EU +18%, US +13%). Lots of discounting sees GM -150bps guided to 48%. You might think manageable. Op margin guided down to 2% from 4%! Low margin businesses so risky. Also note increased H2 weighting warning. Not for widows and orphans!
Market is frit
Nearly all clothes retailers talking about unprecedented conditions. Not just High Street. No visibility on future trading, let alone profits. Be very interesting to read the next Next statement. Relative to what's around then Boohoo (LON:BOO) is looking good. But with no visibility in front, would you buy?
Manolete Partners (LON:MANO) listed on Friday as a competitor to Burford Capital (LON:BUR) - there's no Stockopedia page for it yet unfortunately. I would welcome any views.
EDIT: Here's an interview with the Manolete Partners (LON:MANO) CEO Steven Cooklin.
Hi FREng
Useful link to Manolete Partners (LON:MANO) interview. Many thanks. I have them on my watch closely list.
Regards
Howard
Re K3 Business Technology (LON:KBT)
I like the sound of the fact that they have reduced debt quite a bit. They fall foul in their Trading update of Paul's gripe when companies say they are 'slightly' ahead of expectations, but don't bother to illustrate what the expectations are. Those expectations were probably already managed downwards, but still I guess they are at least holding steady?
K3 Business Technology (LON:KBT) emphasise their wins in the retail sector, and it sounds like the European end of retail may be holding up, but what about the pressures on their UK retail sector exposure?
SCS down 10% this morning with no RNS. The figures show a stable and consistently growing business so why the big drop? Ex-div was in November. Could it really have dropped so much driven by the retail market as a whole? Seems excessive.
What am I missing?
I had the same thought as Vig about SCS (LON:SCS) which is currently down around 10% and I think it's credible for the drop this morning simply to reflect the general High Street woes. My rationalisation is that when companies are saying that consumer behaviour is 'unprecedented' then it's understandable for investors, after a weekend's reflection, to take profits on any shares they hold in the sector that have had a decent run. When you see what happened at Bonmarche Holdings (LON:BON) you might think that there is not much upside at SCS after a good run, but plenty of downside if they issue a profit warning. At £2 the shares are back where they were at the start of the year, which is a creditable performance in this market. I hold and have no plans to sell.
Although the moves across the retail sector have been quite haphazard. Obviously ASOS (LON:ASC) is the big faller, but with CEO Nick Beighton referring to high priced items & men's sneakers as specifically weak areas I'm surprised JD Sports Fashion (LON:JD.) hasn't fallen further. ASOS (LON:ASC) warning also starts to damage the argument that it's worth paying for quality in the sector. e.g. preferring JD. to Secured Property Developments (OFEX:SPD).
SCS (LON:SCS) down 10% but AO World (LON:AO.) flat. I can't see consumers holding back on spending on sofas so they can load up on white goods. Again ASOS (LON:ASC) warning starts to damage the argument that online only retailers are immune. Although Boohoo (LON:BOO) much more confident.
QUIZ (LON:QUIZ) looks stand out bargain to me, now trading close to tangible book value. Reported 62% increase in own website sales at the end of November. Obviously exposure to Debenhams (LON:DEB) but it's reasonably easy to hedge that exposure if one wanted.
A real mixed bag out there and very hard to call in the short term though.
I think perhaps I needed to hear some consensus behind the market move argument for it to sit better with me. It was quite a shock to see it drop so much but I have no intention to sell (though my stop isn't far off!).
I'm a holder of SCS (LON:SCS) now for a few years. Not exactly blown the doors off but picked up a 10% yield on purchase and that has grown along with share price so it hasn't embarrassed itself either.
I warned a friend last week to sell it if nervous. There is a chance they disappoint come next report...I don't think they will but its possible. But a drastic revenue fall is unlikely (exclude HoF outlets). Nevertheless it could fall 30% in the current environment from recent peak for not much reason (taking to a 5 PE with 2/3 of mkt cap in cash, most of that unencumbered, and a dividend yield >10% again).
Its either a really crap business that's going to the wall...or its very ignored/disliked in an irrational way. I thinks its the latter as its smallish, in an unfashionable niche (council house, furnished rental, student digs, etc sofas). Its operating performance has been consistently good. Mgt are very experienced and know who they are and what they do.
Laura Ashley Holdings (LON:ALY) warned that its furnishing business is having tough time so that might be a read across. But its got DFS Furniture (LON:DFS) disease which is being caught in the middle between cheap and luxury...aspirant is the most vulnerable to slow down as this is where the most sensitive squeezed customer is.
If SCS gets any cheaper I think it should be made mandatory for everyone to hold some shares!
It looks like one of the directors of SCS (LON:SCS) saw it as a buying opportunity.
https://www.investegate.co.uk/scs-group-plc--scs-/rns/director-pdmr-shareholding/201812171746277472K/
I hold (mainly for the dividend)
Probably the Rightmove report out today showing property prices decreasing over the last 2 months, and new listings also decreasing (which will probably mean a slowdown in transactions).
Less transactions, less home buys, less furniture needed.
Hi Paul,
You may remember me, we met you at Mello?
I was wondering what you think of Scisys?
Awarded an 11.2 million Euro contract today for their Space division and funded by the EU. Proof that their decision to redomicile to Ireland while simultaneously retaining their AIM status has allowed Scisys to continue to benefit from EU funded contracts. They have a long term clients, visibility of booked revenue and low debt.
(I hold).
Michael
Hi Paul, can you review APC Technology (LON:APC) - "transformational year"
Well perhaps Boohoo (LON:BOO) were right to issue an RNS given that they were down 20% in early trades on the back of ASOS (LON:ASC) update (and updates from others last week). A pity they couldn't get it out before 8am, but it was clearly well in train before then. Price is still down 10% today at 166p and down from 244p on 1st October, so perhaps a buying opportunity...?
I owned continuously from mid 2015 to mid 2017 and more recently traded in and out several times so I am tempted to attempt to repeat my success. However I get the feeling that the game has changed completely in the last couple of months and now is not the time to pay a forward PE of 35x for any retailer.
[I also had a pairs trade with ASOS (long BOO, short ASOS) on two occasions which was quite profitable after some initial pain, but needless to say I closed the latest one far, far too early!]
I am increasingly seeing Minervini's comment play out with a whole range of stocks.
When a secular leader makes a major top, there's a 50% chance it will drop 80% and an 80% chance it will drop 50%.
Minervini calls it the 50/80 rule. On average a market leader will give back 70% of the move.
I'm not a masochist but even though a Sosandar (LON:SOS) holder I'm hoping they don't get into the battle of the updates with Boohoo (LON:BOO) saying there's no flies on us after ASOS (LON:ASC) dropped its mess on the market. Keep to your schedule and don't worry too much on the short term price. A reason (not only) I dabbled then exited from Boo (for a mere 10%) is that I feel they have too much eye on the share price. (Boo holders, just consider it sour grapes from me for missing out on a great story!)
Paul if you do have time I think taking a look at ASOS (LON:ASC) would be helpful as it seems to be affecting a number of retail shares this morning - especially online ones. I have no expertise on ASOS (LON:ASC) so can't add any value.
Among the shares being sold off in response is QUIZ (LON:QUIZ) - again! It is now trading at c.30p as I write. This is a share whose management have recently said they expect 15% revenue growth this financial year, more than a quarter of the market cap is now net cash(!), dividend now around 5%, and it is trading at a forward P/E of 5.6 last financial year's adjusted earnings per share! This seems to more than adequately reflect the risks associated with its Debenhams concessions. Am I missing something?!
Nearly had a heart attack when I saw Boohoo (LON:BOO) release a non 7am RNS.
Given all appears well, not sure why they felt that was necessary. Anyone have any thoughts?
I wonder whether this RNS is due to ASOS's profit warning -to calm shareholders? It is unusual!
(Deleted duplicate post)
Other interesting items (for me anyway):
ASOS (LON:ASC) issues what is in effect a profit warning which is likely to affect e-retailers as a whole, I would think.
Duke Royalty (LON:DUKE) to get a further £180K in royalty payments from Brownhills including a positive 6% adjustment factor (totalling 1.08m per annum from April 2019) and like the business so much they added 1m contribution.
Hopefully they will continue to increase their current 5 partners to 9 using the £30m yet to be deployed during 2019
APC Technology (LON:APC) posted great results this morning; 2018 has been a transformational year for APC. We have significantly increased the scale and profitability of the business..."
My morning smallcap tweet: LIDCO puts a lid on profit.
Safestyle UK (LON:SFE), Summit Therapeutics (LON:SUMM), K3 Business Technology (LON:KBT), Scisys (LON:SSY), Lidco (LON:LID), Fireangel Safety Technology (LON:FA.)
Safestyle UK (SFE) warns FY U/L pretax -£8.2m to -£8.6m, but that's due to significant increase in its contracted workforce in canvass, sales, surveying and installations operations. This has boosted orders. Also inc marketing spend. Guides performance in 2019 ahead of current market expectations.
Summit Therapeutics (SUMM) CFO leaves end Dec. He is thanked.
K3 Business Technology Group (KBT) guides FY results slightly ahead of market expectations.
SCISYS Group (SSY) wins €11.2m contract with Thales Alenia Space.
LiDCO Group (LID) warns FY rev flat. Blames "deferral of revenues as the Company makes more rapid progress to transition existing large UK customers to its High Usage Programme (HUP) business model, an anticipated order from South East Asia being delayed, and longer sales cycles in the US."
FireAngel Safety Technology (FA.) wins contracts from 2 housing associations in Scotland. Tot 9800 homes.
It is being reported this morning (prior to any RNS release) that there is to be a further change in direction for Laura Ashley Holdings (LON:ALY)
Back in August 2018 Graham said this in regard to shop openings/closing of Laura Ashley Holdings (LON:ALY) (share price at the time of 5.25p):
"...But the company is promising to open two new stores and close only five stores over the coming year - wouldn't it be better for shareholders if the estate were to shrink much faster than this?"
The number of UK stores has reduced from 205 at January 2015 to 160 at June 2018 and now planning on closing a further 40 stores in the UK.
Last Friday's CoB share price was 3.24p. Down some 90+% since mid 2015
Their plan appears to be expanding a digital footprint in China before opening physical stores there. If only they had a property in Singapore to work from ;-)
Andrew Khoo, the new CEO of Laura Ashley Holdings (LON:ALY) , has also said this:
"Mr Khoo said that Laura Ashley in the UK had seen some promising signs in the run-up to Christmas including an uptick in clothing sales, but it has been slow to shift big-ticket items like furniture.
“It’s a challenging environment and it could become more challenging,” he said."
https://uk.finance.yahoo.com/news/laura-ashley-close-40-uk-000100629.html
I have highlighted a couple of times the very high stock levels here, stock levels that have over the last five years continued to increase in almost exactly inverse proportion to the decrease in turnover. Fashion acounts for a relatively small part of total turnover. So Mr Khoo's remarks presage nothing good, imo.
I'd expect the, imo, long overdue stock writedown to be brutal.
As for China, well, here we go again! The pretension of the parent group, MUI, to have any great retailing record that would see any kind of breakthrough in China is rather astonishing, given their mediocre track record elsewhere. I wonder if they have really thought about the nature of housing in China, the aspirations of Chinese consumers in terms of lifestyle, and one could go on and on.
The question to be asked about the Tai Seng area property farce in Singapore was why on earth it was bought in the first place, if there were only 10 people working there. Now, I know the tendency of people in SE Asia to simply fall in line with whatever the elder of the clan decides but really, did Andrew Khoo keep quiet through all that fiasco?
Perhaps it is that Mr Khoo feels a hankering for the Chinese market. I can understand that he might. However, imo, the natural market for Laura Ashley remains the US consumer. That is the market with by far the most promising pool of consumers likely to provide business for this brand, consumers with a natural cultural affinity for the lifestyle being offered..
The thought of having to invest once more to chase the fantasy Chinese unicorn must surely frighten any remaining nostalgia buffs still invested here.