Small Cap Value Report (Mon 17 Jan 2022) - MORE, CNIC, HAT, PEBB, PIER, ACC

Good morning, it's Paul & Jack here with the SCVR for Monday. Today's report is now finished.
End of week SCVR podcast
On Friday last week, we trialled a SCVR summary podcast. As it was an unplanned thing, I published the audio file on my personal website here. Jack & I managed to cover 29 companies in 31 minutes, so it's a quick rattle through everything that we looked at during the week in the SCVRs. On the same page, I also typed up a written summary of all those companies which we reported on - mostly trading updates, but a few accounts as well, which you might find useful, colour-coded to show profit warnings & distressed financial situations in red, and out-performing trading updates in green. It's quite good I think, so do take a look.
If people find the podcast & written weekly summary useful, then we'll keep doing more of them. If not, then we'll drop the idea, which is extra work on a Friday afternoon, when I would normally be winding down for the weekend.
Thank you also to the people who kindly left donations towards admin costs on my website. I'll pass those on to ZANE, and will try to change the donate button's function so that it sends any donations direct to ZANE, as I'd prefer any kind donations go to charity, rather than for my admin costs, which are not very much, and I can absorb those myself. EDIT: that's now fixed, the donate button on my website now pays donations direct to ZANE, and I've paid over the money already received to ZANE.
Agenda
Paul's Section:
Hostmore (LON:MORE) (I hold) - a positive end of year trading update ( "well ahead" of mkt exps). This share looks the wrong price to me, much cheaper than listed peers.
Pebble (LON:PEBB) - a positive trading update, but given the premium PER, it needs to be. Profitability has now returned to pre-pandemic level. Quite aggressive accounting, capitalising some costs into intangibles. Doesn't appeal to me.
Brighton Pier (LON:PIER) - a positive-sounding update, but it's only "comfortably in line", so not madly exciting. Forecasts out from Cenkos today make it look attractively valued. Could be worth a closer look.
Access Intelligence (LON:ACC) - profit warning, shares down 25%. Finncap drops forecasts by a lot, and it's still loss-making. Looks precarious, and I think this share could drop much further.
Jack's Section:
Centralnic (LON:CNIC) - I hold - revenue and adjusted EBITDA guidance raised again. It’s been a good year for CentralNic and management has said this is not due to Covid but rather the company’s own actions. That has been said by others before, though… Nevertheless, the group has repeatedly flagged strong operating momentum and its business model is supported by recurring revenue and high levels of cash conversion. Edited to include notes from call with management.
H & T (LON:HAT) - solid results and H2 sees business recovering to pre-pandemic levels. It’s a good mix of quality and value here, with a track record of dividend payments and a strong balance sheet. The share price hasn’t really gone anywhere for quite a long time though, so perhaps more attractive for its income.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Hostmore (LON:MORE) (I hold)
110p (Friday’s close) - mkt cap £138m
Hostmore plc, the hospitality business focused on American-themed casual dining brand, 'Fridays', and the cocktail-led bar and restaurant brand, '63rd+1st', is pleased to announce a trading update for the financial year ending 2 January 2022.
As of 17 January 2022, Hostmore operates 88 restaurants in the United Kingdom and Jersey, a majority of which are in high footfall locations, including retail parks, shopping centres and city centres.
Hostmore is a new listing, having demerged from Electra Private Equity, with MORE shares becoming a standalone company, with a main market listing from 2 Nov 2021.
So far, the demerger has been a flop, due to a mismatch between exiting shareholders (some selling for technical reasons - unable to hold single company shares), and a lack of buyers, because the story hasn’t been explained properly yet.
In my opinion, and based on forecasts published by Edison, this has created a clear value opportunity, where the company looks significantly under-valued compared with its listed peers. So I view this share very positively, for that reason of under-valuation.
Today’s trading update
Odd wording here -
… pleased to report that the trading for the month of December 2021 was ahead of early-month expectations.
It’s not clear if this is like-for-like, or affected (up or down) by store openings/closures?
Revenue for December was 8.3% lower than the comparable period in 2019.
We know that Dec 2021 was disrupted by changes in behaviour re omicron, because other hospitality companies have indicated that the last 2 weeks in Dec 2021 in particular, were disrupted. This sounds encouraging though -
Whilst an increased level of guest reservation cancellations became evident as December progressed, and was in line with Government guidance relating to the new Omicron variant, this was more than offset by a combination of new reservations and walk-in demand which reflected the short-term nature of customer decision making while the uncertainty prevailed.
If cancellations were “more than offset” by new customers, then why was revenue down 8.3% compared with pre-pandemic? That doesn’t make sense to me.
Profitability - “well ahead” is clearly good -
Given the strength of December performance, the Board expects EBITDA (pre-IFRS) for the year ending 2 January 2022 to be well ahead of the market consensus of £18.6m.
Remember that this year will have been heavily disrupted by lockdowns & disruption in H1, and boosted by Govt support schemes. So not a clean set of numbers yet - same for the whole sector.
Current trading -
Trading since 3 January 2022 has been more in line with expectations and reflects what is usually a quieter period post the festive season.
Landlords - hoping to reach agreements with “remaining landlords” on rent concessions. Note that the company has previously indicated it is in pole position for new sites, as a favoured new tenant, because it handled landlords well during the pandemic - paying rents, and doing deals collaboratively. That’s an important point for the future.
Outlook - general comments only, but clearly positive in tone.
Wage inflation in particular is obviously going to be a headwind for everyone in the sector.
Expansion - Hostmore is a roll-out of 2 brands (Fridays, and the new 63rd+1st format). 5 new sites are opening this year, with more in the pipeline. Once the market twigs that this is a roll-out, then I think that’s a catalyst for a re-rating.
My opinion - it’s just too cheap, in my view. So I’m happy to continue holding. There’s been a lot of work done during the pandemic to improve menus & operations, and guest satisfaction scores are rising.
Edison’s last note (9 Dec 2021) shows forecast 10.2p EPS for FY 12/2022. That’s effectively the company’s forecast, and I would expect them to be setting the bar at a level they can beat.
Hence the share price of 110p is likely to be a PER under 11. That’s way cheaper than listed competitors Fulham Shore (LON:FUL) and Restaurant (LON:RTN)
Hence I expect MORE to re-rate to maybe 150-200p over the medium term, as more investors spot the company, and see the under-valuation. That’s assuming nothing goes wrong of course, which you can never be certain about, for any share.
.
Pebble (LON:PEBB)
125p (up 5% at 09:17) - mkt cap £211m
There’s a very wide quoted spread here, at 120p bid/ 130p offer, not something you expect from a £211m market cap company. Real prices are often inside the quoted spread of course, but there doesn’t seem much interest in this company.
I’ve only looked at Pebble once, a year ago here, and wasn’t particularly impressed.
The company sells branded, promotional products.
The Board of The Pebble Group, a leading provider of technology, services and products to the global promotional products industry, is pleased to announce that following a strong close to the year, the Company's results for the year ending 31 December 2021 ("FY 21"), which will be announced on Tuesday 22 March 2022, will exceed market expectations.
There’s no footnote to explain what market expectations are, and I can’t find any up-to-date broker notes.
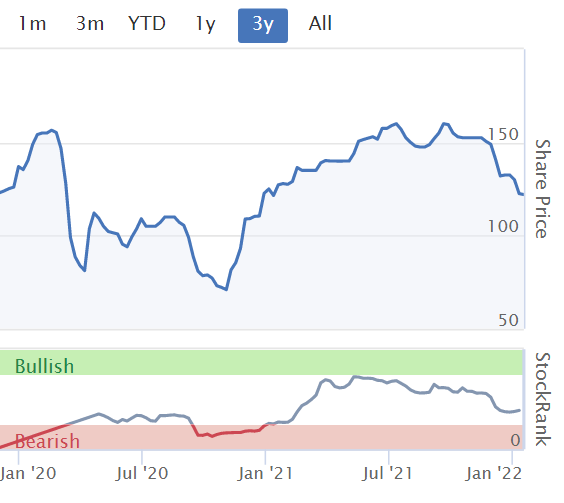
Stockopedia is showing broker consensus at 3.9p EPS, for a PER of a whopping 32 times, so at that high rating, I would expect an out-perform update, just to maintain the current share price.
Guidance - this is useful, specific guidance, even if it is adj EBITDA, not proper profits. Note that PEBB capitalises costs into intangible assets, rendering EBITDA meaningless -
As detailed in the trading update announced on 7 December 2021, both Facilisgroup and Brand Addition traded well throughout FY 21.
Group revenue for FY 21 will be circa £115m (FY 20: £82.4m, FY 19: £107.2m), generating Adjusted EBITDA of not less than £15m (FY 20: £9.8m, FY 19: £15.2m).
Stockopedia has £112m consensus revenue forecast, so this is £3m ahead, +2.7% vs forecast.
Looking back at previous results, this is the trend for adj EBITDA, adj PBT, and adj EPS:
FY 12/2019: £15.2m adj EBITDA, £7.6m adj PBT, 2.81p adj EPS
FY 12/2020: £9.8m adj EBITDA, £6.1m adj PBT, 2.96p adj EPS
FY 12/2021: >£15.0m adj EBITDA (guidance given today)
That looks OK, with the company back to similar profitability as in 2019, pre-pandemic.
Dilution - the share count has remained roughly static over this period, at c.167m, so the EPS figures are comparable.
Looking at the progression of those numbers, it suggests to me that 12/2021 EPS should be nearer to 3.0p, than the 3.9p broker consensus shown on the StockReport, so a question mark hangs over that 3.9p forecast EPS. If that’s right, then the PER would be even higher, at over 40.
Outlook - it’s clear that this share is priced to assume considerable growth in earnings in future, which does make some sense as the economy returns to normal, which seems likely as things currently stand re covid.
Looking ahead, client contracts won in FY 21 have now been implemented and are expected to contribute to revenue growth in FY 22…
The Group has a focused strategy to invest into accelerating the scaling of Facilisgroup revenue alongside the continued attraction and retention of major contracts at Brand Addition. We remain confident in delivering upon our strategy and look forward to updating stakeholders further on the announcement of our FY 21 Final Results on 22 March 2022.
Cash - strong cash generation, with £12.1m net cash (excl. lease liabilities) at end Dec 2021. The last balance sheet looks OK.
My opinion - neutral. I don’t know enough about the company or its business model to form a view. Valuation looks too high to make me want to dig any deeper.
PEBB floated on AIM in late 2019.
.
.
Brighton Pier (LON:PIER)
81p (up 10%, at 11:00) - mkt cap £30m
Brighton Pier Group PLC, a diversified UK entertainment business…
The following sounds upbeat, but the last paragraph summarises it with only “comfortably in line with market expectations”.
… is pleased to announce a positive trading update for the 26-week period ended 26 December 2021. The period started strongly and the businesses have continued to deliver an extremely robust performance. Whilst there was some impact in December due to the restrictions, over New Year the bars recovered their momentum, trading 9 % up on 2019.
The Group expects total sales of £22.7 million, up 177% on the same period in 2020 and up 31% against the same (pre-Covid) period in 2019. On a divisional basis:
· Brighton Palace Pier like for like sales are up 15% on 2019
· The Golf Division's like for like sales are up 33% on 2019
· Bars like for like sales (for 23 weeks, division re-opened from end of July) are up 27% on 2019
· Lightwater Valley theme park acquired in June 2021 continues to trade ahead of expectations
Strong cash flow generation is expected to enable the Group to pay down £7.7 million of debt, reducing borrowings 38 % by the end of June 2022.
This represents an excellent performance during challenging times, underlining the attractions of a diversified asset base of experiential venues and bars well-positioned to benefit from growth in the UK entertainment sector. Management believe the Group is in a strong position to deliver a good result for the year, comfortably in line with market expectations.
Valuation - with so many moving parts (lockdowns, Govt support measures, etc) it’s very difficult to value retail/hospitality/leisure companies at the moment.
Cenkos to the rescue, who have kindly shared forecasts on Research Tree, showing 11.9p EPS for FY 06/2022. That should be a good time period, as it is post the early 2021 lockdown, and would benefit from very strong pent-up demand in the summer & autumn of 2021. Also some benefit from business rates relief, and possibly other taxpayer support measures?
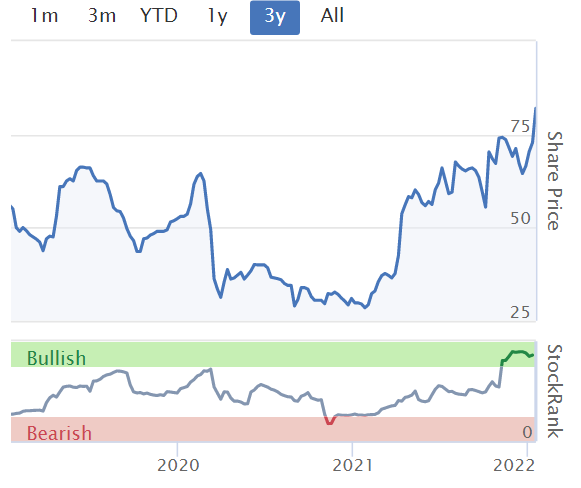
At 81p per share, assuming 11.9p forecast EPS is achieved, then I make that a PER of 6.8 - which looks an attractive valuation, if that level of earnings can be maintained or beaten long term.
Cenkos forecasts for the balance sheet & cashflow also show a reasonably attractive position.
My opinion - worth considering, because the valuation does look attractive. Cashflows, and substantial reduction in debt, are impressive, although its assets (especially the pier) could be a can of worms in terms of big maintenance capex. It's surveyed regularly, but there's always the risk of a bombshell repair bill with a large, old pier.
Although PIER is difficult to value, because pent up demand could wane over time, as people begin spending more money on going abroad?
On balance though, the numbers are looking a lot more attractive than I can remember in the past.
.
Access Intelligence (LON:ACC)
115p (down 25%, at 11:32) - mkt cap £147m
I’m not very familiar with this company, having mostly dismissed it in the past, due to being continuously loss-making, and expensive.
Access Intelligence (AIM: ACC), the technology innovator delivering Software-as-a-Service (SaaS) solutions for the global marketing and communications industries, announces an update on trading for the year ended 30 November 2021.
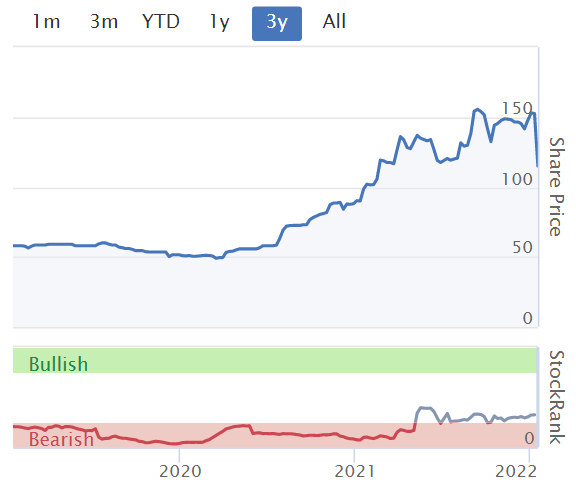
Finncap’s forecasts (revised today, down, a lot) show continued heavy losses, at the adj PBT level, of £(4.7)m for FY 11/2021, and £(6.3)m in FY 11/2022.
So why is it still valued at £147m?
I think this is a really bad time to be investing in loss-making jam tomorrow shares. These are the shares that have been savaged in price in US markets, and where the US goes, the UK tends to follow.
Hence I’m completely ignoring the commentary from the company, and just focusing on the forecast numbers.
This is not of any interest to me at all, and I imagine the shares could drop a lot further in a bearish market for jam tomorrow.
The interim results showed a balance sheet that has enough cash for now, but if it continues burning cash, that won't last forever.
I wonder if this will end up being a "Grand Old Duke of York" share, as Jack calls them - where it ends up back where it started? that looks quite likely to me, based on the poor fundamentals.
.
.
Jack’s section
Centralnic (LON:CNIC)
Share price: 141p (+8.88%)
Shares in issue: 251,160,084
Market cap: £354.1m
(I hold)
This is an internet platform company that derives recurring revenues selling online presence and marketing services. Cash conversion is regularly above 100%, the group knows how to make acquisitions, and its markets are growing. Possible legislation and technological disruption in these relatively new markets, but so far CentralNic has arguably been a beneficiary of such changes.
The group has two segments: online presence and online marketing. The former is to do with providing websites, security, and other services to customers looking to build an online presence, while the latter is connecting advertisers with websites. Both are in large and growing markets, although it is digital advertising that has the more exciting growth potential.
Management isn’t afraid to issue new shares in order to part-finance its growth strategy, so that’s something to keep an eye on.

The Company's organic growth has further accelerated during the fourth quarter of 2021, resulting in year-on-year organic revenue growth of 37% for the full year ended 31 December 2021
Full year revenue is now expected to be c$410m and adjusted EBITDA should be c$45m, both around 5% ahead of consensus estimates, and 70% and 47% ahead of FY20 figures respectively.
Cash has increased from $28.7m at the end of December to $55.6m and net debt has reduced over the same period from $85m to $76m despite spending c$19m in the year on four acquisitions (Safebrands, Wando, a Publishing Network, and NameAction). Adjusted operating cash conversion ‘continues to be well in excess of 100%’.
Ben Crawford, CEO, comments:
CentralNic's growth has continued its acceleration during the last quarter of the year with year-on-year organic growth now reaching a record 37%. The Company has comfortably exceeded the high end of market expectations for the year, which had already been revised upwards repeatedly over the course of the year.
Preliminary results will be published on the 28th of February.
Conclusion
It looks like CentralNic’s online marketing division continues to grow, with its pubTONIC product seeing a lot of demand. I’d like to see some more like-for-like figures, given the group has made four acquisitions in the past year, but perhaps more detail will be forthcoming in the preliminary results.
A risk in this area (as flagged above) is online privacy legislation issues but CentralNic has stated before that its business model does not rely on such methods, does not use cookies, and has not been affected by recent legislative changes. In fact, it appears to have benefitted as competitors adjust.
The same recurring revenue dynamic the group benefits from also means it can be hard to win new customers. But there are plenty more acquisition opportunities in the space, which could be a more effective way of adding scale. CentralNic has built up quite a strong acquisition track record in this regard.
The new chief technology officer is an experienced hire, so the management team has good experience and depth. Meanwhile its businesses have some attractive characteristics such as recurring revenue, strong cash conversion, and structural growth markets.
Net profits and margins have been volatile as the company has made acquisitions and changed shape, but we can see that operating cash flow per share has been steadily rising.

Adjusted EBITDA puts the group on an adjusted EV/EBITDA of roughly 11.6x despite delivering strong progress over the past year or so. I suspect this is less than its peers, particularly those listed in the US.
It’s a short update, with more to come on the 28th Feb, so I’ll leave it there for now. But this is a tech company on a relatively modest valuation that appears to have reached an inflection point recently, and continues to report strong trading momentum with large addressable markets to aim for. Worth keeping an eye on - management does a good job of presenting to the market via video, so you can find material on investormeetcompany.
Edit - meeting with management
I’ve just had a chat with CEO Ben Crawford, here’s a write up of the key points:
- The team appreciates the need to communicate with the market as it made quite a few acquisitions in its first few years, hence the videos explaining CentraNic’s journey so far. It’s the only company of its type listed in the UK, with the rest in the US.
- Online presence offers businesses the key services to get on the internet (web address, website, software). Online marketing connects advertisers to websites with advertising inventory.
- Both segments operate a ‘marketplace’ model (big believer in this model).
- Online Presence - CentralNic is higher up the supply chain than other web service providers like GoDaddy and Google. It is connected to country codes across the world and these are all integrated on its platform, which is quite a feat. It sells to c20,000 resellers including the biggest companies selling domain names. Reliable subscription revenue, one a year.
- Online Marketing - only three acquisitions made here so far, but ecommerce companies generated some $4 trillion in revenue last year with most of their customer acquisition coming via online marketing. More than $400bn spent here annually, growing at around 20% per annum. Reliable revenue but paid far more frequently than in Online Presence.
- Why the move into online marketing? Had been trying to buy the right online marketing company for a few years when they finally got the deal. It was the exact company they wanted. This business had some issues with the company that owned them, and was a fantastic purchase for CNIC. The group has spent $90m on acquiring companies in online marketing and has banked over $250m in revenues from them already.
- This is Ben Crawford’s third rollup (the other two were private). Strategy is to maintain discipline, buy at low multiples, and invest for growth, rather than buying high and seeking to strip out costs, which is what a lot of competitors do.
- CNIC has a couple of really great advantages re. M&A. It has a working business relationship with almost all of its acquired companies due to its position high up the supply chain. This provides an ‘incredibly handy’ perspective on the sector. CNIC sees who’s growing, and most people will take their calls.
- It has also developed a good reputation as an acquirer, and gets good prices on acquisitions by ensuring it is seen as the preferred partner for the business in question. So it leverages its market position and reputation, with minimal input from sell-side advisers etc.
- It has the tools to grow organically at above-market rates, but acquisitions will likely continue due to sticky customer bases. In the domain space, recurring revenue was around 85% of total across the industry last year. So existing customers paying existing service providers. Only around 2% of that cohort look to switch in any one year. So acquisition is the smartest play for scale.
- This is a very good industry for acquisitions as well - recurring revenue, stable customer numbers. They’re just websites automatically billing customers. Ben Crawford was involved in a Media rollup before - this is vastly different, as Media has key person risk (editors and the like).
- Cash conversion - good as it does not give credit to customers but receives it from suppliers.
H & T (LON:HAT)
Share price: 300p (+2.56%)
Shares in issue: 39,864,077
Market cap: £119.6m
H&T forever looks cheap despite good quality metrics. It’s had high StockRanks for nearly a decade now.

Yet there’s been precious little to show for it in terms of share price progress. Perhaps investors are just lukewarm on the company’s business model, which revolves around pawnbroking.

Trading performance during the second half remained consistently strong and the Group expects to report profit before tax for the full year within the range of current market expectations
Those expectations are for profit before tax of between £9m-£10.1m, which continues to suggest good value for a c£116m market cap. Particularly if business continues to recover in the year ahead.
Demand for pledge lending has now fully recovered to pre-pandemic levels, with particularly strong demand in November and December. As at the end of December, the pledge book had grown to £67m, an increase of 39% over the prior year and up 34% since June 2021.
Retail sales have been ‘robust’, up 21% overall at improved margins, with strong demand for high quality pre-owned watches and jewellery. H2 showed a ‘full recovery to pre-pandemic levels’.
Gold purchase and foreign exchange transaction volumes improved in the fourth quarter and were in line with management expectations, but remain below pre-pandemic levels. Money transfer and cheque cashing volumes were in line with management expectations.
The personal loan book continues to reduce with repayments, recoveries, and lower impairment charges more than offsetting new lending. It stood at £2.6m as at 31 December.
The following catches my eye and requires closer inspection:
The company continues to work closely with the FCA and the appointed skilled person in respect of a review of lending processes, creditworthiness and affordability assessments undertaken within the Group's unsecured high cost short term ("HCST") loans business. A methodology for conducting the required past book review has been developed in close collaboration with the skilled person. Following initial review by the FCA, "outcomes testing" was undertaken by the skilled person. This work is under review by the FCA, and a conclusion to their review is anticipated in the near term. H&T will update the market further as soon as it is able to do so.
Perhaps someone more familiar with the situation can enlighten us in the comments? It’s something I’d want to know much more about before investing.
Cash balance of £17m as at 31 December, along with £35m in undrawn funding facilities. Strong balance sheet. Preliminary results to be reported on the 8th of March.
Conclusion
Continues to look good value, in my opinion, trading at around tangible book value but with a solid history of profits and dividend payments behind it, as well as a leading position in the UK market.
The shares have struggled to appreciate in the past. If the market tends to afford this type of business a low multiple, I’m not sure why that would change going forward. Nevertheless an attractive blend of Quality and Value, with a 4%+ yield, a strong balance sheet, and established market position.

The review into the high cost short term loans business is news to me though and is something I want more clarity on before proceeding, just to be safe.
Edit - thanks to the user flagging a new broker note over on ResearchTree. Shore Capital says ‘We remain of the view that any fines, penalties or redress costs will be manageable in the context of the group’s financial resources and should not materially impact on the investment case.’ I’d take it with a pinch of salt, as that’s the house broker, and would like to have more of a handle on the full range of potential outcomes here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Happy with my Fulham Shore FUL shares. Nothing happening for now. I expect people going out more will happen despite the cost of living crisis. In fact, people might well choose a better value meal out like Franco Manca or Fat Greek. Hopefully, new openings will happen soon to coincide with the announcement of the end of all Covid rules after the school holidays as he announced today.
The experimental weekly summary is an excellent idea, and it would be great if you are able to continue it without pushing yourselves too hard. All your hard work and incisive comments are greatly appreciated by me and I am sure by most other readers. Just one small request: Like many others suffering colour blindness I have great difficulty distinguishing greens from reds so it would be very helpful if you could, say, switch from the green to, say a blue at the start of each company summary to highlight its performance..
Jack - thank you for your great and extensive write-up on Centralnic (LON:CNIC) which was extremely informative - especially following your chat with the CEO.
I can see this share having a lot further to go, if it continues to deliver and can avoid issuing more shares. I do hold and will be keeping a close eye to time a potential top-up.
All the best. K
Centralnic (LON:CNIC) has done very well but I would not anticipate much more in the way of multiple expansion from here if US valuations are a guide. Godaddy, which has much better cash generation and margins, is on the same p/fc. Meanwhile US adtech (TTD aside) is on very cheap multiples relative to the growth rates - just like CentralNic!
I’d look at is as a successful roll-up with room to run rather than offering intrinsic value - though I agree it can run further with good M&A.
Paul, For me the weekly, colour coded written summary is brilliant and will be fast to refer to in 3 months time. I suspect the video will take much more time for you and me!
But either is another brilliant service to us here on SCVR/Stockopedia - just don't burn yourself out. I need to read and enjoy your entertaining and informative blog every work day!
Nice update from Petrotal (LON:PTAL) which is starting to look a bit ludicrously cheap in my view.
Todays key takeaway for me was that they are doing 20,000 bopd of production and are finalising deal to extend Brazil export capability to 13,000 pobd. That massively mitigates reliance on the PetroPeru pipeline, which we have seen can be disrupted for political purposes by local communities even though they have very good relations with Petrotal (LON:PTAL) itself.
Petrotal (LON:PTAL) appear to have a good relationship in government as well so political risk appears to be well mitigated in general.
Couple that with an $85 oil price and looks to me like you will be able to buy Petrotal (LON:PTAL) at a negative EV within the next year.
Looking at Petrotal (LON:PTAL) it has some attractive metrics but unfortunately I don't have any spare cash at the moment. One to watch.
Agree. I'm a holder & very hopeful for a good year but I was a bit surprised when you said that they've got good relations with the local community as there were 3 locals shot dead during protests outside their facility last summer ! There's alot of location risk but dirt cheap on fundamentals.
Excellent weekly summary of the SCVR, so good work by yourself and Jack. Your website is also a very useful source of information for the PI so would definitely recommend readers to have a visit if they have not done so already..... both yourself and Jack's input to the SCVR much appreciated.
I had a serious look at Brighton Pier (LON:PIER) quite recently and then discovered that Luke Johnson was the Executive Chairman... I decided to wait for other opportunities..
What was the accepted outcome of Patisserie Valerie? That Luke Johnson was involved or knew and therefore culpable? Or was he in the dark, fooled and duped?
I believe there is a Serious Fraud Office investigation taking place wrt Patisserie Valerie. i do not know the detail of Luke Johnson's involvement but as he was a major shareholder I doubt he knew what was going on.
Paul & Jack -Firstly many thanks for your regularly impressive reports-they are the bedrock of my investment day! I think the podcast with the colour coded summary is an excellent addition which I would welcome . I have a feeling we are all going to need all the help we can get with the year ahead !!
Enjoyed the podcast fella's but would say just do it when you can be bothered rather than committing to it each week you both chuck out enough great info during the week and I'm sure when July/August gets here you would both rather be outside with a beer than going the extra mile.
In short its great but throw it out when you have the time and motivation.
Regards ANDY
Hi Andy,
Very kind, but recording an end of week podcast at 3pm on a Friday, when it's still fresh in my mind, took very little preparation, and we both enjoyed doing it. Typing up the colour-coded summary actually took the most time! But that was because we didn't make it clear enough in the audio whether each company was a meet, beat, or miss, so we'll try and sharpen up on that next time.
Also, we're looking into putting them onto podcast services, will keep you posted!
Judging from the comments, I think there's enough interest from members to continue with this idea.
Regards, Paul.
Hi Paul,
I found the colour coded summary very useful to quickly check if I missed anything during the week.
Hi Paul/Jack
Excellent idea re the podcast and extremely useful. This gets the thumbs up from me providing you both have the required time and you can remember the day of the week Paul!!!
Enjoyed the podcast, thanks Paul & Jack!
Here's today's googledoc, where Jack & I work out what to write about here, and it also shows you the things we didn't cover, and why. Just thought this might be useful to you.
Looks like you covered DP Poland prettty effectively in 2 words! Almost made Mr C look wordy :-)
It amazes me that after so many years of trying, the BOD for Dp Poland (LON:DPP) can't get something as tried and tested, straightforward as rolling out a franchise network and at least squeaking out some profits. They should all be banned from taking any future directorships.
Distil - small/illiquid - lol
WAG Payment Solutions - maybe footballer are looking to improve their financial liabilities
CentralNic - is that a govt thing
Hostmore - sure they would like to
Sorry thought Russia invading Ukraine was smoke and mirrors - Ferrexpo (LON:FXPO) - but who said invest when there is blood on the street - a bit too pertinent even for me
Volex (LON:VLX) looked like some electrons working today but nope, the fuse burst again.
GarryC don't understand your fuse burst again comment re Volex (LON:VLX) - intraday looks OK to me:
Sorry I'm not a day-trader but do look at the daily/hourly when mine are in trouble - and have the time for screen watching.
The trend is your friend.
Trying to find a base support to top up but todays 'doji' is not that day. I will want a strong move up above 350 and then think about it. Not a 'system' (sorry Roland) can't help myself - too much - er - fun.
The big Question is why has this been marked down so badly. I don't have the time for DYOR so use Stock for that. It seems more than a 'tree shake' - weak hands are long gone, leaving us 'believers'. But maybe the days of PER are upon us.
Sorry the above a daily chart my bad. Weekly chart. This cannot be normal otherwise will sell up tomorrow and do something else - maybe repair my roof. MACD close to a weak base so the risker among us - back up the truck - lets go. Not quite yet IMO. Volume not high so there is something going on.
As far as Volex (LON:VLX) are concerned, I think that a number of basically sound shares have taken unjustifiably large falls recently. Today Sanderson Design (LON:SDG) rose 22% on a good but hardly outstanding trading statement after a long period of falling on no news. I am hoping that Volex (LON:VLX) will follow the same path.
Brighton Pier (LON:PIER) Paul, your warning about Brighton Pier possibly having big maintenance charges is spot on; it's like a dodgy used car, bright an shiny on top but a rust bucket underneath. I'd avoid Brighton Pier (LON:PIER) as it will cost millions to put it right / repair / replace.
Like the podcast Paul.
Loved the Friday podcast, both content and format. Please do continue as a regular weekly summary if not too onerous for you guys.
I wouldn't be surprised if the ghost of Cattels was in part not behind the lacklustre share price. I seem to recall that HAT bought a significant number of High street units just before the Covid outbreak which must have been pretty painful for the group. Personally, I think HAT is a fairly conservative in its financials and should be a good anchor in a portfolio in the event of a significant down-turn,. Also we have not felt the effects of massive fuel price and tax hikes yet on peoples finances and unfortunately HAT should be a beneficiary of that. Meanwhile the Div is better than money in the bank.
I seem to think as things normalize all of these units they took on should in theory lead to much higher profit as an whole than they experienced prior to COVID. I do think a resolution of the investigation and the flow through of normality and the extra unit should eventually see this being re-rated. Again I never expect this to double or triple but there's long term upside for the patient ones. (I am obviously long)
Hi Will :
£HAT...and also the ghost of (ex) fellow pawnbroker Albermarle and Bond (ABM). Agree a steady company, with a reasonable dividend - a bit like Unilever ? - both unlikely to shoot the lights out, but both sensible holds IMHO.
Regards
Geoff
Buy and Hold H & T (LON:HAT) and maybe not? I hold having bought in at around 320 pence and earning me a 1.25% dividend now and when equilibrium is reached I shall be gone. It all depends on what happens to the SP after buying.
I have held H & T (LON:HAT) on and off for about 5 years, it's ok, dividend can be good but I feel a bit of a value trap, kicking myself for not selling out, last year when it was around 325p. I suppose I'm a stale bull, looking to sell around 320p also. As soon as I sell it will shoot up to around 370p, no doubt.
Yes I think H & T (LON:HAT) is a nice counter cyclical play if we do see a big downturn or a cost in living crisis. Similar to Begbies Traynor (LON:BEG) in that respect.
Great Podcast Paul. I think its a great idea and a useful summary
I didn't know you had your own website - but its now bookmarked
As ever, your Stocko commentary and analysis is my daily morning read - invaluable.
thank you
H & T (LON:HAT) Hi Jack, SCVR has commented on H&Ts ongoing FCA investigation previously. This review has been rumbling on for a couple of years now and the FCA would have been much more vociferous has the issue, if any, been significant in my view. I recall the revenue from HCST business amounted to only about 4% of H&Ts revenue, so hopefully, any fine will be proportionate and manageable from existing cash. I’m not concerned about this review but I do wish both parties would finally get it concluded. I hold but unless the share price does move over the course of this year I do fear I will lose patience as the dividend is not sufficient compensation for the lack of growth.
H & T (LON:HAT)
SCVR has commented on H&Ts ongoing FCA investigation previously.
Must admit i have parked this on a list not to invest in while the FCA are still twiddling their thumbs "monitoring" the company - based on todays news sounds like it's a bit of dumber and dumber whats going on here with regard to ending the active whatevers in that regard completely. If i held i don't think i would necessarily have sold based on fca stuff but with plenty of alternative other options to deploy new funds why take the risk - albeit i am guessing shareprice could easily be marked down 10/15% at present in that regard so thats not to say now isnt the best time to be adding. I would like to think the fact they are twiddling their thumbs suggests there isnt any specific reason to over worry.
Good morning Paul and Jack and great idea with weekly podcast.
It is ideal for people who perhaps don't get chance to view on a daily basis, and also you can listen to it whilst working or whatever.
But please try and wind down for the weekend, you both do so much as it is, which we do appreciate.
As always some interesting commentary on inflation and positioning from Ruffer Ruffer Investment (LON:RICA) in their six month review to end of Dec21:
http://www.rns-pdf.londonstock...
Thank you Paul and Jack for the new weekly Podcast.
A good idea as it is possible to miss a Company during the week especially a very busy reporting week.
I found it best not to dip in and out but to listen to the full Podcast.
A brief weekly summary is a great idea but I'm not enamoured by the idea of a podcast. Print is so much easier to scan and digest and you can pause whenever and wherever you want. And I've yet to find a way of speeding up the playback of a podcast; something I do all the time with YouTube videos.
Most podcast apps have playback speed adjusters - Overcast and Pocket Casts certainly do.
Yep, the Apple iOS podcast app has settings to play back from half speed up to double speed. It's on the bottom left below the play/pause button. It shows 1x by default.
Same function on the Android Podcast app.
Love the podcast round up of the week Paul and Jack, please keep it going guys, very useful format and easy to listen to during the day.
Dear Paul
I don’t know whether you will have time this morning to cover a trading update from H&T (LON:HAT), but Shore Capital has just been appointed house broker and a research note on the company is available on the ResearchTree website. I hold.
Kind regards
Phillip
Thank you both for the podcast -Found it useful and would look forward to more if they continue Thanks again
Angle (LON:AGL)
…….. announce the publication of breakthrough research undertaken by
the world-class team at the University of Southern California Norris Cancer
Center. The research demonstrates the potential of circulating tumour cells
(CTCs) harvested from a simple blood draw using the Company's Parsortix(®)
system to be used as an alternative to invasive metastatic tissue biopsy for
metastatic breast cancer (MBC) patients.
In the United States, guidelines published by the National Comprehensive
Cancer Network (NCCN) recommend a tissue biopsy of a secondary cancer site in
MBC because of the critical need for up-to-date information on cancer
progression to guide treatment decisions. However, over 50% of all MBC
patients do not have a successful metastatic tissue biopsy because they are
either too ill for the invasive procedure, the cancer site is inaccessible
and/or insufficient tissue is available. Hence, there is nothing to guide
ongoing treatment decisions in these patients. Even in those patients who can
undergo a metastatic tissue biopsy, there is rarely the option for a second
such biopsy, yet the cancer continues to evolve, often to multiple sites. A
simple, repeatable liquid biopsy alternative using the Parsortix system could
resolve the issues with metastatic tissue biopsies and, as the study finds,
provide real time information on the cancer evolution to guide treatment
options.
https://www.stockopedia.com/share-prices/angle-LON:AGL/news/rcs-angle-plc-concordance-of-parsortix-with-tissue-biopsy-urn:newsml:reuters.com:20220117:nRSQ5460Ya
Really is time the FDA got their act together.
Agreed. Expecting a big pop when it does.
Great podcast, thanks for doing. A definite vote more more!
£POLB
promising news this morning
Poolbeg Pharma licences first-in-class broad spectrum RNA-based immunotherapy
for respiratory virus infections from the University of Warwick
I like the weekend summary which will fit in well before I turn to the football and maybe a horse or two. My original home town was Kidderminster now the lowest ranked team in the 4th round of the F.A cup and reasonably placed in their league, They play at home against West Ham on the 5th of February, the match being televised at 12 .30pm. Worth a small bet ?????
Good podcast and good idea. I would like to see this continue. thanks Paul and Jack.
H & T (LON:HAT) published a trading update this morning that was short on numbers but included enough comparables to show everything seems to be back on track or on the route to be back. As a "not loved" business its constantly trading at very low PE levels and should at some point re-rate (but never seems too.)
I do think some day this will get swallowed by the one of the Private equity companies, until then I will continue to be patient.
What do you think of the potential FCA fine for H & T (LON:HAT) at the end of the review process, for their legacy loans business?
Its a small part of their business and at worst they'll get fined a few million. Its a one off event and shouldn't impact the continuity of the business or their ability to continue t generate reasonable profit over time.
Surely the big issue isn't likely to be the fine, but any remediation payments required to customers or ex-customers.
I've just had a look through the trading update from H & T (LON:HAT) , but am very puzzled. I seem to come to the conclusion while "trading" and therefore revenues have improved in H2 vs H1, it seems like PBT has stood still.
H1 did £4.7m PBT, and H2 looks like.... £4.3m to £5.3m, with midpoint of £4.75m. Seems disappointing? Then I realised nowhere in the trading update was there mention of margins, except for "retail sales".
So could one conclude that they have been busier in H2, but making less margin. In which case, are the broker forecasts for a jump from 19.5p EPS to 33p EPS from FY21 to FY22 sensible? After all, H2 did £4.75m PBT (and c12p EPS), and H2 is meant to be the seasonally stronger half of the year too, for earnings.
I note that Shore Capital has not updated FY22 EPS forecast, waiting to do so in March. But they did re-state, as did the CEO in his statement, that they are cautious about inflationary pressures. Maybe a veiled caveat/asterisk to what will be disappointing margin numbers published at the time of FY results, and a FY22 EPS downgrade from 33p to circa 20-25p?
Thanks Paul - Excellent stuff on the podcast and the helpful colour coded blog post - Much appreciated from here
Excellent podcast, so thumbs up from me, and thanks in advance for your thoughts on £HOST , think I'm on safe ground with that assumption.
Hostmore (LON:MORE) even, maybe not as safe as I thought I was - doh
Yup, I'm looking at Hostmore (LON:MORE) (I hold) as we speak...
… pleased to report that the trading for the month of December 2021 was ahead of early-month expectations.
I read this as a comment on the uncertainty posed by the emergence and restrictions around Omicron in Early December
Looks like a decent update, I sold after a shocking experience at their Cribbs Causeway restaurant in Bristol during November and looking at Trip Advisor not much has changed. Considering they are effectively upgrading expectations I wonder just how good it could be if they can sort out the poor experience being reported (they do say experience scores are improving).
might consider dipping my toe here again in future.