Small Cap Value Report (Mon 18 Dec 2023) - BOWL, KWS

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Hollywood Bowl (LON:BOWL) - Up 1% to 285p (at 08:28) £490m - Final Results FY 9/2023 - Paul - GREEN
FY 9/2023 results look in line with forecasts that were raised several times in 2023. This is a lovely cash generative business, with little working capital required, so it's sitting on a decent cash pile of £53m that's now earning interest income. I can't fault this share, still reasonably priced too.
Keywords Studios (LON:KWS) - up 2% to £14.45p (£1.14bn) - Acquisition - Graham - AMBER
This support services provider to the video game industry saw its share price double during the Covid boom. Having now returned closer to our normal market cap territory, today’s £76.5m acquisition sounds promising. KWS may possibly have grown into this market cap.
Paul’s Section:
Hollywood Bowl (LON:BOWL)
Up 1% to 285p (at 08:28) £490m - Final Results FY 9/2023 - Paul - GREEN
Hollywood Bowl Group plc, the UK and Canada's largest ten-pin bowling operator, announces its audited results for the year ended 30 September 2023 ("FY2023").
EXCELLENT PERFORMANCE DRIVEN BY STRONG CUSTOMER DEMAND
AND THE SUCCESS OF THE GROUP'S FOCUSED INVESTMENT STRATEGY
These results look good to me, after allowing for the one-off boost which last year enjoyed from VAT relief (a pandemic support measure).
Revenue £215.1m (mostly UK £192.6m, plus Canada £22.5m)
LFL revenues (excl new site openings) up 4.5% - not bad, but behind inflation.
Group adj PBT £47.8m is actually down £0.9m on FY 9/2022, but that is distorted by a one-off VAT gain last year of £8.6m.
Stripping out last year’s VAT boost, results in £47.8m vs £39.9m LY adj PBT, a healthy progression of +20% in profitability - I think this is a fair adjustment, showing us the underlying improvement.
Commentary says performance exceeded management expectations, but it’s only slightly above market expectations, adj EPS actual of 21.48p vs broker consensus of 21.4p. Note that broker forecasts have been raised during 2023, so this looks healthy to me, given tough macro -
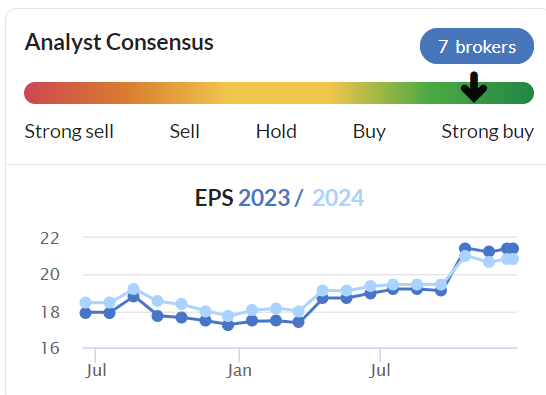
PER is 13.2x based on Friday’s closing price of 283p - hardly demanding, still good value I’d say, even after a strong recent run upwards in share price.
Total divis (incl. a special) of 14.54p, that’s a 5.1% yield (incl special)
Share buyback of £10m announced.
Adjustments to profit boost it by £2.7m, but do look reasonable to me - relating to the Canada acquisition costs & adj to consideration, so I think it’s fine to strip those costs out to show the underlying trading.
Note that interest earned on cash is £1.4m vs negligible last year, a nice boost there.
Finance expense of £10.4m nearly all relates to leases under the rubbish IFRS 16 rules. I’m pleased to see that BOWL says it will keep reporting pre-IFRS 16 EBITDA, as that’s what investors (and banks) want.
Outlook - encouraging start to the new year, it says, but no detail provided.
Balance sheet - actually isn’t as strong as I was expecting, with a relatively modest £59m of NTAV, after I write off £89m of goodwill.
This is absolutely fine though, because BOWL hardly has any inventories or receivables, which means almost all the NTAV is net cash of £52.5m.
Property is nearly all leased, with large lease entries on the balance sheet, showing a deficit of £43m - which suggests it might have some under-performing sites? That is also possibly why there were some write-offs against fixed assets both this year and last? Something to ask management if you speak to them, or on a webinar, if they’re doing one?
Cashflow statement - is smashing, this is a reliable cash generative business. It generates a lot of cash, which not only funds hefty capex (c.£22m pa) plus acquisitions, and generous divis, all from internal cashflow - no borrowings required. It has a £25m unused bank facility.
Paul’s opinion - a really impressive business, no doubt about that. Its listed competitor TEG was recently bought out by a US investor, for around the same earnings multiple as BOWL currently sits on. So I wonder if it might also become a bid target?
It’s difficult to see much, if any downside risk with BOWL.
All I can think of is that gross margin is very high (since the bowling alley revenue has no direct cost of sales), which means profit is highly geared to a downturn in demand. Although given that BOWL seems to have ridden out the cost of living crisis with aplomb, there doesn’t seem any sign of that happening. I like that BOWL says it’s keeping prices competitive, with some food items not having increased since 2019. We could even see geared upside to profit from a consumer recovery in 2024, now that wages are rising faster than inflation, and the 2% NIC cut kicks in from Jan 2024.
All in all, this looks a very good business to me, at a reasonable price, so it has to be GREEN again.
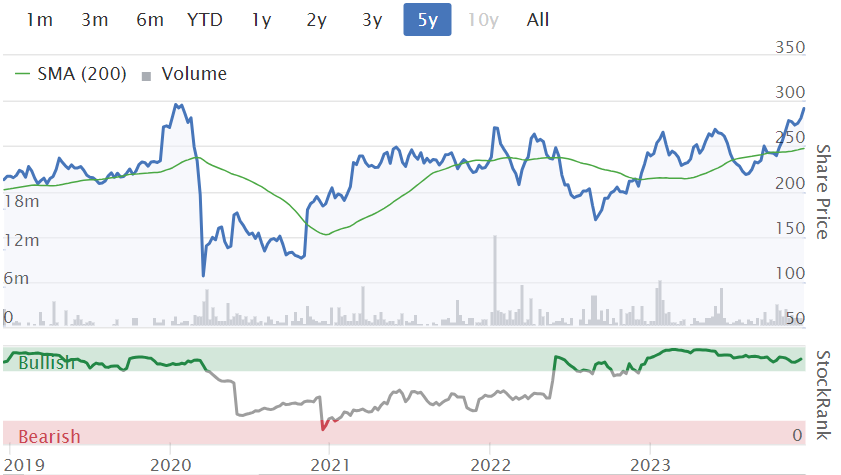
It's really surprising that the share price has almost gone nowhere in 5 years - given that the business and profits have roughly doubled over this period below.
Graham’s Section:
Keywords Studios (LON:KWS)
Share price: £14.45 (+2%)
Market cap: £1.14 billion
This is one of the top 10 AIM stocks by market cap (source) and is strictly speaking beyond our market cap limit. Let’s take a little look at today’s news:
Keywords Studios, the international provider of creative and technology-enabled solutions to the global video games and entertainment industries, is delighted to announce that it has acquired The Multiplayer Group Ltd, a multiplayer focused game development studio headquartered in Nottingham, UK, for £76.5 million.
The current owner of The Multiplayer Group (“MPG”) bought it in 2019, for an undisclosed sum. It’s interesting to see it changing hands again, a little over four years later.
Keywords has a long history of acquisitions in the field of video games support services, and MPG is a co-developer or fully outsourced developer for some of the largest studios in the world. So they appear to be a good match for each other.
MPG’s management team will remain in place and take part in an incentive plan based on targets over the next two years.
Payment: this is a cash purchase.
At its most recent interim results, Keywords had net debt of €11m, very small versus adjusted operating profits for the six-month period of nearly €60m. So it looks like they should be comfortably able to afford this c. €90m acquisition.
Some more info on the financial consequences of the deal:
The business has a strong pipeline of work and is expected to deliver double-digit percentage revenue growth in 2024, with margins in line with those of Keywords' Create division. The transaction is expected to be EPS accretive in its first full year post acquisition and fall within the Group's targeted valuation range of five to seven times EBITDA.
Keywords was already forecast to generate double digit revenue growth in 2024, so I’m not expecting any major change in the revenue growth profile from this acquisition..
The first full year post acquisition is FY December 2024, so MPG should boost EPS next year.
Valuation of 5-7x EBITDA is probably a fair price.
Graham’s view
This seems to be a nice deal for Keywords, with an acquisition that should fit in and hopefully make a meaningful contribution to the group.
Checking the archives (e.g. here and here in April 2019), I previously thought that it might be difficult to justify the valuation of Keywords at £13-£15. This was pre-Covid.
The Covid boom then doubled the company’s share price, but it has since come back to earth. There has been some inflation of the share count over this time. Here’s the 5-year chart:
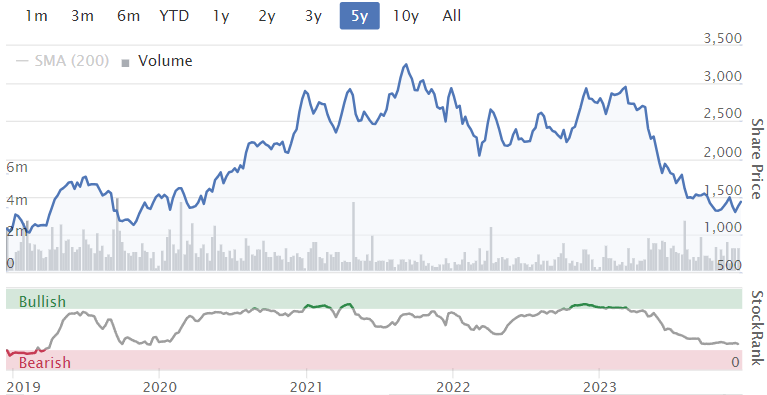
Nearly five years later, the company has grown very well over this timeframe, and has arguably grown into its valuation:
So I’m open to the idea that this could be a more attractive purchase now than it was pre-Covid.
The H1 accounts were a little disappointing to my eyes: free cash flow in H1 was only €11m.
I’ll keep a neutral stance on this share for now but remind me to keep an eye out for its 2023 full-year results. The accounts are likely to be adjustment-heavy but strong full-year cash flows could justify a more bullish stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Zotefoams (LON:ZTF) (I hold) Article re the JV with Nike in Times this afternoon https://www.thetimes.co.uk/art...
The Times is a Paywall and Im not yet woke enough to subscribe.
It's foam, spongy stuff, probably made in China for many markets, but has some moat? other than a snake oil marketing executive. So Sketchers, Clarks, Adidas, Ineos etc are rubbish?
Dr Martens have a differentiator -air soles and oil//chemical resistant and some kudos.
Sorry - for me this is now a harder more cynical market than 2020. Been mugged and will try not to be mugged again. Milk packaging - really!
The foam is better than the competitors you mention. No marathon records have been set in a pair of Dr Martens.
Look at the web site !
Rua Life Sciences (LON:RUA) have announced its interim results ending 30 September 2023 and together with the previous trading update, strategy update and fundraising announcement, there were few surprises. With the fundraising completed our model indicates a pathway to profitability and we publish our nearer-term financial forecasts out to YE 2025. Following on from RUA’s strategy update, we have also adjusted our valuation.
In addition to the product valuation changes reflecting RUA’s strategy update, we have incorporated the cash raised and the shares issuance into our valuation. As a result, our fair value has changed from £120.3m or 542p per share to £65.5m or 106p per share.
https://www.equitydevelopment.co.uk/research/review-of-interims-issue-and-strategic-update
Not small-cap but a possible merger of Londonmetric Property (LON:LMP) with LXi REIT (LON:LXI) has just been announced - continuing evidence that consolidation in the REIT space is still very much on the agenda.
Clinton Cards is now Esquire Retail Limited. Its accounts are overdue and it is going through a creditors restructuring plan to avoid another administration. Its on its last legs really and not really comparable with Card Factory (LON:CARD) which has abouut 25% market share and is the no. 1 player off-line. I do remember when Clinton Cards was a very profitable listed company and audited by PwC. Card Factory and supermarkets destroyed their ability to make profits,
I bought some pans from PROCOOK (LON:PROC) recently. Very fast delivery. It actually arrived the next day. I received an email offering 15% off for any friends that are interested. Here’s the link if you want 15% off.
https://t.mention-me.email/lnk...
Revolution Bars (LON:RBG) Eldose Babu up to 15% ownership now.
http://newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20231218:nRSR1718Xa&default-theme=true
For the first time in over a year there has been a director buy in Diploma (LON:DPLM) at just > £135k, so not quite small change. Should we read into this?
I am a holder of Diploma and recognise their diversity, successful strategy and long term success. If I held my original purchase c. 12 years ago it would have been a 10 bagger+. Sadly back then I used automated stock losses and was wiped out by general market movements. I have been solidly back in since 2018 and this is my 4th largest shareholding.
For the first time in over a year there has been a director buy in Diploma(LON:DPLM) at just > £135k, so not quite small change. Should we read into this?
And by the CFO - which counts double. They’re always much more cautious (and less wealthy as a consequence) than founders. I bought this near the pandemic lows in a rare well-timed purchase. What a great company!
Yes, a great business.
However they now hold their AGM at 9am in The City which is clearly inconvenient for many. Once upon a time it was a more accessible 11am. I did write to the chairman last year to complain; got a very polite response but no change…..
In relation to Diploma (LON:DPLM) wildshot, I noticed that the shares were purchased from his bonus and equivalent to 50% of same so FD not exactly short of a bob or two. (if I have read this correctly) but still meaningful.
"The shares were acquired with an amount equal to 50% of Chris' annual bonus,
net of tax thereon, which was awarded for FY2023. These shares will be held
by the Diploma Employee Benefit Trust on behalf of Chris in accordance with
the Company's Shareholding Policy."
Just back from Lancaster and I noticed a stark difference between Card Factory (LON:CARD) shop which was busy and clintons. Both within 50 yards of each other. Shoezone had no customers in it.
I don't know how Clintons survive.
Shoezone often seem quite, maybe doing more online now, they keep sending me emails about free next day delivery and sale prices.
I’m not sure Clintons will survive.
Believe Clintons went into administration in 2012 and 2019. Not looking good now.
Not very inviting the picture of Clintons and also with the limited range and comparitely expensive. Been adding to position in Card Factory (LON:CARD) under 100p. Outlets seem consistently busy, cheap and cheerful products seem popular, personal observation. Higher sales with the costs of low floor space leading to increased profits, hoping.
I don't see how Clintons, can compete with Card Factory (LON:CARD), the only issue I have as a shareholder is, they maybe too cheap, you can buy 10 cards for £1. The town centre shops are very busy, but the out of town ones are much quieter. I one I visit, there is hardly anyone in there. I think they should have larger shops in the town centres, you can't walk round in some.
I don't understand why Card Factory (LON:CARD) is doing well. Posting cards is a dying fashion. Is it some sort of long slow dead cat bounce?? It should be about as appealing as @Royal Mail or whatever it's called now.
Cards are nothing like a dying fashion and these guys do it well.
Most cards, I don't post. Postage is so expensive now. 125p for first class. Nearly all my Christmas cards are hand delivered, to and from locals, only a few to/from my family by post.
They are expanding abroad. They also sell other products such as balloons and gifts. Their online card sales are weak, think they could improve that.
RBG Holdings (LON:RBGP) continues to tumble following this morning's trading update. Wondering if worth a punt, but high debt probably makes it too risky. The other big problem is partner compensation - they used to pay some of this with shares but as these are now nearly worthless they'll have to either pay more in cash or suffer a lot of dilution - either way this will surely hit profits.
RBG
Have to say it’s pretty hard to feel sorry for the poor partners with their worthless shares
The partners and management were happy to load themselves up at the seeming expense of shareholders
The correct response should be for those partners to prove themselves and work their backsides off for the benefit of themselves and shareholders to rebuild the value
What I fear will happen is yet more shares but at lower strike price however maybe the new management can tell them the gravy train has left the station
Cometh the hour cometh the man .
TIme for the remaining partners to dig deep and rescue the situation.
RBG had a disgraceful senior team, absolute total did grace let’s hope the incumbents get on with the job and don’t make the job one of self enrichment
I remember highlighting the huge zero value FD options given only to be told on here “that’s the way it is “
Anyway hopefully the dogshit management are long gone .
RBG - Could not agree more planetx
Hi Paul. Sorry to hear of your personal issues last weekend but thanks for catching up on the missed podcast. I’m thinking the unscheduled wind reflux must be due to the chocolate hobnobs you’re having alongside your “tea”! Keep up the good work, there are some exciting prospects building for 2024!
Scattergun Opening Positions
On the basis that we appear to be at the start of a possible uptrend decided to adopt a bit of a scattergun opening position tactic on a relatively broad of 8 turnarounds / bid prospects that have been following recently .
No huge convictions on these yet but I find once invested your focus and interest is magnified and you build up more understanding out of which you can increase conviction .
Probably Saatchi , Speedy Hire, and Team 17 are my favourites .
I tend to lose interest with watch lists much better to have a small interest then build .
M C Saatchi
Speedy Hire
Team 17
RM
Centaur
Gooch
James Fisher
Assetco
Increased again on
Transense
Comptoir
MS I (just waiting for 890!)
I’m hoping equals or vertu gets bought out soon so I can play a bit more .
M&C Saatchi (LON:SAA) could be interesting. New CEO who is very focussed on the numbers and chopping out dead wood from the business.
Interesting as you say iamflimflam1 but they need to be careful not to alienate the talent with too much fiscal control. The talent is fickle and they drive the income. M&C Saatchi (LON:SAA) I hold.
Plexus Holdings (LON:POS)
http://newsfile.refinitiv.com/...
sale of non - core asset adds another £300k to the coffers / and pays off a £700k loan
Incanthera (OFEX:INC) - An amazing product commercialisation deal announced today and a placing made at a premium, yet no impact on the share price today. I expected a big SP rise today on this news, but nothing. What am I missing?
It sounds interesting Poker but still loss-making and speculative, it could explode higher or collapse like so many OPEX companies.
On the investment trust side GCP Asset Backed Income Fund (LON:GABI) worth considering. It is a fund that invests in asset backed loans which announced this morning that it has had one of the bigger loans redeemed, allowing it to pay off its facility and it is now debt free. At around a 35% discount to NAV, yielding around 10% and likely looking to wind itself up. If it does, that would be around a 50% return if it could shift the loans at NAV, but if interest rates start to come down, could be even higher. There are a few problem loans iirc but they are accounted for in the NAV.
I have just found out that abrdn Diversified Income and Growth (LON:ADIG) , which announced recently it was being wound up, has been selling GCP Asset Backed Income Fund (LON:GABI) aggressively for months but has now cleared its position. So there looks like a combination of an undervalued asset and a forced seller creating a bargain for the opportunist.
Looks interesting and will try to take a closer look - there quite few ITs on big discounts that are now being wound up. For GCP Asset Backed Income Fund (LON:GABI) presumably the loans will continue to generate an income until they either mature or are sold, so you should have a double whammy of the discount moving to par plus a nice income stream while you wait.
GCP Asset Backed Income Fund (LON:GABI) after what Arix Bioscience (LON:ARIX) did following a strategic review I will avoid. I see they had an approach "On 6 October 2023, the Board received a non-binding proposal from a US-listed investment company (the "Possible Offeror") to acquire the entire issued share capital of the Company. The proposal comprised a cash offer at a level of 68 pence per share in the Company, paired with an alternative pursuant to which shareholders could elect to receive US listed shares in the Possible Offeror for each share held in the Company, with an exchange ratio to be set at a point prior to any firm offer announcement to equate to a value of 76 pence per share. The proposal was unanimously rejected by the Board, following which on 27 November 2023 a second conditional and non-binding proposal comprising a cash offer at a level of 72 pence per share in the Company, paired with a share alternative offer at a level of 78 pence per share was received. The Board agreed to provide the Possible Offeror access to confirmatory due diligence. Prior to accessing such information, on 11 December 2023 the Possible Offeror notified the Company that it would be withdrawing its proposal"
I was a director on GCP Infrastructure Investments (LON:GCP) and can say that Gravis are an honourable bunch. They wanted to link GABI with GCP, but the shareholders of GABI pushed back, and so Gravis relented. They won't do anything without the support of the shareholders imo. Now they have no debt it should become much more attractive. As much as anything else they can start aggressively buying back shares, as there is no way they will be able to lend on better terms than those achieved by buybacks.
Thanks for your posts on GCP Asset Backed Income Fund (LON:GABI) today Donald pond. I can’t fathom why there’s apparently a persistent seller. Not as convinced are you are about the wisdom of aggressively buying back their shares. The theory on that is SO convincing but Trusts that have bought back heavily this year have too often seen the discount to NAV widen even further. So what did those buybacks e. g over £1 billion spent on them by Pershing Square Holdings (LON:PSH) and discount STILL over 30%, achieve?
I agree Ken in general, but buybacks do work when a trust is in wind down mode. If there are £100m assets and 100m shares trading at 70p, and you can buy back say 20m shares during the winding up period, you are left with £86m for the remaining 80m shares, so you have added around 8% to NAV. It is better at improving the NAV than the discount though
IG group (LON:IGG) are at it again, about 25% of the stocks on my watchlist, are telephone dealing only, these maybe all AlM market, not sure. This has been happening a lot over the last 2 weeks.
I could be wrong but I think that tends to happen during the auction periods. Liquidity in general pretty poor in the UK market of course.
Has been most of the morning, has been a regular occurrence in the last 2 weeks.
This is still happening, it is not shown on the watchlist now, but if you go into the share to trade, says no online market. It is annoying as looking to trade some.
Was like that earlier this morning then went back to be able to trade online again via the app
They are back now but only in the last 10 mins or so. I don't use the App very much.
An excellent write up on Hollywood Bowl (LON:BOWL) above, so not sure I'll be adding much but may as well post it. Not bad results against a tough comparison last year. I automatically mark red if it's down on previous year.
A couple of points to add to Pauls commentary. They say they saw a boost from the wet weather this year. If it's dry next year will this cause an issue?
They are switching all their centres to 'pins on strings'. I'm not a bowler, haven't been bowling in years, but looking at some message boards 'proper' bowlers, who play in leagues etc, appear to dislike these types of pins. I don't know how much of an issue this is in the UK as we're not like the US scene, though maybe there is a possibility of losing regular players. Apparently scoring on average is 7% worse from good players with this system. Though this stat is just plucked from the internet, so I have no idea if there's any real evidence behind it. Any bowlers out there who could comment?
Hi Paul and Phil P.
Thank you both for comments on Hollywood Bowl (LON:BOWL) . Paul mentions the apparently high CapEx spend and I wonder if anyone knows if this is mandatory or recurring in some way? If related significantly to the 'pins on strings' programme then we might see a nice drop now that 83% of estate completed?
Cheers
Mark
Hi - are you looking at Invinity Energy? Update to day with revenue broadly in line, but increasing order book for its Mistral storage system and seems to be moving from 10ish MWH systems to 200+MWH systems. On my list for next year!
I took an opening position. I see this as an essential strategic solution for energy transition.
Although I have stated that I will not post here again , I do feel that I have to sometimes after I have read this about Invinity Energy Systems (LON:IES)
This is a serial missing forecasts loss making company that is burning cash all the time and will definitely need a fundraise in 2024.
There was an unsuccessful attempt this year to drive the price above 50p in order for its warrants to be exercised.
Have a nice Christmas everyone!
Yiannos1! Good to hear from you, even if it is only occasionally.
Yes, they even say in the update this morning that "the Company currently anticipates having sufficient cash resources into H2 2024", and that they are in discussions with several 'strategic partners'.
So expect a decent equity raise at some point early next year.
Cheers
Chris
A raise to fund growth? Fine by me. The future is unwritten.
A position I took moths ago btw, so underwater as is, but happy to hold and wait.
Months obv.
You should continue posting Yiannos, the investment substance is invariably worthy of reflection by fellow readers
Definitely agree with yiannos1...
A £50m market cap company trying to make it big in the battery energy storage space? Hah!
Either it will be outmuscled and go to zero.
Or Invinity Energy Systems (LON:IES) will need to raise much, much more money. Guess the dilution to existing shareholders... especially small, minority shareholders who will never get access to the heavily discounted fundraising bookbuilds. Or get the nice big fat chunk of free warrants with their new shares.
James Cropper (LON:CRPR) While there is no news here today I thought I'd mention a bit about this company. I do not hold. It is a local company to me, so now and again I hear a bit from people who work here. Last week I gave a lift to a few employees and listened into their conversation. One person was an American and another was European and the other 2 were English. They all sounded extremely bullish about the company for the future and in particular the Advance Materials side of the business. They expect this side of the business to overtake the paper side in the next year or two. The Advanced materials has a higher profit margin than the paper side and it very interesting. It came about by an employees idea of making products using the process of paper but with made made fibres. This produced a material that was extremely light in weight but very strong. So strong in fact it has been used in military and airplanes.
While the sp has dropped off considerably over the last few years I'm not sure if the bottom has been hit yet or not. Possibly a bit lower? I'm looking for a dip lower over time to around 450p to 500p. I could be wrong and it doesn't go lower, but it certainly is one to have on a watch list imo.
James Cropper (LON:CRPR)
Cheers gmtrader.
Sounds really interesting. Will have to do some research over the festive period.
RE: James Cropper (LON:CRPR) It does sounds very interesting doesn't it. Cheers GM Trader.
The Advanced Materials division relating to hydrogen is the sort of business that could quietly do very well out of the energy transition. The particular coating product for the hydrogen industry for example, (which I do not understand at all I might add) sounds like it is a 'technology agnostic' product, meaning it doesn't matter which electrolyser manufacturers eventually suceed on a large scale, as long as one or more of them buys this product from James Cropper. I would struggle to find James Cropper's competitors as this will be a properly global market.
The comment your passengers made about the Advanced Materials side taking over the Paper Products division is interesting. Very much depends whether they mean revenue and/or profits. Revenue at the H1 results was £19m (AM) v £35.6m (PP), so that would be some stonking revenue growth to catch up there. I can't find a breakdown of the profit for each division quickly.
But as a story of 1 smaller, successful and growing division, and 1 mature but restructuring division could deliver an increase in profit margin relatively quickly, with associated re-rating of the share price.
Thanks again for bringing this to our attention GM Trader.
Long live the SCVR.
Chris
P.s. are you a trader/investor and a taxi driver?
Their comment was in regards of revenue over taking the paper side.
Yep taxi driver in Kendal for 17 years. Investing for 32 years. My ex father in law sat on board meetings in Croppers and I know many that work there.
Hi gmtrader,
I drove past the Cropper plant twice a couple of years ago on the way to walks around Kentmere and Longsleddale and was intrigued so I spent some time researching the company. It didnt lead to an investment, I think the sp was in the 900s then. I did wonder though why they had invested in solar panels when I hadn't seen any sun there, ever!! :-)). Although I imagine they get free power from the Kent and/or Sprint rivers in some ways.
Perhaps I'll take another look.
They also have water sourced from tarn up Potterfell running to factory and some properties below the fell. Yes it does get a lot of rain there below the fells. Used to live below Potterfell with the water supplied from the farm they own.
With the cost cuttings James Cropper (LON:CRPR) have implemented as well as general savings from energy coming down in price, if they do manage to increase revenues then it could well become worth investing in again.
I have heard some of the new designs/products are also top military secrets they can’t talk about.
One thing to bear in mind it is very heavy dependant on energy to run the machines The paper side is very low margins though they do have good contracts in the paper side which is a very specialised niche part of the paper industry.
Mark Cropper married an Iranian lady who I believe is not allowed around certain parts of the factory due to intelligence secrecy or what ever the name for it is. My aunt went to their wedding a few years back. Very formal!
Thanks for the "insider knowledge". I see a M A Cropper, who may also have "insider knowledge" has been a serial buyer £300k+ and only one large sell around the £9 mark, wonder what he knows?
James Cropper (LON:CRPR) They all sounded extremely bullish about the company for the future and in particular the Advance Materials side of the business. They expect this side of the business to overtake the paper side in the next year or two.
Intrigued by this tasty scuttlebutt, I had a look through historical reports from the house broker. I thought it worth adding that this has been well understood by the market for over 6 months and the big surge in SP of April relates to the purchase (mentioned elsewhere) of £300k-worth of shares by the chairman on top of a report alluding to the potential of the technical fibres division.
Nevertheless, the gradual drift down since the spring looks to have created a repeat value opportunity with shares at TTM technical lows and well below the pandemic panic. That is, until you try to buy some - I couldn't get a quote for10 units, less than £100, on HL! Not decided if it is for me, being part turnaround story, part input cost wing and a prayer, when I prefer long term quality. But I can see the investment case and thought it worth checking the liquidity. And there is none!
James Cropper (LON:CRPR) I can get a quote on HL
Thank you gmtrader for your scuttlebutt on James Cropper (LON:CRPR) a company that has long fascinated me, and I'd like to own, but never quite seen the story and the right price. I shall do some research..... tempted to buy a few (if there are any scraps left for me) just to force me to dig deeply,
cheers,
Mark
If you do decide to buy some, then maybe because it seems to be illiquid, put in a buy order at a lower price if it is always nt to buy.
Bear in mind the chart has double bottomed so it may be worth waiting to see if it does indeed rise from here or if it drops lower. It is below the 200 and 50 ma atm, so the trend is obviously down atm. The market will not see whether the revenues increase for a while yet. I think it will be 4 months until yo results are out. So good chance imo it will continue down. NAV I think is about 350p of the top of my head.
The main problem with Cropper is it is very difficult to build a position. I have tried to invest in the past and you can end up forcing your own buy price higher.
Any chance of catching up with XLM today??
Surprised anyone still following XLM to be honest - Paul briefly mentioned in his podcast that it's been a serial disappointer and wasn't intending to spend any time on it.
Arix Bioscience (LON:ARIX) - Re-posting from Friday in case anyone is interested in joining. Meeting on Teams confirmed at 11 am today.
Arix Bioscience (LON:ARIX) - I wrote to Arix Bioscience (I hold) a month ago complaining about the terms of their proposed takeover by RTW Biotech Opportunities (LON:RTW) . The takeover is at an effective 130p against a NAV of 180p odd, of which about 60p is cash which Arix is not planning to distribute but to give to RTW.
I did not expect a reply, but to my surprise, they have written back offering a meeting with their CEO Rob Lyne on Monday 18 December at 11am (to be confirmed). It will probably be by zoom or teams (again tbc).
Are there any members of the Stocko community who hold Arix Bioscience(LON:ARIX) who would like to join this meeting?
If yes, please contact me on richard at mutlow.net (the at symbol has another function on this page and won’t work!)
Regards to all,
Ricardow
Hi Ricardow
Just seen this on Arix Bioscience (LON:ARIX) and can't participate at 11. I hold the company as part of a basket of bombed out biotech/life science cos. Arix is very much a value play in that basket picking up around lows when cash was near market cap and so private and public portfolio were near 'free' (obvs the cash gets 'burned' over time with deployment). So I never had a particularly positive view of Arix or mgt (bit of a mess) but from a capital cycle perspective biotech was interesting and the price was particularly bombed out.
On balance I like the RTW Biotech Opportunities (LON:RTW) deal. I accept there's some elements to it that feel as if small investors are 'cheated' but my view is more magnanimous than that in that Acacia are big holders and need to be on board and Arix is in a weak position currently and not able to drive super terms. I also think RTW team are a large capability upgrade and that the bigger combined entity makes sense (and what Arix prospectively invest in will be better all round)...so I see 'quality' getting added to my value play in biotech capital cycle (which is at bombed out point in cycle). RTW also at a discount to NAV so value remains after deal.
Obvs there's a bit of bitter taste for anyone who bought higher...and that is further soured by the hints of back room dealing in that there are connections between Arix board and Acacia I believe (so feels 'preferred' terms for them totally)...
...but ultimately Arix shareholders are getting a better deal. Some of you may prefer money back through wind down. I don't want that as I'm looking for cycle to turn (not forecasting that's imminent...just bottom fishing) and given the early venture nature of some holdings it will be a pfaff to realise and likely at pretty bad prices
I would love to get some feedback from your call tho. Put up here or if you want contact details can get them to you (perhaps its low interest stock here!?).
Thank you
Best wishes
mojo
Terrible trading statement from RBG Holdings (LON:RBGP) looks they are now entirely relying on legal work to see them through. However I would be concerned about debt because even with the new bank facility they seem to be within 10% which seems close
My morning smallcap tweet: Convex concaved
RBG Holdings (LON:RBGP) Games Workshop (LON:GAW) Invinity Energy Systems (LON:IES) Nuformix (LON:NFX) CAP XX (LON:CPX) Narf Industries (LON:NARF) Eden Research (LON:EDEN) N4 Pharma (LON:N4P), One Media IP (LON:OMIP)
◄RBG Holdings (RBGP)► plenty to make holders' toast wilt today. Warns FY-Dec rev c.£42m (£50m), slightly lower than market expectations mainly due to Convex Capital fee income of £2.19m vs £4.5m expected. This was very likely following last week's RNS about Convex. Adj EBITDA c.£4m (15.8m). £1,8m write-off of bad debts. Extra settlement costs in Lionfish disposal due to case loss. FY24 guidance modest: "There are early signs of recovery in some of the key areas of legal services that were badly impacted in 2023 but we will be presenting a more conservative budget for 2024, with revenue and profit expected to be slightly higher than 2023." [SP=17 Cap=16m]
◄Games Workshop (GAW)► as mooted, agreement with Amazon for prospective development of Warhammer 40,000 universe into films and television. [SP=9790 Cap=3226m]
◄Invinity Energy Systems (IES)► guides FY23 rev £21.6m, broadly in line with expectations. Outlook: "qualified pipeline includes multiple new opportunities in the 200 - 500 MWh size range across North America, Australasia and Europe". [SP=26.73 Cap=51m]
◄Nuformix (NFX)► receives second NXP001 milestone payment from Oxilio. [SP=0.35 Cap=2m]
◄CAP-XX (CPX)► patent action against Maxwell Technologies - US jury has affirmed that CAP-XX patents were invalid. [SP=1.7 Cap=12m]
◄NARF Industries (NARF)► will collaborate with with MITRE and Red Balloon Security "to develop a new threat model for embedded software and hardware solutions that mitigate cyber threats to critical infrastructure". [SP=0.76 Cap=13m]
◄Eden Research (EDEN)► Ecovelex 2023 has been granted temporary approval in Italy for use as a bird repellent seed treatment in corn for 2024. [SP=4.12 Cap=22m]
◄N4 Pharma (N4P)► successful two dose oral administration in vivo trial of Nuvec loaded with a DNA plasmid for ovalbumin. [SP=0.78 Cap=2m]
In line: OMIP
Games Workshop (LON:GAW) tie up with amazon announced, that a TV series will be produced.
Also films
A strangely muted response to this news, which looks pretty significant to me, in the long term. Even without the Amazon tie-up, the valuation looks reasonable with a Price/FCF of 19.5, a healthy dividend of of 4.4% and good good growth prospects.
Even though it will take time for the license revenues from this deal to flow through, but you would think that in addition to increased license fees, it should also lead to greater core sales as their audience expands.
I will remain a happy long term holder here.
Yes I was thinking the same. I did manage to top up about 10 days when it fell back,
I was expecting the shares to be up more than 2% today.
Agreed. I am also suprised by the very limited response to this news. Especially considering the dip earlier in the month was due to people being disappointed by licensing revenues in the trading update. Surely this deal kind of counteracts that concern?
Part of the announcement was that they will spend 12 months agreeing how to use the IP which means no actual production for at least a year so the positive impact may be 18 mths to 2 yrs off?
Games Workshop (LON:GAW) tend to things for the long term…it’s definitely an attractive attribute to me…gradually..cumulatively..shareholders benefit…I have this as my second largest position precisely because of this long term focus on shareholder returns