Small Cap Value Report (Mon 18 Mar 2024) - POS, TUNE, DFCH, BYIT, CURY, MSLH. Quick: NGHT, CHG

Good morning from Paul & Graham!
Today's report is now finished. I'm halfway through SEE, so will finished that tomorrow.
The Week Ahead - today's article is here.
Naked Wines (LON:WINE) - Sky News reports that this troubled wine subscription service has hired Interpath debt advisers to "explore refinancing options". Sounds ominous to me. WINE puts a positive spin on things - "... there may be an opportunity to secure a similar-sized facility that has less limitation on utilisation and more flexible covenants resulting in fewer restrictions on the actions we can take to reduce inventory and drive our broader change agenda." Paul's view - I think it could be in trouble. I can't imagine many lenders would be keen to finance this excessive wine lake, given that the business model has effectively failed to prove it is a viable/profitable business, and now seems in a downward spiral. Massive inventories and/or receivables often hide a multitude of sins. See our archive here for more bearish points. RED.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news) -
Bytes Technology (LON:BYIT) - down 13% to 501p (£1.18bn) - Investigation & Trading Update -
Investigation update - longstanding former CEO made large numbers of trades in BYIT shares without disclosing them, but we already knew this from a previous announcement. BYIT claims its values are nothing like its former CEO’s values. How does that work then?
Trading Update (FY 2/2024) - waffly, positive-sounding, over-PR’d update, doesn’t actually tell us whether it’s traded above, in line, or below market expectations. Given the scandal over its former CEO, you would have thought clarity would be a priority.
Chemring (LON:CHG) - up 6% to 370p (£1.0bn) - Funding Awards - £57m funding from EU for Chemring Nobel (Norwegian subsidiary), ammunition production for Ukraine. Another £32m funding has come from the Norwegian Govt to boost production - aiming to double production in medium term. No more info available (no broker notes for the plebs!)
Summaries of main sections
Plexus Holdings (LON:POS) [Paul holds] - 18.0p (at 09:23) £19m - H1 Results - Paul - GREEN
My quick summary below of excellent H1 results - but NB most of revenues (and all the profit) is from a one-off licensing deal, as previously disclosed. No surprises overall.
Focusrite (LON:TUNE) - 272p (down 30% at 08:14) £160m - Trading Update [Profit Warning] - Paul - BLACK (AMBER/GREEN on fundamentals)
Bad luck to holders, as TUNE shares lurch down on a profit warning. Frustrating lack of broker coverage, so I've pieced together my own estimate of revised earnings. With no apparent problems over liquidity, I'm seeing this bombed out share as a potential recovery situation.
Distribution Finance Capital Holdings (LON:DFCH) - up 9% to 27.9p (£50m) £160m - Trading update (ahead) - Graham - AMBER
Good news for shareholders as prudent loss estimates and tight cost control produce a better than expected financial result for 2023. Guidance for 2024 is unchanged. I remain neutral as I wait for this lender to build a longer track record of decent performance.
Currys (LON:CURY) - up 3% to 58.3p (£661m) - Trading Update & End of Offer Period - Paul - AMBER
Potential bid talks are off, as we already knew, so the offer period has ended. A mildly positive trading update says its at the top end of previous guidance. Huge forthcoming pension contributions put me off, and the very low margins.
Marshalls (LON:MSLH) - down 8% to 268p (£678m) - Final Results - Graham - AMBER
The recovery has been delayed as Marshalls publishes a weak outlook statement for 2024, with no expectations for an improvement in profitability. For investors who wish to bet on a surprisingly fast bounce in consumer confidence, this stock may be of interest.
Paul's Section:
Plexus Holdings (LON:POS) [Paul holds]
Up c.10% to 18.0p at 08:41 (£19m) - H1 Results - Paul - GREEN
H1 numbers look smashing, but as they stress several times in the commentary, most of the revenue has come from the Dec 2023 licensing deal with SLB.
H1 revenue up 617% to £5.1m (£4.1m from SLB licensing)
PBT £2.2m vs H1 LY: loss of £(2.1)m
Cash from SLB deal is in receivables, confirmed receipt in Jan 2024, so cash position now fine, c.£5m.
The commentary sounds good, with some nice nuggets for the bulls in there!
FY 6/2024 outlook in line.
There's a new broker note just out from Cavendish, £14.0m revenues, and £3.5m adj PBT for FY 6/2024, I think that's unchanged. It's a massive turnaround from last year, with revenues up about 9x and a move from losses into profits.
Hopefully some more investors might spot the big turnaround underway here? It supports my view that this is a previously successful, profitable company that is coming alive again. It needs to keep winning contracts to keep the momentum going. Downside risk is that a couple of large deals this year might just be one-offs.
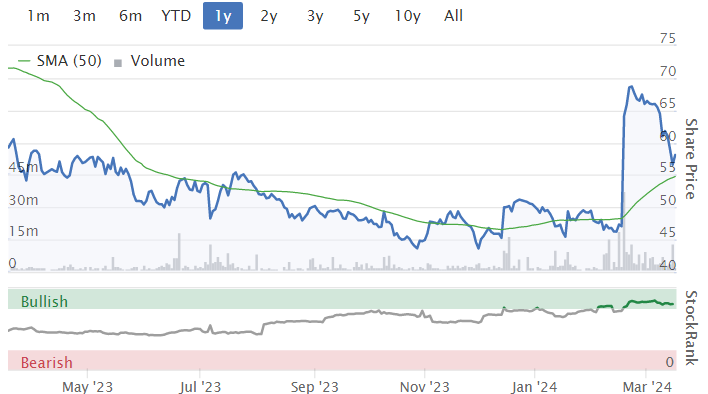
Plexus was the biggest % riser in the UK for 2023 - with most of the rise having stuck -
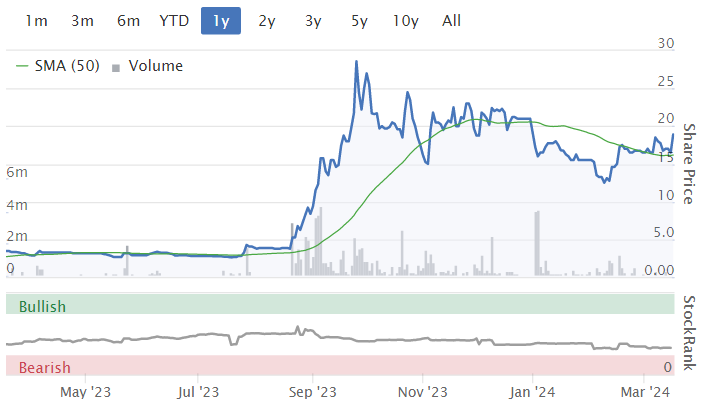
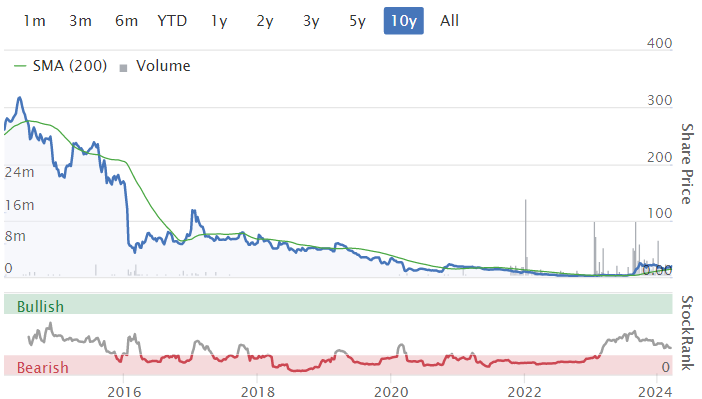
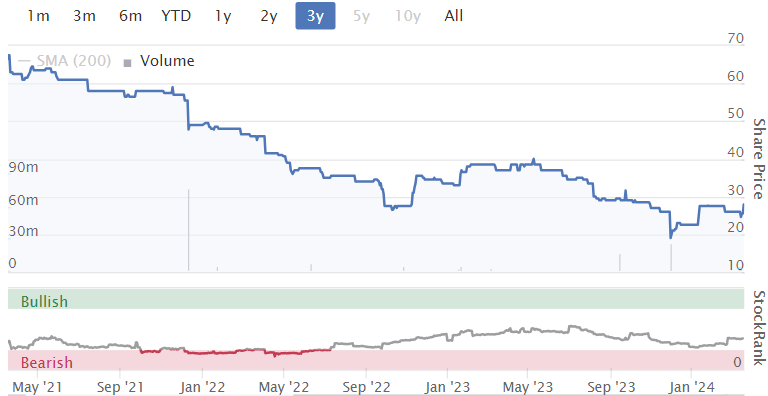
Although zooming out, this is little more than a blip on a long-term downtrend. Interestingly, there's been little dilution since the previous glory days when it was growing & profitable -
Focusrite (LON:TUNE)
272p (down 30% at 08:14) £160m - Trading Update [Profit Warning] - Paul - BLACK - (AMBER/GREEN on fundamentals)
Focusrite plc (AIM: TUNE), the global music and audio products group supplying hardware and software used by professional and amateur musicians and the entertainment industry, provides the following update on trading for the year ending 31 August 2024 ("FY24") based on trading for the six months ended 29 February 2024 ("HY24").
Bad news I’m afraid -
Challenging market conditions have continued in Feb & Mar.
H1 revenues expected £75m+ (H1 LY: £86.2m)
Revenues for FY 8/2024 now guided as £155m+ (it doesn’t say what the previous expectation was, but the StockReport is showing consensus of £182m)
EBITDA guidance -
FY24 EBITDA is expected to be in the range of £27 million to £30 million with a heavier weighting towards H2 than in FY23.
It did mention an H2 weighting in the Jan 2024 update, so that’s not new.
Broker notes - nothing available - a glaring oversight for a small cap, not getting information out to the investors who create the liquidity, and set the share price (private investors). This is often a problem with owner-managed businesses, as they still act like private companies.
Last year’s figures (FY 8/2023) showed adj EBITDA of £38.6m, so the guided range above of £27-30m for FY 8/2024 is between 22% to 30% down Y-on-Y. Clearly a bad year is underway.
EBITDA of £38.6m turned into real profits (PBT) of £28.8m last year (adjusted), and £22.7m statutory, so quite a lot lower than the meaningless EBITDA. I say meaningless because TUNE is a heavy capitaliser of development spend of £9.2m last year, and £8.4m the year before.
Assuming a similar level of costs between EBITDA and PBT, I reckon FY 8/2024 might be something like £17-20m adj PBT. Take off say 22% tax and PAT would be c.£14.4m, divide by 59.2m shares in issue, and I get to an estimated adj EPS at 24.3p. That’s poor, and brings EPS back down to where it was pre-pandemic, despite the acquisitions made in recent years. So it’s looking increasingly likely that the surge in profits at TUNE were lockdown-related after all, rather than structural growth.
Mind you, at just 272p the share price has fallen a helluva lot, and the PER is only 11.2x based on my 24.3p EPS estimate.
The commentary goes into more detail about delays in launching new products, customer destocking, sales mix, macro factors, etc. The bottom line is that sales and profits have disappointed.
Is it in financial trouble? By the sounds of this, I’d say no, it sounds OK -
As of 29 February 2024, the Group had net debt of approximately £26.0 million (31 August 2023: net debt £1.3 million), with the increase mainly attributable to the impact of working capital phasing across debtors and stock, and with one-off impacts of approximately £5 million due to investment in future technologies and recent acquisitions. This position is expected to largely unwind in the second half of FY24 as our working capital improves and to be close to net cash by the year end. Our £50 million committed credit facilities provide ample liquidity for ongoing operations.
Paul’s opinion - this update is frustrating in only having limited information. We’ll have to wait until broker consensus figures update later this week, to see if my estimate above is accurate or not.
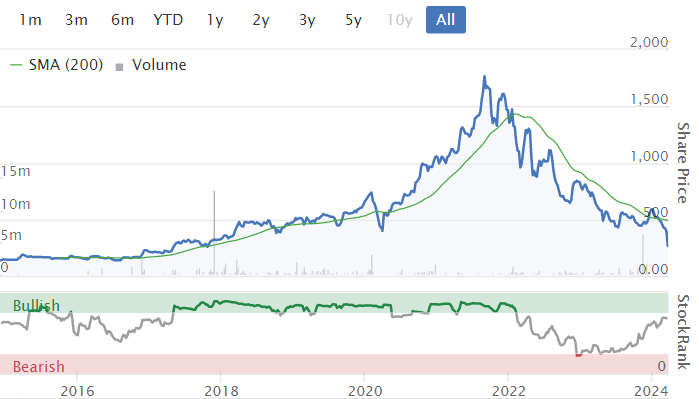
Overall, I think TUNE remains a decent business, with good quality scores. Amazingly shares have fallen c.85% since the lockdown boom peak in 2021. Sure its performance has disappointed, but surely we must be getting close to a point where the shares offer attractive value, and recovery potential?
So I’m leaning more towards seeing this moderately positively for value/recovery, particularly as there doesn’t seem to be any insolvency/dilution risk. It depends though. Is this just a one-off bad year, or is business slipping away to competitors? Its heavy R&D spend is evidence that TUNE has to keep innovating, or risk being left behind.
So I’ll take a risk, and go with AMBER/GREEN on fundamentals, but BLACK to flag the profit warning.
Currys (LON:CURY)
Up 3% to 58.3p (£661m) - Trading Update & End of Offer Period - Paul - AMBER
Currys confirms what we already knew from their announcements, that neither Elliott nor JD.com intend bidding for Currys. Management didn’t seem to want to engage with potential bidders. Elliott’s original 62p indicative price looked too low, and wasn’t likely to be accepted anyway, in my view. This was upped to 67p, but that was also rejected. So at least shareholders now have a benchmark on valuation.
JD.com also walked away, without giving any public explanation, but it was only at “the very preliminary stages of evaluating a possible transaction”.
So that’s that - end of the offer period.
Trading Update - sales “stronger than expected”, and adj PBT guidance for FY 4/2024, is now “at least £115m”, whereas previous guidance was £105-115m range. So moderately positive. NB this includes its discontinued Greece operations, so adj profit will actually be lower.
Will have year end net cash, as Greek disposal proceeds expected near year end.
Pension contributions are rising from £36m pa -
Scheduled pension contributions will rise to £50m in 2024/25 and to £78m for the following three years before a final payment of £43m in 2028/29 within the current agreement. Pension contributions will cease when the actuarial deficit reaches zero.
Paul’s opinion - I can’t get excited about CURY. It’s a very low margin business, and even its aspiration is only to achieve c.3% operating profit margin. With the huge pension scheme payments scheduled, I see little potential for decent divis without taking on debt again. Profit will fall from the Greek disposal. Plus we know know 2 bidders weren’t prepared to pay much more than the current share price for it. So overall then, I can’t muster any enthusiasm to go above AMBER.
Graham’s Section:
Distribution Finance Capital Holdings (LON:DFCH)
Share price: 27.9p (+9%)
Market cap: £50m
DFCH is “a specialist bank providing working capital solutions to dealers and manufacturers across the UK”.
This morning brings some rare (according to the chart) good news for shareholders:
The update is ahead of expectations for 2023, though it doesn’t suggest that there is any need to change expectations for 2024.
Remember that this company announced a profit warning in November, due to a large problem loan. But according to the company’s broker, more than 70% of the £6m impairment associated with this loan has since been offset by the company’s strong trading elsewhere.
The new PBT estimate for 2023 is £4.4m (previously £3m). The reason for the stronger than expected performance is “prudent forecasting of credit loss provisions at the year-end” and “proactive operational cost control by management”.
As for trading in 2024:
The Group is also pleased to report a positive start to the current year, with its loan book, dealer facilities and credit limits continuing to grow year-to-date. The Group's financial and operational performance is in line with the Board's expectations for the year.
FCA review into motor finance commissions: we get strong reassurance on this front.
The Group has not offered products or services that would fall within the scope of the FCA's review, nor does it have commercial arrangements with dealers or brokers of this type. Accordingly, the Group considers it is not impacted by the FCA's current review.
Graham’s view
I had a generally favourable impression of this stock when I reviewed it in April 2023 (share price: 40p), giving it a neutral rating but suggesting that it warranted additional research..
That was prior to the November profit warning, covered by Roland.
As a reminder, DFCH provides inventory finance for a wide range of sectors. For example, the loan that caused all of the recent trouble related to a group of caravan parks.
The company reported balance sheet equity of £99m at the most recent interim report, almost fully tangible. It also claimed that it did not need any fresh equity to grow its loan book to over £800m (from c. £520m).
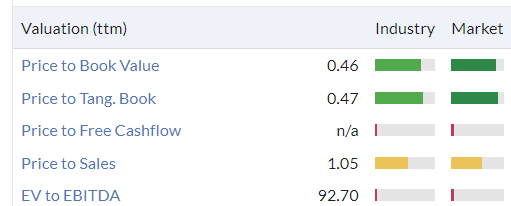
At a market cap of around half book value, it’s certainly cheap - but then isn’t every other financial stock and especially every other listed lender?
Given the high-ish leverage (that is only going to get higher as they act on this £800m idea) and given the company’s recent impairment experience, which includes confirmation that some larger debtors could individually be responsible for a few percentage points of the entire loan book, I suspect that the market is right to put this one on a cheaper book value multiple than its peers.
The footnotes to the interim report showed that the largest industries in the loan book were “lodges and holiday homes” (30%), transport (22%) and “motorhomes and caravans” (19%).
I also note that most lending is done at an LTV of over 90%.
These facts aren’t boosting my confidence in the story.
Of course, the entire market in financial stocks may be too cheap, including DFCH shares, which implies that I should be taking a positive stance. However, I’ve not seen enough here to make me want to give this one the thumbs up yet: the track record hasn’t yet convinced me that this stock is investment-grade.
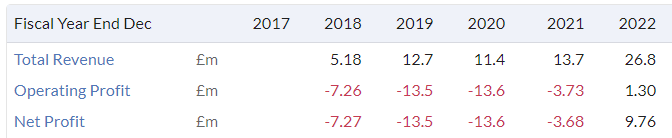
“The better part of valour is discretion.” I remain neutral.
Marshalls (LON:MSLH)
Share price: 268p (-8%)
Market cap: £678m
Marshalls plc, a leading manufacturer of sustainable solutions for the built environment, announces its results for the year ended 31 December 2023
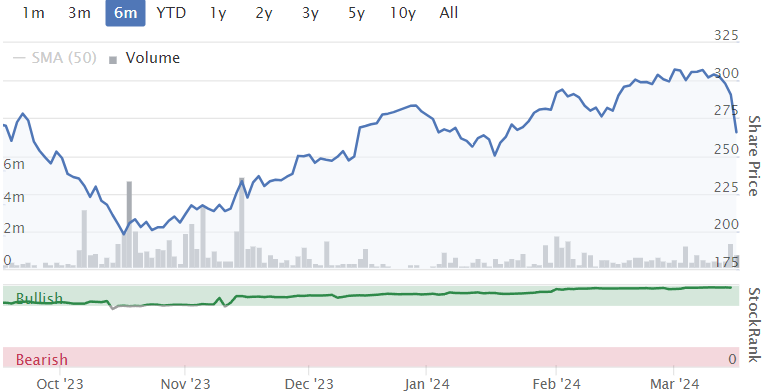
The long-term chart here is terrible, but over the past six months Marshalls had built up some momentum, until today:
The financial summary for 2023 illustrates a tough year, including the negative effects of operational leverage::
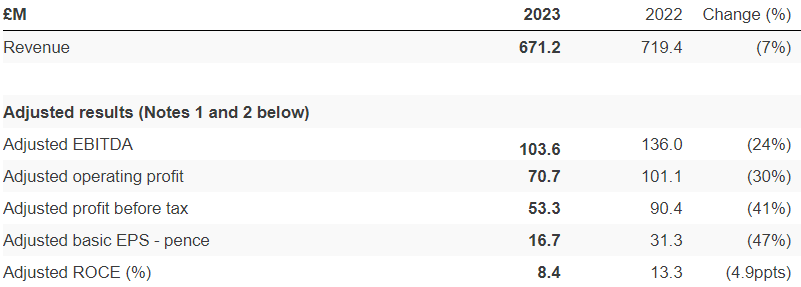
The statutory numbers don’t inspire much confidence either, and as usual the actual profit figures are much, much smaller than the adjusted numbers:
Operating profit down 14% to £41m
PBT down 40% to £22m
The reason for the decline? “Challenging end market conditions” for the UK’s leading landscaping, building and roofing products supplier.
The company has responded by “right sizing” with £11m of planned savings p.a.
Net debt reduced in 2023 from £191m to £173m (excluding leases) with a year-end leverage multiple of 1.9x adjusted EBITDA.
New CEO started this month. He has had a varied career, mostly recently at Genuit (LON:GEN) where he was the COO for 1 year and 8 months.
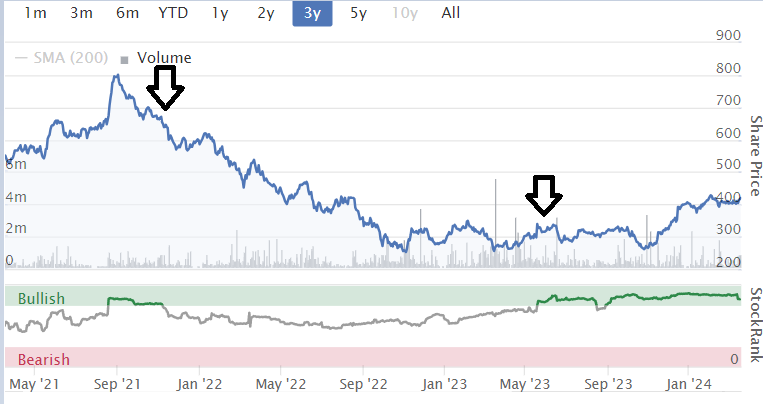
Like Marshalls, the Genuit share price has also suffered a lot over the last few years (just out of curiosity, I’ve marked the beginning and the end of Matt Pullen’s tenure as COO with arrows):
Outlook
With the Marshalls share price down this morning, I’m not expecting a sunny outlook statement:
Revenue in the first two months of the year was lower than 2023 and reflects the continued weakness seen in the second half of last year
In line with recent sentiment of UK economic and industry forecasts, the Board expects activity levels to remain subdued in the first half of the year followed by a modest recovery in the second half as the macro-economic environment progressively improves. The start of this recovery is now expected to be slower and more modest than previously assumed. Therefore the Board believes that revenues in 2024 will be lower than previously expected and that profit will now be at a similar level to 2023…
In other words, adjusted PBT of c. £50m is the new normal (and maybe actual PBT of c. £20m, too?).
Adjustments - I will spare you a detailed analysis of this company’s profit adjustments. But I would like to point out that these accounts are miles away from anything that could be described as “clean” when you have adjustments like this:
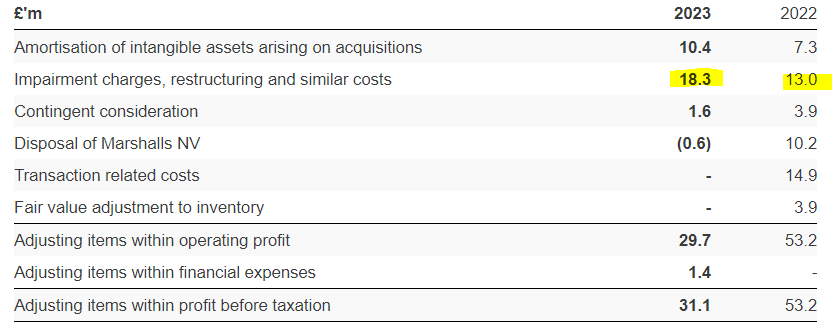
In particular, I would draw your attention to “impairment charges, restructuring and similar costs”. I have a concern that many companies have large costs that could be described as “restructuring and similar costs” if not every year then at least on a regular basis. See that Marshalls had £13m of these costs the previous year, and then £18m in 2023. And most of these were real cash costs, not simply the writing down of invisible balance sheet items.
Segmental results
The biggest hit in absolute terms to adjusted operating profit was in the Landscape Products segment.
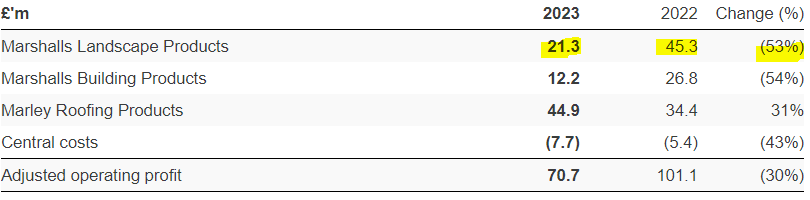
The Landscape segment saw its UK revenues fall 25%, impacted by “lower new build housing and continued weakness in private housing RMI activity driven by the discretionary nature of the segment's domestic products, weak consumer confidence, product price inflation and lower real incomes”.
The Roofing segment saw profits increase in 2023 but that is only because it was acquired part way through 2022. On a like for like basis, profits were down 12%.
Graham’s view
I share the optimism of the Marshalls Board that the medium-term and long-term prospects for the business are probably fine:
Looking further ahead, the Board believes that the UK construction market continues to have attractive medium and long-term growth prospects driven by the structural deficit in new housebuilding, an ageing housing stock that requires increasing levels of repair and maintenance, and the need to continue to improve UK infrastructure.
I’m also optimistic that by the end of the current calendar year, we might see something that resembles a recovery in consumer sentiment.
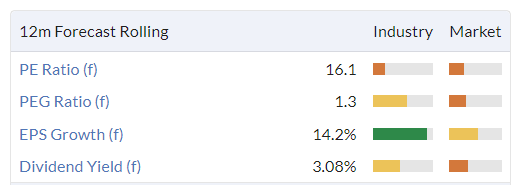
However, there are many ways to play this recovery and I’m not sure if Marshalls is the most compelling choice. Given the cheapness of so many shares, should it not be possible to find alternatives trading at cheaper multiples, with better balance sheets, cleaner accounts, and similar prospects for recovery?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

131 comments
If nobody minds I'll expand on my virtual MicroCaps portfolio. Firstly, RMM and INCE went bust which hurt my real portfolio, escaping from the Mellor Dilution Tool of CNR just in time. In the virtual portfolio then, the remaining dogs are VANL, PEG, ZNWD, AAU, KDNC, ALBA, ZYT, SIXH, KEFI, RAI, VAST, and ADME. I'm sure one of these will come to fruition ;-) however, anyone referring to my first post can see that the other 14 stocks must have performed exceedingly well.
Edit: All of the aforementioned stocks are held in my actual portfolios, more is the pity....
I am certain you do the right thing Paul, I constructed 9 virtual portfolios elsewhere (Stocko doesn't seem to be able to help here) on the 5th of August 2023, and this is how the one outstanding portfolio called Jim's MicroCaps (which holds 29 stocks) stands now:
If only I had put all my money on this horse I would be sending to Zane but as it is, I'm the one who needs my own charity :-)
Silver
Yiannos1: Plexus Holdings (LON:POS) I don't have a strong opinion about this, but when I look at another rental company Ashtead (LON:AHT) I see that their strong bull run went on to double after they were valued at >8*Tangible Book Value. That is ~ to where Plexus is today. I'd accept that this could be an anomaly, but it appears to test your thesis regarding this. It would definitely be true to say that if one had followed your rule when Plexus was 2.35p and the P/TB was .22 then one would have been exceedingly grateful, although with the sea of red on the Stockreport I wouldn't have had the stomach for it. As I say I don't have a strong opinion, but it would be good to see any research regarding the efficacy of P /TB as an indicator, but perhaps the signal for rental companies would be lost in the noise from all the other companies in any study.
Micro-caps are for fools. You would be better off going to a casino. Right off the bat you lose 10 percent because of the spread. And if you did get lucky, assuming you bet the house, then good luck trying to sell it, given the nearly non-existent liquidity.
The US market is just a click away, with largecaps that have the upside of UK microcaps with none of the downside. I've noticed a big difference in my trading performance almost instantly when I quit UK small caps and started trading US largecaps. its unlikely I will be ever going back.
Sorry Guybrush
I can only give the thumbs up once to your comment. Still some opportunities but decreasing day after day.
Thanks for your posts yiannos1. You talk much sense in a world that often has none.
I make good money out of micro caps, by -
1. Stock selecting very, very carefully, which involves rejecting almost everything.
2. Ignoring story stocks that generate little to no revenues (let alone profits).
3. Buying & selling inside the quoted spread, in dribs & drabs over time.
4. When sellers are killing the share price, do nothing - just wait for it to get even cheaper.
5. Most importantly - buying after news where there is some sort of genuinely positive catalyst - eg major contract win, cash burn being slashed, etc.
6. Usually - only buying things that have adequate cash resources and probably won't need a fundraise within say 18 months.
7. Top slice into strength, after a big rise in price, thus freeing up cash for new opportunities.
8. Trying to avoid delisting risk - but this is only usually a risk where a company has either an overly dominant major shareholder, or has obviously come to the end of the road in terms of being able to raise finance from the market.
9. Reasonably competent & honest management, so far as that can be ascertained.
10. Avoiding the usual company promoters, brokers, etc, who float absolute junk.
I find this approach works very well indeed for me, and over the years most of my really big gains have actually been from micro caps.
So I don't like sweeping statements like your "Micro-caps are for fools". There are always opportunities, if you know what you're doing, in many investment areas that might not appeal to many people.
There are some particularly good opportunities right now in micro caps, highly selectively, as so many valuations are completely bombed out from distressed sellers.
Paul.
Great post.
Frustration is high. And the future is uncertain. The stock market industry is as much to blame as the complex tax regulatory rubbish governmental system. IPO's anyone (nah - sorry Primary Bid - only so many golden gooses born each year).
Arm Holdings (NSQ:ARM) - clever boys.
Bytes Technology (LON:BYIT) - one to watch closely and still in the UK.
I work 5 days a week so cannot devote anything like enough time to what I do hold, let alone new opportunities. And the micro/smalls often don't hit the SR70+ safety net.
Guybrush has a point. The huge problem with micro caps is the liquidity issue. If something goes wrong it is very difficult for the average punter to get out their position when everyone else is also heading for the exit. You are locked in - quite possibly with substantial losses.
Poor liquidity also attracts pump and dump campaigns/wash trading etc which can be difficult to spot and are designed to leave the average investor out of pocket.
There also will probably be little/non existent research. It is unlikely that the average investor knows more about the company than the managment so in all cases you are also relying on the quality and the integrity of the management to give an accurate position of the prospects.
If you like a punt and most of your portfolio is in safe liquid stocks then thats fine. The chips are however stacked against private investors on micro caps.
JPmorgan US Smaller Companies Investment Trust (LON:JUSC) - if like small caps well perhaps need to reassess the definition of 'small'.
Leaving JPM with huge resources and govt insiders to do the heavy lifting.
Experimental but in the blue, whereas most of my UK's have been in the red for more than a year and only likely to take off if someone buys them.
Do you confuse Ashtead (LON:AHT) with Ashtead Technology Holdings (LON:AT.) perchance.
One is in deep sea diving repairing and maintaining our energy future. Company should have work forever, not sure about the 'energy future'.
.
Anyone know how to get rid of lines beside the replies to comments on stockopedia - for a macbook pro. The replies are ending up one letter at a time and unreadable on stockopedia comments.
Option 1: Choose "Unthreaded" in the drop down box at the top of the comments.
Option 2: Yiannos honours his pledge to leave this forum - the sooner the better IMHO.
Filter option. Apreciate views but not those who are disruptive, mislead and attempt to agressively intimdate others who don't agree with own opinions. Could go to LSE or ADVFN for that free.
That’s nice!
From the Bytes Technology press release of last week, I was under the impression that the Board had already quantified the remarkable extent of the unreported dealing by their former CEO. Today's press release announces an investigation into both this and his resignation, involving accountants and auditors which will need to be completed before the date of the prelims. for FY 2024 can be chosen. This does not sound to me as though the board is convinced that the full extent of the CEOs errors of judgement have been quantified.
Unbelievable what the CEO thought they could get away with there.At least the FCA is upping their abilities to catch rule breakers.I wouldn't be surprised if they are using data matching/AI software moreso now to match more trading irregularities, which would have gone unknown before, as they have always been understaffed.
.."At least the FCA is upping their abilities to catch rule breakers..."
Well, maybe.
FCA hires chief internal auditor who has no audit qualifications
Treasury committee asked to scrutinise the City regulator’s appointment of an insider, as doubts are raised about his ‘objectivity and independence’
https://www.thetimes.co.uk/art...
I'm sure there's a perfectly 'sound' explanation.
Ho hum.
Sigmaroc (LON:SRC) I hold
I thought today's finals were a decent result in quite challenging circumstances. The acquisition earlier this year of CRH's lime operations is clearly a transformative deal which makes SRC a major supplier throughout most of Europe. It's not widely understood how important lime and limestone are in modern life, being used in almost every industry that manufactures something as well as in construction and the built environment.
One of the aspects of this company that I admire is the pursuit of environmental improvement, everything for carbon capture, low carbon building products , biofuel replacing gas or electricity in its kilns and the production of a valuable product from what previously was waste (Puccini blue stone).
The full benefit of the strategic steps taken so far will be seen in the next couple of years but given how well they have coped with adverse conditions to date, I think the market undervalues this company. I guess everyone only wants to buy when the value is obvious but by that time the value has evaporated,
Would be nice if Paul or Graham could find time to look at the results and catch up.
Assetco (LON:ASTO) - results today are very poor in my view - Martin Gilbert probably should have retired as this v2 Aberdeen doesn't look like its going to have a happy ending. The story has very much like "To travel hopefully is a better thing than to arrive". The strategy was to 'buy and build' asset managers without the legacy issues of abrdn. This hasn't worked as the acquisitions of random sub-scale investment managers has brought even more legacy integration headaches and delays trying to push all of these eclectic managers into River Global at the same time as net outflows have shrunk what was originally acquired: "On 4 December 2023 the Group rebranded its Equities business to River Global, reflecting the bringing together of all of the River and Mercantile, Saracen and SVM brands under one brand and operating model."
Parmenion is probably worth something, but the 30% share of its profit is very small versus the c£13m loss - quite impressive for an asset manager which is normally a highly profitable sector! Net current assets are down to £16m, so they don't even have too much of a cash runway, particularly as this will have reduced for £1.8m going out the door for Ocean Dial and further losses in the first half of the current year. The net cash reported will also have been reduced by the £7m of consideration for the SVM loan notes now paid out post year-end.
Unfortunately, market conditions have been very unkind, but the original concept didn't have firm foundations in my view. I'm a great fan of investment managers and Martin Gilbert was great 20 years ago, but the market has changed and buying up your old contacts for toppy prices doesn't really work!
I did hold River & Mercantile but sold on the exit to Schroders of the the best part of their business. SVM was a loss making investment management business in Edinburgh run by the once mighty investment trust veteran Colin McLean.
There are much better prospects in a beaten-up sector. Of course, they might get lucky if they get a good bid for the 30% of Parmenion that they own, but I can't see much value in River Global as it looks flawed. Good luck to anyone holding, but be wary of the risks.
I hold Chemring (LON:CHG) and can add two observations to the scant press release.
First, what is interesting about this EU award is that - despite President Macron's aspirations - EU money has been awarded to a non EU company with a munitions factory in another non-EU country. This decision follows the loss by the French of the Australian submarine contract with the "restructuring" of the AUKUS submarine project (now also looking less certain as the US dithers).
Second, the award is not for the delivery ammo, but rather the raw materials that go into the brass casing. Chemring Nobel is the old explosives business set up 130 years ago by Alfred Nobel (whose legacy sponsors the Nobel Prize). Chemring Nobel deliver raw materials only, including various formulations of HMX, RDX, NTO, Alkyl-NENAs. Customers include companies like Rheinmetall AG (ETR:RHM) who manufacture the shells and ammo. I also hold Rheinmetall AG (ETR:RHM.
Well, I have my hate helmet on, so its time to venture out of the bunker and bring up the news today on Team Internet (LON:TIG) which has published its audited 2023 accounts and provided a presentation on IMC from the CEO and CFO.
The often noted concerns here are gradually being whittled away leaving, I believe an under appreciated company with a strong future. It used to have to explain why profits were in the future, well pleasingly the future has now arrived, with a PAT of $24.3mm. They have raised their revenue by 15%, bought back £28.4mm of shares, raised their dividend, paid out substantial contingent acquisition costs and still have cash and a not unreasonable debt level. The outlook is for more of the same.
Having spent much of today down up to 7% the market appears to be grudgingly relenting as it moves towards breakeven for the day. May this be the start of good things!
Thanks Aislabie, Team Internet (LON:TIG), I'd also add the share price has worried me less of late, that may be the ongoing share buy backs propping things up. Albeit small the dividend is doubled in today's announcement. As a holder I was pleased to see meaningful growth in both the advertising and domain divisions, and virtually all growth being organic. The cost of share buy backs and dividends is however no reduction in debt, which I ponder often! I'm insufficiently expert but one reason I see TIG as interesting is because it has adopted and embraced AI in it's everyday operations.
Team Internet (LON:TIG) , I hold.
I agree. FY figures looked good and the FD commentary on IMC particularly so.
Now nicely in profit, div doubled and with 23/24 share buyback programme about to conclude. No promises re 2024 use of spare cash but back of fag packet suggests net debt down to near zero unless spend on acquisitions or buybacks. Debt now much cheaper helping bottom line. Next figures (Q1/24) due in 2 months time and should be reassuring and future indicative given FDs comment that they will be within mkt expectations. Fingers crossed with optimism!
I owned Focusrite (LON:TUNE) back in 2017 for six months and feel for holders. I use to think that this was a good quality company that would offer steady returns over time.
I bought in early 2017 and sold six months later (no idea why) and as I watched the price move from mid 200's to £17 I berated myself for not staying in. Would I have got out before the precipitate decline? Based on my track record no. Now I could get back in for less than I paid in 2017.
However
"FY24 EBITDA is expected to be in the** range of £27 million to £30 million with a heavier weighting towards H2 than in FY23." Via Paul
puts me off. How can they possibly know? I need more information before I buy back in.
Regards
Michael
Another data point that UK Equities keep being unloved...
From Bloomberg, there is a snippet:
"Investors yanked $764m from UK-dedicated equity funds in the week ending March 13, according to data collected by the team at Goldman Sachs. There have been outflows every single week this year, taking the total since the end of December to just over $4.9bn"
It seems like last week's outflow was bigger than the average weekly in YTD so far....!
For long term investors in UK equities like myself, maybe it's a good time now to deploy more of my dry powder in the Boon Fund... I'm currently 20%+ cash, but a few buy price alerts have triggered for me in the last 1-2 weeks that I'm aiming to action.
I wonder what proportion of the total $4.9bn represents? Whatever its is, it's a significant amount of selling for the market to absorb.
What would be even more fascinating would be to know how much of this outflow turned into an inflow - directly or indirectly - for NVIDIA (NSQ:NVDA, ASML Holding NV (NSQ:ASML), Novo Nordisk A/S (NYQ:NVO) and other (justifiably or unjustifiably) frothy stocks. Whether such stocks do or don't constitute a bubble, I think the snowball effect of them on the UK market may have further to run and the gap in valuations between the UK and the US may widen further because there are still investors out there who don't own these stocks.
The only catalyst I can see to reverse this is such extreme value being present in the UK that it becomes a no-brainer on a risk/reward basis. That's tricky as I'm not convinced that all the possible electoral risk in the UK is in the price.
Where is the growth in the UK market?
NVIDIA (NSQ:NVDA) has gone up because growth, the forecast PEG is still below 1. They have benefited from cryto currency mining and AI software, needing higher spec graphics cards, shortage of supply increased orices considerably
ASML Holding NV (NSQ:ASML) is looking expensive.
Both ASML and Nvidia are on c.26x CY26 earnings for low to mid-teens growth. The former is offering a touch less growth but that valuation reflects its superior moat and lower cyclicality.
Well going by Stockopedia figures, NVIDIA (NSQ:NVDA) PEG is 0.8 and ASML Holding NV (NSQ:ASML) is 13.6
Rusty you never know-Sir keir Starmer and Rachel Reeves might bring growth.
We are allowed to dream sometimes.
I totally agree that the general prospects for growth in the Uk are much more limited than in the US. Obviously, there could be individual companies with similar prospects to the best in the US.
I also completely agree that there are very good reasons for the shares that I mentioned to have gone up and to continue to go up. I have completely under-estimated the potential of something that I was only able to see being used to write students' essays and allow drivers to watch TV instead of the road.
I'm not convinced that all the possible electoral risk in the UK is in the price.
You’re worried the Tories will get back in?
Not as close as the teapot but a good one!
Ha ha!
Marlowe (LON:MRL) (I hold) , any thoughts from someone following this ? RNS today confirms return in excess of £150M to shareholders following the completion of sale of some parts of GRC business. The form of return is not finalised (special payment or share buyback ) also there could be bolt-on acquistion for its TIC & OH business. Personally the most interesting bit from RNS today is Charles Skinner stepping down as NED. Lord Ashcroft, Alex Dacre and Charles Skinner were the main founders of Marlowe (all from Restore PLC). Alex Dacre will move out of Marlowe as part of GRC deal and now Charles Skinner stepping down. My speculation TIC & OH business is still in play for sell out (sky reported in Jun 23 for £650m). TIC & OH will genereate £400M Revenue and £54M EBITDA for FY24. Though TIC & OH has high recurring revenue it is not a high margin business as GRC , so an exit of 10x proforma adjusted cash EBITDA will give a total value of £690M (£540M + £150M cash from GRC) vs current market cap of £510M. Not a lot of upside, so i'm in a dilemma to sell when the return on cash news is announced or hold to see how it plays out.
Have a good day !
Gamma Communications (LON:GAMA)
Paul has mentioned this the other day and I had a close look over the weekend.
I will start adding this to my portfolio today.
FCF of £75m with net cash of over £250m in 2026.
Shares have been consolidating for two years now and this is very bullish for its SP.
Results out on Monday will probably confirm my thought that share buybacks should start immediately and put that extra cash to some useful use.
All the best
I agree yiannos, its a quality company I think with very solid metrics.
Bought after the Jan update and again on the breakout. For me one of the best looking charts out there, start of a nice stage 2 after a long consolidation by the look of things. Hopefully havent provided the kiss of death now :)
Interesting how investors often work in similar ways behind closed doors - I also bought Gamma Communications (LON:GAMA) this morning. I always like shares that have both the financials and the chart in their favour, I am not one to prioritise a chart over the financials but its certainly a nice added extra. Gamma Communications (LON:GAMA) is breaking out so nicely that if the results come in positive tomorrow we could see a real kick. If it completes the bowl its a near 100% upside, I don't think that's unrealistic, especially if forecasts for 2024 EPS growth are marked up from 7.6% (which seems conservative) tomorrow.
Well, it's been a very long time since I bought on a Friday afternoon and sold at the open Monday morning. If a company warns on profits I can handle it if it's due to a single factor, but the Focusrite (LON:TUNE) warning is so multi-layered I just had to get rid first thing. Possibly the worst aspect for me was the statement about a delayed product launch due to lack of engineering resource. As a life long engineer that rings alarm bells to me! That shows abysmal internal project planning, possibly key staff leaving the business or firefighting on other projects. Who's to say this will be the last warning for FY24?
Id say theres a good chance of another warning at Focusrite (LON:TUNE) Simoan as you say. After the Jan update - "significant weighting towards the second half, a period which is expected to include a number of new product launches." Id initially planned to use a possible profit warning to maybe start a position, but todays update serves up a smorgasbord of problems and potential worry. Aprils Results will be interesting reading.
Yes a disappointing update from Focusrite (LON:TUNE). The engineering resource issue I find particularly confusing, as they have already shipped 4th generation designs - I would have thought the design/engineering work would have been done for the whole range in one go, but clearly not.
At the risk of being accused of clutching at straws, there are a couple of positives. Margins remain strong and stable. The Focusrite brand is still holding a big market share. Indeed, I just checked on Thomann (the biggest European dealer) and Focusrite have 4 of the top 5 sellers in their particular segment, and ADAM 2 out of the top 5.
At least it looks like they haven't had to resort to drastic price cuts to shift the old stock.
Gulf Keystone Petroleum (LON:GKP) up 14% in last 5 days. I hold.
Hopefully the pipeline may be reopening after a year of closure?
GKP are situated on the 'good' side of the Suez canal (away from the Houtis). If the Middle East politics gets finally sorted and the pipeline opens, then this 'perfect location' means the SP should fly as bulk Tankers can fill in the Mediterranean rather than risk the Red Sea route or the extended route around the Cape of Good Hope. In the meantime the management have done a good job in minimising the problem by using overland road tankers to get their oil to market. Apparently they are getting a higher price per barrel too using this transport method rather than the pipeline, but volume is approximately halved. I hold and wait in hope! Definitely one for speculators and optimists!
Long term holder of Hipgnosis Songs Fund (LON:SONG) SONG - comical update this morning as they reveal they have double counted accrued revenue for years and have overstated the NAV by 8% and paid too much in fees because of it. NAV now down >30% in the last few weeks.
Ironically, Hipgnosis Songs Fund (LON:SONG) is being played out of Focusrite (LON:TUNE) today. They have both turned to Oscillate (OFEX:MUSH) ! !
Unfortunately a holder of both -but small positions and had been going to add to Focusrite but didn’t as I have been feeling there are continuing issues with stock in the distribution chain after the last update and given the global slowdown maybe the products are seen as luxury items? Are product launches not being managed well?
Given recent issues with Diageo (LON:DGED) not knowing it had problems with overstocking in Latin America it’s clear that things can go wrong in ways that management can’t necessarily control even for a blue chip never mind smaller companies without the processes and resource. Although, it has to be said that a small company should be closer to the customer in many ways! Has Focusrite (LON:TUNE) become too sprawling too quickly and not developed its management sufficiently? Disappointing as they have come across well on webcasts in the past.
As for Hipgnosis Songs Fund (LON:SONG) the only reassuring thing is the recent appointment of one Christopher Mills as a non exec hopefully he has his boxing gloves on for the showdown with Merck.
Another day another company Bytes Technology (LON:BYIT) where its CEO had unauthorised share dealings. The CEO has resigned. This one is even worse because of previous investigations.
It is a pity because it has taken shine of otherwise a very good set of results.
I hold.
Would like to know what Paul Hill makes of the Assetco (LON:ASTO) RNS?
He has got to be disappointed. They are becoming a very slimmed down business but still appear to be loss making.
That said I see the only significant value is there stake in Patmenion which will be worth more than the whole listing, maybe double. Hopefully the rest of the business becomes worth something before their cash pile grows too much smaller.
Net current assets less all liabilities is c£15m but that was 6 months ago.
Great question
To me Assetco's #1 objective is to become profitable & cash generative, alongside monetising its 30% stake in Parmenion.
Unfortunately though given the difficulties across the fund management industry, this appears to be taking longer than originally anticipated. Hence today's underwhelming FY23 results.
That said there's still plenty of cash on the balance sheet, so no need to raise fresh capital.
Meaning the stock basically remains work-in-progress.
A gloomy outlook statement from Marshalls (LON:MSLH) "In line with recent sentiment of UK economic and industry forecasts, the Board expects activity levels to remain subdued in the first half of the year followed by a modest recovery in the second half as the macro-economic environment progressively improves. The start of this recovery is now expected to be slower and more modest than previously assumed. Therefore the Board believes that revenues in 2024 will be lower than previously expected and that profit will now be at a similar level to 2023." One for the back burner.
I know there were high hopes for a rebound in construction (especially new home construction) starting like Q2, Q3 2024. But there's been enough cautious noise in the past month, that I'm not too sure we will see that.
The uncertainty of a general election and very possible change in government also doesn't help. Along with the uncertainty of when interest rates will start to fall.
On the flip side, does anyone know of any UK-listed building materials companies, that sell quite a bit in the USA, into the DIY / Home Improvement space?
Thinking that as homeowners there are "trapped" in their current houses (3% mortgage rates for 30 years), that there will be a boom of home improvement projects. Loft extensions, building extensions, outhouses, investing in better bathrooms, kitchens, etc... they are swimming in cash (with low interest rates) and unable to move...
I have been a holder of both HSS Hire (LON:HSS) and Speedy Hire (LON:SDY) over the years - currently only HSS Hire (LON:HSS) . Looked at HSS Hire (LON:HSS) last week I came to the same conclusion as you. Past problem of huge levels of debt is well on its way into history - helped by various sales of non core assets. They have a tendency to be extremely volatile - both on down and up - so depending on your timing you have plenty of opportunity to either lose your shirt or make a killing. I think we're closer to the latter than the former at the moment - but time will tell.
Looks like the volatility has kicked in at HSS Hire (LON:HSS) - up 7% yesterday and so far 9% today!
H & T (LON:HAT) chairman buys £20k worth. Shares have rebounded sharply since results last week. StockRank up by 70% over 30 days. Growth and Value look attractive:
He bought £67k in June 2023, a few months after being made Chairman. So this buy isn't huge, both in absolute and relative terms.
H & T (LON:HAT)
Focusrite (LON:TUNE) Trading Update today disclosing a profit warning. Demand for its products from amateur content creators continuing to be affected by the global downturn. As a result the SP currently down by 37%. Maybe a buying opportunity? As an amateur home music producer myself the products are excellent but I wonder how often users tend to upgrade unless they have to? I know that Cockney Rebel is a fan of this stock (or was!) and for me the investment decision is based on the future of demand from amateurs such as myself. I think long term it will improve but I'm looking forward to Paul's and others viewpoint. In the meantime, keeeeeeeep creating!
Focusrite (LON:TUNE) Surely this is similar to the Covid hangover we saw in the cycling sector. There was a surge in demand during the pandemic, but since these type of products are expensive and last several years, you're going to see subdued demand in the aftermath. However, looks a good quality company and they seem to be doing at least as well as their peers so could be a good recovery play, but probably not right now. Will add it to watchlist and monitor.
Focusrite (LON:TUNE) As you are a customer I'd be curious to know what competition Focusrite has and if they have any competitive advantage over other companies selling similar products? I imagine there's quite a few companies around selling very similar equipment so curious to hear your thoughts. Thanks!
They do really excellent home studio audio USB interfaces. Most people I know who do home recording have some Focusrite (LON:TUNE) equipment.
FWIW - I did a similar exercise to Paul and assuming the same gross margin and tax rate and adding 5% to admin expenses (which may be conservative if they can achieve the cost savings briefly mentioned in the TS), I came up with a figure of 22p
If this is a low or close to a low point in earnings, then the shares do have recovery potential but they do say there will be a heavier weighting towards H2 than in FY23, so there must be a chance that they miss again. However on the other side with interest rates due to come down and wages rising, consumer spending ought to recover soon.
I'd add the company do say '... Overall performance continues to be ahead of competitors in what is currently a very challenging market, indicating that Focusrite products continue to maintain or improve market share. Competitors though probably make the same claim
HSS and Speedy Hire
Been watching these fall and fall in past months and it’s starting to look seriously overdone .
Both massively below NAV (possibly understated due to increased valuation)
HSS still makes profit albeit reduced .
Both look slam dunk takeover targets .
If housing shares are bouncing these should by the same logic be following suit .
PE very low, yield very high .
Can’t see how they can go much lower so might tentatively start to add a few.
Can’t decide which is best bet, probably HSS and speedy seem to have invested heavily in hydrogen generators which looks an expensive investment albeit green and ESG positive and I think there is a regulatory requirement for phasing our traditional generators at sone point .
Any other comments before I jump , not sure if it’s a toe in the water job or a heads first dive ??
You might want to look at this excellent analysis of the hire companies
https://www.stockopedia.com/co...
and consider VP (LON:VP.) which I have recently bought into at these levels. It's a better quality company that either HSS Hire (LON:HSS) or Speedy Hire (LON:SDY) with the Chairman and majority shareholder, Jeremy Pilkington, looking to exit. It's the biggest holding of Rights and Issues Investment Trust (LON:RIII) from the time when that was run by Simon Knott. It has a greater diversification of end markets that the two you are considering. There is I would say a small risk of being taken private by the Chairman as there was a brief and unsuccessful attempt to sell it between April and August 2022 when, based on the price at the time, I would imagine the Chairman would have been looking for at least GBP15. Recent updates have reflected the subdued trading environment but this is a well-run business that has weathered previous cyclical downturns.
Thanks , I did read that yesterday .
Think there’s more bounce potential on HSS and looks more fun .
VP seems to have had its recovery whereas the other two are on the downward slide to oblivion .
Think VP is main market listing and I’m holding these probably in ISA so want the IHT benefit of HSS
So HSS held in ISA is the choice as large tax free dividend plus IHT cover .
HSS Hire (LON:HSS) Speedy Hire (LON:SDY) I would never catch a falling knife. The shares may be very cheap at the moment, but they may be even cheaper in a few weeks. If you hold off buying until the share prices have stabilised, then you are less likely to suffer an initial loss, and more likely to have a larger gain in due course.
I’ll scale in rather than pile in don’t worry .
Also once your invested you tend to pay much more attention than watching .
My strategy is normally just get a small starter position, then I’ll start to watch the price daily with dummy buys and sells to get a feel for spread and liquidity .
Once I’ve increased that knowledge tend to find I have decent ability to get my gut instincts in direction of travel .
Not a fan of sitting on the sidelines , if I’ I’m actively holding a few much easier to get a real feeling .
Just can’t see how HSS can capitulate much further and as Warren buffet says “we love it when shares get cheaper”
I wouldn't disagree that HSS Hire (LON:HSS) is cheaper. I'm sure you've noticed, though that consensus forecasts have been lowered by 32% since 13th Feb - i.e. a profit warning by stealth put out through brokers
I agree with mammyoko and have been slowly building a position in VP (LON:VP.) for many of the reasons stated. The one issue that has been a pain is the spread on VP (LON:VP.) shares which is sometimes quoted at an eye watering 5%., so one needs to be patient. There is not a lot of free float, about 17% from memory with 50% or thereabouts held by the founder and approximately 33% held by Institutions.
I doubt that Jeremy Pilkington would take the company private and he isn't going to sell it on the cheap. It serves a diverse range of industries and has a significant exposure to infrastructure. It mainly operates in the UK but also has operations in Europe and Australia.
Plexus Holdings (LON:POS) interim results are posted. I don’t see any surprises . Good to see confirmation that the SLB license payment of $5.2 million has been paid in January. The Chairman’s outlook seems very positive ‘With this background, and as the O&G industry continues to evolve, Plexus is poised for sustained expansion, offering innovative solutions that enhance efficiency, safety, and environmental performance from exploration through to the end of a well's life. This is anticipated to translate into increased value for shareholders.’
Plexus Holdings (LON:POS)
The Chairman’s outlook seems very positive
Surely numbers matter and positive talk wityhout nuymbers is just fluff?
Do we have any expectations for revenue and profits year ended 30/6/2025 - or is this positivity simply not backed up by expected decent real world numbers? Not sure how anyone can make any assessment of the companies prospects based on what has been provided by the company today ! Clearly 2024 results will be god but i have seen zero indication that 2025 will be anything like as good if profitable at all. I get it here that the company made decent numbers back in the day 10 years ago but surely we want something tangible here to back up assertions this company is anything other than a complete punt in the dark?
Surely if they are going places that should show up in ye 30/6/2025 expected numbers ?
Wait to see the CAPEX needed for a rental company cause this is what Plexus Holdings (LON:POS) is now.
Personal opinion this will end up in tears unless their revenues grow over £50m (I don’t think so).
CF Ashtead Technology Holdings (LON:AT.) - a rental company which seems to be thriving but with (apparently) limited Capex?
Ashtead Technology Holdings (LON:AT.) 30% of its revenues is CAPEX!
All the best
Ashtead Technology Holdings (LON:AT.) - additions of assets for rental in 2022 was 18% and 12% in 2021. Not sure where you are getting 30% from.
My point is that - even if you accept your statement that this is a rental company - there are clear examples of where specialist rental companies can prove to have a successful business model.
If Plexus Holdings (LON:POS) continue to win profitable 'rental' contracts, debt financing will be available as it is for other rental companies.
We all know what will happen if they don't.
I hold.
This is exactly what I said in my first post.
They need to increase their revenues as a rental company cause of the massive CAPEX. Since they sold their IP then one can easily assume that it is a rental company.
Ashtead Technology Holdings (LON:AT.) CAPEX can be found in all forward estimate reports till 2026-it’s about £34m.
All the best to shareholders.
Ashtead Technology Holdings (LON:AT.) - again, not quite sure where you are getting 34m from in terms of Capex. The results presentation for H1 2023 stated the following:
Investment of £8m in capex (£7.7m, in rental fleet), with FY23 forecast spend of £20m
So, Capex for 23 will be 18% of consensus revenue forecasts.
Per the company's website, consensus revenue forecast for FY25 is 178.8m - even if consensus forecast revenue for FY26 was the same, Capex as a % of revenue would still only be 19% in 2026. So, unless, you have access to information that isn't publicly available, Capex (and that includes al Capex - not just additions of items for rental) is never more than 19% for Ashtead Technology Holdings (LON:AT.) between 2021 and 2026 not the 30% you quote.
BTW, I also hold Ashtead Technology Holdings (LON:AT.)
Where we do agree is that, Capex is required for rental companies. I do not agree that Plexus Holdings (LON:POS) is a pure play rental company and think you over-simplify the disposal of non-core IP that was announced at the beginning of the year.
Ashtead Technology Holdings (LON:AT.) It is from paid research and the forward Capex is £34m for next year.
You can accept this or not but this is the figure I have in front of me.
Plexus Holdings (LON:POS) is clearly a rental company now for me. Again you can accept this or not but currently all the information I have in front of me leads to this assumption.
Plexus Holdings (LON:POS) has many red flags and I have already outlined them before.
All the best
34m as a % of consensus forecast revenues for 2024 of 162m is 21% and remember that that is total additions to tangible fixed assets not purely assets for rental.
So, I guess you are agreeing with me that your original statement that Capex as a % of revenues for Ashtead Technology Holdings (LON:AT.) is 30% is incorrect?
I would also be interested to know the source of your 'paid research' as sources available to me do not have the figure for Capex that you quote. I would be very interested to put this source to the company for confirmation as it is potentially price-sensitive.
You are, of course, entitled to your opinion that Plexus Holdings (LON:POS) is a pure-play rental company. I do not believe that it is but I do agree that there will be Capex requirements that will need to be funded. I believe that the company will have access to debt funding should it win profitable contracts that require such Capex. That's apart from its ability to raise capital from other sources.
You keep on reminding people of the red flags and I am sure that many people will be grateful for that. I think we are all clear that you are negative on this share so you might want to just let this play out - especially as you won't be around to contribute after the end of May when it's possible that your certainty may be proven wrong.
I will be around after May as many things have cleared. There are many other features in stockopedia that are very useful.
I will not be proven wrong as I haven’t been on Boohoo (LON:BOO) Joules (LON:JOUL^L22) Purplebricks (LON:PURP^F23) and many many others when everyone here thought were on their honeymoon by owning them!
Only recently I have shared the opportunity and the reasonings! on iShares Bitcoin Trust (NMQ:IBIT) and Trustpilot (LON:TRST). Both about doubled and these are big caps where you can buy and sell as much as you want in a single day with minimal spread. Cornerstone FS (LON:CSFS) doubled as well although not a big cap.
Same will happen with Kier (LON:KIE) Pressure Technologies (LON:PRES) and Revolution Beauty (LON:REVB). Personal opinions.
Plexus Holdings (LON:POS) should be priced on its Tangible Book Value as all other rental businesses should be valued. Personal opinion.
Ashtead Technology Holdings (LON:AT.) you are correct on the estimated revenues but my personal opinion is that they will not achieve that so I make the capex about 30%. Time will tell.
Move on we definitely disagree.
All the best
I'm sure we're all very grateful for your certainty about the future which far surpasses my own and also many others' on this board. I drop come across such certainty on other boards but Paul has consistently suggested that posters here temper their certainty about the future and most people respect this sensible suggestion. After all, if any of us were invariably correct about the future we would have little legitimate reason to post here. I am always suspicious of the motives of people who predict the future with certainty.
Thank you for confirming that you were wrong about the Capex on Ashtead Technology Holdings (LON:AT.) - it's a useful trait to admit when we've made a mistake. I've made many and continue to do so.
Firstly you should apologise if you are an honest person accusing me for motives and all that malarkey.
There is no motive here but when someone speaks an opposite view on your beloved holdings then the emotions come into play.
As for Ashtead Technology Holdings (LON:AT.) I am saying that there will a miss on estimated revenues and the CAPEX will be £34m. Personal opinions you do not have to accept them.
Is this a competition? I made wrong judgements in the past for example Mobico (LON:MCG) and I lost 22% of my initial investment but because I diversify well enough I don’t mind I don’t take notice and I move on. I made 200% on McBride (LON:MCB) and still hold half of my initial investment for free.
I was so so so negative on McBride (LON:MCB) but because Boon wrote something : about stabilising input costs! Then I had a look at projected revenues and suddenly it just clicked-they will have no problem paying down their debt as inflation stabilises(always does).
Three words from Boon and an almost 6 figure gain.
So move on , pay attention to what everyone says here and do your own research as I do.
All the best
Your comments are classic examples of Thouless's logical fallacies in 'Straight and Crooked Thinking' which I recommend to everyone on this board. Logical fallacies include astraw man arguments, false analogies, and appeals to emotion or authority (thanks for the reminder ChatGPT!)
Ashtead Technology Holdings (LON:AT.) - you are obfuscating. I questioned your statement that their Capex requirements were 30% of revenue. I did not question whether you were correct that there is a forecast of 34m for Capex. You have admitted that that was incorrect information - at no point is Capex forecast to be 30% of revenue except by your own forecasts which you did not make clear. This is exactly the kind of communication which I am talking about - putting out incorrect information, claiming you have paid research to support it then trying to justify the original statement when your error is revealed.
You are also trying to imply that my motive for this exchange is because I am trying to defend my positions on either Plexus Holdings (LON:POS) or Ashtead Technology Holdings (LON:AT.) . Nothing could be further from the truth. My agenda is only to try and highlight that I find your style of communication (and have observed that others feel the same) sometimes breaks the rules of engagement here and where it has done so I have flagged those comments for moderation. Sometimes, the moderators have agreed and your comments have been removed.
No doubt there are people on this board, as you say, who have benefited from your comments. I am not one of them, though I have benefitted from many others comments here. Frankly, I find your assessments of companies glib and your certainty about the future unconvincing. Just as you have, I believe, in the past correctly reminded us all not to follow Paul's advice slavishly - and I sense some of that in your persistent and simplistic attacks on Plexus Holdings (LON:POS) - I am glad that we have had this exchange today so that anybody reading this can form their own opinion as to whether they should rely on your views in any way.
BTW, I am an ex-Group Financial Controller who has prepared group statutory accounts for multi-billion conglomerates so I always do my research. I merely mention that in response to your suggestion that I do my own research. It doesn't stop me from making huge mistakes though! That's because the accounts are just the starting point for attempting to predict future performance and I am much less competent at predicting the future (hence my dismissal of AI) than you claim to be.
Having not used marketscreener (which appears to be free to use, not as you described it 'paid research'), I checked out the Capex forecasts for Ashtead Technology Holdings (LON:AT.).
This is what the site shows:
I am perplexed as to where you came up with the GBP34m of Capex for 2025 when your own source shows this to be GBNP32.1m
I am also perplexed as to why you chose to misrepresent your own source of information which clearly shows - on the line below capex - that capex as a % of sales is never more than 18.85%.
It is precisely this type of misinformation that needs to be corrected. I'm afraid I don't buy your explanation that you think that sales for 2025 will be GBP 113m which is what you have said they will be to justify your assertion that capex of 34m will be 30% of sales. This implies a miss of 30% on consensus sales forecasts of 162m for 2025 and alone justifies a healthy amount of scepticism with respect to your views!
From September 5, 2023, Ashtead Technology Holdings (LON:AT.) is effectively partly a brokerage using its technology to hire under utilised equipment from one company to another. https://www.stockopedia.com/co...
I hold
Naked Wines (LON:WINE) - one of Simon Thompson's Bargain stocks 2024....
Sunday's podcast had a "mystery share" - my best share idea for the week, exclusively for Stockopedia readers. This was Bodycote (LON:BOY) - see Friday's report here. Beware it's my first look at this mid-cap, so I might have missed something. At first sight though it looks an attractive business, performing well, at a modest valuation. Obviously DYOR as always, and let us know what you think.
With all the attention on Bodycote (LON:BOY) , I remembered that that I had looked at it and turned it down but couldn't remember why (must keep better notes). My problem was it is basically back to below where it is was in 2018, but with higher turnover and lower profits.
So the growth we are seeing is just a slow recovery from Covid. My plan is to try to buy companies that I can keep for ever or if I buy cyclical - know they are cyclical and sell when around an all time high and buy back when out of favour. Perhaps "Profitable growth" is the same as "strong balance sheet", when you read it be a bit sceptical - this company has added about £100m of turnover and produced less profit.
I'm not saying there isn't a trade here, but it's not for me.
While your numbers are incontrovertible, it’s important to consider that in 2018, Bodycote was nearing the top of its cycle, whereas today it appears to be starting its ascent from the bottom. Consequently, comparisons of the financial performance need to be blended with a look at the share price chart, which is the market’s assessment of its position along the cycle. That paints a rosier picture, albeit for a dividend-backed trade rather than a very long-term hold.
You make a fair point and I recognise that there may be a trade here. The dividend barely covers inflation, so we do want some capital growth and with the current share price there is some scope for growth.
I agree that there will be differences from 2018. My point that cyclical companies often spend alot of time trying to persuade the market that they are not really cyclical and if that starts to be reflected in the share price with a substantial multiple on a high % return on sales, that is the time I like to take profits.
So note the outlook statement in 2018, it didn't turn out like that:
Bodycote (LON:BOY)
I think you have cherry picked your data here matinck1 to make your point.
Clearly this company has periods of peak performance and clearly there can be large variability in the profits of this company. To take a peak year in isolation where the profits of that year were up a whopping 33% over the average for the previous 4 years and use that as a yardstick to beat the company with is imho cherry picking data to make the company look worse than it is. They will have been far from alone not seeing the next slowdown in market conditions coming if 2018 was boom time. I would agree there is an argument for saying that overall growth since 2014 has perhaps been pedestrian and perhaps you could be right that they are going nowhere - but if you look at the entire period showing up on stocky and look at the trend from 2021 onwards its not one of a profits zero growth company even if it is factually correct that it will be next year before they break the record (of the last 10 years). I am of course presuming we are not nearing peak profits now ref this current cycle.
Bodycote (LON:BOY)
rmillaree: I was more interested in understanding why I had rejected a share that is now flavour of the month. I had looked at it, wanting to find reasons to invest because I don't spend time looking at a stock to reject it, so its not cherrypicking. I then didn't invest because of how it has performed since 2018 and based on my view of its cyclicality.
I also know from previous experience that BnB and I share a number of investments because we like many of the same things; organic revenue growth, strong free cash flow and consistent high % return on sales and capital, so always interested in different perspectives.
At the end of the day, our choices are just a view on the balance of risk, with a guess on what the future holds supported by data and history. It wouldn't surprise me if Bodycote produces another year of growth. It's more that at some point its cyclicality will return and on a historic 14.7x share price and a 15.9% return on sales, I don't like that balance of risk.
Good luck to holders.
Bodycote (LON:BOY)
rmillaree: I was more interested in understanding why I had rejected a share that is now flavour of the month. I had looked at it, wanting to find reasons to invest because I don't spend time looking at a stock to reject it, so its not cherrypicking. I then didn't invest because of how it has performed since 2018 and based on my view of its cyclicality.
the whole point of cherry picking data is that it can be unintentional - imho you have clearly cherry picked the data here by cross referencing 2018 only as yardstick and ignoring the fact that was clearly a boom year compared to what proceeded it (and followed it) - ignoring comparisons with the 2018 boom year the profits are clearly up long term since 2014 (not a briliant growth rate i must admit) and the profits have been trending very nicely since 2021 ( as one would probably have expected with low point of 2020 and 2021 being particularly poor).
per wiki
Cherry picking, suppressing evidence, or the fallacy of incomplete evidence is the act of pointing to individual cases or data that seem to confirm a particular position while ignoring a significant portion of related and similar cases or data that may contradict that position. Cherry picking may be committed intentionally or unintentionally.[2]
I think you have cherry picked your data here matinck1 to make your point.
I'll let you have the last word after this.
My point is that I wasn't cherrypicking "to make a point". I researched the company before the discussion here to decide whether to make an investment. I don't spend time on a company if I have a predisposition to not invest.
The 2018 headline profit was only 12% up on the prior year, so not obviously an unusual performance.
I guess I can agree that focusing on any individual piece of information is indeed "cherrypicking". I am assigning more importance to that piece of data.
Good luck to holders.
Bodycote (LON:BOY) only had a very quick look, but doesn't seem to have generated much revenue or profit growth over last several years, while share price is basically flat over 10y. Obviously a very crude assessment, but at first glance doesn't appear to offer much in the way of growth.
We can't underestimate the impact of covid on Bodycote (LON:BOY) which hit their business hard, understandable given they service the likes of the civil aviation sector. Needs to be taken into account when looking at historical numbers. As I understand it they also took this period as an opportunity to get leaner and more profitable / cash generative as things normalised.
Key points from an interview with Schroders on Bodycote (LON:BOY) below that I listened to after going through the FY 12/2023 numbers which I agree look very strong with very strong cash generation that is now being used to fund a recently announced share buyback: They got beaten down because of the anticipated effects of a downturn in the automotive industry but in November they said that upturn in the civil aerospace part of the business was strong and compensating, effectively removing air bubbles from key components with high pressure as I understand it – something you wouldn’t want to cut back on! There was also a question mark over whether they would be able to pass on a significant rise in energy costs onto their customers which was depressing the share price. In the end they have shown that were able to do this through surcharges, showing they have pricing power, and a strong competitive position in the market for what is an essential service. They also got more lean and mean during Covid and are starting to benefit from that now as we are starting to see coming through in their numbers. They are also exposed to defence where spending is unlikely to dry up any time soon unfortunately. Good entry point in my opinion but it would be good to hear any bear points.
Paul,
Thanks for the heads up with Bodycote (LON:BOY) .
I did some work on it on Sunday and took a starter position this morning. I always write a short note ( inc Bull and Bear points), to remind myself of why I decicided to buy (and sell) and my likely max position. My buy note to myself below....
Good results and outlook. 3M positive relative strength. F8 and 0.8 PEG, so improving financials and GARP. Operationally geared. £60M share buyback announced.
Passes "Earnings Manipulation screen" so 2x start position maximium. 5Y historical PE 15x so undervalued @ PE 12x and is a potential takeover target.
Great podcast as always Paul you said tuesday but did thursday report somehow and left tuesday out
https://www.stockopedia.com/co...
Yes David. Paul jumped from Monday to Thursday, then did Wednesday and finished with Friday. It threw me a bit and i assumed at the time that I might have nodded off (nothing to do with the content Paul, which was brilliant and informative as usual, just my age)
Oh crumbs, sorry about that. I did suspect that I'd gone a bit wrong in the podcast, but was too far into it to start again.