Small Cap Value Report (Mon 18 Sept 2023) - SFOR, BPM, PDG, CTG, TPX

Good morning from Paul & Graham!
Reminder - it's Mello Monday starting at 17:00 today. Well known fund manager Judith MacKenzie is on first, then it's the new Director Hot Seat feature. Last week's was really interesting, with the CEO of AFC Energy (LON:AFC) subjected to a thorough grilling from an experienced investor. I thought he coped very well! Let's see if tonight's CEO will stand up to scrutiny too?
I (Paul) was starting to feel unwell on Friday, and tested positive for covid on Saturday morning - it's spreading like wildfire in London, where I am at the moment. The good news is that the symptoms are definitely milder than the first wave in April 2020. I've experienced a very sore throat, mild fever, and lethargy as the main symptoms. So my top tip is for subscribers to stock up with soluble aspirin and paracetamol, because they're a necessity for this variant. Anyway, I'm bored stiff after doing nothing for 48 hours, so will do some work here, but please bear with me if it's not fully up to scratch.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
S4 Capital (LON:SFOR) - 95.5p (pre market) £556m - Interim Results - Paul - RED
As usual, a wide range of performance measures is provided, confusing us - what is reality, and what is spin? If in doubt, I look at cashflow, and SFOR doesn’t generate any! Meanwhile it has £111m in deferred consideration to pay shortly, which will increase net debt to dangerous levels I think. This group looks distinctly wobbly to me.
B.P. Marsh & Partners (LON:BPM) - up 2% to 372p (£138m) - Trading Statement - Graham - GREEN
A reassuring update from this investor in early-stage insurance intermediaries. Offering specialist expertise in a small niche of the financial services industry, I am a long-term fan of this investment vehicle. They intend to return £6m to shareholders in the near future.
Pendragon (LON:PDG) - Up 28% to 23.7p (£330m) - Proposed Disposal - Paul - GREEN
An interesting deal, to sell its UK car dealerships & leasing business to an American dealer called Lithia. Then the proposal is that PDG becomes a standalone software company, Pinewood Tech, which is buried in the existing group, and seems to have interesting potential. My only worry is whether PDG has sold its core business too cheaply - that does seem to be the case, based on numbers out from Zeus (many thanks) this morning.
Christie (LON:CTG) - down 5% to 104p (£28m) - Interim Results - Graham - AMBER
This diversified professional services group reports an H1 loss after economic conditions slowed down transactions at its small business brokerage. I expect that it will find its way towards performance recovery but still struggle to get excited about the opportunity here.
Tpximpact Holdings (LON:TPX) - up 1.5% to 41.1p (£38m) - Disposal - Paul - AMBER/RED
I’ve expressed serious concerns about the debt problems at this software contracting business. However today’s news is a lot more encouraging. It’s sold a Bulgarian subsidiary for £7.5m, and will use £5m of the proceeds to reduce debt from £17.9m at 6/2023, to forecast £11-12m at 3/2024. I imagine the bank is likely to be very relieved at this, which in turn reduces risk for shareholders. It will mean losing £13.1m revenues and £1.3m of aEBITDA though, so forecasts will have to be reduced (rather misleadingly glossed over in today’s update I thought). Current trading is in line with expectations. Some big orders have been previously announced.
Paul’s view - this strikes me as key moment, where the risk of insolvency or deep dilution have greatly receded. If TPX can improve its profit margins, which is the plan, then shares could be worth a fresh look. Although several of these IT consultancies have gone badly wrong recently, and it strikes me as being a tough, competitive space, so doesn’t really interest me. But things have clearly improved, so I’ll move up from RED to AMBER/RED. [no section below]
Paul’s Section:
S4 Capital (LON:SFOR)
Down 25% to 72p (at 09:07) £417m - Interim Results - Paul - RED
This is Sir Martin Sorrell’s fast-growing (by acquisition) digital marketing group. Clearly his reputation is second to none, after what he achieved at WPP. However, I’ve never liked the figures at SFOR, and viewed it negatively, RED, on 24/7/2023 (down 20% on a profit warning), 9/6/2023, and 11/5/2023 (in line Q1 TU).
My main concerns are: weak, highly geared balance sheet, and huge adjustments needed to produce any profit, and no genuine cash generation. So major concerns!
Let’s take a look at today’s interim results, with fresh eyes.
Shares have dropped a lot, so there might be a turnaround opportunity here perhaps?
I should add that, in a bear market, it’s easy to fall into the trap of thinking a negative opinion on any share has been proven correct, because the shares are falling. Whereas in reality, it’s often just caught up in a general market downturn, and could be a bargain. Sometimes.
Hence why it’s good to keep an open mind, and change our minds if the facts change.
I’ve just looked at the share price, and seen it’s down 23% to 74p, so clearly the market isn’t impressed with the numbers/outlook today.
My first impression of these numbers is that they're almost unintelligible! We’re even given 3 different figures for revenue! (£925m billings, £517m revenue, and £446m net revenue).
We have a range of profit measures, from adj EBITDA of £36.5m (up 21% reported, but down 30% LFL).
Adj PBT is positive, at £13.8m, down 9% on H1 LY.
Statutory loss before tax is £(23.2)m, much improved from £(85.6)m in H1 LY.
This table does a good job in demonstrating how EBITDA is a nonsense number at SFOR - because the costs it excludes are real-world cash outflows, you can't just ignore these costs! -

Balance sheet - this is a deal-breaker for me. Marketing spending is often cut by customers in a downturn, so that makes it all the more important to have a strong balance sheet to fall back on. SFOR has a very weak balance sheet, the way I calculate the numbers.
NAV was £828m at 30 June 2023. But that included £1,095m of intangible assets, mostly related to acquisitions (goodwill & similar). Deleting that, gives us negative NTAV of £(267)m.
It held cash of £213m, which was exceeded by “borrowings” of £317m, that figure excludes lease liabilities.
So anyone investing here would need to focus on the terms of that debt, in particular what covenants apply? Today it says that debt maturity is long-dated, and that it has complied with covenants (so far).
The borrowings are also expensive - note that net finance charges shot up to £17.5m in H1.
There’s a timebomb on the balance sheet of £111m contingent consideration payable in the next 12 months, which will significantly increase net debt.
Cashflow statement - much as I expected, SFOR doesn’t generate any cashflow, once all real world costs are taken into account.
Outlook - oh dear, it’s another profit warning.
Following slower than expected trading over the summer months, including August and current client activity levels, full year expectations have been further revised. Like-for-like net revenue is now expected to be likely down on the prior year and operational EBITDA margins are now targeted to be in the range of 12% to 13.5%. As in recent years, we expect the full year results to be heavily Q4 weighted reflecting our seasonality and anticipated client activity9.
Our net debt7 will rise in H2 2023 reflecting payments for prior year combinations, after which virtually all of the existing contingent consideration due will have been satisfied. Our expected range for the year end is £180-220 million. We aim for financial leverage of around 1.5 times operational EBITDA over the medium term.
Paul’s opinion - for the reasons outlined above, I think this looks a mess. Why get involved? I’m struggling to understand why the equity is worth anything at all, given that SFOR doesn’t generate any cash, yet will have £180-220m net debt by the year end.
Shareholders must be hoping that it can turn things around, cut costs, and somehow increase revenues. Why would I want to gamble on that? It seems to me that Sir Martin has created a monster here, with over-rapid expansion, at the worst point of the cycle. Bulls will have to hope that his reputation can carry the day, because these numbers certainly don’t.
Pendragon (LON:PDG)
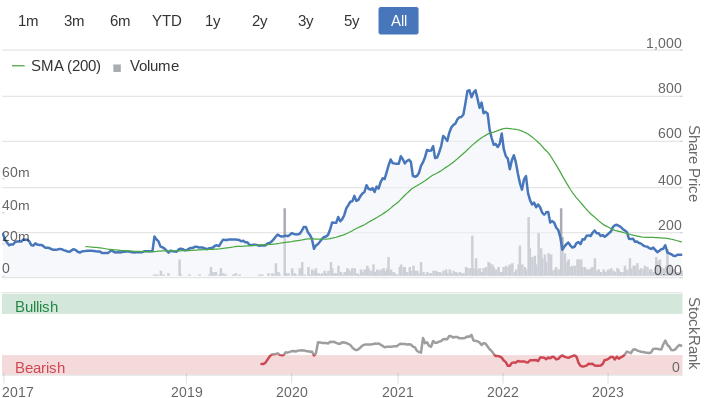
Up 28% to 23.7p (£330m) - Proposed Disposal - Paul - GREEN
UK car dealer Pendragon has done a deal with Lithia Motors (NYSE:LAD) - mkt cap £6.5bn per Lithia's StockReport here (requires US subscription) and also on a low fwd PER of 7.8.
This is an unusual deal, PDG is selling to Lithia for £250m -
“the Company's entire UK motor business and leasing business”
Cash proceeds will be paid out in a dividend of 16.5p (approx. £240m total)
Lithia will invest £30m in new equity into Pendragon, at 10.7p per new share (but no entitlement to the special divi, so it’s really 27.2p for comparison.
Pendragon’s continuing business seems to be its SaaS software subsidiary, Pinewood Tech, meaning that it will be a much smaller, and less liquid share to own (which might lead to some institutions wanting to exit maybe?) But it claims higher growth potential.
Joint Venture with Lithia to roll out Pinewood software in the US - sounds interesting.
Key details we need, are -
Will Pendragon shareholders support this deal? It has one major shareholder called Hedin, owning 27.6%, that I think tried to bid for Pendragon itself a while ago, but it fell through, I can’t remember any details about that. Hedin is notable for its absence from the list given today of institutions totalling 26.5% that have agreed the deal -
Schroder Investment Management Limited, Briarwood Capital Partners LP, Hosking Partners LLP, Farringdon Netherlands BV, Huntington Management LLC, and Sir Nigel Rudd.
2. We need to see pro forma accounts for Pinewood. It says today that Pinewood made £15m EBITDA in FY 12/2022, and hopes to grow that to £27m EBITDA by 2027. However, as we always point out, software companies’ EBITDA is often a fantasy number, due to capitalising of development spending.
Pinewood Technology accounts - I’ve looked these up from Companies House, and for FY 12/2022 it did revenue of £25m, of which almost all £24m was in UK & Europe - so the expansion into the US would be incremental sales, which I like.
Operating profit was a very impressive £11.0m, although we have to be cautious when looking at accounts for subsidiaries in a group, because numbers can be skewed by intra-group adjustments.
Pinewood’s balance sheet looks healthy, with NTAV of £17m, so the injection of a fresh £30m in new shares to be subscribed for by Lithia Motors, suggests to me that Pinewood should be very strongly capitalised as a standalone SaaS company, using Pendragon’s listing in future. If this possibly because a lot of money might be spent to launch its roll-out in America? Lithia is taking all other liabilities with the main operating business that it's buying, so Pinewood Tech looks like it will be a clean, well-financed newly standalone business.
Paul’s opinion - I need more details, but based on the limited information available today, I think this looks an interesting situation. I’m tempted to buy a few PDG shares, at c.24p now, get the 16.5p special dividend, and then end up with a stake in an interesting software company which could increase nicely in value, if its US expansion works out (and being hand-held by a large US partner helps for that roll-out).
What could go wrong? The obvious risk is if Hedin blocks the deal. So it would be important to find out if the shareholder vote is an ordinary (50%) resolution, or a special resolution (75%), if its a special resolution then Hedin could block the deal. Could Hedin launch a renewed bid for Pendragon itself, I wonder?
So I feel that the main downside risk would come from Hedin blocking the deal, then the share price losing its (effectively) bid premium, and dropping back to say 20p. So 20% downside risk, but potentially nice upside if the deal goes ahead, and the market rerates new Pendragon (Pinewood Tech) to a tech company rating, which it might well do.
Based on incomplete information, my hunch is that this deal could be good for PDG shareholders, I like it. GREEN.
Our most recent 3 previous comments on PDG have also been GREEN.
Now when will someone come and bid for Vertu Motors (LON:VTU) ?!
One final thought - I've just looked at an update note from Zeus, which flags up that PDG seems to be selling its core business on a very low valuation multiple. So whilst I accept the strategic rationale for this deal, I wonder if they could have got a better price?
Graham’s Section:
B.P. Marsh & Partners (LON:BPM)
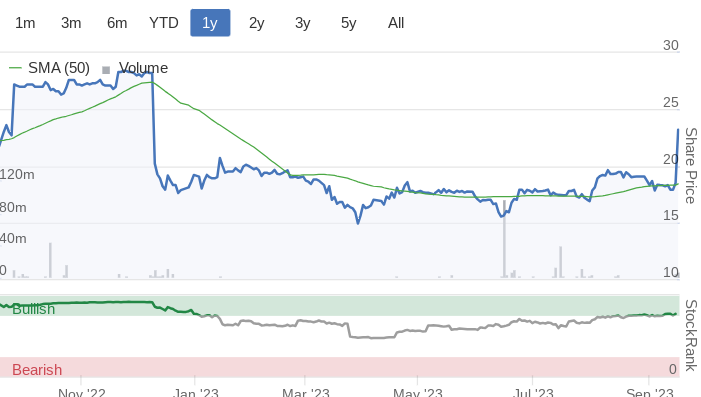
Share price: 372p (+2%)
Market cap: £138m
B.P. Marsh & Partners Plc (AIM: BPM), the specialist venture capital investor in early stage financial services businesses, is pleased to provide the market with an update on trading for the Group's six month period ended 31 July 2023.
I covered this company’s full-year results back in June. I was positive about it due to its excellent long-term record plus the ongoing share price discount to NAV (NAV at 526p or fully diluted NAV at 516.8p, vs. share price at the time of 390p).
The BPM share price has softened a little since then, despite the company buying back its own shares.

Today brings a trading update for H1 (the period to July).
Kentro: the £51.5m disposal of BPM’s stake in this business remains “dependent on certain regulatory approvals and completion mechanics and a further announcement will be made when all conditions have been met”. Note: the disposal price matches Kentro’s balance sheet value at BPM, so I’m not expecting the deal to trigger any change in BPM’s net asset value.
I have no reason to believe that this disposal will not be going ahead.
Dividend and buyback policy: as previously announced, shareholders should get £2m in dividends each year for the next three years, plus a one-off £1m special dividend.
For buybacks, the company is planning a £6m return of capital - “the specific mechanics of how this will be achieved are still under consideration and will be announced in due course”. A tender offer might be the fairest way?
In total, that’s £13m going back to shareholders over three years, or 25% of the expected Kentro sale proceeds.
Latest NAV? We will have to wait and see. “The Group remains positive regarding its ongoing performance.” H1 results will be out on 17th October.
New investments
Shares in the new insurance broker Pantheon, and a loan to it.
Shares in Verve Risk Services
Ongoing investments - highlights
Lilley Plummer Risks - performance “continues to be impressive”.
CBC - “continues to trade significantly ahead of budget”. Achieved £7.5m of adjusted EBITDA in the first seven months of the year, versus full-year expectations of £5.5m.
Cash - it sounds like cash is currently very thin. I think they have a tendency to be fully invested in their portfolio, a policy which makes sense to me. They have no debt.
New opportunities - it remains business as usual on the investing front, although they may feel some pressure to start deploying the proceeds of the large disposal soon.
There are “a high number of potential new business opportunities” and they are “ready to take advantage of opportunities emanating from the financial services industry generally, and the insurance market specifically”.
Industry outlook - in aggregate, insurance rates continue to increase every quarter. UK rates have increased every quarter for the past year and BPM “does not anticipate the market returning to the pricing of the last soft market in the short to medium term”.
Insurance strikes me as a good industry to invest in for protection against inflation: insurers are never shy to increase rates to offset their cost increases!
Graham’s view
No reason for me to change my view on this one. It’s an excellent long-term performer, it’s trading at a significant (c. 28%) discount to NAV, and it’s buying back its own shares. I like the industry and I like the way it gives access to an insurance niche that would otherwise be difficult to invest in. So two thumbs up from me.
Stockopedia likes it, too:
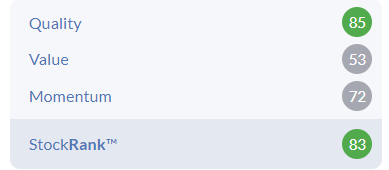
It passes two stock screens, including one of my favourites - the “Neglected Firms Screen”!
Christie (LON:CTG)
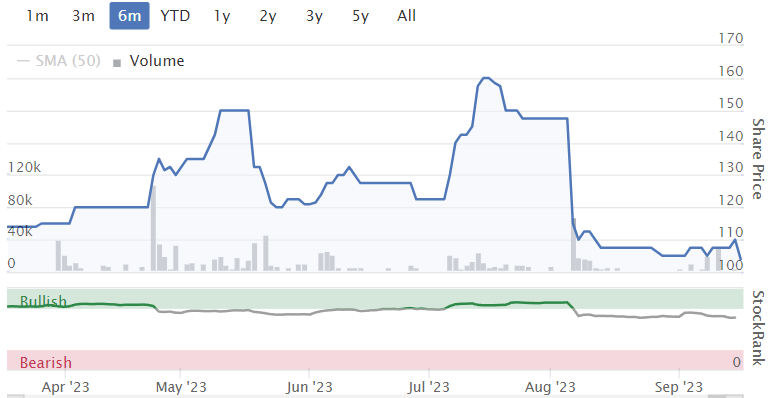
Share price: 104p (-5%)
Market cap: £28m
We already had a recent profit warning from this professional services company. See my comments in August.
Christie has a particular emphasis on brokering the sale of small businesses - but low levels of activity over the summer months have weighed on the stock.
Today brings interim results. Highlights:
Revenues down 1.6% to £33.1m
Operating loss £1.4m (a loss was expected).
The “Inventory Systems and Services” division books a £1m loss, about the same as the loss in H1 last year. Christie acknowledges that it will remain unprofitable at the current level of revenues.
The “Professional and Financial Services” division books a £0.4m loss, versus a profit of over £3m in H1 last year.
Interim dividend: 0.5p (last year: 1.25p).
Outlook doesn’t promise too much:
The delays in transactional deals seen in H1 have continued into the summer period, and the full year outcome will be determined by the number of deals which can be brought to contractual exchange in the remaining four months of 2023. As vendors and buyers adjust to the changed economic environment, we anticipate more normalised levels of activity resuming.
Transactional pipelines have recovered to levels similar to a year ago…
Earlier in the statement, they say “uncertainty remains as to the timing of transactions which will exchange in 2023 as opposed to 2024”. Visibility around the 2023 result seems to be very limited indeed.
Graham’s view
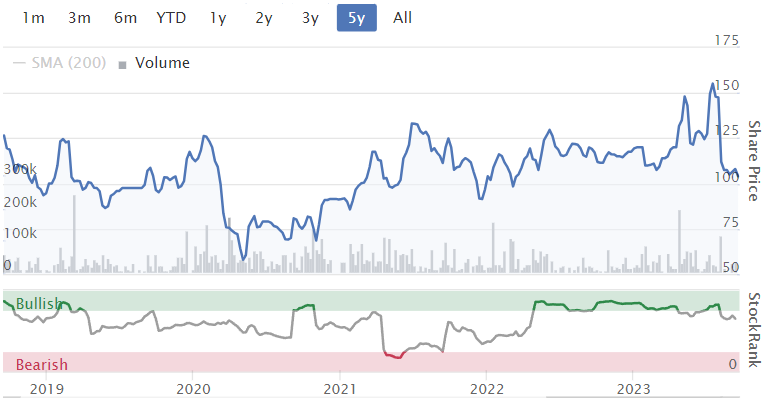
I am maintaining a neutral view on this stock. On the positive side, it has a small net cash position, a very long operating history (usually profitable), and is largely owned by insiders and their relatives.
Against that, there is some uncertainty at the top with the loss of the largest shareholder Philip Gwyn from the Board (28% shareholding, and his relatives also have significant shareholdings).
More fundamentally, I don’t see any medium-term or long-term growth here that is worth writing home about. A solid and diversified professional services business, perhaps, but I’m unconvinced that it makes for an interesting investment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Talk about punchy valuations for a restaurant business... EUR270m for 23 sites at Big Mamma Group.
Big Mamma group sells majority stake to private equity - https://on.ft.com/3LsmnMc
Now if only some of the ftse listed hospitality groups could be valued at £10m+ per site....!
A vaccine reduces the symptoms and seriousness of a disease (bacteria or virus) that has already infected the host. Vaccines do not work like a 'magic shield' that prevent the virus/bacteria from entering (=infecting) the body in the first place.
Vaccines generally work by 'readying' the body's immune system (usually by the quick production of antibodies to neutralise the virus or bacteria) - but this generally only happens AFTER exposure to the virus or bacteria - ie. an infection - the virus/bacteria has already entered the body and 'infected' the host.
Perhaps they're suggesting that vaccines 'prevent infection' by making those who have already been infected less likely to spread the disease thus preventing the disease in others (which is another reason why most of us should be vaccinated)...however vaccines do not prevent the vaccinated from catching the disease in the first place - they reduce the severity of the disease, sometimes to the point that the symptoms of infection are so mild as to be non-existant - but this person has still been infected.
I guess there are 2 definitions of "having the 'flu or covid etc": 1.Being infected with the virus and having no symptoms (which is a more scientific/medical definition - not having symptoms does not mean that the person is not infected - they still have the virus in their body, but it is being fought off efficiently by the immune system) or 2. Being infected and having symptoms - which as a patient we'd describe as "having the 'flu"!
I guess there are 2 definitions of "having the 'flu or covid etc": 1.Being infected with the virus and having no symptoms (which is a more scientific/medical definition - not having symptoms does not mean that the person is not infected - they still have the virus in their body, but it is being fought off efficiently by the immune system) or 2. Being infected and having symptoms - which as a patient we'd describe as "having the 'flu"!
I would say with both 1 and 2 you have the virus - thats simply Asymptomatic or not Asymptomatic - whether you show symptoms or not you clearly have the virus when tested.
From what i have read the net clearly suggests that to a greater or lesser degree it also CAN protect you from getting the flu. This kinda makes sense if the virus turns up (you are exposed) and the body prevents it infecting cells practicably speaking.
If you want another site that suggests the flu jab CAN prevent the flu then the mayo clinic say the following. Note i aint saying it will prevent the flu - just that sometimes it may do that according to these sites - it would surprise me if they would get it wrong by using sketchy language.
https://www.mayoclinic.org/dis...
Reviews of past studies have found that the flu vaccine is about 50% effective for healthy adults who are between 18 and 64 years old. The vaccine may sometimes be less effective.
Even when the vaccine doesn't completely prevent the flu, it may lessen the severity of your illness.
ok thats enough of me going ot for one day if that doesnt convince you i give up - i aint a doctor so i could be spreading false info - apologies if that is the case !!
I'm a doctor! I think the confusion lies in how the language is used: medical vs colloquial.
Point is, vaccines work on the whole.
All the best.
I’ve always liked Bango (LON:BGO) but don’t hold at the moment. I have a soft spot for them having made decent money in the rise up to 180p.
However, they have touted significant cash flow profitability for a while and the sceptic in me says they have always managed to find something to obfuscate achieving this in quite the way investors expect. It’s usually been something “transformational”.
Anyway this time may well be different but I’d just caution that it may pay to keep a sceptical eye open and not get too drawn in by the promised H2 and beyond. I plan on keeping them in the watchlist but I really want to see the tangible evidence come through that strong positive cash is going to start flowing through the coffers and not just out a different door!
Anyway that’s not to say they are a bad investment or don’t have strong potential.
Rightmove predicting house price rise!
of course they do. The stock market, however, has a big bet on house prices falling significantly over the next few months. How? by betting against the house builders shares which are down on average by 50%.
The market is right, House prices will fall but the house builders shares have already priced in that fact.
I think the Housebuilders shares have bottomed out but the house prices has further to drop.
Its funny how so much of the house price tracking and commentary only comes from a few big sources - Rightmove, Halifax, Nationwide. Who all have vested interests to keep people buying, and house prices going up.
I don't think they're being fraudulent and changing the data that is released. But the spin they put on things, and the PR exercise with the media to highlight cherry-picked statements, is one to be wary of.
I have this on my diary front page :o)
'Projections should be handled with care, particularly when they're being provided by someone who has an interest in misleading you' Charlie Munger, Berkshire Annual Meeting 1995.
Vaccines don't stop anyone from catching anything - they dont work like that! But they do significantly reduce the risk of serious illness & hospitalisation.
"Vaccines don't stop anyone from catching anything - they dont work like that!"
Are you sure?
- per NHS Wales
"Having a yearly flu vaccine is one of the best ways to protect against catching and spreading flu."
https://phw.nhs.wales/topics/i...
Note they are very much more circumspect about boasting that the covid vaccine reduces your chances of getting covid - that suggests the data there simply isnt available or perhaps doesnt reduce chances of catching covid if it does.
there are random other websites stating that per the cdc flu vaccines can reduce chances of getting the flu by up to 40%
Must admit i am not expert here so i could be wrong
there are random other websites stating that per the cdc flu vaccines can reduce chances of getting the flu by up to 40%
It varies by vaccine and disease (so flu and Covid are different), but generally a vaccination will reduce your chances of contracting / transmitting the disease in the early stages, while you have antibodies. Over time that protection declines but you tend to retain protection against severe disease when you do catch it.
It's different per vaccine / disease, you have to check the specific guidance per disease. Flu and Covid mutate quickly, a lot of other diseases don't seem to change very much.
With Covid the indications are the vaccines help reduce infection and transmission to start with, which is important because that prevents outbreaks spreading quickly. But the damn thing mutates so fast that what might have been true with last year's variant might not be true with this year's.
timarr
But we know now from the evidence that getting the Covid shot does not prevent you getting it or passing it on to other people. So what is the point when for most healthy people flu is not something they have to worry about, and certainly not children. No vaccine is without risk.
Because flu and covid (and measles, mumps, rubella, polio, diptheria, tetanus, meningitis, hepatitis etc) still kill thousands & thousands of people. And thousands and thousands more are hospitalised and end up with longterm health problems. Vaccines reduce the severity of the illness. That is why we vaccinate!!!!! It's really very simple!!!!
On Pendragon (LON:PDG) section 11 of today's RNS states:
"Shareholders who hold interests in the Ordinary Shares representing, in aggregate, approximately 26.5 per cent. of the entire issued share capital of the Company as at the Latest Practicable Date have each irrevocably undertaken (or have confirmed to the Company and the Sponsor that they will irrevocably undertake) to vote at the General Meeting in favour of the Resolution in respect of the Ordinary Shares to which they are beneficially entitled. The Shareholders comprise Schroder Investment Management Limited, Briarwood Capital Partners LP, Hosking Partners LLP, Farringdon Netherlands BV, Huntington Management LLC, and Sir Nigel Rudd." So by inference, Hedin (27.6% shareholder according to Stockopedia) is not on board.
My understanding of a Class1 transaction is that it only needs a majority vote at the General Meeting. My recollection on this point seems backed up by looking at a Tate & Lyle Class 1 transaction (from 2021) which only needed a majority vote. [But DYOR.]
https://www.tateandlyle.com/si...
There are currently proposals to soften the requirements for Class 1 transaction approvals - but these are only proposals - so pI think will have no effect on Pendragon.
Presumably, the board and Lithia having done all the work (and cost) to get this quite complex transaction to this point believe they can win the vote. Indeed the complexity of the transaction might (I am totally speculating) be driven by the wish to avoid a Scheme of Arrangement (which would require a 75% vote in favour).
I agree that this is an interesting situation. My concern (Hedin apart) is how many investors attracted to Pendragon (low PE value share) will want to hold Pinewood Technologies (which if worth £180m, as the RNS suggests, would be on a much racier multiple). There could be considerable churn in the Pendragon shareholder base as value investors sell out - leaving Pinewood Technologies trading cheaply potentially for an extended period.
DAX looking like it may roll over in the coming weeks. Maybe a slight contraction will cause no problems, something larger tho who knows.
Declining exports to China.
China using the thumbscrews on Germany today.
"Chinese Foreign Ministry spokesperson Mao Ning said at a press conference on Monday that Beijing complained formally to Germany's government over recent comments labeling President Xi Jinping a dictator. The spokesperson described those remarks as an "open political provocation" and "extremely absurd," stressing Beijing is "strongly dissatisfied" with Berlin.
Earlier, during her visit to the United States, German Foreign Minister Annalena Baerbock said that the support to Ukraine in the war against Russia will remain "because if [Russian President Vladimir] Putin were to win this war, what sign would that be for other dictators in the world, like Xi, like the Chinese president? Therefore, Ukraine has to win this war, freedom and democracy have to win."
Tensions between the European block and China have risen after the launch of an "anti-subsidy investigation into electric vehicles coming from China" and Beijing's concerns the move could harm the global industry."
Bango (LON:BGO)
Will be interesting to see if they have now hit the promised land.
Anyone looking at the interims today will think this company is a bit of a basket case (amber/red?)
They have been bedding down acquisition here and the profit ramp up really only starts h2 this year (July-sep24)
this being the case the prior numbers are possibily meaningless.
h1 this year adjusted ebitda loss of $0.2 mill - revenue $20 mill
h2 this year adjusted bitda expected to be $12 mill - revenue $29 mill
Note revenue is seasonal 40/60 this year - so h1 will look bad and h2 will look good - growth not as good as numbers above suggest
next year they had before today $57 mill revenues pencilled in (+15%) - with ebitda expected to be $21 mill plus. They say they have 90% margins so preumably next year they start to make real hay !!!
As ever with this company its promises for the future and ebitda positive again aint real profits (its realyl losses !!) - if nowt else it will be interesting to see if they hit the promised land h2 this year and next year - at present stocky has expected net profit of $14.3 mill next year - so based on what they are currently promising that would look cheap to me if they can deliver clean numbers.
Must admit that this share is giant leap of faith / gamble imho. As ever with these companies that promise the earth in the future not all of them deliver when it comes to the reality of delivering real crisp cashflow profits !!
Hi rmillaree. I think you're probably onto something here and its in a much better shape than "giant leap of faith". It does appear to be at a very pivotal moment. I see Singers have some research on ResearchTree and the analyst is decent. "on track for a transformational H2"
Good luck!
Bango (LON:BGO)
I am certainly not recommending this stock - i have seen too many companies over promise and under deliver when it matters over the years so i am defaulting to being skeptical. So although it has potential i would have it as an amber/red type risk (high) on the basis it hasnt proved itself of yet.
Hi rmillaree
Bango (LON:BGO)
3 months ago I had a one to one zoom with Paul Larbey CEO and challenged him on his confidence at achieving expectations. I did the same via email after the HY update. Each time he answered very confidently with concrete reasons why.
Bango (LON:BGO) are typically H1/H2 weighted due to seasonality. This weighting normal and not a one off. The only time this deviated was in one year due to Covid.
Profitability is expected to show a dramatic improvement in H2 as the cost synergies from the Docomo acquisition which have been effected, show in the numbers.
ARR run-rate of $10m is in great part already in the bag as many new telcos which have signed up in H1, start producing revenue in H2.
Bango have a pretty unique subscription bundling platform which is highly desirable to telcos as it helps them retain customers and increase revenues and means customers can have all their subscritpions in one place. The signs are this is gaining good traction.
Clients and merchants comprise all sizes but importantly includes many of the largest companies in the World - Amazon, Google, Microsoft, Verizon and many more. The fact that Bango has long term sticky relationships with many of these suggests the platform is very good and they are happy.
I consider management display high levels of integrity.
I think today's update was very good.
I am a holder so biased.
Saga (LON:SAGA)
Big write up in The Telegraph few days ago. Cruise companies are doing well at the moment - SAGA should be quite busy
https://www.telegraph.co.uk/tr...
Ugly looking interims from Dialight (LON:DIA) https://www.investegate.co.uk/... Include some wording they probably should have edited out until they actually announce the fund raising they referred to…
Yes Rhom, amazed this didn't gap down this morning, opening pretty flat. Was looking to short it but bloody IG wouldn't allow it. At least their RCF gets ESG bonus points. Shareholders will be happy.
"in a plausible downside scenario, the Directors have assumed that the expected growth in revenue from market conditions returning to normal for both OE and delayed capex projects occurs but that margins remain under pressure from inflation, and we see lower benefits from product cost reductions and factory efficiency improvements. The scenario modelling also includes the potential for a negative outcome from the ongoing Sanmina litigation (see note 11).
Under a plausible downside scenario, the Group has forecasted a potential breach of its Interest Cover covenant, which gives rise to a material uncertainty, and which may cast significant doubt on the entity's ability to continue as a going concern, meaning it may be unable to realise its assets and discharge its liabilities in the normal course of business."
Dialight (LON:DIA)
Well done to rhomboid1 for spotting the word 'fundraising' in the small print. The company has now put out another RNS to explain that and to say that the bank has agreed "subject to documentation, to vary the interest cover covenant for the September 2023 test period from 4.0x to 2.5x". There is also a reference to possible divestment, which I take to be the signals & components division.
This company has good niche products in LED lighting, which everyone is going over to. Perhaps one day someone will write a book on how incompetent management could possibly have made such a mess of that.
The question is whether Neil Johnson, Chair since 17/5/23, will be able to sort it out.
re S4 Capital (LON:SFOR) . Peel Hunt said it has downgraded its net revenue estimates by 6%, EBITDA by 22% and EPS by 36%.
“It is disappointing to see another significant downgrade for S4,” it said.
The broker has cut its price target to 110p from 180p
Thats a big EPS cut, or a "whopper" in Sorrellbullshit lingo.
The shareprice is in a whopper of a stage 4 downtrend as well. Down over 90% from the peak. I know lots of people think charts are just meaningless stupid squiggly lines but they often flash early warnings well before fundamentals catch up.
For those tuned in - Martin S. was on the Today programme about 07.25 this morning - with a load of figs and EBITDA blabla. Incidentally, Why does S4 not show up on the list of DECLINERS in the home page here - at 25% it should be top of the list!
Interesting move by Ashley. Anyone have any theories on the end game here?
Mike Ashley is in talks to sell Missguided to discount fashion giant Shein-
https://www.retailgazette.co.u...
Maybe Mr Ashley now sees Misguided as a basket case, or he's been made an offer difficult to refuse, or perhaps it's just a conflict of interest while he builds up a stake in Boohoo. Or something else. What's your theory Mr Wolf?
I'm really not sure Tein. Seem odd he'd build up stakes in Boohoo and ASOS then sell Missguided to the giant competitor, maybe some sort of partnership is possible?
I have no knowledge of the industry tho so no idea. Would be interested to see what Paul thinks?
Thanks. Perhaps then, Misguided is too small a player in Ashley's big picture, and the price on offer is right. Ashley and his people are pretty astute, perhaps they see a battle of big players looming, Misguided getting squeezed, (as it already was before) and Shein owning the brand not making much difference overall. Alternately, just because there might have been an approach doesn't guarantee a deal - he might be just using it to take a good look at the competition. All speculation on my part, I do not have a holding in Boohoo (LON:BOO) , ASOS (LON:ASC), Frasers (LON:FRAS).
Shein getting local UK capabilities, logistics, and infrastructure via Missguided means probably more bad news for Boohoo (LON:BOO) and ASOS (LON:ASC) as Shein starts to offer locally shipped products?
Of less significance than Paul having contracted Covid (Hope you feel much better soon!)...
...this morning I looked to see whether any broker forecast increases for Games Workshop (LON:GAW) had fed through to Stockopedia. I was a little surprised to see the consensus EPS forecasts had reduced from :
I wonder what data changes caused this.
Get well soon Paul. I had much the same symptoms as you, felt like a bad cold. I somehow caught the flu straight after which knocked me out for a week and was much worse.
My wife who has been vaccinated at every opportunity has had Covid 5 times(she was vaccinated a few weeks ago again) . It's a running joke in the house that she needs it once more to claim her free prize.
The vaccines appear as much use as a chocolate fireguard in preventing catching it.
Interesting. My wife any myself who are both very senior citizens :) have also been vaccinated 5 times, but so far neither of us have caught Covid. Guess it’s just a matter of luck
Yes, seems to be. Wife had it 5 times, I had it twice. Daughter who hasn't been vaccinated had it once. 2 other daughters (yes I've woman nagging me all day) who had been vaccinated had it twice.
Agree. I caught it 2-3 weeks ago, thought I had 'flu (but the 'laziness' after the acute stage is taking a while to wear off). I had a week away in Paris then (not been in public crowds since) but none of the others in my party of four fell ill then (I am 10 -20 years older).
Take care Paul, don't do anything strenuous if your pulse rate is up and get well soon.
"but so far neither of us have caught Covid"
i suspect you may have had covid but been Asymptomatic (not noticed you have had it)
Strangely "allegedly" with the latest top up of the vaccine you are now actually more likely to catch covid than someone who hasnt had the latest top up of the vaccine (Dr John Campbell on you tube said the cdc said that i think ) - that might make sense if the virus is now adapting best to attack the specific bits of the vaccine that we thought worked ! - all very interesting .
... that might make sense if the virus is now adapting best to attack the specific bits of the vaccine that we thought worked
If true that would be exceptionally weird, because the new version of the vaccine is targeted at the latest variants and has been tested against them. It's not a booster, it's an updated version of the vaccine to target the new variants EG.5 and XBB, which are significant mutations.
It's worth noting that vaccines only really prevent transmission for a few months after they've been administered. However, their protection against severe disease is usually longer-term.
timarr
Always best in these situations to go see what the most hyper politically correct, oddball country is doing this week. Over to you Canada.
They're sat meters apart wearing masks like a Orwellian propaganda video, talking of vaccinating 6month olds and checking school childrens vaccine status. You just know they'll take masks off as soon as the cameras are off.
You'd like to think this wouldn't return to the UK unless they want another few million on the NHS waiting list. I'm not so sure these days so can understand if investors get twitchy
Paul….your health is more important than anything ….rest and getting fully better IS your priority task this week ….
Artisanal Spirits (LON:ART) - Western growth enhanced by Eastern promise (new research report: https://www.equitydevelopment....)
The Artisanal Spirits Company (ASC)’s FY2023 H1 results reconfirmed a strong Q2 as well as showing potential for sustained sales growth both domestically and overseas. Profits at EBITDA level remain on track to be positive in FY2023. With further membership expansion, resilient demand for ultra-premium Scotch and important Asian developments in place, we reiterate our view that fair value for the shares is 150p.
Any Zenova (LON:ZED) holders? Views about this minnow. ?I liked last week’s news. Can’t buy it online or on the phone with Degiro. Too small?
Following on from an inline trading update on 5th September, another RNS this morning from Tpximpact Holdings (LON:TPX) re the sale of a non core business in Bulgaria- year end net debt targets (if met) starting to look far more modest?
Think this has previously been flagged as potentially needing a discounted fund raise- this is starting to look like less of a possibility?
https://www.londonstockexchang...
Facilities by ADF (LON:ADF)
On first reading the interim results appear very positive and the company remains upbeat despite the ongoing writers/actors strike in America., which will at some point be resolved.
I hold.
Solid results from City of London Investment (LON:CLIG) given the very difficult market conditions. I'm a big fan of this closed-end fund asset manager despite the fact that its gone ex-growth for now (like most asset managers!). Its a quality company in my view. It also provides a link to the audited glossy annual report on the day it announces its results which all listed companies should be doing.
I was looking at the AiC site yesterday and noticed that investment company IPOs are zero for both 2022 and 2023. This is unbelievably poor, versus the boom 5 years previously!
Investment companies are now on an average discount of c15% overall. This is not helped by wealth managers being forced to ditch investment companies because of the new cost reporting (i.e. holding a listed investment trust in a wealth manager / IFA portfolio doubles the cost ratio as investment trust fees and wealth manager fees are taken into account).
The Chancellor needs to address this. A little known fact is that the UK has the best closed-end fund industry in the world. Much better than even the US if you look at how may of the largest 100 closed-end funds are in the UK! If we want pension funds to invest in UK assets (including small growth companies and private equity) we need a healthy investment trust sector, but its starting to look anything but healthy!
Large discounts in investment trusts = better medium term returns for City of London Investment (LON:CLIG) as they are the activists that encourage boards to close the discounts!
Anyway, I'd be interested in any thoughts people have on this asset manager.
That’s really interesting topvest as I hadn’t realised that wealth managers were being forced to ditch Investment Companies for the reasons you gave. I just knew that a lot of Investment Trusts are extraordinarily cheap and on big discounts to NAV of up to 40% and more even for Trusts with excellent performance records.
Investment Trusts buying back their shares to help reduce the big discounts aren’t working either.
e.g Pershing Square Holdings (LON:PSH) have bought back well over $1 BILLION of their shares and are still buying back daily. Those buybacks have cut the share count by around 25% yet STILL PSH is at a 36% discount to NAV. And that’s despite outperforming the US aic sector with share price up 16% 1 year (US sector 11%) 3 years 39% (US sector 35%) and 5 years 165% (US sector 114%).
One way Investment Trusts could get new issues away again is by doing what they used to and add the sweetener of free subscription shares on say a 1 for 5 basis. Thanks to pressure from Lord John Lee subscription shares are allowed to be held in ISAs too and they can prove to be excellent geared investments in their own right . Geiger Counter (LON:GCL) subscription shares which I luckily held went up nearly 60 times.
Separately so many UK shares are also ridiculously cheap. Oliver Shah in a Sunday Times article yesterday pointed out that in 2008 daily trading on the U.K. Market was £8.6 billion bit it’s now down to just £3.7 billion with Pension Funds in particular moving away from shares and into bonds.
Hence shares like Phoenix group (LON:PHNX) Aviva (LON:AV.) Legal & General (LON:LGEN) M&G (LON:MNG) and many similar are extraordinarily cheap despite paying increased dividends year on year. E.g Phoenix group (LON:PHNX) issued their Results today and they were upbeat and with annual dividend increase to give 10% yield. The others are all paying 9% to 10% too. All of them should be double these prices to give more normal 5% dividend yields. I hold all of them and Pershing Square Holdings (LON:PSH) but not yet cCity of London Investment (LON:CLIG.
it’s now down to just £3.7 billion with Pension Funds in particular moving away from shares and into bonds.
Hi ken
Defined Benefit schemes have largely sold out of equities - and rightly so, they're closed to new contributions, most members will (or shortly will) be into drawdown and they need to match assets to liabilities. However, Defined Contribution schemes mainly target equitites, and the amount allocated is only going to grow over the next twenty years.
At least as big an issue is that fact that there are far more places to invest these days, and the UK equity market is relatively unattractive. That said, there are some extraordinary prices on offer - I hold most of the stocks you mention, and a few more fund managers to boot.
On the IT side, the level of discount is too wide to be maintained. Some of the property trusts, infrastructure and sthe alternative energy stocks where, in effect, the holding companies are really managers of the underlying assets, have derated largely because they've been treated as bond proxies, rather than asset managers. Fair enough, but that's likely to reverse as interest rates start to drop. Assuming they can generate real returns from those assets then the results should be very attractive for investors.
On the other hand, of course, these types of fund can't simply be assessed by looking at the discounts to NAV, because you can't mark to market the valuations. I wouldn't be too keen on PE funds or VC proxies for that reason, but outside of those the scale of the discounts imply a fairly wide margin of safety.
timarr
Hi Tim any thoughts on Liontrust Asset Management (LON:LIO) despite the continued outflows and Gam debacle they do look super cheap net cash and even lower profits to market cap figures look decent but still dropping even on market up days.
Regards Andy
Hi Tim any thoughts on Liontrust Asset Management (LON:LIO) despite the continued outflows and Gam debacle they do look super cheap net cash and even lower profits to market cap figures look decent but still dropping even on market up days.
Hi Andy
I hold Liontrust Asset Management (LON:LIO) - I think Graham has made the case for them several times on the SCVR - uninspiring fund manager but very, very cheap.
In fact I hold a variety of fund managers - M&G (LON:MNG, Legal & General (LON:LGEN, Pollen Street (LON:POLN), Polar Capital Holdings (LON:POLR) and Jupiter Fund Management (LON:JUP) as well as Liontrust. I'm not betting the farm on any of these, but I think they're all cheap and I treat the group as a separate sub-sector.
Active fund managers are cyclical investments - they tend to do well in bull markets when they get marked up as dumb money flows into them in the illusory belief that their managers have some kind of special insight into markets. They don't, so very few do well in bear markets, and the resulting derating is often savage - although I don't remember anything this severe, for this long, in my years of investing.
But when they're marked down they become interesting, as they generally throw off income due to investor inertia, can become prey for larger groups and will eventually rerate when markets turn-up, fresh money arrives in the market and their managers can don their superhero costumes again. As such I was relieved when the GAM bid failed, Liontrust is much more interesting as a standalone entity.
timarr
Thanks Tim
Huge amount of consolidation in this sector with the likes of Charles Stanley, Brewins and Gresham House to name but a few being bought out in the last 1-3 years and personally don't see that trend changing.
The fund management model is capital light once you have the team in place you can scale up assets you can manage/handle quite quickly with no major increase in staff head count.
Liontrust have had a torrid time past 18 months as you say in a bull market most managers should do okay against peers but in 2022 pretty much all of them did badly unless they could short, held a lot of gold, or held dollars/dollar denominated assets.
I'm also hold Legal & General and Polar Cap and happy to collect the dividends whilst I wait for the markets to turn at some point maybe early part of 2024 possibly.
Appreciate your input.
Andy
re Pershing Square (which I hold as well) , just to say much of the discount is explained by the fee structure , which is particularly high. I wouldn't rush off to buy before getting comfortable with that.
As a holder I'd also comment that the speculative punts taken by the managers (some of which have come off) would put off most institutions. Also, quickfire trades (like the purchase/sale of Netflix last year) would also put folks off.
I still like it in spite of these bear points. It comprises 100% of my US market exposure.
Yes, ken - I agree with you on subscription shares. Maybe warrants as well as they seem to have disappeared and used to be a very good leveraged position, particularly if you bought them in the market.
I am thinking that UK shares will make a bit of a relative comeback when the US bubble bursts, as the UK will outperform the US at that point.
A very interesting quote by the Chairman of City of London Investment (LON:CLIG) today. Someone speaking some common sense:
"In 1989 it was claimed that on the basis of Tokyo land prices at the time, the 284-acre Japanese Imperial Palace was worth more than the entire state of California while frothy valuations drove the Nikkei 225 index to nearly 39,000, a level to which it has not returned in the 34 years since. That episode demonstrated that, while markets generally behave in a rational way, occasionally they do not. Fast forward to today and we find that the "magnificent-seven" stocks*are valued at US$11 trillion or twice the level of the entire Japanese stock market and more than 20% of the entire US stock market. Whether or not this has taken this handful of companies into unsustainable "bubble" territory is for others to decide but in the six months to 30th June 2023, they accounted for more than 70% of the rise in the S&P 500 index, underlining the degree to which the recent strength in US equities has been driven by a narrow and powerful "Artificial Intelligence (AI)-bandwagon".
Hi topvest
That was a very interesting quote!
I guess you realise this but in case others don’t, Investment Trust subscription shares and warrants are exactly the same thing, except that if called a warrant it is not eligible for ISAs (unless the regulations have changed as I haven’t checked before posting this) but if it’s called a “subscription share” it can go in to ISAs.
Topveat, I held City of London Investment (LON:CLIG) for a few years upto 2021 and sold out then. I admit that I am a bit out of date with the company.
My main reason for selling was realising (I should have seen earlier), their large holdings in some of the key Emerging Market ITs (eg Templeton Emerging Markets Investment Trust (LON:TEM) and JPMorgan Indian Investment Trust (LON:JII) ). They hold currently over 20% of both of these. I have in my memory that they held upto 29.9% of some ITs (but looking quickly now I can find a current example of that.)
To me, that is too much to hold in one company. I see that you call them an activist (and then having a big stake can be a benefit) but I always understood CLIG as more of an arbitrageur - buying ITs on wide discounts and selling thos on narrrow ones. In this way they could (hopefully) deliver to their clients on outperforming MSCI EM index (abritrage profits > management costs). For this arbitrage strategy to work, you have to be nimble. I would have a few questions, if I were a fund manager thinking of putting money into a CLIG fund, if the AuM had outgrown the liquidity of the strategy (particularly today when liquidity seems so poor.)
While I owned CLIG, the company was focusing on diversifying assets (trying to expand new strategies into binds and through a 2020 US acquisition (Karpus). Given my concerns above - these moves make perfect sense. While I think CLIG’s EM strategies are transferable to other assets, I get the impression that CLIG’s key selling point is still its EM expertise (and EM still accounts for 38% of AuM as of June. 2023).
Sorry if any of these points are out of date now (or it is an activist by design and not by default). But its large stakes in its investee holdings is the reason why even at c400p, I am not a buyer of City of London Investment (LON:CLIG) today.
I have a worry that City of London Investment (LON:CLIG) profit margins are falling and I am not sure what level these will settle at and what it means for the dividend longer term - it's led me to sell out at 450p previously and be nervous about buying back in. Hardman & Co previously said ‘there is gradual decline in CLIG’s revenue margin [or simply revenue from FuM], as new business is generally lower margin than on the back book. In particular, the back book in the Emerging Markets strategy was higher margin than the new business in the newer areas, and it has been experiencing net outflows.'
The US closed fund market had a lot of corporate activity in the 1980's due to the discounts.
Hope you recover quickly Paul, Covid is rife outside of London too (I know 3 people in the last week)
The Pendragon (LON:PDG) offer is interesting & I note carries 26.5% irrevocable undertakings from institutional shareholders and the Board. All eyes on Hedin for their response
At this rate, Vertu Motors (LON:VTU) will be the last man standing
*I hold both
Pendragon (LON:PDG) I hold, I would be surprised if the deal goes through at this level. Hedin (27%) holder had bid 29p last year and they also blocked a previous bid by Lithia. They also mentioned in one of their statements they would not sell their stake for less than 35p / share...
Hello Albm7 - and others - Interesting situation with Pendragon (LON:PDG) here. Hedin offered 28p,last autumn, then wanted more time to review the books (at which time I should have sold at 28p) and then withdrew their offer.
The 35p bit is new to me, and of course I would be happy with that since the company is my equal largest shareholding which I bought speculatively some time ago with a batch of car dealers when Marshalls took off.
Interesting that Hedin didnt think the business was worth 28p and it fell back dramatically when they withdrew, then say they want 35p
Hi ridavies and others....Yes I I know that feeling... (not selling) I bought some more late July and was looking at adding more as it was drifting lower late week, oh well.
Here is the link to the 35p bit I referred too, Would be a seller of their stale at no less than 35p
Also something else I read from the trade press was that Hedin walked away due to a legal dispute regarding Pinewood. Also I know Paul mentioned possibly buying into this to get hold of the Pinewood part of the biz but this link is worth reading as it says the deal is structured in such a way as to remove Pinewood from the deal...Hedin won't be able to block the deal etc
It does appear that as it is an asset sale and not a takeover a 51% majority is all that's is need but as Paul has already mentioned Zeus comments, it does look like they are getting the deal on the cheap, hopefully other shareholders push for a better price.
I for one would like a complete take over - surely if Pinewood was so great why leave it behind as a separate entity unless of course they are parking the litigation risk with it which would not surprise me at all.
Never quite sure why Vertu Motors (LON:VTU) hasn't attracted any bid interest over the years, while all the other car dealers get snapped up. I vaguely recall reading something about the major shareholders being less likely to agree to a bid, and the property holdings could be another factor putting off potential bidders, although =not sure how accurate that is. The bottom line is Vertu Motors (LON:VTU) is probably worth owning on its own metrics, irrespective of whether a bid comes through.
How do you know that it hasn’t attracted any bid?
The company does not have to announce any approach that has been rejected!
Get well soon Paul. I work in London and Covid spread around our office recently, as we are not allowed to work from home, quite a few people went down with it. Some said it was worse than the first time they had it, so looks like you got a lucky escape!
Get well soon Paul. Whoever is reviewing shares this morning please could you include the agreed offer for Pendragon (LON:PDG) which is structured in a novel way
Get well soon PP - Wishes
BTW - Just noticed there's POS news which I am not sure how good or bad it is.
Morning matylda,
The news from Plexus Holdings (LON:POS) (I hold) of the CEO & his family interests loaning the company £700k at 8% interest looks to me another demonstration of his commitment to, and confidence in the company, without diluting shareholders. He's already put in £2.5m in the last year (£1.5m convertible loan, £1.0m purchase of a long leasehold surplus property).
The only bit of today's announcement that has confused me a little is the call option for him to be paid off in shares of a small associate company where Plexus bought a 49% stake in 2018. I think that's probably OK, because the value in Plexus shares is the core patented technology, which has been validated by the Schlumberger licensing deal (extended by another 6 years, and with products due to launch fairly soon I believe). Royalties from global sales could be good, but at present Plexus hasn't given any indication of what the figures might be.
Also the £5m special contract that was then extended to £8m is a direct to customer rental deal (hence all the contract revenue will be recognised this year FY 6/2024). That's huge, considering revenues were bumping along at only about £2m pa in recent years. Rental deals are high margin too, Cenkos reckons it will move Plexus into profit this year. When the market sees those numbers in 2024, I think it could be a nice catalyst for the market to reappraise Plexus from a bombed out failure, to an up & coming player in a sector with big industry tailwinds (esp eliminating methane leaks from well heads, which is Plexus's big advantage, of its patented tech).
Downside risks are obvious - single contract risk for the £8m deal, management owning 59% - but they've always treated outside shareholders very fairly. Incidentally, I spoke to mgt last week, and they were really pleased that a private investor was taking an interest in the company, and they encourage other investors to get in contact, they're happy to talk to anyone. Passionate is not the word! The CEO Ben van Bilderbeek invented this well head tech, and has been frustrated at low rates of adoption, but maybe his time has come, given the new focus on methane leaking into the atmosphere, where it is a potent greenhouse gas apparently.
Regards, Paul.
P.S. Bear in mind that Plexus has had total cash intake of £5m in the last year (£2.5m from its CEO, and £2.5m from up-front customer payment on the £8m contract). So it should be OK re operational cash burn. I don't know, but am guessing that the £700k loan today maybe to build another rental wellhead, which I think cost around £700k a pop, but can be rented out at high margins (the payback period is less than a year, I think). Management is doing everything they can to avoid dilution for anyone. Bear in mind that the convertible loan announcement a while back said there would be an open offer or similar, to allow existing shareholders to inject more cash to avoid being diluted.
So in a nutshell, I don't see today's announcement from POS as being bullish or bearish really.
P.P.S. Just remembered another key point re risks. I worried that Plexus might decide to de-list, as the market cap bottomed out at just £2m, although it's since bounced to £15m. So I discussed this with mgt last week, and they sounded really committed to maintaining the AIM listing. Easy to say, but their reasoning was that as a small co based in Aberdeen, they found it sometimes difficult when dealing with major multinational oil cos, reluctant to transact with a small private company. That was transformed once they listed on AIM in 2005 I think it was. At a stroke, they found dealing with major customers much more straightforward, as they could demonstrate the enhanced regulatory aspects of being listed, credibility in the city, and access to capital if/when needed. So de-listing seems out of the question I think, as it would undo all those proven advantages from being stock market listed.
My morning smallcap tweet: Futura Medical pulling ahead.
Pendragon (LON:PDG) Futura Medical (LON:FUM) Advanced Medical Solutions (LON:AMS) Nuformix (LON:NFX) Plexus Holdings (LON:POS) Tpximpact Holdings (LON:TPX) Hemogenyx Pharmaceuticals (LON:HEMO) B.P. Marsh & Partners (LON:BPM) Zenova (LON:ZED)
◄Pendragon (PDG)► agreed the terms of a proposed sale to US's Lithia Motors of the UK motor business and leasing business for £250m before adjustments. Transition to Pinewood Technologies (dealer management software) and Strategic Partnership with Lithia. Lithia to subscribe to £30 of PDG. £240m div (16.5p). [SP=18.63 Cap=260m]
◄Futura Medical (FUM)► H1-June. Eroxon (MED3000) rev £1.7m. Eroxon®sales are on track to exceed expectations versus its original first year forecasts. [SP=52.2 Cap=157m]
◄Advanced Medical Solutions (AMS)► greement with TELA Bio to commercialise LiquiBand Fix8 in the US. [SP=181.6 Cap=394m]
◄Nuformix (NFX)► to receive new immediate and near-term undisclosed milestone payments as part of an update to its NXP001 exclusive licensing agreement with Oxilio. "Oxilio will acquire ownership of Nuformix's NXP001 patent estate, with Nuformix receiving the additional milestone payments referred to above, whilst retaining further development milestones and royalties capped at £2m PA." [SP=0.26 Cap=2m]
◄Plexus (POS)► £700k in 1 yr loans from CEO or his family vehicle Plexus Property International. 8% interest. [SP=14.9 Cap=16m]
◄TPXimpact (TPX)► sells Questers for £7.5m. Questers generated £13.1m of revenue and £1.3m of adj EBITDA. £5 will be used to repay borrowings. Trading in line and outlook for FY25 is also maintained. [SP=39.02 Cap=37m]
◄Hemogenyx Pharmaceuticals (HEMO)► $830k subscription at 7.5c, a 240% premium, by Prevail Partners. InfoWorks to provide clinical services and technologies for HEMO's Phase I study of its anti-FLT3 chimeric antigen receptor-redirected T cells. The subscription funds will in large part defray the cost for the first stage. [SP=1.82 Cap=21m]
◄B.P. Marsh (BPM)► H1-July update. New dividend and buy-back policy. [SP=363.86 Cap=136m]
◄Zenova (ZED)► first delivery of 13,654 units of Zenova FX500 to USA distributor. [SP=5.5 Cap=6m]
Bango (LON:BGO)
Interims published today.
The share price has pulled back heavily from a high of 260p earlier in the year. 172p on Friday
I think today's update is excellent and confirms rev growth of 88% in H1.
This year's FY targets looked ambitious but the update details several times that management think Bango are on track to deliver FY results in line with these ambitious targets.
Historically and typically revenue is weighted H1/H2 40/60 and this is again mentioned in the update.
Profitability in line for FY as costs already cut are expected to show strongly in H2.
FY ARR expected to reach $10m by year end which is double last year's rate of $5m
With a gross margin of 90%, it is not surprising that Bango say they are on track to deliver a substantial increase in Adj EBITDA in FY24
There are usually broker notes from Singer and Liberum.
At 8.30AM there is an IMC for those interested.
As a long term holder, I am biased but also delighted.
Investegate | Company Announcement
In the presentation this morning they emphasised the growth prospects for their subscription bundling service (DVM)for Amazon Prime, Netflix etc. for which there appears to be no competition. The main competitor threat they said would come from a Telco building a service themselves but this would take time and money for a non-core activity and added that Bango's service is cheaper to maintain for API changes etc., making the service look very sticky. That 3 of leading US telco companies are now on board supports this and they expected further customer wins in the near future building a valuable ARR revenue stream, which is set to grow significantly
Like Michael above, I was very encouraged and added this morning, it really does look like a growth company on a value rating with a FY2024 P/E of just over 10
For those new to the company the interims do not look spectacular because of the Docomo integration costs but that is largely complete and cash generation should greatly improve from H2 onward and the revenue growth is there to see.
I had missed the podcast, but wishing you a speedy recovery and bounce-back
Thanks The Jayman!
Yes unfortunately I can only croak, not speak, at the moment, so couldn't do a podcast this weekend. Apologies!
Regards, Paul.
Best wishes Paul, get well soon.
Get well asap!
Best wishes and only do what you feel able to do, and if that is nothing, then rest up.