Small Cap Value Report (Mon 19 Feb 2024) - CURY, SALT, BPM, SPR, WIL

Good morning from Paul & Graham!
Mello Monday starts tonight at 17:00. Note that our Graham is on the BASH panel, should be fun!
The Week Ahead - this excellent new Stockopedia editorial is out every Monday morning, and is the place to discuss UK & overseas larger caps. Good idea, as we get a bit too congested here! Megan normally writes these, but today it's from Keelan, covering banks, miners, Rolls-Royce Holdings (LON:RR.) and more.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news) -
Petards (LON:PEG) (nanocap £4m) - up 15% to 6.7p - announces a £0.35m order from another police force for its ANPR product. Patchy track record, some years it makes a small profit. Healthy balance sheet. Could be worth a speculative look maybe?!
Esken (LON:ESKN) (nanocap £2m) - down 49% to 0.2p - death throes of equity continue. Bond holder is trying to force a restructuring, meaning ESKN would cede control of Southend Airport. Top 3 shareholders are (amazingly) Toscafund, Harwood, and Richard Griffith. One way or another, existing small shareholders seem likely to be wiped out, probably.
Atome (LON:ATOM) - down 9% to 51p (£16m) - placing at 50p to raise £1.8m, £665k coming from Directors & PDMRs. It’s a pre-revenue heavy cash burner, so high risk. It’s developing green fertiliser projects. Good luck to everyone involved.
Spaceandpeople (LON:SAL) - up 9% to 64p (nanocap £1.4m) - FY 12/2023 TU - sounds OK (edit: actually, quite good considering the tiny mkt cap) -
“The Board is pleased to report a strong performance during the second half of FY23, with total unaudited revenue for FY23 being slightly above market expectations, at approximately £5.8 million (2022 restated: £4.7 million), due to particularly strong Brand Experience revenue, the successful launch of our Rock Up and Pop Up service and the continued recovery and expansion of our German retail business.”
Net cash £0.8m. Why is SAL listed, surely makes sense to take it private at this minuscule mkt cap? Zeus reckons it’s trading just above breakeven, update note out this morning, available on Research Tree. So it doesn't look a basket case, speculative upside maybe? Erratic performance, and a serial disappointer in the past, we've followed this one for many years.
Summaries
Currys (LON:CURY) - up 34% to 63.2p (£716m) - Potential bidders - Elliott (at 62p - rejected) & JD.com - Paul - PINK for spreadsheet - AMBER on fundamentals
Weekend newspapers (and since confirmed on this morning's RNS) say Elliott (one of the world's largest activist investors, from USA) made a 62p takeover approach to CURY management, which they have rejected as undervaluing the company. JD.com also apparently sniffing around, CURY now in play.
MicroSalt (LON:SALT) - 114p (£49m) - Recent AIM float - Paul - AMBER
I review the AIM Admission Document below for this recent float, which has gone to an unusually large premium. Very much a jam tomorrow company, with negligible sales to date, but it's a nice story!
B.P. Marsh & Partners (LON:BPM) - unch. at 466p (£173m) - Trading Update - Graham - GREEN
This investor in small insurance brokers and agents had a remarkable 2023, making disposals of various investments for £93m of upfront cash. Larger dividends and share buybacks are underway but the stock remains at an 18% discount to last-reported NAV.
Springfield Properties (LON:SPR)- up 1% to 77p (£91m) - Sale of land - Graham - GREEN
This Scottish housebuilder announces the sale of land, consistent with its strategy to dispose of parts of its landbank in order to pay down debt. It will announce interim results tomorrow which should shed more light on its debt reduction plans and latest NAV movements.
Wilmington (LON:WIL) - down 2% to 336p (£302m) - Interim Results [in line] - Paul - GREEN
I review H1 results, and come away happy with everything. I continue to see WIL as a good quality business, at a reasonable valuation.
Paul's Section:
Currys (LON:CURY)
Sky News reveals that this electrical retailer has had a £700m (c. 62p/share) takeover approach from Elliot Advisers. The Times went on to say CURY’s Board had rejected the approach as undervaluing the company.
Remember that CURY has a weak balance sheet, and a cash-hungry pension deficit. However, it has had a recent cash boost from the sale of its Greek subsidiary, and has remained modestly profitable despite the consumer squeeze in the last year or so. Maybe an acquirer is looking at potential profit upside from £9bn pa revenues? Only 1% extra gross margin is another £90m profit, after all. Perhaps I’ve been too negative on this one in the past? That said, a 62p offer is not very exciting upside - is it worth taking elevated risk, just for a 30% possible gain?
EDIT: Currys has confirmed it rejects the 62p offer in an RNS this morning, just out.
EDIT: The Times says Elliott is considering making another bid for CURY, and that the company is now in play, which might attract other bidders.
EDIT: I've just spotted that the Telegraph says Chinese giant JD.com is considering a bid for CURY, raising the prospect of a bidding war. Exciting!
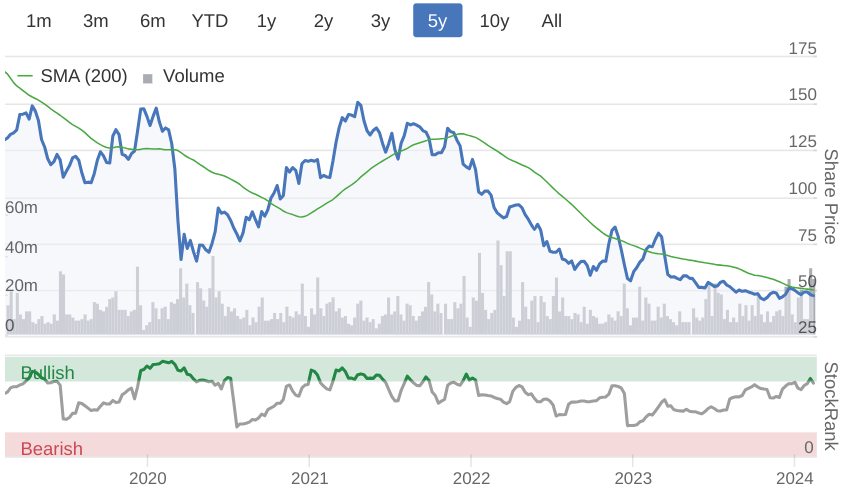
62p seems unattractive when looking at the 5-year chart (bear in mind there has been no dilution too over this period) -
MicroSalt (LON:SALT)
114p (£49m) - Recent AIM float - Paul - AMBER
This recent (1 Feb 2024) AIM float cropped up in last Thursday’s SCVR, when I briefly mentioned it in the mid morning movers section, when it rose 24% to 105p on a US distribution deal. Readers continued the discussion in the comments.
It floated at only 43p on 1/2/2024, and has risen a remarkable 165% to date, at 114p (Friday’s close). This induced me to read the AIM Admission Document over the weekend, here are my notes -
MicroSalt (SALT).
Website: MicroSalt.co
Zeus float to AIM & NOMAD at 43p
Placing 2.15m shares, 5.16m subscription = 7.3m new shares at 43p = £3.1m gross proceeds to the company (£2.5m net of fees - seems very small, and I think the company will need to raise more funds quite soon, this is not enough, especially when all the additional costs of listing are accounted for, maybe £500k to £1.0m pa maybe?)
Important positive point - apparently no selling shareholders.
Important negative point - heavy dilution from warrants (7.3m, exercisable at 47.3p) and options (6.7m) - fully diluted share count could be 57.1m, 32% dilution (subject to conditions, see Admission Document for details).
First dealings 1 Feb 2024, so it’s now trading.
Florida-based company.
Only 7 employees, so it’s an IP company only - manufacturing is only on a trial basis, and is outsourced.
Founded in 2016 by Dr Clifford Gross, and TekCapital (listed: LON:TEK - could be worth considering as an investment into the controlling shareholder?)
What is the product? It’s salt, but made into tiny particles, thus giving twice the taste for the same weight of salt, unlike lower sodium alternatives which use other additives.
No history of sales or profits of any significance, but it claims to now have the first commercial scale orders.
Losing c.$2-3m pa.
TekCapital will own 77.2% after IPO (worth £38m vs TEK market cap of £30m - as of 16/2/2024)
Tiny free float.
Will need more cash, is my assessment of the numbers, beyond the modest IPO proceeds.
Very small historical Directors pay, so expect overheads to rise significantly post IPO.
Convertible Loan Notes of $1.8m from TEK at June 2023.
Key issues/questions -
IP protection - I could be wrong, but the company seems to hinge on just 1 patent in the USA. There are 14 more pending in other countries. The small print says the original founders (who sold the patent) get a 3% sales royalty until 2030 - which makes me want more clarity on when that key patent expires? All questions to ask.
Why float now, raising so little cash (£2.5m after fees)? If sales are about to take off, surely it would have made more sense to hold back, and float for a much higher valuation showing exponential sales growth? Looks a bit desperate to me.
Amazon reviews for MicroSalt - not many, suggesting direct to consumer sales have not yet taken off. One negative review says the very small particles mean that MicroSalt is powdery, like flour, and not usable as a day-to-day alternative to regular salt (resulting in an airborne cloud). So maybe that limits the market to B2B, eg for salted nuts, crisps (which are being trialled), etc.?
Paul’s opinion - this cannot be valued on any historic performance, as it’s only achieved negligible sales to date. So it’s a jam tomorrow situation, that may be amazing, or it might be a speculative frenzy. £50m market cap isn’t a vast amount for a good story in a bull market, I’ve seen large numbers of speculative micro caps go way higher than that, but hardly any reached commercial success.
Good luck to anyone having a punt on it, but personally I’d want a bit more track record and certainty as to whether this product is actually going to take off commercially, it’s too early to say at this stage.
So for me, it’s not of interest at this stage, but I’ll keep an eye on the newsflow. It’s a nice story though!
EDIT: I've just noticed an InvestorMeetCompany presentation from management is in the recorded archive, from 7 Feb 2024, so I might watch that later to hear the bull case.
Wilmington (LON:WIL)
Down 2% to 336p (£302m) - Interim Results [in line] - Paul - GREEN
Wilmington plc, (LSE: WIL, 'Wilmington' or 'the Group') the provider of data, information, education and training services in the global Governance, Risk and Compliance (GRC) markets, today announces its half year results for the six months ended 31 December 2023 (H1 FY24).
Wilmington plc is the recognised knowledge leader and partner of choice for data, information, education and training in the global Governance, Risk and Compliance (GRC) markets. Wilmington employs close to 1,000 people and sells to around 120 countries. Wilmington is listed on the main market of the London Stock Exchange.
I’ve got a favourable impression of Wilmington. Checking my previous notes, I reviewed the FY 6/2023 results here on 25/9/2024, concluding that I like everything about the company - growth, margins, cashflow, balance sheet with plenty of cash, and a reasonable valuation.
This is a first I think - a highlights table that actually gives me the numbers I want! (adj PBT & EPS) -
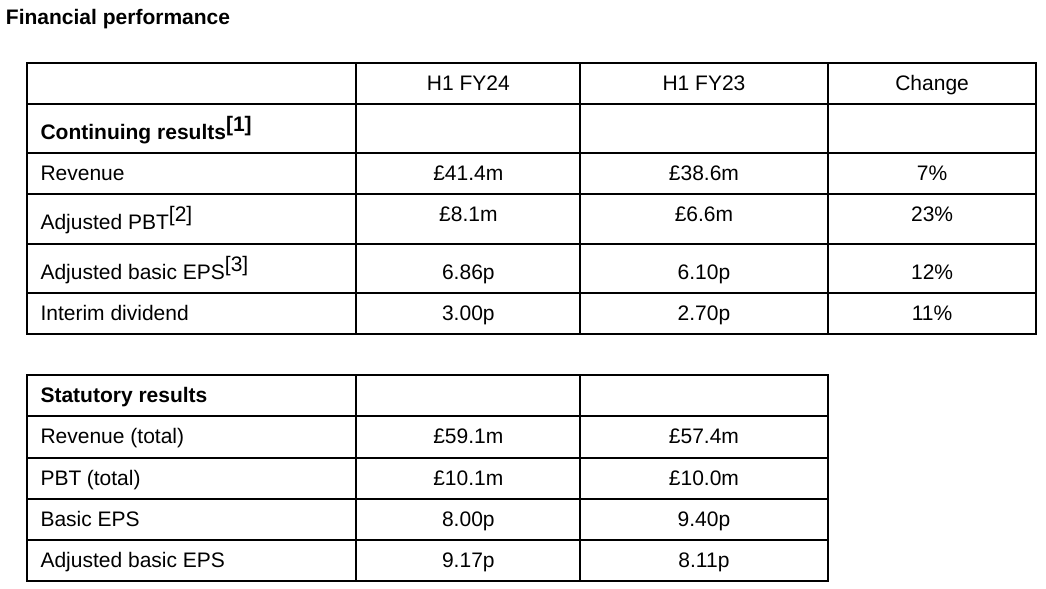
Clearly there’s been a significant disposal, as the statutory figures above show higher revenue & profit than the adjusted numbers.
I like these bits below from the highlights section, especially coming at a time when plenty of companies are telling us that some customers are retrenching -
…strong demand in Training & Education and Financial Services in Intelligence division
Recurring revenue from continuing businesses up 11%, underpinned by strong retention rates
Finance income has had a nice boost from higher interest rates, earning £927k in H1 (£297k H1 LY)
Note that EPS has increased less (12%) than adj PBT (23%), since companies are now having to absorb a significant hike in corporation tax (up from 19% to 25%), but that should already be in broker forecasts. Worth bearing in mind though, as it artificially suppresses EPS growth.
Outlook -
"We continue to actively manage our portfolio of businesses with one earnings enhancing acquisition and one disposal. We have also initiated a sale process for our Healthcare division, after a period of restructuring which put that business in a much stronger position.
"Our strategy is clear: to grow the business profitably across the rapidly expanding GRC landscape by a combination of acquisitions, which provide attractive returns on investment, and investing in our operations and infrastructure, as well as actively managing our portfolio in line with our required characteristics.
"Trading in the current financial year continues to be in line with expectations."
I can’t find any broker notes. The StockReport shows EPS of 22.5p (broker consensus) for FY 6/2024. Since H1 is 6.86p, then this implies a considerable H2 weighting to profits & EPS. I’ve just checked and that seems to be the normal seasonality, at least it was last year FY 6/2023 anyway (the pandemic distorts previous years). So all good I think.
Valuation - at 336p this gives us a FY 6/2024 PER of 14.9x, which seems reasonable for a nice quality business with a strong track record.
Balance sheet - NTAV is only £13m, but that’s fine because it’s a capital-light business model - there are hardly any fixed assets, and no inventories.
Cash is £23.9m, with no interest-bearing bank debt.
Cashflow - looks very simple. It generates plenty of cash, and uses it to make acquisitions, and pay divis. That’s pretty much it!
Paul’s opinion - it’s another thumbs up from me. This niche looks high margin, with plenty of recurring revenues, which tells me WIL is operating in a sweet spot, and clearly delivering services that clients value.
Shares seem reasonably priced still, and a 3.3% yield is worth having, when combined with a share price chart that has been trending up nicely since the pandemic lows, almost 3-bagging since then.
I can’t see anything wrong with WIL, so do leave a comment if you have a bearish view, in case I’ve missed something. It’s another GREEN from me.
Quite a lot of volatility in the past -
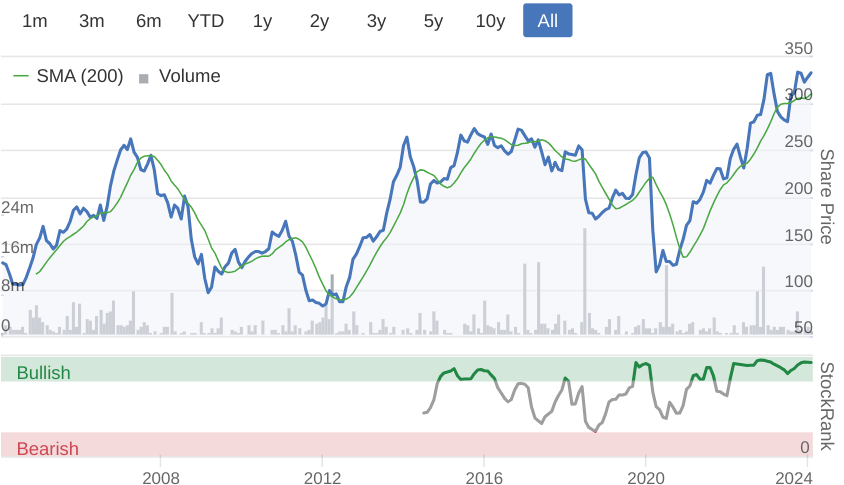
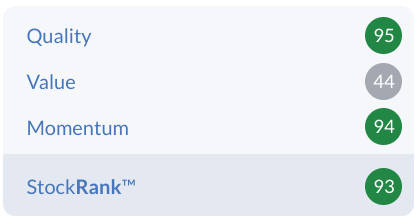
High StockRank reassures me -
Graham’s Section:
B.P. Marsh & Partners (LON:BPM)
Unch. at 466p (£173m) - Trading Update - Graham - GREEN
This investor in insurance businesses doesn’t tend to attract much commentary, but investors have seen a lovely return over the past few years:
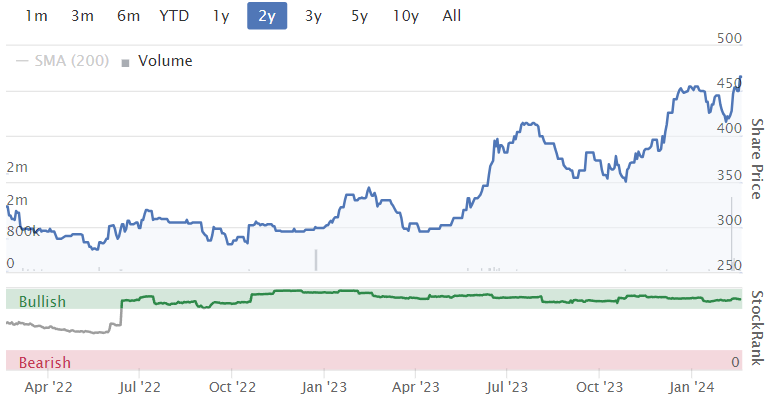
We’ve covered it from time to time in the SCVR, e.g. in September, noting that the last-reported net asset value was c. 516.8p per share (fully diluted). The BPM share price at the time was 372p.
Today brings an update for the financial year ending January 2024.
Key points:
Three disposals for upfront cash of £93m (we already knew this).
Group funds rose to £40.5m as of January 2024.
“A robust pipeline of new investments”.
As we discussed before, the company has put a lot of thought into how to use the windfalls from the disposals made in 2023.
It recently announced the proposed doubling of its annual dividend, to £4m p.a., for each of the years 2024, 2025 and 2026. I think it’s quite rare to see a company signalling its dividends so far in advance!
Buybacks: £1m was spent on buybacks during 2023, and up to a further £6m will be spent on further buybacks.
It seems to me that BPM is probably getting the balance right: they are reinvesting most of the cash they’ve received from their disposals, but they are also providing a nice mix of dividends and buybacks for shareholders. It’s hard to argue against this, in my view.
Recent disposal: I haven’t commented on this before, but BPM’s most recent disposal - announced in December - was at a very nice premium to BPM’s valuation. This might help to provide us with even more confidence in the company’s NAV calculation. BPM is receiving nearly £42m for an investment it valued at £30.5m.
New investments: the new investments made in 2023 look quite small but are in line with BPM’s typical strategy of finding promising new insurance brokers / managing general agents.
Insurance market outlook:
The consolidation trend would seem to threaten BPM’s ability to find small independent companies worthy of investment, but BPM argues otherwise:
The ongoing consolidation trends in the Insurance Market show no indication of abating in 2024. Such activity remains a catalyst for substantial prospects for the Group, both in terms of new investments and activity within our core portfolio.
Both the Group and its portfolio companies continue to be approached by entrepreneurial individuals and teams who do not wish to be part of this consolidation process.
Graham’s view
I’ve been consistently positive on this one, and I’ll leave my stance unchanged here again today.
The share price has risen considerably but fully diluted NAV was last seen at 556p (July 2023) so the discount at the latest share price is still around 18%.
Given that recent disposals have been at or above BPM’s valuation of its investments, personally I’d have confidence in the NAV calculation here. Though it is inevitably a source of some uncertainty.
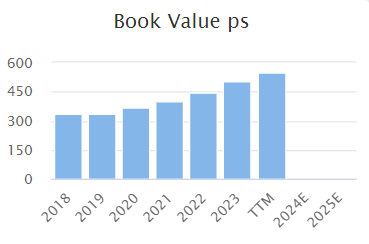
Brian Marsh (age 79) continues to hold 38% of the company that bears his name. I hope and expect that BPM will continue to apply its successful formula for many years to come, and that book value per share will continue to rise, even as the company makes larger dividend payments:
Springfield Properties (LON:SPR)
Share price: 77p (+1%)
Market cap: £91m
This Scottish housebuilder has issued a short announcement, re: the sale of land for £8.7m, most of which will be received in the current financial year.
As we discussed in December, this stock trades at a hefty discount to tangible book (£144m as of the last full-year results). However, one of the reasons for the discount may be some nervousness around the company’s financial position, including £68m of net debt.
However, the company laid out plans to reduce net debt to £55m by the end of the current financial year (FY May 2024), through land sales that would not affect its building plans.
That is the context in which we receive today’s update - with the proceeds from the disposal being earmarked for debt reduction.
CEO comment:
We are pleased to have agreed another profitable land sale, which brings the total since October 2023 to over £18m. With one of the largest, high-quality land banks in Scotland, these sales are an attractive way of monetising our land bank without impacting our development pipeline. We are in advanced negotiation regarding further land sales, which remains a key element of our strategy to reduce our bank debt."
Graham’s view
I’m going to remain positive on this one, as it seems the bull thesis is playing out as intended: the company has kept its debt position under control and is even reducing it, using its very strong balance sheet/asset backing to do so.
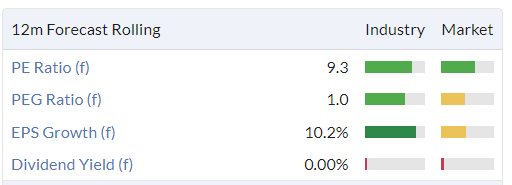
Springfield is not currently paying a dividend but it does offer a cheap multiple and future interest rate movements may be a help rather than a hindrance. So the outlook for shareholders seems quite positive to me. Interim results are due tomorrow, so we’ll find out more:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

109 comments
https://www.lse.co.uk/media/SA...
Webinar with MicroSalt (LON:SALT) on Tuesday 27 February 2024
https://ukinvestormagazine.co.....
From UK Investor Magazine
MicroSalt is an excellent IPO opportunity with a strong management team and carefully planned growth strategy.
When details of its major B2B customers are made public, the company will hit the public investing consciousness fast.
As usual, there are risks — but the rewards on offer are correspondingly promising.
https://us06web.zoom.us/webina...
Rick Guiney, CEO at MicroSalt, will talk us through what it's like being the new kids on the block on AIM, raising £3.1 million on 1st February 2024 following its spinout from TekCapital (AIM:TEK), and why they believe they are perfectly placed to benefit from the increasing demand for low-sodium products.
Webinar registration link above for Tuesday 27 February 2024 at 5:55 PM
Potential offer for Superdry :https://www.stockopedia.com/sh...
Surprised anyone wants to bid for Superdry (LON:SDRY) unless its a pre-pack...
Personally don't know anyone who buys the brand anymore, not sure on the popularity outside the UK but barely see anyone wearing it either.
You can tell its a quiet day in the markets when MicroSalt (LON:SALT) is the most discussed company by a country mile...
A stock that was much talked about here once upon a time - Globo. FCA has given up prosecuting the two directors! Pass Go, and dno not go to Jail. Win. Another kcik in the teeth for PIs.https://www.ft.com/content/e7d...
Yes indeed, incredibly disappointing that the brazen fraud of Globo, where mgt openly admitted the fraud at the end, has resulted in nobody being punished. Sadly, white collar crime DOES pay.
How to avoid similar frauds in future? We spotted most of them here in the SCVRs. Probably the only fraud we didn't spot was Patisserie Valerie.
I took the precaution of saving all my 29 negative articles on Globo, so that it could be used as a case study in future for all the really obvious things that were wrong, and in plain sight. Here's the link -
https://docs.google.com/docume...
Having come to stockopedia slightly after the Globo fiasco and an ex auditor myself, that was a great read.
Well done Paul for sticking to your guns on it and trying to make PI's aware of the situation.
Thanks JamesS,
"Having come to stockopedia slightly after the Globo fiasco and an ex auditor myself, that was a great read.
Well done Paul for sticking to your guns on it and trying to make PI's aware of the situation."
I want to keep the memories & facts about the Globo fraud alive.
Not least because I was brutally attacked by many PIs at the time. There was an organised campaign to get me sacked from Stockopedia. which made the bosses here uneasy. So I just said: back me, or sack me. I'm still here, and I was right. Only one Globo muppet apologised to me. All the rest disappeared in silence.
Regards, Paul.
Mello Events will be hosting their MelloMonday webinar tonight, at 5pm to 8pm. Graham is on the BASH.. The programme for the evening is as follows:
5:00pm James Ashton CEO at the Quoted Companies Alliance presents What is the QCA?
5:30pm Company presentation by Poolbeg Pharma
6:00pm Company presentation by Time Finance
6:30pm Trading Update from Duke Royalty
6:50pm BASH Panel
Do join us. See full details on the Mello posting or link in the SCVR today at the top
SALT Here's the US patent if you're interested: https://ppubs.uspto.gov/dirsea...
The general idea seems to be you mix salt with a carrier medium (e.g. protein powder, but there are many alternatives) to form a slurry (their words). You then dry it quickly (e.g. freeze or spray drying), which limits the size of the salt crystals.
Here's a fun fact: back in the 60's (I think) my late grandad was granted a UK patent to trim the edges of wallpaper. I had a search through the UK patent site, but I couldn't find anything. Maybe the patent wasn't in his name.
My grandad was a dyed-in-the-wool communist but with inventor leanings. One day my dad saw that he had dipped tobacco leaves in molasses and was hanging them out to dry.
MicroSalt (LON:SALT) Ah!! I get the idea now. You mix your cocaine with talcum powder and then it goes a lot further when you sell it and you make more money. Genius.
It is MicroSalt (LON:SALT) patented technology which means less salt needs to be used. This can be applied to, for example, breads, a huge market.
And maybe even their technology could be used for sugar and flavourings, like saffron, which costs so much.
https://find-and-update.compan... link to Microsalt's accounts for period ended 31 December 2022. Microsalt had a loss of nearly US$300k for end of year 2022 and not 2023. The link above is to Microsalt's Company accounts on the UK Government website and Microsalt's balance sheet at 1 October 2023.
Below is the investor presentation.
MicroSalt (LON:SALT)
This can be applied to, for example, breads, a huge market.
If this "invention" is as great as you say surely bread manufacturers could reverse engineer something that does the same job ? - are they really that clever that this "invention" cant easily be copied by all and sundry (for internal use rather than direct sale) ?
i remember beyond meat and a couple of others had huge share of the veggie burger market and similar stuff. I preums now all and sundry foodmakers and simply using their own copycat solution - i note beyond meat is down 97% from its peak which suggests the reality is only 3% of the hype !!
It is Microsalt's patented technology.
https://find-and-update.compan... link to MicroSalt (LON:SALT) accounts for period ended 31 December 2022.
Microsalt had a loss of nearly US$300k for end of year 2021.
Microsalt had an operating loss of nearly US$50k for end of year 2022.
Trade and other payables for 2022 was nearly US$300k and for 2021 was nearly US$250k.
The link above is to Microsalt's Company accounts on the UK Government website and Microsalt's balance sheet at 1 October 2023.
Microsalt at 1 October 2023 had equity of £2.5m and this was before the £3.1m from the IPO.
https://microsaltinc.com/docum... link to the admission document for Microsalt's IPO
It’s clear looking at 6 months accounts 30/6/23 per admission document that the company cannot have made profits 9 months to 30/9/23 end of - poster on other linked site had clearly not looked at 6 months accounts and clearly was talking nonsense when they suggested company was making profits in that 9 month period.
Assets vs liabilities shows a profit for MicroSalt (LON:SALT) at 1 October 2023. Check out the balance sheet for 1 October 2023 on Companies House website.
It is MicroSalt (LON:SALT) patented technology which means less salt needs to be used. This can be applied to, for example, breads, a huge market.
Unless there is something MicroSalt (LON:SALT) are keeping quiet this is nonsense. If you add salt to dough to make bread is dissolves. If the grains are very small it will dissolve quicker, that may be a benefit in making bread, but it's not going to make the bread taste any saltier.
I personally feel sorry for the shareholders that believe all about MicroSalt (LON:SALT.
All the best to shareholders
Assets vs liabilities shows a profit for MicroSalt (LON:SALT) at 1 October 2023. Check out the balance sheet for 1 October 2023 on Companies House website.
XPS Pensions (LON:XPS) - on a tear! I suppose today is making up for the rather subdued response to the +'ve TU a few days ago.
MicroSalt (LON:SALT) . Hard to see much real market here! If you accept that using much smaller particles of dry salt may make things taste saltier with less salt (I'll suspend judgement on that) the big issue is in how many situations does largely dry salt find it's way onto your taste sensors? Any salt added to premade food, or added to food any slower than very quickly before eating will have disolved (and smaller particles will disolve quicker!), so it leaves a fairly resticted set of useses - sprinkling salt on chips immediatly before you eat them, or perhaps salted crisps. I'd think that's a small proportion of total salt use.
Currys (LON:CURY) should be an interesting one to follow and see play out one way or another, for those of us who are interested in the OK! Magazine aspects of the markets.I always feel that the markets goings on are the equivalent of OK! magazine/gossip rags for me!But unfortunately Katie Price and princess Kate et. al do nothing for me.Perhaps i'm a little unusual, but i'm not sure i'd follow and be interested in the markets without the stories and shenanigans.
Looks like shrewd Elliot might have set a private valuation of Curry's at hopefully nearing the end of the bearish consumer cycle?And JD have apparently been forced to show their hands, which suggests they've been following and looking into Curry's business for a while.We all know the UK market is on sale......(!) And Paul Singer started and made his name in distressed stuff too.'"A pioneer in the business of buying up sovereign bonds on the cheap, and then going after countries for unpaid debts" according to his wikipedia!
https://theoakbloke.substack.c...
If this doesn't work then search for the oak bloke on substack.
He has written some articles on MicroSalt (LON:SALT) that are worth reading.
SALT’s Chair is ex-Sainsbury’s Judith Batchelor OBE.
Apart from her experience at Sainsbury’s (as Director for overseeing the Sainsbury’s Brand), her current involvement is as Chair at the FDF - the Food and Drink Federation.
The Oak Bloke spotted that Microsalt Ltd have given a 9 month picture of their accounts as at 30/09/2023.
In these accounts debtors of £0.78m and a tidying up of share capital as they converted from Ltd to Plc (i.e. rolled up the accumulated losses and share premium). The difference in total equity in 9 months is the P&L outcome.
A £338,647 profit.
£0.3m is a modest profit but it shows that SALT is profitable, already.
The Oak Bloke thinks PepsiCo is already one of Microsalt's customers buying their salt for Pepsico crisps, Walkers Crisps.
When annual sales are in the $ billions (e.g. PepsiCo made $86bn sales last year) if you can grow those by 10% that’s $8.6bn of extra sales. If you can make your products less harmful you massively win on the ESG front. Plus people may consume more of your product. Food is a guilty pleasure. Think about how they advertise foods. Then think of the consequences of healthier foods. Crisps with half the salt - can now eat double the crisps without feeling guilty!
The free float of Microsalt shares totals about 16% of the shares. There are 43m shares in issue so the free float is about 6.5m shares. Tekcapital own nearly 78% of Microsalt and the previous CEO owns 5.5%. I believe Tekcapital are not allowed to sell any Microsalt shares for 12 months.
The Oak Bloke has also written about Plexus Holdings (LON:POS) recently.
MicroSalt (LON:SALT) will not make any profits even on a £6m revenues. It is my opinion that what you are suggesting is not true about their profit.
The Oak Bloke from Substack found these figures from their accounts for 30/9/2023.
I know what I have in front of me and these figures are not true. MicroSalt (LON:SALT) is a cash burner and a jam tomorrow company. Perhaps you can share these accounts with us here and the logic behind this profit that exceeds basically the revenues!
These figures are on The Oak Bloke's Substack.
These are run rate figures! and I will not comment further on this.
All the best to shareholders
Thanks
https://find-and-update.compan... link to Microsalt's accounts for period ended 31 December 2022.
Microsalt had a loss of nearly US$300k for end of year 2022 and not 2023.
The link above is to Microsalt's Company accounts on the UK Government website and Microsalt's balance sheet at 1 October 2023.
Equity £2.7m!
Market Cap £45m!
All the best to shareholders
PS: The company is loss making and before you answer anything back I will urge you to study carefully the posts you are directing people here to read. Take this as a friendly advice from an accountant.
All the best
Assets vs liabilities shows a profit for MicroSalt (LON:SALT) at 1 October 2023. Check out the balance sheet for 1 October 2023 on Companies House website.
Hopefully is not another Boohoo (LON:BOO) CAP XX (LON:CPX) Revolution Beauty (LON:REVB) for you!
There are some very experienced and honest people in this forum and it is my opinion to read carefully their comments.
All the best
And Plexus Holdings (LON:POS)
That's a relief :-)
Meaning?
Only pulling your leg Yiannos - it's good to have both bull and bear opinions :-)
Yes I agree with yiannos1 on MicroSalt (LON:SALT) - there's no way it's profitable yet.
I read the whole of the Admission Document for MicroSalt (LON:SALT) over the weekend, and it was clear from the figures (to June 2023, not your Sept 2023) that SALT is definitely still loss-making on very small revenues. Also, I worked out that once listing costs, and proper salaries for Directors are added in, SALT looks set to be making losses of £2-3m pa in future. So it will need another fundraise.
I've not looked at "OakBloke"'s substack yet, but someone else sent me a link to his post on Plexus Holdings (LON:POS) . Also, if I don't know who someone is, or what their track record & experience are, then I wouldn't attach any weight to their opinions at first.
Regards, Paul.
Management at MicroSalt (LON:SALT) are open about the fact they have yet to turn a profit in their IMC presentation - it's all about what deals they can strike going forward and how quickly. There does seem to be momentum there though and serious interest from major industry players that have the potential to move them into profitability this year based on their own commentary. Def high risk though - no bones about it and will be v interesting to see how it plays out.
https://find-and-update.compan... link to MicroSalt (LON:SALT) accounts for period ended 31 December 2022.
Microsalt had a loss of nearly US$300k for end of year 2021.
Microsalt had an operating loss of nearly US$50k for end of year 2022.
Trade and other payables for 2022 was nearly US$300k and for 2021 was nearly US$250k.
The link above is to Microsalt's Company accounts on the UK Government website and Microsalt's balance sheet at 1 October 2023.
Microsalt at 1 October 2023 had equity of £2.5m and this was before the £3.1m from the IPO.
https://microsaltinc.com/docum... link to the admission document for Microsalt's IPO
MicroSalt (LON:SALT)
Johnnycomelately
The Oak Bloke spotted that Microsalt Ltd have given a 9 month picture of their accounts as at 30/09/2023.
£0.3m is a modest profit but it shows that SALT is profitable, already.
sounds like complete bo locks to me
per listing document 6 months to 30/6/2023 figures showed loss/operating of £1.65 million for 6 months - with negative gross margins on minimal sales. If annual run rate is £5 mill pa now - no way it would be possible for them to be profitable by 30/9/2023 looking at 9 month figures due to earlier losses. Note its has to be the case if the profit and loss has turned positive this would be due to exceptional adjusts not trade related - ie didly squat to do with them making any trading profits. Happy to be proved wrong if you or Oak Bloke can come up with rationale explanation as to why my presumption is not correct.
Hi rmillaree
These are run rate figures-in other words-imaginary figures.
Assets vs liabilities shows a profit for MicroSalt (LON:SALT) at 1 October 2023. Check out the balance sheet for 1 October 2023 on Companies House website.
Really?
Can you show us your calculations please?
Thanks
Check out the balance sheet for 1 October 2023 on Companies House website.
MicroSalt (LON:SALT)
Jonnycomelately
its 100% clear to me that there will be "non trade relateed" adjustments to balance sheet - these would show up as credits on the profit and loss. So the fact the profit and loss turns positive probably simply means they have created a profit on asset relvaluations or similar.
Facts are the admission document confirmed they lost 1.6 mill 1/7/2023-30/6/2023
Its ludicrous to presume then missing credits would be an instant change from losing money hand over first to the oppopsite in 3 months - sheet lunacy.
If the company was making money they woudl be shouting that from the rooftops.
If you dont believe me email company and ask if they had trading profit in that period and see what they say.
Hi rmillaree,
Better things to do than trying to help people that do not want to accept it.
He will not believe the company as well!
The sad thing MicroSalt (LON:SALT) is down 17.5% from yesterday.
MicroSalt (LON:SALT)
i dont mind trying to get to the bottom of facts - hopefully Johnny wants to find out the reality here - their response will hopefully indicate if that is the case. There is deffo an information gap here without the detailed profit fro 9 months , we know the profit and loss has had credit of 2 mill odd - seems blindingly obvious to me that will partly or wholly be related to non trade related activities . Hey ho the truth will out on the first set of listed numbers - dont mind admitting i am wrong if my reasonable assumptions turn out to be wide of the mark here. Its clear to me though the assumptions made on the linked article are not reasonable based on info we have - that company was losing dosh quickly that fact is not in doubt.
Imaginary facts!
Revenues-COGS=Profit
There is no other way.
Someone is looking at the assets and liabilities to find the profit?!
Anyway enough
MicroSalt (LON:SALT) .....and you can't short it on IG because, presumably, too much has been lent out already!!
https://find-and-update.compan... link to MicroSalt (LON:SALT) accounts for period ended 31 December 2022.
Microsalt had a loss of nearly US$300k for end of year 2021.
Microsalt had an operating loss of nearly US$50k for end of year 2022.
Trade and other payables for 2022 was nearly US$300k and for 2021 was nearly US$250k.
The link above is to Microsalt's Company accounts on the UK Government website and Microsalt's balance sheet at 1 October 2023.
Microsalt at 1 October 2023 had equity of £2.5m and this was before the £3.1m from the IPO.
https://microsaltinc.com/docum... link to the admission document for Microsalt's IPO
I like Wilmington (LON:WIL) but if you want bear(ish) points the results are not straightforward to follow with disposal of business, impending disposal of another one and acquisition all to factor in.
Ultimately continuing revenue is well back on last years total AND they have to secure half as much revenue again in H2 to hit forecast. Which they did last year but there's hardly a long history of that happening.
There is, at least, the chance of timings not working out and a dreaded H2 miss here. Also dilution is a constant hurdle to leap.
But I'll hold I think.
Wilmington (LON:WIL) I hold. In addition to Doug's points I would like Paul to cast his beady eye over the adjustments. Some seem substantial to me, (e.g. amortisation) and I could barely follow the arithmetic, never ,mind the rationale.
Richard
I'm pretty sure the adjustments with Wilmington (LON:WIL) are completely normal for acquisitive groups - ie excluding goodwill amortisation charges. This is generally accepted, and normal. There's nothing untoward in the numbers at all from WIL, this time, and in several previous reviews I've done of it. (no position).
Edison just released a research note for Wilmington (LON:WIL) Just a quick note, maybe they will cover it more in depth later.
Tekcapital (LON:TEK) and MicroSalt (LON:SALT)
The first one invests in the second one BUT they have the same person as a CFO.
Tekcapital (LON:TEK) need cash!
Conflict of interest? Of course not-welcome to the investment world of the UK small cap.
Another jam tomorrow pointless listing.
All the best
Assets vs liabilities shows a profit for MicroSalt (LON:SALT) at 1 October 2023.
Check out the balance sheet for 1 October 2023 on Companies House website.
I'm not sure that posting the same comment 5x gets us any further on........ Maybe cite the figs you are suggesting........?
You are making assumptions that in accounting make no sense.
I am an accountant but you still want to argue about things that it’s obvious to everyone you have limited knowledge.
Assets vs Liabilities do not show profit in any accounting method.
All the best
Re Springfield (LON:SPR). If I recall correctly they build affordable and social housing in Scotland and are/were dependent, in part, on Govt Policy. It was a change in policy by the SNP that caused the sp to crater. A factor to include in any research.
Springfield Properties (LON:SPR) I have held Springfield since IPO as I know the founding family
While SNP housing policy changes have affected them, it was their high relative debt (£67.7m according to Stockopedia vs their market cap of c£90m) that caused the share price decline imo. I have been pleased to see their recent focus has been on reducing this via land bank sales in the Central belt as opposed to making new acquisitions.
MicroSalt (LON:SALT) looks bonkers. Hardly any employees, no actual sales of note, one patent, huge dilution imminent. Why float now??
Feeding frenzy since launch for no discernible reason. What's their thing? Low sodium salt. Big deal. We can all buy low sodium salt.
So it's low sodium salt with no potassium in it! Big deal. We need potassium and have loads of it in our bodies.
If you want less salt, use less salt. If you want to get faddy, try low sodium salt. If you want to lose your money, buy MicroSalt (LON:SALT) it will micro your cash asap.
I have no position in MicroSalt (LON:SALT) but to be factual, it is not low sodium salt. It is salt. Sodium Chloride. It is just processed in such a way that the particles are much smaller than normal grains of salt so you get the same amount of salty taste but with less salt intake. So when you say "if you want less salt, use less salt", that is exactly what this does. Less salt, same amount of salty taste.
Hi Donald. That's strange. Company brief says
Whether it's low sodium or not, it seems like a terrible investment thesis - "We do smaller particles of salt - er, that's it. We haven't really sold any yet but we intend to try"
Yes, low sodium in the sense that you use less of it in the situations where it can be used. As Paul says, it would be interesting to know more about the patents involved to see if there is any sort of moat. I quite often turn normal sugar into caster sugar or icing sugar by blitzing in a blender. Is there more to micro salt than that?
Co-pilot says:
Low-sodium salt, also known as salt substitute, is a modified version of regular table salt (sodium chloride). Here are some key points about it:
....Apart from low-sodium salt, other salt types that have lower sodium content compared to regular table salt include:
RE :MIcrosalt
I doubt that the health discussion will move this share significantly one way or the other. For the sake of debate however - Scientific American now reports a recent study...
"New Study finds no connection between salt and Heart Disease"
. Link below.
https://www.scientificamerican...
The very definition of old news ... redefining "now". The article is dated July 6, 2011.
Indeed. Never made the news as far as I can recall. I would have thought that the processed food lobby would have been trumpeting this report.
Well there's no evidence (and never will be) that Homeopathy works better than placebo, but that's a multi billion $ industry.
The important thing is that people think it's good to reduce salt!
This has really sparked an interesting debate and all manner of opinions. Try reading the current guidance from the American Heart Association. More importantly the FDA plans to review its guidance to the food industry and take further steps to lower sodium in the food supply to meet the 2,300 mg of sodium limit recommended by the Dietary Guidelines for Americans.
I recently bought a starter position in Wilmington (LON:WIL) , it seems to have the financials I like to see; decent organic sales growth, good operating margins, solid cash conversion, and no substantial amounts tied up in working capital or large obvious areas of accounting discretion sitting on the balance sheet. Seemly decent interims, another step forward, any thoughts from other investors?
I recently bought a starter position in Wilmington (LON:WIL), any thoughts from other investors?
I've held for a while. Regulatory moat, sticky products. Not quite a mini RELX, of which I'm a big fan, but the closest thing on these isles. What's not to like?
Yup I agree with you both. Have just published my own review of H1 from Wilmington (LON:WIL) and I continue to see a really nice quality business, still reasonably-priced, despite shares having tripled from the pandemic lows.
I can't see much likelihood of it suffering a downturn in demand either, as regulation/compliance seems to be an ever-expanding burden on companies.
Thanks Paul and BnB
Another great podcast Paul thankyou. Where else would one hear classics like "oh bugger Joan's at the door" midstream." Very Carry On esque. Hope your Mum recovers quickly.
I enjoyed it too, I noticed the lack of coughing. Is that extra water helping rather than champagne.
MicroSalt (LON:SALT) - Big uses of salt in foods are 1. As a preservative, 2. For flavour. I don't know how the cost of microsalt compares to that of regular salt, but unless it is less that double the price per unit of mass (I doubt this), in order to get the same same flavour per unit cost, I cannot see many companies wanting to make the transition. When it comes to the other key use of salt, as a preservative, does having 1g of microsalt have the same preserving power as 1g of regular salt, if so, why would most companies use the higher cost ingredient. Yes, a few will want to market the products as lower sodium maybe but I cannot see the value in this product as a growth market. If you want your bluesky fix you would be better to buy shares in Zotefoams (LON:ZTF) , get a decent business and your bluesky growth in for free with their Rezorce project. That or go for something over in the US like Crispr Therapeutics AG (NMQ:CRSP) where you have a genuinely life changing technology with a huge runway for growth. (I hold Zotefoams (LON:ZTF))
BenHazz, I would be surprised if it will be used as a preservative. I'm no chemist but I think this works on the basis that the micro particles, when they are on your tongue, taste saltier than normal salt. So you put less on your crisps or steak to get the same flavour.
I'm fairly sure flavour isn't anything to do with the preservative property of salt and I should think if anyone was making brine with MicroSalt they would just be wasting money - as all salt particles are dissolved.
Likewise, put MicroSalt on your cooked veg for flavour but don't put it in the water you are boiling them in.
Tekcapital (LON:TEK) have listed another one of their holdings in the US Innovative Eyewear (NAQ:LUCY) and has almost lost all its value.
MicroSalt (LON:SALT) have been trying to achieve same thing for the last 10 years.
They will certainly have to raise more capital and I believe that Tekcapital (LON:TEK) will take this opportunity to raise more capital as well!
All fair points, I am sure you are correct Roger as your scientific understanding seems a lot better than mine! - In that case the market for MicroSalt (LON:SALT) is quite niche as anything that requires salt for preservation won't use their product, I think even things like ready meals will need preservative salt despite refrigeration. I get Huwsters point about health implications, obviously without the negative impact of sodium on the body there would be no use for the company at all. I agree its a great cause and a nice concept, I just can't personally see how it is going to make any money.
MicroSalt (LON:SALT) I just can't personally see how it is going to make any money.
My hunch is it will take robust government action to force a reduction of salt levels in processed food before food manufacturers are moved to act. This is certainly not out of the question but efforts to legislate against sugar fell well short of ambitions
You're right Roger, preserving with salt or sugar (as in Jam) was explained to me by a chemist I worked with as osmosis. The means by which trees get nutrient to the top branches. Water will move into a concentrated solution of salts etc through a permeable mebrane like a cell wall drying out the cells internals and killing contaminating microbes. So the concentration is crucial.
Misses the point, it's for the major health benefits of less sodium which is a global contributor to heart disease. Management don't think cost is a blocker as salt is less than 2% of unit cost of food production and less product can also be used in manufacturing process of crisps, nuts etc for same flavour profile which compensates for higher cost.
The stock market is not interested about health benefits-British American Tobacco (LON:BATS) would have been zero by now!
MicroSalt (LON:SALT) is another jam tomorrow company that is burning about £3m pa.
Last year PepsiCo said 30% of their Walkers' sales come from "Healthy" snacks.
People like the taste of salt
The potential value of Microsalt is massive and I suspect they will be snapped up by a major manufacturer before too long. In the meantime shares are very high risk.
MicroSalt (LON:SALT)
The potential value of Microsalt is massive
I cant see any broker forecasts - if this product is great should brokers not have great sales numbers pencilled in ? surely the proof of the pudding is expectations of sales and profits to be flowing in over next 12 to 24 months ? If they dont havea broker backing them up giving us numbers should we really be taking them seriously as £50 mill cap company?
in absence of real numbers potential is imho just that - every blu sky company has potental if you believe the hype - its commercial level of sales (delivering decent gross profit) that matter.
I believe the health angle of salt = bad, is a little simplistic. It is bad for high blood pressure, but beneficial for people with low blood pressure. But as nationally more people have high v low blood pressure, the easy story is that it is bad (which of course makes it in to the media).
I have not followed MicroSalt, so not making a comment on the company. Just thought I would add that bit of info for anyone interested
Transense
Ok results
Has a couple million cash and makes about half a million .
Jam tomorrow for sure .
But to be fair a bit of jam today and no debt so ok .
Bonne maman can breathe a sigh of relief .
SALT "Why float now, raising so little cash (£2.5m after fees)? If sales are about to take off,"
This reminds me of a US mining company where a broker spotted a note from one director to another: "Cancel IPO, have found gold."
I'll raise another interesting point that a fund manager made: if the thing was any good, why didn't they list in US? The US love their tech stocks. Did you know that around 30-40% of companies that form part of RUT (Russell 2000) are loss-making? The number of loss-making companies has been creeping up at least over the last 20 years.
I'd also like to relate my experience with a small AIM quite a number of years ago. It was trying to come up with medical stents. I invested in it it because it looked quite promising. As it happened, it was a blue-sky stock that actually worked. I only had a small amount in it, and I think I tripled, or something. I consider that a bad thing, though. The company was taken private soon after it had a viable product. Who knows what it would be worth now? Many many times that value I suspect.
Costs of listing in US much higher than AIM I believe so this may have factored into decision.
MicroSalt (LON:SALT) Red flag as they have tried to raise about £15m unsuccessfully in October. Jam tomorrow company-there are many similar companies trying to achieve the same in this field-heavily loss making with a main shareholder owning around 77%.
Yiannos, yes they had to delay the IPO , date kept being pushed back and they certainly wanted to raise more - so new fund raise certainly likely. But note, main shareholder who owns 77% is an investment company, which itself has no individual shareholder with largest individual shareholder owning 5.5%.
Sorry to hear about your Mum’s fall Paul, wishing her a speedy recovery. Look after yourself too.
Paul, regarding Currys (LON:CURY) , I now see there is an additional RNS from JD.COM, the Chinese Online company, who also confirm some recent press speculation that it is in the very preliminary stages of evaluating a possible transaction that may include a cash offer for the entire issued share capital of the company.
SALT was offered to me three times - given how they struggled to get it away I'm surprised by the rally.
Warrants were offered in the last one so would've thought people would be keen to dump the equity and even cash in the warrants if they were kept in.
Thanks for the write up on MicroSalt (LON:SALT) Paul. I've ordered some of their table salt from Amazon to try it out but as you elude to in your commentary I think the main commercial application will be B2B for companies producing nuts, crisps etc that the company claims will drive near-term profitable growth. I also can't see the benefit of dissolving the product in ready-meals etc but makes sense as a coating. I liked the fact that it has delivered 29 metric tonnes of MicroSalt to one of the world's largest beverage / snack good companies for use in one of its leading crisp brand flavours although it doesn't name the company or give an indication of $ amount. In terms of the Tekcapital share holding, there is a 12-month lock-in period from date of admission but they can exercise their warrants for a period of three years from date of admission at 10% above IPO price. I was pleased to see that they also subscribed for 2,588,140 new ordinary shares at the listing price.
Bank of Georgia (LON:BGEO) acquisition of Armeniabank- looks interesting. 2.6* PER and 0.65 book value should be nicely earnings enhancing. Dividend policy staying the same which given the EPS increase looks like it may also go up - at least over time. In my view good regional diversification at a decent price in a strongly growing economy.
Yes David, Bank of Georgia (LON:BGEO) buying this bank out of its cash ($303m) shows some of the strength of this company.
Any boost to the value of Bank of Georgia (LON:BGEO) increases that of Georgia Capital (LON:CGEO), as it holds 20% of their shares.
I hold both.
Bank of Georgia (LON:BGEO)
For those interested there is a sizable note out from Cavendish this morning and available on Researchtree (not sure if it is free issue). They view the transaction very positively.
(I hold)
Broker target price raised to £67.50 which lines up nicely with my own investment thesis of £60-70 p/share. TNAV should be about £50 p/s forward a year and I’m personally looking for a re-rate towards a 5 or 6* PER multiple, which in itself is hardly demanding, given the long term track record. Even if it only grows in line with GDP from here we are looking at 5-6% eps growth for the group but I doubt thats the likely outlook as there will no doubt be synergies from the deal too, so I am anticipating low double digit growth annually plus whatever the earnings accretive deal adds (I understand estimates for that are 20% to current eps but I need to look closer into this). That’s pretty good given an unfavourable rates outlook for banks generally. (ie lower NIM)
With dividends around 7% at current levels and buy backs generating north of 4% there’s a hefty shareholder yield return so a few % of capital growth required to support my portfolio target of 15%+ cagr. Who knows when the market will start to reward decent banks with slightly better ratings than a PER of 3 though! I understand reluctance around banks with lower capital ratios and those with complex assets that can be marked very differently and screw up equity but simple banking businesses with circa 20% capital and very strong liquidity that seems harsh.
Easyjet founder calls for Nasdaq listing. Ryanair has one and TUI has decided to leave London. Sounds interesting.
“I often look at the value of Ryanair and wonder why it is higher than Easyjet,”
"Ryanair is currently valued by markets at £19.7bn, compared to Eastjet’s £4.3bn valuation. This makes the Irish airline worth over four times as much, despite serving only 1.5 times more routes"
https://www.cityam.com/easyjet...
I wonder if the difference in value could be that Ryanair Holdings (ISE:RYA) makes more than four times the profit of easyJet (LON:EZJ) on just 25% more revenue?
Ryanair Holdings (ISE:RYA) operating margins are three times higher than that of easyJet (LON:EZJ) !
If you look at te comparison on the stockpaedia compare stocks screen you will see the reason.
My morning smallcap tweet: Warning: trading smallcaps may be harmful & quitting can improve your health
B.P. Marsh & Partners (LON:BPM) CAP XX (LON:CPX) Spaceandpeople (LON:SAL) Currys (LON:CURY) Petards (LON:PEG) Transense Technologies (LON:TRT) Esken (LON:ESKN) Dialight (LON:DIA), Wilmington (LON:WIL)
◄B.P. Marsh (BPM)► FY-Jan trading. 'Funds' (cash?) £40.5m. NAV £204m, up £14m over July.. Will pay £6m in dividends over the next three years. [SP=450 Cap=167m]
◄CAP-XX (CPX)► will not appeal Maxwell Technologies's case win after considering the fees and probability of success. [SP=0.66 Cap=5m]
◄SpaceandPeople (SAL)► guides FY-Dec rev c.£5.8m, slightly above market expectations (adj for UK retail rev being recognised on a net basis). Cash at hand £1.9m. [SP=57.15 Cap=1m]
◄Currys (CURY)► confirms report of 62p bid. Rejects it. [SP=47.08 Cap=534m]
◄Petards (PEG)► wins £0.35m order for delivery during 2024. [SP=5.62 Cap=3m]
◄Transense Technologies (TRT)► H1-Dec esrnings in line with expectations on slower revenue growth, partly due to a temporary reduction in overheads. . Guides modest reduction in short term profit expectations due to the carry-over of this investment into next FY. [SP=100 Cap=15m]
◄Esken (ESKN)► subsidiary London Southend Airport has reached terms of settlement of the loan dispute. The recapitalisation proposal would mean Esken has only a minority interest in the airport. Esken has until 4 Mar to agree. Co v short of cash. [SP=0.39 Cap=4m]. I hold.
◄Dialight (DIA)► second interims (Dec) rev down 12%. Orders down 5% at constant currency. "Challenging market conditions expected to continue through 2024, however the Board remains confident in the refreshed strategy and the medium-term benefits of the transformation project." [SP=154 Cap=61m]
In line: WIL
Cavendish Financial (LON:CAV) incentive plan looks very generous, it would be interesting to hear some thoughts on this one.
Back to a real company Cavendish Financial (LON:CAV):
Anyway, my two penn'orth.
Cheers
Chris