Small Cap Value Report (Mon 19 June 2023) - BKS, SNX, CNC, BPM, CREO, MMAG

Good morning from Paul & Graham (back today after a week off)!
Today's report is now finished.
I woke up very early today, after having a weird dream about being interrogated/gaslighted by Ant & Dec, then Ed turned up and rescued me, only to get me involved in investigating the death of a busker. Maybe I should stick to writing these reports, as I don't think my subconscious is displaying much talent for fiction!
I used the spare time to do some investigation of my family tree - a relative made us all do DNA tests on 23andme, and it's throwing up some amazing results!
Weekend podcasts - it's good to see the audience gradually building for my weekly audio output. Part 1 is a summary of the SCVRs, popular amongst the dog-walking community, I'm told. Part 2 is my macro news/views roundup, and is new content (so not in these written reports), which people might find interesting. Or if not, then just ignore. I like doing them, as it helps me collect my thoughts after the blizzard of news & work every Mon-Fri.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
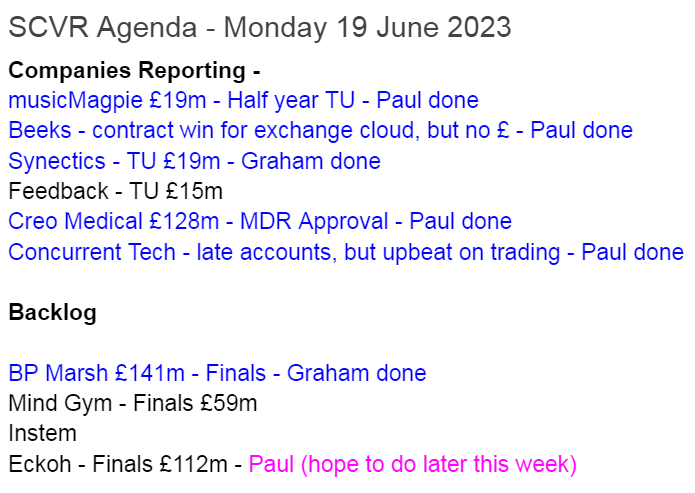
We're not impressed with the micro caps issuing trading updates today, so we've decided to look at some more interesting backlog items as well -
Summaries
Synectics (LON:SNX) - down 2% to 105.25p (£19m) - TU (in line) - Graham - AMBER
This security company issues an in-line update. An H2 weighting is in the works, so the pipeline needs to deliver as expected. Estimates suggest the shares are too cheap but underlying quality appears limited so I’ll wait a little longer before turning green on this stock.
Beeks Financial Cloud (LON:BKS) (Paul holds) - Up 2% to 118p (78m) - Exchange Cloud Contract - Paul - GREEN
A contract win for its flagship cloud computing service with Johannesburg Stock Exchange. I have a look in the section below. Reassuring, rather than game-changing. An interesting GARP stock maybe?
Concurrent Technologies (LON:CNC) - Down 1% to 70p (£52m) - Update on audited results - Paul - AMBER
A further delay to publication of audited accounts, due to several prior year adjustments, and a more conservative approach to capitalising development spend. This will also hit the overdue FY 12/2022 profit by c.£0.6m. It all looks sloppy, but fresh outlook comments sound more positive. So on balance, I'll give it the benefit of the doubt!
B.P. Marsh & Partners (LON:BPM) - up 4% to 390.4p (£141m) - Finals - Graham - GREEN
I remain positive on this investor in insurance intermediaries. In May it agreed to sell a major asset for £51m of cash, with the result that it plans to put an extra £6m into buybacks and pay out £7m of dividends over three years. Balance sheet NAV per share is over 500p.
Creo Medical (LON:CREO) (Paul holds) - Up 14% to 36.5p (£128m) - MDR Approval - Paul - AMBER
I've previously been savage about this heavily cash-burning medical devices innovator. But a webinar with Paul Jordan of Amati, convinced me that, since a £34m fundraise in March 2023, this company now looks adequately funded, and its products seem genuine game-changers for bowel surgery. Definitely NOT for widows & orphans, this is a highly speculative punt only! But its shares are rising strongly, so thought I would update you on it.
Musicmagpie (LON:MMAG) - up 4% to 18.5p (£20m) - H1 Trading Update - Paul - RED
An in line update today, with Q2 better than Q1. However, positive EBITDA turns into a adj LOSS before tax, due to large depreciation & amortisation (of development spending). So it's racking up bank debt, buying products to rent out, that it loses money on overall. I think it's a terrible business model.
Paul’s Section:
Beeks Financial Cloud (LON:BKS) (I hold)
116p (pre market) £76m - Exchange Cloud Contract - Paul - GREEN
Beeks is a niche cloud computing company, providing low latency connections to financial exchanges globally. I think it looks a very interesting high organic growth share, with recurring revenues. With the bear market in small caps, and lack of big contract news lately, the price has drifted down to a more interesting level I think.
This morning it announces that its flagship service Exchange Cloud, launched in June 2022 has won a second client, the Johannesburg Stock Exchange. Unfortunately, there is no indication in the announcement about the contract size or terms. However, a note from Canaccord (many thanks!) is newly up on Research Tree, and this indicates no material effect on Jun 2023 results (as it’s only 11 days to the year end), but “well underpins” June 2024 forecast of +20% organic revenue growth.
A bonus is that the IT kit can be supplied from inventories that Beeks built up during the chip shortage, so no cash requirement from Beeks to implement this contract.
Paul’s opinion - the story had gone a little quiet, so this contract win is a nice boost to investor sentiment. Beeks has told us before that exchange cloud contracts are large and complex, so take time to negotiate and implement. Each new site acts as a further reference site, which reassures potential new customers. So I’m hoping Beeks might build momentum.
It’s more speculative than the usual things we cover here, but Beeks is a tight ship, and has already reached profitability. Management particularly impress me (hands on entrepreneur), and the founder has lots of skin in the game, holding 38%. He's made it clear before that the plan is to build up the company, then sell it in future.
Worth a closer look for growth company investors, I think.
For balance, some investors have criticised the cashflow profile, in that new contracts require up-front capex from Beeks, which has resulted in it needing several fundraises - although far from ruinous, the share count has risen from 49m to 66m in the 5.5 years it’s been listed. During that period revenues have growth from £4m, to est.£25m this year, and it's moved into profit.
Another important point is that staff wages are low, but made up with share options (for all staff I think). So for that reason, I would not adjust out the share options charge in the P&L, as more than with most companies, it's actually staff remuneration.
I think this is one of the more credible small growth stocks on the UK market. There’s lots of detail in the archive here, as I follow this one closely, and hold some shares myself (long-term). This strikes me as the type of share which could re-rate sharply once the next bull market starts.
Stockopedia is singularly unimpressed, with a dismissive score of just 15 on the StockRanks - telling us to (at least) do a lot more digging into the numbers, or for the risk averse to avoid it altogether. Your call!
My view is that the company has made great progress in the last 5 years, but the share price is back down to there it was. To me that's more of an opportunity than a threat. I might add to my position on any further weakness.
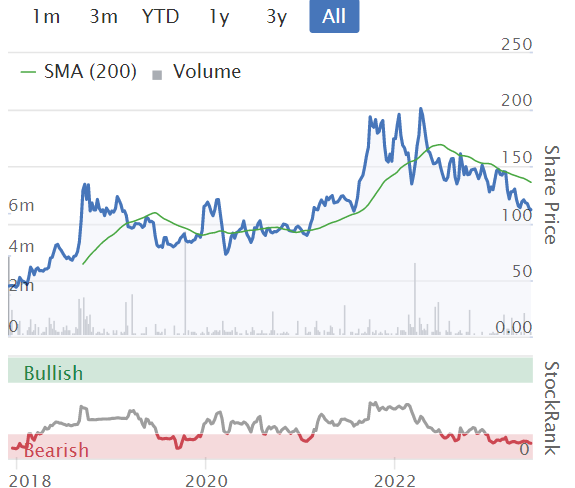
Concurrent Technologies (LON:CNC)
Down 1% to 70p (£52m) - Update on audited results - Paul - AMBER
Concurrent Technologies Plc (AIM: CNC), a world-leading specialist in the design and manufacture of high-end embedded computer systems and boards for critical applications, provides a further update on the timetable for publication of the Company's full year results for the year ended 31 December 2022 ("FY22")
This is really sloppy.
There’s already been one delay, and today it says the auditors need a few more days to complete final reviews. That means it will have taken the company almost 6 months to publish FY 12/2022 results, which is the sort of timescale I normally expect from the lowest quality companies. Which is strange, as CNC is a proper business, historically profitable and paying divis, with an OK balance sheet.
I last reviewed it here in early Jan 2023, when a lacklustre trading update suggested that FY 12/2022 would only be around breakeven, after taking a hit from supply chain problems. The outlook for 2023 sounded more positive though.
The clock is ticking, as under AIM rules, as the company comments today, its FY 12/2022 audited accounts have to be published by 30 June 2023. Otherwise shares would be temporarily suspended - not a disaster, but looks really bad.
It confirms that FY 12/2022 revenue is still expected to be £18.2m. So what? Revenue is one of the simplest numbers to calculate, so I wouldn’t expect that to change post year-end! It’s profit that matters, which can change if audit adjustments are identified.
Prior year adjustments - capitalised development spend of £1.1m between 2016-2020 has to be removed and expensed instead. So that means historic profits were slightly overstated, but at something like £0.2m pa I can’t get too worked up over that.
The more conservative approach to capitalising R&D has had a more significant impact on FY 12/2022 though -
There is no material impact on the reported profit for the year to 31 December 2021, but the change has resulted in profitability in FY22 being reduced by c.£0.6 million as a result of a lower amount of R&D being capitalised.
So this means it’s now looking to be a loss of c.£(0.5)m for FY 12/2022, I think (no access to any broker notes).
This comment confirms my impression of sloppy accounting historically -
There are a number of smaller prior year adjustments requiring to be booked reflecting the rigour from both the Company and Auditors on past accounting.
Outlook - this upbeat paragraph is more important than historic accounting problems I think -
Looking forward to the current financial year ("FY23"), the Board is growing increasingly confident of delivering a significant increase in revenue over FY22 and of its ability to meet and, potentially, exceed current market expectations for FY23. This confidence is underpinned by continued growth in new orders and increasing visibility on physical delivery of key components required to fulfil backlog orders.
Paul’s opinion - I think serious questions need to be asked about the finance team, and whether they’re up to the job.
If you trust management, then the outlook comments sound pretty good to me.
Overall, I’m leaning towards giving them the benefit of the doubt, because historically this has been a decent enough little company.
Shares are priced at 20x est FY 12/2023 forecasts, which factor in a rebound from 2022’s losses. So unless you think it can beat forecasts, then I don’t see any particular attraction to this share. There might be something interesting in the products though, and their potential, but that’s the next level of research that you would need to do, I’m only looking at the current facts, figures, and forecasts, which don’t look particularly interesting. So I’ll go AMBER.
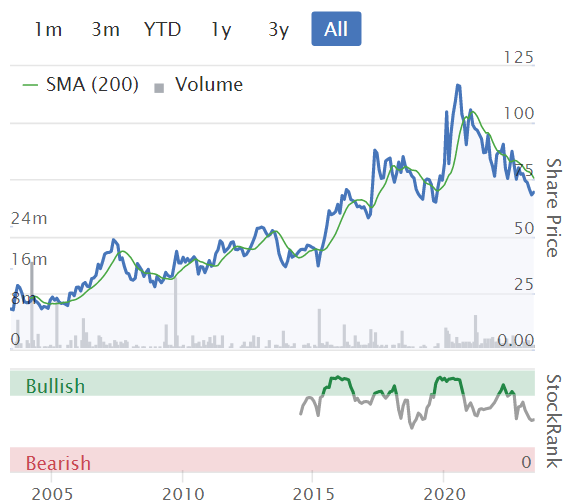
Creo Medical (LON:CREO) (Paul holds)
Up 14% to 36.5p (£128m) - MDR Approval - Paul - AMBER
MDR means Medical Device Regulation (in Europe). Approval has been achieved for CREO’s innovative medical devices for surgery on the entire gastrointestinal tract (previously only authorised for the lower part).
I’ve previously been highly sceptical about this share, due to its enormous cash burn, and it looked likely to go bust. However, major shareholders recently refinanced it at 20p per share for £34m, in March 2023. CREO now reckons it has enough cash to reach breakeven (they always say that though!). This impressed me, that it could raise a decent slug of cash in awful market conditions like this.
Paul Jordan of Amati was extolling CREO’s virtue on a webinar with Paul Hill, so after listening to that, and satisfying myself that cash was now OK, I took a speculative position personally. Well, everyone’s got to have a bit of fun!
Its medical devices allow much more efficient, safer, less invasive bowel surgery. Products have been launched, and seem to be gaining traction with experts in the field.
The bad news is prodigious cash burn (£30m last year alone!), and it’s not expecting to reach underlying EBITDA until 2025. The cash should last until end 2024, it says.
Paul’s opinion - purely as a punt, I think CREO looks intriguing, and it seems to be catching investors’ eyes at the moment. Very much NOT a value, or even GARP share, but as a speculative idea, I’d be interested to hear what readers think! The major shareholders obviously continue to believe in it, or they wouldn't have refinanced it in such a difficult market where they're probably facing client redemptions.
Have shares bottomed out now, I wonder?
Musicmagpie (LON:MMAG)
Up 4% to 18.5p (£20m) - H1 Trading Update - Paul - RED
musicMagpie, a circular economy pioneer specialising in refurbished consumer technology, announces an unaudited pre-close trading update for the six months ended 31 May 2023 ("H1 2023").
Adjusted H1 EBITDA up 7.7%; trading in line with Board expectations
Soft Q1 (Dec-Feb) due to post strikes & low consumer confidence, Q1: £0.8m EBITDA.
Stronger Q2 - EBITDA £2.0m, up 42% vs Q2 LY.
H1 total EBITDA: £2.8m.
Focus on cost control & gross margins, rather than chasing revenue growth.
H1 revenues down in both divisions, totaling £62m (H1 LY: £71m).
Gross margin up by 310bps, but this is not comparable, due to change in revenue mix towards rentals.
Lower overheads in Q2 - good, you need to cut overheads when revenues are dropping.
Active customer numbers on rentals (phones, tablets, etc) is 39k (doesn’t sound very much, but it’s up 28% since year-end of 11/2022).
Bank facility of £30m extended to July 2026, which is very surprising to me - maybe the bank sees something I don’t?
Net debt £13.7m at 31 May 2023. Remember it’s borrowing this money to buy secondhand phones to rent out to people who presumably can’t get hold of phones any other legal way.
Outlook - seems confident -
As evidenced in previous years, the Group has a much stronger second half weighting to its financial year, owing in part to seasonal peak trading around the Black Friday weekend in November. This seasonality, combined with the continued focus on own store sales and the strong performance achieved in Q2 2023, means that the Board is confident in the Group achieving its full year expectations, whilst remaining cognisant of the current tough consumer market.
Paul’s opinion - as I’ve mentioned here before, EBITDA is particularly meaningless for MMAG. Shore Capital’s update note (many thanks!) this morning estimates £8.7m EBITDA for this year FY 11/2023. But that turns into an adj LOSS before tax of £(1.5)m! So it’s not profitable at all. Yet it’s racking up debt to buy all these old phones!
This looks a terrible business model to me. Unless something changes for the better, then I think the bank are likely to get an expensive lesson in how EBITDA is not profit, or cashflow with this business model. If I’m right, then the equity could end up worth nothing.
As nothing has changed for the better, I have to maintain my highly sceptical view, RED. The business model is no good, that’s obvious from the broker’s forecasts. If you think it can smash forecasts, then it could surprise to the upside perhaps, but I wouldn't want to invest on that basis.
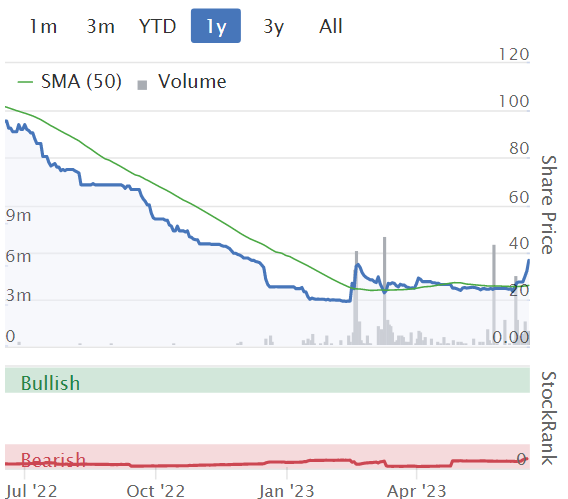
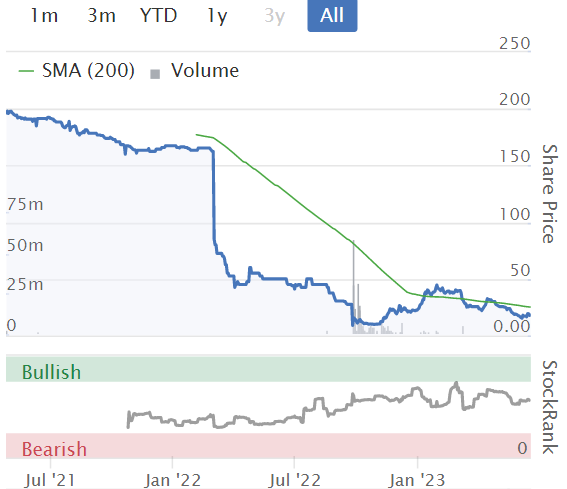
Awful chart below - yes you guessed it, MMAG floated in 2021!
Graham’s Section:
Synectics (LON:SNX)
Share price: 105.25p (-2%)
Market cap: £19m
Synectics plc (AIM: SNX), a leader in advanced security and surveillance systems, provides the following trading update for the six months ended 31 May 2023 ("H1 2023").
This surveillance/security company announces that its current order book, combined with its pipeline, “underpins the Board’s expectations of significantly improved trading in H2 2023”.
It last updated shareholders at its AGM in April, when its Systems division was “slightly ahead”, while its Security division saw “a slow start”. It explained then that the current financial year (FY November 2023) would be more heavily weighted to the second half than previously expected.
Today it says the same thing: that the current financial year is going to have a heavy H2 weighting.
When an H2 weighting appears out of the blue, it’s a sign that things are going badly. But what SNX is saying today is merely a reiteration of what was said before.
A post-Covid / oil & gas boom is underway:
Progress in H1 2023 was underpinned by strong trading in the global oil & gas market, which is expected to continue in H2 2023 and beyond. The Company has already increased supply chain and production capacity in this sector. Progress in other markets has been modest, with further improvements expected in H2 2023.
Net cash: approximately unchanged at £4m.
Estimates: unchanged, with the broker looking for adjusted EPS of 10.9p in the current year, rising to 16.8p next year.
Graham’s view
The underlying quality of this business seems to be average. Pre-Covid, in “normal” conditions, ROCE was in single digits. Indeed, so was the operating margin.
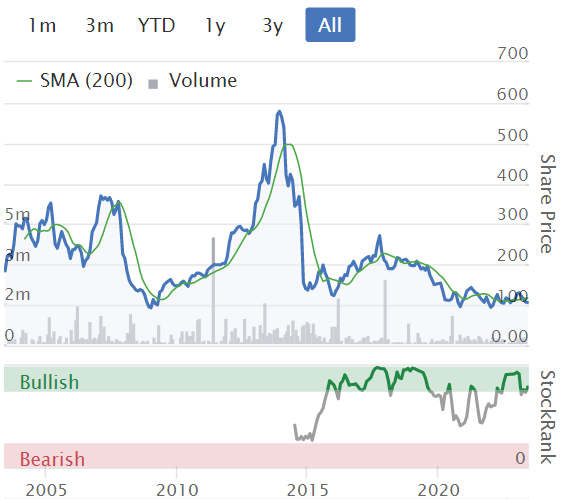
So I’m not sure I’d ever want to pay a high multiple for this one. However, in the current depressed environment, this has arguably fallen into value territory:

If the oil and gas boom continues, or if demand from casinos improves, then perhaps we can see Synectics hitting its estimates (or even getting close to them, which would still be a win for shareholders!). The PER based on next year’s EPS estimate is 6.4x, according to the company’s broker.
I am leaning towards Green on this one, but personally I would stick with better-quality stocks to bet on, so I’ll leave it with an Amber view for now. However, if it looks like it’s going to hit its FY 2024 estimates and the valuation doesn’t budge, then I might be forced to give it the thumbs up in a future report!
B.P. Marsh & Partners (LON:BPM)
Share price: 390.4p (+4%)
Market cap: £141m
This is a share I’ve previously held, and met the management team. However, I ended up selling it a few years back (I think it was one of the ones that sadly had to go in order to fund a house purchase).
My opinion of the company has never really changed: it’s an impressive, founder-led investor in the insurance sector with a track record stretching back over many years (founded in 1990). 40% shareholder Brian Marsh remains involved as Chairman.
I reviewed it positively in February, noting that a buyback had begun with the explicit aim to reduce the NAV discount at which the shares were trading. Net asset value per share, according to the full-year results published last week, was 526.2p (up from 462.7 over the year).
One of the obstacles with this share, in my view, is that it’s difficult and time-consuming to form an independent view on the specific holdings in BPM’s portfolio. So BP Marsh shares are perhaps best treated as a regular investment in a PE fund, where you are taking a chance on the diligence of the managers.
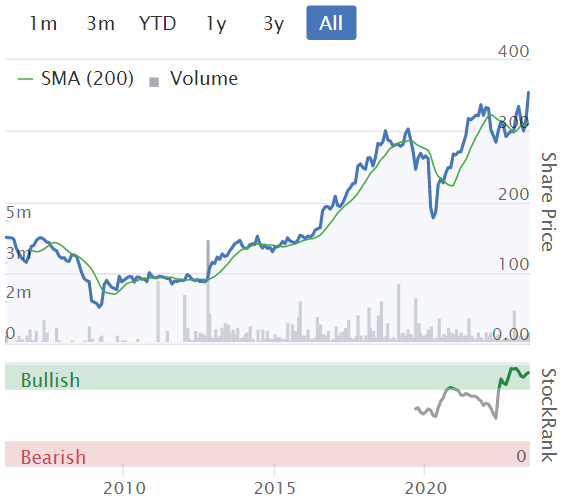
The track record here looks encouraging to me (it goes back much further than 2018):

Let’s check out some of the most interesting bits from the full-year results for FY January 2023, and the outlook.
Total shareholder return for the year of £23.9m, or 14.4% (including dividend).
NAV of £189.5m, or 526.2p per share as I’ve already mentioned.
Fully diluted for share options, NAV per share is 516.8p.
Post year end disposal of Kentro for £51.5m - this was announced to the market in May.
Importantly, the disposal price for Kentro is perfectly in line with BPM’s July 2022 valuation - this helps to boost confidence that BPM’s valuations of its investments are reasonable.
Brian Marsh comments on the results:
"The c.14% increase in NAV (net of dividend) reported in these results demonstrates the strength of our business model which focuses on difficult to replicate opportunities, principally in the growing insurance intermediary markets globally. I look forward to reporting further progress for the current financial year, subject as always to the absence of major macro-economic shocks."
Use of proceeds
With an unusually large cash windfall coming, BPM “will seek a healthy balance between returning cash to shareholders and reserving sufficient funds to be able to continue its proven strategy of making successful investments”.
Dividends: BPM wants to pay £2m to shareholders each year in 2024, 2025 and 2026, plus a one-off £1m special dividend.
Buybacks: an additional £6m in share buybacks.
The company previously said that it would spend up to £1m on buybacks, when the share price discount to NAV was at least 20%.
It’s not clear yet whether the condition of a 20% discount will apply to this new buyback, but more information will follow “in due course”.
Based on the latest share price and 526.2p of undiluted NAV per share, the shares are currently trading at a discount of nearly 26%.
The outlook doesn’t give anything away, but is confident:
The Group believes that these results demonstrate the strength of our business model which focuses on early-stage investment in the insurance intermediary market. This market continues to generate attractive opportunities for B.P. Marsh and our leading position within it means that we get first look at many such opportunities.
Separately, the CIO confirms that it’s business as usual: “The Group remains focussed on sourcing new business and has an active pipeline of new business opportunities which are currently being considered.”
Here’s a helpful breakdown of the portfolio provided by the company, with Kentro shown as 27% of the total:
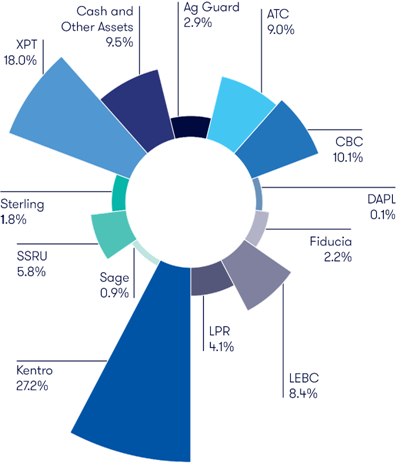
The investments are split between “MGAs” (managing general agents, who work directly on behalf of insurance companies), insurance brokers and an IFA.
Graham’s view
I am compelled to remain positive about this stock, as I liked it anyway, the news is positive, and the market cap remains at a substantial discount to its balance sheet value.
Of course there is always going to be some uncertainty around the true worth of stakes in private companies, but the disposal of Kentro at BPM’s own valuation does help to boost confidence.
Regular readers will know that buybacks are one of my favourite investment themes, especially when they are carried out by good companies at attractive prices. So it’s excellent to see BPM signal a desire to put £7m into buybacks at potentially a substantial discount to fair value.
I could be wrong but personally I believe that the discount to NAV should close here, so I have to give this stock the thumbs up.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Creo Medical (LON:CREO) Paul , thanks for positive comments, i bought this stock some time ago ,being convinced by the creator, certainly seemed a life changer; however i sold in Sept 2020 but will now buy back in with this better news, but yes still very speculative.
Shame about our friend Somero Enterprises (LON:SOM) which i sold in April 2022 ,again i shall get back in but wait for better news; all that Biden dosh must have a considerable affect on the USA economy.
Thanks for ALL your detailed forensic analysis
Shouldn't MP Evans M P Evans (LON:MPE) still be on the backlog list or did I miss it?
Hi Bronstein,
I tend not to cover M P Evans (LON:MPE) (palm oil in Indonesia), due to agricultural groups, especially overseas, being really difficult to understand & analyse, and I don't think I could add anything to the pool of knowledge on this share.
I see it has a long history of paying decent divis though, so that mitigates the overseas risk (history shows that many overseas stocks that list on AIM have got something wrong with them, often very badly wrong! But this share looks OK).
Graham did have a look at MPE here in Dec 2022, hope that helps.
Regards, Paul.
Interesting that ME International (LON:MEGP) dropped 6% today on below average volumes (353k today vs avge 383k).
Whilst it was announced today that it had joined the FTSE250 I am sure that was probably known well in advance so did that cause Fridays spike in volume & price (over 4m shares traded on Friday).
The fundamentals haven't changed, but in the current markets I really don't want to see another company I hold hand back its gains. Its happened too often this year.
Apologies everyone... too many charts made stocko overheat, forcing it into emergency recovery mode. Plug it back in if you wouldn't mind Paul:)
Hi all, does anyone know why tinyBuild (LON:TBLD) (I hold) share price is taking a huge fall at the moment. Down 25% over the last two trading days, on no news as far as I can tell. I know their COO & co founder Luke Burtis announced he was leaving on the 7th June, though this seems a bit delayed for that. Could it be him selling a large portion of his shares? It seems strange to do that at the all time low share price, unless he needs the funds for his next venture. But they did state he was leaving to spend time with his family. “announced his resignation with immediate effect to spend more time with his family.”
I just wanted to check I'm not missing anything obvious. As I see it the stock is now ridiculous value on a PE of around 5/6. Even if profits were to halve it would still be great value for a growing game development / publisher company. Hello Neighbor 2 didn't review well, and I assume didn't sell well either. Though in their annual report they state:
“A material portion of the Company’s revenues have historically been derived from products based on a relatively small number of popular games. These products are also responsible for a disproportionately high percentage of its profits. For example, in 2022, revenues associated with the top five games collectively accounted for approximately 45 per cent of the Company’s total revenues.”
So Hello Neighbor 2 being one of these five games can't be more than 15-20% at a guess. They have a large back catalogue of games, providing a strong base revenue, so they aren't reliant on one game as much as a developer like Frontier is.
I'm trying to find a reason not to load the boat, but at the moment I can't find one. Any opinions or insight would be greatly appreciated. I may well have missed something glaringly obvious.
tinyBuild (LON:TBLD)
There were chunky sales of 250k shares going through today and this is a pretty ill-liquid share.
There is a general wariness around the impact of AI in the games development area.
Personally I'd like to see what's said at the AGM/Interim accounts. They said cash would dip in H1 and then increase in H2 - I'd like to see that is still the expectation. The increase in headcount was eye-watering in 2022, with the corresponding increase in capitalised costs.
Just my thoughts.
(Don't hold but watching)
Thanks for your thoughts.
Interesting point around AI, personally I would only see that as a tool to improve productivity. Games are a creative from of media, so I can't see how AI would hurt that. Though a great point and it only really matters what the market thinks, I'll do some more research on that. Also the other UK game companies haven't suffered the same recent fall (TM17, FDEV, DEVO), though still not doing great, so there's clearly negativity in the sector at the moment.
Yes they have been spending quickly haven't they. Probably a good approach to wait until interim results to see if they have things under control. They are good at generating cash, but also vey good at spending it!
https://youtu.be/AuN5dhKaXrs
Good little insight here.
Thanks for this, very useful.
Your opening paragraph is hilarious and made me smile, which I needed after a pretty awful (non-investing) start to the day.
Thank you.
Regards
Michael
You have stock ranks here,but mine are coming up as unavailable right now ?
CREO: This firm has an identical business model to Gyrus Medical in which I made a great return when they sold-out to Olympus's medical division. And the Chief Tech Officer and Founder, Chris Hancock was involved in Gyrus - so this is in fact second time around - which gives confidence that they will be able to repeat the success.
Interesting Unscheduled Trading Update from Next https://uk.advfn.com/stock-mar... Reflects points that Paul has made about wage rises in April and therefore more spending power for consumers
Trading in the last seven weeks has been materially better than the guidance we issued in May and we are updating the market accordingly. -- Full price sales(1) in the first seven weeks of the second quarter were up +9.3% versus last year. This compares to our guidance of -5%. In the period, we have beaten our full price sales estimates by GBP93m. -- We are upgrading our full price sales guidance for the full year by GBP137m and our full year profit guidance by GBP40m to GBP835m.Thanks Feffer, for flagging the unscheduled, stonking update from Next (LON:NXT) !
I'll cover that in tomorrow's report, and the announcement from Boohoo (LON:BOO) that it is seeking to kick out the Board of Revolution Beauty (LON:REVB) and take over itself.
Exciting developments!!!
What a suprising update!
My reading is that the gloomy economic commentary in the UK is overstated. Meanwhile core inflation is stickily high. Therefore it is more likely that the Bank of England will continue increasing base rates for longer than people are expecting.
I wonder if other parts of the retailing and hospitality economy are starting to feel the effects of higher mortgage payments? There's such a long time-lag effect. The Bank of England has really mismanaged its role, risking a nasty recession of its own making: but not quite yet.
good thru-flu reading for ASOS and Boohoo
Sosandar (LON:SOS) up 6% on the news too. I am wondering which other retailers/hospitality/travel Co's are experiencing the same.
Surely the 10% increase in the State Pension must be going somewhere too, especially as most pensioners will be mortgage free.
Careful on this. Barclaycard Apr & May stats have shown that department store spending is doing decently OK, which I suspect includes Next (LON:NXT) ? But clothing retail category is having a horrid time.
I'd wager that Next is doing well, because it is a high quality company. But I wouldn't be too quick to extrapolate to clothing-only retailers, unless they were high quality too.
65 year old. Still working. Never claimed benefits. Still not financially safe/secure and supporting adult 'kids' and grandkids - so its not all fun cruises and open top sportscars. Just saying.
Thanks HH,
That's a great point actually - inter-generational family support for households that are struggling is a big thing, for sure. This could be softening the blow of cost of living crisis?
I'll include that point in my next podcast, thanks for flagging it!
Regards, Paul.
The blow was softened by the Govt. Paying households £400, for their energy last winter, doubt this will be repeated next winter. Also mortgagees will be soaring. The Govt./BOE seem intent on pushing us into a recession to tackle inflation. The only good thing maybe interest rates will be higher than inflation. I will be doing some fixed rate savings accounts soon, you can get over 5% easily now, maybe over 6% very soon. Considering rates were only around 1.2-1.5%, 2-3 years ago, that is a considerable difference.
Rents are also soaring, some younger people are moving back to the their parents, according to the news.
Higher interest rates won't tackle a lot of the inflationary factors, such as high energy costs, Brexit and a shortage of workers.
Have you looked at monthly savings accounts? I know you can’t put a good lump sum into them but you can open up half a dozen accounts via different banks with interest up to 7%. As they say, every little helps.
Not really, seems too much hassle, amounts are small and many lower than 3 year fixed rate bonds.
Re Concurrent Technologies (LON:CNC) it used to be, and I think still is, a Lord Lee holding, and he is usually good at steering away from companies with sniffy accounting. Clearly not in this case.
Awesome podcast as always. You were asking about AI - I can give some background on why it seems to be the only thing that people are talking about.
What's been happening very recently (over the past few years) is that state-of-the-art techniques have started to become accessible to people outside of the research community. They've reached the point where they work well enough that you don't need to be an expert to use them.
There are also now a lot of off-the-shelf models that are already trained and are general-purpose enough that they can be applied to many different problems.
This has been kind of happening under the radar and hasn't had much attention.
The release of ChatGPT made all this very visible - though I do think we might be reaching peak hype (and maybe already falling into the trough of disillusionment...).
For a bit of history, the current state of the world has been building up for some time.
Deep learning kicked off quite a few years back and was the realisation that there was now a lot of data available along with a lot of computing power.
This meant that you could build and train very large neural networks - the "deep" in deep learning comes from the fact that there are many many layers in the neural network.
There were two problems with doing these deep networks before:
Firstly, there just wasn't enough training data available. This lack of data makes it very hard for a very large network to generalise - so it simply memorises the training data and can't handle anything new.
Secondly, it takes a very long time to train - there are a lot of calculations required so you need a lot of computing power.
The internet solved the problem of there not being enough data. There were suddenly a lot of pictures being made publicly available and it was fairly easy to gather enough people to manually catalogue them.
Gaming GPUs and cloud infrastructure solved the computation problem. By a happy accident, it turned out that the calculations needed to make amazing 3D games are very similar to the calculations needed to train a neural network.
A lot of the focus on deep learning has been around computer vision and object detection.
Over the past few years, we've started to see generative models getting better. These are deep models that can generate or transform content.
The image generation models were the first ones to start getting good enough for people to get excited. The initial versions were pretty poor and only really of interest to researchers trying to improve them, but the more recent ones have reached the point where they are usable and can produce amazing results (take a look at the output the Midjourney can generate).
Text generation seemed to be lagging behind a bit. The models felt like fairly crappy toys. You could create fun things but they would quickly start generating drivel.
These text generation and transformation models are called Large Language Models - The "Large" in the name comes from the fact that they are very big and are trained on a lot of data.
What's interesting about these LLMs is that the training is very simple. They are presented with some text and one of the words is masked out, the model is trained to predict what the missing word is e.g. "The? sat on the mat" - the missing word is probably "cat".
What's been surprising is that this simple training seems to lead to the model gaining an understanding of language. It also leads to some emergent behaviour and the trained models seem to be capable of doing much more than simply predicting missing words.
OpenAI releasing ChatGPT opened up a can of worms - it was very very good compared to what had been seen before.
They had trained a very big Large Language Model, which was capable of solving a lot of problems that previously would have needed a very specific model. It was able to generalise and solve lots of problems.
They then took this model and fine-tuned it to produce responses that people preferred. This is called Reinforcement Learning from Human Feedback (RHLF) - basically, someone asks the LLM to do something and then they tell it how good the response was.
The clever bit here is that you train another model to do the scoring based on how people would score the response and then you fine-tune the original LLM using this model.
They released this fine-tuned model as ChatGPT and everyone went slightly nuts.
A lot of AI researchers were caught slightly on the hop, OpenAI were busy training their next model and predicting that it would be even better and more capable (GPT4 - which is very good).
Suddenly it seemed like AGI (Artificial General Intelligence) might be a lot closer than people had been thinking. The worry is that you can just keep making the model bigger and it will keep getting more and more clever - it's not clear how true this is, but it's got everyone sweating.
The current AI excitement is pretty much all focused on these LLMs and leveraging what they can do.
I talk to quite a few small startups and they are all getting pressure from investors to explain their "AI Strategy" or how they are going to "Embed AI in their business".
One of the problems with this is that it's already kind of happening.
In software engineering there are tools like "GitHub's Copilot" - this is like having someone sit next to you as you work, helping you do your job and making useful suggestions. For some people, this is massively increasing their productivity.
Microsoft (and Google) have been adding AI to their products without people noticing.
Most of the CRM systems have also been adding functionality so sales and marketing are also getting a boost.
Things that LLMs (particularly the ones that OpenAI has) are good at (this is barely scratching the surface):
- Extracting structured data from unstructured data
- Augmenting data
- Turning very vague requests into concrete actions
- Extrapolating new information from existing data
Any business that deals with data (which is pretty much everyone) should be able to find some problem or process that could be improved.
Thanks - very informative
Thanks for the write up of B.P. Marsh & Partners (LON:BPM) Graham. Hasn’t the SP discount to NAV always been a factor though to varying degrees, albeit it has been particularly large of late?
Hi James - yes I think you may be right! There was a decent-sized discount when I was a shareholder a few years ago. A shame for me that they didn't try to close it back then!
Litigation Capital Management claimant wins award in favour
https://uk.advfn.com/stock-mar...
How much do LIT get net?
I can only really speak from what I've learnt about Burford Capital (LON:BUR) (I hold). As far as I can tell the contracts with the claimants are often bespoke but 40% is a good starting point. The litigation funder typically effectively removes most of the risk from the claimant, so they expect to be able to be choosy about the cases they take on and the size of the cut they get.
Some great bs from Coca-cola HBC today...
"The proven complementarity of our premium spirits business with our
strong NARTD (Non-Alcoholic Ready-To-Drink) portfolio enables us to
offer solutions for a broad range of 24/7 consumption occasions,
particularly socialising moments."
Definitely written by AI.
Morning all
Litigation Capital Management (LON:LIT) announcing successful arbitration award this morning. Gross profit of c.£31m, or more than a third of the market cap. And over 600% return on capital. The market is still dramatically undervaluing this company and the prospective returns that will come from Investments on its own balance sheet and the override it receives from its third party funds management business.
There is no listed company that achieves a 600% return on capital.
LCM itself saw a 1291% ROIC for this particular investment, once adding in the performance fees from the fund. Of course this doesn't mean the company itself will achieve these sort of returns as not all their investments will be that successful, and you have to deduct operating/financing costs from case wins, but nevertheless a pretty good result!
looks a great stock , lumpy RNS's though that are spaced out so the SP goes up by 10% then rolls back when investors lose patients ... rolls up then down. Shame they don't pay a divi to keep investors sticky
Yes revenues are lumpy and you just have to accept that, but see a lot of value here based on the backlog of cases. You're right the share price tends to react to good news and then slip back as investors get bored - it had recently fallen around 15% for no real reason so slightly annoyed I didn't top up before today's announcement.
As for dividend, they are very much in growth mode, with any cash put into new cases. I guess they will eventually start paying dividends but probably not for at least a few years.
I hold LIT - it's their past track record that is extremely impressive, from the last results:
‘During the 10 and a half year period we have evolved from being a private company to a public company and have utilised our own balance sheet capital as well as managing third party capital. Encouragingly at the ten-and-a-half-year mark we have seen an increase in our investment performance metrics achieving a cumulative Return on Invested Capital (ROIC) of 162%, [including losses] and a cumulative IRR of 79% (HY 2021: 78%).’
If they can maintain their performance anywhere near 70+% (before costs) then the current p/e of 4.3 and PEG 0.1 is an absolute steal.
Clearly unloved by Mr Market I like the fact that they are revealing these case wins - to garner some attention.
Litigation Capital Management (LON:LIT) (I hold)
"I like the fact that they are revealing these case win"
I really like this too.
I've prudently I hoped assumed $30m AUD, which would include all costs before tax and an exceptional bonus of $5m AUD .
----
At December 31st, 2022, $120m AUD had been invested directly by Litigation Capital Management (LON:LIT)
This figure included the direct investment in today's case - a mere $2.3m AUD - which resulted in a direct gross profit of $14.6m AUD.
The $15.1 AUD performance fee from the fund was a nice bonus too and helped to lower my own doubts of the fund management side of the business.
There have been a lot of good results in the last 6 months, but that seems to top them all.
---
I remain a happy holder and hope that the company are able to rapidly reinvest today's proceeds into more cases.
A
Avacta (LON:AVCT) make me laugh. No fundraising imminent statement today wheels out the £27m cash balance as justification. Well how much cash are you burning? According to Stocko forecasts this lot lose c£40m a year. Revenue might double this year to £20m, there again it might not, which should have a decent drop through to the bottom line if achieved. Still leaves a funding shortfall in about 9 months by my calculation.
Perhaps the CEO would like to explain a little further as he is rather fond of posting RNS announcements. This looks like one for institutions with deep pockets to me. And they have started making acquisitions. Hmm what could possibly go wrong? Agree with Mr C.
I couldn't agree more sevencc. This is the type of company that in the current climate is a big avoid. It's still very tough to raise cash and investors know it will have to come to the market for this soon. The line "anticipates strong news flow in the coming months" is there to keep the private investors (punters) interested.
Ive never looked at Avacta before but saying a fundraise isnt "imminent" hardly reassures. Quite possible its not imminent because they cant get one away.
Quick look at consensus forecasts show net cash turning to net debt of 5m > 25.2m > 32.5m for 2023 >2024 > 2025
Pre tax loss -44m > -45m > -48m
EPS loss -14 > -14 > -15
(Negative) Free cash flow -20.8m > -22.9m -24.3m
These number may be out (sharepad) but to put it politely there doesnt seem great risk/reward here.
Directors not exactly piling in are they
Just taking a weekly look at AIM, FTSE 250 and S&P charts so thought Id post them.
If people prefer I dont, as they do take up quite a bit of room just let me know. I wont be offended.
S&P has diverged from UK markets over the last month. US markets given a boost from A.I and pause in interest rates. UK in a different place re rates.
AIM looking particularly weak. Under all moving averages, almost back to testing October lows. Moving averages turning lower again.
FTSE 250 a little better, tho wont take much for this to roll over
Compare to S&P which is what the start of a bull market looks like. Price above all moving averages, theyve also all flipped round so 50day is now on top instead of the bottom as it was on the way down in 2022. Youd expect people to buy the dip on any move back towards 50 day ma.
It has tho got very overbought short term at least. I use a simple combination of fear and greed index and MACD to decide when to get aggressive buying compared to pulling back/ holding more cash
Ive found Fear and greed useful, as it gives a rough guide to sentiment, which often, tho not always, lines up with short term bottoms/tops. Its at extreme greed just now.
Ive circled the same 5 days on the S&P chart.
I went all in in October and again end December. Right now im 25% cash as I can see any potential short term weakness in US markets transferring here too unless inflation shows a decent drop this week. Obviously individual company news will trump any general market movement, and theres no guarantee the S&P wont just continue rising.
Its been made slighty more complicated by the US/UK markets diverging lately. Theres also some extremely good looking value fundamentally in the UK right now.
Following graph is derived from all US stocks with Momentum rank greater than 70 since beginning of 2022, It shows the ratio of Cyclical (Sectors Financial, Basic Materials & Consumer Cyclicals) and Defensive (Healthcare, Utilities & Con Defensives) . No sign of move into Cyclical stocks yet....
UK looking a little more optimistic.....
Good morning Wolf of Small Street, your hard work shows the current diverging of the US/UK markets, thanks for putting it out. I would mention that right-clicking on a graph opens it up in a new tab fully sized for the benefit of those who are unaware.
Nice work....I would say the bullish S&P 500 looks less bullish the longer you extend ....so a 3 year or 5 year chart is less convincing ....and the converse is true for the UK charts of 250 index and FTSE 100. As always that's what makes a market.
One other point on the S&P. For all the talk of a painful bear market in 2022 from US investors, I dont think it was a bear market at all.
Looked to me a v large correction after a huge rally caused by unprecedented stimulus. Apart from a brief drop below the 200 week ma for one day (when it actually finished well up on the day) it wasnt a 'normal' bear market selloff. Dotcom bust and financial crisis were what Id call a bear market. Both dipped well below the 200 week ma for a sustained period. This is the long term chart from 1982 - today. Amazing how 1987 looks like a tiny blip in the grand scheme of things
From the covid Low - High the market corrected 50% and found support at the 200wma. Briefly dipping below on the inflation panic shakeout in October. The chart is from 2008 low - today.
AIM in contrast is more hand to hand combat. Cant rely on the index growing over time, as its gone nowhere since 1996. Im generalising, but to make money you really have to take it off someone else.
Thank you for taking the time to share this, it is appreciated by me at least!
I am very much in learn mode and can do even better, or less worse as this last 18 months feels like :)
Cheers Tommy
Seems the Beeks Financial Cloud (LON:BKS) JSE contract is IaaS (Infrastructure as a Service so an ETLA variant of SaaS). A business model that seems to turn out well eventually for revenue and profit, but not great for cashflow.
Castings (LON:CGS) released an excellent set of FY results last Thursday and both Roland and Paul have commented positively on them in the SCVR and on the podcast
Listen to the story today at 12.30pm when Adam Vicary, CEO, and Steve Mant, CFO present these results at a webinar for private investors. Register here
Hi Yellowstone,
Your link took me to a page for a Halma webinar, not for Castings (LON:CGS)
Paul.
I see that one of my favorite stocks ME International (LON:MEGP) has this morning entered the FTSE250, so should get more institutional and tracker interest. Excellent momentum and a PE of <13. Nice
Never mind fiction Paul, you really must write your autobiography (then narrate the audiobook version)! The relationship with your dad, the schoolboy book business, getting started in the markets, The Motley Fool, success in the markets, the big crash and rebuilding yourself, a Robbie Burns-esque 'day in the life' as a SCVR commentator. It would be brilliant! I can see Russel T Davies converting it into a Channel 4 drama. Who would you get to play you though?
Thanks for the weekend podcasts, I look forward to them. Excellent listening.
Love both the podcasts. Always interesting and entertaining too!
Yes very much so
Morning all and well done Paul on a most enjoyable podcast canter through the macro landscape.
As its scary interest rate headline week....I just had a quick look at current 2 year discounts and fixes in the mortgage market. Hmmm not the scary 6% I was expecting. I already knew 2 year discounts were much cheaper.....but you can fix at 5.9% over 25 years....who would want to do that Daily Mail readers shout?....well this is actually 10 years at 4.75% followed by 15 years at 7%....Ok that seems a lot better ....you need to add fees etc....but most people move house within 10years.....so actually even fixes are not as scary as standard variable and headlines suggest. My personal experience of std variable is people with low mortgages allow their borrowing to roll onto this rate....often aren't working...and would therefore struggle to borrow otherwise....but dont necessarily need the money. Anyway its not quite as negative as no doubt all the headlines will suggest this week....
wishing you all a great week....
I (happily) am one of those with a relatively small (base rate + .1% tracker min 2%) mortgage and it has increased by £5 pm so far.
On the unpleasant effects for many others I recommend the weekend podcast from the "news agents" basically they point out that behind all the noise of the johnson report ( no comment other than the Jeremy vine joke
"Mr Johnson, what is your favourite lie"
"I don't lie"
"Yes, that my favourite one too")
A lot of things seem to be getting worse, or at least not better as fast as hoped.
Like mortgage rates/inflation/house building/nhs waiting lists etc etc
And some things seem to be getting worse slowly like the leak of a lot of import/export businesses to the EU - 10 years ago it was a UK operation and two people opening post in Paris, now the new jobs are in Paris - that includes good jobs that paid lots of tax.
Surely this situation could be reversed without reversing Brexit? (but then I am a simple person saying this).
Just my opinion and putting flameproof clothing on:
The sort of broken thinking that people used to tell others that brexit would be great is a mirror of the thinking that people are now starting to use to tell others that all will be well if we rejoin.
Two thoughts:
The UK's biggest issues (housing much too expensive, public transport outside london non-existant, adult education, 13 years of underpaying for public services - effectively we did not shrink public services, we just grew the overdraft, the potholes do not appear in the national debt, but the bill for filling them does, everything centralised in London, growing regional inequalities, ... add your own favourites) had little-nothing to do with the EU. This is a problem for our politicians to solve. They did not when we were in and are not now we are out.
The brexiters pattern of treating the EU like a spanish waiter in Fawlty towers - that if you speak slowly and loudly enough over and over you will get what you want (like we very much did not get in northern ireland) is mirrored by those who think we could just rejoin. They wouldn't have us back, we are too much trouble and if we really did ask nicely we would not get the same deal we had before - the cost would be tremendous and not just in money.
Struggling to bring this comment/ sub-thread back towards relevancy, I am reminded of the Hemingway quote : “How did you go bankrupt?" "Two ways. Gradually, then suddenly.”
I do not see economic conditions getting better in the short or medium term.
I do see things slowly getting worse, gradually at the moment.
The papers really do exaggerate things. However, to beat inflation the BoE has to reduce spending power significantly. Interest rates are a very blunt tool because it just transfers money from borrowers to lenders. It 'works' because borrowers have to spend less and lenders tend to save the extra rather than spend it.
One question this begs is do governments spend less when interest rates go up? as the major borrowers of our time ...this could be important.
Governments follow an electoral cycle. Rises in interest rates increase the deficit which is met by more borrowing. Essentially the fall in spending will almost all have to come from the general public.
And therefore from tax not interest rates....
My morning smallcap tweet: The spitting image
Abingdon Health (LON:ABDX) Ocean Harvest Technology (LON:OHT) Bivictrix Therapeutics (LON:BVX) 1Spatial (LON:SPA) Avacta (LON:AVCT), Synectics (LON:SNX), Public Policy Holding (LON:PPHC), Feedback (LON:FDBK), Musicmagpie (LON:MMAG)
◄Abingdon Health (ABDX)► launches of Salistick lateral flow saliva pregnancy test with Superdrug. [SP=14.5 Cap=18m]
◄Ocean Harvest Technology (OHT)► good results from feed trials of animal feed supplements from seaweed. [SP=14.26 Cap=18m]
◄BiVictriX Therapeutics (BVX)► positive interim data in second preclinical efficacy study of cancer therapy. [SP=13.95 Cap=9m]
◄1Spatial (SPA)► wins first two contracts (of 3 months) for its newly launched Traffic Management Plan Automation solution. [SP=48.73 Cap=54m]
◄Avacta (AVCT)► re speculation regarding a possible fundraising - no fundraising is imminent. Cash at hand £27m. [SP=99 Cap=273m]. I'm short.
In line: SNX, PPHC, FDBK, MMAG