Small Cap Value Report (Mon 2 Sept 2024) - IGP, RMV, VTU, XPF, AT.

Good morning from Paul & Graham!
That's all we have time for today, see you tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
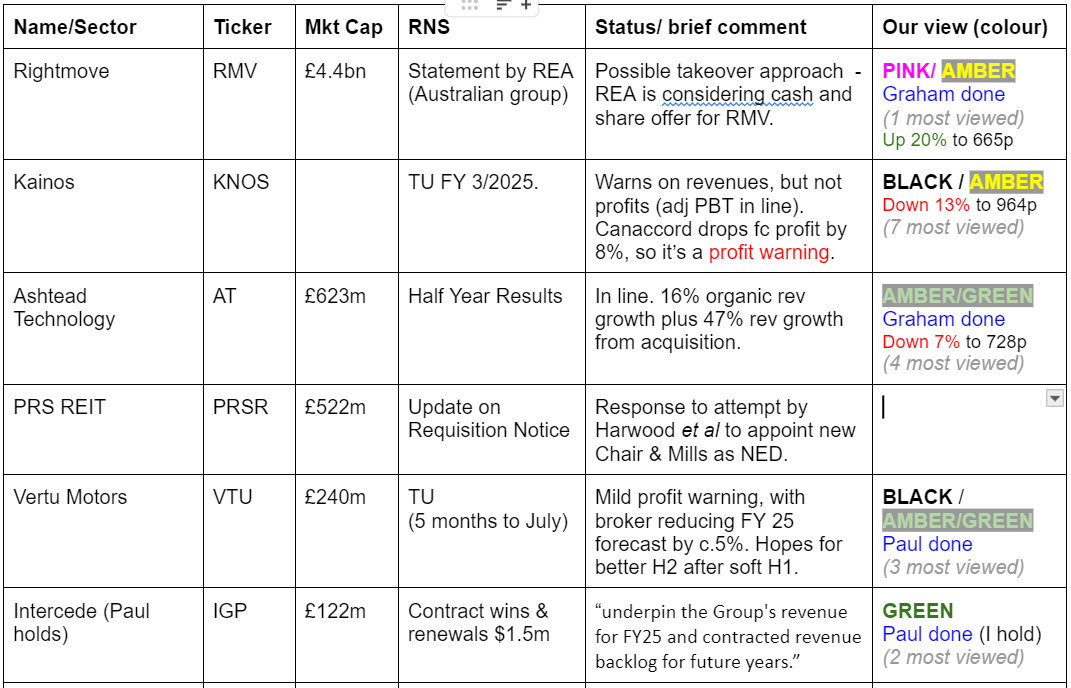
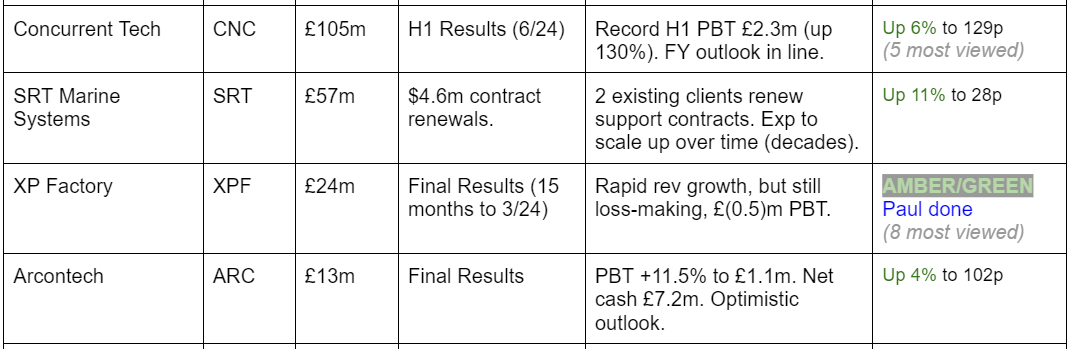
Summaries
Intercede (LON:IGP) (Paul holds) - 208p pre-market (£122m) - Contract Orders & Subscription Renewals - Paul - GREEN
Several contract wins totalling $1.5m. "Underpins" existing forecasts, which are unchanged, per Cavendish. I explain more why I see IGP as an exciting opportunity, even though shares have already soared. It's certainly not cheap on a forward PER of 51x!
Rightmove (LON:RMV) - up 21% to 672p (£5.3bn) - Statement - Graham holds - AMBER
A Murdoch-controlled Australian real estate group is considering a cash and shares offer for the UK’s #1 property portal. It’s a dramatic response to the US acquisition of OTMP, demonstrating that Rightmove itself may receive foreign assistance to keep its commanding market position. I’m moving to AMBER but personally I’d require over 800p before I willingly handed over my RMV shares.
Vertu Motors (LON:VTU) - down 3% to 69.3p (£232m) - Trading Update [mild profit warning] - Paul - BLACK (PW), AMBER/GREEN on fundamentals.
A mild profit warning today, dressed up as "broadly in line", but FY 2/2025 forecast profit & EPS are reduced nearly 5%. Mixed comments on its various activities, with a lot of useful detail. Shares are cheap, and strongly asset-backed too, so I remain moderately positive, despite a less than stellar H1 being indicated.
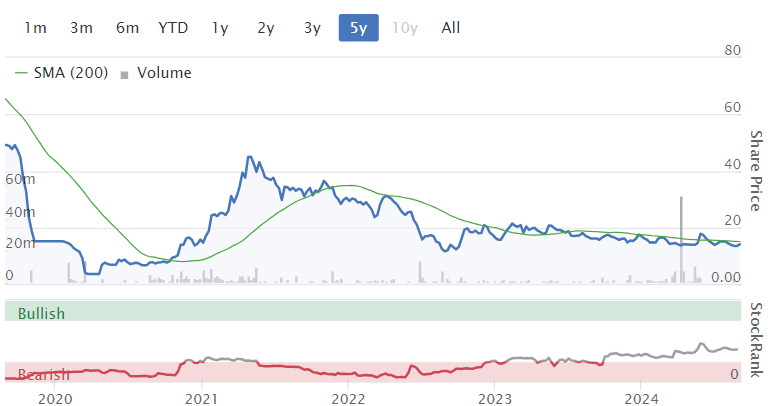
XP Factory (LON:XPF) - up 3% to 14.2p (£25m) - Audited Results (15 months to 31 March 2024) - Paul - AMBER/GREEN
15-month results show a breakeven PBT result in the last 3 months (after 12 month figures were released in March). The big news is a new £10m RCF agreed with Barclays, with removes worries over financing & dilution. Overall I take a moderately positive view of the opportunity here, with highly leveraged upside to any consumer recovery possible, due to exceptionally high gross margins from games revenues.
Ashtead Technology Holdings (LON:AT.) - down 13% to 678p (£545m) - Unaudited Half Year Results - Graham - AMBER/GREEN
AT says that its expectations for the year are unchanged, which makes today’s 13% share price fall perplexing. I speculate as to what may have caused the sellers to dump the stock this morning, but also explain why I have a generally positive impression of this stock. Paul was AMBER/GREEN on this one in April and I’m happy to do the same.
Paul’s Section:
XP Factory (LON:XPF)
Up 3% to 14.2p (£25m) - Audited Results (15 months to 31 March 2024) - Paul - AMBER/GREEN
This is a growing experiential leisure group, with two brands - Escape Hunt (escape rooms), and Boom Battle Bars competitive socialising bars (BBB).
I like the format a lot, so we’ve discussed it here in the past probably more than was justified. I think management has done well to expand considerably, with lots of new sites (owned and franchised), but it’s fallen short of achieving the profitability that was originally forecast. Maybe we can forgive that, because of covid, and the large cost increases (particularly wages and energy) in the last couple of years. It’s an incredibly tough sector, where none of the smaller listed bar operators make any money, and of course Revolution Bars (LON:RBG) has been a disaster, as indeed was Nightcap (which has delisted).
XPF issued its FY 12/2023 results back on 19/3/2024, which we didn’t cover because there were over 20 other companies reporting that day, and its figures were unremarkable, producing a modest loss before tax of £(535)k.
A year end change means that today it puts out 15-month results for the new year end of 31 March.
Nothing much has changed, in terms of profitability, producing a 15-month PBT almost identical at £(539)k, so it’s traded at breakeven in the last 3 months.
Revenue (15 months) was £57.3m. It was £44.8m for the more meaningful y/e Dec 2023 (up £22.8m in FY 12/2022), so you can see the rapid growth from a splurge of new sites opened in late 2022. The new openings have been slower this year, due to financial constraints only allowing it to self-fund about 6 new sites per year.
Strong like for like (LfL) revenues, up 22.4% at BBB in the 65 weeks to 31/3/2024, and up 16.9% for Escape Hunt, as new sites matured.
Recent LfL revenue growth is only modest at +1.9% for Boom (20 weeks to 18/8/2024) and +1.5% same period for Escape Hunt.
Outlook - not madly exciting -
“Whilst the summer uplift in sales in July and August has been modest, forward bookings for the end of year are well ahead in comparison to previous years providing confidence for the coming months and leaving the Board's expectations for the full year unchanged.”
[Paul: Singers has FY 3/2025: £6.4m adj EBITDA pre IFRS 16 = £0.7m adj PBT, 0.3p adj EPS]
New bank facility - the big news I think is credit approval being recently gained for a £10m RCF from Barclays, to fund new site openings. I had a quick call with CEO Richard Harpham (RH) earlier today, and I homed in on this point as being important. He agreed, and said it’s a “vanilla” borrowing facility, and will help them accelerate new site openings from c.6, to c.10 pa, and provides flexibility, eg if a really good site is offered to them, they can grab it, instead of turning it down due to financial constraints previously. This is really good news I think, if you can tolerate the company taking on more debt, which personally I can. This should remove the risk of a dilutive equity fundraise, all being well.
EBITDA numbers I tend to ignore mostly, but as there’s a big depreciation charge on existing sites (a sunk cost) then there’s no denying it does generate positive cashflow on a standstill basis. New site openings are discretionary of course.
New sites - I asked if good deals are still available, eg with capital contributions from landlords, and long rent-free periods, which RH confirmed is indeed still the case. I imagine landlords would much prefer an established, and stock market listed tenant like XPF, and offer it better terms, than any numbers of small private competitors.
Competition - there are plenty of other experiential leisure operators expanding, but RH said he quite likes locating new BBB sites where there is competition, as it’s where the customers are already going, and there’s room for several operators. He reckons it’s the traditional bar operators that are losing the market share, and struggle to adapt, whereas XPF is a specialist and know what works.
Franchises - I recall there being some concern at the inadequate quality of some franchisees, and XPF has bought back some sites, including my local one, Bournemouth, so that gives me an excuse to mystery shop it again in the autumn, when the turnaround has had time to be implemented.
Customer satisfaction scores remain excellent - see eg TripAdvisor.
Cost inflation - XPF took the pain, and has not raised prices, in order to attract more volume growth, and be more competitive. Energy costs have dropped back now.
Broker update - thanks to Singers for a note today, as always incredibly helpful. It echoes the company’s comments that results are ahead of expectations on EBITDA. I can’t get excited about that, as it’s really just trading at or around breakeven when all costs including depreciation are taken into account.
Singers has quite modest forecasts, of adj PBT at £0.7m FY 3/2025, £1.1m FY 3/2026, and £1.4m FY 3/2027. I don’t think that’s going to excite any value investors here, rightly so. Hopefully though, with a consumer recovery and real incomes now rising, there might be scope for out-performance in future? The interesting bit is that more than half XPF’s revenue is almost 100% gross margin from games. Its overall gross margin (incl drinks & food) is a strong 64.6%, but note 6 shows that this includes over half its staff costs, so if we strip that out, the gross margin including only the cost of food & drinks, is much higher at c.84% (my calculations). So in other words, if customers spend more, then the drop through to profit could be spectacular from the super high margin gaming revenues. Hence why I think this share is more interesting than traditional bar operators, with greater potential upside in a consumer recovery maybe?
That translates into EPS of 0.3p, 0.5p, and 0.6p, which means PERs of 45x, 30x, and 25x (3/25, 3/26, and 3/27 respectively). So definitely not cheap on the existing forecasts.
I can quite understand why some readers just won’t be interested in a company that is only forecast to eke out a tiny profit margin despite continued expansion.
However, lots of market participants, banks, and takeovers, value shares using EBITDA multiples. So maybe we’re missing a trick with our old school PER figures here?!
Going concern statement is clean.
Balance sheet - is thin, with only £1.4m NTAV (after eliminating intangible assets), so there’s essentially no asset backing here.
Share price upside will all have to come from earnings and cashflows, not from assets.
However, with the new £10m Barclays facility lined up, then I see a lot more financial flexibility, and hence little risk of a dilutive equity fundraise, which worried a lot of investors I recall when we have previously looked at XPF. Although RF didn’t give me an emphatic no when I asked about potential future equity raises, it was something like "hopefully not".
Paul’s opinion - I think this is looking more interesting now that Barclays has provided a decent facility for expansion.
I see this share as a development project. Management has built a significant sized new leisure operator from scratch, in incredibly difficult macro circumstances in recent years, with pandemic, energy crisis, inflation, and the consumer squeeze. That's to be applauded, and shows they should be safe hands for further expansion. For them to be operating around breakeven now is no mean feat. They’ve done well just to survive, let alone rapidly expand. The bull case is that freer spending consumers could start giving XPF a highly leveraged boost to its bottom line, due to its exceptionally high gross margins.
So I can see a pretty good bull case for this share, if you’re prepared to punt on that upside scenario.
Equally, I can also understand why some more traditional value-style investors would see little to get excited about, given the current breakeven performance, competition, and it just being a horrible sector to make money from as younger people increasingly eschew alcohol.
Personally I think we’re at the concept proven stage, with potential upside if they can open more decent sites and squeeze more value from the largely fixed central overheads.
Note there’s a fair bit of dilution from options, etc, so do check that carefully.
Market cap of £24m looks quite reasonable to me, so I’m leaning towards a moderately positive view, let’s go with AMBER/GREEN.
Vertu Motors (LON:VTU)
Down 3% to 69.3p (£232m) - Trading Update [mild profit warning] - Paul - BLACK (PW), AMBER/GREEN on fundamentals.
Vertu Motors, a leading UK automotive retailer with a network of 192 sales and aftersales outlets, announces the following trading update with regards to the five-month period to 31 July 2024 (the 'Period') ahead of its interim results for the six-month period ended 31 August 2024.
Vertu’s headline -
“Trading Update: Strong performance in Used cars and Aftersales against soft new retail market. “
This looks to be a scheduled trading update, since a similar announcement was made at this time last year.
It’s a slight profit miss -
“ Full year FY25 adjusted1 profit before tax expected to be broadly in-line with current market consensus. H1 profits will be lower than prior year levels as anticipated. Performance in H2 is expected to improve over prior year levels due to a stronger used car market and enhanced used vehicle trade values.”
1 Adjusted for share based payments charges and amortisation.
My first port of call in these situations is to look up broker forecasts on Research Tree, to see how much brokers have reduced forecasts by.
Progressive has issued a (commissioned by the company) update, which reduces FY 3/2025 forecast adj PBT by 4.7% to £40.2m, and lowers adj dil EPS by 4.6% to 8.2p. So actually, this is a mild profit warning, so I’ll flag it as BLACK (that’s purely to flag profit warnings, it’s not necessarily a negative view on the company).
Vertu always puts plenty of useful detail in its updates, so I’ll summarise the ones that look more important -
Aftersales (warranty, repairs, servicing, etc) doing well.
Used vehicle sales showing %% volume growth, and higher gross margin of 7.2%.
Used vehicle supply “increasingly constrained”, which is good for margins.
New vehicle sales down 5.8% (industry average -12.1%) - some discounting & lower margins.
Soft retail demand means new car sales are prioritised for lower margin fleet & motability sales.
Small acquisitions, and more planned.
Gearing “below target levels”.
Higher costs of running demonstrator fleets, as more are high cost EVs, and bigger ranges.
Lower energy costs, and marketing spend reduced.
Higher finance costs now it has net debt (following multiple acquisitions) & higher interest rates (something I’ve flagged before, as now consuming a lot of operating profit).
Govt driven regulation towards battery electric cars is causing “market volatility and negative impacts” - is the time coming for us to grab a bargain EV I wonder? (some secondhand EVs are looking attractive value now, I see from a look through the ads) -
“New vehicle supply in the UK remains strong, particularly for BEVs, as Manufacturers aim to meet Government targets. This supply, coupled with weakening retail demand, has led to significant discounting and attractive financing offers, especially for electric models. Margins have been put under pressure and there has been a growth in the pipeline inventory of new vehicles held by Manufacturers and retailers.”
Inflationary cost pressures, especially wages :
“A significant factor contributing to the rise in salary costs was the increase in the national minimum wage on 1 April 2024. Approximately 25% of Group colleagues are now paid at or within 5% of the minimum wage. To retain skilled colleagues, such as parts advisors and vehicle administrators, the Group has recently further increased pay for such roles to increase the differential to the national minimum wage. Additionally, the Group is progressing with the automation of administrative and finance process tasks, with pilots underway which should deliver cost savings when rolled out in the coming months.”
Outlook - as mentioned above, only “broadly in line” for FY 2/2025, which actually means profit almost 5% lower than previous broker forecast.
Retail demand for EVs is weak. The busy trading month of Sept will be soft -
“The Group's new vehicle order-take for the important plate change month of September is currently tracking at levels below prior year reflective of the weakening retail market in 2024. “
Expecting used car prices to “remain stable”, due to constrained supply.
Overall -
“The Group is delivering on its stated strategy and is well-positioned to take advantage of opportunities that arise whilst the market remains in an adjustment period, given the Group's track record of execution and strong financial position. The Board remains highly confident in the Group's long-term prospects.”
I read that as a bit wishy-washy, saying things are not great in the short term, but we're hoping it might improve.
Paul’s opinion - lots to take in here. It’s clearly not a good update, and forecasts for FY 2/2025 had already come down from 10.8p EPS to 8.8p, with another drop today to 8.2p. Car dealers don’t tend to attract high earnings multiples, I feel c.10x is about right here. That implies 82p/share, so actual price of c.69p at the time of writing, is below what I think this share is worth on fundamentals.
Note that VTU has a habit of doing buybacks, and the share count has usefully fallen from c.383m in 2019 pre-pandemic, to only c.335m today. Although net debt has increased a lot (forecast £122m at 2/2025), as it made acquisitions in recent years. That isn’t a particular worry, because the balance sheet remains sturdy, and packed with freehold property (valued at multiples of the net debt). However, the debt is expensive, eating up a lot of the wafer-thin margin operating profit.
We’ve also got all the uncertainty over the car industry as a whole, and considerable consumer reluctance to buy EVs (expensive, and poor ranges make them unsuitable for some higher mileage motorists).
Overall, I’ve been oscillating between green and amber/green this year. Considering today is actually a mild profit warning, and they’re relying on an H2 improvement just to hit trimmed forecasts, I can’t muster a great deal of enthusiasm. It is cheap on fundamentals though, so I’m still positive, but at AMBER/GREEN today, based on the facts, figures & forecasts as of today. We’re not time travellers from the future, so we don’t know what the future holds.
Intercede (LON:IGP) (Paul holds)
208p pre-market (£122m) - Contract Orders & Subscription Renewals - Paul - GREEN
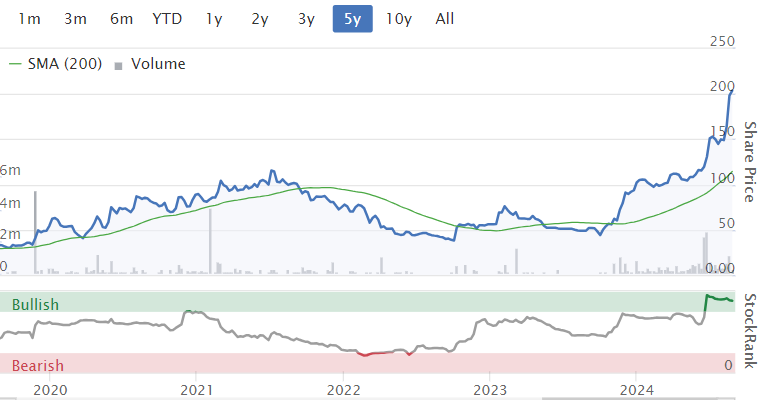
Intercede, the leading cybersecurity software company specialising in digital identities, today announces further contract orders and subscription renewals, in excess of $1.5m in value.
$1.5m doesn’t sound a lot, but in the context of £15.9m forecast revenues for FY 3/2025, it’s c.7% of the total (after converting dollars into sterling), assuming that it’s all recognised in the current year, which may not necessarily be the case, as IGP says -
“These orders and renewals, received via our partners, underpin the Group's revenue for FY25 and contracted revenue backlog for future years.”.
The 4 contracts mentioned are mainly US Federal customers - the area where IGP seems to particularly excel in, and presumably helped by tougher cyber-security laws.
Cavendish issues a brief note this morning (many thanks) confirming that this announcement doesn’t change its forecasts, but today’s news “support expectations and derisk forecasts…”.
Paul’s opinion - I remain very positive on IGP, although obviously with much higher shares now, valuation comes in for closer scrutiny. My view is that £122m market cap doesn’t seem a lot for a small UK specialist in a huge market, with a client list to die for, and winning new business now due to having built up relationships with big systems integrators in the US. That is clearly paying off, so I think the sky could be the limit with this one. I particularly like scalable businesses like this, with no constraints on production capacity, or moving physical goods at all.
With a forward PER of 51.1x (although EV/EBITDA of 18.5x is more normal in this sector for growth companies), then it needs to beat rather than just meet expectations for the full year.
Remember that FY 3/2024 saw a one-off boost from a large single contract, hence why brokers are expecting lower profit in FY 3/2025. However, the £5.6m PBT in FY 3/2024 might have been one-off, but it does show the huge operational gearing here when big contracts are won. It’s also transformed the balance sheet. A few years ago we were worrying about the convertible loan (since paid off). Now though, the last balance sheet had a comfortable c.£17m in net cash. I like the fact that profit turns into cash at IGP, due to sensible & prudent accounting policies - it doesn’t rely on a multitude of adjustments to conjure up a theoretical profit, it is producing decent, cash profits in reality.
My hunch is that IGP is on the runway to considerably greater success, because its software just works, is being continuously improved, and is trusted by the biggest and most security conscious customers you could imagine, primarily in the USA. Building relationships with systems integrators looks to have been a very smart move, as it keeps overheads low, yet after successful implementations having been done, makes it increasingly likely that IGP will be chosen as the preferred partner for the niche of managing online credentials. Legislation requiring better IT security can only help too.
One sizeable US systems integrator actually flew in a US partner in the firm, who gave a ringing endorsement of IGP at its capital markets day in the UK earlier this year. I watched it live, but there’s no recording I’m afraid. I remember thinking at the time that this was such a strong endorsement of IGP from an important third-party.
Overall then, this is an unusually good opportunity in my view, and I won’t be quibbling over valuation. It’s more a question of letting my position run, I think, and not losing sight of the big picture due to over-analysing the detail.
Graham’s Section:
Rightmove (LON:RMV)
Up 21% to 672p (£5.3bn) - Statement - Graham holds - AMBER
(At the time of writing, Graham has a long position in RMV.)
It’s an exciting morning for Rightmove shareholders, as we have bid interest from an Australian real estate group, REA. REA is “a digital advertising company that operates Australia's leading property websites and real estate websites in Europe, Asia and the US”.
Here’s the news:
Further to press speculation… REA confirms that it is considering a possible cash and share offer for the entire issued and to be issued share capital of Rightmove. REA has not approached, nor had any discussions with, Rightmove regarding any potential offer, and makes this announcement in accordance with the requirements of the Code.
As you can see, things are still at an early stage with no discussions between the two companies yet.
The FT has just published an article with some background on REA, pointing out that it previously attempted to make inroads in the UK with the acquisition of the PropertyFinder website back in 2005.
REA is 61% owned by News Corporation.
Rationale
The first reasons given for the potential bid are:
The REA Board believes that there are clear similarities between REA and Rightmove in terms of their leading market positions in the core residential business, continued expansion and innovation of offerings across adjacent segments, leading audience share and strong brand awareness, as well as highly aligned cultural values.
REA sees a transformational opportunity to apply its globally leading capabilities and expertise to enhance customer and consumer value across the combined portfolio and to create a global and diversified digital property company, with number 1 positions in Australia and the UK.
Graham’s view
As a shareholder in Rightmove for several years, it’s natural for me to think that Rightmove is undervalued.
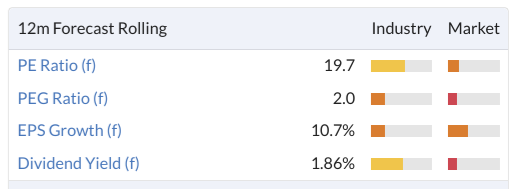
For a company with almost monopoly-like control over the lucrative industry of property search, I’ve grown accustomed to the multiples shown above, but didn’t fully agree with them. Yes, Rightmove has offered little in terms of short-term growth. But when it comes to quality (the ability to make money from a small asset base) and safety (a market position that is secure against competition), Rightmove is one of the most attractive shares that I’ve ever seen.
The safety argument did suffer a blow over the past year, when US-based CoStar picked up OnTheMarket (OTMP) for £100m, with ambitious plans to grow that business. These plans are currently in motion and CoStar recently claimed that visits to OnTheMarket in June 2024 were up 78% year-on-year. However, I’m not sure yet if this has made any inroads into Rightmove’s commanding market share of over 80% (OTMP’s market share gains, if any, could have come at the expense of Zoopla).
So in summary, I’ve continued to believe that RMV deserves an earnings multiple of at least 20x.
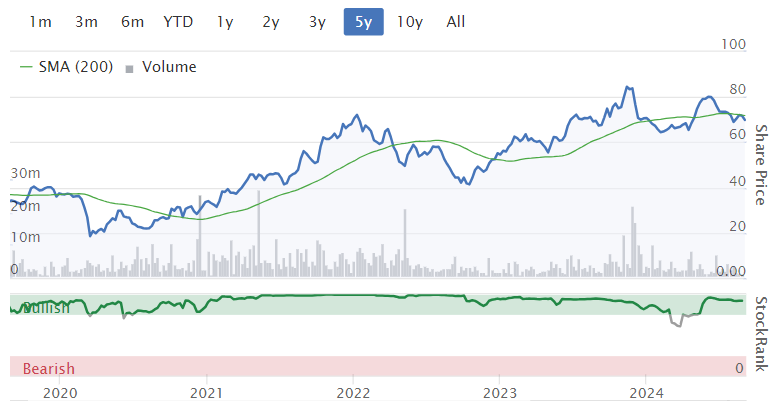
Today’s announcement has sent the shares to levels not seen since 2022:
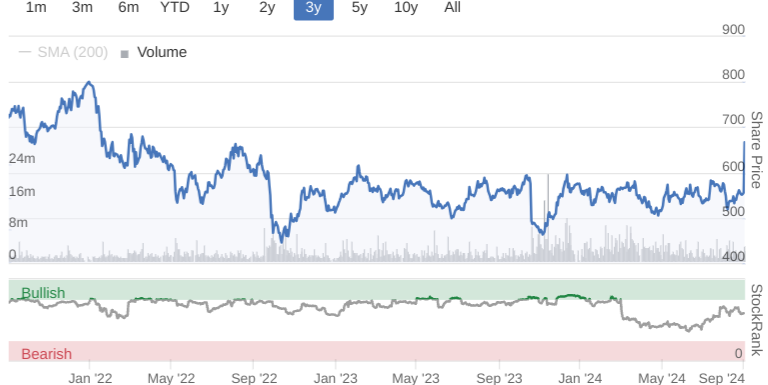
The valuation here is now in the mid-20s in terms of PER, which to my shareholder eyes is a better reflection of underlying fair value than last night’s undisturbed price.
I’m therefore putting an AMBER colour on RMV today, as I could not argue with a straight face that the shares offer great value here. But I do believe that this is a “sleep-sound” type of stock (if such a thing exists). Therefore, with a long enough time horizon, I doubt that buyers at the current level will regret their investment, regardless of whether or not the Australians pick it up.
For what it’s worth, I’d want to receive a multiple of >30x, if I was going to happily give away my RMV shares, i.e. I’d be looking for in excess of 800p.
Ashtead Technology Holdings (LON:AT.)
Down 13% to 678p (£545m) - Unaudited Half Year Results - Graham - AMBER/GREEN
Ashtead Technology Holdings plc (AIM: AT.), a leading subsea equipment rental and solutions provider for the global offshore energy sector, announces its unaudited results for the six months ended 30 June 2024 ("HY24" or "the period").
This has only been listed since 2021, and it has been a great success in share price terms. Paul covered it in April.
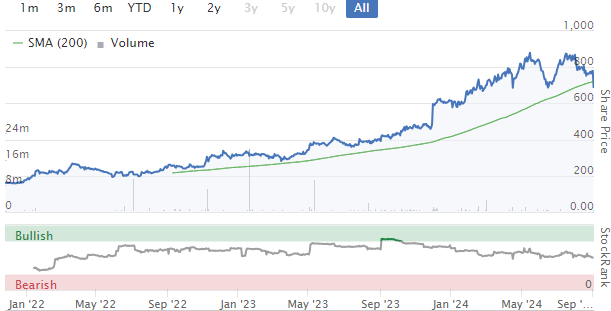
Until 2008, AT part of Ashtead (LON:AHT). It became an independent business in 2008, going private with a PE-backed MBO at a valuation of £96m.
Those who follow the big-cap market will know that the larger Ashtead has been a remarkable long-term success story in the wider equipment rental industry. So perhaps it shouldn’t be a big surprise that Ashtead Technology has been a success, given it has that Ashtead DNA.
Interim Results
The numbers published today are impressive: we have 16% organic revenue growth, plus 47% growth from a November 2023 acquisition, offset by a small FX headwind. Altogether, it adds up to 61% revenue growth (to £80.5m).
Adj. EBITDA increases by 49% (to £31.4m) and operating profit increases by 36% to £20.6m. It’s a nice conversion of revenue to profits, with a strong operating margin of about 25%.
The company calculates and reports its return on invested capital as 25.3%, about the same as last year, and a level that marks it as a high-quality business.
Stockopedia’s ROCE calculation doesn’t quite match it but it’s still coming up with a healthy reading:
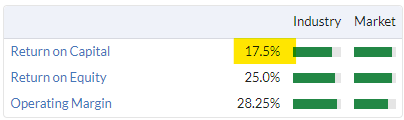
Net debt has increased substantially to £72m. The leverage multiple is 1.2x which should still be manageable.
M&A: is still “a key element of the strategy”, and they want “medium term double digit organic revenue growth”.
Outlook: expectations are unchanged.
CEO comment:
"I am extremely pleased to deliver another record trading performance as we build on the strong momentum seen through 2023…
The outlook for our business remains positive given the strength of the global offshore energy market and our continued investment to support longer term growth. The Board is encouraged by the Group's performance in HY24 which gives us increased confidence on our full year 2024 outturn and our expectations remain unchanged."
Share price reaction?
It’s worth taking a moment to reflect on the double-digit decline in the share price today, despite the company saying that its full-year expectations are unchanged. This is a puzzle but I’ll try to explain it now, after the fact. Perhaps there has been a sneaky downgrade by a broker, but if so that hasn’t been made public, and it would conflict with the RNS.
Firstly, I would note that the share price was already up by c. 90% over the last 12 months, which says straight away that the market has been struggling to value it and that the market’s expectations (as opposed to the company’s expectations) have been rising rapidly. Therefore, some of today’s sellers may have been hoping for an “ahead-of” update.
Secondly, I note that last night’s valuation (based on forward estimates) was steep by some measures and was even more expensive than Ashtead (LON:AHT). The ValueRank was only 9. This makes it extra sensitive to any deterioration in sentiment:
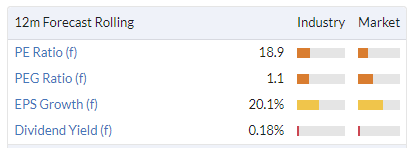
Finally, looking at the results themselves, I note that there was a general decline in profit margins. Costs rose and gross margins declined due to the revenue mix. Headcount increased by 270 (to 559), of which 203 came from the acquisition. Even excluding the acquisition, therefore, AT has been a heavy spender. H1 administrative costs rose by £11.7m (to £30.5m), of which £8.4m were from the acquisition.
The decline in profitability could be seen as a disappointment by some, although the company would argue that it is investing for the future to meet expected customer demand.
On the income statement, unadjusted PBT came in at £17.6m, up by 33% with a very wide gap between that and the 61% revenue growth.
Without asking the sellers, we can’t know for sure why they sold out of AT today, but I would interpret it as profit-taking in light of all of the above
Graham’s view
AT’s customers are in the offshore energy market and this is not a market with which I have much familiarity. However, I can confidently say that in this sector, I would much prefer to take a “picks and shovels” approach rather than to invest directly in offshore energy producers themselves: oil/gas exploration and production, or wind turbines.
AT makes a predictable and good return by leasing equipment to these producers, while the producers take all of the risk associated with specific projects. So there is no question in my mind that AT is the type of company in which I’d prefer to invest in this sector.
I’m not convinced that it’s currently priced at bargain levels but I like the history of this one and have a positive impression of the company, so I’ll leave Paul’s AMBER/GREEN stance unchanged.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Many thanks Paul for your comments onXP Factory (LON:XPF) . Broker forecasts indicate that for Y/e 2027 on a turnover of £78m they only show a pbt of £1.4m which to me indicates that head office costs are too high.
Enjoyed the weekly podcast as ever
I think you are right about central costs Richardho - XP Factory (LON:XPF) used to be one of my biggest holdings but they seem to be running it as a social enterprise, I've been gradually selling out as other opportunities show themselves.... I remember all the excitement about Oxford street and the O2 making a fortune. Can't see it happening now.
The Franchise model for BBB definitely isn't working, they seem to have bought most of them back
Alumasc (LON:ALU) at all time high now with results due tomorrow. They've already fcst UPBT at £12.6m ahead of consensus of £11.9m. Will they beat this tomorrow? SP is up 25%+ in the last 3 months.
Cavendish has a 315p target.
Vertu Motors (LON:VTU) I expect new car sales are soft as people are holding off making big money decisions until the first Labour government budget, which is looking like a disaster already.
Mid morning there is an announcement from EnSilica (LON:ENSI) (I hold)that the the$30mm plus contract , noted in a previous update has now been signed. It is over 10 years, but is significant, and means that the "jam tomorrow" can now start flowing. The broker (Allenby) forecasts are putting in revenue rises of 21% and 28% for May 2025 and May 2026 respectively, although production and supply under the new contract will start in FY2027.
With a StockRank of 10 this stock is a long way from being "Ed Croft approved", and much can yet go wrong, especially as it is quite reliant on AST Spacemobile (ASTS) where Google, Vodafone and AT&T are attempting to build a LEO satellite service where of course Musk's Starlink has a heavy footprint. I like to keep a few small but possible potential firecrackers in my portfolio, this is one of them
Intercede (IGP)
Hi Paul, Graham,
There’s a recording of Intercede’s Capital Markets Day on the Investor Meet Company platform, and also on the IMC YouTube channel.
Regards,
Andrew
Intercede (LON:IGP)
When Paul said that there was no recording this was specific to the contribution by Cara McFadden of Guidehouse (I remember being impressed by it). This came between the Case Studies and Summary sections so if you watch (below) you will see that has been cut and the Summary section begins with the CEO thanking her.
Thanks, apologies for that.
Vertu Motors (LON:VTU) This week's Economist says the entry level BYD model in UK, Dolphin, sells for £25k whilst it is £10K in China. A consultancy says BDD could cut its European prices by 30% and still make the same margin as it does in China.
Thank you for the comments on Vertu Paul, we sold last year but would invest again at 65p, bid interest seems to have faded but imo it's a class act at a fair price anyway. Off topic but I had to smile at your question "is it time to grab an EV bargain?"
At the risk of some mickey taking from upmarket brand drivers here, we have.
We bought on price as the car was not on my target list, our only criterion was not to spend more than £35,000 on an EV and that my not very tall wife was happy with the seating position! A Tesla owning son (3 sons with EV's plus a son-in-law, all much more expensive) sent an Autotrader link for a 550 miles 3 month old Toyota Bz4wx, I watched YouTube reviews for it, and against, but at £9,000 off the £39,500 retail price it's a lot of car for the money, we love it and and it suits our much reduced mileage needs, Toyota build quality is good and they also give a 10 year battery warranty which is better than we have in our early 80's! Car chat over, it was of course an ex-mobility scheme car as mentioned in Vertu's TU.
As a long time holder of Vertu Motors (LON:VTU) I am very disappointed to see they are now selling Chinese cars. I don't believe anybody in thsic country should be buying highly subsidiized Chinese cars. Specifically as far as Vertu is concerned, this could result in a long term decrease in sales of many other brands . To add insult to injury it seems (although I have not checked this) that BYD will be making much higher margins than is their norm, when selling into the UK (and many other countries). I hate this increasing dependency on cheap Chinese products of anything and everything. Rant over!
Article in Daily Telegraph that Robert Forrester, CEO of Vertu Motors (LON:VTU), is saying that manufacurers of petrol and hybrid vehicles are holding back deliveries to avoid penalties for not producing correct quotas of EV ones.
Agree with your view on Rightmove (LON:RMV) Graham. It's a high-quality company so I think it deserves a higher multiple. I wrote a few words on the stock here: https://www.fool.co.uk/2024/09...
Graham your thoughts on Rightmove (LON: RMV) this morning are, as ever, thorough and concise …They must be considered excellent as they were pasted onto London South East discussion site (non-subscription) …admittedly with references to yourself and Stockopedia ….at 11.08 this morning by a stocko member …..Not sure what the desired effect was but maybe it will encourage a few newbies to the site
Thanks very much for the heads up, Pennyledges!
Thank you for sharing your thoughts, Edward! G
The two Mello Autumn networking events have launched and the links and info are on the Mello website
For those who want a loyalty ticket do book early as there are just 100 available and 41 have gone over the weekend. This is the link to the two day Anniversary show
Mello 10th Anniversary tickets – Mello Events
This is the one day London show...
Mello @ LIS tickets – Mello Events
BGUK Just a little snippet of info that I thought worthy of note. I was going through the Baillie Gifford UK Growth Trust presentation, and there were some interesting stats at 2m53s.
They were explaining why growth matters. Rolling 5-year horizons between the period 1994-2023 produced the following median relative total returns by earnings growth ordered by quintile:
Q1 +6.4%, Q2 +4.8%, Q3 +1.9%, Q4 -1.4%, Q5 -6.8%.
They didn't explain their methodology, though. It's good, but they didn't explain if the companies were selected in advance or by hindsight (I suspect the latter). If the latter then it undermines their analysis because you have to invest beforehand, not with the benefit of hindsight. (Otherwise just buy NVDA)/
Hot on the heels of propsals to ban smoking in beer gardens and other outdoor spaces, Labour now going for disposable vapes:
https://archive.ph/J9gQw
Supreme (LON:SUP) taking a hit.
I'm buying Supreme (LON:SUP) on weakness. Disposable vapes have been on the cards for some time, so no need to worry about that - the company has stated they would rather be selling vapes with refills. Furthermore, smokers WILL move to vapes when they are at places where smoking is banned - there is no way that vapes will be treated like cigarettes especially when the NHS have been encouraging smoking cessation by moving to vapes.
Supreme (LON:SUP)
i suspect the worry here is that young ones (under 18) will be prevented from vaping - at present there seems to be no steps taken clamping down on under 18's vaping - furthermore is there not a decent chance that vaping may be similarly targetted despite your thoughts to the contrary? seems like lots of places dont allow vaping in the same manner as smoking!
I see that the the supreme 88vape.com website still has the watermelon and sweet strawberry flavours front and centre of their website despite what they offically announced last year !!
ditto for T- Juice with their dark berry and cherry flavours.
per the company 18/10/2023
3. Age-appropriate flavours only: The naming conventions of all flavours across the 88vape range will be simplified, for example "Peach Dream" will be become "Peach" and "Sweet Strawberry" will become "Strawberry" to reduce the shelf appeal for underage vapers. Any flavours which are likely to be more appealing to underage vapers will be removed entirely from the range.
Note i see that vn labs have gone to the trouble of stating there are dosgy companies using their name on Alibaba - not great if they may get drawn into an issue with dodgy stuff being linked to their name even if they are the innocent party. Ie that would suggest that the curent rules are not strong enough and and clamping down on? (that could partly benefit Supreme if dodgy competitors are removed from the system i would concede)
Why is this company giving the impression to me that they are paying lip service to stuff they say they find important (note 3 above) ?
Vaping is much less relevant longer term for Supreme (LON:SUP) so investors gnashing their teeth at potential changes in vaping legislation just miss the point of this business.
They are a fast moving goods manufacturer and distributor. Their manufacture is done at very high quality and distribution ability/network is highly sought after. They have a distribution network with large and small retailers alike that is very difficult to achieve - so is a good moat.
They are using current profits to acquire new businesses and expanding others. Lighting is coming back and adds materially to profitability, sports nutrition likewise. The whole strategy for Supreme (LON:SUP) is moving away from vaping as a %age of its business. Management is highly opportunistic but also have a sound long term strategy - they were surprised at the take off in vaping but nonetheless managed it well and it helped significantly in a period post covid where inflation caused margin issues in the sports nutrition business and overstocking collapsed the lighting.
This is a business with a very strong balance sheet. Think of the manufacture and distribution as a horizontal and a series of growing verticals, one of which is vaping, that is planned to become a significantly decreasing %age of the overall.
Investors are reacting like Vaping is going away - irrespective of this Governments attempts at state control of its citizens, that’s clearly a nonsense and anyone who thinks Supreme (LON:SUP) profits are heavily dependent on disposables or underage vapers really has little understanding of the make up of this business.
But it is par for the course that any vaping news hits the share price regardless and then the results speak for themselves - and I suspect it will be that way for years so any holders should expect volatility based on the weighing machine effect.
The last Equity Development broker note completely disagrees with your opinion on profits;
"The driver of gross profitability, however, remains Supreme’s own-brand vaping products, principally eliquid and 10ml units, where the Vaping Business Category recorded £36.1m in gross profit, a 43.5% margin and 57.8% of gross total. In this category, we estimate the contribution from Supreme’s own disposable vapes at £13m, taking the Group disposables total to £70m and the contribution from vaping product revenues as a whole to £140m"
How much of the £36.1m gross profit comes from disposables? If the ratio is aligned with revenue then it would be £18m. So any ban would potentially remove just under 30% of their gross profit and presumably have a similar impact on EPS. Not one to get complacent on with regard to valuation.
Those using disposables will just move onto refils. Which have more recurring revenue and more brand loyalty. Given that liquid are a fraction of the price of cigarettes, there is an easy step up for 'premium' vapes and eliquids. Even non smokers here in leafy Cheshire are all jumping on them, wether they are nicotine free, or ocassional smokers who, now, vape loads indoors.
With regard to Mark Carter's mention of Zyn - these are not really used by smokers and are 'frowned' upon, kids use them too (as footballers have been using this and snus), and is super addictive.
I don’t think you read my post very well and I dont think you’ve listened to mgmt or understood the business I’m afraid, AimingHigher
Supreme (LON:SUP)
in what way is AimingHighers post missing the point ? - the numbers seem to cross tally to me - not sure exactly what % of profits come from vaping but to me AimingHighers numbers seem on the money and suggest its a very materially big number as part of overal % of profits - if they are moving away from vaping surely the fact vaping is a bih % of profits matters. Obviously if they can get other stuff to 75% plus of profits then that would indicate vaping is neithrr here no there - are they anywhere near being able to acheive that medium term though other than as an aspirational goal thay may have?
As per RNS
"Total revenue from disposable vapes in aggregate came to £70.7 million in FY24, representing 32% of Group revenue and was reported across the Vaping and Branded Distribution category"
"Supreme's Vaping division, with revenues up £6.7 million to £82.8 million, and our own-brand disposable vapes reported sales of £13.7 million"
The Branded Distribution Category division reported revenues of £63.5 million (FY23: £7.8 million), with the ElfBar and Lost Mary distribution agreement contributing £57.0 million
We are told "ElfBar and Lost Mary are not brands owned or manufactured by Supreme, so have an entirely different financial profile to the Group's core Vaping business"
"The blended margin of the category remains relatively low compared to other product categories within the Group at 14% (FY23: 10%)".
So from what I gather we have 57m + 13.7m = £70.7m that relates to disposables vapes.
Looking at the Vaping division 82.8m - 13.7m = £69.1m of non disposable vape related revenue.
Point being even if we zero the revs for disposables, the profit impact is going to be a lot lower then one might think. (Elf/mary disposables which contributed the majority of revs based on above are lowermargin) + Sandy (per presentation) mentioned the regular E liquids purchases are higher margin then the actual devices (heard similar commentary elsewhere). Those switching from disposable to a pod system will also need to make this bigger up front investment. Sandy also mentioned re: increasing prices as well.
It's possible perhaps revs are a bit lower, but profit not substantially impacted to the downside.
FWIW, I recently heard of a product called Zyn https://www.zyn.com/gb/discove... It's an alternative to ciggies and vapes. It's small in volume, and I think they're looking to grow aggressively.
"Philip Morris to invest $232 million to expand ZYN production at Kentucky plant" https://finance.yahoo.com/news...
Could possibly upend the whole sector.
And do you know who supplies one of the highest quality nicotine pouches Mark Carter?
Hmmmmm… Supreme (LON:SUP) anyone??????
Graham
Well done on Rightmove (LON:RMV) . What are your thoughts on Auto Trader (LON:AUTO) as a similar monopoly share with strong cash flows and margins. I can just never get my head over the valuation so have only ever tried shorting it in the past (briefly paid off over covid then gave up fortunately) thinking the market places or Google would just take the business one day but that clearly hasn't happened
Appreciate not one for SCVR so just posting today given the RMV news
Hi topturkey, I've generally had a favourable impression of AUTO but I've never owned it and never liked it as much as RMV. Sorry I can't be more specific than that! It is fair to put it in the same basket as RMV, I think. G
Rightmove (LON:RMV)
800p + ? The market says probably not, or we’d be settling solidly over 700p around now. Maybe that will still eventuate but I believe it would take a bidding war.
Kainos (LON:KNOS) 15% drop for an in line profit forecast (albeit H2 weighted) is not adequately explained by a disappointing revenue forecast. I could be wrong but, like Tracsis (LON:TRCS), this looks as though the election has introduced delays in order intake. I’ve topped up here as the company is very high quality at what I believe to be a decent price.
Kainos (LON:KNOS) . I also think this is an over reaction. Kainos already explained in their statement on July 25th regarding the agreement with Workday, that they would be increasing their spend on the sales and development of their Workday products, so that they could maximise the opportunity that the partnership provides. They called out then, that the additional spend would be 7m this year, bringing down PBT to about 8% below consensus. The PBT consensus at the time was 86m, so down 8% would be to 79.1, which is what they are reiterating today. So, really not that much new in today's statement except the comments re revenue growth slowing. (revenue still increasing, just not as fast as previously anticipated)
I think the real value going forward will be in the Workday products division. This revenue is much higher margin than digital services and also Workday services. As the ARR resulting from this division ramps up (they are calling out 200m by 2030 from current level of around 60, the margins should increase significantly. Of course, there are no guarantees, that they will hit these targets, but they seem pretty confident.
Agree that today's fall in the Kainos share price looks a bit overdone but perhaps some investors might wonder if it is pure chance that this has occurred fairly soon after the retirement of the very longstanding CEO and Chairman.
Thanks Graham for your view on Rightmove (LON:RMV) , I've been holding on for quite some time and today's share price only takes me into a small profit so I agree your 800p would make a good starting point.
Hi,
Where is the best place to get a list of companies reporting over the coming week/month? I get an email from IG (the week ahead) but it doesn’t seem to include all - leaves out rightmove this week - for example.
thanks
Hi Jimbob, Investors Chronicle publish a list every week.
Jimbob, does Rightmove even have a scheduled update this week? Today is because Australian press revealed a takeover story...
Jimbob, this site provides such a service, to decline cookies, click the greyed out "decline" box
https://www.lse.co.uk/share-pr...
Company diary digital look
Hello Jimbob
South East London do a pretty good day by day calendar for the coming weeks with scheduled company reporting plus dividend ex div and payment dates , together with uk, us and european economic announcements (gdp , employment, prices stats etc) . Its free.
Sorry - I’ve just seen that rwh3ue has already pointed you in this direction !
google finance home page has a list (scroll down bottom right) but not sure it's comprehensive...
i'm interested in a free resource for what companies are going EX-Dividend in the next 4 weeks any helpers ?
ATB
Dividend Payment Dates - FTSE, LSE, AIM (dividenddata.co.uk)
This is very helpful. many thanks Helvellyn
I have held since 2019 and continue to add.
Potential turmoil surrounding the US Election could create squally conditions. But surely security will have to be maintained.
Good morning.
Arcontech (LON:ARC) reports final results for year ending 30th June 2024.
A bit of a microcap company with a market cap of just £13m, Enterprise value of just £5.9m.
Increase in Revenues by 7% to £2.9m.
Increase in profit by 10% to £1.1m.
Increase in cash by 3% to £7.2m, that is 55% of the market cap.
Increase of dividend of 7.1% to 3.75p.
A bullish report given with expected revenue growth and further contracts expected to be won as they increase their sales team. Only negative I see in the report would be the increase in the costs from the increased sales team, which if they do not produce additional contracts will hit the profits. The other real negative would be the low share count of just 13m shares, which would make the company a little illiquid. A PE of approx. 16, which is quite low for this sector and puts the company under valued, especially when you take into account the high cash position.
Broker has a target price of 180p, expecting contract wins to come.
Chart wise, Arcontech (LON:ARC) is looking good, broken out of the downtrend that started from Covid, from a high of 216p to a low of 62p. Trading above the 200sma and the 50 ema. Note, there is a gap to fill at 117p. It has steadily been climbing since July 2023.
Looks like a bargain but looking back at the accounts they have decent margins and generate cash but have struggled to grow. Is there any evidence that there is demand for their services beyond the (presumably) handful of clients they have today? Perhaps there is just a limited niche here? I know nothing about them so would love to hear more from anyone that does. Meanwhile I’ll have a dig.
Hi JonBeddell,
Used to come across them in my old job. They have a contributions gateway to financial data platforms (esp. Reuters and Bloomberg). If say, the African currency desk in a bank wanted to push forward rates onto Bloomberg and Reuters at the same time they could do it off the same spreadsheet via their Arcontech server. As such, the Arcontech product is reasonably well-embedded in their customer's market data architecture.
I'd say they'd struggle to grow much- the advantage at one point would have been compatibility with both major platforms (no need to maintain 2 spreadsheets/sets of formulas...etc.). However, Reuters bought a similar but lighter weight solution (Gissing/Contex) which I reckon they'd just chuck in for free to a customer of any size.
From memory, some official daily publications went through Arcontech back in the day, think Bank of England used it for LIBOR fixings so there might be some enhanced security/stability for Arcontech vs. others. Looking at their customer list, I don't believe many of them are pushing/pulling all their data through Arcontech and I know for a fact that some of them were using Contex heavily in the past as well as publishing directly.
Hi JonBeddell, I do not think it will light up the world for sure, but they are confident to grow at a steady pace, hence the increased sales force. My main point is the company is under valued with such a high cash holding. The benefit to Arcontech (LON:ARC) is the high customer retention and that it is costly and not easy to swap their services. If they can add on additional services through their customer sales team then it should see a slow climb to a more reasonable valuation. I certainly do not know the ins and outs of this service like someone who is in this business, so it is hard for me to comment too much on it. What I see is a low valuation, high cash pile and a high Stockopedia Quality number. Add to this a steady dividend and I'm happy to hold until valuation improves or negative report comes out. Having brought at a lowish price of 85p and 75p, the dividend isn't too bad for me. This company took too large a fall imo from covid.
Thanks Gmjs for your note, it does confirm to me that this is never going to light up the world. Much appreciated.
An interesting UK investment trust merger announced today with Aurora Investment Trust (LON:ARR) merging with Artemis Alpha Trust (LON:ATS) - it seems to make sense given an overlap of holdings. Garry Channon at Phoenix will add Kartik Kumar to his small team. I hold the former, but sold the latter a couple of years ago.
Zane update. Paul's favourite worthy cause and I am a trustee. My wife Angela and I walked the first 3 days of Tom and Jane's grand walk. (13 days of walking with one day off.) It is the Severn Way. You would think it would be a smooth path all the way, believe me it is not. In parts and in woods it is almost impassable. For more info please visit www.zane.uk.com Tom writes a great blog and there is a donate button. Thank you for reading and apologies to any who think this inappropriate on here. Situation in Zimbabwe is dire for many. Charles
Hi Charles
I donated the other day and did so through the general Zane website donation page rather than sponsoring your latest walk as that was through JustGiving.com and I wanted to avoid their admin fees and charges.
Is this the best approach?
Yes. I am hon treasurer of a small charity and always avoid these fees if I can.
Thank you Jayman for donating, it is much appreciated. You did the right thing. I set up my own page last year which was linked directly to Zane, but I couldn't see the point this year. Thank you on behalf of the beneficiaries in Zimbabwe
Ashtead Technology Holdings (LON:AT.) reports H1 figures compared to last year positive anywhere between 26 to 62% increase, but the outlook remains the same.
Great performance but just in line with expectations, so no fireworks expected.
Morning all. First post here. I've been encouraged to sign up after enjoying listening to Paul's weekly podcast for the past few years.
On AT.:
This morning's lacklustre reaction is perhaps explained by 2024 H1 adjusted earnings (19.1p) coming in a shade under those of 2023 H2 (19.2p).
This happened a couple of years ago (2022 H1 earnings of 8.3p were less than 2021 H2 earnings of 9.1p) so it's not without precedent, although I'm only looking at figures from the last 3 years.
If 2024 H2 earnings were the same as last year then FY earnings would be 38.3p, ahead of the current forecast of 37.6p, so broker upgrades seem likely.
Ashtead Technology Holdings (LON:AT.)
Yes good numbers but not stellar, i sold out last week, i feel it has lost momentum and given it was on such a high rating it would have been difficult for it to maintain its trajectory of the last few years.
Still like the stock and the sector but will wait for a rerating to the downside before buying back in.
Good luck to continuing holders.
Someone pointed out a line I'd missed on my just-out-of-bed bleary skim:
"Year to date investment of £16.4m in rental fleet capital expenditure (HY23: £8.0m) with full year forecast of £30m.
"That's a big jump and will have affected margins and profitability, but hopefully points to future growth in turnover. It will be interesting to see what analysts make of the figures.
Hi Zho, I believe that H2 2023 Diluted Normalised EPS figure was actually 13.7p ( I get this from the Stockopedia Interim Income Statement.) So I see the latest figure for H1 2024 of 19.1p as a big improvement from previous H1 & H2 figures. Ashtead Technology Holdings (LON:AT.)
Hi zho,
Welcome to Stockopedia! I'm delighted you've joined us here after following my podcasts, and you've hit the ground running with a 25 thumbs up initial post here! :-)
I recognise your username "zho" as being a sensible poster, maybe from another site?
Regards, Paul.
Hiya Paul,
Thank you.
>>I recognise your username "zho" as being a sensible poster, maybe from another site?>>
Yes, I've posted as zho for 25 years – on Hemscott, ADVFN (sorry), Fool, Cockney Rebel's Slack thread, and now its CR-less successor..
We did have some email contact c. 25 years ago, concerning MDY (Medisys), but I'd be impressed if you remembered that.
Sorry to sound nosy but any way I can get a link or access to the slack thread ?
Hi there,
Try signup.stockprophet.chat
I note that on the AT. website they have published a HY24 presentation. This adds a bit more colour to the RNS. It shows that FCF has turned negative as working capital has increased unlike the past couple or years where it decreased. They are presenting on Investor Meet this Friday so worth trying to find out what caused this.
My morning smallcap tweet: Parsing PR into plain language
Vertu Motors (LON:VTU) Hemogenyx Pharmaceuticals (LON:HEMO) Sareum Holdings (LON:SAR) Oncimmune Holdings (LON:ONC) SRT Marine Systems (LON:SRT) Ethernity Networks (LON:ENET) Feedback (LON:FDBK) MTI Wireless Edge (LON:MWE) Futura Medical (LON:FUM) Intercede (LON:IGP) Eden Research (LON:EDEN) XP Factory (LON:XPF), Concurrent Technologies (LON:CNC)
◄Vertu Motors (VTU)► guides FY-Feb25 1% below market consensus due to poor new EV sales. New vehicle sales fell 6% in the first 5 months in a mkt that was down 12%. [SP=71.6 Cap=240m]
◄Hemogenyx Pharmaceuticals (HEMO)► develops a new and improved version of its bi-specific antibody ("CDX") for the treatment of relapsed/refractory acute myeloid leukaemia. "This advancement could accelerate the progress of this product candidate and allow us to resume its development toward the clinic." [SP=1.27 Cap=18m]
◄Sareum (SAR)► gets US patent for its lead programme SDC-1801. [SP=27.6 Cap=30m]
◄Oncimmune (ONC)► wins $0.7m US contract under a long-term master services agreement. [SP=19 Cap=13m]
◄SRT Marine Systems (SRT)► wins two follow-on maintenance and support contracts from two existing sovereign agency customers in Asia worth a total $4.6m over 12 months. [SP=25.25 Cap=57m]
◄Ethernity Networks (ENET)► delay in the U.S. Government approval process for the $1.05m licensing deal but remains confident of imminent approval. [SP=0.54 Cap=3m]
◄Feedback (FDBK)► wins further £69k funding to extend the delivery of its Community Diagnostic Centre pathway pilot. [SP=54.5 Cap=7m]
◄MTI Wireless Edge (MWE)► wins €2.6m contract for radio frequency components to its biggest defence customer. To be fulfilled by the end of 2025. [SP=40 Cap=35m]
◄Futura Medical (FUM)► Eroxon availabile from Oct on Amazon US and in stores. [Insert your double-entendre here]. [SP=33.5 Cap=101m]
◄Intercede (IGP)► wins $1.5m+ contract orders and subscription renewals. This underpins revenue for FY25 and contracted revenue backlog for future years. [SP=203.94 Cap=120m]
◄Eden Research (EDEN)► temporary approval for Cedroz in Greece for use on potatoes against wireworms for the 2024 growing season. [SP=4.19 Cap=22m]
◄XP Factory (XPF)► FY-Mar modestly ahead of market expectations. Guides FY25 in line. [SP=13.8 Cap=24m]
In line: CNC
The FT is reporting that property listings giant REA is considering an offer for Rightmove (LON:RMV), and confirmed by the potential bidder, although no formal bid as yet. I hadn’t been expecting this development but it makes sense at a time when the shares are considerably better value than they have been for the best part of a decade. Shares are half the price of less entrenched near-monopolies stateside.
Lindsell Train Investment Trust (LON:LTI)
Nick Train will be busy this morning, Rightmove are one of his big core holdings in his investment trust
I don’t think he has any directly in Lindsell Train Investment Trust (LON:LTI) but it’s certainly a close to 5% holding in Finsbury Growth & Income Trust (LON:FGT) (in which LTI has a stake) and the equivalent OEIC. Taken together with the ongoing bid for Hargreaves Lansdown (LON:HL.) that’s circa 10% of the respective trust assets under bid and potentially available for re-investment post-completion - assuming both ultimately go ahead. I have argued on here before that his core holdings (bar the ongoing train wreck that is Burberry (LON:BRBY) ) have bottomed. Unilever (LON:ULVR) regaining altitude under new management. London Stock Exchange (LON:LSEG) ditto post the integration of Refinitiv and the elimination of the stock overhang. Diageo (LON:DGE) has hit an attractive floor. So more optimism around his strategy and portfolio choices. Speaking of bids I’m still surprised that Warren hasn’t chosen to pick up Diageo (LON:DGE) at the current value. I know what I would be doing with a portion of my over $200bn cash pile