Small Cap Value Report (Mon 20 Dec 2021) - preamble, SPE, FA.

Good morning, and welcome to the first SCVR of Christmas week! Just Paul today. Today's report is now finished - very quiet for news.
Over the next couple of weeks, every day the UK stock market is open, then there will be a SCVR here. I've got a very quiet Xmas planned, so distractions will be few and far between.
Agenda -
Paul's Section:
Sopheon (LON:SPE) - this software company expects to comfortably meet expectations for FY 12/2021. The trouble is, that's barely above breakeven. A very poor trend in growth (none basically in the last 3 years) and profits (which have disappeared) since 2018. Does it matter though? That's up to you.
Fireangel Safety Technology (LON:FA.) - a trading update that seems muddled, and doesn't give enough information. This company has performed badly for several years now. It might be able to execute a turnaround, but that's not something I want to punt on. Why take the risk?
Preamble from Paul
Looking at the futures, it seems we're heading for more market turbulence - hardly surprising I suppose, with omicron spreading incredibly quickly. I've been keeping on top of the covid news through health analyst Dr John Campbell's youtube channel. He's got a good track record of explaining covid in simple terms, coming from a teaching background. His daily videos run through published material from reputable sources, and he always provides a link to the research papers, etc, that he's explaining.
Anyway, his latest videos have been explaining how omicron is incredibly contagious, and therefore the world is at the point of a huge new wave, that probably can't be stopped. However, data from South Africa shows that it's milder than previous strains, and a recent study suggests that it doesn't move down to the lungs as readily as previous covid, thus being less deadly. Also cases apparently seem to peak after just 3-4 weeks, then we could end up with herd immunity here at some point in Jan 2022. But obviously nobody knows for sure.
In the meantime a lot of people are going to be off work, mainly with cold or flu-like symptoms (the symptoms have changed from previous strains). Therefore we can expect another month of disruption to businesses (especially hospitality, travel, retail, etc) - you know the drill. After that, who knows, it's too early to say, and not even the experts can predict the future.
In terms of shares, I think (as mentioned previously here) we should expect more profit warnings. The problem is, we don't know which companies have enough padding in their forecasts to sail through and remain in line with market expectations. The flipside is which companies were already struggling to meet forecasts, but thought they might be able to recoup a shortfall by year end, which will now need to warn on profits? Lots of uncertainty.
There could be plenty more opportunities to buy decent companies on short-term, temporary disappointments, at attractive prices. I think it's important to banish feelings of despair in market downturns like this, and instead salivate at the buying opportunities. Today's pain could be next year's big profits, selectively. That's what happened in previous panic sell-offs, although nobody knows what the exact low point will be. There did seem to be some tentative buying in small caps last week though.
Supply chain costs remain a problem, as does wage inflation in particular. Although looking around me, I don't see empty shelves in the shops, and life seems to be carrying on, despite all the previous dire warnings of shortages & panic buying. Supply chains have actually seemed more robust than perhaps we imagined previously. Earnings might be suppressed this year, and maybe next year, from the massive cost of freight charges, but at some stage that unwinds, and supply chains return to normal, and company profits should rise. That's a big opportunity for investors who are calm, and take a long-term view, in my opinion.
I am worried about wage inflation though. Jack was discussing Royal Mail (LON:RMG) in an interesting video (see/hear below) with Paul Hill (a very successful private investor, analyst, and all round nice guy), and David Thornton (highly experienced small caps expert, who writes Growth Company Investor, which I enjoy reading, and also a nice guy, in fact they're all nice guys, and clever!)
I took a look at RMG shares over the weekend, and it looks superficially cheap. However, half its costs are "people costs". You can quickly work out that if people costs were to rise by 10%, then that would wipe out all RMG's profits. Given the company's history as a nationalised industry, complete with a bolshy workforce prone to going on strike in the past, and a them & us culture, what's the betting that wage costs rise considerably? So there are 2 key issues - are there any arrangements in place already for agreed pay rises, which might soften the blow? Secondly, what scope has RMG got to raise its selling prices, to recoup higher costs? Pricing power is the biggest single question to ask companies right now. The companies that can raise prices promptly, should be the winners in an inflationary environment. Does inflation peak, and then reduce next year? No idea. Nobody knows.
I should add that the pension scheme disclosures in the notes to the last annual report for RMG look potentially scary, with vast schemes, and it's not at all clear whether they're in surplus, or deficit. Seemingly both, depending on whether you look at actuarial or accounting figures.
.
.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Sopheon (LON:SPE)
935p (pre market open) - mkt cap £98m
I’ll start with this software company, because it’s popular with private investors. Looking at the 3-year chart below, SPE has been remarkably resilient in the small caps sell-off in recent months, but is still down on the peak it reached 3 years ago. The problem seems to be that revenue growth has gone nowhere since 2018, and the big profits from 2017-18 seem to have largely disappeared. Given that being the case, I’m surprised the share price has held up so well. So far investors seem to accept the bull case, that the switch to SaaS revenues is suppressing short-medium term profitability.
.

Acquisition and Trading Update
Sopheon, the international provider of software and services for Enterprise Innovation Management solutions, is pleased to announce the acquisition of the business and assets of ROI Blueprints LLC ("ROIB"), a cloud-based solution focused on detailed enterprise planning and execution. The Group is also providing a trading update for the current year ending 31 December 2021.
Initiation of M&A strategy coupled with solid execution of revenue objectives for the year
Acquisition - is very small, at $1.5m initial cash (ample cash pile of $24m at 30 Nov 2021). A further earn-out of $1.5m is contingent on 3-year performance.
The key reason for this acquisition seems to be this, which sounds sensible -
We see this as a technology acquisition that will improve our time to market for a key product capability. I believe it would have taken us at least two years of material investment to develop equivalent capability in house."
Trading update - this sounds reassuring -
In our half-year report issued on 25 August 2021, we reported rising commercial traction across our core performance metrics as we migrated the business to a more recurring model.
We are pleased to report that we expect revenues and EBITDA for the year ended 31 December 2021 to be comfortably in line with market expectations, coupled with solid progress on building annual recurring revenue. The closing weeks of the year remain busy with commercial activity. The Board will update shareholders further on the full year outturn at the end of January.
Broker update - Progressive Equity Research has issued a short note this morning, saying no change to forecasts. The trouble is, forecast revenues of $32.7m (still less than 2018 peak revenues, but up 9% on 2020), and adj PBT is not much above breakeven at $0.5m (peak profit in 2018 was $6.9m).
My opinion - does short term profitability matter? Maybe not in this sector, but the reality is that these are deeply unimpressive graphs -
.

.
Fireangel Safety Technology (LON:FA.)
13p (down c.3%, at 08:45) - mkt cap £24m
FireAngel (AIM: FA.), a leading developer and supplier of home safety roducts, announces a trading and business update.
This is the most important bit -
The Company announces that it remains on target to meet market expectations for adjusted loss before tax for the year ending 31 December 2021 ("FY21"), which represents a significant improvement on 2020.
This is a badly worded announcement e.g -
It doesn’t give a footnote as to what market expectations are, just that it’s a loss
Net debt is “ahead of market expectations” - ahead? Does that mean ahead as in more net debt than expected, or ahead as in better? Again, no figure provided.
We’re only 11 days from year end, but it’s still casting doubt over whether it can actually achieve market expectations! So why put out an update now, if there’s uncertainty?
The remaining risk to the Company achieving its market expectations for FY21 is from developing COVID-19 related measures in any given country and related shipping variability.
Gross margin - self help measures underway, but it’s still only generating a lamentable gross margin of 22-24% (LY: 19.8%). That says to me the company has little pricing power.
Supply chain issues - “continued to intensify” in H2 - but “slight improvement” more recently
German partnership for new products going well.
Chinese production of entry level products is progressing - margin enhancing in 2022.
Working capital - sufficient for its needs (no figures given)
Outlook -
"It is disappointing that the global supply chain issues have continued during the second half and continue to impact the world economy. However, we have made good progress against our strategic priorities, in particular our gross margin improvement plan. The growing interest and demand we are seeing for our Connected offering further reinforce our confidence in the long-term opportunity for FireAngel. We look forward to providing a further update in late January 2022."
My opinion - there aren’t enough figures in this update to enable me to form an updated opinion. This was a really good, profitable, cash generative business a few years ago, but more recently it’s been a catalogue of errors and deterioration. Maybe it’s just been overtaken by competitors?
Maybe there’s recovery potential here, but it’s not something I’d want to speculate on. Why take the risk, when there are so many better companies currently being offered at discount prices?
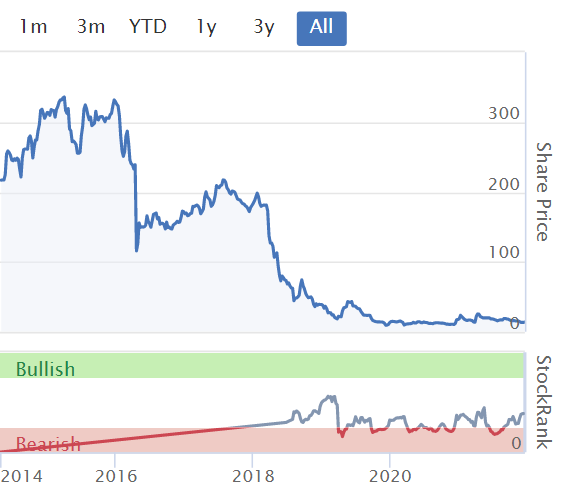
An absolutely dismal track record of shareholder value destruction, as you can see below.
.
Due to dilution from issuing new shares, to prop up the company in recent years, there's now no realistic chance of the share price fully recovering, even if performance does turn around.
.
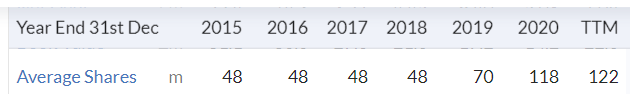
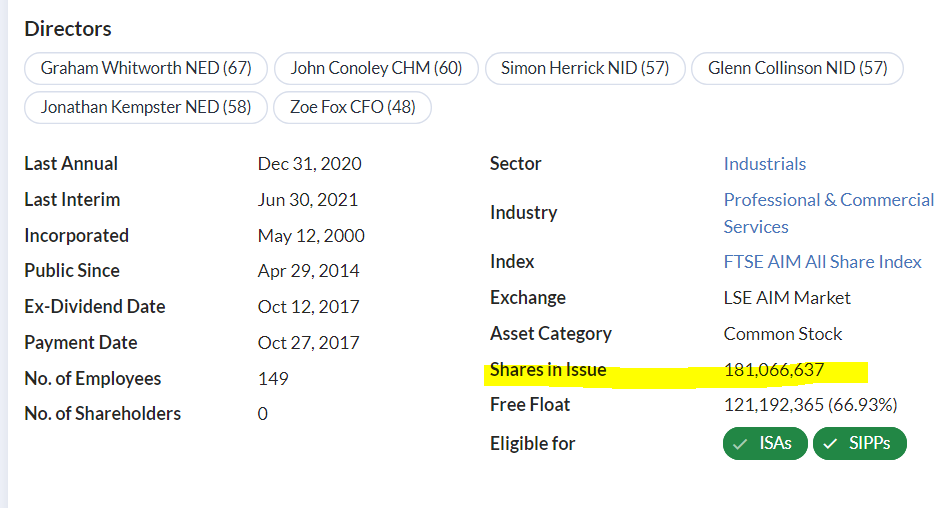
These are averages remember, so you also need to check the latest figure for shares in issue, which has increased further to 181.07m shares, at the bottom of the StockReport here -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
Paul
Lots of thanks for introducing me to Dr John Campbell’s YouTube channel (link above in your preamble). I watched the interview with Professor Hoiby and was so impressed by the information and the balanced, scientific way in which the discussion took place. This is such a contrast to the shrill partisan approach adopted by so many pro and anti-vaxers. Given the difficulty in finding rational and reasoned information in this divided world, Dr Campbell’s channel feels like a gold mine.
For those who are interested, Dr Campbell’s discussion with Professor Hoiby concerns Professor Hoiby’s work in re-introducing aspiration as the first part of an intramuscular injection. Aspiration is the process of checking that the injection is really going into the muscle rather than a vein. Aspiration was standard practice in all intramuscular injections until maybe 15 years ago when (based on limited information) it was deemed unnecessary. Following Professor Hoiby’s recommendation, Denmark has now reintroduced aspiration in all applications of Covid vaccines and serious side effects from the vaccine are now ⅓ of the level experienced in neighbouring Norway where they do not aspirate.
How can Royal Mail be good value when its net tangible equity has actually shrunk over the past 5 years. This means that the dividend is not covered, regardless of what the easily manipulated earnings figures may say - tangible equity growth tells the real earnings story - and Royal Mail is consumer sahreholder wealth not creating it - how can it be doing anything else if its net tangible equity is shrinking.
Covid is real and dangerous as it’s a new bug ans we have some trouble handling it…but dealing with it has descended into a viscous political and morals game propelled by frightened leaders and media keen to frighten for the clicks.
Ivermectin doesn’t cure or prevent covid…it may with many other known, tested and safe drugs help treat some of the symptoms and prevent many more people from becoming critically ill. There has been real research to show this. When we look back it’s absolutely clear to me that we will be amazed we didn’t use medical tools to attempt to moderate a disease that accumulates and builds and overwhelms the body gradually early in its progression before people end up in ICU.
The vaccines are a massive experiment. Deaths and illness may result from them too. For example, teenage boys and young men seem to be at risk of heart problems and this may accumulate if taking repeat vaccines.
Disinformation, fear as a policy tool and resulting mass hysteria is our state. We need to move to a collective coping footing.
Let’s be honest. None of us really know or understand …yet we are all strangely willing to panic as instructed. This is a dark time…and covid isn’t the darkest thing. There’s some sign the media is becoming a little more questioning. My hope is that good deep dive mainstream journalism starts digging in. I believe we have become covidiots (and sort of subconsciously know it) and need an escape route and some people/processes to blame
So far, the official stats show covid cases have spiked to levels notably higher than last winter. So it seems, as reported, Omicron is highly infectious. The stats on hospitalisations are quite flat. Of course, this is a lagged statistic, but there are some tentative signs Omicron might be less lethal. The fear from the government is the Omicron spike is so large, it swamps the NHS regardless, and HMG is seen by the public not to have taken necessary action, in the face of European action on lockdowns.
The virus will propagate regardless, looks like a large percentage of the population will come in contact with it. What that means, is those with vulnerability, will sadly pass away, but with each wave, the population is becoming more resistant. I recall seeing a chart of the Spanish flu which came in four deadly waves from 1918 - 1920 then evolved into a more benign seasonal flu.
I also suspect, this winter the general populations of the western world will have become covid lockdown weary. Many states in America will largely ignore any new measures anyway. In the UK, the government is split between two groups, supporting either no lockdowns or prioritise public health at all costs. Also, public finances would struggle with another round of covid support, the country is up to its eyeballs in debt.
As for your dystopian points, yes, governments have long favoured big national events. It tends to divert the media from domestic issues like the rising cost of living.
As an investor, I'm thinking this winter is the last, or at least second last round. So, I suspect we are getting close to peak gloom on retail, F&B stocks. I bought a few yesterday, bottom fishing. I've noticed the US financial press is more focused on inflation and interest rates now than covid. These are bigger drivers for equity valuations 18 months out.
All seems reasonable jwebster. May not be right and I don’t believe we will have persistent high inflation even tho energy pressure likely persists as we have orientation that discourages more hydrocarbon as we have a magical (hysterical!) view that we can just magically replace it’s importance v rapidly. But could be right. I’m in minority believing we haven’t set scene for persistent inflation.
But I enjoyed the non-hysteria based view. If we carry on with ‘hammer and dance’ we’ll collectively suffocate ourselves. This is darkness. Ongoing self harm that will become chronic if not stopped. Fear and paranoia rather hope and confidence. I feel optimistic that we’ll come to our senses.
But I’ve been wrong re trajectory of covid stuff since the start so maybe I need to just adjust to fear based living like my fellow countrymen. My 3 nights out to pub in last week should probably be fined…maybe a short custodial sentence
In Italy all you need for the title “Dottore” or Dr, is a standard 3 year degree!
Sopheon SPE looks hopelessly overpriced conversion to SaaS or no. There are a lot of very small listed software companies in the UK but this model change is really only about getting customers to commit to a 2-3 year payment deal, isn't it? One accepts that this reduces initial revenues as the change takes place and produces a steadier income stream but it is not a bullet-proof one. Customers can still drop you if they get a better product down the line so rollover is one simple good indicator. There surely needs to be something very special to justify this price, a probable overseas breakthrough, tob candidacy due to a unique product or indeed a new potential maket. What am I missing?
What are your thoughts on Boohoo Paul. Its starting to look a bargain I think.
There's a separate thread on Boohoo (LON:BOO) (I hold) here, which myself & other members here have posted our thoughts recently.
The short version is: I can see why it's fallen, because revenues in EU & USA have declined, but UK is still growing strongly. I think it's dropped far too much, so am buying more.
P.
The trouble with John Campbell is he talks as if he is qualified to interpret COVID results/data from different sources, compare these and reach appropriate conclusions. He isn’t.
It is not that the sources are poor. And it is not that he doesn’t identify them because he does.
The problem is that we cannot rely on his understanding and comparisons of that information. His intentions are most likely honourable but I would give him a wide berth.
Speaking as someone with a BSc, I also think that he should introduce his videos with a clear statement that he is not a qualified medical doctor, as referring to yourself as Dr in this context is potentially misleading.
Springfield - look closely at Springfield’s operating margins, about the worst in the sector.
you may say that house builder margins in general seem high compared to the wider market, but they need to be, house builders have money tied up for years in their land banks.
Springfield would be vulnerable in any future downturn with their margins, certainly the low hanging fruit if conditions become tough,
Spring field have also issued additional shares over the past 4 years, equivalent to a 25% increase in shares, merrily diluting down shareholders along the way. This is not the picture of North of the border thriftyness and prudence tha was described.
On the two negative points Paul raises on Royal Mail (LON:RMG) (I hold), I have taken some comfort from the following:
Wages: On the interim results video call, management said that wage pressures were probably affecting their competitors more than them. This sounded plausible to me as most Royal Mail staff are on permanent contracts with comparatively good terms - competitors are using more contract staff and here is probably where there is the greatest demand for labour. Competitors might find they have to offer terms and conditions similar to Royal Mail to retain staff.
Pensions: There are several schemes, some small some large, and the company are adding new schemes. But clearly the key scheme is the RMPP - which has over £8bn in liabilities. But there is a large (£2.4bn post tax) accounting surplus on this scheme (as well as a much smaller actuarial surplus). This gives some comfort. But trying not to get into the nitty gritty, in November the company announced a £400m return of capital (£200m as special div and £200m as share buy-backs) without having to give any commitment or inject any money into any of the pension schemes - as far as I could see. I took from this that the pension trustees are not concerned by the solvency of their schemes.
The key going forward will be whether the defined benefit pension schemes (which are all UK schemes) are any impediment to any possible future demerger of GLS, which I believe would be positive for the share price.
Of course, it needs to be said that the £2.4bn "pension asset" shown on the balance sheet is not really an asset - and can not be used by the company. This makes up half of the net assets of the company and therefore the low price to book value of Royal Mail (LON:RMG) is a mirage.
There are clearly a lot of negatives (strong unions, poor historical labour relations, structural inefficiencies, declining letter business, the burden of the Universal Service Obligation, potential political interference, uncertainty about reading trends through Covid etc etc). But there are always a barrel of negatives when you buy a stock on a single digit P/E multiple. What has attracted me to Royal Mail is that for a low P/E stock there are also a significant list of positives:
* parcel delivery is a growth market, well-tuned into ecommerce and GLS is 100% parcels and for the Royal Mail's UK business, parcels are now more significant than letters.
* income investors who would have dumped the stock when the dividend was suspended are probably now looking to buy back into the stock.
* There is a lot of long-hanging fruit on increasing efficiency on parcel sorting - and the two new parcel hubs should bring Royal Mail parcel sorting efficiency uptowards those of its competitors.
* The CWU is saying that management/ union relations are the best they have been for a long time.
* May be the future will see a value creating demerger of GLS.
* Given the financial boost earlier lockdowns gave Royal Mail, if Omicron turns out nasty then Royal Mail may be expected to benefit again.
There was an interesting FT article at the weekend about the recruitment challenges for the delivery companies. https://www.ft.com/content/038...
Letter delivery is described as Royal Mail's legacy business. They still have some way to go transitioning their equipment and working practices to being a parcel business.
Some of the comments below the article are from RMG workers complaining about both overwork and poor union support. They made me wonder if the union has been tamed too much - the risk could be wildcat action.
Morning Paul,
I have been wondering if companies delay publishing announcements on morning like today when markets are likely to fall significantly?
Michael
Hi Michael,
I have been wondering if companies delay publishing announcements on morning like today when markets are likely to fall significantly?
I've never seen any evidence of that. Issuing results & trading updates involves a great deal of work behind the scenes, with company mgt, auditors, brokers, PRs, all being involved. Often it's working to a schedule, so the date for the updates is published beforehand. Hence would only be changed for a more serious reason.
As regards unscheduled trading updates, I think the AIM rules are that companies have to inform the market immediately they become aware of trading behind expectations, which is what gives rise to the dreaded intra-day bombshell announcements.
So overall, I think your suspicion is probably unfounded. It might occur at the spivviest micro caps, possibly, but apart from that I've never seen any evidence that announcements are timed for market up days.
Regards, Paul.
Thanks Paul.
talking of RNS bombshells, Friday after hours RNS advising shortage of cash has truly sunk Deepmatter (LON:DMTR) today (I hold but not optimistically).
Interesting debate raised by the Spectator magazine twitter chat with Chairman of Sage. Apparently J P Morgan spotted that the Sage assumptions were all worse case i.e. that Omicron was as deadly as the original virus. When this was tweaked with some South African based assumption the outcome modelled 33% of hospitalisations of the previous Peak, which are quite manageable.
When queried the Sage Chairman said the worse case assumptions were needed to enable the Govt to make decisions.
There was the usual splenetic outpourings underneath the article assuming bad faith, and worse. I can sort of see where the Chairman was coming from. If the infection rate (R Rate) is high you are into the thick of a potential disaster quite quickly, and so presenting the worst scenario does make sense, but it also does put the pressure on Govt to only look at one scenario, and not examine the trend. It also assists the media in outpourings of doom. I would argue that its the media for better or worse that are having a bigger impact on people's activities.
We've all heard of 'weather bombs' and the like, which are emotionally loaded terms, so we know the way it can go.
Sage Scenarios v actual published in the Spectator.
https://data.spectator.co.uk/c...
But with companies, don't we expect the directors to prepare for the worst and hope for the best?
Well, I certainly don't. I don't expect every company on my watchlist to run around with 10x annual expenses in cash in case the world shuts down. I generally think they should actually make a sensible, probability-weighted estimate of the future using non-biased inputs, and then lean toward a slightly conservative approach to dealing with it. I definitely don't think they should assume that the sun stops shining, every customer stops coming to stores, staff walk out en masse and fuel prices quadruple (i.e., the worst of every scenario) and use only those scenarios as the basis for how they think about the world. That would be pretty unhinged.
It would actually be nice if Govt and companies transparently shared a probalistic range of reasonable best, worst and central case outcomes and key supporting assumptions. Instead we are treated like children who cannot be trusted. Sunlight is the best disinfectant and all that. (It also becomes a problem when the 'daddy' figure in this centralised no longer has personal credibility)
Such approach would lead to an open discussion about reasonable worst case consequences (firm go bust/millions die) which tells you how much insurance (conservativism with a small c) to put in place.
On this basis, the reasonable worst case might be millions get infected concurrently, thousands hospitalised, NHS over whelmed, thousands die unnecessarily. This seems pretty bad so firm action is required.
What of course is worse is in investment terms is to spend billions over a couple of years to not solve problems or have solutions in place for problems that are quite likely to come up and which would regardless leave a legacy regardless eg in P18M, trained thousands to do injections, have vaccine production facilities built established novel track n trace systems (geo tag bracelets, etc etc)
Regardless of underlying politics, current administration have not proved very competent managers. Time for a new Mgt team, even if under the same owners? (Disc. I would prefer an activist takeover and change of underlying political strategy :)
Integrated Diagnostics Holdings (LON:IDHC) are moving into Pakistan:
IDH to acquire Evercare Group's 50% stake in Islamabad Diagnostic Centre
(IDC), a leading provider in the fast-growing Pakistani market.
The acquisition will see IDH expand its presence into a highly attractive
market in South Asia with a favourable demographic profile, and gain a stake
in one of Pakistan's largest, most respected, and fastest growing integrated
diagnostics companies
This fits in with the half-year report in September, when they said "we continue to assess potential growth opportunities across new African, Middle Eastern, and Asian markets".
Let's hope they manage the growth well - they have a hub-and-spoke model that's worked so far.
(I hold)
Innovaderma (LON:IDP) snuck an RNS out after 8am with their much delayed final results for the year ending 30 June.
Results are in line. New management putting their mark on the business highlighting the focus on skinny tan and improvements in gross margin from a refreshed pricing model.
There is a note out from Finncap as well who havent changed any of their forecasts and maintain their 90p target.
At what age should we stop believing in Santa's rally?
Clearly we've all been bad boys and girls this year. I am just holding and keeping my nerves at the moment unless the fundamentals on anything I hold changes. I do have some money sitting on the sidelines which I am thinking of moving into some trackers funds at some point (as I want to be able to sleep at night and these will de-risk a bit my portfolio) but I just don't think its certain whats going to happen.
A reduction in cases in Jan and a much milder Omicron is just as likely as everything shutting down and being overwhelmed. Until that becomes clearer I'll do nothing
About 5?
John Campbell is not a medical doctor. He has a PhD in nursing. He has I believe perpetuated the Ivermectin as a treatment untruths. I follow people like @jamesward73 a mathematician who also retweets many of the epidemiologists and other mathematicians I follow. I don't predict where we are going, but a very big number of mild infections can still cause the resulting smaller number of serious infections to overwhelm the NHS as there will also be huge staff absence too. Also, the average age in South Africa is 28 therefore UK risk is 4 times higher approximately.
Yes, let's follow the data modellers and mathematicians.....
Yes, Mr Campbell has a PhD in Psychology rather than nursing…..so thats useful….. Nonetheless his channel is good but he needs to drop the pretend “Dr”. South Africa does have a different demographic and they are in summer but they are still having a much easier time than previous waves with obviously the same demographic as before. (But also increased natural immunity) It’s the massive, self inflicted staff shortages that are going to be an major issue here I’m guessing.
Yes, Mr Campbell has a PhD in Psychology rather than nursing
No he doesn't. He says on his YouTube About tab that
My PhD focused on the development of open learning resources for nurses nationally and internationally.
Think we are both wrong, his phd is in philosophy he got from Bolton Uni 2013 so that’s good……According to LinkedIn anyway
No, I'm not wrong. This is from his LinkedIn page.
At last, Iain1234, well done. Someone has finally mntioned that in S Africa it is actually summertime!!!!!! and its winter here....... and the population density of Africa is far far less than the N hemisphere and Europe especially.......so much more rural living and outdoor living? Huge generalizations I know but huge differences too.
I can assure you that holding a PhD does not equate to being a "pretend Dr".
Yes indeed, Campbell has talked about the S.African situation in detail, including the point about a much younger population than the UK. Hence why he's always said we don't yet know what the impact is going to be in the UK from omicron.
If you follow Campbell, you'll find he's very well balanced, and provides sources. His followers know his qualifications, as he's very open about that.
Of course, as with anyone who puts themselves out there daily, and tries to give clear analysis, there will always be detractors, it goes with the territory unfortunately!
P.
As a long term follower of Campbell, I completely agree Paul. He doesn't pretend to be something he isn't and he also has interesting and well-informed guests, for example: https://youtu.be/w9h-XQm2qEY
There may be no statistical proof (yet) but anecdotally in my own family there is something in this advice!
South Africa may have a much younger population but it also has extremely high rates of HIV, thus a immuno-suppressed population, so it is not simply a case of age. I have a lot of family in SA, the majority of whom have now had covid over the past 3 weeks, and thankfully all of them are absolutely fine.
I think the salient point is right there Paul- we do not know, yet, what the effect of Omicron will be on our population. So whoever you listen to is not dealing from a full deck, and it's merely hypothetical opinions on possibilities with scant data as back-up. This in my view is unnecessary and can be wildly misleading. All I know is that we are hearing of many, many more contacts going down with this variant and indeed suffering more than the 'mild symptoms' being mooted. So stay out of the crowds and hunker down until we get the 2 week sharp lockdown which I think will hit after Xmas.
I think the salient point is right there Paul- we do not know, yet
Exactly. And that's the point of modelling, and why it's easy for the Spectator to pick a one or two preditctions from months ago and say "look how wrong they are". Faced with a new conditions you can either say - lets do nothing till it's entirely clear what happened, by which time it may well be too late to stop many deaths and overloaded ITUs. Or try and model as best as possible from available data to look at the sort of range of outcomes that could occur. No one claims models are what's going to happen, they are trying to get a handle on what might happen. That may mean at times recommending actions that later prove to have been more than needed. But that may also turn out to be a better option than waiting to see, and letting it happen.
What is increasingly clear is that Omicron spreads much more quickly than delta. We also know that the SA population is very different to the UK population, in demographics, prior exposure, vaccinations etc. So it's hard to compare. But it is clear that covid hopsitalisations are rising fast in London, currently the main site of Omicron infections, up 33% in the week to the 17th, so still very early in the spread of the variant. And that even if Omicron causes only 25% of the severe illness of Delta, far from clear at the moment, then given the much higher transmission rates, hospitals are likely to face record levels of admissions.
So, yes, we don't know for sure what's going to happen, or how bad it will be, but it would unwise to ignore those trying gauge that, and not to show some caution until it does become clearer.
crikey - the problem here is that modellers and mathematicians pick which models they want to use. Case in point - you say the average age in SA is 28 therefore we are 4 times higher risk. That is complete rubbish and is a classic case of picking the part in the data that you want to use to form your argument. For example it completely ignores that our vaccination rates are significantly higher for example.
The modellers have already admitted to not using real world data in their forecasts - why? because it doesn't suit the narrative. And if people obfuscate data then you have to ask the question - why?
here is a link to an interesting article on the "modellers" in the Telegraph yesterday.
https://www.telegraph.co.uk/op...
Age segmented data is available from South Africa I think so modellers could use that as a proxy rather than keeping up the pretence that nothing that happened in South Africa applies to here
I'd be fairly wary of following one or two specific data modellers and believing in their predictions. I would put many of the epidemiology models into the same category as economic models; unreliable to the point of being often counterproductive, because they give false confidence in outcomes. Many of these models are far too complex and sensitive to slight changes in input data or assumptions to produce meaningful results. We can't possibly know enough about the dynamics of omicron to produce accurate models yet. So while these models are probably interesting from a research academic perspective I doubt they have much practical usability. The only certainty is people will always be paid to produce questionable models.
Campbell is not a doctor of medicine, he has a PhD, styling himself Dr is a ruse to dupe the gullible into following his youtube channel by conferring a spurious air of authority.
I did watch some of his videos in early 2020 but he rapidly went off the rails, presumably enticed by the revenue possibilities of appealing to as many people as possible. He has now gone further off the rails by pandering to anti-vaxxers.
His statistical 'analysis' has been widely debunked by statisticians and I have long dismissed him as an attention seeking windbag. If you want to know what is going on with covid follow statisticians, epidemiologists and medical scientists not some self regarding nurse trainer who is overly fond of the sound of his own voice
I don't know Campbell - he is not anyone I follow, so I have no opinion on him. But I do know that what you actually should do is overlay real world data on to other statistical models and see how they compare and behave and show that data to the public. What you shouldn't do is build statistical models with theoretical ranges and missing characteristics that suit your narrative and then use those models to sell a message to the public!!
Unfortunately, there are lots of people who would rather listen to someone who is not trained but speaks well than to someone who is trained. What's wrong with listening to government advisers? Or maybe the experts don't know what they're talking about.
If we took a hypothetical but perfectly possible scenario where in a few weeks it becomes clear there has been a global overreaction towards Omicron (the South Africans seem to think so), what stocks and sectors do people think would benefit the most and quickest?
I get as far as the obvious ones – restaurants Restaurant (LON:RTN), Fulham Shore (LON:FUL), nightclubs and bars Revolution Bars (LON:RBG), Nightcap (LON:NGHT), travel Saga (LON:SAGA), £OTB.
Hi Rogerh
"If we took a hypothetical but perfectly possible scenario where in a few weeks it becomes clear there has been a global overreaction towards Omicron (the South Africans seem to think so), what stocks and sectors do people think would benefit the most and quickest?"
This is an excellent question.
Specifically to Revolution Bars (LON:RBG) , which I used to hold, unfortunately Omicron appeared right before its most profitable period. So even if things "normalise" quite rapidly, it's too late.
Looking at their last presentation they were already down to 0% LFL growth vs 2019, and I imagine that December will show a negative LFL vs 2019.
I personally wonder therefore why I would hold now? Why not wait until later in the year when there's at least more certainty?
Off the top of my head the same applies for UK-based companies that sell occasion-wear...it's just too late to reap the usual winter-season profits.
---
A quick skim through my own holdings:
There's probably a few more of my holdings that would be positively impacted by a return to pre-Omicron trends, but those are the 2 that immediately stand out.
I'd certainly be interested in hearing thoughts on other possible quick-recovery companies.
Cheers
A
Hi Abtan,
Thanks for your comment. Thanks also for your earlier reply on European stocks.
I bought into Revolution Bars fairly recently and am certainly guilty of hoping they might squeeze up a little more. I'm not sure how young people, not being one, are behaving as regards going out at night.
Re Air Partner (LON:AIR) I can never make my mind up about this stock but certainly wish I had bought it last year when it was knocked down indiscriminately with all the other airline stocks. Do you mean they would lay on lots of private ski flights for wealthy skiers? That's an interesting thought.
Hi Rogerh
As per their website they have access to over 7,000 aircraft.
Given that France just banned non-essential UK-based travellers, I imagine that there will be pent up ski demand in Jan/Feb IF the borders re-open.
I should add that I hold irrespective of this possibility.
Cheers
A
Hi Abtan,
You're very far from being muddled. I wish I could research and analyse shares as well as you.
Yes, my son ordered a bed which arrived a couple of months ago. Unfortunately part of it was damaged. They can't send out replacement parts so he was offered either a refund or a new bed. He opted for a new bed, which should arrive around February. It has been delayed because of the supply chain issues.
We both sold out of our Made shares at a significant loss a few weeks later. I remember you doing a very comprehensive analysis of Made some time back. Perhaps it will indeed come good in the end.
Thanks for the Revolution Bars video. It seems a nightmare for them.
Hi Rogerh
That's a very kind comment. Sadly all the research and analysis I've done hasn't prevented me from slipping into the red this year :(
Thank you for sharing your experience with Made.com (LON:MADE) and sorry to hear about the loss. It's certainly been a difficult period for the company.
Fingers crossed for profitable holdings for both of us going forward.
Cheers
A
If you believe that then I'd suggest you go and read the article in the Telegraph on the models and how they are manipulated.
There is nothing wrong with listening to advisors but you would be wise to question and interrogate their rhetoric and reason rather than take it at face value. What you should remember is that in this day and age you are always being "messaged". Thinktanks employ senior psychologists to work out what messaging needs to be conveyed in the media to drive behaviour. Models are build around narrative and messaging.
"There is nothing wrong with listening to advisors but you would be wise
to question and interrogate their rhetoric and reason rather than take
it at face value"
You can take that line with any Youtube expert as well. They all have their own agenda. I still think the government expert's agenda is to reduce the burden on the NHS. Other people's agenda is to remove all restrictions and ignored covid altogether, and then you have people in between.
Also why should I believe what the Telegraph has written, I don't actually read newspapers because the stories are just one person's opinion.
I agree - I don't countenance any Youtube expert either.
You say you should listen to government advisors - have you seen their track record of modelling predictions? it is vastly pessimistic and woeful, but when policy and messaging is created around such flawed models the public should question it rather than take it at face value in my opinion.
The rationale for reading the article in the Telegraph is because it relays an impromptu Q&A with a SAGE modeller who answers questions as to what goes into their models. You don't have to believe in anything but given the person being quoted it should make you think!
The Government experts agenda may well be to reduce the NHS burden in the short term I tend to agree, but at the cost of everything else and that really isn't their job to create policy. But using theoretical data that has been proven to be too pessimistic whilst simultaneously ignoring real world data to do so can have major societal implications down the line.
epo001,
You're entitled to your opinion of course, but I don't recognise anything of your accusations against Campbell. People with a Phd are entitled to call themselves Dr. I don't agree with that, but it's the way things are. There's no deception involved at all, if someone with a Phd calls themself Dr, they're allowed to.
I've not seen him pander to anti-vaxxers whatsoever, quite the opposite.
He just presents facts & figures from reliable sources - e.g. this week a Cambridge Uni study, and reliable sources in Hong Kong and S.Africa. He shows the sources, so you can check them directly if you wish.
His statistical 'analysis' has been widely debunked by statisticians...
Can you provide a link to back up that statement please?
Also, I've not seen him doing any statistical analysis, he just summarises important data & reports from good sources, worldwide.
Meanwhile the mainstream media is full of muddled, sensationalist/alarmist stories, concocted by journalists who haven't got a clue about the facts. Therefore someone like Dr Campbell, is a welcome source of unbiased information for laypeople such as us.
I've learned a lot from his videos, and I can see that he's not pushing any particular agenda, he's just trying to give us the facts, in an unbiased way. He frequently says things like, it's too soon to know for sure, this could happen, etc, or it might not, let's wait for more data, etc.
Paul.
People with a Phd are entitled to call themselves Dr. I don't agree with that, but it's the way things are. There's no deception involved at all, if someone with a Phd calls themself Dr, they're allowed to.
There's an old "joke":
"So I understand you're a doctor?"
"Yes, but I'm not the kind that will do you any good."
timarr
Yes, and a PhD is a "Doctor of Philosophy" whereas most medical doctors in the UK have Batchelor's degrees (MB/BS) and to distinguish themselves from medics, the surgeons call themselves "Mister" (what do female surgeons call themselves?). It inevitably leads to confusion, but it would be wrong to infer deliberate deceit.
The lady surgeons are Miss/Ms./Mrs.
I've noticed that dental surgeons have switched to calling themselves Doctor. It's all a mess:
https://www.ncbi.nlm.nih.gov/p...
Thanks for this Paul. For anyone interested in the definition 'doctor', please see eg https://en.wikipedia.org/wiki/Doctor_(title)
John Campbell is fully within his rights to call himself Dr Campbell. In my experience, most people who've grafted to obtain a PhD do so.
John Campbell is fully within his rights to call himself Dr Campbell. In my experience, most people who've grafted to obtain a PhD do so.
This is true, although it is discretionary. It's also different in different countries. In the Netherlands the term doctor is legally reserved for people with PhDs - i.e. they're not medial doctors. In France you'd expect someone calling themselves "doctor" to be a medical professional. In Italy you'll get a mix.
Really, if you're offering medical information you need to be clear that your doctorate isn't in medicine. In this case it would be wiser if he dropped the "Doctor" at the beginning and added "PhD. " at the end. But it's his choice. Just recognise that he's an intelligent layman, not a trained medical researcher and treat his views as a first port of call rather than the last word.
Of course, as we know, on the internet everyone always checks primary sources ...
timarr
I used to use the title when I was a lecturer, it was also effectively a title that went with the job. Students expected to address you as Dr. However, I rarely used it otherwise, and not since I retired. I remember being advised early in my career not to have it on my passport, as it could lead to emabarrasment if another passenger on a flight needed uregent attention, and your name came up on the passenger list.
But Dr. Campbell isn't a layman. His qualifications and experience are in medical training for nurses. He has written standard textbooks to that end.
If I fell ill on a plane I definitely would want his help. So would most doctors, medical or otherwise.
His qualifications and experience are in medical training for nurses. He has written standard textbooks to that end.
Quite.
timarr
One point nobody seems to make is South Africa is heading into Summer, when people spend a lot of time outdoors, we are heading into Winter where reverse is true.
I feel with combination of their younger age and lifestyle we could be in for a worse impact from omicron.
According to Brian May though, and if he does have Omicron, he says he is feeling “truly horrible” and that it’s like “the worst flu you can imagine”:
Brian May ‘perhaps made the wrong decision’ to attend birthday gathering where he may have caught Covid-19 (msn.com)
Queen's Brian May reveals that he has tested positive for COVID-19: 'A truly horrible few days' | Daily Mail Online
if it’s that bad he’s most probably got the original covid19.
I guess he wants to break free - but the show must go on. Don't stop me now. :-)
As long as it’s not, another one bites the dust…
I'm sure i heard on the Radio that he's very unlikely to go Ga Ga
Better not be a Killer Queen
"The study finds no evidence of Omicron having lower severity than Delta,
judged by either the proportion of people testing positive who report
symptoms, or by the proportion of cases seeking hospital care after
infection".
https://www.imperial.ac.uk/new...
It's interesting that you copied that paragraph but specifically chose to omit its final sentence: "However, hospitalisation data remains very limited at this time."
Brian May -"He said he is feeling “truly horrible” and that it’s like “the worst flu you can imagine” before revealing how he believes he caught it.
He's clearly never had "the worst flu imaginable"
I had an awful bout of the flu almost 20 years ago and it would have been impossible for me to spend time on Instagram telling everyone. Could barely move. There's so much exaggeration these days with social media.
It's a long time since I had a bad case of the flu (touch wood) but when I did there was no way I was feeling well enough to be talking to journalists!
Hi Roger,
I can remember getting flu every year at Xmas, when I was in my late 20s, and really burning the candle at both ends & in the middle, working long hours under intense stress, then partying hard all weekend. It seemed that whenever I stopped (at Xmas) I immediately came down with flu.
So I do think that modern, highly pressurised, busy lifestyles and lack of sleep, make us more vulnerable to bugs.
Dr Campbell (if I'm allowed to mention him again) stresses that the following are proven to enhance our immune systems -
I'm a huge fan of the restorative power of sleep, and I've not had flu for about 25 years, which must be at least partly due to working from home since 2002, and taking naps whenever I feel a bit tired, or have a sore throat.
All pretty obvious really.
Regards, Paul.
My Dad swore by Chicken soup to ward off flu, which seem to work until when in a care home with emphysema he caught a cold off his main nurse. He was dead two days later.
Wot? No Gore Street Energy Storage half year results! : )
That said,. Keep up the excellent work Mr C. Much appreciated and thank you!