Small Cap Value Report (Mon 20 July 2020) - BOWL, VLG, INS, TUNG, OPTI, PTD

Good morning, it's Paul here with the SCVR for Monday.
I hear from CNBC that the average American has put on 16ibs during lockdown. I can quite believe the same might be true here. Certainly, basking in the sun on Friday afternoon, I caught a glimpse of myself reflected in the window, and it reminded me of a documentary about a mudslide that had engulfed a whole village. Time to do some sit-ups, methinks!
There was some weak economic data in the US on Friday, with flash consumer confidence numbers coming in well below expectations, and importantly below June's numbers. That's not consistent with the V-shaped recovery that the stock market has priced-in. Combine that with a dearth of guidance from companies, and I remain cautious, and have shorted the US indices again, just as some downside protection. After all, if companies are not putting out guidance, then it doesn't suggest things are going well, does it?
On the upside, news on treatments/vaccines sounds promising, and the wall of money thrown at the markets is artificially propping up everything very well, for now. We'll see what happens with US earnings season this week, as that obviously sets the tone for UK markets too. Netflix results were interesting last week, as the stock dropped sharply - not on the numbers, but on soft expectations for Q3 and beyond. Are things priced to perfection? Some seem to be.
Whereas UK small caps generally seem quite cheap still. No sign of any euphoric bulls over here.
On to today's RNS. Not much news today in the samll caps world, so estimated timings - should be complete well before 1pm official finish time.
Update at 13:45 - today's report is now finished.
.
Hollywood Bowl (LON:BOWL)
Share price: 158p
No. shares: 157.5m
Market cap: £248.9m
Hollywood Bowl Group plc ("Hollywood Bowl" or the "Group"), the UK's market leading ten-pin bowling operator, announces that following the Government's announcement on 17 July 2020, it will reopen all of its English centres on 1 August 2020.
Pre-booking has started already, as you can see from its website here.
COVID-secure operating measures are being put in place. It will be interesting to see how this pans out. A number of members here left negative comments about the idea of going bowling, pointing out that putting your fingers into bowling balls that have been mauled by thousands of other people, repels you. I can understand that point of view, but isn't there a simple solution - just wear disposable latex gloves when you're handling the bowling balls. Then take them off to eat/drink. What's the problem with that? If combined with hand-washing stations, sanitiser, etc, I could see that working fine. Especially as bowling alleys are large spaces, where it's fairly easy to space people out.
My main concern (which applies to most of the hospitality sector) is that spacing people out, and measures to control them, could result in reduced revenues, combined with extra costs. Still, I suppose the aim is to get business moving again, and providing it can operate at above cash breakeven, then it's successfully treading water until covid is under control or eliminated. Then logically, the valuation should eventually return to pre-covid levels, giving a decent profit to people who buy now.
BOWL strengthened its balance sheet in April, with a fundraising of £10,5m after fees. That was only about 5% dilution, and was done at 145p.
My opinion - it depends on your view about how long covid is likely to be around, and the big risk of course is a second wave, and renewed lockdowns in the autumn/winter.
Annoyingly, I had to cut my position in BOWL because of a margin call, but want to buy back in when spare funds crop up. I've still got a long position in smaller rival Ten Entertainment (LON:TEG) .
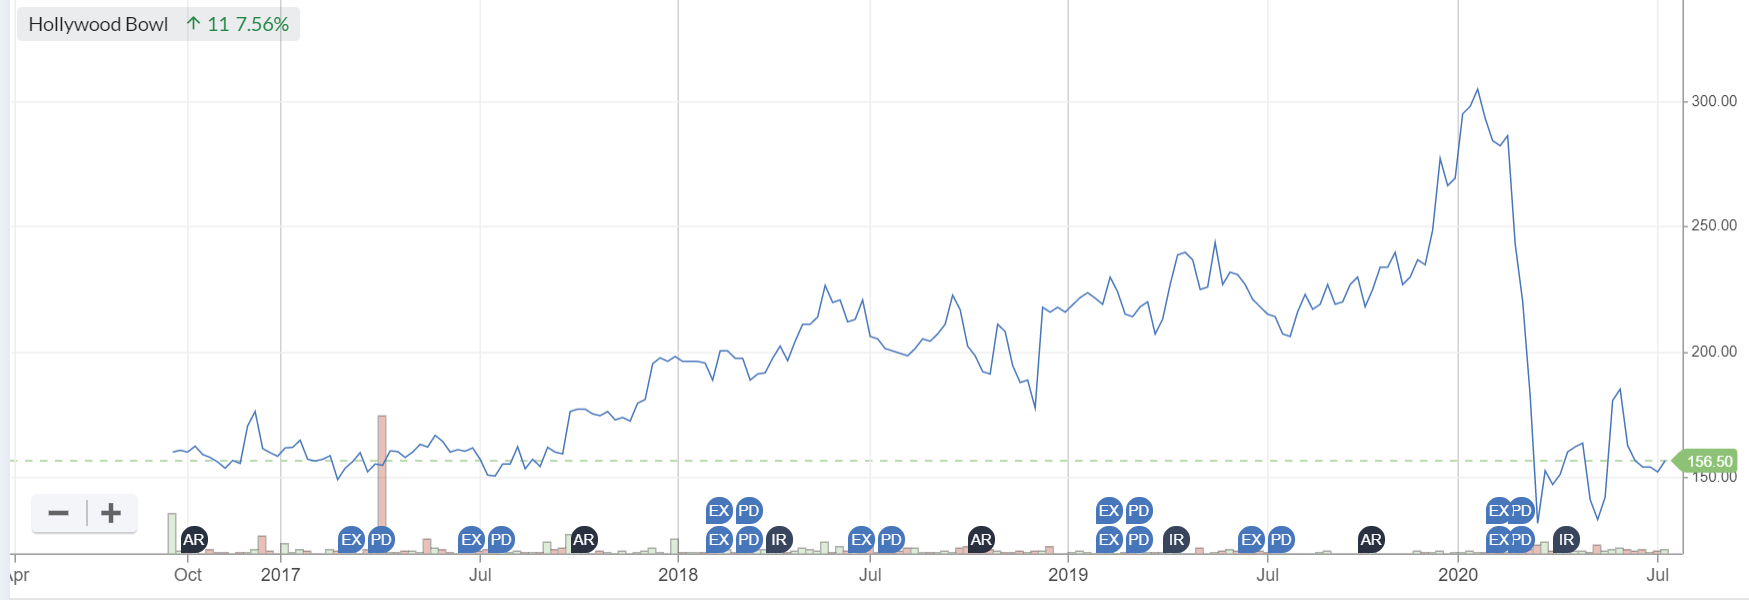
My feeling is that for every person who's terrified by covid, there's another that is itching to get back to normal - which probably should be enough to get BOWL moving again at a sufficient level of trading to cover its costs. I'm guessing there, obviously. Time will tell. For anyone who can look beyond covid, the chart suggests there could be 50% upside here maybe? Plus in due course, divis could resume, which is increasingly important at a time when yield is hard to find. Overall then, I'm positive with a long-term view. Unsure with a short-term view.
.
.
Venture Life (LON:VLG)
Share price: 86p (up 19% today)
No. shares: 83.7m
Market cap: £72.0m
Venture Life Group plc (AIM: VLG), a leader in developing, manufacturing and commercialising products for the international self-care market, provides an update on its performance for the six months to 30 June 2020, after a period of strong trading.
I've only looked at this share once, here on 9 June 2020, where I came away with a very positive impression. Thanks to members here who flagged up the company.
Edited highlights;
· Revenues increased 80% to £16.9 million (H1 2019: £9.4 million)
· 65% from organic growth and 15% from acquired growth
Those are pretty stunning figures.
With our strong balance sheet we continue to explore additive M&A opportunities using our existing cash resources and available debt finance alone.
That's important, as it means management is not intending to issue new shares for acquisitions. As long as they don't over-cook it with debt, then that should reassure existing shareholders.
There's more detail on operational highlights, which all sounds impressive, albeit mostly reiterating previous announcements.
My opinion - this looks a terrific little company, that has achieved a stunning increase in business this year, after years of lacklustre performance.
I'd be really interested to hear from any subscribers here who know the company well, whether you spotted early signs of this major turnaround, and what were they? I don't know what the company's background is. Were new management brought in? Good acquisitions?
Today's update doesn't say anything about performance versus expectations, so we should assume it's in line.
There's an update note today, available on Research Tree. adj EPS for FY 12/2020 is 5.4p, which is said to be conservative - i.e. upside potential on that number. At 86p, the PER is 15.9, but that could be lower if the forecast is exceeded, which is hinted at.
Providing this great improvement in performance is sustainable, then this share still looks decent value to me. A very large contract with a Chinese customer is not ideal, given escalating tensions with China.
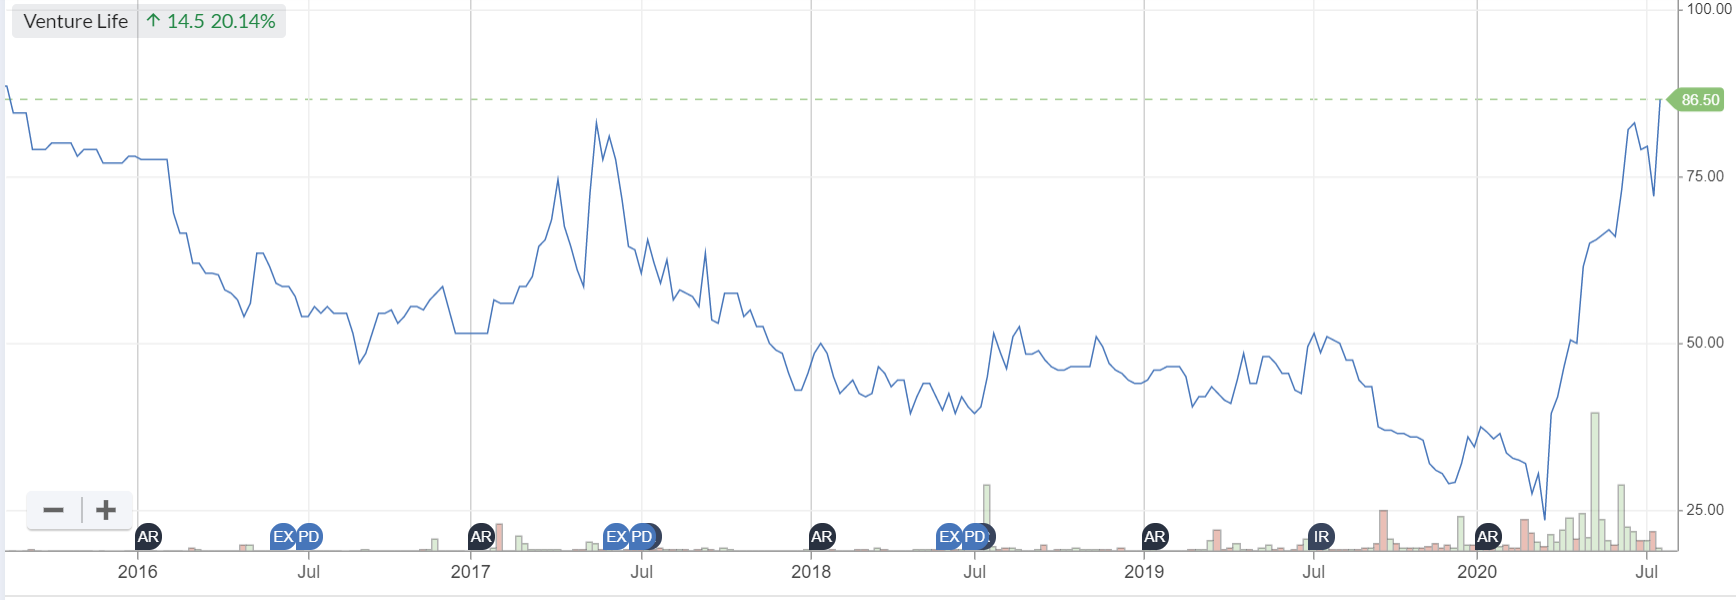
The chart below shows how 5 years of drift was rapidly recouped this year;
.
.
Instem (LON:INS)
Share price: 454p (unchanged)
No. shares: 16.67m
Market cap: £75.7m
Instem plc (AIM: INS), a leading provider of IT solutions to the global life sciences market, is pleased to announce a trading update for the six months to 30 June 2020 (the "Period").
Subscriber Michael Tee flagged this share in the comments section below, providing a nice summary of the share, which got me interested, so I'll take a look at its update today.
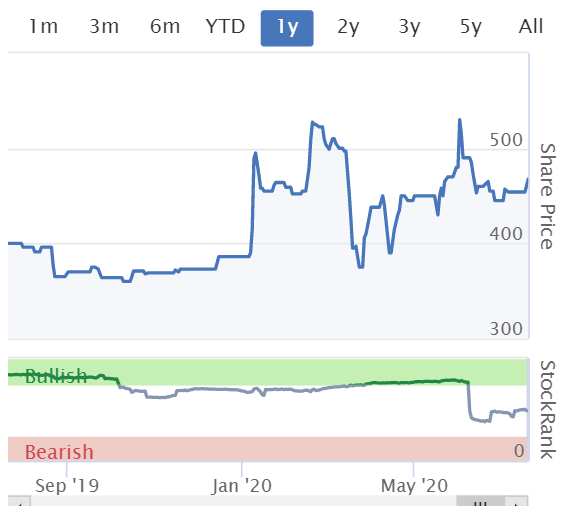
Refreshing my memory, my notes here on 13 Jan 2020, I liked the look of the company, which traded well in 2019. Although it had just shot up on a magazine tip to 490p. We're about 10% lower than that today, after covid of course.
This is all nice and clear, and sounds good;
The Company continued to perform well across all areas of the business despite the wider backdrop and macro impact of COVID-19.
Trading for the Period was in line with the Board's expectations.
H1 2020 revenues increased by approximately 20% with like-for-like revenue growth (excluding the Leadscope acquisition in November 2019) of approximately 12%.
Operational cash generation was strong, with a closing cash balance at 30 June 2020 of £9.1m (30 June 2019: £6.0m).
That all sounds excellent, especially considering that we're going through a massively disrupted economic & public health crisis.
Fundraising -
The oversubscribed £15.75m fundraise (£15m net of expenses), as approved by shareholders on 16 July 2020 and completed post period-end, provides significant capital to accelerate the Group's acquisition strategy, with a number of potential compelling opportunities for bolt on acquisitions and more substantial targets having been identified.
This recent equity raise was at 435p per share. Note also that Directors sold £3.0m of shares at the same time - not exactly a ringing endorsement, so that's an amber flag for me. If the future was wildly exciting, then surely Directors would be holding onto their shares for dear life?
This got me wondering, why did it raise fresh equity earlier this year, if the balance sheet was already loaded with cash?
Balance sheet - the reason is that its 31 Dec 2019 balance sheet wasn't very strong, it actually had negative NTAV of £(1.3m). The company's cash comes from a favourable working capital position, where customers pay up-front. However, given that the company has traded well this year, then the explanation of wanting cash for acquisitions does sound credible.
Outlook - sounds good;
The Company continues to trade in line with the Board's expectations and, given the continued strong organic and acquisitive growth potential, the Board is confident that the Company is well positioned to take advantage of opportunities that arise throughout the remainder of the year and beyond in existing and adjacent markets. With a scalable platform in place and broad portfolio of products and services, the aim is to further grow market share, margins and revenue visibility.
Note how performancce seems to have really shot up this year - so as always, it's key to understand how this has been achieved, and whether it is sustainable, or down to one-offs? That's a generic point, applicable to all shares;
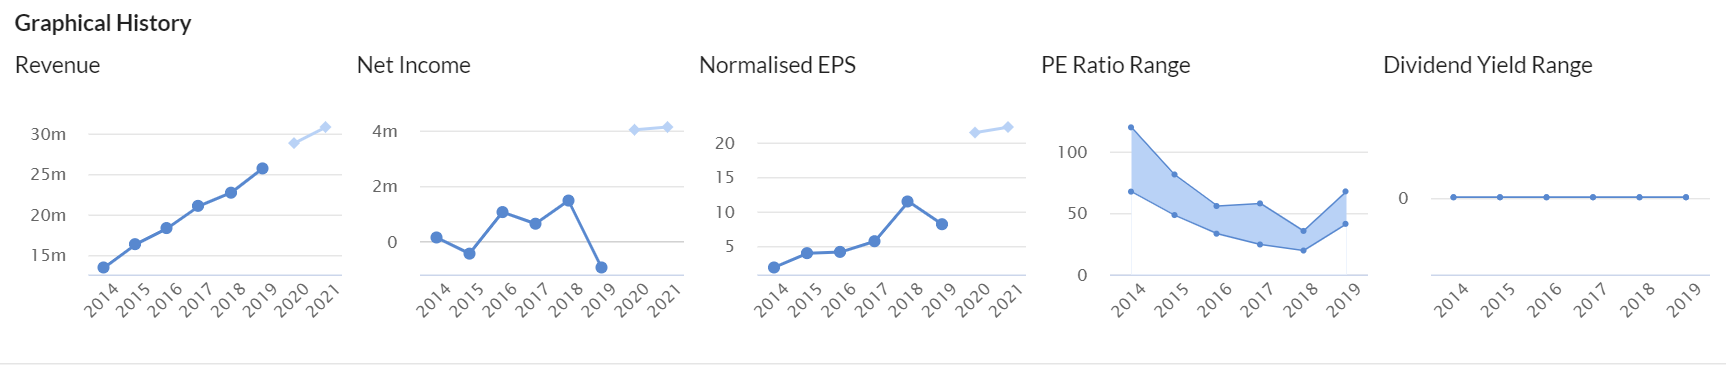
Note also the lack of dividends. Not necessarily a problem, especially for a growth company that can better deploy the capital internally.
Market liquidity - market makers are quoting a ludicrously wide bid/offer spread of 434p/474p, a 40p spread. This deters people from trading the shares, undermining the point of having a listing. The real prices are 438p bid (in 5k shares), 468p offer (in 10 shares), a slightly less bad spread of 30p. Why not qjust publish the real prices, instead of misleading wider prices? I very much dislike this two-tier pricing system (keeping real prices hidden), which seems counter-productive, and rigs the system against private investors. We're forced to use intermediaries that should have disappeared a long time ago.
My opinion - it's rated at about 20 times earnings. Although remember that the cash pile, post fundraising, means it will be able to bolt on more earnings using the cash for acquisitions.
There was a contract dispute mentioned in the last full year results, which could be a fly in the ointment - that would need checking out before buying.
Overall, I think this share looks interesting, and could be worthy of readers taking a closer look. Generating decent organic growth in the current macro situation suggests this is a decent business that could perform better still once economies improve. Please remember that, because of the large number of companies I review here, my views should always be treated as just a quick review of the company. Much more detailed due diligence should always be done before buying anything, as it's quite possible that I might have missed something important.
.
.
Quick fire comments not, on things that don't interest me at all;
Tungsten (LON:TUNG)
42p (up 6%) - mkt cap £52.9m
Trading update for FY 04/2020 - lacklustre revenue growth of 2-3% - good that 93% of revenues are recurring/repeatable, which seems a solid base. Net cash of £3.2m - it looked as if it might go bust a while back, but seems to have stabilised. Adj EBITDA broadly in line with expectations. Profitable in May & June 2020, post year end. Details given of some new contracts/partnerships. Replaced some senior positions. Transaction run rates impacted by covid. Outlook;
We remain comfortable with external forecasts for FY21 on the basis that transaction run rates recover in line with our expectations.
My opinion - for me, this one is too tainted by massively over-promising in the past, and delivering very little. It would need much better growth to get interested again. The key point with this share used to be that it would create a network effect between companies and their suppliers, and finance the supply chain. The financing part seems to have been jettisoned. Therefore it just looks like one of many e-invoicing companies. It doesn't make any profits, so what's the point of it existing, other than to provide employment for staff & Directors?
On the upside, it has sticky revenues with an impressive client list. If it can win new business on top of that, then profits could (eventually) flow. My abiding memory of Tungsten is all the big talk of billions, and trillions, from founder Edi Truell,who wowed everyone with his big talk, and super-self-confident delivery. I was taken in by it, and so were many of the experienced investors I know. It turned out to be largely hot air. The lesson I learned is that "impressive sounding" Directors quite often turn out to be hype. Just because they did something good in the past, doesn't mean their next venture will be any good. Similar sort of things with the mobile phone company fronted by Jimmy Walkes of Wikipedia - that turned out to be hopeless. Give me a down-to-earth, hard-working CEO any day, rather than one that gets everyone hyped up with the vast future potential.
That said, today's update from TUNG does show that it's now viable, and who knows, if they can deliver accelerated sales growth, then it could be work a fresh look. But there's not enough in today's update to make me want to chase up the market cap just on the hope that things might get better in future. So it's not much more than a punt at this stage.
.
Optibiotix Health (LON:OPTI)
55p (up 5%) - mkt cap £48.5m
This follows on nicely from my earlier theme of jam tomorrow companies with promotional CEOs.
a life sciences business developing compounds to tackle obesity, cardiovascular disease and diabetes, provides the following unaudited preliminary revenue figures for the first six months of the financial year and a commercial update.
Revenues are still tiny, at £742k in H1, but the percentage increase look good, at +398% vs LY.
Profit - here's a cunning plan, let's cherry pick a few figures, to make things look good!
We are pleased that these preliminary figures show that each division is making progress against the aim of becoming profitable this year.
The functional fibres division led by Dr Fred Narbel reported a profit during this period,
the ProBiotix division was profitable in three of the six months, [Paul: which ones, what was the trend?]
and the consumer health division was profitable in one of the six months. [Paul: big deal, so it was loss-making in the other 5!]
Spinning off another loss-making part of the business, in order to generate cash from ramping & then selling its shares, is a clever strategy;
The Company also received £747,500 of investment income in this period from the disposal of shares in SkinBioTherapeutics plc which is not included in these figures.
My opinion - I don't care if this triggers the usual wave of abuse from bulls in this share, as always I speak as I find, and keep an open mind if things change. There's nothing in today's update to change my view that this is a jam tomorrow company based largely on hype. I've not seen any convincing evidence that it has any genuine science. From company presentations I've seen, it's generic science talk, and the products strike me as nothing more than hype. Of course people lose weight if they consume fewer calories by substituting one or two meals per day for low calorie shakes. Do the shakes make you feel full? No. So they're no better than drinking a glass of water and swallowing a multivitamin, and feeling hungry for a few hours.
Has there been extensive, and unique scientific research done? No, the company admitted in a videotaped presentation that it just gets university students to come up with the product formulations. Therefore the evidence suggests to me that its products should be seen mainly as marketing gimmicks, used by product manufacturers to appeal to end customers. That's not necessarily a bad thing - look at the yoghurt products with daft names, like Biffidus Activus, etc, which convince people of their magic powers. The trouble is, that needs a big marketing budget. Where's the evidence that any of OPTI's customers have backed its ingredients with big marketing bucks? IF that were to happen, then I could see the appeal of this share.
Cue now, some angry replies, telling me to stick to things I understand!
This share has been listed since Aug 2014, promising jam tomorrow for nearly 6 years now. Yet H1 revenues in 2020 are below £1m. It seems to me that the company is good at signing, and announcing lots of small deals, none of which to date have developed into bigger deals that actually generate material revenues. That does tend to support my scepticism over the company's shares. I suppose there's always a chance it could hit the jackpot, with a blockbuster deal, but 6 years of trying hasn't worked so far. The odds of success must surely be receding somewhat?
.
Pittards (LON:PTD)
39p (down 6%) - mkt cap £5.4m
I didn't realise the market cap had dropped so low, hence this is likely to be my last comment on this share, unless it stages a remarkable recovery in future.
Impact of covid;
This has been significant, with sales running at 45% of previous year's levels. As a consequence, the interim results will show a significant loss.
Debt looks too high;
The Group has however managed the impact on cash through strict cost control measures. At 30th June 2020 borrowings stood at £11.2 million (31 December 2019: £9.8 million).
It does own a freehold, which helps.
My opinion - looks too high risk. An equity fundraising looks inevitable at some stage, and given the poor track record, might have to be done at a big discount. Is it a viable business? Are the costs of maintaining a listing worthwhile? Both are valid questions. For me, it's a very obvious avoid.
All done for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

98 comments
OPTI-some interesting articles below, for some balance and discussion, including a detailed contrast to Pauls review, one also being promoted via Shareprohets.
OptiBiotix Health plc (AIM: OPTI), a life sciences business developing compounds to tackle obesity, high cholesterol, diabetes and skin care announces it has extended the terms of its original manufacturing, supply and profit-sharing agreement with Agropur MSI, LLC (Agropur) as announced on 24 June 2019.....
On Monday 20th July Paul Scott put out another poorly researched hatchet job on OptiBiotix Health Plc (OPTI) and again today in what is nothing more than a rant at the company CEO. Stephen O'Hara - his crime? Having the brass neck to seek to assist Paul Scott in his understanding of the company and address non-factual errors by Paul Scott.
https://lemminginvestors.blogspot.com/2020/07/optibiotix-health-paul-scott-being-bitch.html
Interesting name for a blog - Lemming Investor. Who wants to be one of those?
If the CEO did contact Paul directly, rather than a PR minion, or some such, it's a huge red flag for me. Get your head down and get on with your job mate!! Prove Paul wrong the best way possible by growing revenues and generating profit and positive cashflow.
If I'd held this company (which I have absolutely no interest in based on the fact it is a small healthcare company listed on AIM) I'd have sold on that news alone. Management credibility is a very large factor in my investments. If the CEO can't put his ego to one side then it's uninvestible for me.
All the best, Si
Hope you didn't short the NASDAQ Paul.
Either I or the US markets have totally lost the plot - not even sure I'd back myself at the moment.
We certainly do live in interesting times.
Tesla soared over 142 dollars tonight.
Bournemouth in the News this afternoon, had Paul been creeping round the back of the beach huts his contribution to the Fire Service would have been welcome, might even have put the fire out before it arrived!
Smile please Paul,
Silver Moon
Instem:
I asked Phil Reason CEO about the recent placing, the decision to exclude PIs and the director sales which occurred during the placing and he responded extensively:
"The potential to include retail investors in the fundraise was clearly an area of focused discussion with N1S. To provide some context, in the current circumstances, many institutions are focusing their available capital to provide balance sheet support for their investments that have been negatively impacted by Covid-19. Balance sheet support is obviously not Instem’s situation as we have a good level of cash, with £8.3m reported at the end of April and strong current trading noted in our FY2019 results RNS. In conjunction with N1S, we took the decision to focus our fundraising efforts on the institutions for ease, speed and cost of process and to maximize the opportunity for capturing the pool of institutional capital available. With N1S, we took the view that with what would hopefully be seen as a very modest discount to the prevailing price (4.4% in the end) there would hopefully be adequate opportunity for retail investors to get involved at a reasonable price in the open market, which seems to have happened over the last few days."
Director selling was, in reality, heavily focused on one individual, David Sherwin, who has been a significant holder and NED for 22 years and has been steadily reducing his stake as he plots a course to eventual total retirement. In response to the fundraise being significantly oversubscribed (as per the announcements), it was an opportune time for David to sell approximately 36% of his holding, providing greater opportunity to satisfy existing and new investor demand. The same applies to non-exec chairman David Gare, with 40,000 shares sold from the trust.
Phil Reason was forced into exercising the options granted to him at IPO, as their 10 years will be up in October and will lapse if not exercised. Given the rationale and size of the fundraise the company could easily find itself in an acquisition related closed period for some time. If that was the case, he'd be precluded from trading, a potentially tricky problem. He had to do something. He needed to sell to fund the option price for all of the lapsing options and to satisfy the tax for all of them, which in the USA crystalizes as soon as they are converted from options to shares, even if you don’t sell them! Consequently, his main motive for sell-down was really not about liberating cash and he will end up with a bigger share holding after the transaction.
Phil is very excited by the opportunities that will be afforded to Instem by having this cash on the balance sheet and looks forward to executing on their objective of further acquisitive growth.
It is worth noting there are a number of RNS at the moment from Instem which relate to the placing. Some of them look as though they are sales but they are not. They pertain to those institutional holders who did not take part in the placing meaning their holdings were diluted.
I have a beneficial interest in Instem.
Hi Paul.ref OPTI. I note the almost total lack of comments so far today, versus the volume of ''noise'' and aggression following your February 2019 updates. I hope you have not received any abuse again. Obviously, for what ever reason, many investors have sold out is my guess. However, I do think you should give Stephen Ohara the CEO the right of reply to todays article. Im sure he would be op for it and would be a very interesting ''interview'' or such like, especially as it appears many ''moronic'' types seem to have deserted the ship. I hope you can resurrect your interviews in this regard. Im pretty sure SOH would welcome the chance to defend and hopefully educate against your points.
Optibiotix Health (LON:OPTI) though a general and not specific comment, and very much my opinion. Far too much store is put on what CEOs have to say and not enough on objective analysis. A spokesperson for any company will rightly put the strongest spin on what the company does; that is what they are paid to do. It is up to the individual investor to investigate bull or bear propositions and see if they hold water. If they don't congratulations, you may have an edge. If an investor just laps up the words of a smooth talking CEO then one day they will run headlong in to a Wirecard, Globo, Theranos, etc etc.
Stockopedia endeavours to present objective information, the last thing it needs to do is to allow company reps to pollute that.
''Pollute''? Surely we all want correct facts? Precedence has been set imo by previous Paul Scott articles, and an unhealthy relationship between Stockopedia and sharesoc. . However. I do accept my summary of OPTI make be clouded as a shareholder, as you point out.
Apologies if someone else has already answered this but set up and account with London Stock Exchange and add all those shares you are interested in. Any RNS then arrives just after 07.00.
https://www.londonstockexchange.com/exchange/user/registration.html?execution=e1s1
Simple!
Hey Everyone,
Synairgen (LON:SNG) up 300+ % since morning. I have a small share i picked up this morning and not sure if this is a short term or hold?
Thanks...Ash
SNG...I have been a buyer in the past but long since sold out. However there was an awful lot of noise on twitter on Friday about this stock and I bought some at 34.75p for a trade. Someone always knows. It hit an amazing 238p today on news on its Covid trial. I have sold out most of mine now but kept some "free" ones. I have no idea where next. It is very volatile and risky with volume and trades at an incredible level. Have they really got something and will it justify this market cap? To be honest, I don't care that much looking at my cash account today having got 200p for some. I would merely say be very careful, don't be too greedy but it could easily treble again if big US buyers pile in. It could also fall like a stone.
Incidentally SNG is a Woodford stock. I am beginning to feel a bit sorry for him. Some of his investments are just beginning to come good; the media in particular scared a lot of holders and the sheer panic is just beginning to look a bit silly now. The fund should never have allowed or been forced to offer daily withdrawals; as a result of the press "intervention" investments were then sold for a pittance and in hindsight in a couple of years they might look stunning. The forced seller price SNG was sold for....a crazy price.....someone out there has today made a huge obscene profit and I think we may find some of his other bio and tech investments turn out to be big winners. Unfortunately it is not the small investors who will gain....they are looking at large losses....they get nothing from the near £200 million this stock has added today.
Where on Twitter was all the noise?
The sort of people who when they say it might be a good time to take a profit on a stock a discount placing turns up the next day....or in one recent case that very same night via primary bid. Of course its all luck / in the charts. You have to find them yourself I am afraid.
Hollywood Bowl (LON:BOWL)
"A number of members here left negative comments about the idea of going
bowling, pointing out that putting your fingers into bowling balls that
have been mauled by thousands of other people, repels you"
I was and remain one of those naysayers although I'm not sure I found it "repelling" exactly, I haven't changed my stance however, although I have my own bowling ball and shoes (as an ex-league and fun player) I imagine a lot of groups and families would be more likely to go in search an outdoor fresh air sport (like golf) instead of taking the risk of a potential virus indoors (although the winter months may change that stance of course), and having to wear gloves and having to remove them each time they wanted to take a chunk out of their cheeseburger, as well as wearing a face mask. I don't see the use of every other lane being a problem since I can't see the arena ever being packed.
Paul,
Which US Short instrument did you choose?
Thank you.
Hi everyone,
I’m relatively new to dealing with shares and to stockopedia but have been throughly enjoying reading this small cap report daily for the past couple of months.
Excuse my lack of knowledge but can someone please explain to me what Paul means by saying “this is a jam tomorrow”- is this terminology for saying he thinks there’s value in shorting it?
Kind regards,
Andrew
Jam tomorrow or jam to-morrow is an expression for a never-fulfilled promise. It originates from Lewis Carroll's 1871 book Through the Looking Glass and What Alice Found There. In the book The White Queen offers Alice "jam every other day" as an inducement to work for her: "I'm sure I'll take you with pleasure!" the Queen said. "Two pence a week, and jam every other day." Alice couldn't help laughing, as she said, "I don't want you to hire ME – and I don't care for jam." "It's very good jam," said the Queen. "Well, I don't want any TO-DAY, at any rate." "You couldn't have it if you DID want it," the Queen said. "The rule is, jam to-morrow and jam yesterday – but never jam to-day." "It MUST come sometimes to 'jam to-day'," Alice objected. "No, it can't," said the Queen. "It's jam every OTHER day: to-day isn't any OTHER day, you know." "I don't understand you," said Alice. "It's dreadfully confusing!"
https://www.definitions.net/definition/jam+tomorrow
Not wishing to be long and wanting to be short are completely different positions. Shorting is easy to get wrong, and works best when there is a definitive catalyst like an upcoming debt repayment that can't be made. There are literally thousands of listed equities and not only is there absolutely no need to have a buy / sell view on all of them, it would simply be impossible. A good filter to reduce the opportunity set is to look at companies that never actually do what they say they are going to do. Specifically with respect to this expression, the perennial exhortation that either revenues or profits will take off in the next period, and they never do. They can simply and safely be ignored with no money lost or gained.
Instem (LON:INS)
I used to hold but no longer do.
I feel that the valuation (c£70m) has become quite expensive relative to:
Gross margins are super high (c70%), but these have been wiped out completely by higher central costs over the last few years.
Perhaps leverage will improve in the coming years and it's certainly something I'll keep an eye out for when the next set of results are released.
A
Venture Life (LON:VLG)
Impressive result today from this little group.
From reading the comments I'm probably one of the few sceptics here, but maybe that's because I've missed out on the recent rise and I am subconsciously jealous.
Nonetheless, I thought I may as well share some thoughts, good and bad, for anyone interested in hearing another viewpoint:
This number is obviously lower if including capital expenditure.
The EV of the company is c£66m as I write this, so that's quite some premium and one that at first glance has appeared a wee bit rich for me.
Of course it's the future that matters most, which leads me to....
Delivery/warehouse management/fulfilment expenditure will all have risen and I imagine transporting to places like China will also have increased with the grounding of passenger planes over the last few months.
For reference Operating Margins for Venture Life and Customer segments in FY19 were 9.3% and 16.9% respectively (I still don't understand why it's not the other way around).
Working through the overly complicated revenue growth numbers published today, Venture Life year-on-year growth was actually +218% (or +168% if the acquisition revenue of c £1.4m shouldn't be included here)
That's obviously very good and I don't know why the company didn't state this.
For reference if H2 mimics H1, and operating margins stay the same vs FY19, the operating profit for FY20 will equal £4.4m.
For me that still seems expensive relative to the current price, but there are too many assumptions here for this to be a truly meaningful number.
So I personally plan to wait until interims are released, and profitability levels are clearer, before deciding what to do next.
Cheers and GLAH
A
Hello Abtan.
The agreement with the Chinese client is for collection from VLG factory in Italy. From the point that the products leave the factory VLG are no longer responsible - no transporting, freighting distributing or selling. Additionally the contract is for payment on collection from factory also (I do like this) Normal transit times are 6 weeks but 10 weeks at present due to C19 so VLG have slightly softened their payment terms until Q4 when it is hoped transit time will have normalised. Further details in my write-up.
Michael
Venture Life (LON:VLG)
Hi Michael
That's quite some arrangement Venture Life (LON:VLG) has signed up to.
I can only assume therefore that the Chinese company must be receiving a serious discount to take on the hassle of shipping/customs/etc.....
Out of curiosity do you know if there are clawbacks or penalties if they don't actually order up to €168m over the next 15 years?
It will certainly be interesting to see how margins are affected going forward.
Cheers
A
Venture Life.
I just had a telephone conversation with Andrew Waters CFO.
Will write up my notes.
I have written up my notes on stockopedia: https://www.stockopedia.com/content/venture-life-hy-update-639938?order=createdAt&sort=desc&mode=threaded
A bit surprised that no one has mentioned that Graham Neary has said that he will no longer be writing this newsletter (except as a very occasional "super sub"). I wish him well in his new full time venture and thought his output was always a good balance for Paul.
May I presume SCVR will announce a new team in due course?
It'll probably be me & Jack going forwards.
barnetpeter - Graham was asked this on his cubeinvestments webcast this morning and said he would be doing more SCVR dutiesa as and when asked. Having said that, I note that stocko has removed his picture from the head of this page.
no thats terrible news!!
Instem (LON:INS)
I hold INS as
1. CEO seemed switched on, understands the technical detail
2. They are in a niche which is hard to enter (difficult to hire people with reg approval expertise) and has value by reducing big pharma's time to market unlocking revenues
3. Pharma is a growth industry in general
Recent raising, INS stated will be used for acquisition which is interesting
I guess we all have different perspectives but I’m optimistic on BOWL/TEG. Maybe Covid will trigger improved hygiene standards on handling balls/arcade machines etc. that were overdue anyway. Attitudes/fears will I think soften over the summer. Think the companies will just tick over in the short term, but the dilution from the fund raises was really quite small, monthly cash burn during lockdown was modest too, so taking a medium/longer term view think the market cap drop will prove a buying opportunity. I think it comes down to how we spend our spare time. If less time is spent going on holidays, going to retail parks etc., what do families do with kids?
Separate note/anecdote - went into a bathroom showroom at the weekend. They said they have never been busier. Bit of a backlog from the lockdown probably, but maybe a view that if you’re not spending big ticket money on a foreign holiday etc. then (at least for those with spare money) need something else to do with your time and money.
I am a big fan of the management of £BOWL but sold up as COVID started growing in the UK. I really want to buy in again when this is all over but struggle at the moment to see enough people wanting to go in and play and enough families and children (who like to spend a lot on the machines) going in. Just a question of timing I guess but this is on the top of my list when we know how to survive this virus safely.
It strikes me that Hollywood Bowl (LON:BOWL) is actually pretty well setup to offer a Covid secure environment.
It’s perfectly easy to disinfect the balls and clean the bay in between each game. Each bay is fairly self-contained, whether or not screens would be needed between bays or whether they are far enough apart I don’t know.
I can’t really see any reason why people would be more reluctant to order food and drink to their lanes.
Of course, it does mean that you cannot have two parties sharing a bay so there is a significant reduction in peak-time capacity. I have lost track of what the latest guidance / rules are on party sizes, but if larger parties are allowed, they could use both lanes within a bay. In fact there would also be an option to offer discounts if a smaller agrees to use both lanes, eg a party of six bowling both lanes would finish their game in half the time. (Initially at least they are not taking either of these options)
Also I would presume their trade is/can be more evenly spread across the week during the school holidays.
So, I can see this being feasible.
The question though will be how much will turnover be reduced by? Last year gross profit was 134% of Operating costs, so dependent on how much they can flex opex down (and offset the extra costs of being Covid secure) they probably cannot afford too much of decrease in turnover before they become unprofitable. In fact, I think the question is really, how small can they make the loss over the period whilst restrictions still apply.
We really don’t know the answer to this yet, but I would take some comfort from the balance sheet strengthening that they did that they will be able to survive this period.
In the longer run, if and when we have full resolution of the pandemic there’s no reason that they should not return to their former trading trajectory. So, whilst it is not a ‘buy’ for me at this stage, it is sufficiently interesting to go on my watch-list.
Re £BOWL - Also, if capacity is constrained and demand is solid, the other lever to increase turnover they can pull is pricing/game. I thought (but now cant find reference to) that the bowling game were +/- 50% of revenues. If so, a do-able 10% increase in price/gameraises revenues by 5%, all of which goes to the bottom line. This price increase might then become the new normal and be retained , providing a long term margin boost.
So 2020 will obviously be very poor but every chance to survive and prosper. Capital investments in new scoring boards etc were driving underlying organic growth before COVID. Plenty of cheap space going to come on the market going forward to faciltate expansion.
Good point, although I would think they would be cautious on that until it is clear how well demand is holding up.
That set me to thinking though - their food offering will qualify for the lower 5% VAT rate (& potentially the eat out to help) but I cannot quite work out if the price of a game would also qualify? Entrance fees to Leisure facilities qualify, but is the price of a game equivalent to an entrance fee? If so then they could choose to hold their headline prices and take the extra margin, which would go some way o compensate for reduced capacity.
Does anyone know the VAT position for bowling?
Hi Paul, I would be interested on thoughts regarding Shanta Gold (LON:SHG) Q2 production update and the gold mining industry as a whole. Thanks
Hi Chris,
Sorry, I don't cover any shares in the natural resources sector, because it requires specialist knowledge to add value, and there are so many of them (many of them are dodgy too!), and the selling price of the output is essentially random hence they're so difficult to value.
Regards, Paul.
Thanks for responding, Paul. Totally appreciate your position on this sector and I look forward to catching up on your very informative SCVR in the future. Many thanks, Chris
Re Hollywood Bowl (LON:BOWL) - could be quite a lot of pent up demand and a good outlet for all those still on furlough and likely to be on furlough for some time to come.
I wouldn't be surprised to see increased use during daytime which, perhaps, would previously have been quiet.
I also expect to see an increase in sales of personalised bowling balls and shoes (perfect answer to physical transmission concerns).
So, even with every other lane being closed, revenues over the coming couple of months could surprise??
Really good points, thanks Laughton!
I was tempted by Hollywood Bowl (LON:BOWL) much earlier this year but went for Ten Entertainment (LON:TEG) where at the time management appeared a bit more go ahead, a very subjective view!
I seem to recall Ten Entertainment (LON:TEG) were planning to invest in new bowling lane technology which would both improve efficiency and do something (memory fails me) to return bowling balls to the individual bowler. I sold in early COVID days but may go back in when I next have a few pennies.
I read one of the CEO's (can't remember which) saying they are doing away with bowling shoes. Apparently they were only ever to let the player slide and only the top players do that and they have their own shoes anyway.
I saw your placeholder this morning for Tens Entertainment TEG (which I recently bought and was looking forward for your comment Mr Scott). Disappointed to see you have replaced it with Bowl, especially as you have a long TEG position. Why have you decided not to comment? Why is TEG unloved/overlooked given the great Stockrank. Imo it looks in a much better position than bowl?
{{{ holds head in hands }}}
There's one every day, isn't there.
Couple of points: Paul and Graham only normally comment on announcements and TEG hasn't made one (but BOWL has). You'll also note that the comments Paul has made re BOWL have direct read across to TEG. At the time of posting, you have a dreaded down vote (not from me) - you may or may not care, but I would guess it's because of the slightly entitled tone of your post, rather than the content or for not knowing the "rules" as it were.
Re Hollywood Bowl (LON:BOWL) pessimism by some, I would have thought that bowling balls would be cleaned by the staff after each game has finished....?
Paul: "... flash consumer confidence numbers coming in well below expectations, and importantly below June's numbers. That's not consistent with the V-shaped recovery that the stock market has priced-in."
True, but hard data on the consumer (vs confidence surveys) is consistent with a sharp recovery. This is the advance version of the June total for Retail and Food Service:
You don't get much more V shaped than that.
There is quite a lot of evidence of a sharp bounce back, the question is can it be sustained?
In macro corner, not much is happening. It was supposed to be a big week for the Dollar, Euro etc and so ended up being not much of a week at all. DXY remains at levels being watched for a breakdown. Its been used as an inflation gauge because so little is happening in bonds. Yields are falling but only a little. The spread on 30 -10 s isn't moving but 10 year yields are nudging down. Whilst yield curve control may stop yields rising, there is little reason for it to actually further compress yields...and the Fed has stepped back anyway. So the bond market looks at rises in Copper and other commodities and shrugs. Metals fell back a little over the week... so if anything it was a deflationary week. Its mostly noise however since not much is really going on.
Venture Life (LON:VLG) Simon Thopson in IC has been following them for some time:
A venture worth following
Aim-traded Venture Life (VLG:72p), a developer, manufacturer and distributor of products for the self-care market, has released another bullish trading update that has prompted brokerage Panmure Gordon to push through its third major earnings upgrade on the company since March. Analyst Dr Mike Mitchell now expects 2020 revenue to rise by 50 per cent to £30.2m and pre-tax profit before amortisation to increase by 126 per cent to £5.2m. On this basis, expect adjusted earnings per share (EPS) to leap from 2.2p to 5.1p. For good measure, Dr Mitchell has upgraded 2021 EPS estimate by a thumping 40 per cent to 6.3p.
Key drivers are the previously announced exclusive 15-year agreement worth €168m (£147m) with Venture’s existing Chinese distribution partner, robust sales of hand sanitising gel brand (DISINPLUS), and a contract extension with Alliance Pharma (APH:75p) that will see Venture appointed as second manufacturer of the larger group’s Kelo-Cote products until 2026. Importantly, Venture has ample cash and low-cost debt facilities on hand to fund investment in scaling up manufacturing capacity.
The holding has delivered a 57 per cent gain on an offer-to-bid basis since I advised buying, at 45p, in my May 2019 Alpha Report, during which time the FTSE Aim All-Share Total Return index shed almost 9 per cent of its value. Following the latest earnings upgrade, I raise my target from 75p to 95p, equivalent to a 2021 price/earnings (PE) ratio of 15, not an unreasonable rating given expectations of 23 per cent earnings growth next year. Strong buy
I know very little about Venture Life (LON:VLG) but was flagged by David Thornton at Growth Company Investor in the latest PI World video and I had down to look at so wont catch todays rise but looks like an interesting company.
Re: News Alerts - I use ADVFN and Research Tree (which includes RNS alerts plus alerts on new broker updates, company videos etc that have been posted on the platform) as a backup. Generally speaking, ADVFN is very timely (up to 2 minutes ahead of other services) - I know not why.
Morning Paul
VLG is my No 1 holding.
The figures are clear proof of the 9th June update which stated that it is 'confident that it will comfortably exceed market expectations for this year.'
At that point Cenkos had already provided an upgrade and said the Revenue for the year was expected to be £30m.
H1 Rev £16.9m looks good to me and is a beat, especially when it is an 80% beat on H119.
Michael
I have a positive short term outlook on £BOWL. I think if your happy with the guidelines for a pub to reopen where your pint has been handled, then booking a lane in your bubble, using hand sanitizer is perfectly suitable.
Instem HY update v positive.
Please can you take a look Paul
Instem provides IT solutions to pharma for their new drugs.
Many of the large pharma companies are clients.
My tweet of this morning:
"Strong organic and acquisitive growth potential
Scalable platform
Placing raised £15.75m for acquisitions
Aim to further grow market share, margins and revenue visibility"
H1 rev up 20%
Strong cash generation
Leadscope acquisiation (AI) ahead of expectations
Top 7 holding
Michael,
Sounds interesting, thanks.
I'll take a look at Instem (LON:INS) next.
Regards, Paul.
I am excited by the potential.
The balance sheet is strong and the management seem very good too. Phil Reason (CEO) has been with the company for over 17 years.
Instem:
There is a company presentation on Thursday for Private Investors:
Investor Presentation
The Company will be hosting a presentation through the digital platform Investor Meet Company at 16.30 (BST) on Thursday 23 July. Investors can sign up to Investor Meet Company for free and add Instem via the following link https://investormeetcompany.com/instem-plc/register-investor or for more information please contact Walbrook PR at instem@walbrookpr.com.
Morning Paul,
Mti Wireless Edge (LON:MWE) reporting that they have expanded into the (newly available) French winemaking market with their water management services. It's a company I've followed for a while - and they tick most of my boxes - I'm just concerned about regulation and lack of control over where they conduct most of their services - which is perhaps completely unfounded.
Thanks
I've moved away from Mti Wireless Edge (LON:MWE) for pastures new as its business could be politically exposed to events in China. The watering of French vineyards had not met the news stream in my house last week.
Re £MWE this is also a very big opportunity in Australia where large areas of vineyard are irigated and water very expensive, I know Mottech are already in Australia but haven't heard anything about weather they operate in agricultural water supply there.
Re MTI Wireless Edge (LON:MWE)
Stocko’s news is listing this announcement as a RCS rather than an RNS. My understanding of that is the news is not significant enough for a RNS. So, general comment from the company rather than something expected to materially change their financial situation.
Perhaps I have misunderstood what these RCS announcements are, but had the impression that we should read too much into them.
Mti Wireless Edge (LON:MWE) which has been a favorite of mine for a number of years have announced today that they are using their water intelligence on the wine industry in France which they see as a major opportunity. With 5G on the antenna business and the water business I think this has a good opportunity for longer term growth.
It has the Israeli flag on it which I believe means it trades at a discount but with the strong reputation for rewarding shareholders with dividends I am ok to ignore that.
I am long if its not obvious :-)
Given they are experts in water management, I wish it was a bit more liquid!
I'm sure I heard about bowling is that every other lane will be used.
I think some of the bigger challenges for them lie away from bowling. Eating while bowling seems a bit of a no, wouldn't be surprised if they stop serving food to the lanes.
Surprisingly at least for TEN, bowling revenues make up less than half of the total. Machines and amusements revenue was almost £20m from £84m, food and drink was over £21m. It seems that both of these will take a big hit.
It isn't going to be very profitable even if people return to bowling in the same numbers (unlikely if every lane is shut), but demand for gaming and food is halved. It might be about break-even. But that's a big if. Haven't been bowling for a while but last time I went on a Saturday night was that every lane was in use. That's a lot of peak-time revenue lost which cannot be got back (as some people will be unwilling/unable to reschedule).
Even if a vaccine was found, I think the punitive measures will be around for much longer, maybe forever. After all, other bacteria will be transmitted the same way.
All fair points, but surely as investors we should be looking forwards, rather than just assuming that the status quo continues forever?
"Even if a vaccine was found, I think the punitive measures will be around for much longer, maybe forever. After all, other bacteria will be transmitted the same way".
Good grief! Did the Spanish Flu or anything else have effects that lasted forever?
doubllutz - I echo your sentiments. We appear to have lost all ability to evaluate risk. (this would not apply however to most of the readers of this forum - one would hope !)
Thx doublelutz. The idea that C19 will be around forever is a nonsense (sorry to be categoric Paul). It make take years (2 to 3?) or it might be over sooner but it will certainly not be around forever. Further I see no particularly punitive measures.
As Housemartin2 says people are not very good at assessing risk and also think linearly. That which is happening now will continue ad nauseam in to the future (direction of £TSLA share perhaps.
Don't get me wrong what we are going through is horrific (for some more than others) and I am sure people will agree that when I say I cannot wait for it to be over. But remember "This too will pass".
Sorry rant over.
Kind regards
Michael
Even if a vaccine was found, I think the punitive measures will be around for much longer, maybe forever.
I'm not sure what is "punitive" about measures to protect public health! However, I think measures will be around for some time, but I'd also expect they will phase out over time, and in a couple of years are likely to have largely gone.
However, if mask wearing by those who may be infections from flu, colds etc, became more widespread permanently in the way it has been for some time in the Far East we would all beneift.
That may just replace one disease with a string of new diseases, plus a cost and environmental problem.
I note how the Islington classes were getting all up-tight about plastic, plastic bags, paper bags... The Daily Mail coerced Nick Clegg into a plastic bag tax... and now... they want face masks, presumably disposable, on anything that breathes and moves.
Before I am mandated (correction I am now mandated), before I wear a face mask, I want to know that its material is safe, bacteria free, sourced correctly, and that its fibres aren't going to be yet another source of allergen, toxin, PM2.5, and foreign body that might cause some yet unknown future disease.
There is a reason why Darwin and natural selection makes lifeforms the way they are.
The face mask issue is not done, and if you'll pardon the pun, dusted.
Hi Paul,
Venture Life half year results out today as someone mentioned earlier. Be grateful of your opinion. PER in the low teens and reporting high growth.
ATB
Hedz
Sure, I'll look at Venture Life (LON:VLG) next.
Morning all,
How does everyone get their 7am RNS updates? I've been using the "Folio news" section on the Stockopedia homepage which works great! Well, if a company is on your watchlist anyway... No need to get a million emails from different sources at 7am when it's all sorted right there. Unfortunately though, when you click "All today's news" it's full of endless fund updates which I doubt very few people read. It would be great to see future improvements in this News section so that it becomes more useful. E.g. hide fund updates by default and give an option to view if people really need it.
Cheers :)
Yes, I do the same. I now get all my news for all the stocks I am interested in from one location. No need to go searching.
I set up a ‘news alert’ from the homepage of each holding on stockopedia. I use the alert feature for other things like price action. It’s very useful.
I use ADVN for some reason MTI ( I am a holder) update was not shown this morning, I will use Stockopedia in future, I will not renew subscription to ADVN as Stocko fullfills most of my requirements.
I agree with Kieranj077 that the "Folio News" feature of Stockopedia is very useful. I try to monitor the dealing activity of the handful of fund managers I follow by monitoring the "Holdings" RNS items. I have not found a way of selecting out these "Holdings" announcements from all the RNS announcements so does anyone know how to do this (using any web site)? If there is no simple way, I wonder if introducing a limited search function on RNS announcements via Stockopedia would be technically possible?
investegate.co.uk for looking through all announcements Easy for copying links. One note is that although majority of news alerts show as 7 AM, most don't appear till around 25 past. Use Stockopedia for quick guidance to ones related to my Portfolio holdings.
I use investigate to pick up RNS's. I always click on the the "category" section, then choose the "Results and trading reports' - so that this only pulls up annual results and trading updates rather than all the other fluff
Sthree (LON:STEM) released H1 20 results this morning. Here's an overview by CEO Mark Dorman & CFO Alex Smith. Sthree (LON:STEM) offers an interesting insight into recruitment in the STEM sectors, (Science, Tech, Engineering & Maths). 'A tail of two quarters'.
Separately, don't forget the piworld webinar with Mark Slater, Chairman & Chief Investment Officer of Slater Investments, this Friday 24th July at 1pm. We'll cover off what Mark's been doing throughout CV19, where he sees opportunities, what he makes of short attacks, and much more. Register here.
Many thanks for all the positive feedback on Andy Brough's interview/webinar. For anyone who's not seen/listened to it, it's great entertainment, and packed full of many investing tips.
Hi Tamzin,
I think your interviews are all excellent however there is one question/point, why do you always end them early, or it seems early as there are often loads of questions left and the speaker never seems ready to dash off. I for one would like to hear more listener questions as there are mostly good quality & the interview seems prematurely ended without them.
Maybe thumbs up to this post here could give an idea of supporting a longer interview?
Thanks
John
Contrary opinion. I think the timings are good. "Always leave them wanting more".
I agree about more listener PI World questions - Maybe the answer is an approx hour interview, with up to 30 minutes extra as a Listener Q and A Bonus link, for those who want to hear more?
I watch them all very enjoyable and informative, keep up the great work.
I know Paul doesn't do oil and gas, but take a look at this morning's announcement from TXP. The first reserves report has been published for the Cascadura well. The initial reserves have been assigned a NPV of $500 millions. A little matter of FOUR times the TXP share price of 57p and with a lot more to come. Let's see what the market does with this news. Happy Monday!
Touchstone Exploration Inc (LON:TXP) may well be a fine investment but:
1. I note that the NPV calculation relates to "net revenues before income taxes". In the case of Trinidad, the petroleum tax is a major issue with the tax rate rising steeply with energy prices. Does the valuation sidestep that issue?
2. If you compare with Trinity Exploration and Production (LON:TRIN) which is another T&T vehicle, TXP now looks to have 2P reserves of about 77 mmboe and an EV of £120m. TRIN has 23mmboe and EV of £18m. That basic valuation suggests that TXP is priced at 2 times the price of TRIN. Do you have a view on what justifies the seemingly higher price tag for TXP?
Several things in my view. Firstly TXP is going places and TRIN isn't - yet. Secondly TXP has several other monster prospects and a big drilling/ development programme. Thirdly it has huge near term cash flow with the gas from Cascadura being sold to a buyer so keen (The Trinidad gas co) that they are paying for the pipe to connect the new supply to their system. We await news of the price to be paid. Finally, for now, the Cascadura development is gas not oil, so no SPT to be paid.
Having said all that, TRIN is also on my watch list. As you point ut, the value on offer is compelling and sooner or later it will be recognised.
I am baffled at the difference in EV between the two. Trinity Exploration And Production (LON:TRIN) is less exciting having made its big discovery a few years back and is just diligently driving down costs and further building up the significant cash balance.
I think the market view of them is starting to shift and expect a step change in valuation later this year when hopefully we will get the FID for TGAL / Echo plus potentially an asset acquisition (every rns gets more bullish on this so hopefully something soon).
Watch the video above.
My morning smallcap tweet:
Synairgen (LON:SNG) Gamma Communications (LON:GAMA) Parity (LON:PTY) Tungsten (LON:TUNG) Angle (LON:AGL) Pittards (LON:PTD) Surface Transforms (LON:SCE) Alpha Growth (LON:ALGW) OptiBiotix Health (LON:OPTI) Clean Invest Africa (OFEX:CIA) Bermele (LON:BERM) ReNeuron (LON:RENE), MJ Hudson (LON:MJH), Instem (LON:INS)
Synairgen (SNG) very positive results from trial of SNG001, inhaled formulation of interferon beta, in hospitalised COVID-19 patients. Further analysis will be conducted.
Gamma Communications (GAMA) H1(June) trading. Guides FY EPS ahead of consensus of 46.5p.
Parity Group (PTY) guides H1(June) rev c. £30m, down 33%, and modest adj pretax profit. Co seeing a return of new sales opportunities, following the severe reduction in early stage opportunities and projects during lockdown.
Tungsten (TUNG) guides FY(Apr) rev up 2% and adj EBITDA broadly in line with market guidance. Trading in the beginning of the new financial year has been positive.
Angle (AGL) good results from pilot study of Parsortix liquid biopsy for detection of breast cancer.
Pittards (PTD) H1 sales running at 55% down. Guides significant loss in H1. "Group has adequate resources to manage the likely duration of the COVID19 crisis at these reduced sales levels."
Surface Transforms (SCE) guides H1(June) rev up 55% to £902k. Outlook "on track to reach positive adjusted EBITDA in 2021, report a profit before tax in 2022, and still expects to make further new contract announcements during 2020."
Alpha Growth (ALGW) Fund has seen a significant rise in interest from US registered investment advisors (RIA) and family offices. Next steps involve the RIAs conducting due diligence on the Fund and manager which several have started.
OptiBiotix Health (OPTI) guides H1(June) sales of LPLDL and SlimBiome (I think that is all rev) up 398% to £740k. "We hope to close out one or more agreements within the coming months."
Clean Invest Africa (CIA) delays FY19 accounts to end Sept at the latest. TRading: "Whilst the past few months have been extremely challenging Coaltech is looking forward to the next period with significant optimism due to the substantial and strong pipeline and in addition a developing opportunity to expand beyond coal."
Bermele (BERM) plans RTO of East Imperial, a Singapore co that designs, develops, formulates, manufactures, distributes and sells small batch blended premium mixers. Shares suspended pending completion.
Reneuron Group (RENE) FY loss in line. Outlook "very encouraged to see the potential of our exosome and iPS cell technologies emerge during the period, with further collaboration agreements expected in the near term to complement the agreements we have already signed with major pharmaceutical/biotechnology companies regarding our exosome programme."
In line: MJ Hudson (LON:MJH) Instem (LON:INS)
20 Jult? Monday morning for ya!
I noticed that so many people were piling on the weight during lock down so bought some £WW shares, very nice 50% profit in just 6 weeks.
Hi Troymcclure,
Oops thanks for pointing out my typo, I've corrected that now.
Regards, Paul.
£VLG Small cap high flyer healthcare Venture Life Group plc
Half Year trading update
Terry Randall, CEO of Venture Life said, "There has been step change in the business in this first half of the year, with revenues increasing by 80% to £16.9 million, of which 65% is from organic growth alone. This is a remarkable achievement, amidst an extremely challenging backdrop of the COVID-19 pandemic; ''....
VLG featured in Piworld webinar: David Thornton: Why Small Caps. And What to Buy Now? Jul 3, 2020 by TamzinPiworld.
I bought a few of these a few months ago and have topped up this morning. Looks a very interesting prospect with diversity of both products and markets.
Thanks for flagging the update from £VLG I hadn't spotted that. I'll cover this one next, as it's up 19% I see. Nice company, I was impressed about it. Pity it has the name "life" in the name, as I always ignore those, as they're usually blue sky biotech, whereas this one is a decent little company.
Yes, very good figures from Venture Life (LON:VLG) following the 9/6/20 announcement that "it will comfortably exceed market expectations for this year".
Although today's figures are revenue but not profit there is a video of the CEO from the June announcement in which he points out the operational gearing due to spare capacity in the factory in Italy meaning that much of any revenue increase will fall straight through to the bottom line:
https://www.venture-life.com/i...
Full marks to Cenkos who, like finnCap, allow PI access to their research. They have left their forecasts unchanged this morning having upgraded twice this year.
I have added.