Small Cap Value Report (Mon 20 Mar 2023) - PBEE, TRB, TENG, SPSY

Good morning from Paul & Graham!
Today's report is now finished.
This weekend's podcast went up on Sunday. Here's the link, or it's available through podcast platforms too (called "Small caps podcast with Paul Scott". I kept it down to 32 minutes this week, covering my thoughts on the banking crisis, budget, plus all the company updates from last week.
More turmoil with the banks. I see the weekend press is reporting that UBS has bought out Credit Suisse, combining Switzerland's two largest banks. Stock market futures initially reacted positively, but have since (07:08 today) turned ugly again, with the FTSE 100 futures indicating an open here about 100 points down, at around 7,210. So looks like we need to keep those hatches battened down.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
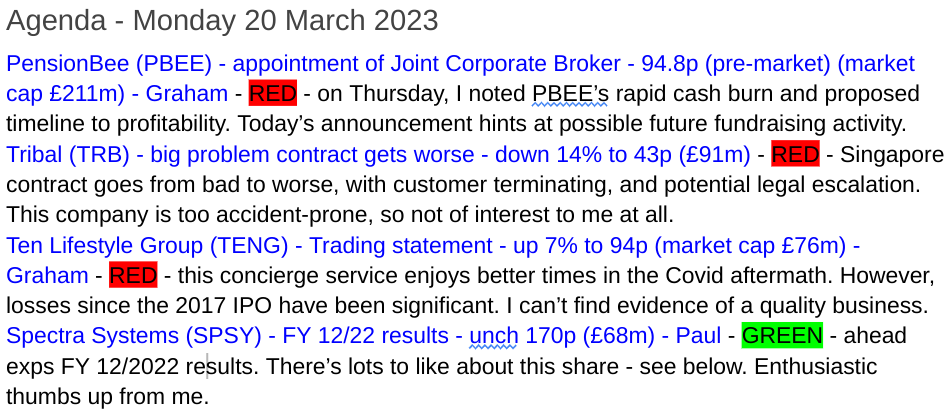
Tribal (LON:TRB)
43p (down 14% at 08:34)
Market cap £91m
Singapore Contract Update and Revised Date for Full Year Results
Tribal Group plc is a pioneering world-leader of education software and services. Its portfolio includes Student Information Systems; a broad range of education services covering quality assurance, peer review, benchmarking and improvement; and student surveys that provide the leading global benchmarks for student experience. Working with Higher Education, Further and Tertiary Education, schools, Government and State bodies, training providers and employers, in over 55 countries…
The current financial year is FY 12/2023.
I last reported on Tribal here on 1 Dec 2022, when it issued a profit warning due to a large contract going seriously wrong. So badly wrong, that to my mind it makes the shares uninvestable (expected loss of £12m over life time of the contract with Nanyang Technology University ("NTU") in Singapore).
Tribal again updated the market on its Singapore contract on 23 Feb 2023, saying that things had deteriorated further -
As announced on 1 December 2022, the Group's trading performance has been impacted by implementation delays on the Singapore contract, due to changing scope and complexity, resulting in substantially increased ongoing costs and lower recognisable revenue. Discussions with the customer have not progressed satisfactorily and we remain in significant disagreement over the detailed scope of the contract. We no longer expect a resolution in the near term and will provide an update as and when appropriate.
Today’s update sounds like a complete breakdown of the client relationship, which now seems to want to abandon Tribal’s software altogether -
Tribal received notification on 17 March 2023 that NTU has purported to terminate the contract and reserved its rights to claim damages. Tribal rejects NTU's right to terminate and is considering its options regarding appropriate next steps. The contract requires the parties to participate in mediation in an attempt to achieve a resolution.
Whether the contract terms would necessarily be binding in Singapore, who knows? It depends how their legal system works.
Accounts delayed - it’s only a few days, so no great shakes. But this does suggest to me that there’s likely to be an increased provision required against the problem contract -
The Company now expects to release its audited results for the year ended 31 December 2022 on 24 March 2023. This allows appropriate time to consider the impact of the contract termination, in particular the accounting treatment of a £4.5m onerous contract provision contained within previous expectations, set out at the time of the trading update released on 23 February 2023.
No doubt that will be adjusted out, in the hope that investors will ignore it, but I think this is a very serious issue - it’s telling me that Tribal’s software, and ability to implement it, just isn’t very good - at least in this one particular case. It would be interesting to hear from other customers whether they’re happy with Tribal’s software & service or not. Do any readers have experience of using Tribal software, or know people who do? First hand user experience is far more valuable than anything companies say about themselves, I find!
My opinion - I don’t see how investors can possibly overlook this serious problem.
There’s a wide range of possible outcomes now, ranging from an amicable mediation settling things, to a protracted and expensive legal battle. That makes it difficult for us to value the shares.
Solvency doesn’t seem to be an issue, with year end debt previously reported at only £3.4m.
I’ve been following Tribal for years, and there always seems to be something going wrong.
I can see there would be some value in the business, due to its recurring revenues, and long standing customer relationships. As mentioned before software companies (even lousy ones!) often attract takeover bids. However, Tribal's financial performance is so erratic, and this latest problem sounds potentially expensive, that I personally am not interested in getting involved in this share. Why leap into the unknown?
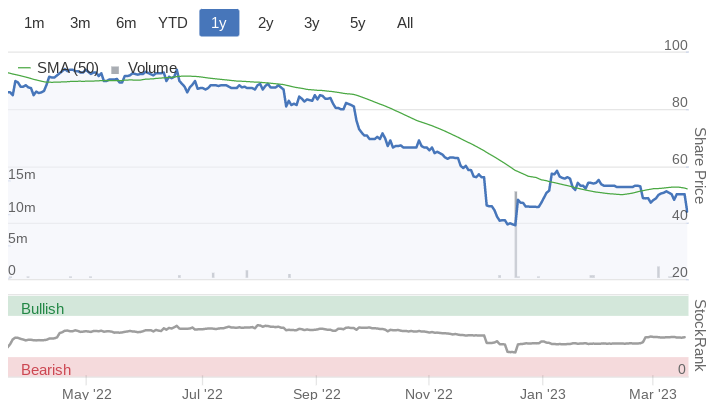
Spectra Systems (LON:SPSY)
170p (unchanged at 09:09)
Market cap £68m
Previous SCVR notes -
Positive view here on 3 Oct 2022 (positive contract update, and upped forecasts).
Positive view here on 12 Sept 2022 (good interim results, cheap valuation, good divis, strong balance sheet, and upside potential from strong pipeline).
Today’s update is -
Spectra Systems Corporation (the "Company"), a leader in machine-readable high speed banknote authentication, brand protection technologies, and gaming security software, is pleased to announce its results for the twelve months ended 31 December 2022.
Key numbers - Revenues $19.6m (up 18%)
Adj PBT $7.8m (up 17%)
Adj EPS 14.5 US cents (Allenby points out this is comfortably ahead of forecasts which were raised 3 times in 2022). This is 12 pence EPS, so the PER is 14.2 - seems cheap to me, providing earnings can be maintained or continue growing.
The annual dividend (there’s no interim divi) is 11.5p US cents, or about 9.5 pence, which at 170p mid price, gives a smashing yield of 5.6%.
The big cash pile means it’s not straining itself to pay a decent divi either.
Balance sheet looks excellent, with c.$18m of net current assets, almost all of which is the $17.5m cash pile. So, whilst it’s helped by deferred income (getting paid up-front), I would say we can safely see the cash pile as being genuine, and likely to be sustained. Particularly as the company has such low overheads - so even if trading suddenly dropped (always a risk with a small company dependent on a few big contracts), then it would probably just be a case of a smaller profit, but remaining cash generative at a lower level. Not loss-making or cash burning. So this is a nice setup.
Outlook sounds encouraging -
"The Board therefore believes that the Company is on track to achieve record earnings and meet market expectations for 2023."
Other points -
Shrewd investors in this share.
Tightly held - little liquidity.
High StockRank
My opinion - As always, I’m just reviewing the numbers, not trying to give a view on the much more detailed work necessary to assess the company’s future potential, which is always partial guesswork anyway.
The numbers stack up very nicely, and there are lots of irons in the fire which could deliver future upside, see the commentary today.
It gets an enthusiastic thumbs up from me.
Graham’s Section:
Pensionbee (LON:PBEE)
Latest share price: 94.8p (pre-market)
Market cap: £211m
I covered this pension app in some detail on Thursday and noticed this morning that they published an “appointment of joint corporate broker” update.
This type of announcement always looks innocuous and it can be entirely inconsequential. But depending on the context, it can make me think that fundraising could be on the cards. After all, why would a small company need two brokers, if it was not planning to use them?
In this particular case, I noted in Thursday’s article that Pensionbee’s cash position more than halved during 2022, from £43.5m to £21.5m. They are hoping to start generating positive adjusted EBITDA by the end of 2023, so bottom-line profitability is still some distance away.
According to Equity Development, the after-tax loss is expected to be £10.8m in 2023, before the company almost achieves breakeven in 2024.
Pensionbee might hit its targets, achieve genuine bottom-line profitability in 2025, and find that it never needs to raise equity again. But that’s probably not the base case scenario that I would assume, based on its financials. And with an extra broker on board, it appears less likely again.
Ten Lifestyle (LON:TENG)
Share price: 94p (+7%)
Market cap: £79m
This describes itself as “the platform driving customer loyalty for global financial institutions and other premium brands”. It provides a premium concierge service to customers of these institutions - including travel, dining and entertainment benefits.
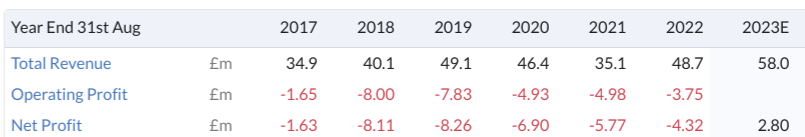
Covid probably didn’t help, but the financial track record here was not particularly good in the first place:
This morning we have a trading update for H1 (the period ending February 2023).
Key points:
Revenue £30.9m showing a very healthy progression against the previous six-month periods (H1 2022: £20.8m, H2 2022: £26.1m)
Similar progress in the number of Active members to 316k (H1 2022: 221k, H2 2022: 275k).
Less positively, net cash has fallen from £3.2m to £0.5m over the six months, but the company has an explanation:
This reflects the Group's normal (pre-COVID-19) seasonality, to consume working capital in the first half of the year and was adversely impacted by a late client receipt of £1.0m, which has now been received.
That sounds perfectly reasonable, but there is more new info re: the balance sheet:
An invoice discounting facility was signed during the period with the Group's bank (H1 2023: £2.1m drawn down), in addition to the Group's £4.6m of loans (FY 2022: £3.4m), to underpin the Group's working capital requirements. The Group expects to generate net cash in H2 2023.
TENG doesn’t seem to have raised much fresh equity since its 2017 IPO. Given that it also hasn’t generated much by way of profit since then, it’s not surprising to see that it now needs loans and an invoice discounting facility (it had net cash of over £20m in 2018).
My view
There is not much more to go on in today’s update, so it’s time to wrap this up.
Unfortunately, I can’t find any evidence of a high-quality business here - financially there are signs of lots of cash burn, a weakened balance sheet, and only some “adjusted EBITDA” for comfort. The company’s statement that it will generate net cash in H2 can be interpreted as seasonality rather than much more than that.
Reflecting on the business model, it seems that TENG itself has very little brand visibility. Rather, it provides a service whose main mission is to enhance the brands and the customer loyalty enjoyed by other companies.
Is it possible to build a competitive advantage / pricing power in the provision of this type of service? I’m not sure - it seems likely to me that TENG’s corporate customers will always be able to negotiate quite hard, since they are the ones who own the relationships with the end-users.
Indeed, I’ve looked up the 2022 financial report and found that two of TENG’s corporate clients accounted for more than 10% of TENG’s revenue for the year: they generated £9.5m out of TENG’s £48.7m of total revenue. With this level of client concentration, I doubt that TENG enjoys very much pricing power at all.
I’m going to have to give this stock the thumbs down for now.
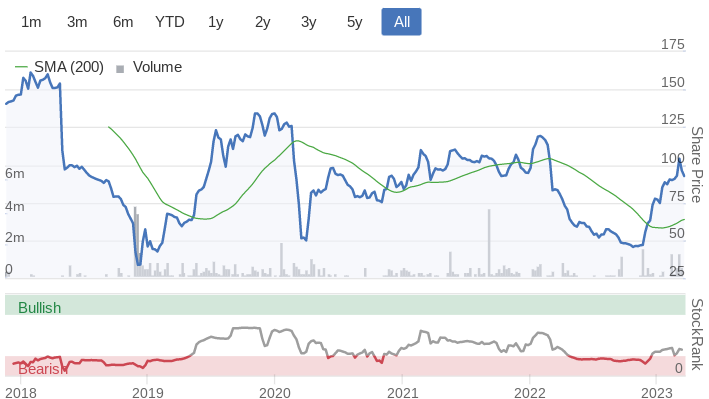
Chart since it listed -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Many thanks to ACounsell for your helpful comments following my post at 2.21pm today.
I must agree there are certain types of Share were the Stockopedia metrics are sometimes skewed and Litigation Finance is another example.
Good to know the renowned Lord Lee holds the very 3 Insurers I have been watching closely.
I have held fire today because of the potential contagion from the Credit Suisse fallout.
Equals Group (LON:EQLS).
MMs playing their games.
I can't get a quote to BUY any, not even 10,000 shares.
I can get a quote to sell 25,000 shares for 73.35p
Mid-price only 72.5p
Can't even buy 300 Equals (LON:EQLS). Can buy 250, great.
Results / update tomorrow I think .
On 27 March 2023, apparently, unless it has recently.
Can anyone with a good knowledge of the Insurance Industry tell me please why it is that Aviva (LON:AV.) with Rankings of 84, 93, and 75 for Value, Momentum and Rank is a lowly 19 for Quality.
The Dividend is 7.6% and with a Market Cap of £11.4 BN I feel tempted to Invest but I find the Accounts of the big Insurers so difficult to understand.
Any comments would be much appreciated.
I’m not sure the Stockopedia standardised accounts system works for Insurance, banks and oil & gas companies. The complexities of accounting for these type of businesses throws up all sorts of ‘funnies’ with respect to the metrics. I hold Aviva (LON:AV.), Legal & General (LON:LGEN) and Phoenix group (LON:PHNX) and topped up on Aviva (LON:AV.) last week (though wish I had waited until 1st thing this morning!). The yields are attractive and look to be reasonably well covered - the experience investor Lord Lee certainly likes them as Income plays as he frequently refers to his holdings in them in his FT Money articles!
Quality is a reference to returns on capital which are poor at Aviva - complicated insurance accounting etc don’t help
This is my first experience of a bear market, having only been investing a few years. I dip my toe in long, it drops, i dip my toe short, it rises. Truly testing my temperament, emotions etc etc.
This is my first experience of a bear market, having only been investing a few years. I dip my toe in long, it drops, i dip my toe short, it rises. Truly testing my temperament, emotions
I think we all understand how you feel. But the trick is to stop looking at the market as some instant arbiter of your progress. Unless you’re set on trading day to day, simply buy a few shares in some great companies and wait for time, good management and the power of compounding to do the rest.
Hi BnB i am certainly no trader! Thanks for your comments.
we have just come out of a bear market, which started when the russia/ukraine thing happened in 2022...the one before that was the 2020 lockdowns...
Hi truegent you think the bear market is over?!
Would you have asked that question a couple of weeks ago when the FTSE was at an all time high ? The bear market ended a while back and this is a correction in the next bull market - all my own views of course ;)
I've also been following Tribal for some time. I was invested at one point and it did very well by me. That was before one of David Cameron's advisors took over as CEO and very quickly brought the company close to bankruptcy. It was only saved by being able to borrow on the strength of its strong revenue stream from its SITS system. The same system that the University of Singapore has just ditched. The problem seems to be the complexity of the system that leads to difficulty in implementing it. The complexity comes from the sheer complexity of universities' requirements deriving from their student's needs and the universities' own administrative needs. The system is complex because it is designed to meet complex needs. Implementing it requires significant input from both the university and Tribal. Unfortunately, some universities don't seem to provide the resources in terms of properly qualified IT staff to cope with the implementation so they and Tribal struggle with the implementation. Those universities that understand what is needed seem to have more success.
That not to excuse Tribal who sometimes seem fail to provide adequate IT staff resources, perhaps because of difficulty in retaining experienced IT staff.
The shame is that the Tribal system is about the best there is in its field and when the implementation problems are overcome their customers are very sticky. Hence the strong ongoing revenue stream.
Not sure if any use to people but I was looking at fund managers last night to see which ones look good value. I've assumed 2023 earnings will be the low and then taken 10% off estimated EPS to see if any are good value. Ones that look good to me are Jupiter Fund Management (LON:JUP) ,Phoenix group (LON:PHNX) Intermediate Capital (LON:ICP) Liontrust Asset Management (LON:LIO)
I would class Phoenix group (LON:PHNX) as an insurer rather than fund manager. Dividends can be cut of course. City of London Investment (LON:CLIG) is another one you could look at but it has fallen so much.
Fair point. I had it in as I was thinking about the standard life brand - adverts everywhere! Aviva (LON:AV.) looks good as well
I would have thought investec and Ninety One would have been on your list. Sometimes useful to compare their AUM (bn) divided by their market cap (bn), although Ninety One has huge Insurance assets and liabilities which tends to skew the picture somewhat
Happy pondering
There has been a lot of director selling at Investec (LON:INVP), there is some South African exposure, as well. I no longer hold.
Premier miton perhaps?
Yes, I already hold Premier Miton (LON:PMI), so many to consider at the moment. Argentex (LON:AGFX) and Ramsdens Holdings (LON:RFX) , not fund managers have been hit with the banking fallout, are looking good value.
Re Tribal (LON:TRB) Paul wrote No doubt that will be adjusted out, in the hope that investors will ignore it, but I think this is a very serious issue - it’s telling me that Tribal’s software, and ability to implement it, just isn’t very good - at least in this one particular case. It would be interesting to hear from other customers whether they’re happy with Tribal’s software & service or not.
I don't have any experience of Tribal's software or service but in 50 years in the software industry I have seen lots of contracts where the customer and the supplier have different views about what the customer said they wanted and whether a 'clarification' was an increase in scope and therefore chargeable. Most software requirements are just text (possibly with a few diagrams) and therefore very ambiguous. This dispute doesn't imply that Triba's software is poor or unusually difficult to implement.
If this is litigated it will be lengthy and expensive. That's why I sell my shares whenever I read that a company whose shares I hold plans to upgrade its key software.
(My own company used mathematically formal specifications for our most critical contracts, to find and resolve the ambiguities before finalising the contract. Most companies don't, but that's a different story).
Additional thought re last weeks why worry about recessions ? Is it really that serious an issue comments.
For me - SVB and CS are deflationary events that force risk reduction. Things may get worse....we have moved into a world where we are no longer data dependent. Why? because the data is now out of sync with markets.... and to return to the question - should we care about recession.... the answer as usual is it depends because the extent of the slow down affects the bond market. Ironically if the economy is not slowing...which I doubt...but have no data to back this up....apart from Bank stress....then the bond market is probably a sell. Why? because the Fed will not be able to tame inflation. However if the economy is now slowing quickly as risk on balance sheets is reduced ...then the bond market no doubt has further to run. And of course the price of risk free assets determines the price of all assets.
For the time being ... bad data is good news because it backstops the bond market. Strong employment or inflation numbers will be taken badly because the Fed is boxed in. This actually means a recession is sort of your friend for now.... and limits equity downside ironically.
Delighted to see Spectra results come in so strong this morning. Another $8m cash generated. Divis increased. Great company. My main concern lies in the geopolitical sphere. With Trubrand focussing on authentication and this clearly being a key factor in China any deterioration in Chinese US relations could impact here. I note the shares aren't moving this morning. But for now I will enjoy the dividends.
The big question is - how much profits does TruBrand actually contribute to Spectra Systems (LON:SPSY) ?
I will be going through results in detail later this week. But a quick skim made me pick up the interesting part, about polymer notes, and working with a global printer (that does it for many central banks?) on a partnership, nearing completion?
For me, this is the potential mid-term growth for Spectra. After spending the last 2-3 years developing their "thing" (you can see I have no idea about the technicals here!) for polymer banknotes but not seeing much sales yet, this might be the partnership that generates substantial revenues, if this partner then licenses/buys the materials from Spectra to incorporate into the polymer banknotes it prints for its clients globally.
Obviously, revenues from this partnership will still only come in 2-3 years time, because central banks take time to switch banknotes...
(I hold in the Boon Fund)
I also hold Spectra Systems (LON:SPSY) and think the results are good. It is a bit of an idiosyncratic company with certain reasons why some people might not want to buy into it. It has not held an AGM for many years (can never reach a quorum, despite management encouraging shareholders to attend), it will be very difficult to organise a takeover - given that a high percentage of the staff and senior management need US security clearance and the CEO/ founder is not a natural salesman. Plus there is significant customer concentration (60% for the top two clients I believe) and no disclosure on clients, because of client confidentiality. In addition, you have to buy into the management's arguments that the core business of banknote security is not in decline. The management I think argue this quite well and the company has a number of potential exciting other authentication products (eg. TruBrand) which could lead to growth.
The move to polymer banknotes presents both a risk and an opportunity for Spectra as its Fusion product seems to offer potentially security features for polymer banknotes that others can not provide. AFAIK, the US Fed (I think it safe to assume a key client) has not (yet) taken the step of moving from paper to polymer notes.
Once one has overcome the negatives, the key positive is the long track record of the management underpromising and overdelivering and the steady cash generative business over the years, punctuated by periods of growth. The next key growth period should start in 2025 with a major new sensor contract. This should lead to a step jump in profits and revenues. Looking at the Allenby note, the big jump in FY25 is supported and dependent on this contract. The contract will be the third such contract from this client (the client basically buys a new generation of sensors every 10 years) and the last cycle was responsible for the step jump in revenues in 2014 and 2015.
Spectra Systems (LON:SPSY) is a good dividend payer but the dividends are subject to US withholding tax. Therefore it is probably not that efficient to hold in an ISA (where the withholding tax cannot be reclaimed).
Provided one completes the W-8 BEN form, there’s 0% dividend tax in a SIPP and 15% in an ISA.
But do all SIPP providers reclaim the tax?
Some don't allow you to buy these type of stocks.
AJ Bell allows Spectra Systems (LON:SPSY) in a SIPP, and so far my dividends have been effortlessly tax free (had to fill in that W-8 form though at the start).
Obviously a very complex situation is unfolding. J Authers as usual is very good on this today.
My view for what its worth is that these crisis seem to evolve more quickly and be resolved equally quickly. VIX is spiking to levels associated with. a lot of stress. Strong solid investments are scarce again. In a rush for liquidity good stuff also gets hit but it comes back. Assuming you are not worried about the quality of your investments ie you are not over committed to banks then ride it out. It will be unpleasant and if losses stress you out, wait for the bounce before looking too closely...which could be weeks away but will arrive.
Deutsch bank and Barclays would be least attractive places to be hiding in my humble opinion. The problem is you may own Natwest but if Natwest buys Barclays say....now NatWest have the problem. If there is a problem which I am not saying there is.
Off the cuff already some interesting stuff to buy....if you have the stomach. eg Rathbones. Last year Brewin was acquired by RBC and Rathbones (LON:RAT) - shares are back again at interesting levels for me. It's basically last man standing.... or Capita (LON:CPI) shot up on recent results and has now come rattling back, again on the watch list. A good time to look for those things you missed in the strong start to the year....Zotefoams (LON:ZTF) you are getting another chance to look at.
Review the shopping list...the sales are starting would be my view...try to ignore the losses. Bonds and Gold are doing very well which is helping to mitigate pain in equities. I think the Fed are pretty much done. So we really need inflation numbers to give them a hand.
RD your way shrewder than me at this game but with regards to Rathbones (LON:RAT) is the big debt and weak current ratio not a concern ? I do follow your logic with fund management take-overs being plentiful last two years and a lot of other sharp investors have mentioned Rathbones as another likely at some point.
Do you prefer Rathbones to Brooks Macdonald (LON:BRK) ?
Regards Andy
Apologies I replied and must have hit the wrong button. Rathbones (LON:RAT) I would categorise as conservative. It has low leverage and high teens capital. Ofcourse being a bank its balance sheet is all the opposite of what you normally expect so liabilities are customer deposits and assets are loans to customers which include central bank balances. Their loans tend to be bridging loans to help clients finance property deals and the clients are v low risk since they also have the investment portfolio. It's not all that though so im sure they have some property developers etc.... anyway I would not look at a current ratio for a bank.
Im less familiar with brooks to be honest. I have a nagging feeling they had some issue a while back after several years as a go go growth stock. It doest look expensive but I don't really know it.
Obviously asset market risk is the main issue for the P&L at Rathbones (LON:RAT) which is why they have been hit. I simply highlight it as a stock that's been weak.... and rallied strongly following the Brewin RBC takeover.
I agree Barclays or Deutsche look like riskier propositions, given ownership of weaker investment banking franchises. But what if their risk management is good? In other words, what if they saw the rate rises coming ( not too difficult given what the central banks were saying) and hedged accordingly? Then they will sail through these problems and come out looking very cheap. We just don’t know.
I would urge any investor to be extremely careful of Tribal. Not only do they have this Singapore problem, but they are capitalising an incredible amount of costs. If that capex is expensed through the income statement, the business makes no money.
And having worked with their products in the past, I have to say I'm surprised more customers haven't just walked from their Tribal contracts.
Japan's two-decade QE policy had kept its inflation very low, more recently Japan's CPI rose above 4% for the first time since 1980. The Bank of Tokyo's policy rate is currently -0.1% having averaged zero for over 20 years. Japan's national debt as a percentage of GDP has grown from c100% to c250%. According to Tokyo-based market commentator Weston Nakamura, more than 25% of Japan's government spending goes on debt servicing. And this is when 10yr Japanese bonds yield just over 0.3%. If you want to consider the worst potential casualty of the unwinding Great Duration Bubble, this crisis's Lehman moment, it may be worth keeping a close eye on Japan.
My morning smallcap tweet: Draining the swamp of smallcappery
Tribal (LON:TRB) Aptamer (LON:APTA) Journeo (LON:JNEO) Ethernity Networks (LON:ENET) Genedrive (LON:GDR) Ten Lifestyle (LON:TENG) Xeros Technology (LON:XSG) Aew UK Reit (LON:AEWU) Saietta (LON:SED) Conygar Investment Co (LON:CIC) Fireangel Safety Technology (LON:FA.) Spectra Systems (LON:SPSY) Mears (LON:MER)
◄Tribal (TRB)► Nanyang Technological University "has purported to terminate the contract [RNS 23 Feb] and reserved its rights to claim damages".Co rejects this. FY-Dec results delayed to 24 Mar. [SP=49.85 Cap=106m]
◄Aptamer (APTA)► launches Optimer-Fc as a new reagent solution for automated immunohistochemistry workflows.. [SP=28 Cap=21m]
◄Journeo (JNEO)► £0.8m order from Network Rail for the manufacture and supply of passenger information displays. Expects to book rev this FY and is included in mgmt expectations. [SP=137.6 Cap=22m]
◄Ethernity Networks (ENET)► UEP2025 bonding product update. [SP=6.8 Cap=7m]
◄Genedrive (GDR)► MT-RNR1 ID Kit is in process for roll out at two further hospital sites. NICE final recommendation is due towards the end of this month. Does that mean NICE is expected to endorse it? [SP=43 Cap=40m]
◄Ten Lifestyle (TENG)► guides H1-Feb up 49% and adj EBITDA c.£5m (£0.9m), In line? Expects to generate net cash in H2. [SP=88 Cap=74m]
◄Xeros Technology (XSG)► sells third licence for XFilter filtration technology to a company that supplies components for the world's largest domestic washing machine manufacturers,. [SP=4.2 Cap=6m]
◄AEW UK REIT (AEWU)► sells industrial holding for £3.75m, 7% above book. [SP=94.8 Cap=150m]. I hold.
◄Saietta (SED)► gets 'commercial agreements' with one of the largest OEMs in Indian light-duty mobility market. Production on track to commence in Q3 '23. [SP=21 Cap=22m]
◄Conygar Investment Company (CIC)► sells development site at Haverfordwest for £9.55m, £0.2m over book. [SP=123.06 Cap=74m]
◄FireAngel Safety Technology (FA.)► delivers fourth development milestone of its agreement with Techem Energy Services. Ditches its joint broker Singers. [SP=10.2 Cap=18m]
◄Spectra Systems (SPSY)► FY-Dec rev $19.6m up 18%, pretax up 18%. Confusing stmt on expectations: "Company's earnings and revenues are up substantially over 2021 both due to strong sales which would in themselves had [sic] enabled the company to exceed market expectations and which were further increased due to over-manufacturing of covert materials for a Central Bank." Is that mkt exp a year ago or now? Guides FY23 in line. [SP=169.84 Cap=76m]. I hold.
◄Mears (MER)► FY22 results delayed "due to an unanticipated absence of the senior statutory auditor responsible for signing the accounts". EY has has apologised unreservedly. [SP=195.5 Cap=219m]
I posted this on my twitter and although you get plenty of people clicking the link not much engagement. Any thoughts on this?
They don't say coco 'pops' for any other reason:
https://washingtonpost.com/business/2023/03/19/why-credit-suisse-coco-bonds-are-causing-anxiety-quicktake/945ef2fe-c69c-11ed-9cc5-a58a4f6d84cd_story.html
Looks like big news if fear of it spreads to other banks
@mginvestor
Hi MGinvestor
An interesting link, thank you.
Regards
Howard
No one cares about the CoCos, which always looked a funny sort of bond to me. The question is, which bank is next in the firing line?
Deutsch Bank I think.
I understand the coco point but my opinion would be they just became very important. Their price determines bank funding rates....so the bank needs the coco onside which means the coco not the shareholder should be directing the bank on which risks not to take. Having said that there must be some technical legal wrangle why the equity wasn't actually zero...which im not sure about.
Agree .... or maybe Commerzbank. I am short both.
Looks like they did what they were supposed to do. Though the point that their cancellation may make getting the same system to work again in the future is a pertinent one.
NFT Investments (OFEX:NFT)
Odd and esoteric, but possibly an opportunity for the brave. NFT is, by their own estimates, trading at 58% below NAV and they're proposing a series of tender offers to return money to shareholders:
https://www.investegate.co.uk/...
The catch is that most of the assets in question are Bitcoin and Ethereum, which they seem to have timed their purchases of particularly well.
timarr
Interesting to read Warren Buffet has been approached for possible support to US regional banks. Support from Warren is usually effective, and expensive. Is it a sitting on hands day friends or a grow a pair day?
Morning ! Looks to me like a fantastic beat from Spectra Systems (LON:SPSY) today...EPS of 14c compared to forecast 11c...nearly 6% div too, and bags of cash with no debt...
It seems like write-off of some inventory at Spectra Systems (LON:SPSY) happened. The adjusted PBT and EPS includes this, but doesn't a stock write-off constitute a one off event and can be adjusted out too?
Somewhat material, it looks like in the $500k-$1m range.
(I hold in the Boon Fund)
Edit: So it looks like my skim missed the actual inventory write-off amount! Total of $694k in FY22. I note that the also did a write-off of $494k in FY21, so hopefully this isn't a BAU thing...
If this was adjusted out of Adjusted EPS, then we would get Adj EPS going from 14.5c to 16c instead.
The FCF progression over the years (2016 to now) is a sight to behold....! Like Swiss clockwork (touch wood).
astonishing lack of volume in it today.