Small Cap Value Report (Mon 20 Nov 2023) - MCB, BEG, HFD, MMAG, POLR, CER, SRT, THRU

Good morning from Paul & Graham!
Today's report is now finished.
Paul's Podcast summarising the week's SCVRs, with some macro/markets commentary went up on Saturday morning, here's the web link.
My summary spreadsheet is also now up-to-date.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
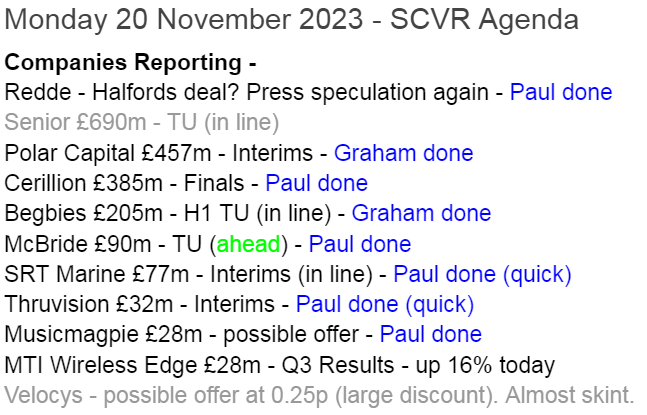
Summaries
McBride (LON:MCB) - 51.9p (pre market) £90m - Trading Update (AGM) - Paul - AMBER
Another ahead of expectations update, following the last one in Oct. Heavy debt remains the biggest issue here, but improved trading means it expects to comply with covenants when they're reintroduced. It's been a good trade so far, but not sure I'd want to hold this low quality, indebted company long-term, where its track record has been poor.
Begbies Traynor (LON:BEG) - up 0.3% to 130.4p (£205m) - Half-Year Trading Update (in line) - Graham - AMBER
A solid update from this insolvency practitioner, confident of meeting full-year expectations for FY April 2024. I admire Begbies but continue to believe it is fairly valued. On the macro side, we might need to start thinking about when the current tailwind of higher rates will start to weaken.
Halfords (LON:HFD) - Unch 234p (512m) - Press speculation - Paul - AMBER/GREEN
Fresh bid rumours swirling in the press over a possible takeover/merger of Halfords by Redde Northgate (LON:REDD) . I bounce ideas around below. Surely Halfords is now required to make a statement, under Takeover Panel rules? I think it's a pretty good business, and a credible bid target, so I'm going up from amber to AMBER/GREEN.
Musicmagpie (LON:MMAG) - up 28% to 24p (£26m) - Response to speculation re possible offer - Paul - RED
Shareholders might be put out of their misery here with 2 potential bidders in early stage talks with the company. Given its very weak business model, profit warnings, now generating losses & accumulating bank debt buying secondhand phones, I remain negative on the fundamentals. But bidders don't necessarily see things the same way. Good luck to holders!
Polar Capital Holdings (LON:POLR) - up 2% to 461.2p (£467m) - Interim Results - Graham - GREEN
These are encouraging interim results: AuM is flat and profits are holding up. Against that, there is a slight dip in relative performance over three years, and a reducing cash balance. POLR’s shares are more expensive than its rivals but I consider this to be justified.
Cerillion (LON:CER) - unch 1,310p (£385m) - Final Results - Paul - GREEN
Very impressive results, which look ahead of forecast. Pricey shares, on a PER of 28x, but it's performing brilliantly. Very strong finances too. Small divis. Who knows what the future holds, but I can't see any signs of trouble in the figures or commentary, so I remain positive.
SRT Marine Systems (LON:SRT) - down 3% to 38.5p (£74m) - Interim Results - Paul - RED
[Quick comment, no section below] - Lousy H1 figures, as indicated in 6/10/2023 update. Expecting a gigantic H2 weighting.
It’s impossible to value this company, as its revenues/contracts are ridiculously lumpy, with seemingly no visibility. I’m not happy with the balance sheet either, despite another placing done near the end. It’s running up debt too, with £9.7m borrowings within current liabilities. It’s much too risky, and uncertain for me, so unfortunately I’m forced to shift to RED, to highlight the considerable risks here. Hopefully it will work out well for shareholders, but as always with SRT, that has to be more based on a leap of faith, than any certainty.
Thruvision (LON:THRU) - unch 20p (£29m) - Interim Results - Paul - AMBER
Promising-sounding products, but it warned on profits on 2/10/2023 when a big expected order from US customs fell through. Raised £3.2m in a placing in Oct 2023. Poor H1 - only £3.5m revenues, and £(1.6)m LBT. Balance sheet should be OK since placing done. Intriguing comments about Pentland (51% owner of JD Sports Fashion (LON:JD.) ) taking a 10% stake in THRU - could it be a takeover target I wonder? Outlook section says expecting strong growth in H2 and beyond.
Paul’s opinion - I was amber/red at the last profit warning, but it sounds as if things might be improving a bit. Speculative, but I do think there’s something interesting here, so I’ll shift up to AMBER. Still a loss-making, rather jam tomorrow company though, at this stage.
Paul’s Section:
McBride (LON:MCB)
51.9p (pre market) £90m - Trading Update (AGM) - Paul - AMBER
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides the following trading update ahead of its 2023 Annual General Meeting.
The current financial year is FY 6/2024.
Looking back through our archive, trading updates have been improving this calendar year -
28/2/2023 - Moves back into operating profit. (RED)
14/7/2023 - Top end of forecast range for FY 6/2023. (AMBER/RED)
19/10/2023 - Ahead expectations TU. (AMBER/RED)
We would have been amber or green, were it not for the huge debt load (and high interest costs), which shouldn’t be ignored. Although as trading performance improves, debt becomes less of an issue. It also gives leveraged upside to equity holders if a highly indebted company trades it way out of trouble without needing a placing. The bank has been very supportive to date as well, with generous relaxation of covenants.
Current trading - is also ahead of (presumably increased?) expectations -
The Group has continued to trade ahead of our expectations in October and the early part of November, mostly a result of the continuing consumer shift to value driving strong demand for our high-quality private label products from our retail partners.
For the first four months of the current financial year, overall volumes were 8.2% higher compared to prior year, with private label volumes growing 11.7%.
Interesting what they say there about consumers switching to cheaper products.
I’m not sure why the above quotes volumes. Surely value is more important to investors? Presumably value would be more than 8.2% up, given likely price rises to MCB’s customers? So why not disclose the number?
Debt & covenants - is still very high, but rising earnings means a 2x EBITDA multiple by 6/2024 year end is much more manageable. Good progress being made, by the looks of it. Also encouraging news on the (currently suspended) covenants - so it's off life support, and is now comfortable, and recovering -
Net debt reduction is progressing well and at our half year of 31 December 2023 we expect to be fully compliant with debt cover and interest cover banking covenants, some nine months ahead of when testing recommences in September 2024. By our year end of 30 June 2024, we anticipate net debt / adjusted EBITDA will be close to 2x.
Outlook - this is the closest we get to an outlook statement, which sounds cautious I’d say. Or is this just the standard type of macro uncertainty that we’re hearing from many companies?
With only four months of the financial year complete, the Group remains alert to the possible risk to full year results from world events which could lead to macro-economic instability and potential increased volatility in commodity markets and ultimately into further input cost pressures.
That seems OK to me, it doesn’t indicate any company or sector-specific problems. Just potential risk that’s outside their control.
It would be interesting to hear whether MCB has managed to improve its business model through hedging of costs, and pass-through contracts with customers? The danger is that every time something unexpected happens, MCB gets walloped.
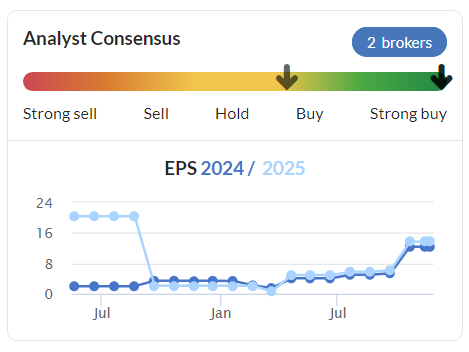
Broker updates - nothing available. This is a recurring problem with MCB, it’s leaving private investors in the dark. So City insiders get the detailed information, and we have to wait for the scraps to fall from their table when the broker consensus graph is updated.
As you can see below, there’s be a lovely upward progression in EPS forecasts, so this turnaround does seem to be working - hence why the share price has been recovering this year.
Paul’s opinion - I like the turnaround here, so a thumbs up for that.
Although it’s not a business that I would want to invest in long-term, due to the low margins, and as we’ve seen in recent years, vulnerability to unexpected input cost increases.
There’s also the issue of substantial debt. This was £166.5m at 30 June 2023, less £5.5m lease liabilities, so £161m bank debt. Note that last year, interest on bank debt was £11.1m, plus another £12.2m costs for “independent business review and refinancing”, so the bank has certainly got its pound of flesh out of this (not to mention all the advisors on the gravy train).
Getting debt down to 2x EBITDA by 6/2024 sounds impressive, but bear in mind that EBITDA is a long way from profit. Last year, it made £34m positive adj EBITDA, but free cashflow was slightly negative, at £(2.2)m. The P&L was only a whisker above breakeven at £0.3 PBT, which ignored £15.4m of one-off refinancing costs. So an overall loss of £(15.1)m.
This year looks as if it’s going to be considerably better though. The StockReport is showing forecast (before any possible upgrades today) EPS of 12.4p, which is £21.8m net (after tax) profit. That doesn’t leave much scope to pay down debt, let alone pay any divis.
Overall, I can see why the share price has recovered, because MCB is no longer in the “could go bust” tray. But it’s still very much in the “has loads of debt” tray, which means the prospect for generous divis is very small, and it would in any case be unwise to pay big divis whilst burdened with excessive debt (and a pension deficit).
Am I worrying too much about the debt? Possibly, and the forecast PER of only 4.0x does factor in a big discount for this problem.
Note there’s also a pension deficit, requiring £4m pa in recovery payments (cash), which further reduces cash available for divis.
On balance, with another positive trading update under its belt, I feel obliged to shift up to AMBER. Although bulls might need to avoid getting too carried away, there are still significant issues here.
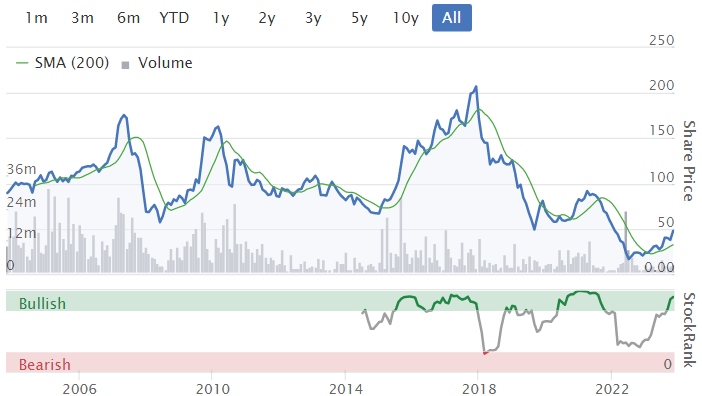
Long-term it's been lacklustre, it's just not a very good business, with little pricing power, and lots of competition I'd say -
Halfords (LON:HFD)
Unch 234p (512m) - Press speculation - Paul - AMBER/GREEN
We covered this car/bike superstores and servicing/repair group here on 13/10/2023, when Betaville (bid rumour website) apparently claimed that HFD was a potential bid target. The price spiked up 19% to 216p, but then almost immediately fell back down again. HFD didn’t publish any statement re the rumours.
Interestingly though, the share price has now climbed back up again, and beyond to 234p.
I gave it the once over on 13/10/2023, concluding that the bid rumours seemed credible, as HFD looks reasonably priced, and could credibly become a bid target in my view.
Anyway, the latest bid rumours which I think originated in the Telegraph, suggest that vehicle hire group Redde Northgate (LON:REDD) (which we like here as a value share) might have proposed a nil premium merger with Halfords. Given that REDD has the larger market cap at £836m, compared with HFD £512m, then it would probably be better seen as an acquisition of HFD by REDD. But given REDD shares are so lowly rated, at a PER of 7.1x, 6.7% yield, and P/TBV of 1.11, why would REDD shareholders want new REDD shares issued to fund HFD which is valued on a higher rating? Surely that would needlessly dilute REDD shareholders, and how would buying HFD add value or synergies?
Both companies know about cars, but apart from that it’s difficult to imagine any particular benefits from combining the companies.
Neither company seems to have issued an RNS. I thought they are obliged to say something if takeover rumours swirl, under the (unsatisfactory) Takeover Panel rules, which allow a false market to happen in target companies' shares, often for months?
Here’s an excerpt below from the Takeover Panel rules. It seems to me, that having twice been the subject of press speculation re bid approach(es) for Halfords, this must have triggered these requirements, surely? -
2.2 WHEN AN ANNOUNCEMENT IS REQUIRED An announcement is required…
… (c) when, following an approach by or on behalf of a potential offeror to the board of the offeree company, the offeree company is the subject of rumour and speculation or there is an untoward movement in its share price;
(d) when, after a potential offeror first actively considers an offer but before an approach has been made to the board of the offeree company, the offeree company is the subject of rumour and speculation or there is an untoward movement in its share price and there are reasonable grounds for concluding that it is the potential offeror’s actions (whether through inadequate security or otherwise) which have led to the situation;
Paul’s opinion - HFD needs to issue a statement to tell the market what (if anything) has been going on.
I’m upping my view from amber to AMBER/GREEN, as HFD looks a credible bid target to me, given that it’s profitable & cash generative, and has a dominant brand in its niche.
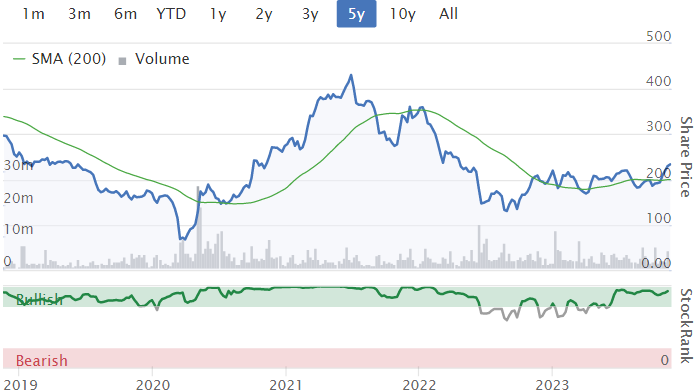
Note that the share count rose about 13% from 200m to 227m during the pandemic. Also note the very high StockRank -
Musicmagpie (LON:MMAG)
Up 28% to 24p (£26m) - Response to speculation re possible offer - Paul - RED
The Board of musicMagpie notes the recent speculation and confirms it is in early-stage discussions with both BT Group plc and Aurelius Group (together "the Parties") as to a possible offer to acquire the entire issued and to be issued share capital of musicMagpie.
Discussions between the parties are ongoing and remain at a very early stage. Accordingly, there can be no certainty that any offer for the Company will be made from either of the Parties, nor as to the terms of any such offer. Accordingly, shareholders are advised to take no action at this time. A further announcement will be made as appropriate.
This looks like one of those announcements which could have been deliberately leaked, to get the company into play, and see if any other bidders surface. Takeover Panel rules have now kicked in, so we'll get a daily deluge of 1%+ holder disclosures now.
Why anyone would want to buy this company is beyond me. Although as we’ve seen with some very surprising bids this year, acquirers sometimes see things completely differently to how stock market investors perceive a standalone company.
MMAG has been a very poor investment, losing c.90% of its 2021 (again!) float price. It was one of many opportunistic pandemic boom floats, wildly overpriced, based on only fleeting profitability.
Every time I review MMAG’s results, I just cannot see that this is a viable business. It’s building up bank debt buying used phones/tablets to rent out, but it doesn’t make a profit from doing this. So what’s the point?
Maybe MMAG’s kiosks in ASDA have caught the eye of the EE mobile part of BT, as a way to recycle mobile phone handsets? That seems credible, and it could stack up if much greater volume is pushed through MMAG's established kiosk network.
Aurelius seems to be an investment firm, so a financial buyer.
Paul’s view - I have a very dim view of MMAG shares, because profitability has collapsed, so it’s now loss-making and accumulating bank debt on what seems an irrational, and deeply flawed business model. So it’s certainly not negotiating from a position of strength with potential buyers.
That said, it’s conceivable that the potential buyers might see things more positively, especially BT/EE, which strikes me as a potentially good fit for MMAG.
The fundamentals are dreadful, so I have to stick at RED, but there’s a chance shareholders might be given an exit in a takeover bid, especially with apparently 2 named parties interested. It will be interesting to see how this develops, and good luck to any holders, I hope it works out well for you! We like to see readers make a bob or two, even if it’s in a pretty rubbish company like this.
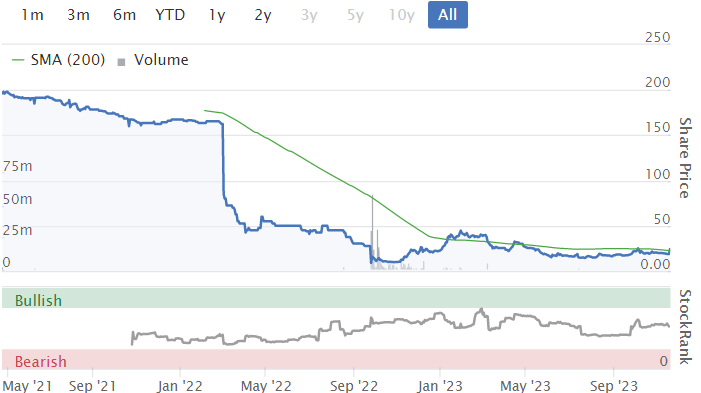
Very weak historical track record, apart from the one-off pandemic boom -
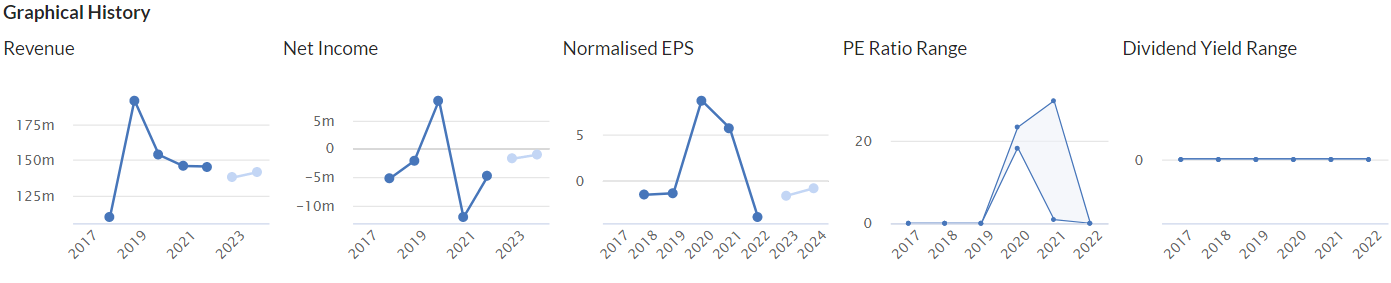
Cerillion (LON:CER)
Unch 1,310p (£385m) - Final Results - Paul - GREEN
Cerillion plc, the billing, charging and customer relationship management software solutions provider, presents its annual results for the 12 months ended 30 September 2023.
Record financial performance
Strong platform for continued growth
Feast your eyes on this highlights table!
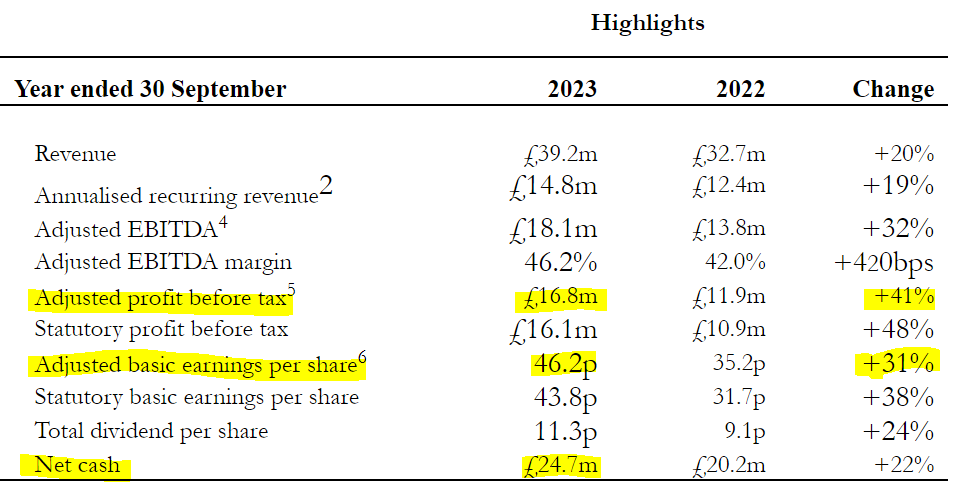
Another year of excellent growth, and the 46.2p adj EPS looks a beat against the consensus of 43.1p shown on the StockReport. Yes it is a beat, I’ve just confirmed that to a recent Liberum note (many thanks) dated 2/11/2023 which forecast 42.6p, so today looks an 8.5% earnings beat. Very nice.
The PER is a lofty 28.4x - you have to pay up for quality and growth, as they say. And of course hope that nothing goes wrong and growth doesn’t slow.
Hence we need to focus on the forward-looking facts & figures as of key importance.
Order book -
Back-order book3 at £45.4m at the financial year-end (30 September 2022: £45.4m); now at a record £52.5m following the recent €12.4m contract win with a new European Tier-1 customer.
Pipeline - very substantial, and rising nicely, at over 6x revenues, but of course only part (unknown %) of this will turn into actual contracts -
New customer sales pipeline7 up 16% to a record £243m at 30 September 2023 (30 September 2022: £209m)
Note 7 New Customer Sales Pipeline is the total, unweighted value of all qualified sales prospects.
Outlook - this sounds confident, and positive to me -
The Company is growing strongly, and its product-based SaaS approach leaves it well placed to continue to benefit from the broad range of positive market drivers, as discussed above. We are also encouraged by the increasing visibility the brand is gaining in what remains a huge marketplace. Our recent Tier-1 new customer win reflects this and Cerillion's inclusion in two Gartner Market Guides* (which evaluated suppliers based on product portfolio, geographic spread and progress in the last year), published earlier in 2023, also highlights the Company's growing reputation and the breadth and completeness of its product portfolio.
Looking ahead, the recent new customer win, ongoing implementation work with existing customers, and the major new deals signed with existing customers all create a strong platform for further growth. The back-order book, now at a record £52.5m, underpins revenue visibility, and the new customer sales pipeline, also at a new high, contains large deal opportunities. This leaves Cerillion well-placed to deliver another strong performance in the new financial year and beyond.
Cerillion's financial position remains very strong, supported by significant net cash, increasing levels of recurring income and strong cash flows. We therefore view the future with confidence and will continue to invest across the business to support ongoing growth.
Balance sheet - very strong. NAV £36.9m, NTAV £32.5m, including cash of £24.7m and no interest-bearing debt. I ignore lease liabilities, which are minimal here at £3.2m anyway.
Receivables are rather high, note 13 shows this is mostly “Contract assets” (also called “accrued income”) of £15.5m - ie work done but not yet invoiced (eg pending contract performance milestones), nicely explained in the text of note 13.
Within creditors there is also (rather confusingly) “Deferred income”. This is the creditor relating to cash that’s been received up-front by customers.
Let’s move on. It’s all fine, I think, although I would ask management for more detail on why receivables overall are pretty high, relative to revenues.
Cashflow statement - very good, but again this flags up the increase in receivables of £6.5m, which has absorbed about a third of the £18.1m cash generation.
Capitalisation of development spend is modest at only £1.1m, showing conservative accounting I think.
Dividends cost £2.9m, with a very modest yield of only 0.9%, but there’s scope to raise divis in future I think. But you don’t expect a large yield on a share with a PER of 28x.
Paul’s opinion - fantastic figures, and a full valuation to reflect that.
I’m reassured by the forward-looking comments, and it does seem that CER is in a sweet spot where there’s increasing acceptance of its cloud products, in a huge global telecoms market.
Something unknown could go wrong of course, but based on the facts, figures, and forecasts we have today, I can’t help but retain my GREEN view of CER shares.
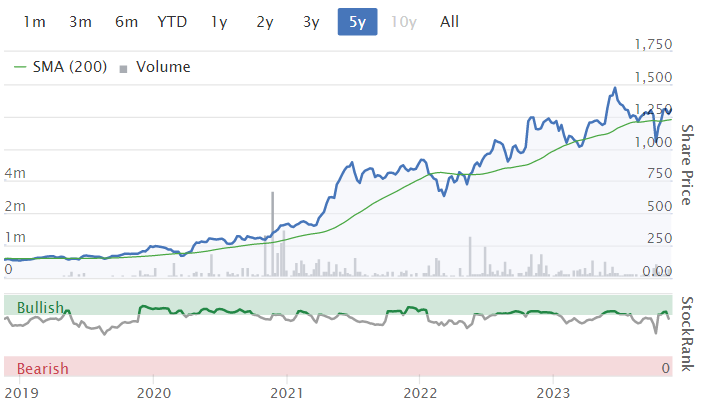
Graham’s Section:
Begbies Traynor (LON:BEG)
Share price: 130.4p (+0.3%)
Market cap: £205m
Begbies Traynor Group… the professional services consultancy, announces an update on trading for the six months ended 31 October 2023.
The past five years have been a pleasant time to own shares in this insolvency practitioner, although the share price has been range-bound more recently:
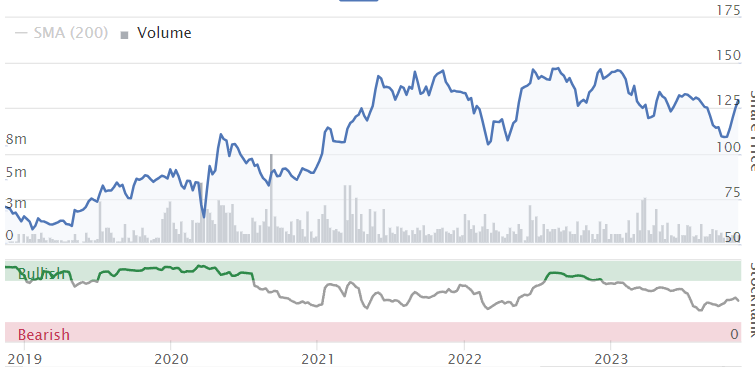
Today’s update confirms that the company is “confident of delivering full year expectations”. Here are the key points from H1:
Revenue and adj. Operating profit both expected to increase by c. 13% (organic plus acquired growth).
Adjusted PBT expected to increase by c. 10% due to higher finance costs.
Net cash as of October 2023 of £1.1m, thanks to strong free cash flow over the six months.
The range of forecasts for adjusted PBT, as compiled by the company, is £21.9m - £22.5m.
So with a market cap of about £200m, these shares could be considered to offer reasonable value. But remember to apply 25% tax, so that adjusted net income is around £17m. Also remember that the accounts are full of adjustments, and the balance sheet offers little by way of tangible asset backing. Value investors might not find everything they are looking for here.
Operational highlights:
Insolvency teams are “busy with increased year on year activity levels”. Overall volumes are “continuing to increase in current interest rate and inflation environment”.
Comment by Exec Chair Ric Traynor:
With 80% of income generated from counter-cyclical and defensive activities, and a strong balance sheet, we remain well-positioned to continue investing in and growing the business."
Graham’s view
Please check the archives for our full coverage of this share. Paul and I tend to have a fairly similar view on this one; my most recent view on it was neutral in July (at a share price of 132p).
At a share price of 130p today and with an outlook in line with expectations, not much has changed:
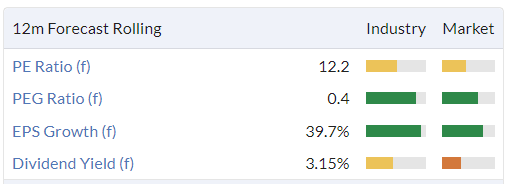
This seems fair value to me for a professional services company with a very good track record and with a mixture of organic and acquired growth. Generally speaking, valuations in this sector should be more modest than other sectors.
Note that the Bank of England is widely expected to start cutting rates again in 2024 and into 2025. Therefore, while there might currently be large numbers of zombie companies heading for extinction in the short-term, financial conditions might start to ease again over the next two years. This will eventually reduce the pressure on companies to undergo insolvency.
I’m guessing that the next two years will also see the start of a new bull market in UK small and mid-caps. When this happens, I don’t think I’d want to have a very large position in a counter-cyclical and defensive stock like Begbies!
Polar Capital Holdings (LON:POLR)
Share price: 461.2p (+2%)
Market cap: £467m
This fund manager has not been de-rated as severely as its peers since 2021, though it is still down by about 50%:
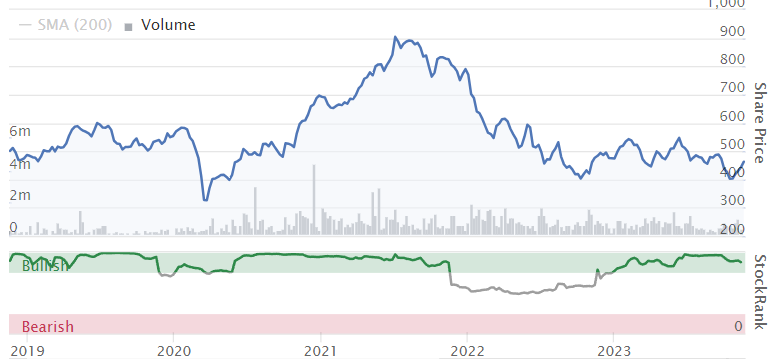
Its fund range can be viewed here. It has a particular emphasis in technology and healthcare.
Here are the highlights from today’s results for the period to September 2023::
Asset under management £19.1 billion, about the same as March 2023.
Net outflows £581m in H1.
In H1 last year, there were outflows of £753m (plus some other outflows relating to fund closures, buybacks, etc.). This rose to £1.5 billion of net redemptions by year-end.
In this context, £581m of net outflows from Polar in H1 of the current year can be seen as an improvement.
As for profits, we have:
“Core operating profit” £22.5m (H1 last year: £25.8m)
PBT £21.1m (H1 last year: £23m)
Core operating profit excludes a range of items which aren’t essential to the business of fund management, including performance fees.
These H1 results from Polar are a mixed bag: core operating profit is lower, but the reduction is offset by fewer exceptional costs. In the end, it’s a solid result in the circumstances.
EPS comes in at 16.2p, which in theory (with perfect cash generation) is sufficient to fund the interim dividend of 14p. There has been a question mark over the sustainability of the payout; Stockopedia puts the yield at around 10%.
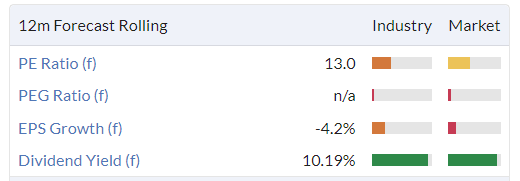
Balance sheet: net assets of £123m (of which about £108m is tangible). It was stronger a year ago, but should still provide investors some comfort.
CEO comment:
"The past six months have been a challenging period for equity markets driven by a volatile macro environment. Like many of our peers, Polar Capital has not been immune from these challenges, but net outflows as a percentage of opening AuM have been relatively modest, and in fact, have materially slowed vs the prior comparable period. This was helped by net inflows into a number of funds…
"Long-term performance remains positive across the UCITs fund range with all funds bar one in the 1st or 2nd quartile of their Lipper peer group since inception. More recently, 77% of Polar Capital's total AuM is in the top two quartiles of the Lipper peer group calendar year-to-date.
Performance across Polar’s funds has weakened on a three-year view (only 48% of AuM in the top two quartiles) but remains good in the short-term and when you view funds since inception.
Graham’s view
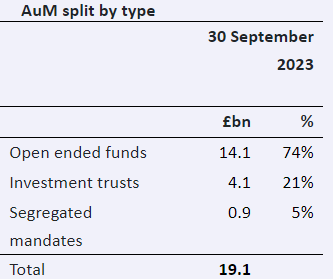
I continue to rate this one highly within the fund management sector. Note that not all of its AuM is open-ended and therefore vulnerable to quick withdrawal:
There is also an important specialisation in the technology sector (and to a lesser extent in healthcare and insurance):
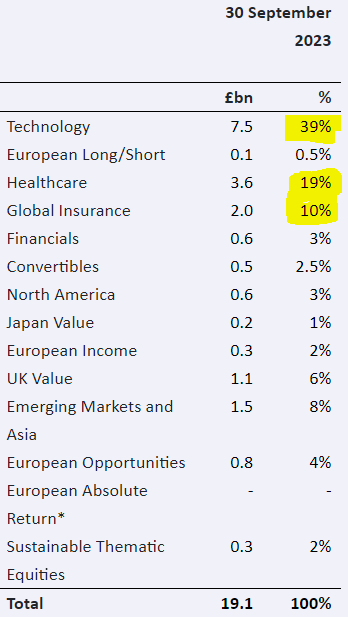
Combine that with outflows which are moderating, and I think the overall picture here is encouraging. AuM is about flat year-on-year. No reason at all for investors to be despondent, in my view.
This is reflected in a valuation that is far more premium than others in the space. Investing £1 in Polar shares today only gets you about £42m of AuM (compare that to others we have covered in this report recently - example).
So this share isn’t offering deep value, but it is offering a high-quality company at a reasonable price, in my view. So I’m giving it the thumbs up.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Polar Capital Holdings (LON:POLR) - Investor Presentation video recording is here:
?si=RIGsPvEflNeajQd7Polar Capital Holdings (AIM: POLR) ran viewers through key details of Interim Results for the period to 30th September, which was a challenging macro environment for equities. Gavin Rochussen (Chief Executive Officer) and Samir Ayub (Finance Director) highlighted the group's strong balance sheet, the decrease in outflows helped by inflows into a number of funds, and strong performance across their range relative to the Lipper peer groups. Management also answered a range of questions from viewers.
Rua Life Sciences (LON:RUA) - link to new note: https://www.equitydevelopment....
In place of a trading statement that updates investors on the progress of its revenue-generating businesses and its products in development, RUA’s strategy update has been well-received by investors because it outlines the path of the business to greater and earlier revenues than we had expected in RUA Contract Manufacture and RUA Structural Heart. The strategy also lowers the risks for investors compared to funding the development of RUA’s products solely by an equity offering, at a time where life science markets are depressed and the potential dilution punitive.
RUA Contract Manufacture, the contract manufacturer of medical devices using implantable fabrics with a biocompatible Elast-Eon coating, is responding to a formal bid request that could result in around £2m in revenues, with much of that recuring on an annual basis. Thus, RUA’s board’s objective of doubling the scale of the contract manufacturing business in the medium term is on track.
Just taken a look at Cerillion (LON:CER) final results. Probably not really adding anything as already covered by Paul and people in the comments, but I've made it for myself so may as well post. On my watchlist as a very strong company in my opinion. In hindsight I should have bought when it dipped below 1000p, oh well, plenty of other stocks for now.
Did you know that the Dow Jones 30 Index weights companies by their share price and not market cap? So Apple (NSQ:AAPL) (MC £2.37t at $190) is less weighted than Unitedhealth (NYQ:UNH) (MC £398b at $534)!
https://www.slickcharts.com/do...
ME International (LON:MEGP) continues to look weak, thought might start rising in to update next week but alas not yet.\
Tempted to add but keeps dropping!
I just sold last week!
For what reason may I ask?
I've loaded up on ME. Hoping for positive news. Got some lovely moats and chucks off plenty of cash.
any thoughts on MTI Wireless?
Somero Enterprises (LON:SOM)
Thought this might be of interest in relation to Somero
Journeo (LON:JNEO) one of my current favourites seem to be going up a lot today on no news.
Does anyone know if they were tipped or something over the weekend? Volume is low so I’m assuming not but clearly some buying going on.
ST weekend coverage.
Ah - makes sense then. Thx
ST? Sunday Times? I have an on line subscription, but cannot see any comment.
Simon Thompson
Good, currently + 7.9 today
Good Energy is giving off Good Energy ...I'm here all week
I bought a very small holding on the 25/10 when it appeared in the Zulu Principle Guru Screen. I think I'll buy some more.
PROCOOK (LON:PROC) has climbed from 18.25p to 24.5p in the last month. Founders own a big chunk of the equity. Could there be interest from Fackelmann in this owner operated Co.? They have accumulated 13% so far. Mkt cap £24m.
PROCOOK (LON:PROC) I am not very impressed with their products, sadly ! Mrs bought some non stick pots which were good. Followed up by some baking trays (non stick wearing off) and kitchen knives (showing signs of rust") which is sad given this is a UK manufacturer and the products are not exactly bargain basement.
Begbies Traynor (LON:BEG) - I have previously seen worries from other investors they might be adjusting out the pay of senior staff kept on post acquisitions as an acquisition related cost - which in some cases would be a very significant adjustment. Has anyone else looked at this before? When I get a bit more time I will try and probe a bit more but would be interested to know if anyone has looked at this before.
Hi Paul, seeing as we're on a roll with J D Wetherspoon (LON:JDW) and you've gone from zero to hero in no time at all as a Spoons customer, and noting your weekend comment that you'd rather not take advertising on your podcast, and that you'd even like to buy a few Wetherspoon shares, then how about approaching Tim Martin for sponsorship? Something like 'Scotties Shares Sponsored by Spoons' has quite a nice ring to it. You could even get him on for an interview, that would be entertaining! I notice there are three Spoons in your town, maybe you could go on tour signing beer mats, or Spoons could even host a live podcast...
More seriously, thank you for the latest podcast, required listening, great for catching up, summing up, cheering up!
And by far the best one is on Poole Quay although admittedly it’s far more attractive in the summer months !!
It can be difficult to find a seat in some 'spoons lately.The big, two floored Brighton Spoons was heaving and completely packed out yesterday on a dark, dank Sunday late afternoon.Had a look around and waited for ten minutes then decided to try the smaller one on the main drag up to the station.Managed to nab one of the last seats there.
Very anecdotal ofcourse but business seems to be brisk in Brighton.I didn't get the impression from overhearing conversations that many were their analysing and/or discussing finance and stocks and shares in the one i got a fish supper in in Brighton though.There's yet another one in the marina which i've yet to try out.
Could anybody point me to where I need to search for the Richard Staveley video mentioned on Paul's podcast please? The only thing I can find is from 4 weeks ago. Thanks
I’m not too sure on the Mello video but I believe Paul Hill is interviewing Richard today on Vox. Hopefully that will be available in the next few days.
Thanks Craig.
Look also on the Rockwell website at the Investor Presentation.
Mello videos are generally only available to subscribers to Mello Monday, but as the Funds webinar was free, providing one registered, you might be able to watch it. You need to go to
https://melloevents.com/
Alternatively Richard Staveley has given similar excellent presentations on
https://investormeetcompany.co...
where you can see his July presentation of Rockwood's prelims, in which he describes his investment approach and covers the companies in the portfolio. You need to register with the website, but once you have done so, the presentation is free to view. Quicker still the presentation is available on the Rockwood website.
Investment Trust - Rockwood Strategic
Thanks Jonno
McBride (LON:MCB)
'With only four months of the financial year complete, the Group remains alert to the possible risk to full year results from world events which could lead to macro-economic instability and potential increased volatility in commodity markets and ultimately into further input cost pressures'. So that's a 3rd of the year to go - could have easily said 'just over half-way through' that and the focus on volumes and not prices sounds like a case of getting your defence in early to me. I don't hold and am unlikely to.
Stereotype announcement by a sensible management.
I do hold from 25p ( when Boon mentioned this one and after a careful and extensive research I took a long position ) and I am unlikely to sell as this will easily be over 100p.
Investors and commentators are missing here that revenue will be over 1B and input costs are stabilising. It’s very rare as well for EBITDA and market cap to be about the same. Mr Market hasn’t missed that though.
Return of dividend next year as well.
I'm glad that you are still holding McBride (LON:MCB) ! I regret now selling a few weeks ago at 50p. Was worried that their customers will now start squeezing them on margins, with raw material prices moderating and also volume growth moderating. Coupled with their still-high debt load, I thought it was the smart move to take profits.
I was wrong... should have held on, as positive trading momentum can be sustained for longer than one thinks!
You were right and spotted this very early on and thanks for sharing this with the community. I was not familiar with this company.
After a lengthy research and an indication by the management that input costs were stabilising , this was no brainer. But the announcement that convinced me 100% about the turnaround ( and added to my holding ) was the payment of £5m to terminate the upside sharing mechanism.
Same will probably happen with On the Beach group plc and Nanoco plc (both still very cheap) ; that can easily double from here.
Other way round, alsy933. They still have two-thirds of the year to go, so not yet half way.
Polar Capital Holdings (LON:POLR)
I have had a reasonable position for some time, so currently 'under water' as is said.
My thoughts are that it is a well managed niche asset manager, not acquisitive like Liontrust Asset Management (LON:LIO) . It looks to build a presence in a particular themes/sectors organically which I much prefer. Also I use it as my exposure to technology. I don't hold any tech shares directly as in fairness I don't fully understand them and even if I did I wouldn't be prepared to pay the asking price for many of them, with particular reference to the American behemoths.
Polar Capital Holdings (LON:POLR) currently pays a a handsome dividend, which assuming it is trading at or close to the nadir, I think will be maintained. Finally for what it is worth it is a significant holding in North Atlantic Smaller Companies Investment Trust (LON:NAS) run by Christopher Mills and has been for quite some time. Whatever you think of Harwood it is in my view the most accomplished investor in UK small caps. I include in that Richard Staveley at Rockwood and Stuart Widdowson at Odyssean, which are part of the Harwood stable.
You will be interested to know that Polar Capital and Rockwood are both presenting twice and Christopher Mills will be speaking in the main theatre at the Mello London conference next week. Ed Croft is also in the main theatre and Paul Scott will be there too.
They are great face to face events so do support them or they will be lost to the webinar world
Begbies Traynor Group (LON:BEG) a solid TU on H1, ahead of interims on Dec 11th. Ahead of detailed results we retain forecasts and a Fair Value of 175p/share. Summary new note with audio here https://www.equitydevelopment....
Steady steady progress with Begbies Traynor (LON:BEG) - so much so that today's update didn't cause any movement in the share price!
Disappointing through that there seems to be no operational gearing. Adj operating profit and Adj PBT are roughly the same growth as Revenues. When you would expect there to be some gearing in the growth, especially as part of it coming from acquisitions (so there must be some cost synergies to extract?)
An acquisition strategy that doesn't create more value for the "whole" is a dangerous one, as there is no value-add. Just taking on risk of value destruction (with a bad acquisition or mispriced acquisition).
Will analyse more when I have time available, but having held this for a few years now, my conviction is not as strong as when I started.
(I hold in the Boon Fund)
I wouldn't expect much in the way of operational gearing - for that you need relatively fixed costs, but for something likes Begbies Traynor (LON:BEG) more work will generally require more (highly paid) staff.
"AHT.L opened down around 14% on Monday after the equipment rental firm cut its guidance for annual profit due to weaker levels of emergency response activity and strikes of Hollywood writers and actors."
It's a share I looked at not all that long ago, but dismissed. I think I didn't like its share rating or debt level, or something. Now that I look at it again it doesn't look so bad.
I seem to recall that it was owned by some fairly prominent UK growth investment trusts, but I can't seem to find out who they are.
These are just my observations in passing as it caught my interest today.
I was a holder until 5 minutes ago :-(
I have sold on the basis that "the story has changed" i.e. the reasons I bought no longer hold true - basically EV to PBT above what I am comfortable with for a heavily indebted company with no PBT growth this year and interest rates looking higher for longer. I do still believe this is a very well run company operationally.
"Full-year guidance and outlook
The Group expects to deliver record full year results. However, reflecting the factors above, we are revising our full-year revenue guidance and earnings expectations:
●
We now expect both Group and US rental revenue growth in the range of 11 to 13% (previous guidance for both: 13 to 16%), which will result in EBITDA being 2 to 3% below current market expectations.
●
In addition, we now expect a full-year depreciation charge of c. $2,120m and a net interest cost of c. $540m which will result in adjusted profit before tax being below current market expectations.
●
Capital expenditure guidance remains unchanged at $3.9 to $4.3bn."
My notes below (should anyone be interested):
House broker reckons it is one-off - I hope so. circa 3% on EBITDA. Note in the above that a 15% increase in EBITDA only lead to a 5% increase in profits
Depreciation charge last year was $1,772. so that's $350 million more. Interest was $368 so that's $130 million more.
Last year 4.411 of EBITDA lead to 2,273
Taking the worst case (11% EBITDA growth) would be $2,276 million PBT v last year $2,273. So no growth at all.
now about level, I will continue to hold
Morning everyone. Another asset manager in Polar Capital Holdings (LON:POLR) releases earnings today. It certainly seems like we're nearing a turning point when looking at Polar. Looks like the consistent bleed in assets under management is slowing and if / when a bull run in small cap stocks comes along, they should return to growth.
I am wondering how they're going to continue the dividend at current levels though, which far exceed the cash they are generating. I also couldn't work out how they arrived at £2.7M of net cash in flow from operating activities from a net profit of £15.6M. Where did it go? Had a quick look through notes but couldn't find any numbers that add up. Could any one enlighten me? Maybe the coffee just hasn't kicked in yet. (I hold)
All the asset managers have been reporting at the moment. I did a snapshot for Liontrust Asset Management (LON:LIO) & Tatton Asset Management (LON:TAM) last week. I'll put a screenshot of them both here for quick comparisons.
There is a note explaining it.... a bit of everything is the answer afraid... reliance on Tech not a positive for me with this one.
Oh yes, thanks. I don't know how I missed that.
Thanks for this Phil P (and your previous posts, they're good). I have a small holding in Polar Capital Holdings (LON:POLR) , partly for the dividend, but also on the basis that if you buy at this point in the cycle (massive investor antipathy) then by the time the next bull market comes along then an increase in share price should be a given. The risk being that things get (much) worse in the meantime and / or I lack the nerve and ditch the shares, missing the recovery.
Anyway, the dividend clearly is at risk like you say, but how much risk is not clear. It's not covered by earnings (for the full year), but the company stated in the annual results:
"The Group's dividend policy is to pay an annual dividend within a range of 55% and 85% of adjusted total earnings, dependent on the scale of performance fees in the relevant year and the anticipated trading conditions for the following year. Where appropriate, the Group will consider using its balance sheet strength to support the dividend."
The adjusted total earnings bit is important, because this gives significantly increased EPS when compared to basic EPS (last year, basic was 36.8p, adjusted was 44.3p). But the dividend was 46p so already much higher than the 55-85% range, as far as I can see.
My (total) guess is that as long as conditions don't get much worse, then the dividend will be maintained at the current level, but that they'll use balance sheet cash to do so. How long that can last for, or whether that's right, is anyone's guess, but as long as they anticipate trading conditions to be better in the next year (Rodney) then they might hold it at the current level until the next bull market. That would be the ideal scenario but frankly who-t-f knows.
Cheers
Chris
General thoughts are that the board have already pretty much already signalled that Polar Capital Holdings (LON:POLR) will maintain dividend based on an expectation for markets to stabilise and earnings to tick up in the next year. So the only way I see the divi at risk from existing levels is if markets take another lurch down. As long as inflows are stabilised then even some small market uplift will shift earnings back to covered.
Hi Chris. I'm of a similar mind to you that the share price will more than likely go higher when the markets turn. This is one of the early individual stocks I bought so have held through the last part of the 2020/21 rally and then all the way down the other side. I've topped up in the 400-470p range though so position not too bad now.
I've enjoyed collecting the dividends which is really the first time I've held a stock long enough to notice some compounding (all re-invested). It does concern me slightly as they don't have a huge cushion in the balance sheet in relation to the size of the dividend. Paid out £30M in cash last interim, only £70M on the balance sheet. Like you say they have been above their previous guidance. So I think they can only maintain another year without improvement as cash has been steadily declining. But like you say who-t-f-knows. Thanks for your insight.
On dividend Polar Capital Holdings (LON:POLR) did say in an investor Q&A previously that they had an uncovered dividend in 2016-17 when the business wasn't as strong, they have the cash to support the current level, and they said sentiment would need to be far worse for them to consider reducing it. I took from that they have no plans to reduce it.
Diploma (LON:DPLM) What a little beauty this share has turned out to be. Revenue growth of 19%, organic growth 8%. Operating margins are even up a little. Good returns on capital.
It's one of the few shares that I've had the discipline to hold onto. I'm usually too hyperactive in my trading. I've held since late 2015, and it has served me well.
Forward PE of 23 will put a lot off, but this has proven to be one of those shares where paying up has proven to be the right thing to do.
I agree (added to my holding this morning). I haven't been in it as long as you, but if you haven't watched the Investment Seminar from June 2023, I can really recommend it:
https://www.diplomaplc.com/inv...
These FY 2023 results are excellent; I love the combination of high operating margin, focus on organic growth, high return on invested capital with low needs for capex, allowing free cashflow conversion at around 90% (TY:100%) to be used for acquisitions with high ROS %. Interestingly the bolts-on are being completed at c.5x EBIT and the platform acquisitions at around 9-10x EBIT.
Thanks. I'll take a look.
Cerillion (LON:CER) FY23 results a superb set of results, it certainly fulfils its Stocko description 'high flyer' and is one of those multi-baggers Ed was discussing in last week's webinar. Today's results:
Outlook: the market back drop remains extremely favourable to drive telco investment in enterprise software layer, which CER serves. They go on to say, in a slower growth environment for telcos there is an increased need to extract more revenue from existing assets and improve operational efficiency.
There's a management webinar on Friday 24 November at 11am where you can ask all your questions. Register here.
Cerillion (LON:CER)
Gartner were a new name to me so did some digging and found
https://www.gartner.com/review...
Note - Summary-level access to Gartner Peer Insights is free and available to the public. Reading the full detail of reviews is also free but requires a simple login.
I do not think this is the catalogue referred to but is interesting to see some reviews.
Two parties interested in acquiring MMAG. Why would BT (LON:BT.A) want to buy Musicmagpie (LON:MMAG) ?
BT gets a lot of second hand phones. Either trade-ins, or customer returns. Likely they already sell wholesale to the likes of Musicmagpie (LON:MMAG).
But apart from that, no idea why BT would see this as a worthwhile acquisition!
re BT (LON:BT.A) Just a thought, but if BT sells 2nd hand phones to MMAG and bearing in mind the big changeover with their domestic service - allegedly coming through this month, bringing with it a possible tsunami of older handsets, BT might be saving on costs etc IF they take over MMAG. ??
BT (LON:BT.A) now charge £2 extra, to keep your landline, just renewed my contract, without the phone. Hardly ever use it now. Most calls I do online for free.
MTI Wireless Edge (LON:MWE) Q3 results seem pretty good compared to the way the share has crashed since the outbreak of the war. Revenue seemed a slight miss but profitability is up 9%.
On the bull side the company continues to do well and will no doubt gain some revenue supporting the Israeli military. Long term I am a bit concerned if there will be a wider boycott of Israeli based companies, particularly ones who are supporting the military.
I have been a long term holder of this share and believe they have some great markets and have doubled my money over the time. I am concerned though about the wider impacts of the companies future being based in Israel and might consider dropping some of these or selling out if the company can recover some its price based on these results.
Polar Capital Holdings (LON:POLR) Navigating tough markets better than most - detailed research note with audio summary here: https://www.equitydevelopment.co.uk/research/navigating-tough-markets-better-than-most
AUM was slightly down by -0.4% to £19.1bn over H1-24 (to 30 Sep 23). This was however a relatively strong performance compared to most other asset managers. Amidst widespread sector outflows, only two from an 11-strong London-listed peer group outperformed Polar on AUM movement over H1, with some recording falls of more than 10% (see page 2).
Investment performance was +£546m, net flows -£581m, and fund closures -£50m. Average AUM was up on H2-23 but down y-o-y from £20.0bn in H1-23 to £19.4bn, with the H1-23 average still somewhat elevated as the full impact of Russia’s invasion of Ukraine had not hit markets (page 4).
We believe Polar is well-positioned to return to growth. It has an enviable track record of investment outperformance; its multi-niche strategy should prove attractive to asset owners; history suggests active management bounces back after market falls; and its net-flow position is certainly improving.
Our fundamental valuation is 575p per share, 27% above the share price, and the sharp falls in asset manager valuations look over-done to us, especially in light of recent M&A activity.
Good morning Paul and Graham. Mercia Asset Management's RNS might have missed you radar but Graham covered it favourably on January 16th mentioning it's fortress balance sheet and cash position. It's listed as a sucker stock on Stockopedia. We hold and today's announcement on a profitable sale of their stake in " n Dreams" to "Aonic"lifts Mercia's cash to c £60 million. Mercia got £26.4 million in cash plus £3.8 million in Aonic shares, A quick comment would be much appreciated if you have time.
I bought a few MERC at the open on this news,
By my reckoning the 17.5% premium for a stake, valued at 15% of assets, adds 2.625% to NAV, which increases the year end NAV per share figure of 45.4p to 46.62p.
As you say cash is now around £60m, which is 30% of the trusts £200m net assets, putting them in a very good position to reinvest, when valuations for the start up companies they invest in have come down significantly. Also, if we are at the bottom of the market, this could be the ideal time to invest
The shares opened at 24p to buy, a discount of 49%, which for such a good cash position looks extreme.
Incredible that these things are at a 50% discount and they have been for quite a while. I’m sure we’ll look back at things like this and question why we didn’t have more! It really looks a no brainer. There’s quite a few things like this at 40 to 50% discounts. The return of the IPO market may signal a sharp closing of these discounts.
I was looking at MERC the other day thinking that this can be a classic ST coverage for his 2024 share tips.
With this increased cash it will certainly be now ; probably management will use some of this cash pile for a tender offer close to its NAV.
My morning smallcap tweet: Pain reaction
Velocys (LON:VLS) Musicmagpie (LON:MMAG) McBride (LON:MCB) Develop North (LON:DVNO) Ilika (LON:IKA) Rua Life Sciences (LON:RUA) Mercia Asset Management (LON:MERC) MTI Wireless Edge (LON:MWE) Cerillion (LON:CER), Begbies Traynor (LON:BEG), Senior (LON:SNR), SRT Marine Systems (LON:SRT)
◄Velocys (VLS)► mooted rescue offer of 0.25p, a 66% discount. "Board recognises that it should assess the Proposal as a whole in light of the Company's very near-term funding requirements and significant long-term funding needs." [SP=0.68 Cap=11m]
◄musicMagpie (MMAG)► re speculation: early-stage discussions with both BT and Aurelius on a possible offer. Another terrible covid lockdown-riding IPO. [SP=18.78 Cap=20m]
◄McBride (MCB)► AGM stmt - continues to trade ahead of mgmt expectations in Oct and Nov. [SP=52 Cap=90m]
◄Develop North (DVNO)► £500k max buyback. [SP=75 Cap=22m]
◄Ilika (IKA)► reaches design-freeze milestone for first customer prototype release of Goliath battery. Will deliver batteries for testing over 6 months. [SP=29.5 Cap=47m]
◄RUA Life Sciences (RUA)► strategy review 18 months ago has "dramatically reduced the future funding requirements". Gets Bid Request for a product range for RUA's implantable textiles with possible rec £1.5m PA. [SP=15.24 Cap=3m]
◄Mercia Asset Management (MERC)► sale of stake in nDreams for £30.2m, split £26.4m cash and £3.8m re-invested into the buyer, Aonic. That's £4.4m above book. Net cash now c.£60m. [SP=22.2 Cap=99m]
◄MTI Wireless Edge (MWE)► Q1 to Q3 rev down 3%, pretax up 6% "helped by positive currency movements and margin improvement". Outlook sounds OK despite the Israel situation. [SP=32.53 Cap=29m]
◄Cerillion (CER)► FY-Sept. No current trading fig but outlook strong. [SP=1300 Cap=383m]
In line: BEG, SNR, SRT
So Kitwave (LON:KITW) has made an acquisition. We are not told how much they paid for it, nor how profitable it is. Only that its turnover is £10m. Not good enough!
I’m guessing,,, (why hide it otherwise) they’ve overpaid for a loss making/break even business - which they might be able to utilise H&B Clark’s scale to turn profitable. If that’s the case though why not say it.
waiting on a brokers note to understand the reality, which should’ve been in the RNS!
Not much at Companies House... https://find-and-update.compan...
WLG (Holdings) was only incorporated in 2019. Somebody may be able to glean more than me re the charge that was in place until 14-Nov-23.
Given the wealth of opportunities preumably available to Kitwave (LON:KITW) as a consolidator, I find it fairly difficult to believe they're the ones embarrassed by details of the purchase.
Agreed. Can see the share price falling as a result.
It’s private..owned by the Wild family who won’t want all their friends/neighbours & employees in & around Oldham to know their business..looks a good business to me
I have had business dealings with Wilds. I experienced very helpful service.
Very informative, thank you.
Kitwave (LON:KITW) (I hold) - when I read the comment about the share price falling on this acquisition my heart sank, but the chart (LSE, 15 minute) gives me no cause for concern. I think holders of Kitwave need to accept that there will continue to be takeovers, sometimes of small businesses, where detailed figures are not going to be revealed. The company says this: 'At Kitwave, we remain focussed on capitalising on the fragmented UK wholesale market and will continue to identify the best opportunities to deliver the most value for our stakeholders.' It comes down to whether you trust the management or not and the recently announced departure of the founder/CEO might give some cause for concern except that his successor is an internal appointment and I don't believe that overpayment for acquisitions is likely to be on his agenda.
Here's the link for my SCVR summary spreadsheet, now updated for last week's companies.
Podcast mystery shares were -
Renold (LON:RNO) (I hold)
Fonix Mobile (LON:FNX)
Something else - I'll have to listen back later, as I've forgotten the third one.
Thanks Paul for this and the weekend podcast - very flowing, insightful discourse.
MCBRIDE PLC
Another ahead of the already ahead of expectations results and debt coming down considerably.
The bonus though will be that they can commence their dividend policy as they will be close to net debt/adjusted EBITDA to x2 by year end.
.....but it would be dumb to pay a dividend while they still have a debt mountain?
Any company that can service their debt (and Mcbride do ) will be foolish not to pay one if their covenants allow them to. Mr Market thinks that as well.
Any company that can service their debt (and Mcbride do ) will be foolish not to pay one if their covenants allow them to
ref dividends there have been many companies doing ok one minute paying chomping dividends - then within 18 months they have been wiped out or had to massively dilute - imho its clearly nonsenical to pay dividends now "just because you can". I won't comment on Mcbride (each company should be judged on its own merits) but clearly just cos you can doesnt mean if you have little margin for error imho doesnt mean you should - for obvious reasons. I would say in this regard having large payables amounts (on credit) owed out can be similar risk even when there is no debt. Part of the problem here is that directors are often in no lose gamble situations - predict the future is goona be rosy if it goes wrong you still walk off and get your well paid job elsewhere - often their shareholding are so small they dont feel the pain like shareholders do - ref options losinagh potential bonus you should never have had in the fisrt place isnt really losing out imho.
We have covered this before (I think) and the share price has about doubled since then!
It’s about cash flows and nothing else; unless you think BP should do any buybacks or pay dividends because they have a debt that is being serviced and gradually coming down.
Last time I bought EBITDA equal to market cap the first one went up 900% (William Hill plc) and the second one went up 800% (PPC.AT).
All the best with your investments.
Meant : Shouldn’t
I think the problem i have is saying something should always be the case when clearly from my point of view is sometimes very sketchy paying high dividends. I am not knocking your specific plans here at all ref this one investment or any other specific investments - if any company does well in the future from such a low price to ebitda starting position to me its reasonably obvious the share price is going to do well whether the dividends were paid out to start with or not - dividends can turbocharge your returns if they are chunky so i am not even knocking the divi bit - just that it doesnt make sense for "all companies" to be doing this if their future is somehwat uncertain - or for example their might be uncertanty over interets rates and ability to service debt.
But this the issue here ; you just do not accept that they haven’t got a debt problem. They have a debt but they can pay it down gradually because they are generating a fair amount of cash flows now.
It’s different than Musicmagpie’s debt where it will never be paid back and the banks are probably pushing them to find a bidder before they go bust (reference as it was in the news today). Good luck to the bidder!
Mcbride plc has never (at least the last 10 years ) managed an EBITDA over £50m. Now they can achieve one close to £80-£90m.
McBride (LON:MCB)
But this the issue here ; you just do not accept that they haven’t got a debt problem. They have a debt but they can pay it down gradually because they are generating a fair amount of cash flows now.
I am not saying mcbride have any problems - my personal opinion is that it should be a red flag company due to what they owe out (trade and debt)- that doesnt mean the company necessarily has any issues as such - i just think it has less room for things to go wrong compared to other companies that are not reliant or debt or largesse of peeps that give them credit. Ref the red flag thats just my opinion its not worth anything more than anyone elses opinion - i dont think in the recent past i have made any suggestions that this a bad invvestment.
To me the red flag is simply there to say if one invests here be prepared to lose your shirt if it all goes wrong - not that the company is likely to fail. I have a (poorly performing) investment in marstons that i would happily flag up as being red flag to others due to the debt - albeit with that company i wish i had paid attention to red flags and sold befoire inflation kicked in - more the full me for ignorinng my own red flag lol
In sumamry i have nowt against mcbride - i am not saying its a bad investment - not disagreeing with anyone who thinks it is a good investment as i havent looked at it closely - but i do feel that from my point of view that red flag gets atatched to this company due to debt and large payables.
I think the third mystery share was REC?
Ah yes, that was it, £REC
Many thanks tablet! :-)
I enjoyed the boy band style singing Paul (genuinely!) More of that please :)
HAha great stuff!! My podcast DIY jingles are inspired by Harry Hill's TV burp. Here's a selection of his best ones -
?si=WUXaxyzZsFmHV2Gu
Great podcast as usual Paul, just finished listening. I second what some other people have said, that your openness adds a lot of value. Portfolio management, strategies, mistakes etc are all just as important as picking the right stock I think and hearing your personal successes & mistakes is always interesting.
I was very surprised when I realised you were talking about me at one point! Thanks for the 'Reader of the Week' accolade, the singing of it made it all the better! :)