Small Cap Value Report (Mon 21 Aug 2023) - RWA, CRST, FCRM, DPEU, 888

Good morning, it's Paul & Graham here today.
Podcast and my SCVR summary spreadsheet were both updated this weekend, so we start the week up-to-date!
Stelrad (LON:SRAD) - many thanks to all the readers who responded to my question last week about how the supply of radiators would be affected by a move towards heat pumps. It sounds as if it might even be positive for Stelrad (a manufacturer & distributor) of steel radiators, if people need to fit larger radiators in future. That's dealt with one of my concerns. The issue over high bank debt remains though. As I mentioned in the weekend podcast, a lot of housebuilding, and building supplies shares are now looking cheap, but there's mounting evidence from their trading updates that macro factors have pushed back any recovery into 2024, and another wave of forecast downgrades looks likely. Hence I'm currently wary of both sectors - it feels too early to be bottom fishing, now that an H2 2023 recovery seems to have gone for a burton (thanks to our friends at the central banks).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Robert Walters (LON:RWA) - 383p (£280m) - H1 Results - Paul - AMBER
H1 results came out on 1 August. I'm taken aback by the 70% fall in H1 PBT, which seems to be due to an ill-timed increase in overheads. With FY forecasts substantially reduced, I'm questioning whether this company is as good as I previously thought? Positives include generous divis, buybacks, and a strong balance sheet. I would have expected profitability to be more resilient, so can't go above AMBER now.
Crest Nicholson Holdings (LON:CRST) - down 14% to 167.3p (£430m) - Trading Update (profit warning) - Graham - GREEN
This housebuilder reports a sharp reduction in expected profitability due to lower transaction levels. I think that property prices will fall further from here but also suspect that this has been priced in already at Crest’s current market cap. Discount to NTAV is tempting.
DP Eurasia NV (LON:DPEU) - up 3% to 52p (£76m) - Update on Russian Business - Graham - AMBER
This rises on news that the Russian subsidiary will file for bankruptcy. It’s good news as the losses and the risks associated with Russia will finally be over. DPEU investors will hopefully be left with a good, profitable business in Turkey. Could be worth a second look.
888 Holdings (LON:888) - down 1% to 115p (£515m) - Holdings in Company - Graham - AMBER
[No section below] [Graham has a long position in 888] We don’t usually comment on a “Holdings” RNS, but I think it’s noteworthy that the former GVC/ Entain (LON:ENT) executives, through their consortium vehicle “FS Gaming”, have started to cut their stake in 888, after their proposals were rejected by 888. Formerly at a 6.6% holding, when they wanted to take control of the company, they are now at 4.5%. Why wouldn’t they sell all the way down to zero, now that their takeover plans have been scuppered? There are some regulatory concerns surrounding GVC/Entain’s historical conduct, and these could potentially have led to problems for 888. 888 should hopefully be able to move on now with a clean bill of regulatory health, although I suspect there will be continued selling pressure from FS Gaming.
Paul’s Section:
Robert Walters (LON:RWA)
383p (£280m) - H1 Results - Paul - AMBER
This is a backlog item, which issued H1 results on 1 August.
I’ve been meaning to review it, as it’s always struck me as a good company at a reasonable price. However, I see that forecasts for FY 12/2023 have reduced substantially, from around 50p EPS a few months ago, to c.30p now. Has the lustre come off this share, will I still rate it highly after seeing the latest numbers? Here at the SCVR we have absolutely no problem changing our mind, if the facts, figures, and forecasts change, that’s the only logical thing to do after all.
Although investors also need to think about the cyclicality of earnings through the economic cycle. If a company is having an unusually weak year because of a cyclical downturn in the economy, at some stage it makes sense to anticipate a recovery, and higher earnings. I’m not sure what stage we’re at, as the macro position is quite fluid & uncertain.
Recapping on previous SCVRs for background, we commented as follows -
6/4/2023 - GREEN - 424p - Solid Q1 TU, Mixed outlook. Roland saw valuation as attractive.
14/6/2023 - AMBER - 402p - Profit warning, FY 12/2023 “significantly lower” than exps. V strong bal sht, Paul thinks it should recover in time.
6/7/2023 - AMBER/GREEN - 417p - Q2 softer revenues. Short-term uncertainty. Paul still thinks it should be fine longer-term.
As you can see, given a string of disappointing updates and considerably lowered forecasts, the share price hasn’t actually been hit particularly hard, particularly given the weak overall small caps stock market. The main move down happened in March, before the above negative newsflow.
Here’s the 2023 YTD (year to date) chart, which still looks firmly in a downtrend -

Let’s have a look at the H1 figures.
Robert Walters plc (LSE: RWA), the leading international recruitment group, today announces its half-yearly financial results for the six months ended 30 June 2023.
It’s not clear if these are adjusted, or statutory H1 numbers, but they look poor regardless -
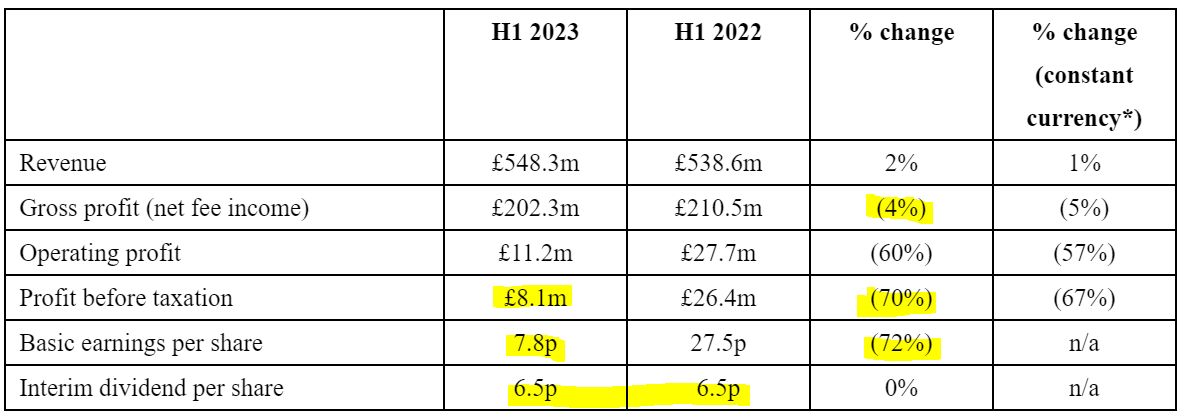
This needs some explaining! Why is PBT and EPS down 70%, when NFI is only down 4%? That seems odd. I suspect the reason is that RWA increased its overheads over the last couple of years, which as we’ve discussed here before, now looks ill-timed.
H1 dividend - is maintained at 6.5p, but note it’s now only just covered by H1 earnings.
Brokers are forecasting divis being maintained, with the yield an attractive 6.4%.
Share buybacks have been ongoing.
Contract/temps now generate 33% of revenue (up from 29%).
This is an international business - mainly Europe & Asia, which generate 76% of NFI - so we shouldn’t make any false conclusions about these results from how the UK economy is performing.
Current trading - “remains in line with Board expectations”
Sector comments - quite interesting for possible read-across to other shares -
Candidate and client confidence has been muted throughout the first half of 2023 in a continuation of the trend we first experienced during the second half of last year. Whilst recruitment market fundamentals such as vacancy levels, candidate shortages and wage inflation have remained relatively solid, job churn has reduced, and time-to-hire has lengthened and been compounded by a noticeable increase in buybacks as organisations fight to retain their top talent.
I’ve not heard the term “buybacks” from a recruiter before. From the context I presume this means companies offering people more money to stay put, when they announce that they’re leaving?
The technology and financial services sectors have been particularly volatile during the period. Large-scale technology layoffs have continued right across the globe, a rightsizing of the industry following the high volume of hiring to underpin the global digital transformation that has taken place over recent years. The collapse and merger of several banks during the first half also served to affect confidence levels across the financial services market worldwide.
Geographies -
On a regional basis, Europe and Asia Pacific, which together account for 76% of the Group's net fee income, proved to be most resilient with our blend of permanent, interim and contract recruitment underpinning growth in net fee income across Europe in particular. Our UK, US and Mainland China businesses have been most significantly impacted by the lack of client and candidate confidence and we have been and are acting in each market to mitigate the short-term pressure but with a sensible lens to ensure we are still able to quickly take advantage of any return in confidence.
Balance sheet - NAV is £166m, less intangible assets of £31m, gives a healthy NTAV position of £135m. That’s nearly half the £280m market cap supported by what is mainly working capital, since fixed assets are modest in this sector.
Net cash looks very healthy at £69.8m at 30 June 2023, meaning RWA has plenty of flexibility, strength, and of course the ability to keep paying divis and doing buybacks, despite the disappointing level of profit currently. It’s much better to hold high yielding shares where there’s pots of cash available for divis, rather than some other situations where divis are being paid out of bank debt.
Overall then, there’s nothing to worry about with RWA’s balance sheet, it’s solid, and well able to withstand an economic downturn, should it worsen.
Paul’s opinion - I’m unsettled by the sharp drop in profitability, because it’s not as if the world is in a recession. So if the first signs of trouble produce a halving of profit forecasts, then maybe RWA isn’t such a good business after all?
It seems to be in a tricky position where it’s increased overheads (which will be mainly people and premises, I suppose) at a time when the sector is turning down. Now it will be having the quandary of whether to maintain higher overheads, or reverse course to boost short-term profitability (but maybe then not being in such a good position to capitalise on future recovering markets).
Overall, I’m lukewarm on RWA shares now, so viewing it AMBER.
I now much prefer SThree (LON:STEM) which has not seen any major reduction in its forecasts, and seems to have more reliable repeating earnings from mainly contract (temporary) staff. Whereas RWA seems to have been hurt by both increased overheads, and a greater reliance on permanent recruitment.
For these reasons, I’m not tempted to put RWA on my personal list of possible buys, I think it would need to be a good bit cheaper to tempt me into taking the uncertain macro risk. In any case, with SThree (LON:STEM) now looking the more robust of the two staffing companies we’ve previously admired here, then I’m more likely to focus any available money on that one.
There again, the leveraged downturn that RWA has seen, could flip into a leveraged upside case once macro improves.
As with a lot of cyclical sectors, it currently feels too soon to be bottom-fishing for a recovery, in my view - we can’t just ignore the worsening newsflow.
Fulcrum Utility Services (LON:FCRM)
Down 70% to 0.25p (£1m) - Results & Delisting - Paul - RED
We’ve not looked at this nanocap this year, because it’s too small, and performance in recent years has been disastrous. I last commented here on 5/12/2022, with a RED opinion, noting the big discount on a convertible (at 0.5p) emergency loan fundraise.
It's always worth looking at situations that have gone wrong, to learn from them, and avoid similar situations in future.
For a little while, earlier in 2022, this share had looked quite interesting as what looked like a fairly well-funded potential turnaround. However, the commentary from management turned out to be wildly optimistic, and the cash ran out, leaving it at the mercy of major shareholders including Harwood Capital, who certainly extract their pound of flesh in crisis situations, potentially diluting existing holders to almost nothing through a 0.5p convertible loan. When they're the only game in town, activist shareholders just name their terms, and management don't have any other options.
Figures today for FY 3/2023 look bad, but it’s still a significant sized business, and the balance sheet isn’t actually too bad (NTAV of £18m). The trouble is inadequate liquidity, which has enabled the two largest shareholders (Bayford & Harwood) to lock it in their vice-like grip, and take control. Now they’re delisting it, to save costs and simplify the business. I wonder if, once they've sorted it out, it might come back to the market at a very large multiple of the current market cap?! That's a tried & tested strategy in Harwood's playbook.
Small shareholders had plenty of opportunity to sell up, so it’s difficult to understand why anyone would still be holding now?
Anyway, that’s the end of that one - for small shareholders anyway, although there might be a chance to retain a position in it as a private company, which can sometimes work out alright.
Graham’s Section:
Crest Nicholson Holdings (LON:CRST)
Share price: 167.3p (-14%)
Market cap: £430m
It’s a profit warning from this property developer. Transaction levels across the industry have weakened, “particularly in recent weeks”, with no material improvement expected between now and the company’s financial year-end in October.
Here is the explanation:
Against a backdrop of persistently high inflation and rising interest rates, trading conditions for the housing market have worsened during the summer of this year. While pricing has remained resilient in a market with limited supply and few distressed sellers, the economic uncertainty is deterring prospective home movers. Additional mortgage borrowing for those looking to upgrade or for those with low levels of equity, notably first-time buyers, has become significantly more expensive with no Government support (following the end of Help to Buy) now in place to cushion this impact.
For buyers, is this currently the worst of all possible worlds? Usually, higher borrowing costs should be accompanied by the compensation of an attractive discount in the price paid. But the discount on offer is very limited: according to Nationwide, house prices have fallen by 3.8% in the year to July 2023.
That is the largest fall since 2009, and it’s much larger in real terms if you subtract inflation over the past year, but it’s hardly the sort of fall you might have been hoping for if you are going to pay 6% on your new mortgage.
First-time buyers can be forgiven for taking a “wait-and-see” approach. Some will have no choice, given the affordability constraints. And with fewer transactions taking place, maybe it is only a matter of time before sellers start to accept larger price reductions?
At Crest, sales per outlet per week (“SPOW”) has fallen to 0.25 over the past seven weeks, versus a forecast rate of 0.50.
Management actions - the land portfolio has been increased with the addition of “several high-quality sites”, but Crest “expects future land activity to reduce significantly”. Cost overheads will be reduced for next year.
Dividend - the profit warning does not affect the declared dividend.
Outlook - “positive and confident” over the medium term, as inflation and rates are expected to reduce. Adjusted PBT is now expected to be c. £50m (previously forecast to be over £73.7m).
Graham’s view
This is a severe profit warning that has emerged over just a seven week period. It’s another reminder that housebuilder profits are highly vulnerable to macro conditions.
And when the company says it is positive and confident over the medium term, because interest rates and inflation are expected to reduce, I think it’s important to bear in mind that the company has no idea when these things will happen - none of us know for certain!
However, despite the enormous uncertainty clouding the outlook here, I’m going to maintain a Green view on the shares, on valuation grounds.
Crest has been weak for some time, and is making new lows today. I think this profit warning was largely priced in already:

Paul covered the H1 results here, and noted that the company had a tangible balance sheet value of a staggering £848m, and a net cash position.
Therefore, I like the risk:reward on offer at a market cap today of c. £430m. Even if asset values are written down significantly, the stock is still likely to be trading at a healthy discount to tangible NAV.
How long it might take for inflation and interest rates to reduce is anyone’s guess. But even at a much lower rate of profitability than Crest shareholders have become accustomed to (e.g. PBT of £40-50m p.a.), I think this stock is potentially attractive at these levels.
The ValueRank of 97 here tells the story: the stock is looking very cheap. Perhaps that is for good reasons. But for patient investors who hold this until conditions are booming again, I think it could be very interesting:

DP Eurasia NV (LON:DPEU)
Share price: 52p (+3%)
Market cap: £76m
This Domino’s pizza company has reached a conclusion for its Russian operations: bankruptcy proceedings.
While that might not sound very promising, it does put a full stop on the Russian business which had already been classified as “discontinuing” (see our report in January). DPEU did attempt to sell it as a going concern, but those attempts have come to nothing.
When this stock was originally listed in 2017, the Russian growth story was its most exciting component, as the business in Turkey was already mature.
With the attempt to make money in Russia now conclusively over, it’s understandable that the evolution of the stock price looks like the chart below. It’s hard to imagine that Domino’s will be going back into Russia any time soon:

The financial consequences of the proposed bankruptcy are explained as follows:
It is too early to have an exact estimate of the financial impact of a potential insolvency of DPRussia on the consolidated financial position and results of the Company. The Company can confirm that the external debt of the Russian segment is an amount of c.RUB 520 million, which was guaranteed by, inter alia, the Group's Turkish subsidiary, has been fully and finally settled by the Turkish subsidiary out of existing cash resources, with the Group's gross debt reducing accordingly and a resulting gross cash balance of TRY 162 million (based on the actual but unaudited cash position as at 18 August 2023).
Since DPEU’s financial performance has been less than stellar over the years, and the balance sheet has not been terribly strong, I think it’s important to take a moment dwell on the cash/debt position here.
Firstly, the amount paid off in Russia: 520 million Rubles converts to only about £4 million.
With that amount paid off, DPEU is now left with a gross cash balance of 162 million Lira (£4.7m).
According to the June trading update, the company had access to an undrawn £15m bank facility (in Lira).
Bottom line: DPEU should have access to plenty of liquidity, even after paying off the external debts of the Russian business.
Overall, it does still have a net debt position. A recent -July - broker note from Liberum forecast that the company would finish 2023 with net debt equivalent to c. £16m (using latest exchange rates).
So the company remains significantly indebted, but with good continued access to liquidity.
Graham’s view
It will be easier to judge this when the dust settles: hyperinflation in Turkey and military operations with Russia have been more than slight distractions for DPEU and have impacted financial performance in a variety of ways.
But I think it’s possible that when we finally do get clarity, the picture that emerges could be a pleasant surprise.
The most recent full-year results from the company showed an operating profit on continuing operations of 189 million Lira (£5.5m). Unfortunately, the moving parts of hyperinflation, debt interest expense, and losses on the Russian operations made things complicated for investors to understand.
I’m remaining neutral on this but am primed to turn positive if we start to get clean numbers out of Turkey and an improving balance sheet.
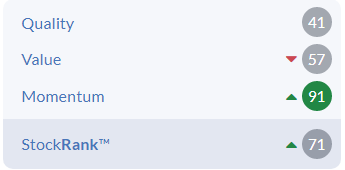
The StockReport is starting to see things it likes here, with the StockRank rising to 71:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Crest Nicholson Holdings (LON:CRST)
“…..tangible balance sheet value of a staggering £848m, and a net cash position.
Therefore, I like the risk:reward on offer at a market cap today of c. £430m. Even if asset values are written down significantly, the stock is still likely to be trading at a healthy discount to tangible NAV.”
The vast majority of a house builders NTAV will be Land bank and WIP. Depending on the region of the country and selling prices; a drop in selling prices of say 10% can translate to a reduction in land values of 30% because land valuation is a residual appraisal exercise.
Housebuilders: a value opportunity or a value trap?
The sector had another wobble as predicted by many in this site.
The reasons are well summarised in today's Crest Nicholson profit warning and in Graham and Paul's reviews above.
Two questions need answering first: will house prices fall further and have the builders share prices fallen enough to account for that. In my mid the answer is Yes and Yes!
Looking beyond the next cycle, Two years time, for me the housebuilders offer outstanding value. Value trap is when a business no longer can produce the product or offer the services that the customer demand. Here , the demand is still there, supply remain limited and inflation and interest rate will fall in due course. The fear factor against that bet is quite high now.
Investing require a degree of intellectual guess, ( scientifically called prediction or forecast), Even the Bank of England prediction for those events proved wrong, if so, I am in good company!
You could look beyond to the next cycle. But you've got to be sure that the company you invest in will survive to the next cycle.
Market is Not Functioning .
The small cap market is nuts at the moment .
Probably money to be made for the fleet footed .
Example, 5 million wiped off the valuation of Belvoir today and that’s down to me selling a chunk of shares cos I needed to realise sone funds for a private investment .
Decided to sell only 30k of shares and went and knocked the share price down 5%.
I think a lot of the drifting is just incredibly low volume and market malaise .
For micro caps totally pointiess in many cases even being listed as impossible to raise money and listing feee of 300k plus a year are an unnecessary cash burn.
I’ve spoken to CEO of a micro cap I have a chunk of and suggested they take it private and save 300k costs . They were making staff reductions and I pointed out it was a touch offensive for people to be losing their jobs whilst they maintain a vanity listing that does nothing more than costs money and reduces agility .
It’s going to a necessary move for a lot of good solid microcaps to go private .
Any chance you could sell a handful more and get it down to 100p planetx? :)
What a wit.
Funny enough I bought at Belvoir (LON:BLV) 105p when the pandemic hit. I still hold and would be happy to add, but as always more buying ideas than money.
Hey ho.
I was about to make the same plea to Planetx to sell another tranche before seeing the waggish WoSS got there first. I was a buyer down at 170p in March and will be again.
No point in taking the risk of unproven companies, business models or recovery plays when there is actual value in front of you right now. That said Jonno is right that most of us have more good ideas than free funds to invest
There are some strange prices being quoted today, B.P. Marsh & Partners (LON:BPM) was down to around 282p and just now AstraZeneca (LON:AZN) had an email from Stocko, that price is 1067p, down 9590p, clearly incorrect. Anyone else getting these sort prices?
Is it a Stockopedia issue or a wider one?
Re Price Anomalies Today
Yes, I kept getting email alerts that AZN price was down to 4,400p and the like - if only; and if only I had the cash to benefit from it.
I can't see any trade that low on AstraZeneca (LON:AZN). On B.P. Marsh & Partners (LON:BPM) there does seem to be a trade around 282p.
Just wonder if auto stop losses would be trigger on low trades or glitches.
On market sentiment comments I fully agree. As an equity investor we have to be prepared for large drawdowns of up to 50%. Its been a poor time, particularly for UK small cap investors but nothing like the GFC as of yet. In some ways, in 2023 it feels worse because the US market (AI bubble related) is doing much better. Things in the UK will improve at some point. Personally, I am expecting things to get worse before they get better as we haven't had the global recession the inverted yield curve has been predicting - its been inverted for over 400 days already! For me its a case of being cautious for now. Its a case of getting my watch list ready with the 50 or so stocks I will buy/add when I think the time is right, but I can't see that now is the time to be buying anything that is not recession resistant. Of course, I may well be wrong and being way too cautious. Good luck to all!
In a high interest rate world, it seems pretty clear where US investors have been squirrelling away cash over the summer.
Yes Paul, a sad and rather predictable end for Fulcrum Utility Services (LON:FCRM) as a listed company, at least for now. Floated at 10p at the end of 2009 as a troubled and loss-making spin-out from National Grid. It struggled in the early days, then restructured the business and was profitable and successful for 5+ years paying nice dividends, before doing some poor acquisitions and losing their focus on the core business again.
Cost inflation on contracts agreed in advance was a major problem for them as was poor financial management. I did buy at about 7p, saw my shares 10-bag, but held on too long and only got out in the 20's. A bit embarassing and a lesson to bank profits of that magnitude when the chart breaks down.
These results look a tad kitchen-sinked for delisting. I was keeping a watch to see if it was worth getting back in at some point as I have quite a bit of sector knowledge. Anyway, Harwood will probably turn it around and sell it on for an elevated price at some point - at least I own most of the Harwood vehicles so will watch and see what happens. They are always the opportunist and you can't really blame them given how badly Fulcrum have performed of late + how much they have lost on their investment already.
For those of you with a bearish confirmation bias that you want to scratch;
https://www.youtube.com/watch?v=6-gU3KM16p4
It looks like Ben Hunt is speaking from the Star Wars Imperial Senate. Other views are available, but I find that although he is quite repetitive, some of his points are interesting.
£CRST
Thanks Graham or the write up. I have started nibbling again in Crest and one or two of the other housebuilders. I have traded/ invested in this sector for over 33 years! The big discounts to NAV especially allied to decent balance sheets are historically a very good entry point. It’s why Persimmon was such a straight sell relative, trading at a huge premium to book in the last couple of years.
Personally I expect Crest to be taken out at some point. Their discount is as much a function of historic poor management team which has changed. The same dynamics still exist in the U.K., finite land, growing population etc. I would still expect the peak of the rate cycle to be the trigger for any re rating. Anecdotally I am already hearing of banks flexing deals to reduce monthly payments especially through duration. I also wouldn’t be surprised to see some form of help from government in such an electorally important sector.
I've never seen such misery in the UK stock market? This for me feels worse than 2008. Do any long termers feel the same way? People last week posted they are down 10% - I'm down a lot more - from the start of the year till around May I was managing to extract some profits from buying and selling now everything seems to be going down from month to month to month. Its relentless and there is no place to hide and then you get profit warnings which lurch stocks down violently. Even oilers have been hit this year.
It's nowhere near as bad now as 2008, nor the pandemic bear market. Not even approaching the level of panic, uncertainty, and capitulation that we saw then, in my view.
yes i lived the pandemic bear market - that was truly horrifying for anyone holding there. I still have screenshots of my watchlist of stocks all up to 12% down or more for multiple days in a row. It was like the world was ending but luckily that was brief. Thankfully I suspected that the Chinese pandemic would spread to Europe and reduced my holdings in advance so the hit wasn't too big. I even tried shorting the airlines then but they were resisting gravity (so i ended closing them!) until the pandemic hit with all its horrors.
Yet one has to ask whether you truly can make money trading stocks or holding stocks for the long term or whether this is just a negative-sum game where the only ones who have any real chance of a good exit are the executives/directors? I would expect anyone fully invested from the start of this year could be up to 35% down or more if he's just invested in the UK. (and I'm a bottom feeder who tries to look for bargains!) You are clearly experienced Paul with many years of experience - but honestly have you managed to make NET money over the last decade say or is trading/investing in UK stocks just a painful way to slowly waste your hard-earned money away?
I've been investing/speculating on UK stocks since before 2008. Honestly if i were to start again i wouldn't do it - it is just not worth the stress.
For anyone wanting a glimpse of the Covid pandemic horrors before the stimulus was announced here are a couple of screenshots. I remember sending these to my accountant in horror. I was asking him - how many days like this before everything turns to zero!? If you've had the misfortune to get seriously hit with this I wouldn't blame me if you ended up getting sick to the stomach. Imagine facing your partner and telling her 40% of your life investments have been wiped out in days.
12th March 2020
16th March 2020
It is nothing like 2008, just look at the UK indexes.
It is certainly possible to make money as I am sure a lot of people here can attest. I have personally transformed my own financial situation over the last 11 years or so. Of course this last couple of years has been less fun but you can’t have the juice without the squeeze.
Maybe index funds would be a better fit for you? No shame in that at all. It is what Buffett recommends for most people.
Hi ben,
You are clearly experienced Paul with many years of experience - but honestly have you managed to make NET money over the last decade say or is trading/investing in UK stocks just a painful way to slowly waste your hard-earned money away?
Yes, I have made money on my ungeared portfolio. Compound gain since 2013 (when I combined old pensions into a SIPP) has been c.14% pa, which has multiplied the total to about 4.2x what it was originally. I've not put in, or withdrawn any money, so that is a clean figure.
I'm not happy with that return, as I could have done much better, but it took a huge knock in 2022. Also for long periods, I didn't really do anything with my ungeared portfolio as I was too busy making & losing millions in spread betting accounts (which I've now closed, as it's too stressful).
I've lived like a king for a lot of the last 20 years too, so god knows how much I've spent over that time period. I've given away about £1m in total to friends & family (including 2 houses) over that period. So I must have made some pretty good money along the way LOL!
So bottom line is this - we definitely can beat the market, focusing on small caps, or having small caps as an element of our portfolios. I've got dozens of friends who consistently beat the market overall - nearly all the same way - by being disciplined, carefully researching value/GARP shares, and being patient (and not using gearing). Although everyone has the odd bad year when your ideas just don't work, that's completely normal, it comes with the territory.
But there are many different approaches which can beat the market. Good luck whatever you decide!
Regards, Paul.
It’s certainly nowhere near as bad now as in the 2008 Banking crisis nor the 2020 covid crash. And note this! Both were soon great buy opportunities as soon as it became clear that drastic Central Bank and Government action was starting to be taken to deal with the crisis.
This is just a slower downturn but as in 2008 and 2020 a very good buy opportunity including, and arguably even especially, for UK quality UK small caps that have been hammered and are at bargain prices. We’re spoilt for choice.
But just as the downturn this this time is more protracted so the same applies to the big bounce. It WILL come as all bear markets end, but we might have to wait a while. But this is a great opportunity to buy shares and Investment Trusts at bargain basement prices! Some Investment Trusts are on extraordinarily high discounts and paying growing dividends too and with yields even in double figures.
Like Paul, and plenty of Stockopedia subscribers too surely, I took advantage of those previous big buy opportunities and have been buying again.
e.g as the 2020 bounce started I bought and still hold Mining Investment Trusts Blackrock World Mining Trust (LON:BRWM) at 260p and now even after big falls still much higher at 561p Blackrock Energy and Resources Income Trust (LON:BERI) at 44p and now 110p and CQS Natural Resources Growth and Income (LON:CYN) at 55p and now 171p. Dividends on all 3 at those buy prices are very high. Also bought India Capital Growth Fund (LON:IGC) at 40p and sold for 127p and now 151p and Commercial Property Trust Aew UK Reit (LON:AEWU) at 62p and now 95p but down from peak 127p. Big 13% dividend paid quarterly at that 62p buy price. Commercial Property Trusts are again at bargain prices. Also bought Legal & General (LON:LGEN) at 175p and now a depressed 218p despite near 9% dividend and with increases promised.
I’ve posted those gains and hold similar winners bought in 2020 or later temporary dips not to show off but to point out that now or soon is another such buy opportunity. Our successful buys now will also multi bag in time for some. AND though the paper profits reduce in bear markets, as the examples here show, the profits remain large.
So take advantage of the current downturn and don’t get too depressed if only starting to invest recently and losing for now. My more recent buys are often down too. It’s inevitable at times like this. Get rid of any we know we’ve got wrong and usually on bad news or profits warning. For other quality losers and green small caps covered here, further falls will often mean they are even bigger bargains and perhaps worth buying a few more.
My focus and skills are not small caps but we’ve the benefit of Paul and Graham’s superb analysis here and some very clued up posters to help us find the best ones. And I’m nibbling at some including Volex (LON:VLX)
It’s arguably a mistake only to invest in UK small chaos as isn’t that all our eggs in one basket? There are Investment Trusts enabling us to invest all round the World with some on astonishing discounts,,AND some UK large caps are also at astonishing Bargain prices.
Not a brilliant year for longs..but i have a long / short portfolio so am actually up 12% this year so far. a couple of big winners for me e.g ME International (LON:MEGP) and £YU. and have cut a lot of losers early.but shorts have more than covered any losses.
I've never seen such misery in the UK stock market? This for me feels worse than 2008. Do any long termers feel the same way?
No! This is nothing like 2008. That was properly scary when the entire global financial system was on the point of collapse and stuff got really stupidly cheap. Right now is just mildly irritating by comparison. I feel sorry for those that are down and thinking with such negativity. For most of us, investment is 10% skill and 90% psychology. I've personally been "playing defence" for some time and being down 0.25% YTD is frustrating but not fatal.
For anyone thinking this is worse than 2008, it really isn't. Today is low volume and orderly.
Take AIM market-
2000-2003 over 80% drop from peak. First 3 months went off a cliff.
2007-2009 around 70% drop. 2nd half very fast and very disorderly.
Today is only down around 44%. Can still make decent money during this correction. Lots of rallies to trade or sell into. Good companies in uptrends. Might feel hopeless right now but this is a doddle compared to 2008.
Maybe it's the old death by a thousand cuts. Cards on the table after the covid crash my PF went from £30k to £100k in about a year and a half and I thought I was a investing god! My bad run started in April 2021 and I've gradually invested/traded it back down to £28k during that time, It's been a very tough learning curve.
So no, not as bad as 2008 but £70k is a lot of money to have and let go of through overconfidence and greed, and I am so looking forward to the next bull market.
That 'investor god' feeling was stimulus money. Stimulus money isn't coming back.
...oh yes it is (will)!
Excessive govt debt will not be repaid. I combination of monetisation and yield/credit control will effectively equate to stimulus whether explicitly said or not. Debt deflation is not a route our mass participation proletarian societies (inc China) can tolerate with social and political collapse/revolution.
My point is 'financial cleansing' will never come...we will carry on 'dirty'...and stocks will remain a valid investment (sometimes good, sometimes bad)
I update my spreadsheet once a month, so I am guessing but probably up around 15 to 16% YTD. I last sold some shares in February last year. I don’t think I am very typical and I struggle to find people who think like me. 2022, I was down 28%, 2021 down 15%, and 2020 up by 54%. For me. I avoid stress by never having leverage, buying companies where I think there is a very good possibility of holding them forever and buying when I consider them under priced using the saying “all companies are worth their present and future cash flows discounted accordingly”. It’s very rare that I see anyone here valuing a company and or explaining how they got to their valuation. I also take time to consider management as I think I am giving them a lot of trust and I know that they will have some hard times, so I want to trust them and leave the decision making to them. I will start selling when I retire, so although the market valuations will be volatile, I don’t have to care and it may even produce great opportunities. I will be a buyer this month and probably next, but that is really getting ahead of myself as I have no idea what the market will do in the short term. I think it will be worth a lot more in ten years than today. This philosophy keeps me stress free and I see it working, and I accept that some years will not look good on my personal balance sheet, but those years generally produce the building blocks for great future years.
Re: Changing the way we speak. Steve McClaren developing a Dutch accent (while speaking his native English) after only a couple of months in his job there takes the biscuit, surely?
Is today's 'theft pandemic' going to lead to retailer profit warnings (re lower margins), higher selling prices, the closure of more physical stores or even all 3?
“Retailers across the board are seeing a rise in crime. This isn’t driven by a need to put food on the table, but rather professional shoplifters stealing for greed over need.”
https://www.theguardian.com/bu...
Someone next to me yesterday using the personal check out machines, deliberately put a couple of items into her bag without scanning them . I wonder how many daily do exactly the same ? These machines save staff expenses , but at what cost ?
What also struck me recently is that supermarkets run their businesses to probably a specific margin - so if they all aim for 3% margin they are all putting up the prices to cover the increasing theft. So the reality is that the law breaking needy are really stealing directly from the honest needy if the honest needy need to cover the costs of whats stolen via higher prices. I suspect we are probably mostly in agreement here that letting this blatant law breaking run rampant without making any effort to tackle it really is hitting the honest needy directly in the pocket - while slapping them in the face saying well the dishonest needy are fine to do that as no action will be taken. I suspect small majority do in on an industrial scale and higher % do it as they see nothing ever happens if you are caught.
Yes indeed. In the case I mentioned, the woman was apprehended by a member of the staff ( local M and S ) and she explained it was done in error. Full of apologies and off she went !! Bizarre
At our local co-op, the tills work by weighing the bag you put the produce in, so you can’t slip something into your bag without the system raising an alert. Obviously you could still pocket the odd item surreptitiously.
TV chef Antony Worrall Thompson caught shoplifting cheese and wine | Antony Worrall Thompson | The Guardian
It is 11 years ago..................... lets try and be slightly up to date
Another reason to buy online than in the shops then. No need for honest us to subsidise the shoplifters?
Hargreaves Lansdown (LON:HL.) website not covering itself in glory this morning.
Just logged into my a/c OK - what's up? Unfortunately mine is still showing far too many losses from recent enterprises..................not sure they can fix that.
Hornby (LON:HRN) SP has dropped nearly 12% today. Does anyone have a view on this stock (no recent RNS)? Paul looked at this one nearly 12 months ago and held a positive view.
It's only dropped 12% because of a tiny uncrossing trade at 20.4p on Friday.
Market makers haven't moved, no trades today.
US Markets
S&P down 2% on the week. Loads happening last week with plenty spooking the market.
Looks like a nice buying opportunity may open up soon tho. Fear and greed index dropping back towards levels offering better odds.
Fear + Greed
US 10 year treasury approaching new highs.
Atlanta Fed Q3 latest GDP prediction
China 50 not looking great. Down 6.2%
Even seeing daft suggestions like this in the press now -
UK Markets
FTSE 250 Down 3.75% on the week.
Price closed right on the October uptrend line. Thursday and Friday felt to me at least like some very mild capitulation with sellers just looking to stop the pain. Volume was very low tho, no sign of institutional selling on a big scale. Looked like 2nd lowest volume week this year, last week being lowest.
Only 12 UP – 234 DOWN
Only 30 above 50 + 200d moving averages
Only 4 above 2x normal volume rather confirming a lack of buyers stepping in rather than mass selling.
AIM All Share
Down 3.2%. Drip, drip, drip of pi sales and redemptions. Broke below July lows now, so cant rule out this heading towards the Covid lows. Some individual shares looking very good value and theres still some positivity out there but while its below the moving averages the general index looks sick. Could change quickly of course, August being a crap month generally, but thats how it looks at this point.
152 UP – 380 DOWN
127 above 50 + 200d moving averages
63 above 2 x Normal weekly volume.
Drip, drip, drip since May gap down.
Hope everyone has a good week.
Further signs of deteriorating housing market from Crest Nicholson Holdings (LON:CRST) this morning with a big drop in forecast PBT for FY23 as high interest rates continue to impact sector. I’m on sidelines for now.
My morning smallcap tweet: DP Eurasia makes calzone of Russian biz.
DP Eurasia NV (LON:DPEU) Fusion Antibodies (LON:FAB) Smarttech247 (LON:S247) Harland & Wolff group (LON:HARL) Renalytix (LON:RENX) Trufin (LON:TRU) Fulcrum Utility Services (LON:FCRM)
◄DP Eurasia (DPEU)► gives up on attempt to sell DPRussia. Will close it. [SP=52 Cap=74m]
◄Fusion Antibodies (FAB)► agreement with a leading US-based AI/ML business to support Fusion's new AI/ML-AbTM service offering. Follows May's MoU. Both parties will co-market the combined service offerings. [SP=6.64 Cap=4m]
◄Smarttech247 (S247)► strategic partnership with Abnormal Security to bring AI-powered email security to Europe. c.€400k contract win from it, with a global aviation organisation. [SP=33 Cap=40m]
◄Harland & Wolff (HARL)► judicial review of the Islandmagee Gas Storage Project will have judgement on 31 Aug. [SP=14.59 Cap=26m]
◄Renalytix (RENX)► KidneyIntelX included in the draft Kidney Disease Improving Global Outcomes (KDIGO) 2023 Clinical Practice Guideline for the Evaluation and Management of Chronic Kidney Disease [SP=99 Cap=118m]
◄TruFin (TRU)► conditionally accepts £3.2m non-binding offer for its holding in Vertus Capital [SP=65 Cap=71m]
◄Fulcrum Utility Services (FCRM)► proposes de-listing. Blames limited prospects of raising additional equity, illiquidity and costs. Has 57% support so far. Also FY results. [SP=0.8 Cap=3m]
Great weekend podcast Paul.
Even my (financially disinterested) wife who drifts in and out when I listen has quietly become a fan, well mainly when you call out egregiously muppet-like behaviour by management teams and Boards.
Agreed. Don't worry about dropping your gs Paul, you might remember that Lord Peter Wimsey and all the toffs did that in the Ian Carmichael TV series. Plus you're down wiv da kids!
English is a living language, not subject to centralised control and censure, with the way that even the educated (and hence, arguably relatively "well-spoken") speak it noticeably changing in the last decade or so. Having your Gs and Ts kidnapped - whether affected or not - is a point of note, given the numbers of those in government who can be heard to do so.
Haha yes, do you remember that time George Osborne put on a hi-viz vest, hard hat, and spoke to some workers at a factory. He suddenly went from plummy, to speaking estuary english - it was utterly bizarre, and hilarious!
Also, I've noted that Julia Hartley-Brewer's podcast (when she's not on holiday) has suddenly changed - she's trying to sound more street, a PR has obviously told her to downgrade her accent. I've unfollowed her actually, as the ads are unbearable - the same ad about the national lottery is played TWICE, then an ad from Amazon talking about its ad-free podcast service ends with a disclaimer "some podcasts may contain ads". That was played twice too. So I've decided to stop wasting 10 minutes of most days listening to that particular podcast. Also, Julia doesn't really do any research on issues, just gives the populist knee-jerk reaction of a middle-class Mum, which is not really of much interest to me. Although I do like her still.
All of the above is why I flatly refuse to put ads on my podcasts. I think it shows disdain for the listeners, by indicating that your time isn't important, and I would rather make half a penny from inflicting an annoying ad on you. My niece tells me that I should be more tolerant of ads, as the content makers have to get paid somehow. I can see both points of view, I suppose. Ads just need to be brief, and relevant, not the same thing repeated multiple times.
George Osborne was certainly another and the footprint of his tendency to drop the odd letter is larger than one photo opportunity! Still the point is well made and documented.
Your advert free weekend broadcasts are much appreciated.
Working at home nowadays, I watch TV whilst having lunch. Lunchtime advert breaks are long, tedious and depressing. You can improve circulation in your feet, get cremated at a bargain; take out insurance for your funeral, get some balm for your poorly back, and leave a bequest in your will! If you do go the advert route Paul, please choose something uplifting!