Small Cap Value Report (Mon 21 Nov 2022) - ACRL, TTG, TUNE, POLR, PODP

Good morning from Paul & Graham! Today's report is now finished, as I want to spend some time after lunch typing up the podcast written summary.
Agenda
Paul's Section:
Episode 21 of my weekly summary podcast went up as usual on Saturday. There were 4 mystery shares this week (being my best stock picks of the week, reserved solely for Stockopedia subscribers). So see Wednesday's SCVR for all of these (the whole report is mysterious, apart from McBride) which are (in my opinion) the best value/GARP shares of the week. It's great fun recording these podcasts, and feedback from listeners at Mello last week was really positive, so I now know it's worth creating them, and they're not too serious, so hopefully also an entertaining & fast moving listen. I haven't got round to typing up the written summary yet, that will probably have to follow tomorrow, as I have to somehow get back to Bournemouth from London today, on a rail strike day. So this afternoon could end up spending 5 hours sitting on a bus. What joy! We seem to have been teleported back to the 1970s, with another winter of discontent looming. As my mother likes to say, "I think mankind is going backwards!"
Accrol group (LON:ACRL) - an upbeat-sounding H1 trading update. After a lot of problems in the past, things now seem to be improving, with a decent level of profitability having been achieved again. Although I still have questions about the business model, so it's not for me.
Focusrite (LON:TUNE) [quick comment] - announces today that the audit for FY 8/2022 numbers is taking longer than expected, so the date is pushed on from 29 November, to 8 December. Importantly, it also reassures that there is no change to profit guidance from the trading update on 14 Sept. It makes me nervous when companies delay accounts, as it can mean something nasty has emerged during the audit. However in this case, I think TUNE has a strong track record, and re-confirming guidance is a reassuring sign. Shares have fallen right back to immediately pre-pandemic levels, and look more sensibly priced now, so could be worth a fresh look. There is question mark over whether the large rise in pandemic profits is sustainable though? [no section below].
Pod Point group (LON:PODP) - my first review of this installer of EV charging points. The short version? It looks a lousy investment. More detail below.
Graham's Section:
TT electronics (LON:TTG) (£256m) - excellent news from this manufacturer of electronics components. The company’s £500m defined benefit pension fund has swapped out all of its assets for a bulk annuity contract with L&G. Under this contract, L&G is responsible for TTG’s member benefits, removing all of the financial risks associated with pensions from TTG. The result is a £6m annual cash flow boost for TTG and an easier path to deleveraging its own balance sheet, which has been a cause for concern. I mentioned this stock at Mello last week as potentially offering a value opportunity and a share price rebound, if equity markets recover and if it successfully deleverages. Today’s news undoubtedly strengthens the investment thesis.
Polar Capital Holdings (LON:POLR) (£474m) - interim results here show large percentage declines in profitability as the company’s AuM takes another hit from outflows and from negative investment returns. The company’s exposure to the technology sector has turned into a liability as the excessive valuations in that sector unwind. While some short-term negativity is easily justified, I think this may have already been priced in as Polar’s stock now trades at a much lower level compared to last year, despite the fall in AuM being relatively modest. Dividend cover has reduced but the yield on these shares is now in the region of 10%.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Accrol group (LON:ACRL)
25.7p (pre market open)
Market cap £82m
On track to deliver FY23 results at least in line with market expectations*
* For the purpose of this announcement, the Group believes market consensus for FY23 to be revenue of £213.5m, adjusted EBITDA of £15.0m, adjusted PBT of £7.1m and net debt of £26.3m.
Good to see a footnote, providing details of market expectations. All companies should do this. I have heard of one broker that removes the footnote when management include it. I would name & shame them, but have forgotten which broker it was.
Things seem to be going well for this tissue paper company, which has had a lot of problems in the past.
…substantial growth in volume, revenue and profit
Cost inflation - there’s a strong statement here, note the use of “all”, instead of “mitigate” which lots of companies are saying at the moment -
The Group continues to demonstrate its resilience against the challenges of input cost inflation, successfully leveraging its supply position with customers to recover all additional costs in the Period.
Net debt -
Net debt at 31 October 2022 was lower than anticipated at c.£30.5m, despite a significant increase in tissue stocks…
This is expected to reduce in H2, as inventories decline.
Revenues - a large increase, which seems to be mainly through higher selling prices, and a more modest increase in volume. If companies can maintain or rebuild profit margins, then over time, inflation results in a larger business -
Revenue up 64% to £121.1m (H1 FY22: £73.7m), with volumes increasing by 14% in the Period
Market share up from 19.5% to 21.5% - evidenced by volumes increasing (as I would expect the total market to remain roughly static)
Outlook - given that it makes value-orientated products, I can see why Accrol would do well in a consumer downturn, as customers trade down to cheaper (but hardly any different) products -
The Group's main market, the discount retailers and private label products continue to grow strongly, driven by the cost-of-living crisis.
The Group has delivered substantial growth in the Period and the Board is increasingly confident that the growth trajectory of the business is sustainable. The volume growth in H1 FY23 is expected to continue as consumers move away from high-cost, low-value branded products in search of best-value.
Whilst mindful of the wider economic uncertainties, the Group's model is robust, and the Board considers the Group to be on track to deliver results for the full year ended 30 April 2023 ("FY23") at least in line with market expectations* with net debt reducing ahead of expectations to c.1.5x EBITDA by the end of FY23 (FY22: 3.0x).
* For the purpose of this announcement, the Group believes market consensus for FY23 to be revenue of £213.5m, adjusted EBITDA of £15.0m, adjusted PBT of £7.1m and net debt of £26.3m.
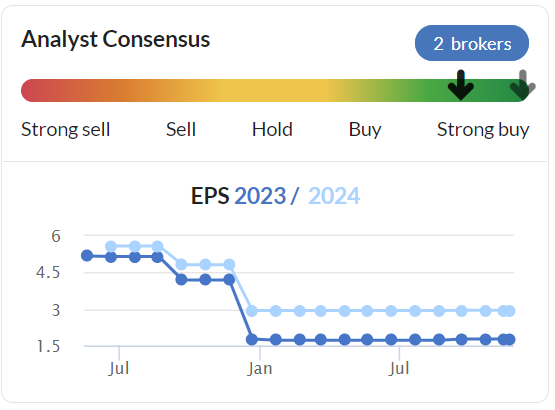
Broker expectations - there’s a difference between beating tough forecasts, and (as in this case) just stepping over a bar that’s been moved down to very low. See below how forecasts have been reduced by over two thirds for FY 4/2023 -
.
Liberum and Zeus have issued update notes this morning, available on Research Tree, many thanks to both. Liberum has £7.5m adj PBT and 1.8p EPS for this year FY 4/2023, then a big increase to £13.9m and 3.1p for next year. I’d like to be clearer why they expect such a large profit increase next year, and why that would be achievable.
If these FY 4/2024 figures are achieved then I can see that a higher share price would be justified.
My opinion - it’s looking like ACRL has finally been sorted out. Remember the history here is terrible It floated in 2016 on the basis of a bonanza in profits due to cheap input costs. That then unwound, and the company got into serious trouble, and almost went bust. Shareholders propped it up, but that means the share count went up from c.93m, to 319m now, hence the previous highs of c.150p share price are not likely to ever be recouped.
This also demonstrated the big flaw in ACRL’s business model - that it has no control over input prices, only makes a small gross margin, so then is dependent on being able to pass on price rises promptly to customers (supermarkets) that are notoriously resistant to price rises, because they themselves only make a tiny profit margin.
So the key questions to ask management are how their contracts are now structured, in terms of controlling input costs, and controlling selling prices? If they can’t match those up better than in the past, then the business model is still flawed, and hence more profit warnings would be just a matter of time.
The business model doesn’t interest me at all, so it’s not for me. Although for existing holders, at least today’s news shows that things seem to be on an improving trend. It's difficult to see why ACRL would be a listed company, other than to take advantage of bumper profits through an inflated IPO price, when it originally floated. I cannot see any compelling ongoing reason as to why this share is listed.

.
Pod Point group (LON:PODP)
65.6p (down 14% at 09:29)
Market cap £101m
This has just dropped £16m in value on today’s update -
Growth in H2 (of FY 12/2022) has “slowed markedly”
Blamed on supply chain problems resulting in car manufacturers delivering fewer new EVs (electric vehicles), hence less demand for home charging points (PODP's main business).
Govt grants for home chargers pulled forward demand, ahead of abolition at end March 2022.
Guidance for FY 12/2022 -
As a result of these challenges the Group expects full year 2022 revenues to be approximately £70m with an adjusted EBITDA loss of circa £7m.
This represents a recent slowdown as follows:
H1 2021 revenues £26.5m
H2 2021 revenues £34.9m
H1 2022 revenues £41.6m
H2 2022 revenues £28.4m (latest guidance)
FY 12/2023 guidance - also provided today is for FY 12/2023 of £85-90m revenues, so an expected recovery compared with H2 2022. It’s blaming some of the 2022 shortfall on supply chain problems, which we know are generally easing, so it makes sense that better supply should mean more installations in 2023. Supply chain issues also include restrictions on the supply of new EVs, thus causing a knock-on reduction in demand for home chargers.
Background - as this is the first time I’ve looked at PODP, I looked back to this years’ interim results, so here are my notes.
What does it do? Mainly installation of home charging units for EVs, but also commercial installations too.
Margin are is low (gross margin of 25% for H1) - so little pricing power. There are numerous providers of EV charging points, so lots of competition, although PODP seems to have decent market share of 22% in H1, helped by deals with car manufacturers. But so what, given that these are mainly one-off sales?
Recurring revenues? Very little, only £0.8m in H1, from commercial units only (there don’t seem to be any recurring revenues from installing home chargers, which is the bulk of revenues). The recurring revenues of commercial installations are only £41 per unit, which wouldn’t be enough to cover the cost of just one maintenance callout, if anything were to go wrong.
Losses - it made a £(1.4)m EBITDA loss in H1, and bear in mind depreciation & amortisation are quite large, so the real world (statutory) loss before tax was £(7.5)m in H1. This includes a £2.6m charge for share based payments. It infuriates me when loss-making companies dole out free shares to management. Build a profitable business first! Then get some reward for it, is my apparently outdated view.
FY 12/2023 guidance is for continuing losses in “mid-single digital [sic] adjusted EBITDA loss in 2023”. Clearly a typo, which should read: mid-single digit, I think. Does that mean percentage, or in £m’s?
88% of jobs are installed by partners.
Stopped selling in Norway, which was immaterial anyway. Norway is a mature market for EVs, which perhaps indicates there's not much mileage in PODP's business model for overseas? Another reason to be sceptical of this share.
Big increase in headcount, using IPO proceeds.
Cash pile is large, but depleting: £96m end 2021, £82m at H1, expected to be £70m end 2022, and guided to be c.£50m at end 2023. Fully funded for now, but what happens longer term? More placings, at much lower prices, would be my best guess.
The big question, is whether the cash is being spent productively? I would say a resounding no to that! It seems to me the cash pile is probably being squandered on uneconomic growth.
Green credentials in the commentary - all very commendable, but if it was my money being burned, I’d want more of a focus on building profits.
Maintenance costs - I need more information on this. PODP provides EV charging points commercially, e.g. at workplaces, and in supermarket car parks. However, in my experience, these sometimes tend to be out of order. So a key question is, who pays for the callouts to get engineers to remedy faults? If it’s PODP, then the recurring revenues of just £41/site would not be enough to cover those costs.
Ownership - note that major electricity generator EDF controls PODP, with 55% ownership. So it would be interesting to know how that relationship works? Does EDF provide subsidised electricity, or any other support? Why did it float PODP? Maybe to get someone else to part-fund the roll-out of EV charging points?!
My opinion - I’ve only done an initial review here, and have already seen enough to make me highly sceptical that this is a viable business. So I reckon the most likely outcome is that the cash pile continues depleting, with nothing much to show for it, in recurring revenues or profit. It's not clear to me how driving revenue faster would help, as recurring revenues are so small.
If PODP could demonstrate that it’s rapidly building recurring, high margin revenues, then great. But I don’t see anything at all of that kind, rather the opposite.
The economics of the business just look awful to me, so I wouldn’t go near this share. Let the institutions fund the loss-making part of the green agenda, rather than us.
This is only based on an initial review though, so I’d be happy to learn more about the company, if they do webinars, etc.
Anything connected with renewables might have been fashionable in recent years, but I think it's really important to take off the rose tinted glasses, and instead look at the hard numbers with a cold, analytical view. On that basis, some business models might look very wobbly indeed, as PODP seems to be.

Graham’s Section:
TT electronics (LON:TTG)
Share price: 145p (pre-market)
Market cap: £256m
There is a really positive pension-related update this morning from TT Electronics, a global manufacturer of electronic components.
We’ve discussed recently how rising interest rates are having a major impact on pension funds.
Some funds got in trouble due to their hedging practices, but on the whole rising interest rates should be great news: rising interest rates mean higher future returns on any cash which a pension fund puts to work.
This morning, TT announces a “buy-in” (see explanation by PWC): a bulk annuity contract with an insurance company under which the insurer is contractually obliged to pay all of TT’s defined benefit members’ benefits in future. The insurer in question is L&G.
The contract has been bought with existing pension scheme assets, and does not require any further payments by TT:
TT will not be required to make any future contributions into the Scheme regarding defined benefit liabilities and the buy-in delivers greater security to the Scheme's members. The Scheme's circa £400 million of liabilities are now matched by the insurance policy, and TT no longer bears any investment, longevity, interest rate or inflation risk in respect of the Scheme.
The impact on cash flow is a £6m benefit for TT both this year and in future years.
At its most recent interim results, TT noted that the net accounting surplus for its DB pension scheme had improved from £74m to £92m, “due to increases in yields on corporate bonds in the half year causing the scheme obligation to decrease”.
Today’s news locks in those gains (although treat that £92m figure with a large grain of salt).
My view
This is a stock I mentioned at Mello last week, arguing that it has the potential to rebound very strongly if equity markets recover and of course depending on its own execution. Underlying trading has been very strong, its order book has been growing, its costs are being passed onto customers, and yet its share price has halved over the past year.
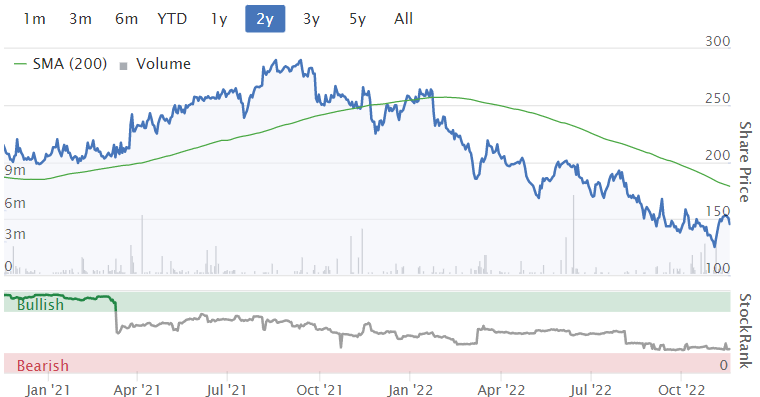
Its balance sheet has been a point of concern: net debt was £142m as of June 2022 (including leases). However, the company has guided that its leverage multiple will reduce from 2.4x to its target range of 1x - 2x by December 2022.
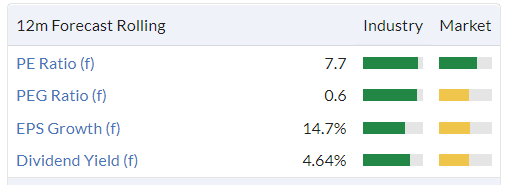
Today’s pension deal surely makes that job much easier, reducing financial risk and adding strength to the view that this stock offers a value opportunity:
We should hopefully receive many more examples of good news along these lines from company pension funds in the months ahead.
Polar Capital Holdings (LON:POLR)
Share price: 470.5p (-0.4%)
Market cap: £474m
I looked at Polar’s FY March 2022 results back in June.
Today we have the interim results up to September.
AuM Movements
- AuM falls by £3.3 billion to £18.8 billion (down 15%).
- Of the £3.3 billion fall, negative returns accounted for £2 billion.
- The rest of the fall was made up of outflows: customers pulled out nearly £0.8 billion, and there were £0.5 billion of fund closures.
I’ve noted previously that 75% of Polar’s funds (currently £14.1 billion) are open-ended in nature, meaning that customers can pull out their money at any time and receive the fund’s NAV.
Flows into open-ended funds like this are sensitive to short-term investor sentiment and the changing popularity of particular investment themes.
Over the last six months, Polar’s huge Technology Fund has seen big outflows: £569m to be precise.
This fund currently has £3.7 billion of AuM, down from £4.4 billion six months ago.
It has suffered from weak performance over the past two years, which tends to go hand-in-hand with outflows:
Polar Capital Global Technology Fund's performance has improved but remains well off its high-water mark due to a challenging 2021.
The Technology theme reduced from 42% to 37% of Polar’s total AuM during H1.
Elsewhere, UK and European equities are also out of favour.
Money has been pulled out of both the UK Value Opportunities Fund and the European Opportunities Fund.
The summary of events at the UK Value Opportunities Fund will be of no surprise to readers here:
Polar Capital UK Value Opportunities Fund has materially underperformed its benchmark as it has high exposure to small and mid-cap domestic companies which have been de-rated due to the weakening UK economy. The performance of the benchmark (FTSE All Share) has been driven by oil and resources.
Regarding UK and European equities, investors have been “cutting exposure to these two regions significantly.”
Funds doing better include the outperforming Global Insurance Fund, the Emerging Markets Stars fund, and healthcare funds, but these are all significantly smaller than Technology.
Financial results
- Core operating profit £25.8m (H1 last year: £36.3m)
- Pre-tax profit £23m (H1 last year: £31.7m)
- Unchanged interim dividend 14p (paid from basic EPS of 17.7p, so not much cover).
Market comment
I nearly always find something interesting to read in fund manager commentaries. For example, Polar’s CEO observes that bond indices have recently been declining by as much as equity indices.
He notes that -
“a 'balanced' portfolio of bonds and equities is experiencing its worst year for at least a century”, and that “a GDP weighted world government bond index is on track for its worst annualised return since 1920”.
Outlook
Our diverse and differentiated range of sector, thematic and regional fund strategies where 73%, 87%, 86% and 93% of our AuM is in the top two quartiles against peers over one year, three years, five years and since inception, our improved distribution capability and significant remaining capacity gives us confidence that we will perform for our clients and shareholders over the long term.
My view
Overall, I still have a positive view on Polar due to its specialisation in strategies which should do well over the long-term (technology, insurance and healthcare are its three largest strategies).
The size of the Technology strategy is admittedly a headwind to performance as the technology bubble bursts, so timing an investment in Polar isn’t easy: who knows when the NASDAQ will find a bottom?
I certainly don’t know if we’ve reached the lows yet, but I do suspect there is plenty of value to be had here: the Polar share price is almost 50% lower than the high price it reached of c. 900p in summer 2021.
In June 2021, AuM were £22.8 billion. Polar discloses today that its AuM, as of 11/11/2021, had recovered to £19.2 billion.
So between June 2021 and November 2022, Polar’s AuM is down by only 16%.
Operational leverage has worked in reverse and has hurt the company’s profitability, but it will start working positively again whenever markets bottom and inflows resume.
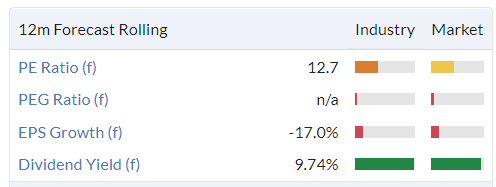
So for me, this is another good value share in the fund management sector.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
"People will also drink more when feeling depressed, so full pubs is a red flag imo , not a reason to be cheerful."
You may be correct about drinking when depressed but £JDW recent performance would suggest the latter part of what you say may not be as insightful.
This recent performance?
Exactly .
I’m clearly missing your point…
Hi Paul/Graham, can I just say your analysis is simply gold dust. I've had a lot of subscriptions over time whilst learning about investing (FT, investor chronicles, shares mag, SCSW, Research Tree, various free blogs) but now I only have one subscription (Stocko) simply for your brilliant commentary. When writing up my trade diary I have a column labelled where the idea came, from 90% say SCVR......says it all.
AUM fell 15% in H1-23, from £22.1bn on 1 Apr 22 to £18.8bn on 30 Sep 22 for £POLR. Unsurprisingly, given the widespread sell-off in equities, investment performance accounted for -£2.1bn of the fall, with net outflows of -£0.8bn, and the closure of the Phaeacian funds in the US -£0.5bn.
• Despite gloomy markets, there are multiple positive signals and signs of management confidence:
• Positive net inflows were recorded in multiple funds, including Global Insurance, Biotechnology, Healthcare Blue Chip, Smart Energy, European ex-UK Income, Emerging Market Stars, Forager and Global Absolute Return, and net outflows from open-ended Technology funds have slowed.
• Polar has reported a strong pipeline of investor interest in multiple strategies, and that the short list of new potential investment teams is larger than for many years.
• The board has declared an interim dividend of 14.0p per share, unchanged from H1-22 (if the total full-year dividend is maintained at 46p, that would be a yield of 9.7% at today’s share price).
• Directors’ have made over £2.2m of share purchases, in cash, during 2022.
We maintain confidence in the strength of Polar’s strategic positioning, and that it is well positioned to return to growth, despite significant short-term uncertainty.
Our fundamental valuation is 600p per share, 27% above the current share price, and we flag that Polar’s PER of 9.3, is undemanding and below a peer group median of 10.0.
https://www.equitydevelopment.co.uk/research/core-profit-margin-still-over-30-in-brutal-markets
There is also a presentation Thursday at 12.45 https://www.equitydevelopment....
Accrol group (LON:ACRL)
Paul - Whilst I don't hold these I have made some money on them in the past and input costs were my key concern. One of the things the new management did was to re-negotiate the contracts to include the pass through of input cost inflation to the retailer automatically. So unless anything has changed since I last looked this significantly changes the balance around the business model concerns. I presume there is still some lag in that pass through (3-6 months I'd guess) but should no longer be business destructive.
I'd say they will have a tailwind of demand in the next couple of years as more people switch to cheaper own brands and discount supermarkets. I haven't read todays statement in any detail yet so have no view myself as to the merits of the investment case.
Thanks david, that would certainly be an important point to (at least partially) address my concerns about ACRL's business model. If they do a webinar, I'll have a listen, armed with your additional info,
A post by Roger Lawson in his blog on Friday has reminded me that possibly not all investors are aware of the impact of "MEES", the Minimum Energy Efficiency Standard, and I think there could be question marks over the reporting of some freehold property values in company accounts. The original legislation was in 2015 and was brought into effect in 2018. It prohibits the leasing of buildings which currently have an energy performance rating below E (ie: F or G). From 1 April 2023 continued tenancies of such buildings are also prohibited. Exemptions are available but are restricted in application. The rules are well understood in the domestic private rented sector but I think it has only been quite recently that the commercial property sector has started reacting to them. This may be because a number of councils (who are the enforcing authorities) have obtained funding to pursue and fine landlords of sub-standard properties.
Furthermore the Government’s UK Energy White Paper proposes that all non - domestic properties will need to benefit from at least a C rating before they can be let from April 2027, and a B rating from April 2030. I have no idea how the latter requirement will be met. My wife and I own1 commercial and 4 domestic property investments - none of these have a B rating, and I don't think they ever could.
Roger's blog quotes the H1 report of Value and Indexed Property Income Trust (LON:VIP) which includes this paragraph:
Land Securities has just sold a prime long-let London office at 9% below its March valuation, while the market for older or secondary offices has fallen off a cliff, with some now virtually unlettable and unsaleable where they do not meet environmental standards. The deep “brown discount” for properties in all sectors with non-compliant Energy Performance Certificates (EPCs) is the clearest evidence so far of the growing market impact of ESG. Two-thirds of car showrooms, for example, are currently estimated to have non-compliant EPCs.
An owner can continue to occupy a non-compliant property (at the moment) but if it's illegal to let it the book value must be in doubt if it hasn't been revalued recently, which is why I'm posting this.
The SPs of Eurocell (LON:ECEL) and Safestyle UK (LON:SFE) look to be reasonably good value and likely to benefit from "MEES" as replacing windows is probably the cheapest / least impact thing you can do (outside loft insulation).
I bet a lot of people (small landlords) are unaware of the looming deadlines here.
With our old housing stock you would be lucky to achieve a C rating let alone a B. All leading to less choice for tenants of course. The EPC report as it is done at the moment is a joke and does not give sensible suggestions how to improve the rating.
Hi
Just below the SCVR £700m market cap ceiling, Molten Ventures (LON:GROW) interim to 30th Sept.
I think this is one for a watch list if you are interested in investing into technology. Its share price has fallen a lot over past months. It hit 1150p 8/9/21, today 433.40p so -62.31%. Consequently the reported NAV is now 837p, therefore share price discount to NAV is -48.12%.
The RNS points out risks with valuations of holdings (which they have adjusted in this RNS) and lower liquidity for investments in the sector (no surprises there). Although the SP has had a recent noticeable rise (up 59% in 1 month) it has fallen back after today's RNS.
I perceive that Molten Ventures (LON:GROW) could be quite a volatile share for a while but once market conditions begin to stabilise, these VC Investment Trusts can often be early risers as a falling market begins to turn. IMO I think the -48% discount to NAV suggests there might be quite a nice upside at some point, plus Molten Ventures (LON:GROW) is a well established player in this space in the UK.
Hence one for a watch list if you are interested in these technology/VC/ITs.
I hold a small position.
Highlights copied from RNS here ...
FINANCIAL HIGHLIGHTS
· Gross Portfolio Value of £1,450m* (31 March 2022: £1,532m)
· Net Assets of £1,280m (31 March 2022: £1,434m)
· NAV per share 837p (31 March 2022: 937p)
· Gross Portfolio fair value decrease of -12%*, -17% gross of FX impact (six months to 30 September 2021: gross fair value growth of 27%)
· £112m of cash invested in the period from plc, as well as £17m from the EIS/VCT funds (six months to 30 September 2021: £165m from plc and £4m from EIS/VCT funds)
· £28m consolidated Group cash (31 March 2022: £78m plc cash, including restricted cash), as well as £58m available to invest in the EIS/VCT funds (31 March 2022: £61m)
· Operating costs (net of fee income) continue to be less than the targeted 1% of period-end NAV
· Cash proceeds from realisations of £13m (six months to 30 September 2021: £67m)
· Loss after tax of -£155m (profit after tax for the six months ended 30 September 2021: £218m)
· £150m expanded debt facility (£90m drawn at 30 September 2022)
Link to RNS here ......
https://www.investegate.co.uk/...
For those interested note these ......
A live webcast of the presentation including Q&A will be held today at 9.00am for analysts and will be available on https://brrmedia.news/Molten_HY . Conference call details for the Q&A are available upon request.
A further presentation will be held at 9.00am tomorrow, 22 November, via the Investor Meet Company, which is open to all existing and potential shareholders. Questions can be submitted on the platform.
Regards
Howard
I believe Molten Ventures (LON:GROW) and its seemingly large discount to NAV should be treated with some caution. I believe the NAV has high odds of shrinking further and that a discount could remain in place due to funding issues for Molten which means they may need to issue equity to raise funds for follow on investments in their companies (...and if they don't they get diluted and lose some value...you got to keep in playing the funding game).
There's decent probability that VC and tech/nasdaq conditions stay muted for a period now after much euphoria. This can continue to compress valuations particularly for the VC companies that rely on nasdaq names holding high multiples. In addition, Molten holds small stakes in such large VC backed companies that the realistic exit is to IPO.
So what was a jolly up escalator could be in for a long grind down.
Hi mojomogoz
I do not disagree with your points at all. Points noted from the US do indicate VC/PE funds are drying up fast. I agree its an investment to be treated with great caution.
Regards
Howard
I should have added...a home run in holding or at least a decently large exit does have great impact and the latter provides needed liquidity too. So there is upside surprise potential that makes the NAV and discount look much more enticing.
Polar Capital Holdings (LON:POLR) on dividend cover, company has previously stated that they have significant cash balances so would be able to comfortably cover divdend for some time if required. The dividend therfore looks pretty safe for the foreseeable future.
cash balances are about 1/4 of the entire market cap at the moment so that certainly seems reasonable plus the divi is actually covered anyway at these levels.
£ZIN Has anyone looked at this? The management team had a very good track record turning ITN Productions into a proper business and after a few years of restructuring seem to be making good progress here. They're still in investment mode, setting up new brands, bringing in swathes of luvvies etc etc but certainly seem to be getting revenue traction if today's update is anything to go by. rare to find pure content businesses at all let alone on 0.5x sales. Turns a profit this half. It strikes me that real operational gearing only comes from syndication and I'm not sure what market Bargain Loving Brits will find overseas but you never know. I own a small position
Hi
NextEnergy Solar Fund (LON:NESF) positive update this morning. Share price up +3.75% as I type.
Comprehensive RNS worth a read if you are interested in this solar/battery storage investment. Here are financial highlights copied from RNS ......
Financial Highlights
· +9.4p (c.8.3%) increase in Net Asset Value ("NAV") per ordinary share to 122.9p over the six-month period (31 March 2022: 113.5p).
· +£56.2m increase in ordinary shareholders' NAV to £724.7m (31 March 2022: £668.5m).
· Earnings per ordinary share of 13.1p (30 September 2021: 7.74p).
· Total Gearing (including preference shares) of 42% (31 March 2022: 42%).
· Second interim dividend of 1.88p per ordinary share for the quarter ended 30 September 2022 (30 September 2021: 1.79p).
· Estimated cash dividend cover of 1.3x - 1.5x for FY22/23 (31 March 2022: 1.2x).
· Total dividends paid of 3.76p per ordinary share in respect of the six months ended 30 September 2022 (30 September 2021: 3.58p).
· Target dividend of 7.52p per ordinary share for the year ended 31 March 2023 (a year-on-year increase of 5%, above the 4.1% calculated Retail Price Index ("RPI") rise for the 2021 calendar year).
Worth noting, NAV 122.9, share price 114.68 (as I type), thus discount -7.16% (was even wider at market opening). It's a nice dividend payer as well.
Also, the RNS explains that they have factored in the windfall tax announced in the budget.
RNS here ....
https://www.investegate.co.uk/...
I hold
Regards
Howard
A quick note to give my thumbs up for the podcast, been busy on other projects recently so was great to catch up on last weeks events this morning over a lazy coffee !
Interesting re TT Paul. Although it has to be kept in mind that as the pension fund has been sorted the debt has just become a lot more expensive. (or has it I will have to review the debt report back on that one).
"At 31 December 2021 the Group had available undrawn committed and uncommitted facilities of £272.4 million. The Group’s borrowings are in the form of a multi-currency Revolving Credit Facility (RCF) and private placement fixed rate loan notes (PP). The RCF matures in November 2023, with no short-term re-financing risk for the Group. In August 2021, TT agreed a debut £75 million PP issue with three institutional investors. The funds were received in December 2021 and the issue is evenly split between 7 and 10 year maturities with an average interest rate of 2.9% and covenants in line with our bank facility. " (2021 accounts page 41)
So actually the private placement issue at 2.9% was a pretty good raise. The RCF has another year when likely it will become a bit more expensive, so 2022 accounts should look good.
Sorry Graham. I meant you not Paul.
An announcement today by struggling tiddler Real Good Food (LON:RGD) (market cap £1.2m) that it has raised an additional £2.5m of secured borrowings, could be an important development Judith MacKenzie’s £DSM.
The new debt is secured against assets and ranks ‘ahead of the Loan Notes in Security’ potentially pushing DSM’s loan note investments down the pecking order in the event of default, in what is a highly leveraged and commercially struggling cake decorator.
RGD has been DSM’s largest holding for some time representing 13.26% of DSM’s Net Asset Value “NAV” at 31 August. Only 0.3% of the 13.26% was invested in listed equity. Of the remaining investment 8.32% was invested in 10% loan notes and 4.64% was invested in 12% loan notes.
The unquoted nature of the notes means their value in DSM’s NAV is not updated as frequently as the value of DSM’s quoted equity investments. DSM reported £5.3m of unquoted loan notes at 31 August 2022.
DSM trades with a market cap of £29.2m but with a NAV of £34.8m implying a discount of 16%. This has recently come down from over 20% after some marketing efforts.
For me, DSM carries the hazardous risk that the discount between the DSM share price and its NAV does not fully reflect the risks and underlying value of its RGD investment given the high leverage and how precarious RGD’s business appears to be.
Problem with these micro caps is the bid offer spread. Unless you want to hold for five or six years.
Pod Point group (LON:PODP) I thought back in Feb ‘22 (as a battery car user now on our second BEV), Pod Point group (LON:PODP) didn’t really have a USP. It seems to do just what it says on the tin - its a car charger point! I can’t see what’s changed. They’re in a crowded market place and as an EV user myself, sorry to say they don’t stand out.
Unless you’re buying new and the deal includes a Podpoint, what is the incentive to purchase one of their chargers? There are other much smarter chargers out there to choose from that work with solar panels for example https://myenergi.com ; with energy companies DSR programs https://octopus.energy/intelligent-octopus/ and with the grid https://ohme-ev.com/ev-smart-charging
Also the £350 government grant has been withdrawn to homeowners to install a charge point. https://www.gov.uk/electric-vehicle-chargepoint-grant-household/eligibility
Hi Paul
Just wanted to say how much I’m enjoying your podcast, it’s a must-listen for me over the weekend while doing jobs around the house or walking the dog. You’ve got a natural gift of keeping it both interesting and educational. Not easy I’d imagine when just talking by yourself with no guests etc. keep up the great work, it’s much appreciated. I’m also in favour of keeping a few ideas back for Stocko subscribers too
Great, thanks organictrader, I'm glad you like my podcasts. I'm a podcast addict myself and love pottering around in or outside, with headphones on, making use of otherwise wasted time to listen to anything interesting or entertaining, not necessarily about shares.
If people have any interesting podcast (or audiobook) suggestions, do post a comment here. Friends recently recommended "The Dealmaker" by Guy Hands (of private equity fame), which I've found a bit slow to get moving, it's a pity autobiographies always seem to start with peoples' childhoods, which rarely interest me, but I suppose it forms the basis for everything else, so has to be ploughed through. It's got a lot more interesting now he's getting plastered at university, whilst running a door-to-door selling business (paintings) on the side! And beating the locals at poker!! All whilst trying to navigate dyslexia before it had been identified.
A vote of thanks to Graham. I previously owned TT electronics (LON:TTG) having exited two years ago or thereabouts. There was some news on a blue-sky technology for the non-invasive detection of the covid virus, which struck me as somewhat dubious. I had been reviewing the company of late prompted by Graham's presentation at Mello and this morning's announcement regarding the defined benefit pension scheme was the trigger for pushing the buy button.
A modest starting position, as there are no guarantees, but clearly a significant positive for the company.
I also hold Polar Capital Holdings (LON:POLR) that reported very acceptable interims this morning given the economic backdrop.
Zinc Media (LON:ZIN) Any chance of some analysis on this please? It hasn't been looked at since 2013. Ahead of expectations and expecting to be profitable in the second half. Thanks
Recession you say ? I was down Nottm this weekend and it was RAMMED ! Absolutely jam packed with shoppers.
I was out in a shopping area of SW London and was also surprised how really busy it was!
Heaving in central London on Sunday evening.
I was out in Cambridge and it was chocka. Rev Bars was full at 2pm.
Cambridge is pretty affluent , I doubt the ‘cost of living crisis’ will bite there too much. Nottingham is full of students and apparently above average level of lower paid workers & above average unemployment, this group of people are experiencing higher wage growth and benefits rising in line with inflation, London is always an outlier.
Personally, as someone who saves and invests, my disposable income is dropping as I maintain this process. Pay award of 4.5% in private sector. And whilst I also have seen shopping centres busy, it’s places like TK Maxx, B&M, Lidl, The Range where I’ve seen to be busy.
People will also drink more when feeling depressed, so full pubs is a red flag imo , not a reason to be cheerful.
The assault on private landlords by the Scottish Govt. is also killing the market here, I intend to sell my rental property as a result, and also to prepare for the mortgage shock coming next year - I doubt I’ll be the only one.
Recessions take some time to bite, we are in the early stages of this process.
Sorry for the rant, but the euphoria expressed here ground my gears a little!
"People will also drink more when feeling depressed, so full pubs is a red flag imo..."
So anytime pubs in the country are full, it's because we are all depressed?
Perhaps a certain football tournament may be skewing things just now too…
I also made no reference to ‘anytime’ , and people do drink more when depressed. The pandemic is a proven recent example.
I don't understand why is, pubs full a red flag, why is it connected to depression? People drink when they are depressed, and drink can cause depression. That doesn't mean full pubs equals everybody is depressed. It could be works Christmas do's, football, work at homes getting together with their colleagues, birthday parties. This is what I have witnessed along with the odd depressed person sat in the corner.
By honing in on this small part of my post, you are missing the point. The previous posters were claiming ‘recession, what recession’ and using full pubs and shops as the justification for their perspective.
The reasons you give are also valid reasons as to why footfall in pubs may be above average, but how does it compare to previous years at this time? That is a fairer comparison.
Be careful.... many surveys showing that customers are starting their xmas shopping early. So what might look unusual in terms of Nov footfall... might end up being a quiet December on the high street.
I offered to take my brother and his wife out for a pub meal middle of last week - semi-derelict ex-coal-mining town that has been a major unemployment blackspot since the late 60s and couldn't get a table at the first pub - had to go out to a village a few miles away. I haven't been back for a few years. It's still a poor area but I don't think employment has been this high since the second world war ended!
Sadly, the people I see out in the pubs the most, are the ones who do not work.
How can they afford it? I find pubs too expensive now.
Full employment is a myth…
https://ersa.org.uk/news/the-r...
TLDR:
It would be interesting to have a look at and/or discussion of Pod Point group (LON:PODP) today. Poor results based on a big fall in uptake of plug in vehicles (PIVs) and a SP drop that matches the fall in revenue expectations. But there’s no stopping the eventual huge wave of PIV registrations to current owners of ICE cars. The risks appear to be more focused on competition from oil majors, electrical industrials - ABB pre-IPO-ed their EV business this morning, and cost-conscious late arrivals like Luceco. Thoughts anyone, Paul and Graham included?
It's quiet for news today, so I'm happy to take a first look at Pod Point group (LON:PODP)
I'll get started on that now, should be up by c.11:00
Regards, Paul.
Hi Paul,
Enjoyed the podcast as always over the weekend. Interesting to hear that a lot of people at Mello mentioned you giving too much away and their disapproval with that as annual subscribers. Personally I think the podcasts are a nice weekly summary, but I pay to listen to the thoughts of all the writers and also to read the discussion. As a relatively new investor, knowledge is power and there is a lot of that to be gained from this community. Just a contrarian perspective, two of my friends (who are also investors of less than 5 years) who I had previously pushed towards Stocko with no success, are now joining having listened to the podcast.
Many thanks to everyone on the team,
Ben
Oh that's good news, thanks Ben!