Small Cap Value Report (Mon 21 Oct 2024) - BOWL, XLM, CER, RCDO Briefs: MIDW, TSTL, MRIT

Good morning, it's Paul & Graham here!
Podcast - I didn't have any inspiration this weekend, so it's a bit delayed. Hopefully I should catch up later today. With my apologies to the financial wing of the dog walking community! EDIT: podcast now done, sorry it was late. Published 26/10/2024.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
Summaries
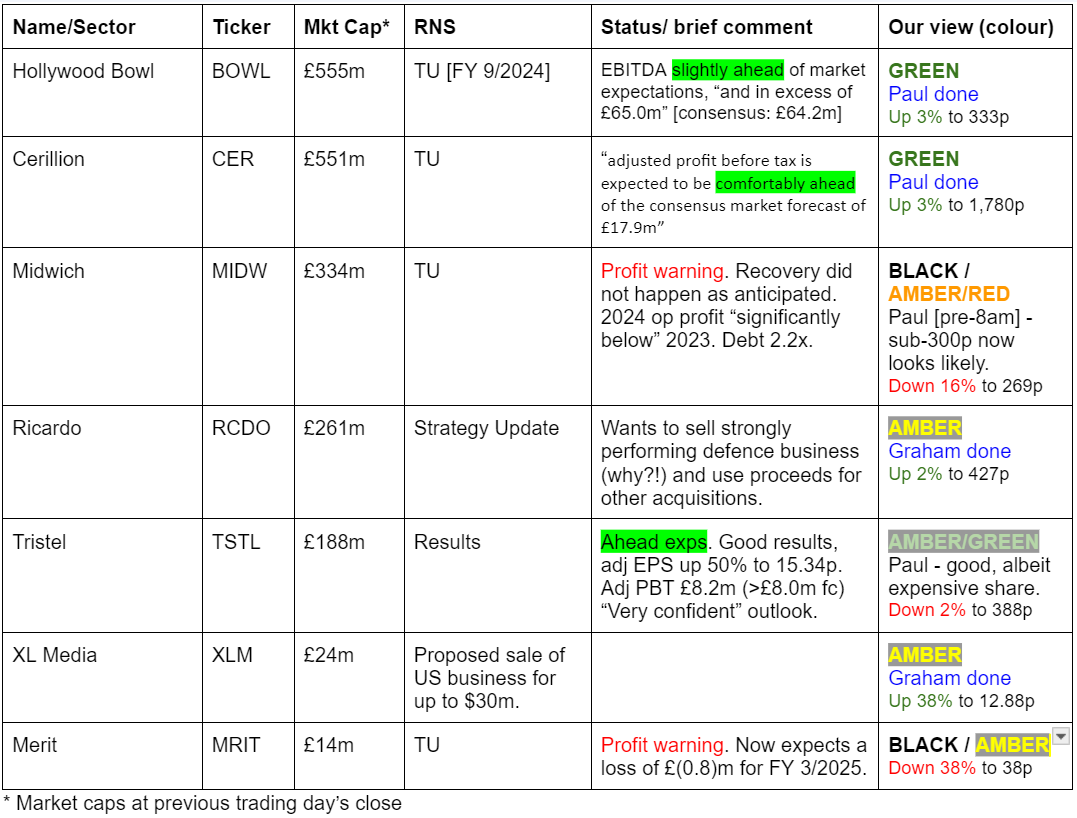
Hollywood Bowl (LON:BOWL) - up c.2% to 332p (at 08:15) (£570m mkt cap) - Trading Update [FY 9/2024] - Paul - GREEN
A slight beat against forecast is announced today, ending FY 9/2024 with a flourish. Not much said about the outlook. Lack of revenue growth slightly concerns me, which raises the question of whether we've hit peak bowling, after several year's strong growth? I'll stick at GREEN because this is an excellent business, generating lots of cashflow, which enables it to self-fund new sites, and pay decent 4% divis on top. Valuation seems reasonable.
XLMedia (LON:XLM) - up 40% to 13p (£34m/$44m) - Proposed Divestment of North America business - Graham - AMBER
XLM is leaving us after 10 years on the market, as it plans to convert into a cash shell. They have conditionally agreed to sell their North America business for up to $30m. I do some quick calculations and can see a potentially attractive return over the next year from the current share price, with some caveats.
Cerillion (LON:CER) - up 3% to 1,780p (£516m) - Trading Update - Paul - GREEN
Another beat against expectations, as we suspected was being lined up given the soft forecast. Order book & pipeline sound exciting, and historically Cerillion has delivered on its prospects. Hence why despite a lofty valuation, I'm taking a risk and staying GREEN. We just have to hope nothing goes wrong, as it heavily relies on licence sales still - risking that a gap in the order book could bring a profit warning unexpectedly.
Ricardo (LON:RCDO) - up 2% to 426.5p (£265m) - Strategy update - Graham - AMBER
Ricardo is looking to sell its Defence business despite that business contributing a huge chunk of last year’s operating profit. Perhaps it is excellent timing and the sale will free it up to focus on environmental markets? I don’t see any reason to object to the decision, but the price is all-important.
Paul’s Section:
Cerillion (LON:CER)
Up 3% to 1,780p (£516m) - Trading Update - Paul - GREEN
Cerillion, the billing, charging and customer relationship management software solutions provider, is pleased to provide an update on trading for the financial year ended 30 September 2024.
This niche software company is one of AIM’s star performers, having roughly 20-bagged since 2016. Although most of the gains have come in just the last 4 years. It seemed to find a sweet spot, in cloud-based billing services for telecoms companies and has won bigger & better orders as each order develops into another reference site.
This year to date, I was GREEN on both 22/4/2024 and 13/5/2024, noting that modest forecasts for FY 9/2024 looked beatable. Reservations include its dependence on licence wins, with only about a third of revenue being recurring. Plenty of cash, and big management shareholdings, so it has the owner’s eye - which often seems to deliver better long-term performance.
CER was one of my top 20 share ideas for 2023, despite it looking expensive at the time (at 1210p), it’s risen 46% since then - demonstrating that occasionally it is worth paying up for high quality growth companies. It’s so difficult though, to identify in advance which companies will actually deliver on their forecasts, and which ones will disappoint. Everything is obvious, but only after the event, I find!
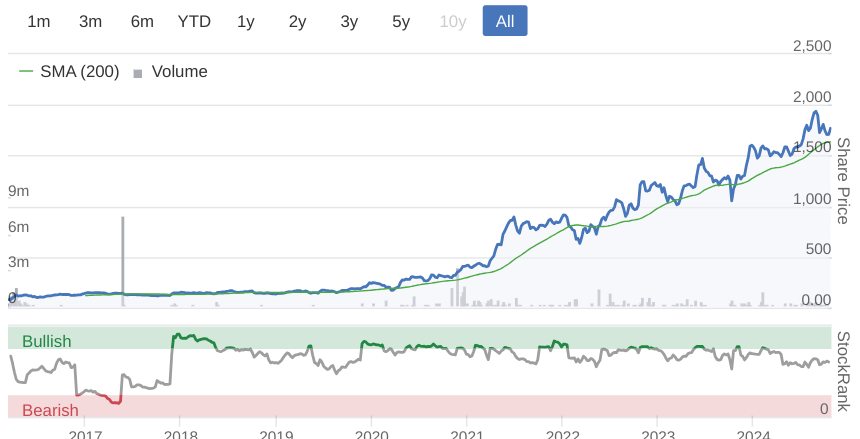
What’s the latest? Today it says -
“The Company traded well over the second half of the financial year, after record first-half revenue and adjusted pre-tax profit. Revenue for the year is expected to be approximately £43.8m (2023: £39.2m), and adjusted profit before tax is expected to be comfortably ahead of the consensus market forecast of £17.9m (2023: £16.8m).
The balance sheet remains strong, with net cash at the financial year-end increased to £29.8m (30 September 2023: £24.7m).”
I like that they’re using actual profit as the performance benchmark, not EBITDA (which can often be wildly inflated at software companies, and nothing even remotely similar to cashflow due to capitalised payroll costs).
What does “comfortably ahead” of £17.9m forecast mean here? At a guess, I imagine perhaps £19-20m adj PBT?
H2 revenue by implication must be £21.3m, because H1 actual was £22.5m, and the total for FY 9/2024 is £43.8m. So H2 revenue down c,5% on H1.
Adj PBT in H1 was £10.5m, so expecting H2 profit to be down a bit on H1, is also pointing towards c.£19m FY 9/2024 adj PBT.
Note the really high profit margin - adj PBT was 47% of revenue in H1, showing that this is a quality business with very good pricing power, and lean overheads.
Broker update - I’ve just noticed Panmure Liberum has updated us, most helpful. I could have saved myself the job of reasonableness checking the numbers, as they’ve done it for us, and come in at exactly the same number as me, £19m adj PBT.
That turns into fully diluted EPS of 49.4p, giving a PER of a tooth-suckingly high 36.0x.
Forecast for FY 9/2025 is left unchanged at 52.8p - obviously this will have to be significantly beaten to justify a share price of 1,780p, let alone any higher. The contract win news has been very strong, so I think we need to work on the basis that something nearer say 60p EPS is likely, otherwise there’s no way such a high share price could be maintained.
Order book - most of this has already been announced, but is still exciting -
“Total new orders signed in the year were significantly greater than in any previous year, reflecting new customer wins as well as the growing value of the installed base. The full benefit of these new orders is still to come through. New orders secured in the period included two major new customer agreements; a €12.4m win signed in early November 2023 with Virgin Media Ireland and an $11.1m contract signed in May 2024 with a leading provider of connectivity solutions in Southern Africa. As part of its expanding commitment to near-shoring in Bulgaria, the Company also moved to a new office in Sofia, in line with its growth plans.
The Company has entered the new financial year with a robust back-order book* and a strong sales pipeline, which includes some large opportunities. The Board continues to view growth prospects very positively.
*Back-order book consists of sales contracted but not yet recognised as revenue at the end of the reporting period plus annualised support and maintenance revenue.
Paul’s opinion - this is so tricky, because CER shares undoubtedly look significantly over-priced, based on the current forecasts.
However, it tends to set forecasts prudently, via the brokers, and it is clearly enjoying a remarkable trend of success since 2020 -
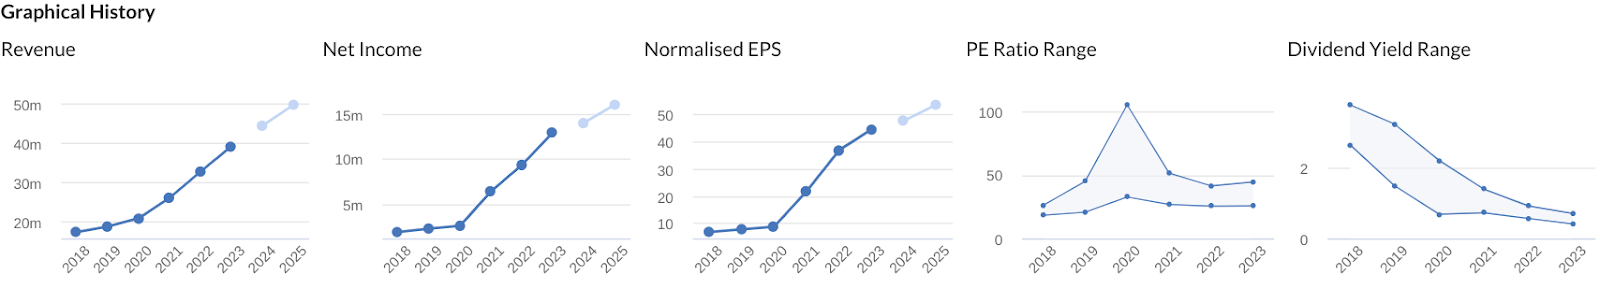
Graph 4 shows that the valuation is always high, so why baulk at a high valuation now, given that the company keeps delivering excellent growth?
I think the phrase “includes some large opportunities” above swings it positively for me, because CER has such a good track record of converting big opportunities into revenues.
Hence I think this is a rare occasion where I can stay GREEN despite a toppy valuation.
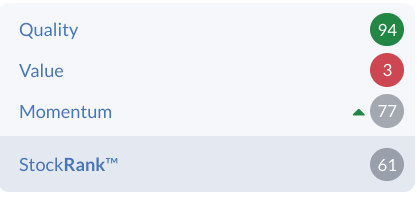
The StockRank starkly points out that CER is high quality, but certainly not good value!
Hollywood Bowl (LON:BOWL)
Up c.2% to 332p (at 08:15) (£570m mkt cap) - Trading Update [FY 9/2024] - Paul - GREEN
Good news today from the UK’s largest operator of ten pin bowling (72 sites), and with smaller operations too in Canada (13 sites). That includes 8 new sites that were added this year. The plan is to grow to 130 sites by 2035, which looks realistic and fundable from internal cashflows.
We’ve been positive on this share for some time here at the SCVR, because it’s a reasonably-priced self-funding roll-out of new sites, and is an impressively cash generative business model that also pays good divis.
Previous SCVR coverage this year -
3/6/2024 - GREEN at 344p - good H1 results, and in line FY outlook.
16/4/2024 - AMBER/GREEN at 333p - badly worded, vague TU that didn’t directly mention performance vs mkt exps - thus introducing doubt. Also I felt that shares had had a good run up at the time, hence moderating my view slightly.
Today’s trading update is much clearer -
“The Group expects to report EBITDA pre-IFRS 16 ahead of market expectations4 and in excess of £65.0m”
4. Based on company compiled consensus average of analysts' expectations for FY2024 where EBITDA pre IFRS 16 is £64.1m.
Slight beat - that’s only 1.4% ahead of expectations, which is nice to have, but not I would suggest a fundamental out-performance. All good FDs should leave a little caution in the forecasts, just in case something untoward crops up, enabling the company to finish the year with a little flourish, which is what this is - it’s good, but not exciting. Hence also why the share price reaction of +2% at the time of writing is only modest, and looks about right . Still, it leaves us the opportunity to buy back in (I’m not currently holding, as needed some money to buy something else recently in my trading account) at a similar price to where it was six months ago.
Note that BOWL shares are fully listed, so not at risk from the threat of AIM inheritance tax being possibly curtailed.
Net cash has reduced a lot, but still looks ample. The business model is terrific, in that it gets paid in cash from customers (hence little in receivables), and also little in inventories (just some food & drink). Hence a very favourable negative working capital model -
“£28.6m net cash at year end, following record levels of capital investment in FY2024 (FY2023: £52.4m)”
There’s also an unused backup bank facility of £25m.
Demand - note that there was no like-for-like revenue growth in the UK, which it says is due to demand normalising after several years of strong growth. So it looks as if we reached peak bowling in 2024. That’s not ideal, as some costs will have increased (especially wages), although the commentary points out that 70% of revenues are not subject to “cost-of-goods inflation”.
Outlook - not a great deal said, and mention of the longer term below might be interpreted as being a little hesitant about the shorter term? - plus the use of the vacuous phrase “profitable growth” of course, deliberately vague, and always jars with me whenever it appears - because it confirms they're not able to say anything stronger -
“We remain confident in the long-term opportunity for future profitable growth across both the UK and Canada. Our strong cash position means we are well placed to continue to invest in our growth, increasing the size and quality of our estate and looking to continually enhance the customer experience."”
I like the self help things BOWL has been doing, eg automating customer reservations (hardly rocket science in this day and age), and installing solar panels on lots of sites to reduce energy bills.
Valuation - no broker notes are available. Stockopedia shows broker consensus of 21.8p for FY 9/2024, rising slightly to 23.2p FY 9/2025 - good to see only a modest forecast increase, making it more likely that plan is met or beaten. Also that seems realistic, given that organic growth from existing sites is now harder to achieve after strong growth in the aftermath of the pandemic. Maybe people went bowling in 2022 and 2023, but are now focusing disposable income more on foreign holidays?
BOWL should be able to bolt on more growth from acquiring independent operators and building its own new sites too. Plus it’s been refurbishing some existing sites.
Hence I’m wondering if we should see its core business as having reached maturity, with maybe low expectations for any further growth from existing sites? The danger with new sites is how do they avoid market saturation? That could be an issue that’s worth asking management - what is their process for identifying new sites with enough unmet demand?
At 333p per share this morning, the forward PERs are 15.3x, which I’ll adjust to 15.0x to allow for the slight beat announced today. That falls to 14.4x FY 9/2025 forecast (which should be achievable/beatable). That seems a reasonable price. The dividend yield is about 4%, with roughly half earnings paid out as divis.
Paul’s opinion - the lack of LfL (like for like) revenue growth does concern me a little. That said, ending the year with a slight beat is pleasing. Going forward, I don’t see particular scope for this share to re-rate any higher in terms of PER as the market seems comfortable to price it around 14-15x PER, which is where we currently sit. Is there scope to beat forecast? Maybe, but looking at historical performance, 2020 and 2021 were obviously hit hard by the pandemic, but demand then bounced back strongly in 2022 and 2023. It seems to me that BOWL probably enjoyed peak trading in 2022 and 2023, and might now be struggling to maintain that growth - with new & refurbished sites possibly taking up the slack from it not being possible to deliver any further growth from existing sites in the shorter term?
The good news is that household incomes are now rising again, well above inflation. This should mean that plenty of working households will be enjoying more disposable income again. As an affordable leisure activity, I think bowling could benefit from that macro effect.
We don’t know what the future holds, all we can work on is the figures available today. These show a reasonably priced share, in a company with prodigious cashflows, which it utilises to self-fund further expansion, and pay decent divis. That’s such a good combination, that I have to stay at GREEN.
There’s also the possibility of a buyout offer - BOWL is the only remaining listed bowling operator, with a smaller competitor having been bought out - private equity like to buy these companies, grow them further, then sell them back to the city for a higher price a few years later. I imagine an offer of 400-450p would be likely to succeed, as institutions like liquidity events that enable them to cash out for a premium.
Graham’s Section:
Ricardo (LON:RCDO)
Up 2% to 426.5p (£265m) - Strategy update - Graham - AMBER
Paul covered Ricardo’s full-year results in detail here (results to June 2024).
Ricardo is a consultancy with its fingers in a lot of pies: eight sectors in total. If I had to describe it in two words I would say it's an engineering consultancy, but it provides very broad expertise that is beyond what you might typically expect from that.
However, it announces today that it’s seeking to narrow down with the divestment of its Defense business.
This business “provides capabilities in engineering and production services for land vehicles in the defence sector”.
I’ve checked those revenue full-year results again and I see that Defense contributed £123m of revenue (Ricardo total: £496m).
It also contributed £23.5m of underlying operating profit (Ricardo total: £57m before central costs. After central costs, Ricardo’s total underlying operating profit was £39m).
In other words, Defense was by far the most profitable business in Ricardo in FY 2024.
It also made a major contribution in FY 2023, although at a lower level.
Clearly this new strategy is going to make an enormous difference to Ricardo’s future profitability, assuming that a divestment takes place. They observe that “the potential divestment is expected to be dilutive to the Group’s earnings per share in the near term”, which is a very calm way of saying this!
They continue:
Depending on the level of proceeds received from the potential divestment, the board will consider the appropriate use of proceeds in line with the Group's capital allocation policy. As part of this, Ricardo has been actively exploring potential acquisition opportunities to reinvest some or all of the proceeds in the event of a completed divestment. Any potential acquisition would be expected to be earnings accretive and in line with Ricardo's strategy to increase its presence in the environmental consulting market, thereby accelerating our portfolio transition to a high-growth, high-margin, lower-capital intensive business.
Graham’s view
I initially suspected that the planned divestment might be intended to get Ricardo’s debt levels under control, but the leverage multiple as of June was only 1.25x which would almost always be considered a safe and conservative level of borrowing. Net debt was £47m.
Since that theory has no legs, I am inclined to take Ricardo at its word: it wants to focus on “environmental and energy transition”, in line with its long-term (5-year) strategy announced back in 2022.
I’m rarely opposed to a company increasing its level of focus, so in theory I have no problem with this move.
That leaves one potential hair in the soup: the price. Let’s see what sort of deal Ricardo can come up with.
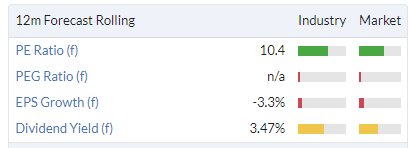
My overall view on Ricardo is the same as Paul’s: neutral, even at this lower share price (it was trading at 500p when Paul covered it). Consultancies make for tricky investments in my experience, and even a large and highly accomplished one such as this could be fully valued here:
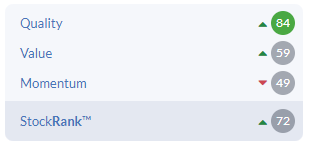
The StockRanks are a little tempted, giving it a 72:
I suppose much depends on the price achieved for the Defense business. If they manage to strike a great bargain, and if future performance benefits from increased focus on their selected markets, then perhaps Ricardo could be cheap at this level.
XLMedia (LON:XLM)
Up 40% to 13p (£34m/$44m) - Proposed Divestment of North America business - Graham - AMBER
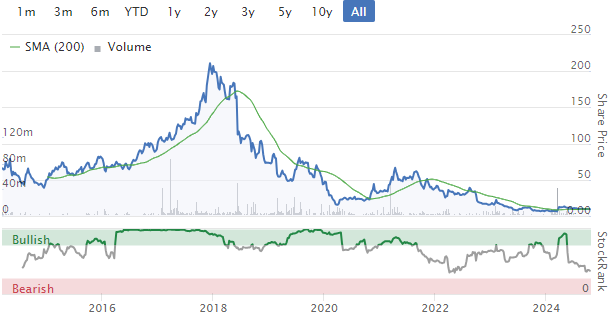
This company may be leaving up after ten years on the stock market. Ultimately, it didn’t produce a long-term sustainable business:
The news today is that XLM has agreed to another disposal. This follows the sale of its “Europe business” for up to $42.5m earlier this year.
We now have the agreed sale of XLM’s North America business. Key points:
$20m up front, plus up to $10m additional in April 2025 depending on performance. Equivalent to up to 8p per share for XLM shareholders.
31% of XLM shareholders have already pledged to back the deal, so it’s highly likely to be approved.
After the deal goes ahead, XLM will be a cash shell (as defined under AIM rules).
The deal values XLM’s North America business at 5.5x adjusted EBITDA for 2023
Rationale for the sale: after the disposal of its Europe business, XLM did not have the scale to compete in the US, and the remaining North America business may have been “too small to remain listed”. Sounds reasonable to me.
Graham’s view
Our historic concerns about the quality of XLM’s online marketing operations are irrelevant now, as the company has decided to convert its assets into cash and move on.
The only big question now is whether there is any value in XLM as it turns into a cash shell and distributes sale proceeds to investors. After that, we might wonder how the cash shell might be used.
Here is all the cash that is likely coming XLM’s way.
Firstly, the cash balance as of June 2024: $19.4m, minus $4m in a deferred acquisition payment that was due, so let’s call it net cash of $15m.
Additional $10m due in October 2024 (second payment for Europe disposal)
$7.5m plus an earnout of up to $5m due in April 2025 (final payment for Europe disposal)
$20m initial payment for the sale of the North America business, assuming it goes ahead.
Up to an additional $10m in April 2025 (final payment for North America business).
Roughly speaking, this says to me that XLM should have net cash of between $52.5m and $67.5m by April 2025, depending on the sizes of the final payments for their disposals.
Some costs may drag these estimates lower. In its interim results for the period to June 2024, XLM said that it “continues to incur transition and rightsizing costs”. With the Europe business having been sold, its remaining operations were costing about $1m per month in terms of its operating losses.
The share price is up by 40% this morning to 13p, equivalent to a market cap of about $44m. I’m inclined to trust that the market is right to be cautious, even though $44m is lower than the lower bound of my simple cash estimate ($52.5m).
There is always the risk that the deal falls through, there is the problem of cash drain until the North America business is sold, there is the discount for time as payments to shareholders may not be completed until next summer, and there is the question of whether the cash shell will want to retain some funds for future plans.
Perhaps I would put the market cap a little higher, maybe around $50m, but I don’t want to stray from a neutral stance on this for the sake of a few million dollars, so I’m staying AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Saga (LON:SAGA)
mopdys has downgraded saga's rating - based on the words coming out of the mouth ref solvency issues and their inability to maange situation with a cunning plan its probably not a surprise.
https://www.reinsurancene.ws/m...
Last year both Sondrel and Wandisco (now Cirata) went through a period of multiple reporting of new and exciting contracts only for them to revealed as an illusion, with disastrous results. At the time Simoan noted in the comments that, regarding Sondrel, he had been close to the ASIC industry for many years and had not come across them. Since then EnSilica (LON:ENSI) has spent much time insisting that they are not the same as Sondrel even though it appeared that their contracts announcements seemed to be to similar products/markets and clearly the share price has not given them any breaks.
I have been generally impressed by Ensilica and have looked at their growing contract base (another today)with approval, but am still trying to find whether they are correct to believe that they can prosper and grow in what is sometimes regarded as a commoditizing market in ASICs. Can Simoan or anyone else offer their knowledge on the likely competitive position of Ensilica, which seems to be unreasonably cheap, for such an apparently promising future?
I have been generally impressed by Ensilica and have looked at their growing contract base (another today)with approval, but am still trying to find whether they are correct to believe that they can prosper and grow in what is sometimes regarded as a commoditizing market in ASICs. Can Simoan or anyone else offer their knowledge on the likely competitive position of Ensilica, which seems to be unreasonably cheap, for such an apparently promising future?
I’ve been retired now for 4 years and so can’t really comment on the current situation. I think I mentioned last time that EnSilica (LON:ENSI) looked very much better than Sondrel because they at least have some specialisation in RF and mixed-signal ASIC design services for which there is a market. I also know of a couple of the leadership team indirectly through former long-term colleagues (who worked with them in the late 90’s).
However, I don’t really believe companies with this type of business model should be listed because it won’t make a good long term investment - you only have to look at the lack of free cash flow the company has produced in it’s entire life as a listed entity to see it is almost definitely only those that work for the company that are doing well from it. The design services industry lurches from feast to famine, and although judging by the recent RNS it’s feast time now, famine will follow sure as night follows day. Anyway, I hope it works out for you.
All the best, Si
Thank you very much Simoan, I appreciate your insight into EnSilica (LON:ENSI) and the ASIC business, it is exactly the kind of informed view I was looking for and I will keep my enthusiasm under tight control!
B.P. Marsh & Partners (LON:BPM) Up on volume today. Interims on Wednesday. I hold.
Seplat Energy (LON:SEPL) shares have reacted well to being given permission to buy Shell's Nigerian assets.
This year's NAPS selections contained several very good performers.
Seplat Energy (LON:SEPL) Should see a further bounce in the morning when confirmed by the RNS, hopefully with details of the deal. Been a long wait on this one but it was always coming. My largest position so certainly cracking a beer tonight.
In case anyone here interested in the Mining sector hasn’t seen it, I started a thread on it last December. It was in expectation of a big Mining Sector bull market in 2024…………which hasn’t happened ….yet. Why it hasn’t is covered on that Mining thread.
Here’s the link for it:-
https://www.stockopedia.com/co...
A key point about the Mining sector is that it can move up and down independently of how Markets in general are doing. e.g that savage Mining Sector bear market that ended in 2015 was while Markets in general were doing overall OK. Yet such were the share price falls that Anglo American (LON:AAL) bottomed at just £2.20 ahead of going up 10 fold in no time in 2016. Anglo American (LON:AAL) saw off a bid from BHP (LON:BHP) around 6 months ago, Talk now of BHP bidding again (hence Anglo American (LON:AAL) share price going up last week while most of the sector saw falls).
For reasons I can’t fathom a lot of small investors favour early stage “hope” Miners hoping eventually to get to the producing stage. Most don’t get there and shares like 80 Mile (LON:80M) have fallen 99% but still with investors believing! There’s nowt as strange as illogical human behaviour. Why buy those when there’s sometimes so much upside for Miners that have got to the production stage they dream about.
A good example of producing Miners doing well is gold shares thanks to the big gold bull market this year. Having come unstuck with gold producers in the past I have missed out on that bull market that has seen some quality shares quadruple this year. There’s a post on those shares on the Mining thread.
I’ve never come unstuck with the big Miners like Rio Tinto (LON:RIO) etc nor with Investment Trusts investing g in the Mining sector. There’s more on those too on that Mining thread. BlackRock World Mining Trust (LON:BRWM) is well worth those not keen on trying to select the best shares in the sector, having a good look at BlackRock World Mining Trust (LON:BRWM) .
If there are any reading this post who haven’t seen the Mining thread (and there are a few other Mining threads that get lost too) and are keen on the sector, then please post on it to help keep it alive.
Now that is something I can get on board with. Small percentage in BlackRock World Mining Trust (LON:BRWM) as a diversification from the rest of the equity market - job done!
Thanks Ken, as always.
I’ve been involved in Avation (LON:AVAP) for a while now as I personally consider it highly undervalued but as many others have also found there was no obvious catalyst for it to re-rate closer to other industry valuations other than the fact that 50% NAV clearly felt like the wrong price particularly against the airline leasing wider macro dynamics.
I also didn’t want to sell at a low valuation despite the fact that I was clearly aware of the opportunity cost (it’s not like I was getting a dividend) as I was conscious I may miss a re-rate.
And so it proved - with the stock going up in 2 days by about 35% to a more reasonable 170p though still way below what I consider reasonable value.
Which gets me wondering - opportunity cost is all well and good but there is no guarantee that what you move into generates anything better and comes with increased costs of trading in/out. So is patience and conviction the right answer? Should we set a realistic target return on our portfolio and view something over 3-5 years? Or is the time value of money more important and we should set a timeframe for each position irrespective?
You could argue one is trading and the other is investing but I think it is more complex than that. What do others do when thinking about opportunity cost and time value of money?
Hi David... measuring my annual return for the whole portfolio has been a game changer for me ( and not something that I bothered doing prior to joining Stocko, as I just held funds )... now, I'm far more conscious of the Velocity of returns, which should encourage culling stagnant investments... long story short ... the higher the conviction that an investment may prove fruitful, then the more patience... but if that conviction isn't there, then there is a measurable goal incentivising one to sell and move on....
Hi David,
I find that splitting my investing styles into ‘pots’ is a helpful way to allow me to adopt different approaches to different situations and time frames. Value investing by nature requires a lot of patience which generally doesn’t suit me as I struggle to watch holdings decline in value significantly and hold a ‘long term view’. I don’t like holding onto losses. Most of my ‘investment’ activity is in essence trading on a time frame of a few days up to 12 months. I take this approach exclusively in my ISAs. For this fund there has to be a compelling value OR growth story, but existing momentum is mandatory, as is a defined stop loss. This links to your comment about a ‘catalyst’ and opportunity cost, because I only hold stocks here where I think there is a catalyst in play or emerging, and if I’m wrong I don’t hold for long and move on. I’m usually 60-75% in cash so lately have been holding short dated gilts to pick up some interest.
Since I’m not naturally a long term investor I need to follow momentum and cut losses quickly in this pot, and since taking this approach over the last 3 years I’ve made above market returns with very low volatility. But I have to exclude deep value altogether in this pot, and I only invest in long term value in my SIPP. In my SIPP I also favour momentum alongside growth or value, but I do allow an element of long term deep value on the basis that this pot has a longer horizon before I plan to access it (10-15 years). I tend to hold upto 30% of the SIPP in stocks that I think are so fundamentally undervalued that I’m able to ride out the volatility, for example GSK (LON:GSK) and a small amount of Enquest (LON:ENQ) . I have 35% in gilts, 25% in FTSE100 and 250 ETFs and the rest are trading holdings like Triple Point Social Housing REIT (LON:SOHO) , Gulf Marine Services (LON:GMS).
Obviously I sometimes find that certain stocks are valid in both pots, like SOHO and GMS which both look like value opportunities but are showing reasonable short term momentum too.
The main thing for me is that wherever the opportunity cost question comes up I will only hold it in the long term fund and will try (against my natural instincts!) to ignore the fluctuations and forget about it.
Great response. There is always room for sensible compromise.
"So is patience and conviction the right answer? Should we set a realistic target return on our portfolio and view something over 3-5 years? Or is the time value of money more important and we should set a timeframe for each position irrespective??"
Hi David
My personal goal is to achieve a 15% CAGR over the long term.
That means +15% growth in 1 year, +32% growth after 2 years, +52% after 3 years, etc....
I think Avation (LON:AVAP) is a great example where patience is necessary to achieve this.
I don't want to bore anyone with my workings, but based on my own cash flow projections:
Additionally if my analysis is correct then there's always the possibility that someone comes in with a cheeky bid close to NAV before 2026, which would be another route to that +15% CAGR target.
So for me it's better to hold now even though psychologically it's hard to be patient when the share price remains flat for so long.
As you mentioned it's only the re-rating this week that has finally got things going. For me personally it's also the first time in c 1.5 years that each of my individual purchases has moved into meaningfully positive territory.
I should add that I try to take this approach with many of my holdings, but of course, sometimes it doesn't work out how I hope it will.
A
The Ricardo (LON:RCDO) plan to sell their defence business reminds me of Oxford Metrics (LON:OMG) who sold half their business and then sat on their cash pile for ages trying to find something to buy. Only half the risk is getting a good price, the other half doing something worthwhile with the money. I hope Ricardo have some targets in mind.
I think the clue is in the update i.e. "Reflecting its current strong financial performance, the potential divestment is expected to be dilutive to the Group's earnings per share in the near term". Why on earth would Ricardo (LON:RCDO) dispose of their best business unless they are being offered a premium price? At least Oxford Metrics (LON:OMG) managed that part. It appears to me that Ricardo (LON:RCDO) are contemplating selling the crown jewels (and diluting earnings to boot) simply to tick the box of being a pure environmental services play. Have they been listening too much to their brokers telling them that they can get re-rated as a pure play?
Is yhere a Mello Monday this evening?
Good question as it looks like there should be: https://melloevents.com/
But I haven't received an email so perhaps it's not happening for some reason?
AA, Damian,
I think there is a Mello evening this Thursday 24th "results show" 17:00-19:30.
Graham.
There is a Mello Monday scheduled for next Monday as they are usually every fortnight. We were due to have a Results show this Thursday to include Nabil but there were no other companies wanting to do anything ahead of the Budget...management are frozen in the headlights and not committing to very much at present.
Looks like it is now next Monday according to post on X (Twitter as was).
System1 (LON:SYS1) results are tomorrow. Interesting the shares have bounced back over the last fortnight. The company was upbeat in the last update a while back.
For clarity it’s the H1 trading update, would have added more but looks like many have recently added (and swiftly moved the price) in anticipation of those previous positive statements.
I too wait with anticipation. Since the moves, both down and back up, have both been on almost no volume, I am not taking them as indicative of any specific outcome. Fingers crossed for tomorrow!
I don’t hold , but some say sell as a precaution after a good run up to results. Card Factory was perhaps an extreme example but the Naked Trader was right on that one.
is the naked trading not in risk of setting the market though when he shouts from the rooftops ?
He mainly trades mid caps and low billion large caps these days so pretty unlikely he topped up on ME International (LON:MEGP) on his last blog (last Thursday) as it pushed through £2 but last time I looked its off a bit today.
If he was fishing in sub £100 mil market cap I would agree but given he's mostly in stuff £300 mil minimum market cap and above I think effect these days is less marked.
He does also say on his blog warnings "don't follow me" but no doubt some will same as there will always be those who follow Paul & Graham on Stocko.
He said he had topped up ME International (LON:MEGP) at 203p last Thursday.
Thank you very much for your observations on XLMedia Graham, it's one of our dying dogs that's just whimpered. Our decision now is either sell and have the capital loss to hopefully use one day, or hang on hoping for a better payout. Insults and comments welcome from stockopedia members. We could buy a few more CLIG which is a much safer bet imo.
It's looking like XLMedia (LON:XLM) sits in the Last Chance Saloon today. I don't hold XLM any more but did keep this pampered pet from 2016 till last March, making capital gains on 3 occaisions of spikes. I'm still in the process of ridding myself of other kennel members in our portfolios, good luck to holders.
Card Factory (LON:CARD)
Given the share price, the market doesn’t believe it will achieve expectations; also I expect the anticipated increase in employer’s NI contributions is weighing on the shares. However at 90p the risk/reward looks attractive. I bought back in around 95p and am tempted to add.
Ramsdens Holdings (LON:RFX)
Apologies for sounding like a broken record, but the gold price is now above £2100 per ounce, added to which the recent update said that “all key income streams are growing and we have optimism for further growth in FY25”.
I can only assume that it is the overhang from Downing selling down that is keeping a lid on the share price. Plus it is AIM listed, but the company is still performing. Again tempted to add.
Very good investment case for Ramsdens Holdings (LON:RFX) made on the Sharepickers Investment Club by Justin . Worth a read.
Apologies to Paul and Stocko for mentioning a rival, but there's room for everyone so I hope they forgive me.
Link?
Cerillion (LON:CER) A quality company no doubt, however I note that whilst they announced a slight beat on PBT (EPS upgraded by 1.8p), they missed Panmure Liberum's top line forecast of £45m by £1.2m. Considering they are on a PER of >36x and are forecast to grow EPS at ~13% next year (PEG just under 3x), I think shares are fortunate to be up. That being said, they would be near the top of the list of buys if we see a significant negative reaction to next weeks budget.
Risk management is rarely discussed on this site.
Gold/ silver/ uranium and oil are very good diversifiers, which means that shares in these sectors have attractions over and above their potential returns.
These commodities are quoted in dollars. The pound has been strong and the dollar weak over the last year, which means that if this reverts, these commodities will also benefit from an exchange rate change.
Anyone for Hochschild Mining (LON:HOC) or Yellow Cake (LON:YCA) or Seplat Energy (LON:SEPL) ? (I hold).
I topped up on Global X Uranium UCITS ETF USD Acc (LON:URNG) this morning, after the news on Microsoft and Google planning to use nuclear power to power their data centres.
Centrus Energy (ASQ:LEU) . A play on uranium and more generally nuclear energy.
I hold Hochschild Mining (LON:HOC) Epitychia , bought too many in the 2020's and subsquently parked it in my kennel, I'm looking forward to realising some future paydirt but will not be adding because of the lack of a dividend. Having said this, I've added to Serabi Gold (LON:SRB, also no dividend but hey, it's balancing and diversification in one. I sold out all Centamin (LON:CEY) last week but have reconsidered and bought back in while maintaining my trust in Anglo Asian Mining (LON:AAZ) . I must keep an eye on the AISC's of these small miners while I'm at it.
Hi Epitychia,
"Risk management is rarely discussed on this site."
Eh?!! I baulked at that because surely everything we do is all about trying to calculate & manage risk:reward? Hence why we flag up risky shares with RED & AMBER/RED, to help steer people away from losing money on the riskiest things.
Diversifying into things like commodities, currencies, previous metals, etc - surely that's little more than guesswork, unless you have some sector expertise?
I'd rather specialise into things where I can demonstrate experience, and a track record of beating the market (which basically boils down to one thing - filtering out the junk in small caps, and just owning the good ones).
So the danger for me would be if I diversified into lots of other things such as the ones you mention, I would lose my competitive advantage. Sure I might diversify away some of the risk, but I'd also dilute away my advantage in small caps, so probably end up generating average or low returns.
Also I think when areas become fashionable to invest in, they often seem to end up going wrong.
Regards, Paul.
Paul, Stocko Team,
Apart from all that you do to flag risk, through various reports and presentations. Surely 'Risk Management' starts and ends with each individual investor?
Graham.
I'd rather specialise into things where I can demonstrate experience, and a track record of beating the market (which basically boils down to one thing - filtering out the junk in small caps, and just owning the good ones).
Paul - Your filtering junk comment reminds me of an excellent 2015 Cliff Asness research paper, "Size Matters, If you control your Junk", which cites signifigant evidence of a small cap premium, but only if you select for quality. So true!
https://papers.ssrn.com/sol3/p...
Individual shares are highly correlated, this is measured by beta, a form of standardised correlation coefficient.
In a market decline most shares will fall, the reverse in a market rise. This is not the case for commodities. It is a matter of record that certain commodities are not highly correlated with shares and in some cases have a negative correlation. They reduce volatility and also offer crash protection.
I am not suggesting that you invest in things you have no knowledge of but i am suggesting that investing across a range of asset classes will reduce your risk. The next downturn will sadly demonstrate this.
BBG) -- Citi starts coverage with a buy recommendation, saying Yellow Cake (LON:YCA) is a “unique vehicle” for exposure to physical uranium.
Analyst Ephrem Ravi writes that Yellow Cake’s low operating costs and volume growth are key attractions for the stock
Offers alternative to directly owning the commodity, while also helping to alleviate the multitude of risks that come with owning uranium equities
Citi sees a positive outlook for uranium demand until end of the decade
PT set to 750p, implies a 26% increase from Friday’s close; stock now has 5 buys, 1 hold and no sells
Tristel (LON:TSTL) looks good to me below 400p. Bear in mind these results were pre-announced back in July, when their release took the SP over 500p. Chart looks like many other quality names where the selling starts as August turns to September. It’s not wise to anchor to previous levels, but I believe we’re seeing CGT crystallisation across this and other names with long term gains. And that will hopefully mean-revert. Damnit, if I’d sold in early Sept I’d be buying back in right now and feeling smug.
Podcast was missed Paul, The dog had a shorter walk this Sunday :)
I'm not surprised your inspiration tank is low, this market is a bit miserable isn't it? Well done anyone actually making money at the moment.
Glad I'm not the only one. Was having a storming first half of the year then the election being announced seemed to bring things to a shuddering halt. for all the ups and downs since it's made zero impact on my equity. Really should have just sold in May and come back in ummmm November?
Hollywood Bowl (LON:BOWL)
Nice update.
From my view the business is developing steadily and the strategy to move into Canada is gaining traction. New openings take time to contribute on a like for like basis so the absence of LFL growth is not of overly concern. Self financing is in my view the best way to grow a company as opposed to raising debt or issuing equity
I hold.
Serabi Gold (LON:SRB) good results again. This does have very compelling earnings growth. Eps predicted 2026 almost 80% of current share price.....is it just the "Brazilian" risk that keeps it lowly valued?
I literally have no idea about Serabi Gold (LON:SRB) itself, but I can answer your comment about mining stocks (and oil exploration) more generally with reasons why these are all 'casino' bets with a heavy bias to the 'house'.
1. There is usually no way of knowing accurately what is in the hole in the ground.
2. The cost of extraction and complexity of doing so is also unknown.
3. Management will always give the bullish case on the value of what might be there.
4. Governments in some of these countries sometimes move the goalposts and claim rights to the find.
5. Small shareholders will always be the last to know the bad news about an empty site.
The above (and doubtless many more reasons) are why most of these stocks trade on huge discounts to their supposed value and it is also why the vast majority of them end up failing.
Analysing this sector is impossible and the reason why Paul, Graham et al don't do so - quite rightly, in my opinion.
So good luck with your bet on '24 Black' - "this time next year we'll be millionaires, Rodney".
Serabi Gold: (LON:SRB) So good luck with your bet on '24 Black' - "this time next year we'll be millionaires, Rodney".
Of course there is far less risk investing in AIM shares.
I hold Serabi and will continue to do so.
Thanks Sparkler. I fully agree that speculative "finds" pre-production are a lottery. But Serabi Gold (LON:SRB) has been in production for years, has ten years life left and keeps digging up more gold than last year. So it does seem lowly valued at a forward PE of 1.8?
Whilst it is often a gamble with miners it’s ’usually’ not quite analogous to a spin of the roulette wheel. By employing professionals to analyse sites it’s about shifting the odds more in your favour..in this instance putting another 30 ‘24 blacks’ on the wheels. The challenge is to find a company with top management and professionals !
A touch harsh imo. I dont own Serabi Gold (LON:SRB) but it's a producer and not an explorer so risk is less. It has a proven resource so knows how much gold is in the ground. It will have an AISC that is relatively stable so cost of extraction is known, although liable to future change, just like the input costs of most companies in any industry. The job of mgt of any company is to give the bullish case, it's up to investors to see through that. Location risk is a threat to most companies, look at UK North Sea O & G. I agree it's a high risk sector but that's mainly because finding & extracting metals & other mineral resources from the ground is hard but vital to our economy & future growth so needs to be supported imo.
Fair point about being a producer rather than an explorer, Joe. That lessens the risk and like I already said, I know none of the specifics about Serabi Gold (LON:SRB) . However, they are still vulnerable to 'mining rights' issues as RDHowarth says below, not to mention extraction issues etc ,etc.
Of course, AIM is full of risky and spivvy stocks (some of which Paul seems to get drawn to - don't we all!) but I would rather this forum stick to trying to analyse those than comment on the 'unknowable' in the mining world. That was all I was trying to say, really.
For those that do see the value in the mining sector Ken Mitchell has created an excellent post.
There are definite risks to investing in gold miners, and many will avoid them for that reason, but I did want to add a few words about Serabi Gold (LON:SRB)
It has rocketed in price, so investers may believe they have missed the boat, but it is an unusual share that has actually got better value, even whilst getting more expensive.
Share price (pence) on Jan 2nd was 46.8, 2023 EPS was 8.74 cents or 6.9p (exchange rate of 1.2731) giving a P/E of 6.8. This sound reasonable for a Brazilian gold miner, or at least not pricey
Current share price is twice this now, but EPS for this year is expected to be 37.8, i.e four times higher, and hence a P/E of 3.21. Barring disasters, this should happen, as nine months production and cost/price is a known quantity already.
What is even better is that the P/E for next year, is forecast at just 1.82.
What is happening here is a lot more than just a play on the gold price rising.
1) Production is up as a second mine is coming on stream, and new equipment is being introduced to increase efficiency.
2) Increasing production is also reducing the AISC so that margin would increase even if the gold price stays static.
If you look at what I believe their credible plans are for increasing production to 60000 ounces a year in a couple of years, with increased margin, then this still looks very cheap to me. They also have no debt.
Caveats:
This is my third largest position so obviously I am positive about this and probably suffer from some bias.
It is a small gold miner in Brazil, with all the attendant risks.
Having said all that, if you are an invester that considers companies like this, I would suggest that the risk reward ratio is interesting. The company has some very good presentations available, so you can dig into the detail yourselves.
David
I think the main concern re Serabi Gold (LON:SRB) has been retention of mining rights... which rear their ugly head from time to time, normally when the stock is out of fashion.
....thanks RD. Serabi Gold (LON:SRB) looking ok for the next three years on this but yes there is always a risk there I agree.
Presumably though with the mine itself fully owned the Brazilian government gets nothing back if it doesn't allow the licence??
Ditto ref thumbs up for cgtcalculator - haven’t found anything else free that is better -
Don't worry about it Paul. My dog will get over it.
No podcast, Rover is livid!
I suspect Paul was ill or just had other priorities - while much missed it's bound to happen from time-to-time
You obviously don’t read the header, which was why I wrote the comment, it was a joke not a complaint. I think the fact we all noticed there was no podcast is indicative of how we all enjoy it so much and it’s part of our weekend’s enjoyment!
My oversight Ox2906
My morning smallcap tweet: Send in the Frowns
Merit (LON:MRIT) Midwich (LON:MIDW) Ricardo (LON:RCDO) Impact Healthcare REIT (LON:IHR) Ocean Wilsons Holdings (LON:OCN) XLMedia (LON:XLM) Avacta (LON:AVCT) Cizzle Biotechnology Holdings (LON:CIZ) Light Science Technologies Holdings (LON:LST) EnSilica (LON:ENSI) Sareum Holdings (LON:SAR) Zinc Media (LON:ZIN) 1Spatial (LON:SPA) Hardide (LON:HDD) Cerillion (LON:CER)
◄Merit (MRIT)► warns FY-Mar down 8% and adj EBITDA c.£2m. That's 10% and 40% below mkt exp resp. Blames conversion of the sales pipeline falling short of expectations at Software & Technology Resourcing div. [SP=60 Cap=14m]
◄Midwich (MIDW)► warns FY-Dec rev only marginally up and adj op profit significantly down. Blames mkt outside UK and NA, which has not improved as expected. [SP=320.03 Cap=334m]
◄Ricardo (RCDO)► to divest its Defence business and exploring acquisition opportunities to reinvest some or all of the proceeds in the event of a completed divestment. [SP=419 Cap=261m]
◄Impact Healthcare REIT (IHR)► changes name to Care REIT (CRT) effective tomorrow. [SP=88.85 Cap=368m]
◄Ocean Wilsons (OCN)► sells 57% holding in in Wilson Sons for R$4.352bn ($768m), equivalent to R$17.50/sh. 15.0% to 22.5% Brazilian withholding tax on gain - as much as $142m. [SP=1495 Cap=529m]
◄XLMedia (XLM)► proposes sale of North America Business for $20m + $10m earn out. Would leave a cash shell. [SP=9.2 Cap=24m]
◄Avacta (AVCT)► collaboration with Tempus AI, a US company leading the adoption of artificial intelligence to advance precision medicine and patient care. Plans to leverage things that can be levered, natch'. [SP=60 Cap=217m]
◄Cizzle Biotechnology (CIZ)► licensing and partnership agreement for its proprietary CIZ1B biomarker hroughout the USA and Canada. $300k upfront. [SP=1.93 Cap=8m]
◄Light Science Technologies (LST)► follow on order from an existing customer in its Passive Fire Protection division, worth £1.17m. For completion in H1 2025, [SP=2.7 Cap=9m]
◄EnSilica (ENSI)► wins c.£2m Contract to start in Nov. Rev runs into next FY, supporting market expectations for both FYs. [SP=48 Cap=46m]
◄Sareum (SAR)► further subscription of £1m at 22.5p. [SP=27 Cap=32m]
◄Zinc Media (ZIN)► sells remaining legacy tele-sales contract publishing business for £100k. [SP=65 Cap=14m]
◄1Spatial (SPA)► wins second major customer for 1Streetworks with a £1m 12 month contract. [SP=65.93 Cap=73m]
◄Hardide (HDD)► guides FY-Sep sales of £4.7m down 15%. H2 rev better than H1 despite some delays in new business work now expected in next FY. Expects adj EBITDA close to break even. Expects strong recovery in revenues in FY25. New CEO imagines [er, states, surely?] that "the business now increasingly well positioned to deliver profitable growth."" [SP=5.5 Cap=4m]
◄Cerillion (CER)► guides FY-Sep rev c.£43.8m and adj pretax comfortably ahead of market forecast of £17.9m. Board continues to view growth prospects very positively. [SP=1730 Cap=511m]
I had not been able to see the webinar at the time, but I've had a chance to view it now. Thanks to Ed, Megan and the rest of the team for putting it together. I thought I'd share some ideas that came to mind as I watched it.
Regarding turnarounds, one idea that I had in mind is to look for momentum reversals. FEVR was a stock that was analysed. It has a terrible M (momentum score). The good thing about Stocko is that you can set alerts based on a number of criteria (adding a 52w-high would be nice). So set an alert when the M score is above 19 as a buying opportunity.
BRBY is another example. Will it recover, or will it not? There are arguments both ways. The M score is 2 at the moment, and analysts seem to be getting more pessimistic as time goes by. Again, put a trigger on when the momentum score crosses 19.
FXPO is another one I added. I invested in that some time ago, much to my chagrin. It is a mining company in Ukraine, which explains why it all went pear-shaped. But the Russians might pull out one day, and that will be your opportunity.
I added CVS, too. It runs veterinary practices which was hit by concerns over gouging.
You can broaden your search simply by running a screen on shares with a minimum market cap, and sort by ascending momentum rank. If something looks like it might survive then add a momentum alert.
The good thing about this is that you can set and forget, you don't have to keep everything in mind all the time. When an alert is triggered, sell something in your portfolio that is a bit of a plodder, or search behind the back of the couch to see if there's any loose change, and buy a position.
Sure, you'll miss out on some of the rebound, but it also means that you're not catching a falling knife where the bottom could be anywhere.
For high-quality shares, you can almost do the reverse. Set price targets. Look at the charts for a few years and look for "support levels". Set a price target for when the shares fall below that price, and top up a holding or create a new holding.
It's far from infallible of course, but it should increase your batting average.
What is the name of the webinar please? When I do a search/find there is no other mention of webinar on this page. The only one I can see with both Ed and Megan is about selling. Thanks
The one about selling is the one I'm referring to; albeit I'm talking about buying.
With all this talk of CGT being raised in the budget and having some more and less successful trades outside and ISA or SIP I thought I should consider what my position might be. But, rather than build my own, where to find a spreadsheet or calculator to tell me what might be due?
After some stumbling around and searching I found this site which seems to provide exactly what's needed http://cgtcalculator.com/
Simple format into which to arrange your trades and press the button and it gives you the detail. There's also nothing to stop you putting in hypothetical disposals to see how your liability might change.
Finally, it's important to note, as explained on the AJ Bell site, that losses can be carried forward indefinitely but have to be registered with HMRC within 4 years. At least that'll do something to reduce the pain of some of my speculative disasters.
While I'm pretty confident that CGTCalculator is doing the right thing, it would be great if Stockopedia could either check it out and confirm that, or even produce their own version.
We all suffer losses!
This looks useful for many of us who use brokers (e.g. Hargreaves Lansdown) which don't calculate a gains/losses report for you.
As you say the CGT burden has already increased and will be raised again in the Budget, so its important to be proactive about crystallizing losses to carry forward. Where you have an underwater position (we all have them) but continue to have positive conviction, then sell to crystallize the loss and then re-buy in an ISA/SIPP to enjoy the rebound tax free. These "harvested" losses will then provide a cushion and for setting against unsheltered gains, which BTW don't have to arise from shares.
Thumbs up for the cgtcalculator. I've used it for a number of years as part of my submissions.
Ocean Wilsons Holdings (LON:OCN) long awaited announcement of the sale of its OWOIL subsidiary this morning. Any help in unpicking the complicated announcement very welcome! Ocean Wilsons Hldgs - Sale of interest in Wilson Sons to SAS Shipping #OCN https://www.voxmarkets.co.uk/r... #voxmarkets undefined
USD 578m sale. C £444m. 35 m shares. £12.70 a share. That's what I make it :)
Ocean Wilsons Holdings (LON:OCN) Thanks Gimmers for working it out. This has been a long-time coming but looks a satisfactory result. I also wonder what impact it is going to have on Hansa Investment (LON:HAN) which I also hold. After the capital return in 2025 it would appear sensible to merge both investment companies given they have the same family controlling it and the same investment manager. I suppose it depends on their tax position, but given its all in Bermuda probably neutral.
£13 plus £7 for investment portfolio gives £20. But has always traded at discount, such that you could value that around 13 or 14£ say? And deal only closes H2 2025.
How much will they return to shareholders? Best case is all £13 and change if tax isn't worst case plus the 7 valued at 4ish gives £17.
The most promising thing is the potential need for a 75% vote if they need to change listing category.( UKLR 21.5 Transfer between listing categories - FCA Handbook ) That may give minorities like City of London scope to push for bigger divi return or winding up OCN - giving 30% upside to £20. But sounds like insiders don't want to do that. But what need is there for the OCN listing when they have Hansa Investment (LON:HAN)?
There is even scope for competing bid - Brazilian press have suggested other bidders are circling and I Squared want to go direct to PORT3 and buy it: I Squared prepares offer for Wilson Sons, but competition may arise | Business | valorinternational . However, MSC seems the deepest pocketed trade buyer so I don't know how likely this is. The Brazilian brokers had targets of c. R$23 so the 17.5 figure is somewhat disappointing and actually a discount to where PORT3 was trading Friday.
Ocean Wilsons Holdings (LON:OCN) - thanks for the press article Samscvb: it looks like I Squared Capital were dragging their feet, whereas MSC have come up with a clean and acceptable offer in a short period of time. I need to have a think about my holding and Hansa Investment (LON:HAN) holdings - unfortunately I hold them both outside of an ISA. Any return of capital through a dividend would be painful, and probably much more so in 25/26 tax year given what the Labour government supposedly have in mind. This is a good example of a Bermudan company (i.e. offshore) where I have made a capital gain that is taxable, but it is not a "real gain" as a 50% gain over 10 years is just inflation and I've paid tax on the dividends in the meantime.
CGT is unfair without indexation allowance in my view. Politicians seem to have forgotten that they removed indexation in 2008 and that was the reason why there was an allowance and lower rate. It is unfair to have no indexation and a high rate for a capital gain secured over 10 years or so. I'm sure many others are in a similar position.
Hi topvest,
The link further down this thread , provided by Damian Cannon takes you to The OakBloak's blog and is well worth a visit.
I hold Ocean Wilsons Holdings (LON:OCN) after reading the blog and weighing up the Pro's and Conn's, having looked at this one previously.
Graham.
Ocean Wilsons Holdings (LON:OCN) - thanks for the blog - quite a good summary. I think the problem with the worst case scenario is that you could effectively end-up with a £10 special dividend / buy-back and the remaining £10 per share left in the investment portfolio. There is also exchange rate risk. The RNS says that they will return a meaningful amount of the proceeds, not all of it. Ocean Wilsons Holdings (LON:OCN) and Hansa Investment (LON:HAN) are both on c40% discounts. I am contemplating selling my Ocean Wilsons Holdings (LON:OCN) holding and buying back in my ISA. May wait a few days - no rush.
Does anyone know what happens if there is a bidding war as I couldn't see what happens in the RNS if the financial bidders suddenly offers a premium takeover offer to Wilsons itself? There is a US$80 break fee receivable if MSC can't complete.
This is a reasonable take on the outcome: https://theoakbloke.substack.c...
What I would say is that once the sale goes through then much of the NAV will simply be cash which leaves the remaining holdings at a whopping discount.