Small Cap Value Report (Mon 22 April 2024) - TYMN, PAY, MTEC, REVB, AFRN, CER, CLIG

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news) -
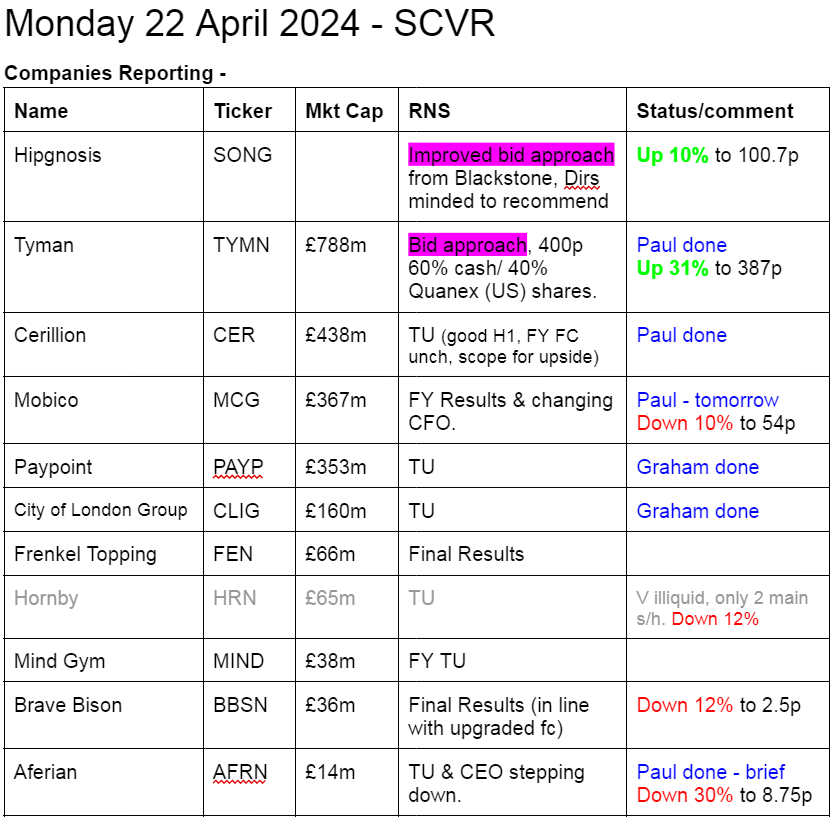
Made Tech (LON:MTEC) - up 32% to 12.25p (£18m) - £19.5m Contract Win - Paul - AMBER
This is another disastrous 2021 float, an IT services group that focuses on the public sector. Even after today’s bounce it’s still c.90% down on the IPO price.
I reviewed its last update on 1/2/2024 which sounded negative about the outlook due to slow order intake. Good to hear today that a large order has been won with the oddly worded Dept for Levelling Up, Housing & Communities (DLUHC). It mentions creating a database & portal of private rental housing.
Paul’s opinion - I had to flag the poor performance last time, with amber/red, although the decent balance sheet gives confidence. H1 results weren’t bad, although note that capitalising costs means cashflow is still negative. If you wanted to have a punt on this share, I wouldn’t try to talk you out of it, due to the solid balance sheet with plenty of cash, and today’s news of a big contract win. So I’ll shift up from amber/red, to AMBER. There could be a recovery trade for a bounce here, possibly? Although I'm still unconvinced about the quality of the business. Contracts like this are competitive tenders usually, and if things go wrong, they don't necessarily make a profit on them.
Revolution Beauty (LON:REVB) - down 8% to 28p (£91m) - Possible legal claim from Chysalis - Paul - RED
Investor Chrysalis issues this attack today -
“...has not been satisfied with the limited responses received from Revolution Beauty and its legal advisers to date, and accordingly the Company issued draft Particulars of Claim to Revolution Beauty on 19 April 2024. The draft Particulars of Claim note a claim of £39m, together with a claim for consequential losses of a further £6.2m. The Company considers that it has a strong case and is willing to pursue it….”
There have been lots of ongoing problems with this company, with both Graham & I being wary. We think it could need an equity fundraise. Auditors suddenly resigned recently. The trading turnaround is not yet convincing either. With this potential legal action further muddying the waters, I’m happy to keep well clear, so for now it’s RED to flag the higher risk. We don’t know what will happen in future, as with everything, so it’s not a prediction.
Aferian (LON:AFRN) - down 30% to 8.75p (£10m) - Trading Update (profit warning) - Paul - BLACK (RED on fundamentals)
CEO stepping down in Oct 2024, after 14 years.
Results for FY 11/2023 are now expected towards lower end of previous range EBITDA $1.6m to $2.6m.
Net debt is a problem - it was $6.1m at Nov 2023 year end, but has since risen to $12.3m at 31/3/2024, reflecting seasonal movements it says. This includes $1.4m owed to major shareholder Kestrel.
Outlook - further deterioration in the core business, so more cost cutting is being done. Now doesn’t see any improvement in trading in FY 11/2024 vs LY. In discussions with bank over renewal of borrowing facilities, set to expire Nov 2024.
Paul's opinion - looks a can of worms, so I’m keeping well clear. Will shareholders be prepared to stump up more cash in an obviously needed future equity raise? De-listing risk also seems high, with 3 dominant shareholders owning over 50%, who might want to take it private to give less prominence to one of their mistakes, and save further costs? RED I’m afraid, but good luck to everyone involved.
Summaries of main sections
Tyman (LON:TYMN) - up 31% to 387p (£761m) - Recommended Cash & Shares Offer - Paul - PINK (takeover)
Recommended takeover deal from US building supplies group Quanex, which is not a lot larger than Tyman, so this proposal looks as if it will stretch Quanex's finances, and includes it taking on a $750m term loan. Many investors may not want a mix of cash & Quanex shares. Only c.17% support so far, from one institution - Teleios (persistent seller at CARD). I wonder if this deal will be voted through, it doesn't look particularly generous given how cheap TYMN shares are. Hopefully a higher, more credible bidder might emerge? Deals need to be in cash, not a mix of cash & unwanted shares.
PayPoint (LON:PAY) - up 3% to 499.5p (£353m) - Post-close trading update - Graham - GREEN
An “in line” update from Paypoint, which made it onto my best ideas list for 2024. The extra bit of news today is that directors are actively considering a buyback, given their ongoing confidence and PAY’s excellent free cash flow generation. I think the company should be able to comfortably afford this.
Cerillion (LON:CER) - down 4% to 1,435p (£423m) - Trading Update [in line] - Paul - GREEN
Good H1 performance, and FY 9/2024 forecasts are reiterated, and could be beaten I suspect. Plenty of cash. This is such an impressive UK growth company, which seems to be in a positive cycle of winning larger contracts. Not without risk, but I remain a big fan.
City of London Investment (LON:CLIG) - up 4% to 330.5p (£168m) - Trading Update - Graham - AMBER/GREEN
A good Q3 update from this fund manager as it sees strongly positive net inflows. I was previously AMBER here but I agree with Paul that divi yield is attractive. There is no denying that CLIG’s track record when it comes to flows is not bad, even if I struggle to understand the appeal of their strategies.
Paul’s Section:
Tyman (LON:TYMN)
Up 31% to 387p (£761m) - Recommended Cash & Shares Offer - Paul - PINK (takeover)
Tyman supplies building products related to doors and windows.
Directors have agreed a takeover from a US building products group called Quanex Building Products (NYQ:NX)
Price: 240p cash, plus 0.05715 new Quanex shares (worth 160p at Friday’s close - this could change of course, depending on what happens to Quanex’s share price in New York) - so 400p in total.
Dividend of 9.5p in the system will still be paid.
Premium: 35% to Friday’s close.
Reason: increased scale, cost synergies, diversification.
Funding: Quanex isn’t much bigger than Tyman, and is taking out a $750m loan to fund a lot of this deal, together with newly issued paper. This will leave the combined group geared up at 2.1x leverage.
Support from shareholders: the only significant holder mentioned is Teleios (who have been selling continuously in other UK companies, especially Card Factory (LON:CARD) ). Therefore this deal looks to be a mechanism to allow marooned institutions to exit, as we’ve seen with other takeover deals of late.
Paul’s opinion - it’s annoying to see decent UK companies being sold off to the US, mainly to provide a liquidity event for institutional holders. The head of research at Peel Hunt was saying on a podcast with Merryn Somerset-Webb last week that the UK market is 25% undervalued compared with international peers, hence why companies here keep receiving takeover bids. Each cash deal injects liquidity, and the bargains on offer are attracting buyers, hence there’s plenty of money to be made from UK shares. I agree, its a highly attractive market as we’re being offered pound notes for 75p. Then we just have to wait, and Americans offer us £1 to buy them. It’s an absolute gift, why aren’t more investors excited about the opportunities we have on a plate in front of us?! I don’t recall ever seeing such attractive value opportunities in UK shares.
I’m concerned this deal from Quanex doesn’t look too great. 240p cash is nice, but then TYMN investors are lumbered with shares in a US company they don’t really want to own. So that’s bound to cause downward pressure on Quanex’s share price, hence the eventual value of this deal might be well below 400p.
With only 16.7% support so far, almost all from one institution, Teleios, this deal may not be voted through by shareholders, so I wouldnt be surprised to see this deal fail. Hence selling some in the market on the initial spike up today, could be a good strategy maybe? Tyman shares look good value, and pay nice divis, so I’d be tempted to reject the bid, as you should get a 30% uplift in a few months when the economy begins recovering. So not a good deal, in my view.
Cerillion (LON:CER)
Down 4% to 1,435p (£423m) - Trading Update [in line] - Paul - GREEN
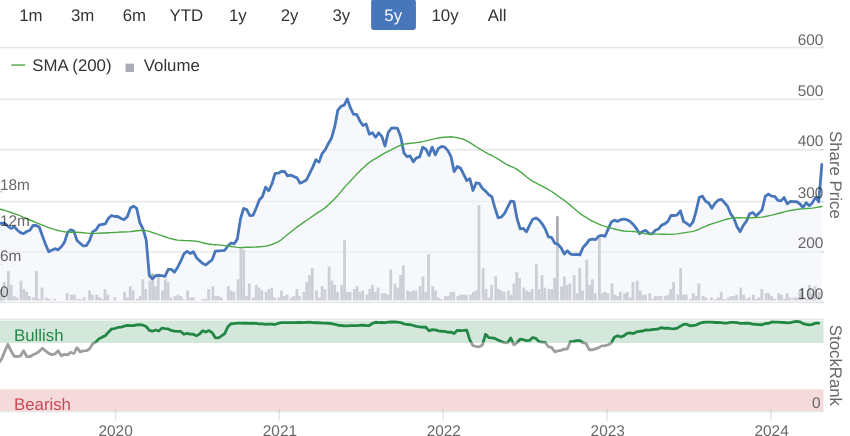
One of the growth stars of the UK market, this niche software company (mainly billing software for telcos) has 10-bagged in the last 5 years.
As it’s concise, here’s the main section in full -
Results for the six-months ended 31 March 2024 are expected to set new highs for revenue and adjusted EBITDA. Revenue is expected to be approximately £22.5m (H1 2023: £20.5m) and adjusted EBITDA approximately £10.9m (H1 2023: £9.9m), both 10% higher year-on-year.
Net cash at 31 March 2024 has increased to approximately £26.6m (31 March 2023: £23.6m), providing a very firm underpinning to the Company's strong balance sheet.
The first half performance reflects ongoing strong demand from customers and the trading backdrop remains favourable. Telco digital transformation, the transition to Software-as-a-Service solutions and investment in enterprise software to achieve revenue and efficiency gains remain key features of the market, and consequently the Company's sales pipeline is strong. It includes a number of substantial potential new contracts, which are at various stages of the negotiation process. The Board believes that the Company remains well-placed to meet market expectations for the current financial year and beyond.
Paul’s opinion - I’ve been raving about this company for a while, and the last 3 reviews here have been GREEN. As we always say, it’s expensive, but it just keeps on delivering. Contract wins seem to be moving up the size scale, with each new bigger customer acting as a reference site for more bigger deals in the pipeline. Patience is being rewarded here. I can see a very strong argument for paying up the hefty valuation, and just treating it as a “coffee can” long-term hold type of share.
The main downside risk is that despite SaaS revenues growing, profit is still highly dependent on large up-front licensing wins. So there is a risk that at some point there could be a gap in the contract wins, triggering a spike down (which I would be inclined to consider as a buying opportunity, were this to happen, which it might not of course).
With the strong, cash-rich balance sheet, and down-to-earth owner manager in charge, this remains one of my favourite UK growth companies.
Liberum leaves forecasts unchanged, but hints there might be upside for FY 9/2024, depending on timing of converting pipeline into contracts.
Graham’s Section:
PayPoint (LON:PAY)
Up 3% to 499.5p (£353m) - Post-close trading update - Graham - GREEN
This is a short update for FY March 2024, I can paste almost the entire thing here (emphasis added):
The Group anticipates that underlying EBITDA will be in excess of £80m for FY24, year end net debt below £70m and underlying PBT in line with expectations, as outlined in our Q3 trading update issued on 24 January 2024.
In FY March 2023, PayPoint achieved underlying EBITDA of £61.3m. So the year-on-year growth on that figure will be at least 30%.
The acquisition of Appreciate completed in February 2023, and I expect that it made a meaningful contribution, so it’s important to bear in mind that this 30% growth rate is not organic. Many spectators view Paypoint as being inherently ex-growth!
The update continues:
The strength of this performance, underpinned by sustained strong cash flow and our confidence in the delivery of continued growth and achieving our financial targets, has enabled the Board to now have under active consideration a share buyback programme to further enhance shareholder returns. Details of this will accompany the announcement of PayPoint Plc’s preliminary results for the financial year ended 31 March 2024 on 13 June 2024.
Graham’s view
The Board may feel obliged to disclose this news (that a buyback is being actively considered), but I do prefer it when companies simply announce and start doing their buybacks at the same time, giving the market less time to react!.
After all, one of the attractions of a buyback is that the company has the opportunity to buy its own undervalued shares. So I wouldn’t necessarily want a share price to rise all the way to fair value, before that happens.
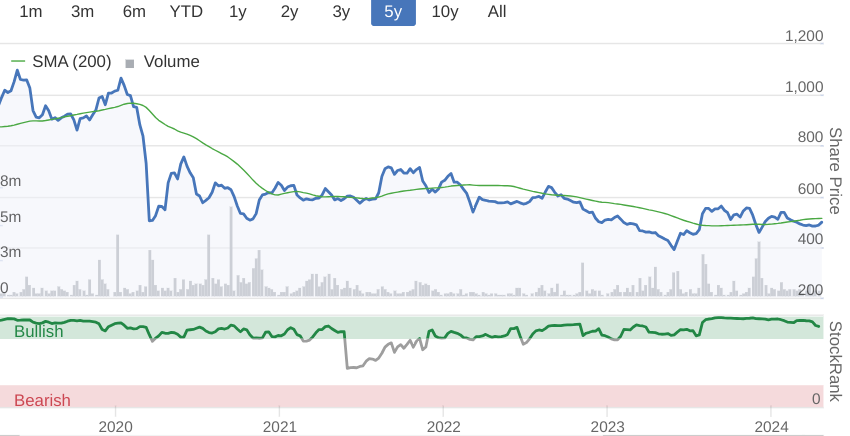
So far this morning at least, the Paypoint share price is up by only 3%. So if you’re a believer in this company, it probably still has some way to go, to get to fair value.
Here are the value metrics as of last night:
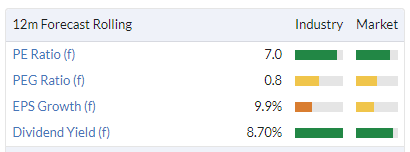
With excellent cash generation, a buyback should be affordable.
As of September 2023 (see SCVR commentary), the company reported having net debt of £83m. Estimates from Liberum suggest that the company will achieve after-tax adjusted net income of £48m for FY March 2024, rising to £52.6m for FY March 2025.
Most earnings are paid out in the form of a generous dividend yield (c. £25m p.a.), but the remaining profits could still pay for a helpful buyback that would boost EPS for shareholders going forward.
City of London Investment (LON:CLIG)
Up 4% to 330.5p (£168m) - Trading Update - Graham - AMBER/GREEN
A positive headline from this fund manager for its Q3 update (to March 2024):
City of London (LSE: CLIG), a leading specialist asset management group offering a range of institutional and retail products investing primarily in closed-end funds, announces that as at 31 March 2024, FuM were $10.1 billion. This compares with $9.6 billion as at 31 December 2023, an increase of 5.5%.
Thankfully the gain in FuM is not just the result of market movements: we also have positive net flows.
The positive flows are largely thanks to the “International Equity” strategies:
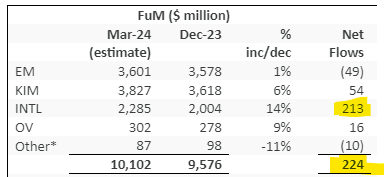
For context, in H1 (six months to December 2023) the company saw net outflows of $294m.
In the previous financial year (FY June 2023), net outflows were $357m.
Performance prior to that was up and down, with some positive years and some negative years.
So I think that net inflows of $224m in the latest Q3 period should be seen as significant - a much improved performance on the most recent prior periods.
Performance: “mixed”. As specialists in investment trusts, they continue to see bargains as trusts generally trade at wide discounts to NAV:
The investment teams continue to find value in the closed-end fund (CEF) universe as discounts remain historically wide across a number of asset classes.
Cost savings: the previously announced $2.5m of annual cost savings “will be fully realised in the next financial year”, i.e. FY June 2025.
Estimates: Robin Savage at Zeus Capital has prepared estimates including adj. PBT of $27.7m for FY June 2024, and adj. PBT of $29m for FY June 2025.
Graham’s view: I was neutral on this when I first looked at it in January. Paul followed up with a somewhat more positive outlook in February.
I remain unsure about the investment case here, perhaps because I’m unsure about the appeal of CLIG’s strategies.
I can understand why investors choose passives, and I can understand why investors choose active funds with a particular niche and a good track record.
But in an environment of fee compression, and as investors increasingly try to remove as many layers of fees as possible, I struggle to understand the appeal of investing in baskets of closed-end funds. I’m sure that this approach offers terrific diversification, but surely it must be expensive, when you consider all of the fees involved? CLIG itself charges about 0.7%.
Their developed markets strategy has delivered a return of 6.79% annually and net of fees over the past 10 years.
This has beaten MSCI’s All Country World Index (excluding the US) over that timeframe, but it says something that they exclude the World’s largest and best-performing stock market from their benchmark.
Their emerging markets strategy has achieved 3.59% annually over this time frame, also beating its benchmark, but this strikes me as a rather low return on an absolute basis given the long 10-year timeframe.
To be absolutely clear, I do not doubt CLIG’s expertise. I simply struggle to understand the appeal of these strategies, given the fees involved and the difficulty of earning a high return. It strikes me as a low-ish risk, low-ish reward type of deal, with more complexity than alternative strategies that could earn a similar return.
On the positive side, I will acknowledge that from the perspective of a CLIG shareholder, the track record in terms of flows hasn’t been too bad, considering the performance of other fund management groups in recent years. And this Q3 result is definitely something to be excited about.
I can’t quite bring myself to give this one the thumbs up. However, since Paul called it “AMBER/GREEN” last time, since I agree that the shares are cheap, and since today’s update was a positive one, I will also go with AMBER/GREEN.
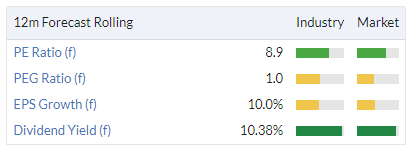
It has been getting consistently cheaper for the past 10 years. With a yield of over 10%, maybe it has reached the bottom?

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

98 comments
Bicycle Market Armageddon
Continues
Kona bikes just gone out of business .
Bought few years then loaded with debt and ordering too much and pop goes the weasel .
Nice historic brand Kona worth “nicking” and tucking away but there is always huge complications in buying a brand like this as the Taiwanese / Chinese vendors just say to the new owner “you must pay me “
Having said that all these companies disappearing is starting to leave an opening for anyone wanting to build a portfolio .
Hopefully Mike Ashley doesn’t buy kona but it’s got to be a possibility .
Kona footnote
Possibly not a bankruptcy more a sale (2 years after buying !)
I saw Pole have also called in the administrators at the end of last week. Can't see that being the end of it either - I was in two big e-bike shops at the weekend and not a single customer buying........but hardly surprising when they are asking £7k for a low spec e-MTB and £12k+ for the top spec. Madness.
A very large end of day trade recorded against Celebrus Technologies (LON:CLBS) today - realise these don't have to mean very much at all but worth noting perhaps
Celebrus Technologies (LON:CLBS) Thanks for highlighting this Plinkut. I believe this is over 3% of the company. Will watch for an RNS
Hi Peter T - looks like the RNS might have come out today, Canaccord reducing and Close Asset Mgmt starting a new position. I listened to the Celebrus Technologies (LON:CLBS) Nov '23 Capital Markets Day - terrible sound but some interesting stuff there. I was aware of D4T4 a while back via a tech related newsletter but never took the time to look into it in detail, definitely one to keep an eye on I think.
On 8 Aug 2023 Graham looked at SDI (LON:SDI) when it was trading at 122p and wrote
"I’m not ready to go green on SDI yet but I think it’s starting to look interesting at a sub-£130m market cap. I think I’d be very interested at a £100m market cap. For now I’m neutral. Any improvement to the organic growth figure would be highly encouraging."
On reviewing SDI on 7 Dec 2023 Graham noted his concern about the lack of organic growth, and downgraded his previous 'good value' territory from below £1 down to sub-80p.
In recent months BGF Investment Management Limited (private equity) have substantially increased their holding in SDI to 13.81%
I'm hoping today's price of 56.1p represents a good entry point as I have taken an initial position.
That’s an interesting comment on SDI (LON:SDI) I see that directors are beginning to put their toes back in the water, though on nothing like the scale of their previous sales.
SDI (LON:SDI) Are they? I can only see one small buy this year, unless Stockopedia has missed some?
lt does look tempting at this level, having sold some Judges Scientific (LON:JDG) l might buy some.
Journeo (LON:JNEO)
There have been several comments on Journeo's Reach announcement this morning. The contract is not financially significant (otherwise it would have been an RNS) so why publish it? I would suggest that it is not about the contract itself but that this is showing that the promised bringing together of Journeo's long- standing Stockholm engineer team with recent acquisition MultiQ has brought forth its first result. See the first sentence of the CEO's comment in today's Reach https://www.investegate.co.uk/... and listen to the answer to question 8 in the recent presentation: https://www.investormeetcompan...
Cerillion (LON:CER) good company but oh the valuation, Stockopedia has VR of only 3. I hold but sold most of mine. Always look expensive, well they have gone up 50% in about 6 months, so looks even mor expensive now, growth does not look great for such a high valued stock, PEG is 3.2, compared to some vastly over valued US technology stocks who have PEG under 1.
I noticed this the other day: "TBILISI, April 16 (Reuters) - Riot police in Georgia waded into demonstrators and cleared them from around part of the ex-Soviet state's parliament on Tuesday as lawmakers debated a bill on "foreign agents" that the opposition denounces as authoritarian. The bill would require organisations receiving more than 20% of their funding from abroad to register as being agents of foreign influence. It is likely to pass in a parliament controlled by the ruling Georgian Dream party and its allies." Is this likely to affect Bank of Georgia (LON:BGEO) ?
The President has said she will exercise her right of veto, so my understanding is that it doesn’t matter whether it passes parliament. That’s irrelevant and so this is really pre election positioning.
As I posted the other day - this type of bill is seen as potentially anti democratic by the EU. Ie it was used in Russia to oppress dissenters. That doesn’t mean the same would be true here and those proposing the bill say it wouldn’t (but then they would wouldn’t they!!)
If this were to pass it would make EU membership very unlikely imo for Georgia and is one reason why there are demonstrations against it. This is not new - its been dragging on for a couple of years.
But my view is that doesn’t really impact Bank of Georgia (LON:BGEO) unless it stalls GDP or alienates Georgia significantly. That is also now somewhat mitigated by the regional diversification they have gone through.
davidjhill, I have read that the current government has such a majority in parliament that the presidents veto would be null and void. The political party in power is very close to Moscow and any further demonstrations could be used as excuse to ask for intervention from Moscow, remember Russian troops already occupy 20% of the country as a peace keeping force! It would be much harder for the EU or NATO to assist in any interference from Moscow. Further more the Georgian economy is booming because it is being used to break EU sanctions on Russia. Noy a great situation if you want to join the EU.
Any one holding shares in companies in Georgia might wake up one day and find that their company has been confiscated. Why take the risk
Aa - edit: fat fingers
That is closer to the mark I fear.
I work closely with Ukrainians in Poland, UK and Ukraine. They all think things will kick off in Georgia which is why I have always been a bit wary of Bank of Georgia. Such a shame as it is such a beautiful country and most young people looks longingly to the West. They have some of the most wonderful vineyards and orchards I have ever seen and a lovely warm climate and fascinating history.
The place is full of exiled young Russians who are not universally welcome, many of whom support Putin's war in Ukraine ... they are just not willing to die on the front line for Putin's colonial wet dream. I have a dear friend who teaches at the University of Georgia in Tblisi. She tells me there are tensions in the University and there are many places in Tblisi which refuse to take trade from Russians. She also tells me rental prices are through the roof because of the huge influx of exiled brave Russians seeking to avoid the war but who still support it.
Of course this all means business for Bank of Georgia (LON:BGEO) has gone through the roof and the bank is cheap, with very low levels of bad debt and fantastic credit spreads. The country is at a good place in the debt cycle, but I cannot escape my friend's feeling that they have welcomed a 5th column into the country.
Where does this end up? I have no idea and neither does my friend.
Journeo (LON:JNEO) wondered why this rose earlier and then I spotted the Swedish announcement on reach. Looks like business case continues to play out so these contract wins are good to see. Enormous opportunity in US and Europe so continued expansion across nordics and then into Europe should provide a long motorway of potential growth. So far so good then…….
Don't these countries already have something similar?
Journeo (LON:JNEO)
Happy to see a new order come in but should we be celebrating a win worth considerably less than 1% of annual turnover? The messaging feels needy at best and some might say desperate. I do hold for similar reasons to you but announcing such a paltry win erodes my confidence instead of boosting it.
BnB - this was put out as an RNS Reach - ie non price sensitive news
So they are flagging wins in a new location but highlighting it isn’t RNS - surely that’s a good thing, keeping investors up to speed with development in the business but not pretending they are all price sensitive.
I’d say it increases my confidence rather than erodes it.
Again in strong agreement David. It is a win from the latest ,and relatively small acquisition, MultiQ bought at 2.5M euros with revenue for the year to 31 Dec 23 estimated at 3.3M euros. In the context of those numbers the win announced today is significant. Personally I would like to be notified of any win with a contract value in excess of £1M. £300k per annum over 6 years will produce circa £2M. A good deal - and I am delighted to learn of it.
The size of the contract is irrelevant and not really the news. The successful integration of engineering talent is the news. I hold.
The size of the contract is irrelevant and not really the news. The successful integration of engineering talent is the news. I hold.
A less charitable, but defensible interpretation would be that the “win” is no more than a contract renewal for work that the “new” client, who turns out to be the company Journeo bought MultiQ from, has been performing for years with its end user customer, and for which they still need the MultiQ skillset. It’s clearly not bad news and could lead to greater things. I’m a holder and hope that’s the case. But it reads to me as though this collaboration was baked into the acquisition agreed last September.
Journeo (LON:JNEO)
Agree David, significant runway for growth provided management get the execution right. Not sure where Downing Strategic Micro-Cap Investment Trust (LON:DSM) are with their holding as of 31 March it wasn’t one their top 5.
Tyman (LON:TYMN) I hold - bit disappointed with outcome really. Another quality company getting taken across the pond. Reasonable profit for me but not exactly generous. I guess they want as many people to take shares in the enlarged company but think for the equity risk the bid should have been priced higher.
Can’t see a competing bidder but I suppose you never know
I hold Card Factory (LON:CARD) which has risen by 10% in the past few days. The results are due shortly. Has there been a tip somewhere?
I suspect it is the usual buy ahead of results….seems like a normal pattern of trading with Card Factory (LON:CARD)
I think on Friday someone mentioned there was a good write up about Card Factory in Shares Magazine.
We're getting quite a few people announcing their trades here. Please could people refrain from doing this, because nobody cares, and it clutters up the comments here! By all means tell us about why you've bought or sold, with your reasoning. But a one-liner just saying that you've bought/sold with no other details, is totally pointless.
Thanks, Paul.
Thanks for the write-up on Made Tech (LON:MTEC) Paul. Enterprise value only £6m against a mkt cap of £14m (as of Friday). Management own 43% of the equity. Could there be an MBO here at this bombed out valuation?
Would be good to get a comment on Elixirr International (LON:ELIX) FY23 results a pleasure to read & show true resilience despite all the doom & gloom in the consulting industry:
• Rev +20% to £85.9m (underlying organic +15%)
• Adj EBITDA +24% to £25.4m
• PBT +40% to £22.1m
• Adj dil EPS +22% to 37.2p
• Net cash of £18.1m
• Final divi +37% to 14.8p
This all for a PE for FY24 of ~13.5 ex cash.
Outlook: First 3 months strongest ever. On track to meet decent looking FCs.
Recap: Revenue has been growing at a CAGR of 37% from 2019 to 2023 (industry 8.4%). Extremely selective with M&A & this is shown in their high margins & organic growth. Elixirr offers over twice the pace of growth for half the valuation of peers.
I hold.
Last time I looked at Elixirr International (LON:ELIX) , they had some really scathing reviews on Glass Door. You can never tell if it's just disaffected employees letting off steam but it gave me pause for thought.
I would welcome some comments on Mobico (LON:MCG) results. Looks like there is a lot to be unhappy about with high debts, write offs and poorly performing parts of the business. However the free cash flow was about half the current market cap and if the school bus business gets sold for a reasonable sum the investment case might start to look compelling?
Mobico
I followed the market verdict today and sold out with 50% loss.
PayPoint (LON:PAY) - its due to £135m of client cash. Corporate cash is £22m. Debt is £94m using year end numbers.
Remember that they hold lots of customer cash, the other side of which is a liability. Hope this helps.
Tyman (LON:TYMN) - yes Paul, disappointing that this is being bid for by another US company and doesn't look a very attractive a deal. It was on my watch list as its a very good company. Anyway, I did hold some shares many years ago - readers may remember that Greg Hutchings (Tomkins dealmaker) originally set this company up as Lupus Capital and did the first few deals before being ejected from the pilot seat!
I have held Tyman (LON:TYMN) for 3 years, I sold this morning at 382p, it is 30% higher than before, been looking to sell for some time. So for me the deal fine. Don't like the deal anyway.
There is a Mello Trusts and Funds show tomorrow at 1pm if any of you would like to watch and ask questions. It is completely free to join just register on the webpage Mello Investment Trusts & Funds, Tuesday 23rd April 2024 – Mello Events
Here is the programme
1:00pm Emma Bird, Head of Investment Trust Research, Winterflood Securities
1:30pm Company presentation by JPMorgan Asia Growth & Income plc
2:00pm Company presentation by Literacy Capital
2:30pm Company presentation by International Biotechnology Trust
3:00pm Investment Trusts and Funds Panel
On PayPoint (LON:PAY) my initial reaction to the share buyback news was why isn't the company paying down debt instead?
But then I remembered that the market is demanding a hefty 8%+ dividend yield from the equity, so definitely worth reducing that capital base instead of debt, at that tye of "cost"!
(I hold in the Boon Fund)What debt? On Stockopedia there is no debt on PayPoint (LON:PAY)
They literally mention it in the RNS today...
"year end net debt below £70m"
PayPoint (LON:PAY)
Confused by this one. If their year end net debt is ca. £70mil, then not sure what happened to all that cash. Any clarification would be greatly appreciated.
I think you're making an assumption here that Stocko numbers are always accurate...
Final reports for FY Mar22, FY Mar23 all show net debt. Same with HY Sep23 report.
I do rely on Stocko's numbers being correct. It's concerning if they are not..
This comment will surely catch Paul's eye;-(
So why are Stockopedia figures so different, did an acquisition go through in last 6 months? Presume Stockopedia figures are from the November update?
I think in PayPoint (LON:PAY) case it has to do with messy treatment of their ringfenced customer cash, from their payments processing side of the business, as well as Love2shop vouchers side of the business.
Probably the way Stocko gets the financial numbers includes those.
The net debt position has been present for several years.
PayPoint (LON:PAY) Boon, thanks, I see, something to be aware of. I will have to check Pauls reviews, see what they reveal.
Not much, Graham is a fan, Mark Simpson, did strip out the customers payments, which did leave a debt of around £70m. He was also quite keen on it. It is quite difficult if you go by Stockopedia figures, l'm sure they affect the rankings as well.
I’m also confused why/how the Stockopedia debt figure for PayPoint (LON:PAY) is £-113. Doesn’t that indicate a large surplus not debt?
Regarding the PayPoint (LON:PAY) 113 I believe is from the B/Sheet in theSeptember interims and it looks like this:
Another positive data point for the UK homebuilding, estate agency and building products industry.
According to Rightmove, the average asking price of UK properties coming to the market rose to £372,324 in the 4 weeks to mid-April - up 1% on March.
I’m with Paul Hill on the positive UK homebuilding outlook. Despite the expectation that lower interest rates will not be delivered by the BOE as soon as originally thought, there is definitively more activity on the large development close to where I live. Sold boards are definitely increasing on the development after a pretty sluggish autumn and winter. Whether that is replicated nationwide of course I cannot comment.
The housing market always used to pick up in the spring.
Lots of housing developments in my area have been delayed.
In a debate on Saga (LON:SAGA) on Friday a subscriber BenHazz in response to my post said "I think the joke here was the phrase used was podcast which is Audio only"
This comment set me thinking. Many of us listen to Paul Scotts podcasts but how do you define a Podcast? According to the Economist Podcasts got their name in 2004 thanks to a British Journalist Ben Hammersley who mixed "IPod" and "Broadcasting" and came up with Podcast.
Podcasts are primarily an Audio Medium but some Podcasts also distribute Video either as their primary content or as a supplement to Audio. Certainly the Investor Meet Presentation on Saga (LON:SAGA) was a combination of Audio and Video so I suggest BenHazz was not correct in saying a Podcast is Audio only.
Except when a podcast becomes vodcast...
You learn something new every day, happy to be corrected on my definition of a podcast Portugull. I do still maintain that grumpy5's comment about being unable to read body language in a podcast was meant as a joke around them being *typically* audio only - hence the wink. Maybe he can enlighten us!
Brave Bison (LON:BBSN) (I hold) - results appear to be solid, as Paul mentions in the summary, they were inline with forecasts that were recently upgraded. There's £6.8m net cash and the 2024 outlook contains the word we like: ahead. The adjustments seem reasonable.
The Green Bros are Mello regulars and IMO are a credible team. It's just nice to find a business operating in this sphere that appears to be delivering with some emerging consistency.
And particularly as the market has marked the shares down by a fair bit (11% as I write), I'll stick my neck out here and say I think these could well be cheap and a good entry point for those interested.
A new note from Cavendish sees Brave Bison (LON:BBSN) valuation as "compelling" and notes the "high quality revenue" and 24% CAGR since 2021.
As always I'm open to the bear case if there are more sceptical readers.
IMC webinar at 10 today.
I added this morning
Elixirr International (LON:ELIX) has delivered some very strong y/e numbers. Hopefully worth looking at, as lots of cash on the balance too.
Reported normalised eps 37.2p vs consensus of 32p.
Outlook statement positive -
- FY 23 momentum has continued into FY 24, with three record revenue months in Q1 2024 and a strong pipeline for the remainder of FY 24
· Momentum is expected to continue throughout the remainder of the year, with FY 24 revenue expected to be in the range of £104-110 million
Not expensive but presumably the woes in the consulting industry in the UK are holding this back.
Eenergy (LON:EAAS) has news today, "SIGNED AN ESTIMATED £5.2 MILLION CONTRACT WITH SPIRE
HEALTHCARE
GROUP TO PROVIDE A PV SYSTEM ACROSS 38 SITES"
This seems to be building into a nice company and looks to me like it could be undervalued.
The number of companies delisting from London’s junior stock market has risen sharply in the last year, adding to concerns about the future of the City’s financial sector.
In the past 12 months the number of companies on the Alternative Investment Market (Aim) has fallen by 70 to 738 at the end of March, according to London Stock Exchange Group data. That is a drop of 9%, and is significantly more than the drop of 25 companies the year before.
Sharp rise in Aim delistings casts doubt over City of London’s future | Financial sector | The Guardian
I wonder though how many of the 70 companies shouldn't have been listed in the first place and/or were just rubbish and is the market better off without them?
All of them and the market will be in a better place without them. Perhaps some more should and hopefully will be delisted as soon as possible.
Leaving fewer/better companies to divide up the available investing pot. Certainly could be viewed as a positive. Pruning the dead wood.
How many of those have gone out of business?
Listing is expensive for small companies.
Trading on the AIM has been difficult recently with lack of liquidity and low volumes.
Frequently l can't get a quote to buy or sell shares.
There's a ridiculous number of coys with a Mkt Cap of less than £5m. !
The problem is it is not just the deadwood that is thinking of leaving the UK market.
Shell (LON:SHEL) and Ocado (LON:OCDO) also thinking of decanting for the US. I think Marks and Spencer (LON:MKS) will have an opportunity to pick up the rest of the JV on the cheap as Ocado seeks to convince NASDAQ they are a tech play and not a grocery delivery business.
What's the betting that OCDO will work an AI angle into it by any means necessary?
100% ...LOL
I wonder how much of Shells announcement is linked to the lack of visibility regarding govt support for future investment / tax structures in the UK. It's a pretty big lever that they have - I think 8-9% weighting in the FTSE100.
edit: also their new CEO may have closer links to the US than the UK.. just another point to be added to the scales
Shell (LON:SHEL) might be seeking to leverage a position with the government on the future of current tax structures for the North Sea. However, Shell's production exposure to UK water is pretty minimal in the context of their global portfolio. The reason is simply they are worth half the value of the US majors such as ConocoPhillips (NYQ:COP) , Exxon Mobil (NYQ:XOM) , Chevron (NYQ:CVX) despite having similar 2P reserves. The Board wishes to close the valuation gap.
I hold Shell (LON:SHEL) and am adding as there is good chance they will seek at least a dual listing in the US and the passive buying by ETFs alone will give a boost to the share price.
I agree with your point regarding ETFs. I have been thinking of how much of a positive feedback loop they create in pushing capital towards where it is already concentrated. I wonder whether the logical conclusion of your thesis is that most multinationals would have an interest in having some sort of presence in the US market.
30% of all stock buying on US markets in 2023 was by ETFs. There are also some significant value hedge funds that would be interested in an oil major with a global footprint at half the price of existing listed US majors. Once the trend starts the CTAs will pile in reinforcing the action. If they dual list, there may also be some interesting arb opportunities for the fleet of foot.
Shell (LON:SHEL) already is dual listed Shell (NYQ:SHEL)
They must be talking of a complete decamp from LSE then. That would be a shame.
There is talk about moving it's primary listing from London to New York. That was about 2 weeks ago.
TradingView has them listed NYSE ticket SHEL.
The paradoxical nature of Britain's financial landscape presents a problem that is hard to overlook. On one hand, Britain stands as a global powerhouse, ranked as the fourth largest exporter in the world, outpacing other economic giants like France and Japan. This is a testament to the country's robust industrial and commercial capabilities, reflecting a strong, outward-facing economy with a global footprint. Moreover, London's preeminence as the world's largest exporter of financial services is undisputed, further solidifying the UK's stature on the international stage. Damn, Brexit!!
Bridging the Gap Between Global Finance and Local Growth in the UK's Market Landscape
Journeo (LON:JNEO) First contract in Sweden through its Multiq subsidiary. Anticipated revenue of £300,000 per annum over six years. Contract to deliver passenger content for 1000 buses each having three vehicle displays. Sounds promising as a stepping stone in the development of its European business.
PayPoint (LON:PAY) Trading in line with net debt anticipated to be below £70m. Strong cash flow and a confident outlook. As a result the Board is actively considering a share buy back. Details to be announced with the prelims in June.
I hold both.
Ditto Jonno re holdings.
For Journeo (LON:JNEO) the main reason to buy recently was that they were just in the process of getting European certification for their systems, which if they do get it provides a catalyst for sales in that huge multi company and multi country market
I hold Journeo (LON:JNEO) despite my reservations about their ability to convert sales to free cashflow in a consistent manner. However, the forward visibility of earning is increasing....6 years is a good result.
Journeo (LON:JNEO) Journeo has shown significant financial improvements in recent years. Revenue growth has been impressive, with a CAGR of 29.6%. Operating and net profits have shifted from losses in 2019 to strong gains by 2023. Improvements in cash and working capital management indicate enhanced financial stability. Overall, Journeo seems to be moving in a positive direction, with positive trends in EPS and ROCE.
A modest City of London Investment (LON:CLIG) update today. I have a smaller holding than I used to; the outlook seemed a bit dimmer than before, but I find these results good enough to encourage me to hold. A small increase in potential income plus a small cost reduction (with others in place). So a gentle Hold for me.
What's encouraging about the update is there are now net client inflows. This is a good turnaround given there were -$294m net client flows at the half year point so the last quarter has been good - echoing Polar Capital Holdings (LON:POLR)'s update.
Feels like fund managers are now at a turning point hopefully.
The somewhat unreliable Jupiter Fund Management (LON:JUP) are also updating this week.
Polar Capital Holdings (LON:POLR) Perhaps Megan would kindly help again on this one - 'eligible' for IHT AIM ?? Thankyou KBR.
Cerillion (LON:CER) A reasonable trading update from Cerillion (LON:CER) . Revenue and adjusted EBITDA both up about 10% and a strong cash position of 26.6 million. I was a bit concerned that the slowdown in Telecom spend that came through in the likes of Calnex and Spirent would show through here, but so far that does not seem to be the case. The outlook is positive with a number of contracts in various stages of negotiation. They do not put out much detail in their updates, but always seem to deliver. As they complete more and more implementations the recurring revenue will build and build. The software that they supply is basically at the core of operations for these telecoms companies, so it is highly unlikely to be replaced unless there is some major problem. Although it may seem expensive on a pure PE basis, extrapolating this level of growth forward, with a slightly increasing margin makes it look reasonable.
Morning Stocko team! Is there time to look at Brave Bison (LON:BBSN) today? The results look good, but some aspects (fall in statutory profit) look dubious. Cheers, Jim
Morning Nothingventured,
Brave Bison (LON:BBSN) - we'll try to look at it, but need to get the larger stuff out of the way first. I remember being mildly positive on BBSN in the past, from memory.
Regards, Paul.
acquisition & restructuring, of SocialChain in H1 FY23 is exceptional cost BBSN
Hi Paul,
Ref Brave Bison (LON:BBSN)
Can you or a member of Stock explain the discrepancy, please?
I believe you plan to have a close look at the Company. This may provide a head start. I plan to update myself. I am happy to provide you with a final copy if it interests you.
Analysing the fiscal year FY23 financial highlights in relation to the projected fiscal year FY24 goals and evaluating the company as a going concern yields several insights requested by the old duffer because Stocko has the following warning.
Revenue Growth: The company showed robust revenue growth from FY22 to FY23, with Net Revenue/Gross Profit increasing by 23% from £16.9m to £20.9m. The market expectation for FY24 to achieve a net revenue of £21.0m appears conservative, projecting a minimal increase from FY23, suggesting that the company might be expecting stabilisation in its revenue growth or facing a plateau in its current markets.
Profitability: Adjusted EBITDA increased significantly by 42% from £3m in FY22 to £4.3m in FY23, indicating improved operational efficiency and profit margins. The forecast for FY24 sets the Adjusted EBITDA target at £4.2m, slightly below the performance in FY23. This forecast might reflect anticipated challenges or investments that could temporarily reduce margins.
Cash Flow and Liquidity: Net cash increased by 10% from £6.2m in FY22 to £6.8m in FY23. This suggests the risk of bankruptcy or fears as a going concern are exaggerated. The expectation for FY24 to exceed £9m in net cash by year-end suggests strong cash management and liquidity, enhancing the company’s financial stability and its ability to meet short-term obligations.
Earnings Per Share (EPS): There was a significant improvement in basic EPS from 0.19p in FY22 to 0.27p in FY23, an increase of 42%. Adjusted basic EPS also grew by 18%. This positive trend in EPS is crucial for investor confidence and reflects well on the company's profitability on a per-share basis.
Concerns: While the company showed positive growth in many areas, the decline in Profit Before Tax by 24% from FY22 to FY23 to £1.1m from £1.5m raises concerns. Higher acquisition and restructuring costs influenced this decline. Monitoring these costs will be crucial for maintaining profitability.
Conclusion as a Going Concern: Based on those numbers, the company appears to be in a strong financial position with positive growth in revenue, profitability, and cash reserves, which supports its status as a going concern. The conservative revenue forecast for FY24 suggests a cautious approach, possibly due to market saturation or economic uncertainties. The expected increase in net cash positions the company well to handle potential challenges and invest in growth opportunities. Investors and stakeholders should be aware of the management's strategies to handle acquisition and restructuring costs which have previously impacted profitability.
Investor meet company have them on at 10am this morning?
https://mail.google.com/mail/u...
Monster contract for tiddler Made Tech (LON:MTEC) - Mkt Cap £13m:
Made Tech awarded £19.5m new contract with DLUHC
Made Tech, a leading provider of digital, data and technology services to the UK public sector, is pleased to announce that it has been awarded a new contract with The Department for Levelling Up, Housing & Communities ("DLUHC"), worth up to £19.5 million revenue to the Group over a 24 month period with a 12 month extension option.
http://newsfile.refinitiv.com/...
It’ll be interesting to see what happens to this contract when / if the DLUHC is scrapped / merged into another government department after the next election especially given the levelling up turns out to have been little more than a catchphrase intended to win votes rather than a promise to deliver anything to deprived areas.
If the contract revenue is split evenly over 2 years, the turnover represents 25% of the current level, so very significanr.