Small Cap Value Report (Mon 22 Jan 2024) - XPF, TRI, MIDW, KOO, CLIG

Good morning from Paul & Graham!
Mello Monday is tonight at 17:00, details here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
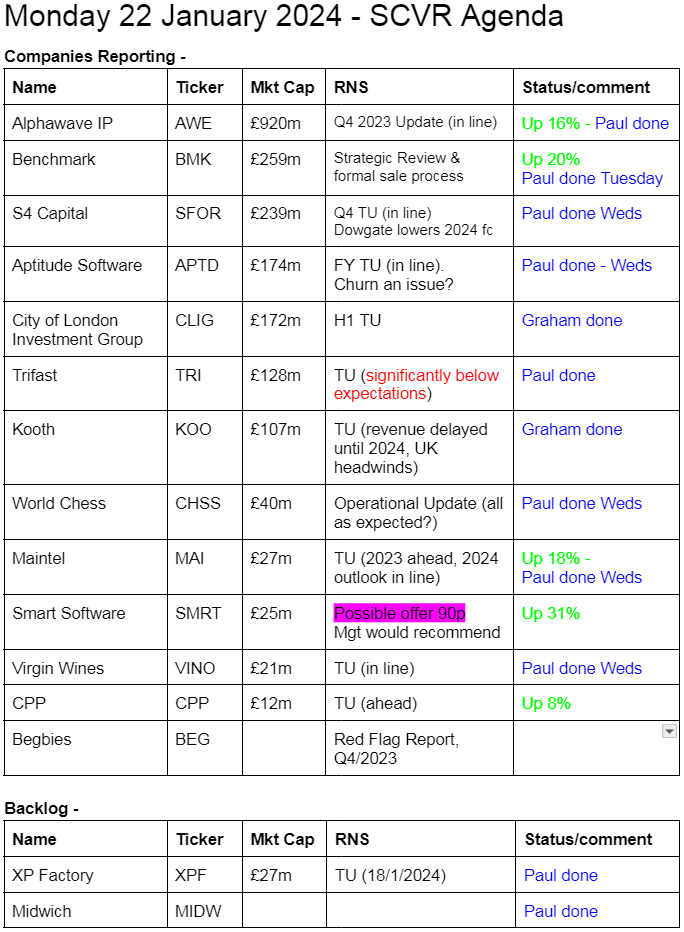
Summaries
XP Factory (LON:XPF) (Paul holds) - 16.0p (£27m) - Trading Update (18/1/2024) - Paul - AMBER/GREEN
Strong Xmas trading, but only expects in line for 15-months to 31/3/2024. Singers forecasts continuing PBT losses, and only breakeven FY 3/2025. Possible upside though from high operational gearing, and a resurgent consumer in 2024 maybe?
Trifast (LON:TRI) - down 27% to 68p (at 08:08) - £93m - Trading Update - Paul - BLACK (profit warning flag) - AMBER/RED on fundamentals
A stinker of a profit warning, with FY 3/2024 forecast adj PBT slashed by 46% to £6.0m. The company only discloses operating profit (EBIT), but that ignores finance costs, which use up half of EBIT. Balance sheet is quite strong, although inventories seem excessive. Outlook sounds grim, so I'm steering clear for the foreseeable future, am not tempted to catch this falling knife personally.
Midwich (LON:MIDW) - 371p (£383m) - Trading Update - Paul - AMBER/ GREEN
In line trading update for 2023, despite challenging market conditions. This share is looking cheap on a low PER, and with a nice yield. Could be worth a closer look, although I don't know how 2024 is likely to pan out.
Kooth (LON:KOO) - down 2% to 287.5p (£104.5m) - Trading Statement - Graham - AMBER
I’ve softened my stance on this from negative to neutral. The company is “cash flow positive” although will probably still post a loss for 2023. Revenues have surged higher thanks to US contracts and the company has plenty of liquidity after raising funds last year.
City of London Investment (LON:CLIG) - up 6% to 340.2p (£172m) - Six Month Trading Update - Graham - AMBER
This investor in closed-end funds announces an unchanged interim dividend on similar H1 profits to last year. Newly delivered cost savings will improve results. I admire the long-term track record here and see the yield as attractive, but see few signs of potential growth.
Paul’s Section:
XP Factory (LON:XPF) (Paul holds)
16.0p (£27m) - Trading Update (18/1/2024) - Paul - AMBER/GREEN
Just for full disclosure, this used to be a large position for me personally, but it’s only small now, because I needed the money for something else. It's frustrating when something you think is good doesn’t go anywhere, and of course there’s an opportunity cost in missing out on other shares that are attracting more interest. I’m sure we all have the same dilemma from time to time.
Background - XPF was originally just an Escape Room format, but it made the transformational acquisition of Boom Battle Bars in late 2021, then embarked on a breakneck pace expansion of new sites particularly in H2 2022, so those new sites contributed a full year in 2023, hence very rapid revenue growth in both 2022 and 2023. Some sites are owned/operated by XPF, whilst others are franchised.
“Experiential leisure” is an interesting growth concept at present, with competition emerging and growing. The idea is you play games of various types whilst socialising, which is proven as a good team-building thing for corporates, and is a lot more interesting and fun than just sitting around talking in a conventional bar. I think this is taking a chunk out of the business for traditional bars targeting younger people (XPF’s core customers are 25-35 it says).
Anyway, on to the latest news -
XP Factory, one of the UK's pre-eminent experiential leisure businesses operating the Escape Hunt and Boom Battle Bar brands, is pleased to provide an update on trading for the 52 week period to 31 December 2023.
The financial year end was changed, so the current period is going to be 15-months to 31 March 2024.
52 weeks to 31 Dec 2023 -
Revenue up 95% to £44.5m
Very strong LFL sales growth for the whole year, +29% Boom, and +17% Escape Hunt (“EH”) - although I would expect strong LFL growth from the new Boom sites at first, as they get established after opening mostly in late 2022.
Dec 2023 particularly strong (LFLs +50% for Boom, and +20% EH)
That’s all great, but the overall performance is only in line -
Performance provides confidence of meeting market expectations for the financial year to 31 March 2024
Hopefully they’re holding something back for a beat?
Broker forecast - thanks to Singer (via Research Tree) for an update.
It shows 15-month forecast for 3/2024, with an adj EBITDA (pre-IFRS 16) of £6.1m, which sounds good until you notice that this translates into a loss before tax of £(1.6)m.
Looking at H1 results, the depreciation charge for fixed assets is about £3m per half year, so that makes up the bulk of the difference above between EBITDA and the PBT loss, when annualised to c.£6m.
The good thing though is that site fit-outs are a sunk cost, so EBITDA is actually a rough approximation to cash generation in this sector, and is widely used for acquisition pricing, and by banks. So it’s one of several useful measures.
XPF should be generating cash now, and it can therefore open as few, or as many new sites as it can afford - it’s all discretionary spending after all (maintenance capex should be minimal, as most sites are new). Therefore it doesn’t need to raise more equity, but might choose to do so, if it wants to accelerate the roll-out pace. Large landlord incentives are available to fund much of the new site fit-outs.
Management clearly needs to get the share price up considerably, before raising any fresh equity.
Costs - there was an interesting CEO interview on Vox recently. Bear in mind these are promotional, PR things, not independent. Nevertheless, a couple of points stood out for me -
Increased living wage in April 2024, the CEO indicated they can absorb the extra cost due to strong LFL revenue growth combined with 70-80% gross margin (remember the games revenue is 100% margin).
Energy costs have fallen right back down again he said. I checked this, and wholesale energy is now cheap again, so it depends what deals and what hedging companies have done.
Paul’s opinion - it was meant to be profitable by now, proper profits (PBT), but doesn’t seem to be. That’s muddied by the change in year end, with a 15-month period ending 2/2024.
However, the Singers forecast for FY 3/2025 only shows £0.1m PBT on £58m revenues. It should be making more than that. So all these great LFLs and high gross margins, only results in breakeven. That doesn’t excite me at all.
The upside comes from a rebound in consumer discretionary spending, which may well happen in 2024, particularly from April. Therefore I see XPF as conceptually similar to Tortilla Mexican Grill (LON:MEX) (I hold) - where they’re operating around breakeven (but cashflow positive) in current, difficult macro conditions. So investors that hold these shares (and other hospitality companies) are betting on increased demand (at high gross margins) creating future operational gearing, and much higher profits. Food/drink and energy costs also now abating is helpful, but higher living wage is both a negative (higher costs) but also helpful in giving a lot of its customers a considerable real terms pay rise, which is bound to increase demand.
Overall then, I think £27m market cap for XPF does leave upside potential, if consumer spending accelerates in 2024 as I expect it to. But on the downside, I’m disappointed it’s not yet properly profitable. So let’s go with AMBER/GREEN and see how it pans out. The strong peak trading performance should mean it delivers at least in line with forecasts, hopefully.
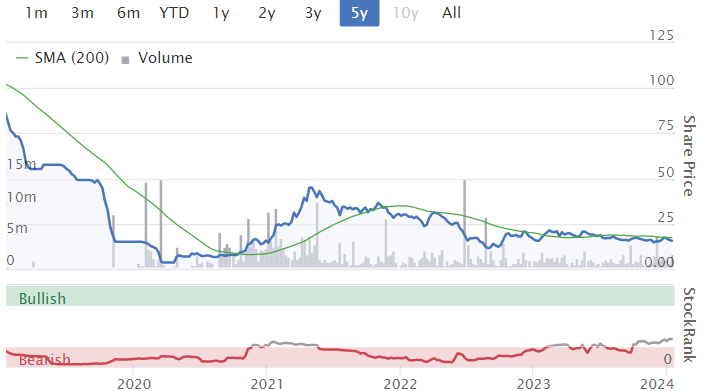
So far the market hasn't given XPF any credit at all for the rapid expansion of the business - that might change in the next bull market, especially if it starts beating forecasts (but there's no guarantee that will actually happen of course) -
Trifast (LON:TRI)
Down 27% to 68p (at 08:08) - £93m - Trading Update - Paul - BLACK (profit warning flag) - AMBER/RED on fundamentals
Leading international specialist in the design, engineering, manufacture, and distribution of high-quality industrial fastenings and Category 'C' components principally to major global assembly industries
This year is FY 3/2024.
Profit warning -
…the Board now expects that the Group's results for the year ending 31 March 2024 to be significantly below its previous expectations, with revised revenue at c.£230m and adjusted EBIT margin percentage of c.5%.
That works out at £11.5m adj operating profit (EBIT).
*Consensus forecasts FY24 prior to this announcement were revenue of £254m adjusted EBIT £15.5m
However, EBIT is a poor measure here, ignoring the substantial finance costs lower down the P&L.
It gets worse -
The more testing environment that we are now experiencing in 2024 in terms of growth is being severely impacted by a further slowdown in customer demand and volumes across the business and to an extent by the reported macro-economic challenges and geopolitical events.
Further details -
Q3 (Oct-Dec 2023) - “low visibility and volatile demand…”
Dec - “significantly lower than forecasted volumes…”
“Excess customer inventory levels…”
“Challenging conditions to persist” until year end 3/2024.
Recovery later in 2024.
Focused on improving efficiency & productivity, but not enough to offset lower revenues.
Cutting 10% of non-operational staff globally, to save £3m, but at what impact to the business I wonder?
Further strategic reviews, possible closures of sites I wonder?
Trying to reduce debt to below 1.5x EBITDA
Broker updates - thanks to Cavendish & Zeus, who both update via Research Tree. Cavendish withdraws forecasts, and will update later after talking to management, but points out that the revised guidance is 26% lower than its previous forecast at EBIT level.
Zeus reduces its FY 3/2024 adj PBT by 46% to only £6.0m. That’s 3.5p adj dil EPS. So at 68p/share I make that a PER of 19.4x
It lowers next year (FY 3/2025) from 9.3p to 5.8p, a PER of 11.7x - probably about the right price, but that’s assuming it can significantly improve profits in FY 3/2025.
Balance sheet - I’ve flagged before that TRI has much too high inventories. These have come down in the last 18 months, but were still £83m at 30/9/2023. I worry that this is not only tying up a lot of capital, but could contain obsolete items - so I see an elevated risk of a stock provision being needed maybe as part of the FY 3/2024 audit? With poor results anyway, the CFO might decide to kitchen sink the figures, to give a nice springboard for future recovery? That’s guesswork on my part, but the inventories are clearly much too high, at about 6-months cost of sales.
Other than that, the last balance sheet is pretty sound, with £93m NTAV, and a big surplus on working capital, albeit funded partly with gross long-term debt of £60m. Net debt was £28m at 30/9/2023, and they should be able to reduce that further by liquidating excess inventories. So overall, solvency & dilution don’t seem to be significant risks.
Paul’s opinion - I would be running a mile after reading this phrase -
…severely impacted by a further slowdown in customer demand and volumes across the business
I can understand tough macro causing a bit of a profit warning, but this seems altogether more severe. Is something more serious going wrong - ie customers shopping around and buying their fastenings elsewhere?
The PBT margin is now down to only <3% of revenues, and it doesn’t sound like there’s much chance of a short-term recovery.
Overall, I see this negatively, but with no solvency worries, it’s not bad enough to go red, so I see it as AMBER/RED. A possible future recovery, but I don’t see any rush to get involved here. It’s increasingly looking a rather poor quality business. More restructuring usually means more one-off cash costs too (redundancies, etc).
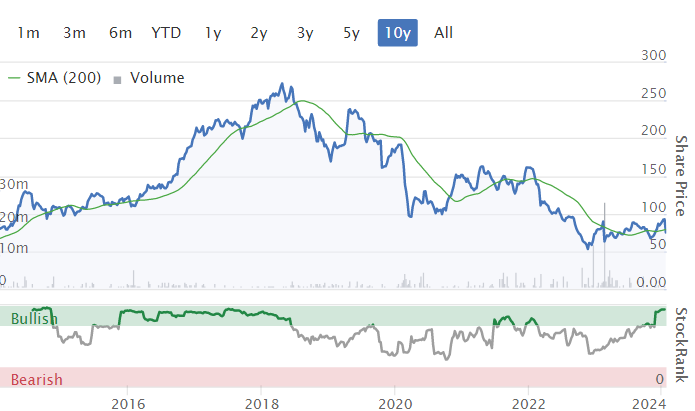
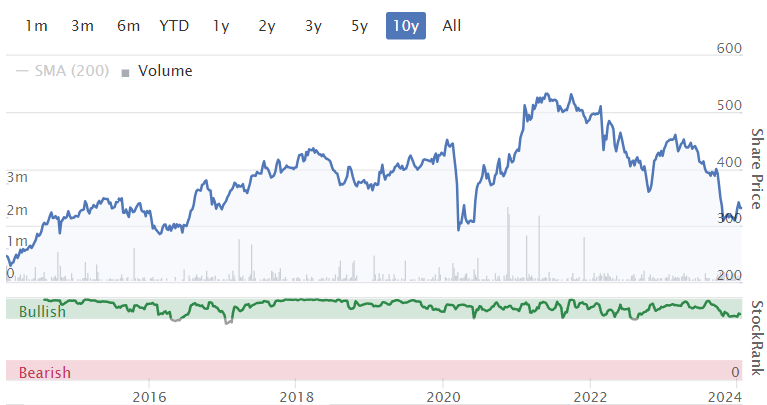
The long-term chart looks like a business in decline, and it's been almost constantly restructuring in recent years too. Maybe it's just too competitive a sector to make a decent return?
Midwich (LON:MIDW)
371p (£383m) - Trading Update - Paul - AMBER/ GREEN
Midwich Group plc (AIM: MIDW), a global specialist audio visual distributor to the trade market, is today providing a trading update for the year ended 31 December 2023.
This is concise, and self-explanatory - and it's great to see another company reporting adj PBT, instead of the often meaningless EBITDA -
The Group finished the year well and the Board now expects to report record revenue for 2023 of c.£1.3 billion, representing growth of approximately 7% over the prior year (6% at constant currency), with organic revenue in line with the prior year.
Positive product mix resulted in gross margin of c.16.8%, exceeding pre-Covid levels. The Board anticipates reporting adjusted profit before tax of approximately £50 million, which is in line with market expectations*.
The Group delivered strong cash generation in the year, of around 100%, ahead of our long-term expectations of 70-80% of adjusted EBITDA. Adjusted net debt** at 31 December 2023 was c.£90 million (representing approximately 1.3 times adjusted EBITDA***).
*Market consensus based on an average of £50.3m and a range of £49.4m to £51.0m, as at 16 January 2024
Outlook - the rest of the commentary sounds quite cautious, with acquisitions having taken up the slack in 2023. It raised some additional equity for acquisitions in June 2023, so I'm happy that the balance sheet is not stretched, despite intangible assets growing with each deal -
"After two years of exceptional revenue growth, the market backdrop throughout 2023 was much more challenging, with demand for our more mainstream AV products impacted significantly in many territories. We responded to this by focusing on our technical product categories, completing a record seven acquisitions in 2023 and ending the year with a strong M&A pipeline…
Whilst the broader market backdrop remains uncertain, the recent acquisitions have integrated well and continue to trade broadly in line with our expectations. Consequently, the Group remains well positioned to continue to deliver both organic and inorganic growth in 2024 and the longer term."
Brokers have trimmed forecasts a little -
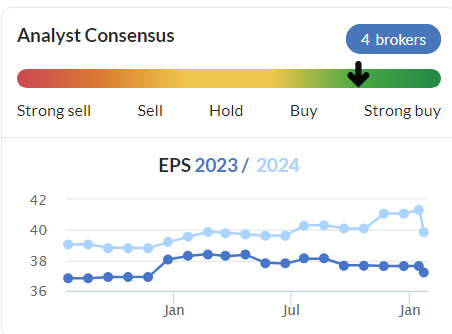
Paul’s opinion - I honestly don’t know what to make of Midwich.
Despite difficult conditions, it’s met market expectations in 2023, helped by improved (but still very low) gross margins. Although it depends what costs they are absorbing into cost of sales, it may be more than just direct product costs? It makes sense for distributors to minimise the reported gross margin, so suppliers and customers all think they're not making much of a markup.
The forward PER is only 9.3x, with a nice 4.7% yield on offer too - attractive value, if forecasts are achieved.
Lots of acquisitions might be taking management eyes off the ball a bit, maybe?
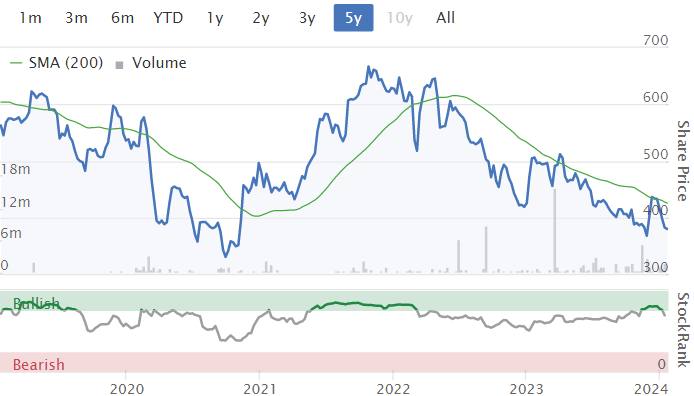
The share price is close to a 5-year low, which seems harsh. Maybe the market doesn’t have lot of faith in the 2024 forecasts, who knows?
On valuation grounds, it looks intriguing, so might be worth a closer look. So I’ll go with AMBER/GREEN based on the info available to me today. Obviously I have no idea how trading will progress in 2024, so it might out-perform, or it might warn on profits, we simply don’t know at this stage.
Graham’s Section:
Kooth (LON:KOO)
Share price: 287.5p (-2%)
Market cap: £104.5m
Kooth, a global leader in youth digital mental well-being, announces a trading update for the financial year ended 31 December 2023.
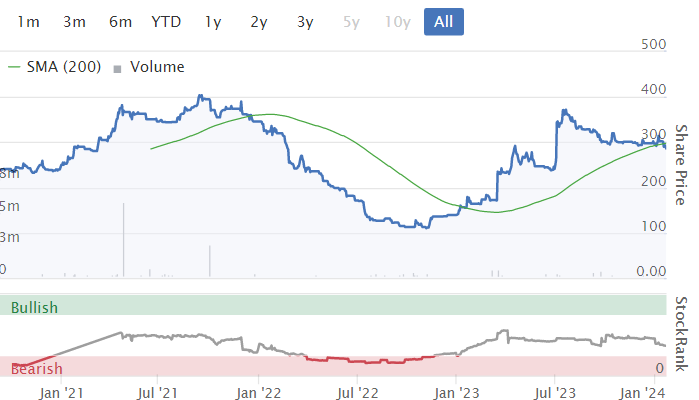
Paul and I have been inconsistent on this one - I’ve been bearish, Paul (briefly) bullish, and more recently Paul took a neutral stance.
Today’s announcement sees 2023 revenues up by c.65% to £33.3m.
Despite this tremendously strong rate of growth, this result appears to be below expectations (£34.3m forecast on the StockReport). There is an explanation:
c.$4 million of revenue billed in 2023 relating to revenues received from US contracts, which had been expected to be recognised in 2023, but will now be paid and recognised in early 2024.
The opportunity in the US for Kooth is still very young and I don’t think investors will be overly concerned about a few million dollars of revenues slipping into the current year from 2023.
Other points from this update:
“Positive operating cash flow” - Kooth has been EBITDA positive but is probably still loss-making at the net income level.
Net cash balance £10.9m, plus an undrawn working capital facility for USD $9.5m.
In the key US markets, we have the following news. The Soluna mental health app has launched in California. In Pennsylvania, Kooth is “finalising discussions” around extending its existing service contract.
In the UK, there continue to be headwinds, “reflecting a focus on NHS cost saving and the ongoing acute care backlog”.
CEO comment: he says that Kooth “is now a leader in the important US digital mental health market and a provider of choice for the provision of services to children and young people.”
Graham’s view
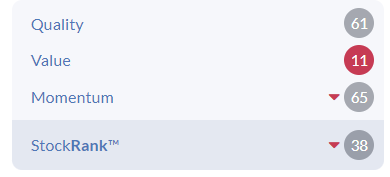
I’m inclined to play it safe and stick with an amber view on this. Last April, I gave the company the thumbs down (at a share price of 230p), pointing to limited UK growth prospects and uncertainty around US growth.
Here we are nine months later and arguably both of these things are still true, but the company can point to extremely strong revenue growth for 2023 and is probably not far off breakeven.
I still struggle with the £100m+ valuation and for the avoidance of doubt I still suspect that it’s overvalued at a P/S ratio of 3x for 2023. But I’m happy to take a neutral stance: I can’t rule out the possibility of continued sales revenue growth, led by US contracts. And who knows what profit margins it might ultimately achieve?
This is less speculative than most of the early-stage, blue-sky companies we have previously covered in this report, but it is still at an early stage in its development.
City of London Investment (LON:CLIG)
Share price: 340.2p (+6%)
Market cap: £172m
We don’t cover this one very regularly but the market has reacted favourably to today’s interim trading update.
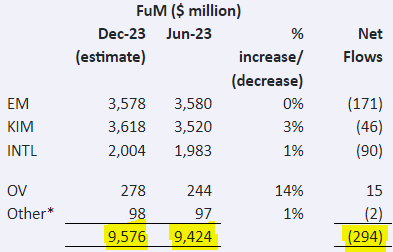
The company reports that funds under management increased in H1, from $9.4 billion to $9.6 billion. This is despite outflows of $294m.
In table format:
I don’t study this one often, so I’ve had to refresh myself on how CLIG operates.
Funds are spread out as follows:
EM = emerging markets.
KIM = Karpus Investment Management, closed-end fund strategies for wealth management clients in the US.
INTL = international.
OV = “opportunistic value”.
Performance: “mainly positive” in H1, some strategies outperforming and some strategies underperforming.
CLIG is an investor in closed-end funds, whose discounts to Net Asset Value have been notoriously large in recent times, at least in the UK. In this regard CLIG says:
Significant CEF discount widening through late 2023 was partly reversed in Q4 which helped relative performance into year-end while NAV performance was positive.
They also say:
We are focused on new mandates in a number of the Group's asset classes with very good long-term performance as CEF discounts are at compelling levels and there is ample capacity.
Operations: the company transparently discloses that its run-rate of operating profit is c. $3.2m, before any profit-sharing with fund managers.
70 basis points of management fee income = $67m annually based on current FuM.
On a monthly basis this is $5.6m of fee income.
Fixed monthly costs are $2.3m.
So deducting that leaves c. $3.2m in operating profit per month.
Profits in H1: Adjusted PBT in H1 (to December 2023) is around $13.9m, the same as H1 in the previous year. Note that we can’t expect this to match up against the calculation of monthly profits shown above for a couple of reasons, one of which is the profit-sharing arrangements. Also, the funds under management figure is constantly changing.
Cost savings: $2.5m of annualised cost savings have been delivered and will be seen in the new financial year.
Cash: $28.8m.
Interim Dividend: unchanged at 11p.
Graham’s view
I’m going to adopt a neutral stance on this one for now, as further research is needed on my part to build a more robust view on it.
Comparing my notes with Roland’s notes in 2022, I see that CLIG’s net fee margin then was 0.74%. If that’s on a steady decline it’s no surprise, given the pressures in the fund management industry, but it’s something to be aware of.
According to Roland, FuM were $11.4 billion in Dec 2021. Again, no huge surprise to see FuM on the decline (a 16% fall over two years), but it’s important to bear this in mind.
Back then, the company was talking about “capacity limitations” - it’s only sensible for a strategy to invest so much in closed-end funds on the secondary market, as you don’t want to overpay or to be responsible for closing their discount to NAV.
Today, the company appears to be more optimistic about capacity. But I must say that CLIG’s investment universe seems quite narrow.
Over ten years, CLIG’s share price has made little progress, but the company has paid an enormous regular dividend. Perhaps it’s best to treat this as a relatively boring but hopefully a reliable income stock, and not expect much growth?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Re Kooth (LON:KOO) - it a great story and some impressive top line.
However, I believe that growth will be more capital/cost intensive than is expected or perhaps visible. Its a sort of Uber Technologies (NYQ:UBER) for mental health resources...not being facetious, rather trying to pick out something analogous. The reason Uber works where many other Uberised businesses failed is that it had easy low cost simple to plug and play capacity meaning very little complexity in order fulfilment. This will not be the case for Kooth particularly as it grows more....and it has a much more critical need to ensure capacity is there when and where needed (running peak time rates like Uber to kill some demand will not be tolerated).
There's loads of instances where Uber-like business models run into to a brick wall. The idea always seems cool tho...software engineers can rule the world blah blah. The scope for service errors at Kooth is low. To avoid they need to run fat and heavily invested...they can't do lean and mean and shrug and learn through mistakes...
Just to let you all know it will be the first Mello Monday show of 2024 tonight and we have six companies presenting or being analysed on the BASH plus the very popular Paul Hill as our guest speaker.
Mello Events will be hosting their first MelloMonday webinar of the year this evening, Monday 22nd January 2023, at 5pm. The programme for the evening is as follows:
5:00pm Paul Hill presents “Where the markets are wrong & how to profit?”
5.30pm New IPO…Tertre Rouge Assets(TRA)
6:10pm Company presentation by Hercules Site Services (HERC)
6:50pm Educational Session
7pm Company presentation by Good Energy (GOOD)
7:40pm BASH Panel with Kevin Taylor (JNEO), Mark Simpson (NXQ) and Richard Crow (AVON)
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50.
PayPoint (LON:PAY) PayPoint wins DVLA contract for International Driving Permits
PayPoint Plc is pleased to announce that it has been awarded the Driver &
Vehicle Licensing Agency (DVLA) contract for providing International Driving
Permits across its extensive network of retailer partners across the UK.
The multi-year agreement will see the service move from the Post Office to
PayPoint from 1(st) April 2024, exp 300,000 permits issued each year.
No mention of the value but a new revenue stream ahead of the trading update on Wednesday. I hold.
I'm glad PayPoint (LON:PAY) are finding novel ways to monetise their vast network of convenience stores!
But this is small money. 300k permits, say Paypoint make £1 from each, it's loose change.
(I hold in the Boon Fund)
Following the second consecutive quarter of less than quarter a per cent of growth, the latest Begbies Traynor's “Red Flag Alert” report (snapshot of British corporate health for over 15 years) highlights the speed at which critical financial distress is growing in the UK. The number of UK businesses in “critical financial distress” has jumped for the second consecutive quarter as high inflation and interest rates lift costs and weaken consumer sentiment.
All sectors were affected, construction, real estate and support services in particular.
Link to announcement
One fund manager recently summed up the environment as "the weak get weaker and the strong get stronger." So companies with little debt and able to fund expansion or acquisition through internally generated cash should do well in the long term.
Eenergy (LON:EAAS) - "£30m Energy Management disposal to unlock growth potential" (full detail in our new note, accessible here: https://www.equitydevelopment....)
As trailed in November, eEnergy has now agreed the disposal of its Energy Management business for an initial consideration of £29m, plus earnout (estimated range of £8m to £10m subject to performance). This is a transformative deal, which will eliminate all debt (previously a constraint to growth and a drag on sentiment) and leave the Group with net cash in excess of £15m to reinvest in the high growth Energy Services division. We note that the initial cash consideration (£25m) is similar to eEnergy’s current market cap (£26m at Friday’s close). We reiterate our 13p Fair Value estimate and will publish new forecasts post completion (General Meeting on 7th Feb).
Kooth (LON:KOO) It has succeeded in winning a good level of contracts and is promising in US. But has not managed to get NICE recommendation in UK whereas 4 other companies are : Lumi Nova (BfB labs); • Online Social anxiety Cognitive therapy for Adolescents (OSCA); • Online Support and Intervention for child anxiety (OSI); and • Space from anxiety for teens, space from low mood for teens, space from low mood and anxiety for teens (Silvercloud)." So that must hold them back in competing for business.
Additionally I had some concerns myself about their model, investigated and found that there had been some significant complaints re safeguarding on their platform. It hasnt been widely reported (hence unusual source ) but Maria Caulfield Under Secretary for Mental Health and Women's Health stated this in response to an MP who raised concerns. 'This matter has been escalated to the national and regional safeguarding and mental health teams due to the severity of the issues brought to our attention. NHS England is also raising the matter with Kooth directly, and will update the DHSC on the outcome. The DfE will continue to work with the DHSC and NHS England as it investigates this matter and will consider any further action required..'' https://catholicherald.co.uk/c...
Not sure that article is saying Kooth is bad per se. It's more about a Catholic teacher complaining that Kooth users are too pro-trans for her liking and that Kooth should balance it with anti-trans opinions as well.
Likewise the escalation of the matter is more about what the government's policy towards the trans issues in young girls should be rather than any problem with Kooth.
One part of the issue was that Kooth were allowing chat rooms where they werent properly moderated. Thats where the safeguarding reference comes in AFAIK which is different from any ideology clash.
Regarding Alphawave (LON:AWE), I refer you to a research note by Jefferies dated 26 September 2023 with a target price of 270p (at the time of note 129p). This short note includes an explanation of how the company is transitioning and moving away from low-margin legacy businesses. Perhaps Paul can get a copy of this (and other) reports before he comments.
Superdry (LON:SDRY) some big volumes going on here pre trading update on Friday.
It's a trading position for me, which I rarely do as I never can get in or out quick enough, but there's something brewing (further sales of IP, being brought back in private, new activist coming on board). As they say, sometimes it is worth following the money.
Being a PI is probably the worst stakeholder to be atm in Superdry (LON:SDRY) IMO.
Lenders in driving seat. They might extend more money, but at more favourable terms to them. Could be more security, or extremely cheap warrants even.
If it's not the lenders, then it is major shareholders in the driving seat. If they do an equity fundraising at a deep discount. Via a bookbuild that only institutions and existing large shareholders can access. And maybe also get a big slug of cheap warrants. All, of course, "in the interest of all shareholders" signed off by the "independent" director.
Boon, I do agree. I'm hoping to grab a 25% profit without having to wait until Friday.
Like I said, trading isn't usually my thing, but only by deploying cash do you learn some vital lessons!
Trifast (I hold)
Clear turnaround situation with turnaround management now in place .
Turnarounds take 2-3 years so remains a clear textbook plan just needs delivery .
- reduce inventory to 3 month stock turn
- clear all old stock and if not sold provision it
- cut costs
- reduce the debt by inventory reduction and cost cutting
- sell off / discontinue any non core assets or non performing divisions .
Situations like this don’t get worked through in 6 months so short term results aren’t relevant .
M - define the mission
O - objectives
S - strategy
T - tactics
Key to turnaround is simple - “get on with it”
I think new management are doing exactly what they need to do .
Mr Market loves the dopamine hits of “ahead of expectations “ and hates the “behind expectations” but these are purely short term fluctuations .
Any credible CEO knows his mission and is executing his plan irrespective of Mr Market .
I think looks good but it’s not a dopamine hit most stock pickers love .
I think I get what’s going on having personally overseen a similar turnaround albeit on a smaller scale so we’ll done to management who just need to crack that inventory issue which will take 6 - 12 months of good purchasing / sales by a strong FD .
Time for FD to show what he’s made up of and the next 12 months is where the action really starts .
That’s the bull case .
Any ideas why Castings (LON:CGS) has dropped 6.52% this morning?
hi Indie
Castings (LON:CGS)
SP fall today triggered by a large seller. Has sold in 3 batches of 750k, 575k and 250k shares all at 330p, total value £5.2m (app 3.5% of M/Cap).
Likely there will be an RNS tomorrow revealing the identity of the seller.
Snazzy
Castings (LON:CGS)
Thanks, Snazzytime. I don’t access that level of info. Most helpful.
The sales of Castings (LON:CGS) are visible on lse.co.uk which is free to view. They were interspersed by 4 curious purchases of 3, 3, 5, and 1 shares, all at 10.23.37 a.m. at 350p.
Richard
You can also see them on the ADVFN app/ website which is free
Castings (LON:CGS) / how to view recent trades.
Thanks, RichardK and 2+2=Fish - very useful resources on seeing recent trades. (I was partly getting muddled with seeing potential trades on Level 2, which I don't pay for.)
Share price has largely recovered (phew).
Forgot to say - I hold.
CSO selling 20k of shares at Eagle Eye Solutions (LON:EYE) just now. Surely that indicates no imminent new contract orders on the way. With a trading update last week not much upside here in the short term one would think. I've just sold out in the hope of getting back in a bit cheaper further down the line.
There were huge director sell last thursday in Eagle Eye Solutions (LON:EYE) too. No idea whats going on as the company seems to be still in a great sweet and put out a positive outlook in the trading statement.
Not sure it’s that big a deal. The sale by the CSO was for 4K shares out of his holding of 182k i.e. 2%. The ones last week were from exercising options. In fact the CSO retained 55.7k from the exercise so his net shareholding has actually increased by 51k shares in the last week after today’s sale.
The other sale was by the founder of their Untie Knots acquisition whose lockup on the share consideration has expired.
Hi Brother, I don't disagree with your point at all, it's not a big deal as a long term holder. I jumped into Eagle Eye Solutions (LON:EYE) here as more of a trade at 510p. I am just of the opinion that if a big contract is on the cards you wouldn't sell anything, not even 20k. You'd wait an extra month until after the contract announcement and bank the extra few grand that it would make you. Medium and long term it still has lots of potential and I may look to come back in as the technology and most is strong. Just in the next month or two I can't see myself missing out on a contract announcement that's going to alter the SP significantly, and therefore deploying the money elsewhere for another trade. Knowing my luck they will announce Walmart are taking on their new tech tomorrow at the SP will double!
Fair enough BenHazz. I tend not to trade short-term unless something is obviously over/undervalued.
Thanks for your thoughts on Midwich (LON:MIDW) Paul. I was quietly optimistic at the start of the year, I'm more 50/50 now.
I don't like brokers nudging down forecasts, and being acquisition happy you'd hope they've bought well, so this statement does sow some seeds of potential worry.
"The recent acquisitions have integrated well and continue to trade broadly in line with our expectations"
No broker notes available for us plebs, so probably better risk/reward to be found elsewhere.
@equity_research on X
Eenergy (LON:EAAS) news today which an agreement reached to sell the energy management division for £29.1m + £8-10m contingent on earn out.
- debt to be repaid in full
- GM held 7th Feb to approve
- transactions proceeds a whopping 90% of current market cap
Positive trading update from Alphawave IP (LON:AWE). This is a stock we discuss at the Edinburgh and Lothian Signet investor group and it held by several of us. Not an easy company to understand and partly in transition (hence historic numbers less useful). But a rare example of a UK technological company related to AI and with a key position in connectivity.
Report in the Daily Telegraph today that because the West is being far more cautious about sharing high tech secrets with China, China are simply trying to steal them instead.. MI5 and our global partner equivalents report over 20,000 attempts to steal secrets through various means but by hacking is certainly one of them. This could be a lucrative long term trend for companies involved in cyber security. Could someone kindly remind me of the UK companies involved in this area as it may well be worth taking an other look. Thank you.
I think Darktrace (LON:DARK) are one of the leading UK companies in that area.
In the US, have a look at Palo Alto Networks (NSQ:PANW) and Crowdstrike Holdings (NSQ:CRWD).
For insurance, Beazley have a very profitable line in cyber insurance.
Might be worth considering L&G Cyber Security UCITS ETF USD Acc (LON:ISPY) orWisdomTree Cybersecurity UCITS ETF USD Acc (LON:CYSE) . Not much UK influence there and may just be more volatile versions of a Nasdaq tracker.
You might have missed the boat a little here from a US perspective. Crowdstrike Holdings (NSQ:CRWD) which is probably the darling in the US right now is up nearly 200% in the past year. Palo Alto Networks (NSQ:PANW) up over 100%. I'm not as knowledgeable on UK listed Darktrace (LON:DARK) but I know it has struggled in comparison.
Most larger cybersec companies are international i think.Avast was the last one to leave the UK market a few years ago and i think Darktrace (LON:DARK) is the only UK listed one to invest in now.
To add to the mentioned US listed cybersec companies so far, SentinelOne (NYQ:S) has just got upgraded if you're interested.
'SenintelOne Stock Spikes on Upgrade Citing Strong Demand, Rising 'Attack Volumes'
'SentinelOne shares are trading sharply higher after BTIG published an enthusiastic research note on the security software provider, citing signs of strong demand from customers.'
'Powell said that over the past few weeks, he talked to five large
companies about the outlook for the endpoint security market, and found
“a clear uptick in discussions,” leaving him “feeling better about the
market’s growth potential in 2024 relative to 2023.” Feedback on
SentinelOne in particular was consistently positive, he said.'
'The analyst said he sees room for SentinelOne to keep gaining share in
all of its core target markets. And he is bullish about the company’s
new product initiatives, which include cloud security, data lakes, and
the company’s “Purple AI” artificial intelligence-powered software for
threat-hunting, analysis, and response.'
https://www.barrons.com/articl...
Kooth (LON:KOO) TU looks interesting. Revenues up 65% to £33.3m. £34m was expected originally, but there is £4m in revenues that has ben deferred and will be paid next year. I don't hold but think i'll look into this company.
Brickability (LON:BRCK)
Another somewhat chunky acquisition announced here looks like it’s very similar in nature to the prior acquisition last year. Note these 2 most recent acquisitions are pretty material compared to the size of Brickability.imho companies that expand quickly tend to work best when they assimilate companies in significantly lower pe’s there can be instant benefit if your listed company has pe of 15 and is acquiring companies on pe 7 say. Brickability has none of that advantage its shares are very lowly rated. The company is only issuing new shares for only a minor % of the purchase price to they can still say the acquisition is accreative. Overall management here really need to be on the ball if they are going on material acquisition binge when its own shares are lowly rated. Benefits for shareholders can be great if profits of acquired stuff pay for purchases over time and overall company growth increases quickly - the stock market is littered with companies that have tried this strategy and failed though. I don’t really know much about this company is the low P/E ratio due to the enhanced risk here ?or is the market missing a trick that this company will have quickly rising profits ?
EDIT - removed as I misread the RNS!
Low PE due to its exposure to housing, the acquisitions of Topek and now TSL reducing their weighting once more to housing (sun 50% now). Facades is an area where there will be a glut of work for they next ten plus years as buildings (above 11m in Scotland and abive 18m in England and Wales) are re-worked following the terrible Grendel tragedy, and of course new builds also add to the project pipelines.
I think this should be it for now in terms of acquisitions for Brickability (LON:BRCK) , they’ve got some good businesses - as soon as they housing market turns the financial performance should fly and along with that the SP
Apologies for spelling errors all, on the train and only have my mobile to hand so can’t edit…
Good morning Paul, I listened to your podcast at the weekend when you asked that we mention anything that had been overlooked. I posted this on Thursday but the day was very busy. Thanks.
Corero Network Security (LON:CNS)
Paul, Graham,
On this busy day can I ask you to possibly revisit next quiet day, what I see as a GARP share which snuck under the radar yesterday while the world was reading all the news from more high profile companies. It was covered by a post by Equity Development, here, but no comment apart from me.
The company is Corero Network Security (LON:CNS) Corero Network Security and for anyone not aware of what they do, they sell software to counter Distributed Denial of Service attacks, DDOS, by which bad actors conspire to shutdown web sites. They do this usually by tempting very many innocent web users to follow clickbait which installs malware on their computer, this malware can be remotely activated to swamp a website with traffic such that legitimate users are frustrated in their attempts to use it.
This company goes back a few years, but appears to have reached an inflection point having paid off the last of its debt which it has used instead of the usual route of regular share issues. The company has little in the way of intangible assets to write off either and is now self sustaining with a growing order book. The word operational gearing is maybe appropriate here. You may remember I flagged WAND, having spent my life in IT, well this is as far from that as you could get.
Chunky cuts to Trifast (LON:TRI) forecast from zeus
2024 eps cut 46%.
2025 cut 37%
Trifast (LON:TRI)
Market reaction could be quite savage given the recent SP improvement.
Yikes, thanks for flagging deep cuts to Trifast (LON:TRI) forecasts, I'll have a section up by about 08:30, just started looking at it now...
Brickability (LON:BRCK)
I take the same view as gmtrader.
Looks to be a good acquisition. Brickability (LON:BRCK) is paying £40.3m of which £10m is in shares at 58.5p and £20m deferred consideration for historic revenue of £38.7m and £8.1m PBT.
I hold.
Nice balanced write up on XP Factory (LON:XPF) Paul, I know you won't have time but if would have been great to hear a follow up interview with Richard so you could ask those tough questions. The vox interview is all well and good but a bit too fluffy for my liking.
For example Richard said they had managed to absorb most of the fixed cost increases and not pass them onto the customer, how is that a good thing for the company if it's not profitable and wants to grow,? sounds more like they haven't been keeping their cost calculations updated
It's a really hard environment out there for this type of business but I hope Richard knows this is the period in the company's journey that he needs to be tough. Reduce fixed costs and focus on the bottom line.
It's my 2nd biggest holding so quite disappointing
XP Factory (LON:XPF)
Although I have warned on numerous occasions , this will go much lower as it will eventually need a new fundraise. In a couple of years all these sites will need refurbishment. Having visited a couple just for my own analysis, I have no doubt that they will be struggling to make a decent profit (if any) and return anything back to their shareholders.
Selling early your losing positions is a recipe for success.
Having just done a deep dive to update my own notes on XP Factory (LON:XPF), I also concur with you yiannos1 that they will need a fundraise.
They just are not profitable, holistically, on their sites. Their sites seem to need amazing amount of capex, judging by the D&A. Right now they're in the honeymoon period - have sunk in lots of investor funds opening new sites, and no huge maintenance or capex required yet. So cashflow will be OK. But... wait 2-3 years...
I wrote more about why I'm barge-poling them for now on my Substack. For me, they will repeat the story that has happened with Revolution Bars (LON:RBG) - now in a perpetual cycle of decline. No money to spend on refurbs, lower footfall, lower profits, even less money available for refurbs, until they have to close the site down permanently.
Boom Battle Bar margins (target of 20-25% site level EBITDA) is just not enough to cover the capex required. And they are still below that 20% lower bound number!
Looks to be a good acquisition of Topek Southern Limited for a consideration of up to £48m for Brickability (LON:BRCK)
£17m upfront and a dilution of 5.7% and the rest later.
Immediately it will be accretive in the first full year. In the 12 months to 31 August 2023, TSL generated audited revenue of £38.7m and PBT of £8.1m.
Brickability (LON:BRCK) (no position)
FY23 looks like an outlier year for Topek Southern Ltd, which might explain the unusual purchase price structure.
If we look at the accounts for each of the previous 2 years on Companies House, Operating Profit was closer to £3.1m, before jumping to £8.1m in FY23.
I also noted that in the FY22 Annual Report there was specific mention about the great year ahead:
A similar comment on expectations for FY24 was absent in the FY23 report:
Brickability (LON:BRCK)
Great investigative stuff abtan - one can really see why this company is rated quite lowly with the £100 mill they have spashed out beinga real leap of faith. I would say the margins being made by Topek seem overley high for that kind of contracting business - i ssupect they must have been in ten right place at the right time ready to go - i would be very dubious that they could keep up such amazing numbers over the long term as presumably supply and demand equialise - someone must be looking at those numbers and saying well we can give custokmers much better value. Perhaps if they do have a specific moat ii could be convinced otherwise - eg if they are the specialists in the field that peeps turn to when what needs doing "must be right" or is super complicated to work out exactly how it needs to be done and implemented. I really would worry withnthnjese acquisitions that they are done at peek "cladding catchup" boom time. Hopefully there is no connections with main peeps in charge of either business to each other outside work.
I had XPF was a favourite for 2023. Don't think any of the news has been bad but other prices are moving quicker! I wouldn't be surprised if Graham was looking for someone to buy it as he said he wanted to build a business, roll it up, and sell it when I met him at Master Investor (I think?) in 2020.
Good update from Pan African Resources (LON:PAF)
AISC lower
Production higher and may well increase guidance
Guidance for 2025 expected to be significantly higher
AISC for 2025 should be lower too due to the commissioned solar plant built
KEY FEATURES
PRODUCTION GUIDANCE
FINANCIAL RESULTS
Cobus Loots, Pan African’s CEO commented:
“We are pleased with the Group’s excellent safety, production and cost performance for the Reporting Period which positions us well to deliver on our guidance for the full financial year. Commissioning of the world-class processing plant at the MTR Project towards the end of this calendar year will further increase the Group’s production with approximately 50,000 oz per year of high margin ounces.
The commissioning of Barberton’s solar PV plant will contribute to further cost savings in the next financial year, adding to the benefits already being realised from Evander’s PV solar plant. We are also excited by the positive and tangible impact the Group’s ESG projects have made on improving relationships with our host communities and contributing to the sustainability of these areas.”
Thanks for this. I have held Pan African for a few years now and it’s been treading water for much of those years. If it wasn’t for the dividend I would have sold but this update sounds positive so maybe I will keep hoping.
SDI (LON:SDI) Farewell Mike Creedon, suddenly departed, albeit with thanks. You won’t be missed by me with your disingenuous share sales. Although they did accurately signal to get out last year - so perhaps I’m being harsh.
This should be a real positive for SDI (LON:SDI) one would expect Investor Meet Co’s to be a little less terse and irritable going forward which can only make the business more shareholder friendly.
I think you are being harsh BnB, Mike was the driving force behind SDI for the past 13 years. He pursued a successful buy and build strategy which resulted in the share price rising from 21p to touch a high of 200p in 2020 & 2021. It subsequently fell back after sales of their Atik cameras declined post Covid and was c80p before today’s news.
He was passionate about the company and engaged well with private investors. I recall his first visit to Mello in May 2019. I was their Room Monitor and before their presentation I said that I expected it would be popular. He didn’t believe me and it was only when the room was full to capacity and we had to lock the door to prevent more coming in that he realised the interest from pi’s. He came along to subsequent Mello’s and I appreciated his long-term engagement, it’s fairly rare in the small cap world. I appreciate that his share sales did cause angst amongst shareholders (& I’ve been one since 2018) but I’m not sure his motivation in running the business was always financial
I chose to sell my holding this morning as I was unhappy with the manner of his departure and that we were only told after the fact
Hi Astongirl. I did offer that I might be being harsh and you're probably right. I fully appreciate the company's growth story and I made a multi-bagging profit selling not far from the top - thanks to the clue offered by Mike's last share sale. My issue surrounds not the sale itself but his explanation for it. He flat out lied about his motivations. saying "I don't look at the share price". If he had just come clean I'd offer him more respect. But his blatant obfuscation wound me up.
I wonder why the abrupt departure. It usually signals high level discord and disagreements coming to a head. Sorry you chose to sell. I think shares look pretty good value down near 70p. A lot of the company's difficulties these last two years are reflecting a general malaise in biotech and life sciences that might be due to reverse. It would just be nice to know what the fallout is over. The next TU might a be a kitchen sink and bathroom cupboard affair under a new CEO!
Half year results out of City of London Investment (LON:CLIG) . I have a modest holding, having reduced the size about a year ago. This is the asset manager, not the investment trust.
In summary, assets under management pretty unchanged, earnings pretty unchanged, dividend unchanged. Modest cost reductions to come. I rate this as a strong hold but perhaps not quite a buy yet. XD 29 Feb, Divi 28 Mar. Still a very useful dividend into my retirement pot.
Client outflows have continued but that seems to be a theme of the fund management sector in general in the last quarter of last year. Based on similar PBT figures as last year maybe we can expect underlying diluted eps again of around 18p for the half year? (Although I think they may have a slightly higher tax charge this year). I don't think there's as pronounced effect in any H1/H2 split so let's say if markets are completely stable it might get similar result to last year of 36p. I think that looks good value at current share price for 10% dividend and with the upside to come of rebounding markets. (I hold).
The big unknown in the fund management sector is the rise of passives. Regulators keep piling costs on the sector, so unless you can show consistent outperformance, it is very difficult to keep profits growing. And tbh I look at the size of the UK stock market and the number of listed fund managers, and it seems like a sector that is over crowded. There will be winners and losers, but I suspect the active management sector as a whole is in structural decline.
Agree but in the short term at least they are like geared plays on market recovery so I think now is a great time to invest in them. The likes of e.g. CLIG/POLR are paying massive dividends while we wait for markets to recover.
RE:CLIG
The company has changed slightly in the last couple of years following the retriement of its long standing Chair. Their original concept of identifying discounts to NAV in Frontier and Emerging markets seems to be now less core to the business.
Have held for a number of years and the dividends received have covered the original purchase cost. No obvious reason to sell and continue to watch and hold.
City of London Investment (LON:CLIG) and Polar Capital Holdings (LON:POLR) are also likely to benefit from interest rate cuts
I have held clig for many years and poor fo a year
Comments on the decline of the uk stockmarket/ rise of passives make me move these from 'collect the divi and forget' to 'keep a weather eye' not least as the last thing fund managers will do is cut their own salaries to support profits.
On the plus side the rise of passives will increase the number and scale of market mispricings. So good for specialist competant (or lucky) fund managers and us.
If Graham could cast an eyeover City of London Investment (LON:CLIG) it would be appreciated by quite a few of us I'm sure. :-)