Small Cap Value Report (Mon 22 July 2024) - BKS, TSTL, FNX, ARC, ADVT, CSSG. Brief: GUS, BAR

Good morning, Paul & Graham here!
It's a clean sweep today, we covered everything, and mostly interesting companies too. So we'll sign off.
Let's hope the IT problem that caused so many problems globally on Friday has now been resolved, with prompt RNSs at 7am hopefully. Update: so far, so good!
Mello Monday starts 17:00 later today - details here. One of my favourite shares over the last couple of years, Cohort (LON:CHRT) is presenting. Having done so well, do the shares have further upside? I believe Richard Crow is on the BASH panel, he's always worth listening to. Also Vin Murria of AdvancedAdvT (LON:ADVT) is on!
Begbies Traynor (LON:BEG) - it's the quarterly Red Flag Alert Report - which is particularly gloomy this time, even by Begbies standards! There's been a considerable increase in companies classified as being in "significant financial distress". Especially in travel & tourism, hotels, health & education, and bar/restaurants. "Serious concerns" remain in construction, real estate, and support services sectors.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Some interesting stuff here! First published at 07:49, then updated throughout the morning.
Other mid-morning movers (with news)
Ryanair - thank you to readers who have pointed this out. Not a share I follow, but the newswire says shares have “tumbled” 18% in New York, on missing profit targets for April- June, and warning that fares for the key summer months would be “materially lower” than last year.
This has caused shockwaves in other travel shares today. No view from me, as I haven’t properly looked into it, just flagging the news.
Summaries
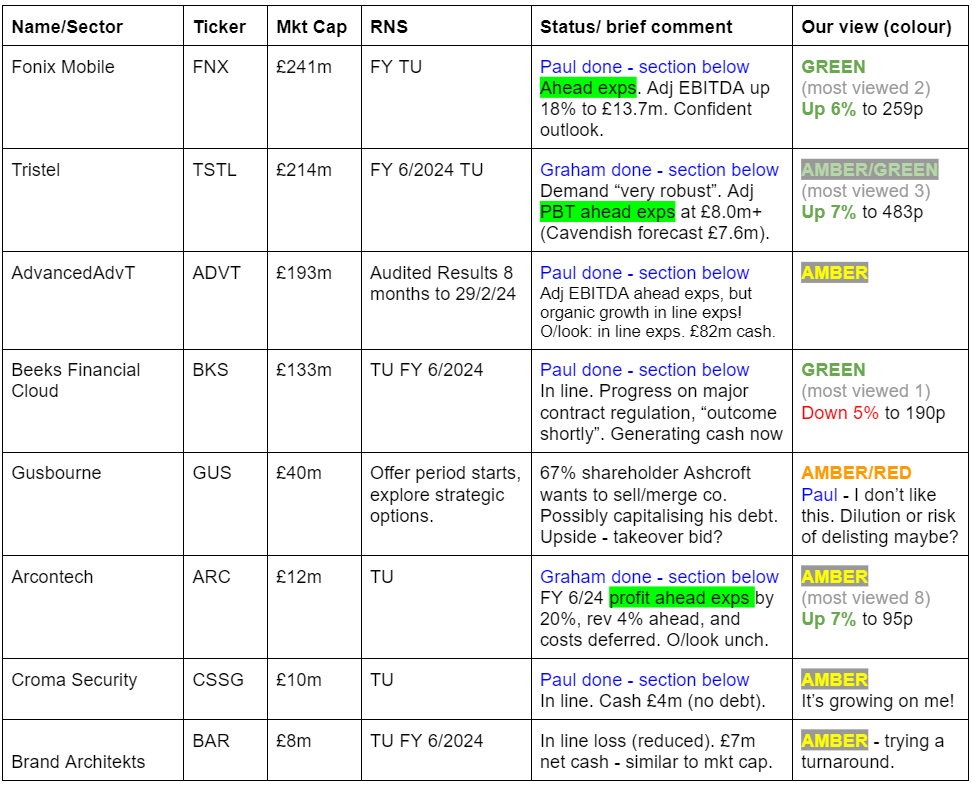
Beeks Financial Cloud (LON:BKS) [Paul holds] - down 6% to 190p (08:11) £125m - Trading Update - Paul - GREEN
FY 6/2024 trading in line (although a revenue miss). Claims to now be cash generative. Outlook comments strike me as encouraging, but the market seems to have done a bit of profit-taking this morning. I remain a bull - this seems an unusual high organic growth niche company with exciting prospects.
Tristel (LON:TSTL) - up 6% to 478.55p (£228m) - Trading Update - Graham - AMBER/GREEN
A very nice update as Tristel beats management and sell-side expectations on revenues, profits and cash. I take a few minutes to explore ways a company might be able to justify a very high valuation such as the one that Tristel has. I think Tristel might be able to do it, so I’m comfortable with AMBER/GREEN.
Fonix Mobile (LON:FNX) - up 7% to 261p (£258m) - FY 6/2024 Trading Update - Paul [ahead] - GREEN
Ahead of expectations flourish to end FY 6/2024. Cavendish raises 2025 forecasts a little, but says they're being conservative. Punchy rating, but I think this share is worth it. Intriguing possibilities from further international expansion, and a broadening of its UK services. A continuing thumbs up from me - I think it's worth the premium valuation.
Arcontech (LON:ARC) - up 5% to 93p (£12m) - Trading Update - Graham - AMBER
Customers have been using products more intensely than expected, giving a 4% boost to revenues and a 20% boost to adjusted PBT. However, there is no change to FY 2025 expectations so it may just be a temporary boost. With a cash pile covering about half the market cap, this may be worth studying.
AdvancedAdvT (LON:ADVT) - down 2% to 143p (£189m) - Accounts for 8 months to 29/2/2024 - Paul - AMBER
Quite complicated, due to acquisitions, a disposal, big cash pile, owning 9.8% of M&C Saatchi (LON:SAA), and a change of year end, so plenty to unpack there! I think it looks quite interesting, and more than half the market cap is backed by cash & SAA shares. We'll have to see what further acquisitions the forceful and experienced Vin Murria makes!
Croma Security Solutions (LON:CSSG) - unch 72.5p (£10m) - Trading Update [in line] - Paul - AMBER
Updating myself on the particulars here, I think risk has reduced (after a nice lump sum of cash received from the highly material disposal receivable), and rolling out a modestly profitable (but very small) operating business does have some attractions. I'm teetering on the brink of moving up to amber/green, but let's monitor events for a little while.
Paul’s Section:
Beeks Financial Cloud (LON:BKS) (Paul holds)
Down 6% to 190p (08:11) £125m - Trading Update - Paul - GREEN
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, provides an update on trading for the year ended 30 June 2024 (FY24).
I could be biased here, as for full disclosure, I have a small position in BKS personally (<1% of my portfolio, as I was hoping to buy more cheaper, but it went up instead of down!) and so far it’s a very good performer (up 90% YTD) on my top 20 share ideas for 2024.
Today’s update strikes me as reassuring, but not price sensitive either way. Key points -
FY 6/2024 trading has been in line -
“FY24 results are expected to be in line with consensus expectations, with Beeks having delivered significant double-digit growth on the prior year, driven by a strong performance across Beeks' Private, Proximity and Exchange Cloud offerings.
Growth - why do they give the percentages, but not the actual numbers? This wastes everyone’s time, having to look up and calculate the numbers -
“Beeks exited FY24 with approximately 18% growth in ACMRR in the year to £28.0m (30 June 2023: £23.8m). Revenue for FY24 is expected to be approximately 27% higher than FY23, delivering underlying EBITDA1 growth of over 27% and underlying profit before tax2 growth of approximately 67% versus FY23. “
Broker update - many thanks to Canaccord, whose note this morning fills in the gaps. EDIT - previous glitch with Research Tree has now been resolved.
Canaccord says for FY 6/2024 revenue was £28.4m (up 27%, and slightly faster growth in H2 than H1). However, this is £1.6m below Canaccord’s estimate of £30.0m revenues. So revenue looks a miss against Canaccord forecast.
EBITDA is a nonsense number here, so I’ll ignore that.
Underlying PBT is said to be up 67% vs FY 6/2023, which Canaccord says is £3.9m, slightly below its estimate of £4.1m.
Overall then, BKS says it’s in line with broker consensus, but it looks c.£0.2m below Canaccord’s estimated adj PBT.
That’s about 20 minutes wasted trying to piece that together. Clearer reporting is needed in future please, Beeks!
Accelerating growth - obviously the historical profit numbers at BKS are unexciting, but it’s a rapid growth company, so sceptical value investors are looking at all the wrong things! The excitement with Beeks is that its lengthy process of winning large contracts subsequently delivers increased revenues (“land and expand”), and a long-term, growing stream of recurring revenues. I particularly like the word “accelerated” in this paragraph -
“Significant wins secured in H2 FY24, including (as announced in March) the Johannesburg Stock Exchange's (JSE) Exchange Cloud Contract Extension and a Proximity Cloud Win with one of the world's largest banking groups, have contributed to Beeks' increasing levels of contracted, multi-year, recurring revenue, providing a strong basis for accelerated growth”
For a company that’s just grown revenue by 27% (organically), to be talking about accelerated future growth seems remarkable.
Cashflow - a question mark and food for the bears, has been BKS previous inability to generate free cashflow. I’m more relaxed about that, because many tech-based companies have to spend up-front, to then generate a long stream of recurring revenues. They need to reach a tipping point where increased scale means cashflow turns positive, and can then grow rapidly due to high growth, high margins, and a largely fixed infrastructure. That’s the hope here, and maybe hope is starting to turn into reality? Although I’d like to see the full numbers before drawing a firm conclusion. Today it says -
“In the second half of the year, Beeks continued to achieve a positive free cash flow position in line with management's previously stated strategy, with unaudited net cash of £6.58m at the period end, (H1 24: net cash of £5.44m; FY23: net cash of £4.41m) notwithstanding continued investment in Beeks' product offering.”
Big contract - this was already known, and is a key reason why BKS shares have done so well this year. I think investors are anticipating at least some of the upside from a large contract win, still in regulatory approvals stage. Rumour has it that this is related to New York’s stock exchanges. As I understand it, the figures for this contract have not yet been included in broker forecasts, and there could therefore be big upside if/when regulatory approval is achieved -
“As announced on 6 February 2024, Beeks conditionally secured a third Exchange Cloud contract with one of the largest exchanges globally (the "Exchange"). Completion of the contract with the Exchange is subject to regulatory approval, following which deployment of services and recognition of revenue will commence. Advanced progress has been made on this approval process, in line with expectations, and Beeks looks forward to updating shareholders on the outcome shortly.”
“shortly” is tantalising there!
Outlook - I think this bit below is quite bullish, but at the moment the market disagrees! -
“The Exchange Cloud pipeline continues to build, with advanced discussions taking place with other major Exchanges across the globe. Having signed a contract extension during FY24 to meet stronger than anticipated customer demand for the solution, the JSE is providing strong references to other potential customers of Exchange Cloud.
The conversion of Beeks' record pipeline across each of its offerings remains a core focus for FY25 and the new financial year has started promisingly, including the contracts already signed in FY24 for delivery and revenue in FY25.”
Paul’s opinion - I’m a little surprised shares have eased off today, dunno why - traders taking profits maybe? It seems to me this update is pretty good. BKS shares are difficult to value at this stage, as it’s rapidly growing, and we don’t know for sure what the numbers will look like when it reaches maturity. Growing revenues at close to 30%, organically, and with a major new contract going through regulatory checks (which is not yet baked into the forecasts) sounds an exciting set up to me.
It’s a mistake to value rapid growth companies on a PER basis, in my opinion. If you do that, you won’t invest in any of the fastest growing, and best companies! PER is for mature companies.
My view is that £125m market cap here looks good value for a rapid growth company that is building sticky recurring revenues globally, in an interesting niche.
Management has been open about their plan to rapidly grow the company, then sell it in due course.
So it’s a continuing thumbs up from me, but I have no idea what the shares should be valued at, the valuation methods used by the public and private markets for growth companies are a bit of mystery to me!
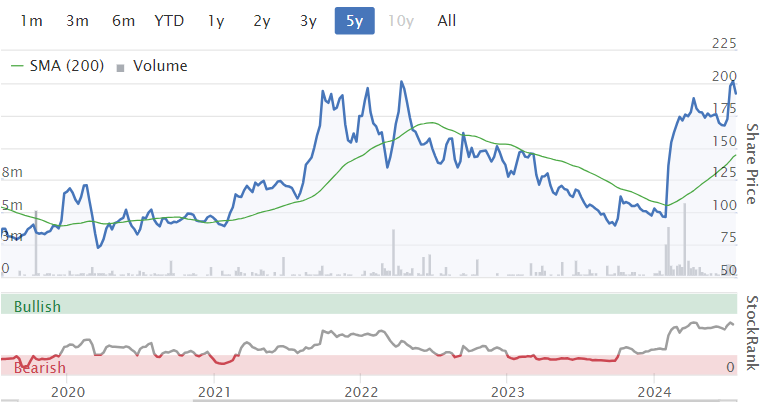
Can it punch through that 200p barrier in due course? I think it's possible if/when the big new contract gets regulatory approval. Downside risk obviously that regulators don't approve it.
Fonix Mobile (LON:FNX)
Up 7% to 261p (£258m) - FY 6/2024 Trading Update - Paul [ahead] - GREEN
Fonix Mobile plc, the mobile payments and messaging provider, is pleased to provide an update on trading for the year ended 30 June 2024 (the "Year").
The niche that Fonix seems to dominate in the UK (and growing in Ireland) is for phone/text/messaging for interactive TV shows - so think charity, reality TV, talent shows, competitions, etc, where audience participation is encouraged to either vote or donate. Fonix takes a fee from those revenues. Its systems have to be 100% reliable, as they have to cope with a deluge of transactions when a TV opens voting. Hence to clients, the fact that Fonix never goes wrong, means they stick with it, rather than shopping around for a better deal. That looks like a moat to me! But also brings risk if its systems ever were to be hacked or broken in some way.
One of my favourite companies, it’s another one that usually looks a bit too expensive, but it keeps performing well, so I’ve remained positive on the fundamentals.
Previously -
14/11/2023 - GREEN at 193p. Positive TU. Podcast mystery share!
24/01/2024 - GREEN at 225p. H1 TU marginal ahead exps.
1904/2024 - GREEN at 232p. I remain positive, despite Director selling.
FNX floated in Oct 2020, and hasn’t put a foot wrong, developing into a reliable growth company, high margin, sticky repeating revenues, cash generative, capital-light so it reliably pays out about ¾ of earnings as divis.
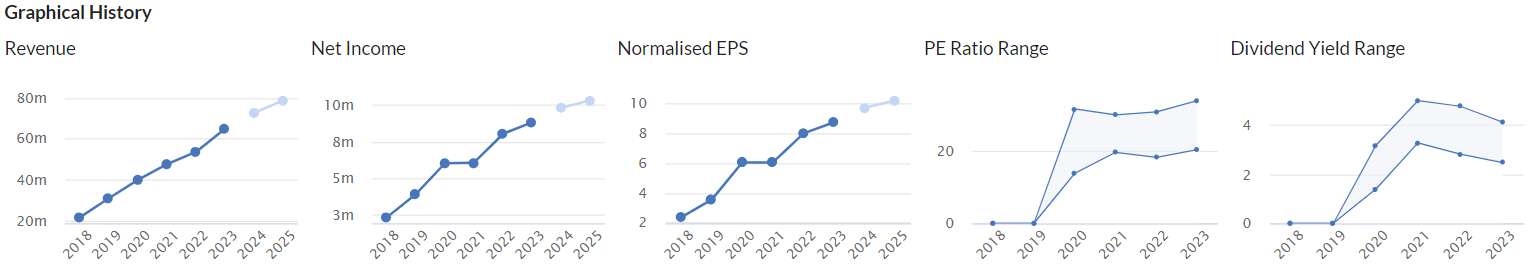
An impressive (organic) growth company - lots to like here -
Today’s update - is good news -
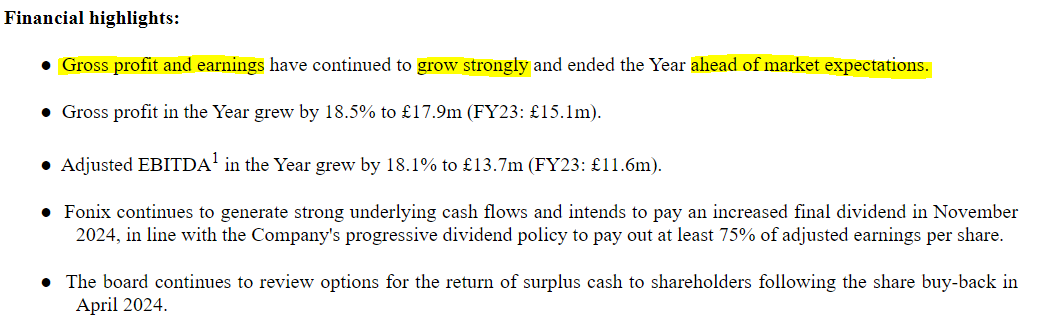
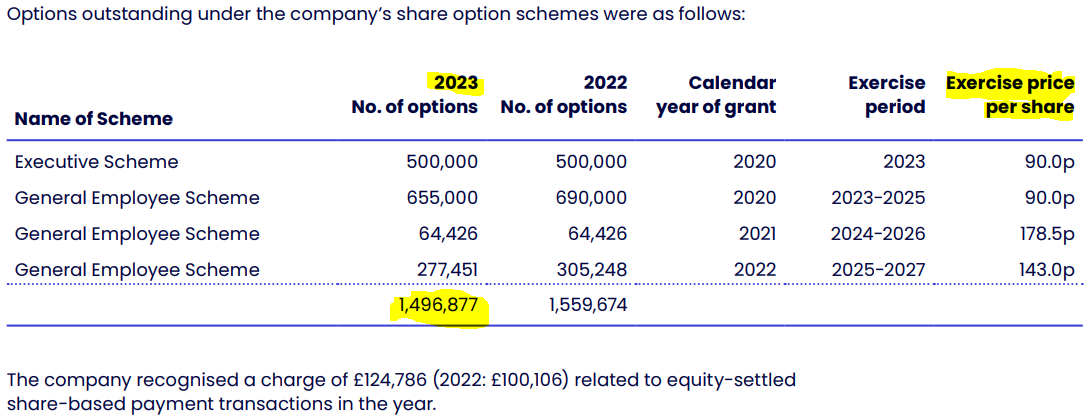
I like share buybacks at companies with no debt, and surplus cash. However, generally I’m only keen on buybacks when the shares are obviously cheap. That doesn’t seem the case here. Also buybacks can be a cover for generous share options. I’ll check that now actually. Rummaging through the RNS, it seems that FNX has indeed awarded shares from exercised share options from its treasury shares. However, the quantities of share options issued looks very reasonable to me -
“ the Company has now issued 1,904,174 options over shares since the Company's admission to the AIM in October 2020, of which 192,797 have subsequently lapsed, 127,557 have been exercised and 1,583,820 remain outstanding. The outstanding options represent 1.58 per cent. of the Company's issued share capital.”
Also note that the options are not nil cost. They seem to be issued with an exercise price set at the market price of the shares at the time of issue. So options only reward additional share price value created from the point of issue. This seems exemplary to me, if I've understood it correctly. From the 2023 Annual Report - modest dilution (on 100m existing shares), and at market value at time of issue -
Broker update - see Cavendish’s very helpful note today, they’ve upped FY 6/2025 adj diluted EPS from 10.2p to 10.6p, a punchy rating of 24.6x, but it says the upgrade is conservative, ie likely to be beaten, hence the actual PER might end up somewhat lower.
Outlook - I would have preferred a more specific confirmation about meeting market expectations for the new year FY 6/2025, especially since FNX enjoys reliable, repeating revenues.
Still, this all sounds interesting below, especially the bit about entering a new European market - does anyone know which country this is?
“The Board remains confident in Fonix's growth potential for FY25 and beyond, supported by high levels of recurring revenue with a strong run-rate, an expanded commercial offering, and significant opportunities for further international expansion…
"We are pleased to announce another year of robust profitable growth across our core markets and segments. We have continued to see strong underlying growth from our long-standing customers, alongside new income streams from recent client wins such as ITV and RTÉ, and new adjacent product offerings including live broadcast voting and online payment portals. Our expanded client base and product suite has not only generated new income sources but also enhanced our credibility and competitive edge in the market.
Looking ahead, we are making steady progress on our plans to enter a new territory in mainland Europe, with several TV and radio broadcasters lined up to trial services once we launch in the region. We are optimistic about starting to transact in this new market during FY25 and we hope to be able to give further details at the full results in September."
Paul’s opinion - it’s the same message as previously from me - terrific company, and shares are a bit pricey, but I do think the valuation is justified.
Further international expansion is potentially exciting too.
So yes, it’s a thumbs up from me. This just has that look of a company which is on a roll, and seems likely to keep delivering. That’s worth a premium price, in my view. The same message from all 3 of our main sections today, coincidentally.
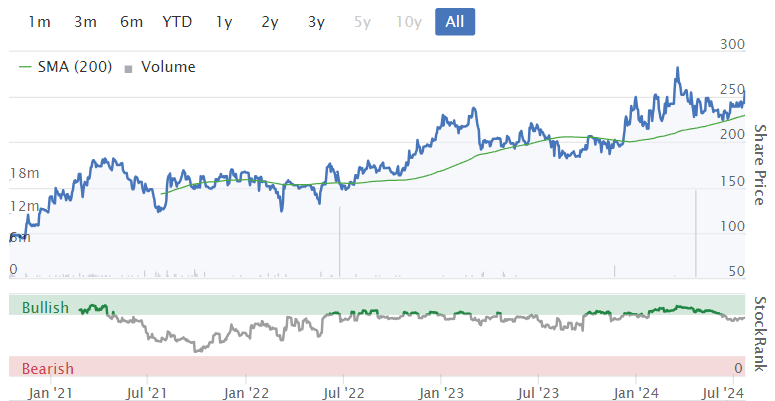
A good listing, and with generous divis paid too -
AdvancedAdvT (LON:ADVT)
Down 2% to 143p (£189m) - Accounts for 8 months to 29/2/2024 - Paul - AMBER
“AdvancedAdvT Limited (LSE: ADVT, "AdvT", the "Group"), the international software solutions provider for the business solutions, healthcare compliance, and human capital management sectors, has published its period end results for the eight months to 29 February 2024. “
This is a shortened year, due to a previously announced change of year end to Feb 2024.
It’s a special situation, being Vin Murria’s acquisition vehicle.
There are 4 elements to its valuation in my mind -
- Businesses already acquired,
- Another acquisition after the 2/2024 year end,
- Substantial cash pile, and
- 9.8% shareholding in M&C Saatchi (LON:SAA)
For our purposes here, it would take too long to plough through those various elements in detail.
Briefly though, the main things are £82.1m cash pile (and no debt) at 29/2/2024, c.43% of the current market cap, so highly material.
A small acquisition of £5m net cash cost was completed c.3 weeks ago, reducing cash to £77m.
It’s earning interest on the cash pile, with net finance income of £2.3m in the 8 months to 29/2/2024.
SAA shares have done well in the last year, rising from a low of 125p to 205p now. ADVT tried unsuccessfully to buy it, so the increased share price should have recouped the losses from wasted deal fees. That market price of ADVT’s holding in SAA is now £24.8m. Add that to the net cash, and it’s effectively got about £102m of cash and marketable shares in SAA combined. So you’re paying £87m for everything else - the operating companies bought so far. I’m not convinced that’s a bargain, but time will tell once we have a clearer picture of how trading is likely to progress. Investors are also arguably paying a Vin Murria premium, given her track record and high esteem.
It’s too early to analyse the trading numbers, since it’s had acquisitions, disposals, a £2.6m gain on the SAA shares, etc, so a lot of moving parts.
Outlook - in line -
"Current trading and outlook
Despite the significant macroeconomic uncertainty and disruption, we believe that the current environment will present numerous opportunities to develop the Group, both organically and by acquisition.
In the current financial year, which started on 1 March 2024, the Group has continued to make good progress and has secured a number of large, long-term contracts across both public sector and private sector customers. The improvement in performance of the four units has also continued. Overall, the Group is trading in line with the Board's expectation.
Paul’s opinion - too early to judge, but I’ll follow it with interest. It all depends what acquisitions are made using the cash pile.
Very nice asset backing for over half the share price, so it’s a comfortable AMBER for now. I definitely wouldn’t be betting against Vin Murria, that’s for sure!
EDIT: I've just seen that Vin Murria is presenting on Mello Monday tonight at 18:40, talking about ADVT!
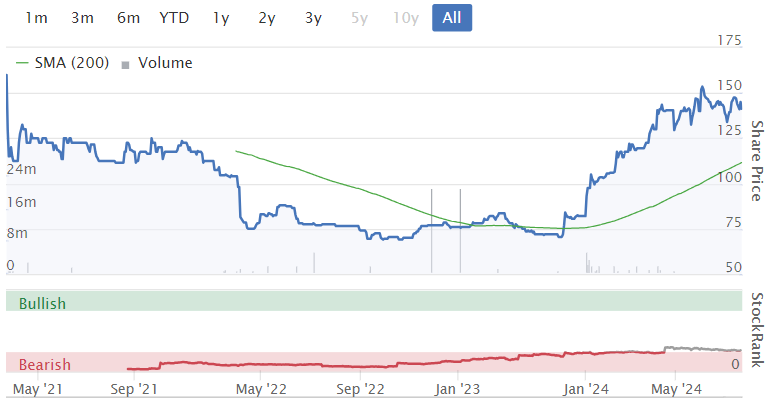
Relatively early days so far, and shares have recovered from earlier mis-steps and bear market -
Croma Security Solutions (LON:CSSG)
Unch 72.5p (£10m) - Trading Update [in line] - Paul - AMBER
Croma Security Solutions Group plc (AIM:CSSG) is pleased to announce the following update on trading for the twelve months to 30 June 2024.
Trading in line, but it doesn’t say what expectations are -
“During this period, the Company has traded well and continues to develop its security centre network, add new commercial clients and expand the security solutions the Group provides. As a result, Croma expects to report FY2024 results in-line with market expectations.”
Zeus helpfully shares their model with us, which has forecast £0.8m adj PBT for FY 6/2024, double the prior year. Sounds promising, but note all the increase has come from changes to the finance charge line. The adj operating profit (EBIT) line is unchanged Y-on-Y at £0.5m. So you need to avoid running away with a misconception that profit is soaring! (because it isn’t based on any change in operating profit)
This is a very small business, which offer fire & security, and locksmiths services. Only £8.6m forecast revenue in FY 6/2024, but at least it’s profitable, albeit very small for a listed business - is the listing really worth the hassle and cost? If they’ve got something good to roll-out, then maybe it could be? I’ve got an open mind.
This reminds me a little of React (LON:REAT) - a small business that is trying to expand, but struggling because it can’t get a high enough rating on its shares to be able to issue more for acquisitions. I put that question to REAT in a Mello webinar, and the reaction from management was priceless - the body language clearly showed I touched a raw nerve, whatever came out of their mouths in answering my question! But the fact REAT didn’t try to conceal their frustration is actually a positive to me.
Anyway, back to CSSG - what I like here is that it doesn’t need to issue new shares. There’s a sound balance sheet, and it can roll out these small locksmith & other services through its existing cash. Could be interesting. Although is there a big profit opportunity here? Surely these are usually one or two man bands, who enjoy being independent? What value can a group add? Or is this the next Timpsons in the making? Who can say?
Going back to my previous (brief) notes on CSSG here on 21/2/2024, the main issue was the highly material disposal, where the terms were payable in cash instalments by a startup - which in my experience frequently fail midway through the payment plan, after the first few payments have been made.
Today’s update reassures -
“In June 2023, the Group sold its manned guarding business Vigilant for £6.5 million, in order to focus on the Company's core businesses, Croma Locksmiths and Croma Fire & Security. As reported earlier this month, the Company received a cash payment of £1.76 million as part of the consideration for the sale of Vigilant with a further £3.48 million including interest to be received over the next 8 quarters. As at the date of this announcement, the Company has no borrowings and a cash position of £4.0 million.”
It’s moving in the right direction, but personally I would still put a hefty discount on the expected receivable, and plan for a default, so I can see how things work out if there is a default. 40% of the market cap is now net cash, that’s a nice position, no arguments over that! Risk is not prediction, remember, we have to think about all possible scenarios, and weight the valuation accordingly.
Outlook - sounds interesting -
“Croma's strategy remains focused on driving the core business as well as acquiring traditional locksmith stores and transforming them into modern security centres with stronger in-store product ranges and much greater profit potential. The Group boasts a strong balance sheet and there is a good pipeline of store acquisition opportunities to support the Group's ambitions to roll out its security centre network nationwide.
Roberto Fiorentino, Chief Executive Officer, commented: "We are pleased to have completed a successful year in what has been a challenging market environment. Looking ahead, we have a clear strategy together with the financial resources and management expertise to execute it. As a management team, we are therefore very focused on expanding our store presence and benefitting from the resulting growing economies of scale."
Paul’s opinion - not something I can get madly excited about, as rolling out a stores-based format takes a long time, and plenty can go wrong. That said, it’s starting from a good point - already profitable, and with a good balance sheet.
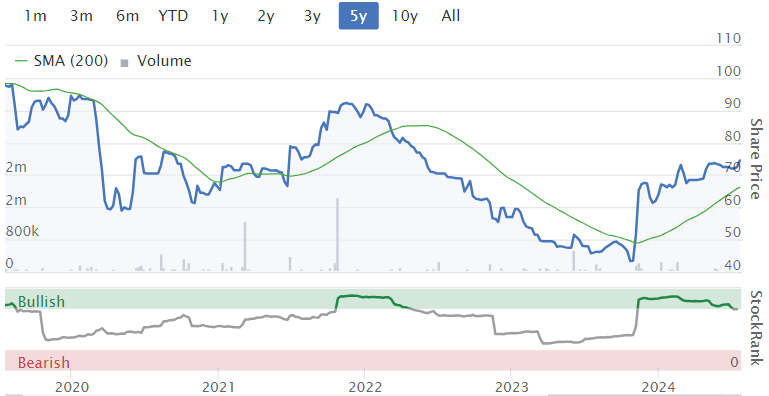
Probably priced about right for now, but as a long-term investment idea, I’ve seen many far worse ideas.
I’ll stick with AMBER for now, but if a few more instalments come in, and they can demonstrate good returns from new sites, then could see myself moving up a notch to amber/green in future. Let’s keep an eye on it - I know we have some bulls here already.
Have management done any webinars? If so, I'd be interested in observing the cut of their metaphorical jib. Overall best summed up as: I'm getting slightly interested!
Graham’s Section:
Tristel (LON:TSTL)
Up 6% to 478.55p (£228m) - Trading Update - Graham - AMBER/GREEN
Pleasant news:
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, announces a trading update for the year ended 30 June 2024, having delivered a strong trading performance ahead of market expectations and the Company's own performance targets.
I’m always a little paranoid now that a company might be referring to a previous beat of expectations, rather than a new beat of expectations.
However, that’s not the case here. There hasn’t been a trading update from Tristel since the half-year report published in February. The broker note from Cavendish confirms the extent of the outperformance:
Revenues up 16.4% to £41.9m (estimate: £40m)
Adj. PBT at least £8m (estimate: £7.6m) [this excludes the impact of share-based payments]
Cash £11.6m (estimate: £10.1m)
Share-based payments had a cost of over £1m in FY2023 so it will be worth checking their cost in FY2024.
CEO comment describes the company’s evolution:
"This is my last trading update before I hand over the reins to our incoming CEO…
"In June last year we achieved the major milestone of obtaining approval from the US Food and Drug Administration for our Tristel ULT disinfectant for ultrasound instruments. During the first half of FY 2024 we set up manufacture of the product with our North American partner…
“Tristel has become a leading global player in a specific niche of the global infection prevention industry: the decontamination of non-lumened heat sensitive medical devices. The niche sweeps up many of the diagnostic tools used in hospitals ranging from ultrasound probes to small endoscopes. Looking to the future, we are confident that we will also become a leading player in the hospital surface disinfection market with our unique chlorine dioxide chemistry. We are all very excited for the Company's future prospects."
Graham’s view
Congratulations to long-term holders. If you’ve been in this for the long haul, you’ve probably earned a fine return on your investment:
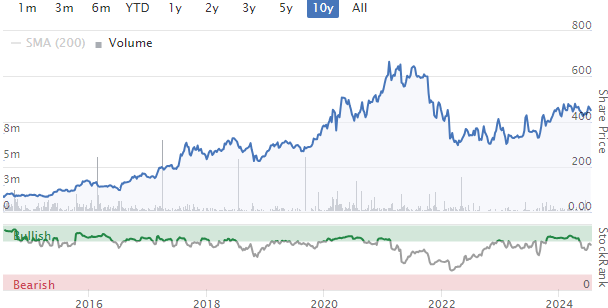
As we’ve said many times here - most recently from Paul in February - it might be tricky for value investors to justify the price here.
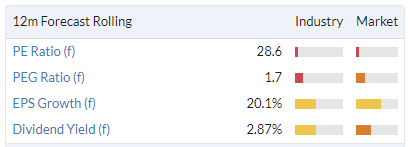
How to justify it? Well, I think it does require a bit more work than with the average stock.
For example, here’s how I would begin my Tristel studies.
To justify a high PE multiple, we’re going to need either a financial reason (e.g. operational leverage kicking in to boost profits in future years) or what we might call an economic reason (e.g. the company having a very strong competitive advantage.
Looking at Tristel, it seems plausible to me that there could be both financial and economic reasons to justify a high P/E multiple for it.
Financially, it earns a gross margin of 80%. And yet it currently converts over £40m of sales into just £8m of adj. PBT. Its profit margins have been steadily improving year-on-year, as more and more sales and gross profits get converted into bottom-line profits. If this continues, there is the potential for the bottom line to keep growing at a much faster rate than planned top-line growth of 10-15%.
Economically, the company claims to already be a leading player in one niche, and to have the potential for a similar achievement in another one.
This is where an investor benefits from industry knowledge, and this can also be the hardest part of investing.
If I run a search for “decontaminate heat sensitive medical devices”, Tristel doesn’t show up for me until page 4 on Google.
(If you do an even more specific search, “decontaminate non-lumened heat sensitive medical devices”, Tristel is the #1 result for me in Google.)
Most of the search results are non-commercial. Others are specific to dental devices. A company that does show up for me and that may be a genuine competitor is STERIS.
A little bit more googling on STERIS provides me with a list of companies active in ultrasound probe disinfection, including both STERIS and Tristel.
In this way, little by little, we can build up our knowledge of an industry. Who are the competitors, and on what basis do they compete?
One sign of a company with a competitive advantage is a high market share - and I love to find and to invest in companies with a high market share (e.g. I own the likes of IGG and RMV). Does anyone know if Tristel has published market share numbers for any of its products?
Overall, I’m happy to leave our AMBER/GREEN stance on Tristel due to its long track record of profitability and seemingly excellent prospects for the future. I wouldn’t personally be willing to pay this rating for it, but I also think it deserves something more than a neutral stance. So I’m glad we expanded our colour coding system!
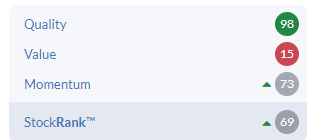
The StockRank system also notices the quality and the momentum here, while being wary of the limited value on offer:
Arcontech (LON:ARC)
Up 5% to 93p (£12m) - Trading Update - Graham - AMBER
We don’t very often see companies at this market cap that are consistently profitable but that is the case with Arcontech:
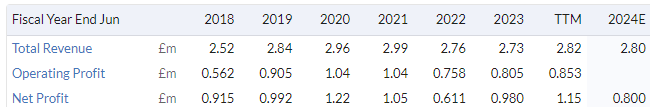
It even pays a rising dividend:
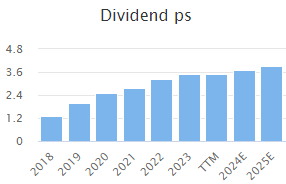
Today’s update is short and sweet.
Arcontech (AIM: ARC), the provider of products and services for real-time financial market data processing and trading announces that for the year ended 30 June 2024 (FY24) turnover is expected to be ahead of market expectations by approximately 4% as result of increased use of product by certain customers, whilst adjusted profit before tax is expected to be ahead by approximately 20%, as a result of the aforementioned increased product usage and certain planned staff costs only being incurred at the end of the financial year (FY24).
Expectations for the current financial year (FY25) remain unchanged.
So investors can get excited, but not too excited: the company is not extrapolating increased customer activity out to future years.
Graham’s view
Paul gave Arcontech’s interim results a quick review in February, noting that the company had net cash of £5.7m. That leaves a tiny enterprise value but it’s also fair to point out that the company has seen very limited growth over the years. For a software company, that’s a worry - the phrase “if you’re not growing, you’re dying” often applies.
According to the StockReport, revenues were only supposed to grow by 2.5% this year, prior to today’s update. With a 4% beat on expectations, that suggests we still have a single-digit growth rate - not bad, but investors often look for more.
At the same time, I don’t want to downplay the company’s 20% beat on profitability. And it’s no mean feat to achieve profitability for so many years at this end of the nano-cap market.
As you can tell, I can’t quite make my mind up on this one. Perhaps I could go AMBER/GREEN, but the £12m market cap is also a worry; anything below £10m I now consider to be high-risk due to illiquidity and the delisting risk. Arcontech is almost at the limit of market cap respectability.
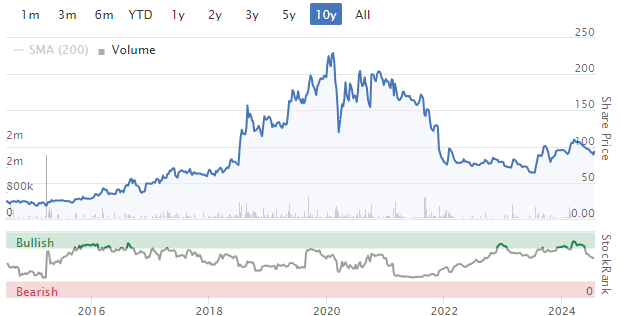
I acknowledge that this is paradoxical. We should be getting more interested in companies as they get cheaper, not less interested! But I do think that listing costs and liquidity become factors at certain levels.
I’m leaving a neutral stance on this one: an interesting value play with some impressive features, but there are also some reasonable grounds for concern.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
Can't believe it. Been following Card Factory (LON:CARD) like a hawk waiting for the Teleios sell out news. Of course I'm travelling to Canada when it happens and I only find out after the bell. I imagine it will open up another chunk up tomorrow morning and the easy money will be gone! Oh well, that's the game!
AdvancedAdvT (LON:ADVT)
One of my personal Bete Noires is Group Companies changing their accounting year end date.
Maybe there are good reason but in my view for acquisitions it is the role of an acquired entity to change its accounting year end date to line up with the Group Company's and not vice versa. This maintains a consistency of approach which gives you some hope of understanding what underlying performance is.
For me a Group change of year end date is a trigger to wonder whether they are just trying to veil some weighting of the accounts period to enable them to present a better picture than would ordinarily be the case. That way a later longer period will hopefully open the opportunity for business to improve, and perhaps skate over an underwhelming quarter's periods trade or so. It could also allows an acquisitive outfit to hope to make another later acquisition which may further change an observers view of either topline or bottom line growth, along with the other adjustments that are typically made in today's business environment. It can of course work both ways as to shortening or lengthening the end date, depending on where a perceived duff trading period, might be.
A prime example of this used to be K3 Business Technology (LON:KBT) who messed around with theirs on more than one occasion both in their earlier days, and then again much later on. Coincidentally, a prior CEO of KBT went on to be employed in a subsidiary of Vin Murria's last successful business, though I doubt a canny VM needs any lessons on any presentational matters.
Within the accounts report it says the year end was chosen to fit in with AIM requirements. But I have no idea what that means, and it is not explained, so it could mean anything. An AIM business usually has to report to the market in a 3 mth period following its year end date.
I think the Company is a British Virgin Islands registered company, and if that is right, it is not bound by the takeover code.
It will on that basis take a while I believe to see where this VM vehicle will go.
I hear what you're saying, and I know myself that I once changed a year end in order to save a business where I was CFO from collapse - I came up with the bright idea of moving the year end from 30 Sept to 31 Jan, which made a 16-month period that included 2 Xmas trading periods. The numpties at the bank (this was in the 1990s) didn't notice, and I saved over 1,000 jobs with that spontaneous decision.
So yes, year end changes can be a warning sign.
However, I also think that auditors have bottle necks now. So you can get your audit done cheaper, and faster, if you move your year end from Dec to say May or July, It can be sensible.
Vin Murria explained this on Mello a couple of months back, when the first aquisitions had been formed into the company and it started to operate. - around 3 months or so in.
Important to remember this was a cash shell that could have purchased / acquired anything, is this not just setting up the new company?
The explanation provided was that given most of the recurring client base are government organisations she altered the year end to match customer annual budgets. Im guessing this provides forward visibility and guidance on a good chunk of revenue that can go into year end reports.
Yes agree auditors are a bit tight for resource so a discount can be sought for a change of date. Its just that the statement in the report doesn't mention this or the Govt contract end dates also referenced below as a reason.
I may be making too much of it in the short term. We'll wait and see I guess!
Don't AIM companies have 6 months to report? Main market I thought was 4. Been out of the reporting role so forgetting rapidly!
Croma
Looks ok to ne Im a reasonably long term holder .
Managrment have a simple plan rhat they have executed on time .
Being of limited brainpower I tend to apply the acid test “would I buy this busiiness” .
4 million quid Now with a promise of 3 more
Plus freeholds and stock Im guessing at 2-3 million
Making 500k now to 1 million
In a fairly stable market .
Looks ok to me though Id suggest the managrment are a bit too well paid but not offendively so .
Id buy thar company and let it run.
For sure better investments going fo make you more money out there .
But this is a Dennis Irwin / Norman Hunter share not a Ronaldo / Maradona .
Palace Capital (LON:PCA)
Waiting for the funds from the tender offer to reach my ISA, but in the meantime I see that Christopher Mills and his North Atlantic Smaller Companies Investment Trust (LON:NAS) has increased its holding to 8.4% from 6.3%. Interesting!
Jonno- I did not tender any of my holding. There is value in PCA- need NAS and Peter Gyllenhammar to push the board to act a bit faster.
Hi Charles
Fair play to you. I tendered the 23%, I still have a reasonable holding relative to the size of my portfolio, but wanted the cash to provide some flexibility as I operate exclusively within my ISA.
Just a reminder with one hour to go......We have a great Mello Monday show lined up for tonight and very topical as Vin Murria is back with us presenting the AdvancedAdvT results that have just been released this morning. The BASH should be interesting with Richard Crow aka Cockney Rebel and Alan Charlton on the panel. We will also look closely at the Renold situation on the BASH as it has been a popular company since we analysed them.
Join us for a jam-packed MelloMonday on Monday 22nd July 2024, at 5:00pm. The programme for the evening is as follows:
5:00pm Paul Hill presents "Investing in turnarounds”
5:30pm Company presentation from True Royalty
6:10pm Company presentation from Cohort plc
6:40pm Vin Murria presents AdvancedAdvT Limited results
7:00pm Company presentation from Time To ACT plc
7:30pm BASH Panel with Richard Crow and Alan Charlton
For more information, click here: https://melloevents.com/mm220724/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1317444
*EXTENDED ANNUAL PASS OFFER* Get 20% OFF our Spring Annual Pass (May 2024 - Apr 2025) with the code APJULY20 https://tickettailor.com/events/melloeventslimited/1245910…
Just a reminder re Card Factory (LON:CARD) . Edison FC 14.4p EPS for 2025 so even with todays SP move we are just over a PE of 7. If it re-rated to say 11 we'd be back up to 158p which I don't think is unreasonable.
Card Factory (LON:CARD)
Looking at the RNS for Card Factory this pm have Teleios just dumped the remainder of their position?
Stockopedia | Card Factory PLC - Holding(s) in Company | Card Factory News (CARD)
EDIT Sorry just seen thread below - news only just reached Norfolk.....
I know that Paul is not well disposed towards marketing companies (SCVR June 17 2024)but I hold Brave Bison (LON:BBSN) and, while i am pleased to see the14.8% rise today, I have to admit that the revenue growth that we saw last year is certainly much more subdued now, with a "second half weighting " statement to keep our hopes up. The Green brothers focus on the marketing opportunities in social media are a strong USP, and the increases in cash and profitability are welcome, but the return of top line growth will be a key question for the second half.
Hi Aislabie,
Thanks for mentioning Brave Bison (LON:BBSN)
I saw it rose 13% today, but I've logged off for today, so didn't round to reviewing it, sorry about that.
You said -
"I know that Paul is not well disposed towards marketing companies (SCVR June 17 2024).."
I read that, and thought to myself, that sounds wrong. Sure enough, on checking our archives, I was GREEN on BBSN here on 25/1/2024, and Graham was also GREEN on 13/5/2024.
So please can we set the record straight, that the SCVRs have been positive towards BBSN, and not negative as you suggest.
This type of thing is really frustrating for me. I respect your views normally, but would you mind fact-checking via my summary spreadsheet here, before posting, which is deliberately open to anyone, so you can see what we actually said, rather than incorrect recollections.
Thanks! Paul.
I am happy to apologise that I have got the wrong end of the stick here and I acknowledge your positive notes on BBSN. Which I am pleased about, even though as my own comments show , I am now a little bit wary about growth! My general comment, rather than BBSN specifically , stemmed from past notes, such this from September last year , which suggested something less than enthusiasm for this area of the market.
“Digitalbox (LON:DBOX) - 3.75p (£4m) - Trading Update - Paul - AMBER/RED
Worrying comments from this nanocap digital advertising business, about damaging actions taken by Google/Facebook. I think this serves as a good warning to steer well clear of all the digital advertising businesses, such as XLMedia (LON:XLM) , Tremor International(LON:TRMR) , LBG Media (LON:LBG) and others. They're not in control of their own business models in my view, and look like accidents waiting to happen.”
We also jousted before on Team Internet (LON:TIG) (nee Centralnic) and I conceded a score line of “Paul 1 : Aislabie 0” , as the share price fell, but I am pleased to note that since then TIG have pulled back a couple of goals! So we wait on the August 12th announcement of the first half to see if I can pull ahead.
Others have said it, but I very much appreciate your great effort on these daily reports and the regular podcast, thank you.
In the weekend FT 'Money' section Lord Lee writes a good piece "Three ideas to boost the UK's investment culture'. First is the need for financial education about the stock markets in schools, the third is the suggestion to restrict ISA investments in the future to UK listed companies. But the second gets my vote, the complaint that there is no television coverage of the UK stock market whatsoever. Many of us watch CNBC and Bloomberg but it is so USA centric (and as a consequence thoughts can turn to Wall St when investing). Given Paul Scott is a natural entertainer and smart analyst he is surely the perfect presenter? Let's hope someone at Sky is thinking along the same lines! https://www.ft.com/content/2ae...
Thanks for the compliments Toad1957, but no thanks! It sounds a horrific idea!! (although strangely tantalising - it's the sort of thing I would probably agree to over a lavish dinner, and then launch on a wave of optimism, before collapsing into acrimony within days. That's what usually happens with projects I get sucked into LOL!)
EDIT: making it all the more remarkable that Stockopedia have put up with me for 12 years!
Hence why now I just do monologues on the podcasts, it's better that way. People either like them, or they don't, and I don't give a rusty Austin Allegro (as the rhyming slang goes) either way.
I fear you cannot thrust stuff like this down kids throats - i suspect most kids who are interested in stuff like this would probaably say - you must be mad investing in uk stocks when us has this return on tesla/apple/nvidia and crypto has that return al of which detroys uk stock returns.
Not sure even i would be for forcing or bribing people to buy british either - is that not kinda anti market forces. If we pump up temporarily on one off fashion the price of uk popular uk stocks as there is limited options is that not likely to unravel at some stage ?
When I arrived in South Africa for an assignment almost 20 years ago, I was surprised that a music channel gave the gold and dollar prices in the breakfast show. All we get here are a couple of slots on the Today programme.
I think it was Moira O'Neil who has done a couple of articles in FT money in recent years with ideas on how to get children interested in investing, including the silver screen.
What we need are some new finance based films more along the lines of The Big Short than Wolf of Wall Street.
Since Eddie Murphy is revisiting his 1980's offering, perhaps he'll be open to a 2020's version of Trading Places?
I used to like a money programme that used to be on tv at midday and I think it was called 'Working Lunch' presented by Adrian Chiles who was very good. In fact he was a better, more humble football presenter as well than who we have now, who think they are God in all things.
Who remembers "Show me the Money" on channel4? Even had everyone's favourite miserable git Tom Winnifrith on.
Probably launching it right at the height of the dot-com bubble should have been a warning the top was in, but I was buying as much loss making junk as the contestants at the time. The bear market following was a doozy, 3 year mental disintegration.
Card Factory (LON:CARD) Teleios all out
Card Factory (LON:CARD) I can't see the RNS. Where are you looking please?
https://newsfile.refinitiv.com...
Card Factory (LON:CARD)
https://www.investegate.co.uk/...
Card Factory (LON:CARD) - yep 9.9% down to zero.
Says two things (1) overhang is gone and (2) as this wasn’t done as an announced secondary placing suggests new/increased institutional ownership which should be supportive.
Let’s see if this draws investors back in
Initial reaction - I'm in! 20% bounce I reckon.
No hang on, this needs more caution. Let's give it some thought. Leave it with me.
Intriguing comment Paul?
Looks like Teleios Capital Partners out of Card Factory (LON:CARD)
on 18th so must have been an off market transfer? Hasn't shown up on volume
Beat me to it Wolf! Just bought another 5k's worth and hoping for a quick boiinngggg!!!!
We all like a quick boiinngggg, Gimmers
Still plenty shares available. Maybe holding a few under 3% still.
I thought when stated 0% that mesant zero-not less than 3%. But no expert on the TR-1 form
So did I, would normally say below 3% wouldn't it
Yes, youre probably correct, they'd normally say under 3%. Someone's happy to reload the offer for now even with all the buying.
Amazing it's taken over a year for them to shift 20%
Now let's see who the buyer is! Card Factory (LON:CARD)
Presume we will see the buyers RNS this week as even if they went to an existing holder it will have crossed a threshold somewhere. Nice piece of good news for holders. GLA
Fantastic! Let the rerate begin! Card Factory (LON:CARD)
Card Factory (LON:CARD)
Have been adding a few of late. I wonder who has bought out Telios? Funny enough Richard Crow suggested a few weeks ago that someone would buy out the Telios stake. Fair play to Richard he is a very astute investor.
All being well the share price should re-rate. It will never attract a high rating but providing trading is in line., a PE of 10 should be readily achievable.
Time will tell.
Card Factory (LON:CARD) Wolf Thank you for your post. This was on my Waiting to Buy list, the required event being that Teleios had sold out. I have just bought some as an opening position, and will buy more if the price continues to rise.
British stocks set for a boost
https://x.com/MoneyWeek/status...
"Carpetright is set to be saved from collapse by rival flooring retailer Tapi but hundreds of its shops are expected to close, putting many jobs at risk.
Tapi Carpets & Floors is expected to buy the Carpetright brand name, the company's intellectual property, two warehouses and 54 stores.
Jeevan Karir, managing director of Tapi, said that initially it had wanted to save all of Carpetright, but it "quickly established saving the entire business was unviable"."
Source: BBC https://www.bbc.co.uk/news/art...
Loungers (LON:LGRS) continues to expand (I Hold) "Loungers has opened its largest Lounge to date, Ritorno Lounge in Bristol. It says the unit ‘makes quite an impact on Bristol’s iconic Harbourside with an outside terrace overlooking Pero’s Bridge, a 10.5-metre-long feature bar, huge mural paying homage to Lounges across the UK and, in a first for Lounges, its very own private dining room.’"
Sods law in action, Ryanair Holdings (ISE:RYA) give a bad trading update and drops 1%
easyJet (LON:EZJ) drops 8%
Well Jet2 (LON:JET2) is down 6% and the company announced excellent prelims last week with a 34% increase in the final dividend. Also unlike Ryan Air, the company operates Airbus and not Boeing aircraft and has been ahead of the curve in acquiring/ordering new aircraft.
Jet2 (LON:JET2) has the best customer service reviews in its field by far and adept management. A quality company that is just the wrong price, despite its cyclicality, in my opinion.
Just goes to show how fickle and at times how bonkers the market is, which ultimately creates opportunities for patient investors.
Jet2 (LON:JET2)
With big companies we have to understand that a news event here might cause brokers to downgrade earnings on similar companies we hold. I dont know to what extent this happens ??- but if brokers are looking at the news today and see some cross contamination surely they might downgrade Jet2 somewhat.
Note the price reduction today is simply reversal/part reversaL of increase since last update.
So practicably speaking price since last numbers update has gone nowhere so no surprise that bad news from Ryanair has simply removed the "recent froth".
will be intersting to see if there are any downgrades to Jet2 or not.
To point out Jet2 has over 100 Boeing aircraft in fleet. Mainly 737-800, but also a few golden oldies, 737-300 and 757, all fantastic aircraft and one of key reasons Jet2 has been successful up until now.
Jet2 (LON:JET2)
Jonno may have ben referring to these specific points made by Ryanair here
We expect European short-haul capacity to remain constrained for some years as A320 operators work throughsignificant P&W engine repairs, OEMs struggle with delivery backlogs, and airline consolidation continues,including Lufthansa’srecently approved takeover of ITA (Italy), IAG’s delayed takeover of Air Europa (Spain)and the upcoming sale of TAP (Portugal). These capacity constraints, combined with our significant unit costadvantage, a strong balance sheet, low-cost aircraft orders and industry leading OTP, will underpin a decadeof low-fare profitable growth to 300m passengers by FY34.
not sure if this is some sort of point scoring excercise (perhaps o'leary needs to get into f1 if that is the case) on behalf of boing or not if they are Boing disciples - so whilst not being sure of the exact the implications the fact Jet2 have the firm delivery stream of 146 new aircraft turning up hopefully ensures they are decently placed if there may be problems for others who dont have firm orders booked already?
if nothing else perhaps it does evidence that their large order of aircraft for which they will need to find wonga is hopefully a sensible cunning plan if supply is constrained as the comments above suggest . I note some here were worried committment to buy might be too risky (if cash pile goes and is replaced by debt) - i for one have zero concerns though if they are getting list price discounts i have seen mentioned and are buying on tick surely there is opportunity to sell planes if needs be if they may not be needed. Is owning outright not more flexible than leasing where there may not be the exact same flexibility to sell perhaps (without perhaps being stung for fees)?
Jet2 (LON:JET2)
Orval makes a fair point, but my reference was principally to the extract below taken from the recent prelims.
"Looking Ahead
I am extremely pleased with how our Leisure Travel business has performed in the two years since the pandemic. Not only have we capitalised on the growth opportunities presented, with the business having nearly doubled its pre-Covid revenue, we have also remained true to our values of carefully investing to secure our long-term growth aspirations, whilst ensuring we maintain financial stability and flexibility.
With this in mind, and demonstrating our confidence in our future growth plans, we recently exercised the remaining 36 purchase rights of our Airbus aircraft order originally announced in late 2021, meaning we now have a firm delivery stream of 146 A321neo aircraft through to 2035. This valuable long-term order provides favourable operating cost efficiencies and enables us to confidently plan for the long-term as we continue to expand our footprint and the range of new and exciting destinations, ensuring we can continue to delight our Customers for years to come. In addition, our People, Service, Profits philosophy is timeless and actively guides our engagement with our most valuable asset, our Colleagues. Combined, these qualities provide a strong foundation to continue on our exciting journey in delivering on our long-term strategy, To be the UK's Leading and Best Leisure Travel business."
NewInvestor- strange given Easyjet has a strong holiday element as well as flights. I have bought more on the drop.
Definitely out of favour sector still since the pandemic even with today's Ryanair Holdings (ISE:RYA) news.A pandemic discount similar to the Chinese megacap shares discount to us peers perhaps.
Ryanair is down 14.59% in Dublin
Gusbourne (LON:GUS) Paul, neither do I ! Both listed English wine companies now in "offer periods" . I hold GUS and Chapel Down (LON:CDGP) . GUS has quite a lot of debt compared with CDGP and Ashcroft wants his £20m debt back. I am tempted to sell GUS. I am hoping CDGP will ask shareholders for the money to build the new facility rather than selling out to an overseas buyer.
The dynamics of the wine trade are interesting. You need to be a specialist or a supermarket.
In the uk it seems that producers need to be supermarkets and sell to a price. Gusbourne (LON:GUS) is small but not quite a specialist. Pricey but not got the cachet. Not sure we will get a really high end uk specialist producer for a while. Chapel Down (LON:CDGP) is a mass producer to supermarkets but also has a kits coty line that has won a number of awards. I wish more uk investors would take a long term view on them ( I hold).
And wine merchants need to be specialists. I was a big fan of Naked Wines (LON:WINE) when they were a specialist. They (in my opinion) are still too big. There are a fair number of specialists out there ( dbm and vine trail in Bristol). You cannot compete on price with a supermarket. So don't.
Andrew- I am assuming your in Bristol- this is an interesting Bristol wine importer from Portugal-by boat ! https://xistowines.co.uk/
Thank you. I must try some of their reds.
Let's be honest! Their wine is rubbish, and costs maybe 3-4x French, Spanish, or Chilean (or Co-op or Tesco).
This is why Ashcroft & all the other investors want out. No return! They want to pass on their bad investments to some new mugs!
NB don't be that new mug!
Let's be honest! Their wine is rubbish, and costs maybe 3-4x French, Spanish, or Chilean (or Co-op or Tesco).
This is why Ashcroft & all the other investors want out. No return! They want to pass on their bad investments to some new mugs!
I’m sorry Paul, but this is just nonsense. You’re conflating two totally different things; the quality of the wine and the quality of the investment. Only idiots invest in wineries, the clever money drinks the best products. Taste buds are funny things and taste in wine is no different to taste in most other things. Most people that have taste buds and enjoy wine acknowledge that English sparkling wines are amongst the best available.
Paul, I think Adobe might be casting its net for subscribers as this has also happened to me.
Re Research Tree technical glitch - has now been resolved, I've been emailing them & had this confirmed a little while ago, so we don't need to do anything, or update our systems, etc.
We have a great Mello Monday show lined up for tonight and very topical as Vin Murria is back with us presenting the AdvancedAdvT results that have just been released this morning. The BASH should be interesting too
Join us for a jam-packed MelloMonday on Monday 22nd July 2024, at 5:00pm. The programme for the evening is as follows:
5:00pm Paul Hill presents "Investing in turnarounds”
5:30pm Company presentation from True Royalty
6:10pm Company presentation from Cohort plc
6:40pm Vin Murria presents AdvancedAdvT Limited results
7:00pm Company presentation from Time To ACT plc
7:30pm BASH Panel with Richard Crow and Alan Charlton
For more information, click here: https://melloevents.com/mm220724/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1317444
*EXTENDED ANNUAL PASS OFFER* Get 20% OFF our Spring Annual Pass (May 2024 - Apr 2025) with the code APJULY20 https://tickettailor.com/events/melloeventslimited/1245910…
Hi David, no mention of Renold (LON:RNO) ? I guess they didn't accept your offer to provide further detail on the recently created management performance share packages? Thanks
Renold management unavailable but we will probably discuss the situation post results on the BASH
Beeks Financial Cloud (LON:BKS)
As I suspected there was no new price sensitive news. A few traders bailing out first thing has just brought buyers back to the table and price recovered nicely. For me that is a strong bullish signal. The initial drop was unsurprising given this was a tip in Justin Waites new newsletter and had clearly been trading up on potential news.
Takeaways for me are
Investment thesis holding up well imo. Happy with the trajectory
Beeks Financial Cloud (LON:BKS) "The initial drop was unsurprising given this was a tip in Justin Waites new newsletter and had clearly been trading up on potential news."
He has a newsletter? Lol Anyone wanting to learn about investor psychology during a bear market should watch all his vox videos starting end 2021 to 2023. Its a video diary of what not to do.
Beeks Financial Cloud (LON:BKS)
For a company that’s just grown revenue by 27% (organically), to be talking about accelerated future growth seems remarkable.
Hmmmm what do they mean by accelerated growth ? - if sales grow £5 mill this year and £6 mill next year could that qualify as accelerated even if the % is reducing. Not saying i dont trust any company not to use sketchy wording but i dont trust most companies not to use sketchy wording.
It looks like various travel stocks are down based on Ryanair Holdings (ISE:RYA) Q1 update: https://newsfile.refinitiv.com...
In a nutshell, average fare down considerably despite costs rising.
I hold both On Beach group (LON:OTB) & Jet2 (LON:JET2)
Despite my positive view on Jet2 (LON:JET2) I have sold out today, with a view of buying in cheaper in a few months time as I've seen the news from Duke Capital (LON:DUKE) which has been on my radar and I see better prospects short term here.
Puzzled with the fall of On Beach group (LON:OTB) today, as the Ryanair Holdings (ISE:RYA) update is actually positive for OTB.
Ryanair states that passenger volumes in Q1 (Apr-Jun) are up +10%, but revenue per passenger was down like -10%.
They also state that the outlook for Q2/summer is good in terms of passenger volume growth continuing. But ticket prices still very soft.
This is actually good for package providers like OTB because:
So far all TUs from airlines, the passenger volume updates from UK airports, the lack of strike action this summer, the terrible weather, the extra money in pockets since Apr24... all point to an outstanding result from OTB come end Aug, early Sep.
I would have topped up some more today on the fall, but I'm already at my max position for OTB in my portfolio.
(I hold in the Boon Fund)
Morning Graham, I know you have Tristel on your list but I thought I'd make an early comment. My largest holding btw. What I find interesting about the trading update is the fact that it implies the growth has not come from the US - but that all the signs point to the US taking off. Think Tristel could be in breakout mode. Paul's always called this as expensive but if the above is true it may be "expensive" for a good reason.
Hi Berksbee,
Yes I agree with you comment on Tristel (LON:TSTL) . I wrote the early snapshot comment in the list above, on a quick skim of its update this morning, and was impressed. The growth is indeed impressive, and upbeat commentary points to continuing decent growth.
As regards the US, it will be interesting to see what sales are achieved on an ongoing, repeat basis. Sounds like the initial sales are for stocking up purposes.
As you say, I've always complained TSTL shares look expensive (which they still do), but have overall been positive on the shares, eg AMBER/GREEN most recently on 26/2/2024, and 19/12/2023, although I wobbled to AMBER in between when the CFO sold some shares.
It will be interesting to see Graham's take on it today, which should be up soon when he pings me to say it's ready to publish.
Nice balance sheet too of course, which I always flag up when reporting on it.
Regards, Paul.
Fonix Mobile (LON:FNX) Hi Paul, Thank you you for your excellent appraisal of Fonix Mobile. With regard to New European territories they may be entering. I seem to recall them mentioning Austria some time last Year. Given the length of time that these contracts take to start this could well be the Country in question.
An ahead TU from Brave Bison (LON:BBSN) this morning, with net cash up significantly. SP has been week lately, IMO making for a good entry or top up point.
There a new note from Cavendish out too on Research Tree. There seems to be an issue this morning with the PDF reader though which hopefully will be resolved soon.
Brave Bison (LON:BBSN) TU issued after 8:00 so some may have missed this. Fairly muted response.
Financial Highlights
Unaudited (stated on a not less than basis)
H1 FY24
H1 FY23
% Change
FY23
Net Revenue
£10.1m
£10.0m
+1%
£20.9m
Adj. EBITDA (1)
£2.1m
£1.9m
+12%
£4.3m
Adj. Profit Before Tax (2)
£1.8m
£1.5m
+20%
£3.6m
Net Cash
£6.8m
£4.3m
+58%
£6.8m
have you got a copy of the cavendish note ?
Beeks Financial Cloud (LON:BKS) my 2nd largest holding.
Some good growth here together with recurring revenue, which is where they want to be, grab a contract then pay monthly (up 18%).
Higher revenue and excellent 67% increase of profit before tax.
Already announced Jo'burg contract extension and another in the pipeline (tease).
FCF and small increase in cash reserves.
Record pipeline for 2025.
Downsides as I see it is seeking redulatory approval for contracts - although that has always been the case, so not a new issue. I never thought I would say (type) this - decent sterling strength may impact fx.
In line update, nothing to see here. No talk about exit stratergies, which I know have been discussed - I'm holding, although may trade in and out on dips.
Beeks Financial Cloud (LON:BKS) teasing us after all. No major change. I hold.
A very brief trading update is out for Arcontech (LON:ARC) . Revenues expected to be 4% ahead of market expectations and PBT ahead by 20%.
Fonix Mobile (LON:FNX)
There seems to be lots to like in Fonix’s trading update this morning , revenue and EBITDA :-( up 18%, strong overseas growth, new income streams and new customers, Applepay opportunity, strong cash generation leading to increased dividend and talk of returning surplus cash to shareholders. The SP has been treading water lately so it will be interesting to see the reaction this morning.
I'm perplexed by Fonix Mobile (LON:FNX) - everything seems to always be moving in the right direction except for insider action which is unanimously towards selling - institutional and director deals are a sea of sells. It spooked me enough to sell down recently and yet today's results would suggest that was a mistake.
Fonix Mobile (LON:FNX)
John,
My bullish reply to your hesitancy would be this. In April this year the Fonix directors sold 6.5 million shares in a secondary placing at 225p, of which the company bought and cancelled 1 million, so the institutions who bought the balance are in profit by 10% and the directors derisked a lot of their holding so everyone is happy. A very similar situation to Warpaint London (LON:W7L) where 2 directors sold 7 million shares at 450p to institutions at the beginning of May 2024, again a nice derisk of assets for the directors but more importantly those institutions who bought at 450p are now sitting on a gain of nearly 40% in less than 3 months. Nice work by everyone.
So not all director share sales are a red flag.
Lovely results from Fonix Mobile (LON:FNX) ahead of expectations. I had always thought I would take money off the table around 225p but actually the more I see the delivery the less inclined I am to sell. I actually wonder whether this can become a global leader in its space. Be interesting to see who the new international market is and how that performs as it could be a good lead indicator for a momentum shift in the share price.
Not cheap at 20* but given the recurring and sticky revenue base it will likely always trade on a bit of a PER premium.
The directors clearly had a strategy around share sales over several years - they are obviously prudent managers and this seems to translate to their own wealth management. On both occasions of their large sales to date the business went on to over perform so I don’t see the director sales in this company as having any bearing on future performance personally given the track record.
@FNX The Selling of shares appeared in an RNS on 19.04.23 as a Secondary placing of existing shares to fulfil institutional needs. I am a long term holder of this share and continue to hold.
Fonix Mobile (LON:FNX) it was this year actually. Easy to sell because of large director sales, l hold.
Similar sales have happened at Cerillion (LON:CER) and Ashtead Technology Holdings (LON:AT.) but the share price is considerably higher now. Large director holdings will often be reduced at some time.
Difficult to know the reasons.
Stocks you should have followed directors on are Boohoo (LON:BOO), Ab Dynamics (LON:ABDP) and Solid State (LON:SOLI).
RNSs were prompt Paul. Croma Security solutions TS seems solid if slightly lukewarm. We hold and perhaps planetx will pedal all over this one later as he's contributed on this company previously. No borrowings, £4 million cash with £3.48 still to come over the next 8 quarters from a previous sale. Not exciting enough for many members but sits well enough in our portfolio.
Croma Security Solutions (LON:CSSG)
Held this for a while. They are not going bust.
Disappointing growth rate with a FCF margin of only 4.5%. Better opportunities elsewhere on growth prospects.
All the best
yiannos1,
Your FCF margin for Croma Security Solutions (LON:CSSG) is based on the zeus forecasts, which I think are over-prudent. On my estimates, it will be around 11% for 2024 .
This is not a growth stock, but it could become a GARP opportunity if it can deliver on its buy and build strategy. The potential benefits from operational gearing are very material.
Meanwhile, it has a rock solid balance sheet and an existing business that is clearly significantly undervalued after adjusting for cash (current and future from the Vigilant sale).
So, limited downside and potentially material upside. I'm happy to hold.
Croma Security Solutions (LON:CSSG)
My statements are not misleading and are always written after careful and extensive research and NOT whether I hold a share!
2025 FCF margin will be 4.4% and 2026 FCF will be 5.32%. These are the company’s estimates and I always look for the 2/3 years going forward,
As I said they are not going bust but there is no material upside here (as you suggest) and for me this is another pointless listing in the UK small cap world. The SP has never really gone anywhere for the last 5 years as the growth prospects are limited.
All the best
Apologies for my careless wording, yiannos1. I have edited my post on Croma Security Solutions (LON:CSSG) accordingly.
We'll just have to wait and see on the GARP potential. If they don't reinvest their cash in successful bolt-on acquisitions, you will be right, if they do, then I will be.
I very much like the asymmetric risk profile.
Hi Effortless Cool,
Can I just say that you very much earned your nickname with this superbly classy reply to Yiannos -
"Apologies for my careless wording, yiannos1. I have edited my post on Croma Security Solutions (LON:CSSG) accordingly."
We're all human, and the natural reaction is to fire off a hostile, unthinking reply to someone criticising you (God knows, I have to deal with it every moment of every day). So to take a deep breath and calmly apologise and put it right, is something I respect.
Well done!
Regards, Paul.
Thanks, Paul, it's something I am trying to get better at and, when I looked into it properly, yiannos' post was backed by facts and it was my original post that was potentially misleading.
Regarding your question about Croma Security Solutions (LON:CSSG) webinars, there was one late last year following the final results:
https://www.investormeetcompan...
Excellent podcast, and the last nano-second comedy genius, made old Ernie chuckle.
Yes, he's getting really good at these.
LOL it's an essential safety valve. Thank goodness the censor intervened at a meticulously timed moment.