Small Cap Value Report (Mon 22 May 2023) - BEG, WIN, TLY

Good morning from Paul! Graham's busy today, getting ready to fly to the UK for his star appearances at Mello Chiswick. We're both looking forward to seeing many Stockopedia subscribers at Mello tomorrow, and Weds. Do come along if you can, and say hello!
Podcasts - I ran into technical trouble on Sunday, and it looks like my website has been hacked somehow, as it now diverts to an online pharmacy selling Viagra. I just wanted to confirm this is not some new subsidiary activity of mine! So I uploaded the audio to Acast this Sunday, as usual, which distributes it via most of the big podcast channels, so it should be there (search for "Paul Scott small caps"), or here's a direct link to Acast which you can bookmark if interested. Most people seem to tune in via Apple podcasts, so it seems you've mostly got iPhones or iPads. There might be a problem with google play for this weekend's podcasts, sorry about that.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Paul’s Section:
Begbies Traynor (LON:BEG)
132p (pre market)
Market cap £204m
Begbies Traynor Group plc (the 'company' or the 'group'), the business recovery, financial advisory and property services consultancy, announces an update on trading for its financial year ended 30 April 2023.
Good news here -
Results expected to be ahead of market expectations
How much ahead of expectations? It’s a modest beat, with adj PBT of £20.7m, vs market expectations of £20.3m (consensus). Well done to the company & its advisers for giving us the precise figures, and market expectations, in the trading update. That’s best practice.
With revenue up 11% to £122m, but adj PBT up a greater percentage, at +16%, this shows an improvement in profit margin, as well as actual profit.
Net cash of £3m, despite having made acquisition-related payments of £11m in the year. Plus it’s paying divis too, of about 3%. So this is a genuinely cash generative business.
Bank facilities sound ample at £30m.
Outlook - the general tone of this update sounds upbeat, and current trading/outlook sounds good, and a reminder that it’s also growing through acquisitions -
"We have started the new year confident in our outlook for a further year of growth. Our insolvency team will benefit from their recent insolvency appointments, together with anticipated further growth in the insolvency market. We continue to identify growth opportunities for our advisory and property teams, including the recently announced acquisition of Banks Long & Co."
Broker update - Equity Development has issued an update note, raising EPS (which is what I use) from 10.0p to 10.5p for FY 4/2023. That means a PER of 12.6x
We can probably expect maybe 11-12p for FY 4/2024, which would lower the PER to 11-12x
Paul’s opinion - at 132p per share, that strikes me as a reasonable valuation, certainly not stretched. Plus divis, and being counter-cyclical, BEG shares are nice to own if you have a negative overall macro view, since insolvencies usually increase when the economy is weak.
Overall then, I can only have a positive, GREEN, view of this share at the current price of 132p. Upside? I imagine 150p+ is possible, with some patience.
Wincanton (LON:WIN)
Up 3% to 224p
Market cap £278m
Wincanton plc ('Wincanton' or the 'Group'), a leading supply chain partner for UK business, today announces its preliminary results for the year ended 31 March 2023.
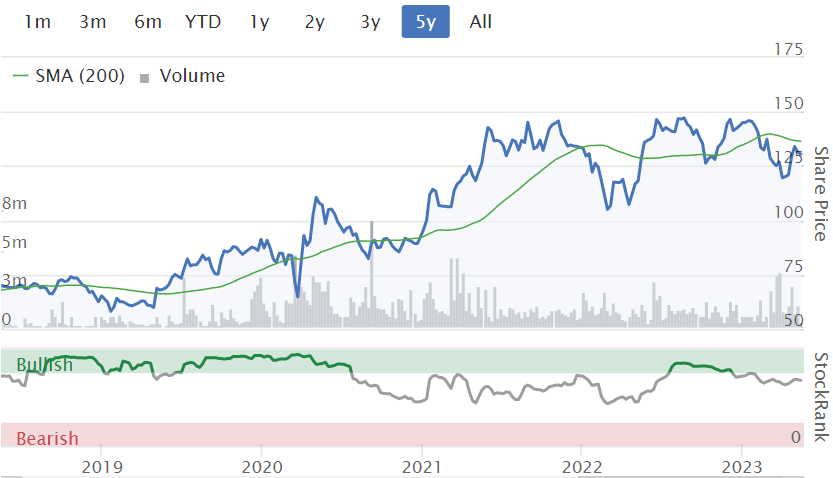
As you can see from the 5-year chart below, this logistics group did well in the pandemic, but its shares have since come all the way back down again to their pre-pandemic level - like so many small caps.
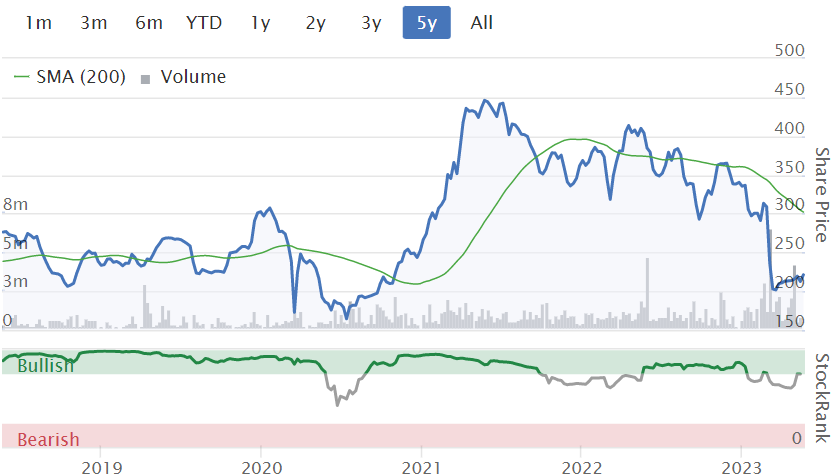
More recently, we can see the profit warning which I covered here on 7 March 2023, with a sharp vertical drop in the chart above, which has not yet been recovered.
The problem was the loss of a large & lucrative HMRC contract, which didn’t impact FY 4/2023 numbers, confirmed in line with expectations in the 7 March update. However, FY 4/2024 forecasts were cut considerably, by about 20% in EPS forecast, due to the HMRC contract loss (on re-tendering). The narrative today says important lessons have been learned about pricing contracts, and that there are good opportunities with UK Govt agencies to win more business.
Sure enough, the FY 3/2023 headline numbers have come in slightly ahead of expectations, e.g. Liberum had 41.5p adj EPS, and the actual is 42.5p. For a share that’s only 224p, we have a really low PER of 5.3x
So far, so good.
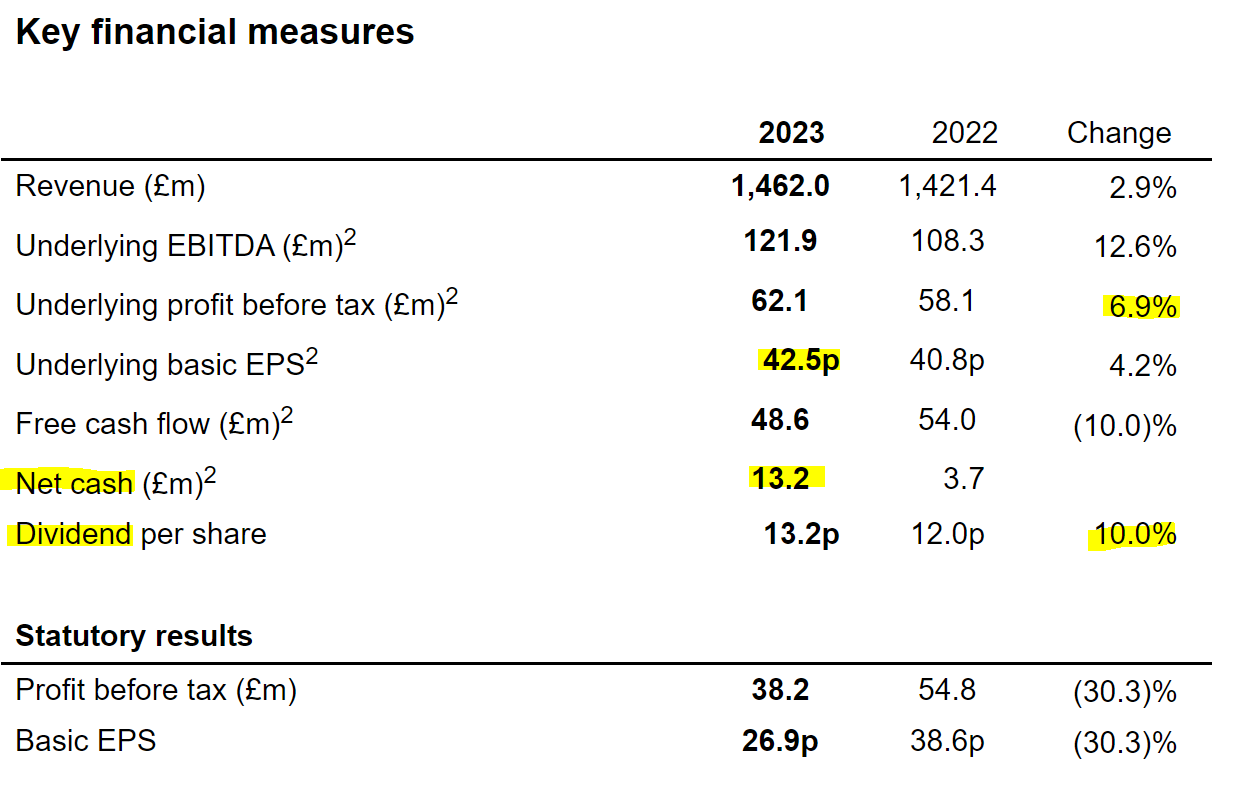
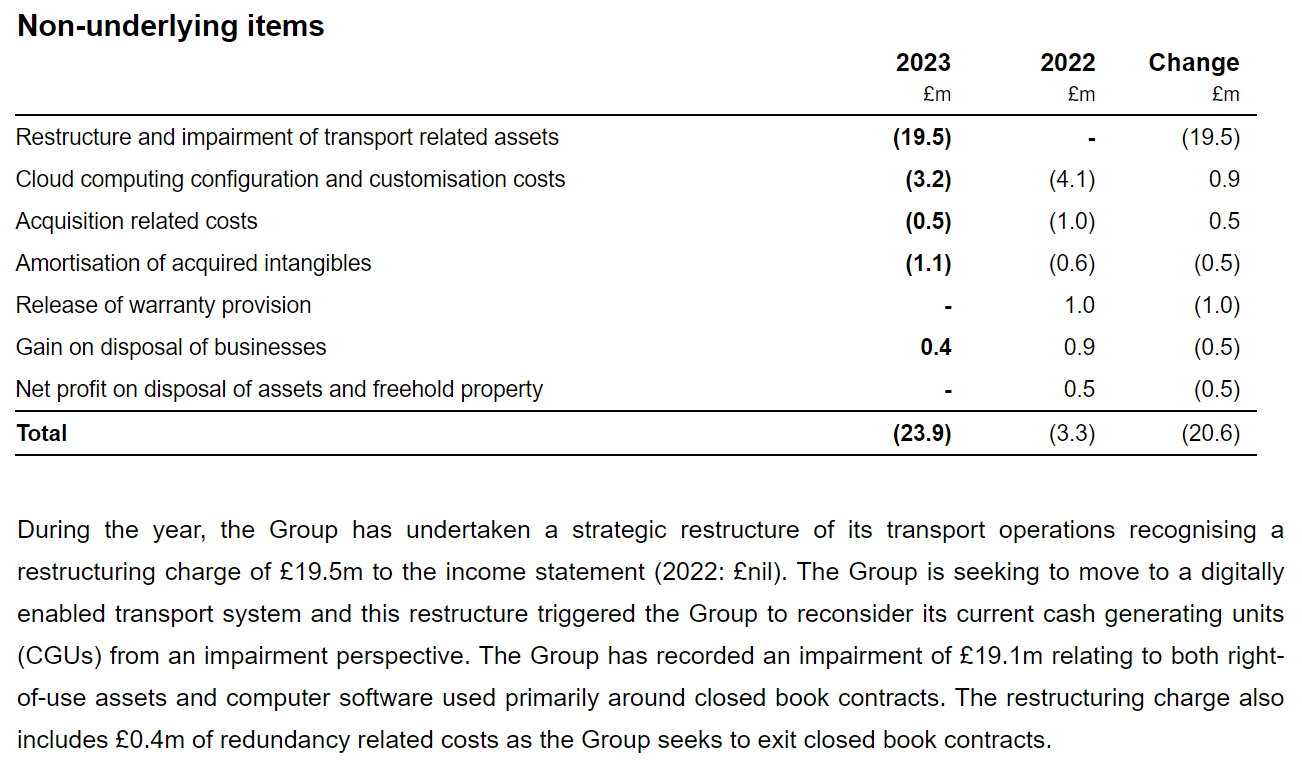
Note that the statutory figures are well below the underlying numbers, so I’ll have to carefully check what the roughly £24m shortfall is, comparing the two profit numbers above.
Inflation - just a reminder that WIN has proven adept at passing on cost increases to clients, since a lot of its contracts are “open book”, i.e. passing through costs, with an agreed profit margin.
Pension deficit - previously a major cash outflow each year, it now looks close to being fully funded on an actuarial basis (the more important method, since it determines any cash contributions). I covered this issue in more detail here in Nov 2022 when WIN’s interim results came out. In a nutshell though, I think the pension scheme is nearly fully funded, which could trigger a re-rating of the shares in due course.
The accounting surplus is about £115m, mentioned today. It’s usual for the accounting method to produce a much better picture than the actuarial basis, which is why it’s best to ignore the accounting basis for pension scheme surplus/deficits.
EDIT: although I see that Liberum's note today (many thanks) shows pension cash contributions of £22-25m pa continuing for the next 3 years - hefty amounts.
Adjustments - can’t say I’m convinced that these considerable costs below should be adjusted out. They look like fairly normal costs of running the business to me, so there’s a question mark over whether the “underlying” numbers are valid, in my view -
Going Concern note - says things will be fine, even in a severe downside scenario.
Balance sheet - is weak. NAV of £59m includes £222m in what I consider spurious assets (£105m goodwill, and £117m pension asset). Get rid of those, and NTAV is heavily negative at £(163)m. Although interestingly, there isn’t any interest-bearing debt. So this is not a stretched balance sheet. It’s just that WIN operates normally with negative working capital. It doesn’t have any inventories remember, and customers seem to pay up-front, which means it doesn’t need any net capital.
Although I would like to see what the average daily net cash/debt figure is, as that might look very different from month end snapshot figures depending on when customers pay, and when suppliers are paid.
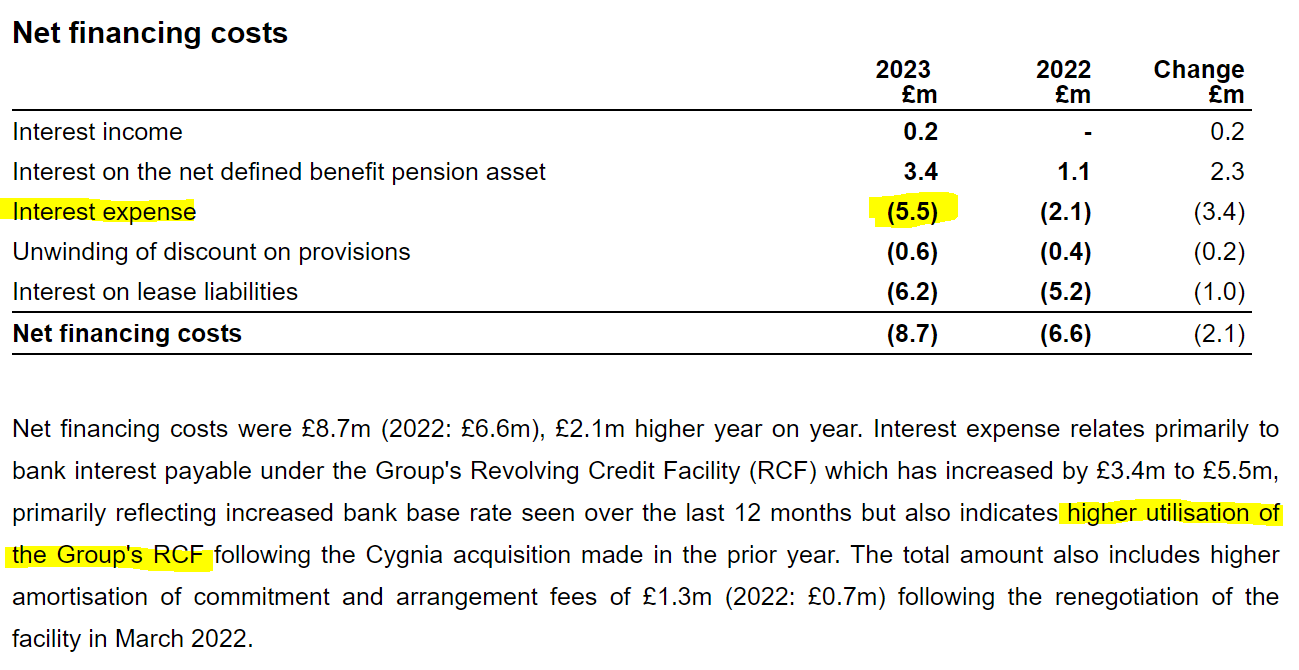
My hunch on this is confirmed by the interest expense note, with £5.5m of bank interest costs for the year, suggesting that an average daily position on cash/debt might be something like £100m overdrawn, a long way from the small net cash position presented on the year end date!
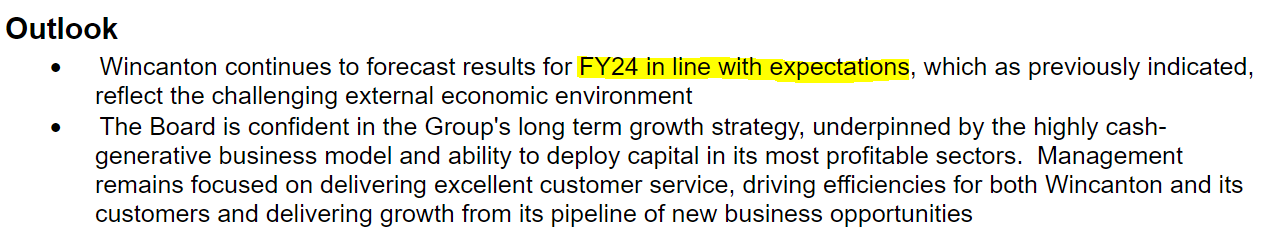
Outlook - rather bland, but confirms in line for FY 4/2024 (remember forecasts were lowered considerably before) -
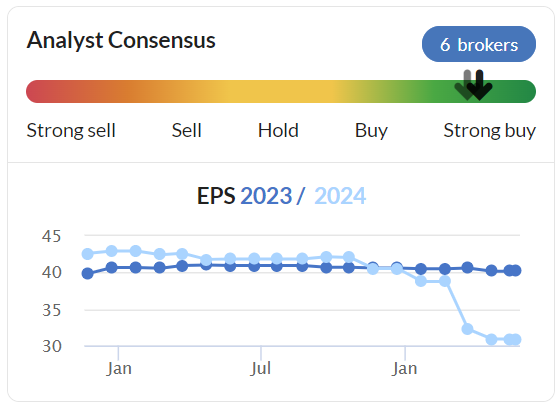
As you can see below, we’re looking at c.30p for FY 4/2024, giving a forward PER of 7.4x - still good value I think.
Paul’s opinion - I remain of the view that this is a good business, and have kept it on my top 20 watchlist for 2023. It was obvious, given macro conditions, that there would be some profit warnings on my list, so only having 2 to date (WIN and QUIZ) is actually quite pleasing. These 2 fallers have been more than offset by strong performances from most of the other shares, with the list currently averaging +12% YTD - not bad at all in a depressed small caps market.
I deliberately picked shares that would be resilient, even if they suffered temporary setbacks.
That’s how I see WIN. Losing a big, profitable contract is clearly a setback, but WIN has a good track record of winning new business, and makes positive noises about that today. So I reckon this share should recover, if we’re patient. Hence I remain of a GREEN (positive) opinion in our traffic lights system (see explanatory notes from what this means).
On the downside, I find the accounting a bit aggressive, with average net debt probably a good deal higher than the year end snapshot, and the large adjustments to profit seem tenuous. Overall though, I don’t think these undermine the value case for WIN shares.
Totally (LON:TLY)
Up 4% to 21.5p
Market cap £42m
Announces "multiple contract extensions" - ie contract renewals, totalling £12m. That's in the context of £144m forecast revenues for FY 3/2024.
It says this underpins existing forecasts, rather than being additional business, so I don't think it's anything to get excited about.
Paul's opinion - not yet convinced by this share, but will keep an eye on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Viagra? You were saying some of your stocks were a bit firmer Paul.
Loving your podcasts Paul :)
I don't think gold miners are covered here but Hummingbird PLC announced today that their 2nd mine in Guinea will start producing soon (by end June) - it will bring Hummingbird PLC to a mining producer with two mines one in Mali and one in Guinea - enroute to becoming a 200koz producer. If everything goes to plan it represents great value at these levels. https://www.londonstockexchang...
Touched on by Paul earlier, but please find here (for any interested readers) our new note out this morning on Begbies Traynor (LON:BEG): https://www.equitydevelopment....
Equals (EQLS)
Just finally broken the key support level 1 pound barrier and heading north at a rapid rate .
Seems to have a lot of momentum now and market seems to have really woken up to it .
I was weighing up Equals v Argentex about a year ago and plumped for Equals because I only see Argentex as money traders whereas Equals have a much more scaleable and interesting business model .
Of course Argentex shot up and Equals trod water .
Both still good value but Equals looks to have the wind behind it right now .
I think both Equals (LON:EQLS) and Argentex (LON:AGFX) are excellent value and own both. What I would say is that they both seem to trade in what I would call steps. They will lag fundamentals for a while then catch up quickly, slightly overshoot, settle back, trade sideways for a while and repeat. So I wouldn’t put much store in one shooting up whilst the other treads water - I think they are just each trading in different phases at different times.
Equals (LON:EQLS) has capital markets day coming up. Seems unlikely this would be scheduled unless they were confident so suspect that is helping the rise too.
Hi Planetx & Davidjhill.
Equals (LON:EQLS).
The CMD was last week as was the AGM which I went to.
I'm with Planetx. They are doing really well with all products but particularly the Solutions biz which targets larger instutions. It more than doubled rev in last 12 months and is taking market share from the big banks on both price and customer service. They only have a tiny piece of this market so far, so there is a lot to aim for. Revs could reach £100m from the UK.
They are also developing massive potential future growth via the Oonex acquisition announced in March which will mean they can trade in the EU, a market which is 5 times larger than the UK and also the partnerships in the USA. Califonia alone has nearly as many SMEs as the whole of the UK.
Thanks Michael - I’m on holiday (unfortunately miserable weather and to top it off my hot water tank exploded leaving me with a cm of water all over my floor and a new tank to buy) but clearly that (probably the wine) hasn’t prevented me from losing track of time on the CMD (which I presume went well)!!
Agree with all you say on Equals (LON:EQLS) - they are also a decent size holding for me and trade on a pretty lowly valuation for both the growth and potential, but suspect the step trading pattern will hold.
How was theAGM? Well received?
How was the AGM? Well received?
I think it took a couple of days for anyone not attending to notice but momentum has picked up now. Chart watchers might see a possible cup and handle breakout forming with ATHs in range after a long base. But that's not my expertise so I welcome correction by one of the local experts.
Hi Davidjhill
Surprisingly there was only one other shareholder at the Equals (LON:EQLS) AGM.
Alan Hughes (Chair) added a pre-cursor to the AGM statement congratulating Strafford-Taylor CEO & Cooper CFO saying how much progress they had made with the biz in the last 2 years which is roughly when Hughes came on board. Hughes made a very good impression. Being one of only 2 shareholders meant I was able to spend a few minutes with management which is invaluable.
Hope the weather improves as has the Equals share price and your leak is repaired!
Equals (LON:EQLS) has capital markets day coming up. Seems unlikely this would be scheduled unless they were confident so suspect that is helping the rise too.
Deleted.
I was weighing up Equals v Argentex about a year ago and plumped for Equals because I only see Argentex as money traders whereas Equals have a much more scaleable and interesting business model
My thinking too. I've long had a large position in Alpha International (LON:ALPH) - as sizeable as my other "big 5" holdings in Microsoft and Alphabet, ASML and Schneider Electric, which is a measure of my respect for the name. Now, I see Equals (LON:EQLS) moving onto similar corporate ground and away from the spot fx business of the past. The products, margins and returns are not as well evolved yet but neither is the valuation. Good luck with the investment, in which I joined you with the proceeds of my sale of Network International Holdings (LON:NETW).
Morning all, hope to see some of you in London this week! David Stredder has asked me to send in a reminder that there are still tickets available for Mello 2023 (melloevents.com) which is running from Tuesday to Wednesday in person, and on Thursday online. If you are buying a last-minute ticket, make sure you use a coupon code to get a big discount off the headline price - my code is Neary50, and David has promised to buy me a pint for every person who uses it! Cheers. G
Thank you for the very clear disclosure Graham!
My morning smallcap tweet: Monday Maelstrom
Totally (LON:TLY) World Chess (LON:CHSS) EnSilica (LON:ENSI) Quadrise (LON:QED) Quixant (LON:NXQ) BSF Enterprise (LON:BSFA) Catenae Innovation (LON:CTEA) Ethernity Networks (LON:ENET) Zinc Media (LON:ZIN) Norman Broadbent (LON:NBB) Oncimmune Holdings (LON:ONC) Inland Homes (LON:INL) Renalytix (LON:RENX) Blackbird (LON:BIRD) Kinovo (LON:KINO) Begbies Traynor (LON:BEG) Chesnara (LON:CSN), Venture Life (LON:VLG), Ilika (LON:IKA), Stelrad (LON:SRAD), Wincanton (LON:WIN)
◄Totally (TLY)► wins c. £12m of contract extensions of 6-12 months. [SP=20.5 Cap=40m]
◄World Chess (CHSS)► World Chess officially open. It aims "to reinvent the chess club culture in its entirety". No chess boards then. [SP=9.95 Cap=63m]
◄EnSilica (ENSI)► the ASIC used in the automotive vehicle launched in June 2022 is being designed into additional models. Hikes contract rev exp to $40m over the next 6 years. [SP=61 Cap=48m]
◄Quadrise (QED)► fuel trial in Morocco aborted because QED's pump failed. Why didn't it make two pumps? [SP=1.35 Cap=19m]
◄Nexteq (NXQ)► name change from Quixant effective today. [SP=NA Cap=NA]
◄BSF Enterprise (BSFA)► first distribution agreement and three new customers for its patented City-MixTM supplement, culture media booster. A culture media booster? Will that make the Times Literary Supplement more interesting? [SP=14 Cap=14m]
◄Catenae Innovation (CTEA)► court rejects attempt by two the minority shareholders of Hyperneph Software to seek Summary Judgement in the claim against the Company. [SP=0.13 Cap=m]
◄Ethernity Networks (ENET)► gets $230k as part of promised subscription from 5G Innovation Leaders Fund (see 25 Feb). $1,5m remains. [SP=3.29 Cap=3m]
◄Zinc Media (ZIN)► major contract win (no fig) for series for Canadian Broadcasting Corporation and BBC. [SP=107 Cap=23m]
◄Norman Broadbent (NBB)► Q1 rev up 67% with Net Fee Income up 66%. In line? CEO 'delighted'. [SP=4.74 Cap=3m]
◄Oncimmune (ONC)► sells Oncimmune Limited for £13m. Co will continue to operate its ImmunoINSIGHTS business, primarily through its subsidiary Oncimmune Germany. Also the latter signs a 5 yr Master Services Agreement with Freenome for services worth €1.14m min PA. [SP=37 Cap=27m]
◄Inland Homes (INL)► gets planning consent for mixed-use development of 1,525 homes and c. 2,700sqm of commercial space at Cavalry Barracks in West Hounslow. [SP=8.5 Cap=23m]
◄Renalytix (RENX)► expansion of insurance coverage for KidneyIntelX with CareFirst BlueCross BlueShield, the largest health care plan in the Mid-Atlantic region of USA. [SP=85 Cap=102m]
◄Blackbird (BIRD)► restructures business, cuts jobs, to save c.£0.5m PA. CEO trills ""I am excited about our prospects". [SP=6.32 Cap=23m]
◄Kinovo (KINO)► boosts 5 yr contract worth £12m to £40m over 8 yrs. Alos £2m of other new contracts. [SP=50 Cap=30m]
◄Begbies Traynor (BEG)► guides FY-Apr ahead of market expectations with rev up 11% and adj pretax up 16%. Outlook confident. [SP=132 Cap=199m]
◄Chesnara (CSN)► long term strategic partnership with FinTech market leader SS&C Technologies which will provide co with "access to a modern, flexible and cost efficient policy administration service". [SP=286 Cap=429m]
Morning Paul.
"I ran into technical trouble on Sunday, and it looks like my website has been hacked somehow, as it now diverts to an online pharmacy selling Viagra. I just wanted to confirm this is not some new subsidiary activity of mine!"
Thanks for making me laugh!
Priceless :) :)
See you at Mello. Please come say hello.
Michael
This is why Starling refused Paul a bank account for the new business he was trying to set up last week. All makes sense now.
Should put lead in your pencil
"I ran into technical trouble on Sunday, and it looks like my website has been hacked somehow, as it now diverts to an online pharmacy selling Viagra. I just wanted to confirm this is not some new subsidiary activity of mine!"
Keep it up Paul! (the good work that is ;-) )
Morning all, had a look into Knights group (LON:KGH) over the weekend. Thought the HY23 results from January were worth a watch (see the video presentation from the link below)- a little more insight into what Beech is trying to achieve and a potential pivot to organic growth and debt reduction going forward (maybe this in turn will start to produce some clean, unadjusted figures)
https://www.knightsplc.com/com...
I tried the podcast a few times and thought Paul was having laugh with the viagra website! Of course I have my own dealer so didn't use it :)