Small Cap Value Report (Mon 23 Jan 2023) - SAGA, PAY, DTY, IGP, TBLD, BOOM

Good morning from Paul & Graham!
Today's report is now finished.
Podcast - covering last week's SCVRs went up on Saturday morning, here (and on podcast platforms). I'll type up a separate article about the macro news/views section of my podcast, but for the individual companies, all you need to do is refer to my weekly summary spreadsheet (I'll put the link in at the end of this report, and if of interest, please bookmark it).
12 more value/GARP shares ideas for 2023 - I published this new article last night, as a follow up to my previous article from 8 Jan 2023, listing my favourite 20 value/GARP shares. Readers seemed to like this format, hence why I wrote another article - we do like to give you more of what you vote for with your online thumbs ups. Incidentally, wasn't it a great idea to remove the thumbs down facility - the site's so much better without all that negative energy, and the kerfuffle it used to trigger!
In a similar vein, Graham wrote up his best ideas for 2023 here on 16 Jan 2023, in case you missed it. As always, we've just flagging up share ideas for you to properly research. As we covered 533 companies in the SCVRs last year, it stands to reason that we can't possibly do all the research into every one - please remember our reports are just initial reviews, so you need to always do your own, much more detailed research. That's what we firmly believe, it's not just a disclaimer.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/Summaries
We didn't manage to cover everything today, but I'll circle back to Colefax tomorrow, as we like that share.
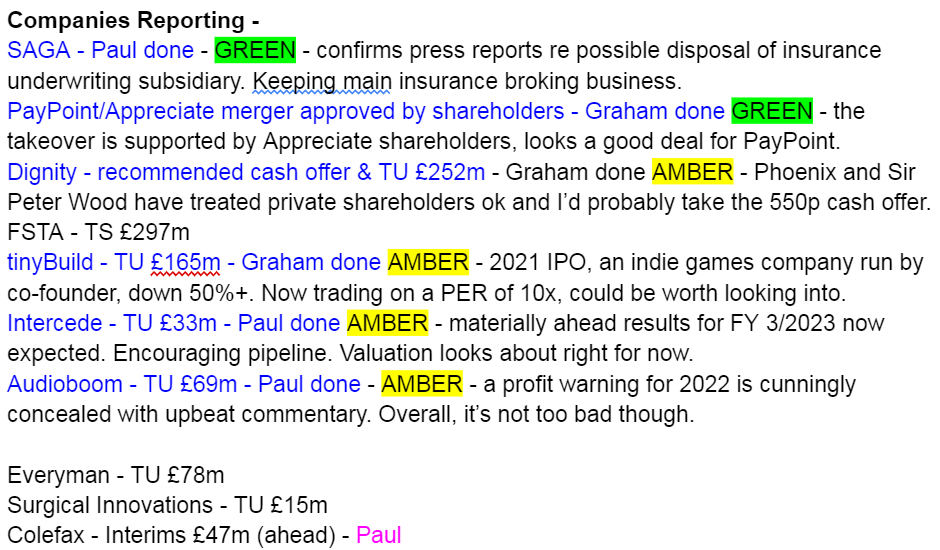
As always, do let us know in the comments, if we've missed anything significant. We don't always cover "in line" updates, as they're not price-sensitive.
Paul’s Section:
Saga (LON:SAGA)
150p (pre market) £211m mkt cap
The weekend press (Times) reported that Saga was trying to find a buyer for its insurance underwriting business (which is smaller, and less important than its retail insurance broking business, remember).
Saga responds today - confirming that it is in discussions for this disposal, which if it goes ahead would, it says: reduce debt, crystallise value, and enhance long-term returns.
My opinion - most of the insurance division profits come from the retail broking part, which is being kept. I’d be happy to see risk reduced by getting rid of the underwriting business. This news doesn’t strike me as particularly price sensitive, and if they can get a decent price (I think the Times mooted c.£90m) then that would take a nice chunk out of the net debt, which some investors find excessive (and mgt has previously said it wants to reduce debt from cashflows).
Intercede (LON:IGP)
71p (up 25% at 08:36) - mkt cap £41m
A strong rise in share price today for a positive trading update from this interesting company that specialises in digital identities for mainly blue chip & Govt organisations.
Positive momentum has continued, and it now expects to report FY 3/2023 results with revenue 5-8% of market forecast (£11.3m, so new guidance is £11.9m to £12.2m.)
Adj EBITDA is expected to be “materially ahead” of £0.6m forecast.
H1 revenues were £6.1m (up 24% on H1 LY), so it looks as if H2 is on track to be about the same as H1.
I’ve no idea why IGP quotes EBITDA, because investors usually assume this will be an inflated number, especially at software companies, because they often capitalise a ton of payroll costs. However, IGP doesn’t do this, so it would be far better off reporting profit after tax (PAT), which would show the benefit of tax credits. Also, EBITDA isn’t mentioned at all in the interim results, so it’s difficult for me to tie in today’s update with the H1 figures. I’ll email the company to point out this sub-optimal reporting!
Thankfully Finncap clarifies things with an update note today (many thanks), saying that it’s upped FY 3/2023 adj PBT from £0.2m to £0.6m. It’s also slightly raised next year from £0.6m to £0.8m adj PBT. Quite small profit numbers for a £41m market cap.
Outlook - encouraging, I’d say - because mgt tend to be quite conservative in the messaging, hence I would assume there’s a reasonably good chance these deals might close, otherwise they probably wouldn’t have been mentioned -
The pipeline of new business continues to grow, and the Group has several further contract opportunities that could close before the fiscal year end.
The integration of Authlogics (as announced on 10 October 2022) is on track and embedding well.
My opinion - Intercede has an astonishing client list of very sticky major clients. However, it's struggled to generate meaningful growth.
It invoices mainly in dollars to US customers, but costs are mainly in sterling, so I think this would have been a significant benefit in a year when sterling has mostly been weak (although recovered somewhat more recently).
In valuation terms, I think the price looks probably up with events for now. Maybe investors are anticipating another beat against forecast, if the deals mentioned are indeed closed by year end?
The bull case is that, with almost 100% gross margins, if IGP can really accelerate growth by winning big new contracts, then it could be transformative for profitability. I’d been patiently waiting 4-5 years for that element of the turnaround strategy to happen, but lost interest, so I'm just watching from the sidelines for now.
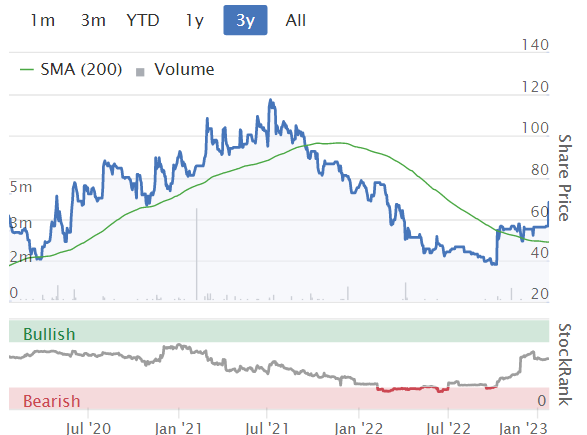
Audioboom (LON:BOOM)
405p (down 4% at 11:33) - mkt cap £66m
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to provide a trading update for the 12 months ended 31 December 2022.
I’m not at all happy with the way this update has been presented. It trumpets strong growth - revenue up 25% to $75.5m, and adj EBITDA up 16% to $3.6m, but it is then revealed in a broker note from Finncap (many thanks) that this is c.10% short of previous forecast, so it’s actually a cunningly concealed profit warning!
H2 revenue is $34.6m, down 15% on H1 - they don’t flag that in the TU today, funny that!
H2 adj EBITDA is $1.6m, down 20% on H1.
So I think we’ve established that this is a heavily PR-d announcement, cherry picking figures that are up, and obscuring numbers that are down. That really puts me off from investing, as I like companies that are straight with investors, not ones that PR the announcements to obscure the truth - in this case, that it’s a disappointing outcome, below forecast.
Cash looks good though, at $8.1m (up from $3.0m a year ago), plus an undrawn $1.8m overdraft. Although note it had risen to $5.8m at the half year. I had previously flagged excessive receivables at BOOM, so it looks as if some of that might be turning into cash, which is moving in the right direction.
I covered BOOM in more detail here on 17 Oct 2022, a lot of which is still relevant.
CEO & Chairman comments are bit more realistic, including -
...but ultimately our performance was restricted by global economic headwinds which negatively impacted the wider advertising market…
We are focused on ensuring that the Company is structurally resilient, and I am pleased to report a record year-end cash position of US$8.1 million - critical during uncertain economic periods. We continue to focus on controlling costs, operating with a lean team, to ensure we can deliver maximized profits for shareholders in 2023.
Across 2023 we will restructure our sales organisation, ensuring we remain competitive at the top end of the podcast industry. Despite the continued uncertainty in the advertising market, we have made positive progress, having secured more than US$44 million in advance advertising bookings for 2023…
I am confident that the business is not just showing good resilience, but is moving forward, fully primed for further growth as the advertising market improves across 2023."
My opinion - I would have preferred a much more honest form of reporting, which should have said, look advertisers are reining in their spending due to macro factors. But, we’ll be fine because we’re low gross margin, so not much operational gearing, and we can trim our central costs. And we’ve got enough cash, so won’t need to dilute shareholders. We’ll do better when ad markets recover.
Instead, I’ve had to ignore the prominent sections of this update, refer to a broker note for the reduced guidance, and (whatever the opposite is of cherry-pick) the realistic bits out of bullish commentary, to piece together the truth. That leaves a negative impression, and only defers a negative share price reaction.
Overall, it’s an OK business, a decent turnaround I think in the last couple of years, under new management, from a previous basket case.
Valuation is the tricky bit. The price has crashed, along with tech valuations generally. Is it cheap now? That depends how you look at it. To me, the market cap of £69m looks reasonable, and as mentioned before, it might be a bid target at some point, doing most of its business in the USA. So overall, I'm neutral on this one.
Graham's Section:
PayPoint (LON:PAY) and Appreciate (LON:APP)
It’s farewell to Appreciate as a listed, standalone business as the shareholders of Appreciate vote to accept the proposed takeover. In the end, only 1 million shares (out of 186 million total outstanding shares) voted to reject the deal.
There are still some conditions to be satisfied but normally these are just a formality, after the FCA and shareholders have both supported the deal. The whole thing is expected to close by the end of March 2023.
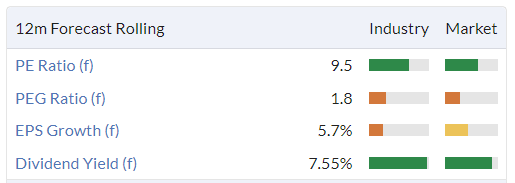
I remain intrigued to see if PayPoint can wring some proper synergies out of this takeover. As I said last week, it strikes me as more of an opportunistic bid for a familiar company that had fallen out of favour in the stock market, rather than a truly synergy-driven deal. But we shall see. I do think it’s clever business by PayPoint and it increases the attractiveness of PayPoint shares as a value investment. See the metrics already on offer:
Dignity (LON:DTY)
Share price: 545p (+8%)
Market cap: £273m
Let’s check out the big news here first. Dignity shareholders are being offered 550p per share to relinquish control of the company.
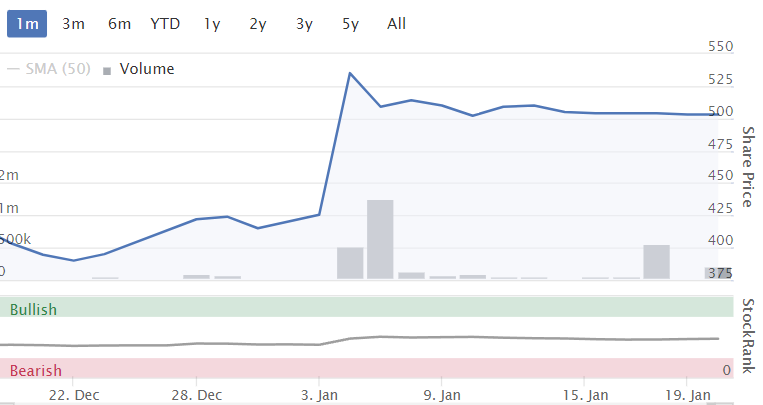
That’s merely 9% higher than the share price as of last week, but it’s 29% higher than the share price which prevailed on January 3rd. That date is relevant because it was on January 4th that an official announcement was made regarding a “possible offer”.
So the trading in Dignity shares since then has been on the basis that an offer was possible or likely - here’s the 1-month share price chart:
Paul covered the Jan 4th announcement in some detail here, noting that proposals from the buyers had been made as far back as October 2022, but nothing was announced to the market until January.
Indeed, this is now at least the fifth bid proposal from these buyers: 475p, 500p, 510p, 525p, and now 550p. I wonder what they really think it’s worth?
Offer detail - under today’s proposal, DTY shareholders can choose to receive unlisted shares in the new Dignity holding company. Alternatively they can choose to receive listed shares in Castelnau (LON:CGL), an investment vehicle managed by Phoenix Asset Management.
The buyers - the proposal has been brought by a consortium consisting of Sir Peter Wood’s investment vehicle, an investment vehicle managed by Phoenix, and Phoenix themselves.
These are the same people who built a 58% position in Stanley Gibbons and then demanded that it go private, threatening to withdraw their financial support if it did not.
They are good, shrewd investors and I’m not sure that I’d want to be on the other side of a trade with them, to be honest.
Any Hornby (LON:HRN) shareholders must be aware that Phoenix owns a majority of that company and delisting risk at that company must be very significant indeed.
Phoenix understand very well that public, listed markets are often not the best environment for businesses to grow and prosper, particularly if surgery is needed. Here is an excerpt from their explanation as to why they Dignity should delist:
…under private ownership, Dignity will not only have access to patient, long-term capital, but also a supportive environment for management to implement its current strategy, ahead of an envisaged medium-term exit.
…Dignity's strategy will be enhanced through access to a significant level of investment to expand organically through increased marketing investment in its new funeral plan products, upgrading and modernising of physical infrastructure, further investment in its workforce and technology, and strategic expansion of its crematoria portfolio. Bidco will also provide Dignity with the financial support to grow inorganically by taking advantage of acquisition opportunities as they arise at attractive prices, given the current uncertain market environment.
So why couldn’t Dignity do all of these things as a public company, I hear you ask? That’s a good question. For the answer to that question, let’s switch over and take a look at today’s full-year trading update for 2022. Highlights:
Underlying revenue £275m (2021: £312m).
Underlying operating profit “no more than £20m” (2021: £55.8m).
Cash of £8.5m, net debt £508m (excluding IFRS 16 liabilities).
Commentary - the comments are uninspiring. There are “early signs of increases in market share growth” and “progress in addressing operational challenges”, but against that:
…performance continues to be impacted by changes in pricing strategy and the continued shift towards lowered-priced products, despite higher-than-average death rate persisting post-COVID 19.
Furthermore, excluding the impact of the lower promotional expense, the cost base of the Group has increased in the year because of planned investments across the estate and in facilities, as well as ongoing increases in regulatory and operational costs which have been partly driven by macroeconomic factors.
Bondholders have consented to waive covenants, a typical sign of financial stress.
So it’s not hard to understand the argument that Dignity, as a listed company, will be unable to fund the various investments it might like to make in the short-term. It’s highly indebted, low on cash, and profits are shaky. And this is not a good environment in which to raise new equity.
Here’s a snapshot of recent profits and losses:
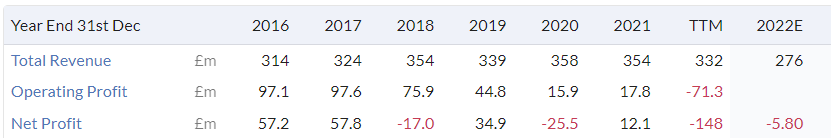
My view
Given the amount of debt involved, I would be inclined to cut my losses here, as a Dignity shareholder (or take profits, if I was one of the lucky few sitting on a profit).
What can we learn from this? Maybe we need to be even more careful of the “value” opportunities the market often throws at us. More often than not, there’s a hidden risk lurking under the surface. The risk could be something as mundane as delisting risk - either because the company is too small to justify its listing expenses, or because the major shareholders want to turn it around themselves, away from the glare of the public markets.
Before buying any shares, I think a good question to ask is: “why is this company listed?”. If you are dealing in very small or troubled businesses, the answer might be unclear!
In this particular case, Dignity shareholders do have the option to take listed or unlisted alternatives to the 550p cash offer. So again, Phoenix have done more than the bare minimum they were legally required to do, for the benefit of smaller shareholders. Taking shares in the listed investment company Castelnau could be an interesting choice for some.
tinyBuild (LON:TBLD)
Share price: 80p (-1%)
Market cap: £163m ($202m)
A reader asked me to check this one out, so here we go!
TinyBuild is a publisher of indie (independent) video games, so it’s probably similar to Team17 (LON:TM17). It listed in March 2021 at 169p, and is now down by the customary 50%+.
Let’s see the highlights from this full-year trading update. FY 2022 is described as “a challenging year”:
Revenue in line with expectations, adjusted EBITDA “broadly in line” (usually means lower).
Cash finished over $25m, “impacted by timing of M&A and higher development spending on new titles, both announced and unannounced”.
Adjusted EBITDA reflects “a greater investment in marketing to accelerate revenue growth”.
A few small financial disappointments here, evidently. More positively, the games portfolio is said to have diversified into new genres, and the revenue sources have been diversified too.
As these are indie games, it’s no surprise that I’m unfamiliar with all of the titles mentioned in this update.
Staff - a remarkable increase in headcount from 147 at the time of the IPO, to over 500 now.
Outlook
Early indicators of positive consumer traction across the Company's diversified portfolio and pipeline are very encouraging, and the Board looks ahead to FY 2023 with confidence.
CEO comment - he mentions taking a “decentralised approach” to management, and “building something to outlive us as a generation”. Sounds interesting! I would also note positively that he is a co-founder of the business and is the largest shareholder (38%).
(On a side note, he also lives in the Netherlands and “doesn’t have any citizenship on Earth”. TinyBuild is headquartered in the US State of Washington and operates internationally.)
My view
I would need to build more familiarity before taking a view on this, but it sounds like it could be worth digging into.
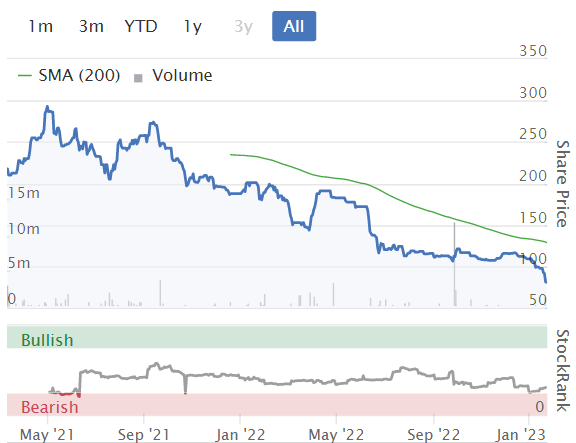
According to the StockReport, there is a pleasing trend of rising revenues and profits, and the shares are only trading on a PER of about 10x.

Link to SCVR spreadsheet summary (which I update every day). There's no need to "request access" - you can view it just using the link, and bookmark, save a copy locally, if you find it useful. Please don't share outside of Stockopedia, as it's intended as a service specifically for subscribers here. Thanks!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Thanks for covering tinyBuild (LON:TBLD), Graham. Not too much here to sink your teeth into. Full results released on 29 March.
Unfortunately the latest release of their biggest game/franchise has been a bit of a flop (Hello Neighbour 2) which is weighing heavy on their prospects. Personally I'm quite surprised it wasn't a more polished end product (it has a few bugs, and it's a pretty short game for a £30 price tag) with most reviews saying 'yeah it's alright but could be better' - very much in-keeping with the Franchises' first release, though that proved to be enduringly popular.
Will be interesting to see how it all plays out, which will provide clarity on how much they rely on one title (I suspect a fair amount, though nowhere near to the degree of Frontier Developments (LON:FDEV)) In many ways it might be a good learning lesson for the biz - they always bang on about Hello Neighbour so should encourage them to continue diversifying with different games, and give every release the care and attention it deserves.
I also wasn't a huge fan of the closing line "we are building something to outlive us as a generation." My initial reaction was get over yourself!! - But, at the same time, I don't dislike him fronting up as a leader with a clear vision, and not being afraid to make that sort of statement.
If anyone can stomach it, the CEO did a good interview with an Aussie game developer recently. It's long, but he delves into the latest in the Ukraine/Russia conflict, all the work TBLD have done (and continue to do) to keep staff safe - and you learn a fair amount about the man himself (he's very objective and logical, but seemingly in all the right ways - i.e. still cares about people, rather than being a cold and heartless something something.)
I did come away thinking - wow, if this guy can lead an organisation through a war, and through that process identify staff/leaders who you can trust to deliver under the most intense circumstances, then they're pretty well set to face any other challenges which come their way (those which a games company normally face, e.g. an underperforming title, rather than a war...)
I find myself wondering if Hello Neighbour 2 got as much coverage from Twitch & YouTube gamers as the first game did, hence the drop? I know my kids wanted to play the first game desperately because someone on YouTube that they like played it for a time. But my kids don't even know Hello neighbour 2 was released, or do i think, even care.
Interesting. Twitch tracker stats look pretty similar for both games, but that's just from taking a glance.
I know MrBeast (129m subscribers) is due to release a 'live action' version of Hello Neighbour 2. Perhaps that will have some impact when it does release.
tinyBuild (LON:TBLD) - thanks and perhaps the name says it on the tin.
"CEO lives in the Netherlands and “doesn’t have any citizenship on Earth”. Headquartered in Washington USA - well resourced.
I hold and did not DYOR, just went on a story in Shares. No big holding just play money and so it proved - should have downloaded 'Secret Neighbour' and got more bang for my bucks. Have learned a lesson unfortunately not a positive one for small caps.
IGP - I noted in the interims that were reported in November that the acquisition will add to profits next year. I suspect that PAT and EBITDA this year were impacted by acquisition costs and excluding these means a higher return going forward.
Hi
Not a holder in Dignity/Hornby but took a look at the castelnaugroup.com link out of interest. Couple of observations - it talks about Hornby as if its part of its family so Graham;'s point is well made. It seems to be buying some well known AIM names.
Also - https://www.phoenixassetmanage... - gives an interesting list of books
Yes, all effectively over on the APP bid. I've taken 42p a share for my Appreciate shares in the market today, along with the 0.8p dividend as its xd. The 44p bid value assumes a 580p Paypoint price so the bid is worth about 43p at the moment given Paypoint is 10% lower. There remains some market risk on the 43p value on offer. I think that there may be some further selling of Paypoint shares when APP shareholders get a small allocated holding. I do think that Paypoint looks interesting, so I have that on my watch list if it goes below £5 or so. A disappointing end to APP really caused by poor management under the previous CEO and Chair. Well done to the new Chairman and Harwood for at least creating some return to weary holders over the last 6 months! Any thoughts from other holders?
Update from Chapel Down (OFEX:CDGP) today, no surprises in the FY Dec22 numbers to what I was expecting. Wish they would have also included profit numbers, not just revenue, but easy to work from their easy business model.
It would have also been good if they could quantify the supply-side growth possible in 2023, since 2022 sales were constrained by supply. 2022 harvests were phenomenal (both quantity and quality). That will translate immediately to more still wine supply in 2023, and more sparkling wine supply from 2025-2026. Harvested grapes were +42% YoY, but would be nice to see what translated to barrels increase YoY.
For those that want to dig further, there's good visibility on future supply, by calculating the acreage planted in the last few years, and applying a vineyard maturity curve. I make it that 2023 potential grape volumes could be almost +50% from 2019 (normalised for weather), and another c+25% at least by from 2023 to 2025.
The big downsides, I see, are:
(I hold in the Boon Fund)
I have held Chapel Down since they went public (through SEEDRS). If you like their product, and I am a happy consumer of their better sparkling wines, then I have found that the 30% shareholder is a very handsome dividend!
Sorry, that should of course have been “shareholder discount”
The Saga (LON:SAGA) underwriting subsidiary, Acromas, is based in Gibralter, so not regulated by the Financial Conduct Authority (FSC), and underwrities 70% of Saga's motor insurance policies. That percentage may cause difficulties with the FCA, including its Fair Treatment of Customers https://www.fca.org.uk/firms/f...
Potentially any purchaser of Acromas will have to factor in a lower percentage of Saga's motor business going forward.
Is that the real reason why Saga (LON:SAGA) are divesting the underwriting business? Regulatory reasons? That would make more sense. Than what seems at the moment to be for raising cash to pay down debt.
Having looked at Acromas's accounts this morning, I reckon they lack scale to play in today's retail motor market. I suspect the FCA's recent rule-book changes are simply the icing on the cake.
What are Saga (LON:SAGA) underwriting that is not retail?
(replied to wrong comment >_< )
Sosandar (LON:SOS) news looks excellent for brand visibility - however i worry if partnering with Sainsbury's which is typically lower end market & a lot cheaper will damage Sosandar's premium brand image? Also given it's wholesale they may sell the clothing at a substantially cheaper price than Sosandar's website. I don't have a background in retail so i could be completely wrong.
Do you have any thoughts Paul ?
I was thinking a similar thing Josh but not too familiar with the brand. Texted the target audience (Mum!!) and her response was (paraphrased to) 'Heard the adverts on tv, tried some clothes, cheaper fabrics, but I think popular and nice styles' . I wonder if the nice styles, popular and cheap fabrics mean entrance to retail via Sainsbury's alignes quite well?
I don't hold, but on my watchlist recently.
All good points, but I see this as a Sosandar (LON:SOS) win. OK, it's Sainsbury's, but the SOS team would have considered this. More eyes on and more sales. It's still a very young brand...
I think it's good news re: Sosandar (LON:SOS) . They did say it'll be a limited range (or at least thats how I understood 'curated selection') which could well be cheaper items in the range, and then hopefully the quality is a gateway to customers buying more from them direct. I'd also wager that whilst many people are snubbing the high street during the spending crunch, there's no getting away from needing food - so might be some impulsive buys there too with a weeky shop. Let's see!
I really like the simplicity of the daily Red/Amber/Green SCVR spread sheet coding.
The colour coding reminds me of some of Buffett's key principles, where its possible that Red may lose you money and Green are more quality/value, that may out-preform.
Of course the colour coding is a starting point, so its also necessary to DYOR.
Why does he not stick to his No. 1 rule then?
SOS - interesting new third party agreement with Sainsburys. Not a holder.
Yep. Like that. Young brands need visibility. Good validation of the products. Bought more this morning. This is starting to look like a good fashion success story.
Too small for the SCVR but a pretty good trading update by Touchstar @TST this morning. its a tiddler with a market cap of 6.8m but now has cash of about 3.5m (up from 2.5m at the end of last year.)
Revenue Growth is only 10% which is the part that really needs to accelerate for a re-rating and they are looking at using some of the excess cash to grow into other regions or through an acquisition. Profit has doubled to about 500k which again is small but shows a lot of revenue growth can flow to the bottom line. Only a small holding of mine but an interesting punt to leave there for a couple of years.
Morning Brookeda,
Yes I agree, Touchstar (LON:TST) looks an interesting nanocap, and we have covered it here before. I held personally for a few years, but eventually got bored and moved on, once it got back to my original purchase price of about 80p.
As you say, it's making a modest profit, and the last balance sheet looks OK - strangely, it had cash, but also "borrowings" of £1.2m when last reporting at 30 June 2022. So be careful to be using net cash, not gross cash!
£2.4m order intake in Q4 reported today, and y/e order book of £1.7m is up strongly (was £0.6m a year ago at Dec 2021).
"Accelerating investment" in expansion announced today, sounds like up-front costs, so not likely to see profit growth in the shorter term.
Overall, I think this share looks potentially interesting. Very small though, so I can't see why it's listed.
Regards, Paul.
Yes I think companies like this have a constant revolving door of investors who buy in get bored after 12-24 months of it going nowhere and pass their shares to the next one. There's always an hope at some point it explodes (and I have my fingers crossed) but I guess most times they don't
Colefax
Lovejy 6 month update .
Share buybacks keep increasing EPS and this is a great strategy for this company in my opinion .
Numbers are great
20 million cash
47 million market cap
5 million profit 6m so say 10m
Ahead in most markets
Good spread of sales us v uk v Europe
30 million ish balance sheet
Dividend is low but In this case I prefer the buyback.
Headwinds acknowledged but clearly not digging in and the share price drop and cracking set of numbers above are more than allowing for it .
The US market looks strong and they are clearly making headway and profitable headway too. Sanderson also strong in US so looks like both companies are doing well there .
Very very under rated and a somewhat sleepy share that is a quite illiquid though there was a big seller recently so I managed to get a good chunk a few months ago .
Spread can be high .
Strip out the cash you get 27 million with 10 million profit, another 10 on the balance sheet and if they keep rattling out similar numbers and keep reducing share count then unless I’ve missed something it’s super solid .
DYOR I do sometimes miss something .
You missed the main investment case scenario :
Christopher Mills is not a shareholder!
What’s up with Christopher Mills apart from seeming awfully posh ?
Wonder if there is a positive read across to Sanderson Design (LON:SDG) ? One of the points I took from listening to Chris Payne in his recent presentation on the Headlam (LON:HEAD) trading update was that the more expensive end of the flooring market was holding up better than lower price points. Anecdotal perhaps, but one never knows?
Jonno
Definite read across for SDG and Colefax .
Both excellent companies and real interesting to compare the “tactics”
SDG seemingly with the higher profile brands and a more dynamic CEO , lovely next license agreement . Cash .
Colefax very well run but management more steady and probably more self rewarding .
I actually topped up SDG first thing but couldn’t pick up many .
I did favour SDG initially but long term I think those share buybacks at Colefax are going to make it more rewarding and a better way to use the cash .
But I hold both .
I’ve actually held SDG for 15 plus years ftom Walker Greenbank days it is my longest holding.
My previous FD actually tried to oust the then CEO a chap called “Charles” if I remember correctly but that was literally decades ago .
Morning planetx,
Coincidentally I added to Sanderson Design (LON:SDG) on Friday, then saw the price close down at 110p, but also noticed that 500,000 shares went through at 113p after the market closed. I admit to being a fan of Lisa Montague, the relatively new CEO. She has been a breath of fresh air and energised the company and its brands.
I have also held Sanderson Design (LON:SDG) since its days as Walker Greenbank and was fortunate enough to add during the pandemic. Although I have top sliced and added back along the way.
I believe that Sanderson Design (LON:SDG) supplies fabrics to Colefax (LON:CFX)
Extra £2 million energy costs for SDG this year. That's a not insubstantial amount
Intercede (LON:IGP) trading update, revenue expected 5-8% ahead of forecast and FY23 results materially ahead. Mentions several further contract opportunities that could close before the fiscal year end. Really pleasing from a long term holders point of view that ever since the purchase of Authlogics, the business seems to be turning around.
Was interesting that a large (for this stocks daily turnover) trade printed after market on Friday above the offer price. Clearly someone had a crystal ball!
Not necessarily (although also quite possibly!)....I topped up my Intercede (LON:IGP) in mid January (no crystal ball, just trying to top up a selection of my small-caps) and couldn't get a quote - had to leave limit orders. Same was true of Avation (LON:AVAP).
If you are are a small cap fund manager trying to get cash into the market then you have little choice but to pay up, sometimes above the spread to shake out some stock. In AIM stocks even quite small trades can qualify for deferred trade reporting...so there are potentially innocent explanations....
I agree to a point but in this instance there had been a seller around the 55pence mark for the last week or so and then low and behold, a print after market at 59 pence, above the offer of the day on a Friday ahead of a bullish trading update....Coincidence?
Yes I had problems getting a quote on B.P. Marsh & Partners (LON:BPM), most I could buy was 10 shares, which is ridiculous.
My morning smallcap tweet: Perked up or stitched up?
Surgical Innovations (LON:SUN) Audioboom (LON:BOOM) Kinovo (LON:KINO) Everyman Media (LON:EMAN) Trufin (LON:TRU) Argo Blockchain (LON:ARB) Gulf Marine Services (LON:GMS) DG Innovate (LON:DGI) tinyBuild (LON:TBLD) Sosandar (LON:SOS) Saga (LON:SAGA) Hellenic Dynamics (LON:HELD) Getech (LON:GTC) Touchstar (LON:TST) Dignity (LON:DTY) Colefax (LON:CFX) Newmark Security (LON:NWT), Invinity Energy Systems (LON:IES)
◄Surgical Innovation (SUN)► guides FY-Dec rev up over 20%, ahead of market expectations. Adj EBITDA c.£0.7m, in line. Strong UK sales growth Q4 has continued into the current year, [SP=1.5 Cap=15m]
◄Audioboom (BOOM)► guides FY-Dec rev up 25%.Adj EBITDA $3.6m up 16%. ""The challenging economic conditions in which Audioboom operated during 2022 prevented even stronger financial growth in line with our initial expectations." That's not clear to me. [SP=423 Cap=69m]
◄Kinovo (KINO)► contract worth £4m over 2 years from the London Borough of Waltham Forest. [SP=34 Cap=21m]
◄Everyman Media (EMAN)► guides FY-Dec rev up 63%. EBITDA up 75%, ahead of market expectations. Expects the volume and quality of new releases to significantly increase in 2023. [SP=86 Cap=78m]
◄TruFin (TRU)► further to previous RNS, Satago is extending its agreement with Sage, adding Satago services to certain Sage 50 subscription packages in Ireland. What is Satago? [SP=57 Cap=54m]
◄Argo Blockchain (ARB)► has regained compliance with Nasdaq rule re: SP over $1. [SP=13.9 Cap=82m]
◄Gulf Marine Services (GMS)► contract to provide support for the construction and development of a major offshore wind farm in France, to complete in Q1 2023. [SP=4.69 Cap=47m]. I hold.
◄DG Innovate (DGI)► subscription to raise £400k at 0.12p, a 14% premium, for the commercialisation strategy for its Enhanced Drive Technology and Enhanced Battery Technology. Also a Broker Option. [SP=0.1 Cap=9m]
◄tinyBuild (TBLD)► guides FY-Dec re in line but adj EBITDA only broadly in line (due to a greater investment in marketing). Outlook "Early indicators of positive consumer traction across the Company's diversified portfolio and pipeline are very encouraging". [SP=81.5 Cap=166m]
◄Sosandar (SOS)► will sell a 'curated' (ugh) collection of its products through Sainsbury's. Initially online only with selected stores planned later this year. [SP=21 Cap=46m]
◄SAGA (SAGA)► confirms press report that it may sell underwriting business. [SP=150.08 Cap=211m] I hold.
◄Hellenic Dynamics (HELD)► general update from the medical cannabis cultivator. On track for Q2 2023 revenues to meet distributor demand . Wholesale prices of medical cannabis flowers holding strong. [SP=0.12 Cap=15m]
◄Getech (GTC)► guides FY-Dec rev £5m, ahead of market expectations. Outlook " strong balance sheet, sales pipeline growth, plus good customer and partner momentum. Getech's Board has no current plans to raise capital from shareholders." [SP=13.75 Cap=9m]
◄Touchstar (TST)► guides FY-Dec rev up >10% and pretax doubled, both in line. Net cash generation significantly ahead. [SP=79 Cap=7m]
◄Dignity (DTY)►550p rec offer. Warns FY-Dec rev no more than £275m, U/L pretax no more than £37m. [SP=503 Cap=252m]
◄Colefax (CFX)► H1 in line. Guides FY ahead of expectations due to strong Dollar. [SP=630 Cap=47m]
◄Newmark Security (NWT)► FY-Apr. Current trading "returned to profitability and positive operating cashflows during FY 2023, whilst also continuing to grow revenues. Transition to a high margin hardware enabled SaaS HCM business is continuing with a significant increase in ARR". Going concern: "reasonable expectation that co and group have adequate resources to continue in operational existence" [SP=40 Cap=4m]
In line: IES
Saga (LON:SAGA) flogging off underwriting business...wants to become a capital light business
I don't know how Saga (LON:SAGA) is going to become capital light while it operates cruise liners.
maybe it's the light at the end of the tunnel...
This is the worst time to get a good valuation for an underwriting business! The whole industry for motor and home has been struggling with the surge of claims, turbulence of the new pricing regulations for new/existing, and then just general inflation.
I suspect that Saga (LON:SAGA) is selling off part of the family silver on the cheap. It is not easy to build an underwriting business. And this is almost the equivalent of a "sale and leaseback", as they'll still need those underwriting services to do the sales and marketing of their insurance products, only now they are going to have to pay up annually to a third party for accessing underwriting.
Agreed - seems a dumb move to me unless I'm missing something fundamental.
Good morning Paul and Graham, I would appreciate it if either of you gets chance to give Getech's TA today the once over. I've looked back to your comments Graham from 2019 and I like the last two paragraphs, I am comfortable with what the company does but it's a shame the shares have almost halved since. We are long term sufferers in this company but I can't help feeling there's a multi-bagger in here trying to get out! I'm now braced for Stocko members to shoot me down.
re Getech (LON:GTC) , this must be one of the longest Trading Updates I have ever seen, but there is no mention of profit, or even EBITDA, for the year which has now ended. That said, conditions are now favourable, and more revenue growth seems plausible. I hold.