Small Cap Value Report (Mon 23 Nov 2020) - AA., CINE, CER, CDM

Good morning, it's Paul & Jack here with the SCVR for Monday.
Timing - there's a fair bit to cover today, so we might over-run the 1pm official finish time. I'll make a note here once we're done, as usual. Today's report is now finished.
Agenda -
- Aa (LON:AA.) Update on Possible Offer (Paul, done)
- Cineworld (LON:CINE) Significant additional liquidity secured (Paul, done)
- Codemasters Group (LON:CDM) Interim results (Paul, done)
- Cake Box HY results
- McBride AGM Trading Update (see tomorrow's report)
- Carr’s Final Results (see tomorrow's report)
- Cerillion Final Results (Jack, done)
.
This part written by Paul
Aa (LON:AA.)
Share price: 31.5p (down 6%, at 08:12)
No. shares: 622.8m
Market cap: £196.2m
It looks as if things have moved forwards in a positive way for shareholders (anything above 0p is a good outcome, in my view);
The Board of Directors of AA (the "Board") notes the recent press speculation and confirms that it has received a non-binding proposal from TowerBrook Capital Partners (U.K.) LLP and Warburg Pincus International LLC (together the "Consortium") regarding a possible cash offer of 35 pence per AA share for the entire issued, and to be issued, ordinary share capital of the Company (the "Proposal").
On 27 October 2020, AA announced that commercial discussions and due diligence were progressing with the Consortium. The Company confirms that these commercial discussions have advanced and that following a period of due diligence have led to the Consortium submitting the Proposal.
The bidders intend to inject more equity, and help refinance the huge debt mountain.
AA’s Board says it has considered all options, and would be willing to recommend this 35p bid
My opinion - this is a lucky outcome for AA shareholders, who were in such a weak position vs debt holders, that a wipeout for equity was a considerable risk.
Is a higher competing offer likely? It’s always possible, but the greater risk is that the bidders might pull out, and that could easily end up with equity worth little to nothing.
Therefore, in my view, the logical thing to do is to accept the 35p offer, if it becomes formal. Actually, if it were me, I would sell in the market now, just in case the bid falls through.
Gambling on a takeover bid at an effectively insolvent company, is complete madness, in my view.
.
Cineworld (LON:CINE)
Share price: 54.0p (up 17%, at 08:41)
No. shares: 1,372.8m
Market cap: £741.3m
Significant Additional Liquidity Secured
This is a hugely indebted cinema chain, which follows on nicely from the AA, which is in a similar mess because reckless management took on way too much debt at both companies, thus destroying shareholder value.
Although to be fair, very few people saw covid coming. It turns out that many business models we thought were safe, with repeating revenues that could be relied upon, were not actually safe at all. A lot of thinking needs to be done about what valuation we should put on businesses, and what level of debt is safe to take on, given that another pandemic could occur at any point in the future. Or will everyone forget within a few years, and everything goes back to how it was before? That’s what tends to happen, in my view. Look at the 2008 crisis. It wasn’t long before the excessive gearing that caused the crisis was building up again.
As I mentioned last week, recent press reports were suggesting that CINE could be teetering on the brink of financial collapse. Many of its cinemas have been forced to close, and there’s been a lack of new releases, as film producers have also faced restrictions due to covid.
Personally, I think the bigger threat to cinemas, is that many people now have large televisions at home, and would probably prefer to see films released direct to consumer (a very important investing theme) to stream at home.
Personally I loath going to the cinema, and last time I did, the experience was ruined by people constantly coughing, rustling sweet wrappers, and their mobile phone screens lighting up in the darkness. I thought to myself, this would be so much more pleasant if I could watch at home on my 65” Samsung, sitting right in front of it, which makes for a more immersive experience than being in a cinema with the general public, picking up germs too, even before covid came along.
Anyway, it seems to me that the days of cinemas could be numbered, once the big film makers decide to disintermediate, and sell direct to the end customers with a streaming service. Although a counter-argument to that, is that cinemas charge per person, whereas streaming would be per TV - so a household paying say £6 to download a film would generate much less income that say 4 or 5 people going to the cinema together.
Even without its colossal debts, I wouldn’t be interested in buying CINE shares.
Additional funding - has been secured, as follows, which does have a whiff of scraping the barrel;
· Secured a new debt facility of $450m and issue of equity warrants
· Agreed bank covenant waivers until June 2022
· Extended maturity of the $111m incremental RCF from December 2020 to May 2024
· Accelerated tax year closure to bring forward an expected tax refund of over $200m to early 2021
Cineworld believes that together these steps will provide the Group with financial and operational flexibility until lockdown restrictions in key jurisdictions are eased and studios are able to bring their enhanced pipeline of major releases back to the big screen.
Equity warrants - there’s a separate RNS detailing the terms of the warrants being issued to the lender(s), as follows;
Exercise price 41.49p (10% discount to last closing price before today)
Exercisable at any time in the next 5 years
Dilution of up to 10%, being 153.54m warrants, per the RNS, but the dilution looks to be 11.2% based on the current number of shares in issue, by my calculations
For anyone not familiar with warrants, they’re very similar to call options, giving the holder the option, but not obligation, to buy new shares at a fixed price, over a defined time. Therefore if the company does well, and the share price rises in future, then the warrant holder gets the benefit of buying shares below market price. If the company does badly, then the warrant holder can just do nothing, and after 5 years in this case, the warrants would lapse.
My opinion - the issue here is that the upside for existing shareholders has been trimmed by the dilution from warrants. It would be important to check the last Annual Report, to see if there are other warrants in issue. I’d be worried that a precedent has been set, and in future re-financings, the debt providers might demand a chunk of the upside too, with more warrants.
Total debt is on a massive scale now (and I’ve seen much higher figures in the press, which might have included IFRS 16 leases maybe?);
After accounting for the New Debt Facility, the Group will have aggregate gross debt financing of $4.9bn with a weighted average interest rate of approximately 4.5%.
The problem with debt on that scale, is there’s only one long-term solution - some kind of debt for equity swap, or a huge & highly dilutive placing. The big danger is that it might have to be at a deep discount, to raise fresh equity. Therefore, the upside per share could be very limited in future, if there are (say) 5 times as many shares in issue as there are now.
Investing is all about weighing up risk:reward. In this case, CINE shares look extremely risky to me, and with probably quite limited upside, since heavy dilution seems inevitable, sooner or later. The key thing is that re-opening, once vaccinations have happened enough to allow re-openings, doesn't solve the problem. There would still need to be major repairs needed to its balance sheet.
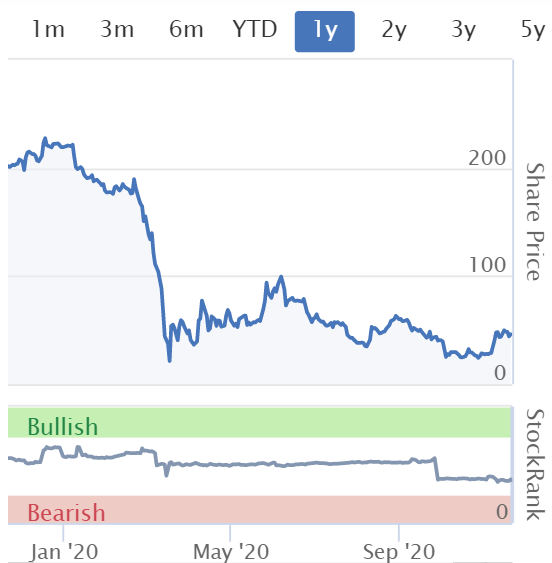
In the short term, price movements can be violent in this type of situation. Short squeezes are likely, when they panic buy, to cover positions, when news like today (of continued survival) comes out. So it’s dangerous to open short positions where there is already a big short position. I’ve been stung lots of times in the past, even at companies which subsequently went bust, there’s usually a big short squeeze near the end. So personally I don’t touch things like this any more, on the shorting side of things. And I certainly wouldn’t consider going long, in a company that has such high levels of debt, and is clearly struggling for survival at the moment. There are far less risky ways to play the covid recovery, in my view, where you don’t have to worry about insolvency.
.
.
Codemasters Group (LON:CDM)
Share price: 489p (down <1%, at 11:32)
No. shares: 152.4m
Market cap: £745.2m
Codemasters (AIM: CDM), the award-winning British video game developer and publisher specialising in high quality racing games, announces unaudited results for the six months ended 30 September 2020 ("H1 2021").
I was hoping not to cover this one, but it’s so popular with readers that my arm has been twisted! Here are my notes. Please remember I don’t know what the future holds, so am just reviewing the historic numbers here;
Revenues doubled to £80.5m in H1 - I couldn’t find a split between organic, and growth from acquisition(s). The text mentions an acquisition called Slightly Mad Studios
Adjusted EPS (my preferred profit measure) also doubled to 13.7p, which looks good in the context of a full year estimate of 18.69p, which now looks too low, depending on seasonality & the release schedule for new games
Outlook - H2 has “begun well”, but nothing said about performance vs expectations
Digital delivery now very high, at 72.9%, helped by covid forcing closure of physical games stores for part of the period
Brought forward tax losses are particularly large, at £125m - hence very low tax charge. Should we be normalising the tax, to value the shares? Possibly
Creative sector relief of £5.0m boost to profits in H1, and £9.0m last year, is a major contributor to profitability. This looks like sector-specific tax relief - a risk, in that if it is reduced, or eliminated in future, then that would crash the share price
Balance sheet - looks OK, although note the big non-current liabilities, which would consume a lot of the cash pile. Overall, it looks healthy enough
Cashflow statement - again, looks fine to me. A genuinely cash generative business. Note that amortisation charge for capitalised development spend is roughly in balance with the capex booked. Amortisation policy (65% in first month), then balance over a year, looks prudent, and reflects reality
Recommended offer from Take-Two Interactive - estimated to complete in Q1 2021.
Cash & shares. See RNS from 10 Nov 2020.
120p per CDM share in cash, and 0.02834 shares in $TTWO
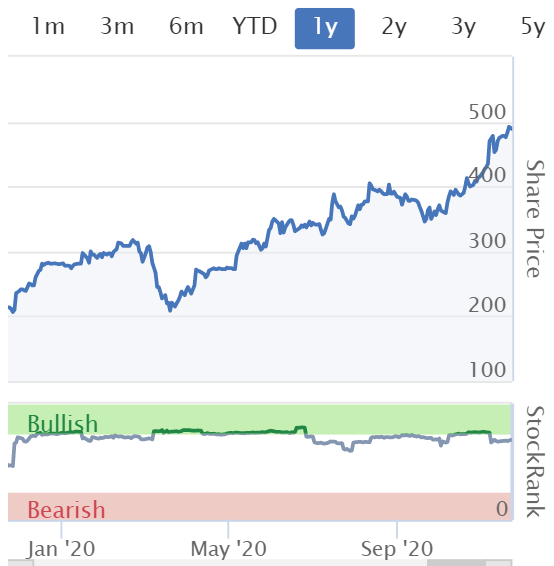
TTWO shares are currently $170.0 each (volatile price lately), which (including the 120p cash element) values this bid currently at 480p
Are TTWO shares attractive? It’s a big company, valued at £14.7bn, listed in the USA. Stockopedia data on it looks good, with a StockRank of 88, and strong/growing profitability;

TTWO certainly isn’t cheap, on a forward PER of 30, but look at the growth above! If you want good growth, you have to pay up for it at the moment.
It’s worth noting that TTWO has a large, and growing cash pile, most recently $2.4bn. So it’s not clear to me why it is mainly using its shares are currency for the CDM deal? It can, and should pay cash! I don’t like takeover deals using the acquirers shares, as it creates an overhang of sellers who don’t really want their new shares.
Is the takeover price attractive? Probably not I would say, but I don’t have any up-to-date forecasts for CDM. Based on these interim figures, then the full year results could be 20-30p maybe? If so, then that would make the takeover price somewhere between PERs of 16-24 - hardly a knockout price, for a rapidly growing group.
I’d be inclined to reject the takeover approach. It needs to be higher priced, and all in cash. 600p+ strikes me as the right starting point.
Why on earth has CDM management recommended this seemingly ungenerous bid? The commentary says it’s a good deal for the company’s progression, but is it a good deal for shareholders? Do management have enough skin in the game to make the right decision for shareholders? Have they got the backing of the biggest shareholders? I don’t know.
My opinion - it looks an interesting company, but remember that a fair chunk of the profits come from favourable tax arrangements. Profits in this sector come from churning out new games, with a rapid payback, then a long, slim tail of revenues once the novelty has passed. This makes me nervous of the sector. That said, it’s clearly a growth area, and the graphics on some of these new games are almost lifelike.
Covid lockdowns may have boosted demand, from people on furlough, which could recede as we go into (hopefully) more normal conditions in 2021. I like digital delivery, as that can disintermediate the retailers, resulting in higher margins for the games makers, maybe?
As regards the takeover bid, it just doesn’t seem credible to me. Why would shareholders want to exit at this stage, when the company is doing well, for a modest premium, and receiving unwanted shares for three-quarters of the price? Sure, TTWO is a liquid share and you could lock in the selling price by opening up a short position via a CFD or spread bet. Then sell your physical shares, and close the spread bet simultaneously, when they are issued.
In the meantime, I’d be asking management some searching questions about why they have recommended this deal? Maybe they know something we don't, and the price achieved is fair after all? Who knows?
.
.
This part written by Jack
Cerillion (LON:CER)
Share price: 329.9p (+4.73%)
Shares in issue: 29,513,474
Market cap: £97.4m
Cerillion (LON:CER) has a 20-year track record in providing software for billing, charging and customer relationship management ("CRM"), mainly to the telecommunications sector. It has around 90 customer installations across 45 countries.
The business was originally part of Logica before its management buyout, led by CEO and major shareholder Louis Hall in 1999.
Business has been good for the group and it recently announced its largest ever contract win in September 2020 (£11.2m) - but you could argue that its premium tech valuation (with a forecast PE ratio of 26.8 and a forecast PEG of 2.3) has so far muted the reaction.

Final Results
The final results look solid, with ‘all key financial performance measures reached record highs’. Running through a bit of the detail, we have:
- Revenue up 11% to £20.8m and recurring revenue up from 27% to 29% of total,
- At the year end, on an annualised basis, recurring revenue was up 57% year-on-year to £7.9m - so this looks to be accelerating,
- New orders matched last year’s record of £23.3m, which appears to represent a step change in activity,
- The Back-order book is up 41% to £31m
- Adjusted PBT up 7% to £3.7m and reported PBT up 8% to £2.6m
- Adjusted EPS up 10% to 12.4p and reported EPS up 13% to 8.8p
- Net cash up 54% to £7.7m
- Total dividend up 12% to 5.5p
Brokers were forecasting EPS of 10.4p. Cerillion’s adjusted EPS figure is calculated by taking profit after tax and adding back amortisation of acquired intangible assets, share-based payment charge and exceptional items.
I would add back the share-based payment charge of £68,727 but this is not a material sum and so the adjusted figures seem reasonable. On that basis, it’s a forecast beat and puts the group’s shares on an FY20 PE ratio of 25.4.
The Group's revenue streams are categorised in three segments: software revenue (comprising software licences and related support and maintenance sales); services revenue (generated by software implementations and ongoing account development work); and revenue from other activities (mainly from the reselling of third-party products).
- Software revenue fell by 16% to £7.6m (2019: £9.1m) and accounted for 37% of revenue. This was due to the reduction in licence sales during the year to £1.6m (2019: £3.9m).
- Services revenue increased by 44% to £11.3m (2019: £7.9m) and comprised 54% of total revenue (2019: 42%). This was due to a significant increase in new customer implementation work.
- Third-party income remained constant at £1.8m (2019: £1.8m) and comprised 9% of total revenue (2019: 10%).
Conclusion
The trend is encouraging here and Cerillion’s CEO does say:
Revenue, pre-tax profits and the back-order book are at record levels, and we closed our largest ever contract win in the final quarter of the financial year, continuing a trend of larger wins.
So perhaps it can push on, continue to win bigger contracts, and grow into its valuation. That must be what holders are anticipating, and Cerillion has a decent chance of achieving this.
Founder and CEO Louis Hall owns 30% and institutions have been increasing their stakes, so they must see potential.
Demand for billing, charging and CRM solutions in its core telecommunications market is forecast to rise, with 5G rollouts driving a wave of investment in both telecoms infrastructure and ancillary systems. Cerillion also has that healthy order book.
It’s looks like a high quality operator too, with strong cash conversion, prudent finances, and double-digit returns on capital and operating margins. Of its c£25m of assets, only around £7m are goodwill and intangibles (while cash and accounts receivable come to nearly £15m). It has paid down £1.2m of debt this year and expects to pay off its remaining outstanding debt in FY21.
Furthermore, with gross margin coming in at 74%, perhaps there is scope for decent operating and profit margin expansion here as well.

The main concern here is probably generating that earnings growth in a timely manner in order to justify the premium valuation. But given the recent large customer wins and existing positive market trends, it looks like Cerillion has a fair chance of achieving this in my opinion.
.
We ran out of time today, but I'm doing some more sections early for Tuesday's report (on Monday evening).
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
re Codemasters Group (LON:CDM) :-
"Frank Sagnier, Chief Executive Officer of Codemasters, and Rashid Varachia, Chief Financial Officer of Codemasters, along with the senior executive management team of Codemasters intend to remain with Codemasters following completion of the Acquisition and will continue to lead the Codemasters business within Take-Two's organisation and its 2K label"
I wonder if they've already negotiated their remuneration packages?
Re Codemasters Group (LON:CDM) sure they have already agreed the current options packages will vest and pay and and then they get a load more, excellent for managers, stick up for shareholders, this type of takeover situation is not uncommon, third time for me. They will be staying on, as confirmed in earlier RNS.
don't they have a responsibility to act in the interest of all of their shareholders?
The problem that always arises in these situations is that if the dissenting shareholders win and keep the company independent who is going to enthusiastically run it? The management who have just been denied a large chunk of money and continued employment (if they want it)?
I am a holder and agree that the bid is too low, but while a higher bid would be better, a lack of a bid could be a serious problem. I am reminded of the great success the shareholders did (NOT!) have when Revolution Bars management recommendation of a takeover was voted down.
In respect of - News announcement @ 22/11/20 https://www.itv.com/news/2020-11-21/chancellor-rishi-sunak-to-announce-500-million-package-to-support-mental-health-services
Perhaps a beneficiary would be Kooth (LON:KOO) . I hold.
Recently ipo-ed. An excellent write up can be found on https://martinflitton1.wixsite.com/privatepunter/post/kooth-plc-09-09-20
Strong list of inst. Investors (includes a PE firm).
BULL POINTS:
- online therapy is probably the way forward with counselling (faster turnaround, convenient access vs commuting etc)
- mental health awareness and its importance is increasingly growing in 2020
- government pumping in £500 million into mental health package. Likely beneficiary is Kooth (LON:KOO) (Per AIM admission doc : The Directors of the Company believe there is potential to replicate Kooth’s success to date in providing services to children and young adults into the NHS adult market. The NHS spends around £11 billion annually on adult mental health services and the Company has identified a potential £300 million addressable market for Kooth Adult. The product was launched in Q4 2018 and is gaining traction. As at 30 June 2020, Kooth Adult had 10 customers contributing £500,000 annual recurring revenue to the Group )
- Kooth are targeting corporate market as well (reduce sickies, increase productivity). Per AIM Admission doc - A research report by Deloitte published in January 2020 estimated that mental health-related issues cost UK businesses up to £45 billion annually and that every £1 spent by employers to tackle mental health related issues results in a £5 return on investment. The Directors believe there is a £150 million addressable market in the UK. Kooth Work was launched in Q2 2019 and as at 30 June 2020 was delivering £260,000 annual recurring revenue from its eight customers. )
- Opps to license our software to overseas healthcare providers + earn license fees. Co. Is beginning to explore them.
- Rev for H1 FY 2020 (YE 31st Dec) vs H1 2019 – YoY circa 50% growth.
- Net cash of circa £8mn (after listing and paying off the oan of £5.3mn @ 30/6/20 + is from the PE firm that is a shareholder. That should give a few years runway.
- Rev is recurring
BEAR POINTS
- Spread is 400bps
- still loss-making (strong rev growth though).
- stock liquidity may be low – given 85% is owned by insti. Investors
- receivables high - £1.4mn 2019 – mainly NHS – so not much of an issue
- Intangible NA are high – due to mainly software dev.
AIM Admission doc - https://investors.kooth.com/wp-content/uploads/2020/09/x_174048-Project-Peace-Admission-as-printed.pdf
BTW - Lord Lee and the Naked Trader are shareholders.
Key Driver – Additional spending of £500mn by gov + willingness to outsource NHS non-core services to 3rd parties likely will benefit £KOO. Usual caveats – dyor
Perhaps a beneficiary would be Kooth (LON:KOO) . I hold.
Me too, although only a taster stake. Fascinating company - it's a technology platform really:
Our technology is separated into three parts – the service for users, community/clinical engagement and insights and intelligence. We use co-production to build out our welcoming user friendly platforms. Our service users are provided with a range of different therapies and tools that they can use to set goals and receive support.
Our patient administration system has been designed and built with counsellors to ensure it meets the needs of therapeutic intervention and our insights and data technology is built in conjunction with our clients and research and evaluation team.
https://www.koothplc.com/about...
I'm really keen on tele-medicine providers, looks like an obvious area of growth, albeit one that's been impacted by the focus on CV-19 this year.
timarr
Paul
You commented positively on Carr's (LON:CARR) 's trading update on July 15th. Today's results look better than the consensus estimates in Stockopedia for Revenue and Profit but not for EPS, which I don't understand as the share count hasn't changed. What am I missing?
Excellent work Paul on Codemasters. I have ben a shareholder for some time and of course they've done really well as have a lot of gaming companies but I just don't understand accepting a bid at this level. Bid looks very opportunistic to me and I don't want shares in TTWO.
As a codemaster Codemasters Group (LON:CDM) shareholder myself , I'm very disappointed with the management , one has only to look at other companies in this sector and see there growth numbers for example Corsair gaming £crsr who makes gaming accessories who recently beat estimates. see link below
This sector is forecast to grow at 13% annually for next 7 years, see second link below
https://ir.corsair.com/news-releases/news-release-details/corsair-gaming-reports-third-quarter-2020-financial-results
https://www.grandviewresearch.com/industry-analysis/video-game-market
Braemar Shipping Services (LON:BMS) announced news for their 27% associate listed in Norway AqualisBraemer (AB). Braemar Shipping Services (LON:BMS) shares are up 5% and i'm not surprised - AB shares are up 20% which alone adds 8p to BMS NAV.
I've had a more detailed look.
Braemar Shipping Services (LON:BMS) has big CASH flow (albeit cyclical industry) but also high(ish) debt (2 times). there is also a deferred acquisition payment looming (half shares/half CASH) but i dont worry too much about that as it is performance contingent.
However, the 27% stake in AB is worth c.£13m but BMS might also get warrants for shares worth up to a further £4m (in my analysis i estimate only 2m though). I don think the market realises that BMS has this safety net investment to offset its debt.
the acquistion is a major step for AB. it is same size. They are paying c.4times EBITDA and the business has net CASH. AB estimate that there are synergy savings of 3.5m p.a. (that would add 20%! to the pro-forma profits. AB is already on a low rating but shar price is re-rating. AB is looking to be 50% into renewals (offshore wind by 2025). So it really is re-inventing itself IMHO.
I think this is all then really interesting for £BMS. b/c AB is now much larger it will be easier for BMS to dispose of its stake. I also think that the larger size and merger cost synergies will give AB a chance of obtaining a higher rating that currently on higher profits. i,e. BMS is sitting on a potential valuable stake in a renewables growing business.
Braemar Shipping Services (LON:BMS) is valued lowly as it is cyclical and has debt. I think the investment in AB is being ignored and b/c it offsets the debt, and the mgt turnaround situation, that the low rating is unwarranted.
disc I hold. I am value investor.
Braemar Shipping Services (LON:BMS) seems to be very illiquid. Maybe that's holding it back.
Braemar Shipping Services (LON:BMS) certainly this morning it was a very tight market. but over the past few months i've found it ok to deal most (but not all) days i tired. for me, i am value investor and see the opportunity to buy steadily and wait for the mgt restructuring efforts to be complete and then (hopefully) be recognised by the market over a couple of years
Useful 352 - I bought LON:BMS just after the recent results - liked what I saw and your analysis only adds to my view. Also, like you, I found it easy enough to buy - but maybe because it was a down day.
Further on Codemasters Group (LON:CDM) the top three holders are:
Slater Investments 9.32%
Swedbank Robur Fonder AB 9.5%
Artisan Partners 8.27%
That is enough to block the Scheme of Arrangement but will they?
Codemasters Group (LON:CDM) Paul asks: "Why on earth has CDM management recommended this seemingly ungenerous bid?"
Here is what the Daily Mail said (with thanks to Nick Hewett who pointed this out here on the 13th) :
Codemasters chief executive Frank Sagnier would make £15.7million if the takeover goes ahead, while finance boss Rashid Varachia stands to make £7.1million.
Ian Bell, head of Slightly Mad Studios, which Codemasters bought last year, would make £9.2million.
https://www.dailymail.co.uk/mo...
But if the bid offer for Codemasters Group (LON:CDM) was higher say 560p, then presumably these directors would make even more money?
We do not know whether the directors have been offered roles with the purchaser or whether it is just the opportunity to cash out that makes it so attractive to them
Regardless it seems v clear they are not working for shareholders
Even more absurd, on the face of it, than them accepting this offer it would make no sense if shareholders vote this giveaway through.
Equally given the performance of the business surely there must be a counter bid - even wholly cash at say 550 p would be vastly superior
This is all so odd that maybe there are things we don’t know - I’m afraid I always think of Patisserie Valerie, as well as a few others!!
With apologies for not writing this sooner. Total Produce (LON:TOT) have released an RNS indicating that results for this year will be slightly ahead of last year's. I bought Total Produce (LON:TOT) on the dip earlier in the year for three reasons. 1) The chairman, CEO and CFO were all long-serving Fyffe employees (at Board level). 2) They are in the process of taking over DOLE Produce that is in private hands. 3) People will always want to buy fresh fruit. If this goes well, it will significantly grow the company. I believe it will as these board members know well the business they are in. I bought Fyffe shares c9 years ago at c30p. Fyffe was sold to a Japanese company for c180p a few years later. One of my better purchases and I'm hoping for a repeat performance - though not necessarily for it to be bought out.
Since the Aa (LON:AA.) is a topic today and I've talked about it in the past here's an update...
https://www.stockopedia.com/co...
(I started as SCVR comment but it got a bit long)
Would just like to day Paul and Jack on the days you work together the sheer volume and quality of content is first class I haven't seen a dynamic duo like this since Batman and Robin.
I was musing Del and Rodder's for the dynamic duo but although hugely loved they were better at losing money than making it a bit like my early stock market years anyone remember Minmet and E Capital :)
Regards Andy
Bids everywhere or so it seems. As well as those already mentioned today above, there is confirmation of the bid today for Countrywide (LON:CWD) by Connells at 250p cash per share following due diligence (subject to agreement by the Board). That is a thumping premium for a share that was bumping around 50p / 60p in April. Another company that is loaded with a lot of debt. I suggested a few months back on here that this estate agency holding company had a lot of well known brand names; again this looks like a very good exit price for shareholders IF the Board recommend. They have been very quiet so far.
Commenting today, David Livesey, the Connells Group Chief Executive, said:
"Countrywide shareholders have repeatedly been promised jam tomorrow and it has never been delivered. There is no quick and easy fix for Countrywide. Turning the business around, especially in unpredictable market conditions, will be a difficult, expensive and lengthy process. Countrywide needs new ownership, not yet another speculative scheme that is based on hope rather than experience. Our proposal gives Countrywide shareholders significant immediate upside in cash, at a 72% premium to the undisturbed price, with none of the downside risks of remaining independent."
So who is next? Two likely candidates are moving up strongly today. Quiz (LON:QUIZ) and Works Co Uk (LON:WRKS) but who knows? Nothing makes the market get more excited more than a stack of takeover bids in my experience. Cash is cheap, the UK stock market is very cheap compared to its peers and there are so many possibilities. Something like Stanley Gibbons (LON:SGI) has a wonderful brand going back hundreds of years but there again there are just so many candidates. Would shareholders now take 50p for Revolution Bars (LON:RBG) when they turned down £2 before?
Perhaps one issue is that this time has concentrated directors minds? The usual response that "this is an opportunistic bid that undervalues the company" seems to have gone missing for the moment. A bid a day is good for the markets (and shareholder wallets!).
Some weeks ago I suggested that we would greatly benefit from one of the main contributors on here giving us a heads up on how to spot potential take over targets using the stock reports (assuming this is possible) plus other supporting data. This got a high number of up ticks, so as the 'urge to merge' is clearly on the rise I am repeating the suggestion again.
Back to the report layout discussion, sorry. It was only after reading Paul's last post that I realised he was going to write about Codemasters Group (LON:CDM) . Would have missed it otherwise. I still think it would be better if the write-ups could be put in the order they are written so readers only have to scroll up to find the first one they haven't read earlier rather than, today, having to scroll up through all of Jack's musings to see if Paul has added anything further.
Maybe it's different on the new site, in which case apologies for bleating.
It's just work-in-progress until the official finish time of 1pm (or sometimes later). By all means check it out before 1pm, but don't expect everything to be polished up & ready!
Thanks Paul but I obviously didn't explain myself very well.
Never mind - I guess it's not the end of the world.
Re £Boo, in my experience Judges are extremely wary of throwing out even the flimsiest of cases.
This is a shout out for those questioning the Boohoo (LON:BOO) drop....note this comment does not point to cause of the drop it's just a bit of intel on market sentiment for anyone interested.
According to the FCA's daily shorts list (23/11/20) we can see that 1.75% of the share cap is shorted at present.
Interestingly, Shadowfall are not there.....so perhaps they have moved on to other pickings......
AFAIK Shadowfall never had a declarable short on Boohoo (LON:BOO) - Matt Earl is not that big league.
Tks Gromley – BTW I read and enjoyed your beginner guide to balance sheets post at the wkd:
So edit on the above:
There may well be more than 1.75% of the Boohoo (LON:BOO) issued share capital being shorted..but in terms of what is disclosable to the market this is what we know.
FCA Rules
A private share notification must be made when the net short position in shares reaches 0.1% of the issued share capital of the company concerned, and again at each 0.1% increment after that.
This relates to both increases and decreases of the position (including each time the position drops from 0.1% or above to below 0.1%).
A public share notification must be made when the net short positions of shares reach 0.5% of the issued share capital of the company concerned, and again at each 0.1% increment after that.
The heavily populated Southern part of China is creeping slowly towards it Winter months. I would expect more outbreaks during this period. They have a relatively short Winter compared to the West, so will be interesting to watch.
Hi everyone, I'm relatively new to all of this but have been reading the SCVR every day for the past month or so and am very grateful for the insights! Thanks for making it always easy to understand.
I bought Mccarthy & Stone (LON:MCS) before the takeover talk and it's my largest winner to date, but from what I can understand, many large investors are selling chunks of their shares - what are others doing with theirs?
Paul mentioned a couple of weeks ago that he'd sold his, am I being foolish holding and hoping for another rise? I'm not sure how long takeover talks usually go on for before a deal is done/falls through.
Cheers!
Isn't the bid for 115p, the same as the market price? Haven't the largest shareholders and the Board agreed? Then surely you would sell? Why hold on? Find another undervalued share and invest the money. Good luck.
Any opinions on the Telegraph's article attacking BooHoo for offering fake discounts?
Is it just another media attack that is unlikely to have much impact on BooHoo's prospects?
Just read this on Retail Gazette. It doesn't look good if the court rejected BooHoo's attempt to dismiss the case.
Standard part of the process.
It's a fact right? It's not just a "media attack", it's in front of the US courts.
I'm long Boohoo (LON:BOO) but there's no point sticking my head in the sand about this. I await the resolution and whilst losing this case wouldn't be good as £75m is a significant slice of profit, I don't see it mattering too much over a 5 year view.
I've asked Boohoo (LON:BOO) about this US legal case, and they said it's not a concern at all.
Old news Meldrew, today The Times has a full page spread on Ethical Investing Funds - you know funds that don't invest in nasty companies that make land mines and such like. Standard Life Aberdeen's Stephen Bird, cites how's he's upping his game and gives an example. Now, normally its tough making the business pages eye catching, but I (Patrick Hosking) have an idea - how about we fill half the page with a picture of skimpily dressed girls? And the company he uses as an example - yep you've guessed it LON:BOO!!! I beginning to wonder if all this attention isn't going to ultimately help BOO, if nothing else it keeps the brand in the public eye.
My theory about all this ESG stuff, and the impact on Boohoo (LON:BOO) is that it's depressed the price, as lots of fund managers are presumably dumping their stock. However, given that the ESG issues have been very openly published by BOO, and it's taking determined action to fix everything, then the next logical step (I know not when) could be fund managers looking to buy back in because the ESG issues have been resolved.
Hence, if combined with continued strong trading (why wouldn't it be given that customers don't give two hoots about ESG, and BlackFriday is end of this week, with physical competition shut), then hopefully we might see the share price begin a sustained recovery.
I've suggested to BOO management that they switch to a NASDAQ listing. Valuations are sky high there - e.g. look at FarFetch, It's about the same size as BOO, is valued at £12bn, yet it still makes massive losses! Given that BOO is growing its sales in the USA quickly, then I reckon investors there would see the upside as considerably higher than UK investors, hence switching the listing would make a lot of sense in my opinion. Although possibly some tax issues for shareholders?
Risk:reward looks absolutely outstanding to me, with a 2-year (or more) view, hence why this is my largest position, and I'm still buying.
Regards, Paul.
The press certainly have it in for Boohoo (LON:BOO) at the moment. Today's Times has an article about the new CEO of Standard Life Aberdeen headlined, 'Public 'can smell if you're an ethical investor or not'' with a substantial description of why he sold his Boohoo shares. It's illustrated with a colour photo of two Boohoo models.
I don't see this sort of thing affecting the sale of Boohoo's product at all.
Re £Boo, In my work I have been involved in moral panics (eg mental health or learning disabilities scandal in a hospital or care setting). One quickly learns that whatever the organisation that is trying to do to address the concerns, it doesn’t matter, they have to continue to adopt regret, humble apologies, action ‘we are taking/have taken’, ad nauseum. And then one day it stops. The ‘concerned’ people have had enough, the issue is too old, whatever, it just falls away.
So my only concern is not what the media say, but rather what £Boo demonstrates as their actions to put these issues to bed....and as you say to also continue to deliver excellent growth! I look forward to their next results.
Over the weekend I was researching Saga (LON:SAGA) thanks to Paul's helpful recent articles and would like to raise some points/ask some questions to help my research. Sorry if this is a bit off topic today but I think a number of us on this site have been looking into Saga (LON:SAGA) so I hope this is helpful to raise but I am happy to move this chat elsewhere if preferred.
There are two issues that make me nervous in buying (more*) shares:
1. The insurance business
Total insurance business revenues fell, by my calculations, from £763.8m in the 6 months to July 2018 to £700m in July 2019 and £608m in July 2020. Profit before tax has also declined from £763m to £608m during that time-frame. Does anyone understand what is happening here? From the different annual reports it sounded like the market has become more competitive and maybe Saga (LON:SAGA) have ruined their relationship with some of their existing/previous customers? I see their margins were previously quite good, so have they started to lose out to lower margin insurers?
I never usually touch insurance businesses as I don't understand them or their market very well, so I might be overlooking some regulatory or other external changes.
2. The travel and cruise business
The profitability of the travel business doesn't look great to me although admittedly if it goes back to 17-18 things look a bit better.
The business has mentioned each new cruise ship would produce £40m pa EBITDA although the company suggests (slide 45) this assumes 999 'berths' 365 days a year if I have read that correctly <- isn't that max capacity? As someone with a still basic understanding of balance sheets I am not quite sure how EBITDA translates to a rough profit before tax figure - any idea?
A more minor gripe is that their results presentations seem unbelievably long and wordy. I say 'minor' but these presentations give you a slight impression that management hasn't adequately sifted through or analysed all the information presented to them internally.
*I currently hold after I broke my own rule not to buy during price volatility. I began researching and had an initially positive impression, then had fear of missing out after the 30% price rise so i dipped my toe in! Now sitting on a loss of course...
The Competition and Markets Authority has been seeking to remove the "loyalty penalty" from a number of markets including insurance. They also found last week that "Most favoured nation" agreements with price comparison websites whereby they agree not to allow pricing below that shown on the comparison website are illegal and fined CompareTheMarket £17.9m
My own experience with Saga makes me think that a fair part of their insurance profit historically came from rolling over policies at higher prices in an era when their customers were less canny at shopping around online. They have adapted their proposition to offer fixed price multi year policies in response to the CMA concerns. I don't know if that allows them to protect their margins.
https://assets.publishing.serv...
https://www.gov.uk/cma-cases/p...
Hi Patrick L,
If you look at the recent interim results for Saga (LON:SAGA) , the insurance business is doing OK - profits of £70m in the half year (flat vs LY H1) looks pretty respectable to me!
Re cashflow for new cruise ships, it's £80m expected EBITDA. I reckon the interest cost on the relevant financing is about £25m p.a. Depreciation charges and maintenance might be, say £10m pa. per ship, at a rough guess? So I make that a pre-tax profit to the P&L of about £35m, very rough figures I hasten to add.
Plus the travel division sells holidays from third parties, which should do very well once travel resumes.
I'm working on the basis that the elderly probably get vaccinated between now and March, hence the travel sector may be able to re-open from maybe April or May 2021?
As Saga said (several times) in the results webinar recently, "demand [for the cruise ships] will not be a problem". People are itching to go cruising again, having been denied it in 2020. Hence I foresee several bonanza years, when Saga's brand new, all balcony ships (with fresh air ventilation, not recycled air) are likely to be in very strong demand. They're not cheap either, I was quite taken aback by the cost. But it's the oldies who've got all the money! Properties owned outright, and final salary pension schemes. Hence why it's such a good demographic to think about when investing.
(I hold, now my 2nd largest position)
Clearly there's been a seller in the market in recent days, but once they're done, we might see the upward trend continue. Not that it matters really, as personally I'm taking a 2-year view on this, and think it could multi-bag over that time, if Sir Roger + team's efforts to take the brand back to basics, of unique services and tip top customer care, bear fruit. I don't think anyone is denying that the brand has been damaged by poor management over last 15 years, but it's still one of the most recognised brands out there, and potentially very valuable, if it regains a positive reputation.
Oh I nearly forgot, I thought your criticism of its presentation being too long & detailed, seems odd. As a shareholder, I want as much detailed info as possible, so for me that is a positive!
1. The insurance business
Total insurance business revenues fell, by my calculations, from £763.8m in the 6 months to July 2018 to £700m in July 2019 and £608m in July 2020. Profit before tax has also declined from £763m to £608m during that time-frame. Does anyone understand what is happening here?
Yes, it looks like you've typed up the wrong numbers! Could you check this bit please? ;-)
Regards, Paul.
oops! Yes PBT for insurance has gone from 109.3m to 70m according to my notes - I'm out and about right now so can't double check that figure but I think the company stated it clearly. Sorry about that.
Thanks Paul for the really helpful response.
Hi Patrick. I hold £Saga, but wouldn't be surprised if the insurance take did continue to decrease.
I presume a large % of their target market is still not that tech savvy and so might just accept the renewal. Look at the outrage, mainly from this age group, at NS&I because they wont send out premium bond any more and it’s all online.
My mother is in this age group and I am helping with her become more tech savvy.
I also help her with quotes for travel, car and house insurance.
I have been shocked at the sky-high quotes I have got from Saga, in some cases 4x the price of other insurers quote.
Maybe Sage are happy to have such a massive profit margin for the clients who can’t be bothered or aren’t tech savvy to look elsewhere. But as more do become used to getting quotes on the net, Saga may find their insurance take dwindling, unless they stop ripping their customers off.
Gambling on a takeover bid at an effectively insolvent company, is complete madness, in my view.
I made this mistake with Flybe a couple of years ago. Company was losing money hand over fist and I believed the hype that their landing/takeover slots at heathrow would mean they would be sold at 50/60p and bought in at 20p. Several months later my jaw dropped when I saw them sold for 1p (I managed to get out at 4p suffering a 80% dilution.)
I learnt a couple of lessons there
1. Never but a stock just because you think it could be taken over (it must have the business and results behind it)
2. Don't believe the crap on twitter and other forums with people with clearly hidden agendas
3. Buy stock in companies that are solvent , profitable or a clear path so profitability.
I learned this lesson the hard way and got wiped out on Flybe too!
I also got Flybe completely wrong. I focused on the balance sheet, which was actually in reasonably good shape, as they owned some aircraft, which were on the books at more than the debt. Hence I assumed they could do sale & leaseback of the planes if they needed more liquidity.
As it turned out, clearly the planes were not worth what they were on the books at, and/or lenders were not prepared to refinance them.
Then I remember both BA and Virgin were mooted as potential bidders. The shares were about 20p at that level, and I cheerfully thought a bid might come through at c.50p. Shortly afterwards the bid came through, at a penny!
It was a total fluke that I happened to have sold just beforehand, and I calculated that if I hadn't had sold, then I would have take a £60k loss - which would have been painful.
Since then I've been much more careful in my approach towards struggling companies. They must have cash on the balance sheet, and little to no debt, to interest me. Otherwise I tend to avoid, or just take a small position if there's multibagger upside potential.
Regards, Paul.
P.S. Thanks for the reminder on Flybe. Always good to revisit our mistakes, and refresh our memories, so that we don't make the same mistakes again.
I can't access this article but sounds like Boohoo (LON:BOO) hasn't been successful in stopping the discount claims lawsuit from going ahead in the US. Anyone have a sense of the potential financial impact if they lose? https://www.telegraph.co.uk/business/2020/11/22/lawyers-quiz-boohoo-executives-fake-discount-claims/
I have read the article, here are some extracts "The fast fashion retailer is accused of offering big discounts to customers based on inflated original prices which were almost never the prices it had previously asked customers to pay... The court sided with the lawyers bringing the legal claim but reserved judgment on one technical legal argument about whether it has jurisdiction over the parent company in the Boohoo group....They should admit what they’ve been doing is wrong, issue refunds to the customers they have misled, and put a stop to the fake sales and false advertising" Boohoo didnt comment
A few things here:
1) AI law is a one man band. this is most likely on a contingency basis (no win no fee)
2) This was raised in the USA - the court believe it doesnt have jurisdiction so unlikely to go anywhere
3) If there are genuine issues with discounting, this wouldnt be just an issue with Nasty Gal etc Amazon and many others have been accused of the same practices especially around Black Friday deals
Hi Patrick,
I won't paste everything for copyright reasons, but here are a few paragraphs from the article:
<<Top executives at Boohoo (LON:BOO) are set to be quizzed by lawyers after judges rejected the retailer’s attempt to dismiss a $100m (£75m) legal action over “fake” discounts.
The fast fashion retailer is accused of offering big discounts to customers based on inflated original prices which were almost never the prices it had previously asked customers to pay.
Manchester-based Boohoo and its subsidiaries PrettyLittleThing and Nasty Gal failed this month to persuade judges to throw out the class action lawsuit.
The court sided with the lawyers bringing the legal claim but reserved judgment on one technical legal argument about whether it has jurisdiction over the parent company in the Boohoo group.
The US lawyers behind the claim said they now expect to take testimony from Boohoo’s executives and high-ranking managers.>>
(it goes on to make reference to supply chain concerns and resignation of the auditors)
"A Boohoo spokesman said it intends to rigorously defend the legal claims" there is nothing about the potential impact. The case is not yet at the stage of discussing the potential scale of damages, they were just debating whether it could be heard at all.
Paul can you cover Cineworld (LON:CINE) if possible on the debt deal.
(went short end of last week as hadn't realised what a run up it had on covid news. Sided with your PoV that ultimately it should be 0p but market thinks otherwise. Feels like a lifeline and dilutionary warrants issued before they need to go again with a bigger raise maybe?)
Sounds interesting, OK I'll look at Cineworld (LON:CINE) next, it follows on nicely from the piece I've just written about debt-laden Aa (LON:AA.)
Thanks Paul for £CINE. starting to wish maybe i hadn't gambled either. I totally agree with you on where is the upside for shareholders on all this, just maybe some short covering at the moment as it gives them some certainty over being able to continue in business for the foreseeable . not sure where the earnings is going to come from to cover all the debit + interest and it'll end up being an AA but a lot worse with negligible equity value
Good morning Paul -it would be great if you could have a look at Thruvision (LON:THRU) (Thruvision) who appear to be under the radar ( excuse the pun ) as they are the " leading provider of safe distance, people security screening technology." Despite covid effecting the first half completely they managed to maintain sales and have achieved break even ebitda for the first time and net cash of aprox £8 million .Considering one of their main markets is aviation this is pretty resilient and reflects the success they have had in the logistics and retail distribution sector where non invasive screening is becoming increasingly important as online sales increase. As the aviation , travel and mass transit markets open up in tandem with vaccine introduction I don't see how they will not benefit. I would be interested to know if you share that view.
Hi fred9566,
I've had a quick look at Thruvision (LON:THRU) interim results, at your prompting, and have decided against covering it. Reasons;
Many years of losses, and still loss-making in today's Interims
Since there are no profits, actual, or forecast, then how can we justify the £37m market cap? It rests entirely on hopes of future improved performance. It's not really my job to guess at what the future might hold for this company & its products, so I can't really take it any further.
As you say its cash position looks healthy, so unlikely to go bust.
It looks a serial disappointer.
Outlook comments don't exactly exude confidence either.
There must be better situations to invest in, surely, than this?
Sorry about that.
Regards, Paul.
Hi Fred9566
I don't know if anyone else has better insight into this company - obviously it is still a "blue sky" proposition, and I can understand Paul's reasons for being reluctant to spend time on it. My own feeling is that the results are disappointing if compared with what they were hoping for a year ago. However, if you consider that their main markets are in retail and mass transportation, then static revenues and approximately neutral cash flow are surely a pretty good outcome. The worry must be that, after the disaster of this year, there may be quite a time lag before potential customers resume talking to their sales team. So there has to be a risk that the next 12 months could still be pretty duff. I hold.
Hi Paul thanks for the reply -on the face of it you are correct but Thruvision has only been in its current form since November 2017 and prior to that it was a division of Digital barriers . It now focuses on loss prevention and border control markets .Sales have increased from £2.024 miilion in 2017 , £3.103 million in 2018 , £6.0 million in 2019 and £8million in the year to March 2020 . Without the effect of covid on aviation this projection would have continued - as well as the cash there is a good gross margin 48 %. Like you I would not normally look at something like this but I believe this could be a very interesting proposition as the effects and changes from covid roll out over the next 12 months . As you often say we are trying to look forward at least 6 months when looking at a share
Thanks for the reply
Thruvision (LON:THRU)
Fred/Sunday Trader
Thanks for sharing your thoughts on this company.
I didn't realise until now, but it's actually on my main watchlist (with no private notes sadly) so your comments prompted me to look further (again?)
It looks quite good actually - growing fast and not burning cash - and at least worthy of more research, so thank you.
Cheers
A
Cake Box Holdings (LON:CBOX) management are joining us today at 3pm to run through their investor presentation. All welcome. https://zoom.us/webinar/register/5516061182295/WN_XQzArQhnRKqo3Ps8WxmVUw
Hi Paul, if you have time I would be grateful for your views on Codemasters in the light of the positive H1 results today and the rather low offer on the table from Take-Two Initiatives which is being recommended by the Board
Hi banterex,
I don't think there's much I can add to Codemasters Group (LON:CDM) as it's not a sector I have any knowledge of. But seeing as so many readers seem to be interested in the company, I'll take a look at it next. Just don't expect any particular pearls of wisdom, but will try my best!
Regards, Paul.
My morning smallcap tweet: Long winter for Summers at GMS?
AA (LON:AA.) Xpediator (LON:XPD) £CMC McBride (LON:MCB) Gulf Marine Services (LON:GMS) US Solar Fund (LON:USF) Avacta (LON:AVCT) Gresham Technologies (LON:GHT) Total Produce (LON:TOT) Rua Life Sciences (LON:RUA) Concepta (LON:CPT)
AA (AA.) long talks result in non-binding offer of 35p. Many expected a breakdown. [SP=33.55 Cap=209m]. I hold.
Xpediator (XPD) guides FY(Dec) adj pretax at least £6m, up 18% as trading continues recovery. "A new customs brokerage team has been established, set up to handle the likely increase in declarations whatever the Brexit deal outcome. If there is a change in border controls, then the Group believes it will have an increased workload." [SP=25.8 Cap=37m]
Chamberlin (CMC) The customer 75% of machine shop's output will take business elsewhere, in a earlier transition to the next product evolution. "Ongoing customer orders are likely to be a fraction of the original contract. The Company will be pursuing a claim relating to the earlier than planned transition and in the meantime all staff in the machine shop have been furloughed." [SP=NA Cap=NA]
McBride (MCB) FY outlook unchanged (a modest improvement in profitability) but uncertainties abide. [SP=65.8 Cap=120m]
Gulf Marine Services (GMS) CEO Tim Summers suspended pending an internal investigation into a severance agreement of 10 Nov re £429k payment to him on that date. [SP=6.92 Cap=24m]
US Solar Fund (USF) all 41 projects fully operating. Construction and development cost savings of c. $4m plus proceeds from better-than-expected pre-COD electricity sales of c. $1m (compared to assumptions at acquisition). This equals 2.5c/sh. [SP=1.05 Cap=210m]
Avacta (AVCT) rapid covid test: initial tests show very good analytical sensitivity. Will proceed to clinical trial. [SP=135.5 Cap=342m]
Gresham Technologies (GHT) framework agreement for Clareti with large bank, worth $2.3m min over 3 years. However it only boosts forward-looking recurring revenues by $0.2m PA. [SP=124.55 Cap=87m]
Total Produce (TOT) the chips are up, with FY(Dec) Sales, adj EBITDA and adj EPS now expected to be slightly ahead YoY. [SP=115 Cap=NA]
RUA Life Sciences (RUA) new design of heat valves easily passed required lab tests. Plans further refinement to manufacturing process for even better hydrodynamic performance. [SP=140.12 Cap=23m]
Concepta (CPT) buys The Genome Store, a recent start-up provider of home-administered postal genomic test services, for £0.28m and £0.24m contingent, all in shares. An initial portfolio of tests will be launched in Q4 2020. [SP=0.94 Cap=5m]
Bid for SThree (LON:STEM) if you have time please.
Upgrade to market expectations "marginally above the top end of the range" out today, and its been a member of the Jim Slater screen for a month or two.
Stock Rank of 99 and a Super Stock and Graham covered it way back in 2018 with the comment " My interest in recruitment companies has waned but I do think that this is one of the best ones, if not the best one."
You wrote a week or two ago that recruitment companies are the first into and first out of a recession, if you could cast your expert eye over this one to see if Graham's previous comment is still warranted, it would be appreciated. I hold.
oxford vaccine trial 70% successful
This is great news, particularly for developing countries. Cheaper and much easier to store and transport. The Astra-Oxford vaccine was always going to do the heavy lifting of a vaccine response. In addition, it appears that a half dose followed by full dose booster was 90% effective in that subgroup.
Fantastic stuff.
Doesn't it need to be 90%+ effective single dose to be practically useful ? (I am not a vaccine expert not an epiderminologist (sic?)
Currently influenza vaccines often (normally? not sure...) have much lower effectiveness than this. 90% is another great result. Strange that the results are being averaged in the press at 70%. If there are two regimes, one works at 60% and the other at 90%, surprise, surprise, the 90% regime will be used!
This is really quite astounding to have 3 effective vaccines (using I believe two different technical approaches) within a year! Presumably more to come from other research around the World.
Yes but it does seem unexpected that a half dose followed by a full dose works so much better than two full doses. One of those “intriguing” results as they say that raises more avenues to explore.
It would allow a third more people to get vaccinated for a given supply of vaccine.
Flu vaccines are less effective because there are so many strains, and the matching vaccines have to be chosen months before the flu season. based on forecasts.
Some experts are sceptical at the validity of the surprise result of one and a half doses haveing a better outcome than two, so sensible to take the 70% figure for nowI MO.
Using approximate numbers if they got a 70% average where the individual results were 60% and 90% then two thirds of the trial volunteers were given two doses and a third the one and a half dose regime.
IF that’s enough results to be statistically valid, and they seem to imply it is, then there’s no reason to rollout the two dose regime. So it will be one and a half doses and 90% effectiveness.