Small Cap Value Report (Mon 23 Sept 2024) - OMG, AWE, TRT

Good morning from Paul & Graham!
Mello Monday is tonight, with 3 interesting companies presenting, all of which I think are worthwhile for consideration by investors, depending on your investing style.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
Summaries
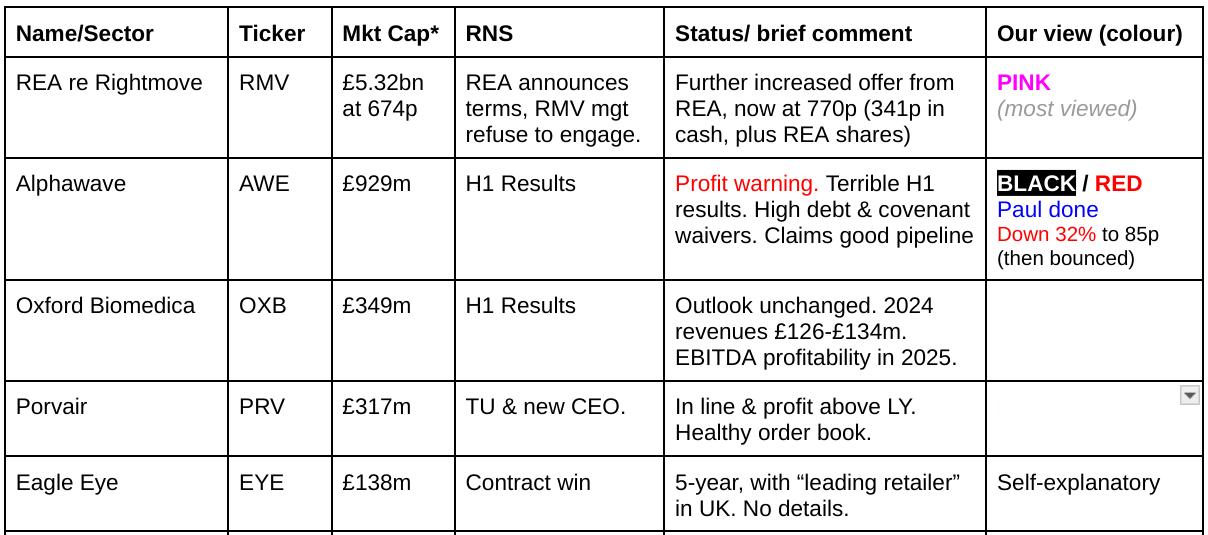
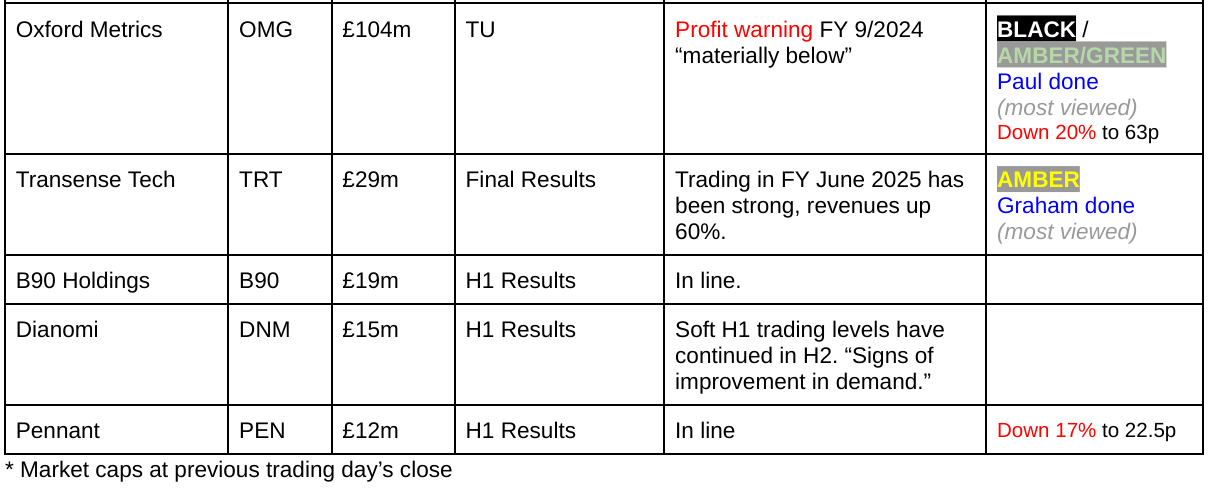
Oxford Metrics (LON:OMG) - down 20% to 63p (at 09:39) £84m - Trading Update [profit warning] - Paul - BLACK (PW), AMBER/GREEN (on fundamentals)
Misses its numbers for FY 9/2024, which surprises me since we were told in June that it had 90% full year visibility. Net cash pile of £50m is now well over half the market cap, sounds ear-marked for acquisitions - let's hope they do good one(s). Shares look attractive value to me now, possibly overshot on the downside?
Alphawave IP (LON:AWE) - down 30% to 88p (£647m) - Interim Results - Paul - BLACK (PW) / RED on fundamentals.
Shockingly bad H1 numbers, raise the question of whether this highly indebted company could be heading for zero? Total bargepole job for me, as mentioned 4 times previously this year.
Transense Technologies (LON:TRT) - down 4% to 182.7p (£28m) - Final Results - Graham - AMBER
Decent results from this company and they are accompanied by a very strong outlook statement. However, the group only has two trading businesses and they are both very small and early-stage. The outlook statement suggests that they are both about to have a great year but with revenues of only about £1m and £0.5m respectively, these are far too early-stage for me.
Paul’s Section:
Alphawave IP (LON:AWE)
Down 30% to 88p (£647m) - Interim Results - Paul - BLACK (PW) / RED on fundamentals.
One of my least favourite shares. The only thing I’m in AWE of, is how on earth did the brokers manage to get a multi-billion valuation at IPO in 2021?
Checking my previous notes, it’s been RED four times this year, so today makes it five.
23/1/2024 - RED (Paul) 134p - In line TU. But EBITDA doesn’t produce any actual real cashflow.
16/4/2024 - RED (Paul) 119p - Profit warning. Poor cashflow. Complicated accounts.
24/4/2024 - RED (Paul) 108p - Poor 12/2023 results. Weak bal sht. Are profits & cashflow real? Shares could be heading considerably lower.
1/5/2024 - RED (Paul) 114p - Clears out unsuitable NEDs.
On to today’s H1 results.
“LONDON, United Kingdom and TORONTO, Ontario, Canada, 23 September 2024 - Alphawave IP Group plc (LSE: AWE, "Alphawave Semi", or the "Company" and together with its subsidiaries, the "Group"), a global leader in high-speed connectivity for the world's technology infrastructure, announces its interim results for the six months ended 30 June 2024.”
What on earth does that mean?!
H1 numbers are terrible!
- Revenue down 51% to $91m
- Loss before tax in H1 of $(50)m (LY H1: $(6.6)m loss)
- NAV $439m, including $309m goodwill and $237m other intangibles, so NTAV is negative $(107)m
- Net debt up to $142m.
Bank covenants have been breached, but lenders have relaxed them.
Going concern is clean, although it’s totally dependent on lenders remaining co-operative, so not sure I’d place much reliance on this going concern statement. The company is clearly financially distressed, as it’s breached banking covenants. So I regard this share as high risk.
Outlook - it reckons things will improve in H2, and claims a large order backlog.
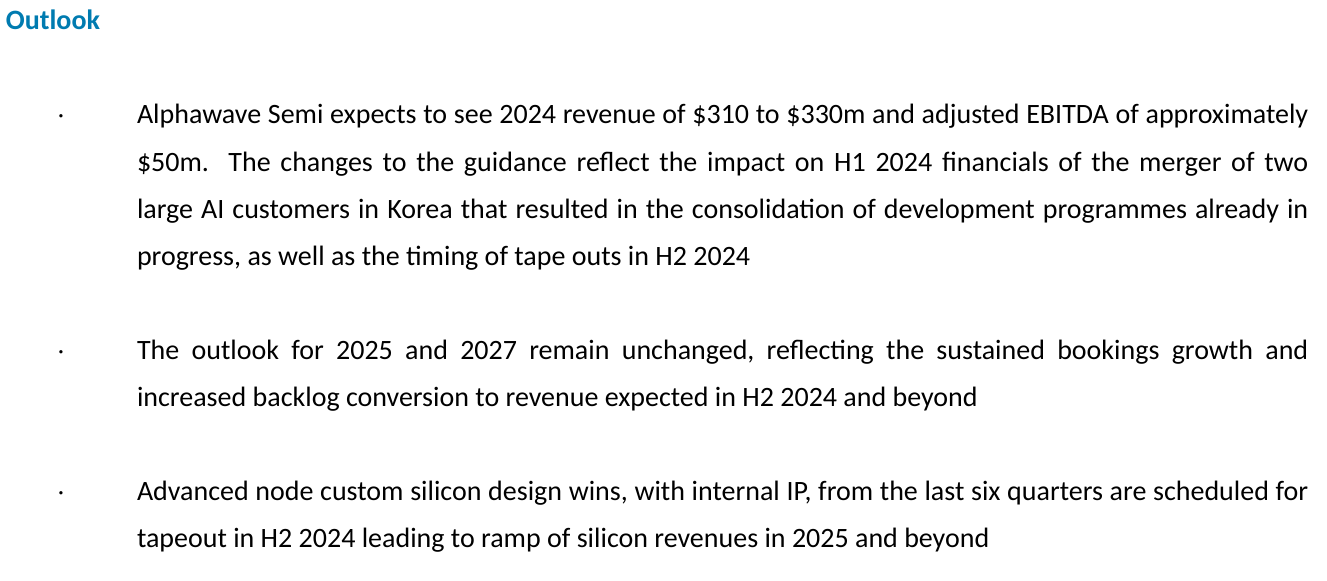
Cashflow - is negative again, a big concern of mine in the past. More than all of the operating cashflow is consumed by capex, including $34m capitalised development spend in H1 alone.
Paul’s opinion - I’ve seen enough to reinforce my negative view. It’s not at all clear if this is a viable business, the numbers suggest it isn’t. So everything now rests on it turning the talk of improved outlook, into cashflows.
Based on performance to date, this share could end up at zero, in my view.
Maybe it does have some amazing tech I don’t know, but the figures so far suggest it’s a basket case.
A total avoid for me, bargepole job. It could transform itself in future, who knows? Why would I want to guess about what the future holds, when the present looks so dreadful?
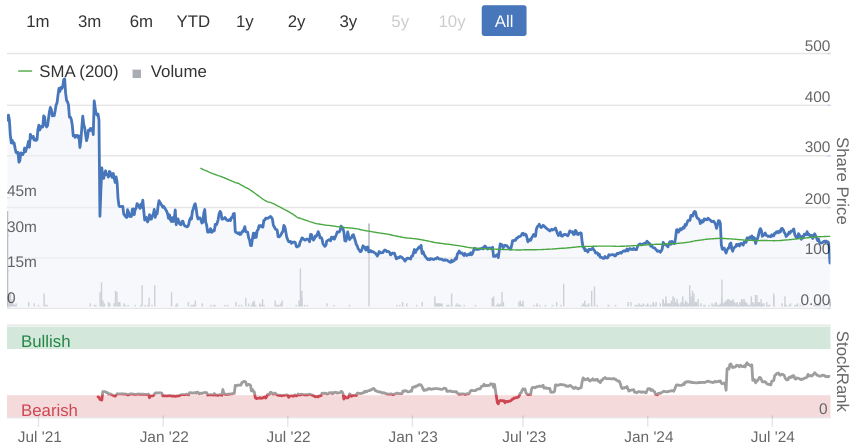
IPO investors were sold a dud at a crazy price. Hitting a new all-time low today, and could have a lot further to fall I reckon (to zero, possibly) -
Oxford Metrics (LON:OMG)
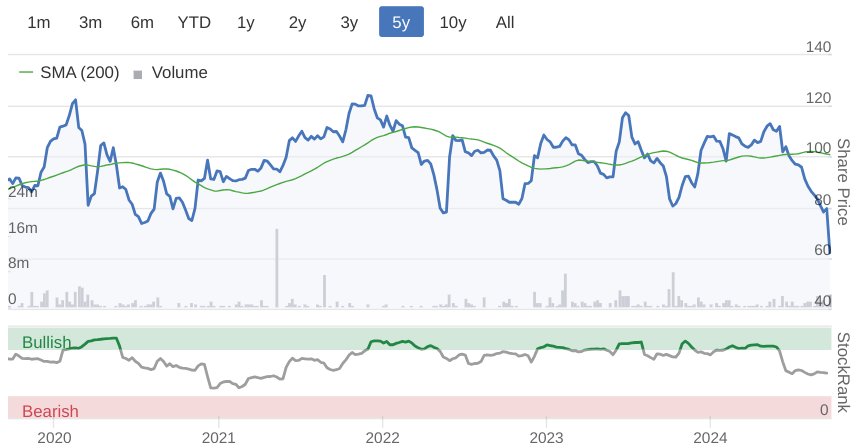
Down 20% to 63p (at 09:39) £84m - Trading Update [profit warning] - Paul - BLACK (PW), AMBER/GREEN (on fundamentals)
Oxford Metrics (LSE: OMG), the smart sensing software company, servicing life sciences, entertainment, engineering and smart manufacturing markets, today provides the following update on trading for the financial year ending 30 September 2024.
Orders are slower than expected -
“While the Group continues to have a healthy pipeline, the trend of more extended buying cycles has developed in the second half against a strong prior year comparative. Globally, we are seeing customers across our markets exercising greater caution and purchasing decisions are taking longer to conclude. A number of opportunities in the pipeline have now shifted into the new financial year.”
Hence revenue & profit guidance is reduced -
“The Group now expects to report revenues in the range of £40-£42million and is expected to result in Adjusted PBT* materially below current market expectations* for the financial year.”
*Oxford Metrics' compiled market consensus as at 20 September 2024 is as follows: FY24 Revenue £48.6m / FY Adjusted PBT £7.8m.
Now we have to guess what “materially below” means in numbers.
Looking back at its H1 results, it said >90% revenue visibility was in the bag for FY 9/2024, that was on 11/6/2024, which makes it surprising that it’s missed target revenues by c.16%. How come? Either some order(s) have been cancelled, or the previously mentioned visibility wasn’t firmly contracted. Either way, I think we need more information from the company as to what’s gone wrong.
Cash & acquisitions - the cash pile is c.half the market cap (probably more, once the share price has taken a likely hit today), so a key issue is whether management spend it wisely or not -
“The Group continues to have high gross margins and remains in a strong financial position with a robust current net cash position of c. £50 million, enabling the business to continue its active pursuit of a number of M&A opportunities within the smart manufacturing space to enhance our recent acquisition of Industrial Vision Systems ("IVS"). We are excited about the opportunities open to us to drive more applications into the smart manufacturing space to build the Group's position in this important market.”
Shares are down c.30% to 55p at 08:06. With 131.4m shares in issue, that’s £72m market cap, and with £50m net cash in the bank, the EV is only £22m. Surely it’s likely to attract buyers at that level I imagine? We’ll soon find out!
I can’t take the analysis any further at the moment, as I need a broker update to give revised forecasts.
However, I’m leaning towards seeing this as a value buying opportunity at 55p (since bounced to 63p), so will colour it AMBER/GREEN for now.
At a 5-year low today, and OMG pays divis too. Middling StockRank.
Transense Technologies (LON:TRT)
Down 4% to 182.7p (£28m) - Final Results - Graham - AMBER
Paul tends to cover this one but I’ll step up and have a look at it this morning for once.
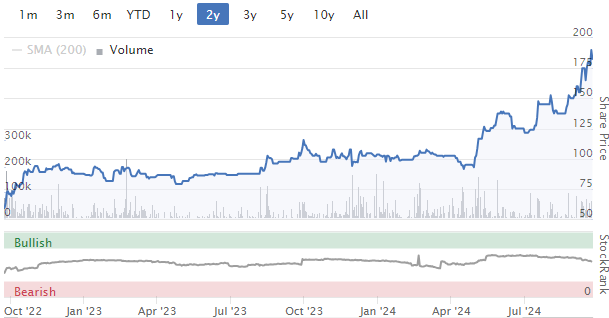
It’s up about 80% over the past year:
Transense Technologies plc (AIM: TRT), the provider of specialist sensor systems, announces its final results for the year ended 30 June 2024.
At first glance this appears to be a “jam tomorrow” type of share. However, it is profitable and has a cash pile, which automatically means that it’s a cut above so many other AIM-listed tiddlers. Here are the final results highlights:
Revenue +18% to £4.2m
Adj. PBT +20% to £1.3m
Cash £1.3m (slightly higher, year-on-year).
Revenues and profits are “in line with the expected growth trajectory”.
There are three components to the business.
Tyre monitoring system - “residual royalty income” from Bridgestone until 2030.
SAWsense - “advanced sensor solutions based on proven, patent protected Surface Acoustic Wave (SAW) technology”.
Translogik - smart, connected commercial vehicle tyre inspection equipment.
Judging by the description of their customers, it sounds like this is a business that earns far more than £4m in revenue p.a.
However, Translogik revenue was only £1.1m (up 9%), making a small operating profit. They see an addressable market of $25m p.a.
For the year ahead, Translogik “is now positioned to convert new business for its tyre management products directly with fleet customers and has several large potential contracts under negotiation.”
SAWsense revenues were down slightly to £0.45m and the company made a net loss. Transense provides lots of detail on target markets for SAWsense and their plans to grow this business, but from my perspective it’s probably too small to be relevant for stock market investors. They do say that there is a “level of commitment by our customers to pursue full scale industrialisation” after current projects are completed.
Outlook - is very positive, with strong revenue growth:
Trading in the period since the financial year end has been strong, with revenues approximately 60% ahead of the corresponding period last year, profits showing good progress despite increased overhead costs, and net cash at 31 August 2024 increasing to £1.49m. The depth and scale of customer engagements across the Company's two trading segments is intensifying.
Graham’s view
My impressions of Transense are positive, but I’m afraid I don’t see how to value it. The market cap of £28m gives a seal of approval that the two trading businesses have good potential, and unsurprisingly the commentary from the commentary helps to make a good argument that this is the case.
But it’s just so early-stage. SAWsense had less than half a million pounds of revenues in these results. Yes, it might have great potential, but I would argue that’s a question for venture capitalists to figure out, not for people investing their pension funds - I assume that most of us here, like most stock market investors, are saving for our pension!
Translogik is further advanced but on a standalone basis it would also be far too small to justify a stock market listing, in my view.
The combined group has been given a market cap of nearly £30m, so the market is clearly intrigued by the potential here. But this goes firmly into my “too difficult” pile. Paul’s previous neutral stance on this one seems fair to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Just to add my voice to all the others thanking Paul for his really excellent podcasts.
I watched the screens youtube video this evening and then spent a couple of very satisfying hours setting up my own. Great results and plenty of options to investigate. Although at the end of that my head hurt a bit and I needed a lie down…!
Earlier, I listened to the weekly podcast with great interest as ever. I find I really need to concentrate to get the best from these, I cant multi task at the same time. So my preferred listening method is to do so whilst driving - I’m beginning to regard Paul as a kind of Peter Kay car share passenger !
Yes if you choose to go down the annuity route then £1m won't go far. However, even a fairly average investor should be able to generate an 8% return a year - that's 80k which is surely enough for most people.
I don't know where this £1 million pension has come from. The average 60 something UK bloke has around £230K in their pension, the average woman about £150K. In neither case is there much chance of the capital being maintained, it'll need to be drawn down in order to achieve a reasonable lifestyle.
https://www.charles-stanley.co...
Assuming the standard 4% drawdown rate then with the state pension that's around £20K pa for a man and £18K pa for a woman. Just about OK for a couple, but hardly living in the lap of luxury.
There isn't much allowance for having a low income / no savings either, even with pension credit and savings credit a pensioner's income would only be a bit over £12K. It's also worth noting that 62% of the people receiving pension credit are women.
As for care home fees - the state of care home provision in this country is an absolute disgrace, but if you're a pensioner needing care without any savings you'll struggle to get into any care home and the ones that will take you ... well, let's just say they offer a minimal standard of service, even where the staff are doing their best. Meanwhile around 13% of NHS beds are blocked because of a lack of care home places to take patients so the wider ramifications of the social care defecit are having wider societal and economic impacts. The current government seems to have no better idea than the last one as to how to solve this.
timarr
Capita (LON:CPI) up 4% today on a company presentation day, that bodes really well, I find the companies usually drop on these days, the turnaround plan seems to be working.
Capita (LON:CPI) There was a positive announcement today. Capita extends smart meter licence contract
No guarantees of course, but listening to the presentation this afternoon, I thought the newish CE of Capita (LON:CPI) really understood the scope of requirements and opportunities to (at last) turn the company around., and appears to be making real progress.
I hold, so hope that I’m right!
Is seem quite apt in light of their results that Oxfords symbol is OMG!
The transformational impact of Elon Musk and SpaceX's low earth orbiting satellite constellation Starlink (see below charts).
Indeed this is one of the reasons why Filtronic (LON:FTC) 's shares have literally gone to the moon!
It will be interesting to see how the Shetland Space Centre fares once viable rockets are launched from there and the company lists. It's all go from there currently, but getting rockets to actually work is the issue as the recent RFA test launch demonstrated so graphically. Strange that Wernher von Braun was so successful in this sphere 78 years ago, but the problems persist so strongly today.
Wonder why directors sold some shares with such a promising tie up?
Can I ask, what's the general consensus for cash vs. invested with the Labour Party budget due soon. Personally I'm 50/50, and sold M&S last week as I can see their customers being a Labour target market for tax?
I'm all in. 100% invested.
i try never to guess how the market will react to an event as it always does the oppositeI would say there is an awful lot of negativity priced into the budget and a lot of investors are sat on their hands / cash waiting for it. My guess is the market goes up after the budget.
Holding cash is a drag on long term performance. It's also well known how poor investors are at timing the market (which is what you are doing when you hold cash). Time in the market beats timing the market as they say.
I'm also a holder of a small position in Marks and Spencer (LON:MKS) and after the share price has surged, it's tempting to sell. I'm holding for now however as I believe they are a much higher quality company that Sainsbury's and Tesco with much higher quality revenue (generating similar profits off a third of the revenue of Sainsbury's for example) yet trade at similar PE (although their PE ratio has finally caught up). They are gaining share as waitrose loses share at the top of the market while growth at Tesco and Sainsbury's will remain hampered by competition with Aldi and Lidl. Management's plans to close their less profitable stores and focus on locations they believe can generate them better profits is clearly working. In my opinion, they have further to run.
I'm staying invested although i just invest/ attempt share picking within shares isas.So nothing too complicated and involved tax wise.As long as they leave those alone... ?!As long as Marks and Spencer (LON:MKS) carry on with their current strategy, i don't see too many folk switching.Their clothing is great value imo and their food has always been on the pricier side and traded through many different governments and economic environments including the recent cost of living crisis.
I’m 40% cash earning 5% ish I’m not good at timing the market but feel s&p is running hot and think labor could make some big moves in the budget so hoping to snap up some bargains too.
Fully invested here and VERY optimistic too. Irrespective of the colour of your politics, what the markets like and need is stability, and we now have that in spades. What businesses need from govt are a moderately light touch, a plan, and consistency. Again, tick,tick,tick. Pile on!
SKY:
Exclusive: Dame Julia Hoggett, the London Stock Exchange CEO, has warned the Treasury about the “ongoing viability” of the City’s junior stock market and “significant market volatility” if business relief is removed from AIM shares in next month’s Budget.
I think we have to prepare for AIM benefits being removed - whether we like it or not the reality is that this is a very generous "odd" relief that probably has no place in a fair system where inheritance needs to be charged on large estates in fair manner. Obviously i would say remove the benefits in sensible fashion - ie share purchases after budget day will no longer be eligible for that exemption - that seems fair middle ground to me.
I fear a tax grab starting from midnight on Budget day!
. Reduce max amount for 25% cash tax free on pensions (currently £268k max)
. Remove free IHT for passing pensions on deaths before age 75
. Raise CGT %
. Abolish Business Relief on AIM shares
. Some kind of meddling with cash ISAs?
It's going to be pretty ugly imo.
It frightens me!
compared to the tax rises the tories have already implemented i dont see anything significant ref the above. if anything its just reinforcing what the tories have done over the last 5 years.
Obviously i would say knee jerk reaction to go too far too quick wont be good but we have stark choices if we want to give the powers that be £17k to spend for each person of taxpayers age in this country and we dont want to overload payment onto future generations
being frank if labour had been in charge over last 5 years and done all the changes the tories have done those who support the tories would have ben up in arms well before now.
pensions for example does one need £1.1 million in ones pension to make ends meet in retirement on top of state pension - probably not - so i find it hard to say minot tweeks down to say 200k wouldnt be tolerable on fairness point of view provided its done fairly for those near amount now. Personally i think the 25% lump sum is the least likely one to be targetted but there you go we will have to wait and see - there has to be an elkemt of scaremongering going on here by some - perhaps even labour themselves.
"does one need £1.1 million in ones pension to make ends meet in retirement on top of state pension"
Spending £1m on single life annuity linked to inflation will get you about £36k in annual pension (approx, it varies by the day)
That is an awful lot less than many middle-ranking public servants will be retiring on with their final salary schemes, let alone Sir Keir with his own special version!
Yes if you choose to go down the annuity route then £1m won't go far. However, even a fairly average investor should be able to generate an 8% return a year - that's 80k which is surely enough for most people.
But you could live for 30+ years , so you would need to reinvest 30-40 k just to maintain the value of your pot against inflation... so you're left with 40-50k to actually spend ...the local care home to us is 90k per year ( admittedly the best in the area )... many people spend more than 5 years in care ... and the majority of old people won't be investing, post retirement ,in Equities that generate 8%...
THATS WHEN YOU SELL THE HOUSE
Ok....
So from your shouty capitals, I'm presuming that you prefer wealth redistribution ?
I'm only a Newbie to this site, but I had thought that there would be more inclined to charitable giving, rather than Big Government enforcement..
Think I'd rather keep the £1m and draw down.
Annuity or drawdown invested in cash / equities / bitcoin / fast cars women and booze (and wasting the rest acc. george best)
As with all these things it all comes down to attitude to risk
What some may miss is that pensioner inflation is not normal inflation.
You tend to spend a lot at the beginning (big hols / nice car etc) then it declines then rises again later on (cleaner / gardener / nursing home)
A fixed annuity is a poor match for that and so people can end up not owning their house. Drawing down requires both foresight and discipline.
Personally. I intend to take the yield on 60% UK equities and let a 40% global equity tracker run. Not saying this is a brilliant thing to do but on the basis that yields sort of track inflation and the US is still a growth engine, I am content.
Many pensioners are sitting on a large asset buffer in their house, which they won't need when they are gone. It can provide serious backup if required to deal with the very unpredictable but potentially significant costs of old age care. It's quite possible to release some of the value of a house, and for that to be charged against the estate after death. For many that is a very significant asset that shouldn't be ignored in planning retirement.
Is it fair how two people in the same job with the same earnings can be treated so differently? Where one save for his retirement and then pays for his care home while the other spends all through his life and then gets his care home paid for, receives benefits to top up his state pension.
should the government really be taxing again those that plan and pay their own way.
I suspect the standard of living and especially security of income would be v different though. Would you want to be reliant on politicians to determine your std of living?
I suspect the standard of living would for those who rely on the hand outs because they spent every penny.
No I would not want to be reliant on the politicians to determine my standard of living, so I make sure i be am not reliant on them by working hard, saving and investing.
Unfortunately, it seems the working person who saves and pays their way are the people that will have to pay for those that do not. How is it fair that a person who may earn a couple of pounds a week more so they are not then entitled to benefits be worse off than a person earning a couple of pounds less? I have no qualm about people getting benefits, but seriously, they should never be better off than a person who works. And I am not talking about people who can not work due to disabilities. It is commonly known that someone who works 16 hours and receives benefits is better off than another working 30 hours. Fix the system instead of taxing more the ones who work and pay tax. Make working actually more beneficial to people. If people then want a higher standard of living, then that’s great, but it should not pay to work less. If people want more pension then save some while they are working. It should not be a given.
Think you will be spot on for most of what you quote.
the problem is that the 'AIM benefits' you mention are one of many things that fall under the BPR (business property relief) umbrella
for example: working farms are exempt, to avoid family farms being wrecked by tax bills upon deaths. a sensible and reasonable exemption. a side effect of this has been UK billionaires e.g Dyson buying up land and 'using' it for farming/agricultural purposes for that sweet, sweet BPR. despite him being, fairly obviously, not a farmer.
how do you address and minimise this use of that exemption in the legality of it but clearly not in the spirt of it?
IHT is, un-ironically, extremely difficult to minimise. you get ~£1m as a kicker between being married, main residence. ok, maybe you have a private business, some AIM stocks. perhaps you can add on a few more. but past £3m+, it gets very, very difficult to minimise
before people scream 'PUT IT IN A TRUST BRO' - money is taxed on the way in AND out, as well as taxed at 6% (IIRC) per decade. you are actually paying MORE tax over the decade of the trust's lifetime (up to 99 years), in exchange for complete control over the when, where's, how's and why's of the money
the only real ways to minimise or not pay IHT are:
give all your stuff away and hope you don't get hit by a bus within 7 years (although practically: 5.5-6 years should do it due to the taping)
leave the country to somewhere that doesn't have IHT and never return to the UK. announce you are going to see your days out/die elsewhere. e.g change of citizenship + change of domicile (archaic law TOO STRONK, plz nerf)
so, this is a very long winded way of saying: don't touch BPR on AIM shares, as you VILL cause a snowball effect on other qualifying reliefs, which will in turn cause an avalanche. IHT is, despite everyone whinging about it, an extremely fair and well implemented tax as it currently stands
(this means i've jinxed it now, doesn't it?)
Follow Terry Smith and go to Mauritius! (No, seriously.)
I suspect the adverse impacts of BPR removal on AIM shares on the junior market (both companies raising funds via IPOs/secondaries as well as the liquidity in the secondary market) has been explained to the Chancellor.
A more pragmatic measure for Reeves might be to limit the total BPR available per estate and possibly end the practice of benefiting from BPR to exempt from IHT and then re-basing for CGT purposes at death and make lifetime transfers more difficult.
Let's see, and not much given away in her speech today which was mainly given to platforming platitudes and wishful thinking.
Commercial forestry is very tax efficient.
unsurprising!
AIM (as an index) is already a shambles
remove one of the few benefits for most - i.e those who are NOT stock-picking and researching individual companies to filter out the dross - that is: IHT planning?
it goes down, down, down (and the flames go higher etc)
Just a reminder....
join us tonight for MelloMonday at 5:00pm! The programme for the show is as follows:
5pm Keynote Presentation Paul de Gruchy with ‘DG19: Everything’s gone wrong. Who is responsible?’
5:30pm Company Presentation from Warpaint
6pm Company Presentation from Windward
6:30pm Educational Presentation
6:50pm Company Presentation from Van Elle
7:20pm BASH Panel Kevin Taylor The Property Franchise Group (TPFG) & Mark Simpson Billington (BILN)
For more information, click here: https://melloevents.com/mm230924/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1367828
More Upcoming Events:
Mello @ The London Investor Show on Friday 1st November 2024, 9.30am – 5.00pm Novotel London West https://melloevents.com/mellolistickets/
Mello 10 Year Anniversary Event in DerbyTuesday 19th November & Wednesday 20th November 2024, 9.00am – 7.00pmDerby Conference Centre, Derbyshirehttps://melloevents.com/mello10tickets/
*ANNUAL PASS LIMITED TIME OFFER* We have lots of exciting virtual events in the pipeline for the upcoming months! Grab yourself an annual pass receive a FREE one-day ticket to our 10 year anniversary event worth £99! https://melloevents.com/annualpass/
David
Not sure why Metals Exploration (LON:MTL) exploration is down 2% this morning. Half year results show EPS is virtually all of the forecast yearly EPS, so half year PE will be <2 and debt eliminated,.The forecast for future years is for the gold to run out, but it isn't happening yet. Am I missing something?
Hi Dave, I have a decent profitable holding ,just to show I have an interest.
I suspect some were expecting a bit more of an update on the NEW ABRA project ,which is hoped to be the future, as current mine closure is just over two years away. I am quite content to hold . Possibly the management ,are keeping their cards close to their chest until they have completed the buyout business with RTL by sept. 30th.? RTL appear to have been a bit of an awkward creditor this year.
Following up the positive points you note , I would add the gold price has advanced several %age points since H1 ,so their should be an even greater cash holding going forward. This subject to steady production ,and gold price holding up .
The management suggest Q4 for some details forthcoming on the first drilling results at ABRA . Fingers crossed . In the meantime we are likely ,with current conditions, to be creating cash greater than current market cap ,to mine closure. I remain a very happy bunny with this holding. Tony
I was hoping for a better reaction, but can understand why nothing really happened.
Life of current mine is short 3 -4 years left.
They dug up less gold this H1 than they did last year, only the boost in price of gold saved the day, but how long will that last?
The quality of the gold is not as high as the mine gets older.
However, having said all that this is an interesting interview Metals Exploration (AIM:MTL) - Acquisitive Cash Generative Gold Junior (youtube.com)
and the very last line of and I paraphrase "the dividend at the end of the life of the mine, would be higher than the current share price" is interesting.
Sell and lock in my profit (26%) or stay along for the ride.....on balance while the stockrank stays high will probably stay, but will keep a 20% stop loss for the highest point (£ 0.0565) in place just in case.
Paul, just watched your Video on Stock Screening Strategies. What an amazing piece of work you have delivered. I know you had to do it twice which must have been a pain, but the result is fantastic. Very helpful and as always a great learning tool. I followed it carefully and made a lot of notes. I will now reproduce the screen. What was also incredibly useful was the statistics at the end on the success of green labelled stocks.
You have developed an amazing set of data which clearly works. Big thank you. Charles
Fast pace I thought, then I noticed it was set to a higher playback speed. My brain bandwidth needs a slower speed I'm afraid but I'm probably not the only one. Makes Paul sound a bit more like Brian Blessed though lol.
Yes, many thanks Paul. All the additional AV content you put out is much appreciated.
"But please don't follow me blindly" Paul said about his Plexus Holdings (LON:POS) TR1!
As if we would Paul...however up another 24% today, so I'm pleased I've been following your advice and let's hope that the next RNS will offer some great company news.
We don't offer advice!
It's news and views only here. You have to do your own, more in-depth research, because covering over 630 shares already this year, mine & Graham's comments are necessarily just quick reviews, and we might miss things that are important. We fling ideas at you, for you to properly research in more detail. Also it's vital everyone takes ownership of their own decisions. Not just a catchphrase or a disclaimer, this is crucial to what we're doing - swapping ideas here & then discussing them.
Thanks, Paul.
Whoever is loading up on Plexus Holdings (LON:POS) today, do keep it up, good work, it's on a nice run!
It's probably Paul - wait for the 5% holding notification! (tongue very firmly in cheek!)
Dave
Threadneedle: OSB Group deserves more
Investors are overlooking the fact that Osb (LON:OSB) is trading profitably and focusing on short-term volatility, says Columbia Threadneedle’s Julian Cane.
The Citywire Elite Companies AA-rated challenger bank is a top 10 holding in Cane’s CT UK Capital & Income (CTUK) trust, where it makes up 4.4% of the £380m portfolio.
The trust’s performance was ‘adrift’ in August, which was ‘entirely down to the performance of one of our larger holdings, OSB Group,’ said Cane.
‘Its share price had been very strong – up 20% in July – and was so perhaps a bit over-extended into results, which proved to be disappointing, leading to the share price falling 26.5%,’ he said.
Despite the poor results, Cane said the group is ‘trading profitably – indeed more profitably than mainstream banks’ but ‘many investors are very focused on the volatility of short-term warnings’.
‘While frustrating, we continue to believe that the attractive returns generated by OSB Group should be more highly rated,’ he said.
The shares softened 1.4% to 378.5p at the end of last week.
Osb (LON:OSB)
Threadneedle: OSB Group deserves more
Investors are overlooking the fact that Osb (LON:OSB) is trading profitably and focusing on short-term volatility, says Columbia Threadneedle’s Julian Cane.
You have to laugh at this - its clear that the trend in expected earnings has had 1 way trend downover for the last 12 months - how can you ignore the fundamental issue that every time they update that seems to result in lowering of expectations ref profits this year and next. Should investors ignore that the reality isnt matching the prior promise just because they are still expecting "some" profits.
Threadneedle: OSB Group deserves more
Investors are overlooking the fact that Osb (LON:OSB) is trading profitably and focusing on short-term volatility, says Columbia Threadneedle’s Julian Cane.
That reminds me. I have a sack of salt in the garage for use when I hear a fund manager talking about shares they own. Normally gets emptied after watching the Fundsmith AGM!
So Alphawave IP (LON:AWE) .....
Bookings up 20% and revenues down 50%.
Looks like the market is finally waking up to which metric matters!
Raspberry PI Holdings (LON:RPI) have their results tomorrow. Much as I love their little gadgets (my son has one with various add-ons) I'm afraid I couldn't stomach the IPO price.
My son was annoyed with me for not buying some in his JISA - let's see who was right.....
Well he was right since they floated at 280p and got to 490p and are still 80p above the float price…but unfortunately his allotment would have been so scaled back it wouldn’t have bought him a copy of the Beano…
The verdict won't be announced till my son's 18th birthday.
Plenty of time yet. He may know what Python is, but after 2 weeks at "big" school he still can't manage his own tie in the morning.
Is that a parenting fail, or am I simply equipping him correctly for the workplace of the future?
I should also add that the failure of various Google Home related technologies to reliably get him out of bed in the morning bodes poorly for the Alphabet (NSQ:GOOG) share price.
Both
Alphawave IP (LON:AWE)
this company has always had a ridiculous amount of red flags - if they have a decent viable business here they are doing their best to hide that fact by the ridiculous smoke and mirrors stuff that goes on with everything that comes out of their mouth.
and their excuses today are comedic in nature - complete nonsense babble.
this company has always had a ridiculous amount of red flags - if they have a decent viable business here they are doing their best to hide that fact by the ridiculous smoke and mirrors stuff that goes on with everything that comes out of their mouth.
It’s a complete crock. I used to work in this area and from day one said it would end in tears. And to think some supposed informed commentators were comparing it with ARM at IPO. I couldn’t believe a normally sensible company like Blackrock would put the thick end of $400m in at the IPO, but then I guess that’s very small beer for them.
All the best, Si
I sold a while back after i realised i had made a bad pick after getting bamboozled by the whole ai chip datacentre thing and the decent marketcap/not a nanocap more importantly.Doesn't surprise me it's being heavily bought though on 'the dip' as ai chips and datacentres are still hot both sides of the atlantic it seems.Wouldn't surprise me now if it ends the day flat.Volatile trading to say the least.
RE: Alphawave IP (LON:AWE)
I sold a while back after i realised i had made a bad pick after getting bamboozled by the whole ai chip datacentre thing and the decent marketcap/not a nanocap more importantly.Doesn't surprise me it's being heavily bought though on 'the dip' as ai chips and datacentres are still hot both sides of the atlantic it seems.Wouldn't surprise me now if it ends the day flat.Volatile trading to say the least.
Day to day share price moves are largely irrelevant. As rmillaree said, there have always been so many red flags that the valuation at IPO was always going to look stupid, and the overall direction of travel looks set. The biggest red flag of all for me is why a supposedly world leading Canadian technology company would list on the UK market rather than the TSX or Nasdaq? It just made no sense. The only positive thing you can say is that the acquisitions they made have at least broadened the product portfolio and kept the company going. Without them, the original listed entity would likely already be in its death throes.
https://x.com/GigaBasedDad/sta...
Best of luck.
Very funny.
Thankfully some of the 2010s cohort seem to be doing OK despite the COVID interruption. Taking hard shots to the face as goalkeeper seems to be teaching my son exactly the same life lessons that the rugby pitch taught his 1970s father.
And his elder sister warns her embarrassing father not to make his unreconstructed views on new-fangled pronouns clear in public. "Of course you are right Dad, you just can't say it".
All is not lost, despite what the media would have us believe.
RPI Yes, despite all the lunacy of the adults, there seems to a sufficient core of the younger generation with their heads screwed on. We'll all be relying on them to fix the mess that we all made.
RPI's results will be eagerly awaited, I'm sure. I will bear you in mind when they come out. Does the old dog know a few tricks that they pups haven't learned yet, or is his old man reached the stage of shouting at clouds? We shall see tomorrow.
RPI will give a presentation of their half-year results over on Sparklive at 2.30. It is a site run by London Stock Exchange. I'm sure that they'll be a deluge of commentary by pundits on what most people would consider a prestige listing for the exchange.
I have a miniscule position in RPI , so I'm on your son's side. ;)
RPI is down a little today, 0.75%, Safety belts on.
SAAS just seems to be none stop positive RNS with good forward numbers yet share price languishing, don’t get it
Capita (LON:CPI) are holding a webinar for private investors today at 3.00pm. CEO Adolfo Hernandez and Deputy Director of IR Stephanie Little, will provide an update on performance following the publication of the HY24 results which were released on 2 August.
Since then the disposal of Capita One has been completed which moves the company to a net cash position (Pre IFRS16) at the end of the year. There is a lot going on at the company and if you have any questions you want to put to management now is the time. Register here
Big thanks to Paul for yet again doing extra work at the weekend with the video "Looking for bargains". These extras take hours to make so THANK YOU PAUL
Thanks alex, that's so kind.
I've noted that people seemed to like my ad hoc videos on screening for ideas, so will try to do more of what you guys seem to like, when ideas crop up! :-) They're quite fun to do also. I plan them ahead, but sometimes it's better to just start recording, and see where it goes LOL, warts & all! :-)
"sometimes it's better to just start recording, and see where it goes LOL"
As long as the volume is on Mr Scott!!
Personally, I have a loss of confidence in how Oxford Metrics (LON:OMG) have presented RNS information.
">90% revenue visibility was in the bag for FY 9/2024, that was on 11/6/2024"
If a company puts this in an RNS then they really have to hit the target. They ended up missing.
For todays RNS, they say there is a significant drop is revenue but do not state how this will impact profit.
A very poor way to communicate with shareholders and as such the loss in confidence.
I have to agree re: Oxford Metrics (LON:OMG) - plus given share price went into a nosedive following said June announcement suggests they are a bit leaky. Not a good start for new management.
Oxford Metrics (LON:OMG) Have to agree with Graham's & Paul's analysis plus viewers comments on this one, the share price decline since the last update speaks volumes. As Paul has alluded to still a large cash pile but it depends on what they do with it. Graham's previous comments about the new CFO previously being at Fire Angel that investors do not look back on fondly does not inspire confidence.
Sold out of #OMG much earlier in the year when it became apparent that they didn't have a plan for the excess cash and more importantly weren't seeing a lot of growth. In the last 12-18 months I have become much more brutal in clearing out shares where my conviction for growth goes and so far I keep seeing after a while those decisions being justified.
On Oxford Metrics (LON:OMG) are some of their applications (entertainment, virtual reality) going to see a sensors + silicon approach displaced by pure silicon leaving OMG behind?
Mirrors my action and opinion on Oxford Metrics. Given they are in the middle of a very plausible 5 year growth plan, they seem to have no idea what to spend their money on. Plus, while £50m sounds a lot (and relative to their mkt cap it is) it doesn't buy you much in the tech world.
Hat tip to Graham Neary, he flagged several points back in June that was holding him back from Oxford Metrics (LON:OMG) , after reviewing I held back from investing, plus the stockrank has been in decline since, a good early warning sign perhaps. I’ve just double checked the stockrank trend on the stocks in my portfolio!
big 1million£ directiors sales in omg 18 months ago also, old cfo.
Eagle Eye Solutions (LON:EYE) : 5 year contract win with a leading UK retailer... potentially a cash flow inflection point as the company really seems to be dominating the sector ..
Pennant. , Transense,
Pennant
Think theres some real drive to realise some value here driven by Rockwood / chairman Ian Dighe .
3.1 million ish to come from selling Cheltenham freehold plus 20 staff to go annualised saving .
Runway on contracts extended due to government military spend review, must be a nightmare trying to deal with government beauricracy and civil servants issuing contracts .
Transense
Nice update steady as she goes .
Pennant International (LON:PEN)
Hasn't gone to plan so far but I think a little bit of patience required here as the direction of travel is very good, 2025 should be a pivotal year for them assuming the new Auxilim software product lands these much vaunted defence contracts.
My morning smallcap tweet: A watching grief
Distil (LON:DIS) Oxford Metrics (LON:OMG) Mirriad Advertising (LON:MIRI) Mycelx Technologies (LON:MYX) Kromek (LON:KMK) Deltex Medical (LON:DEMG) Microlise (LON:SAAS) £LGD Petrofac (LON:PFC) TR Property Investment Trust (LON:TRY) 4Global (LON:4GBL), Elixirr International (LON:ELIX), Eden Research (LON:EDEN), B90 Holdings (LON:B90), Pennant International (LON:PEN)
◄Distil (DIS)► £0.65m placing at 0.12p, a nasty 40% discount, to keep the lights on. I won't drink to that. [SP=0.21 Cap=2m]
◄Oxford Metrics (OMG)► warns FY-Sept rev only £40-42m and adj pretax materially below current market expectations (£48.6m and £7.8m resp). Blames extended buying cycles. [SP=80 Cap=105m]
◄Mirriad Advertising (MIRI)► warns FY-Dec below mkt exp. [SP=0.4 Cap=4m]
◄MYCELX Technologies (MYX)► warns FY-Dec rev $4.5-$5m, from $9.5m guided due to delay in Nigerian project. Co will recognise the project value of $5.4m in 2025. Minimal impact to FY24 cash balance. [SP=47.5 Cap=23m]
◄Kromek (KMK)► selected as a supplier for Gov't Radiological Nuclear Detection Framework for radiological nuclear detection equipment and supporting services. "Kromek is pre-qualified to be selected for orders...which over the four-year term of the Framework have a combined maximum procurement value of £84m." [SP=5.5 Cap=35m]
◄Deltex Medical (DEMG)► H1-June. broadly in line with internal budgets however sales of the new TrueVue monitor are still building and have not reached their anticipated run rate. [SP=0.12 Cap=2m]
◄Microlise (SAAS)► wins 5-year contract renewal with JCB. [SP=120 Cap=140m]
◄Logistics Development (LGD)► Fight! Shareholder Richard Griffiths attempts to wind up co via two requisitions. Co claims requisitions are invalid. [SP=NA Cap=NA]
◄Petrofac (PFC)► gets another month's forbearance for non-payment of coupon on its senior secured notes. [SP=17.26 Cap=91m]
◄Galliford Try (TRY)► appointed to two lots on the new Wessex Water Capital Delivery Framework. It is expected to be worth over £400m to Galliford Try over initial 6 years. [SP=354 Cap=1123m]. I hold.
◄4GLOBAL (4GBL)► significant expansion of its agreement with U.S. Soccer to provide the data, platform and strategic insights to enable U.S. Soccer to better understand US soccer facilities. No $$$. [SP=45 Cap=12m]
In line: ELIX, EDEN, B90, PEN
Rockwood Strategic (LON:RKW)
Richard Staveley presentation of Rockwood Strategic (LON:RKW) results, should be interesting
https://www.stockopedia.com/sh...
Watched Paul's video yesterday on looking for bargains. Really informative as well as entertaining! Thx Paul.
Watched Paul's video yesterday on looking for bargains. Really informative as well as entertaining! Thx Paul.
Same here - really good - I'm glad you published it to YouTube since it's a much easier viewing than watching it from within loom for me (on mobile at least)
Hi Could you please post a link to Paul's video on you tube, couldn't find it ? Thanks
On Friday stock report video
it's on today above the companies reporting box but copied here for you
Looming US ports strike threatens fresh supply chain crisis
Business groups warn of ‘devastating impact’ on economy if dockworkers walk off the job
https://archive.ph/jUdzg
According to Reuters, Australian property listing firm REA Group said earlier today, that its sweetened 698p /share (stock & 305p cash) bid for Rightmove (LON:RMV) had been rejected by the RMV Board.
IMO, 305p/share in cash simply isn't enough.
Indeed REA have just increased their offer to 770p/share of which 341p is cash - equivalent to a 22.4x EV/EBITDA multiple.
That's not much of an increase as it's only on the cash part. I'm thinking of selling all my holding in my ISA and keeping that which is in my trading account in order to steer clear of capital gains issues. I just hate it when opportunists muscle in and upset the apple cart.