Small Cap Value Report (Mon 24 Jan 2022) - RBG, SAA, GMS, DLAR, CNS

Good morning, it's Paul & Jack here with the SCVR for Monday. Today's report is now finished.
Mello Monday is tonight at 6pm.
Agenda -
Paul's Section:
Revolution Bars (LON:RBG) (I hold) a short video I made over the weekend, mystery shopping the reopened, refurbished Bournemouth site. I was impressed. 19 refurbs underway (28% of the estate) should drive strong sales & profit performance this year, in my opinion. Hence I think the ducks are now lined up for a much improved performance in 2022, whilst remembering there are cost headwinds too.
M&c Saatchi (LON:SAA) - Vin Murria looks to be flogging a dead horse here, with her ill-judged takeover attempt. There's a 40p cash element added, but the bottom line is she hasn't got the firepower to buy SAA, so should back off.
EDIT: SAA has now issued an interesting update, worth reading if you hold, basically saying there's no merit in the deal, so the independent Directors have unanimously rejected it.
Gulf Marine Services (LON:GMS) (I hold) - an in line update. This is an interesting situation - very high debt, but the strong and predictable cashflows from medium-term contracts, being renewed at rising daily rates, gives a predictable path to debt reduction. The benefit of that could flow through to equity holders over the next few years. Guidance for 2022 is positive, and specific numbers provided.
Jack's Section:
De La Rue (LON:DLAR) - profit warning, with a c20% downgrade in FY operating profit from £45m-£47m to £36m-£40m. Seems like quite a change from interims reported in late November of last year. The turnaround is set back by a year and there’s a question mark over the profit growth profile going forwards, with ongoing substantial pension contributions to consider. FY results out on 25 May, so it could be worth waiting until then for more detail and commentary.
Corero Network Security (LON:CNS) - EBITDA to be ‘materially ahead’ of expectations, with a maiden profit before tax in sight. There has been a lot of equity dilution in the past and that makes me wary, but the direction of travel appears positive. Its ‘Highly Speculative’ riskrating is well-earned.
Here is mine & Jack's weekly SCVR summary on 29 minute audio. We rattle through almost all the companies covered in the SCVRs for the week, flagging the best ones. Typing up the written summary below the audio, takes a ridiculously long time to do, although it is useful, and I've only done about half of it so far - which ate up about 2 hours of my weekend, which wasn't good. So we might have to look at a quicker way of doing that.
Edit - shout out to Lawrence, who has got the podcast on Spotify! Here is the link, do follow us on there if you get the chance.
More shenanigans in the US markets late last week, with markets selling off again. Although futures are up strongly this morning, so who knows whether this is just a healthy correction from over-valuation, or a new bear market? With about a third of the trades in the US markets being programmatic trades, which chase direction (either way), rather than fundamentals, then it could easily reverse as fast as it fell. Plus, powerful rallies are the norm in a declining market. So if there's anything I want to sell, the trick is to wait for a strong up day, and ditch it then, not panic selling on a heavily down day.
I'm focused on the fundamentals of the UK shares I hold, and most of them seem to be putting out rather encouraging trading updates at the moment. To me it seems more like a necessary, and healthy correction.
The re-opening trade looks better than ever, since covid restrictions are now being dropped, and we look set for a strong recovery in trading at travel/leisure/hospitality. So it would be a pity to panic sell these shares now, just when the upside should start to come through, hence I'm sitting tight. It will be interesting to see how many sectors trend back towards pre-covid behaviour, and how many have changed for good? Everything seems unusually busy in Bournemouth - shops, casfes, bars, look more like a busy spring or summer, not late January.
Revolution Bars (LON:RBG) (I hold)
I made the above short video, mystery shopping Revolution Bars (LON:RBG) (I hold) re-opening after a refurb. The company is refurbishing 19 of its bars (28% of the estate) this spring - a benefit of having paid off all the debt, and now being net cash, after 2 placings at 20p. The refurb is fantastic, the whole place looks shiny & new, and is pulling in punters off the street at a time of day when it was normally dead. Even the food was great, which is not something I've ever been able to say about Revs before. It seems to me that management are rebuilding this business very well, everything was dramatically improved. Hence I'm anticipating strong trading from Revs during 2022 - refurbished bars typically trigger strong uplifts in sales & profits. Plus all that pent up demand from youngsters who are getting their lives back again, and want to party. Or "par-tay", as my niece tells me it is now pronounced :-)
My chat with the Bournemouth site manager was also very encouraging - he defected from a larger competitor, saying they exploit people. Whereas Revs now has a reputation for looking after staff, and having a great team atmosphere, which is the culture the newish CEO brought in with him, and is known for at his previous jobs. So I think we have the right management in place here, doing the right things. The problems have been sorted out, and I'm quietly confident that 2022 should see much better trading reflected in strong numbers. Time will tell. There are cost headwinds though, which nobody is immune from.
I know it's never good to extrapolate from just one site visit, which could be unusually good or bad. However, with 19 refits underway in total (6 already done), the refitted Bou'mth bar should be a representative example of how much better the refitted sites look, which pulls in the punters. Newness is everything. I've emailed the CEO suggesting they move to a "little & often" maintenance strategy, to keep these sites looking new, instead of slow dilapidation - which seems to be the norm in this sector. Maintenance spending to keep the bar's appearance top drawer is not capex, it's essential spending to maintain profitability, in my view.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
M&c Saatchi (LON:SAA)
175p (pre market open) - mkt cap £214m
This is a very peculiar situation. Vin Murria is trying to take control of SAA through a personal shareholding, bolstered by her listed cash shell AdvancedADVT also having used some of its cash to take a stake in SAA.
There doesn’t seem to be any strategic rationale for the deal, other than a change in control of SAA. Why would SAA shareholders want to swap their SAA shares for shares in a cash shell that would then own SAA? It’s all a bit ridiculous I think.
The offer has been raised by 20.7%, to 2.245 new ADVT shares, or a partial cash alternative of 40p cash (less than a quarter of the current share price), plus 1.633 new ADVT shares.
This is not an attractive offer, when the currency is mainly new shares in a cash shell. The problem with that, is the valuation of ADVT would just reset to whatever the market thinks SAA is worth. So there’s not really any premium at all.
My opinion - it’s a bum deal, and I hope shareholders reject it, as the independent Directors of SAA have. This seems a rare mis-step by Vin Murria - her fundamental problem seems to be that her acquisition vehicle hasn’t got the financial firepower to do the deal. This situation also raises the question of whether Vin Murria's place on the Board of SAA is tenable? I suppose she could stay on as a non-independent Director, but it looks an awkward situation.
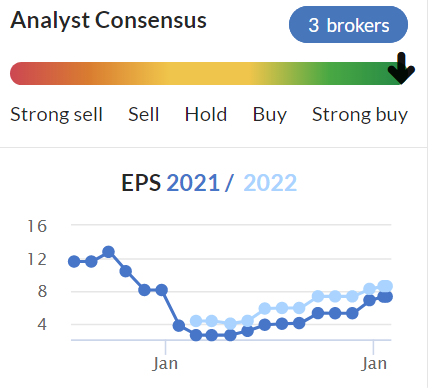
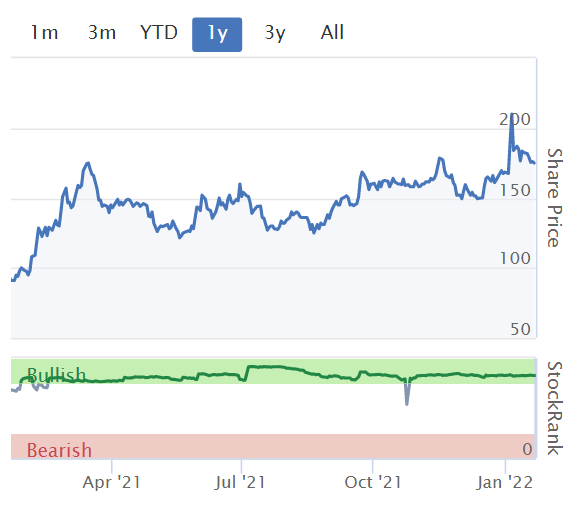
The company itself is trading well, putting out positive trading updates & upgrades to guidance. Looking at the neat Stockopedia graph, I wonder if earnings guidance might continue improving?
.
.
Gulf Marine Services (LON:GMS) (I hold)
6.4p (flat, at 08:08) - mkt cap £65m
GMS, a leading provider of advanced self-propelled, self-elevating support vessels serving the offshore oil, gas and renewables industries, is pleased to provide the following trading update.
Guidance for 2021 is in line with expectations -
Vessel utilisation for 2021 was in-line with expectations at 85%. As a result, EBITDA is expected to be between US$63-US$65m and within the previous guidance range given.
[£1 = $1.355]
That’s £47m EBITDA, for a company with a market cap of £65m - the reason for cheap shares, being that there’s a lot of debt. However, the bull case for this share is that the company is now a cash generation machine, maintenance capex is modest due to the fleet being fairly new, and there’s no expansion capex. Hence debt should be reducing now from cashflows.
Most vessels are rented out on contracts of typically 1-2 years, and supply is now tight, so when they come up for contract renewal, daily rates go up. Hence this is an easy situation to model, with predictable cashflows, that looks set up to resolve the excessive debt situation over the next few years. The upside then should flow through to equity holders, as debt reduces - hence why I hold this share, with a 2-3 year view, for a re-rating - as it should progress from being a financially distressed company, into a stable company generating good cashflows, and eventually dividends. It does depend on the price of oil though, which is driving the improved charge out rates for GMS’s vessels.
Outlook comments seem reassuring to me, and this highlights the excellent visibility on revenues & profits -
Recent contract awards have positioned the company well for 2022. Utilisation across the Company's larger and mid-size, high earning E&S class vessels, is currently 94% contracted, with overall secured vessel utilisation standing at 78%.
Average secured dayrates for 2022 are currently 10% ahead of 2021 actual levels. The Company expects dayrates to continue to improve further, based on a strong pipeline of new opportunities and as the market continues to tighten.
A two-year option period on a K Class contract has been exercised and the current Backlog (Firm + Options) stands at US $216 million.
EBITDA guidance for 2022 is expected to be in the range of $70-$80m million, which remains in-line with market expectations, and is supported by the improved trading conditions.
"Our markets continue to improve with dayrates on recent contract awards showing healthy increases from legacy contracts and secured utilisation for 2022 already close to where we finished 2021, underpinning the expected improvement in the performance of the business."
My opinion - this looks a very good, and predictable turnaround. It’s not dependent on guesswork, because of visibility from contracted revenues, at rising daily rates, driven by a shortage of available capacity for this type of vessel. Normally the high debt would have put me off, but in this situation, I like the high cashflow visibility, which makes it very easy to foresee decisive reduction in debt in the coming years.
So far, so good.
This is a special situation, so it won't appeal to everyone, and people need to be sure you understand the risks.
.
.
De La Rue (LON:DLAR)
Share price: 109.2p (-27.2%)
Shares in issue: 195,150,407
Market cap: £213.1m
De La Rue says the ‘significant headwinds’ of commodity and energy costs and supply chain challenges have become more pronounced. Omicron and Delta Covid variants have led to increased employee absences and this will result in lower total operational output for the full year.
The group now expects adjusted operating profit for the full year to be £36m-£40m compared to market expectations of £45m-£47m. That’s a material impact and a roughly 20% reduction in expected profitability.
This all sets the company back by about 12 months in terms of its turnaround plan, and the headwinds are expected to persist in FY22-23, slowing the operating profit growth profile.
Net debt expectations are unchanged (last reported as £43.9m of net debt at the half year stage) and the revised outlook still reflects ‘substantial’ year-on-year growth in DLAR’s two core businesses.
The Board retains full confidence both in the Turnaround Plan and in its execution. There is no change to the elements of the plan: the growth areas of Currency, driven by the continuing and accelerating trend of conversion to polymer, and Authentication, driven by increasing demand for digital and physical solutions for governments and corporations, remain strong and in line with the Plan's expectations. The Company is also intensifying its efforts to deliver further efficiencies and cost reductions, to mitigate some of the factors described above.
Currency and Authentication should see adjusted operating profit growth in the range of 35%-45% from the £27.5m delivered in FY21, so between £37.1m-£39.9m.
Diary date - full year results to be announced on 25 May 2022.
Conclusion
This is obviously a setback in what was a potentially interesting turnaround. De La Rue is making year-on-year progress but is facing cost inflation, supply chain disruption, and labour absences. The first two are now well known, but I wonder if the last will be more of a theme in the next couple of months?
Taking a longer term view, the shares are still well below previous highs. Shares in issue have increased from about 110m in 2012 to 195m today.

There is potential upside here even after the dilution but the tone of today’s update will be a further hit to sentiment. It’s not just a 12-month setback; the profit growth profile going forwards has moderated. So the shape and scale of the turnaround needs to be reassessed.
I wonder how long management has known about these issues? It strikes me as a vastly different tone to the one conveyed in the interim results back in November, when cost inflation was noted but management sounded more positive. That was only seven weeks or so ago.
The level of capex over the past few years has been making the group free cash flow negative. We’re not yet seeing the benefits of all this invested money, with ROCE declining, but there can be a lag between investment and tangible financial results.


There’s also a pension scheme to account for, with substantial cash outflows of some £15m per annum. It’s possible that modestly higher rates might lead to a reduction in contributions at the next actuarial valuation, so there’s scope for this to shift from a headwind to a tailwind. But right now it’s the former, and needs to be looked at more closely before forming a full view of the enterprise.
And as above, investor sentiment will take a hit with this update. The drastic change in tone from late November to mid-January jars slightly.
It’s worth a look as the valuation drops, but there are questions: the pension situation, the impact on DLAR’s turnaround and growth profile, and the fact that such a change in outlook comes as such a surprise to the market. Given the change in prospects and the brevity of the update, I wouldn't personally consider buying until we get more detail on the 25th of May.
Corero Network Security (LON:CNS)
Share price: 11.74p (-0.05%)
Shares in issue: 494,852,304
Market cap: £58.1m
This is a leading provider of real-time, high-performance, automatic Distributed Denial of Service (DDoS) cyber defense solutions. Cybersecurity is a long term growth market, but Corero itself has racked up a lot of trading losses and equity dilution.

It does appear to be closer to profitability now, but the above makes me cautious.
Corero performed strongly in FY 2021 with revenues broadly in line with market expectations at c$20.9m (2020: $16.9m), up 24%, and EBITDA anticipated to be materially ahead of market expectations in an estimated range of $3.8m to $4.2m (2020: EBITDA loss of $1.4m).
This should result in a maiden profit before taxation figure to the tune of $1.2m-$1.6m (2020: loss before taxation of $4.0m).
The profit figures include c$0.2m of foreign exchange gains (2020: $0.4m foreign exchange losses); and non-recurring income from the forgiveness of a US Payment Protection Plan (PPP) loan of $0.6m.
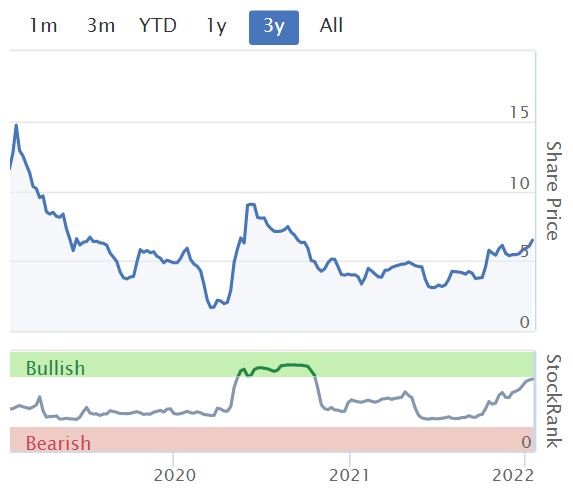
This upgrade was previously announced on 22 December 2021, with shares rising from 9.25p to 11.4p then, hence the lack of share price action today. You can see that move on the right of the chart below, but what also stands out is the general level of volatility here over the years.

Annualised Recurring Revenues ("ARR") increased to c$12.8m as at 1 January 2022 (up from $9.8m a year earlier).
Net cash as at 31 December 2021 was $8.4m (H1 2021: $5.1m; 2020: $7.6m).
Conclusion
This has been a good year for Corero, which looks to be on the brink of elusive profitability. The group intends to invest in additional resources in 2022 to further drive growth.
Corero has racked up years of losses and the rate of equity dilution is quite scary - sustainable profits could put an end to this, but the track record so far affects how I view the company.
I’ve got no particular insight in terms of the quality of its services, but I’m curious to see the more detailed final results.
The StockRanks remain fairly skeptical, falling by 9 points to 25 over the past 30 days. Corero is hardly cheap, with a £58m market cap on £18.9m of trailing twelve month revenue. The top line is forecast to grow quite quickly over the next two years though, and cybersecurity is likely a long term growth market. I'm open to the possibilities but aware of the track record.
It’s too speculative for me right now given the equity dilution, price volatility, and small free float (c30%).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
I do wonder about the UK market in particular and the effects of what appears to be almost total illiquidity in all but a handful of big FTSE100 type stocks.
Reach (LON:RCH) as an example : less than £4m worth of shares changed hands on a £750m market cap and the price is marked down 11% !! That is just one stock but similar applies to lots of others out there. MMs just don't want stock so any selling, even very small, is cratering share prices. The UK market was far behind the US in terms of valuations being applied prior to the collapse but is keeping pace with US declines. It's all a bit odd and I can only attribute it to the clear illiquidity, but that doesn't bode well for the UK market long term. It needs better liquidity than this to maintain its place in world markets.
The UK market has never been close to the liquidity of its US counterpart , and will never be. What you are saying is nothing new and will be the same in the future.
This is a very important point. Personally I think this is getting worse all the time, mainly due to passive funds and indexing. Private pensions are almost universally directed to passive funds favouring sovereign bonds and mainly US equities, because of the huge US weighting. While indexing takes a greater and greater hold over the long run it seems to me there will be fewer and fewer discretionary traders of mid to small cap UK co's.
Might be good for UK stockpickers finding bargains, but I think in general this is very unhealthy for markets. I think the general lack of discretionary players has contributed to the extreme volatility during sell-offs in the last few years. You get glacial levels of volatility on the market march up and very fast plunges like we're seeing right now and in March 2020.
Surely Thg (LON:THG) is well over sold?? 20% down on the day?!?!
If I've already filed, can I now delay my tax payment by a month as well?
Yes. Check the HMRC website to confirm.
HMRC are still charging interest on payments after the normal 31st January deadline unfortunately. You just aren't charged the late submission penalty of £100.
Interestig video re Revolution Bars, but of course, until the business begins to generate a net tangible surplus relative to its MCap, investor must just see RBG, as a stock that could one day be of interest, no sort of investment right now.
The selling has been pretty constant since Q4 last year.
If anybody has made any money since September / October last year, you've done very well. I suspect not many have. Very difficult swimming against the current.
My ISA showing +1.8% and SIPP showing -1% since 1st Oct 2021 (So Q4 + so far this month to date) so barely keeping my head above water on a blended basis.
For Jan22, MTD is -1% in ISA, +2% in SIPP. Blended probably +0.7% for the month so far. Hoping it holds and I can at least eke out a profit for the month of January.
Caveat is that I have held alot in cash during the period (see my BBB Fund monthly articles). Currently 53% cash in ISA, 28% cash in SIPP. Lots of buy trigger alerts coming in, albeit all on loss-making growth companies, and contemplating whether to starting deploying some of my cash pile today.
On my watchlist for possibly buying later today:
- Topping up on Spectra Systems (LON:SPSY) , along with some Begbies Traynor (LON:BEG) and Appreciate (LON:APP) and Itv (LON:ITV)
- Dipping into new starting positions in Thg (LON:THG) and Deliveroo (LON:ROO) as they are bombed out unfairly now IMO
- Avoiding Boohoo (LON:BOO) even though it has blown past by buy alert and screaming value, due to the huge amount of short interest now
- Surface Transforms (LON:SCE) am lukewarm as this is the type of share likely to be pummeled further
(I hold SPSY, APP, BEG, ITV)
I think most would take those figures given the carnage of the last six to eight weeks.
Regards
Andy
Hello,
Wanted to get some insight into your reasoning behind Thg (LON:THG) over Boohoo (LON:BOO) (I hold). You mention Boohoo (LON:BOO) has a large amount of short positioning against it, which it does: Marshall Wace (2.7%), WorldQuant (0.53%), and AKO Capital (0.98%), and I'm sure there are others below the 0.5% reporting line. However, so does Thg (LON:THG): AHL Partners (0.61%), QUBE Research & Technologies (0.55%).
While both are arguably in deep Value/Contrarian territory. I do have a stronger conviction in Boohoo (LON:BOO) due to brand strength (as much as that exists in the retail space), and management experience compared to £THG.
Kind Regards,
Nik
My personal view when it comes to shorts, and this could be a purely arbitrary thing that has no scientific basis... is that I don't touch any shares with more than 3% short outstanding, or have 4 or more investors reported above 0.5%.
That's my line. Boohoo (LON:BOO) meets the 3%, and until recently, also had 4 investors reporting >0.5%.
Brand strength - I would disagree. Thg (LON:THG) have some top eCommerce brands in the beauty space (Cult Beauty, Lookfantastic, Perricone, Myprotein, etc). Whereas Boohoo strategy is now buying up cheap/failed brands, ones that have been flogged to death to the point they go into administration to be picked up cheaply. I have yet to see Boohoo reinvigorate any of those brands. Look at Debenhams - IMO they are just milking whatever legacy brand equity there is left there, not building it back up. I'm not saying I think Boohoo has terrible brand strength - they still have Boohoo and PLT - but I think THG is on par or better.
Supply Chain, Inflation - this is where I see THG having the edge. Higher end premium products, ones with more margin. They'll weather the cost and supply chain inflation better than Boohoo (LON:BOO) will with its cheap-as-chips clothing. While Boohoo (LON:BOO) have now belatedly started investing in logistics, warehouses, back-end tech.... THG have been doing it for years, which leads me onto...
Ingenuity - a lot of criticism have been levelled here at this bit of the business. But this diversifies THG away from just an eCommerce company (which is 100% Boohoo), and into a B2B, SaaS/LaaS part of the business too. Fundamentally, eCommerce has gotten so competitive nowadays, that if you were setting up a new company, it would take too much capex investment to create a world-class, 5-star rated logistics, distribution, warehousing operation. Sure, 10 years ago you could sell CDs out of a garage (which is how THG started). But you'd get 1 star reviews now if you did that, AND lose money because its not efficient. It is like Cloud Hosting. Every website, including Stocko, now outsources their hosting to a cloud provider like AWS, Microsoft, etc. Sure, you could still stand up your own server in your garage, but the website would load so slow, and cost you more. Ingenuity is building that entire tech, logistics stack for mid-sized eCommerce businesses out there. Of which there is a huge market size. Think every single brand that wants to do D2C. I'd argue that the opportunity for them is greater than Ocado's opportunity in online groceries; as in Ocado's case, most markets have 2-3 dominant grocery players who have the money (and market share) to think about building their own online grocery operation.
(I now hold, as of this afternoon, shares in Thg (LON:THG) )
Hi Boon
Thanks for sharing your thoughts.
That's really interesting on Thg (LON:THG) . I must admit to only having glanced at it in the past as I was put off by its (to me) high valuation.
The ingenuity product sounds interesting, though I can't work out what the USP is. It seems to be a combination of Amazon's FBA service and the services offered by a company like Shopify/Channel Advisor - see here:
https://www.channeladvisor.com...
There are quite a few companies like Channel Advisor, many of which are listed, so perhaps I am missing the opportunity with Ingenuity.
I don't hold $SHOP, $ECOM or Thg (LON:THG) .
---
To pick up the point on Boohoo buying old brands that don't add much to the business, that may well be the case with Debenhams, though I'd like to highlight that Asos (LON:ASC) seems to be flourishing with the old Topshop brands, especially in the USA.
From the last trading update Topshop sales have grown 200% YOY, albeit from a low base.
I do hold £ASOS and am looking to make it a much larger portion of my portfolio (though not because of the Topshop brands).
---
Thanks again.
A
I've not had direct experience of Thg (LON:THG) Ingenuity myself, so really am basing it off on investor presentations and my understanding of the service digging around their website for marketing materials.
But what I gather is that it is complete turnkey solution for brands. You can literally outsource the entire eCommerce operation to Ingenuity. Website, digital marketing, customer service, warehousing, fulfilment. And globally, not just in one market. You could be Primark, with no online capabilities, and within X months have fully functioning eCommerce operation without building headcount, spending CAPEX.
Amazon FBA only does the warehousing and shipping. Not the website, marketing, customer service. And definitely not packing items into fancy branded boxes (I believe it still arrives with Amazon tape on the box!)
Shopify only does the online website, order processing, payments. But not warehousing and fulfilment, and limited marketing. Plus, you still need to manage the website yourself, code it, update content, creatives, customer service, etc.
Channel Advisor is just an inventory management software, so it hoovers up all the orders from your various sales channels (amazon, website, ebay, etc) and sends them to warehouse. Does not give you an eCommerce website, nor manage the warehousing and fulfilment or customer service.
The question is how many brands want a fully outsourced solution (or maybe partial? I think Ingenuity can be bought in modules), since "digital" is meant to be the future. On the other hand, if Ingenuity does it well, and does it cheaper, then brands will happily outsource.
Trying to think of an illustrative example. Sodexho is the first that comes to mind. Companies can completely outsource their catering requirements to this company, who then does everything - make food, maintain canteen premises, manage payment, regulations, do marketing (website/email with menus). Complete turnkey solution. As Sodexho has the same playbook, systems, equipment for all company canteens, they are uniquely positioned. Some offices will still run their own catering, if they're big enough or too small, but many small offices outsource to Sodexho.
Thg (LON:THG) (no position)
Thanks Boon
I understand what you're saying; having everything organised under one roof certainly sounds appealing.
I guess what I don't really understand is that it will take many many years for Thg (LON:THG) to build a completely independent worldwide warehousing/delivery system and in the meantime several companies are already doing this.
In the UK £NEXT comes to mind, and more globally Asos (LON:ASC) , which has spent hundreds of millions of pounds over the last 3-4 years setting up a next day delivery service in the USA, and still plan to spend another couple of hundred million pounds this year alone automating their warehouses further.
Asos have also started taking orders for retailers such as Adidas and Rebok, which are then fulfilled by these 3rd parties directly.
For a bigger, better known beast in the USA, Shopify also offer fulfilment services, alongside online store creation:
https://www.shopify.com/plus/s...
https://www.shopify.com/plus/s...
I'm certainly not saying that Thg (LON:THG) won't be able to achieve success with Ingenuity, but I get the impression that they've just started a race that began a while ago. Or maybe I'm simply missing what's so special about it.
I'll try and keep an eye on it, as I'm genuinely intrigued, though like you, I am wary of any Softbank investments, especially after the WeWork debacle.
Cheers
A
You're right that there are some other players globally that could offer what THG is trying to do with Ingenuity. Like ASOS. Even Amazon, if they really wanted to pull together a complete turnkey solution for brands.
Thanks for your insight. I will have to take a closer look into the Ingenuity aspect of THG's business.
I can't remember the exact figure that was part of the Thg (LON:THG) scandal. The one where Softbank invested some money into Ingenuity for a future potential option to get a bigger shareholding. But that deal valued Ingenuity at like $6bn.
Now, I take Softbank valuations with a grain of salt. But they're not complete nutters. So that was what made me dig into Ingenuity. To see if there was actually some substance in it. And I liked what I saw, in terms of their ambition and vision. However, execution is important, and we haven't seen proper ££ figures yet for Ingenuity I believe.
I will definitely swap you, I am negative 10% and it is rapidly getting worse.
Hi again Boon
That is a ridiculously good YTD performance. I am 30% cash too, but my portfolio is still down 8% for the year.
Nice to see Spectra Systems (LON:SPSY) is on your top up list. I topped this one up last week - the first purchase of the year.
I've been slowly topping up a few other holdings today (including Asos (LON:ASC) ) but still retain a decent sized cash position.
Fingers crossed with the deployment timing!
A
Ah, I didn't end up pulling the trigger today on topping up with Spectra Systems (LON:SPSY)
The De La Rue (LON:DLAR) update spooked me. Can Spectra really escape the same shortages and cost inflation?
SPSY usually overdeliver in terms of EPS compared to broker forecasts. So maybe they'll still hit FY21 and FY22 forecasts even with headwinds, as the forecasts are conservative. Hmm.
Will mull it overnight and maybe decide tomorrow.
Spectra Systems (LON:SPSY) (I hold)
I don't really follow De La Rue (LON:DLAR) , so I can't really comment on their trading update.
I do know that from today's Spectra Systems (LON:SPSY) update there was specific mention of an additional $700k in revenue above forecasts for the year.
Presumably if the forecasts had changed, one would hope that the company would have told us at the same time!
As for margins, I'm not really sure how these might be impacted.
Company revenues are quite small (c.$17m pa at the moment for the entire company) relative to some of the customers they deal with (eg Dr Pepper, Major National Banks, State Lotteries, etc...) so I imagine that if there are raw material costs to pass through, the end customer won't really have an issue with them.
It's also worth adding that:
Of course, nothing is guaranteed, but I've found that this company has been quite good at communicating with their shareholders.
Fingers crossed nothing has changed yet.
Cheers
A
The De La Rue (LON:DLAR) update spooked me. Can Spectra really escape the same shortages and cost inflation?
There's not a great deal of detail in the De La Rue update but my guess is that the cost inflation primarily relates to their banknote production. Spectra, on the other hand, don't do any banknote production, they produce the security features that go into the notes such as security threads and inks (and therefore may be a source of the cost inflation, rather than the victims).
I wouldn't take this as gospel - it's quite hard to figure out everything that Spectra do, and De La Rue weren't exactly forthcoming - but I didn't immediately start panicking and sell my Spectra shares.
timarr
That's a fair point, as far as I know Spectra don't have run production facilities for banknotes.
Thanks for covering £cns Corero.
As Jack says there has been massive dilution over the years. That said, no one has put more money in than Jens Montanana.
JM bought into cns in 2011 and basically controls the company. He is a big hitter in the world of IT. He could have cut his losses on cns several times over the years but hasn’t. Instead he has continued his support seemingly throwing good money after bad. That makes me think cns could still come good.
My theory is that cns was completely wrong footed by the shift to cloud. I think they invented a product for on-prem hosted web servers and when the cloud took off they were left with no market. But that’s just my theory.
I haven’t followed cns for years now but maybe they have now got a product that can fit the cloud and the alliance with Juniper is opening up that market?
When I researched cns in 2017 Arbor and Akami were the market leaders in DDOS and they were both $b companies which suggested to me that cns could be a big winner if it ever took off.
Do any SCVR subscribers have any view on the story, or any experience of the DDOS protection market please?
Many thanks to Lawrence, who has put the SCVR podcast on Spotify! Here's the link, so give us a follow if you'd like to hear more.
https://open.spotify.com/show/5a88szPaUW23D5U2h9dwvc?si=311867556461422b
Blimey, some real panic selling today in UK small caps. I always remind myself that panic selling is not necessarily logical (a lot is irrational, driven by fear). Therefore just because a share I like is down 7% today, doesn't say anything about whether my reading of the fundamentals is right or wrong. An important point to remember I think.
Also, that today's big falls, will in some cases, be future profits. Anyone sensible enough to have kept some cash back, is now in a lovely position, being able to choose your spot, and pick up bargains. I like buying in 3 tranches, in situations like this - not trying to catch the exact bottom, which can be impossible as everyone tries to buy at once - I remember that happening in March 2000. I began buying heavily about a week too early, but managed to get nice sized positions in some illiquid stocks. Then when the market did turn, you couldn't buy at all in some of them, as the sellers had dried up. So they just rose vertically.
I've no idea when the panic selling stops this time, but it looks to me like we could be getting near to a capitulation low, and then a big rally. But that depends on what computers in the US do! Not something we can control.
I hope subscribers aren't getting too stressed!
Regards, Paul.
P.S. It's usually about now that one or two people turn on me, and blame me for their losses. So I'm expecting that any day! ;-)
I hope subscribers aren't getting too stressed!
Thankfully i am more worried about trying to get tax returns filed before 31st January - seems like a good time to remind everyone about the tax return filing deadline next week. Have you been a good boy and filed yours early Paul :)
Re: TAX RETURN ONLINE FILING DEADLINE: This year only it has been EXTENDED TO 28 Feb 2022
https://www.moneysavingexpert....
"You could be hit with a £100 fine if you miss the deadline to file - plus, extra penalties for paying the tax late
"Normally, you are charged a £100 penalty if you fail to submit your return by the deadline – even if there's no tax to pay. However, this year HMRC says it will waive late penalties so long as you file online by 28 February. Miss this deadline though and the £100 fine will apply."
However Imaybe useful to add that interest will still be applied to payments paid after 31st. Although no penalties until 28th Feb as you mentioned.
This headline is a bit of a lie - well probably more of a complete lie being honest
"TAX RETURN ONLINE FILING DEADLINE: This year only it has been EXTENDED TO 28 Feb 2022"
The filing deadline most certainly has not been extended - the only thing that has happened is that some of the fines etc have been pushed back a month. If you file or try to file after 31/1/2022 your return will be filed late and you may still suffer the issues that can crop up if you file late as per ususal (extra 3 months for tax office to enquire into your affairs being an example).
Yes! Very painful so far; i'm seeing near 5% down. I'm fully invested, so no money on the side-lines for me either. I've given up looking at my portfolio and am just keeping an eye on the Stock front page, which shows overall percent down on the portfolio and keeping an eye on the RNS feed (in case there is news that needs looking at). I'm long term, so have to keep reminding myself this is just a blip :)
Still don't know how much cash I need to pay HMRC on Jan 31-waiting to see my completed return from accountant. Any spare then will go into the market. Good time to think about charitable donations to reduce the bill! Do't forget that these count 12 months in advance, so OK for 2021-22 tax year but credited now.
<duplicate removed>
Thanks for the note about Stress Paul
Advice to oneself stay calm - surely one knows how markets operate after 30 years of checking everyday.
yet upon checking ones portfolio the same fast heart beat and Stress levels reappear again and again. :(
So, don't look.
A bit stressed! My annoyance is not shorting the DOW/NASDAQ at the start of the year. This could be near bottom, so shorting now would be risky...DOW could easily spike up 1000 points any day!
Hi Paul,
There is some reassurance that we are all going through this turbulence together. FTSE250 is struggling to maintain a key support level. Is this a low point or the start of a bigger drop?
I top sliced Somero Enterprises Inc (LON:SOM) recently and now I'm buying it back at 15% discount (super company in my opinion).
Saga (LON:SAGA) looks like a buying opportunity at £2.68 but I'm already overweight.
Of course if the Russians invade Ukraine then all bets are off in the short term so I'm keeping some powder dry.
Painful to look at share prices sometimes, so thanks for the note of calmness Paul!
Good time for topping up on long term holds
I have about 20% of my wealth sitting in cash at the moment (from surplus income ) which has been sitting their patiently waiting for a market correction. I haven't pulled the trigger yet as I believe we need to see what pans out in Ukraine over the next few weeks but I am moving money around to be ready.
I missed out on the dot com by having no surplus cash (I was building an house) and only partially took advantage during COVID. I don't want to miss out this time but also don't feel its time to go in. I very much like your idea of buying in tranches but I'm also a bit too conservative at times.
I am waiting for the BBC to have in their headlines about a stock market crash and that'll be my trigger
John Authers' column today has some interesting thoughts on the markets generally. Worth 10 minutes of your time if the macro view interests you. I am suffering too - 95% invested. Lots of companies on my watchlist going below my target buy price in the last couple of days.
link please
stressed???? I've hit 3 stop losses today lol!
This is the first time I have ever posted on here but I was interested in your comment on the UK Stockmarket getting to a low and rallying. The S&P 500 has just dropped below 4,300 and there was an article in the FT last week saying that the stockmarket is a ‘superbubble’ that is about to burst and that the S&P 500 might go as low as 2,800 i.e. a drop of c.60%. While this might be sensationalist headline I am concerned there might be some truth when you look at the valuations and the lack of cash generation from a lot of the tech stock stocks.
I have gone 100% cash partly to fund a house purchase (poor timing I think!) but also because I think the shares I had will drop 40-60% as when America sneezes Europe catches a cold. I have been frustrated by the lack of share price growth in the UK post Brexit and post Covid compared to the US particularly when companies have outperformed their numbers they did well for a week / a month but then dropped back into line with the indices which was mediocre at best. I am genuinely wondering where to deposit my cash post the bursting.
Thanks for your brilliant work Paul and Jack which I so enjoy reading / listening and would be interested in your thoughts.
Best,
Barnaby
Barnaby
Just to say that it’s best to be very wary of anyone who thinks they know where markets are heading, except sometimes very short term. Time and again markets do the opposite of what we expect and they can climb “a wall of worry’” or fall heavily when least expected to.
e.g look the huge and fast rally from April 2020 when covid news was dire, much of the economy here and elsewhere shut down, and fears of another Great Depression ahead. Then many “market experts” were predicting a long and savage bear market. Instead it turned out to be a great once in a decade buying opportunity.
These days, with computers a factor in this, markets can turn on a sixpence, even on the same day.
E.g one day last week the Dow Jones index swung from 400 points up to 600 down by the end of the day.
Note too that more than half the shares in the US Nasdaq index are regularly hitting new 12 month lows, and many of those have now fallen over 50%. It’s the sometimes hugely overvalued shares like Tesla (PE300) that have hidden the much bleaker picture underneath that has been going on for a while now.
Key thing when we’re worried and markets are having a bad run is to sell anything we know we’ve got wrong, and also to have more in cash than usual (though arguably 100% in cash is extreme!) to take advantage in falling markets of the opportunity to buy quality bargains at a discount and to top up existing holdings we’re still confident about.
Sorry, typo but too late to edit. I meant March 2020 of course, not March 2000! Apologies.
I can see Vin Murria's thinking. She probably looks at Martin Sorrell's S4 Capital, it acquisitions and its significant market cap, and thinks here is an opportunity which M&C are missing., and that the cash shell provides some of that monetary fire power if there is basically a share swap.
However, VM has no other presence in this particular segment of the market, and by the manner of the approach, does not seem to have pleased the board which she is part of.
She needs to be very careful, PR and advertising is very people orientated, and they can walk if they think the company is unstable or no longer serving their needs.
Backroom plotting can look very unedifying if the vision appears self-centred, so VM probably needs to do more work on projecting the vision for the Company, but the problem if the incumbent management fundamentally disagree or aren't interested, it seems like a dead duck.
Accrol Group (LON:ACRL) H1 results presentation by Exec Chair, Dan Wright, CEO Gareth Jenkins, and CFO Richard Newman, given last week following publication of results. Video & podcast. This is the management team that came in from DS Smith, which they turned around. They have been dealt a very tricky hand with such strong inflation. They are handing on cost increases to customers, but there is a time lag. The outcome of the strategic review will be a key insight. They were open about the challenges and how they are dealing with them.
On a relatively quiet day today, (apart from SPs going through the floor), Car Dealer shares seem to be particularly hard hit on Friday last. &% drops were not uncommon. Was anything published about outlooks from any of the big brokers?
like the RBG video…..First thing I noticed (other than the peacock blue colour) was that the tables ,as you walked in, had legs that made an ‘R’ shape ……Nice touch ..
Does anyone else watch small company renewables, especially Hydrogen and Energy Storage related stocks? There has been a big sell off in Afc Energy, Powerhouse Energy (LON:PHE), Ilika (LON:IKA), Invinity Energy Systems (LON:IES) and even the top stocks like Ceres Power Holdings (LON:CWR) and Itm Power (LON:ITM) too. It seems that jam tomorrow/tomorrow really is not the flavour of the month.
Obviously, many of the smaller stocks came from nothing so are still showing huge gains on the Sp's only a few years ago, but at the time of COP 26 in Nov 2021 were standing much higher than now.
So many investors really seem to be into short termism and especially perhaps cashing in on some of the profits made last, top slicing or selling out altogether into cash. Thoughts anyone?
Same goes for uranium - Geiger Counter (LON:GCL) and Yellow Cake (LON:YCA) too.
it’s one thing after another! So much FUD at the moment - pandemic, interest rates, inflation, Russia/Ukraine. Last two quarters my e-commerce portfolio took a hammering, and still is, along with growth stocks. There’s clearly panic selling going on. I’m frustrated that I can’t average down as my ISA allowance is maxed out. 4% down today at the moment and about 10% down over the past 3-4 days. Things will get better, just not sure when. When it does I’m hoping the uplift will be as quick as the drop!
Think the main thing to remember is that stocks won't go to 0, and to have cash on the side to take advantage when the market stabilises/rises...easier said than done!
I hope not, I’m 8% down today!! :-)
De La Rue (LON:DLAR) Wow, the market took that RNS badly this AM. Down 27 - 28%. I have been getting uncomfortable with the time their turnaround is going to take and this certainly will extend this time. Time to cut & run???
Time to buy I say. Omicron must have resulted in plenty of their staff reporting sick or on quarantine but the worst is over. Omicron hit Malta quite savagely but cases are now down and people aren't caring so much about it.
re De La Rue (LON:DLAR), as I read the RNS the big hit was on staff availability, so really that impact should be going away now.
One other potential headwind with De La Rue (LON:DLAR) is Crystal Amber's 10% holding in DLAR. Subsequent to a continuation vote, which Crystal Amber lost, they are having to "reorganise, reconstruct or wind-up". Crystal Amber could start offloading their stake into the market depending on how they view today's update, thereby adding further pressure on the share price. Alternatively, with such a sell off, I wonder whether there are any potential buyers that would be interested in buying the stake.
From today's revised underlying operating profits of £36m-£40m, my back of the envelope calculations resulted in PBT of £30m-£34m after finance costs. Applying a 19% effective tax rate results in an EPS of 12.3p - 13.8p and a forward PE of 8.3 - 9.3 which offers a lot of value.
Management aren't saying the Turnaround Plan needs significant alteration and the labour shortages are will be temporary. However, they have indicated inflation and chip shortages are likely to persist for a while.
This one is like a see-saw: trying to balance the value v management's commentary v Crystal Amber's position.
Its patently obvious that De La Rue (LON:DLAR) did not find out on Friday afternoon that they were going to miss profit forecasts by such a wide margin. How long have they hung on to this information without updating the market? And management are in a business where trust is a key issue. Trust lost IMHO and they're uninvestable if they won't update the market promptly.
Very much enjoy the end of week round ups. As somone who writes for a living, I know these written up summaries can take ages. While very useful, I would personally be very happy just to have the audio, with perhaps just a list of the companies featured.
I agree, especially as the podcast is a round up of previous articles. So we get the transcript of the podcast of the articles that were already published - where do you stop?
Good Morning, Bouden54,
Thanks for the feedback. Yes, maybe I'll stop typing up a full summary of the podcasts - it's about 3 hours work, which I really don't want to do on a weekend!
As you say, there are summaries at the top of each SCVR anyway, so it's duplication. Think I've made up my mind that typing up a colour-coded summary is not a good idea to continue with.
Best wishes, Paul.
If it's hurting Paul then don't do it - a long time ago I was struggling to produce a projection for the ensuing day's production at the end of my night-shifts as part of an efficiency drive and told my boss it was killing me. He said not to do it it then so I didn't and never looked back.
Best Wishes, Silver
Hi, I believe you can dictate it into Powerpoint, they use voice recognition to produce text.
I really like the colour coding. Maybe just have a list of the shares mentioned (without the summary) and colour code the names/ticker?
Ive started writing very short traffic light notes onto charts. Ahead, Materially ahead, Miss, In line etc. I find it's a great help for a quick visual reminder of a companies progress over several years.
But I always preferred looking at pictures to any serious reading
Hi Paul,
How about using Dragon naturally speak to dictate your summary instead of typing it up? Could be a lot quicker.
How about using Dragon naturally speak to dictate your summary
I've tried it, and it just doesn't work. Too much technical stuff, and text it doesn't recognise. I spent more time editing & correcting, than typing it myself!
P.
Hi Paul, If you and Jack find the following a useful aid for referring back, you could just list companies & the audio times at which their discussion begins - much as Tamzin does at PI World. Either way, thanks for doing the audio summaries.
Taken a bite of Cake Box Holdings (LON:CBOX)
Time will tell if catching this knife was wise, but a PER of 17 for this year looks a damn sight better than almost 30x 3 months ago.
Ive read Maynard Patons points, and agree it looks unprofessional. There isn't really anything new tho that I can see, market was happy to ignore at the time, and management say they are improving 'control and governance framework'
Hello Gringo. Remembering their presentation at Mello recently, they have yet to implement ingredient price increases to their franchisees which is in the offing now. That wont help franchisee sales and especially profits. Cant see much upside at the moment with household money getting tighter.
Hi,
Thanks for flagging, I hadn't spotted that Cake Box Holdings (LON:CBOX) was down 20% at the time of writing to 260p. I think this could be a good buying opp. It's not a share I hold personally, because it was too expensive previously. But suddenly dropping heavily on some article, looks a nice opportunity to pick up a good share at a much better price.
It got over-valued at c.400p, and then mgt selling down some shares put me off, as founders know the business best, so if they're taking some money off the table, it's often a good idea to follow them out.
Pity I don't have any spare cash, otherwise I'd be a buyer at 260p. We like CBOX at the SCVR - it's reported positively throughout the pandemic, and we like the entrepreneurial founder.
Regards, Paul.
EDIT: I've read Maynard's article - wow, what an impressive really deep dive into the Annual Report, must have taken days to produce that article, so respect is in order.
It looks like a lot of muddle, with errors being corrected (which quite often happens with prior year figures being changed). The whole thing just looks sloppy to me, rather than anything seriously wrong.
I've looked at the last published balance sheet, and can't see anything large or obviously worrying. The balance sheet is where the bodies are buried, if accounts are being mis-stated, e.g. Globo had a range of large & unusual phantom assets on its balance sheet, which were obviously dodgy. I can't see anything like that on CAKE's balance sheet, but who knows. It wouldn't be particularly difficult to bury a few million quid of excess profits in there, by under-stating liabilities and over-stating assets. So it's possible. Auditor resigning, and making negative comments, is definitely a concern though.
So maybe I wouldn't be so quick to rush in and buy?
The big Director sell not long ago was a red flag though. I think we commented on it here at the time possibly?
Earning Manipulation Risk
Bought into Cake box at 2.79.
Last week. I decided to give myself a refresher course in stockopedia, so had a look at 'How to conduct forensic investment analysis' the one thing that stood out with CBOX was Earning Manipulation Risk.
After a high of 4.26 on the 19th Jan the shares dropped another 12p
I sent an email to the CEO "
Dear Sir
As there is no contact page for investors on your corporate web site (which is unusual for a PLC) I have taken this root to contact you regarding the share price.
a) It may be in everyones interest to comment on the fall in the share price down another 12p as I write.
b) The fact that you never made a comment on the sale of shares by S.R.Chamdal on the 25th November has not helped
May I say that the company has done very well to this point which is why I hold shares, however, an RSN Trading Update to steady the ship my be a good idea at this point.
I received an answer from the CFO
"Thank you for writing to us and your support as a shareholder. We have noted the points you make. Sold at 3.20 the next day.
Good idea to look at each holding you have and run it through the forensic investment analysis
Tony
Does anyone know what caused Cake Box Holdings (LON:CBOX) to crash today? Its 24% down. I cant find any news that caused this ..
See above.
Cake Box Holdings (LON:CBOX) Maynard Payton has a very well written article on Sharescope - Google will find it
Please ignore above post - I found the reason in the thread below started by JohnDoe2378
https://knowledge.sharescope.c...
More shenanigans in the US markets late last week, with markets selling off again. Although futures are up strongly this morning, so who knows whether this is just a healthy correction from over-valuation, or a new bear market?
The Russell 2000 is already down 19%. The Russell 2000 growth ETF (IWO) is down 27%..
Indexes are only up 0.5% at the moment hardly strongly, my US stocks that are open 24/7 are mixed, some up, some down, nothing up more than 1%. Considering the massive sell off on Friday, this is small beer.
Flight to safety?
People are talking about a tech sell off. But Bitcoin has crashed too (down over 30% in the space of a month). Is what we are seeing more a flight to safety across the bored rather than something more segment focused?
If so, what is the safer haven? Cash - surely not with inflation rampant. So, where?
When has Bitcoin been a "flight to safety" asset?
Does anyone have any stats showing bitcoin performance during times of risk off?
Don't have stats, but bitcoin essentially behaves like a risk asset. If you want safe havens think US Dollar, US Treasuries and especially TIPS (inflation linked treasuries). Gold another option but less predictable and more volatile.
One bitcoin is still worth one bitcoin. If that's a stable and useful store of value then what's the problem?
If people are expecting it to continually buy them more US dollars - well that emperor has no clothes on.
Sorry my post was poorly worded. I’m not saying Bitcoin is a flighty to safety asset. What I’m saying is that people are fleeing away from high risk assets one of which is Bitcoin so what does one flee to?
Nothing. In a risk off environment, everything is sold to cash. Sometimes because of leverage, so sold to cash to pay off debt.
Traditionally one goes for gold in risk off. But that doesn't seem to be working anymore these days. £SGLN is the easy choice for gold. I see its up today and last few days, but nowhere near what it should be if gold was seen as the flight to safety asset.
(I hold)
It was reported over the weekend that so far this year, Elon Musk's net wealth has dropped by $28 billion and Jeff Bezos net wealth is down by $20 billion. If that is any consolation!!!
Graham F I think your post was badly read, not badly worded.
Like the video. So, was that 3 different rooms with bars? Looks very big place. Are the other sites of similar size?
Would I be right in saying this site is on the edge of the centre of town? If it is the spot I remember there will be plenty of other drinking spots quite close by. When I lived there, there used to be 30 odd night clubs and it was a very busy place for a night out. I imagine it still is.
Morning gmtrader,
Re Revs Bar in Bou'mth, it's one main room, with a raised bit at the back, up 3 or 4 steps, then up another 2 or 3 steps to a VIP area. The bar is an oval shape in the middle.
There's a side room (in the second section of my video), which was usually empty before, but is now done out as a nightclub section, and function room. So for example when I was there, a group of 6 cackling young women were in there, doing what looked like a cocktail making/tasting session, which got progressively louder! I think better use of the side room (with its own decent sized bar) should drive LFL sales up a lot.
As the Manager pointed out, once the social media "influencers" are in the bar, and pouting for their instagram photos, it "pulls in the lads!"
The Bou'mth site is in Old Christchurch Road, which is about a 5-10 minute walk to the East of the town centre, and together with the town centre itself, are the two main drinking/partying/curry-kebab type areas. So yes, lots of competitors bunched together, e.g. a large Walkabout, DNA Bar, and other smaller cocktail bars.
After its refit, Revs is now the stand-out biggest, brightest, cocktail bar in the area. I think they'll do a roaring trade after this refit. There are quite a few bars that closed, and have never re-opened too, so some empty units still nearby.
P.
cheers Paul
I thoroughly agree with "... suggesting they move to a "little & often" maintenance strategy, to keep these sites looking new, instead of slow dilapidation - which seems to be the norm in this sector. "
March 2020: Gold down 15%, Bitcoin down 50%. I'll stick with the tangible.
I see that the Ukraine situation is bearing down heavily on the FTSE at opening today.
Mmm. Wont be helping Ferrexpo (LON:FXPO) one little bit. Right in the line of fire in Eastern Ukraine. Area called the Donbass which Russia would like to annex and quite a lot of the local industry and population wouldnt worry too much I would guess. That area has tended to be backward in development and eastwards facing in trade.
what about POLY? Would that be impacted? Any other companies you see could be impacted by a possible incursion?
Definitely Polymetal International (LON:POLY) which I hold, but what about all the other gold and precious metals miners? I run a virtual portfolio of 25 miners and it is down 3.1% today, only 2 companies see a risen SP.
I put it down to the impending exit of our current PM. Nothing else makes any sense at the moment.
Silver Moon
Morning all,
Cake Box Holdings (LON:CBOX) sharp fall this morning, any reason why?
I do not hold.
£cbox
I have seen some posts on Twitter, from reliable sources (@MaynardPaton) suggesting auditor concerns about control and governance. Not in an RNS but annual report.
I have not checked myself
Maynard Payton article on Sharepad: alarming remarks from auditor and unusual financial disclosures in accounts
Cake Box Holdings (LON:CBOX) Latest accounts and governance questions have been raised by Maynard Paton causing the SP to drop circa 25% . Sell or a Buying opportunity? I would welcome Paul or Jack's take on this?
Cake Box Holdings (LON:CBOX) Sod's law: Did My Own Research and bought only 2 weeks ago. My financial analysis not good enough to spot what Maynard has spotted :-(. Now in quandary as to what to do.
Optimistically, this is a small company that grew into a large, still growing company without maturing financial processes, has now recognised this and is taking steps to fix. Pessimistically, this is a company that has accounts that are not under control and is hiding things. Definite lesson learned: if an auditor resigns - read the resignation letter.
I think that the FD needs to review his position (or have it done for him), and not impressed with the Chairman either. He has held some successful company posts including with Kape Technologies (LON:KAPE) too. In this type of business, the spectre of Patisserie Valerie is always there. Maynard Paton does show a significant number of real discrepancies.
Sold out this morning at a loss. Should have followed the CEO's second share sell out in a year last November at a discounted price of £350 vs SP of around 400p at the time.
Bitter taste in the mouth. Will have to watch choice of Mello company presenters more carefully in future,. Been quite a few casualties in the last 12 months. Always DYOR and don't blame anyone but yourself is my motto. I trust the Mello Bash sessions more than anything. There you have the expert investors putting cases forward and being questioned by the other experts. Balanced review.
If you guys are interested, there is a rebuttal piece written here:
https://blackswanshares.substa...
Personally, i've like cakebox shares for a while and see this as an opporunity to top up my position. However, they should really do more to fix these governance and accounting issues.
https://knowledge.sharescope.c...
Hostmore (LON:MORE) (I hold) Following on from Paul’s mystery shop of TGI’s. I went to the Gloucester Quays TGI on Saturday at 7.30pm. It was really busy. Loads of fun, good value but short of staff.
They were so short of staff that the duty manager Roxy was covering half the tables as well as managing the store. She prevented a complete meltdown in service. A superb employee but people that good won’t stay long if they don’t get support from management.
As an investor I’d implore the executives to pull out the stops to hire the best staff in the industry. Be the best place to work and pay the highest rate. The hospitality winners over the next few months will be the firms that can serve the high levels of pent up demand.
Following my visit I am continuing to hold. If this is their quiet period then they will be very busy in the spring assuming they can serve their customers.
The Gloucester one is always busy, I've never been in myself, but I've heard a lot of good things about it.
It would be interesting to compare with the Cheltenham one only a few miles away. That's been there for ages, in a completely different location and rarely looks busy.
Bloxs & Revs8. OK fellow investors - I live abroad so can't really help. Get mystery shopping and post your results here. Enjoy yourselves whilst you do it.
Wow, didn't realise there was a Gloucester branch of the SCVR, maybe we need to go to "Fridays" to compare notes.
The Cheltenham one is in a totally out of town location with only a hotel next to it, to help get the punters in, but as you said, its been there ages, I probably last went in there 20 years ago, so it must be doing something right. The Gloucester one defo has a cracking location and never had a bad meal in there.
Hi GloucesterBob. I noticed from your name we must live in the same locality. I’m in Cheltenham.
Agree that tgi Cheltenham is in a strange location. Assume it’s viable as it’s been there for a long as I can remember. Possibly hotel and local customers.
happy to meet up if you fancy a face to face. Start our own Stocko investment club? An excuse to mystery shop hospitality sector ;)
If I have any money left in March will try to set something up, we can drown our sorrows if nothing else.
Why does Gross gearing for Hostmore show as -800%? Is it likely to be a data error?
Not a good day for £DLAR.
Could have been even worse though - see this headline from a few days ago:
De La Rue, the banknotes manufacturer, has avoided adding £20m to its
pension scheme’s liabilities after a judge ruled in its favour over how
certain members’ deferred benefits should be revalued.
Similar company in the same space Spectra Systems (LON:SPSY) announced new contract wins today. But possibly might have the same supply chain, Omicron labour issues as £DLAR ?
(I hold)
When is the trading update from Saga expected?
Thursday 28/1
Thanks DT
Saga (LON:SAGA) According to stockopedia update is due Tuesday 25th,
Saga investor website has the update on Thursday 27th.