Small Cap Value Report (Mon 25 Sept 2023) - SPSY, PDG, DEVO, VCP, SED, WIL

Good morning from Paul & Graham!
Today's report is now finished.
Mello Monday is tonight at 17:00 - details here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Here's what has caught our eye today -
Summaries
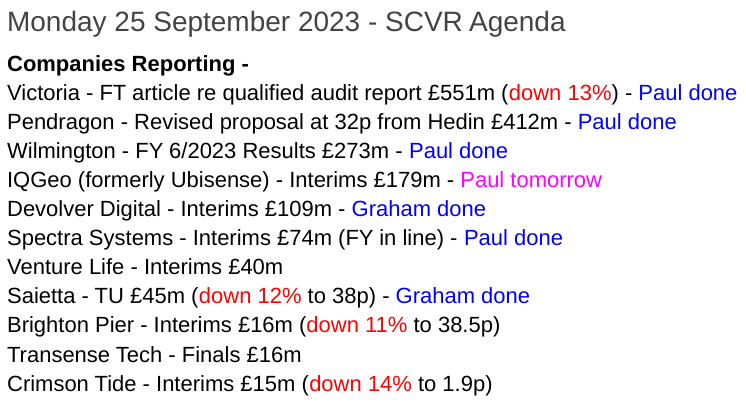
Spectra Systems (LON:SPSY) - 166p (pre market) £74m - Interim Results - Paul - GREEN
Excellent H1 numbers, with most of the FY 12/2023 forecast earnings already in the bag, so I expect an earnings beat later this year. The cash pile is 18% of the market cap. Generous divis from healthy cashflows, with a very asset-light business model. Assuming it continues to perform well, then these numbers stack up very nicely, hence a thumbs up from me.
Pendragon (LON:PDG) - 29.6p (£412m) - Revised proposal from Hedin at 32p - Paul - AMBER
Announced on Friday afternoon, major shareholder Hedin has sweetened its takeover proposal (not yet a formal bid) to 32p. This strikes me as a better offer than the plan by management to sell (too cheaply?) the core business, give shareholders a 16p dividend, then keep a rump holding of its Pinewood software business. Maybe time for PDG management to capitulate?
Devolver Digital (LON:DEVO) - unchanged at 24.4p (£108m) - Half Year Results - Graham - AMBER
This publisher of indie games announces bad results, as expected, and reiterates guidance for adj. EBITDA breakeven in the current year. I keep my neutral stance because it does at least have a large cash balance. Interesting games coming out over the next 12 months.
Victoria (LON:VCP) - down 12% to 486p (£557m) - FT article re audit report - Paul - AMBER/RED
A highly critical FT article today (flagging the qualified audit report issued last week) caused a big spike down in price this morning, for this floor-coverings group. Is it a storm in a teacup, or signs of deeper problems? I don't know. I've taken the opportunity to review the last accounts, and am put off by huge adjustments, and a nasty balance sheet with negative NTAV and far too much debt. So it's definitely not for me.
Saietta (LON:SED) - down 18% at 35p (£36m) - Full-year trading update (earnings downgrade) - Graham - RED
A terrible trading update from this EV drivetrain company. Its cash balance has fallen to little over £1m; it says that this is enough but forecasts suggest a rising net debt position. Its results are late and must be published this week to avoid a rule breach. Bargepole stock.
Wilmington (LON:WIL) - Unch 311p (£273m) - Results FY 6/2023 - Paul - GREEN
Super results from this lovely GARP share. It ticks pretty much all my boxes - good profit growth, high margins, reasonable valuation, strong cashflows, plenty of cash in the bank, and ample dividend paying capacity. I suspect this might become a takeover bid target, and like the shares a lot.
Paul’s Section:
Spectra Systems (LON:SPSY)
166p (pre market) £74m - Interim Results - Paul - GREEN
A nice clear description here of the group’s various niche activities -
Spectra Systems Corporation ("Spectra Systems" or the "Company"), a leader in machine-readable high speed banknote authentication, brand protection technologies and gaming security software, is pleased to announce its interim results for the six months ended 30 June 2023.
I have a favourable impression of this share, and checking my spreadsheet summary (using CTRL+F, ticker), find the following positive previous commentary here -
20 March 2023 - GREEN 170p - 12/2022 results ahead exps. Lots to like, thumbs up.
24 April 2023 - GREEN - 160p - down 13% on abrupt departure of CFO. Paul likes this GARP share.
14 June 2023 - GREEN - 166p - Minor, reassuring update about 2 contracts.
The only concern there is the CFO departure, which can sometimes be a sign of trouble ahead. The share price has been going sideways this year - not bad in a bear market.
Interim Results (6m to 30 June 2023, reporting in US dollars) - key points -
H1 revenue $11.6m (up 25%), helped by earlier delivery of a key contract, WHI note says.
Adj PBT $5.8m (up 59%) note the very high profit margin, at 50% of revenue!
The P&L is characterised by having high margins, and low overheads - this is clearly a lean operation, relying on know-how rather than fixed assets.
Statutory PBT is similar, at $5.5m, so only small adjustments (generally a good thing)
Adj EPS 10.8 US cents.
Outlook - on track to achieve record earnings, and meet market expectations for FY 12/2023, it says. Since Allenby’s full year forecast is 13.1c, and 10.8c is already in the bag from H1, it strikes me that an earnings beat now looks highly probable. Hence risk of a profit warning looks very low.
Balance sheet - very healthy indeed, including $16.6m in cash, about £13.5m (remember to translate all numbers into sterling, easily forgotten!), or 18% of the market cap.
NAV is $27.2m, less $7.0m intangibles, gives NTAV of $20.2m, which is nearly all cash (since fixed assets are minimal). Note that the cash pile is now earning interest, with $172k interest income in H1.
Cashflow statement - looks fine. The simple version is - it generates real cashflows, and pays it out in dividends. That’s pretty much it! There’s little (almost no) capex, again emphasising what a lovely business model this is.
Paul’s opinion - remains very positive. Given the likelihood of an earnings beat, then I’d guess the PER is usefully lower than the 15.1x shown on the StockReport. Something nearer to about 12 is probably more likely, if H2 is even half-decent.
Plus you’ve got c.18% of the market cap in the company’s cash pile (which is mostly permanent, not timing differences from customer payments).
Spectra’s propensity to be generous with dividends is another positive - it’s not often you find high margin growth companies that pay out value share dividend income!
So these numbers get an enthusiastic thumbs up from me, again. Obviously what I cannot tell you is what the future holds. You have to make your own assessment of that, and this is arguably the main skill in investing - spotting future winners. It seems to me that the commentary today contains plenty of interesting nuggets about future business, to be hopeful that strong performance might continue.
So assuming that performance continues to be positive, then the numbers stack up very nicely for this share, hence another thumbs up from me.
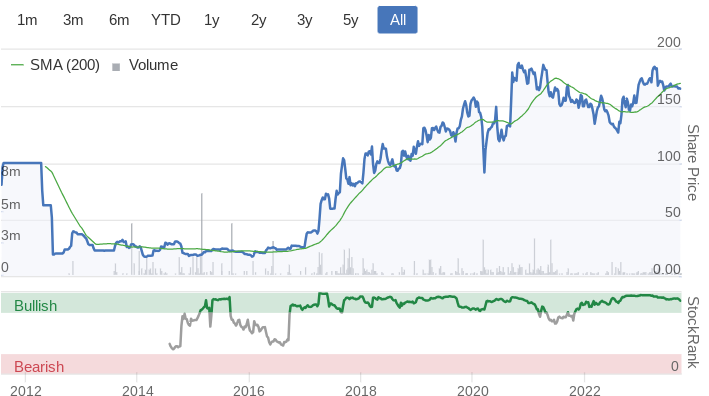
Shares started to take off in 2017, have multibagged since, and not looked back!
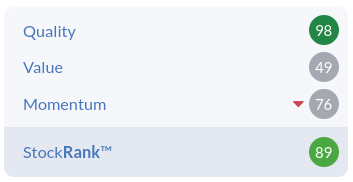
Note also the high StockRank, which we like!
Pendragon (LON:PDG)
29.6p (£412m) - Revised proposal from Hedin at 32p - Paul - AMBER
I think this could be the decisive move in the takeover battle for car dealers Pendragon. Major shareholder Hedin/Penske has sweetened its indicative proposal to 32p cash, which I think is more attractive than the company’s original proposal to sell its core business (too cheaply?) to US-based Lithia, then change its listing into the standalone Pinewood software business. That deal would give shareholders a 16p dividend, and a residual holding in a small software company (which many shareholders may not want).
Probably time for management to capitulate.
The shareholder vote on the Lithia deal has to go ahead, as it’s been signed. So the question arises, what would the costs be to terminate the deal with Lithia? Let’s hope the lawyers drew up the contract well to allow PDG to extricate itself without heavy penalties.
Shares have almost doubled in recent weeks, so well done to people who had the sense to hold, I’m still kicking myself for selling just before the approaches were announced. Can’t win ‘em all, so never mind! For remaining holders, it must be tempting to bank some profits in the open market now, as there’s no guarantee the Hedin proposal will go ahead, they haven’t done any due diligence yet. Also, one of the Sunday papers reported that there’s a large contractual dispute with a Far Eastern company at PDG’s software division, which could muddy the water, and be expensive if the case goes against PDG, or could scupper any deal in the meantime, who knows?
Victoria (LON:VCP)
Down 12% to 486p (£557m) - FT article re audit report - Paul - AMBER/RED
A friend flagged up an article in the FT today, which spotted that the recent audit report is qualified, for this rapidly expanding (through lots of acquisitions) floor-coverings group. It’s complicated, and seems to only relate to some kind of shenanigans at a small acquisition. Although VCP management apparently restricted the scope of the audit over this issue, which is not a good look. Therefore I think investors & potential investors here need to carefully scrutinise the audit report in the 2023 Annual Report here.
The FT article seems quite scathing, and it does raise some important questions. Although I think once the initial shock has worn off, it will probably be quite easy for the company to bat away these concerns, no doubt saying that they relate to a tiny, immaterial subsidiary only.
I’ve got mixed feelings about Victoria. I recall a very good meeting with the Chairman a few years ago, where he very convincingly explained his strategy of picking up sleepy, over-capitalised European floor-coverings companies, then applying proper discipline to their processes and working capital, thus freeing up a large part of the acquisition price from the target’s own resources. Clever stuff, no doubt about that.
However, looking at its most recent accounts, what I see is a seriously over-stretched balance sheet, with far too much debt (although a lot of it is secure bonds), heavily negative NTAV, and mind-boggling adjustments that make it impossible for me to deduce whether this thing is highly profitable (adjusted numbers), or loss-making (statutory numbers).
Paul’s opinion - I don’t understand the accounts, they’re too complicated and over-adjusted. But I can see a weak balance sheet when I see one.
Overall then, I think it’s too risky and opaque for me to consider investing in, hence my overall AMBER/RED opinion - just best avoided I think.
The gyrations in share price today have been a nice opportunity for traders, with it spiking down as low as 410p, with a strong rebound currently underway (back up to 505p, down 8% on the day) as I write this (at 11:25).
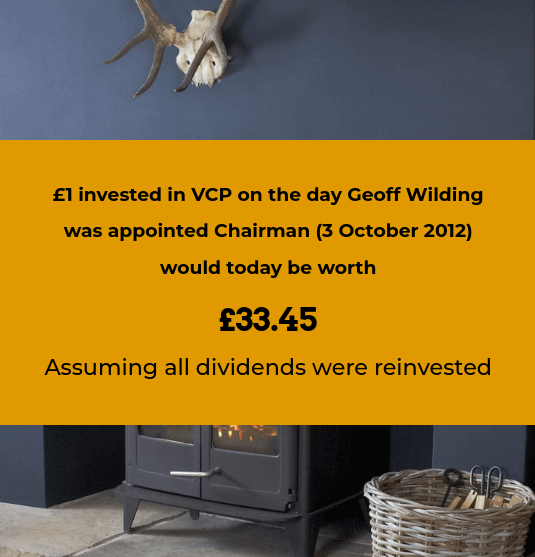
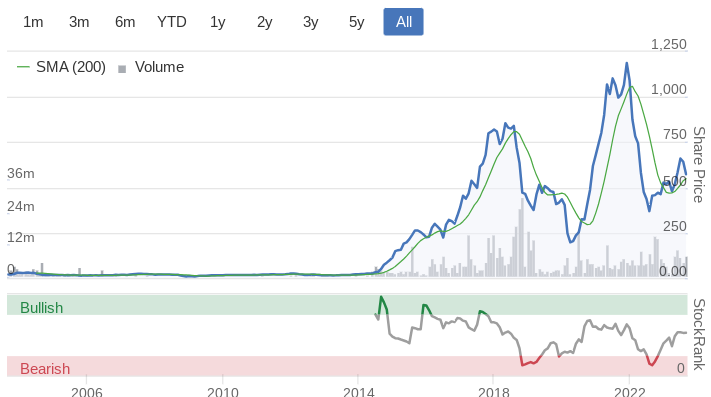
Opaque accounts, and sometimes dangerous levels of gearing, have been a recipe for a wild rollercoaster ride in share price in recent years. Although Geoff Wilding can still point to this share having been a major multibagger since he got involved. Indeed what I call the "Geoff-ometer" on VCP's investor relations website (below), makes sure we don't lose sight of who created the shareholder value here!
Wilmington (LON:WIL)
Unch 311p (£273m) - Results FY 6/2023 - Paul - GREEN
Wilmington plc, (LSE: WIL, 'Wilmington' or 'the Group') the provider of data, information, education and training services in the global Governance, Risk and Compliance (GRC) markets, today announces its results for the year ended 30 June 2023.
I’m really impressed with the results from this group, so it’s an easy GREEN conclusion.
Here are my notes of the main points for FY 6/2023 -
Revenue up 9% (continuing operations) to £122.1m
Adj PBT £24.1m (up 30%) - note the impressive 20% PBT margin.
“Efficiency of digital-first model” is helping grow margins, very nice.
Regulation, risk, compliance, these all strike me as growth areas to be focusing on, so I like the business model here, and imagine there’s open-ended growth potential internationally (it already sells into 120 countries).
Adj EPS 21.3p (up 27%) is in line with broker forecasts.
PER of 14.6x looks reasonable to me, for a nice quality, growing business that’s good value actually I think.
Total dividends 10.0p (up 22%), giving a 3.2% yield. However note that I think the dividend paying capacity is a lot higher, so there’s scope to grow divis considerably.
Net cash has more than doubled, to £42.2m, and the un-needed bank facility was cancelled in August 2023, due to the strong cash position.
Adjustments are small, with statutory PBT of £24.0m almost identical to adj PBT of £24.1m.
Current trading - in line with expectations. Note that FY 6/2024 forecasts are set quite low, with minimal growth, so I think it’s set up to produce likely earnings beats.
Balance sheet - NAV £80.6m, less intangibles of £66.3m, gives £14.3m NTAV - not very much, but it’s an asset-light business model, with cash paid up-front by customers, hence why it’s sitting on a £42.2m cash pile (£33.6m of which has come from up-front subscriptions and deferred income).
Cashflow statement - very impressive, this is a strongly cash generative business. As mentioned above, it could clearly pay much larger divis if it wished. I imagine management is likely to keep using cashflow for more bolt-on acquisitions, self-funded.
Paul’s opinion - highly impressive numbers, this ticks all my boxes as a GARP share (growth at reasonable price). An enthusiastic GREEN from me.
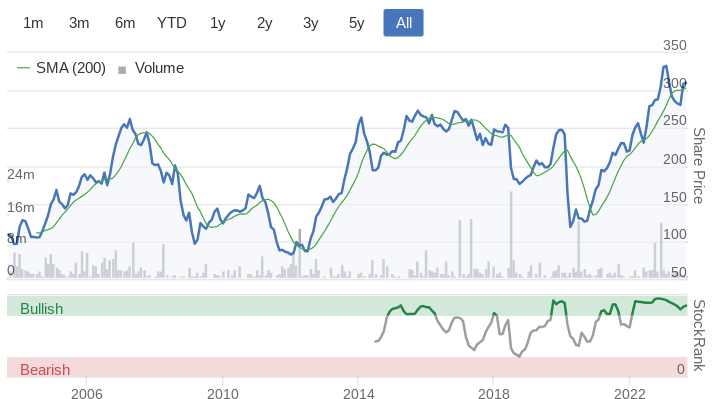
I also think this could be set up nicely to be a bid target, so a potential +30% profit to be had here, if a private equity bidder comes along - this is the sort of quality, high margin, structural growth type of business that is attracting bids at the moment.
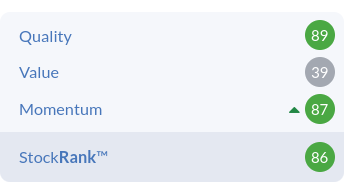
High StockRank too, puts the cherry on top!
Graham’s Section:
Devolver Digital (LON:DEVO)
Share price: 24.4p (unchanged)
Market cap: £108m
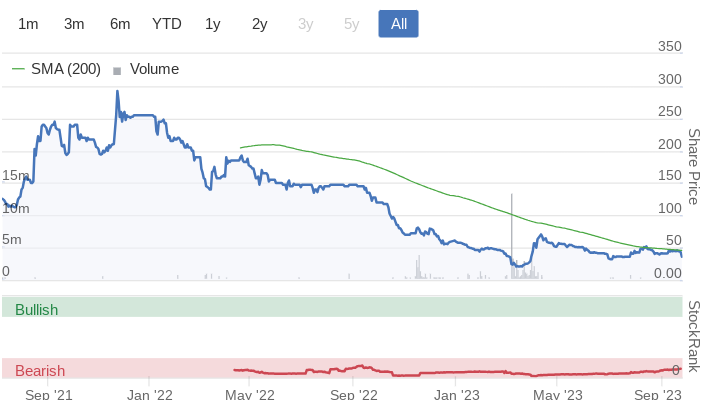
This is a video game IPO of 2021 vintage that has gone off:

However, in the short-term, the stock has bounced by a remarkable 74% since we looked at it in August.
I took a neutral stance then, as the majority of their market cap was covered in cash at the time (thanks to $65m/£50.6m of cash on the balance sheet).
Let’s take a look at today's interim results.
Highlights:
Revenues were $43.9m, down 17%. It’s rare that a company is so reluctant to share its absolute revenue figure - you have to scroll down through lots of other commentary and information before finding this!
Statutory net loss $10.1m (last year: $16.6m loss).
As previously announced, “high potential titles have been delayed to 2024 to ensure that they have the time, effort and support to succeed”.
The Texas-based company also “declined subscription deal proposals that undervalued the titles' value and revenue opportunities in 2023 and 2024, resulting in lower subscription revenues.”
Let’s skip ahead to the outlook statement and see if there is anything new:

This is a reiteration of guidance. Zeus (who floated the company at 157p less than two years ago) have left their forecasts unchanged, i.e. adjusted EBITDA of breakeven in the current year, rising to $8m in 2024.
Chairman’s comment excerpt:
"The first half of 2023 was a reset for Devolver, with delays to new releases as we prioritise the quality and long-term potential of major titles scheduled for the second half of 2023 and 2024. Devolver's DNA is to commit relatively low spend on high quality titles that stand the test of time. We look forward to returning to our normal cadence of releases in the rest of 2023 and 2024 with big titles to come such as Wizard With A Gun and The Talos Principle 2, as well as The Plucky Squire and Baby Steps.
Trailers for some of Devolver’s future games can be viewed here and here, for example - I must admit they look very nice!
Cost management - there is “a group-wide exercise to reduce overall expenses”, including rents, professional fees, and admin. They are also going to seek co-funding for publishing larger titles in future.
Graham’s view
The cash flow statement shows $15m flowing out of the company in H1, although hopefully the $7m spent on buying back shares (to fund staff bonuses) is a one-off event.
If we treat that as a non-recurring event, then the cash flow performance is not too concerning - again, considering the company’s very large cash reserves.
The games are quirky and fun, but they are indie games, not flagship titles. Personally, I find the appeal of indie games difficult to understand: if you have a modern gaming console, why wouldn’t you want to play games that push the technology to the limit with the most advanced graphics and gameplay possible?
That said, there is clearly a large market for indie games. The trailer for Devolver’s delayed title Wizard with a Gun has amassed 1.2 million views, for example. There is clearly a good deal of excitement around it, but also frustration that the game has been delayed for so long.
I’m remaining neutral on this share:
The June cash balance still covers nearly half of the market cap.
Financial performance should improve with a much busier release schedule coming up than the company had in H1.
Against that, the track record in terms of profitability is patchy and the company doesn’t have much of a financial history to hang your hat on. I have some doubts when it comes to investing in indie video games and there is probably no one who can estimate with confidence what this company’s financial performance might look like a few years from now. So there isn’t any other option for me but a neutral stance.
Saietta (LON:SED)
Share price: 35p (-18%)
Market cap: £36m
This “electric vehicle drivetrain ("eDrive") specialist” has given a full-year trading update ahead of its AGM tomorrow.
It still doesn’t have full-year results for FY March 2023 (!) and it is remarkable that its AGM will go ahead without an annual report for the prior year.
The Company is concluding the preparation of the annual report and accounts for the 12 months ended 31 March 2023 which have been delayed to allow time to conduct the impact assessment for impairment of intangible assets arising from the discontinuance of Retromotion activities, the revised contractual arrangements with Consolidated Metco Inc ("ConMet") and the suspension of marine product commercialisation. The annual report and accounts will therefore be released after the AGM with a target date of 29 September.
Remember that there is a six-month rule for AIM-listed companies to publish their annual results, and so Saietta is set to run right up against this deadline. If they miss that deadline, things could get messy.
We haven’t covered this one since Paul looked at it in April. Saietta’s CEO resigned shortly afterwards; a new CEO will join in October.
Here are the unaudited results for FY March 2023:
Revenue +40% to £6m
Adjusted EBITDA loss £9.9m, including losses from discontinued activity of £6.4m.
Pre-tax loss £23.8m including all writedowns and discontinued activities.
You probably don’t need me to tell you that this is about as bad as it gets.
And now for the cash position:
Cash as at 31 March 2023 period end of £7.3m (2022: £18.4m) and at end of August 2023 of £1.2m which, combined with additional sums receivable from key customers and JV partners, the Board is confident that this provides the Company with sufficient funding to meet its current requirements for its focused AFT eDrive production plan.
This does not sound believable to me, although the company insists that it has restructured and cut its operating costs significantly. Does this mean that £1.2m is enough? Personally, I would be very surprised.
The company’s broker estimates that it will have a net debt position of £5m by the end of the current financial year (FY March 2024), and £10m by the end of FY March 2025. The broker also significantly downgrades EBITDA expectations for the next two years.
Outlook
It is now working on one product category only::
Led by immediate customer requirements, Saietta is undergoing a transformational shift from a multi-segment product development company to a focused eDrive manufacturing business. The Board expects to be able to announce production contracts and specific developments in this regard over the coming weeks.
Chairman comment:
Saietta has reached the point of inflection as we expect to go into series production at our manufacturing plants in Sunderland, UK and at our all-new facility in Delhi, India. We are focused very heavily on our core target market of lightweight electric vehicles (LEVs) which offers the biggest, nearest and most certain commercial opportunities…
Graham’s view
I have to put this in the “bargepole” category, for a number of reasons:
Extremely large losses, with the company still a long way from breakeven.
Balance sheet weakness: very little cash left and a very strong risk of dilution (which actually would not be a bad outcome - it could be worse).
Late results: shares are suspended if companies can’t get their results out within six months. Not only is it very inconvenient for shareholders to have to wait so long for audited results, but it also suggests that there are more problems inside the company, if it can’t get its numbers audited in a reasonable timeframe.
Two thumbs down from me; I would avoid these shares with great enthusiasm.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Couldn't help notice the roughly 90% rise in Gear4music (HOLDINGS) (LON:G4M) even though no significant developments. Just shows how illiquid small caps can really surge once a fee buyers comes in.
Yes, I've also been taken aback by the strength of rebounds in one or two stocks. As you say, Gear4music (HOLDINGS) (LON:G4M) stands out - we knew it was cheap, but the last trading update was nothing special, so I didn't take much notice of it, but the shares have been on a terrific rebound of late. CockneyRebel spotted a large trade last night, so it looks like about 10% of the company has changed hands.
My theory is that there's no particular logic to which shares are rebounding, and by how much. It just depends on whether there are overhangs in the shares or not. There must be lots of small cap funds trying to exit positions, but stuck in them. So it's almost random at the moment.
Overall, it's feeling increasingly like the start of a new bull market in small caps, in my view. These things take time, but I'm very bullish overall that we could be entering a very lucrative time for small caps, as the wall of money that's currently sitting on the sidelines earning interest, gradually gets tempted back into the market by strong gains.
‘Sin stocks’ under pressure today I see after Entain (LON:ENT) Profit Warning this morning and tobacco stocks British American Tobacco (LON:BATS) & Imperial Brands (LON:IMB) on possible stricter future legislation
While none of these are small caps there could be a read across to others in their sectors
Entain (LON:ENT) wasn’t even a profit warning! They maintained profit guidance but did slip slightly vs revenue. Bizarre reaction - clearly was also known as stock had slipped 80p in 2 days beforehand so a net 20% down on an in-line profit guidance. didn’t justify that. I reckon in 1-2 years the BetMGM subsid will be worth the current market cap. They might be better working out a way of divesting that entity to create value. Possibly agree a separate US and Canada listing for BetMGM on an in specie basis for shareholders though that would require MGM to also play ball.
CEO turned down bids at 1800p and 2400p on the basis they could treble earnings when the share price was 1500p!
Right now she is looking like she has destroyed rather than created value with the stock trading at just 40% of the last bid! Suspect her job is looking increasingly tenuous….. she has a lot of repair work
Article close to Paul and Graham's hearts in last weekend's FT Money section., proposing investors are given access to stock research.
A review by Rachel Kent proposes "every limited company should be guaranteed research coverage with reports available to investors via a central platform . . ."
And the only company to effectively offer this to date as far as possible has been Research Tree who have plumbed in to almost all analysts and offered PIs a route to most research.
The government should ensure they listen to them.
Hargreaves Services / HS2
Wonder if some of the imfrastructure beneficiaries of HS2 are going to come under pressure as HS2 seems to be getting derailed even before a track is laid
Always was a ridiculous load of hot air and political will gone mad .
Re Hargreaves Services (LON:HSP) and HS2 I recently wondered that also and found the following..
Check out the recent Investor Meet Update (9th Aug 2023), where they confirm the position. The second question in the Q&A section was specifically about this.....essentially they don't think the section they are working on will be effected (Buckinghamshire), they say nothing they have in plan for next 2yrs will be impacted and they haven't included anything north of Birmingham in their forecasts.
Am no expert on HS2, but hopefully Hargreaves Services (LON:HSP) will not be adversely impacted by any possible changes in the pipes.
Hope this helps.
Andy.
Has the new CFO - Edward Spies - joined Spectra Systems (LON:SPSY) yet? Results don't mention his name.
If there are any skeletons it won't be in these results then, as Nabil is now fully controlling all the strings in finance.
Results are good today. WH Ireland broker note was OK, nothing interesting new - and they take their usual stance of not upgrading EPS for the FY, despite dropping many hints that it was very likely / foregone conclusion.
I like the dividend and the stable high margin revenues; on the other hand the client concentration is high, revenues might be a bit lumpy, and the diversification of revenues very slow, and too much control by one person introduces governance and fraud risk.
So hence why despite holding since Mar21, I've never had the conviction to up my stake past a c5% of my portfolio. On the other hand, over 2.5 years have had a nice 15%+ dividend return and paper capital gains of around +5%, so can't really complain.
I think with today's good HY results, this should really be trading at closer to 200p, but it looks like other investors aren't convinced, and price hasn't really moved today. Looking at the trades, plenty of buys near the ask spread, but it looks like there's some big sellers looking to offload into the liquidity today too.
Will be analysing fully in the coming weeks, which will probably appear as a comment on my latest Boon Fund article or in the next one.
(I hold in the Boon Fund)
A quick note, I will read more later.
Does anyone else hold Imperial Brands (LON:IMB) there seems to be no news today, dividend is paid on Friday so it has not gone ex-today, just wondering if there is anything obvious that I have missed causing the 5% fall today?
Thanks
Tommy
There was talk over the weekend about the government bringing in a rolling minimum age for smoking. It would mean younger people never being old enough to buy cigarettes. Maybe because of that.
Thank you, I also hold British American Tobacco (LON:BATS) which was only down 2% and is going ex-divi on 28 Sep 2023, so without announcements on either, and a total lack of reading news this weekend probably explains it. Thanks Tommy
well, just makes their share-buybacks even more effective!
(they have announced & begun quite the buy-back program)
Judges Scientific (LON:JDG) H123 results presentation given last week here video & podcast. A strong H2 expected due to the timing of the next Geotek coring expedition. Strong H1 order intake augur well for H2. In line with expectations for the full year. Also forSDI (LON:SDI) holders worth listening for the read across.
Pendragon (LON:PDG) - no holding
Being sued for £260m.
"Legal case has been rumbling on since last summer but was not announced to Stock Market"
https://cardealermagazine.co.u...
That article is from January 9, 2023!! Pendragon (LON:PDG)
It might be cold news but apparently still ongoing according to the Telegraph
ByMark Hollingsworth24 September 2023 • 5:37pm
Car dealer Pendragon is battling to have a £260m software fraud claim against it thrown out of the High Court as it attempts to secure the sale of its car dealerships.
A Pendragon subsidiary has been accused of fraud and breach of contract by a marketing company for allegedly reselling its new software directly to dealerships throughout Asia and the Pacific, according to court documents.
The company is being sued for failing to supply state-of-the-art customer software to Pinewood AP Ltd, a specialist marketing company, despite an agreement for them to market the new product in Asia, the Telegraph can reveal.
Pendragon responded by trying to have Pinewood AP’s claim struck out.
During a recent court hearing, Pinewood AP sought disclosure from the subsidiary regarding whether there is evidence of “fraud” under the reseller agreements.
A ruling on Pendragon’s application is imminent.
The lawsuit comes at a turbulent time for the troubled car dealership.
Last week, Pendragon agreed to sell its UK motor division to the US group Lithia for £280 million.
Two days later its largest shareholder, Hedin, attempted to derail the deal by launching a takeover bid, but this was rejected.
Alphawave IP (LON:AWE)
Interims today contain the following:
"During the second quarter of 2023, the Group's fixed charges coverage ratio (FCCR) was below the minimum allowed ratio of 1.25x, which represented a breach of the covenant. Long-term waiver obtained from lenders covering the period to 30 June 2024"
So why on earth was this not mentioned in the trading & business update on July 20th? If you were cynical you might speculate they didn't have the waiver in place until later in Sept....
And is this related to the CFO stepping down in May, or was that for the share suspension, not to mention the typos all through the prelims that had to be corrected?
When you are trying to regain the confidence of the market after a short raid this really doesn't help.....
I have read and re-read the announcement today for ,Alphawave IP (LON:AWE) , in which I have a small holding. Even as an accountant I am struggling to figure out what is going on in cash (a key piece of information for me). The stock has taken a beating today even though encouraging performance is anticipated and the forecast for the year is held.
I would love to know what the receivables level is and some reconciliation of the massive number changes from year to year seems to be warranted. I am not surprised that the market does not know what to value this at
Well, they are still pouring cash into Wisewave, so look at the JVs for starters.
Now, who else was it that liked JVs? Oh yes, hello Iqe (LON:IQE) !
But for anyone who is interested in Alphawave this article is a useful refresher:
https://www.fabricatedknowledge.com/p/ride-the-wave-alphawave
I have no exposure and haved mixed emotions on this one - the technological opportunity is intriguing but the company appears at best to be careless, and it rarely ends well when you find yourself having to assume the best of someone......
You're potentially right that it was not resolved by 20th, although I would think it's material news that should be provided to shareholders. It is not uncommon for lenders to reserve their rights against a breach and consider their options before deciding how to address the situation (waive / amend / call in.) However, a good company will notify a lender in advance and work proactively in presenting a solution, so still reflects badly on mgmt.
Alphawave IP (LON:AWE)
This company has a history of issues like this - not great if they continually fail to meet basic levels of communication . One might accept it for short period after listing but this is £1 bill market cap company - items like this can only reflect bad on the head honchos for not avoiding the issues or having the decency to flag up in timely fashion.
As said by others clearly the market as a whole doesnt really quite believe the "story" being put forward by this company.
Just seen this soundbite, so can probably assume the opposite will happen.
PMIs (nicked from Longview economics)
France.
Germany
UK
US
Thanks for covering Devolver Digital (LON:DEVO) Graham. Regarding the appeal of indie games, there are a few reasons there's a space in the market for them:
My chief concern with Devo is their CEO and CFO have very limited games industry experience. Douglas Morin (CEO) worked for 24 years in global equity markets and Daniel Widdicombe (CFO) similar. That, coupled with their incredibly poor track record since they joined (2020), has kept me well away.
Would still be keen to hear your thoughts on Team17 (LON:TM17). They're investing for the future and have seen their costs jump up thanks to timing of marketing spend, bigger headcount and general inflation. This has seen profits squeezed and a drop in the share price to 2019 levels (albeit higher share count) which could provide a good entry point should new titles perform and they keep a lid on costs.
Interesting article in the FT Alphaville section this am on Victoria (LON:VCP) which I believe Paul is going to look at.
The incumbent auditor has said that the Company has prevented looking further into some questions arising on an audit sampling of one of it subsidiaries by limiting the scope of the audit, despite a request by the auditor.
The reason is apparently that Victoria (LON:VCP) have appointed another professional adviser to look into it having been alerted to the issue, and they are saying that the issues arising aren't material to the audit. There is a statement by the auditor in the now published Group accounts.
The details of the issue with the acquired subsidiary appear to be that payments were still being made into a non company account that related to Company debts after the business was acquired. Some of these were in cash apparently and over the threshold that need compliance with Money Laundering Regs, but were not notified. There may be a fine associated with any finding of non-compliance.
The business has retained a sum of deferred consideration to the sellers of the business in lieu of the matters being investigated.
Yes, and it came to light from a random small sample.
A 30 second search on google 'Victoria (LON:VCP) vcp audit issues' threw up this short position
Victoria Plc ($VCP.LN): Mites under the Rug | Iceberg Research (iceberg-research.com)
suggesting some irregularities, involving 2 specific acquisitions
Oh and 'Where are the shareholder yachts?'
Yes, interesting situation at Victoria (LON:VCP) . I did hold briefly, but luckily escaped at break-even. I purchased due to the apparent Buffett / Munger style, until the penny dropped that this was possibly a clever "cover" for Wilding's antics. Its a perfect story to hide behind. Wilding is clearly an impressive deal maker that's for sure - I live near Kidderminster and you can see the success of Alliance Flooring. They have just taken a huge space in Worcester to replace the Kidderminster head-office and distribution facility. I remain sceptical that this will all end in tears though - as Paul mentions, the balance sheet is shocking and there are very heavily adjusted numbers due to the long stream of acquisitions. To be fair, the business does, apparently, generate very strong operating cash flows.
The yacht stories have been around for a while and the fraud risk is very high. I seem to remember that Hanover was the company that short-sellers were alleging fraud on some time ago. The fact that management limited the auditors scope is a big red flag - did they have something to hide?
What was also another big red flag was that the very capable FD resigned for a role at Eurocell a year back. Maybe he became uncomfortable with what was going on!
Something didn't feel right to me and still doesn't. Now the auditors have concluded the same and it looks like they have been very slow on coming forward on the problems. I would expect GT to now resign the audit role - good luck to them in finding new auditors!!
One of the companies mentioned by short-seller Iceberg - Hanover Flooring - is the subject of the Victoria (LON:VCP) FT article re GT's qualified opinion, it would seem.
Another 0 in the making.
I was scared off Spectra Systems (LON:SPSY) by the sudden loss of the FD without explanation in the recent past. Does anyone have any insights into the reasoning for the change and any views on the new FD. In the past I remember a couple of people on here also selling up due to the lack of a properly constituted AGM and I sold out at the same time but considering getting back on board.
No specific insight I am afraid but I do remember at the time there was speculation that part of the reason may have been not earning any interest on the cash given the new environment where that is possible. Also, at least one person queried if the cash was genuine given no interest. I am a holder so will be checking that for H1 when I get the opportunity.
Are there any broker notes on Spaceandpeople (LON:SAL) which reported its interims today? The SP dropped 12% on tiny volume and the outlook statement was unnecessarily vague (as Mr C) pointed out). Nevertheless SAL looks to me to have decent prospects in Germany, Austria and with its recent extension with UK rail locations. I hold.
FREng, there you go. Don't follow but looks unchanged to me
Yes Zeus have released a report that you can read for free. Profit estimated are unchanged but they are estimating an increase for year end cash of £1m, up from £500k.
Thanks Wolf and GMtrader. It seems to me that the market reaction is unwarranted.
Yes, I have held 3i (LON:III) for 15 years or so; virtually all its out-performance has been from Action which has been phenomenal. Definitely a lesson for private equity in running your winners!
3i and Action
Clearly 3i does not follow the well rehearsed saying " do not have more than 10% of your porto in a single stock". It has served it well though!
Thanks Paul for your commentary on Pendragon (LON:PDG) . I only bought them at the start of September (lucky me) but spent some of the weekend thinking about it. The upside is probably 2-3p maximum now whereas I am concerned the downside could be greater so this morning I sold out. Happy with my 50% return and moved it straight into Oxford Metrics (LON:OMG) which I believe has some big upside especially when the cash is deployed into something new.
Will keep hold of all my Vertu Motors (LON:VTU) which I've happily held for three years now (150% up so far.) I wish all my stocks were like these .
I would also add my holding in Pendragon (LON:PDG) was partly your response a few months ago about holding many companies in this sector which got me thinking. Glad I rethought this one
According to Telegraph today ,Lawsuit ready for Pendragon (LON:PDG) for fraud in software business. Time to sell i believe.
Writers strike in US looks to be coming to an end. Maybe see a bounce in a few companies this morning
Hopefully, I have a reasonable holding in Facilities by ADF (LON:ADF) and rightly or wrongly have hung onto a much smaller holding in Videndum (LON:VID)
Hi Jonno, I was looking to buy Facilities by ADF (LON:ADF) myself but got my timing totally wrong on it so never pulled the trigger. Should have bought on the dip in July like a couple of others here. If broker forecast are anywhere close it should do well.
Cheers Wolf
I am still underwater having bought shortly after listing and added on the Location One acquisition, but it appears a well run company, the balance sheet is sound and it is the dominant player in a very niche field (in he UK).
Other positives from my perspective are that the listing price of 50p was reasonable and the reasons for listing were creditable. Also the founders continue to retain sizeable holdings. The company has continued to pay a dividend despite the headwind of the strikes.
I live very close to a major film studios that is expanding significantly and know how busy they are.
At 50p or thereabouts the shares are very cheap, assuming a return to normal operations, despite the capex on the new trailers.
Hello Jonno and others on Facilities by ADF (LON:ADF) but the situation is not so simple.
There are still 1000,000 actors out on strike and they don't have a deal.
Moreover the writers will have to vote on the deal when the legal beavers have been through the small print, though their negotiators seem to be trumpeting their achievements.
So too much excitement maybe a bit premature ?
Not signed and sealed as you say, but the strikes will end at some point, writers and actors.
Both sides need each other. The studios need the writers/actors and vice versa. For me it is just a matter of being patient
I do meant to top up Facilities by ADF (LON:ADF) when they recently went down to around 40p. I did load up with some more Videndum (LON:VID) despite concerns about the potential for financial stress due to debt levels
Zoo Digital (LON:ZOO) the way I'm playing this story. It's only rallied a bit so far.
Saietta (LON:SED) placing looking all but certain here. Cash reduced from £7.3m in March to £1.2 August.
Marine division, which was supposed to proved cashflow originally, is suspended.
They dangle the carrot of production contracts soon but I'd imagine any spike in price would be used to raise funds.
It’s a tough gig being an OEM supplier. They’re typically involved relatively early in the design phase with the OEM, often months if not years before production and revenue is generated. The design, refinement and production capacity build out makes the business model both capex and working capital intensive.
And at all times they're following a timeline controlled by the whims of the OEM.
Given supplier OEMs also tend to retain the commercial risk of end user demand not materialising as expected, the business model is not for the faint hearted and probably best addressed by established, well capitalised businesses that can fall back on existing positive cash inflow from other up and running projects.
I think the Saietta (LON:SED) story shows how hard it is for new players to be successful!
Saietta (LON:SED) looking at broker forecasts seems £5m is needed but this is anticipated as debt rather than equity.
The ramp up in India is now critical for them.
It’s a shame they haven’t been able to make more of the marine division but in all honesty the two main electric alternatives to petrol outboard motors Torquedo and Epropulsion have done a fantastic job of establishing themselves as strong brands. Let’s hope that Saietta (LON:SED) are talking to both about licensing -or maybe even the incumbent petrol outboard manufacturers like Evinrude, Mercury etc who seem to have been left behind.
My morning smallcap tweet: You dread it here first!
Brighton Pier (LON:PIER) Saietta (LON:SED) Pelatro (LON:PTRO) Microsaic Systems (LON:MSYS) Invinity Energy Systems (LON:IES) Crimson Tide (LON:TIDE) Spaceandpeople (LON:SAL) Spectra Systems (LON:SPSY), Windar Photonics (LON:WPHO)
◄Brighton Pier (PIER)► H1-June rev down 6%. Adj pretax -£1m (+£700k). Warns FY op profit likely to be below expectations after weaker than expected summer trading. [SP=42.75 Cap=16m]
◄Saietta (SED)► guides FY-Mar rev up 40% (in line) and pretax -£23.8m accounting for all write downs and discontinued activities. Cash at hand only £1.2m end Aug but with sums receivable from key customers and JV partners, is enough to "meet its current requirements for its focused AFT eDrive production plan". Outlook - "expects to be able to announce production contracts and specific developments in this regard over the coming weeks".AR delayed to c.29 Sept due to "impact assessment for impairment of intangible assets arising from the discontinuance of Retromotion activities, the revised contractual arrangements with Consolidated Metco ("ConMet") and the suspension of marine product commercialisation". [SP=44 Cap=45m]
◄Pelatro (PTRO)► warns FY rev only c.$7m (a $1m miss) due to delays in deliveries to customers and in hardware procurement by customers. Expects adj pretax loss of c.$1m. [SP=0.75 Cap=1m]
◄Microsaic Systems (MSYS)► has cash c.£350k, enough to mid-November. Fundraise talks.Needs £1.5-2.0m min. Exec chmn scarpers "to enable him to devote more time to his other business commitments". Yeah, right. He is thanked. [SP=0.01 Cap=m]
◄Invinity Energy Systems (IES)► US plans to fund projects that will use 84 MWh of Invinity's next-generation product in six sites. Expects contact by end Dec. Delivery of the batteries by Invinity expected in 2025. No $$$. [SP=44.3 Cap=84m]
◄Crimson Tide (TIDE)► H1-June rev up 31%. Pretax -£471k (-£860k) in line with mgmt exp. Outlook - "Because of external market conditions, Beepro development and marketing was paused. In addition, there has been some natural churn of smaller historic contracts where businesses have been unable to grow [therefore] our focus will be on profitability, emphasising and prioritising customer success." [SP=2.3 Cap=14m]
◄SpaceandPeople (SAL)► H1-June rev 5%. Pretax loss £424k (£377k). Outlook vague. Agreement to supply new units into Centres operated by Multi Corporation in Germany. [SP=91.5 Cap=2m]
◄Spectra Systems (SPSY)► H1-June rev up 25%. Pretax $5.5m ($3.3m). Guides FY in line. [SP=162.35 Cap=75m]. I hold.
In line: WPHO
in addition to the contract wins, Invinity Energy Systems (LON:IES) also published their interim results today: http://newsfile.refinitiv.com/...
There will be a results presentation and interactive Q&A for all shareholders at 3pm (UK time) on Thursday 28 September 2023 on Investor Meet Company.
UP Global Sourcing Holdings (LON:UPGS) - UPGS today announced the opening of a new showroom in Paris, which will facilitate the expansion of its leading homeware brands not only into France but continental Europe overall. Furthermore, as demonstrated with Petra in Germany, stronger sales and an elevated business profile expands the scope to make growth-oriented acquisitions in the region.
We continue to place a fair value of 250p for UPGS’s shares, which in our view is reasonable given it implies 1.3x sales and 11x EV/EBITDA based on our FY2024 forecasts. Investors should also note that the company’s two most recent updates included better than expected outcomes on net debt and sales growth. Link to our new note with audio summary: HERE
UP Global Sourcing Holdings (LON:UPGS) opening of Paris showroom looks an interesting development as they push out through France and rest of Europe. Its interesting that the CEO of Action was cutting the ribbon given they have 2,300 stores across Europe and are the fastest growing retailer in Europe and probably the Western World!
UPGS and Action super market remind me of 3i which has done better than both of them!
As a sometime holder of 3i (LON:III) I'm well aware of Action's phenomenal growth - if UP Global Sourcing Holdings (LON:UPGS) can capture even a bit of this then should do very well indeed. Perhaps even a bid from 3i is not out of the question - one of 3i's key themes is discount consumer goods and they own a number of such companies in their portfolio, alongside their much bigger position in Action. UPGS might be a nice addition for them,