Small Cap Value Report (Mon 26 Feb 2024) - WIN, BEG, OCDO, COG, IES, ENSI, TSTL, IPF

Good morning from Paul & Graham!
The Week Ahead - just published (by Roland this week) - the excellent new macro/large cap editorial here on Stockopedia.
Mello Monday - starts at 17:00 today, with a talk I don't want to miss from Vin Murria at the start. Also React (LON:REAT) are on, which I think looks to have interesting potential, I was pleasantly surprised at some of the numbers when I last reviewed it recently. Although it has an ongoing challenge with lowly rated equity meaning it can't do any meaningful acquisitions without diluting away the benefit.
Housebuilders
Further investigation by CMA (competition & markets authority) - interesting news here, saying that the CMA has found areas of concern in its investigation into housebuilders -
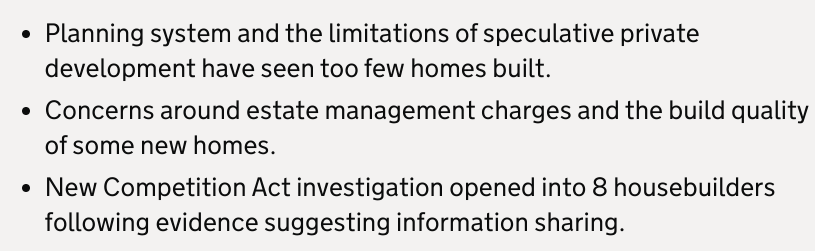
The third bullet point above is the one that concerns me, more detail saying -
The CMA has also today opened a new investigation into the suspected sharing of commercially sensitive information by housebuilders which could be influencing the build-out of sites and the prices of new homes. While this issue is not one of the main drivers of the problems we’ve highlighted in our report, it is important we tackle anti-competitive behaviour if we find it.
These are the companies suspected of sharing information -
The CMA has therefore launched an investigation under the Competition Act 1998 into - [reformatted by Paul into a list] -
Barratt,
Bellway,
Berkeley,
Bloor Homes,
Persimmon,
Redrow,
Taylor Wimpey, and
Vistry.
The CMA has not reached any conclusions at this stage as to whether or not competition law has been infringed.
The CMA’s report today is only short, and very interesting, so I recommend others to read it in full. All sounds like common sense to me (Paul).
Looking at the early morning prices today, some of the above companies have seen 1-3% share price falls so far (written at 08:26).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
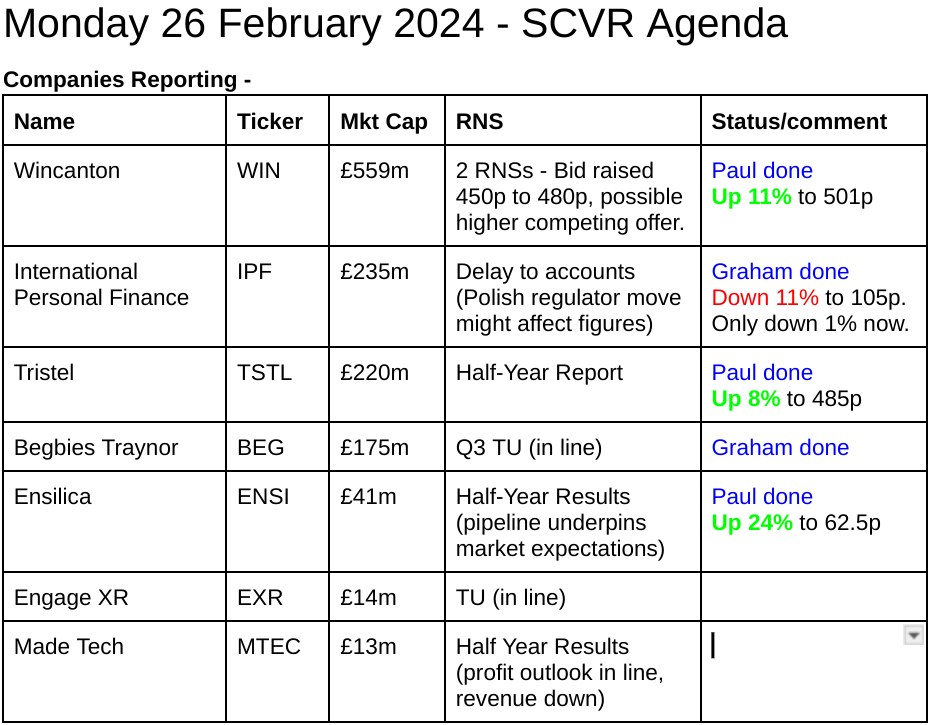
Other mid-morning movers (with news) -
Ocado (LON:OCDO) - down 5% to 499p (£4.2bn) - no RNSs, but the newswire here on Stockopedia often has useful news snippets, which today says that Peel Hunt has lowered its price target from 845p to 784p. Also I picked up news elsewhere that apparently Marks and Spencer (LON:MKS) has withheld payment for its joint operations, due to dissatisfaction with service. My view - Ocado has been a multiyear major under-performer, just losing money year after year. Apparently its robotic warehouses are a joy to behold, just a pity they don’t make any money!
Cambridge Cognition Holdings (LON:COG) - up 8% to 53p (£19m) - “Midas” share tip over the weekend in the Financial Mail. Interesting company, that we’ve followed for years, loads of stuff in the archive here. I’ve cooled a bit on the fundamentals, as it spent the cash pile on acquisitions, and losses are continuing. Note recent broker forecasts have trimmed expected losses. Might catch a wave of excitement about AI, big data, etc, so a possibly interesting trade maybe?
Invinity Energy Systems (LON:IES) - up 14% to 27p (£53m) - Strategic manufacturing deal & product validation - encouraging-sounding update from this battery developer , but nothing I can assess. We didn’t look at IES in 2023, as it’s a heavily loss-making jam tomorrow company, so not something we can value reliably on fundamentals. TU 18/12/2023 said 2023 revenue is up 500% to £21.6m. Reckons it should have enough cash into H2 2024, but doesn’t say how much cash it has now. I’ve looked at the numbers (H1 results & TU since), and I think it’s running low on cash, and will need another fundraise quite soon. Hence I’m keeping it on a RED view, but at least there are signs of life with rapidly rising revenues (although note in H1, it sold product at below cost!). Safest to wait until it's refinanced, in my opinion.
Summaries of main sections
Wincanton (LON:WIN) - 449p (pre-market) £559m - Raised final offer to 480p & Possible competing bid - Paul - PINK (takeover situation)
Exciting news that the existing bid from a French logistics group has been raised from 450p to 480p. A separate announcement says another potential bidder has indicated potential interest, but there are no details. Could we see a bidding war? Looks a possibility.
Begbies Traynor (LON:BEG) - up 2% to 111.53p (£177m) - Q3 Trading Update - Graham - AMBER
This insolvency practitioner (now diversified into a range of related professional services) reports an unchanged full-year outlook and a slightly larger debt facility, enabling continued growth by acquisition. Share price has been soft; could be worth studying for value.
EnSilica (LON:ENSI) - up 26% to 63.5p (£52m) - H1 Results - Paul - AMBER/RED
It's trading around operating profit breakeven, but expensive debt tips this chip designer into losses. Balance sheet is wobbly, and going concern statement indicates it needs more funding. Massive claimed pipeline is the exciting bit! More a punt than an investment.
International Personal Finance (LON:IPF) - down 1% to 117p (£262m) - Delay of Results - Graham - GREEN
Some worrying news for investors to chew on this morning as a letter from the Polish financial regulator forces a delay to the full-year results. Hopefully it will take just a week for IPF to digest the contents of this letter. I continue to view this as risky but attractively cheap.
Tristel (LON:TSTL) - up 7% to 480p (£228m) - H1 Results - Paul - AMBER/GREEN
Nice H1 results, and I can't see anything wrong in the numbers (apart from grumbling about adjusting out share option costs, but many companies do that too). There seem very good reasons to expect growth to continue. The only question is valuation - it's up to you whether you're prepared to pay a hefty valuation for future growth. Overall I like the company a lot, but not so keen on the share price at this lofty valuation, but it may well be justified.
Paul’s Section:
Wincanton (LON:WIN)
449p (pre-market) £559m - Raised final offer to 480p & Possible competing bid - Paul - PINK (takeover situation)
Two announcements this morning, for this excellent logistics company (it was on my top 20 for 2023, so we like it here at the SCVR).
Raised offer - the 450p offer has been raised to 480p from French logistics group CMA CGM. This is excellent news for investors who hung on for the final payout. It’s so difficult to know what to do in takeover situations - sell in the market, or hold on for the full pay out and the possibility of a higher bid (but also the risk of the bid falling through).
The bidder says it’s now a final offer under Takeover Panel rules, but of course those rules allow them to increase their offer if a higher competing bid is received. So it’s not really a final offer!
Note that WIN’s board continues to unanimously recommend this bid.
“...received an approach from a potential competing bidder “
We’re not told who the company is, so can’t assess how credible this approach is.
WIN is providing due diligence information to the other party.
“No formal proposal” as yet, but I wonder if the new approach might have informally given an indication on price?
“This announcement has been made without the consent of the potential competing bidder.”
Paul’s opinion - exciting times for WIN shareholders! I can remember a bidding war for Lavendon some time ago, which proved lucrative for shareholders who sat tight, as it went backwards & forwards with higher bids. Hopefully WIN might do the same possibly? Worst case scenario, shareholders get 480p, as that deal sounds unlikely to fall through (unless WIN shareholders reject it, which can happen, as it did last year with a 74p failed bid for Tribal (LON:TRB) )
I imagine the share price might go to a small premium over 480p today, if the market thinks the new approach has credibility (writing this at 07:53).
EnSilica (LON:ENSI)
Up 26% to 63.5p (£52m) - H1 Results - Paul - AMBER/RED
EnSilica (AIM: ENSI), a leading chip maker of mixed-signal ASICs (Application Specific Integrated Circuits), is pleased to announce its unaudited results for the six months ended 30 November 2023 ("H1 FY24" or the "Period").
Strong new order momentum supports growing order book and new business pipeline.
This floated in May 2022. I’ve only looked at it once, here on 14/12/2023, useful for background, when it did a small placing. Shares have almost doubled since then, including a 26% rise today, so it’s worth another look in case there’s a multibagger in the making here!
Last time I concluded that cash outflows were a concern, but the massive claimed sales pipeline looked interesting.
H1 Results (6m to 30/11/2023) - key numbers -
Revenue up 11.5% to £9.6m
Loss before tax of £309k (LY H1: £(202)k loss)
Makes a tiny operating profit, but finance costs high at about £750k annualised, so there must be debt - not good at small companies that don’t make much profit.
Balance sheet - NAV £16.5m, less £15.2m intangible assets = NTAV £1.3m.
Receivables of £5.9m look too high, and note the separate £1.4m tax receivable - presumably for R&D tax credits.
Cash of £2.1m, less borrowings (“bank loans”) of £3.7m, so net debt of £(1.6)m, plus lease liabilities. Not ideal, I think it needs to do another fundraise to be comfortable.
Going concern note - this needs careful scrutiny. It says that some big receipts are overdue, and it’s trying to line up an additional £1m borrowing facility, and invoice discounting, to give it more headroom. I don’t like that, it shows there is significant risk here.
Note that it raised £1.56m in a 40p placing in Dec 2023, and those new shares come with warrants exercisable at 55p. So that could be headwind for the share price, as at 63.5p the price now makes those warrants in the money, so some holders might be tempted to exercise them and sell in the market. Be aware of the dilution risk at least, you can decide if it matters to you or not, as with everything we cover here.
I’d say another placing looks likely, and would be good to strengthen the balance sheet and lower risk.
We saw a debacle at a similar company Sondrel (Holdings) (LON:SND) where it also ran out of money, and remains on a knife edge financially. When are brokers & companies going to learn, that floating with overly optimistic forecasts, but inadequate finances, is such a bad strategy. Yet they do it over & over again, thus turning sensible investors against IPOs altogether because so many of them see crashing share prices.
Outlook - there’s loads of exciting-sounding upside potential in the commentary, too much for me to copy/paste it here. So it’s your decision whether this is jam tomorrow from a cash-strapped small company, or tremendously exciting upside! I don’t have a view on that, because I don’t know the company or sector well enough.
The current sales pipeline of opportunities and potential contracts stands at c.US$512 million following a review by management to focus on projects which meet our criteria, and this pipeline remains a strong endorsement of the quality of our business output and our growing reputation in the chip sector…
Encouraged by the improving broader trading environment, management is looking ahead to the remainder of H2 FY24 and beyond with confidence and is excited to explore potential new mandate opportunities to add to the sizeable contract wins already secured in the second half of the financial year.
Paul’s opinion - based on the historical figures, including today’s H1 results, I would value the fundamentals here at very little.
So the £52m valuation rests entirely on expectations for future growth and as yet elusive profits.
I don’t know the likely outcome, so I’m leaning towards amber. Although the obviously stretched finances and need for more capital means that I also have to flag elevated risk, so let’s stick with AMBER/RED, my existing view last time in Dec 2023.
Given all the tech excitement in the US, especially around NVIDIA (NSQ:NVDA) and Elon Musk, punters are sniffing around for anything in a vaguely similar sector that could be a future multibagger. So being a chip developer with an apparently huge pipeline, means I could see punters gathering around this share, which seems to be happening today. Hence the share price is probably now detached from fundamentals, so we can’t really add a lot of value (or predict what happens next) in these reports. Good luck whatever you decide!
Tristel (LON:TSTL)
Up 7% to 480p (£228m) - H1 Results - Paul - AMBER/GREEN
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products utilising proprietary chlorine dioxide technology, announces its interim results for the six months to 31 December 2023, exceeding internal growth targets by delivering 20% revenue growth and 44% growth in pre-tax profits. The Company also announces a doubling of its interim dividend payment.
The Company's core business is the sale to hospitals of its proprietary chlorine dioxide chemistry used for the decontamination of medical devices under the Tristel brand, and for the sporicidal disinfection of environmental surfaces under the Cache brand.
For background, I reviewed its H2 TU (trading update) here on 19/12/2023 which I described as brimming with positivity, and I came away with a moderately positive view (amber/green) despite the very high PER (which we always moan about here with TSTL shares!).
Then, TSTL shares wobbled 10% to 405p on 11/1/2024 when Director selling was announced. The CEO is retiring though. Interesting to note that the share price has since risen c.20% from that dip, so Director selling isn’t always necessarily negative - a topic we’ve discussed a lot here, with various opinions. Sometimes it’s bad, sometimes it isn’t, you just don’t know which it’s going to be!
Key H1 numbers -
Revenue up 20% to a record £20.9m (2022: £17.5m) - “exceeding internal growth targets”
Reported profit before tax up 44% to £3.4m (2022: £2.4m)
Adjusted* profit before tax up 34% to £4.1m (2022: £3.1m)
Reported EPS up 104% to 6.50p (2022: 3.19p) - note that this 104% jump in EPS is flattered by a low tax charge, so the 44% increase in PBT is a more reliable guide.
Adjusted* EPS of 8.68p up 87% (2022: 4.65p)
Are the adjustments reasonable? Not really, no. It’s all down to share options - although this is generally accepted treatment by analysts, I think some investors are more sceptical, after all share options are just staff bonuses, so why should we ignore that as a cost?
*Adjusted for share-based payments of £0.7m (2022: £0.7m)
Although I like that the share options have rewarded mainly staff, not Directors -
The share-based payment charge of £0.7m is derived from the Group's All-Staff share option scheme which is based upon periodic share option grants to staff members (£0.5m), and the Executive Management LTIP scheme (£0.2m).
It’s up to you whether you’re prepared to value this share on statutory or adjusted figures, but to be prudent I’m leaning towards the statutory figures as better reflecting reality.
Balance sheet is excellent, no issues there.
Regulatory approvals in UK & Europe - in a separate announcement today, this seems to expand the potential market for products which currently make up c.9% of TSTL global sales.
USA expansion - has only recently started, through a partner so I think it’s too early to judge, as the figures are obviously very small so far -
Parker's manufacturing processes have been validated by our quality team and production is now underway. The product has been through beta testing at a number of healthcare institutions in the United States, with very positive feedback. Parker Laboratories plans an extensive marketing and trade show programme throughout 2024 and is in the process of expanding its salesforce in order to capitalise on the potential that Tristel ULT represents. During the first ten weeks of activity our revenue and royalty income from North America totalled £46k. We are very encouraged by this positive start.
In the second half of the year, we will procure office premises and recruit a small number of United States based staff to support Parker's marketing and sales efforts and establish a local regulatory capability.
Broker update - thanks to Cavendish for an update note today. As mentioned last time, it seemed obvious that the existing forecasts are too modest, which Cavendish hinted at previously. It’s left forecasts unchanged again today, so given strong H1 performance, the next move in forecasts looks increasingly likely to be up.
I wonder if something nearer 15p might be on the cards for the full year? That would give a PER of 32x, a racy valuation, so holders must be factoring in the potential for considerably more earnings growth in the future. Given all the upbeat comments from the company, and growth in the US royalties, there seem good reasons to expect earnings to continue rising.
Paul’s opinion - same as before - the fundamentals here look great. It all boils down to whether you’re prepared to pay up-front for future growth, with a high (but probably justified) valuation.
So I’m happy sticking with AMBER/GREEN.
Graham’s Section:
Begbies Traynor (LON:BEG)
Share price: 111.53p (+2%) (at 8.06am)
Market cap: £177m
We have an in line with expectations trading update from this “professional services consultancy” many of us know as an insolvency practitioner.
Q3 trading update: the company is confident of delivering market expectations for FY April 2024, those expectations being revenue of £131.1 - 135.2m and adjusted PBT of £21.9 - 22.5m.
(Performance in the prior year: revenue of £121.8m, adjusted PBT £20.7m.)
Due to the highly acquisitive nature of Begbies, there are typically substantial adjustments made to profits. This includes the amortisation of intangibles and a bunch of costs which the company collectively refers to as “transaction costs”. I presume that there will be another substantial set of adjustments in the current year.
Last year: £20.7m of adjusted PBT converted to £6m of reported PBT.
The previous year: £17.8m of adjusted PBT converted to £4m of reported PBT.
New debt facility: the company’s existing debt facility with HSBC was due to mature in August 2025. It has therefore been replaced by a new HSBC facility:
£25m RCF (same as before)
An additional £10m accordion (up from £5m)
Matures Feb 2027, possibly extended up to Feb 2029.
The new facility’s costs are “broadly in line with the previous facility”, presumably on the basis of a floating interest rate. The effective interest rate on the facility last year was 6.7%, which doesn’t seem excessive.
I also note that Begbies had a small net cash position as of the most recent interim results. The main point of the HSBC facility is to enable further acquisitions, as Ric Traynor (Chairman) confirms today:
"We are pleased to have agreed a new debt facility with HSBC which, alongside the group's cash generation, provides us with the flexibility to complement our organic growth with selective acquisitions. This will enable us to both build on our decade long track record of growth and execute our strategy to extend our scale and range of services."
Graham’s view
I don’t think there’s much news here that will change minds on Begbies. The new HSBC facility only shows a larger accordion facility than last time, signalling perhaps slightly more intent when it comes to acquisitions. But otherwise it’s a case of as you were.
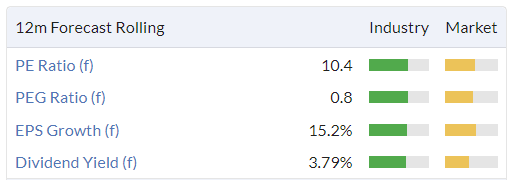
Applying a 25% tax rate to the lower bound of the adj. PBT forecast, the company trades on a current-year PER of less than 11x (£177m market cap divided by adjusted net income of £16.4m).
This is consistent with what the StockReport is telling us:
However, this does require trust (some might say faith) in the usefulness of the company’s adjustments.
I remain wary of what the company refers to as “transaction costs” and adjusts out of its expenses - Paul and I have discussed this before many times, e.g. I discussed it here.
Transaction costs include some very large numbers, e.g. they include something called “deemed remuneration” with a value of £12m in 2023 and £10m in 2022.
These are payments to the sellers of acquired business, where the sellers are obliged to continue working within Begbies for a period of time after the sale. These payments are required by the accounting rules to be treated as an expense, instead of getting the normal acquisition treatment.
Personally, I agree with this accounting rule! Although I can also see that from the point of view of Begbies, it might artificially depress profits. From the point of view of shareholders and potential investors, however, I think the rule does a good job of highlighting for us that this is a people business.
I do generally have a positive view of this company and I note that the stock has made little progress in recent years. Could it be getting into value territory again? There is a level where I would have to turn bullish on it, but I’m not sure we are quite there yet. Sticking with AMBER for now.
International Personal Finance (LON:IPF)
Share price: 117p (-1%)
Market cap: £262m
Some tricky news for IPF shareholders today; full-year results for 2023 are delayed due to:
“…the receipt by Provident Polska, the Group's Polish business, of a regulatory communication from Komisja Nadzoru Finansowego (KNF), the Polish Financial Supervision Authority. The letter details the KNF's views on how existing laws and regulations relating to non-interest fees should be interpreted by credit card issuers. The Group is considering the potential impact of the communication from the KNF on the performance of Provident Polska and whether this needs to be considered in finalising the Group's 2023 year-end results.”
The good news is that this is thought to be a “sector-wide communication”, i.e. IPF’s Polish subsidiary has not been singled out by the regulator.
Additionally, IPF reckons that it will only need about a week to study what it has received, after which it will be able to publish its results.
The bad news is that IPF needs to consider whether the Polish financial regulator might be making “a significant change to the existing approach”.
IPF has already done a huge amount of work in recent years trying to understand and navigate new Polish regulations on non-interest fees. As we discussed at the time of its Q3 update, lending in Poland by IPF is down 23%.
Modifying its business model and shifting away from home credit, IPF issued over 100,000 credit cards in Poland, to comply with the new regulatory landscape. Credit cards are now responsible for 25% of IPF’s loan book in Poland.
Unfortunately, today’s news is another reminder of the inherently unpredictable nature of regulatory risk. Even without any new laws or regulations, a new interpretation can result in business upheaval.
The IPF update does also provide some positive news:
The Group confirms that its year-end results reflect a stronger than expected trading performance in 2023 and this momentum has continued in early 2024.
Graham’s view
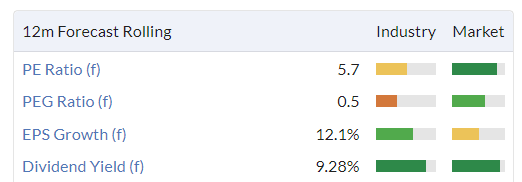
I’ve been positive on this one due to what I perceived as an extremely cheap valuation which I sensed could price in the risks. That cheap valuation remains available today, and includes a chunky yield:
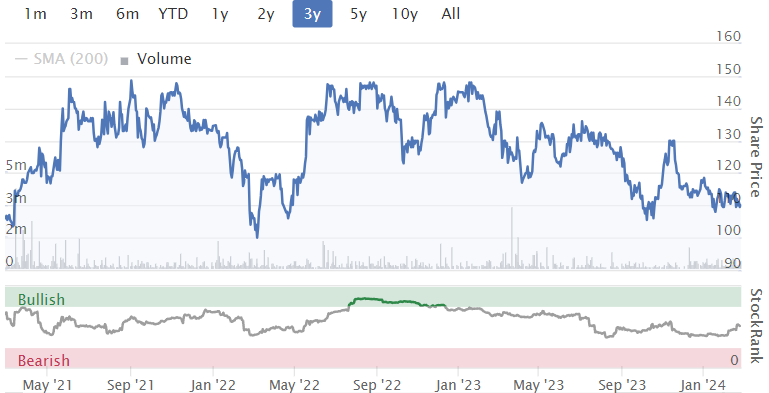
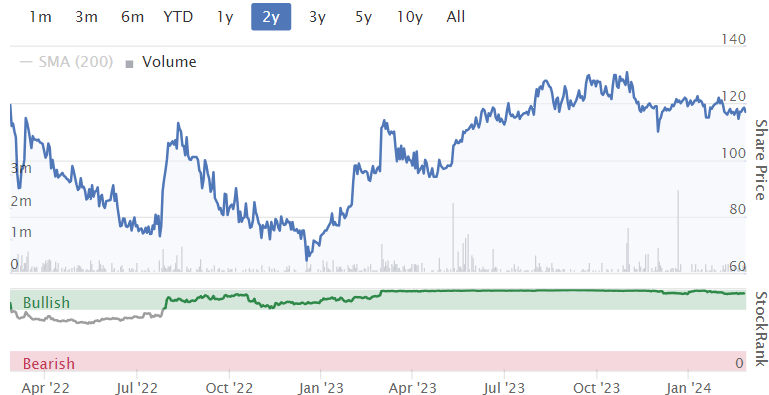
That valuation is despite a significant recovery in the share price over the past year:
Reminding ourselves of some balance sheet numbers, the report for June 2023 showed tangible net assets of c. £410m (the current market cap is a c. 36% discount to this).
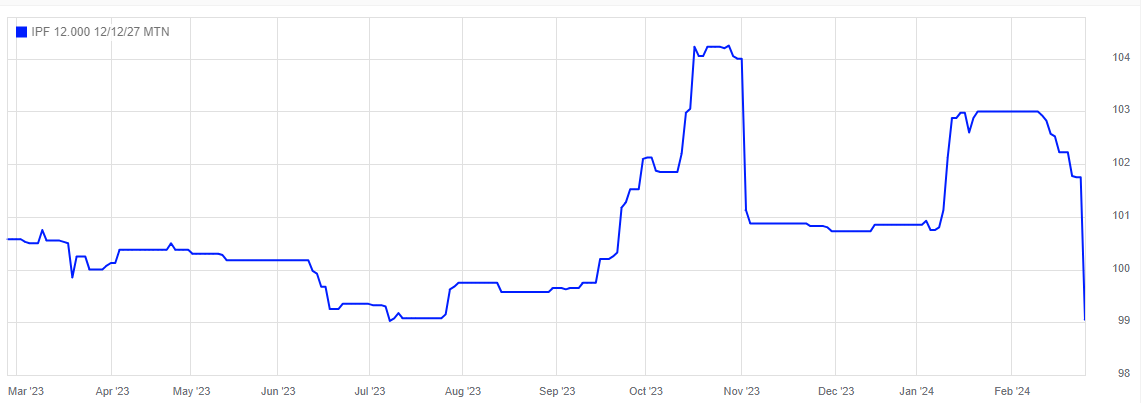
IPF’s 2027 retail bond (paying a 12% coupon) has taken a hit today, down a few percentage points, but still officially trades at around 99p in the pound:
Personally, I think this 12% bond would suit my own risk profile better than the equity here. But they both seem to offer good value, for those willing to take a bet on home credit businesses in Eastern Europe, Australia and Mexico.
According to the newswires, broker Peel Hunt have today placed their target price and rating “under review”, due to the material uncertainty caused by today’s announcement. I’ll stay positive, while acknowledging that this is perhaps not a stock for the faint of heart.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Shein, the china consumer outfit, is now considering a UK ipo - now that would be interesting!!
HOUSEBUILDERS What really concerns me is this whole "estate management" annual fee. That just seems like out-and-out rent-seeking behaviour. Welcome to the brave new world where you will own nothing and be happy.
Off topic but Tesla (NSQ:TSLA) has broken through $200 again, seems to have been a bit of an invisible barrier. I get your point Paul from the weekend podcast on the magnificent 7, also Megan's write up on the good, the bad and the ugly (TSLA being the ugly). I still have it as my biggest holding though, 50% compound annual growth target up to 2030, some years more, some a bit less but 50% average.
I think they will do it, FSD V12 is so close to being full self driving, I think they will crack it in the next couple of years, then go for approval bit by bit. Optimus is coming along leaps and bounds, the affordable Tesla next on the line for 2025, lots to look forward to.
I suppose ultimately it comes down to do you believe in a sustainable energy future. I do and think Tesla will be at the heart of it..
cue the bear case :)
Guybrush I cannot buy Arm Holdings (NSQ:ARM) through Hargreaves Lansdown so can I ask which Broker you used for your purchase?
Hi Portugall, I use Barclays Smart Investor.
As for ARM, please make sure to DYOR. I don't like being blamed if things go pear shaped:)
Volume spikes in IP (LON:IPO) and Tortilla Mexican Grill (LON:MEX) Cambridge Cognition Holdings (LON:COG) today
Tortilla Mexican Grill (LON:MEX) Yes Mr Wolf, you beat me to it!
Mex has been as dead as a dodo for months and it now looks like 10% of the company has just changed hands at 38p, no RNS as yet but my eyes are peeled
Cambridge Cognition Holdings (LON:COG) was tipped in a newspaper.
Bloomsbury Publishing (LON:BMY) up another 5% today! So glad I decided to open a position last week. I was indecisive as I thought I might be too late to the party, but I am glad I started to think more rationally.
BMY has a fwd PE of 16.8, but that seems to be based on 2025 estimates of 32.2p, which are down from 2024 estimates of 45.8p. My own feeling is that the 2025 estimates are too low, and are likely to revised upwards. So the PE is less demanding than the stats suggest, IMV.
There still seems like a lot of mileage in Harry Potter. Jane Maas is doing the numbers, too. Watch out for children's author Katherine Rundell, too. Her book Impossible Creatures made it to "Instant Sunday Times bestseller." Can't be bad.
I hold.
Add their strong net cash position and the PE is even less demanding
I have made more money with Marks and Spencer (LON:MKS) than any other share I have held. That's what you need in a portfolio, strong knicker elastic ;-)
Haha ... and sometimes a strong stomach to go with it.
Arm Holdings (NSQ:ARM) . I hold. After recently gapping up and doubling in a very short time, price has just broken out of a tight flag pattern, which typically forms at the mid point of move. My first foray into US stocks, and very excited...
Arm Holdings (NSQ:ARM) Am I right in thinking that they only IPO'd with 10% of the stock sold. I think Softbank still hold 90%. What would happen if they released it all?
This is SoftBank and not an AIM company!
How clever of you to spot that.
SoftBank is a multi billion market cap company and they just do not go in the market and sell or release shares ( exactly what you said ). They will sell down their stake at some stage but they sell it to institutional investors (the likes of Blackrock) and the price then will move even higher. It will not be an AIM deal to offload shares to individual investors.
Thanks
Well, they sold a fifth of Alibaba shares in one go. If the deal is there, they will do it. I think Alibaba's shares slump on the news.
Chinese stock nothing to do with Arm Holdings (NSQ:ARM) AI and the chip sector in general. I wouldn’t call a 3% fall on the day as a slump in the price. They have rallied later in the year 25%!
I do not hold Arm Holdings (NSQ:ARM).
"Chinese stock nothing to do with Arm Holdings (NSQ:ARM) AI and the chip sector in general."
How clever of you to spot that.
Can I comment on what a great daily review this has become. Just reflecting on how it was a year ago, I thought it was really good then and the comments at the time reflected that general contentment.
But even better now with comments on movers, table of announcements and your plan, larger companies/ general macro issues where there is read across to Small Caps.
I think it's really hard to have the imagination to improve something that is currently working and Paul, Graham, you deserve our thanks and recognition.
Thanks martinck1, nice to get some feedback on our various innovations! I did wonder if people found the new ideas helpful or not. Best wishes, Paul.
Thanks for the write-up of Begbies Traynor (LON:BEG) Graham. As a holder I asked management at a recent InvestorMeetCompany webinar on their half year results to explain what exactly was included by adjusting out 'acquisition consideration / deemed remuneration' because I was worried by someone on Twitter/X claiming they were adjusting out some staffing costs.
Begbies said it is what is outlined in a sale and purchase agreement. They said it is treated as a P&L item rather than a capital item because they require the vendors to stay with the business for a set time (usually 5 years). They pay those individuals a salary which is charged ‘above the line’ - it is only the consideration element that is excluded.
As an aside they also said very few (less than 10%) of staff leaving after deferred acquisition payments are complete (same link).
Trustpilot (LON:TRST) has more than doubled since Graham reviewed it back in July 2023. I'm not a holder, but his analysis proved to be spot on, and his "tip" came early, not well after the rise, which is what I care about, as I don't chase rallies. Time to re-check Grahams small caps and growth ideas for 2024.
Did you mean to post that as a reply on Begbies Traynor (LON:BEG)?
I'm not sure Graham would describe his Trustpilot (LON:TRST) analysis as a tip. But just as a bear argument I am sceptical about the valuation at Trustpilot because their recent revenue growth has come from pushing through price rises and not new paying customers. New paying customers only increased by 4% in the last half yearly results - I don't think that deserves such a premium growth rating and I expect the market will realise that once price rises aren't masking low growth.
Not as a reply on BEG, but to agree with your appreciation of Graham, who I sense is not one to blow his own trumpet, but he doesn't need to with his track record which speaks for itself:
As for trustpilot, these tech companies have P/E ratio's that may seem bonkers to some, but based on Graham's own valuation metrics, they were still quite cheap relative to similar US stocks.
As for me, a technical buy signal would have occured c.115p, if this share had been on my radar at the time.
Invinity Energy Systems (LON:IES) seem to have played a dangerous game in the RNS setting such specific expectations of a strategic partnership within 'four to six weeks'. I'm caught between taking this at face value and believing their confidence is placed on seemingly having several different partners as options vs thinking this is a cunning ploy to get some momentum in the share price to place into. The cynic in me is winning the debate for now.
What I do like in this announcement is the direction they seem to be heading with licencing out some of the regional manufacturing and potentially adopting a capital light model.
My view on the CMA Investigation into the housebuilders is that this relates to Sales and Marketing. House builders speak to each other at nearby sites at Sales Negotiator level to determine how many they have reserved that week, what sort of deal/incentives they have had to make and determine actual selling price per square foot. This is not price fixing. This is to ensure their own product remains competitively priced against the competition locally and often gives the Sales Negotiator the ammunition to present to their Sales Manager/Director to review their pricing or offer more to the customer to incentivise a sale. This is little different to the supermarkets ensuring their prices compete with others and is a practice which has gone on openly for decades. The insinuation here is that the housebuilders operate as a Cartel to fix prices against each other which is not the case.
House builders speak to each other at nearby sites at Sales Negotiator level to determine how many they have reserved that week, what sort of deal/incentives they have had to make and determine actual selling price per square foot. This is not price fixing.
I might be getting my knickers in a twist here - but since when has it been normal practice in business to have matey chats with competitors ref level of pricing.
Surely when tesco check asdas current pricing they do anything BUT ring up asda asking for details of what their deals are this week? - i might be wrong but would be gomsmacked if tesco and any other supermarket chain discuss pricing on the record (or off the record but authorised) with their competitors.
You are not wrong rmillaree.
I was a CEO of several agri-food businesses supplying most of the major UK and several European supermarkets for quite a few years. The supermarkets don't talk to each other and neither do suppliers.
It all became very "partner" supply chain driven about 20 years ago .... just supermarket code for another way of kicking your supplier, but smiling while you lay the boot in. Factories in the commodity end of the food industry end up deeply committed to one supermarket chain. The agri-commodity suppliers get the kicking because they cannot treat the big global FMCG companies with the same disregard ... they just walk away and you have no Hellman's mayonnaise on your shelf which is not a good look.
But none of us talked to each other, but we did walk the aisles every week and we did talk to the lorry drivers (who are an amazing source of market intelligence and promotional activity). It does sound to me like the building companies might have been naughty boys and girls.
I think the supermarkets threw the pain around with big FMCG companies quite a bit. It wasn’t restricted to agri-commodities, I remember Sainsbury throwing Andrex out for a few weeks and also David Lloyd of Lloyds Chemists slashing Gillette from his shelves. Very tense for the people involved!
Thank you to Wolf of Small Street and Chris de Bal for your comments on RBG Holdings (LON:RBGP) following my post today. I have sold this morning at 8.7p and I have learnt a valuable lesson or two. I should have sold in February 2023 when the Board fired the CEO very unexpectedly. By not acting swiftly I increased my loss by at least £3k.
Portugull,
In investing, when it goes wrong, panic first, panic hard and ask questions later.
I've not seen that in many MBA courses, but i'm sure it's right!!!
Chris
Not small cap, but since Ocado has been mentioned .... There is a bit of confusion in the trade press as to exactly how much money Marks and Spencer (LON:MKS) is withholding from Ocado (LON:OCDO) . The Grocer reports £190.7 m and the Grocery Gazette reports £109.7 m. Looks like a typo to me, but my understanding of the contract is that it is binary. It is all a bit odd as in 2022 Marks and Spencer (LON:MKS) said they were happy with progress and a £200m payment was consequently triggered. The partnership seems to have gone a bit sour in 2023. I hold Marks and Spencer (LON:MKS) and supplied their food division for many years.
Marks and Spencer (LON:MKS) Could the problem be a function of the fact that the contract was started when Covid was still quite a live discussion issue with the older demographic likely to buy/afford M&S and so the sales through Ocado were quite high?
Paul,
The CMA's report is only short, and very interesting, so I recommend others to read it in full. All sounds like common sense to me (Paul).
I read it and found it a bit frightening, just imagine Labour winning the next General Election and then nationalising the business lock, stock, and barrel. Well, town councils do need a good kick up the backside!
From the CMA report
The evidence shows that private developers produce houses at a rate at which they can be sold without needing to reduce their prices, rather than diversifying the types and numbers of homes they build to meet the needs of different communities
No shit Sherlock! I'm all for more housing being built but I'd like businesses to be allowed to make a profit. As for the suggestion that Labour might nationalise the lot (Silver Moon, not the CMA), I don't think you've been following politics very closely if you think that's in prospect under Starmer and Reeves.*
*Apologies for the politics reference :-)
Ah, BnB, there are manifestos first and then comes the reapraisal ;-)
Ah, BnB, there are manifestos first and then comes the reapraisal ;-)
I do a lot of work with a (very) left wing organisation aimed at community action. And their visceral antipathy to Starmer is a major hindrance to their actually making any progress. It consumes all their energies and the above is what I keep telling them!
Re CMA report - Thanks for sharing
As someone who is an elected local councillor, on a local Planning Committee and about to vote on a Local Plan, I can certainly attest that the Planning system is a mess - and that it is unavoidably political with significant investment consequences! No need for BnB to regret the political references. Over the next year they will drive a lot of price action!
(On an political point, I do note that the big builders have given millions to the Conservative Party and that they have arguably achieved excess levels of profitability in the last 10 years through having more resources to better game the dysfunctional planning system than the under-resourced and poorly paid council planning teams. This might come back to haunt them under a Labour administration even if they switch the donations!)
Vs demographic need (itself a partly political choice given the high levels of immigration), the result, at least in the south, has been an excessive focus on executive homes on which margins are much higher and too few 'affordable' homes, all built with poor standards in new builds that will require almost immediate retro-fitting if the Government is to achieve its climate goals (insert your own view on the importance of this issue but note a new housing standard will come in for 2025). The result has been price escalation faster than income and high fuel bills and a big transfer of unearned wealth to older generations who already own their own home. That's why £Saga cruising is doing well! Since Labour will likely be elected on a much younger (ie under 50!) vote for whom housing shortages are a key issue, I expect Planning (and tax!) laws to be reformed and opposition 'bulldozed' to double the number of new builds/year within a first Labour term.
But the land bank assets of the big builders are I think vulnerable to a Land Tax of some sort - the favourite tax of economists like Reeves (which is why I favour the building suppliers like the brick and 'green' building product suppliers). Even a suspicion of collusion will give grounds for quite radical action. Since building will generate a lot of NIMBY anger and take 3-5 years at best to translate into the benefit of significantly more and better houses, I'd also expect action early in Labour's first term so its visible by 2028. (Note I also expect Labour to keep all of the Tories 'permitted development' rules to densify towns/cities cheaply and to push for EVs/microgeneration-all of which will be a further spur to building suppliers.)
No one knows for certain, but the above assumptions are certainly guiding my investment choices. at the moment.
Interesting, thank you.
On the Marks and Spencer (LON:MKS) and Ocado (LON:OCDO) tie-up
M&S withholds payment to Ocado after poor performance - Retail Gazette
I used to hold BEG but gave up because it kept increasing its share count.
BEG
Good company for themselves not the shareholders!
make good money but their remuneration is excessive.
Hi yadi,
BEG Good company for themselves not the shareholders!
To be fair, and looking at facts & figures, the dividends at BEG have been very reliable (paying throughout the pandemic was good), and yield currently forecast at 3.8%, which isn't bad!
Also, dilution has only been to fund acquisitions - which seem to have added value - look at the EPS trend below -
I'm wondering if the historic EPS figures might be statutory and the forecasts adjusted? There seems an unrealistic jump from actual to forecasts.
Finally, BEG still has the owner's eye with Ric Traynor at the helm, and the largest shareholder. Although the obvious question is when will he want to retire and buy a gin palace so he can enjoy floating off the coast of Corfu?! Although I'm told it's still possible to run a company remotely from that location! ;-)
eps line on Stockreports
"I'm wondering if the historic EPS figures might be statutory and the forecasts adjusted? There seems an unrealistic jump from actual to forecasts". Written re Begbies Traynor (LON:BEG) ).
Paul - you are correct and I find this one of the most confusing and potentially misleading parts of Stocko. The actual figures are not always those in the report by the company but modified by Stocko. In this case the figure is 4.33p for 23 cf 3.31p for 22. However the company shows:
(23 in bold). Search the company's a/cs for 4.33 and you will not find it.
Brokers' forecasts are usually "adjusted" and it helps to know the comparison. If the brokers concerned are of the type that view us PIs as what you have described as 'Pond life' then we are left frustrated. However, in this case Equity Development to the rescue. In a note issued in December they show
Later expanded to basic and diluted:
So the increase from 23 to 24 is 2.9% compared to Stocko's 135% in turn making Stocko's PEG figures ridiculous.
If you could convey this problem to t' management it would be appreciated.
Rather off topic but looking for help from anyone who can assist my understanding of a gilt I was looking at.
Tr26 0.125% 30/01/26 is 92.471
But maturing only a few weeks later
Tr26 0.125% 22/03/26 is 98.135
Why such an enormous difference?
Explanation would be very much appreciated! Thank you.
I think the one that matures in January is T26 (not index linked). The one that matures in March i.e. TR26, is index linked I believe.
I see from an earlier post that, like me, you may be a Ramin fan. He did an explainer video some time back which I found useful.
Many thanks Peter T and others! I’ll check out a few of his videos. Really appreciate your time.
Former is Fixed Interest and latter is Index Linked, so depends on whether you are looking for income or capital gain from your gilt, as there is no CGT to pay on gains on gilts.
Thanks shopping365 it’s the capital gain elimination I’m looking for.
How can you tell whether it is a linker or fixed is it just that the yield to maturity is higher if it’s fixed?
Good morning NeilS.
I think the first gilt is a conventional government bond paying income twice yearly with a redemption price at 100 in January 2026. The second gilt, if I am correct, is an index-linked bond where the value of both income and capital are indexed according to the level of inflation.
Regards
Phillip
Join us for MelloMonday tonight at 5pm. The programme for the evening is as follows:
5:00pm Market overview from ‘Queen of Tech’, Vin Murria
5:10pm Company presentation from AdvancedAdvT
5:40pm Damian Cannon explains the Zulu Principle
6:10pm Company presentation from React
6:30pm Company presentation TBC
7:00pm BASH Special, featuring companies chosen by the Mello Community
For more information, click here: MelloMonday 26th February 2024 – Mello Events
All annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. Buy Ticket for MelloMonday – MelloMonday, 26th February 2024 – Zoom, Mon 26 Feb 2024 5:00 PM - 9:00 PM (tickettailor.com)
There were a couple of postings on Incanthera (OFEX:INC) (I hold) the week before last. On a quiet day, I thought I would add my two pennyworth. The Progressive video with Tim McCarthy is the best way to gain an overview.
A blue-sky stock with added sun protection
https://www.proactiveinvestors.co.uk/companies/news/1038087/incanthera-chairman-on-transformational-deal-with-world-s-largest-health-beauty-retailer-1038087.html
This link is also informative and a quick read:
https://www.incanthera.com/news-media/news/2023/2023/december/commercial-skincare-deal-with-marionnaud/
This is a company which has consistently lost money since 2018. It has a quality ranking of 0… At 15 minutes into the video, McCarthy states there will be multi millions coming in this year, at 16 minutes they are paying a dividend and at 17 minutes, there will be no need for future fundraisings. It’s lucky the video stops at 20 mins as he would be walking on water by 25 minutes.
Is there anything of substance behind all the hype? Quite possibly. Incanthera have signed an exclusivity deal with AS Watson, the world’s largest health and beauty retailer for Europe and Asia. Products should be in the shops in Q2.
“The products, developed using Incanthera's proprietary technology, efficiently deliver bioactive vitamin B3 through the skin, a feat previously unachievable. This breakthrough has significant implications for skincare, particularly in protecting and repairing skin from UV damage. The initial launch will occur in Switzerland and Austria, with plans for rapid expansion across Europe and Asia, tapping into Watson's vast network of over 16,000 stores.”
Many millions of men have scalp keratoses, including me. Too much time in younger days on beaches and tennis courts with a receding hairline and no cap. In my case they are a bit unsightly but superficial, so clinically unimportant. Not everyone is in this category, unfortunately. I will certainly be trying out the cream once it’s on the shelves.
The Skin + CELL range will be manufactured in Switzerland and have Made in Switzerland on it, for lovers of Rolex and all upmarket products. It will be expensive. You can see the product in the video.
Since I wrote this early last week, management have awarded themselves 3% of options…
I would be very interested to hear whether others regard this as snake oil or something of substance.
Yet another word of caution, so I don’t get accused of ramping. Tim McCarthy is the same gentleman who presided over the debacle at Immupharma some years ago. They had a great drug Lupuzor, which was benefitting the trial participants significantly. Somehow in the Phase 3 trial, the placebo turned out to be almost as effective as Lupuzor…I didn’t lose any money with Immupharma but felt so sad that lupus sufferers could no longer benefit from Lupuzor. Happily, this is being retrialed in the US with Avion, who have worked closely with the FDA on the trial structure. I would be amazed if the drug does not finally come to market after this.
Love your scepticism here!
This is a company which has consistently lost money since 2018. It has a quality ranking of 0… At 15 minutes into the video, McCarthy states there will be multi millions coming in this year, at 16 minutes they are paying a dividend and at 17 minutes, there will be no need for future fundraisings. It’s lucky the video stops at 20 mins as he would be walking on water by 25 minutes.
The share price spread is pretty enormous 8 - 11p according to Sharepad. It was interesting to note that AS Watson owns Superdrug in the UK which I would perceive as catering towards the lower end of the cosmetics market, which didn’t sound like their target market.
Reading this about Incanthera (OFEX:INC) I'm reminded of Amyris (PNK:AMRSQ - another skincare biotech with a good story. It was a good trade if you caught the wave and a disastrous long term hold.
I made a couple of recent posts on this, seeking views from others, including after the Dec 23 RNS. It seems to me that if its a good as it sounds, it could well be a multi bagger. If it goes wrong in some way, no doubt it'll be a zero, so its still quite binary.
There's a bit more background on the co in this interview from 2021. I bought speculatively after that and topped up in Dec 23 as I felt the RNS de risked it majorly and the risk reward is much better now. One thing that encouraged me to stick with it was the Dec 22 RNS where the directors agreed to waive remuneration to preserve cash. I felt that was correct and honourable - I think they deserve their 3% options and I hope they do extremely well from them.
There are many companies that make a fine living out of selling harmless products pumped up by clever marketing. But, looking past the big claims it is always my view that if the active ingredients do not require extensive drug testing and can be sold over the counter without prescription or control, then either the active ingredients are already well known to be safe (and easily replicated) or the active ingredients are not very active!
Thanks Rogerh and Poker111 for raising this. When Poker111 first mentioned it I think I dismissed it as another jam tomorrow stock, the likes of which have burnt me more times than I care to remember. However, having delved into it a bit further whilst it still is speculative consider it as worthy of a place in a VC style of one of a dozen bets. It may still come to nothing but IF some of the claims are valid it could be a big winner.
I will take the risks as a given. In terms of the upside:
-If has a potentially unique and IP backed way to deliver chemicals below the skin for significant solar keratosis healing
-Anecdotal reports of efficacy in healing the skin are v.striking
-It does have some validation in the A.S.Watson roll-out
-If effective, with Marionnaud it has the opportunity to expand across access a huge luxury market across Europe and Asia
-It is backed by credible funds and if effective it may move to AIM opening up more fund exposure
-Cosmetic success would trigger research to prove clinical efficacy and new markets
-The sub-dermal mechanism IP has potential for delivery of other drugs
- What could this unique process be worth to L-Oreal? What multiple of £8-9m?
- They haven't released pricing numbers, but playing with figures to see what the present value could be and just to show that all that really matters is if the product is good the stock is very cheap: if it sells the product to retail at c.£50 and sells 200,000 in the second larger roll-out across Europe £10m sales could give a £1m operating profit. Add in Asia and you multiple this. That is before the US and other regions. Apply a c.12x EV/EBIT multiple for the IP backing/cosmetic brand and it is not hard to see the upside with various levels of blue sky.
All still speculative but at this price I do not see a lot of the potential reflected in the current price.
Remember to check out this morning's Week Ahead article (this week, handled by Roland), covering the large caps and international markets in the spotlight: https://www.stockopedia.com/co...
Ah I've just seen this, crossed in the post, as I put a link into the main report too!
Just had to share this from the weekly market roundup from Ramin Nakisa. Had me in stitches!
“Perhaps the most succinct summary of the company's results came in meme form: CEO Jensen Huang comes on stage to announce Nvidia's Q4 results.”
I hold RBG Holdings (LON:RBGP) and face the dilemma of whether or not to buy at 9p which will average down my holding dramatically .
I have read Paul’s comments from last May and July but I am finding it very difficult to truly understand if the Company is a basket case or the shares are in fact oversold.
I bought at 145p in 2021. Huge loss but only 2% of my portfolio.
My broker HL have informed me of the retail offer from RBG Holdings (LON:RBGP) .
If I do not participate I will be heavily diluted.
Any views much appreciated.
Would you buy a new position in (LON:RBGP) if you didn't already hold. That is your answer.
portugull if im down 94% then dilution is the least of my worries. Id be removing it from my watchlist, forgetting I ever owned it and moving on to something more positive.
Cheers for the Beeks Financial Cloud (LON:BKS) podcast interview with Gordon Paul.Really interesting to hear the business and business plan explained from the horse's mouth.Puts some colour and background to the figures and company.Interesting play as an infrastructure as a service play.Nice to have an interesting IaaS/SaaS type smallcap company listed.
Reminded me of Michael Lewis' Flash Boys, where all the US big players were spending millions competing within the high frequency trading world to colocate their 'black (trading/matching boxes' as close to the exchange as possible and to get the straightest/quickest physical connection to the exchange.You need the speed to compete with a lot of quant trading strategies nowadays and not just payment for order flow.
For those techie geeks, of which i pretend to be (or have a bit of a hobbyist interest time to time), there are rumours the hardware outfit Raspberry Pi, https://www.raspberrypi.org/, are going to be listing on the LSE!
There are two elements to Raspberry Pi, the foundation which stays as a charity and the manufacturing bit which will be IPO'd.
I have a few raspberry pi's running as servers in my homelab. Media, Ad blocking, NAS, home automation. They let hobbyists down a bit during the chip crisis and instead of waiting I bought two refurb 1U mini computers which run Proxmox virtual machines, which adds another five servers running things like pfSense router/firewall. I have a peer to peer connection to my home network using Zerotier, which means my phone and Tablet are always on the home network behinds it's firewall, with end-to-end encryption.
Further RNS this morning from Plexus Holdings (LON:POS:
CEO, Ben van Bilderbeek, opens window in office
International Personal Finance (LON:IPF) This is not the news shareholders want to wake up to, a c1 week results delay due to possible Polish regulation changes (which sound complicated & possibly beyond my pay grade so will await more information )
However I’ll take solace in “its year-end results reflect a stronger than expected trading performance in 2023 and this momentum has continued in early 2024”
There's an update out (RNS Reach here) from my largest personal holding, Plexus Holdings (LON:POS) . I don't think it warrants inclusion in the main report, but I've posted a comment elsewhere, so for completeness thought I'd copy it here:
The best bit in today's RNS Reach (done for information/promotion, rather than being regulatory requirement) is that this R&D project was bespoke, and customer sponsored. And of course that it's been "successfully completed". Which logically suggests to me that order(s) should follow at some point in the future.
I know nothing about the tech itself, so every time technical terms are mentioned, I have to google them! But it's easy enough for a layman to piece together the implications of each announcement.
Once again, Plexus is looking increasingly like a company that's coming alive again, and on the front foot. I remain of the view that the initial re-rating from £2m to £17m market cap could just be the beginning, if profitable orders continue flowing. As always though, it's dependent on them winning more orders, and establishing a new track record of profitability, hopefully similar to what has been achieved in the past, when the market cap soared as high as £300m. The tech is proven of course, so this isn't some blue sky AIM nonsense. Good progress so far anyway, and I like the more regular RNSs recently, which keep us interested. From a shareholder perspective, there's nothing worse than long periods of silence from companies, eg look at how long Volex leaves updates, and people naturally start to worry, and invent ideas about how things must be going wrong. So I like the regular updates from Plexus, it's good.
Regards, Paul.
(Plexus is a riskier share, so definitely not for widows & orphans)
Thanks Paul.
Would be great if anyone out there with oil/gas sector knowledge could "de-code" the Plexus Holdings (LON:POS) gobbledygook potential?
I completely agree that long periods of silence from companies clearly indicates not much is happening. Surely announcements like this are a red flag and intended to generate interest in the shares without any contract news. You have to wonder why the company is encouraging shareholders to value potential contracts rarer than actual contracts.
There is a lot of PR effort here without actually giving any useful contract information. I would also consider it a "red flag".
All in my IMHO.
Do not hold - not short either
I don't think Plexus Holdings (LON:POS) (I hold) is excessive at all in its announcements. As a holder, I find them useful, and everything they have RNS'd so far are helpful updates. Today's in particular is interesting - customer funded R&D, having completed successfully is surely a good precursor to likely contract wins. Why would anyone want the company to withhold that information? The more the merrier I say, and I can make up my own mind if it's significant or not.
But I take your general point, that there is a fine line between informing investors about what's going on, and overkill that sounds like ramping. There are numerous companies on AIM which churn out company updates which contain all sorts of KPIs and selected data, suggesting everything is going great, then the published numbers come out and they're absolutely pathetic. OptiBiotix Health (LON:OPTI) is a good example, Versarien (LON:VRS) another one, there are too many others to mention.
The difference with POS is that it HAS announced major contracts already, and the latest Cavendish forecast is for revenue to rise about 9x this year, and a bounce back into a significant profit. So this is not jam tomorrow, the jam is happening already. Hence if they have interesting details of contracts, I'm more than happy for it to be announced on RNS Reach, which is clearly marked as non-regulatory, so you can ignore it if you wish.
Although the bottom line is that we can't be certain about anything until audited numbers are out, and even then, audited numbers are not 100% reliable.
EDIT: there's also the issue of client confidentiality. Look at what happened with the Schlumberger deal - it had to be heavily redacted, and left us all scratching our heads as to the significance of it, requiring a follow-up clarification. Far from ideal but not a deal-breaker for me. Other people may see it differently, that's what makes markets so interesting and full of opportunities & danger.
RDHowarth: I would agree if this was an RNS, but an RCS announcement seems entirely reasonable. (I do not hold Plexus Holdings (LON:POS) ).
I do agree with you and Is it is my opinion that these announcements are a red flag and are usually followed by an equity raise.
"If it looks like a duck, swims like a duck, and quacks like a duck, then it probably is a tip.
Hi Paul
I do not normally post comments.
But on this occasion I feel I can add a bit of my little knowledge on Plexus having spent the last 38 years on oil well construction both as an engineer and as a manager.
Plexus manufactures and installs wellheads and associated equipment on new oil/gas wells.
The emphasis is on new wells.
Wellheads are the upper parts of oil/gas wells and directly connect with the Xmas trees: the flow controlling valves that you can open and close manually or remotely.
Oil/ gas flows from the reservoir (as deep as 25 k ft) through a steel production casing (flow pipe) that sits on the wellhead. This is a simplified explanation of quite a complex process. Wellheads are the speciality of Plexus. They are not involved in any other activity on the well.
Current there are very few drilling operations in the North Sea where Plexus is mainly involved.
There are also other larger competitors to Plexus and there is a price war between the suppliers of wellheads.
In my humble opinion there is little upside in the Plexus shares. Of course future events may prove me completely wrong.
Regards
HR
Thanks Goodfella,
Plexus Holdings (LON:POS) (I hold) doesn't compete with mainstream wellheads, and have recently licensed their tech to Schlumberger, who are going to launch it for that market worldwide.
Plexus do specialised, bespoke work, like the £8m rental deal announced in 2023, where high temperatures and high pressure mean that guaranteed leak-free kit is required.
Also they recently announced a £1m deal in the plug & abandonment area, in the Dutch section of the North Sea. This is expected to be a good growth area for Plexus, hence why winning that deal was encouraging.
So I agree with you that there's not much work for Plexus in conventional wellheads in the N.Sea, hence why business dried up in 2015, and profitability collapsed into multiyear losses. However, the key point is that they've diversified, and are now winning business in specialist areas, given the increased worldwide focus on methane leaks.
Anyway, the FY 6/2024 figures should tell the story better than any of us can! The reason I jumped on this share last summer, was because of a huge upgrade in broker forecasts, due to the largest ever contract win, not on vague promises of jam tomorrow.
Thanks for posting, great to hear from someone in the industry.
Regards, Paul.
Plexus Holdings (LON:POS)
Paul
do you have any idea when plexus may provide estimates with regard to 2025 figures to the market. Seems to me that in the absence of "formal expectations" ref sales and profits for 2025 then the only peeps in the "know" are the company insiders and peeps lucky enough to be able to access data from those peeps.
If nearly every other company sees fit to have formal expectations for the following year that they update as time goes on why do Plexis choose to keep peeps in the dark?
I kind of understand that everything was uncertain until the debt / licencing issues were sorted reasonably recently but should they not about now morph into sensible grown up company that provides us with expectations ref numbers via broker ?
cant blaming anyone for taking the viewpoint that if they choose not to provide expectations then that suggests their expectations are NOT great or equally as bad that they might be witholding that data if it suits their purposes. Even if expectations are poor for 2025 now then having a yardstick that they can formally compare to as time goes by (and hopefully improve on) seems to me to be the proper way to do things. Obviously if sales dont ramp up till 2026 would be happy for 2026 numbers to be provided.
Note if we look at similar companies that have not traditionally been shareholder friendly - for example Northern Bear (LON:NTBR) have been somewhat shy in the past ref updating ref future trading , even they have numbers pencilled in for next year and they are marker cap of less than half that of plexus.
Does this company want to be taken seriously by investors? or are are they happy to keep peeps in the dark? or are they keeping peeps in the dark as theu have almost zero visability ref sales levels that would please then market?
Thanks Paul, in some respects knowing that a company has been successful in it's execution of a project for a customer is almost more reassuring than the fact they signed it in the first place so I personally welcome this release. It seems from the release that not only was the work paid for by the customer but they have the freedom to operate in terms of selling it to other customers - at least that's my read.
Wincanton (LON:WIN) a further RNS released at 07.10 confirms a second potential bidder has emerged, which no doubt prompted the increased bid to 480p
I do like a bidding war (my mum holds a few shares ;))
My morning smallcap tweet: Everything’s Coming Up RNSes
Invinity Energy Systems (LON:IES) Wincanton (LON:WIN) Ondo InsurTech (LON:ONDO) Tristel (LON:TSTL), ENGAGE XR Holdings (LON:EXR), Begbies Traynor (LON:BEG), Made Tech (LON:MTEC), EnSilica (LON:ENSI)
◄Invinity Energy Systems (IES)► agreement with its Taiwanese partner, Everdura, to undertake domestic manufacturing of its next-generation vanadium flow battery product for the Taiwanese and other markets. Co hopes to make agreements with one or more other partners in 4-6 weeks. [SP=24.28 Cap=47m]
◄Wincanton (WIN)► it's win WIN as takeover offer hiked 30p to 480p, no doubt in response to another possible offerer. I didn't see that coming. [SP=449.34 Cap=560m]
◄Ondo InsurTech (ONDO)► South West Water to deploy LeakBot product and service to an initial 6,000 customers by the end of March. [SP=25.36 Cap=22m]
◄Tristel (TSTL)► gets recommendation for UK & EU and Medical Devices Regulation certification of TANK ClO₂ Sporicidal Disinfectant system. [SP=450 Cap=214m]
In line: EXR, BEG, MTEC, ENSI
Tristel (LON:TSTL)
Jan 2024
down 10% to 405p (£192m) - Director sales - Paul - AMBER
CEO & CFO sales announced yesterday afternoon hit the share price by 10%. The CEO is retiring, but why did the CFO also sell? Not vast amounts each, but it has clearly hurt short-term market sentiment.
Not great trades - currently circa 500 p