Small Cap Value Report (Mon 27 Feb 2023) - BKS, BEG, ARC, SNR, QTX

Good morning from Paul & Graham! Here we go again.
Normal service resumed over the weekend with my summary podcast here. Hopefully the SSL certificate works now. Let me know in the comments below if you're still having any technical problems. Or it's available on the main podcast platforms.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Here's our to-do list for today - sorry we didn't finish all the items on the list, got a bit bogged down in the others.
Paul’s Section:
Quartix Technologies (LON:QTX)
288p (down c.1% at 14:26)
Market cap £141m
Quartix Technologies plc (AIM:QTX), a leading supplier of subscription-based vehicle tracking systems, analytical software and services, is pleased to announce its audited results for the year ended 31 December 2022.
Revenue up 8% to £27.5m
Statutory profit before tax (PBT) was £5.5m, up slightly on 2021’s £5.4m
It’s confusing as to which numbers are which, adjusted or unadjusted. The way they’re presented, looks the wrong way around to me. It would be clearer if they had called the columns "Statutory results" and “underlying results” rather than “adjusted”, perhaps?
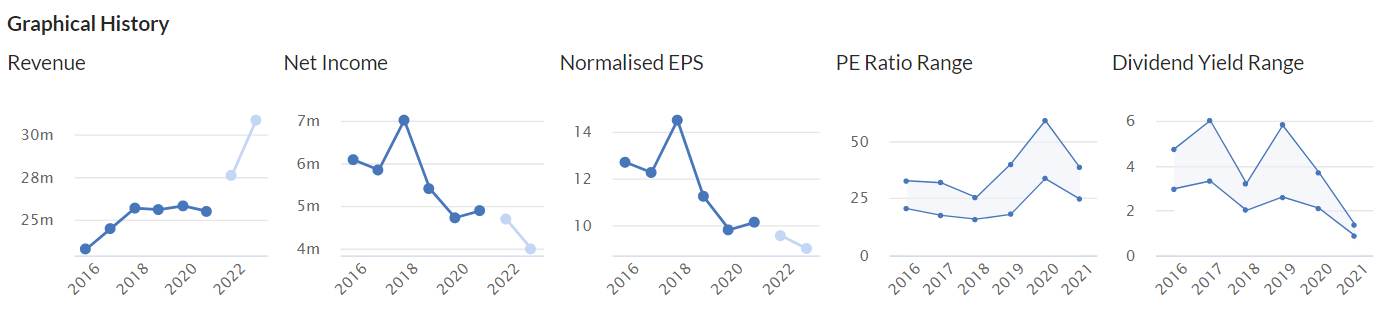
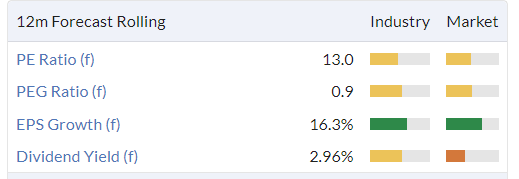
EPS is either 10.9p or 10.4p, two measures are provided, giving a PER of about 27x, which as I’ve mentioned before, just looks much too high to me, given this track record & forecasts of slowly declining profitability, falling dividend yield, and rising PER -
Balance sheet - looks OK. NAV of £20.9m, less goodwill of £14.0m, gives NTAV of £6.9m. Net cash looks more than adequate at £5.1m. This business has almost nothing in fixed assets, and is paid by many clients on reliable monthly subscriptions. Therefore it’s a very stable, and favourable financial setup. So shareholders can sleep soundly at night, or indeed at any other time of their choosing.
Cashflow statement - is very simple. It’s a reliable cash generator each year, and pays out those cashflows in divis. That’s pretty much it! Very easy to understand, which I like a lot.
Note that it overpaid divis (well above cash generated) in 2021, which was obviously a policy decision to return surplus cash to shareholders. Again, that’s a nice sign, if a business is in a position to do that.
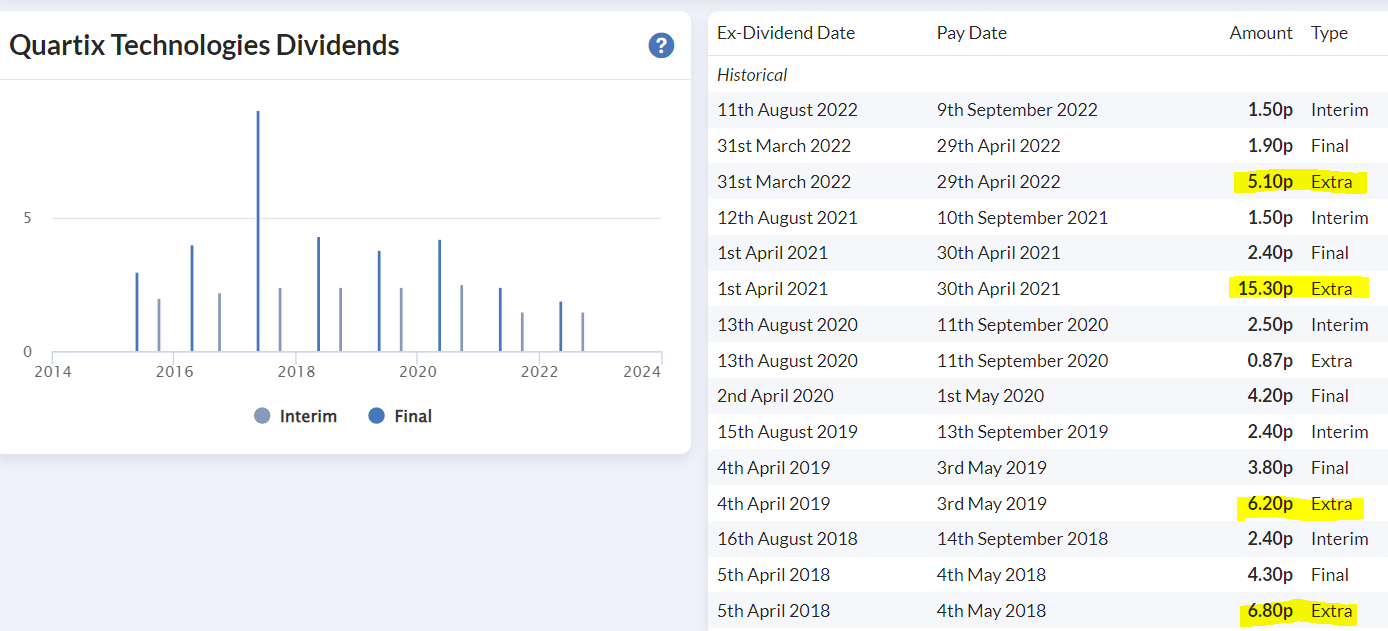
Dividends - Quartix has a good track record of being generous with divis, including special divis (see below). So this is unusual for a smaller tech company, in being nicely cash generative, and dividend paying -
My opinion - in the last 5-6 years, QTX seems to have been running to stand still, or even going slowly backwards in profitability. The trouble is that it’s facing constant price erosion (nearly 5% on average in 2022), and customer attrition. Therefore it needs to generate strong new business just to compensate for these two negative factors.
The current strategy is to be more aggressive with expansion internationally - going quite well in France, less well in USA.
This is a very competitive sector, so Quartix must have a decent product, because it makes a good profit margin, and is managing to expand overseas.
For me though, a PER of 27x is still way too high for me to want to consider investing, given the track record of declining profitability, and only marginally higher revenues, over the last 5 years. I’d need to see more evidence that growth is genuinely accelerating, and that profitability has stopped falling.
To assess this share, the best course of action would be to speak to independent people in the transport sector, who know Quartix’s product, and have also used competitors' products. If they rave about Quartix, then we could be onto something with the shares. Without that information, we're just investing blind.
Beeks Financial Cloud (LON:BKS) (Paul holds)
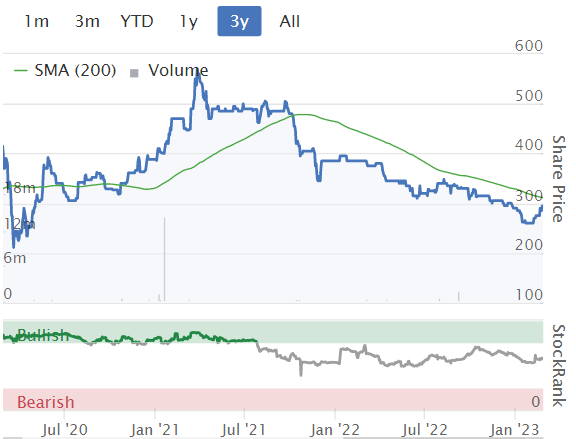
143p (pre market)
Market cap £93m
27 February 2023 - Beeks Financial Cloud Group Plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its unaudited results for the six months ended 31 December 2022.
To save me re-typing the numbers, here’s the table for key numbers below. As you can see, EBITDA turns into only a small adjusted PBT number -
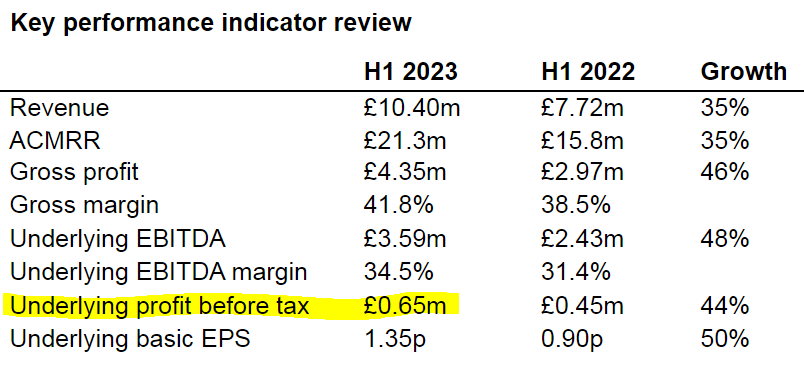
Overall, BKS made a statutory loss of £478k after tax. I tend to use PAT as the key profit number for companies like this, which can claim significant tax credits related to R&D.
Outlook - this is more important than the unexciting H1 figures. Crucially, it confirms that FY 6/2023 market expectations should be met.
Canaccord has £25.0m revenues and £3.3m adj PAT pencilled in for FY 6/2023. I’m not entirely happy with the adjustments. In particular, share-based payments of c.£2m is repeating staff remuneration, so should not be adjusted out, in my opinion.
Some excitement is provided with “two material contracts at the final negotiation stage”, so that should give the shares a boost when/if those contracts are signed. Long sales cycles are mentioned, which has been flagged before.
“Record pipeline”.
Canaccord’s update note (many thanks) this morning says that FY 6/2023 forecasts are well underpinned (remember BKS is mostly recurring revenues), and that there’s scope to upgrade FY 6/2024 forecasts, depending on when the strong pipeline converts into signed contracts.
Price rises have been put through, to recover higher energy costs at data centres.
Supply chain is said to be easing for supply of equipment. Note that inventories of £2.4m has gone up in the last 6 months - this is a stockpile of computing equipment, to enable faster deployment of new contracts. This should be capable of being run down again once supply chains are eventually back to normal, I imagine.
Balance sheet - looks adequate. Although note that BKS is unusual for a software company in that it has relatively large fixed assets (computers and cabling in its data centres). This often requires up-front expenditure for new contract wins. So PPE is on a rising trend, and is now £17.8m. This has required several placings over the years, although quite modest dilution for a rapid growth company. The share count has risen from c.51m in 2019, to c.65m now, which has enabled revenues to more than triple, so I think that’s OK. Note the founder/CEO Gordon McArthur owns c. 37% of the company still, so I like that owner’s eye, making dilution much less likely than at similar companies where management only have some share options, which often drives empire-building with new shares being thrown around like confetti. Not the case here.
NAV is £31.5m. I would take off intangible assets of £7.3m, which gives a still-healthy NTAV of £24.2m, most of which (about 74%) is fixed assets.
Net cash of £3.4m isn’t particularly great. We can’t rule out the possibility of another smallish placing being needed to help fund big contract wins (the up-front capex associated with them), but on a £93m market cap, a bit of dilution wouldn’t be ruinous, so I’m not panicking over that possibility. Institutions would probably be happy to fund a small placing to fund major new contracts, such as the two that are said to be in final negotiations.
Shareholders just have to accept that the business model of rapid growth, and up-front capex for new contracts, probably will require some further additional funding. The temptation is to hope that it won’t need to do another placing, and then be disappointed when it does! So I feel most comfortable assuming there might be another placing or two, which in the past have only enlarged the share count by roughly 10% each, so not a big deal.
Cashflow statement - it’s cashflow negative in H1, due to increased working capital, and heavy capex. Note also that £1.4m in H1 of development spending (i.e. payroll!) was capitalised onto the balance sheet. Perfectly permissible, but this inflates EBITDA, which it by-passes completely.
My opinion - no surprises here in the numbers, plus an in line with expectations outlook for FY 6/2023. I was hoping for an upgrade to expectations, although maybe that was being greedy, as a jump from £18.3m last year, to £25.0m this year, would represent very strong revenue growth, and I’m pretty sure that’s substantially all organic growth too. Revenues are high quality, being mostly recurring, from sticky customers. Profits should follow in future, once the business has scaled up through the current rapid growth phase.
I very much like the whole investing theme of cloud computing niche businesses, where strong growth is in evidence (small cap examples off the top of my head include Beeks (I hold), Cerillion (LON:CER) , and WANdisco (LON:WAND) (I hold).
Beeks is being run for growth, rather than immediate profit, which is fine, that’s the deal with this share. It won't appeal to everyone.
Overall, I think the upbeat outlook comments mean that I’m happy to go to sleep again with this share for another 6 months. There should be some decent contract win announcements in the pipeline, that could give the share price a boost along the way. Although for now, in a more bearish stock market, £93m market cap strikes me as high enough.
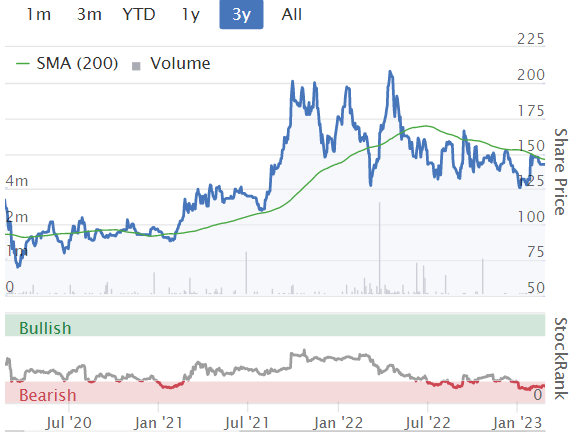
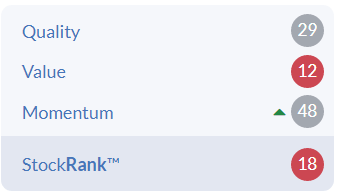
The Stockopedia computers doesn't like it - always a good sense check, to make sure the bull case really is as good as investors think -
Graham’s Section:
Begbies Traynor (LON:BEG)
Share price: 133.7p (pre-market)
Market cap: £207m
It’s a Q3 update from this “business recovery, financial advisory and property services consultancy”.
Once upon a time, it was reasonable to think of this company as simply an insolvency practitioner.
Trading in Q3 has been in line with H1. As a result, “the outlook is unchanged and the board therefore remains confident of delivering market expectations”.
There is “an encouraging level of new insolvency appointments”, and this includes the administration of Paperchase (a high-value case).
In financial advisory, there is “a good pipeline of engagements to meet expectations for the full year”.
Estimates - the company helpfully observes that forecasts for revenue are £117.7m - £121.4m and for adjusted PBT £19.7m - £20.6m.
My view - there’s no reason to change the detailed view that I expressed in December (and November), namely that I think Begbies is fairly valued around the £200m mark.
Bull points:
Low net debt
Excellent leadership from Ric Traynor
Usually has good operating cash flow
Insolvency market very strong
Bear points:
Limited balance sheet support (i.e. not much tangible asset backing)
Macro conditions perhaps can’t get any more favourable for Begbies than they are right now?
People-based business
Overall, I think Begbies should trade at an average earnings multiple. That being the case, I’m neutral on the stock.
Senior (LON:SNR)
Share price: 161.8p (-0.4%)
Market cap: £679m
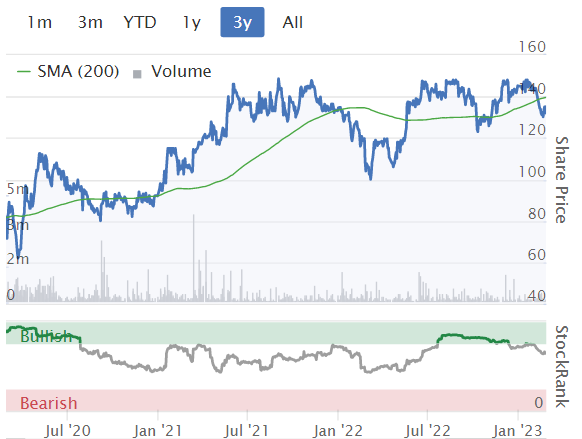
I’m intrigued to see how far this defence stock has rallied since we covered it in January.
The share price is up by another 11% (and it already rallied 7% on January’s trading update).

At this rate, it will be beyond our SCVR market cap limit soon!
Let’s quickly review these full-year results, for the period to December 2022.
Revenue +20% at constant FX to £848m
Adj. operating profit +285% at constant FX to £28.5m
These results are even better if you use actual exchange rates (but constant exchange rates probably provide a fairer comparison).
Pre-tax profit, without any adjustments, was £22.4m.
Net debt (excluding leases) rises by £20m to £100m thanks to an acquisition made in 2022. This acquired company contributed only negligible amounts to revenue and profits.
Net debt to EBITDA is 1.47x, an improvement from 1.87x last year (due to improved profitability).
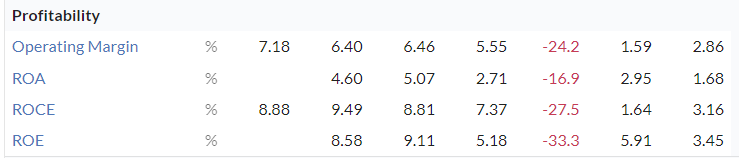
Annual ROCE improves from 1% to 4.7%.
I think the low ROCE is the Achilles Heel of any bullish argument for Senior shares. We know it, and the company knows it: its returns are too low. From the StockReport:
Let’s see what the company has to say about that today.
The CEO:
We remain on track to drive the Group ROCE to a minimum of 13.5% in line with our previously stated ambition…
The increase in ROCE reflected the significant increase in profitability, while managing the increase in capital employed which was mainly due to the acquisition of Spencer Aerospace. This improvement in ROCE is an important step to delivering our Group ROCE target of 13.5% over the medium term.
Will they succeed in reaching 13.5%? Perhaps. If you look into the distant past (10-15 years ago), Senior regularly earned double-digit ROCE. But based on where they are now, they have their work cut out if they are to achieve that again.
Dividend - this stock abruptly cut its long-standing dividend stream in 2020.

Today, the company announces a 1p final dividend, making the total payout for the year 1.3p. Adjusted earnings per share was 4.36p, so the majority of earnings are being retained.
Outlook
Strong growth in 2023 is set to be in line with expectations.
As we start 2023, our order book is healthy, reflecting favourable market dynamics, with commercial aerospace recovery in full swing and other important markets remaining buoyant. Demand is currently holding up well, though we remain mindful of the potential impact of the ongoing supply chain pressures in aerospace, as well as the broader macro-economic situation and geopolitical uncertainty.
My view
I’m happy to reiterate my view expressed in January that Senior is one of the higher-quality aerospace/defence stocks, although it still doesn’t tick enough of the quality boxes that I look for in companies generally. However, in the context of aerospace and defence, Senior deserves its positive reputation.
When you read the detailed review of its divisions, you find a company with exposure to the enormous North American markets (and the US dollar, which nearly always helps), to the long-term structural growth of civil aviation, and to valuable power and energy markets. This is a very reputable international company and a worthy member of the FTSE-250 index. I wouldn’t buy it at the current valuation, so I’ll stay neutral on it for the time being:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
.
LON:BEG to add further colour to Graham's review of Begbies ' Q3 update , Equity Dev have published this pm. Unchanged forecasts and Fair Value of 175p / share. Note and audio summary here: https://www.equitydevelopment....
Nice update from minerals sands producer (Titanium ore) Base Resources (LON:BSE) overnight. Not much commentary on resource stocks so thought I'd highlight this one as it's one of the better companies out there imo. Stock Ranks like it a lot too.
FY23 half-year results - high prices deliver record first half revenue. Available to buy today at 13.65p, so 1.1p per share interim dividend = 8% yield.
Happy to remain a holder here, still looks cheap. Plenty of positive news flow in the pipeline and getting paid well whilst waiting, what's not to like!
https://wcsecure.weblink.com.a...
Good read across to Kenmare Resources (LON:KMR) too, which I also hold.
From the macro perspective, Titanium is such a useful metal, with so many growth/demand drivers, that it doesn't appear likely that prices will recede any time soon.
ie. increased defence spending (missiles and aircraft), space exploration/satellites, medical devices, corrosion resistance (desalination plants) to name but a few...
Thanks for the heads up Forsby. I had KMR on my short list but wasn't aware of BSE. I'm now taking a good look at it.
I liked what I saw. I think I've just moved the market!
I refuse to go anywhere near Begbies Traynor (LON:BEG) on a point of principle. I've had direct experience with them and they're absolute sharks, vultures feeding on dead carcasses. They charge extortionate fees for nothing, complete money for old rope.
Came across this video, analysing Begbies Traynor (LON:BEG).
The conclusions are quite similar to Graham's, that the SP is just about full value right now.
I'm a holder, but I'm considering selling.
I was hoping for a 'ahead of expectations' update today, considering the macro picture, but the investment case really hinges on how bad things might get in the next 6-18 months.
Technically, the 150p level has been tested repeatedly... if we break it, 180p-200p could be on the cards, but 150p could also be the level at which we've topped out, and the SP may drop from here.
The glass half full might be coming for Begbies Traynor (LON:BEG) , courtesy of this FT article recently with many opinions from the restructuring industry: https://www.ft.com/content/237...
Select quotes:
There is definitely a pick-up in activity,” says Sam Whittaker, managing director for the investment bank Lazard’s restructuring business. “We would expect this to continue through 2023, and into 2024 and 2025.
We’re starting to see distress coming through a bit more,” agrees Issy Gross, director of turnaround, financial and operational restructuring at PwC in the UK. While this is not yet widespread, as most companies still have access to cash and debt, she is concerned about what will happen when interest rate hedges drop away and companies need to refinance at higher levels
PwC found there were 474 winding up petitions made last November — about four times as many as November 2021, when there were only 120. In the first 11 months of 2022 there were 2,990 — over three times more than in the same period in 2021. These formal applications from creditors to shut down companies are a leading indicator of future distress and creditor sentiment, PwC says.
Of course, the glass has been half full for a while with Begbies...
(I hold in the Boon Fund)
Perhaps the worst is yet to come, unfortunately, as the effects of interest rate rises will take time to fully manifest.
Bankruptcies are still on a steep upward gradient as shown here:
6m interims trend for revenues, op. profit and EPS
Thank you Breakout Trader for telling me about this video which analysed the company well. I am not the buyer now but hold for the time being.
Hercules Site Services (LON:HERC) SP dropped 37.5% today to 45p, in line with new shares issued in a discounted rights issue. Dilution is less than 7% so interested to know if anyone thinks the fall in today’s share price is overdone?
Premier Milton buying into Hercules Site Services (LON:HERC) in recent placement. Getting to buy as Gervais is a privilege. Bit of jam tomorrow. Speculative punt at these prices. I'm in!
I see that that in the Register of Members Interests (https://members.parliament.uk/...) Lord John Lee has now disclosed a holding in £Hollywood Bowl Group BOWL, up nearly 5% today.
Thanks for the link. Great way to follow his holdings!
Shoe Zone (LON:SHOE) 10th Jan Final Results stated:
It is proposed that a final dividend of 3.3 pence per share will be paid on 22 March 2023 based on a 40% pay-out ratio. The Board is also proposing an additional special dividend of 8.2 pence per share (paid on 22 March 2023), giving a total dividend of 17.0 pence per share.
I can't see anywhere what the ex div date is. Presumably it hasn't been announced (or passed)? Anyone know please? (I Hold)
"Dividends are recognised when they become legally payable. In the case of interim dividends to equity shareholders, this is when declared by the directors. In the case of final and special dividends, this is when approved by the shareholders at the AGM."
You need to wait for the AGM...
https://www.shoezone.com/Inves...
Thanks Truegent.
But why then do I have other shares where the proposed final dividend and ex div date are stated in their Full Year Results and the ex div date is prior to the AGM?
I think its because different companies do some things differently...
Shoe Zone (LON:SHOE) dividend
You asked about the xd date and received a reply telling you to wait for the AGM. That is incorrect - only the pay date has to be after the AGM. Indeed the last time SHOE paid a final dividend the preliminary report said:
The dividend will be paid to shareholders on the register on 28 February 2020, payable on 18 March 2020 if approved at the Annual General Meeting, which will be held on 5 March 2020. The shares will go ex-dividend on 27 February 2020.
This year's announcement clearly has an omission and I suggest you email the company.
I think the reply from the FD below shows my above post was correct ?
It is shown as Thursday 9th March here . https://www.dividendmax.com/un...
Dividendmax is wrong. Just had an email reply from Terry Boot Shoe Zone's FD as follows:
On the assumption that all is passed at the AGM on the 9 March and we subsequently announce on that day, the ex-Dividend date will be the 16 March.
Thanks for the update from the company. I think DividendMax was just a forecast
Anyone heard if Stockopedia plan to offer level 2 services? I would definately be interested in upgrading my subscription if that were the case.
I would definitely be interested in real time pricing. Not actually sure what level 2 is but heard lots of mention it before - my understanding is that it's very useful for traders, but would it also be useful for long term buy & hold investors?
https://www.investopedia.com/a...
Well, didn't Robbie Burns use it to buy that stock mentioned in Investor Chronicles(I forget the name), when he noticed an unusual large buy order on the order books? Level 2 should help with timing entries and exits , and so should still be helpful for long term investors. Ive not used it myself so can't comment on the intricacies, but from what I've seen and read, it appears to be worth having.
I have level 2. It is useful in identifying large buy or sell orders on the order book, which can be a good indicator to buy or sell!
A stoking trading update for consultant Elixirr International (LON:ELIX) this morning, after a -15% drop on Friday and price weakness 6 months prior to that. Not sure what happened on Friday unless investors took fright on consultant redundancies at KPMG and McKinsey.
But this morning's price is not up to Friday's open despite announcing +40% sales, a record start to the new year and £20M net cash. Paul or Graham - This looks to cheap . Any thoughts please?
It would be good to have a review of Elixirr International (LON:ELIX) . Demand for the global consultancy groups has dropped, but this company is such a minnow in this huge market I'm not sure that makes any difference?
I've made a note to come back to look at Elixirr International (LON:ELIX) when time permits. Sorry we didn't get round to it today.
Can't believe it only took someone dumping 38k ELIX shares on Friday to cause a 20% mkt drop, AIM SETsqx traders beware!
Good morning all. A mid cap but I think worth my mentioning CentralNic (LON:CNIC) who's full year results (unaudited) announced today include the proposed introduction of a small maiden dividend. The company also recently completed a 2.5m shares buy back. Stellar growth in marketing earnings although more conservative performance in the domain services segment. Investor Meet presentation available today. I hold.
i was thinking and maybe I am biased but this just seems so undervalued given its growth and on the NASDAQ this would be much more highly valued. What am I missing?
they made a loss and their balance sheet is incredibly weak with massive negative (tangible) equity, too many intangibles and debt after loads of acquisitions...just my view of course...
I have just sold my CentralNic (LON:CNIC after reading todays results. Buying them was a mistake that I should not have made. I was lured in by the very large forecast increase in EPS. What I should have paid much more attention to is the fact their normalised EPS has always been much higher than their reported EPS. This difference between these two figures being a never ending stream of adjustments made by the company to flatter their results. I will not make such a mistake again.
I see a director sold £2m recently. I was considering it, thanks for the warning.
4% of his holding or thereabouts. Maybe his utility bill was causing some concern.
I also see that M.M.Royde purchased £3.5 million from Sept 22 in various quantities the most significant being £1.8million in Nov 22 at 124p. His current holding is 6.2% while that of the most recent director sell of £2million is 12.1% -
Extract from CentralNIc website: "Max Royde is currently managing partner at Kestrel Partners, an investment management company specialising in business-critical software companies, which has a beneficial holding in CentralNic of 56,583,670 shares, or 22.53%. Max co-founded Kestrel Partners in 2009 and is a fund manager of Kestrel Opportunities. Prior to Kestrel, Max was a managing director of KBC Peel Hunt, running its technology franchise. He has over 20 years’ experience focusing on the technology sector"
As noted above Kestrel Partners have a 22.53% holding in CentralNic (LON:CNIC) ( could not confirm this from their website)
Extract from Kestrel website "We actively manage a portfolio of 15–20 technology-rich companies, all with low levels of financial gearing. We focus on cash flow and the compounding of cash over the long term."
Perhaps this makes this company more interesting. ? PS - I do not hold and please DYOR
Yes but despite all the share buying, his holding has not grown, there must a lot dilution going on. This is going in the "too difficult" pile. Good luck with your investment.
Kestrel hold over 27% in Smoove (LON:SMV) , which performance has been rather "meh". If that is anything to go by, I am not sure whether you can read too much into Kestrel's involvement.
I wouldn't get excited about Kestrel being involved in anything. They're over-sure of their strategy & ability to pick winners, in my experience. I'd be interested to see what their funds performance has been like. I recall them being absolutely certain that some dodgy dating website was completely kosher, and it turned out not to be.
Hi Paul,
According to this article https://citywire.com/selector/..., Their performance is quite good. 7/56 over three years in UK smaller companies sector. Not that this means they are right about @cnic of course.
David
Thanks David, that's interesting about Kestrel's performance being better than I expected. I should have checked before commenting. Regards, Paul.
It was Horst Saffrin that sold but for context he still owns another £49m worth!
The major adjustment is $36.4m for amortisation of intangible assets from acquisitions. I believe this is a non-cash adjustment i.e. the cash is still coming in to provide FCF for divis / pay down debt /fund Capex etc. (Please correct me if I'm wrong.)
There's also $5.7m of share based compensation. This *is* genuinely annoying but SBC is very common in techie businesses.
Hi Haggis58. I believe that you are correct to say that amortisation of intangible assetts is a non cash adjustment. In a similar way depreciation charges are often applied to tangible assetts. But if they keep making acquisitions, then the likely-hood is that amortisation charges will keep depressing the reported EPS numbers, which today are still negative. My overall impression is that I can't put any faith into their normalised and forecast EPS figures because it's a smoke & mirrors act.
I am a holder of CentralNic (LON:CNIC) and an impressed one. The charges levelled here on the commentary can I believe be dealt with without concern, but the tone of the negative comments ("EPS is a smoke and mirrors act) suggests a lack of credibility that I see as entirely unjustified. These accounts are reasonably complex but this is entirely in line with accounting rules for a business going through the swift change of a number of large acquisitions. I think that todays IMC webinar did not leave any of the questions glossed over or unanswered. There are legitimate concerns over whether current accounting rules deal correctly with asset light businesses. Instead of understanding that Intangible Assets are ASSETS there is a tendency to sneer at them because of their "Intangible" label. There is no damn need for CNIC to go out and buy an office and I will be very concerned if they do.
More generally, I am concerned that shareholders and the City in the UK just do not have the cojones to imagine that a business can aspire to be world class and size. CNIC has spent the last few years ambitiously acquiring businesses to establish an expandable beachhead in world markets. Yes they have added stock and borrowed money, and yes they have not paid dividends, but these, in my view, laudable ventures, have panicked investors in a way that would be unthinkable in silicon valley.
Our economy has suffered from the lack people of energy and ambition to start building the world class companies that we need in our economy to replace the ones that have been broken up or sold off cheap before their potential is realised. So if I have a worry it is that the animal spirits in CNIC have been captured and neutered for a 1p dividend.
Technology is not a place to run a safe unadventurous company because their is no such thing. Holders of GBG, sitting on a p/e of twice that of CNIC, can look over a stolidly run business that in the blazing hot world of cybersecurity has not managed to quite double its revenue in four years and halved their share price, but hey! - they pay a dividend.
For me the important thing to focus on is cashflow - free cashflow in particular. They are currently valued at less than ten times historic, ie actual, free cashflow. They are forecast to have a net cash balance sheet in 2024. I do hold and for me such a cash generative fast growing business is a core holding.
further impetus should come from google removing support for third party cookies by the end of this year from its chrome browser. This is important as the online marketing division of CNIC generates business without 3rd party cookies.
CentralNic (LON:CNIC)
For me the important thing to focus on is cashflow - free cashflow in particular. They are currently valued at less than ten times historic, ie actual, free cashflow.
I think this is the key counter-argument to the charge that profits are illusory.
Another contributor to shareholder scepticism is the difficulty in understanding what the business does. One side is easy - it is a small scale competitor to Verisign in the registration and hosting of internet domain names. A very sticky but slow growing business. However, the digital marketing side is harder to unravel. I can maybe illustrate with an example: my power drill failed last week and I conducted an internet search for a replacement “Best power drill UK”. As I understand it, this is where CNIC comes in. You might have carried out similar searches yourself and noticed comparison site, journalist- or advertorial-driven content with titles like “Best power drill 2023”. CNIC provides a proportion of this content across the web, embedded within which are links to manufacturer sites or adverts which CNIC serves to the consumer, thus earning its fee, both from pay per click and from sales commission.
As for the drill, I chose the Bosch Home and Garden Cordless Combi and several entities got paid along the way, Bosch, Amazon and perhaps even CNIC ;-)
Seems as if there are quite a few peeps with a CNICical attitude to this stock. Mmm...
I agree with both your points mevans6890. It's true that the reported eps is (slightly) negative in FY22 (though going positive next year onwards), BUT the business is hugely cash generative. Contrast this with the companies that manage to boost their reported eps with various (legal) accounting strategies yet do not produce high FCF - that would be more of a concern.
Intangible assets don't necessarily have a zero value, I think much of the CentralNic (LON:CNIC) income is fairly directly derived from those intangibles. The large translation losses don't help but they won't always be a loss.
What I would like a bit more understanding of is the taxation cost of some $17M. On the face of it, it looks like there is no tax relief on the $36M amortisation costs. If those intangibles are being written down over time to $0, that would mean another $348M has to be written off before tax aligns with profit declared (based on today's balance sheet). I am no fan of EBITDA and in the case of CNIC it is very misleading as the intangibles are (hopefully!) the major driver of the income.
Having said all that I think they have built a phenomenal business that will be highly profitable in due course, just not yet as profitable as the headline numbers suggest. I remain a holder.
They made $15 pre tax. I don't understand why the tax charge is so high. Cash flow from operations nearly doubled to £86m. They look very undervalued to me. Given that most of their assets are web domains, pages, software and IP you would not expect them to have high tangible assets. No one's stopping you from buying shares in a utility company.
CentralNic (LON:CNIC)
I don't understand why the tax charge is so high
The company’s explanation is that the deduction for amortisation of intangibles is not available in many of the jurisdictions in which they operate. And tax rates vary across jurisdictions.
Thank you
Positive preliminary results from CentralNic (LON:CNIC) this morning disguised under as slightly different format headline of UNAUDITED PRELIMINARY ACCOUNTS FOR THE YEAR ENDED 31 DECEMBER 2022, so nearly missed in my screening
Also proposing paying a dividend.
Thanks for the weekend podcast Paul.
FMP it worked well focussing on companies with positive developments and picking the negatives where they were illustrative of wider learning points.
I also enjoyed the interview with Paul from Vox Markets, running through the investment case for some core watch list companies. Many of us completely agree with your position that you can’t invest in every idea which piques our interest, if only that with finite funds we will miss the true gems which we get to know better over time. I avoid buffets for similar reasons.
Hi TJ,
Many thanks for the feedback!
Regards, Paul.
My morning smallcap tweet: The sin bin for flim flam
Ince (LON:INCE) Deltex Medical (LON:DEMG) LungLife AI (LON:LLAI) Forward Partners (LON:FWD) Elixirr International (LON:ELIX) Guild Esports (LON:GILD), Directa Plus (LON:DCTA), Begbies Traynor (LON:BEG)
◄Ince (INCE)► FY-Mar accounts delayed again as auditor "raised further queries ...in relation to historical accounting treatment". [SP=4.95 Cap=19m]
◄Deltex Medical (DEMG)► repayment date of the £1.1m converts extended from February 2024 to June 2026. [SP=1.02 Cap=8m]
◄LungLife AI (LLAI)► nodule evaluation using LungLB projected to be cost-effective in US healthcare system. [SP=70 Cap=22m]
◄Forward Partners (FWD)► Portfolio Fair Value slightly ahead of expectations at £79m+ at end Dec. That's down 40% exclusive of new and follow-on investments. NAV/sh at least 71p. [SP=38.7 Cap=52m]
◄Elixirr (ELIX)► guides FY-Dec in line with rev up 40% and adj EBITDA c.£20.5m. Thus Q1 Q1 trading ahead of expectations. [SP=420 Cap=194m]
◄Guild Esports (GILD)► launched in January Guild Studios, a new production and creative division "that provides bespoke campaign-led solutions for brands and media owners looking to connect with esports, gaming, Gen-Z and Gen-Alpha [who?] audiences". It has has secured client mandates with brands including Samsung Mobile. Fantastic marketing guff follows. [SP=0.95 Cap=5m]
In line: DCTA, BEG