Small Cap Value Report (Mon 27 June 2022) - W7L, ING, NTBR, CBOX, BEG, CTH, HYVE

Good morning! It's Paul & Graham with you today. Today's report is now finished, and I'm off to visit my nearest CakeBox store, to mystery shop it!
Agenda -
Paul's Section:
Warpaint London (LON:W7L) £97m) - a positive H1 update from this make up company. It's coping well with inflationary pressures, actually increasing gross margins. Sales also up strongly. Looking good. With a strong balance sheet, generous (and growing divis) plus positive trading, and all at a reasonable valuation, this share gets a thumbs up from me.
Cake Box Holdings (LON:CBOX) (£74m) - sparkling results for this franchise cake business. Due to previous accounting issues, I've had a good rummage through the accounts, and flag up a few minor queries. Also, note that over half profits seem to come from selling new franchises, which are one-offs. So to maintain profits, expansion has to continue. Overall, I think the positives possibly now outweigh the negative, so it's looking tempting.
Caretech Holdings (LON:CTH) - a recommended takeover bid at 750p, with the founders buying it back. Recommended, and looks likely to go through.
Hyve (LON:HYVE) - this international trade show events group makes positive noises about recovery in today's trading update. However, on closer inspection the finances are very weak, with a hideous balance sheet, and problem debt - which has come down a lot, but refinancing discussions are still unresolved, so I suspect continued bank support might require more dilution from an equity raise. Risk:reward looks bad to me.
Graham's Section:
Ingenta (LON:ING) (£13m) - this small software company releases results for FY December 2021. The stock has some “value” features including a dividend, a well-aligned Chairman, and increasing profits. It also has a StockRank of 79. The company is attempting to diversify both its product set and the sectors it serves. The stock has been listed for over 20 years and readers may wonder if the company’s optimism is well-founded, or if this is just another false dawn for the stock.
Northern Bear (LON:NTBR) (£11m) - this building services company announces a trading update for FY March 2022. Adjusted profits have rebounded (and hopefully the adjustments won’t be too large). A new Chairman is looking to shake things up, with larger acquisitions and other possibilities on the cards. This is a “Super Stock” which may continue to attract value investors who can look past the unpredictable nature of the sector, especially now that there is a potential catalyst in the form of the Chairman.
Begbies Traynor (LON:BEG) (£236m) - [no section below] - this professional services company is known to be an insolvency specialist, but it has its fingers in many pies now across a range of activities. Today it announces the £2.4m purchase of a firm of chartered surveyors (including contingent consideration and cash earn-out). This will integrate with Eddisons, the property services division of Begbies.
Begbies shares have done very well in anticipation of increased insolvencies and its own successful integration of acquired business. Adjusted PBT for FY April 2022 is expected to be £17.8m (up 55%). The company is now priced at more than twice forecast sales, so perhaps the valuation will soon reach a ceiling?
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Warpaint London (LON:W7L)
126p (up 12% at 08:22)
Market cap £97m
Trading Update (AGM)
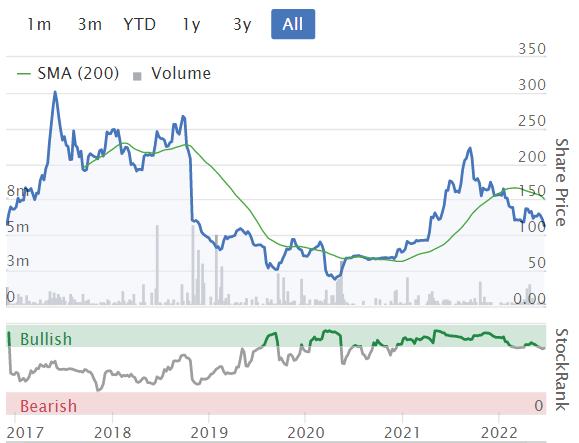
I have a generally favourable impression of this make up company. Although looking at the chart, the share price is not that much higher than the 97p placing price when it floated on AIM in Nov 2016.
Although divis have been generous over the last 5 years, totalling 20.3p, so if we add that to the current share price, the total shareholder return would be 146.3p, which is a 51% gain on the listing price - not too shabby actually. Wouldn’t it be great to have a share price chart that also included cumulative divis too? That’s top of my wish list for a new feature here!
Plus, the business now is considerably bigger than it was 5 years ago, so the shares are better value for money now, compared with when it listed.
I’m looking back at my previous notes here on 1 Feb 2022, when W7L issued a positive (ahead of market expectations) full year trading update for FY 12/2021, together with a positive outlook comment, indicating a good start to the new year FY 12/2022. Although I baulked at the valuation at 165p per share, with the PER into the twenties, which seemed too high at the time.
It’s usefully cheaper now, so do the shares appeal after today’s update? Clearly the market likes it, with the price up 12% as I type this.
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands…
Strong trading in 2022 to date - H1 sales ahead of the Board’s expectations at the start of the year - but note that market expectations have been raised since then, so it’s not clear if this is upgrading full year market expectations or not - I’ll have to see what the brokers say (as they’re steered by the company usually).
H1 2022 sales expected to be >£24m (up 30% on LY - this is also a similar uplift on the pre-pandemic H1 sales, which were c.£18-19m in both 2018 & 2019, as you can see here on this very useful table.
UK: strong growth.
Europe: particularly strong growth - interesting, I wonder what’s driving that?
Other regions: performing in line with mgt expectations.
Gross margin is up on 2021, despite inflationary headwinds for input, and transport costs - that is good news - pricing power is a key factor right now, so this is strongly positive, suggesting W7L has been able to pass on price rises without putting off customers, although that’s not explicitly stated, rather implied.
H2 weighting for 2022 expected, as in previous years - I’ve confirmed that on our useful table here, with both 2018 & 2019 seeing a split of around 18:30 in H1:H2 revenues, so that’s actually a strong H2 seasonality - driven by Christmas sales.
Final divi of 3.5p confirmed (up from 3.0p last year) - giving an expected 6.0p relating to FY 12/2021, a healthy, and growing yield of 4.8%.
Balance sheet - nothing is said today, e.g. about cash, but I’m checking all balance sheets anyway, for every company, given tough macro conditions. W7L is excellent - very healthy, with net cash and a very strong working capital position, so the finances are safe, and divi paying capacity is good.
Strong order book, ahead of last year (no figures provided)
Outlook (from the Chairman, Clive Garston) -
I am confident that the Group will continue to perform well for the remainder of the year.
Broker updates - we’re spoiled for choice, with both Singers and Shore publishing updates on Research Tree - very useful, thanks to both. I like to acknowledge brokers which help the private investor community by letting us access research. In my view, it’s a great shame that other brokers deny us their research notes, despite them having privileged access to the company, but then restricting research notes based on that (effectively inside information/guidance) to their favoured clients only - highly questionable, and obviously unfair, in my opinion.
Looking at Singers note, it’s only pencilled in an £8.0m rise in revenues for FY 12/2022, despite the company already having achieved a £5.6m uplift in H1. Therefore the target looks beatable, which is acknowledged in the commentary. Softish broker forecasts are essential right now before investing, in my view, as that should hopefully minimise the risk of a profit warning wiping 30% off the share price at some random point in future.
Hence I reckon the 8.1p EPS forecast for this year might turn out to be nearer 9-10p if growth continues, which it sounds like it’s likely to do, given upbeat outlook & strong order book.
EDIT: I see Shore is estimating 8.8p EPS for this year, which looks more realistic to me. End of edit.
Valuation - at 126p per share, with 9-10 EPS looking realistic, then the current year PER would be 12.6 to 14.0 - which looks pretty good to me, given that the company is growing strongly, despite tough macro conditions.
It mentions that the value for money product offer is appealing to customers.
My opinion - the valuation has come down a lot, despite improving fundamentals, and this share now looks a lot more appealing as a result.
It’s an excellent income share too, with generous & growing divis - very important, to help reduce the erosion of inflation on our investments, and giving a flow of cash whilst we wait for stock markets to recover at whatever point that happens, currently unknown!
I’m pleasantly surprised with the strength of current trading, and reassured that it’s coping with increased costs and clearly passing that on to customers, given stronger gross margins.
In current market conditions, I’m being generally a lot more sceptical, but W7L comes through with shining colours, trading well, and at an attractive valuation, hence it gets the coveted SCVR thumbs up! As always, this is never a recommendation, but it could be seen as a green light for readers to go on to do your own research. there's a decent StockRank (currently 73) to reassure that it's not a dud.
Thinking about downsides, I suppose there must be some fashion risk with make up, as companies in this sector do need to keep launching new ranges, which may or may not appeal to customers. Although there are also continuity products, which customers repeat buy, so the split of that would be a good question to ask management - hopefully they’ll do webinars - I recall watching a webinar before, but can’t remember which platform it was on. Management struck me positively, seeming to be hands on, down to earth entrepreneurs, which is what I look for in small caps.]
As an aside, management showed impeccable timing, with 2 Directors banking £2.9m each right at the all time high, in Oct 2018. Although they've not sold any shares since, and retain very large stakes (just over 50% combined). So I would watch carefully for any further, large Director sells, and bear in mind that they're very shrewd, so for me big Director selling after a strong share price move up, would be a sell signal for PIs too.
.
.
Cake Box Holdings (LON:CBOX)
184p (up 10% at 10:40)
Market cap £74m
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces its audited full year results for the twelve months ended 31 March 2022.
PR headline -
Strong results and robust current trading, confident of further progress
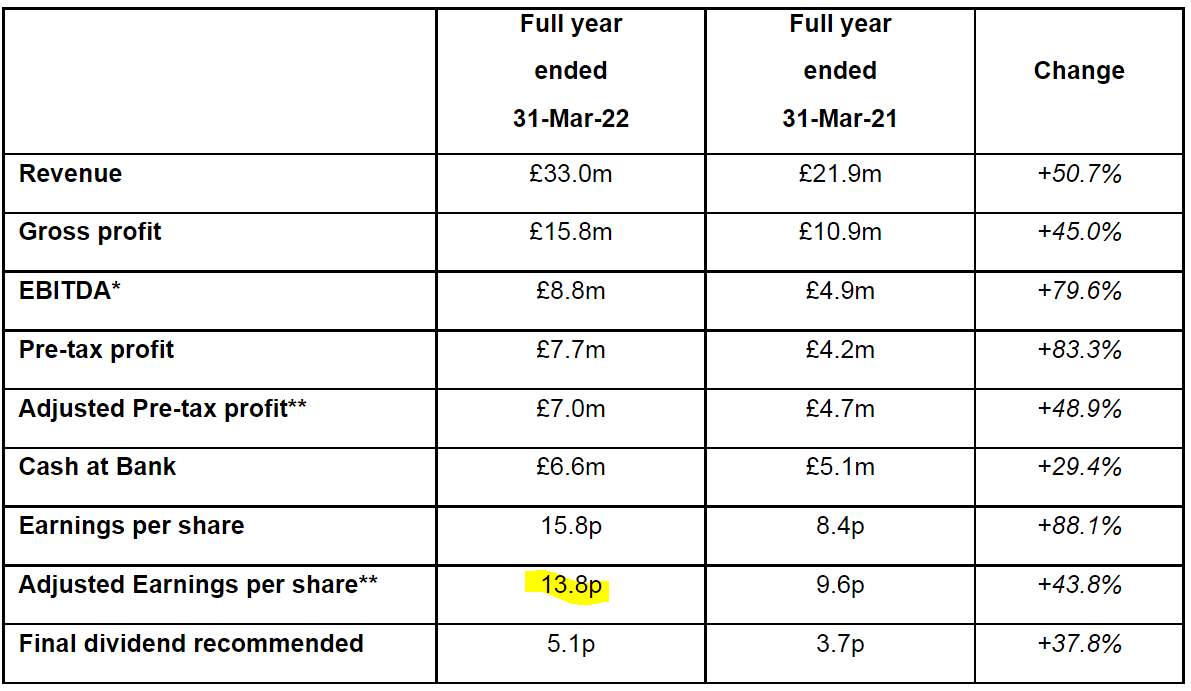
Fantastic figures here, as you can see -
.
Valuation - that’s a PER of only 13.3, which is low for a rapidly expanding, and decently profitable franchise business (hence low revenues, but high margin, because the shop sales don’t go through CBOX’s accounts, because shops are operated by franchisees).
Adjustments to profit actually reduce profit, which is unusual! This relates to one-off gains from releasing provisions, and a credit due to share options lapsing. So the adjusted numbers look reliable.
Dividends - are up, total for the year is 7.6p - a yield of 4.1% - and the divis are rising rapidly too.
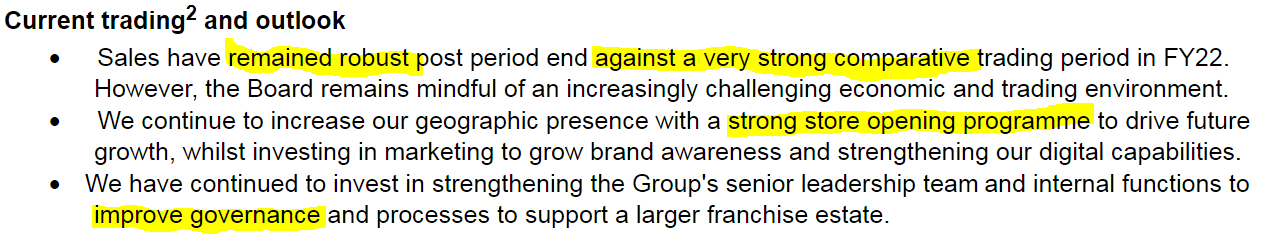
Current trading - covers Q1 of FY 3/2023 - sounds good -
Freehold property revaluations - I like revaluations of freeholds, providing the valuations are realistic, as that shows the current value of properties. Many companies opt for historic cost, which can lead to assets being undervalued on the balance sheet. Others may disagree, but it's good to have both disclosed, as happens here.
The commentary says its HQ was revalued upwards by £2.5m, but a gain of only half that is shown on the comprehensive income statement (note 13 seems to suggest that the other half was booked in the restated prior year figures) - i.e. it by-passes the profit & loss account, so profit, EPS, etc are not boosted by property revaluation, only the balance sheet is. That’s fine, and it’s transparently done (debit freehold property assets, credit revaluation reserve, both balance sheet entries). See note 13 for more details.
Freehold property is now on the balance sheet at £8.7m, with mortgages totaling £1.4m. I am a huge fan of freehold property - it de-risks investments very well, and gives long-term asset value increases. I don’t care about freehold property suppressing some quality measures, that’s a red herring in my opinion. Especially in a potential downturn, investors need to focus on bulletproof balance sheets, stuffed with cash & freeholds, to reduce risk, in my opinion.
I’ve gone through all the notes to the accounts, for closer scrutiny, given the accounting problems unearthed by Maynard Paton in Jan 2022 - by far the most serious was the auditor resignation, which condemned CBOX’s financial controls, and dishonesty/incompetence (e.g. not disclosing a cyber security incident) of the former CFO.
Note 7 - staff costs - why does CBOX have 17 maintenance staff? Seems odd, because the stores are franchised, so surely the franchisees would look after maintenance? So this would be a good question for the webinar - and are any of these staff relations of the Directors? I can’t understand why this business would need 17 maintenance staff. Oh, maybe it includes cleaners for the production facilities? That’s possible.
Travel & entertaining costs (note 4) of £372k seems odd, and high - in admin exps (see note 4) - again, worth querying.
Sale of franchise packages - generated £3.8m (note 3). This is the first time I’ve seen the disclosure of fees generated from selling new franchises. This is a highly material figure, as it’s likely to be largely profit.
Given that adjusted profit before tax is £7.0m, then it seems 54% of total profit comes from expansion - selling new franchises. So for profit just to stand still, it has to keep selling the same number of franchises each year. Although ongoing fees would grow with each new store. The danger is that expansion could slow down or stop, which would cause profits to roughly halve.
On the positive side, it’s good to see an income stream of £938k described as online sales commission.
My opinion - these numbers look superb, and it’s very tempting to throw caution to the wind over the previous accounting problems, and just buy this share on the basis it’s too cheap, for a rapid roll-out of an obviously successful format.
Although I wouldn’t get too carried away with the PER, because half of the profits come from selling new franchises, which is not necessarily a permanent income stream.
Even so, I could see say possible 50% upside on the share price, if the market gets over the accounting issues and begins to trust management again. They do seem to be putting the house in order, but you never know how deep problems like this go, in terms of the culture of the whole business.
The other issue I’ve mentioned before, is that the big shareholders were practically all selling. So that could mean a big, and long-term overhang, suppressing the share price, possibly.
We also have to consider that small cap fund managers are likely to now be getting client redemptions, because many investors tend to take money out after market downturns (which is arguably the opposite of what makes sense!). So fund managers may become forced sellers in small caps, if markets remain in the doldrums. What do they sell? Low conviction, and problematic shares, which could include CBOX maybe? We don’t know though, but watching the “Holding in company” announcements from CBOX is particularly important.
Overall, I’m very tempted to buy a small position here, but am aware of the risks, hence important I think not to over-size it.
.
.
Caretech Holdings (LON:CTH)
739p (up 21% at 11:34)
Market cap £838m
Takeover bids are still happening, which I see as bullish. Note how a lot of them have been software companies, and companies providing some sort of infrastructure services (e.g. Menzies), with buyers often being overseas (especially USA).
This deal has been agreed by Caretech’s Directors, it’s a 750p cash bid, a premium of about 21% - not overly generous, but it’s just about an all-time high, so I don’t think anyone can complain.
Caretech has been in an offer period since March, so that also explains why the bid premium isn’t huge, as it would have been partly in the price already.
It looks as if a consortium has been formed by the founders, so they’re buying it back, funded by lots of debt.
So far it has indications of acceptance from 38.5% - not a certainty that it will go ahead, but it seems fairly likely to do so.
Given uncertainty in the markets, I think it probably makes sense to bank the profits now at 739p, rather than hang on for the last remaining 11p - because bids are more likely to fail in a bear market, maybe? But that’s a decision every investor has to make for themselves. It’s not binary either - sometimes I sell half in the market, and run the balance to competition of the takeover.
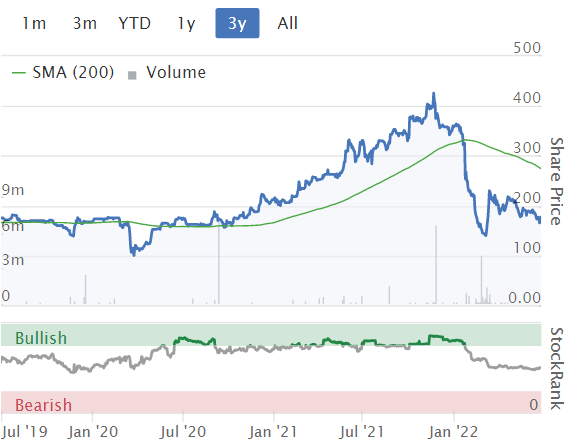
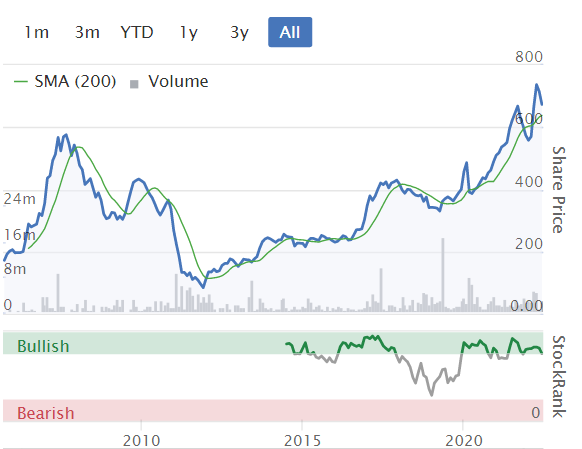
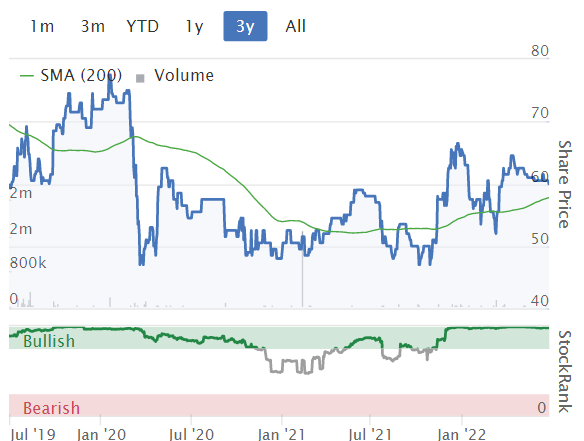
This is certainly an unusually positive chart at the moment -
.
Hyve (LON:HYVE)
71.5p (up 5% at 12:14)
Market cap £209m
Hyve Group plc, the next-generation global events business, today announces a trading update for the period from 1 April to 24 June 2022.
PR headline -
Faster than anticipated recovery continues
Improved net debt position
Running in-person trade shows has obviously been a horrible area during the pandemic. However, HYVE has received substantial insurance payouts re cancelled events, and it’s managed to survive this far, so it could now be a recovery situation.
It gives a positive update today, on recovering bookings. It’s not simple to work out how the business is likely to perform in future, because performance pre-pandemic was erratic, and there’s been a lot of restructuring since.
The disposal of its Russian business for example received very little cash up-front, and proceeds will mainly be 10-years of earn-outs. Hmmm, let’s see how much of that is actually received in cash from Russia. It’s probably safest to assume zero!
There are continuing lockdown-related problems in China, affecting HYVE.
Net debt has come down nicely, to £53m, but the balance sheet overall is a car crash - when last reported, NTAV was negative £(139.6)m, so it clearly needs refinancing with fresh equity. Therefore I wouldn’t go near this, until it’s properly fixed the balance sheet.
Although the business model receives fees up-front, so it probably could run with negative working capital, but not this much.
Although with a market cap of just over £200m, if it were to do a (say) £40m equity fundraise at the behest of the banks, then that might be 20% dilution, which is a fair bit, but not ruinous. However, fund managers can name the price, especially in hard times, so they might insist on a deep discount. It’s such a big risk, and one I wouldn’t want to take. Why invest in any company with wobbly finances, given macro problems?
I can’t find any broker research either, which doesn’t help.
Looking back at the interims, there are alarm bells over balance sheet weakness, but also in the going concern statement, which talks about possible bank covenant breaches & waivers, and that the company is trying to refinance its bank facilities.
Today it says this about refinancing the bank facilities -
The refinancing process is in progress, with the Group in discussions with existing and prospective lenders.
My opinion - until it sorts out the balance sheet, with fresh equity, possibly as part of a deal to renew the bank borrowings, then I would treat this as too risky, and best avoided.
It’s not even cheap. On current broker consensus forecasts, there’s minimal profitability this year FY 9/2022, and the PER for next year is 29.5 - that’s very high for a company with a desperately weak balance sheet. Hence anyone buying or holding this share would need to be very confident it’s going to thrash forecasts, and successfully refinance. Hence for me, risk:reward looks very poor.
On the upside, in-person events look to be coming back, and maybe HYVE could be valued on a sum-of-the-parts basis for each show?
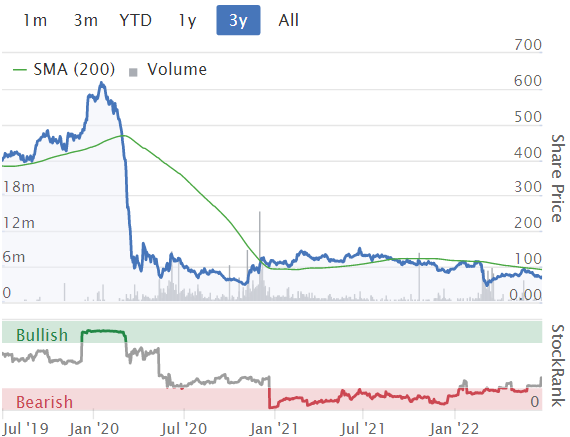
Note the share count has shot up from 75m in 2017, to 292m now. So that's a huge headwind for the share price, meaning previous highs are now unlikely to be recovered.
Graham’s Section:
Ingenta (LON:ING)
- Share price: 84.90p
- Market cap: £14m
This is a small software company that serves the publishing industry.
It has been knocking around AIM for a long time, by the standards of the junior market. It first listed by means of a reverse acquisition in April 2000.
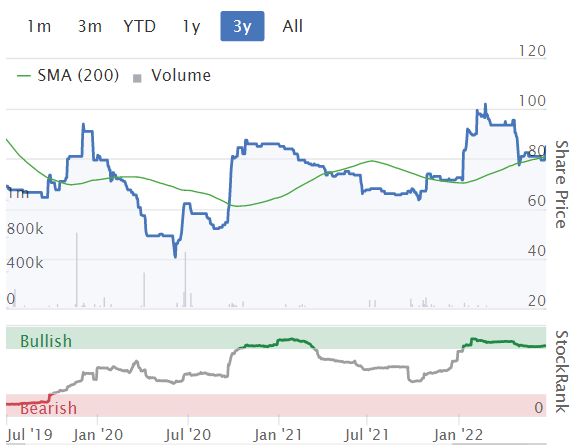
Profitability has been sporadic over the years, and you can see yourself from the market cap that the company is still deep in micro-cap territory.
Today’s results are for FY December 2021, and are as follows:
· Revenues down slightly to £10.1m, “reflecting a focus on core software offerings”.
· Net profit of £1.8m (up from £0.4), but this includes a £1.2m tax credit. So net profit of £0.6m, excluding the tax credit.
· Good cash flow from operations (£2.0m), helped by working capital movements. The company’s cash balance improves from £2.3m to £3.0m.
As this is a small company with business customers, contract wins and “go-lives” are measured in the single digits. Ingenta saw four customers going live during the year: three on a web publishing platform called “Edify” and one on a music public platform called “Conchord”.
Current trading – since the results shown are for the period that ended nearly six months ago (!), shareholders will be more interested in a report for the current period.
The current year is said to be “strong”, with “growth in revenues and profit over the prior period”. This is said to be “driven by existing customer base with extended sales cycles persisting for sales to new customers”.
How would you feel, as a shareholder, if your company was only very slowly finding new clients, but was deepening its relationship with existing clients? My view is that this is ok, particularly in a difficult economic environment.
In a tough economy, it makes sense that sales cycles would be longer. But if the existing customer base is happy with the products, and wants to buy more of them, then that says a lot for customer satisfaction!
Anyway, results for the current year are tracking ”comfortably in line with market expectations”.
Company strategy – Ingenta wants to broaden the scope of the markets it sells into, beyond its traditional IP management for publishers. The contract win in music publishing is its first success from this growth strategy, whereby it can serve new customers from a wide range of industries.
Two of its new web publishing customers were NGOs, which is a step forward in this customer diversification plan.
While some of Ingenta’s revenues are non-recurring in nature, it wants to focus growth efforts on recurring revenues where possible, i.e. “Software-as-a-Service”.
Dividend – this company is a dividend payer, and proposes an increased dividend of 2p for the year, giving a yield of c. 2.4%.
Outlook – confident:
With our newly established operating fundamentals firmly in place and generating returns, the Group can look forward with optimism to the next stage of its development - generating revenue growth and leveraging our expertise in the wider IP management arena.
My view
I’ve not studied this one before, but have done some groundwork this morning which will enable me to comment on it in future, should it start to pick up some momentum.
While the growth aspirations are commendable, the lack of sales growth in 2021 is noteworthy. An interim report should be out in September (judging by last year’s release dates), and hopefully this will prove that 2022 is more positive.
The 2021 numbers do show an improvement in margins and good control over operating expenses, and hopefully that will continue.
Some other positives:
· The Chairman is the largest shareholder, so alignment with external shareholders should be very good.
· A nice recent history of dividends, and I appreciate the company’s move to buy back some shares.
· KPI metrics used by the company include a focus on cash flow.
· Stockopedia calculations have also noticed the numerical attractiveness, and have given the company a StockRank of 79.
The only major negative, from my perspective, is that the company has been around for so long and has presumably had many false dawns in the past, all under the current Chairman.
I think it will be worth our while continuing to monitor this one.
.
Northern Bear (LON:NTBR)
· Share price: 58p (-4%)
· Market cap: £11m
This building services company tends to offer a cheap multiple against prospective earnings. It’s in a tricky sector – things can go wrong (e.g. bad weather!), it’s labour-intensive, and of course highly competitive.
Services provided by the company include construction, roofing, electrical installation, fire protection, etc.
In FY March 2021, Covid was the big problem, although the company also mentioned “uncertainty surrounding Brexit” and supply chain issues. Northern Bear reported an operating loss for the year, after it took a big impairment at a commercial interiors subsidiary.
If interested, you can find a list of Northern Bear’s subsidiaries here.
The company will release FY March 2022 results soon, and this is the main subject of today’s trading update.
Despite ongoing supply chain/inflation problems, we learn that the second half of the year has gone well:
..the Group has generated strong operating results that continue to exceed those from the prior year to 31 March 2021 ("FY21"), as well as those from the comparable pre-pandemic year to 31 March 2020 ("FY20").
The Board's current expectation, subject to audit finalisation, is that operating profit for FY22, stated before amortisation, one-off costs and other adjustments (in the format used in prior years' results), will be in the range of £2.5 million to £2.6 million.
The adjusted profit figure was £1.4 million in 2021, and £2.2 million in 2020.
So FY March 2022 is shaping up to be a nice improvement over both prior years.
Cash at year-end was £2.2 million, although the company acknowledges that this is a seasonal high. The company has been using its £1 million overdraft and up to £500k from an RCF.
That’s another complication in this sector: huge cash swings, as large lumpy payments come and go. But Northern Bear’s headroom, given the presence of the overdraft and a £3.5m RCF, seems comfortable.
Strategy – under the leadership of a new Chairman, the company has recently considered two acquisitions “of a more substantial size than those we have made previously,” though neither of them came to anything. Interesting stuff!
The new Chairman (since 2021) is a Toronto-based investor who first got involved with the company in 2019. He currently has a 25% stake and doubtless has ideas about how to drive shareholder value – watch this space.
My view – if it hadn’t been for Covid-related issues, this company may have proven that the low rating attached to its shares was just far too cheap.
However, the same might be said of many companies! The fact is that the Covid disaster did happen, that Northern Bear was exposed to its consequences, and that the company continues to be exposed to the supply chain and inflation issues that have flowed from it.
But despite these trying circumstances, the company is now performing well again, and it has a Chairman and major shareholder who will bring a new perspective on how to unlock value for shareholders.
It would be remiss of me not to mention that this is a Super Stock, with a StockRank of 99:
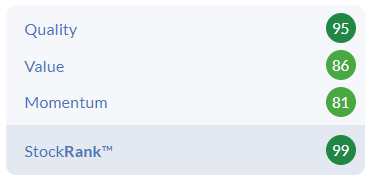
So whether as part of a diversified StockRank-based portfolio, or as a speculation on what the new Chairman might achieve, or simply as an investment in a company that is cheap relative to potential earnings, there is a lot to be said for this one. Worth researching.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Caretech: "run the balance to competition"?
There were two sales of 200,000 shares each in Spectra Systems (LON:SPSY) today. The price was unaffected, so it seems unlikely that the MM absorbed them.
And....?
I agree its much more than the average daily trading volume. But still <1% of total share count in £SPSY.
Hi Paul, thanks for your analysis on £CBOX. You mentioned: ”Given that adjusted profit before tax is £7.0m, then it seems 54% of total profit comes from expansion - selling new franchises”.
Would have to kindly disagree as it’s my understanding that the “franchise package” income covers costs incurred for pre and post opening (E.g. store fit out, initial set up costs, pre opening support and training). These costs are required prior to the franchisee trading so must have some margin allocated as part of their contractual agreement, the £3.78m income would not in my view be clear profit, only a percentage thereof. Would be very surprised that only 10% of their revenue generated 54% of their profit.
Edit: they used to charge new franchisee’s £120k as the initial investment, and a management service fee of £200/month, there were 31 new franchise stores in the reporting year which would come to £3.79m (would assume the c £10k discrepancy is because not all 31 new packages would have been operating for the entire 12 month period).
Thanks
Hi Discodave4,
IRe. Cake Box Holdings (LON:CBOX) - 'd be very surprised if the initial franchise fees cover the shop fit-out - surely the franchisee pays for that direct with the shopfitters?
£3.8m franchise fees, for about 30 new shops opened in the year, suggests £127k per site. That's a bit less than Cake advertises on its website here, where it costs from £160k+VAT to buy a franchise. Maybe some are discounted, to close the deal?
It says that includes 3 weeks training at CBOX HQ (which wouldn't cost much). The website doesn't say anything about fit-out costs.
So, I take your point that the £3.8m is unlikely to be entirely profit, but I reckon it's probably mostly profit. We're both making educated guesses though, this is a question we really need to ask management to expand on, in the next webinar.
Regards, Paul.
Hi Paul,
The £120k and £200/month service cost was taken from a Cakebox link but could be out of date?.
In their results today it states:
“The franchise package consists of up-front revenues which relate to pre and post-opening costs mainly for store fit-out; and initial set up costs to cover site selection,pre opening support, and franchisee and staff training Each part is considered distinct.
The pre and post-opening costs are required to get the new franchisee trading and are therefore recognised at a point in time which is at the end of the month in which trading commenced. Each package is tailored to a specific franchisee's needs and elements can be added or removed as appropriate which will affect the price. Each element carries its own price.”
Would imagine fit-out costs aren’t cheap and possibly sub-contracted out by head office to third party contractor. It is a guess on how much they pocket from the £120k’ish and a worthy question to ask.
Thanks
Fair points discodave, well made.
Yes we need to clarify this, by directly asking CBOX mgt how much profit element is contained within the £3.8m new franchise fees. It needs to be that specific question, otherwise they could easily waffle around it, to give a favourable impression! As Peter Mandelson said in his memoirs, politics and economics are all about asking the right questions. Not that I want to base anything I do on him!!
Regards, Paul.
I don't wish to revive painful memories for some, but it is interesting, as reported today, that auditors Grant Thornton have settled the suit of Pat Val's ( £CAKE ) adminstrators. Claim was £2m. Settled amount undisclosed. Luke Johnson, chairman, receives a wedge, presumably because he made a director's loan to the co.
hi grumpy5
re £CAKE
I think you'll find the claim was for for £200m not £2m.
Luke Johnson's loan was for £10m
OK.
If readers like the look of Warpaint London (LON:W7L) you might also want to look at Creightons (LON:CRL) (I hold) for potentially better value. At 48p currently and the TTM EPS figure is 5.4p and I am expecting about 6p EPS for the FY22 full year results to end of March, based on the uplift seen in H1, plus a bit for recent acquisitions minus expected dilution from share awards. So that puts them on a p/e of around 8 for a company with a good growth track record. Their 2024 aspirations are for £100 million sales, net profit margin 10%, ROCE 30%, dividend yield 2.5%. If achieved, and I think these look achievable, put that on a p/e of just 10 and you get a multi-bagger at these levels within 2 years. FY22 results are due on 19 July.
Of course in the current economic climate people might cut back their spending on cosmetics and beauty, although Creightons (LON:CRL) do a lot of work at the "lower" end of the market such as manufacturing supermarket own brands.
Northern Bear (LON:NTBR) i think it is worth noting the 2 recent NED appointments.
to me these seem like very successful and experienced City backgrounds. the C'man paid 70p for his stake. He is committed to capital allocation. i agree the historic businesses are steady / dull / carry some risks, but I dont think the company will be at £10m MV in a few years time and i dont think a 25% holder will dilute their own value unless the acquisitions add value.
disc i hold
it also strikes me that in this nervy bear market (esp smaller cpas), the 200d chart trend has been very steady upwards - i.e. indicates no sellers. for my strategy Northern Bear (LON:NTBR) offers a very good risk/reward with limited downside, backed up with excellent Stock rating of 99.
I held Northern Bear (LON:NTBR) until a couple of months ago. I bought in back in 2019 and topped up in the second half of 2020. What caused me to sell was the legal claim against them (see RNS from circa Christmas if I remember correctly). Whilst this did seem fairly low risk it was for £2m which is not insignificant for a £10m market cap company, so I decided to play safe and sell out whilst I still could at a small profit. This virtually guarantees the share will double bag by the end of the year.
I would be highly confident that if brokers are publishing data even if that is purely to their private members , then that data will in "theory" not contain any inside information at the time the note is published. If that wasnt the case the whole system simply wouldnt work.
Presumably brokers additional info extracted is no different to what the company would release on conference call or via phonecall to shareholders or responding to email request. Presumably if they do get info in advance they dont publish anything till taht news is out in the open.
The exception would be if the person receiving info agrees to being made an insider themselves - practicably speaking though i would expect stuff like that to only apply to corporae actions not broker notes.
Whether the reality works as it should i know not.
Note i know nowt here really so i could easily end up with egg on my face - but i cant belive FCA would allow clients of brokers to have inside info generally speaking unless thye themselves are agreing to be an insider.
I would be keen to understand if any fellow subscribers have bought, or are considering buying M&C Saatchi (LON:SAA) given the price pull back. They are in the highly unusual situation of not recommending one offer from AdvancedAdvT (LON:ADVT) (I hold), and then recommending that shareholders also decline a second offer from Next Fifteen, after previously recommending it. Are any ADVT holders thinking about holding Saatchi as a hedge, in case Vin Murria juices up their bid price? Saatchi appears a reasonable stand alone business at this valuation, even if bids are not received, assuming there is no major downturn. Any views?
I have recently opened a small stake in M&C Saatchi (LON:SAA) as I think the stand alone business and valuation looks good, and if an offer comes then all the better. It appears to be bouncing off some support from pre take over, so lower downside risk IMO. I think if an offer comes in I would off load on the jump if am honest. If it breaches the support I would be again looking at off loading without going into actual numbers.
Hope that helps
No mention of Cake Box Holdings (LON:CBOX) today Paul ? Prelims today, I thought this one was on your watch list ?
I was too hasty ! Thanks for covering it...
Hi truegent,
No problem! It took me a lot longer than usual to go through Cake Box Holdings (LON:CBOX) accounts today, as I wanted to really look closely, given the accounting/audit shenanigans.
I'm off to mystery shop their Bournemouth site now. Will report back!
Regards, Paul.
I'm very pleased with today, Graham and I covered everything important - here's our GoogleDoc (blue means done) -
Paul writes: In my view, it’s a great shame that other brokers deny us their research notes, despite them having privileged access to the company, but then restricting research notes based on that (effectively inside information/guidance) to their favoured clients only - highly questionable, and obviously unfair, in my opinion."
If their research notes are inside information (which seems a reasonable description) then any trading based on those notes would surely be illegal if it was carried out before the information became fuilly available to the rest of the market participants.
Has the FCA ever expressed their views on this? FOI?
FREng. I could not agree more! I wonder if Sharesoc have ever put this point to the FCA?
Warpaint London (LON:W7L) - Paul, thanks for covering - "Management struck me positively, seeming to be hands on, down to earth entrepreneurs" - Met them at the recent physical Mello (great event although it was a pity to not be blessed with your presence) and had a good 15 minute chat with them - I can confirm this to be the case and, it's also interesting to see how much of the stock management still hold - They did mention that they rely on the yield as their primary income so I suspect they will retain an interest in a strong balance sheet and maintaining that healthy yield.
They did also mention that they still have a healthy runway, even just in the UK, it was something like only 20% of their products in 20% of the stores they serve at present (Boots, etc.) - Don't quote me on that though as it's probably not exactly what they said (but it was along those lines) - I had asked the question of them, if they had saturated the UK market and they were basically quite clear, by no means, that they had not.
Thanks again
Hi matylda,
I just want to acknowledge your very interesting feedback about W7L management, thank you!
I intended to attend Mello Chiswick, but that week turned out to be a massive news week on the RNS, and there was no way I could do 6-7 hours work on the SCVR, then spend 3-4 hours travelling up from Bournemouth to a very inconvenient part of London, then spend ages being affable to people, then find my way to my second home in Canonbury at about 2am, completely plastered like last time.
Also, I'm 54 years old now, so I need a nap around lunchtime.
I've got to say, going into London for anything, feels like a real pain right now, and I'd rather stay in the pleasant micro climate of Bou'mth. Zoom meetings are so much better. Really frustrating for everyone, especially my old friend David at Mello, trying to rejuvenate in-person events, but it's going to be a long haul. Maybe there's a middle ground, with smaller, shorter events?
I do miss the social interaction though.
Regards, Paul.
Thanks Paul, you're welcome and thanks for taking the time to reply.
Completely understand your reasoning there, living outside the UK, Zoom, Goto Webinar, etc. have been invaluable and they suit me much better.
The physical Mello was most welcome though (after a 3 years) and hopefully David will continue to get the support he needs to host, at least, an annual event - Perhaps in central London instead ;) As I too would find that much more accommodating.
I continue to value your daily content, and also welcome the return of Graham (have to say Jack's content was also first rate), long may it continue.
Here's to the next meet, hopefully sooner rather than later.
Wishes,
Jon
ps - Since I breached the half-century mark I too have found that a mid-day nap is essential :) I consider myself fortunate to be able to include it in my day!
Good Morning Paul,
As you suggested I used the green button to contact Stockopedia on Friday concerning the data for Smiths News (LON:SNWS) and I heard back from Daniel within the hour. Over the weekend the data has been updated to reflect the H1 Results published on 4 May.
As you will know as a trained Accountant the numbers are all about interpretation.The key number for Smiths News (LON:SNWS) is the net debt. As you can guess it all comes down to IFRS16 Leases.
In Smiths Accounts Net Debt excludes the Leases and is £38.8m down 44.6% from the prior H1 number and Net Debt including IFRS16 is £67.4m down 33.5% from £101.3m.
The updated Stockopedia number for Net Debt is £64.5m.I do not know how Stockopedia arrive at their numbers for TTM but clearly different interpretations have a material impact on the Z Score which I now realise cannot be relied on.
However one looks at the numbers what I do think is that the Management Team at Smiths News are delivering on their promises to rapidly reduce net debt which should deliver big increases in the Dividend. A yield of 13% on a PE of 3 even in this market is highly attractive.
Hi portugull,
Absolutely, those are the points I've been making here about Smiths News (LON:SNWS) for a while.
BUT, why is it on a PER of 3? Because the business is structurally declining. It can only cut costs so far, and management have already told us that their 3 year plans are now close to the limit of what they can cut, in terms of fixed costs.
It's good, but don't be blinded by the high yield & low PER. It's like that for a reason.
That said, I recall about 10 years ago, TNI was in a similar position. It 10-bagged, when the market realised earnings were more resilient than imagined. So SNWS could be good. Who knows? I think it's cheap, but don't currently hold.
Regards, Paul.
Paul/ Graham - if you have time would you look at Polar Capital Holdings (LON:POLR) results from today please? Seem very strong given their core competency is US tech, and they have clearly diversified nicely. Awesome dividend. Would love to hear your views v Liontrust Asset Management (LON:LIO) last week.
Dividend looks good for Polar Capital Holdings (LON:POLR) at 46p vs c.520p share price. However, Equity Development have their EPS estimates at 40p for FY23 and 38p for FY24. Given the US tech focus of Polar Capital Holdings (LON:POLR) performance will probably continue to be a bit suppressed without a change in sentiment towards that sector but the dividend is attractive and Polar Capital Holdings (LON:POLR) also have net cash at about a fifth of the market cap.
essentially, the dividend is not covered but it has strong balance sheet for now. Hold for me.
Polar Capital Holdings (LON:POLR) remind us this morning that they pay between 55% and 85% of adjusted total earnings depending on the scale of performance fees and anticipated trading conditions for the following year.
So I think the dividend is covered but for some reason brokers have the DPS at higher than EPS for the current and next financial year - I think that is an error based on Polar Capital Holdings (LON:POLR) policy.
Hi BritishExpat70,
Sorry we didn't get round to looking at Polar Capital Holdings (LON:POLR) - I'll ask Graham if he fancies checking it out tomorrow. As a former fund manager himself, Graham should have some good insights.
The divi yield looks fantastic, at 8.2%
It has a strong balance sheet too.
Looks quite interesting, but profits are down.
Most funds seem to be open-ended, so I wonder whether AuM might fall?
It needs someone more knowledgable to look at this, but at a first glance, I think it looks potentially interesting, although obviously very geared to stock market returns.
Regards, Paul.
NextEnergy Solar Fund (LON:NESF)
Pleasingly solid numbers today.
NAV of 113.5p so still trading at a slight discount and a yield approaching 7%.
Never going to shoot the lights out but useful as an inflationary hedge in current times I think.
Phil
(I hold)
NextEnergy Solar Fund (LON:NESF)
Pleasingly solid numbers today.
NAV of 113.5p so still trading at a slight discount and a yield approaching 7%.
Never going to shoot the lights out but useful as an inflationary hedge in current times I think.
Can you explain how this is a hedge against inflation, particularly if the sun doesn’t shine enough? Also, how is the NAV calculated? Most of these infrastructure funds use a DCF type model and rising interest rates will adversely effect the discount rate used in calculating the NAV. And just look at the epic amount of equity dilution! Sorry but I just don’t get these funds. Something tells me they are far more risky than they would have you believe.
All the best, Si
Cashflows are strongly correlated to long term power prices, so that provides the inflation hedge.
Cashflows are strongly correlated to long term power prices, so that provides the inflation hedge.
What cashflows? Maybe the StockReport is not showing a true picture of the real cashflow for some reason and painting a poor picture of the investment thesis, but it seems high dividend payouts are not being covered by earnings or free cashflow over the years, and shares in issue has gone up 300% in 5 years. As a casual observer, that's a bit like you'd expect a Ponzi scheme to look like :)
I guess the high yield in itself tells us there is risk involved.
All the best, SI
The hedge for NextEnergy Solar Fund (LON:NESF) (I hold) comes from the fact that they are selling energy under long term agreements that are inflation linked. You're right to make the point about higher interest rates and their impact on NAV, but compare inflation (9%) to long term interest rates (2.5%) and you'll see the point. Imagine a quite likely scenario where we see inflation come down in 2 years, with interest rates following. The rise in inflation remains baked in to their sales prices for ever more, unless we are to see deflation, but rates will have fallen back. Meanwhile most of their costs for any given asset were incurred in the past.
On the cashflows, note that according to the stocko figures, capex is always zero. The "operating cash flow" includes all figures. As you'd expect in most businesses, free cash flow was negative in the early years, but has since turned positive.
Overall, I think you're right to highlight the risks but they all have mitigations. Some points I'd highlight on Next Energy are: a massive component of their revenue ultimately comes from government subsidies, so what does the future hold there? - and they have diversification by country (30% outside the UK) and by asset type (e.g. 10% in battery storage and 15% in ventures), so they are not totally reliant on the British weather.
On "equity dilution" the picture is complex and all moving parts should be considered. Firstly, issuing new equity at close to NAV to build the assets makes sense as it diversifies them and reduces overheads as a %. Second, they issue scrip dividends each year which is effectively another form of funding. Thirdly they have a substantial tranche of preference shares that will convert to ordinary beginning in 2030.
I'd agree that these companies are riskier than they seem on the surface, but for me personally, I like to get exposure to as wide a variety of risks as possible, so some exposure to these particular risks makes sense, particularly in times like these.
The hedge for NextEnergy Solar Fund (LON:NESF) (I hold) comes from the fact that they are selling energy under long term agreements that are inflation linked. You're right to make the point about higher interest rates and their impact on NAV, but compare inflation (9%) to long term interest rates (2.5%) and you'll see the point. Imagine a quite likely scenario where we see inflation come down in 2 years, with interest rates following. The rise in inflation remains baked in to their sales prices for ever more, unless we are to see deflation, but rates will have fallen back. Meanwhile most of their costs for any given asset were incurred in the past.
Thanks for the explanation. In theory it sounds good at least!
On the cashflows, note that according to the stocko figures, capex is always zero. The "operating cash flow" includes all figures. As you'd expect in most businesses, free cash flow was negative in the early years, but has since turned positive.
Yes, I noticed the zero capex shown on the StockReport, which didn't seem right. But you take my point that dividends have effectively been paid by new equity issuance rather than from cashflow. So new investors have effectively been paying the dividend for current investors... Mmmm.
Overall, I think you're right to highlight the risks but they all have mitigations. Some points I'd highlight on Next Energy are: a massive component of their revenue ultimately comes from government subsidies, so what does the future hold there? - and they have diversification by country (30% outside the UK) and by asset type (e.g. 10% in battery storage and 15% in ventures), so they are not totally reliant on the British weather.
Thanks. I don't find the dependence on UK weather or government handouts the least bit attractive in an investment. As you say, who knows what the latter holds going forwards?
I'd agree that these companies are riskier than they seem on the surface, but for me personally, I like to get exposure to as wide a variety of risks as possible, so some exposure to these particular risks makes sense, particularly in times like these.
I guess if you are looking to mitigate against inflation this could be used to achieve that as part of a portfolio of similar investments. Not of interest to me but I can see how that might work for others.
All the best, Si
Northern Bear (LON:NTBR)
Solid year end update with £2.5 mill operating profit - hmmmmm operating profit is sketchy - but at least no nasties mentioned today - we will see if any hidden nasties later.
Lets take 25% of that number of for tax (how long before government reverse the corp tax increase to 26 % due to come in 1/4/23? - we are past half way point now i think ref next election - so they will need some positive spin sooner or later)
Say £1.9 net profit market cap £11 mil - so p/e of just under 6 ish give or take - about par for the course with Northern Bear (construction services !)
Jeff the new big hitter has been engaging with the board ref "change" and they have the following to say.
This review remains ongoing and in recent months we have assessed two
potentially accretive acquisitions of a more substantial size than those we
have made previously, which ultimately did not come to fruition. We continue
to explore avenues for increasing shareholder value.
Based on their cheap valuation and minimal positive net cash (year end is highpoint as they themselves are kind enough to remind us) - not sure how larger acquisitions will work out well for current holders - it kinda has the dilution feel to it. Hey ho they have net cash and minimal interest paying debt some of the time - note balance sheet is getting better - but they generally have large payables and receivables which is always slightly sketchy with contruction companies where the prospect of customers not paying for whatever reason can be higher than your average company type - they have one such quibble in the courts at present from memory ref one hisotic customer not being happy with what they did.
Same old same old in summary
Warpaint London (LON:W7L) and Cake Box Holdings (LON:CBOX) having good RNSs today. These were purchased recently by me and progress seems excellent against the challenging environment. Confident long term holds through the market multiples compression.
Warpaint London (LON:W7L) and Cake Box Holdings (LON:CBOX) having good RNSs today.
There's a thing called the Lipstick Effect which seems to have some credibility. It suggests that in a recession women will buy cosmetics as an inexpensive way of boosting morale during tough times. The research also seems to indicate that given a choice consumers will opt for a more expensive brand, rather than going for a budget option.
Also, people will tend to go for inexpensive luxuries when they can't afford much else. I'd imagine a nice cream cake might fit the bill.
Anyway, both Warpaint and Cake Box seem to be doing well. The latter is obviously putting a lot of effort into fixing its compliance issues which shows positive intent and a recognition of that there was a problem, at least.
timarr