Small Cap Value Report (Mon 27 March 2023) - BLV, NAR, TND, BVXP, Mello, EQLS, CML, ITS, SFR, DIA

Good morning from Graham and Paul!
Today's report is finished (13:30).
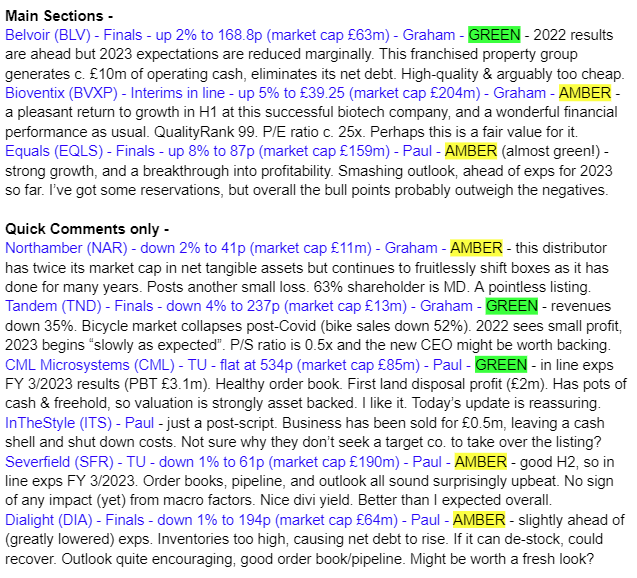
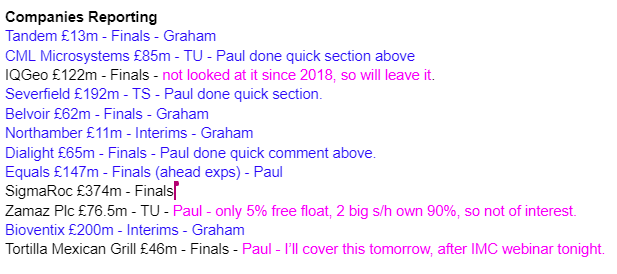
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
MelloMonday reminder - tonight's online show starts at 17:00 - details here. I was chatting to Mello’s founder, David Stredder last night, and I managed to get 10 free tickets out of him, for SCVR readers who want to try before they buy! Our discount code is SHR100.
The highlight for me is David Cicurel, the long-standing CEO of Judges Scientific (LON:JDG) - so if you want to see what the CEO of a 100-bagger share is like, this is your chance!
I can still remember Cicurel first giving a talk about JDG at Mello Beckenham in 2008. He gave an interesting and quirky talk about his plans for JDG, all delivered with humour, and a wonderful strong French accent, hence why it was so memorable!
Other than being a nice chap, with a sensible business plan, there was absolutely no inkling at all that this share would be a 100-bagger! If only we could travel back in time & buy the shares again at one-hundredth of the current price!
Cicurel has just executed flawlessly over the past 15 years, making a series of shrewd acquisitions, and seemingly not putting a foot wrong. Could you have predicted that? Of course not. Early shareholders really just got lucky. Although the story did get better over time, as each acquisition added value. I wonder if there are any people who have held JDG continuously? I can remember people (e.g. CockneyRebel) flagging JDG when it was about 100p. The other thing is, it got pretty expensive at times, and I think it lurched down with the occasional profit warning too. So the path to a 100-bagger certainly wasn’t smooth. It’s fascinating to ponder though, in the hope that we can find the next one!
Bottom line for this 100-bagger - it’s all about backing great management, with a good strategy. Then holding, regardless of valuation & mishaps along the way. And just being lucky!
Equals (LON:EQLS)
- 87.3p (up 8% at 09:48)
- Market cap £159m
Equals (AIM:EQLS), the fast-growing payments group focused on the SME marketplace, announces its final results for the year-ended 31 December 2022 (the 'year' or 'FY-2022') and an update on trading for the period from 1 January 2023 to 24 March 2023.
'Well-invested platform delivering rapid growth, significant cash generation and enhanced profitability'
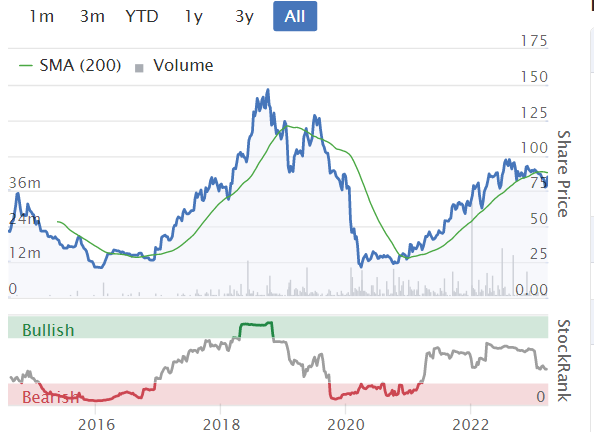
It’s mainly a forex business, a sector that has been doing well since the pandemic lows. Although if you zoom out on the chart, the long-term performance from EQLS is not actually that impressive -
Key numbers for FY 12/2022 -
Revenue £69.7m (up 58%)
Adj EBITDA £12.1m (up 81%), but as the company clearly discloses, it capitalised £4.2m of payroll costs onto the balance sheet, which by-passes EBITDA.
Adj diluted EPS is my preferred measure, which is 3.03p (2021: 0.02p), giving a PER of 28.8x
It’s worth emphasising that this is the first year of meaningful profitability - personally I prefer companies with a more established track record of profitability in good times & bad than is the case with EQLS -
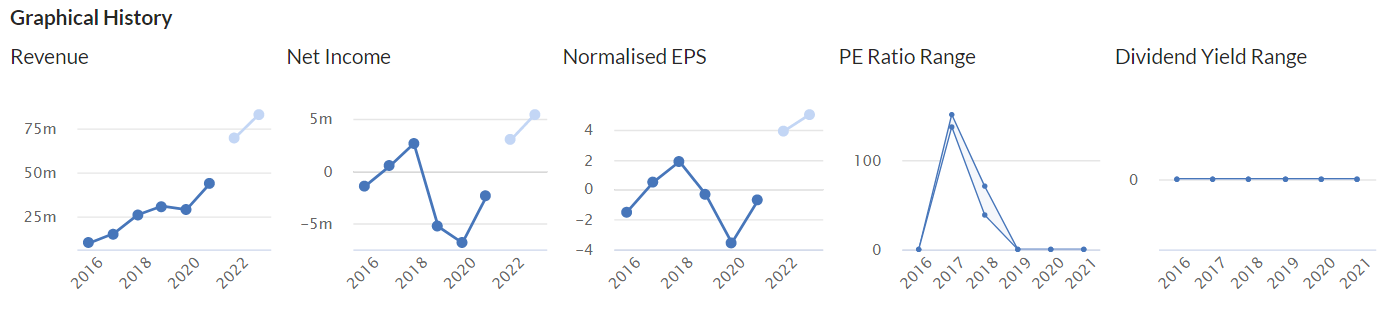
As you can see, it doesn’t pay dividends, which suggests a business that has not as yet been significantly cash generative.
Of course shares are valued on future performance, not the past. So the all-important outlook section matters the most, and it looks really good - ahead of expectations again, this business is clearly on a roll -
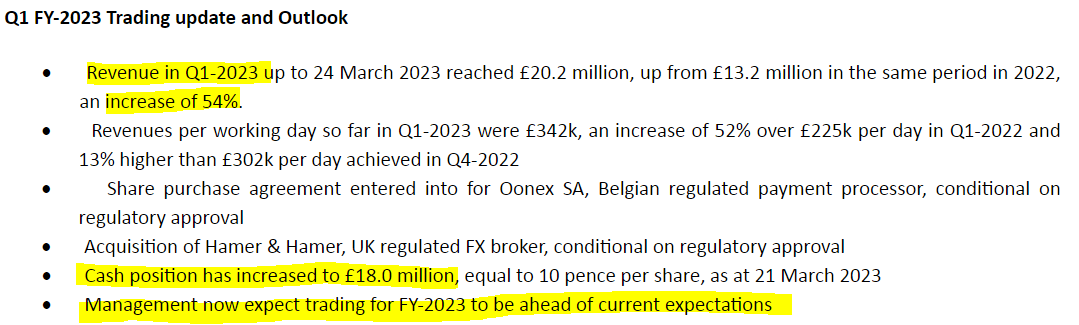
Although note that 2023 forecast (the upper line below) was trimmed back in Jan 2023 from 6.2p EPS, to 5.067p, and we’re now told that the company is trading ahead of (lowered) expectations.
I really like this presentation of the P&L, which gives much more information than most companies do, enabling us to much better understand its cost structure -
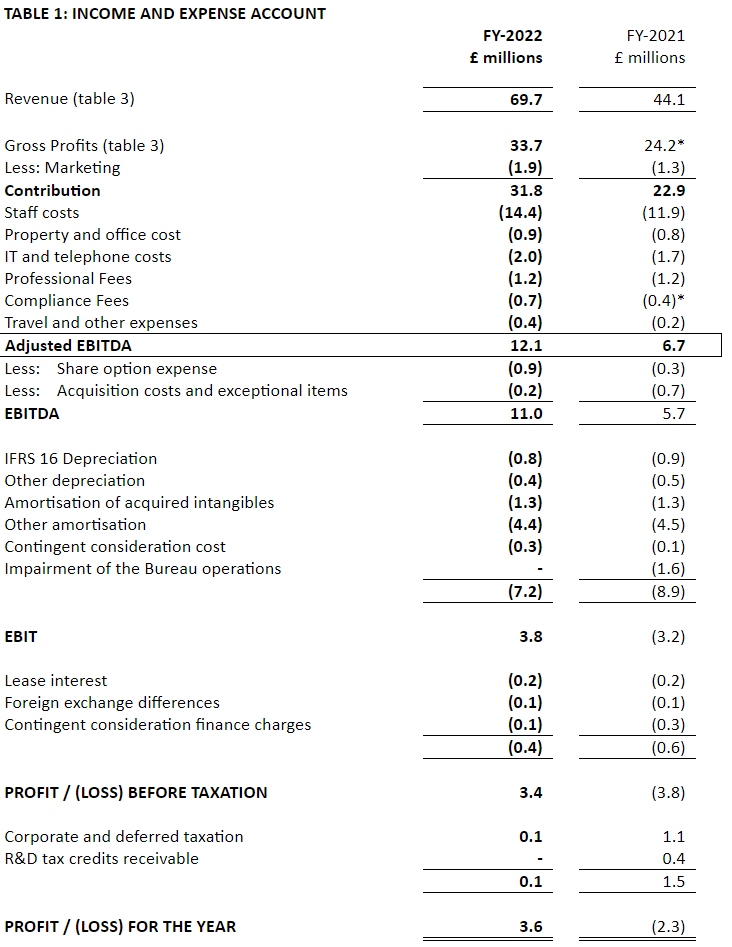
Taking into account all costs, the PBT is only £3.4m, which isn’t a lot for a company valued at £159m.
Balance sheet - NAV is £42.9m, which includes intangible assets of £30.0m. So NTAV is £12.9m, or only 8% of the market cap. Hence negligible asset backing to support the share price, if earnings were to collapse.
No sign of that happening, but it’s important to know whether there’s asset backing to cushion things, which there isn’t here (that’s true of lots of growth companies though, to be fair).
Working capital looks OK. There’s £31.2m in current assets, including £15.0m in cash), and £21.3m in current liabilities, which looks fine to me.
Substantial client cash balances are held separately, so are not on EQLS balance sheet. I can’t find a figure for this, but might have missed it. There must be a good opportunity for EQLS to earn interest on client cash, now that interest rates have risen. Although realising this, clients might well start demanding credit interest be paid to them. Or be reluctant to leave cash balances with EQLS perhaps (especially during a banking crisis).
My opinion - clearly this sector is a good place for investors at the moment, and EQLS is performing well, with superb growth. I really like the strong growth, and the operational gearing that’s coming through, from ramming more business through its platform.
So this looks an interesting growth company, with a nice bull case.
Quibbles are as mentioned previously here, EBITDA rendered meaningless due to heavy capitalisation of payroll costs, modest balance sheet, limited track record, no divis.
So it’s really a question of weighing up the pros and cons, and making your own choice.
I can see the appeal of this share, so whilst I’m neutral (amber), I’m leaning more towards green than red, for what it’s worth!
Graham's Section
Belvoir (LON:BLV)
- Share price: 168.8p (+2%)
- Market cap: £63m
Belvoir is one of the listed property franchisors, along with Property Franchise (LON:TPFG) and M Winkworth (LON:WINK) . Returns in this sector can be very good, and I gave these stocks an honourable mention in my list of ideas for 2023.
Today we get the full-year results for 2023 from Belvoir. The company claims that it now has a record of unbroken profit growth going back 26 years – I’m not able to independently verify this, but it wouldn’t surprise me based on what I know about it!
Key points for FY December 2022:
Revenue +14% to £34m (12% attributable to acquired businesses)
PBT down 2% to £9.1m, but after-tax profits increased marginally.
2022 results are ahead of forecasts, but broker estimates for 2023 have been reduced marginally.
Segmental analysis: lettings is the most important activity, providing 56% of gross profits.
Financial services is the second-largest contributor at 23% of gross profits. Belvoir did purchase a network of financial advisors during 2022. So while financial services revenue grew strongly, organic growth in this segment was just 4%.
The number of written mortgages by Belvoir is up even as the number of house sales is down.
Net cash improves to £1.2m.
CEO comment:
Whilst we have seen a bounce-back in our mortgage activity for the year to date, up around 20% on Q4 2022, with house transactions taking up to five months to complete from agreeing a purchase, the increased market activity so far in Q1 will take until H2 to flow through to our financial performance…
Our property franchisees benefit from the strong recurring lettings fees earned from their managed property portfolios, and our financial advisers are able to draw on their extensive bank of clients who are looking to remortgage.
At Belvoir, there are now just as many remortgages as there are new mortgages. However, the fees earned on a remortgage are only 70% of the fees earned on a new mortgage, so the company would certainly benefit from a return to a thriving new mortgage market!
My view
There’s little reason to change my view here - I continue to like this business.
Pulling out the cash flow statement for a quick sanity check, I see that the company generated £9.6m of cash from operating activities.
Investing activities cost £3.4m but there’s little in here that worries me much - £4m was spent on acquisitions, capex was negligible, and then there are some loan payments to and from franchisees.
I’m going to give this stock the thumbs up because I liked it anyway before today, and it has just generated nearly £10m in operating cash during a difficult year. At a market cap of £63m and with a dividend yield of over 5%, I like it.
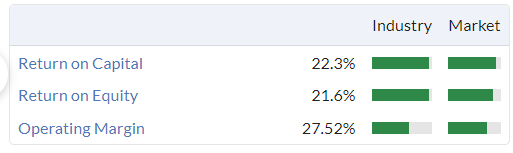
It also passes no fewer than six of Stockopedia’s bullish stock screens:
Greenblatt’s Magic Formula (one of my favourite screens)
Philip Fisher Growth Screen
Neglected Firms Screen
Free Cash Flow Cows Screen
Buffettology-esque Historical Growth Screen
The Screen of Screens - Quality Investing
Bioventix (LON:BVXP)
Share price: £39.25 (+5%)
Market cap: £204 million
I provided detailed thoughts on this well-followed biotech share back in October.
In today’s interim results, I’m pleased to see a return to faster revenue growth. Broker forecasts for the current year are unchanged, although they now anticipate larger dividends:
Revenues +25% to £5.9m
PBT +27% to £4.5m
Cash balance £5.2m
A quick explanation of its performance from the company:
Sales of physical product have performed well and revenues from our vitamin D antibody and other core antibodies have all increased as anticipated.
Sales relating to troponin antibodies grew significantly once again during the period. The continued roll-out of high sensitivity troponin tests provides further encouragement for our future sales in this area.
The prose is quite brief in this report. It concludes with:
Forthcoming changes to both the UK Corporation Tax structure in respect of Research and Development and the headline rate of Corporation Tax will have an impact on our future reported earnings and cash flows. Nevertheless, we will endeavour to follow our established dividend policy…
In conclusion, after the difficulties experienced during the pandemic, we are pleased to see a solid performance of our core business and look forward to this continuing over the remainder of the year. We remain optimistic about our troponin revenues and the success of these high sensitivity troponin products around the world and we look forward to reporting further progress in the second half of the year.
My view
I have again gone to the cash flow statement for a sanity check, and am reminded of some of this company’s exceptional features. It generated £4.2m in net cash from operations, and then also generated positive cash from investing activities, as interest received exceeded capex! Remarkable.
Additionally, the rejuvenated growth figures help to wash away one of the concerns I expressed back in October, when growth appeared to have slowed.
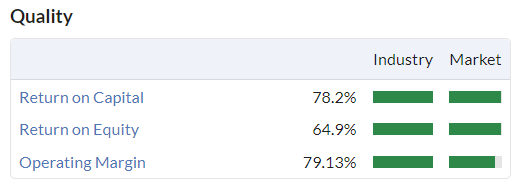
The overall financial performance here is second-to-none, and this shows in a QualityRank of 99. I’ll stay neutral on Bioventix mostly on the grounds that its technology is difficult for me to understand, but I continue to greatly admire its financials.
The valuation for this sort of business is obviously not going to be cheap and the P/E ratio on forecast June 2023 earnings is c. 25x.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Equals (LON:EQLS) Seems to be a lot of angst today about capitalisation and the relevance (or lack of) to an ebitda number.
The company capitalises about the same as the depreciation number so the incremental effect going forward is no more than marginal.
The more important thing to look at in my view is the cash. Company now generates £1m p/m of FCF and this is growing. By year end it will also have circa 15p of net cash. Even if we conservatively assume no further growth in cashflow this year then the company is actually trading on circa 10* generated cash (if we strip out the net cash position).
I think that is a better way of looking at whether the share price supports the valuation since it's pretty clean. Then you can more easily factor in growth and its impact on forward earnings.
Spot on David. Cash is King.
CMC Markets (LON:CMCX) have just issued a trading statement, does not seem that good, shares are down 12%.
Really don't like it when companies do that - why can't they announce at 7am like everyone else? Not a fan of CMC either - they have a history of putting out nasty surprises. The spread betters do seem to be facing more challenging conditions generally, which I suspected would be the case as easy money is withdrawn.
CMC Markets (LON:CMCX) have just issued a trading statement, does not seem that good, shares are down 12%.
I don't know if I'm misreading it, but at a quick glance it looks like operating profit will exceed forecasts. If so, presumably it was the following which spooked the markets:
"February and March posed a more challenging environment with lower equity volumes and a higher proportion of lower margin institutional trading activity."
Doesn't take a great deal to cause a sell off right now.
timarr
Yes particularly when they announce it at 4pm!
You could be right, I did not have time to study it.
Very poor form, issuing it at 3.50pm. I thought it was a profit warning.
Shares closed down 21%, will see what happen tomorrow.
CMC Markets (LON:CMCX) I thought I remembered them doing this before. They issued one in 2019 at 14:21. Same reaction.
CMC Markets (LON:CMCX)
Very poor form, issuing it at 3.50pm. I thought it was a profit warning.
According to a friend, it is, I was skimming.
I've been told that some companies do these late RNSs to avoid internal leaks - i.e. they announce as soon as they know, even if late in the day - but it doesn't inpire confidence.
timarr
"Bottom line for this 100-bagger - it's all about backing great management, with a good strategy. Then holding, regardless of valuation & mishaps along the way. And just being lucky!"
Thank you for the musings on [Judges Scientific](https://www.stockopedia.com/pe...) (LON:JDG). It will always be the question - can you screen for 100 baggers, buy and hold on for dear life or is it 90% luck.Ian Cassel wrote a good article titled "The Patience to Hold " (though I can't find it now) and David Gardner (Motley Fool) talks about having a policy of never selling, which is why he has held Amazon since the low single digits and Nvidia from similar level. But after picking a possible winner you have got to have the stomach for it. Just in the last 18 months NVIDIA (NSQ:NVDA) has dropped 60% in 12 months and then subsequently gone 2.5 times in less than six months. I hold both but not from single digits unfortunately.
I think it very hard to pick and then stay with 100 baggers and will put it down to luck for most people. I am still waiting for my first 10 bagger.
Regards
Michael
I wonder how much of choosing a 100-bagger is simply down to going with your gut? I don't think any amount of research can tell you just how well a company will perform, despite what forecasting might show. I've had a couple 5 and 10 baggers, but I wouldn't dare suggest that it was because I could really anticipate how high the share price would go.
100 bagging is partially about making good choices and partially about patience.
Obviously you have to pick the right stocks but then, at least according to Christopher Mayer, who wrote the original book on 100-baggers, you have to wait an average of 26 years.
I imagine a lot of investors can select the right stocks, but I doubt many will be prepared to hold for that length of time, through thick and thin.timarr
Podcast 'The Fund Your Retirement' with Lee Cleasby, chatting to Chris Boxall of Fundamental Asset Management and director of Investors Champion (yet to look it that up so not plugging).
Interesting comments on bullish CEOs, some of whom are more city promoters and financial engineers rather than know having worked at the coal face. Those that have are worth listening to.
Also that AIM are not mega cap global IT cloud $b in the making - pretty much all that is known is known, and if have a niche or new spin then will get hoovered up by a bigger beast, venture capital etc. So maybe no longer 100 baggers or less out there, maybe 10, but something that actually works and someone will want to add to their existing IP.
Noted Somero and Wall St perhaps not interested in a concrete levelling gadget so ended up on AIM.
Podcasts are great - just got into thanks to Mr Scott - a mine of information. At least half dozen quality pods on the mining space and amazing insights. Some selling their wares but you can learn a lot on the free stuff.
Bought my first gold coin from Hattonsoflondon - a 2023 King Charles III Accession One Eighth Sovereign for £69 (apparently worth £149 - gets you in the door of course and immediate ok box sets, but hey ho, happy to start the bullion journey. One per household so don't get greedy. Gold will be higher at some point so to me a no brainer when cash is becoming a bit less robust, shall we say.
I have first hand knowledge of a multi bagger which is staggering. A £400 holding of the Danish medical devices company Coloplast A/S (CPH:COLO B) bought 40 years ago in February 1983 and if held continually through multiple bonus issues would be worth at todays closing price in excess of £750K. At its recent peak in August 2021 the value would have been in excess of £1m.!! . That is many times more than a 100 bagger. Sadly I have only held since 2013 and have top sliced since then leaving me with a holding of c. £10K. In that time it is only up c. 3x.
Agree Mr ACounsell posted and then read. But I'm of an age where I need some big wins now and can transfer onto those left. There must be ways to put into early starters for the early starters - and protect it from their parents meddling - and one day they get the letter through the door and - OMG Grandpa/Grandma - Grump for short - not there to see it but - that is not the point.
Bioventix (LON:BVXP) (I hold)
I was pleased to see the numbers this morning, but then found myself questioning the growth. While EPS is up on H1FY21, it's down on H2FY21 (0.9 so 20%). While there has been an H2 weighting since 2020, it looks like this was due to a gradual improvement as we came out of the pandemic disruption. Historically, I can see no H2 weighting and don't see anyreason why there should be going forward.
The consensus EPS estimates on stockopedia show 152. If there is no H2 weighting this year, then it looks like they will miss forecasts.
I'm somewhat tempted to sell out for now and wait for further news.
Bioventix (LON:BVXP) (no position)
Hi Glorenfeld
There was a H2 weighting pre-2020.
Cheers
A
Hi Abtan,
The income statement on stockopedia shows very little weighting at EPS level
Bioventix (LON:BVXP) (no position)
Hi Glorenfeld
I don't look at EPS, but from the screenshot it looks as though it only includes 2 pre-covid years:
Excluding this anomaly, revenues, and probably EPS, were H2 weighted in this time period, as per my screenshot.
From your screenshot, EPS from 2020 onwards also seems to show a H2 weighting.
Hi Abtan, yes it is only two periods pre COVID. You may well be right that H2 weighting is the more usual position for Bioventix (LON:BVXP) . The market certainly seems to have reacted well to today's update.
Simon Thompson at Investors Chronicle reiterates his BUY rating on Equals with a 144p/share price target.
https://www.investorschronicle...
Thanks Paul for the Equals (LON:EQLS) analysis. I am not sure I have sufficiently investigated their performance before investing. Why are they capitalising payroll costs, I wonder? Are these costs relating to Software Development.
Whilst it is legitimate to capitalise such costs, they may be an ongoing cost to the business, and as such are really an overhead (unless there is defined period of development) so don't really regard this as a capital item myself.
That said unless they grow like topsy, it could be with increasing revenues they will diminish as a proportion of revenues.
Here's my thoughts Trident. I've owned shares in EQLS for 3 years & Canaccord have just upgraded their forecasts & Price target to 164p/share
https://www.linkedin.com/posts...
Hi Paul, just watched, and thanks for that. One thing I’d like to ask, as it wasn’t mentioned during the 25 min chat, is the earnings per share.
Can someone give me a steer on the EPS situation for Equals? Looking back 6 months, forecasts for EPS were 4.6p for 2022 and 6.2p for 2023. They were then revised to 3.93p for 2022 and 5.07p for 2023. Actual EPS for 2022 have come in at 1.73p reading todays update.
Another question that wasn’t asked (unless I missed it) is why is the acquisition being funded with share issues rather than the cash pile?
Any help on these queries would be much appreciated. Thanks.
On the IMC presentation this evening I asked why the deal was funded in shares. Basically CEO wanted to lock in the sellers and tie them to performance of the group, particularly as there is an European e-money licence involved, Belgian regulatory approval required and strong European expansion rationale.
The dilution is less than 3% so on balance whilst they generally prefer to do the deals in cash this one was a little different.
Thanks Paul. What's your view on the capitalisation issue? Clearly you take a positive view on the stock
It's a total Red Herring.
2022 capitalised R&D was £4.6m vs the £4.4m of internally generated amortised R&D.
Minimal overall impact (ie +£0.2m) to the adjusted EPS numbers.
Pebble (LON:PEBB) FY22 management presentation from last week video & podcast.
It had a strong run into results but it's a nice business. Interesting to see how the promotional products industry is so strong, also endorsed by 4imprint (LON:FOUR) FY22 recently.
Hi
Sigmaroc (LON:SRC) audited results, extract from the paper (below).
I am not sure I fully appreciate the implications of all the footnotes, particularly No. 1. Does this imply a bunch of costs will be coming into the 2023 figures so in effect these 2022 figures are over stated?
Any comments from more informed investors, or Graham/Paul, gratefully accepted?
(I have small holding and have followed Sigmaroc (LON:SRC) for quite some time).
SP up only +0.33% as I type. It seems the market has fully digested their 31st Jan TU which presented the unaudited figures then and so these audited results have not suggested a reason for further SP moves.
Full audited results report is here .......
https://uploads-ssl.webflow.co...
Regards
Howard
Sigmaroc (LON:SRC) I too would be interested in understanding this. The directors bought/took up rights to £1.1m in the space of a year. On the stated figures it should be doing well, it's just whether the figures are saying what i think they are saying is the issue.
Hi Funnymoney
I have followed Sigmaroc (LON:SRC) since their early days and bought/sold at stages along the way. My general assumption is that they seem to be quite transparent, a quality management team and executing a sensible strategy well.
This is the second time they have presented something which has raised an eyebrow for me.
The first being the recent £30m placing (21/2) which, to me, seemed to have been done for the benefit of institutions and not the loyal private investors who had supported them over the years.
Based on these observations, I hope a less satisfactory culture has not crept into them as they have expanded. It's just my personal opinion/observations though.
Regards
Howard
Many thanks for your thoughts on Belvoir (LON:BLV) Graham. Glad to read your positive view, which as a somewhat biased holder I agree with.
re: £BLV
You're welcome jonno! Good luck. G
Somewhat curates egg from Pressure Technologies (LON:PRES) . A substantial order for its Precision Machined Components division, which appears to be in full recovery mode and follows on the £18.2m order for the Chesterfield Special Cylinders division in February.
Richard Staveley manager of Rockwood Strategic IT, part of the Chris Harwood stable has taken a seat on the board as a non executive director. Rockwood Strategic own 20% of Pressure Technologies (LON:PRES) This followed the anticipated and now confirmed delay of the full year results due it is reported to revenue recognition issues. The shares are to be suspended from 3rd April and anticipate relisting by the end of the month
Grant Thornton are the auditors who have hardly covered themselves in glory in recent years, if memory serves me right they were the auditors to Patisserie Valerie? They are now perhaps trying to distance the Patisserie Valerie debacle by ensuring audits 'are on the money'. No pun intended.
On a more straightforward note, creditable results from Belvoir (LON:BLV. I very much like Dominic Gonsalves and the management team.
I hold an opening position in Pressure Technologies (LON:PRES) and have a larger holding in Belvoir (LON:BLV).
Any thoughts Paul/Graham?
Belvoir (LON:BLV) also worth noting that this had hugely lagged Foxtons (LON:FOXT) and Property Franchise (LON:TPFG) recently, both of which have seen a big bounce over past few months - can't see any logical reason for this so Belvoir has to be a good trading opportunity if nothing else (although I think it's a good solid business too, so happy to treat it as long term holding).
Equals (LON:EQLS) prelims today, wow they really want our attention on the adjusted EBITDA figure don't they ! Good results but EPS coming out at 1.8p against a forecast 3.93p gives a p/e of nearly 50x - ouch ! Nice business and nice 'ahead of' outlook too, but they need some serious growth this year to justify this p/e...in my view of course !
Equals
The very good thing is they are clearly now into the phase of the business where they are generating cash .
Not sure why they would finance an acquisition with shares whilst sitting on an 18 million cash pile, there is a 2 year lock in so keeps the Belgians motivated .
Valuation high but all moving in the right direction and the fact it is now spitting out cash is good
Equals' cash flow has averaged £1m/month so far in 2023. Which on a £160m mrkcap business represents an annualised 7.5% yield. For a company also growing sales at 50% YoY.
I am a holder of Equals (LON:EQLS) but have not yet committed what I regard as a full holding. My hesitance is that, as with all these payment companies, there is no doubt that the market is growing fast but the margins available continue to decline making this a difficult business.
In todays announcement we see a table showing the Gross Margins and a statement that they are improving. However still the largest part of the business by revenue is International Payments and margins on that continue to decline. The Solutions and Card businesses have ridden to the rescue, so for the future we should expect too see a company with a significant change in its character and not so much a payments business.
The rise in staff costs is also quite significant, especially if the capitalized amounts are added back, rising in total from £14.9 mm to £18.5mm, £4.2 being capitalized in 2022.
It is good that they seem to be moving forward but I would like to see them get a bit further ahead before I go larger.
Hi trueagent - please read davidjhill's comments above for a better perspective. Cash is King
Hi Paul any further thoughts on Tortilla Mexican Grill (LON:MEX) who have an update today? I remember you visited the company in February & were generally positive. ..although I notice forecast EPS is heading the wrong way..
Thanks for flagging Tortilla Mexican Grill (LON:MEX) - yes I'll take a look at that, and report back.
There's an InvestorMeetCompany webinar this afternoon at 16:30 I see.
Tandem Group (TND)
Horrible results .
Balance sheet is super strong but that is based on the freehold etc and new warehouse .
Cash has evaporated due to new warehouse .
Interestingly stock level looks ok as only 4 million so looks like they have not got an over stock issue which is very good .
I would estimate they will swing to a 1-2 million loss this year .
Good points - great balance sheet and stock level not excessive
Bad points - moving to loss making and moving from net cash to debt .
It’s an Iron Maiden share right now
Run for the hills .
Wasn't this a ST from IC share tip a while back - has he gone cold on it as well?
Interesting.. green light from Graham, 'run for the the hills' from planetx. Valuation now 50% of NAV, P/S 0.5x. What to do ? (I hold). Reckon I´ll just hang on for the divi and hope the winds change direction in due course.
Thanks to planetx for the comment re: TND (and I believe he is extremely well-qualified when it comes to this share).
I do have mixed feelings on TND but I said last time that the new CEO might be worth backing. I don't think I should change my view until/unless it's confirmed that the company remains of the same poor quality as it was under prior management. G
Graham
Not heard great things about new CEO , an industry journeyman who has no record of producing shareholder wealth let alone running a PLC.
In fact I heard the opposite of good things .
Industry is in meltdown .
Tandem is super cheap valuation so hopefully the cash losses in the next 2 years don’t eat into the balance sheet too much
Can’t see how that won’t happen .
Hard to beat a falling tide .
Equals Group (LON:EQLS)
Excellent FY update and outlook statement.
Management now expect trading for FY-2023 to be ahead of current expectations and it's only March.
FY22 rev + 58%
All about Q1 23 & outlook
Q1 23 Rev £20.2m (£13.2m) +54%
Q1 23 £342k/day (Q1 22 225/day)
Q4 22 £302/day
Cash up at £18m
Also announces bolt-on with potential to expand into Europe and disposal.
I have a large position and am vey pleased with the strategy and results.
Investegate |Equals Group PLC Announcements | Equals Group PLC: Final Results
Thanks for Saturday's double-helping of the small cap podcast Paul.
The double format worked well, delineating your reflections on company updates and readers comments from broader market and macro commentary. These are always interesting, providing perspective and a dash of welcome humour. Thanks for taking the time.
Agree with that. I liked having the separate podcast on macro comments, as I often skip ahead to that bit when I am short of time.
Hi, TheJayman (and PatrickL),
Many thanks for the podcast feedback. I agree that it's best to split them into 2, one for companies, and one for macro/markets news & views. Also it's less rushed then, and I don't have to do a hard stop around 30-40 mins, depending on which computer I'm using, as the file size becomes too large to upload into Wordpress. Although it did let one slip through that was 30.1Mb, when the max file size is supposedly 30.0Mb, to my enormous relief!!
Must admit I really enjoy doing them, and seem to have a small but perfectly formed audience, so is worth continuing! Just wish my throat would stop clenching up, which always happens the moment I start recording, and have coughing & burping fits!!
:-D
Best wishes, Paul.
CEO buys almost £50k worth of stock in £MTC! Shares have been in the doldrums for quite a while. Perhaps a turnaround is on the way.
https://www.investegate.co.uk/...
My morning smallcap tweet: Slick operation or sick corporation
Tandem (LON:TND) Pressure Technologies (LON:PRES) Nuformix (LON:NFX) Aiq (LON:AIQ) CML Microsystems (LON:CML) Renalytix (LON:RENX) ImmuPharma (LON:IMM) Tristel (LON:TSTL) Invinity Energy Systems (LON:IES) EQTEC (LON:EQT) Inland Homes (LON:INL) Belvoir (LON:BLV) Northamber (LON:NAR), CentralNic (LON:CNIC), Severfield (LON:SFR), Hyve (LON:HYVE)
◄Tandem (TND)► FY-Dec. Outlook clicks down a gear: sales slow, as expected. Also "significant number of delays with our goods passing through UK ports due to additional custom checks, further impacting Q1". [SP=229 Cap=13m]
◄Pressure Technologies (PRES)► £3m order, underpins FY23 outlook and gives substantial order book coverage for FY24 H1. But a separate RNS delivers the kidney punch: won't get FY22 accounts out in time so shares will be suspended on Apr 1. As announced delay is due to adjustments re accounting treatment applied to long-term defence contracts in FY22 and in prior periods to FY19. [SP=45 Cap=17m]
◄Nuformix (NFX)► good result from studies of NXP002. [SP=0.44 Cap=3m]
◄AIQ (AIQ)► $459k contract to set up a virtual datacentre; to be fully delivered in approximately seven months. [SP=4.95 Cap=4m]
◄CML Microsystems (CML)► guides FY-Mar in line. Completes sale of a £2m parcel of its spare land. [SP=539.05 Cap=85m]. I hold.
◄Renalytix (RENX)► adds 3m people to insurance coverage base in US for KidneyIntelX. [SP=84 Cap=79m]
◄ImmuPharma (IMM)► Lupuzor Phase 2/3 clinical trial protocol has now been submitted to the FDA. [SP=1.76 Cap=6m]
◄Tristel (TSTL)► submitted the additional data requested by the FDA for Duo ULT high-level disinfectant. A decision is expected before 30 June. [SP=324.5 Cap=154m]
◄Invinity Energy Systems (IES)► 1.5 MWh battery sale in Hungary. "The contract was included as part of the Company's Base category in its most recently disclosed commercial pipeline." [SP=30.8 Cap=59m]
◄EQTEC (EQT)► project for waste-to-RNG plant in France. Expects financial close in H2 2024 with the Plant completing construction and commissioning by early 2026. No £££. [SP=0.2 Cap=19m]
◄Inland Homes (INL)► troubled tinpot builder signs contracts to sell 31 affordable homes to Eastlight Community Homes for £6.54m. Completion will take place in phases over the coming months. [SP=5.27 Cap=12m]
◄Belvoir (BLV)► FY-Dec rev in line, pretax £9.1m ahead of management's expectations. [SP=169.5 Cap=63m] I hold.
◄Northamber (NAR)► H1-Dec rev up 4% ut op loss £250k (£116k) due to inflation. [SP=41 Cap=11m]
In line: CNIC, SFR, HYVE
Thanks for these summaries - always really helpful and very much missed when you're not here.
CML? Thoughts on JNEO?
Good set of interim results from Bioventix (LON:BVXP) this morning returning great dividends for shareholders (of which I am one).
Highlights
· Revenue up 25% to £5.9 million (2021: £4.7 million)
· Profit before tax up 27% to £4.5 million (2021: £3.6 million)
· Closing cash balances of £5.2 million (2021 £5.1 million)
· Interim dividend up 20% to 62p per share (2021: 52p)
Bioventix (LON:BVXP) - Interims notable for unusually (for Peter Harrison) upbeat language re Alzheimer's research. And pyrene detection - as a result of exposure to fires.