Small Cap Value Report (Mon 27 Nov 2023) - D4T4/CLBS, FDEV, EPWN, SYS, CNC, MMAG

Good morning from Paul & Graham!
Today's report is now finished.
Mello Chiswick - it’s this week, Wed 29 & Thu 30 November. It’s an absolutely superb line-up of high calibre speakers this year. Also a great social event, where we enjoy chatting to pretty much everyone in the bar over the course of the evening, so if you’re there, do say hello. Everyone on the Stockopedia team loves to meet subscribers in person. We've roped in Roland to provide some cover here, so that people not attending Mello won't lose out with substandard SCVRs.
++ BREAKING NEWS ++
Musicmagpie (LON:MMAG) announces that both named potential bidders, BT and Aurelius have stated they do not intend to bid for MMAG. It continues to seek buyers, and this is looking increasingly like a desperate, rescue or bust type of situation. I was already RED, because the business model doesn't work. I think equity could easily be worth zero here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries -
D4t4 Solutions (LON:D4T4) / £CLBS - 176p (pre-market) £70m - Interim Results - Paul - AMBER/GREEN
H1 results as expected, and it sounds fairly confident in meeting full year expectations too. I raise a query on its revenue recognition and receivables, which look very unusual to me - almost all H1 revenues seems to have been billed at the end of the period, and not yet paid by customers. Other than that query, I have a generally favourable view of this business, at £70m market cap it could end up being bid for maybe?
Frontier Developments (LON:FDEV) - down 19% to 158.6p (£63m) - Business Update (profit warning) - Graham - GREEN
This video game developer offers yet more bad news with another profit warning taking the share price lower again. The shrinking cash balance is now almost one third of the market cap as the company goes back to its original, focused strategy. A highly contrarian pick.
Epwin (LON:EPWN) - up 6% to 71p (£102m) - Trading Update (in line) & Buyback - Paul - AMBER/GREEN
A remarkably perky update today, and it's going to start £2m share buybacks, on top of a generous (and twice covered) c.7% dividend yield. How come Epwin is baulking sector trends? Looks very interesting, worth a closer look I think, but I'm wary of macro.
SysGroup (LON:SYS) - down 4% to 38.25p (£19m) - Half-Year Report - Graham - AMBER
This managed IT services company announces that it’s embarking on an artificial intelligence/machine learning strategy, hoping to help small and medium enterprises to use these new technologies. I wish them good luck but would be in no rush to buy in here.
Concurrent Technologies (LON:CNC) - up 4% to 75p (£64m) - Trading Update - Paul - AMBER/GREEN
A rather gushing update today focused too much on revenue growth, but is only in line with 2023 market expectations for profit (although after a big rise in July). Some slippage of orders into 2024. Very upbeat about growth & pipeline, so it still looks good to me. Although I'll want to scrutinise cashflow and balance sheet carefully when the FY 12/2023 results come out.
Paul’s Section:
D4t4 Solutions (LON:D4T4) / £CLBS
176p (pre-market) £70m - Interim Results - Paul - AMBER/GREEN
Celebrus Technologies plc (AIM: CLBS, "the Group", "Celebrus"), the AIM-listed data solutions provider, announces its half year results for the six months to 30 September 2023 ("H1 FY24").
We looked at Celebrus (new name), D4T4 (old name) quite recently on 31 Oct, when it issued an in line H1 update, my thoughts being -
AMBER/GREEN - In line update. H2 seasonal weighting. Loads of cash. Maybe bid target? Tough macro might make pipeline tough to convert? (SCVR 31 Oct 2023)
Today's news -
H1 revenue jumped from £8.1m H1 LY, to £13.0m this time, but don’t get excited because a lot of the increase is low margin pass-through hardware sales.
Adj PBT is £0.2m, improved from a loss of £(1.3)m in H1 LY.
Note there’s a heavy H2 seasonal bias to profitability, which is normal for this company.
Cash remains healthy (and no debt) at £14.7m, although that’s down from 6 and 12 months ago.
Outlook sounds OK -
Solid progress in the first half and the high visibility of opportunities expected to close in the second half underpin the Board's confidence in both achieving full year market expectations*** and continuing to drive growth in ARR.
*** For the purpose of this announcement, the Group believes market consensus for FY24 to be revenue of £32.1m, and adjusted profit before tax of £5.4m.
Year-to-date progress and the high visibility of opportunities expected to close in the second half underpin the Board's confidence in achieving full year market expectations and the continued growth in ARR.
Bill Bruno, CEO of Celebrus, commented:
"Several key steps have been taken to further our strategy in the first half of the financial year. Not only have we delivered the expected results and continue to remain confident in our ability to meet market expectations for the full year, but we have continued to invest in Sales and Marketing and are seeing the positive effects in the form of building pipeline momentum. A key investment at the beginning of the year was in Customer Success, and we have now built a Sales and Marketing machine that can focus on winning and expanding those wins as we land them. We continue to focus on driving ARR and our ability to build scalable, single-tenant, cloud-based environments for our Celebrus customers."
As a Board we have aligned on profiles for potential acquisition targets that could provide good bolt-on technology to the Celebrus platform. While there is nothing imminent, we are making this more of a focus. As we began to sell more directly to customers, we soon realised that there would be more we would want to deliver for customers in the world of data activation. We will continue to explore this prudently.
The big H2 weighting does tend to make H2 a nail-biting time for Celebrus shareholders, but it has a good track record of delivering, or at worst seeing a delay if deals slip past the year-end.
I'm not too keen on the talk above about possible acquisitions. Doesn't that imply the Celebrus product isn't giving clients enough of what they want? Or that management may not be that confident about the growth potential of its core product? Don't shoot the messenger, I'm only asking questions.
Annualised recurring revenue is important here, although as with a lot of SaaS companies, they still need high margin additional revenues to hit forecasts -
Annual recurring revenue ("ARR") increased to £17.4m (H1 FY23: £15.8m, FY23: £16.7m)*
Balance sheet - my usual checks for financial health. Overall it’s strong, with NTAV of £16.5m. Remember software companies don’t need a big asset base, as they typically get paid in advance of providing services, and have few fixed assets. So this is more than adequate.
Receivables has ballooned, from £7.6m at 31 March, to £17.3m at 30 Sept 2023. That looks very peculiar. Note 7 shows trade receivables of £13.9m, which is crazily large, as H1 revenues were £13.0m. So it looks as if almost none of the revenues booked in H1 have actually been paid for by the customers! The commentary says this -
Trade receivables at the period end were £13.9 million (H1 FY23: £1.8 million); the majority of these result from contract wins and invoicing towards the end of the period. In relation to certain of these contracts, especially those with a third-party hardware component, trade creditors were £5.3 million (H1 FY23: £0.2 million).
The Group has no overdue receivables of any significant size, and no bad debt losses have been recorded in the period.
We have to trust management that the numbers are real, and haven’t been manipulated, with almost all the H1 revenues being booked at the last minute, that certainly raises questions for me. I’m not suggesting anything is wrong, just flagging that this looks unusual, and needs explaining. I would have expected revenues (especially the significant recurring revenues) to be booked monthly throughout H1. Not almost the whole lot booked at the end of the half-year, and hardly anything collected in cash. That doesn’t make sense for a recurring revenues business, surely?
Despite not getting paid by its customers in H1, Celebrus still has a very healthy cash pile of £14.7m, which should go up once customers pay up.
Note that creditors have gone up a lot too, in particular the new deferred income line in long-term creditors of £3.7m is unusual. So it looks as if a customer has been billed up-front for multi-year services, but hasn’t paid the invoice yet. If my reading of the figures is right, the double entry would be DR receivables, and CR deferred income - both balance sheet entries, so this won’t have had any effect on the P&L.
Paul’s opinion - I’m a little disturbed by the balance sheet movements mentioned above.
Everything else looks OK though.
Celebrus/D4T4 has always looked a promising company, and has a nice track record of profitability and cash generation. The trouble is that growth has been too pedestrian to keep investors excited, so the valuation has drifted down, along with lots of shares in this 2-year small caps bear market.
Could Celebrus be a good stock pick for a recovery or a takeover bid? At £70m market cap, I think risk:reward looks pretty good actually, so I’ll remain at AMBER/GREEN.
Although I’d like more detailed explanations of the peculiar balance sheet movements, and why apparently almost all of H1 revenues got billed at the end of the period and hasn’t been paid, when this is supposed to be a recurring revenues business?
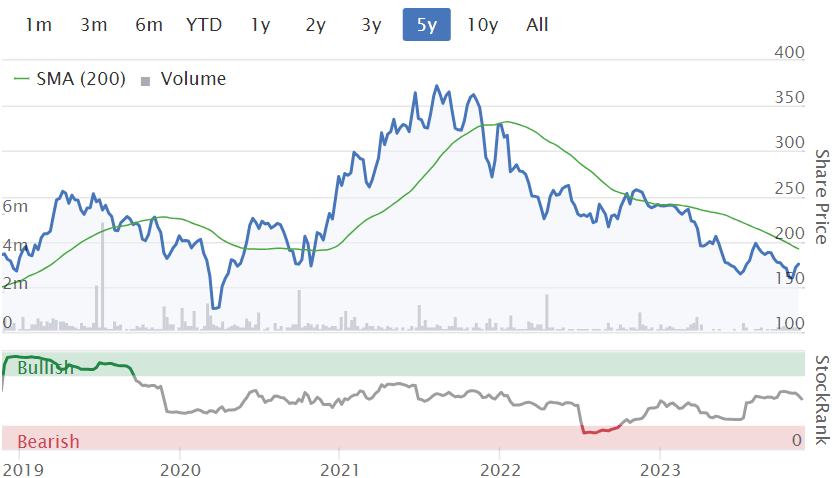
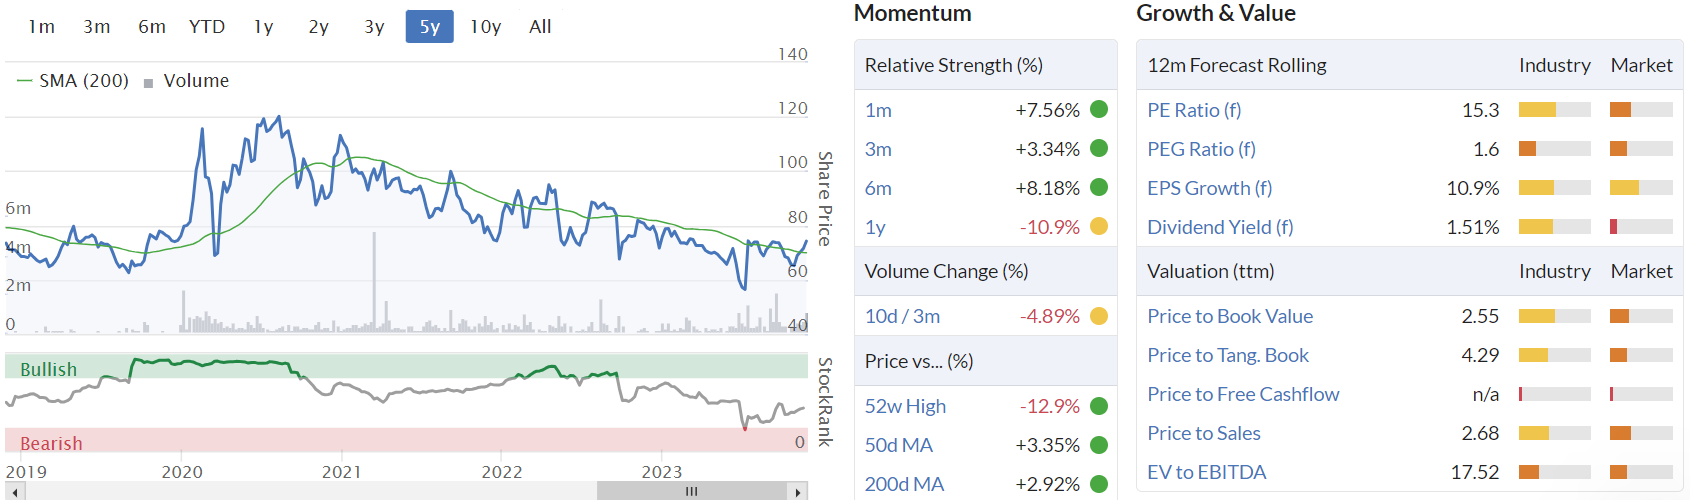
On a 5-year view, the share price has come all the way back down again -
Epwin (LON:EPWN)
Up 6% to 71p (£102m) - Trading Update (in line) & Buyback - Paul - AMBER/GREEN
This is only in line with expectations, but I’ve been wanting to refresh my view on Epwin for a while, as its value metrics are looking really attractive, and someone sensible (fund manager perhaps?) mentioned it on a podcast recently -
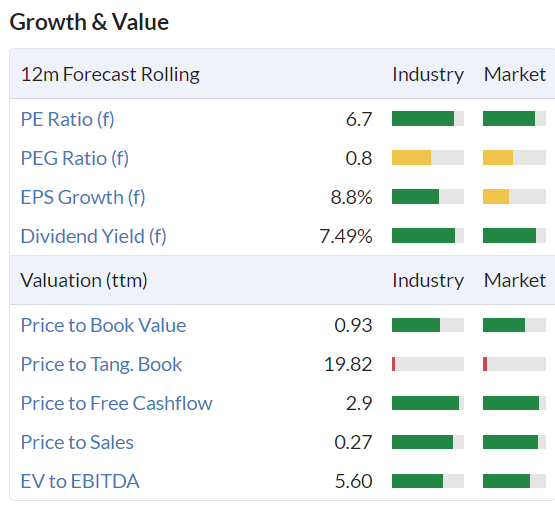
A PER lower than the dividend yield is often worth checking out, although it can also be a warning sign that something’s going wrong, and/or debt might be too high, and that the yield may not be sustainable at that level. So everything needs to be carefully checked, especially with smaller caps where information can be scarce.
Looking back at our archive, we’ve rather neglected Epwin this year, with the only coverage being on 4 April 2023, with Roland concluding AMBER at 72p per share (almost identical to today’s 71p), saying that FY results were solid, and it might be good value, but macro factors present the main risks.
Today’s news is an FY 12/2023 trading update, and news of a new share buyback (usually a good sign).
Epwin Group Plc (AIM: EPWN), the leading manufacturer of energy efficient and low maintenance building products, with significant market shares, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors is pleased to announce a trading update for the second half of its current financial year (FY 2023) to date
This is worded very well I think, giving us the information we need (although I would prefer adj PBT, rather than operating profit) -
On track to meet FY 2023 expectations; continued strategic progress
Trading in the second half has been resilient, despite the more variable end-market conditions widely reported across the UK construction sector in September and October 2023. The Board remains confident of achieving FY 2023 underlying operating profit ahead of the prior year and in line with market expectations (company compiled analyst consensus of £24.0m).
Bear in mind that the market cap is only £102m, so an operating profit of £24m is impressive. What’s the catch then? And how come it’s performing fine, when the sector is struggling?
These factors seem to have helped -
The Group has made good further progress with its strategy, including continued operational improvement, new product development, integrating recent value-enhancing acquisitions and sustainability. The medium and long-term drivers for the Group's products remain positive.
Interim results - to June 2023 look good, and it achieved £11.9m H1 underlying operating profit, so guidance today is for a very slightly better H2, to do £24m FY op profit.
H1 adj PBT was £8.7m, so that’s a £3.2m shortfall between op profit & PBT. Assuming that remains the same proportion for the FY 12/2023, this implies about £17m adj PBT this full year.
That’s about 9.7p adj EPS, giving a PER of only 7.3x (an earnings yield of an attractive 13.7%), with about half earnings paid out in divis (forecast 4.75p divis, a yield of 6.7%).
Is the balance sheet over-geared? In a word, no! More details -
It’s not great, with only £5m NTAV. Clearly there have been substantial acquisitions over the years, as it’s dominated by £99m goodwill and similar at the top.
Note that lease entries are quite large, and show a deficit (RoUA: £70.6m, liabilities £93.3m), so a good question to ask management would be to expand on excess/loss-making leases, which they clearly have.
There’s £7.8m in deferred consideration that will have to be paid - not excessive, but it’s cash out of the door in future.
Bank debt is £26m gross, £13m net of cash - that looks fine, providing future profitability remains as buoyant as it has proven in 2023. Covenant net debt was a modest 0.6x EBITDA at the interim results.
Overall then, I think the balance sheet is adequate, but not strong. Gearing is not a worry to me, and bank debt looks fine, it’s not excessive.
Cashflow statement - operating cashflow looks amazing, but it’s overstated compared with reality, due to lease costs being lower down, as annoyingly required by bad accounting standards.
Overall though, it looks a decently cash generative business, which is using its cashflows to pay divis, fund capex, and make acquisitions.
Share buyback - this is music to my ears. I wish more companies with bombed out share prices would do buybacks -
The Board considers that the Group's strong balance sheet and cash generation provides the opportunity to take advantage of current market conditions to repurchase shares at attractive levels. The Board takes a disciplined approach to investment, returns and the capital efficiency of the Group, in order to maximise shareholder value. The Group intends to return capital to shareholders both by way of the Company's on-going dividend policy and the buyback programme, alongside the Group's continued investment in its strategy….
The Programme will not impact the Company's existing dividend policy.
Even better, looks like the divis are safe, with buybacks on top. Very nice!
It’s about £2m-worth of shares to be bought back in the market by Shore Capital -
intends to commence a share buyback programme (the "Programme") of up to 3 million ordinary shares
Paul’s opinion - I’m really impressed with this update.
I don’t really understand how Epwin seems to be shrugging off tough sector conditions, so that is my main query. My worry is that sometimes companies can continue performing well in a tough sector for a while, but gravity catches up with them usually once the order book has been worked through. So good performance now does not guarantee continued good performance in 2024 and beyond. Similar to what we’ve been saying about the structural steel companies in recent updates - good so far, but what happens next?
Overall though, it’s difficult to ignore this solid update in tough times, and the generous dividend income stream for investors (enhanced by the £2m buyback). So I think it’s only fair to up our view here from amber to AMBER/GREEN. Not fully green due to macro factors, but it’s up to you to decide if the lowly valuation already factors in downside risk?
It would be worth readers considering the products that Epwin sells, and what competition there is? I do wonder if building supplies companies have benefitted from jacking up prices when supplies were in demand, and short supply, during the pandemic, so could face downward pressure on prices now that supply chains are normalising, from customers shopping around perhaps? Who knows, only time will tell!
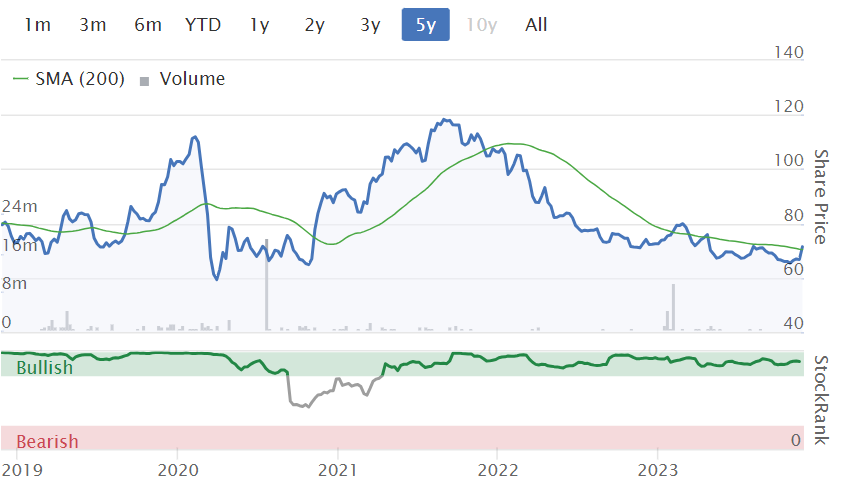
So many 5-year charts for small caps are looking almost identical aren't they! Here's another one -
Concurrent Technologies (LON:CNC)
Up 4% to 75p (£64m) - Trading Update - Paul - AMBER/GREEN
Concurrent Technologies Plc (AIM: CNC), a world-leading specialist in the design and manufacture of high-end embedded computer systems and boards for critical applications, is pleased to announce a trading update for the year ended 31 December 2023 ("FY23").
Checking our previous notes, I was bowled over by an excellent, ahead of expectations update on 7 July 2023, even making this share a podcast mystery share! (my favourite update of the week). Previous sins of sloppy accounting & late results, quickly forgiven.
Today’s update says -
Revenues ahead of expectations.
*Consensus revenue expectations for 2023 are £27m
Additional upside from acquisition of Phillips Aerospace.
Supply chain problems have “continued to ease”.
Strong order book from product development investment over last 2 years.
Larger orders, and more diversified markets.
Continued strong order intake, material revenue growth expected in 2024.
Multi-year pipeline of £100m revenues anticipated from recent design wins (albeit not yet contracted).
After all that bullish talk, what about profit then??! It’s in line, due to higher costs -
The Board are pleased to note that profit contribution has strengthened quarter-on-quarter throughout FY23, and it is anticipated that Q4 2023 will be the strongest quarter in an already record-breaking year. To position the business for the future, management have continued to invest in the operational scale of the Company to deliver an increasing level of revenue in the future years. Accordingly, the profit of the Company as a whole in FY23 is expected to be in line with current market expectations**.
**Consensus profit before tax expectations for 2023 are £3.5m
Order slippage - nicely finessed here! -
This increased level of performance across the Company has been delivered despite several larger multi-year orders, for which the Company has already been down selected, moving from the current year into FY24 due to customer timelines, further strengthening the conviction of management in the delivery of further growth in FY24.
Broker update - thanks to Cavendish for updating us. It’s leaving FY 12/2023 unchanged at £3.5m adj PBT, but there’s a small increase to FY 12/2024 to £4.3m, and FY 12/2025 to £5.8m.
In EPS, that’s 4.56p, 4.79p, and 6.26p.
The current share price of 75p seems in the right ballpark for now, I’d say.
Paul’s opinion - I find today’s update a bit too over-excitable, and would have preferred a more measured tone. It’s mixed too - lots of focus on revenue, but no change to (admittedly raised in July) 2023 forecast profit, and delayed order slipping into 2024 was rather glossed over. That said, delays being absorbed without a profit warning is good enough.
The commentary on product development, design wins, etc, all sounds encouraging to me, and is nice supporting evidence to expect continuing growth in revenues and profits hopefully.
The last balance sheet showed cash reducing, and inventories having built up too much. So when the FY 12/2023 figures come out, I’ll be looking for cash to have improved, and inventories under better control.
All in all then, I think this share looks good. I’m going to moderate to AMBER/GREEN, as I want to see cashflow and balance sheet improvements in the Dec 2023 figures first.
Graham’s Section:
Frontier Developments (LON:FDEV)
Share price: 158.6p (-19%)
Market cap: £63m
This morning brings more bad news for FDEV shareholders. There has been no shortage of bad news at this stock:
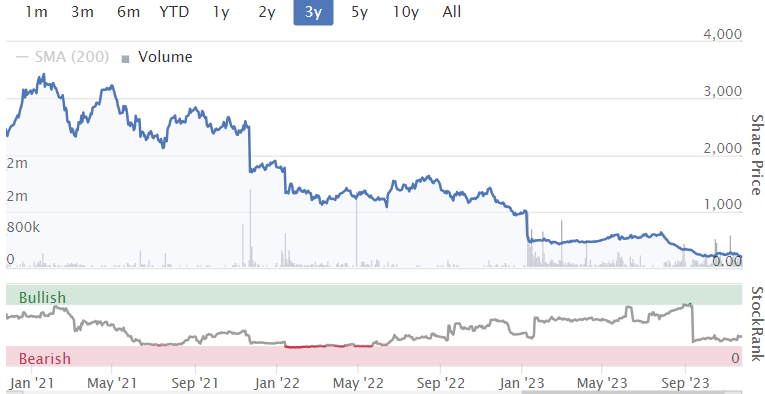
I turned positive on it on 19th Jan 2023, with the shares trading at £5.20 (vs. a peak share price of £32, and a current price of around £1.60). Despite letting the share price fall by over 80% before turning positive, I was still far too early!
Unfortunately, the company continues to struggle on the sales front: the new Warhammer game released ten days ago has seen lower than expected sales so far. This is on the back of FDEV’s first game in the F1 Manager franchise failing to perform to expectations.
Change of strategy - the company admits that attempts to diversify its games portfolio in the last five years haven’t worked, and it is going to refocus on “creative management solutions” (CMS) games.
These games “delivered stronger and more predictable returns through Frontier’s expertise and leadership in that genre”.
The Company's four CMS games (Planet Coaster, Planet Zoo, Jurassic World Evolution and Jurassic World Evolution 2) continue to perform well and have each achieved over $100 million of gross revenue with a combined total of over $500 million. All four games achieved profitability within one month of release and delivered over 100% return on investment within 12 months of release. The three games which have been in the market for four years or longer - Planet Coaster, Jurassic World Evolution and Planet Zoo - have all achieved a cumulative return on investment of over 250%.
The plan is to release a new CMS game every year for the next three years (starting in FY May 2025, not the current year FY May 2024).
Outlook
Next we have the revenue/profit warning for the current year:
FY May 2024 revenues now expected to be £80-95m, down from previous expectations of £108m. That’s a downgrade of up to 26%.
The previous expectation of a £9m adjusted EBITDA loss “remains achievable towards the upper end of revenue guidance”, thanks to cost savings and an improved gross profit margin. We discussed the company’s planned cost cuts last month.
For FY May 2025, the company is expected to “at least break even”.
Graham’s view
The reasons I have been positive on this share in 2023 are 1) a healthy balance sheet, 2) a cheap price to sales multiple for a videogame developer, 3) the possibility that in the medium-term, its run of poor title launches could come to an end.
Today the company announced that its cash balance finished October at £20m. This is down from £28m as of May 2023 - the company is loss-making, so this is hardly a surprise.
They are currently in cost-cutting mode, with a recruitment freeze and staff redundancies.
Let’s keep a watchful eye on the cash balance, but I am hopeful that they can stop the bleeding soon. They do think that FY 2025 will be “at least break even” (possibly at the adjusted EBITDA level).
I note that joint corporate broker Liberum have put their target price, recommendation and forecasts under review - so I don’t have access to any broker forecasts as of this morning.
On balance, I think the “healthy balance sheet” still holds, providing that the company does stop the bleeding in the next 6-12 months. The October cash balance is nearly one-third of the current market cap.
Price to sales ratio: this is currently about 0.65x-0.80x, depending on where the current year’s sales figure eventually ends up. This remains extremely low in a video game context (Team17, covered by Paul on Friday, has a price/sales ratio of 1.7x).
If you are willing to deduct the cash balance from the market cap and use enterprise value, then the EV/sales ratio for the current year is in a range of 0.45x-0.55x.
So the healthy cash balance and the cheap price to sales ratio are still in place.
The great imponderable factor, then, is whether the company’s run of poor launches can come to an end.
I would argue that today’s announcement does improve the likelihood of this happening: they are going back to their bread and butter with the development of titles in the genre that has worked out well for them in the past (with the likes of Planet Zoo and Jurassic World Evolution). Surely this strategy is the most likely to see them return to their previous levels of financial performance?
I am therefore going to leave my positive stance on this share unchanged.
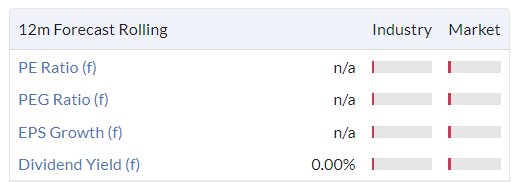
However, I can completely understand if most people would prefer to avoid a share with valuation metrics that looked like this:
(Paul adds: this is a rare occasion where Graham and I disagree! But that's fine, it would be a bit odd if we agreed on everything, and we encourage everyone to DTOR and form their own opinions. Graham's explained it all well, but for me, the overall balance would be more like AMBER/RED, to reflect very poor performance, and having to go back to basics after a failed strategy to diversify. The cash pile looks likely to dwindle, as it sorts itself out. Also, I'm not a fan of price to sales ratios. I'm happy to eat my hat, once it rebounds!)
SysGroup (LON:SYS)
Share price: 38.25p (-4%)
Market cap: £19m
SysGroup plc (AIM:SYS), the end-to-end data solution provider, is pleased to announce its unaudited half year results for the six months ended 30 September 2023…
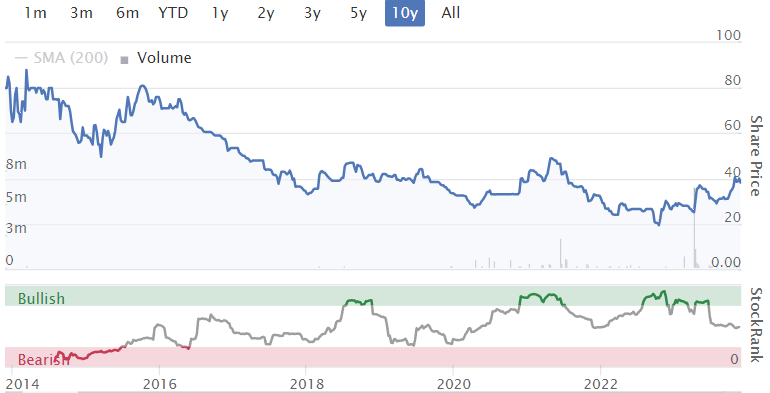
After many years of poor share price performance, perhaps this one has found a base?
Let’s check out the highlights for these interim results:
Revenues down 3% to c. £11m (Paul reported on fast revenue growth at the most recent full-year results, but this was mostly thanks to prior acquisitions).
Adj. EBITDA £1.6m (H1 last year: £1.7m)
Pre-tax loss £1.09m (H1 last year: pre-tax loss £0.19m).
Net debt £3.4m
Not a very inspiring set of highlights by any means, even at this low market cap of less than £20m.
The new Executive Chair is working on a (drum-roll) Artificial Intelligence/Machine Learning strategy:
SysGroup is well positioned to participate in the burgeoning field of AI/ML, a technology set to redefine our era. AI's prominence is undeniable, with daily media coverage and increasing demand for AI strategies at the board level of every company. The reality is that AI is here to stay and will be a powerful tool for those that embrace it.
Sysgroup will be “the go-to end-to-end data solution provider for SMBs embarking on their AI/ML journey”.
Turning back to the results, here is the latest reconciliation between adj. EBITDA and the pre-tax loss:
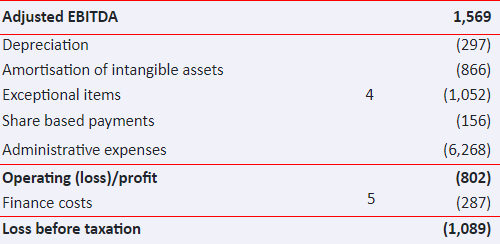
It’s never nice to see a pre-tax loss, but some investors might take comfort in knowing that there was a profit before these items. Personally, I prefer to see much cleaner accounts than this.
The company has £20m of balance sheet equity but it’s all goodwill. Deduct goodwill and intangibles, and the company is in negative equity.
Graham’s view
I don’t see anything here that particularly stands out to me here, either good or bad. Obviously I would treat the AI/ML strategy with caution, as so many companies are jumping on this bandwagon. But my stance is neutral. With a half-decent cash flow performance, SysGroup could justify this market cap.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Frontier Developments plc
I disagree with Graham’s analysis and the supposedly healthy balance sheet. Cash burn has been about £5m only the last 2-3 months and it doesn’t seem that this cash drop will ever stop!
A very bright red for me.
Thank you for your coverage of Epwin and Concurrent Paul, we hold, your cautions are noted and my optimism is reigned in slightly.
ECO Animal Health (LON:EAH) - following Interim Results this morning, just a reminder that we are hosting an investor presentation with Q&A on Wednesday at 3pm, sign up to register at the link here: https://www.equitydevelopment....
Creightons (LON:CRL) Managing Director has left the company today, he is third largest shareholder with 8% of company. Creightons share price is at a 5 year low, 22p. I got fed up in July 2022 after year end results, and sold out between 38p and 43p. My average buy price for Creightons was 80.7p, and sell price was 55.7p, so I lost 30%, which is a big loss, but glad I did sell out as the share price has since halved.
Sorry for size of the posting, technophobia strikes again Saga (LON:SAGA)
Hello Paul Scott. Re your podcasts. I am an avid fan though I admit that recently I have been diverted by family issues. However, I take them on my phone and I notice that I am missing the following 'issues' 36, 38, 39, 41, 44, 45, 46 and I have just picked up your 47th this morning so something is working.
Can you or anyone else give me some hint of what might be happening. Its not as if I am not getting any at all, viz 47 is there this morning. Also, up to 35 I have had a completely full run.
Although a bit late - horses bolted and all that - I do like to go back over some issues, as I do with the SCSW issues I subscribe to. So are they available elsewhere eg YouTube?
Thank you Paul, and anyone else who can come back with constructive suggestions where/how I might find the missing ones, and give me some confidence that the pattern will not continue, ramdom though it would seem to be.
PS looks like thanks to gpxtra at 7.21 this morning I have the answer. https://www.stockopedia.com/co...https://podcasts.google.com/fe...
PPS or maybe not. I still don't seem to have a reliable route through to my phone which I listen to via bluetooth. Any help gratefully received......in words of few syllables. I am not a techie!
they are also available via Spotify if you have an account that is
No I dont but thanks anyway blaz
ridavies, I replicate a small part of my Google home page:
You can see these boxes are shortcuts and the one you will be most interested in is the one that contains the URL :
https://feeds.acast.com/public... thanks to Paul for placing it on his SCVR.
Silver
Thank you Silver Moon
I listed to another excellent podcast from Paul over the weekend and I was interested in his comments about the work Stockopedia has been doing into multi-baggers. Paul mentioned one of the factors is quality of management. A few companies ran through my mind, but one stood out, DP Poland (LON:DPP) which had a change of management in the middle of 2022. One institutional investor who has met him described as being in the top 1% of CEO’s he had met during his 25 year career.
New CEO Nils Gornall has been there just over a year and has been instrumental in a significant turnaround at the group. He’s got 25 years working in Dominos stores doing all the jobs as well as owning some of the best performing franchise stores. Since he’s arrived Quality has improved, customer satisfaction has improved, delivery times have reduced and sales have grown impressively. Double digits growth most months and October LFLS were up a whopping 37.2%. The company has historically been loss making but as sales grow that is likely to change. You can watch a webinar of the HY results here.
Going back to multibaggers, for those that can remember, Domino's Pizza (LON:DOM) was one of the great multi baggers of the early noughties - why not DPP in the 2020’s?
Im going to watch the multi-bagger webinar this week for any more gems.
I listened to the same podcast (I imagine) re DP Poland (LON:DPP) and came away absolutely’ wowed’ by Nils Gornall, if they can keep him in post and no more share dilution I agree with you this has serious potential.
I’ve had some recent trips to Poland and it’s positively booming. I got a very strong sense of optimism from the young (mid twenties early thirties) people I spoke to. I’ll take a look at DPP as it would be good to get some exposure there.
I was looking for the D4t4 Solutions (LON:D4T4) report on stocko this morning but it isnt on here. any idea why? is this a bug?
D4T4 has turned into Celebrus CLBS and I imagine Stocko is scrambling to sort out the change
I would of thought the system was robust enought o cope with a ticker change. ive asked the stocko team anyways
There is a Stockopedia issue with name/ticker changes in my experience.
With PhotoMe Group's ME International (LON:MEGP) change all the RNS data was lost from the date of change, which is frustrating.
Obviously it is not as ii has got it all together.
Molten Ventures (LON:GROW) acquisition of Forward Partners (LON:FWD) = 100% poo-show.
Molten using its even more discounted to book shares to acquire Forward whilst at the same time sneaking in a £50m cash raise as neither they nor Forward have the adequate cash to keep funding their portfolios. The fact they can pick up approx £14m cash from Forward for issuing £45m in confetti for all share deal was probably not insignificant.
The mini scale of Forward and its holdings do not really fit with the more jumbo sized Molten. Forward doesn't bring any operating cash flow either which Molten needs more of to keep the lights on without burning cash.
Altogether a hope and prayer merger with an excuse for a cash raise on the side. Its pretty likely that both portfolios got more (and maybe v significant) write downs to come. It no longer matters whether the stock market turns up or the environment for venture funding. Why? As the next 'bull or animal spirits' will be for shiny new things and the old will be quietly culled. Molten got a lot of this as they played the game of continually writing up unprofitable portfolio companies as they went through endless rounds of happy funding as the future smelt good...and that process will relentlessly unwind now even into renewed good spirits. The only viable exit for many cos is onto public markets at a heady valuation as there isn't an industry buyer who would want or will pay the excess valuation...game over dudes.
Mercia Asset Management (LON:MERC) is the best operating model in the space with enough actual revenue through ongoing 3rd party fund management services to pay the bills and decent dividend. I no longer own. Partly as thought some of their big holding on balance sheet looked troublesome (kudos for getting out of nDreams the biggest even if the exit price was meh...monkey off the back imo) and some of the newer (maybe more exciting?!) are a good while away from being exits. Nevertheless they have plenty cash to deploy (including 'off balance sheet' in 3rd party funds) meaning if you are a Mercia backed company you are v lucky...as long as they keep liking you. But an important difference with Mercia and the two reprobates above is that they write up value more cautiously and exits more to industry acquirers rather than dreamed of Nasdaq big splashes...sounds dull, but is good management (and imo they also take their write downs in timely way too...never sweet medicine at the time but makes for a much healthier concoction over time).
I possibly should have held on to Mercia but I saw/see some binary risk around whether good exits can be achieved on some big holdings and specifically nDreams I was worried it might be a down exit (its been somewhat troublesome child imo and the environment has deteriorated) and that was a hole that if they fell into would have kept Mercia down for a bit (though important to note that their operating model would have pulled them out of it without external help needed!). And the baleful general market throws up other opportunities and I felt I could improve my strategic risk-reward by moving elsewhere (I look for high returns and Mercia were at lower expectation end for me and I never invest just for value)
Private Equities
I can not really trust their NAV and quite rightly mr market does not either. Otherwise why should they be at such a huge discount. The only PE with good accounting is 3i which a few months ago was on discount but now is at small premium. The bet on a single unlisted company has worked for it until now.
The price-value is always uncertain whether public or private (obvs today's price is clear public...). However, I trust Mercia Asset Management (LON:MERC) prices in that they tend to be conservative...doesn't mean that they haven't got their price wrong tho
On Molten Ventures (LON:GROW), Sequoia is reported to have written down the value of its holding in Graphcore to zero, but GROW has written down its holding by 11.3% (purchase price of £24.0m vs. stated value as at 30.9.23 of £21.3m, although GROW was holding its stake at a higher valuation on 31.3.23). This is not to say that Sequoia's valuation is correct, but the dispersion between the two valuations is striking.
Molten Ventures (LON:GROW) in weaker position and must scrimp and scavenge what it can to keep valuation up so as to keep a route to funding open. Tick tock
Agee with most of this, although I do think Augmentum Fintech (LON:AUGM) also looks interesting in this space. On a c50% discount, but tons of cash so no danger of a dilutive fund raise, and they are also quite prudent in terms of not excessively writing up valuations.
Frontier Developments (LON:FDEV) (i hold as a punt about 30-40% higher now)after yesterday's 40% haircut to Team17 (LON:TM17) .Not a great business update at all, nevermind the revenue haircut .How low can it go.. market cap wise.. surely under these testing economic coditions and without the need for an imminent raise not much lower?The share has given back all of its capital gains over the last 10 years just from a pure chart viewpoint.There does seen to be heavy buying for now at this level.I'm keeping on keeping on.Good luck to any fellow holders.
Software Circle (LON:SFT) this is an interesting one, seems they are trying to emulate constellation software, Vitec, etc. with this pivot into VMS acquiring. If successful could be a great investment (CSU compounded at 30% for 15 years). Hard to replicate - as without Mark Leonard it is like Berkshire without warren buffett.
I hold a tiny position in Software Circle (LON:SFT) as a chat a couple of years ago with chair Jan Mohr made me curious. And yes you are correct on the planned path for the company...
To be proven out and at this point in time highly speculative and risky. But Jan Mohr is an interesting and impressive guy...not normally my reason to invest (but it is v small holding for me)
I do like his communication style in the RNS releases. For example I enjoyed this joke in the update this morning “We kept the logo similar so it’s easier to change our Grafenia tattoos.”
One thing that made CSU great is the number of acquisitions they make every year. For example in 2005 they acquired 12 companies for $28m. SFT by my count have only made 4 in 12 months.
Another is their treatment of minority shareholders - I have never come across such excellent corporate governance. They do not dilute shareholders in any way and insist on employees buying shares in the market instead of issuing share options.
I plan to sit, observe and evaluate their strategy implementation for 2-3 years prior to investing. As if it even approaches CSU’s trajectory missing the first few years won’t matter.
I hold a tiny position in Software Circle (LON:SFT) as a chat a couple of years ago with chair Jan Mohr made me curious. And yes you are correct on the planned path for the company.
The obvious large scale model from my experience is Roper Technologies. And what a superb business that is. The key is to get cash flowing and re-invest in cash-generative assets. Rinse and repeat. Obviously a bit of work to do on that front and too early in the process for me to jump on board. But good management is the key. Best of luck to holders.
Morning Paul, a quick note to thank you for all the helpful thoughts you provide via the SCVR and the excellent weekend podcast - essential Sunday evening listening. Hopefully meet in person at Mello, Andrew
A very curt RNS from Creightons (LON:CRL) this morning:
"Creightons plc (LSE: CRL), manufacturers of personal care, beauty, and
fragrance products, announces that Bernard Johnson's employment has
terminated and he is no longer a board member. The board is considering
options regarding the appointment of a new Managing Director but in the
meantime the Company wishes to assure all stakeholders including staff,
customers and shareholders, that the Company continues to be managed
effectively by the executive team."
It doesn't quite say fired but there is none of the traditional "thanks for long service" or "for personal reasons" in the announcement.
"Creightons plc (LSE: CRL), manufacturers of personal care, beauty, and
fragrance products, announces that Bernard Johnson's employment has
terminated and he is no longer a board member”
For a 78 year-old CEO with 21 years of service, this is a very terse statement and a rather sad denouement. Though who knows what illness/coup/malfeasance precipitated it.
“the Company continues to be managed effectively by the executive team."
Not the message the share price is sending
Well, as of his last share sale back in September, he still owned 7.75% of the Creightons (LON:CRL) voting rights.
I guess we have to consider that a potential overhang, regardless of what has happened.
The share price is telling us that things are worse than the story in the last update. This would seem to be confirmation. This has been one of my poorer investments - usually I try to avoid low margin businesses dependent on volume. Particularly disappointing when contrasted with Warpaint. I should stick to my principles.
@CLBS - As has been mentioned previously, recurring revenues here are billed annually, most of which fall at the back end of H2. They aren't billed monthly, and so there are often large receivables coming out of FY (and here, it looks like out of HY). This has been the case for many years, nothing new here.
Hi GavSmith01,
Thanks for that.
You say "nothing new here", but the reason I flagged the very high H1 receivables is precisely because it IS new. Receivables were £4,157k at 30/9/2022, but ballooned to £17,346k at 30/9/2023. That's a massive increase, and given that H1 revenues were £13.0m, it looks a really excessive receivables figure, and a dramatic change from the position a year earlier. So why were customers apparently billed so much later in this year's H1?
I think we need more colour on this rather than to dismiss it as business as usual.
I take your point that it's annual billings, not monthly, which has affected H2 in the past. I'm just perplexed as to why the H1 figures are so different this time around.
Regards, Paul.
D4t4 Solutions (LON:D4T4) (It's annoying that 10 days after the change in name - stocko still doesn't recognise CLBS ) I hold.
Cavendish have released an updated research note this morning which is available free via research tree.
https://www.research-tree.com/...
I also found it positive that CLBS included their view of the market expectations in the rns. Wish more companies would do that.
Receivables. This is not unusual. Happening more often at FY. Here from the FY22 AR -
Trade debtors were high at £25.0m (FY21: £10.2m) due to two of our major partners paying just after the year end. Both of these partners account for a number of end clients and the payments were received during April.
Looks to me that the delayed contract which included the high level of hardware was through one of the major partners - typically Terradata/Pegasystems - through which major banks tend to procure their whole IS. Cavendish are equally confident in their research note.
Worth noting that a lot of the recent investment in sales teams is to establish their own direct channel of sales - reducing their reliance on these large US partners - though it will probably remain the case that Tier 1 customers will deal through their IS partner?
Acquisitions:- Investors are always asking what CLBS intend to do with all their cash. IIRC CLBS previously said that they did not see the need to make any acquisitions - which was at the time of the 12.5p special dividend - in response to investors grumbling that they should be looking to bolt on acquisitions. Now that they acknowledge that they might make a bolt-on - its entirely natural that investors will grumble that perhaps their existing products are not up to it? I think its a bit of both. Via the existing major partners there is not much opportunity for cross selling additional products, the partners control that. Via their own direct selling channel there will be much more opportunity to cross sell once it builds up. Bolting on might make a lot more sense when direct selling - in terms of providing an easier one stop experience for their customers.
Overall: CLBS has delivered on its H1 revenue and profits. Looks increasingly that their combination of product development and sales team/success team will be at the right place at the right time - in terms of growing fraud and data anatlytics combined with cookie-less data?
The forecast is a 60% increase in adjusted FY profits on a 50% increase in revenue. That's quite a step up from previous levels of performance. Promises to be interesting?
cheers
Mark
Hi Paul - are you joining the Volex (LON:VLX) investor meet at 10am? Would be great to hear your thoughts after if so
Hi joshwood,
No, I'm too busy to listen to £VLX IMC, and I don't really have any queries on it anyway. So I'll watch the recording later, once we've finished the report here.
Others are welcome to post your thoughts on it here, and indeed any other webinars with management. They can give a nice "feel" for things, I find, and help me weigh up my general perception of what management are like - how promotional are they, are they on top of all the facts & figures as they should be? Do I trust them or have any doubts?
Regards, Paul.
I listened to the Volex (LON:VLX) [I hold] presentation this morning and was overall very happy with it, albeit not the most polished delivery. Nat Rothschild (age 52 and with 25% shareholding) started turning the company around in 2015 and said things are now really on the move and that he expected to be with the company for the rest of his business career (although they have succession planning in place at all levels).
All acquisitions have been bought at sensible prices and the latest, Murat, is integrating well and opening avenues for new group sales to existing Murat customers.
Interesting that they are not chasing the Chinese EV market as they feel it is too low margin.
Investor Meet's reminder email came in at 12.54pm, I 've noticed the reminders are getting too tight but this was ridiculous. A good job I noticed just in time the note left in the SCVR that it was planned for 10 am. I hold Volex (LON:VLX) and was cheered up by Nat.
Silver Not sure it's Investor Meets' problem. I got a reminder from them before 0900 this morning.
Epwin (LON:EPWN) in line trading update, share buyback 3million expecting opertating profit above last year.
Good morning davisallen77, we are long time holders in Epwin, our holding is down about 40% but I'm still a believer and dividends have soothed the pain. We tried to add a few more when the market opened but only managed two lots of 500 on Barclays Smart Investor platform after several attempts, an at At Best indicated price for 2500 was 80p, we didn't pursue it! We had no problem topping up on Concurrent Tecechnologies which we also hold and will try to buy another 1500 when Barclay's get their act together.
Never buy illiquid stock early, i hold a tiny amount sold half a few week ago may buy back
ECO Animal Health (LON:EAH) I would appreciate yours or Grahams eagle eye on this one if you have time
Overall inline with 94% of revenue covered, still LPS tho of 1.93p
Cash of £20.6m vs market cap of £72m reassures
China remains the risk but good to see US picking up with revenue +26%
I hold & am en route to Mello today (& for the Aquis Showcase tomorrow) so I’ll see you both there…
I'm not quite sure the 94% number in ECO Animal Health (LON:EAH) is such a solid visibility for FY Mar24 expectations.
For one, it includes current order book, which may or may not be subject to cancellations, delays, etc.
And two, it is also based on "current run rate".
Coupled with the "cautious optimism" statement and "FYI second half weighting" and some other woolly caveats in the outlook statement...
Suggests to me that management may be hedging for a high possibility of missing full year expectations.
In addition, China's hog industry is getting weaker in the run up to Chinese new year... Not great for that market, if farmers pull back on Aivlosin because of poor hog prices.
Increase in cash flow here has nothing to do with operational positive cash flows-just working capital movements and decrease of inventories.
100m revenues (probably a future miss!) on a 5% operating margin and a 72m market cap is nothing to get excited about.
Edit - I would have put this as a reply to gmtrader but his post went up while I was typing mine
Frontier Developments (LON:FDEV) new game - licensed by Games Workshop (LON:GAW) - some reviews here: https://store.steampowered.com... not good enough.
Read across to Games Workshop? Yes to some extent but their core market is not screen-based, it's tactile and inter-personal. And new generations are coming in. Photo of typical GAW customers at a recent event in Australia (not a GAW game but the poster says this is what their customers look like) (https://www.rmweb.co.uk/topic/...):
And this caught my eye:
https://www.rmweb.co.uk/topic/...
What is this, orcs vs emus?
They look bored to death, is that a set up?
Pretty sure it’s AI generated
Alegedly it's The Great Emu War Of 1932. I have not researched further....
Ha ha. Sorry, couldn't resist.
See what you've started now?
Forward Partners (LON:FWD) Directors agree to sell all their £10 notes to Molten Ventures (LON:GROW) for £5 each because 70% shareholder Blackrock told us to.
Dear Asset-Stripper
Forward Partners (LON:FWD) I hold
Personally, I think this is a sensible outcome given the difficulties currently being faced by private equity/venture capital companies.
My interpretation of the Forward Partners interim results, published in September, was that it was all about cash conservation rather than outright growth of the company’s portfolio.
Although the discount to the Forward Partners NAV is an estimated 50%, that of Molten Ventures is actually closer to 60% according to the most recent Edison research note. What this tells me is that analysts are dubious about the accuracy of future NAV figures. As we now know, rising interest rates have dramatically changed the investment landscape and, until valuations can be accurately tested through transactions, I suspect these discounts will remain.
Nevertheless, I feel that I have a better chance of recovery being part of the considerably larger Molten Ventures (where, incidentally, Nic Brisbourne worked for seven years) rather than Forward Partners remaining independent.
Kind regards
Phillip
Have you got any more £10 notes you want to sell for £5? I'll take them all!
Dear Asset-Stripper
Forward Partners (LON:FWD) I hold.
My point is that I exchange an FP share currently standing at a large discount for a Molten Venture share that also stands at an equally large discount. Mind you, if you read the comments from Mojomogoz at 1004 this morning, I am swapping one bucket of poo for another!!
Kind regards
Phillip
Haha Phillip...I'm known to be wrong.
And whatever at least you have a more liquid bucket of poo should you choose to gardyloo. I'm less knowledgeable on Forward Partners (LON:FWD) than Molten Ventures (LON:GROW) who I feel quite assured in my dislike of. But I may misunderstand and if so then the value is considerable!
DSW Capital (LON:DSW) H1 webinar today 1pm following results published this moring. Register here.
Outlook: Adjusted FY24 expected £1.1-1.4m.
'Resilient performance with M&A activity returning to more normal levels'.
Frontier Developments (LON:FDEV) Terrible update imo. I can only see this continue to drop. The company only expects to break even by 2025 (jam tomorrow and very thinly spread jam).
On the new game released, Realms of Ruin, the company says "We were pleased to
see at launch that Realms of Ruin received mostly positive reviews from game
critics and from players".
Yet a quick google search on the game for reviews show pretty poor ratings:
3/5EurogamerWarhammer Age of Sigmar: Realms of Ruin got a 3 stars review on Eurogamer.55%PC GamerWarhammer Age of Sigmar: Realms of Ruin scored 55 percent on PC Gamer.6/10Steam
So, providing the company gets it's act together, it will break even in 2025. No reason to hold or buy imo and I'm guessing this will be below £1 in time.
Zotefoams (LON:ZTF) interesting update re award for their beverage cartons. Looks like the project is really gathering momentum and could be a great value add to their main business.
Zotefoams (LON:ZTF)
I don't usually pay much attention to these 'we won an award' type RNS's but I wonder if this one maybe different. If successful the potential market is huge.
My morning smallcap tweet: Frontier on the back foot (geddit?)
Frontier Developments (LON:FDEV) CPPGroup (LON:CPP) Gfinity (LON:GFIN) Revolution Beauty (LON:REVB) Quadrise (LON:QED) Concurrent Technologies (LON:CNC) Live (LON:LVCG) Rightmove (LON:RMV), Epwin (LON:EPWN), Zinc Media (LON:ZIN) Forward Partners (LON:FWD)
◄Frontier Developments (FDEV)► another games developer warns FY24 rev likely to be only £80-95m cf F/C £108m due to weak sales of new Warhammer game. However market expectation for an adj EBITDA loss of c. £9m remains achievable towards the upper-end of rev guidance. Expects at least break even in FY25. Chmn scarpers after only 12 months. The Warhammer game is called Realms of Ruin! [SP=196 Cap=77m]
◄CPP (CPP)► sells its majority interest in Globiva for c.£5.1m because it's non-core. [SP=143.89 Cap=13m]
◄Gfinity (GFIN)► sells remaining 27.5% interest in Athlos Game Technologies for £260k due to ongoing losses. [SP=0.07 Cap=2m]
◄Revolution Beauty (REVB)► re speculation: remains in negotiation on both potential legal proceedings against ex CEO Adam Minto and with Tom Allsworth, the previous owner of Medichem, to reach a revised agreement on the terms of its acquisition. [SP=30.25 Cap=96m]
◄Quadrise (QED)► AGM stmt - review of project progress. [SP=1.38 Cap=21m]
◄Concurrent Technologies (CNC)► guides FY-Dec rev ahead of market expectations of £27m. H2 rev expected to be substantially higher than any prior half-year. Confident of of material revenue growth next FY too. [SP=72 Cap=62m]
◄Live Company (LVCG)► bricking it as overall creditors remains in the region of £3-4m despite costs cuts. Looking at cutting of non-performing business and the addition of new verticals. Bricklive has entered into an outsourcing agreement with Iconic Bricks so that Bricklive now a sales only biz. FY22 accounts still not ready. Co is aware of all regulatory timetables". [SP=2.08 Cap=5m]
◄RIghtmove (RMV)► the mkt bellweather states rev since July marginally ahead of consensus expectations, despite uncertainty in the housing market. [SP=507.47 Cap=4078m]
◄Forward Partners ►(FWD) all share takeover by Molten Ventures at 31.1p equivalent, a 7% discount.
In line: EPWN, ZIN
Concurrent Technologies (LON:CNC) really positive and informative trading update. Next year on course to be superb.
FDEV not looking too clever with new revenue guidance of £80-95m from £108m. Perhaps not unexpected after TM17 on Friday. Chart almost at 7-year lows. No obvious trade there.
I've posted a new video having researched 100-baggers. Not that hard to find but the difficulty is in holding onto them!
Team17 (LON:TM17) some post profit warning buying from directors reported this morning.
A LITTLE BLAST FROM THE PAST. I took down some diaries that I had in the loft because I wanted to try to find a particular note I made.
I took a look at first note I made, this was from 25.9.12: "Diploma (LON:DPLM) sell at 461p." I had bought around 307p. So I made 50% in that share. I further noted "PE 14.2. Good share, but I don't see an extra 50% on the cards any time soon,. I also sold to buy Dialight (LON:DIA)."
I was clearly chuffed with myself. I did buy DPLM again in late 2015, this time at 717p. The latest share price for DPLM was 3342p. If only I had kept that share I'd be on a 10-bagger right now. AARGH
I bought DIA on the same day at 1209p. It was a CANSLIM stock trading at a PE 31. That one now trades at 154p. Ouch. I had sold out at some point, but I haven't dug through my notes to see how much money I would likely lost.
I made this note about Boeing Co (NYQ:BA). on 8.5.13 when it was trading at 381p. I noted "modest growth in underlying EPS for 2013 is anticipated". BA now trades at 1068p. That's a 148% gain over a decade compared to a 15% gain in the ASX (All-Share). Hasn't the index preformed miserably? A lot of the gain from BA has been relatively recent, though. I actually went and bought BA shares in late 2021 at 575p, for an 86% gain in less than 2 years. I am still bullish on BA, mind, due to its modest forward PE ratio, high returns on equity, and a dividend cover that is not projected above 2. I think that one to look for if you want growth is a high dividend cover, as it suggests that the company wants to hold on to capital because it sees growth opportunities. We shouldn't be too surprised to learn that BA sees a lot of opportunities at the moment.
On 13.5.13 I came across this little scribble I made from a Twitter user that I shall call "PB". Here's his investing bit of wisdom back then: "THAL, GAH, DRV [presumably buy recommendations] added with funds from QPP disaster". That turned out to be a case of out of the frying pan and into the fire. THAL is down over 90% during that time, DRV down 75%, and didn't GAH turn out to be a fraud or something?
This was a note from 29.9.12: "Growth stocks are a coiled spring says Nuveen's Mullinex". I don't know who he is, presumably some high-profile asset manager, but he sure called that one right.
No doubt I will find plenty more gems.
Topically, I heard recently that Grangemouth oil refinery is closing. Grangemouth is in Stirlingshire, Scotland. For a bit of geography, Aberdeen likes to call itself the oil captial of Europe. It is an administrative centre. I used to work in the oil and gas indutry for a spell, but I can't say that I have any insights into the oil industry itself. The oil pipelines from the North Sea actually runs to Peterhead (correct me if I'm wrong). So things are spread around a bit.
The refinery is owned by Petroineos (at least now, anyway). It is Scotland's only refinery. That sounds pretty disasterous. The Telegraph carries the headline "Scotland’s only oil refinery to shut amid fears of Starmer-led crackdown. Grangemouth to stop processing crude oil as Labour plots North Sea projects ban"
Getting a bit political for a moment, I always said that Britain's energy policy was muddled. The politicians can't seem to work out whether to love it or hate it. Even SNP don't seem particularly fond of oil despite Scotland being the ones that have most to lose. I always suspected that the politicians (if they have any sense) secretly like oil because of the jobs and the tax revenue, but publicly wave the banner of green energy because it sounds good to the ears of many voters.
Grangemouth's viability was an issue 10 years ago. The Guardian said in Oct 2013 "Grangemouth closure reversed after union accepts Ineos 'survival plan'. Ineos to make £300m investment after Unite agrees pay freeze, three-year no-strike pledge and pensions overhaul" https://www.theguardian.com/bu...
The price of oil is something I've been sweating about lately on account of owning some shares in Shell (LON:SHEL). From about 2015 to 2021, Brent crude has been in the $40-$60 per barrel range, ish. Today it is $80. The mean cashflow per share of SHEL over the last 6 years has been 325c, which is around 257p. Shell has been buying back shares over the last few years, but let's ignore this complexity. The current share price is 2595p, so you're getting a freecashflow yield of a shade under 10% (257/2595). That's a pretty good return. Remember, that assumes that oil is in the $40-$60 range. If it remains elevated, then you'll obviously do much better. If Brent falls below $40, then that likely represents a good buying opportunity. Food for thought, anyway.
Quote of the day: "If you can see where the con men are flocking, you can tell which groups [of stocks] are about to peak" -- Ralph Wanger
I was one of many buying Asos at 7p, about £2k worth. Sold at 10p happy with the profit then a few weeks or so later bought again and resold a few at a loss around 10-12p range.
Went to 7000p without splits. A £2m return if I'd held d'oh
May get a chance to rebuy at 7p soon!
Hi Paul, was there a podcast on Saturday? I could not find it on Acast. David
Episode 47 - Paul Scott's weekly summary of UK small caps (20-24 Nov)
Morning David! Yes my podcast went out on Sunday :-)
Web version is on Acast: https://shows.acast.com/paulsc...
Thanks, just looked again and there it is. I should also take this opportunity to thank you for the podcast and the team for the SCVR as they are both a superb resource. I have read numerous investing books, but always learn something new from these and of course from the knowledgeable subscribers.
Yes, it's there. He posted on Sunday rather than the usual Saturday. Thanks to Paul for dating the podcast. That's a useful piece of information.