Small Cap Value Report (Mon 29 April 2024) - EYE, ZED, SAL, S247, CAM, PFC, ADF, DPP

Good morning from Paul & Graham!
Today's report is now finished.
Woodford Views - this is a new blogging site, started by Neil Woodford - the famous fund manager whose career and business unravelled a few years ago when he strayed out of his area of expertise into speculative small caps in an open-ended fund, with disastrous results. Unlike many other commentators, I don't see it as my job to chastise or pour scorn on him. My view is that he's had a remarkable career, with huge highs and lows, and like many of us, has made mistakes along the way - which he addresses in his three blog posts so far. Anyway, somebody with that level of experience is going to be worth listening to, and I find his blog posts very interesting. So thought I'd flag them up to you here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Monday 29 April 2024 - SCVR
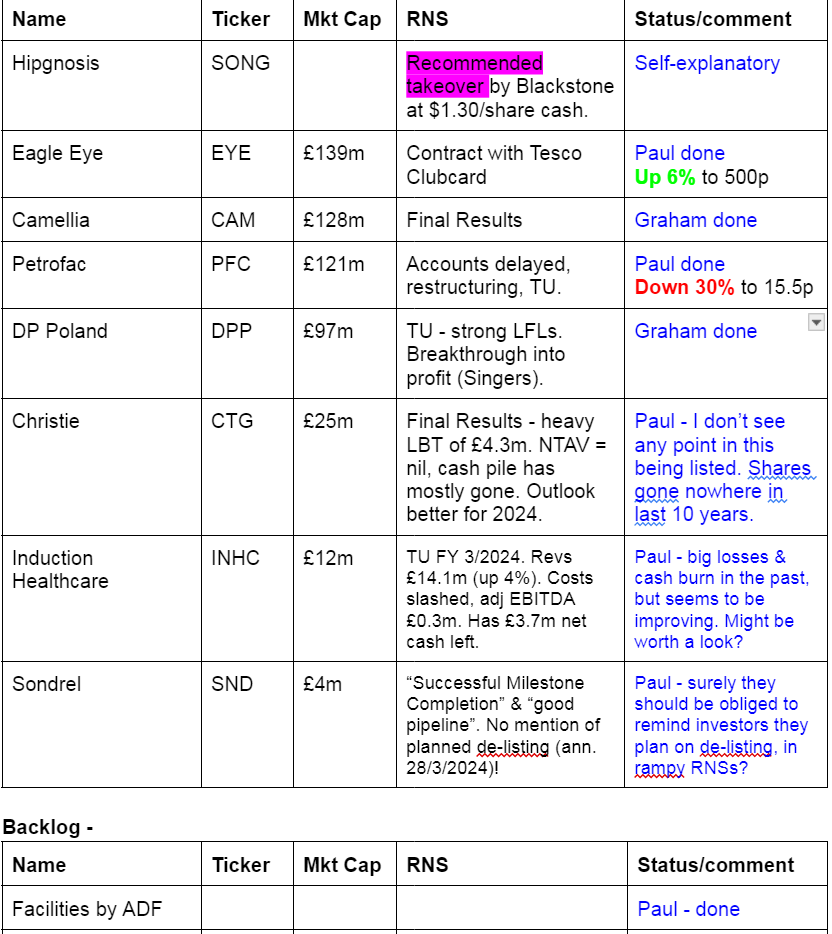
Companies Reporting -
Other mid-morning movers (with news) -
Zenova (LON:ZED) - up 24% to 2.35p (£3m) - £2.4m Fire Protection Paint Order - Paul - Speculative
Speculative nano-cap that has promising-sounding products, but very weak finances - loss-making, cash burning, under-capitalised. We had a quick look at it here on 25 Aug 2023 after “FoolHardy” flagged it as potentially interesting.
Today it says a customer has placed an order for £2.4m over 2 years, for 200,000 litres of its fire retardant coating for steel.
Securing a contract of this size further demonstrates the value-add of Zenova and its suite of high performance products, as we bring solutions to global needs. I fully expect our team to continue to deliver new business across all of our paint and extinguisher products, and look forward to updating the market on those developments in the near-term and beyond."
Paul’s opinion - sounds intriguing. I need reassurance on the finances though - a tiny £677k placing was done at 2p recently. It is almost certainly going to need another placing. With a large order received, and talk of a strong pipeline (talk is cheap!), maybe something interesting might be developing here? Just for gamblers at this stage.
Spaceandpeople (LON:SAL) (I hold) - up 16% to 93p (£2m) - FY 12/2023 Results - Paul - Speculative
A long-standing nano-cap that does promotional work for shopping centres in the UK and Germany. Considering the market cap is only £2m, these figures aren’t bad - revenue up 23% to £5.8m, and £103k PBT. I have some queries on the accounts, (1) what is the £241k “Ancillary charges” shown in note 5 that creates all the operating profit? Weak balance sheet with negative NTAV of £(2.2)m. Clean going concern note reassures. Note 14 shows a £551k provision for doubtful debt - why do business with customers that don’t pay up? Note 17 - what is in the £3.1m “Other creditors”?
Paul’s opinion - has survived the pandemic lockdowns, and seems to be on the mend. Commentary sounds fairly upbeat. Speculative punt at this stage, but the £2m market cap tempted me to have a nibble. My main worry is now de-listing risk.
Smarttech247 (LON:S247) - up 10% to 22p (£27m) - $2.1m Contract Win - Paul - AMBER/GREEN
Cyber- security company which floated on AIM in Dec 2022, which was brave of them! Ronan Murphy (Exec Chmn) owns 70%, and the EBT 9%, so I think that more-or-less rules it out for me. What’s the point in having a listing, when there’s negligible free float? Pity, as the FY 7/2023 results look good - well the adjusted numbers do anyway, with E2.15m adj operating profit, but only £204k of statutory PBT. Good balance sheet with E6m of net cash, mostly raised in the IPO. Loads of RNSs about contract wins. Today’s news is a $2.1m, 3-year contract with an existing pharmaceuticals client.
Paul’s view - this actually looks quite an interesting company, might be worth a closer look, if you can live with the Exec Chairman being in complete control with 70% ownership.
Summary of main sections
Eagle Eye Solutions (LON:EYE) - 470p (pre-market) £139m - Tesco - Clubcard Challenges - Paul - GREEN
A non-regulatory announcement, but quite interesting. Tesco clubcard has signed up for a 1-2 year contract with EYE to offer personalised promotions to its customers. This sounds a striking endorsement of EYE's tech, acquired through UntieNots, which seems to back up management assurances that this was a key acquisition in early 2023. Shares look expensive, but could be worth it, in my view.
Camellia (LON:CAM) - down 3% to £44.80 (£124m) - Final Results - Graham - GREEN
Times are tough as tea, Camellia’s main product, remains oversupplied. Despite its operating losses, and a long delay in the sale of an insurance investment, I think I have to remain positive on this. It’s trading at only about a third of net assets and if that sale goes ahead, I expect it to carry out a meaningful buyback.
Petrofac (LON:PFC) - down 30% to 15.5p (£82m) - Delayed results, restructuring, TU - Paul - RED
A very complicated, very high risk special situation. Equity could easily end up worth nothing, as control seems to be slipping away to the bondholders. Large debt for equity swap seems on the cards. With so much risk and uncertainty, why get involved? I've no idea how things will pan out, but usually in situations like this, equity gets clobbered, as it ranks behind all creditors.
Facilities by ADF (LON:ADF) - 51.5p (£41m) - FY 12/2023 Results - Paul - AMBER
2023 results were clobbered by disruption from the US sector strikes. Recovery so far seems rather hesitant, and I'm not convinced 2024 targets are achievable. Could be a good share if 2025 targets are hit though. So I'll sit on the fence for now. Quite a nice niche business, but I'm not convinced it's scaleable much further without risky overseas acquisitions.
DP Poland (LON:DPP) - up 5% to 11.4p (£105m) - Trading Update - Graham - AMBER
We are usually negative on this Polish Domino’s Pizza business, but I am more comfortable with a neutral stance on it today given the involvement of Domino's Pizza (LON:DOM) on the shareholder register, good like-for-like numbers, and bullish broker estimates suggesting that profitability is on the cards in the near-term.
Paul’s Section:
Eagle Eye Solutions (LON:EYE)
470p (pre-market) £139m - Tesco - Clubcard Challenges - Paul - GREEN
This is a non-regulatory “Reach” announcement which looks interesting.
I’ve warmed to this share in the last year, as it’s proving to be a credible organic growth company, that specialises in sophisticated customer loyalty programmes for big grocery chains, internationally.
I asked management about competition recently, and they confirmed that the main competition is from supermarkets doing their own loyalty schemes, with of course the Tesco Clubcard being very important in the UK.
Today we’re told that Tesco Clubcard has signed up for a 1-year contract with EYE, with an option to extend for another year, to offer customers personalised promotions -
Following a successful trial, with a higher than anticipated participation rate, Tesco will roll out Personalised Challenges to more Clubcard members in the coming months, under the name Clubcard Challenges. The solution will power personalised and gamified offers and promotions to each individual Clubcard member.
Paul’s opinion - this strikes me as a significant validation of what EYE does, if the UK’s leading supermarket, with its own highly developed loyalty scheme, thinks that EYE offers something additional which it seemingly hasn’t got in-house.
I struggle to know how to value EYE shares, and it does look expensive on conventional metrics. However, I also think there’s something special here, and a high valuation could well be justified. Today’s news reinforces that view.
Petrofac (LON:PFC)
Down 30% to 15.5p (£82m) - Delayed results, restructuring, TU - Paul - RED
I’ve only looked at this large engineering group for the energy industry once here on 12/4/2024 when it came up on my top % movers section, being down 30% on an ominous update. I flagged it as RED due to the considerable risk of equity dilution (or wipe-out) in a restructuring. There could be a very wide range of potential outcomes, from zero, to a multibagger, it all depends on negotiations.
It’s done the same thing again today, dropping 30% on another worrying update. Main points today -
FY 12/2023 accounts delayed, now expected by 31 May 2024.
Audit “substantially progressed”, but more time needed to complete annual report.
Shares will be suspended from 1/5/2024 due to late accounts, so last day of dealings for now will be tomorrow, 30 April - hence today’s stampede for the exit.
Some bondholders have offered $300m in fresh credit lines for necessary guarantees on existing contracts. Conditions include a “significant proportion” of existing debt to convert to equity (but not indicated at what price the fresh equity would be issued at).
Discussions ongoing with credit providers.
Bond coupon - expects to default on 15 May, but has a 30-day grace period. Holders of 41% of the notes have agreed forbearance until 30 June.
“Good progress” on disposals.
Problem contract in Thailand won’t be resolved by accounts publication date, so $130m extra provision required. Another problem contract has caused a $15-20m hit to profit.
Excluding these contracts, performance is “broadly in line” with TU of 20/12/2023.
Net debt at 31 Dec 2023 was $583m, less than expected.
Outlook -
“Petrofac has a large order book of high-quality projects, strong market positions and compelling future opportunities which are evident from the recently announced awards. We are working to put the performance guarantees and the right capital structure in place, in order to deliver on this potential.”
Paul’s opinion - clearly this is a highly complicated financially distressed special situation. Only get involved (long or short) if you really know what you’re doing. This is a classic tussle between bondholders and equity. Remember that equity ranks bottom, below all creditors, and often gets all but wiped out in situations like this. No view from me, other than it’s super high risk, and the range of outcomes possible is probably wide. Why get involved when big dilution is coming even in a positive outcome? RED.
It joined the 99% club today -
Facilities by ADF (LON:ADF)
51.5p (£41m) - FY 12/2023 Results - Paul - AMBER
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV") announces its audited final results for the year ended 31 December 2023 ("FY23").
Main issues/questions from me -
- Impact of US strikes, and recovery from that?
- Streaming boom might have been a one-off?
- Brexit - difficult to cross the channel with kit, visas needed? Any impact?
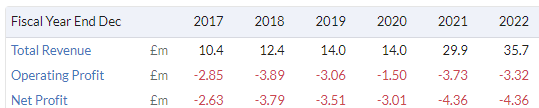
As you can see from the table below, the Hollywood strikes badly hit forecast for FY 12/2023 in July 2023. Slower than expected recovery also caused a profit warning which Graham covered here on 29/2/2024. Despite the problems, both Graham and I are quite positive on the company fundamentals. This was a sensibly priced and well financed IPO in Jan 2022 from Cenkos (now part of Cavendish). The problems since have been caused by external factors, although you never can be entirely sure if there might be other internal problems too.
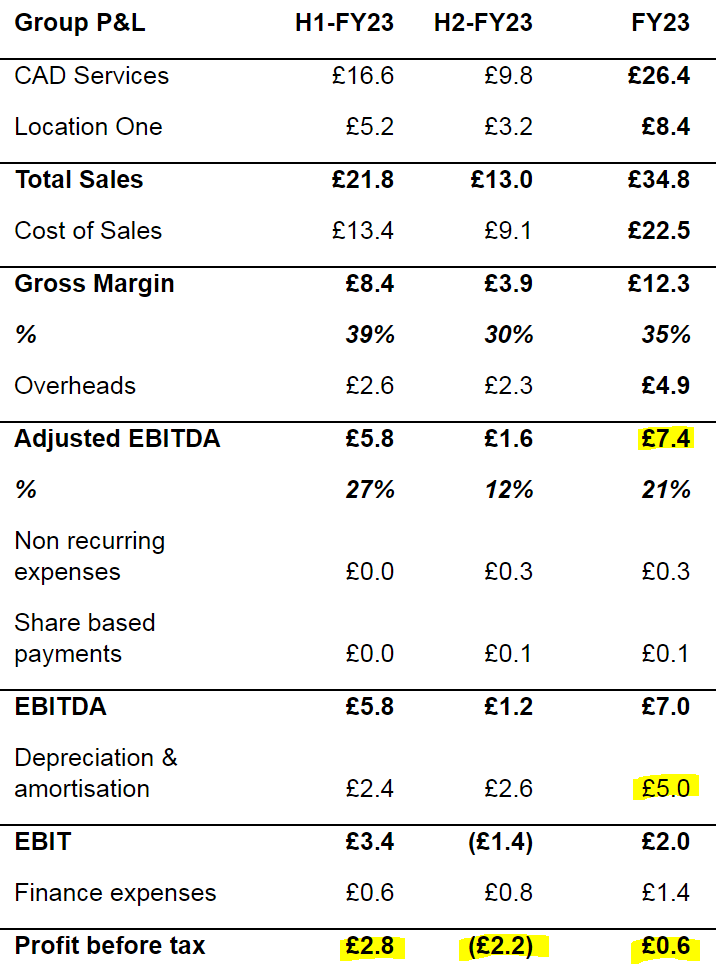
I really like the P&L table below, which splits out performance into H1 & H2, to clearly show how it was doing well in H1 (PBT £2.8m) but then was clobbered with a sharp slowdown in H2, plunging into a loss of £(2.2)m due to the Hollywood strikes causing delays to TV productions.
This table also neatly reconciles adj EBITDA £7.4m down to PBT of only £0.6m. I am really growing to despise EBITDA. The main item is the hefty £5.0m depreciation charge, since ADF is renting out large items of physical equipment, so the capital cost of those cannot simply be ignored, and of course they wear out and have to be replaced over time, which is what the depreciation charges try to account for.
Similarly with finance costs, those are real world cash outflows, so cannot just be ignored.
Overall then with a loss-making H2, 2023 as a whole wasn’t much above breakeven.
Obviously the hope is that in future, it might be able to annualise the £2.8m H1 profit, so perhaps c.£5-6m might be a sensible ballpark future target for PBT?
Webinar - there’s an IMC webinar tomorrow (Tues 30/4/2024) at 10:30. They put the wrong date in the RNS. I find these webinars wonderful, it’s great to see many companies connecting with us in this way.
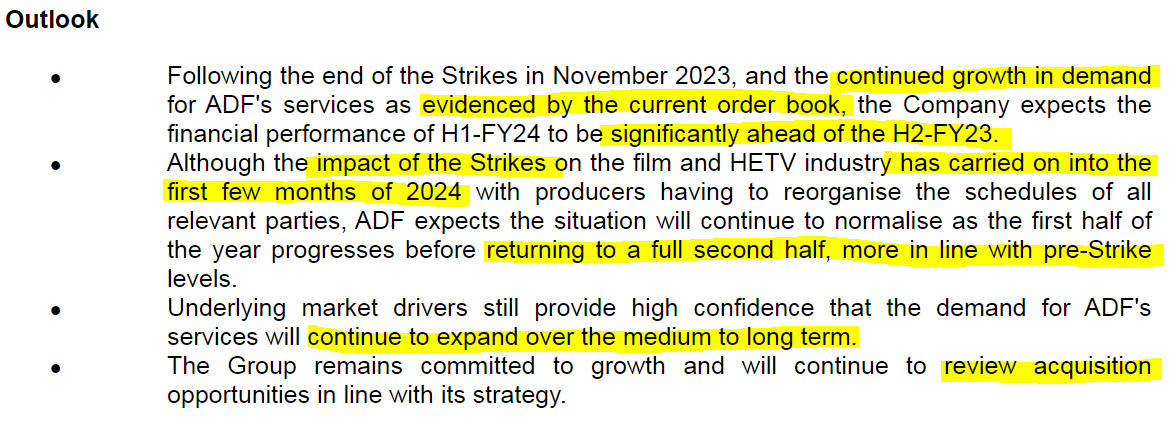
Outlook - it seems to be taking time for things to improve, so I’d say we’re being prepared for lacklustre H1 results in due course -
Balance sheet - looks reasonable at c.£19m NTAV.
Most of the assets are leased, rather than owned outright - which is much better than having large bank borrowings, and the worry of having to meet covenants.
Paul’s opinion - this looks OK. We should see a gradual return to more normal business, by 2025. I don’t see enough scaleable upside here to excite me though. Probably priced about right? So I’ll go with AMBER, and that’s already factoring in the likely improvement in profits by 2025. It’s an OK business I think, but I suspect it might struggle to meet 2024 broker forecast of £5.0m adj PBT, given the hardly scintillating outlook comments. So I’m happy to sit on the sidelines, as I think there’s a medium risk of another profit warning here.
If it succeeds in achieving £8.0m adj PBT forecast for FY 12/2025, which is 8.8p EPS, then I suspect the shares would have good upside, maybe to something like 75-100p in a bull market? Tricky one, we’ll just have to wait to see what happens, my crystal ball is a bit foggy today!
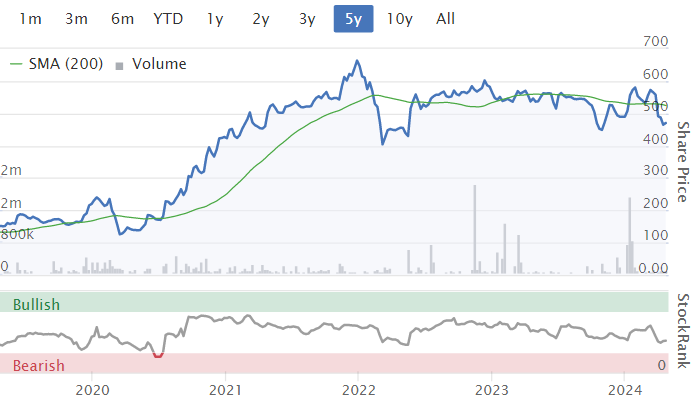
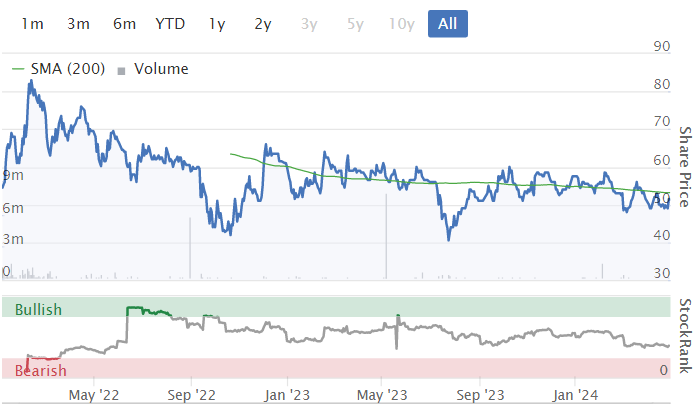
Actually not a bad track record as a listed share, considering the pandemic, small caps bear market, energy crisis and Hollywood strikes -
Graham’s Section:
Camellia (LON:CAM)
Down 3% to £44.80 (£124m) -Final Results - Graham - GREEN
This is primarily an agricultural group, with its core products being Tea, Nuts & Fruits. But it also owns an unusual collection of other assets (property, insurance investments and an engineering company), for reasons that are difficult to understand.
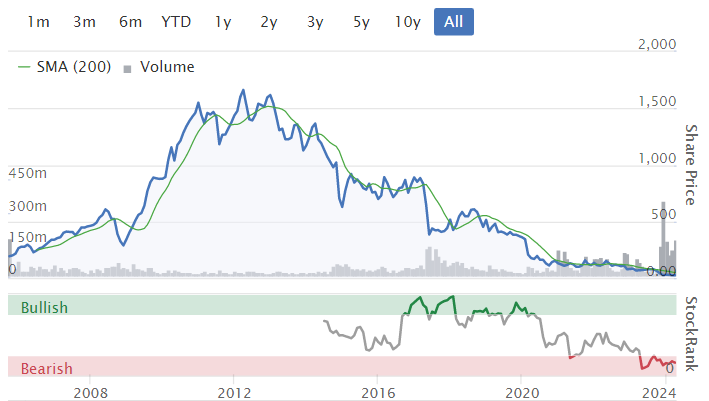
I think it’s fair to say at this point that the unusual capital allocation hasn’t been successful. Camellia’s share price hasn’t progressed over the years (it doesn’t really matter what timeframe you use for the chart):
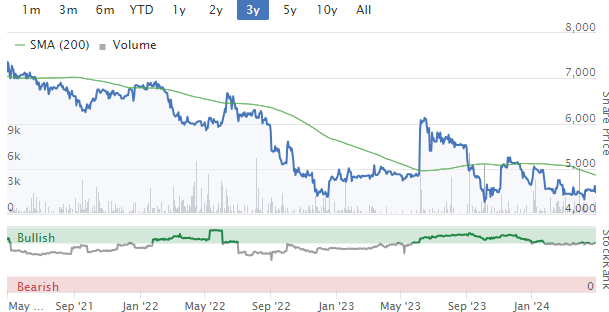
Last June, the market was excited by the news of a disposal (and I turned GREEN on the stock), but the excitement was short-lived as the deal still hasn't been completed yet.
However, the situation remains fluid as a programme of non-core disposals continues. More on that in a minute.
Here are the headlines from today’s full-year results.
Difficult conditions in key agriculture markets impact 2023 performance; continue to focus on our primary agricultural businesses and investment to diversify activities by crop and location
2023 was a tough year:
Revenue down 8% to £272m
Trading loss for agriculture £5.6m (LY: trading profit £15.5m)
Tea production rose but “tea prices significantly lower and wage costs were up in all regions resulting in a £9.8m fall in profit”.
There was also a £5.8m fall in profits from macadamia, offset by a £2.6m increase in profits from avocados.
Overall operating loss across the entire Camellia group £1.3m.
This figure includes some positive exceptional items. The “adjusted” operating loss, which excludes exceptional items, is much larger at £18.1m.
Net cash was £22m at the end of the year.
Balance sheet showed net assets of £326m for Camellia shareholders.
Outlook is “challenging”:
…revenues are expected to be above 2023 but with a significantly higher adjusted loss before tax. This reflects the effect of continuing low tea prices, lower macadamia and soya crop volumes, lower cereal pricing, the consequence of strengthening of the Kenya shilling as well as the as yet unclear impact of the Red Sea crisis on shipping times and therefore on avocado exports.
CEO comment: reiterates that tea is oversupplied. The other commodity prices don’t seem to be helping much, either. He finishes by saying:
...The Board recognises that the Company's financial performance falls short of shareholder expectations and is working with the Group companies to identify potential operational improvements, and actively examining the long term risks and opportunities for the Company more broadly. Despite the outlook, our substantial cash resources, our investment portfolio and limited gearing mean we are well placed to withstand these difficult market conditions."
Graham’s view
I think I would now classify this as a special situation, rather than a value play.
Last June, the major announcement from Camellia was the sale of a stake in an insurance company for $96m (£76m). This would transform Camellia’s balance sheet and allow for a share buyback: this was a key reason that I was positive on Camellia’s stock last year.
The problem is that this sale hasn't been completed yet. It appears that the insurance company might not be too keen on Camellia’s plan.
In an announcement last month, Camellia explained that the insurance company (“BF&M”) first of all created a poison pill, a device whose purpose typically is to prevent a change of ownership.
After that, the insurance company entered into a complicated partnership with a 3rd party. The result of all of this is:
As previously communicated, these developments have impacted the anticipated timetable for regulatory approvals for the Sale. While a number of the required regulatory and tax approvals have been forthcoming, some key approvals remain outstanding which we now expect in Q2 2024.
In today’s results, the auditors say in relation to the planned disposal:
There is a risk that the sale is not highly probable, and that the sale will not complete within one year from June 2023.
On the balance of probabilities, I think that the sale of BF&M is still more likely than not to go ahead, although it’s not a sure thing.
The Camellia Board today say that they still intend to consider a share buy-back, “subject to the sale of BF&M completing, and the Group's balance sheet permitting”.
Overall, I continue to view this as an interesting value play.They have made progress in disposing of non-core assets over the past year. Although I wouldn’t say they are acting with a great deal of urgency: they still own an engineering company, a portfolio of listed equities, another insurance company investment, and various investment properties.
The listed equities, in particular, could be sold very quickly and the funds returned to shareholders.
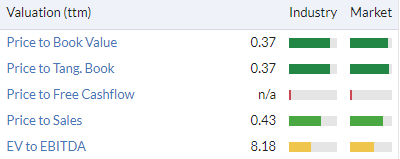
But with a market cap of only 38% of balance sheet net assets (almost entirely tangible), and with the sale of BF&M still, I think, likely to go ahead at some point this year, I feel obliged to leave my GREEN stance unchanged here. However as is the case with many value stocks - and value traps! - the time required to see value realised may prove to be a source of frustration.
DP Poland (LON:DPP)
Up 5% to 11.4p (£105m) - Trading Update - Graham - AMBER
DP Poland, the operator of Domino's pizza stores and restaurants across Poland and Croatia, is pleased to announce a trading update for Q1 2024.
This is a positive update, with key points:
Full-year EBITDA for 2023 in line with expectations.
Q1 2024 like-for-like system sales up 17.9% year-on-year.
Q1 2024 like-for-like orders up 14.8%, thereby driving most of the increased sales.
Non-delivery and delivery sales are both up by similar amounts.
The CEO is bullish:
After almost two years since the adoption of a High Volume Mentality across all operations, we have transformed the Polish business into one of the fastest growing Domino's markets globally. Momentum in the business is very strong and we are in an excellent position to drive Company expansion.
The plan is “to deliver 200 stores by the end of 2026 and transition the business towards a franchise led model”.
Note: as of the most recent interim results (to June 2023), they had 116 stores.
Graham’s view
As regular readers will know, I greatly approve of the franchise business model. However, despite the company’s plans to transition towards a franchise-led model, it may take some time for the company to get there.
According to the recent fundraising announcement, out of the company’s total store portfolio of 116, only 8 were franchised.
Therefore, even if they grew exclusively using franchise stores, they would still operate most of their own stores when they hit the 200-store milestone.
Their actual plan, again going back to that fundraising announcement, is:
DP Poland is targeting 45% of its store network to be franchised by the end of 2026. DP Poland expects the majority of the new openings to be corporate stores with the additional openings of 5-10 franchised stores.
Therefore, I can’t see DPP as a franchise-led business for the foreseeable future. Maybe by 2027-2028?
Remember that its own corporate stores have been loss-making for a long time. Hopefully the situation can improve with increased scale?
Domino's Pizza (LON:DOM) invested £11m in DPP in the most recent fundraise. That’s peanuts for them, but surely they must have done due diligence on the plans?
Estimates from Singer suggest the company will make a small adj. PBT this year (<£1m) before making £2.9m next year, and on an improving trend from there.
Normally I give this one the thumbs down, but I agree with Paul that it’s more reasonable to be AMBER in these circumstances. There are signs of life.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
My thoughts are that by promoting Woodford you are crossing a line that should not be crossed. He is delusional , has lied consistently, tried to game the system by attempting to list unsaleable companies on illiquid stock markets to meet certain guidelines, but above all has lost millions of pounds of peoples' life savings by almost incredible stupidity, avarice and ignorance. There is absiolutely no excuse for this nor for your proposition that he has 'experienced up and downs' and therefore should be listend to.
I just put up a link to a blog about economics that readers may find interesting. I'll leave the moralising up to you.
There are many quality companies quoted on the AIM100 index, that have had outstanding performances over the last few years.
This is why it is so difficult to invest succesfully in "Small Company" UK shares. And probably why there is No AIM 100 tracker! Only a sucker would buy in. And remember these are the "best" AIM shares
I have tried to invest intelligently and prudently, but the odds of succeeding are well nigh impossible. If the government of the day ever withdrew inheritance tax benefits many AIM shares would be uninvestable and would plummet in value, even more, almost overnight!
Key AIM 100 Index readings
20/03/2020 - 3190.57
03/09/2021 - 6547,27
14./10/2021 - 3686.18
27/10/2023 - 3195.37
29/04/2024 - 3683.98
AIM 100 Shares - Uninvestable, practically speaking the odds of positive returns are stacked against any would-be investor
Well Graham and I seem to do alright here, by screening out the dross, and focusing on the good smaller caps (mostly AIM). We're not buying an index. We're buying carefully chosen individual stocks, of which there are dozens of very good companies on AIM. We're both up about 20% YTD.
I aim for a 20% annual gain each year, and achieve it most years. That compounds astonishingly well. So my message is: don't despair, but sharpen up your stock picking skills instead, and don't invest in the junk that proliferates on AIM, find the good growth companies instead! We find lots of them here, and mark them GREEN, so we've done a lot of the preparatory work for you!
Oh, and I think we're at the start of a new bull market, so the gains from these lows should be really exciting, for the best company shares.
Despair is other people's opportunity! It's exciting! :-)
Regards, Paul.
Hi Mark, I'm afraid I have to side with Paul, ie it comes down to stock selection. I have a lot of AIM shares in my Portfolio and I find the key to being a successful investor is picking high quality profitable growth companies which have bottom left > top right momentum with rising EPS... this gets you so far. However, the other important part to being a successful investor is to avoid the poor quality loss making dross. I learnt many years ago that by avoiding the dross makes a huge difference to my Portfolio returns. So far this year my Portfolio is up + 18.5% YTD. To view the shares I hold just click on my avatar / name. If only I had bought CMC MARKETS but you can't win them all.
David.
There’s also a big investment world beyond AIM, including small companies not on AIM, bigger Companies, those paying big and sustainable and increasing dividends, etc as well as Investment Trusts enabling us to invest all round the World. A balanced portfolio with a wide range of investments that can include AIM shares is a good way to go. It’s worked for me if that’s any help!
Yes Ken I agree with what you say. Hence the reason why I don't limit myself to just owning AIM shares, its about having a Balanced Portfolio. In fact when I was typing my response I thought of you and your article 'Buy Quality at Bargain Prices. It Works'. This is very true and it does work.
Buy Quality, avoid Dross.
David.
Space and Peopke
I must admit to being somewhat confused as to the coverage it has received on stocko.
On many occasions i recall it has been said “we don’t cover nano caps below 10 million. Market cap “
Nothing wrong with covering SAL but a bit of consistency would be good to see .
Can we take it that nano caps are going to get coverage in future or is it limited to the companies that stocko reviewers hold ?
I’m fine either way but does seem a touch inconsistent to give good coverage to a nano cap 1.8m market cap after failing to comment on others in the past year or so often quoting the “too small for us to cover “ story .
I’ll probably get shot down for this .
Hi PlanetX,
On many occasions i recall it has been said “we don’t cover nano caps below 10 million. Market cap “
Nothing wrong with covering SAL but a bit of consistency would be good to see .
Can we take it that nano caps are going to get coverage in future or is it limited to the companies that stocko reviewers hold ?
It's fine to query anything! :-)
I recently started doing a new section under the companies reporting list, called "Mid-morning movers with news". These are just quick notes from me, on large % daily movers, if there has been some significant news.
SAL fell into that category yesterday, so it was nothing to do with me happening to own the shares personally. I'd read the accounts quickly anyway and made notes, so it was dead easy for me to type those up in about 5 minutes.
The main sections, where we devote most of our time each day, are mostly focused on £10-1bn market caps, and we're tending to do less of the smaller companies where they're only trading in line, as they're less liquid.
Also I'm on a personal mission to exceed last year's coverage of 609 unique companies in 2024!
So the golden rule here is mainly that anything we see which looks interesting, we'll try and do at least a short note.
Best wishes, Paul.
good presentation SAL , no chance of delisting anytime soon ! (question asked )
Hi M B3,
Yes I liked what mgt at Spaceandpeople (LON:SAL) [I hold] said in today's webinar. As you say, CFO emphatic that de-listing is not being considered, and that being a listed company brings benefits to SAL.
International expansion - existing operations in Germany are to be used a springboard for expansion into Austria, also mentioned possible France and Luxembourg. Driven by requirements of the shopping centre owners.
Network Rail contract is important, being re-tendered from Sept 2024. Can't disclose details, as commercially sensitive.
Rock Up & Pop Up - new format kiosks have been well-received, particularly in higher end shopping centres (eg Westfield) and scope to further expand.
Current trading - good start to 2024, ahead of last year, so far pleased. H2 weighting seasonality is normal. CEO - "back up & running again, with a vengeance"
Dividends - not a priority for now, debt reduction is more important.
Broker note - out today from Zeus (is on Research Tree). Not madly exciting, with PBT expected to rise from £103k to £185k. Personally I'd be disappointed if that's all they achieve!
"Core" - new website to help brands access data.
My view - surely it's got to be worth more than £1.8m market cap!?
Regards, Paul.
Spaceandpeople (LON:SAL)
My view - surely it's got to be worth more than £1.8m market cap!?
the problem is they have spent many years generating nothing meaningful for shareholders - so i can see why the market isnt going to give them the benefit of then doubt until there is more evidence of something for shareholders is more tangible (divi - profit jump?) . on the flip side they did back in the day make profits of £1 mill even £2 mil plus pa so at least they have been there and delivered before. deffo potential decent upside - but there has to be the danger they subsist only enough for mangement to take their salaries.
Aberforth Split Level Income Trust (LON:ASIT) roll-over announced today in a new c£100-150m investment trust, Aberforth Geared Value & Income Trust plc. For those that don't know of this it is the geared and smaller "mirror image" of Aberforth Smaller Companies Trust (LON:ASL). I think it's the 3rd roll-over. The first two vehicles were very successful but the 3rd and existing one hasn't made a positive return, before dividends. I will roll-over into the 4th vehicle - they normally have a 7 year life and have a dividend yield of c5%+. Given the leverage of 30-40% though ZDP shares they are higher risk, but higher potential reward.
Aberforth Partners are a well known value style UK small-cap investor with a c30 year record of achieving c10% per annum. On the law of averages, I would expect the next 7 years to be better than the last 7 years, so possibly worth backing. The unlevered investment trust is safer, but both employ the same investment style. Anyway, thought I would flag to readers. There is also going to be a placing and offer for subscription. It will be launched on 1 July 2024.
Thanks for mentioning Topvest
Spaceandpeople (LON:SAL) does look like its turned a corner. H2 results is pretty good, operating profit went from £311k in H2 to £594k! Quite an improvement, albeit all small numbers.
I agree with Paul - seems like a lot of company for £1.5m market cap. No debt risk it looks like, only 0.3m due in Jan25, and they should be able to generate enough FCF to pay it down in FY24.
The key issues for me are:
If ignoring all this, they could be set up to do like £400k+ of operating profit in FY24 I reckon, which would be some achievement on a £1.5m market cap.
I thought perhaps the fall of Seeing Machines (LON:SEE) might have been overdone after poor figures and Paul's red card. My punt has been successful, and the plan has been to sell: but now I'm wondering. Paul's strong red was based on a large debt due in 2025, and doubts about the long term demand for the product. He sees self drive vehicles taking over in the medium term, but I can't see it happening in scale in congested urban areas within the very long medium term, and then slowly, leaving a long profitable tail for SEE. If the bull case holds, I don't see a huge problem with the debt. At worst, I would expect the existing lender to roll over the debt in exchange for a lower conversion price.
Or is this all rubbish?
Hi sheeza,
Actually I'm quite positive on Seeing Machines (LON:SEE) now, after having discussed my concerns with management a few weeks ago.
The point I'd missed is that EU regulations look set to drive demand strongly upward for SEE's products, and management reckon this should drive a high margin, operationally geared surge into profits.
They also reckon the cash remaining will be sufficient, and the debt should be repaid or refinanced in due course. So quite a few ifs there, but they also talked me through the competitive situation, which looks very good for SEE, if what they told me is accurate.
£182m market cap (at 4.4p/share) is punchy for a company that has not yet delivered a profit, and has massively diluted through lots of fundraisings, but the bull case is actually quite compelling due to car manufacturers facing legislation which means they have to fit this equipment to new cars fairly soon.
So I'm probably now thinking AMBER, with a possible leaning towards AMBER/GREEN, but that's based on management assurances, which can be dangerous!
Regards, Paul.
Seeing Machines (LON:SEE) probably also worth adding something around cash burn. If you extrapolate last years burn gross cash looks tight but in reality net cash outflow should be down to a a run rate of around minus £1m by end of this FY. The Directors confirmed that in a recent call and given they were already halfway through H2 I assume they were pretty confident in that regard.
So the key elements are demand and refinancing of the convertible. The latter looks easily achievable assuming cash flow positive (and would be beneficial as avoids any equity dilution). The former I have minimal concerns over at a macro level. As Paul points out the EU regulations are driving strong demand. The concern I have is over short term timing of demand - that concern diminishes if the business has achieved monthly positive cash flow though.
I disagree with Paul that £182m is punchy - this is one of about two global market players in this space. The size of that market going forward is enormous and Seeing Machines (LON:SEE) has a level of credibility that can only be built over many years. I do hold some (not a big position) shares and my hope is that someone doesn’t swoop in to buy the IPR given the weak share price. I contend that the value of this business IPR is a multiple of existing market cap. The job of management is now to avoid getting lowball bids and grow the share price.
DG Innovate (LON:DGI)
Apparently the Mrs of the company’s Chief Technology Officer and an Executive Director has been selling shares but not disclosing any of the sales simply because she did not know the rules.
Nice one!
Sucker Stock says Stocko Algos! DG Innovate (LON:DGI)
Re: Woodford blog. I get tired of articles selectively using statistics as he has done in order to paint the picture he wants, Just simple pieces of misdirection such as using a median rather than mean average as he does can change things completely. And then you have selective unscientific drawing of chart axes to misdirect. The government do it all the time to fool people and make things look better than they really are. If you can’t see this then you should read The Art of Statistics by Prof Sir David Spiegelhalter.
Besides, we get a much better picture of the real UK economy by reading company results and trading updates every day. As such, I don’t recognise the economy Woodford describes.
Happy Warpaint London (LON:W7L) holders here - and there must be many - will be further pleased to note that JP Morgan Asset Management has increased its holding 3.5% to 8.7%. With institutional support for UK small caps all too rare, this seems a notable endorsement. And a note to pusillanimous UK pension fund managers!
Mello 2024 news...We will release the names of the first ten companies that are joining us at the conference tomorrow and we should end up with close to 40. Warpaint, Time Finance, Polar Capital and The Property Franchise Group (including Belvoir) will certainly be there for starters.
Mello2024 – Mello Events
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24 BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
Are there RNS issues this morning on Stocko?
For example, Camellia (LON:CAM) has a Final Results out at 7am this morning, but Stocko is not showing the RNS yet.
Sorry to offer a gloomy view, but, while the media is undoubtedly negative and the UK may be turning the corner, politically as well as economically, it’s important to remember that the performance of economies ultimately reflects their relative exposure to two major factors, cheap energy and technological advancements. Here we have potential in wind power but a somewhat disappointing level of achievement to date, while in tech we are quite simply dead and buried - a position from which there is no coming back without a remarkable, and unlikely, shift in industrial policy that would carry significant risks and no guarantee of success. It will still be possible to make money in small companies over short intervals, but I’ll be locking my long-term money away in much stronger economies, which only a tiny number of high-quality UK companies are adept at exploiting - and I wouldn’t dare restrict my choice to those UK champions.
Have a look at ARIA, a state funded attempt to harness blue sky thinking.
Disagree re wind power we have done well by comparison with many countries I believe.
Disagree re wind power
But not really better than other countries with comparable wind resources. And until there are wind farms in the Cotswolds, Chilton and South Downs, I maintain that we aren’t taking it seriously
We are a world leader in wind power.
Just come here you can see loads. Now my area is being wrecked to bring the power on land.
Storage is the problem, if you build much more, we will have too much on windy days, but then not enough on still days.
In trying to assess the place for my savings I am very aware that wind power in the UK has been a significant investment and while covering the UK in wind turbines can give more, the efficiency of this investment is highly questionable, even on the lower cost of onshore installations. We have about 28GW of installed capacity. Today, a fairly windy one, we are getting 9.9gw and while that is 29% of our requirement it is pathetic capacity usage, and certainly leaves nothing to boost up any (currently minimal) battery storage. Although I look with interest at Invinity Energy Systems (LON:IES) for signs of massive commitment. Over the weekend wind was contributing as little 4% of our needs so any back up has to be (unrealistically) enormous. The steel, concrete, and high ongoing maintenance, while contributing to possible good investment in those areas does nothing to help wind’s net environmental impact (before we even talk about thousands of hard to recycle blades).
So at some point reality will take hold here- as abroad - and we will get serious about nuclear, where there really does seem to be an investable future.
I think wind farms are hugely expensive and inefficient ,particularly without a means of storage. They are environmently damaging very unlikely to repay their carbon footprint. CO2 in not our enemy, the planet is greener today than 20 years ago, and we able to feed the growing world population thank goodness for photo synthesis
They built the farms but not the grid - duh!
Offshore wind farms are great for fishes - trawlers daren't fish too close to them, so they create a protected area for fish to spawn - marine conservation no fishing zones.
Expensive bollards.
Yellow Cake (LON:YCA) released an update today, it also noted development by some countries regarding nuclear generation.
https://www.londonstockexchang...
There's a great Meryn Talks Money Podcast on this topic - the one with Kathryn Porter I think. In summary it says we have maxed out on wind power and need to stop subsidizing it any further. Batteries are a long way off and exports don't work as everyone has excess wind power the same time as we we do. I'm with you on this Mike.
There's a great Meryn Talks Money Podcast on this topic - the one with Kathryn Porter I think. In summary it says we have maxed out on wind power and need to stop subsidizing it any further.
You need to be careful who you listen to and consider what their position is. I heard that podcast and then looked up Kathryn Porter. She’s a well known climate sceptic and mouthpiece of the Oil & Gas industry. What we need is facts, not unfettered biased opinions.
If I’m thinking of the right podcast, Berksbee, then I agree that it was interesting. Link to the episode website here: How to reach net zero within a capitalist system
Edit: realised this is with Akshat Rathi, not the Kathryn Porter you mentioned...
Or presumably this one with Kathryn Porter, who you mention: Why nuclear power should be ramped up
If you want a great podcast on wind generation I highly recommend ‘Britain’s a Gonner with Wind’ from the team at Argonaut Capital: https://www.argonautcapital.co...
As far as I know I don’t believe they are linked to the oil industry. And just as an aside I don’t understand why people can’t seem to accept that two things can be true at once i.e. climate change is a fact but wind generation is not necessarily the right solution given cost, intermittency, etc. As has been mentioned upthread it seems to surprise some that wind turbines depreciate too. And the ones at sea doubly so given the unforgiving saline environment. Most wind turbine blades cannot be recycled and hence cause a massive issue at end of life. But the key issue is the intermittency. We are not even remotely close to having solved the electricity storage problem. Note this is not just a question of beefing up the grid to get the electricity from X to Y. It’s having the storage. The only solution right now is nuclear. Rolls Royce has some of the best small modular reactors in the world. Presumably with modification they could be used in the civilian market. Why aren’t we helping them to become a world leader instead of subsiding incremental wind power and HS2? The UK is condemned to life in the economic slow lane until we have a Damascene conversion in our approach to energy, amongst many other things…
Rolls-Royce Holdings (LON:RR.) despite their expertise in subs don't expect to have a SMR up and running on land till the early 2030's.
Governments and utilities wont want to invest in theoretical reactor concepts. High risk high reward. Huge rising cost per MW of energy. See Nuscale Power (NYQ:SMR).
Of the larger France's Flamanville 3 has an estimated cost of $15bn 4x the forecast when started and construction has risen from 4.5years to 16 years. These costs translate to expensive electricity - which of course will be sold to the UK.
It seems nuclear is the ONLY net-zero tech out there but it will take years of fossil fuels to get there.
The elephant is the distribution systems to get it around the country with the switching and kit to balance the power and intermittency. Don't know about batteries, they will play a part but huge container like storage, really? gonna need a lot more mining.
So I'm looking at the infrastructure companies doing the building, miners, cable makers, road digger uppers, plylon constructors, steel makers, cement grinders and the stuff to control this 'power'.
I suppose it will still need insulation in the form of oil derived pvc.
Lets hope some 'bring spark' comes up with something new, or perhaps the aliens can revisit Area 51 and give us a boost.
The 2030s are not far away for nuclear to be a key part of our energy pattern, and ten years of oil and gas to make it happen is not a problem given the number of solutions that follow from widespread electrification. But nuclear has another advantage: the serious costs of building out more grid strength is increased by/bringing offshore Scottish wind energy to the heavy usage areas in the Midlands and South. More flexible placement of nuclear facilities allows some of this long distance power transfer to be avoided.
But the ten years has to start now and include the production of the fuel rods for our security, and the two years required to produce sufficiently enriched uranium only starts after we acquire or build the necessary centrifuges. Every pound spent on wind delays this.
There's a thriving startup, privately held tech industry in the country.It's currently ranked as third in the world behind the two current (current/future?) superpowers, USA and China.UK tech startups have been valued at a combined £820 billion ($996.8 billion).We have the right infrastructure and talent here at home.Hopefully some more might be persuaded to list on the lse in the future to allow us uk ibnested punters to grab a piece of the promising future action without onerous forex fees.Darktrace (LON:DARK) is/was one.
Thanks Paul for the Woodford links. He was always a great read and these initial blogs are excellent. He is always very positive about the UK, unlike many others. Just think how good the UK could be if the media view was positive and not so negative all of the time.
I was very negative on Woodfords investment strategy well before it imploaded and repeatedly warned that the outflows would leave investors with toxicity as the liquid shares were sold. Interestingly, I am still trolled on ADVFN many years later by at least one person that lost money with Woodford because I pointed out that his illiquid small-cap punts would bring down his open-ended fund.... which it did. Every single post I make on ADVFN about anything is still voted down immediately some 5+ years later!
Anyway, Woodford has paid a heavy price for his poor investment strategy and deserves a second chance........ at least to be heard, in my view, as he is an excellent commentator. Investors that lost money have had some compensation from Link......and should learn from their mistakes....... as we all have to do most weeks!
'Woodford has paid a heavy price for his poor investment strategy'
Woodford continued to withdraw £100,000 a day in management fees from his fund even after his investors had been prevented from withdrawing their money. This was a disgraceful instance of an enormously wealthy man showing contempt for the small investors who had placed their faith in him.
I agree with you John2 that Neil Woodford should have made more of a personal financial contribution to the losses incurred, for example through fee waivers. If he had done so, he wouldn't have been treated as harshly. I think he is still being pursued anyway by the FCA. He has certainly paid the price in being depicted as a villain and not being allowed to invest other people's money.
What I don't really agree with is the creaping compensation culture!
If you look at Neil Woodfords small-cap investments over 90% of them were absolute disasters and I don't believe any of them were massive multi-baggers in the end. Can anyone name a successful one? Despite the denial, he definitely changed his style between Invesco and Woodford - he did have a small weighting of eclectic stocks and speculative micro-caps, even at Invesco, but then went in very big at the speculative start-up end both in his investment trust and the open ended fund. Very diifferent to investing in tobacco stocks and the patient capital vehicle never recovered any real value!
"If you look at Neil Woodfords small-cap investments over 90% of them were absolute disasters"
This seems an unusually bad performance.? I suppose that Woodford might argue that this is due to a forced wind-down of private non liquid assets rather than planned disposal.
Even so, I doubt that Woodford will get much sympathy.
In my view Woodford was clueless. He was right place right time to run an income fund and own Utilities that were just recently listed and completely mispriced. Hence a great source of income and capital growth and why they were almost all taken over.
To think that this is somehow preparation for unlisted tech/biotech investments just tells me how arrogant and lacking in self awareness he was. I cannot have any sympathy for someone so clearly taking the piss and getting paid for it. This fund was totally mis sold.
I ran a desk at one of the big investment banks with over a 100 traders. The market has always been full of people who don't truly understand why they made money but assume it was somehow their innate "brilliance".
Very true MH1 - the old adage of “rather be lucky than good” I think.
I agree with john2 about Woodford exploiting private investors. I think it is fair to say that Paul's surprising attempt to act as an apologist for Neil Woodford has failed. The sooner he disappears (Woodford, not Paul) the better. Woodford has demonstrated an appalling lack of judgement so best of luck to anyone who reads his blog. Incidentally, I did not lose any money with Woodford but my sympathies lie with those private investors who did.
Why is Woodford being discussed on the SCVR? Promoting his new blog is imo an insult to all those investors who lost money.
A nice start to the week with the pointer to Woodford Views - I’ve just had a read and have long held the view that the media incl. X are so inclined to be negative, surely the opposite will be more rewarding. I’m not sure why so many people who weren’t there to tell us to invest feel compelled to tell us not to. Particularly on Twitter. Anyway thanks for being open minded and pushing me to have a read of Woodford’s Views …. With so many others so willing to highlight all the negatives I feel the probability is high that negatives rather than positives are affecting UK indices recent past.
Well I have to say Paul that I would much prefer to hear your views than those of Neil Woodford. Have a great day!
Paul Thanks so much for your podcast, particularly about the driving licence. Of to Scotland tomorrow. Just looked at my license which is out of date! How many others are in the same position? Never had a reminder.
Echo the sentiments about the podcast, excellent education and entertainment at the same time! I also wanted to point out/remind listeners there is a full transcript of the audio on the podcast home page which I discovered yesterday and helps if one forgets the names of stocks amid the avalanche of info! Cheers Paul and have a good week all!
Thanks TheOx2906!
This is news to me -
I also wanted to point out/remind listeners there is a full transcript of the audio on the podcast home page which I discovered yesterday and helps if one forgets the names of stocks amid the avalanche of info!
Could you point out where my podcast transcripts are, as I've not seen them!!
Thanks, Paul.
Hi Paul it’s on Apple Podcasts, when your new episode arrives, scroll down to the bottom of the episode link and it’s there, very clever, I’ll try and paste a link;
https://podcasts.apple.com/gb/...
Re podcast transcripts, that must be something specific to your player. I use RadioUk where I get online radio stations too, and no transcript on there but it's free. Which do you use?
Samsgrandad
I refer to your post/ comment last week. I located my own comments as you suggested. However I could not find posts/ comments of others. Could you please describe the process again to achieve this.
Also is it possible to access the past posts/ comments of a contributor?
Seems could be confusion between the terms post and comment?
Hope you can help. Thankyou. KBR.
KBR - in the absence of other replies perhaps this will help you and recent subscribers:
In Stocko terminology what I am writing is a comment. The post is today's SCVR started by Paul but anyone can create a post.
To find the activities of others simply click on their name and that will bring up a screen with their profile. On the bottom left are two tabs 'About' is the one you are on so click 'Activity' and you will get this:
On the right you can click 'All recent activity' to give a menu with Posts or Comments only.
Thanks for that Sharw and apologies KBR for not getting back. A picture speaks a thousand words and I was away from my laptop whenever I had time available. Tried explaining on the phone but gave up.
Don't forget if you're over 70 your license needs renewing every 3 years. You can apply 90days before.
For those of us who were Bidstack (LON:BIDS^D24) shareholders (small holding for me but a wipeout for everyone) and may not have seen the intersting development of a shareholder group that's seeking redress for how the saga ended: https://www.bidstackshareholde... Do register to show your support and spread the word.
Sorry to hear Quilleron and best of luck with the shareholder group.
Regardless of anyone's thoughts on the business I think it shouldn't be legal that existing directors can let a business fall into administration then pick it up for themselves on the cheap. To the best of my knowledge no equity placing was offered - usually in these situations every broker has it to pass around but I didn't hear of one.
Same happened with MPM and the directors got a decent business for very little, and shareholders were wiped out.
Nice rns from Metals Exploration (LON:MTL) , not one for Paul but maybe Ed can make a guest appearance as it is one from his NAPS portfolio.
Nick Candy owns 43% of the company, and he did unload 3% of his holding last Thursday and the price dropped 10% on the day, only to go up 12% on the Friday, so it could be volatile if he continues to unload, but someone is picking them up.
My morning smallcap tweet: Finger on the pulse or hand on the jugular?
Petrofac (LON:PFC) Biome Technologies (LON:BIOM) Literacy Capital (LON:BOOK) Induction Healthcare (LON:INHC) Smarttech247 (LON:S247) Quadrise (LON:QED) Libertine Holdings (LON:LIB) Zenova (LON:ZED) Digital 9 Infrastructure (LON:DGI9) DP Poland (LON:DPP) Sondrel (Holdings) (LON:SND) Image Scan Holdings (LON:IGE)
◄Petrofac (PFC)► FY23 delayed till end May. Shares suspended from 1 May till publication. d4e and re-capitalisation talks progress. Will miss next coupon payment. Will miss FY23 f/c. [SP=22.3 Cap=117m]. I'm short.
◄Biome Technologies (BIOM)► FY-Dec. Also guides Q1-Mar rev down 44%, slightly lower than mgmt expectations. Blames shipping delays and production and regulatory difficulties at two end customers. Still guides FY24 in line. [SP=109.6 Cap=4m]
◄Literacy Capital (BOOK)► book value 510.4p/sh up 2% over Q. [SP=510 Cap=303m]
◄Induction Healthcare (INHC)► guides FY-Mar rev up 3.7%. Adj EBITDA c. £0.3m, in line with mkt exp. Wasn't the rev in line then? [SP=12 Cap=11m]
◄Smarttech247 (S247)► wins $2.1m 3 yr contract. [SP=19.9 Cap=25m]
◄Quadrise (QED)► still negotiating contract with Cargill which was expected by end Mar. Nevertheless co "does not expect any material delay to the overall MSC vessel trial programme at this time". [SP=1.68 Cap=29m]
◄Libertine (LIB)► Strategic Review & Formal Sale Process. "Further resources are required to advance the technology into customer programmes and full commercialisation." An understatement since cash runs out in July. [SP=4 Cap=6m]
◄Zenova (ZED)► £2.4m two year FP fire protection coating order. [SP=1.82 Cap=3m]
◄Digital 9 Infrastructure (DGI9)► receives deferred consideration payment of $25m. Will make c.£47m RCF repayment. [SP=21.17 Cap=183m]. I hold.
◄DP Poland (DPP)► guides FY23 EBITDA in line. Current Q1 LFL system sales growth of 17.9% in Poland. [SP=10.9 Cap=100m]
◄Sondrel (SND)► squeezes out another drib of news. Completes tapeout milestone on ASIC engagement for a Tier 1 OEM Automotive customer. [SP=4.15 Cap=4m]
◄Image Scan (IGE)► wins c.£300k initial order for portable X-ray systems. Further orders are expected over the period of the partner's two-year framework contract. [SP=1.14 Cap=2m]
Welcome back MrC, your daily summaries much missed during their absence.
Thanks for the link to Woodfords Views Paul - very interesting and a good read. It is great to have someone shine a light of positivity on the economy for once. I for one am sick to death of the mainstream media being overly critical and extremely downbeat continuously.
The mainstream media is a mirror on societies feelings, my view is the mood is poor and the press reflects that, the mood changes so will the media’s tune.
The Uk stock market looks like it’s starting to turn and I generally think we’ve hit the bottom in terms of the mood of the UK. Our decaying infrastructure aside, but that will ultimately need fixing and that will in itself drive growth.
not sure I agree it seems to me that the mainstream media with its leftest idealogy has constantly been downbeat on Britiain to point of not reporting facts honestly or fairly. Its one thing to be anti government its quite another to be anti british
The trouble is that Woodford is talking about GDP rather than Per Capita GDP. The former is up, the latter is slightly down on 2014 numbers.
So the country is a little richer, the individual isn’t. The difference is migration.
Legal migration, for the avoidance of misunderstanding in the currrent political climate.