Small Cap Value Report (Mon 3 April 2023) - NUM, PEEL, TRCS, D4T4, WHI, SCE, CINE

Good morning from Roland and Graham!
Today's report is now finished (10am).
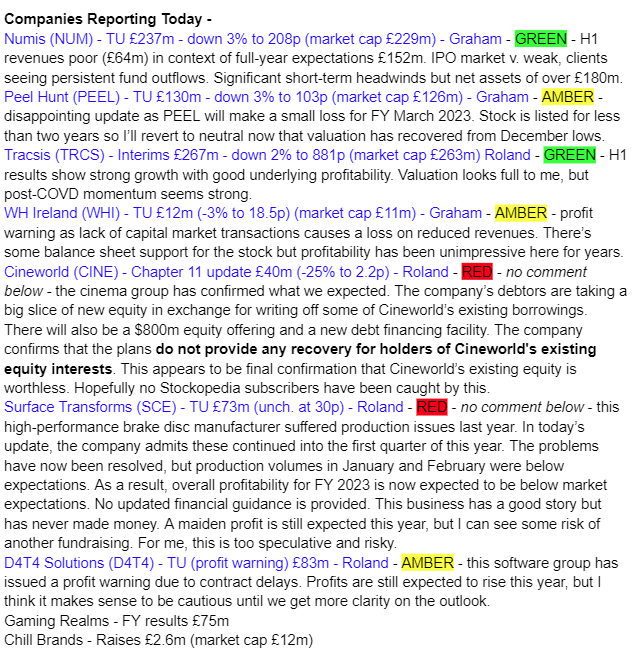
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Roland's Section
Tracsis (LON:TRCS)
- Share price: 895p (pre-open)
- Market cap: £267m
“Unchanged expectations for the full year”
This company provides software and related services for the rail industry in the UK and North America. Tracsis is an AIM success story that’s four-bagged over the last 10 years and 20-bagged since its 2007 listing.
It’s not such a small business anymore, though, so I’m interested to see if the growth rates and profitability seen in the past can be maintained.
Today’s half-year results cover the six months to 31 January and appear to show solid growth in both revenue and profit:
Revenue: 34% to £39.2m
Adjusted EBITDA: +21% to £7.5m
Statutory pre-tax profit: +76% to £2.3m
Interim dividend: +11% to 1p per share
Net cash: £17.0m (July 2022: £17.2m)
It’s probably worth pointing out that last year’s pre-tax profit was depressed by various acquisition-related costs, so the increase in EBITDA is probably more representative of the underlying growth rate here.
Operating update: Tracsis has two main operating divisions. Both appear to be performing quite well:
Rail operations and planning (revenue +43% to £7.6m): this provides software solutions to help with staffing and operational planning. Around 20% of UK rail journeys are said to be supported by the company’s flagship TRACS Enterprise system.
A new deployment of TRACS went live with a UK train operator in January, but these large projects are typically quite lumpy and the next full TRACS go-live is not expected until the next financial year.
Digital Railway & Infrastructure (revenue +76% to £8.8m): this division is primarily involved with remote monitoring of railway network equipment and other safety and risk management services.
UK sales are linked to the five-year investment cycles (control periods) of the UK rail network. The company has “several large contracts” for the supply of RCM equipment through to the end of the current control period in March 2024. Visibility beyond that appears to be more limited, but my impression is that Tracsis is quite well embedded in this market.
In North America, demand for RCM products is said to be increasing, with new orders from an existing customer and a number of new customer trials underway.
Balance sheet & cash flow: free cash flow for the first half of the year was less than £0.5m due to a £4.7m increase in working capital and a c.£1m payment of contingent consideration for a previous acquisition.
However, the company says this reflects normal seasonal trading patterns. Stockopedia’s data reflects this, confirming that the business is normally more cash generative in the second half of the year:
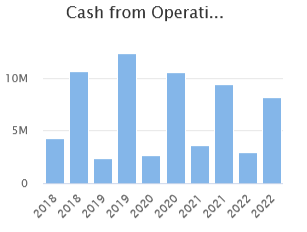
Tracsis’s net cash position continues to provide a strong underpinning for its growth. However, I note that the balance sheet shows nearly £9m of contingent consideration for past acquisitions, of which £8.1m is due in the next 12 months. So perhaps we should adjust down the true net cash position, slightly.
Profitability: One point that’s probably worth making is that the company’s acquisitive business model has depressed its reported profitability in recent years.
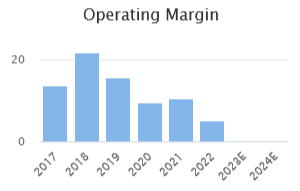
This has happened because each acquisition has typically included a proportion of intangible assets (software, brands, customer lists). These are booked on the balance sheet and then gradually amortised (written off), resulting in a corresponding deduction from profits.
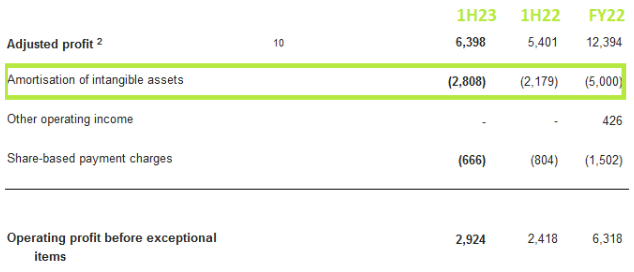
These amortisation charges are non-cash today, but they reflect capital allocated to acquisitions in the past. I think they’re worth considering to understand the success of past capital allocation decisions, but they don’t affect the free cash flow of the business today.
Adjusting out these amortisation charges gives Tracsis a trailing 12-month operating margin of around 15%, by my calculation. That’s significantly above the 9% figure suggested by statutory operating profits.
Outlook: management says that Q3 has started strongly and that full-year expectations are unchanged.
There’s an updated broker note from finnCap available on Research Tree this morning. Earnings forecasts for the current year have edged up from 37.1p to 37.3p per share. That’s broadly in line with Stockpedia’s consensus estimates of 36.6p.
These numbers put the stock on an adjusted forecast P/E of 24x for the year ending 31 July 2023.
My view: Tracsis’s acquisitive business model appears to have worked well to drive growth and create new expansion opportunities.
I’d like to do further research to understand the profitability and growth profile of the different businesses within the group. But on balance, my view on this stock remains positive.
In terms of valuation, I’d probably be more comfortable with a P/E of under 20x earnings. The shares first reached their current level nearly two years ago and have made limited progress since then.
However, taking a longer view, Tracsis has been an admirable investment for patient investors. My guess is that this could remain true.
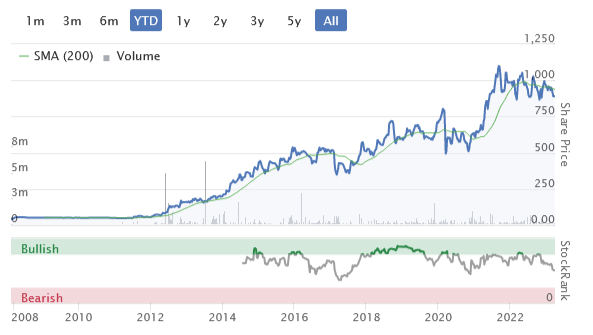
D4t4 Solutions (LON:D4T4)
- Share price: 173p (-16.5% at 09.00)
- Market cap: £69m
Today’s trading update from this AIM-listed data solutions provider is unfortunately a profit warning.
D4T4 Solutions’ products are used to help companies to manage and extract insights from their customer data.
Checking back in the archives, Paul commented in December that H1 results were not very good, showing a £1.3m loss. However, the company’s results had historically had a strong H2 weighting, so this wasn’t necessarily a problem.
Contract delays: The company says that it’s encountered delays signing two contracts. One of these is with an existing banking customer, while the other is with a new customer for the company’s Celebrus system.
My guess is this may be the same contract wins announced here in November, but I should stress this is only an assumption.
D4T4’s financial year ended on 31 March, so this clearly came down to the wire.
Trading update: management says that annual recurring revenue from software and related services is expected to have risen by 14% to £16m during the year just ended. I’d imagine this should drive an increase in profit margins, although this isn’t explicitly confirmed.
The company says new wins during the second half of the year included a bank in Spain, a US healthcare organisation and an Asian insurer. A “key upsell” was also secured with a US bank client.
Revised guidance: Helpfully, the company has provided clear guidance on the financial impact of these contract delays:
FY23 Revenue: £21.5m (FY22, £24.5m, previous forecasts: £28.1m)
FY23 adjusted pre-tax profit: £3.5m (FY22: £3.3m, previous forecasts: £4.2m)
While D4T4 still looks set to deliver double-digit profit margins this year, we can see that profit growth this year is likely to be fairly minimal, compared to previous expectations.
My view: I’ve always had a fairly positive view of this business, which has a long track record of revenue growth and (mostly) double-digit profit margins:
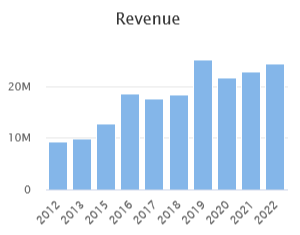
However, profitability has weakened over the last couple of years. Management said last year that this was due to a temporary increase in sales of low-margin third-party products.
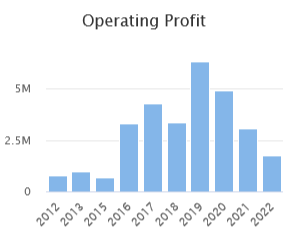
This mix was expected to improve in FY23, so I’ll be interested to see how margins have improved over the last year, perhaps driven by the higher recurring revenues.
By my estimate, today’s profit warning has left D4T4 shares trading on c.22x FY23 earnings. That seems high enough to me for now. Profit warnings often travel in company, so I’d like to see the company’s FY23 results and get some visibility on the outlook FY24 before forming a more detailed judgement.
Graham's Section
Numis (LON:NUM)
- Share price: 208p (-3%)
- Market cap: £229m
Numis is one of the higher-quality investment banks I cover. This morning. it gives us an update for H1 (the period to March 2023).
Revenue will be c. £64m, which is 14% below H1 last year.
This doesn’t sound very good in the context of full-year revenue expectations of £152m. To hit expectations, they would need to generate £88m in the second half.
Let’s check performance at each of their divisions:
1. Investment Banking
In the first half we have continued to build on the successful diversification of our UK investment banking business…
In line with the broader industry, capital markets revenues will be materially lower than the comparative period. Whilst our ECM market share in the UK has increased relative to FY22, overall market levels of issuance remain at historic lows.
Numis has broadened the scope of its investment banking activities, to help shield itself from the volatile UK stock market fundraising cycle. Unfortunately, it sounds like the volatility in this division is still at an uncomfortably high level.
2. Equities
Numis has expanded its EU-focused activities and reports that its European client base continues to grow.
Back at home, domestic funds saw “persistent fund outflows” during H1:
As a result, institutional income was lower than the comparative period and our trading profit was flat over the last two months of the half year as market conditions remained challenging.
Outlook
Numis is positive on the flow of advisory work for its investment banking business, but it doesn’t see any meaningful improvement in IPO activity during this financial year.
My view
This update doesn’t read very well to me and I don’t think other investors will like it much, either.
I still think Numis is a high-quality operation and referring back to my previous notes, the company had net assets (that were nearly 100% tangible) of £185m as of September 2022.
That’s very significant asset backing at the current market cap. I will retain my positive view on the stock, which I initiated at 183p and which is based on my view that the current conditions in the equity market can’t last forever. However, there’s no denying that the short-term headwinds are significant.
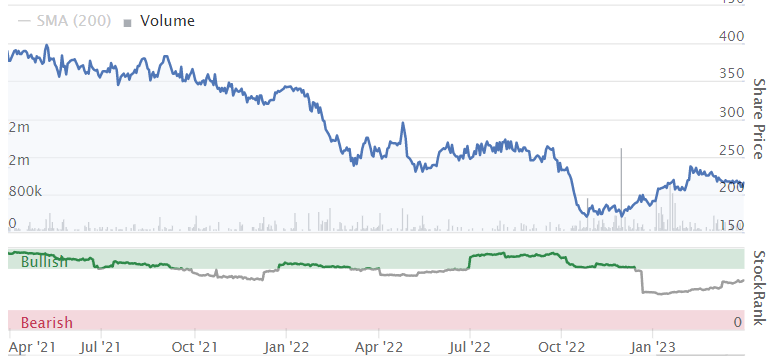
Peel Hunt (LON:PEEL)
- Share price: 103p (-3%)
- Market cap: £126m
I warmed to this stock in December 2022, after it published reasonable H1 results.
Now we have a full-year trading update (FY March 2023).
Revenues are £82m (FY 2022: £131m), with “capital markets activity at historic lows” throughout the year.
Investment banking revenue will be much lower than the prior year.
Trade execution revenue is also down year-on-year “due to lower market volumes”.
Research revenue is “resilient” although is also likely to be down by a few percentage points compared to the prior year.
I’m disappointed to read that the company is going to make a full-year loss, even if it’s only a symbolic one. Ideally, I like to see a breakeven performance achieved even in terrible years:
Administrative expenses increased following our IPO, as expected, and we have continued to face inflationary cost pressures. Notwithstanding actions taken to rationalise costs, we expect the business will now be marginally loss making for the full year against market expectations of broadly break even.
Strategy - more clients added from the FTSE-350 and like Numis, they are diversifying their investment banking activities. They are also expanding to Copenhagen.
Their retail fundraising platform Rex has been relaunched as Retailbook, a standalone business, and the website looks promising to me.
Outlook:
We have seen a gradual improvement in our pipeline having been mandated across all Investment Banking products during the last few weeks. However, execution risk remains high in light of continuing negative macroeconomic news, most notably the recent bail out of a number of banking institutions on both sides of the Atlantic.
My view
I previously estimated that Peel Hunt’s balance sheet was worth about £90m. When the market cap was around there, I was happy to take the view that it offered investors a value opportunity.
At these slightly higher levels, I’m on the fence between Green and Amber, and I think I’ll stick with a neutral view. My main reason is that unlike Numis, Peel Hunt doesn’t yet have a proven track record of earning profits and dividends for its stock market investors. As a smaller business without such a long track record, it seems a riskier bet.
WH Ireland (LON:WHI)
- Share price: 18.5p (-3%)
- Market cap: £11m
This small wealth manager and investment bank also provides an update for FY March 2023. It makes it clear that this is a profit warning:
The Group continued to be impacted by market conditions throughout the second half of its financial year and accordingly trading is now below previous management expectations.
Revenue is £26m (prior year: £32m) and there will be an underlying pre-tax loss of £2.2m (prior year: underlying PBT of £1.4m).
The reason is the same as for the companies discussed above: “the widely reported lack of transaction activity across capital markets”. The number of retained clients is unchanged.
In wealth management, AUM remains impressive at £1.5 billion (last year: £1.6 billion).
My view
I don’t have a strong view on this one - it seems to offer a decent service to its wealth management clients, but it hasn’t done enough over the years to suggest that its stock is worth buying:
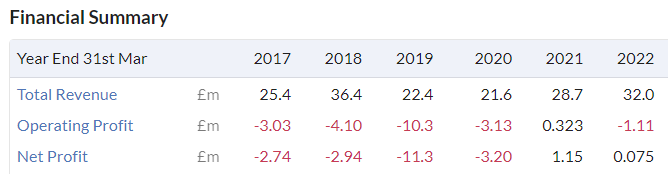
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
D4t4 Solutions (LON:D4T4) (I hold) Trading Update and profit warning. Interesting discussions. Thanks David and Roland for the rapid evaluations.
At first glance it looks like a simple case of contract signings slipping across the year end. Never pleasant though, and under the current conditions I sense that the market is not of a mind to 'take hostages'.
By coincidence I'd just re-listened to the Zeus interview with management (thank you David for the link) and made a note to consider buying more on the next update. Which gave me a dilemma this morning.
Do I tend towards the management explanation of a slippage in contract signings (not that surprising under currrent conditions)?
Or do I err on the side of caution and assume that it's likely worse than management think (also not that surprising under current conditions)?
Not an easy decision. But there is a bit more information in the trading statement that's worth considering I think.
Revenue for the year just ended (FY23) has fallen by a whopping 24% - oddly for this kind of warning - adj earnings appear to have fallen much less - I estimate likely 10-15% depending upon your view of likely tax charge on adj earnings.
Normally you'd expect operational leverage to cause such a fall in revenue to result in higher percentage falls in earnings. The bulk of the delayed contracts is 'low margin 3rd party hardware' - listening to the presentation this is typically 10% margin, wheras the Celebrus propriety software licences billed as Annual Recurring Revenue are typically 70%+ margin. The build up in high margin ARR - just over 74% of FY23 revenue - and just over 50% of FY24 - is making the business much more resilient to movements in hardware contracts, which is a good thing in my book.
Despite the fall in revenue cash generation looks to be good with £17.7m net cash, about 25% of the MCap today, up 6.3m yoy and that's despite paying a 12.5p special dividend in the year. Intriguing. How many growing software businesses are throwing off that much cash?
Management have tried to sweeten the pill with the news that the prospective business pipeline has increased 27% in value with a 4x increase in quotations submitted to new and existing customers. Well they would say that wouldn't they - but the figures are significant and do bear considering.
The problem I've always had with buying more D4T4 is that its tended to be on a high rating. Yes it's still highly rated on todays reduced FY23 earnings, about 23x at the current 175p. Which makes no allowance for cash and assumes that the business has been lost rather than delayed.
If you tend towards management's explanation then after todays fall in SP it looks a lot cheaper on current year forecasts. An unusually low price for the business at just over 15x current year (FY24) earnings - without adjusting for the increasing cash pile, allowing for any one-off contribution in the current year from the delayed business or any futher increase through the improving business pipeline.
I can't know what the future will bring. I do think that the cash generation and high level of ARR gives a good basis for reducing downside risk at the current shareprice - whilst the potential upside has increased thanks to the shareprice and improving pipeline of prospects.
Accordingly I've had another scrabble around down the back of the sofa and spend what little I could find on some more shares in D4t4 Solutions (LON:D4T4) this morning at 173p. I plan to follow up with further buys in the coming weeks to significantly increase my holding.
cheers
Mark
Hi Mark - I am similarly minded. One of the delayed contracts was low margin, the other a high margin ARR. Once this concludes it will also push ARR up above the £16m
I noted in the podcast that the ARR contracts are multiple year non cancellable contracts. They just invoice annually for the licence rather than spread it monthly or as a lump sum.
It is for this reason I lean towards being pretty comfortable with forecasts for the coming year - ie a big percentage is high quality non cancellable ARR with half of the rest made up from the 2 delayed contracts plus an increase of 27% in the weighted pipeline.
This arbitrary Y/E deadline for a profit warning or in-line statement based on a few days delay in contract signing is a bit bizarre. Businesses don't run themselves that way but as investors if it is one side of the line everything is fine, if its a few days later its a problem! with D4t4 Solutions (LON:D4T4) I think a bit longer term. Do I want a business capable of growing ARR 15% for the next few years, throwing off cash, with a net cash balance sheet making up 1.3rd of its market cap and paying dividends? Looks better value to me than many other companies more richly rated.
Being underwater in D4t4 Solutions (LON:D4T4) I bought more shares at 174p as I see that doubling down is the most feasible route to getting out of this hole. It's reassuring to read illiswilgig's view supporting Dave and Rolands evalutions and look forward D4T4 getting off this rocky road.
Slightly off topic - OPEC yesterday said it would cut production in May by 1.6m barrels a day. This is obviously quite good for the FTSE that is heavy in oil stocks but quite negative overall for indices as it will increase costs for companies and likely increase inflation, which may then give the FED reason to continue their interest rate hikes. Looks like the indices will continue to have a choppy time for 2023 still. Any thoughts on this?
OPEC must be playing the market, hasn't oil production already been cut? I hold Gulf Keystone Petroleum (LON:GKP and the Iraq government shut the Kurdistan pipeline last week causing a steep fall in the share price while the price of oil rises. To me this means the pain of a cut is going unshared, for the moment at any rate.
Yes it was cut back in November by 2m barrels
What is interesting is gold normally drops if the likely hood of interest rates go up but this time it’s the opposite because we have seen what the rising interest rates has done to banks. Everything seems to be topsy turvy atm.
https://twitter.com/rudawengli...
The situation is being resolved according to the Iraq oil ministry.
Tracsis (LON:TRCS) Although the stock may not look cheap, unlike most peers, it expenses all of its development costs. While other tech firms are capitalising significant R&D costs, that will come back to bite the income statment in the future, Tracsis continues to expense everything immediately.
As mentioned in your article, the only amortisation that is happening is in relation to acquired intangibles.
If Tracsis were to capitalise development costs like most tech peers, the valuation (P/E etc) would look significantly cheaper.
Elixirr International (LON:ELIX) - results out today are excellent. Finncap's updated their report today - https://www.research-tree.com/... Current PE stands at 16.
Hi Graham - you're wrong on D4t4 Solutions (LON:D4T4) - EPS will be around 12p this coming year with 85% revenue visibility and over £20m of net cash. Its on an adjusted earnings of sub 10* (not 22)
Go check the two broker notes on it as well.
'Will' is a strong word to use...
Finncap have adjusted EPS of 11p in fiscal 2024. That looks like 16.5x? This is assuming you are happy letting them adjust out share-based payments (a real cost) and whatever other restructuring they're liable to lob in there
Net cash is 1/3rd of the market cap
hi davidjhill
D4t4 Solutions (LON:D4T4)
Wouldn't it be more appropriate to ask Roland (not Graham) how he arrived at his estimate of 22x PE rather than to just dismiss it? He may well have some good reasons why it differs from yours.
Your estimate of 12x PE may well prove more accurate in time but it is, after all, still only an estimate.
Views and forecasts expressed on this forum can never be so black and white.
Snazzy
I'm not dismissing it. I know where Roland gets the number from - it is stocko based. My point is that looking at it from that arbitrary headline number isn't correct. Roland or Graham won't have time to dig further or try and understand the intricacy when they are trying to hammer out a bunch of analysis on a series of stocks so it's not a criticism.
To be fair to Roland (not to be confused with Graham) he was referring to the p/e based on FY 23 earnings i.e for the year ended 31 March 2023. According to Stockopedia the forecast earnings for that period are about 8.5p so at a price of 182p that is indeed about 22 - and perhaps more if earnings need to be revised downwards
Not sure it is right to adjust out cash as I suspect this mostly represents customer cash received in advance. A nice position to be in, but not really free cash.
I suspect projections for 2024 may also be revised downwards - are there new broker notes out today, or is the projected figure of 12p from before today's profit warning?
More generally there seems to be a trend of software companies missing revenue targets generally citing longer sales cycles. NCC and Shearwater are other recent examples. Perhaps in the current macro-economic climate we need to distinguish between software which directly drives the bottom line for customers, and that which is just nice to have if you can afford it.
No - it is not advance cash : it is net cash
£6.5 of revenue has just moved from year just finished into next year. combine with the £16m ARR and you can see why earnings haven't been adjusted. more likely to beat forecasts rather than miss them imo. But thats courteousy of the 2 contracts moving into Q1
Btw - this is nothing like Shearwater or NCC. Two contracts didn't quite get signed in time and moved a few days. Otherwise the trading update was actually in line.
Roland, thanks for a brilliant explanation of the effect on Tracsis's profit and loss but not the cash, from previous acquisitions. SImple to understand for non accountants in a couple of sentences.
Some interesting price movements today - eg Sylvania Platinum (LON:SLP) down nearly 6% for no apparent reason ? Wonder. - are people crystallising their CGT gains AND losses.. ahead of the tax year end ?
It looks as though the EPS forecast dropped significantly today (but only seems to be updated on the EPS graph, not on the table on Stocko...). I wonder also whether there is any link to the recent results at Central Asia Metals (LON:CAML), where the recent results missed the forecast by about 3x. I think that it would be a great feature for Stockopedia to show previous EPS estimates vs the reported figures, it is only really possible by looking through the historical pdfs.
Central Asia Metals (LON:CAML) I wouldn't really call it a miss - underlying earnings were all in line. There was a non-cash markdown of one of their mines, mainly just reflecting current commodity prices, which explains the fall in statutory profits.
It seemed to me that a change in net profits from $87.5m to $19m was significant and the Sasa impairement of $55m didnt seem very well explained. It looked to me that zinc prices were higher in 2022 than 2021 (although more volatile), lead seems to be a similar story. Ok, I understand the inflationary costs, but surely this applies across the business, unless the Sasa mine has big wage inflation.. The production volumes dont seem to explain this large markdown, maybe it is based on future reserves. Would love to understand it better if you know !!
Roland explains the subject of amortising and the profit and loss, and its irelevance to cash generation far better than I could in his Tracsis above analysis but I'm happy with the company's paying down debt, cash reserves and future growth of eps from acquisitions. The CAML talk on Investor Meet Company was very good and covered that subject well.
Hi Samsgrandad, thanks for the pointer - I watched the Investor Meet Company Presentation, question answered at 45:32 - so reducing the Sasa asset value on the balance sheet, but insignificant vs the overall life returns from the site. They also do not expect any further impairments, either at Sasa or Kounrad.
For the same reason that when the oil price goes up or down so follows the share price of oil companies. IN SLP's case, its the price of Rhodium, which is tanking.
Sylvania Platinum (LON:SLP) share price is heavily influenced by the rhodium price. It has been on a big decline recently and dropped further from 8000 to 7400 over the weekend. This has come down big time from close to 20000 around a year ago. This will be linked to the drop today I think.
Price of rhodium has fallen off
Amusing headline of the day! Genus (LON:GNS) Animal genetics company Genus announced the appointment of Jorgen Kokke as its chief executive officer-designate
Comment removed.
GKP an oil producing company has shot up more than 15% this morning.
News are out that the oil export from the Kurdistan will resume soon. The oil price rise this morning was the icing on the cake!
GKP dividend is high compensating for the geopolitical risk.
One point to note about GKP (LON:GKP) (I hold) is the last note on the recent update - the Local Kurdish Govt get the revenues and then pay GKP. These payments are often late. It's an additional risk but when the money does eventually come into GKP they often announce a special dividend.
I think Gaming Realms (LON:GMR) is worth a look this morning. A small beat top line, decent beat on EPS. 2023E now look light off the back of the the performance in the first two months?
Sigmaroc (SRC) gone from 44 stock rank to 91 ! Blackrock increased holding by 4.8 m on 28 March 2023. Comments please.
Spancan
SRC thanks for bringing it to my attention.
Revenue up 98%. EBITDA up 106%. Pretax profit 62.7m. Earlier subsidiary Nordkalk won a compensation claim for economic loss (18m$) with Swedish state. Market apathetic.
The 44 to 91 SR does need explanation please from head office.
Well that's Q1 out of the way.
It felt like a long one - with many index points travelled.... but ended positive. UK All share is up 2%.... US a surprisingly stunning 7% and the Nasdaq +17%. What to make of this? Well firstly we should all have hopefully made a positive return.... which is good.
I think the volatility measures VIX and MOVE help... perhaps most importantly MOVE ended at 135 ... having peaked at 200. A number above 150 is extreme stress in bond markets. VIX ended sub 20 at 19....and did not make it above 30. VIX peaked at 80-90 in 2008.... The story of the quarter was increasing conviction that the Fed was behind the curve. My "guess" is record positioning to reflect this in short short dated bond ie 2 year Treasury.... and then this month the banking crisis produced a huge reversal. This propelled the Nasdaq forward which feels like a 2020 repeat .... I have no real view on the wisdom of this move.
For what it's worth my positive UK equities view has not held much sway in Q1. Although they are up the very low relative valuation compared to the US has not made any difference. Never the less I am retaining my position. We have debated the degree to which it matters whether we drift into recession or not. For me, everyone is so negative on the UK it matters a lot less.
In the US the answer is more nuanced - the Nasdaq move suggests the mkt anticipates lower rates and tech to be defensive. This "may" not be true...esp if it's based on the covid experience. We will see.
If rates do fall bonds "should" do ok. I note my positions are up a little....but nothing compared to the income being accrued. The thing is I have to continue to hold them to get the return. This is why I like short dated bonds which I will hold to maturity. Therefore I may get a poor relative return but it should be exactly what im expecting unless I need the money early ( SVB!).
Net net... I would love to take a little money off the table ahead of the summer but we have a month or two yet and in all honesty I need some positions to mature closer to my targets. Large positions in BT (LON:BT.A), Sherborne Investors (Guernsey) C (LON:SIGC) , Volvere (LON:VLE), Serica Energy (LON:SQZ), Fresnillo (LON:FRES), Yellow Cake (LON:YCA) plus a few bottom draw things all retained....pretty much fully invested.
Good luck all.
Saietta (LON:SED) looks to be starting to build a little bit of momentum. Partnership signed in India last month and £5 million contract award announced this morning. Share price has doubled in the last couple of weeks. Revenues just need to be translated into profits for validation that their model is sustainable. As we get closer to Global Nations all electric vehicle target timescales over the next decade Saietta's products do look to be targeting the right sectors. Just fingers crossed there's no need for another fundraise which is a definite risk next year.
Thought it looked completely the wrong price when it hit 20p a month or so back, since when it has trebled. Wish I'd had the courage of my convictions there but alas....
The Chairman seemed pretty confident that revenue visibility meant they would hit cashflow profitability with the runway they had and I think that is important for them to do with regards forward credibility. Todays announcement is a good step in that direction. If Vic can sort out the marine division issues then that business can be worth way more than the current market cap in its own right but we need to see signs of that too.
D4t4 Solutions (LON:D4T4) goes from bad to worse. Clearly, when the former company head stood down and the new CEO was based in the US, they rattled the markets when they said they would be sacrificing shrt term profitability for long term growth. The US seemed to be the market to go for. However, this is happening at a much slower rate than anticipated, and the plan continues ot be kicked down the road. Next year........next year. They seem to have a good product with the Celebrus range but its not happening at the moment. I sold out a long time ago.
why bad to worse? A slight delay of a couple of months on the signing of 2 contracts is pretty irrelevant in the grand scheme of the business longer term.
ARR is up again, cash is strong and underlying growth is good. The market is in a state where it wants gratification now but this doesn't really alter the characteristics of a good business
Net cash is 50p and EPS will be 11.5p this coming year (probably more with the contracts slipping into H1) particularly as ARR makes up 60% of the revenue already. So It is now on a cash adjusted earnings of 10*. That's very cheap for a profitable cash generating IT data led business.
edit : and I can see that aside from a c couple of early sales it has been all buys so far this morning on the initial markdown.
Some fair points re D4t4 Solutions (LON:D4T4) daidjhill, so at SP 18% down right how, you should be filling your boots?
I think the key is to look at fundamentals rather than short term moves or, in this case MM driven moves. D4t4 Solutions (LON:D4T4) looks cheap to me now and all the trades going through appear to be buys rather than sells, so it seems a fair few others agree and are taking the opportunity to get into a GARP type stock at a good price.
The business model is an ARR model but it isn't a subscription model. The difference is that most of D4t4 Solutions (LON:D4T4) deals are non cancellable 3-4 year deals. There is a licence element that gets paid annually and this is in the ARR. So it actually has better revenue earnings quality than people assume because the ARR has contracted visibility 3 years forward. The ARR number now makes up 60% of next years revenue forecasts - the additional 2 contracts that slipped actually means that revenue for next year has about 85% visibility. That produces an EPS of circa 12p. Net cash would be £22m or about 1/3rd of the market cap. My guess is that the slippage this year leads to a beat next years I anticipate the numbers could be better still. So strip out 60p of cash and all things being equal 12p EPS versus 110p of share price is sub 10*.
An ARR business of this type usually trades on a much bigger multiple than 10* cash adjusted earnings. The business is high quality, cash generative with good product USP and the fact that a couple of deals moved signing date from the end of H2 to the beginning of H1 the following year should be a complete irrelevance to investors. Different story if those were lost or material uncertainty surrounded them but that isn't what was said.
This from the RNS looks encouraging too;
"The total sales pipeline grew by 27 percent during the year whilst the value
of proposals out with potential and existing customers increased fourfold,
providing strong visibility into performance for the first half of the new
year, and reflecting the investment into sales, marketing, and customer
success."
Maybe window dressing - maybe not.
Jim
Agreed Jim
We have 85% of expected revenue for the coming year covered (60-65% is ARR and 20-25% is the two contracts delayed into Q1). That leaves 15% or about £4.5m of additional contracts to find during the entire year. Given the 27% growth in order book I'd be surprised if they don't achieve well in excess of that but let's assume it is just as expected.
so circa 12p EPS (adjustments are actually quite small. share based payments which I agree are an expense should be low few hundred k) and with net cash forecast to get above £21m this just looks like a baby and bathwater knee jerk reaction.
I don't understand investors fixation on a few days either side of a Y/E to determine a companies valuation. In reality if those 2 contracts had been executed the trading update would be bang in line and everyone would be fine. In reality the real growth of the long term business is unaffected and the product is increasing traction across many verticals. I'm slightly irritated by short term reaction but happy to hold / buy more over the next couple of years when I think it will be 2 or 3 * the current share price.
David, re D4t4 Solutions (LON:D4T4) thank you for your insightful comments. I always take your comments seriously and they are a must read for me. This is now Tuesday, and although thy were punished yesterday, they have recovered today. Clearly you are a man of influence!
In the light of your comments, I will add them back to my watch list again. I always had a soft spot for them, but they hurt me when they made the major change of strategy.
Thanks again.
On D4t4 Solutions (LON:D4T4)
The warning reads across from the NCC (LON:NCC) results last week
My sympathies to anyone holding NCC
My morning smallcap tweet: Bear necessities
Cineworld (LON:CINE) Redx Pharma (LON:REDX) WANdisco (LON:WAND) Cyanconnode Holdings (LON:CYAN) Provexis (LON:PXS) WH Ireland (LON:WHI) Intercede (LON:IGP) Tekmar (LON:TGP) Industrials REIT (LON:MLI) Surface Transforms (LON:SCE) EnSilica (LON:ENSI) Filtronic (LON:FTC) D4t4 Solutions (LON:D4T4) Saietta (LON:SED) Chill Brands (LON:CHLL) Zinc Media (LON:ZIN) Numis (LON:NUM) Litigation Capital Management (LON:LIT) SRT Marine Systems (LON:SRT), Peel Hunt (LON:PEEL)
◄Cineworld (CINE)► conditional agreement with lenders for restructuring. Nil for shareholders. [SP=2.9 Cap=40m]. I'm short.
◄Redx Pharma (REDX)► mooted merger with Jounce formally lapsed. [SP=32 Cap=104m]
◄WANdisco (WAND)► CEO and CFO resign. The independent investigation has confirmed that orders of $14.9m for FY22 are false and sales bookings of $115.5m recorded in FY22 are also false. [SP=1310 Cap=884m]
◄CyanConnode (CYAN)► MoU with Alfanar, a leading engineering, procurement, and construction co, "to explore joint investment opportunities in Advanced Metering Infrastructure projects." [SP=16.65 Cap=45m]
◄Provexis (PXS)► update on attempt to sell excess Fruitflow stock. Still expects to need equity finance or loan finance in the coming months. [SP=0.86 Cap=18m]
◄WH Ireland (WHI)► warns FY-Mar rev only c.£26m and U/L pretax loss over £2.2m. Blames lack of transactional activity across Capital Markets. [SP=19.9 Cap=12m]
◄Intercede (IGP)► majority of contract opportunities have been closed and several support and maintenance contracts renewed before YE (Mar). Total $6m, which will be recognised from FY24 onwards. [SP=59 Cap=34m]
◄Tekmar (TGP)► £7.3m placing and £1m Retail Offer at 9p, a 6% premium. [SP=9 Cap=5m]
◄Industrials REIT (MLI)► final possible cash offer of 168p, a 42% premium. Board intends to recommend it. [SP=118 Cap=7783m]
◄Surface Transforms (SCE)► reported production problem solved but Jan-Feb volumes wer lower and scrap costs higher than planned. Warns FY23 profit below market expectations. Still has enough cash. [SP=29.5 Cap=73m]. I hold.
◄EnSilica (ENSI)► $2.4m contract with an existing customer, spanning this and next FY. [SP=72.5 Cap=56m]
◄Filtronic (FTC)► $0.8m contract, expected to be recognised in FY24. [SP=11.87 Cap=26m]
◄D4t4 Solutions (D4T4)► warns FY-Mar rev c.£21.5m (£24.5m) and adj pretax c.£3.5m (£3.3m). Blames delays in signing of a project with an existing banking customer. [SP=207.5 Cap=83m]
◄Saietta (SED)► c.£5m order for 3,000 eDrive units from existing US customer, AYRO. Production starts in Q3. Final batch scheduled for delivery in Q4 2024. [SP=43 Cap=44m]
◄Chill Brands (CHLL)► £1m placing at 4p (10% discount) and £1.6m convertible at 12%, 8p strike. Both are from a high net worth investor. CEO trills "We are thrilled to have secured funding..." I bet you are. [SP=4.5 Cap=12m]
◄Zinc Media (ZIN)► £7.3m multi-series win (136 hours of Bargain Loving Brits) with £5m expected to be recognised in 2023. That's only £54k per hour. [SP=85 Cap=19m]
◄Numis (NUM)► guides H1-Mar rev c.£64m, down 14%, "despite weaker overall investment banking markets". Institutional income and trading businesses experiencing a weaker end to H1. Warns "unlikely that the IPO market will see any meaningful pick-up during the remainder of our financial year".# [SP=216 Cap=238m]
◄Litigation Capital Management (LIT)► receives £22m profit in realisation of a case. [SP=71.6 Cap=84m]
◄SRT Marine Systems (SRT)► new distributor in US. [SP=42 Cap=76m]. I hold.
In line: PEEL
◄WANdisco (WAND)► CEO and CFO resign - WTF, they have been paid until now? I guess with a Garden Leave payment as well?
If they pop up in the directors register on another company - it will look like a short opportunity.
Capita (LON:CPI) released their FY 22 figures on 2 March and was covered by Paul on the SCVR. There was a strong recovery in earnings and previous concerns about excessive debt have now been fixed. Under the traffic light system Capita was green. If this turn around story caught your interest then the webinar with Helen Parris, Director of IR and Stephanie Little, Investor Relations Manager may do too. The team will present the FY results and talk on the outlook at a webinar for private investors on Tuesday 18th April at 12.30pm. A good chance to hear the story and ask your questions. Register here
Tracsis #TRCS H1 results with a management overview here video & podcast.
Tracsis management will present H123 results with Q&A this Wednesday 5.4.23, 1pm, register here.
Burford Capital (LON:BUR) At last some positive news out later I presume, an out of hours update was issued last night. Still some way to go before a final settlement but at least they have won the Petersen case (for now, possible appeals I guess).
Yes, Burford Capital (LON:BUR) are up 30% on the news. What’s a fair price now?
Also rose 30% on Friday evening so almost doubled from last week. I always thought Burford was worth at least £10-15 ex-Petersen so should be worth well over £20 now. I hold.