Small Cap Value Report (Mon 3 July 2023) - MEGP, YGEN, SIS, EYE, CNIC, BLTG, PRV

Good morning from Paul & Graham!
Podcasts went up on Saturday, I kept them a bit shorter this time, thanks to using my egg timer. Part 1 is a summary of the week's SCVRs. Part 2 is new material, being my roundup of macro/markets news.
I've written up about half of my half-year review of 2023's watchlist picks, so bear with me on that, should be up later today, or tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Science in Sport (LON:SIS) - 13p (pre-suspension) (£22m) - Temporary Suspension - Graham - RED
“Final sign off from the auditors is still outstanding” on 2022 results which were published in an unaudited form last week. Those results weren’t very good and while the company talks up its outlook, I’ve lost what little faith I had that the company was turning itself around.
Eagle Eye Solutions (LON:EYE) (Paul holds) - up 5% to 540p (£154m) - Morrisons 5-year contract - Paul - GREEN
More a growth company than value. Paul sees something very interesting here. I use a contract win announcement as a trigger to review the company's progress this year, which I think is looking good. Shares are expensive, but I feel it's justified for the long-term track record being built.
CentralNic (LON:CNIC) - 118.06p (+2%) (£334m/$415m) - Expansion of Buyback - Graham - AMBER
Centralnic greatly increases its 2nd buyback programme from £4m to £34m. As a cash-generating business that reports in US dollars and issues quarterly numbers, it must view itself as cheap relative to US peers. But this is an unusual decision, as I explain below.
Porvair (LON:PRV) - 664p (+5%) (£308m) - Interim Results - Graham - AMBER
Solid numbers and a good outlook from this industrial technology company. There has been some destocking by customers of one segment. Porvair has an excellent long-term track record and my neutral stance is unchanged due to the earnings multiple pushing 20x.
Blancco Technology (LON:BLTG) - up 8% to 168p (£128m) - Trading Update - Paul - AMBER
Good to see an "above market expectations" trading update for FY 6/2023, although no figures or broker guidance is provided. I find the accounting a bit aggressive, and too many adjustments. But if you think growth can continue strongly, then it might be worth a closer look. I'm neutral.
Paul’s Section:
Let’s start with some quick comments to get up before 8am -
ME International (LON:MEGP)
164p (pre market) £619m - Japan acquisition - Paul - GREEN
Operator of photobooths, laundry machines, and other self-service machines.
One of my favourite value/GARP shares this year, it issued an ahead of expectations update on 9 June, when I commented that the shares still look reasonably priced, despite having doubled in the last year (not bad going in a nasty bear market for small caps).
Today it announces a modest, but attractive deal (only £5.5m) which can easily be afforded from either a cheap loan in Japan, or if not then from existing cash.
ME is buying a Japanese competitor's (Fujifilm) photobooth business. It’s currently only operating just above breakeven, but ME expects profit of £2.2m pa to be added from this acquisition. So presumably that is coming from stripping out duplicated costs.
It bolts on 20-30% extra revenue in the Asia-Pacific region.
Clearly this is an excellent deal, but not material, I reckon that looks about a 3% uplift in next year’s profit, so not something to get over-excited about, but it should be worth a few pence onto ME’s share price.
Yourgene Health (LON:YGEN)
Recommended takeover bid at 0.522p cash.
Novacyt SA (LON:NCYT) is buying Yourgene Health (LON:YGEN) for £16.7m cash. That seems a lot, given that NCYT’s market cap is only £26m - which seems to be way below its own net cash, so I’m not quite sure what’s going on at Novacyt?
It’s a 168% premium being paid for YGEN, but when your share price is under a penny, then it’s not been a good result overall for shareholders.
Both these companies had a boom during the pandemic, which has since fizzled out and they’re now cash-burning again.
NCYT could be an interesting one for special situations investors to have a look at - if the cash can be safeguarded and unlocked in some way maybe?
At least YGEN shareholders get to salvage something from this failed, jam tomorrow investment.
In the current market, nobody is interested in providing follow-on funding for loss-making cash burners. So it's better for YGEN shareholders to at least salvage something with this deal, rather than it going bust at some later stage.
Eagle Eye Solutions (LON:EYE) (Paul holds)
Up 5% to 540p (154m) - 5-year contract with Morrisons - Paul - GREEN
Eagle Eye seems to be that rare thing - a genuinely global specialist in a niche (customer loyalty schemes for big retailers, especially grocers). It has an impressive client list (and note the US is now its largest market) -
The Eagle Eye AIR platform is currently powering loyalty and customer engagement solutions for enterprise businesses all over the world, including Asda, Tesco, Morrisons, Waitrose and John Lewis & Partners, JD Sports, Pret a Manager, Loblaws, Southeastern Grocers, Giant Eagle and the Woolworths Group.
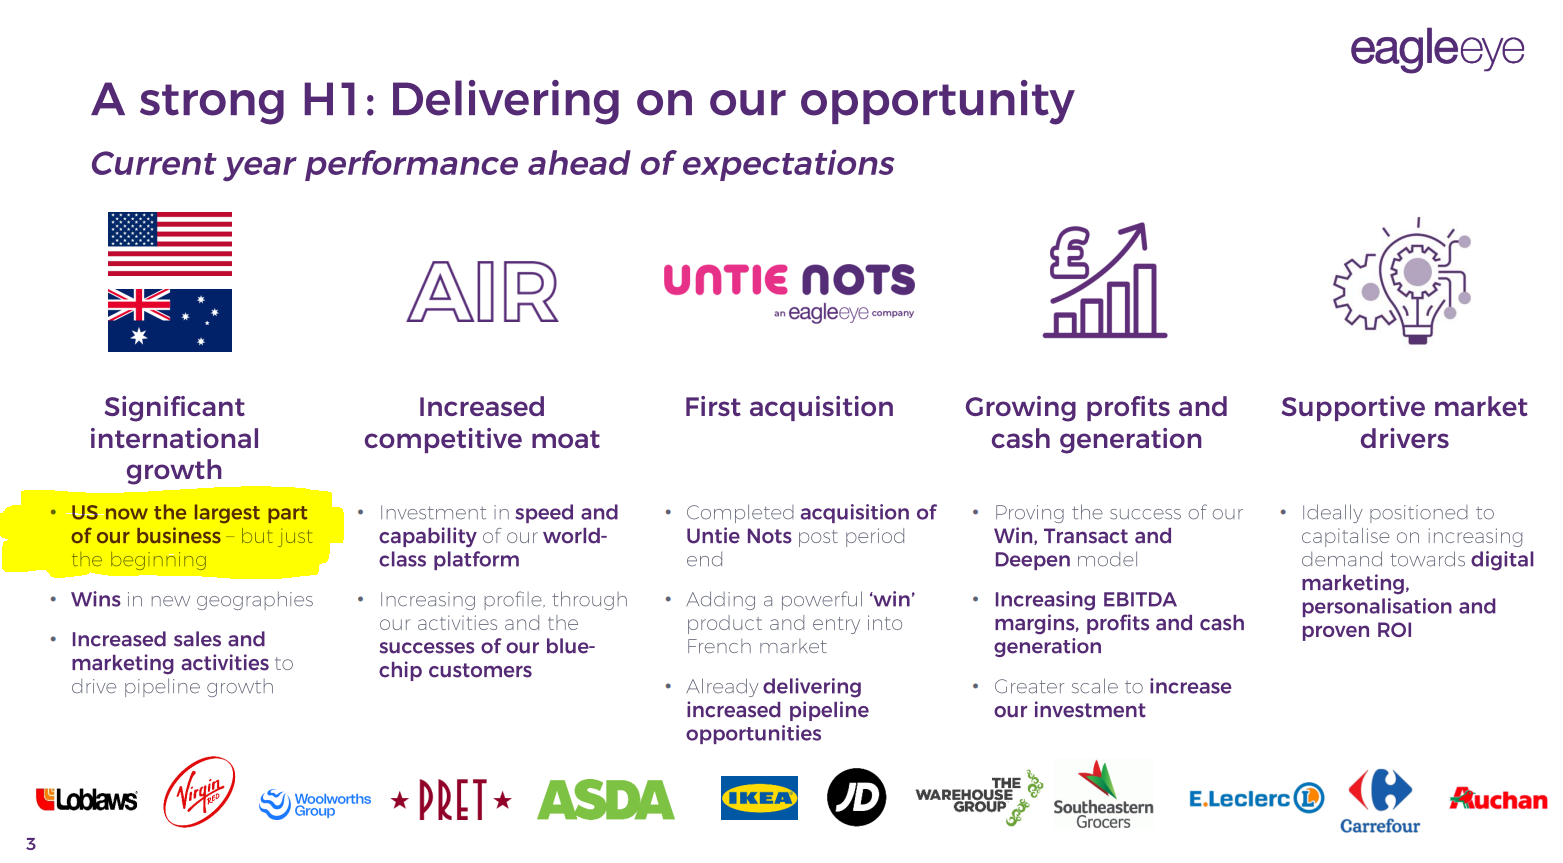
[Source: company website, investor section, Interim results slide deck]
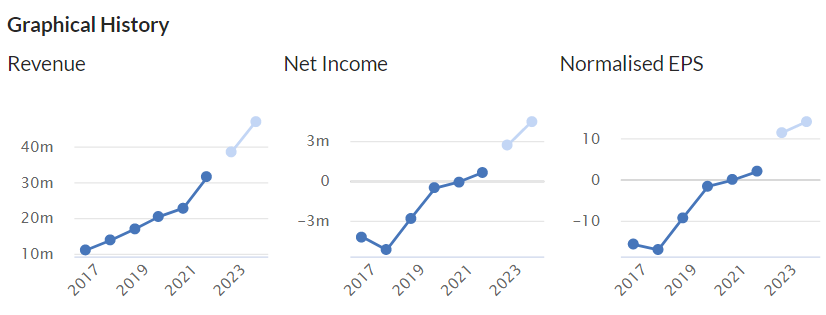
The Stockopedia graphs show an attractive growth company is developing here -
This year, I’ve reported 3 times on EYE here, summarised as follows -
18 Jan 2023 - H1 TU in line. Strong organic growth. Forecasts look too low. Impressive growth company, but not cheap. GREEN.
14 Mar 2023 - H1 in line. “Confortably ahead” outlook. Profitable. Sky high valuation looks justified (Paul). GREEN.
26 Jun 2023 - John Lewis/ Waitrose contract win.
3 Jul 2023 (today) - Morrison's 5-year contract win.
Morrison s win - it’s not clear if this is extending an existing contract, or a completely new one, with ambiguous wording -
… to further develop its loyalty and promotional offering.
Loyalty schemes might sound old hat, but they’re developing into more targeted, and personalised offers, which is what EYE specialises in.
I believe EYE developed the newish ASDA rewards scheme, with its cash pots (instead of points), which I use, and it’s very interesting how it works. It sets targets for you, so called gamifying, to meet challenges by e.g. getting £2 off if you spend £20 on meat or fish within x-days. I’ve found this does engage me. Although it’s also sometimes wasteful - e.g. the other day ASDA unexpectedly gave me £5 in my cashpot, for meeting a target that I hadn’t even noticed! But the feelgood factor certainly makes me more loyal, and I've been shopping at ASDA more frequently since joining its loyalty scheme, created and run by EYE.
I also think EYE's acquisition of French market leader in the same space, Untie Nots, could be very interesting. There was a good webinar about this acquisition, which I remember listening to in April, whilst getting hopelessly lost, hiking in Gozo! So it clearly made an impression, as I remember it, and I listen to so many webinars, few stick in my mind.
Paul’s opinion - for disclosure, I bought a standard position size in EYE shares earlier this year, intended as a long-term hold. There’s little doubt the company is building an impressive track record, and is profitable now (but ignore EBITDA, it’s a nonsense number).
The only question is how to value it. PER isn’t a very helpful measure for growth companies in my view, and I also dislike multiples of EBITDA or sales. So valuation is really just guesswork. What size might the company scale up to, and what would it be worth then - that tends to be my way of looking at things.
There might be a clue in the April 2023 growth share plan. I despise growth share schemes, which seem like legalised theft to me, whereby management are given shares in an intermediate holding company.
However, for a bad concept, this one seems well thought through. It’s based on stretch share price targets, and the dilution isn’t excessive, as you can see below, so I can live with this -
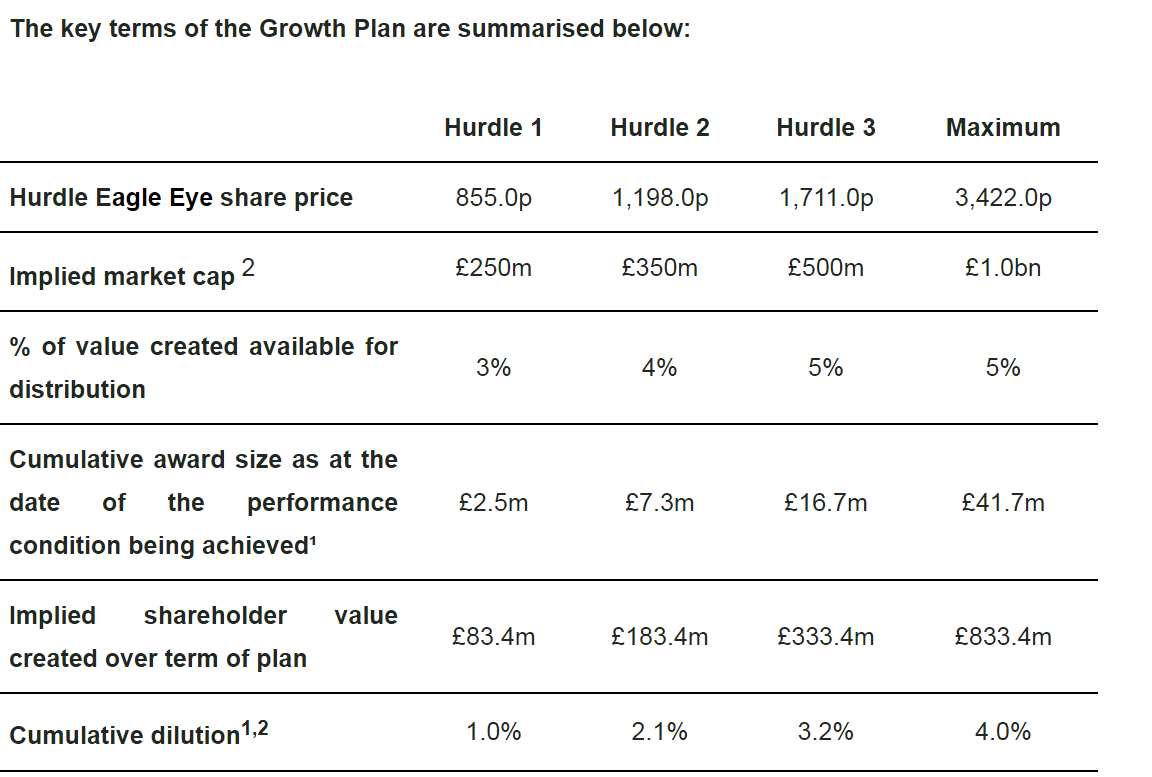
4-5% dilution, for 6-bagging the shares, is acceptable to me.
Maybe this gives an idea of management ambition, and the potential upside scenario? Or it could be pie-in-the-sky, we’ll have to wait and see!
Stockopedia has the fwd PER at 37x, which is obviously high, but that reflects the strong organic growth, and recurring revenues.
I thought it would be useful to have a recap EYE shares. Today’s news about Morrisons is encouraging but not game-changing. I do think highly rated shares need to provide regular positive newsflow, so this helps underpin my view that this company looks unusually interesting. I wonder if it might also be a takeover target? Although I’d rather have a multibagger over the long-term, than a 30% premium now.
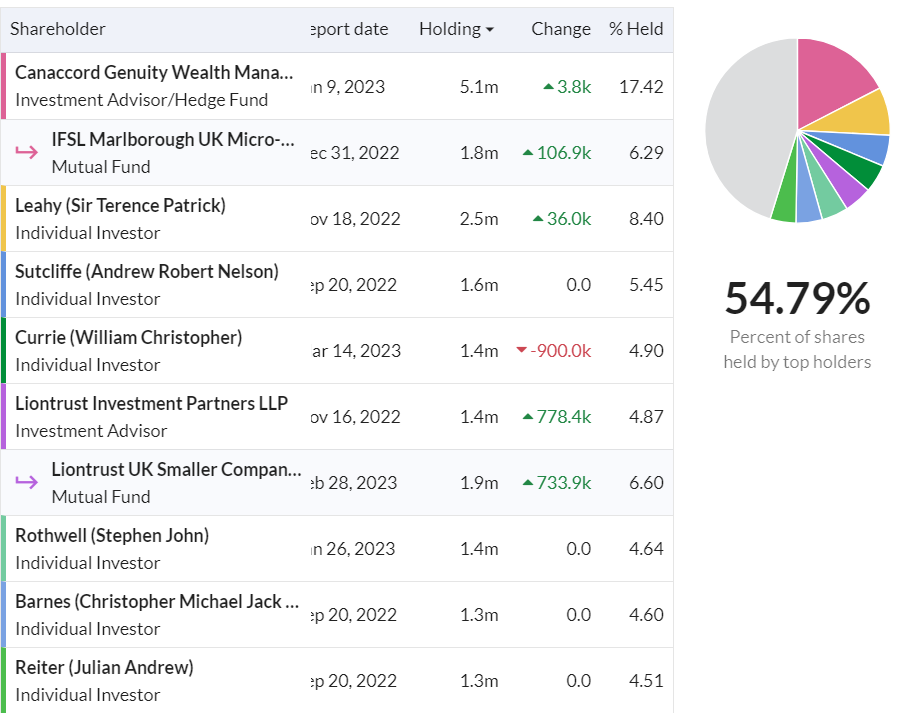
Notable shareholders include the biggest being shrewdie Canaccord/Marlborough at 17.4%, Sir Terry Leahy on 8.4%, and William Currie on 4.9% - google the names if you’re not familiar, all know what they're doing, in my opinion.
Blancco Technology (LON:BLTG)
Up 8% to 168p (£128m) - Trading Update - Paul - AMBER
We haven’t covered this share for about 18 months, so let’s have a recap, seeing as the shares are up 8% on today’s update.
Blancco Technology Group (AIM: BLTG), the industry standard in data erasure and mobile lifecycle solutions, announces the following trading update for the year ended 30 June 2023 ("FY2023").
Full Year Results expected to be above market expectations with broad-based growth across all geographies
Strong performance in H1 continued in H2.
Growth drivers are sustainability, and governance.
Revenue above market expectations (no numbers provided).
Operating profit “comfortably higher than current forecasts”.
High level of repeat revenues, and new business wins.
Well placed for continued growth.
That all sounds good to me, although it would have been nice to have some numbers, even if only estimates, or a range.
Any broker updates to quantify things? No, there’s nothing at the moment on Research Tree.
Balance sheet - I recall there were issues in the past, but its last balance sheet at end 12/2022 looks adequate, only £6m NTAV, or £10m if I ignore deferred tax, but this type of business is capital-light, so that’s enough, no concerns over the balance sheet.
Cashflow looks superficially good, but it capitalises a lot of development spend (£2.5m in H1, almost half of the £5.3m adj operating cashflow). So real world cashflow is not very good for the market cap size.
Paul’s opinion - it’s good that trading is ahead of expectations. Stockopedia is showing 8.0p adj EPS, so if it’s ahead of that, maybe 9p? That would give us a PER of 18.7x, which I can’t get excited about as a value share.
Is it a growth share? Well, revenues have improved in recent years, and it seems to now be making genuine profits.
Hence this share now boils down to whether you think it is on a sustainable growth trajectory that could see profits rise, and hence be good for the share price. That would need a lot of additional research, so I don’t have a view on it. Overall, with rather aggressive accounting, lots of capitalisation and adjustments, I’m not keen, so will just go neutral on it, AMBER.
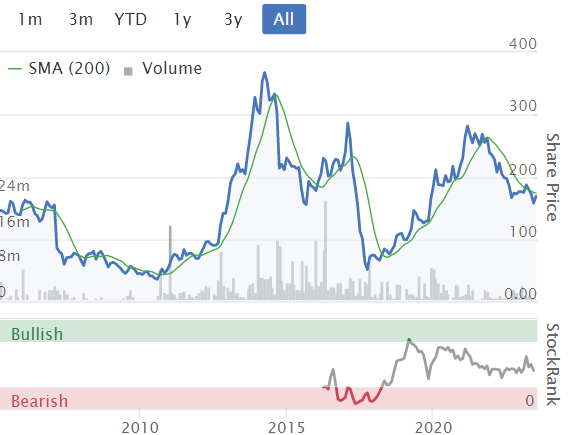
A rather erratic share price chart. I think this group used to be called something else (was it Regenersis?), and refurbished old phones, but that didn't work out, so it morphed into BLTG (after the former Directors had banked multiple millions in share sales a few months before a profit warning).
Graham’s Section:
Science in Sport (LON:SIS)
Share price: 13p (pre-suspension)
Market cap: £22 million
Ominous news here for shareholders, as the shares have been suspended:
Science in Sport plc (AIM: SIS), the premium performance nutrition company serving elite athletes, sports enthusiasts, and the active lifestyle community, announces that it has not been able to publish its audited financial statements for the year ended 31 December 2022 by the six month deadline as final sign off from the auditors is still outstanding.
They reassure that the audited statements are expected “imminently”, and the suspension can be lifted then.
However, this isn’t normal for a well-run company. If I was a shareholder here, I’d be very disappointed by the failure to follow a simple deadline. Even if the suspension is lifted tomorrow, why did it have to come to this? Six months is plenty of time to get your accounts sorted, especially for small companies!
By the way, any shareholders with strong attention to detail were given a warning that this might happen. Last Thursday, the company did publish preliminary results at 7am, but it issued a replacement three and a half hours later.
The replacement said (I’ve added the bold):
The following sentence has been deleted from note 1 of the Notes to the Consolidated Financial Statements for the full year results announcement released on 29 June 2023 at 7.00 am with RNS number 3025E as the results are unaudited: "The auditors' report on the statutory accounts for the year ended 31 December 2022 and the year ended 31 December 2021 is unqualified, does not draw attention to any matters by way of emphasis, and does not contain any statement under section 498 of the Companies Act 2006."
It’s normal for interim (i.e. half-year) results to be unaudited, but full-year results are supposed to be audited.
For example, here is what one of my favourite companies, H & T (LON:HAT) , said in its results statement for FY December 2022 (published back in early March). I’ve added the emphasis:
The financial information has been abridged from the audited financial statements for the year ended 31 December 2022.
The financial information set out above does not constitute the Company's statutory accounts for the years ended 31 December 2022 or 2021 but is derived from those accounts.
As you can see, by early March, H&T already had audited financial statement for the year ended December 2022.
Indeed, many large PLCs get audited numbers out with lightning speed. There is no excuse for small companies to struggle with the deadline.
Graham’s view
The numbers published by SIS last week were poor, with a loss at the EBITDA level. The company says it does expect to be EBITDA positive in H1 2023 (a period that has already finished). They say “momentum is building” in terms of revenue growth, but we are in an inflationary environment and the company has spent big on a new Blackburn facility, so revenue should be growing.
I also note that net debt reached nearly £11m despite the company raising £5m from new share issuance.
While I came to a neutral conclusion when I looked at SIS earlier this year, I would be actively avoiding it after the announcements of the past week. So this share gets the thumbs down from me today.
CentralNic (LON:CNIC)
Share price: 118.06p (+2%)
Market cap: £334m ($415m)
Paul normally covers this one and I strongly recommend that you dig into the archives for more of the background into this stock.
In its own words, it is “the global internet company that derives recurring revenue from privacy-safe, AI-based customer journeys that help online consumers make informed choices”.
Today it is increasing its buyback programme by £30m (from only £4m).
The reason given is succinct:
The Board considers the Buyback Programme to be in the best interests of all shareholders, given the cash generative nature of the business. It reflects the Group's renewed capital allocation policy geared towards greater returns to shareholders.
Centralnic will spend up to £34m and it will buy up to a maximum of 28.9 million shares (corresponding to 10% of the company).
I note that at the current share price (118p), 28.9 million shares would cost almost exactly £34m - so the company is saying that it would buy the maximum number of shares allowed at the current share price.
Graham’s view
I love a good buyback, but is this a good one?
According to the most recent quarterly report, the company was carrying net debt of $49 million. A good buyback is typically associated with a cash-rich business that has run out of productive uses for its enormous cash balance.
It’s atypical to see a large buyback from an indebted, rapidly growing technology company. One would imagine that a company like this has many possible productive uses for its cash, besides paying down its debt.
As for whether or not they can afford it, I note that quarterly cash generation in Q1 was $6m. Add back in the cost of buybacks and acquisitions, and real quarterly cash generation was maybe in the region of $12m.
With a market cap of just over $400m equivalent, I can understand why they might think they are undervalued at that level.
Here are some of the value metrics:
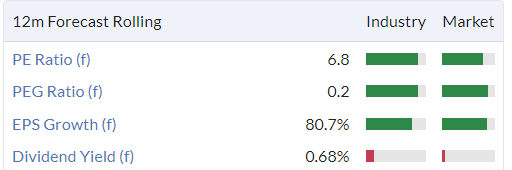
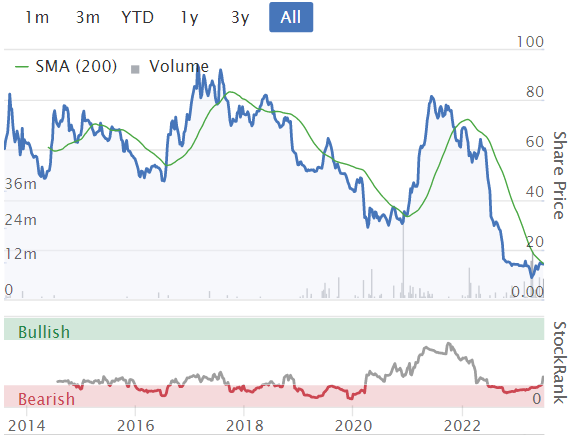
For a company that reports in US dollars and publishes quarterly numbers, I can only assume that they consider themselves to be undervalued relative to US-based peers.
Personally, I am biased towards seeing debt reduction before buybacks, so it’s difficult for me to get fully on board with their decision to expand the buyback programme. Therefore I’m going to sit on the fence with this one for now.
Porvair (LON:PRV)
Share price: 664p (+5%)
Market cap: £308m
Porvair plc ("Porvair" or "the Group"), the specialist filtration, laboratory and environmental technology group, announces its interim results for the six months ended 31 May 2023
I was impressed by this company when I looked at it in April, but I stayed neutral due to its valuation.
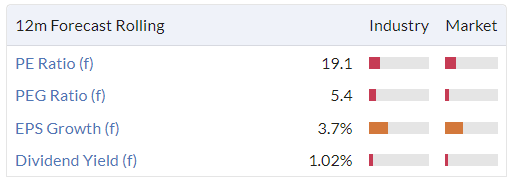
The shares are up 10% since then, suggesting that I was too cautious perhaps? Valuation naturally remains on the rich end of the spectrum:
Here are some of the highlights from today’s interim results:
Revenue +10% to £90.6m, up 5% on a constant currency basis.
Operating profit +16% to £11.7m
Cash balance is nearly £20m.
CEO comment: he remarks proudly on this “record set of results… despite inconsistency of demand across markets served".
"Looking ahead, while noting that inconsistent order patterns pose risks to forecasting, the Board expects the Group's full year result to be ahead of that for 2022. The aggregate Group order book, which has been at record levels for much of 2023, remains high. Porvair's long-term earnings record is supported by established global trends…”
The company reiterates its strategy and its long-term record, both of which I commented on last time.
The only major weak spot in the results came at the “Laboratory” division, where revenues fell 6%.
Here are the comments on what happened: de-stocking and normalisation of lead-times.
De-stocking of laboratory consumables from the second quarter affected Porvair Sciences, where lead-times have now fallen to more normal levels. This helps levels of customer service and inventory turns, but challenges manufacturing efficiency. In the plants affected, cost-reduction programmes have been undertaken to balance changing order patterns.
As outlined in the results announcement in January, the Board anticipated this de-stocking cycle and does not see any fundamental changes in the underlying growth drivers of the Laboratory division, in which investment continues.
Graham’s view
I don’t see any reason to change my view on this one, so my stance is unchanged. It appears to be a well-run company, and it may be priced about right. I’d be uncomfortable paying an earnings multiple much higher than it has already achieved.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Has anyone got any comments on Harland & Wolff group (LON:HARL) Financial Results? (I have a small holding.) The RNS came out late on Friday thus just escaping share suspension. They seem to be growing at breakneck speed and investment has massively overshot revenue. Taking on so much debt in the current environment looks very risky.
Hi chrisgb,
Prompted by your post, I've had a quick look at the FY 12/2022 results from Harland & Wolff group (LON:HARL) - they are absolutely diabolical! It looks hopelessly insolvent.
A key point from the Going Concern statement says this -
The Company is in advanced discussions with potential funders (both debt and equity) to raise additional funds. Whilst there is no indication at the date of signing of these financial statements that this financing will not be forthcoming, there can be no certainty that it will be successful. Should the Company not be successful in raising these additional funds and continues to retain its current cost base, a material uncertainty exists that may cast significant doubt on the group's ability to continue as a going concern.
The auditors have included material uncertainty in relation to Going Concern in the audit opinion.
The balance sheet shows NTAV of negative £(60)m!
There's £61m of (expensive!) interest-bearing borrowings within current liabilities (so repayable within 12 months), with the notes saying this -
Other borrowings
Riverstone Credit Partners LLC (RCP)
On 9 March 2022, the Company announced that it has entered into a group-wide $70 million Green Term Loan Facility (the "Facility") with affiliates of Riverstone Credit Partners, LLC ("RCP") , a dedicated credit investment platform managed by Riverstone Holdings LLC ("Riverstone") and focused on entities engaged in building infrastructure and providing infrastructure services to generate, transport, store and distribute both renewable and conventional sources of energy, as well as entities focused on or otherwise engaged in the energy transition from fossil-based, to a zero-carbon economy. The Facility will be used to support growth in the business and supplement the Company's working capital requirements.
The Company upsized the facility on 1 March 2023 to a total of $100 million with the entire facility maturing on 31 December 2024. The Facility will attract an interest rate of the published 90 day Secured Overnight Financing Rate (the "SOFR") plus 9% per annum, with the floor of the SOFR set at 1%.
Overall this share looks one of the worst things I've ever seen. The equity looks worth nil, to me.
The upside excitement seems to be a large order book. But if anyone wanted to punt on this, I would be inclined to wait until it's done a proper equity refinancing, as that could be at a deep discount.
Regards, Paul.
Thanks Paul, I rather feared that was the case.
Hi Paul ,
With an EV around £200m by the year end , this is a ZERO in the making.
I think they have already tried the fundraising option……….
Hi yiannos1,
Thanks. I could scarcely believe how bad the 2022 accounts are for Harland & Wolff group (LON:HARL) . Do we know why the lender was prepared to extend such large borrowing facilities to a company that looks a complete basket case? It looks like a "green" lending facility, where they just throw money at projects that meet ESG criteria, which looks like a fad to me, and probably not sustainable, once they've been stuffed with a load of bad debts by risky borrowers.
As you say, that leaves the equity at HARL looking incredibly vulnerable, and probably worth nothing, unless something miraculous happens.
So a definite avoid, based on the information we currently have. RED.
Regards, Paul.
Probably they will end up with the whole equity in a reorganised business!
Re CentralNic (LON:CNIC) - one other thing to consider is that non-exec Director Max Royde's investment company has been slowly buying new shares and has been at 23% of the company. With this buyback announcement that will edge up. Does anyone think there might be something untoward here?
Stocko shows Royde at 6.33% - I don't think he has sold any although he was diluted a little along the way. For me that is a very good signal, particularly given the heavy 2023 sales of other insiders.
Most of his holdings are through Kestrel Partners.
Technology Minerals (LON:TM1) - I hold. A couple of advisers were announced this morning for Recyclus battery recycling. One is a certain Andrew Goss, Chairman at Vertu Motors (LON:VTU) which I find interesting.
WANdisco (LON:WAND) have the begging bowl out for a 50p fundraise. I think it was £13 before suspension so a roughly 95% discount. I think they might be being optimistic on even that price.
WANdisco (LON:WAND) Nice salaries for the CEO and CFO
CentralNic (LON:CNIC) [I hold] are buying back shares roughly equivalent to the current net debt. In principle am comfortable with that if the cash flow is rock solid.
In this case, amounts spent on acquisitions have built a valuable IP and subsequent cash flow, but have left significant intangibles and profitability will be average at best until they are fully amortised., which I seem to recall this will happen in about 5 years time. Just imagine if the statutory profit was on a par with cash flow, following full amortisation of the intangibles and at the same time net debt had been fully repaid. If any meaningful growth is maintained the PE might be double or treble on higher earnings (after intangibles have been written off).
As it stands I am not sure a 10% negative dilution makes much difference, theoretically a 10% increase in the share price. I wonder, in fact whether the program is to do with insider/s wishing to realise their investment, perhaps also explaining why Ben Crawford left the scene following a very successful run, but whose benefits had been entirely reinvested in the operation. S Dayani and A Siffrin have sold over £5M worth in 2023. Siffrin still holds over 12%.
Operationally the recent growth has been good, following a period of astounding organic growth. Perhaps the operation was particularly well suited to lockdown, when purchasers could not go to a department store and physically compare and discuss items with a salesperson.
I will continue to hold for now, in the belief they have a strong technical IP, large growth potential and that their operational gearing will ensure continued strong margins. However the large director sales in 2023 makes me a little anxious whether this is indeed the case, so I await the next formal results with my finger on the trigger!
So often Directors get the timing of buybacks wrong. Concerned that CentralNic (LON:CNIC) have big debts. They must have very good cashflow coming through to justify this scale of a move. Why don't they halve the debt and increase the real profitability of the business rather than giving sops to the City and financial engineering? If they had $40m net cash rather than a similar level of net debt I might think differently about this.
Have been watching MP Evans for some time and looking for a drop in price which has arisen over the past few weeks. I am however still hesitant due to opposition to palm oil and would be interested to hear of your views regarding the future prospects for this company. Your past comments on the company have generally been positive and the Stockopedia ratings are still sound.
The World Wildlife Fund has a section on palm oil problems and solutions - link is here.
I hold M P Evans (LON:MPE)
I was looking for something else but came across the Stocko rating on Barratt Development:
Ranking 99, Value 95, Quality 94, Momentum is low for obvious reasons 72.
it is cyclical but we may be approaching the trough for the Housebuilders.
Shanta Gold (LON:SHG)
Wondered if anyone had any thoughts on Shanta.
Confirmation this morning that with Singida it has become a 100k oz gold producer.
Has been caught up in the Odey disaster taking it down from close to 12p to 9p - but according to Friday's RNS Odey's holding is now down to 1% - and continuing high volumes suggest Odey is close to out.
Looks good value, so took a starter stake this morning.
Agreed on Shanta Gold (LON:SHG) this is a special situation where selling pressure from a large holder has led to the share price falling when you would expect the opposite. Well done, I think your purchase will turn out to have been well-timed. I have held for 3 years and don’t want to add to my position. Remember there were takeover talks not long ago, that’s always a possibility.
The problem with Shanta Gold (LON:SHG) that I see is the cause of the sell off, the CEO sudden announcement of leaving. With ODEY almost sold out now it may see a lift soon though, but that I suspect will rely on what the price of gold does. Personally I think Resolute Mining (LON:RSG) is in a better position with 6 quarters of growth. Been hit in price recently from the drop off gold price. A head and shoulders pattern showed up in the charts which would give a target drop of about 18.5p, which it is close to now.
Technically Shanta Gold (LON:SHG) has bounced off strong support, but it has also moved down below it's upward trend channel and so I would like to see it move above it's 50ma at the least.
I'd also like to wait until a new ceo takes over and find out whether there are any nasty surprises to be seen.
Shanta Gold (LON:SHG) was added to our portfolio earlier today after executing a deferred decision to sell the Lookers (LON:LOOK) there being little point in hanging on until the end when other investment opportunities arise. Listening to the webinar was quite encouraging I thought.
That new LON:AVON deal looks a decent one. Might be a good bet on a turnaround?
This looks like a good deal for MEGP. My favourite share, held for a few years, not selling anytime soon!
So thats the 1st half of the year gone, hows everyone done so far?
Personally Im +20% so not too bad. Jan and Feb were very good. Banking panic didnt help March/April and the last 6 weeks have been a bit of a slog, giving back 3 or 4%.
Tradingview have a neat trick where you can remove the chart and view only the moving averages, removing all the noise and leaving only the trend. S&P500 continues to show all the signs of entering a new bull market, unless this chart rolls over badly. I dont fully understand it but there appears to be some liquidity easing by the US in Not QE- QE. UK appears to be still tightening liquidity, tho how long for remains to be seen
p.s theres an interesting video on liquidity here - https://www.youtube.com/watch?...
Fear and greed index is back into extreme greed
VIX is at very complacent levels (tho im not convinced VIX works as it used to do)
Taking all this into account risk/reward on the S&P to me personally looks poor, its the opposite of October when it looked extremely good.
Normally at this point Id be top slicing, taking some profits and cutting 1 or 2 losers if possible, then wait for risk/reward to turn more favourable. But the FTSE250/AIM have decoupled from the US since May UK inflation data, so it makes an already difficult market to read even harder.
Theres lots of value in the UK markets and I think we may be heading towards potential 2009/2020 style returns once this bottoms out. But no one has a crystal ball, im only guessing.
Decided to look a little into the whole “sell in May and go away” to get actual figures on it. Much easier to find in the US.
This is the 20 year average up to 2023
this is from 1990-2022
Complicated by pre election years
this is positive years vs negative years
Conclusion = **** knows. Probably in general markets tend to trend sideways more in June-Oct period, with Sept-Oct being the worst months. Another headwind for markets or will FOMO keep momentum to the upside?
UK Markets
FTSE 250 rallied a little from short term oversold levels.
93 up on the week – 149 down.
47 shares above 50+200d moving averages.
AIM all share trend, being sentiment driven is definitely negative for now. What Id want is a nice upward trend kicking in like 2016 or 2020, m. averages flipping round into a bullish look. What piece of economic data, news or event will start this I havent got a clue.
This AIM selloff looks more like 2002/3 than 2009 to me, tho every one is different, it does have that protracted feel to it.
Hope everyone has a great week.
+20% is very respectable in this market - well done!
June was a decent month, with the market rallying, but I'm still finding this year to be tricky. AI has been a strong trend, though possibly getting ahead of itself and pricing in some hype in the short term.
At the half way point, my performance is:
ISA (Longer term holds): -0.9%
Spread-Betting Account (Trading): -9.2% (Improving to -3.6% if I were to close off current open positions)
My largest ISA holding is Begbies Traynor... some degree of risk, but with the BoE pushing up rates to 5%, I do think H2 could be tough for SME's, and I expect Begbies to do well for the next 12months or so at least.
Nice post, thank you. Do you mind me asking which stocks have been driving your outperformance this year?
Burnt Onions...Ive mostly been trading things with some earnings momentum- Billinton Holdings, Yu group, Kitwave, ME International, Hvivo, card factory, jet2 etc. Getting in on an uptrend for a few weeks/months and selling when momentum runs out. Find these much safer than buying bombed out shares in a downtrend. Plus have couple of S&P trackers which helped.
Also buying things on trading updates like Volex ,James Fisher, Paypoint which have been in a long downtrend, market pricing in bad news and its actually OK news. Its tricky right now as the markets are choppy, so easy to get stopped out. Ideally im looking for a trend change, a trading update or other news within 1-4 weeks + earnings momentum if at all possible. If you know the exact date of a results/trading update even better because it gives you the option to bail out before.
Ive had plenty of losers too tho, just try not to lose more than 8-10% on average, and winners 15%+. So even when I get half wrong can still make some money. Just the way I do it, great thing about the stock market is theres lots of ways to make (and lose) money.
The big money will likely come when the market turns, whenever that is. Its a good time to prepare now screening a decent sized watchlist if you have some cash on the sidelines. Just have to be patient.
Thank you Wolf of Small Street (can we call you WOSS for short?), I very much appreciate your candour and openness.
Very familiar with your winners, I've held half of them myself but probably not been as active in trading them as I have gradually moved more to buy and hold as I've got older. However in this market I think your strategy is absolutely spot on.
One final point, you say this bear market feels like 2002/2003, and I think you're right. I was a small cap broker around this period and there was a long bleed out from 2000 to 2003 as investment interest fizzled out very slowly, much like now. The wheels didn't stop turning straight away after the dot com bubble burst, it took time and this time around feels much the same. My gut feeling is we are more than half way through the bear market. Twenty years ago it was the outbreak of the Gulf War which triggered a huge rally and amazing subsequent bull market, don't know what the trigger will be this time but after the summer I will begin to position accordingly for it with a wide spread of low risk high reward positions. I will soon be casting out my fishing nets and hoping for a big catch in 2024.....
Thank you burnt onions. I didnt realise you'd been a small cap broker, how interesting. You'll know much more than me looking back on the dot com bust so its good to hear you see some similarities too.
I will point out back then while you were probably a quality investor and intelligent strategist I didnt have a clue what I was doing, just buying anything with a website:)
You can call me WOSS or anything else no problem.
Very interesting. There seems to be a massive sell off in the summer in a bear market, this is the conditional seasonality chart. Do you know how they define a bear market and where the data came from?
Epitychia-
Thank you very much.
About 40% up largely driven by Tesla and my other US tech stocks. Still down since the start of last year though as 2022 was horrific! Just about managed to hold on and not capitulate. Hoping for a steady H2 now.
Thats a fantastic result B&V, well done! Yep, I missed out not getting involved in US Tech this year, there's been some enormous rises in the last 6 months alone.
Remember reading in August/Sept that US Tech was not the place to be. How quickly things can change.
great comment, incredible effort!
Congrats on the H1 performance in your portfolio!
How would you categorise your investment style, and the asset classes that you invest in?
Morning Paul enjoyed your podcasts this weekend as ever. Regarding tinyBuild (LON:TBLD) I am pleased that they have recruited a new cfo from outside the company who must have some clout because he has instigated write offs and a realism to the financial position. Hopefully also he can maintain a control over expenditure which appears to have been running wild in the past year.
i believe the sell off is overdone and am looking forward to a recovery in the H2
tinyBuild (LON:TBLD) The new CFO is not an external appointment, he has been there nearly 3 years as their M&A expert, so responsible for their disastrous purchase of Verses Evil. A reward for failure and someone else who is probably not strong enough to stand up to Alex, the CEO and majority shareholder.
Apologies but I must have misread the broker note
What I was trying to say is from my experience if a new cfo comes in they like to make a meal of a difficult situation because they don’t want the downgrade under their watch and can therefore take credit if recovery occurs
ME International (LON:MEGP) nice bolt on acquisition in Japan for up to £5.5m
They’re projecting quite an improvement in profitability from them I see, currently they look to be generating an average profit before tax of £0.29m whereas ME believe it will add £2.2m
I hold
Check out the number of suspensions on AIM this morning due to non publication of annual reports!
Also, a material ramp up of the share buyback at CentralNic (LON:CNIC) to roughly 10% of the market capitalisation. Looks interesting given it seems to be perceived as a loss making, non cash generative business.
My morning smallcap tweet: Meat-free news substitute
MTI Wireless Edge (LON:MWE) Sondrel (Holdings) (LON:SND) Avon Protection (LON:AVON) Gresham Technologies (LON:GHT) Eagle Eye Solutions (LON:EYE) Verici Dx (LON:VRCI) Eden Research (LON:EDEN) Blancco Technology (LON:BLTG) Science in Sport (LON:SIS) ITM Power (LON:ITM) Supply@Me Capital (LON:SYME) ME International (LON:MEGP) MGC Pharmaceuticals (LON:MXC) Yourgene Health (LON:YGEN)
◄MTI Wireless Edge (MWE)► repeat order from a European customer, worth US$1.4m. Delivery within 14 months. [SP=44.82 Cap=39m]
◄Sondrel (SND)► completes second key milestone in a material turnkey ASIC contract for a Tier 1 OEM Automotive customer. [SP=64 Cap=56m]
◄Avon Protection (AVON)► gets second delivery order worth $38m from the U.S. Army under the Next Generation Integrated Head Protection System contract. [SP=852 Cap=256m]
◄Gresham Technologies (GHT)► $240k PA five yr contract for Clareti. [SP=140 Cap=117m]
◄Eagle Eye Solutions (EYE)► 5 yr contract with Morrisons for loyalty and promotion services. No £££. [SP=510.75 Cap=151m]
◄Verici Dx (VRCI)► validation of Clarava (pre-transplant prognostic test for risk of early kidney rejection) from an international clinical study. Co on track to commence the initial US commercial launch of Clarava before the end of 2023. [SP=12 Cap=20m]
◄Eden Research (EDEN)► Ecovelex seed treatment approved in UK. [SP=9.41 Cap=36m]
◄Blancco Technology (BLTG)► guides FY-June revabove market expectations and op profit comfortably higher. [SP=157 Cap=118m]
◄Science in Sport (SIS)► one of several shares suspended since FY accounts late. [SP=12.5 Cap=22m]
◄ITM Power (ITM)► strategic (natch') collaboration with Mott Corporation to further advance porous transport layers in electrolyser stacks. [SP=72.58 Cap=447m]
◄Supply@ Me (SYME)► first UK Inventory Monetisation transaction using traditional funding sources. 3 yr £1.8m max. [SP=0.12 Cap=78m]
◄Me Group (MEGP)► buys Japanese photobooth biz fot £5.5m. Biz made £0.29m pretax av. Projects biz will add £2.2m pretax in FY24. That's an aggressive improvement. [SP=163.57 Cap=619m]. I hold.
◄MGC Pharmaceuticals (MXC)► Australia becomes the first country to allow psychiatrists to prescribe psychedelics to patients with depression or post-traumatic stress disorder. "MGC has positioned itself as a key player in pioneering psychedelic research and development and as a result, the Company is now able to offer accurate, pharmaceutical-grade products. " [SP=NA Cap=NA]
◄Yourgene Health (YGEN) )►0.522p (a 161% premium) agreed offer from Novacyt.
Results out of Wynnstay (LON:WYN) today, I have a decent sized holding.
Mildly disappointing but pretty much in line with expectations. A very modest dividend increase. The reversal of fertiliser prices back to historic norms is the cause, plus bird flu and reduced dairy herds due to low milk prices v cost. Grain is looking good.
On the very positive side, net assets are greater than the share price.
This is basically a bet on UK farmers and the UK economy, post Brexit. To me a Hold at this price, which may drift lower. At the least I would want the board to level peg with inflation. For inflation watchers, UK food inflation should decrease.
I hold Wynnstay (LON:WYN) as well. Not the most exciting company, but is run very well. Interesting that they have announced the impact of the oneoff stock losses in H1 and therefore forced to disclosed the corresponding gains number for last year which had such a positive impact. Good disclosure, but consistent with most companies they only come clean on large one-off quantification when it's negative! Anyway, I find that this company is a good one to top up on cyclical weakness. Must have about the best dividend record of any company on AIM.
Good to hear opposing views Wynnstay (LON:WYN). I sold out thus morning after frantically trying to get a quote- couldnt even sell 500 shares! Good company but has never really attracted a premium, looks justified with pedestrian numbers.
For a little company like this - you would have thought the directors might hold a few shares -may have jumped to the wrong conclusion, but looks like less than 1.00% for the entire Board..!
Wynnstay (LON:WYN) H123 results webinar on Friday 7th July, 1pm. It's an interesting overview for the agricultural sector. Relevanct to NWF among others. Agree with Topvest, it's well run. Register for the webinar with Q&A here.
(There's also a link for the Tpximpact Holdings (LON:TPX) FY22 presentation to be held this Thursday 6th July, 1pm, too).