Small Cap Value Report (Mon 30 Jan 2023) - DPEU, INSE, 888, SPE, BXP, STEM

Good morning from Paul & Graham!
Today's report is now finished.
Small Caps Podcast - went up on Saturday morning. I really enjoy doing these, so it's not a chore. However, typing it up is a chore, so I've decided to drop that - apologies for any inconvenience, but the current workload is so intense, something had to go. Seeing as most of the podcast is summarising the shares we covered during the week, all the info (apart from the short markets/macro bit) is already on my SCVR summary spreadsheet, so it felt like duplication typing up the podcasts, and it's a good 2-3 hours work typing, which I could do without at the weekends! I hope you don't mind.
This week I flagged 2 mystery shares (my best ideas during the week, just for Stockopedia subscribers), and have left a comment here in the comments section of Friday's SCVR to reveal them, and why I picked them. Also bear in mind that, unusually, I own both these shares personally (intended holding period: 1+ year, but dependent on future newsflow), so there will inevitably be bias, which there always is when anyone talks about shares they hold personally.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Inspired (LON:INSE)
9.15p (Friday’s close) - mkt cap £89m
Inspired (AIM: INSE), a leading technology enabled service provider supporting businesses in their drive to net zero, controlling energy costs and managing their response to climate change, announces a trading update for the financial year ended 31 December 2022.
Strong full year trading performance, an improved cash position and confident outlook
An annoyingly vague self-description above, that doesn’t really explain what the company actually does.
Today’s update reads well - key points being -
Positive H2 momentum
Strong overall trading for FY 12/2022
Revenue of £88m is 10% ahead of market exps, and up 30% on 2021
Adj EBITDA of £21m is “in line with market expectations” (I’m wondering why it’s not ahead, given that revenues are 10% ahead?)
Net debt reduced, as expected, to £37m (very different from the misleading headline which says “improved cash position”!)
Strong demand for energy services, due to energy crisis, so it looks as if INSE is likely to be in a sweet spot, for now.
It says cashflow is strong, but the interim results reveal that it capitalises a lot of costs into intangibles, so I’d want to make my own assessment of real cashflows.
ESG activities “gain traction” with revenues up 175% on LY.
Outlook - says it’s confident for 2023.
"With a sales pipeline that is at record levels, and a notable acceleration in Optimisation and strong growth in our ESG practice we are increasingly demonstrating that we are the market leading solution at a market leading price point, and therefore we are confident of future success."
My opinion - this update sounds positive, but is only in line with market expectations, so shouldn’t really be price-sensitive.
The StockReport shows attractive PER (6.5x) and divi yield (4.2%) stats, so I’ve done a bit more digging into the accounts - which did not go well. The balance sheet is threadbare, with negative NTAV, worryingly high receivables, and too much debt for my taste. Cashflow isn’t great, once capitalised intangibles are taken into account. Note also £10m of contingent consideration is within current liabilities, so that’s either a lot of cash to pay out, or dilution from share issuance.
We’ve seen problems with listed energy consultants in the past, therefore I would be wary of getting involved with anything in this sector, so it’s not for me.
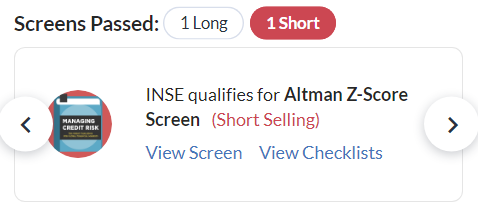
Note that it's coming up on a shorting screen, but I wouldn't take this as gospel, more something to check out, as a potential warning -
Sopheon (LON:SPE)
692p (up 11% at 10:02) - mkt cap £74m
Sopheon, the international provider of software and services for Innovation Management, is pleased to provide the following trading update for the year ended 31 December 2022.
FY 12/2022 revenues - in line with market expectations, at $36.5m (up 6% on LY)
Would have been “comfortably exceed” revenues at constant currency.
ARR (annualised recurring revenues) up 18% to $24.3m at end 2022
Revenue visibility for 2023 is strong, at $28m
Adj EBITDA c.$7m (up from $6m in 2021) - “comfortably exceeding market expectations”, and note this is after a $1.6m writedown.
“Careful cost management” is flagged as one reason for higher than expected EBITDA.
Net cash healthy at $21m, down $3m vs LY, reasons given sound sensible, so no cause for alarm -
A large part of this reduction reflects a fall in the Dollar value of Euro and Sterling cash deposits due to currency movements, the extended payment terms for the US Navy contract announced in July, as well as the impact of acquisition payments.
Operational update section sounds interesting, with 2 acquisitions having expanded its addressable market by $2bn! Although I usually disregard addressable market stats as pie in the sky.
Transition to SaaS (recurring fees instead of one-off licences) is being accelerated, which it points out will -
“slow revenue and profit development in 2023, but should accelerate ARR growth - delivering traction and more predictable growth in subsequent years, with a higher quality of revenue.”
Investors should be familiar with this argument, but it does mean putting up with years of lacklustre growth, as the SaaS transition grinds on. The trade-off is that the likelihood of volatile earnings, and profit warnings, should gradually recede.
Broker updates - as we know, adj EBITDA isn’t real profit, especially at software companies which capitalise development spend, which SPE does.
Finncap kindly lets us see its spreadsheet, which converts $6.8m of adj EBITDA into just $2.6m of adj PBT. Good job I checked! This is 20.2c EPS which converts into 16.3p EPS, so a PER of 42x - so you’re being asked to pay a lot up-front for earnings growth that hasn’t happened yet.
Forecast for FY 12/2023 is a reduction in adj PBT to £1.1m, US cents 7.0 EPS = 5.6 pence = PER of 124x (not a typo!)
This doesn’t look at all appealing to me. So investors must be imagining that these numbers can be thrashed. Finncap caters for them too, with a more aggressive FY 12/2024 forecast of £3.0m adj PBT, and 24.4c, or 20p EPS = PER 35x
My opinion - it’s too expensive, for where the company has currently got to.
I completely get the argument that current profits are suppressed by moving customers, new and old, onto SaaS, which foregoes up-front licence fees in return for spreading the revenue over a longer time period. However, the trouble with that, is it leaves a business that hardly makes any money in 2023, and you have to hope that it can keep winning more business than it loses, to become profitable in 2024 and beyond.
I’m struggling with the concept, and the valuation.
Patient investors might do well in the long run though, but looking at the numbers dispassionately, this looks like a business running hard to stand still. So you can view it either way really. Therefore I’ll just say I’m neutral, so amber on this one for now, whilst recognising there is a fairly good bull case that’s not coming through in the numbers yet.
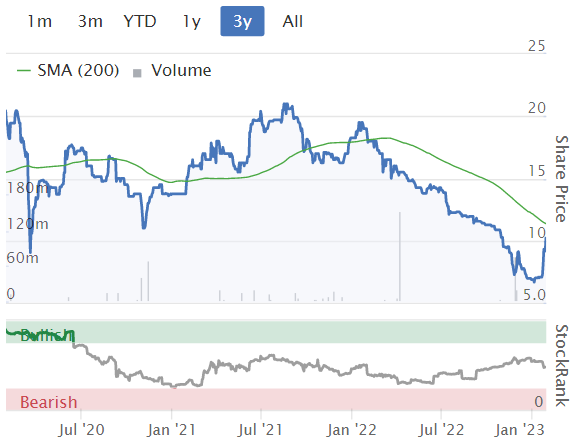
People chased the valuation too high in the last two bull runs (2019 and 2021), so I’d be reluctant to follow that route again now. Pity the bid/offer spread is so ludicrously wide too. That lack of market liquidity begs the question, how do institutions exit if they decide to sell?
SThree (LON:STEM)
414p (unchanged) - mkt cap £558m
Final Results - FY 11/2022
SThree plc (‘SThree’ or the ‘Group’), the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics (STEM), today announces its financial results for the year ended 30 November 2022.
Record profit performance up 24% driven by continued demand for flexible STEM talent and well-established strategy
No adjustments to the 2022 results, hence the missing column.
Excellent results, as expected, with £1.64bn revenues, and £77.0m PBT (up 28%)
EPS 41.0p - giving a PER of 10.1x
Total divis 16.0p - yield of 3.9%
Net cash £65.4m
Balance sheet - lovely, as usual! £200m NTAV (which gets a £7.1m boost from forex), and loads of working capital: current assets £430m (including £66m cash), current liabilities £244m, giving £186m surplus, and a current ratio of 1.76x
There’s no long-term debt either, with only £26m non-current liabilities, mainly lease liabilities.
So this is a bulletproof, sleep soundly at night in any market conditions type of balance sheet!
Cashflow statement - working capital again absorbed cash.
Also note the cashflow used by the employee benefit trust is hefty, at £9.9m, which is about two-thirds of the amount paid to shareholders in divis of £14.65m. I think this £9.9m cost goes through reserves, rather than through the P&L as a cost (see note 11). So that would need double-checking, as it could mean profits are effectively being over-stated, if this indirect employee remuneration is not being recorded as a cost? I’ve lodged a query with the company, so will report back on any further info gleaned on this point.
Outlook - this quote below sounds consistent with what STEM said last time (some softening in Q4, but overall pretty upbeat about the medium to long term) -
As we enter the new financial year, trading continues to track in line with expectations, supported by a healthy contract orderbook. The macro landscape remains consistent with the softer conditions seen toward the end of the year. However, our global reach combined with a specialist niche focus in structural STEM disciplines is underpinned by a proven resilient business model and a robust balance sheet. This provides us with a strong position from which to pursue our unique opportunity over the medium to long term."
Note below that the 2023 forecasts have slightly crossed under the 2020 forecast/actual. I’d prefer 2023 forecasts to keep going downwards, to build in more of a safety margin, in case macro conditions bite harder as 2023 progresses.

My opinion - similar conclusion to last time - namely that I think this is an excellent company, reasonably priced. It should do well long-term, I reckon. Thumbs up.
However, I’m a little worried that macro conditions could cause a tougher year in 2023 for earnings. For that reason, it looks possibly priced about right in the short term.
It’s on my watchlist, as something to buy for the long-term, if it plunges on a profit warning later in 2023. That may not happen of course, it could continue trading in line with expectations, and has good visibility, since it's mainly contractors working on projects, not one-off recruitment fees.
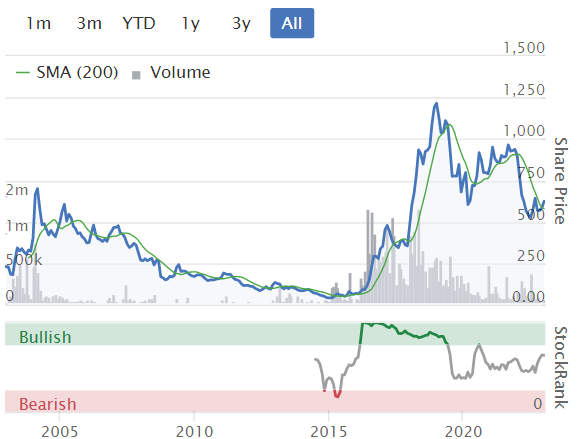
Stockopedia loves it, see the StockRank jammed near maximum.
There's probably nice upside on this share, when the economy improves.
Investor briefing - STEM is doing a webinar at 13:00 today, and says it will be recorded & published afterwards. The topic is the company’s “technological improvement programme”.
Graham’s Section:
DP Eurasia NV (LON:DPEU)
Share price: 58.7p (pre-market)
Market cap: £85m
It’s strange to see this one reporting its Russian operations as “discontinued” - for years, Russia was seen as its most exciting growth opportunity, But the political (and military) situation has now made that untenable.
Another recent development here has been the use of the accounting standard known as“IAS 29” - Financial Reporting in Hyperinflationary Economies. Inflation in Turkey is currently running at 64% and as you can imagine, this makes financial reporting somewhat complicated.
That is the context in which we get today’s full-year trading update for 2022, that is ahead of expectations. Here are the highlights I’ve picked out:
Number of stores 859 (up from 817 in 2021).
Group system sales from continuing operations +1.5%, after accounting for hyperinflation (note that 95% of these sales are in Turkey).
On a like-for-like basis, group system sales from continuing operations are down 5.6%, again after accounting for hyperinflation.
It’s the like-for-like comparison that really matters to me, as it is not distorted by the contribution of new stores.
The company says that their performance in Turkey was “good” when you consider that 2021 included a temporary VAT reduction of 7 percentage points.
Russia - even though Russia is described as a “discontinued operation”, and “work on a potential transaction is ongoing”, we still don’t know when DPEU will get these 159 stores off their books.
Liquidity - the company has cash of TRY 368 million (£16m) and an undrawn bank facility of TRY 225 million (£10m).
This implies good headroom but the company is likely to still have a significant net debt position (at the interim results, net debt was £47m). Perhaps the sale of the Russian operations can help it to deleverage?
CEO comment:
"Trading momentum sustained into the final months of the year, as we continued to implement our targeted action plan in reaction to and in order to overcome macro factors largely outside of our control. As a result, we anticipate adjusted EBITDA(8) for 2022 will come ahead of current market expectations…
Given our strong pipeline and sustained franchisee interest, we remain confident that 2023 will be another solid year for network expansion.
Estimates
Liberum has increased its 2022 adj. EBITDA forecast by 8% to TRY 353 million (£15m), but has not yet provided estimates based on IAS 29 (i.e. after accounting for hyperinflation).
My view
Financial success at this company always feels like it is just around the corner.
As it does have a large and mature presence in Turkey, I can’t help the feeling that it should be able to turn a profit here at some point. The current strategy of selling mini-pizzas for $1 doesn’t encourage me too much, but I do think that in the absence of hyperinflation and with a healthy Turkish economy, DPEU could eventually do well.
In the short-term, I should remind readers that DPEU has needed covenant waivers from its Russian bank. A deal could be announced tomorrow that would sell the Russian operations and solve the debt problem, but I don’t think that betting on these events is a sensible investment strategy. So I would avoid these shares for now.
888 Holdings (LON:888)
Share price: 79p (-23%)
Market cap: £354m
Disclosure: I (Graham) have a long position in 888.
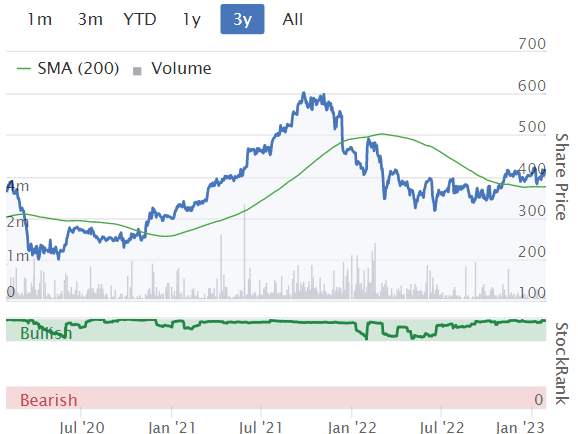
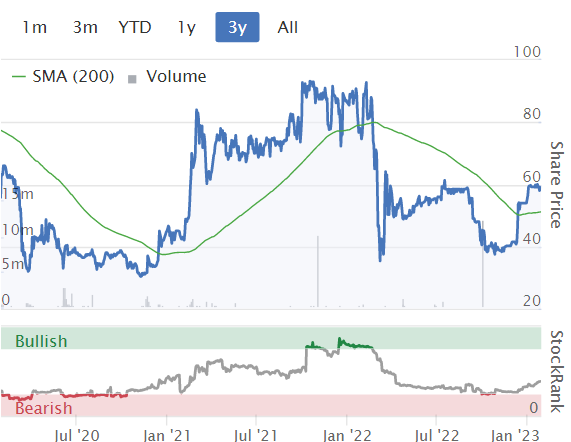
This is a share I’ve held through thick and thin. It reached a high of almost 500p in 2021, and is now well and truly in the doldrums:

It issued a trading update earlier this month which left me feeling optimistic. Its main challenge currently is to find the minimum of £100m of promised synergies from its merger with William Hill International (the non-US parts of William Hill), so that it might start to attack the £1.8 billion of gross debt that it’s carrying.
Only this weekend, I was looking at some comparisons with Entain (LON:ENT) and Flutter Entertainment (LON:FLTR) and observed some enormous disparities. Even before today’s share price fall, the market was not giving 888 a “normal” rating for its sector - probably because of worries over its excessive debt load.
(When I bought into this, it had a very strong financial position - but it used that to take over William Hill, an aggressive move which may ultimately prove to be its downfall. It’s too easy to say in hindsight, but I should have simply sold when the WHI deal was announced)
Today brings no fewer than three RNS announcements from 888. None of them are particularly long, so this shouldn’t take long.
1. Directorate Change
888 (LSE: 888) announces that Itai Pazner, Chief Executive Officer and Executive Director, is immediately leaving office as CEO and as a Director.
This isn’t what we like to see, as shareholders - an immediate departure without any proper succession planning. The Chairman (Lord Mendelsohn) thanks him for his long service to the company. But we were counting on Mr.Pazner to integrate WHI and take us to the promised land of synergies and deleveraging. What’s going on?
RNS number two may possibly contain a clue…?
2. Suspension of 888 VIP customers in some markets
Following an internal compliance review, it has come to light that certain best practices have not been followed in regard to KYC (Know Your Client) and AML (Anti-Money Laundering) processes for 888 VIP customers in the Middle East region. While further internal investigations are underway, the Board has taken the decision to suspend VIP customer accounts in the region, effective immediately. The Board currently estimates that the impact is less than 3% of Group revenues, should the suspensions remain in place.
Oh dear. The regulatory environment is already a major issue when it comes to profitability in this sector. If certain Middle East VIP customers are found to be unsavoury types, using 888 for unsavoury purposes, it’s not going to make things any better. Plus there is the loss of 3% of (high margin) revenues.
Lord Mendelsohn says:
We will be uncompromising in our approach to compliance as we build a strong and sustainable business.
One area of concern at 888 has been the imminent departure of its CFO. To lose its CEO as well would be too much - thankfully, we also get RNS number three:
3. Directorate Change - Update
888 (LSE: 888) announces that further to the announcement on 13 January 2023, the Board and Yariv Dafna, Chief Financial Officer and Executive Director, have agreed that he will remain in his posts until the end of 2023, rather than stepping down on 31 March 2023.
Small mercies!
My view
The share price is down by over 20% today, from what I already believed was a cheap level, though I acknowledge that there are serious risks at play here.
The primary risk, in my mind, has been the debt load. Annual interest costs are running at c. £130m. About 60% of the debt has been fixed for three years, but there is an element of floating debt and after three years, certain hedges will expire leaving the company exposed to whatever rates prevail at that time. Clearly, debt reduction must be a priority.
But today’s news heightens another two risks. Firstly, management disruption - the loss of the longstanding CEO, and a CFO who is waiting to leave, create a risk that belief in the WHI integration and synergy plan might falter.
On top of that, we have regulatory risk - might 888 be on the hook for penalties and tighter restrictions on how they do business, as a result of how they dealt with Middle Eastern VIPs?
Therefore, even if the temporary loss of these VIPs reduces revenue by only 3%, I can understand the loss of investor confidence expressed in today’s share price fall.
Therefore, I can’t take a bullish stance on these shares. I still believe they are “cheap”, but the risks are significant and probably beyond what most investors would be willing to tolerate (for good reasons).
888 was worth 4% of my portfolio. After today’s news, it is only worth 3%. That’s the price of my stubbornness - but at least my position sizing was reasonable!
Beximco Pharmaceuticals (LON:BXP)
Share price: 47p (-6%)
Market cap: £223m
We don’t regularly cover this one but I thought I’d take a quick look.
This company is based in Bangladesh and reports in Bangladeshi currency. Normally that would make it uninvestable for a lot of UK-based investors. However, this one has been listed on the LSE since 2005 and has paid dividends every year since 2015, which to me suggests that it is more trustworthy than the typical foreign company listed in the UK.
It’s a manufacturer of generic drugs and pharmaceutical ingredients, and today reports its H1 results (for the period to December):
Net sales +16% to £164m equivalent.
PBT down 15% £22m equivalent.
MD comment:
“While we have continued to see macroeconomic headwinds impact our bottom line, another period of double-digit revenue growth is testament to the underlying progress of the business. We have launched seven new products in Bangladesh and received a further 12 new registrations internationally. We remain focused on our commitment to delivering high-quality, affordable medicines…”
My view
The most interesting aspect of this stock for me is the long-running theoretical arbitrage opportunity between the London-listed shares (technically they are “depositary receipts”, not shares) and the Dhaka-listed (Bangladeshi) shares.
The shares in Dhaka trade at 148.20 BDT, equivalent to £1.13, an enormous premium to the price in London.
However, over many years, nobody has figured out how to make the arbitrage work, as the London shares and the Dhaka shares aren’t fungible or convertible to each other.
Short-selling the Dhaka shares while also simultaneously buying the London shares makes sense rationally, but there are logistical difficulties and besides, how long might it take for the prices to converge? People have been talking about this topic for nearly a decade!
I am curious to see if the pricing of these depositary receipts in London ever makes sense. Relative to the Dhaka price, the London shares are certainly a bargain:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Beximco Pharmaceuticals (LON:BXP)
The LSE shares (or depository receipts) have, over the last five years, traded mainly in a range of 50 - 65% of the Dhaka price. Over the last six months, this has dropped to around 40%, suggesting a bargain. The dividend yield has risen as a result. It is not clear why the LSE price should now be trading at such a large discount, but one possibility is that a number of platforms now disallow holdings in an ISA, which may have contributed to selling pressure if investors are required by their platform to offload their holdings in lieu of moving to another wrapper eg a SIPP.
Paul as usual top notch podcast, was only sad to miss the "macro" bit, which I love as I think you provide so much added value when giving your views on this stuff, quite often in unguarded moments. Anyway I digress - regarding the transcript - have you ever tried using the Word dictation feature? Click on the microphone in Word, and it transcribes everything. Surprisingly accurate even for my estuary English, and with your fine diction all the more so I would think. Would probably require 15 minutes editing afterwards. Just a thought - personally I love pretending I am a 1960's international CEO dictating to a beautiful and admiring secretary - each to their own!
I listened to the podcast for the first time this week. Very good and really useful. I then went back and listened to all of them from late December onwards. I wish I'd been a listener earlier. Well done Paul and please keep it going.
Thanks Funnymoney! Wow, you must be sick of the sound of my voice after all that podcast catching up!!! ;-)
Share talk excellent as always Paul. My favourite part tho was "sorry, I lost control of my mouth there". Haha
LOL yes that was a good one! ;-)
Trouble is when doing the podcasts, I'm having to think, read, and speak, all at the same time. Which as us chaps know well, multi-tasking doesn't always go smoothly!! Still, it's great fun to leave all the mistakes & off the cuff stuff in there, as it's only a few hundred people listening, and none of it's exactly of earth-shattering importance.
I was in the gym so it was infinitely better than staring into space whilst doing the various resistance machines!
Personal group (LON:PGH) trading update seems reasonably encouraging with Insurance Annualised Premium Income up 15% and Benefits Platform Annual Recurring Revenue up 56% partly offset for weakness in the Let's Connect business attributed to Royal Mail. I am a long "suffering" shareholder in this one, and have come close to bailing out in the past. However, there are encouraging signs that the core insurance business is growing again after taking a big Covid-19 cut, so I will keep holding after H2 EBITDA effectively tripled versus H1. Also good to see the Sage business prosper, although I'm not sure this segment is as profitable despite being a sector that is much celebrated by investors (being a technology related benefits platform recurring revenue). Any other holders with thoughts?
Topvest, that's a good summary. I'd bought some PGH in December, having previously held in 2021
Decent update I'd say, probably bottomed out now so growth this year should be very doable.
Cenkos cut PBT and EPS by 7% for this year but still looks decent growth compared to 2022. PE around 13.5x
I'll stick with it as long as the share price stays above 200p. Nice divi too.
Hi Wolf of Small Street - thanks for the Cenkos update. Yes, I do think Personal group (LON:PGH) left themselves with a lot to do in H2 so pleased they made the numbers despite the Let's Connect business stalling. If they can keep the core business growing then its very good value, but they have disappointed before.
I think Martin Bennett (ex-Homeserve) as the Chairman has probably really helped kick-start the recovery - he's been in place for 2 years now.
Be nice to see them exceed expectations at some point in 2023, but maybe that's asking a bit much!
I have some passing knowledge of Personal group (LON:PGH) from a few years back. They used to have an incredibly spend-averse culture which I assumed would still exist. A brief look at the figures makes me question this due to their lack of profitability in comparison. I do wonder about the new guard running things. I was very tempted at sub £2 a few years ago but failed to press the button. The positive is that the woman who runs it has quite a bit of stock, (partly because they took her company over?).
Beximco Pharmaceuticals (LON:BXP)
This one is more difficult that it first appears. Personally I ignore the arbitrage between the non-fungible listings as I don't see a quick solution.
Having trawled through the interims there are a few things going on - reduced margin, increased inventories etc, although the key factor in the Q on Q profit decline can be found in the Other Income, where there is no repeat of a 600k Vaccine Distribution Fee (part of the whole COVID 19 / AZ vaccine / Serum Institute saga). Otherwise operating profit would be up.
Given what the Taka has done it is no surprise that margins are being squeezed - anything they have to import will have gone up in price substantially, and for Bangladesh that includes electricity and fuel. Bangladesh is better placed than some regional comparators, but it is highly vulnerable when the $ appreciates as it has, and it is far from out of the woods from a macro perspective.
However.
What we are not provided with is proper like-for-like growth stats. There have been acquisitions - they acquired 54.6% of the Bangladeshi Sannofi business (now renamed Synovia) in Oct 2021, and from recollection that was expected to add about 10% to turnover. Quite how this has been consolidated into the accounts is not entirely clear (to me, at least), especially in terms of the acquisition occurring halfway through the prior period.
The P&L does break down the PAT between "Owners of the Company" & "Non-controlling Interest", but this was also the case in Sept 2021, presumably because they own 85% of the 2018 Nuveen acqusition, so this clouds the picture further. If you look at Q4 2021 vs Q4 2022 you can see the Income Attributable to Non-controlling Interest flip from -56,383 to +8,376. Which is the right direction, but trying to observe what is going on in the original business and what has come from acquisition is tricky.
Will need to look at this further
This might be one to put into the "too difficult" drawer?
But my rudimentary calculation of NTAV for Beximco Pharmaceuticals (LON:BXP) puts the current share price at 0.7x NTAV, which seems like a bargain.
So perhaps if one takes the current weak BDT currency as not likely to go lower, then that 5% dividend yield looks like it'll be a sweet 6-7% soon, and looks pretty secure given the reliable profitability and cashflow of the business over the years.
If I was going to continue investigating, I'd look into the shareholder structure, see if there is a dominant controlling shareholder (probably is), and/or whether there might be a take-private or strategic sale to an industry player at some point.
That will be the most likely route of "closing the discount gap" between the GBP DRs and the actual Dhaka listed shares.
Thanks for this . I've held BXP for a while and my personal view is the share is on fundamentals, cheap. I guess the principle risk here is the massive impact of currency headwinds. In any event its not a bad divi stock with a reasonable yield which seems to continue to grow
Inspired (LON:INSE) is one I held a while ago as I liked the story and seemed cheap too - the idea is they would act as an energy specialist for mid sized companies (getting the best energy deals, doing all the ESG reporting, improving efficiency, etc). This is a complex area and very fragmented market so in theory sounded good. Also some decent shareholders, and I've heard a couple of fund managers rave about it. However, the numbers always looked terrible - tons of adjustments, weak balance sheet and por cashflow so eventually gave up on this - good to see Paul thinking along the same lines.
I've added an auto-generated transcript to Paul's podcast - it should be reasonably good (the new AI-based ones work very well) - but it may not handle tickers very well.
Hi Chris,
I was wondering where you had posted this, but found it in the comments to my website here: https://qualitysmallcaps.co.uk...
Have to say, I'm remarkably impressed with that auto-generated transcript, it's done a remarkably good job. Would you mind sharing which software you used, and is it free? If so, I think this would save me hours of typing when I do CEO interviews. I've tried other transcript software before, and it's hopeless usually, and takes the same amount of time to edit, as it would to type it from scratch, but your software seems tons better!
Thanks, Paul.
I used something called whisper - unfortunately, it requires a bit of technical know-how to run it (you have to use Python and install it from pip - so if those words don't mean anything to you it might be a bit much...). The details are here: https://github.com/openai/whis...
I'd be happy to try and write some instructions to make it a bit more approachable if anyone wants to try.
I just found this site that uses the same model, but does it all online: https://modal-labs--whisper-po...
Thanks for that. Please could you let me know how you did it? Thanks
Hi Graham,
888 Holdings (LON:888) Entain (LON:ENT) and Flutter Entertainment (LON:FLTR), valuations.
Although 888 Holdings (LON:888) can look cheap in comparison on a number of metrics, I believe that the growth in BETMGM and Fan Duel with the opening up of the USA gambling market are being factored in the Entain (LON:ENT) & Flutter Entertainment (LON:FLTR) valuation, and the difference does not look so wide.
With CEO and CFO going, there are probably plenty of cupboard skeletons to be exposed.
Although 888 Holdings (LON:888) does look attractive if you can stomach the debt. (One I think won't swing at personally), there are plenty of risks for the next 12 months.
As always DYOR.
BSV
Where is (LON:888) this huge debt showing on stocko - stocko report shows net debt of -£280million which i imagine means a negative debt ie surplus ????
Please enlighten me
https://uk.advfn.com/stock-mar...
888 to Offer GBP1.02 Billion in Notes, Borrow Up to GBP909 Million to Fund William Hill Deal.
It's not in Stocko yet as the company has not reported the detailed number for 2H of 2022 yet. 888 Holdings (LON:888) say it will cost them about 170M in interest payment in 2023.
Please feel enlightened.
Let me know if you don't feel like DYOR (doing your own research) again. I just do it for you.
BSV
Many thanks BSV, but I still have no idea where I would get that info RNS ?
I've just had a quick look at 888 Holdings (LON:888) and the big acquisition & debt splurge seems to have happened quite recently, so won't be included in the historic numbers yet.
For example, the 6/2022 interim results for 888 start by saying this -
"888 (LSE: 888), one of the world's leading online betting and gaming companies, announces its financial results for the six months ended 30 June 2022 (the "Period"). The acquisition of the international (non-US) business of William Hill completed on 1 July 2022, and as such, the reported interim results, and commentary thereon, reflects 888 only."
It does provide a brief pro forma P&L in the interim results statement, which shows that the business would roughly triple in size after the acquisition, so it's a huge transaction.
There doesn't seem to be a pro forma balance sheet provided within the interim results. Although it refers to pro forma figures being on the investor relations website, so it might be worth you looking there.
In any case, financial websites like Stockopedia wouldn't show the pro forma numbers anyway. It will just feed through when the next set of published accounts show the enlarged group.
Hence whenever there's a material acquisition or disposal at any company, it's vital to manually go through all the numbers.
Regards, Paul.
After a promising start with my position in my 888 Holdings (LON:888) taken late last year, the outlook has definitely soured after today’s announcement. I’ve taken the ‘first loss’ on this today while it remains small and moved on.
Strange question but bear with it... does anybody know of any companies in the UK that are working on the use of insects as a food source addition/supplemental addition for the human population?
As a starter for your research rather than a destination…
Harper Adams university are very into their research on insects as food. In their article on ‘entomophagy’, they mention Sainsbury’s as having sold insects so someone must have supplied them. There are also links to other events and research.
Hope helpful.
there is one but I can’t for the life of me remember the name - will try and get back to you with its ticker - but defo an interesting area
it was Agronomics I was thinking of Agronomics (LON:ANIC)
There is this place: https://www.thebugfarm.co.uk/a..
Also this: https://www.eatgrub.co.uk/prod...
If I were inclined to gamble on 888,I might prefer to look at the debt.You might get a good yield right now,and rank ahead of the shareholders if things went pearshaped.
Opened a position in Finsbury Food (LON:FIF) following the recent positive trading update and this morning's announcement of the acquisition of Lees Foods. Finsbury Food (LON:FIF) won't shoot the lights out, but is a well managed company doing well in a challenging market. The acquisition of Lees Foods looks to be good business.
Morning all.... after such a strong start to the year its natural to reflect a little. I am reminded of the saying oft repeated at the start of a fell race... in Northern twang..."start too fast and you'll never last - better start slow, and go go go"..... hmmm
Yet we have started fast. I sat next to a well know small cap manager for decades and he also would add that every year starts with a dash for trash but inevitably ends with a strong preference for quality. hmmm
Makes you think as the FTSE is up 4%... the 250 index is up 6%.... the S&P slightly ahead of the 250 and Nasdaq up 10%, leading this small pack. Emerging markets have also been very strong, all helped by a weaker dollar.
After reading Jeremy Granthams election cycle piece I'm inclined to stick with my positioning... but with an expectation that index levels will struggle to maintain current pace. Otherwise we will all be looking at gains that are simply too high. Although the gains have been much fun, Id say the year isn't really panning out as I thought....with a lot of very beaten up stocks surging in a squeeze. This isn't quite the return to value and valuation based investing I and others were expecting.
My plan is to end the quarter with a stronger cash pile than current. My top investments are concentrated.... Sherborne Investors (Guernsey) C (LON:SIGC) mentioned last week... turnaround vehicle...BT (LON:BT.A) cheap but geared, strong yield - needs better results. Yellow Cake (LON:YCA) Uranium play - GDP agnostic Id argue, to a degree. Volvere (LON:VLE) v conservative turn around vehicle with significant cash backing and discount to book. Co retiring stock. Serica Energy (LON:SQZ) Fresnillo (LON:FRES) and Gold.
BT (LON:BT.A) I bought after covid...it did very well but had a lousy year last year and did not do the defensive job it should have done. It is now very results dependent but seen quite a few broker upgrades. Never the less... could be a candidate to reduce if disappoints. Also Serica Energy (LON:SQZ) could well have the hallmarks of an error. I bought for a return of a cold spell after the shares had been hit with the windfall tax and warm start to winter. In the meantime they have completed a controversial deal. Im inclined to side with management...but the shares aren't doing well... so it is definitely a candidate to be cut if the shares don't improve rather quickly. Gold and Silver have been a massive winner in the Dollar sell off cycle and therefore this would also be a potential source of cash.
Finally for those with a bottom draw (stuff that fell so much you just can't sell) ...its worth considering off loading selectively if you no longer have any real confidence in the story ... especially if rallied strongly.
On my watch lists would mainly be Zotefoams (LON:ZTF) Weir (LON:WEIR) Oxford Instruments (LON:OXIG) Spectris (LON:SXS) and others in the broadly old economy basket....
Best regards and hope January was a good one. Lets hope this continues...but a bit more measured perhaps.
Morning,
I agree, I think the froth will start to come off the markets next few weeks. February is never a great month anyway!
Beximco Pharmaceuticals (LON:BXP) this is one of my favourite pharmaceutical companies, I would be buying this morning but unfortunately I can't hold it in my ISA so will have to let the opportunity pass. I have only one major concern with the company, the factory is based in Bangladesh at 5m above sea level. Will it still exist in another 10 years time? No position.
A quick note for any other holders of Beximco Pharmaceuticals (LON:BXP) - I got my online broker (one of the major platforms) to do a "reverse bed & ISA" on my shares, selling out of the ISA and repurchasing in the dealing account, thus preserving the tax wrap on the proceeds, rather than an outright transfer of the shares out of the ISA.
If your platform has forced you to remove the shares from your ISA I would suggest you negotiate very firmly indeed on any commission.....
Stockopedia have listed Beximco Pharmaceuticals (LON:BXP) as being non-ISA eligible for years. How certain platforms got this wrong is a surprise to me.
Why is Stockopedia correct and platforms wrong? I have often found Stockopedia information regarding this as incorrect. Some platforms won't trade certain shares for various reasons or won't deal with withholding tax. I nave held Beximco Pharmaceuticals (LON:BXP) in an ISA in the past. I see on HL, no ISA but can put into a SIPP.
On my other ISA platform I can buy shares.
Quick question Paul (or others) . . . . . .you mention above that the shares covered in the Podcast are included in the SCVR summary spreadsheet. However, I can only see tabs for “”Top 20 Value/Garp”, “Runners Up”, “Speculative” and “”New ideas during 2023”. Am I missing a general page covering a larger universe of shares linked to latest SVCR updates?
Thanks in advance.
Hi
Different spreadsheet - hopefully this works:-
https://docs.google.com/spread...
Phil
That's the one! I'm trying (probably in vain!) to keep the link secret, just for Stockopedia subscribers. Hence why I don't include it more prominently in the reports, as otherwise anyone who gets marketing emails from Stocko would get the link.
Hi Paul and other Stockopedia subscribers,
If I click on 'Add shortcut to drive' does this save a copy of the Google doc s/sheet and capture the daily updates as and when they are populated?
Best wishes,
Imran.
is it possible to put a password on this which could be renewed/updated at regular intervals?
Avingtrans (LON:AVG) announces that Adaptix, a company in which holds an 11.9% stake plus £2m in convertible loan notes has received FDA approval for its portable X-ray/CT scanner. Good news, but more importantly it has a direct read across to Magnetica, which is 75% owned by Avingtrans (LON:AVG) and is developing parallel technology for a portable MRI scanner. Steve McQuillan, CEO of Avingtrans (LON:AVG) was recently appointed non-executive Chairman of Adaptix.
The investment in Magnetica is not reflected in Avingtrans (LON:AVG) shares and is essentially in the price for free.
I hold
Paul, I like the new mystery share summary you have just posted, a very useful reminder of ideas to further research, thank you.
Good morning Paul and Graham. If you have time, does CentraliNic's TA make you even more comfortable Paul with the share price and company since your December analysis? Cash up debt down and ahead of expectations, we hold and I'm tempted to add to one of our rare currently small winners.
We never know but this should not be in the small cap in the next year if it continues to deliver. Surely this might be due a re-rate
Morning JASVFS,
Yes I'll look at CNIC today. It's been quietly growing on me, but wish I understood what it does, how it makes profits, and what the competition is doing. That's a cavernous gap in my understanding! The historic growth almost looks too good to be true, but last time I looked at the numbers, I couldn't spot anything untoward in them.
We'll take a fresh look later today. In the meantime, do please leave your own comments on it, as that might help guide me.
Thanks, Paul.
CentralNic (LON:CNIC) main business, in a nutshell, is serving ads on domain names that either misspells or defunct, where there is a chance of traffic and hence monetisation.
An example is: http://www.meatsnacker.co.uk/
Used to be an operating online store that closed down. But there are still links and customers out there who will visit the site. So it's now serving ads to monetise that rump of traffic.
CentralNic (LON:CNIC) main business, in a nutshell, is serving ads on domain names that either misspells or defunct, where there is a chance of traffic and hence monetisation.
An excellent description of the main growth engine for last year and unaffected by Apple’s privacy changes. But worth acknowledging that, chugging away in the numbers, is a sizeable domain registration business, essentially a niche Verisign or GoDaddy, providing very sticky, reliable revenues.
I've looked at their Corporate website Paul and the best answer I can give you is to repeat what it says there :- CentralNic provides tools to entrepreneurs, enterprises and Governments in virtually every country in the world to build, secure and monetise their own part of the internet. They've acquired 22 companies since they launched on AIM in 2013 to help them to do that. It seems like a management with a mission to me but I turn to you on the financials if you get time. I acknowledge Boon and BnB help on this.
CNIC -£126k director share purchase on 20th January and the price has dropped from £6 since early January. Updated positive report on Research Tree . Be interested in Pauls view but this looks to be heading for bargain territory
Stockopedia | CentralNic Share Price - CNIC Share Price Quotes, Charts, RNS & Stock Market News
The SP was not £6 in early January ( unfortunately) If it had been i would not be holding now ;-))
Helvellyn thanks... sorry meant £1.60 DOH !
My morning smallcap tweet: Clem Chambers' Horror Show.
Impellam (LON:IPEL) Eden Research (LON:EDEN) Sopheon (LON:SPE) Online Blockchain (LON:OBC) DP Eurasia NV (LON:DPEU) Novacyt SA (LON:NCYT) Aptamer (LON:APTA) Ra International (LON:RAI) Inspired (LON:INSE), Civitas Social Housing (LON:CSH), Personal group (LON:PGH)
◄Impellam (IPEL)► guides FY-Dec ahead of its 'original expectations' (=current expectations?) with gross profit of £315m. Sells Regional Specialist Staffing businesses in the UK for £85m. [SP=680 Cap=306m]
◄Eden Research (EDEN)► Mevalone has received authorisation for home garden use in Italy, the authorisation for domestic use. [SP=4.61 Cap=18m]
◄Sopheon (SPE)► guides FY-Dec rev in line, adj EBITDA to approach $7m ($6m) comfortably exceeding market expectations. [SP=650 Cap=66m]
◄Online Blockchain (OBC)► plans NFT project based on The Rocky Horror Show. Clem Chambers, CEO, says "I would like, if I may, to take you on a strange journey." [SP=21 Cap=3m]
◄DP Erasia (DPEU)► guides FY-Dec rev up 77% or 13% after IAS29. Adj EBITDA ahead of current market expectations. [SP=59.6 Cap=85m]
◄Novacyt (NCYT)► trial in dispute with Gov't to start 10 June 2024 and is expected to last 16 days. [SP=75.92 Cap=61m]
◄Aptamer (APTA)► follow on project with multi-national consumer goods company worth up to £185k. [SP=38 Cap=26m]
◄RA International (RAI)► wins contracts worth $8.2m [SP=12 Cap=21m]
◄Inspired (INSE)► guides FY-Dec rev 10% ahead of market expectations at c.£88m. Adj EBITDA up 6%, in line. [SP=9.35 Cap=91m]
In line: CSH, PGH
SThree (LON:STEM) (I hold) post excellent figures for last year. Positive forward guidance too.
“As we enter the new financial year, trading continues to track in line with expectations, supported by a healthy contract
orderbook. ”
Excellent weekly summary over the weekend Paul - always a much appreciated “take-stock”. Thanks