Small Cap Value Report (Mon 30 Nov 2020) - DLAR, CAR, TUNG, MBH, TRMR, VCP

Good morning, it's Paul here with the SCVR for Monday.
I've done some work over the weekend, catching up on some of last week's backlog, as follows;
Agenda -
De La Rue (LON:DLAR) - Half year results
Carclo (LON:CAR) - Interim results
Tungsten (LON:TUNG) - H1 Trading update (profit warning)
Michelmersh Brick Holdings (LON:MBH) - Trading update
Tremor International (LON:TRMR) - Positive trading update
Victoria (LON:VCP) - Interim results
.
Today's report is now finished.
.
Mello Monday - today!
Yes, it’s that time again. David Stredder’s interesting & enjoyable Zoom investor evenings are proving very popular. Most of the 500 available places have already been filled, with annual passes selling well.
I’ve been asked to appear on the BASH (Buy, Avoid, Sell, Hold) stock discussion panel tonight. Also I’ll be briefly plugging my sister-in-law Lauren’s Christmas harp concerts on there too (see below). There are some really interesting speakers and companies that will be giving presentations.
3 hours might seem like a long time, but the time flies, and of course being at home, we can wander around with headphones on, doing other things at the same time, if we wish. So a really flexible format.
Details & tickets here. NB. Discount code MMStocko21 will get you half price tickets!
Harpy Christmas
My sister-in-law, Lauren Scott, is a professional harpist. As with most other musicians, literally all her bookings were cancelled this year, due to covid restrictions. Christmas is usually her busiest time, with many live performances of Christmas carols & traditional tunes. So Lauren has decided to play live concerts on Zoom instead, for a modest fee.
Here is an example of Lauren playing Xmas tunes. I can’t tell you how relaxing & fun a Christmas singalong to the harp is, as usually my family enjoy this every year in person, but we've decided it's best not to meet up this year.
The harp has a remarkable calming effect I find, as you can tell from this short video of Lauren playing Xmas tunes;
.
.
Please forgive me for plugging a family thing, but I’m sure many of you would really enjoy Lauren's online concerts over the festive season, and it would also help out a self-employed musician who is tremendously talented & experienced, but as with so many people in the arts sector, suffering a major loss of income this year.
I’d personally be so grateful to everyone who signs up (and hopefully spreads the word on social media too), as it helps my family keep the music playing in these exceptionally difficult times, and will bring pleasure to others too.
More details are here, including how to buy tickets, probably too cheap, but we weren’t sure what level to set it at, as it’s a new idea.
You can also “sponsor” a tune, and Lauren will read out your personalised message to your loved ones before playing it live - e.g. dedicate the tune to family that you can’t meet up with this year, and they will hear your message, from anywhere in the world.
I asked Lauren to record her own introduction, here, which explains it better than I did above!
.
There are quite a few backlog items left over from last week, so I’ll rattle through those that look most interesting now.
De La Rue (LON:DLAR)
Share price: 166p
No. shares: 195.0m
Market cap: £323.7m
De La Rue plc (LSE: DLAR) ("De La Rue", the "Group" or the "Company") announces its half year results for the six months ended 26 September 2020 (the "period", "H1" or "half year"). The comparative period was the six months ended 28 September 2019.
De La Rue has been a very interesting, and strong turnaround this year. It’s gone from looking almost bust, to a success story, with lots of costs stripped out, new contracts won, and an equity refinancing completed.
Note that the share count rose substantially, from 114m to 195m shares in issue earlier this year, in a rescue refinancing. Another example of a company with a stretched balance sheet, whose shareholders paid the price, with substantial dilution. With almost twice as many shares in issue now, the share price might struggle to reach previous highs, since that would be almost double the equivalent market cap.

.
A few key numbers;
- Revenue (adjusted) is down 15.1% to £174.7m in H1
- Adj operating profit up 596% to £15.3m
- Adj EPS 6.5p (LY H1: (1.4)p) - a big improvement. If we simplistically double that for a full year, so 13p EPS, then the PER would be 12.8 - looks cheap
- Net debt greatly reduced to 21.6m, vs 170.7m LY - that’s improved from danger territory, to comfortable. I wonder if any tax, or other creditors have been stretched? The main benefit has come from the £100m equity raise in July
- Adjustments relate to the run-off of UK passports contract, and a disposal of the international identity solutions subsidiary
- Huge cost-savings of £36m annualised
Outlook -
"Our two ongoing divisions, Authentication and Currency, are performing well. We are building strong order books and have secured a number of important strategic wins in the first half of the year.
"Trading for the financial year 2020/21 has been positive, with the outlook for revenue, adjusted operating profit and net debt for the full year in line with the Board's expectations."
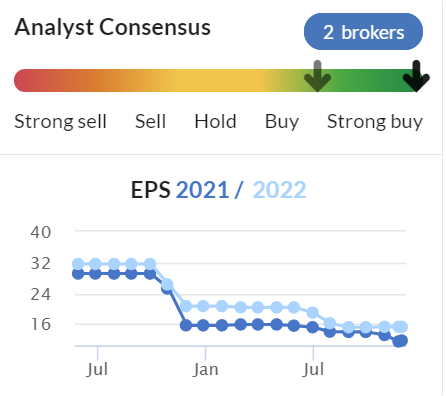
Unfortunately, there’s no footnote telling us what those expectations are. Looking at the Stockopedia broker consensus forecasts, they’ve only got 2 brokers submitting forecasts, which is surprisingly low. Unfortunately that’s been caused by Mifid II, which seems to have been counter-productive, in greatly reducing the amount of research produced.
FY 03/2021 consensus is 11.75p, so the 6.5p achieved in H1 leaves only 5.25p to achieve in H2. Could we end up seeing a beat against FY expectations in due course? If they’re ahead at the end of H1, with upbeat outlook comments, then there's a decent chance of a beat.
Forecasts have come down a lot, which might indicate upside potential as the economy hopefully begins to improve, and maybe normalise as we progress through 2021.
.
.
Tobacco authentication - this looks a very interesting growth area. A friend who is bullish on DLAR, and who normally talks sense, says this could be a decent money-spinner for DLAR in future, as it’s one of only a few companies authorised to do this.
De La Rue is targeting Authentication division revenues of £100m by FY 2021/22, with strong operating margins and strong year-on-year growth in this division during the three-year period of the Turnaround Plan, as more countries adopt tobacco tax stamp schemes to comply with the World Health Organisation (WHO) Framework Convention on Tobacco Control (FCTC).
Covid immunity certificates are another innovative area under discussion with Governments.
Currency printing - DLAR is a leader in this field too, with special polymers. Only 3% of the world’s banknotes by quantity (but 12% value) have moved to polymer. So there’s a big market opportunity as those figures rise.
Cashflow/dividends - some future cash outflows are mentioned in the commentary, for contract rebates, and restructuring costs. However;
… by the end of the Turnaround Plan in FY 2022/23 we aim for the Group to be generating positive free cash flow and capable of supporting sustainable cash dividends to shareholders.
Liquidity - ample. Figures are given on bank covenants too, which also look to have plenty of headroom. Therefore I have no concerns about solvency. It looks secure now.
Pension deficit - has almost disappeared on an accounting basis, due to strong asset prices more than offsetting low interest rates.
The actuarial valuation is rather different - a funding shortfall of £142.6m at 31/12/2019, rolled forward to 30 April 2020 when it rose to £190m - yikes.
However, equity markets have risen a bit since end April (although remember April saw a large bounce from the March lows), so this deficit could come down, depending on how much of the scheme assets are invested in equities.
Deficit funding payments are a hefty £15m p.a. Until March 2023. That’s highly material to the valuation, and when you take this into account, the low PER is perhaps justified.
With interest rates probably now zero for the foreseeable future (maybe even possibly following Europe & Japan into negative rates, who knows?) then investors do need to adjust the valuation to take into account these large ongoing cash outflows.
Balance sheet - looks OK, but when you adjust the pension deficit for what it really is (very much larger than it appears), then the £130m net assets would disappear.
Now that the company is profitable again, and raised £100m in fresh equity, its balance sheet strikes me as adequate. So no concerns overall for me.
Cashflow statement - it’s not really generating any cash as yet, but that’s explained in the commentary. The big items are the equity raise, and use of that to repay debt.
My opinion - I thought it looked cheap until I was reminded of the substantial cash outflows in the coming years in order to address the pension deficit. Sometimes I wonder if some investors might buy into shares like this, thinking they’re cheap, only to then realise how material the cash outflows re pension funding are, some time later?
Overall, the turnaround at DLAR looks excellent, and the company seems to have some really good growth potential in areas like tobacco certification, polymer banknotes, etc.
Therefore I reckon it looks pretty good overall, and I can probably live with the pension deficit, although it undoubtedly limits the upside.
I don’t see any reason to rush in and buy at 166p, because I think there are better upside opportunities with other shares. If it dropped say 20% from here, then I think that would be more compelling.
.
Carclo (LON:CAR)
15p - mkt cap £11.0m
As I’ve mentioned before, several times, we need to be very careful with this one, because its finances are highly precarious - specifically a gigantic pension deficit, and far too much bank debt. Also its aerospace division is not exactly in a buoyant sector (although it is only a very small part of the group)
On the upside, there seems to be a decent business here, underlying EBITDA in H1 being £4.6m (down from £6.3m).
Looking through these interim results to 30 Sept 2020, it strikes me as a very risky situation - this one is for gamblers only.
Net debt is down a bit, but still too high, at £24.4m (excluding lease liabilities)
Pension deficit has shot up from £37.6m at March 2020, to £58.1m at Sept 2020. This was caused mainly by the reduction in discount rate from 2.3% to 1.5%, used to value liabilities. This is another good example of just how toxic pension schemes can be at the moment, with just a small change in assumptions causing chaos to the balance sheet here with Carclo.
My opinion - I cannot see any value in the equity here. It looks as if all the group cashflows will probably be needed to feed the pension scheme, and gradually reduce excessive bank debt. What’s left over for shareholders? Probably nothing, as no divis can be paid before July 2023 under a funding agreement.
Shareholders need to pray for a dramatic improvement in trading. Then there could be leveraged upside on the equity. Without that, this looks a zombie company, whose cashflows are needed to feed the pension fund, and keep the bank at bay. Once it's stable enough, an equity fundraising looks inevitable, to reduce debt.
Very high risk.
.
Tungsten (LON:TUNG)
28.6p - mkt cap £36.1m
How about this for a dismal track record;

.
This invoicing software company has a 30 April 2021 year end, so it updates us on performance in H1 to Oct 2020.
Key points;
- Challenging market conditions due to covid
- Transaction volumes down 7% in H1
- H2 expected to also see reduced transaction volumes
- Longer sales conversion cycle, expected to continue. 4 new clients won in H1
- Guidance - revenues for FY 04/2021 expected to be similar to FY 04/2020
- H1 revenues expected to be £18.0m excluding TNF, whatever that is. Please would RNS writers include a footnote for every abbreviation used!
Profit warning -
Underlying adjusted EBITDA is now expected to be not less than £3.2m, materially lower than previous guidance.
Adjusted EBITDA was £2.7m last year, FY 04/2020. Note that TUNG capitalises about £2.8m p.a. in development spending, so in the real world, it’s trading around cashflow breakeven at best.
Cost-cutting has been done, expected to reduce annualised savings of £4m in future. Very sensible in the circumstances
Net cash - remains tight, at £1m (£3m cash, less £2m borrowings)
Outlook - hopes that transaction volumes will improve
My opinion - you really do have to be an optimist to own this share, given its track record. Fair enough, this year has been really difficult because of covid.
TUNG has been able to cut costs, so I don’t see any risk of insolvency for the time being. Maybe someone might come along and buy it, who knows? Software companies sometimes attract generous bids, for their recurring revenues, client relationships, cross-selling value, and removing costs. As a standalone business though, it’s very difficult to see much value in Tungsten. It’s not really convincing as a covid recovery share either, because it was trading poorly before the pandemic too.
.
Michelmersh Brick Holdings (LON:MBH)
111p - mkt cap £104m
As with so many cyclical companies, this has had a big surge on the recent good news re vaccines.
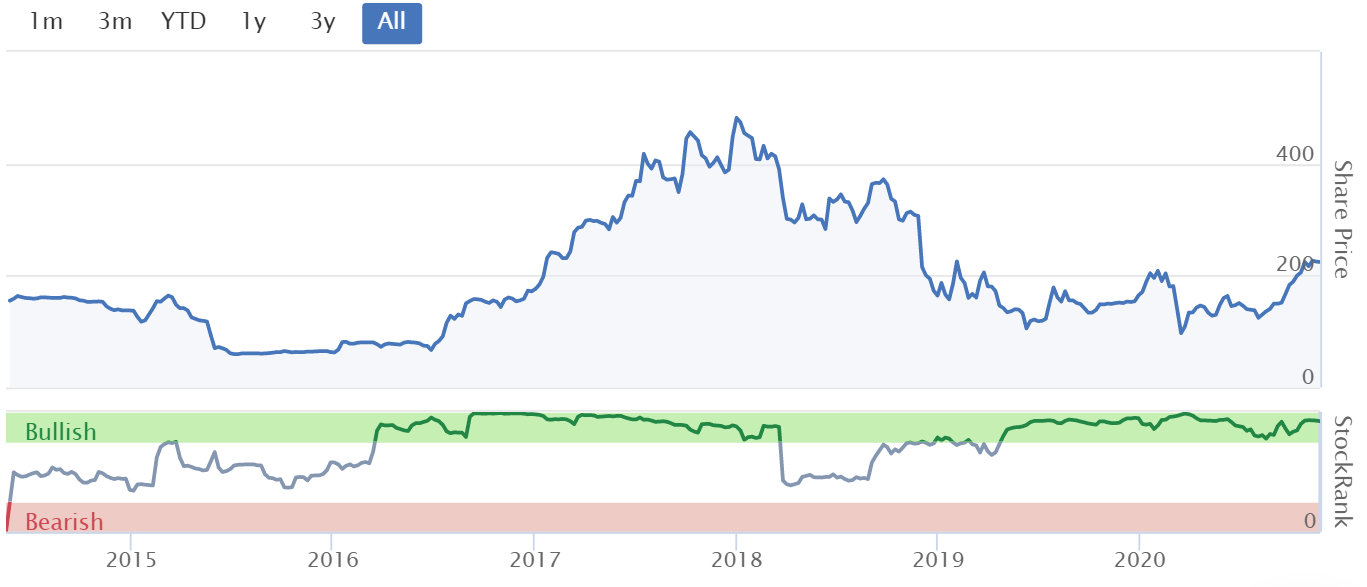
Although it’s not much more than a blip on the 3-year sideways chart;
.

.
This is the problem with markets in the last few years. Investors want growth, not value. So traditional companies making bricks, are not likely to excite people enough to generate much upside at the moment, or ever.
I like value shares that churn out cashflow, and pay great divis, but the divis here seem lacklustre.
Trading update
Michelmersh Brick Holdings Plc (AIM: MBH), the specialist brick manufacturer, today announces a trading update ahead of its final results for the year ended 31 December 2020.
This bit below sounds encouraging, and could have good read-across for the whole housebuilding sector, as things seem to be getting back to normal. Albeit boosted by the temporary Stamp Duty reduction;
Trading performance of the Group has been resilient since June 2020 and this has continued through November. Current production capacity is back in line with pre-Covid levels and Group turnover for the months of July to October was 7% ahead of the equivalent period in 2019. The Board now expects that underlying revenue and profit for the Group will exceed market expectations for the 12 months ended 31 December 2020.
We’re not told by how much it will exceed market expectations, nor what market expectations are!
Furlough funding of £0.5m is being repaid to the Government.
I still don’t know the full reasons why some companies are repaying furlough monies. Is it a social conscience, a legal requirement, so they can pay divis without a backlash, to generate positive PR? I have no idea. But it’s surely a good thing that some companies are repaying taxpayer support, well done to Michelmersh, whatever the reason(s)!
Net cash - strong cashflow in recent months. Net cash will be positive at 31 Dec 2020, versus net debt of 6.5m at 30 June. Very good.
Dividends - 2.25p will be paid in June 2021, wrt. FY 12/2020.
My opinion - a good solid company. Looking at forward earnings, and asset backing, the current price strikes me as fair. Hence I cannot see any reason to rush out and buy (or sell). I think this is possibly the type of share to vaguely monitor, and buy on any big sell-offs, on the basis that it should recover whenever something goes wrong either internally, or on the macro side of things. Bricks are always needed, after all.
.
Tremor International (LON:TRMR)
Share price: 293p (up 27% at 12:23)
No. shares: 133.2m
Market cap: 390.3m
Tremor International Ltd (AIM: TRMR), a global leader in video advertising technologies, provides an update on trading for the year ending 31 December 2020, following a period of record revenue and profit growth.
It’s achieving strong organic growth -
Tremor continues to drive substantial customer momentum in the second half of the current financial year, demonstrating strong organic growth despite the impact of Covid-19. Revenues generated across October and November 2020 were the highest in the Company's history. Overall, it is anticipated that the Company will now achieve 37-43% revenue growth in the second half of 2020, compared to H2 2019.
Substantially raised guidance for FY 12/2020 -
US dollars | Revenues | Net revenues | Adj EBITDA |
Oct 2020 guidance | $340-360m | $30-36m | |
New guidance today | $390-400m | $171-175m | $50-52m |
.
That’s a 55% increase in guided adj EBITDA, taking the mid-point of each range. That strikes me as a highly impressive rise, given that it’s coming near the end of the financial year. At this late stage of FY 12/2020 I would expect tweaks to guidance, not a >50% increase!
The share price has responded very positively, up 30% as I type this at 08:44, the day’s biggest riser at the moment. Well done to shareholders!
What’s caused this strong growth? It seems to be 3 particular services, see this table, showing stunning growth;

.
It says the current growth trend is set to continue. If so, then it sounds like things could get exciting here.
Virtual demo - I have no idea what services Tremor offers, so this online product demo might be worth attending, to learn about the company;
Tremor will also be demonstrating the capabilities of its cloud-based platform on a finnCap Tech Virtual Demo for Institutional Investors on Wednesday, 9 December at 3.00 p.m. UK time. Please contact IR@finncap.com if you would like to join. This will be recorded and subsequently available to all investors at Tremor's Investor Relations website and https://www.finncap.com/sector-expertise/technology
My opinion - none, as I don’t understand the business at all. The only thing I would caution, is that in the past the bumper earnings generated in this sector have tended to be transitory. Google or someone else suddenly changes an algorithm, and that clobbers earnings at companies which were milking it in some way. Or regulations change, switching off a cash cow.
Therefore, my main worry here would be whether Tremor’s profits & growth are sustainable? Substantial Director selling can often be a good indicator that they’re probably not, so that’s worth checking out. The huge growth that seems to have appeared from nowhere, in its 3 new product areas almost looks too good to be true. If profits appear so quickly, as if by magic, then again, how sustainable are they likely to be?
On the plus side, there’s a brief update note out this morning from Finncap, which points out that Tremor is priced at, “a vast discount to its US peers”. The broker has a 700p price target on it.
Must admit, I’m tempted to take a small, speculative punt on Tremor.
The company seems to have been able to reinvent itself, after things went wrong before.
.
.
Victoria (LON:VCP)
Share price: 610p (up 1.7%, at 09:54)
No. shares: 116.85m
Market cap: 712.8m
Victoria PLC (LSE: VCP) the international designers, manufacturers and distributors of innovative floorcoverings, is pleased to announce its interim results for the 27 weeks ended 3 October 2020.
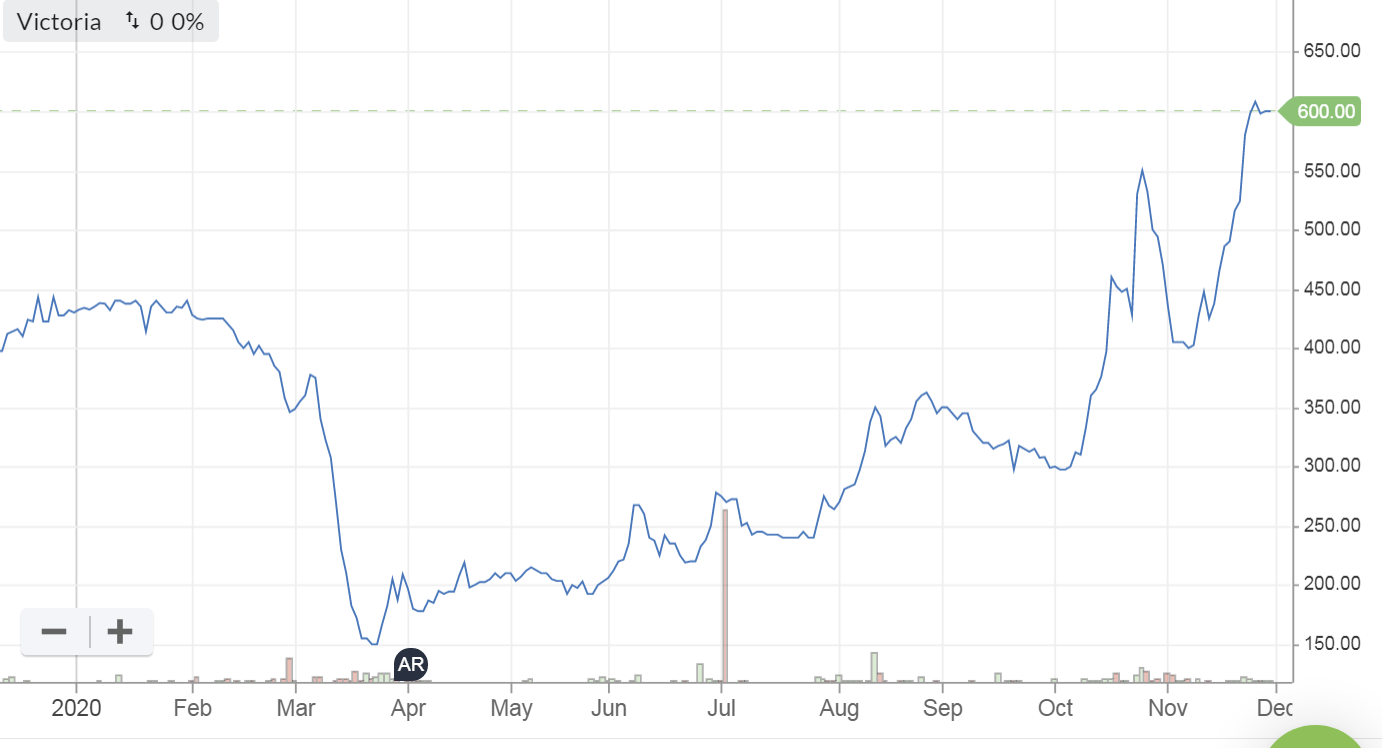
This share has enjoyed a strong rebound in recent weeks, along with almost everything else of a cyclical nature.
The headlines for this RNS motivate me to read more;
Strong Post-Lockdown Recovery and +300bps Margin Growth
Current Trading Significantly Ahead of Market Expectations
These interim results include at least 2 months of lockdown, and the recovery period afterwards, so I’m not expecting great figures.
In the circumstances, these figures look resilient -
.

.
As a general point, we should remember that covid lockdown trading will usually include substantial help from Govt schemes - e.g. furlough, business rates holiday, tax deferral, possibly grants & loan guarantees, and equivalent schemes in overseas operations.
Net debt - whilst still rather too high for my liking, bear in mind that 3.3x EBITDA is not outrageously high. Also it is covenant-free bonds (July 2024), so very much safer debt, than bank debt. A very smart move by the company as it turns out, with lucky timing just before covid hit.
Post lockdown - record performance, with +9.2% LFL revenue growth. This mirrors what other companies in home improvement have been saying - that lockdown has triggered a surge in households wanting to spruce up their homes.
Margin improvement of 300bps described as “unprecedented”, due to efficiency gains implemented last year
Substantial investment by Koch Industries (a large US based conglomerate) - previously announced, this is just a reminder. Could this be a precursor to a full takeover bid, I speculate?
Outlook - ooh look at this, it's rather good!
Although erratic government actions make it difficult to provide formal guidance, the Board does expect the full year outcome to be well ahead of current market expectations.
The strong demand we are currently experiencing for our products is expected to continue due to consumers prioritising spending on their home environment, supported by some of the highest household savings rates on record. As a result, meaningful organic growth is expected to continue into the New Year.
Pity we’re not given a footnote to tell us what market expectations are. It really does help when companies provide that information. I’m told that some brokers push back against this idea, which is awful in my view. Why on earth wouldn’t you want investors & potential investors to be given helpful facts?
Acquisitions - a worked example is given for how Victoria has theoretically got the flexibility to finance acquisitions up to £700m, based on an acquisition multiple of 7x EBITDA, partly funded using debt, and earn-outs. This looks credible. Victoria has been highly acquisitive before, and it seems that's set to continue.
Adjustments to profit - this is mostly reversing out amortisation of acquired intangibles, i.e. goodwill, so that’s absolutely fine by me, I think valuing the share using a multiple of adjusted earnings is sensible.
Finance costs - debt interest is quite considerable, consuming not far off half of the adjusted operating profit, worth bearing in mind.
Balance sheet - relies heavily on bonds to finance the business. Some figures;
NAV: £261.7m. However, if we remove the £433m intangibles, then NTAV is negative, at £(171.3)m. Deferred tax liabilities seem to be mainly related to intangibles, judging from note 19 in the last Annual Report, so I’ll remove that too, which takes NTAV to £(101.3)m - not good, but bulls would argue that the business generates enough cash to make that a tolerable position.
I think given its resilient performance through covid/lockdown, then the debt is more tolerable that I previously thought. Also, as mentioned above, it’s very well structured, as covenant-free bonds. The only risk is if the July 2024 refinancing date happens to coincide with a major financial crisis.
Working capital - looks very healthy, with a Current Ratio of 1.94. The business is funded by long-term creditors, of £661m, which includes lease liabilities & deferred tax.
Overall, I would much prefer positive NTAV, and less reliance on debt. But the way things are structured, is deliberately designed to leverage the upside for equity. Providing nothing serious goes wrong, then the risk is probably tolerable. The structure has proven itself well during the intense stress of covid/lockdown, which bolsters my confidence.
My opinion - it’s all pretty impressive in my view. Victoria has really proven the resilience of its business model, and that gearing can work, if it’s structured carefully, i.e. not subject to the whims of bank managers, or external events triggering covenant breaches.
Presentation slides for today’s interims can be found here.
I think the recent strong recovery in share price is fully justified. Unfortunately, I didn’t quite muster the courage to buy near the recent lows, which is a pity, but there we go. The current share price looks about right for now, so I’m not going to chase it any higher.
.
.
That's it for today. See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Lauren Scott got a plug on Mark Forest's show around 17.22 this afternoon on Scala. Clearly she has a reputation!
Paul, I know you've analysed Spectra Systems (LON:SPSY) too before. Reading through your commentary on De La Rue (LON:DLAR) it strikes me they are super similar and overlap in clients and products.
How are they different and given De La Rue issues in the last few years, has Spectra benefitted? Or is there yet a third or fourth big player globally in this space?
When I read Spectra it seemed like competition was limited to maybe one or two other players globally. DLAR will be one, who are the others?
Good questions! What's your view?
I'd never trust a FAANG company to host my businesses/systems.
How could you trust a company like Microsoft, Apple, Google or Amazon?
In the blink of an eye, and without notice, possibly even in error, your I.T. infrastructure could just disappear without trace leaving you with one massive problem.
I don't want to elaborate too much but I like at least 3 copies of everything in different locations by different business owners.
You also don't know how secure the host provider really is. They've all got indictments against them for security and privacy breaches.
What ever can go wrong, will go wrong.
All those companies are better at hosting business than (generally) any individual company is at hosting their businesses themselves. They have much better resiliency, failover, performance monitoring and security monitoring than most companies can afford for their own datacenters.
You can fail over between the major vendors if set up correctly to offload single vendor risk.
Hi Paul,
I think the music your sister-in-law creates is wonderful and I for one will certainly be spreading the word via my LinkedIn and Facebook accounts.
Highly enjoyable and thank you.
Mark
Thanks Mark. It's been an incredibly difficult year for almost everyone in the arts. So earning a few bob from doing online concerts, is a lifeline for professional musicians.
Best wishes, Paul.
Here are my heat maps for today (prices as at ~2pm).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volume; or moving more than a 20d EMA of the ATR):
Big movers today in the SCVR world (moving more than 20d ATR EMA against either yesterdays close, or today's open):
Breakouts today in the SCVR world:
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR relevant ones here in the hope that others may also find them interesting or useful.
greensiax
Hi Paul, I know you've spoken to boo management frequently in the past. (I think you mentioned it on Friday), if Arcadia collapses, what do you think the likelihood that BOO might pick up some of the brands, and even some retail outlets ? In your expert view are the brands valuable ?
Do you think there's any chance they might pick it up for a song, and decide to go into competition with primark on the high street ??
If so might this be the moment to top up ??
cheers K
Evans certainly has a significant online presence, and that is just from my Missus :-)
Why on earth would they want to shift their highly successful business model to take on the high overheads of shops?
Sorry I did not make that clear - ditch the high street shops and cherry pick the online business.
Hi kenobi,
I could be wrong, but my impression is there's close to zero chance of Boohoo (LON:BOO) (I hold) wanting to operate physical stores. Why would they?? They're crushing physical stores by selling online. Just wait for the competitors to go bust, and buy the brand name & email customers list, for tuppence ha'penny. Then keep its design team, hugely expand the product range, put it all through the BooHoo marketing & logistics machine, and within say 2- 3 years, they have another highly successful online brand, making loads of profit.
As for Arcadia brands - I'd like to see BOO pick them up for a low price, esp TopShop/TopMan, but even those two (the best Arcadia brands) are old hat now. What are they worth? Probably not that much.
Mike Ashley's ego is probably the most likely buyer - prepared to pay a higher price to vanquish & totally humiliate his big rival Philip Green, above any commercial value of those brands.
I could be wrong of course, who knows what negotiations go on behind the scenes?
Lots more High Street competitors gone. Arcadia is very important to Debenhams, so that's likely to disappear too. High Streets & shopping centres become wastelands for fashion - BooHoo thrives.
It's so obvious the way things are going, and we can buy the big winner for 26 times 2021 earnings! It's crazy. Such a brilliant opportunity, to pick up BOO shares c.300p. A total no-brainer in my view.
Regards, Paul.
Hi Paul, sure I agree that this is the conventional logic, however if clothes shops disappear, and particularly women like shopping in physical stores, it does make you wonder if at some point there'll be so little competition on the highstreet, and they'll have such scale, that going up against primark, and using the stores to physically showcase their products might be a good idea, and of course perhaps sell more premium items. Or there has been talk for years that as shops die out, you'll get places where you can view and try on product, perhaps show rooms if you like. and perhaps you try on and order from there, and it gets delivered to your home. There fore many less returns as you've seen and tried the stuff on, no need to order double what you want. I wonder if there's milage in this approach. Of course you don't have to buy arcadia to try this. Interesting your views on Mike Ashley.
As an aside it seems incredible to me that a billionaire with a 300 M yacht, should let his retail empire go bust because he couldn't secure a 30M loan. It seems to me that this is a convenient out for him, and that he's long since lost interest.
thanks for your thoughts,
K
Wow, harp absolutely lovely, especially Celestial Spirals. Made up for the site being down today. I think you should turn to your favourite music when you are stressed.
Re: £Tracsis
Apparently they have been asked to bid for Traffic management around the mass vaccination process the Govt is planning to enable smoother admin of the process.
If they get an award it is an interesting adjunct to the general Event Traffic management they handle for concerts etc.
Tremor International (LON:TRMR) stunning update from them today. 55% increase in earnings way ahead of expectations. The key is in connected TV. Interestingly trades at a fraction of the price of its two US competitors for some reason and as Paul says broker has stuck an upwardly revised target of 700p on it
If you don't know what the company does and why the company thinks the current trend should be more sustainable than in the past the H1 investor update gives a reasonable overview in 12 mins.
/5c3d3e3e02Novacyt Sa (LON:NCYT) Hi, anyone got a view on this article in the Independant? It saying there are some issues with the rollout of testing machines in the NHS, that could impact any further agreements. Would explain the 4% drop this morning, but its really hard to workout any longer term impacts? https://www.independent.co.uk/news/health/coronavirus-rollout-of-rapid-testing-machine-in-english-hospitals-to-be-halted-b1762732.html
What really got my goat about that headline is the following response of a government spokesperson, contained in the very same article, which effectively stated that the headline claim was untrue:
The government has insisted that the rollout is not being stopped and that there are no plans to remove the existing machines, some of which have been validated and are now providing rapid testing for hospital patients and staff.
A spokesperson for the government said: “All the testing technologies used in NHS hospitals have been clinically validated and are highly accurate.
“New testing technologies are being developed at pace to enable speedy and accurate diagnosis of Covid-19, and ongoing assessment of these technologies is taking place as they are rolled out across the NHS.
“We will continue to analyse and determine the best clinical use for all of our rapid technologies, including Primerdesign, and will deploy these tests across the NHS in line with the latest findings.”
Good point! Thanks Westway001
Looks like we are getting the usual run-up in Sosandar (LON:SOS) share price before they report interims tomorrow. My guess is they will still be some way from escape velocity. Not enough progress being made on social media (Instagram followers barely moving) by my calculations compared to rival brands. Where could I be wrong? Repeat customers - one of the most important metrics for any consumer business. If repeat customers are coming back and buying in good volume that could be an important early indicator that the after-burners might be starting to power up. That’s what I’ll be looking for evidence of as it would not only solve the cash burn problem but also evidence that the brand has staying power. Good luck to all holders (I’m not one yet).
I agree, I hold, but I'm wondering if this is like the boosts we've had in the past just before the next round of fundraising, with boo looking so much better value I do wonder if downsizing and moving some in that direction might be worthwhile. We might find out tomorrow if that would have been a good strategy today.
Hi Paul, regarding pension deficits, how do you quantify what is a big deficit and what is not? I am asking so I can Do My Own Research. Right now, I need context for the absolute number where I find it.. EG a metric or a calc.
Grateful for a response. Also this would be a useful stock metric to auto flag on the stock report page
Tks snooker
Some quick thoughts for you. First, you want to find out what the ‘buyout’ deficit is as opposed to the accounting deficit. ‘Buyout’ deficit (i.e. the amount that a company like Legal & General would view as the real deficit if they were to acquire/take-on the deficit) is closest to the economic value of the deficit (accounting deficit often understates the problem). Then consider that buyout deficit versus the market cap of the company. You need to use your own judgement here but if the company already has significant normal debt (i.e. enterprise value materially bigger than market cap) and the pension deficit equals (say) 25% of the market cap or higher then in my view that would be looking unattractive. You are spoiled for choice in the stock market and lots of good companies out there without pension deficits - company would have to be really special in my view to invest in when there is a large pension deficit.
THANK YOU NEBRASKA,
I have saved your reply and I am grateful for you taking the time to respond in a comprehensive way....I am not an accountant so the whole DYOR is a nightmare. Also, given what you say above, this looks like an easy metric for Stocko to plug in.....
TKS again, Snooker
Hi Snooker2020,
Re pension deficits, I tend to look at 2 things, to determine if a pension scheme is a big problem or not;
1) Size of actuarial deficit "D" (i..e not the usually much lower accounting deficit) relative to the market cap "MC" of the company.
As a rough, guess, if D/MC is less than 20%, then I probably wouldn't worry too much.
If D/MC is say 20-50%, then I'd be making a significant reduction to the valuation of the share - i.e. I would want the PER to be say 10 instead of 15.
If D/MC is above 100%, then I'd probably steer clear altogether, or want a very low, single digit PER.
2) Cash outflows - I find out from the cashflow statement what the company is paying each year in deficit recovery payments.
Then I compare this with its profitability.
E.g. if it's paying £15m p.a. in deficit recovery payments, and profit before tax is £40m, then that means about 38% of profits are disappearing into the pension scheme.
Therefore I would reduce the PER I'm prepared to pay by a similar percentage. i.e. if I think normally this share would be worth a PER of 20, then I reduce that by 38% to a PER of 12.4. If the shares is at that PER, or cheaper, then I would consider a purchase.
The above are not hard & fast rules, it's just what I do roughly in my head when looking at pension schemes.
At the moment, I'm generally avoiding all shares with a significant pension scheme deficit, because long-term interest rates could come even lower, hence these deficits could get much bigger, and stick around for 20-30 years. That's very unattractive, as it could make dividends difficult to pay, and justifies a large reduction in the valuation of the company. This is why Norcros (LON:NXR) always looks so cheap for example.
I think investors are generally being too blase about pension deficits, and not discounting valuations enough, that's why I think it's safest to avoid companies with deficits. It just brings in too large an uncertainty, as the deficits can swing very wildly - e.g. recent figures from De La Rue (LON:DLAR) showed pension deficit grew by a very large amount in the 4 months to 30 April 2020.
Hope that gives you some ideas!
Regards, Paul.
The 3rd thing to look at is the actual size of the pension scheme relative to the size of the company and the deficit. A deficit of £50m with £5m pa cash payments is much more predicatable into the future on a scheme with assets of say £300m and liabilities of £350m than it would be on a scheme with say assets of £1bn and liabilities of £1.05bn.
A really big scheme relative to the size of the company could be considered suspect even if it showed a small surplus at the last valuation.
Pensions
Generally I probably fit into the category of investors who Paul regards as too blase on the subject. That might be fair, although I would defend myself by saying that I am assessing the risks appropriate to my risk tolerance. I do accept Paul's basic premise however.
If anyone is interested in learning more though; I could suggest 600 (LON:SIXH) as a fantastic case study. They had a huge and growing pensions surplus on an accounting basis. On an actuarial basis the position had been steadily improving and had (if memory serves correctly) moved into surplus on this measure.
However, (because they were seriously strapped for cash, having already sold Grandma) the eventually sold out the scheme on a 'buyout valuation' that gave them fractions of pennies in the pound on the actual surplus.
Personally I am selectively bullish on companies with pension deficits (By way of full disclosure - I should admit that I have been 'wrong' on this point for over a decade!)
It is (in my view) a risk factor, some companies will be smothered by their legacy pension liabilities, others I believe are unduly beaten up on the subject.
I cannot immediately find my notes on 600 (LON:SIXH) , but if I come across them I will share.
Tremor (LON:TRMR) - was known as Taptica. Being a foreign company listed on AIM I have steered clear of this.
That's a bit simplistic - £TRMR is an amalgamation of Taptica, RhythmOne and Unruly : all pretty large brands in their own right and delivered Tremor International (LON:TRMR) a horizontal strategy which is key to current commercial success in my view.
Whilst it certainly came out of an Israeli tech and I think is still HQ'd there it is really run out of the US now. The CEO is there. Frankly, it should probably re-headquarter and list in the US if they want to create extra value.
Wow, you don't realize how much you have come to rely on something until it is taken away. Really missed Stocko and SCVR this morning - the service you offer here is first class. First time I've experienced it dropping out so no complaint from me - everyone gets one lol.
It has not been first class at all.
There have been issues for a month or two, including time lags on both systems and a few outages.
However Stockopedia has helped add to my personal wealth this year - considerably.
For that, Stocko, and Mr Scott and Co., gets my sincere gratitude and lattitude.
Completely agree with PS on Tungsten (LON:TUNG)
I was a holder late 2014- early19.
PS advised (I think) to get out at about 160-180. I thought I knew better and eventually exited at ~50-60
Even now I look at the excellent client list and think "there must be money in there somewhere"
I know enough to know that TUNG used to be called OB10 (I think) and it has _never_ made real money
It was my most expensive lesson. That lesson being FCF must be > 0 and forecast to be so for the future
This filters out most of the jam tomorrow stories.
I don't think you meant to use the word 'advised' in your second para.
Thanks Housemartin2! :-)
My morning smallcap tweet:
Tremor International (LON:TRMR) WH Ireland (LON:WHI) Urban Exposure (LON:UEX) Gore Street Energy Storage Fund (LON:GSF) STM (LON:STM) ULS Technology (LON:ULS) Location Sciences (LON:LSAI) Symphony Environmental Technologies (LON:SYM) Sealand Capital Galaxy (LON:SCGL) Keystone Law (LON:KEYS) WANdisco (LON:WAND) Panoply Holdings (LON:TPX) Accsys Technologies (LON:AXS), Curtis Banks (LON:CBP), Omega Diagnostics (LON:ODX)
Tremor (TRMR) guides FY(Dec) rev $390-400m, net rev* $171-175m and adj EBITDA $50-52m. Prev guidance: rev $340-360m, adj EBITDA $30m-36m. Co believes current growth trend is set to continue. [SP=295 Cap=388m]
W.H. Ireland (WHI) conditional acquisition of Harpsden Wealth Management for £5.3m + £2.5m contingent. £5.3m placing at 40p, a 3.6% discount. [SP=42 Cap=20m]
Urban Exposure (UEX) tender offer terms. Up to 55% of shares at 75p. [SP=71.9 Cap=114m]
Gore Street Energy Storage Fund (GSF) £60m olacing at 100p, an 8% discount. Then a programme of subsequent issues of up to 250m shares. [SP=107.69 Cap=90m]
STM (STM) FY(Dec) in line. Will adopt a more prudent methodology to its guidance for FY21. Cites covid, very low interest rates, Brexit and uncertainty in the financial markets. "This revised approach primarily affects the level of new business for our life assurance and SIPP products." Guides rev up 7% but better EBITDA margins. [SP=32.25 Cap=19m]
ULS Technology (ULS) £27.3m sale of Conveyancing Alliance. Will repay debt and leave £25m of pro forma cash. "ollowing the sale of CAL, and taking into account the current level of investment in Digital Move, the Group remains profitable at the EBITDA level." [SP=75.8 Cap=49m]
Location Sciences (LSAI) wins second client for GeoProtect (Verify Audience) platform. However expected pick up in Verify revenues in Q4 hasn't happened. Partly offset by other wins. Has cash until 2022. [SP=0.52 Cap=3m]
Symphony Environmental Technology (SYM) further successful test reports on its anti-viral nitrile gloves and polypropylene fabric facemasks, made with co's d2pAM (antimicrobial) technology. "The masks are already available in commercial volumes and, subject to securing manufacturing space, we hope to be able to supply the gloves during the second quarter of 2021." [SP=23.4 Cap=39m]
Sealand Capital Galaxy (SCGL) extension to the contract with Suncity Group Leisure Services. Extra $67k rev. [SP=1.33 Cap=7m]
Keystone Law (KEYS) guides FY profit comfortably ahead of market expectation of £4.6m. [SP=499.98 Cap=156m]
WANdisco (WAND) $3m initial Azure contract with major US Telecom co. [SP=465 Cap=244m]
Panoply (TPX) H1(Sep) rev up 58%, adj EPS doubled. "We remain on track to achieve our commercial vision of both £100m revenue and £12 -14m adjusted EBITDA, on a run rate basis, by 31 March 2023." [SP=190.6 Cap=130m]
Accsys Technologies (AXS) H1(Sep) rev down 3%, U/L pretax -€0.1m (-€2.2m). On track to deliver our '5x' production capacity growth target by 2025, [SP=112.25 Cap=184m]
In line: Curtis Banks (LON:CBP) Omega Diagnostics (LON:ODX)
We will make it up to you all at Mello this evening.....
https://melloevents.com/mellomonday-30th-november/
What you have missed at the start of your day we will deliver up at the end of the day
Five top draw panelists on the BASH panel
Four companies assessed
three company presentations
two Investor QQ interviews
and a fund manager interviewed in depth
What more could you want
Tickets half price with the code MMStocko21
Very sorry about the outage this morning. We had some database replication issues which were a real nuisance.
Just to be absolutely 100% clear about this - these problems are due to our legacy software stack that we're engineering away. We're at the end of a 3 month project to move absolutely all of our tech stack onto the Amazon AWS Cloud. I'm hopeful that will be complete within a couple of weeks. After that, these reliability issues should be far, far more rare.
As has been seen with Twitter "fail whales" and so on in the past, when a service is growing there can be quite a lot of flux in coping with the demands. We are investing heavily in the service and the engineering stack.
So please bear with us - these are growing pains rather than terminal issues!
Please feel free to not answer as it is nothing to do with shares
But
Why AWS?
Just being nosy, my $employer is using MS Azure and a major client has just implemented our product on AWS. I am more involved in the client facing end and have no idea who the people who evaluate/ mandate these things are.
Thank you for the update. The Stockopedia product roadmap page states that both the "referral program" (!) and "improved table usability" are in development and "folio performance reporting" is coming next.
Data migration isn't mentioned in the roadmap. Mindful of its critical nature shouldn't the roadmap page need updating to include this to reassure subscribers?
AWS had a major outage on Wednesday! Outsourcing puts your business in someone else’s hands. I doubt AWS guarantees compensation for consequential damage.
AWS
With the same high standards and care of its couriers (kicking parcels into wheelie bins).
And Microsoft: The company of who's world leading Operating System will reboot itself or spend hours doing upgrades of its own volition in the middle of your working day, taking away what ever work the owner user is doing.
And Google: The Media company that will suddenly mute a sound track of someone's upload without notice or redress.
And Apple: Who actively sabotage the performance of end users' hardware over-the-air.
Thank God these muppets aren't allowed to make Life Support machines.
It does put it in someone else's hands, but then your IT is always in someone else's hands, even if they are your own employees. However, the big cloud providers tend to be better at running infrastructure than most companies are at managing their own.
I could never sleep at night knowing someone could just DELETE my business.
If Microsoft et al picked up the phone when you called them with a problem THEN perhaps I'd trust them.
Only this month, one cloud provider decided I couldn't renew the SSL certificate we buy off them for a leading web server platform.
Repeated calls to ask them to call us to talk it through...
No response...
Result... pulled their contract... (no follow up from them why we've taken away our business)... moved to another provider.
Its shitty piss poor ways of doing business, and I'm sticking to my old school ways.
+1
Something that is little understood. We all stand on the shoulders(?) of other standardised components.
I came across the story of someone who tried (plotspoiler- failed) to make a toaster from scratch.
Thomas Thwaites - Wikipedia
he also has a TED talk on it.
Elon Musk seems to talk-the-talk - know every part of his rocket business.
Personally, I know everything from crimping an ethernet cable to the SSL/TLS code at the other end several thousand KMs away, and some of every bit of code and software in between.
It would strike me dead with fear to trust this to people I don't know and haven't met, even more so knowing that they might be rivals, foreign operators, or potentially hostile parties in the future.
Anyway, good luck.
Hahaha. Funniest thing I read all day.
I look forward to reading how you set up a several thousand km long proprietary data transfer solution. How did you do it, did you launch your own satellite or go the deep sea cable route?
Glad you are amused.
Try a TraceRoute Mr IGotPoesJacket .
It will explain to you all the different parties involved.
Err, no it won't. But whatever lets you sleep at night.
I'm a business owner higher-risk Investor... I sleep with one eye open and screen by the bed. :-)
@Edward Croft, is this migration a mirror of on prem code/infra to the cloud or a re-architecture/rewrite - ie a move to micro services. A 3 month project makes this feel more like a lift and shift exercise?
Migrating to RDS (as an example) wont lessen the impact if RDS has a (rare) issue.
J*s*s C****t!!!
@Edward
Are those AWS servers specifically UK hosted, or EU hosted?
Is private data leaking out of The UK?
Can foreign Governments or other third parties get access to, or subpoena, Stockopedia users' Folios?
I think there maybe a few users who'd be most uncomfortable if they knew The US or French government or tax authorities could coerce data discovery, not to mention the feminist "family law" divorce lawyers. *
* I've been done, and don't intend to go around again.
Its unnerving knowing my data might now be in The US, Singapore, Germany and Japan simultaneously.
Don’t worry UK Investor, the Russians and Chinese have already hacked into your Folio, the other countries are a long way behind.
Don't say that. Not even joking.
I watch IP addresses and they are always running penetration attempts and sending weird web packets.
Do you have a hardware firewall?
Do we get free 'prime' with our subscription :)
Good result from VCP today as far advised I can tell, any thoughts on this?
where was everyone this morning?
Hi ambrosia, there's been a technical glitch with the servers unfortunately. It's coming back now. Profuse apologies.
Regards, Paul.
and I thought everyone had just drifted off listening to harp music
fantastic Paul! Thanks