Small Cap Value Report (Mon 30 Oct 2023) - SOLI, SPEC, NTBR, BVXP

Good morning, it's Paul & Graham here. Raring to go, especially as it's daylight again when getting up at 06:30 here in the UK, after the weekend's clock changes - thank goodness everything is updated automatically these days, as it always used to confuse the c*#p out of me in the old days! Disrupting all my pre-recorded video settings, getting up at the wrong time due to forgetting how to change the time on my clock/radio, etc. Although it never made any difference to cooking, as the oven permanently flashes 00:00 all year round.
Lots of profit warnings at the moment, let's see what further horrors this week holds. Or will we get the long-overdue bounce? Who knows.
Graham's YouTube link today (live at 11:30, a recording thereafter)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
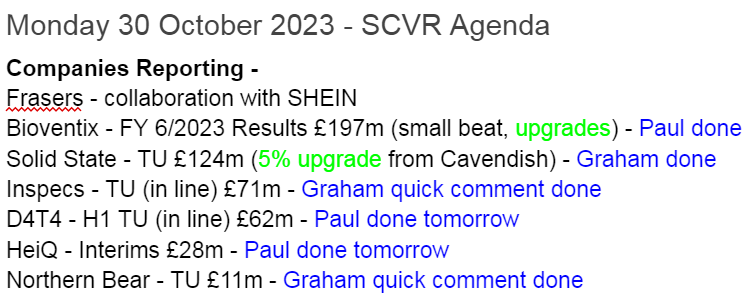
A nice manageable list today, and some decent companies here, so we'll aim to get at least the top 5 done by lunchtime -
Summaries
Solid State (LON:SOLI) - up 7% to 1168p (£132m) - Trading update (ahead) - Graham - GREEN
I’m taking a positive stance on this electronics manufacturer after another positive update. EPS momentum has been great here while the share price has drifted in recent years. Revenue growth is encouraging and debt is minimal. Worth investigating further in my view.
Bioventix (LON:BVXP) - Down 5% to 3,580p (at 11:38) £187m - FY 6/2023 Results - Paul - GREEN
Very impressive numbers. Ultra-high profit margins might eventually attract competition, but BVXP seems to have considerable moats.
Inspecs (LON:SPEC) - Up 7% to 74.6p (market cap £76m) - Q3 Trading Update - Graham - AMBER
Graham posts a quick comment below, on this in line update.
Northern Bear (LON:NTBR) - Unchanged at 56.6p (market cap £11m) - Graham - GREEN
Graham gives a quick comment below on this trading update. Looks cheap.
Paul’s Section:
Bioventix (LON:BVXP)
Down 5% to 3,580p (at 11:38) £187m - FY 6/2023 Results - Paul - GREEN
Bioventix plc (BVXP), a UK company specialising in the development and commercial supply of high-affinity monoclonal antibodies for applications in clinical diagnostics, announces its audited results for the year ended 30 June 2023.
I’ve followed this remarkable company since it listed on AIM in 2014. I have a feeling it was previously listed on a junior market. I can still remember a presentation at Mello when it moved to AIM, and thinking at the time what a remarkable company it was - with an extraordinarily high profit margin (currently 79% PBT margin), due to considerable moats around its products - which take years to develop, and rely on the knowhow of a small group of people working for BVXP, especially Peter Harrison (who has sold some over the years, and reduced now to 6.8%).
The Stockopedia graphs below tell me that the company is in a long-term growth trend still, makes astonishingly high profit margins (moat, pricing power), steamed through covid with barely a blip, enjoys a PER almost always above 20, and pays out almost all profits as dividends - hence little capital required, and plenty of cash generation. These 5 little graphs tell us almost everything we need to know, to determine whether something is worth doing more work on, I find. A great shortcut when looking at hundreds of companies, as we do here -
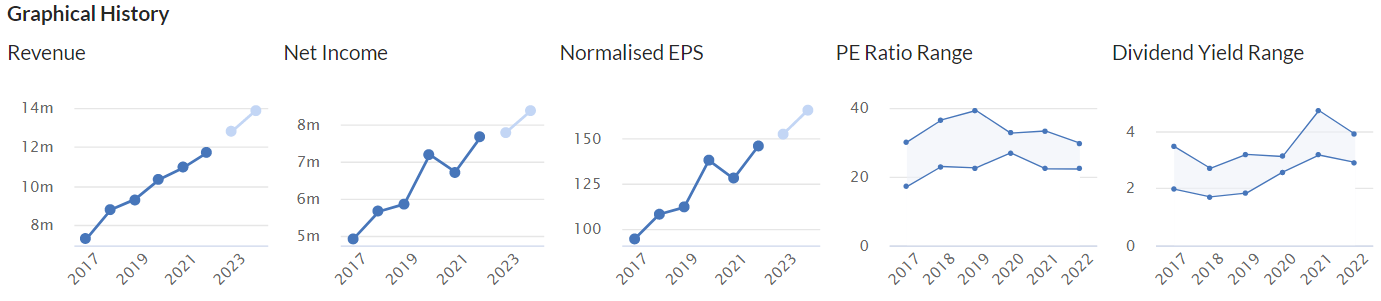
These are clean, unadjusted numbers, with no funnies in them.
Share options are notable for the lack of greed, £174k FY 6/2023, and £245k FY 6/2022. That’s only 1.7% of PBT for FY 6/2023.
Revenue up 9.4% to £12.8m
Gross margin a remarkable 93.5%
Admin costs very small at only £1.8m - demonstrating that this is a high IP company, operating with few staff, almost on a shoestring really.
PBT £10.1m, a remarkable 79% of revenues! Margins this high often attract competition, but so far anyway, BVXP’s moats seem reassuringly deep.
Diluted EPS is 158.3p (up 8.5%) - PER of 22.6x - at the bottom of the range of PERs that BVXP has generally been valued at (albeit that was during the zero-interest rates era, which fed higher valuations).
Balance sheet - is fine. There’s hardly anything in fixed assets, and I can’t see any capitalisation of development costs, which is nicely conservative.
Receivables are high at £5.8m, but I queried this in the past and am happy with the explanation - that large pharmas are the customers, and report usage stats in arrears to BVXP, so it bills customers several months after period ends. Hence revenues are booked in advance, and cash collected later. If this was a spivvy AIM stock, I’d be very sceptical of high receivables (often a precursor to serious problems). However in this case, BVXP’s track record reassures me that there’s nothing wrong in these numbers, it’s just how the business works, and the cash has always been collected in fine historically, and paid out in generous divis.
Very healthy £5.7m cash pile - more than enough, as the business doesn’t need any cash for anything - it’s just paid out as divis.
Cashflow statement - is gorgeous, and very simple.
A small positive change is the receipt of £101k interest received, compared with almost nothing throughout the zero interest era.
Negligible capex this year (£10.6k) and last year (£11.8k)
New shares issued £139k.
Slightly more than all the cashflow was paid out in divis (£8.4m FY 6/2023, and £7.9m FY 6/2022).
Outlook - this is such a specialised company, that I cannot add anything more than repeating what the company says, and refer you to the broker note (available on Research Tree) -
We are pleased with our financial results for the year which we believe reflect steady growth in the use of our established products and the continued roll-out of the high sensitivity troponin assays.
Excellent technical progress has been made with our research projects and we anticipate that our pipeline of opportunities will create additional shareholder value in the later 2020s and 2030s and we look forward to further progress in the years ahead.
This share has always been a long-term project, and it’s delivered tremendously well to date. Hence why I place a fair deal of reliance on its outlook comments.
I think people need expert knowledge to assess what its future pipeline might be worth, which I don’t have. Or, just trust management.
Forecasts - thanks to Cavendish, via Research Tree, for an update note.
It works on a (slightly) adjusted EPS of 161.6p for FY 6/2023, and has increased (by 2%) FY 6/2023 EPS to 168.4p, growth of 4.2% - although this modest growth is mainly due to absorbing a higher Corp Tax charge. Underlying growth of PBT is forecast at +10.7%
Then 181.5p EPS for FY 6/2025 - a forward PER of 19.7x - fairly expensive for an ordinary company, but this is not an ordinary company.
Paul’s opinion - the main risk I see here is not valuation (which is nearly always at the top end of reasonable), it’s that some unforeseen competitive threat emerges. Bulls point out that designing new products takes great expertise, years, and the volumes are relatively small so not likely to attract any major enterprises. Powerful arguments, but competition could come from some tiny startup that probably wouldn’t even be noticed by anyone until products were launched. Massive profit margins do attract interest in any sector. So that’s worth keeping in mind.
In all other respects, BVTX looks fantastic to me. It’s a buy and hold forever type of specialist company in my view, and you get a healthy dividend yield of almost 4.8% (after today’s 7% fall in share price) to enjoy whilst you wait.
The eventual outcome? Probably a sale of the business, I imagine. How long does key management want to keep running the company, I wonder?
Overall, I think this share appeals considerably, so I’ll go with GREEN (Graham was amber last time, but it’s fallen in share price a bit since then, and we’ve just had good results today, and a small broker upgrade).
Graham’s Section:
Solid State (LON:SOLI)
Share price: 11168p (+7%)
Market cap: £132m
Solid State plc (AIM: SOLI), the specialist value added component supplier and design-in manufacturer of computing, power, and communications products, announces a trading update for the six months ended 30 September 2023.
Some good news here for shareholders, although it’s unlikely to be life-changing good news: Solid State says that FY March 2024 is now expected to be “marginally ahead of current consensus revenue and adjusted PBT expectations”.
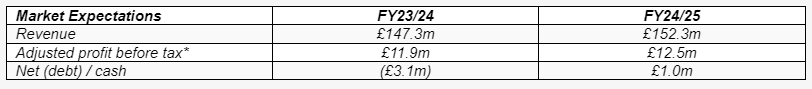
The company helpfully names the brokers whose forecasts it is using, and gives us a table of expectations:
Key points from today’s update:
H1 revenues up 48% to £88m, including acquisitions. Organic growth is 35%.
H1 adjusted PBT up 67% to £7m.
The company reports strong demand from security/defence clients, however:
…we are seeing clients move to more normalised levels of stocking because of improving component lead times combined with the higher interest rate environment, resulting in increased customer focus on managing working capital.
The order book has been a talking point here (see SCVR comments in April) as manufacturing supply chain issues saw orders backing up. This has cooled down now and the order book reduces to £99.7m (September 2022: £112m, and March 2023: £120m). It’s more like business as usual now, I think.
Solid State gives us one of the benefits of a smaller order book containing fewer long-term orders:
“the shorter lead times will enable more efficient conversion of the order book into billings”.
Estimates: with thanks to Research Tree, I can confirm the following changes to FY March 2024 forecasts at Cavendish.
Revenue +5.6% to £155.5m
Adjusted PBT +5% to £12.5m
Net debt is forecast to finish the year at £4m (it started the year at £8m)..
They make no changes to FY March 2025 forecasts.
Graham’s view
If you see my comments in April and in Dec 2022, I’ve generally been impressed by this company.
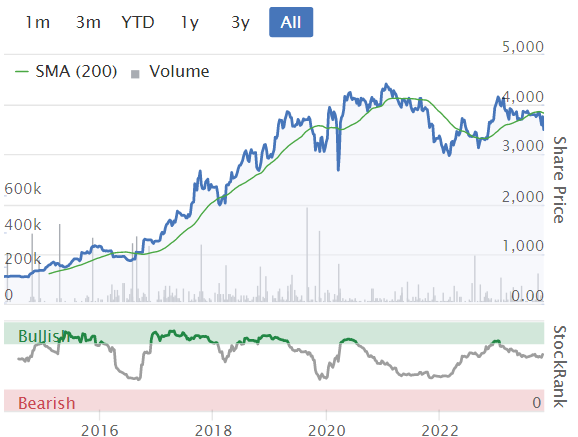
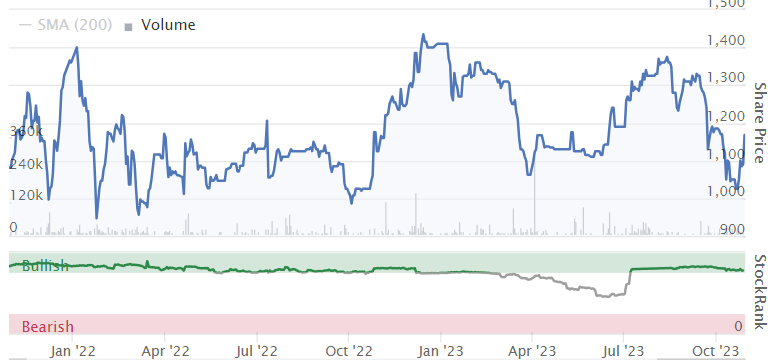
Even after this morning’s 7% rally, it’s still nestled firmly within the range of the past two years:
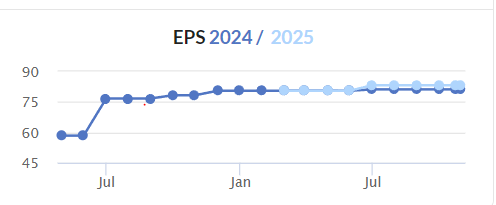
That’s despite positive earnings forecast momentum, with another upgrade today:
Given the very strong revenue growth figures and the improved balance sheet with debt and deferred consideration being paid, I’ll switch my stance on this from neutral to positive. At a PER of about 13x,I think it might offer enough value at this level to justify a second look.
Quick comments
Inspecs (LON:SPEC)
Up 7% to 74.6p (market cap £76m) - Graham - AMBER
Today’s Q3 update is in line with expectations. Year-to-date revenues are up 4.6% to £159m. At constant currencies, only up 2.4%.
Investors in this eyewear manufacturer can be encouraged that net debt (excluding leases) has fallen £6.4m year-to-date to £21m.
CEO comment -
"All of the Group's major markets are performing as we expected. Construction of our new manufacturing facility in Vietnam is progressing well with completion expected in H1 2024.”
Graham’s view - this one floated in 2020 and has been a difficult stock to hold through a serious profit warning, debt worries, and the loss of its original CEO. Recent interim results gave PBT of £4m on revenues of £111m. Production takes place primarily in China and Italy, with lens manufacturing also taking place in England and a new factory opening soon in Vietnam.
Unfortunately, the underlying quality of the business remains questionable in my view (what IP, if any, do they own?). It might be “cheap” at this level but I would continue to treat the shares cautiously given the mixed track record.
Northern Bear (LON:NTBR)
Unchanged at 56.6p (market cap £11m) - Graham - GREEN
The third trading update in seven weeks from this building services group. It appears to be in line, with a small increase in H1 of this year (period to September) compared to last year. H1 adjusted operating profit should be £1.7m to £1.8m, and today’s update includes a promise that adjusting items will be almost zero.
Outlook
The Group's forward order book remains strong and should support trading performance in the coming months, subject to ongoing uncertainties in the macro-economic climate in which the Group operates.
Graham’s view - the company is trying very hard to convince the market that its shares are underpriced, as the Chairman is currently looking to sell his 25% stake. For what it’s worth, I do think these shares are worth considering at a reasonably clean PER of about 4x and with a balance sheet that should hopefully still be ok after the planned £3m tender offer.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
BVXP: If you're wondering about the price drop today - we've picked up a shorter: Michael Taylor (shiftingshares). Very odd choice - yes BVXP is priced highly - but for very good reasons as Paul articulates. So, courtesy of Michael you may wish to pick up some more BVXP at a good price.
That in the knowledge - that at some point he's going to have to close his short ;-)
It’s not really such a crazy idea tbh. The one thing you know with BVXP is that there’s not going to be some rampy RNS appear out of the blue, plus you know that you’re likely front running the selling of the UK Buffetology fund which has the stated objective of reducing their more illiquid holdings.
Shorting BVXP on the chance that the Buffetology Fund is a forced seller into the now lower price? I think I can imagine higher probability trades.
Bioventix (LON:BVXP)
Thanks Graham (podcast) and Paul for your comments.
Despite being marked up at open as it came in a little above forecasts, at the time of writing it is 255p down. Is this just the market mood at the moment or is there something to worry about? As a long term holder (my largest holding until a month or so ago) I have been asking that question and think there are two things to watch -
a) competition from China - it pays to re-read the penultimate para under '2022/2023 Financial Results' that includes "We also recognise that continued antibody technology development in China and elsewhere constitutes a longer-term threat". Graham mentioned in his podcast how concrete-laying company Somero Enterprises (LON:SOM) was shafted by China. The only one I know that does well is Strix (LON:KETL) that whatever its (many) other faults can boast that it has been established in China for so long that it knows the right way to protect its patents.
b) the development pipeline's big hope is the tau antibody (for alzheimers). Until recently that may have been seen as the icing on the cake of growth. However it has become essential as we now know that the royalties on the present growth driver - troponin - will end in June 2032. The tau project has looked good so far but there are still hurdles to overcome.
BnB i think you are correct about Gore Street Energy Storage Fund (LON:GSF) .
I note the RNS from 3 October that Management and Staff of the Trust hold 4.456 million shares which suggests that they have a lot of confidence in the future.
Also HL quote discount is 43.66% so pretty spot on.
BnB i think you are correct about Gore Street Energy Storage Fund (LON:GSF) .
Well it hasn’t produced the usual ST 5-10% pop. Everyone else must have cancelled their Alpha subscriptions as well ;-)
I'm not a subscriber to IC Alpha but I see Simon T is recommending a renewables infrastructure investment company this morning. The double digit yield and 43% discount to NAV described in the teaser looks to me like Gore Street Energy Storage Fund (LON:GSF, which, coincidentally, I had been researching along with its obvious counterpart Gresham House Energy Storage Fund (LON:GRID this weekend. They are looking pretty interesting if interest rates have peaked.
Are there any Alpha subscribers here who would confirm or correct my hunch?
It's Triple Point Energy Transition (LON:TENT) .
It's Triple Point Energy Transition (LON:TENT) .
Very helpful, thanks. I don't know anything about the company but I can see that both daily liquidity and the dividend payout ratio fly a little too close to the wind for me. Also, their website says they invest "holistically" - and that's the real killer!
What is anyone thinking about Gore Street Energy Storage Fund (LON:GSF) and Gresham House Energy Storage Fund (LON:GRID) right now. Looking good or still too early to dive in?
Probably still too early, BnB. I thought I'd got in at the bottom when I bought at 70p after the 12 October RNS. How wrong can I be!! The market took against the last RNS (24 October) which announced the securing of project finance for their Big Rock, California project without announcing the interest rate being paid. A big omission which forced the market to draw its own conclusion. I would wait until the dust has settled before buying. Both this and NESF have proved disappointments for me so far. So much for investing in green energy infrastructure.
Very helpful thanks. It does look as though it will pay to wait for better funding conditions. Of course the other problem with pure energy storage plays is the enduring opacity of the revenue model.
How wrong could I be? Is today's strong rise signalling a change of direction or just a blip on the downward path?
Great opening paragraph, Paul.
In a similar but different vein to Mark Carter over the very wet weekend , and after a torrid 6 months in the Markets, I looked at 13 Holdings in my Portfolio which were under performing using the closing price on Friday 27 October and comparing it to the highest price since 28th April.
The average fall was a shocking 28.56%. The main culprits were RBG Holdings (LON:RBGP) GB (LON:GBG) Boohoo (LON:BOO) Entain (LON:ENT) and Saga (LON:SAGA)
2023 will go down in my memory as a very difficult year but I find Stockopedia gives me some encouragement that better days are ahead I hope!
I am quite surprised by the 15% drop in Altitude (LON:ALT) (I hold) this month, particularly following what I thought was another update reporting continuing strong growth and resultant increasing profitability since 2022.
Sanderson Design (LON:SDG) another licensing agreement. This time with Habitat at Sainsbury. Royalties to be shared with the National Trust. Not significant perhaps? But it all helps
Feels like its an existing range with National Trust, now bringing on a distribution partner in the form of Habitat?
So not quite sure how much more incremental in revenues this will be for Sanderson Design (LON:SDG) but it will hopefully be incremental, given Sainsburys have a much wider retail distribution than just National Trust.
No upfront licensing fee to book as revenue now, so we'll have to wait (until... 2025?) for revenues to flow through.
I personally don't think the Habitat brand is quite what it was - Sainsbury's seem to flog a lot of cheap furniture using that brand.
Ascential (LON:ASCL) is a significant holding for Odyssean Investment Trust (LON:OIT) one of the Harwood stable of investment trusts. Well done to managers Stuart Widdowson and Edward Wielechowski.
I hold Odyssean Investment Trust (LON:OIT)
Are Odyssean Investment Trust (LON:OIT) a Harwood investment trust? Looks to be Frostrup, or have I overlooked a connection?
Both Odyssean Investment Trust (LON:OIT) and Rockwood Strategic (LON:RKW) run by Richard Staveley have a close association with Christopher Mills and Harwood. Young Christopher holds above 28% of Rockwood Strategic (LON:RKW)
North Atlantic Smaller Companies Investment Trust (LON:NAS) of which Christopher Mills is CEO has a substantial holding in Odyssean Investment Trust (LON:OIT) .
From the North Atlantic Smaller Companies Investment Trust (LON:NAS) interims:
top ten investments as at 31 July 2023
Fair
value
£'000
% of
net assets
Oryx International Growth Fund Limited*
UK Listed
81,494
12.2
US Treasury Bills
US Treasury Stock
80,612
12.1
Harwood Private Equity Fund V LP
UK Unquoted
49,015
7.4
Polar Capital Holdings plc
UK Quoted on AIM
33,950
5.1
Hargreaves Services Plc
UK Quoted on AIM
29,903
4.5
Ten Entertainment Group plc
UK Listed
29,500
4.4
EKF Diagnostics Holdings plc
UK Quoted on AIM
25,680
3.9
Odyssean Investment Trust Plc
UK Listed
25,440
3.8
Niox Group
UK Listed
25,350
3.8
MJ Gleeson Group plc
UK Listed
23,045
3.5
403,989
60.7
A YEAR OF QUALITY. Given the tedious time we've been having in the stock market lately, I thought it would be interesting to look back and see how the "quality shares" had fared over 1 year. I have defined them as those having a ROE of at least 12.5%, reasonable debt (interest cover of at least 5) and reasoable PE (none of the shares were purchased at silling PEs).
For comparison, the 1 yr performance of the ASX (All-Share) is +1.5% (yes, the index has actually risen over 1 year).
Meanwhile, the "quality" ones have had the following performance: BA 34.5%, BNZL 2.5%, CCC 31.4%, CWK 20.1%, DPLM 11.2%, HWDN 22.1%, IGG -21.7%, III 67.5%, MACF 6.3%, MGNS 18.7%, SLP -22.6%, SRP -13.5%, ULVR -1.1%
That's an average of 12.0%. I haven't weighted by portfolio value. I have just taken an equal weighting. My 5 biggest holdings in the above are III, BA, FPLM, CWK, CCC (in descending weight). So my performance would have been better in practise. I have still suffered a lot over the past few years, so this is likely to have afair bit of luck to it.
I don't really consider SLP or SRP to be quality shares (SLP is a cyclical, so can't really be classed as "quality"). The mean would be 17.4% if they're excluded.
There's a few surprises, like DPLM being up a lot despite having a punchy PE rating. It won't come as a surprise to discover that BA is up a lot. What did surprise me is IGG, that has taken a right bashing. hwdn might also come as a surprise given that it is a kitchen and joinery supplier. Earnings estimates have been coming down on it, too.
OK, that was what you should have done, how about now? Value shares, as opposed to quality, are in the bargain bucket right now, so they could be make a fierce comeback relative to growth and quality. If the economy worsens, though, then there could be more pain ahead for the cheap-as-chips companies.
The quality companies aren't on absurdly high valuations, so there's still room for them to run. BA, for example, is on a (fwd) PE of 16.3. Not cheap, but not much more expensive than long-term stock market averages. ULVR is on a PE of 16. Again, not "cheap", but its historical rating has usually been higher, at around 18. BMY is on a PE of 12 (it has a Q score of 99, although its ROE is below 12.5%), MACF is on 8, which are undemanding multiples for good-quality companies.
A couple of large caps that I don't own but caught my are EXPN, on a PE of 19. Hardly cheap, but it usually trades on multiples of at least that. DGE is on 17.8 which, again, usually trades higher than that. Perhaps they're nothing to get too excited about, but you will probably beat the Footsie over 10 years. None of this constitutes a recommendation, you understand.
So, a little food for thought for today.
Thanks for sharing this interesting insight Mark.
Thanks. I was playing around with the "Dividend growth streak" filter on Stocko earlier. Dividend "achievers" are those that have increased their divs 10 years ina row. I read earlier that Dividend "aristocrats" (those that had achieved 25+ years of divvie growth) beat the market by about 2%pa. I'd hope to do better than that.
Perhaps look for a Q score of at least 80, high interest cover, and a ROE of at least 12.5% average over 5 years. You know you should be getting some really high quality shares that have withstood a lot of vicissitudes. I think being an Achiever might be too strict, though. There are plenty of really good companies that have either stalled or reduced their dividend in some year (e.g. GRG) only to reinstate it at a much higher level.
So the Achievers might make a good starting point. Of the shares I own, WYN, CWK, DPLM, BNZL, BA are on the list.
If you have trust in the Quality StockRank on Stocko, this is the easier way to see the performance YTD against benchmark... clearly not very good...!
Yep - high Quality Stocks got highly overvalued before the bear started. Valuation compression has been the driver of the weak returns. P/E multiples tend to come back to earth. Best time to buy quality is in a bear market, then you can benefit from the P/E multiple expansion as things recover.
Strix Group (LON:KETL) new note out after Friday's news of lenders to Strix agreeing to temporarily ease its key banking covenant, plus CFO announces retirement. Our forecasts are unchanged, but fair value adjusts to 167p per share. Read / hear summary of new note here: https://www.equitydevelopment....
Bioventix (LON:BVXP) results out. 1 or 2% above forecast and Cavendish raises forecasts for 24 by 2% with TP 4400.
Growth in key troponin test revenue was 11% after being flat in H1.
Solid as a rock with a "moat" that I think even Warren Buffett would be proud of - the barriers to entrance are huge and this is priceless in today,s market .
Price is down a little at the opening, which actually suits me. I only have a tiny holding, but I'm looking t increase in ISA season.
Whenever I read about Bioventix I can’t help but think about the (in)famous quote from Sun Microsystems CEO following the first tech boom:
“…2 years ago we were selling at 10 times revenues when we were at $64. At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at $64? Do you realize how ridiculous those basic assumptions are? You don’t need any transparency. You don’t need any footnotes. What were you thinking?”
Bioventix trades at 15x Revenues and on a 5% OpFCF yield and a 4% Dividend Yield. I don’t disagree that it’s a remarkable company. But I do wonder if this represents attractive value in today’s high interest environment. Revenue has grown by a nominal £2m in 2 years. In a £200m mkt cap company. Stating the obvious but if margins were to falter just a little bit this valuation would be decimated. Just throwing it out there for debate. Have no position long or short. Would love to understand more how long term holders see this one playing out in the mid term. And I know the company has a lot of hardcore fans
Bioventix (LON:BVXP)
Bioventix trades at 15x Revenues and on a 5% OpFCF yield and a 4% Dividend Yield. I don’t disagree that it’s a remarkable company. But I do wonder if this represents attractive value in today’s high interest environment
You concentrate on the multiple of revenues but for a company with very high margins you should be expecting top pay top dollar and then some ref that metric - if the bottom line numbers stack up . 5% OpFCF doesnt sound extortionate to me if you take the view that the company has the "opportunity" to double or treble profits over the medium term (i have no idea if they do). I don't know what the prospects are but whilst not being cheap the expensive price to revenues metric seems to be pretty irrelevant if the metrics that matter ref opfcf yield and dividend yield are in alignment with similar growth companies. To me here price to revenues seems completely irrelevant for this company.
Ref margin issues that would be a concern - but is this generic concern , surely we could worry about margins for any company we invest in?
Bioventix (LON:BVXP)
Agree with rmillaree. Price to revenues is not significant as a valuation tool for this share. What I'd worry about is whether their second revenue stream has genuine potential to replace the first. From the report
"Over the next few years, the continued commercial development of the new troponin assays and their roll out by our customers will have the most significant influence on Bioventix sales."
Otherwise, it looks ex-growth and vulnerable to the continued progress in Chinese antibody development.
Bioventix (LON:BVXP)
They also said the following which aint exactly jam anytime soon kind of progress - i dont know anything about this company so aint gonna knock it though.
ref outlook
Excellent technical progress has been made with our research projects and we anticipate that our pipeline of opportunities will create additional shareholder value in the later 2020s and 2030s
I hear you all. A few counterpoints:
1. The reason why ev/sales is relevant is that it signals an anomaly. Sales multiples north of 10x are rare. Why? Because generally markets outside of natural monopolies have some competition and hence exceptional margins all the way down the p&l are rare. Super normal profits attract attention. And when you have shares on exceptional ratings the fall from any stumble can be brutal. Look what just happened to Rightmove on the mere hint of competition to its de facto monopoly. So I think people are missing the main point. To me the exceptional profitability is perversely a red flag. And that is before the next point
2. You have a rich valuation accompanied with only modest growth. 9% nominal growth in a world of high inflation is not exactly shooting the lights out. I think people misunderstand the attributes of an exceptional company. High margins / ROCE is not itself a panacea if you can’t reinvest the capital at comparable rates of return. Bioventix seems to have zero capex and divies out most of its cash flow, presumably because it can’t find a productive use for it. That’s not the hallmarks of an exceptional business. That’s a business that has found a tiny interesting / lucrative niche in a global pharma industry worth billions. If it can really conjure up significant new lines of revenue with no capex / cash flow then congrats. You have found the holy grail of investing. Most pharma companies seem to need to spend healthily just to stay in the race. Not Bioventix it seems. They have discovered alchemy. Sorry. Colour me sceptical. Because if they can’t achieve this miracle then all you have is a modeslty growing niche annuity stream whose exceptional margins are potentially at eventual risk of competition
It’s your money so I wish you all the best. As Paul says this probably gets snapped at some point. But there is a reason the share price has gone nowhere for a while. Until there is evidence of the ‘miracle’ there is no reason why it should. Best of luck. No doubt better to be in Bioventix than many of the dogs out there. Given the exceptional value on offer though in countless derated shares I just struggle to see this as an interesting trade at these levels. Didn’t mean to touch a nerve lol
Didn’t mean to touch a nerve lol
No nerve touched here, just that the Scott McNealy quote is amazingly stupid when you analyse it. Who enters any investment under the criteria he describes? But then he was renowned for having an oversized opinion of himself. I remember he spent most of his time slagging off Microsoft. Well, look where Microsoft is now, and then look where Sun Microsystems is..,
Whenever I read about Bioventix I can’t help but think about the (in)famous quote from Sun Microsystems CEO following the first tech boom:
“…2 years ago we were selling at 10 times revenues when we were at $64. At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at $64? Do you realize how ridiculous those basic assumptions are? You don’t need any transparency. You don’t need any footnotes. What were you thinking?”
All this tells me is that Scott McNealy is/was an idiot. Read it and think about it… what he’s saying makes no sense from an investment perspective. Who expects this kind of return based on the multiple of revenue you pay for an investment? No, this is actually Scott McNealy’s “Ratner moment” -when it became clear he didn’t have a clue. A big warning to all Sun Microsystems shareholders at the time. And he’s only famous nowadays for staying as CEO for so long whilst overseeing the long terminal decline of a once pre-eminent computer company. Since he left Sun he has done absolutely nothing of note because he lucked out at the end of last millennium meeting the two brilliant engineers that developed the Sun workstation. Steve Jobs he is not!
This is all besides the point anyway, because comparing Sun Microsystems to Bioventix is so ludicrous. Many of the points he made are not true of Bioventix i.e. they only have a dozen employees and DO have no cost of sales or Capex to all intents and purposes. And as others have pointed out using Price-to-Sales as a valuation metric should be reserved for VC’s to justify the price of unprofitable companies only.
Graham, you've shown interest in Lok'n Store (LON:LOK) several times. Would be interested in your thoughts on today's final results especially as the price is still hovering around what you believed was a more reasonable NAV when you last wrote about it.
My morning smallcap tweet: Laughing stocks
RBG Holdings (LON:RBGP) Starcrest Education The Belt & Road (LON:OBOR) Powerhouse Energy (LON:PHE) Pineapple Power (LON:PNPL) Versarien (LON:VRS) Guild Esports (LON:GILD) Electric Guitar (LON:ELEG) RC365 Holding (LON:RCGH) Northern Bear (LON:NTBR) Batm Advanced Communications (LON:BVC) Infrastructure India (LON:IIP) Frasers (LON:FRAS) Solid State (LON:SOLI) Tissue Regenix (LON:TRX) Avation (LON:AVAP) Quantum Blockchain Technologies (LON:QBT) Heiq (LON:HEIQ), D4t4 Solutions (LON:D4T4), Inspecs (LON:SPEC)
◄RBG Holdings (RBGP)► settles £1.2m claim for comp for being sacked from its former CEO. Co pays £200k comp + obscene £300k legal costs. RBG has withdrawn the allegations of breach of fiduciary duty. [SP=20.84 Cap=20m]
◄Starcrest Education (OBOR)► cancels acquisition of Fairview IB World Schools. [SP=0 Cap=11m]
◄Powerhouse Energy (PHE)► further progress towards JV with Hydrogen Utopia. Co "has a number of potential projects in its pipeline and needs to prioritise amongst them and assess the impact each of those will have on the Company's existing cash resources". [SP=0.38 Cap=16m]
◄Pineapple Power (PNPL)► terminates proposed RTO of Element 2, Co actively considering another RTO opportunity in the renewables sector sp shares remain suspended. [SP=2.74 Cap=2m]
◄Versarien (VRS)► GM stmt - "turnaround continues to progress in line with its stated strategy". IP and plant bought from Hanwha Aerospace in 2020 continue to be marketed for sale. Applying for grants. [SP=0.7 Cap=2m]
◄Guild Esports (GILD)► £1m (max) subscription by strategic investor (an international esports, content creation and media brand) at 0.5p, a 10% premium, "to implement Guild's strategic drive for its brand and services more deeply into the industry eco-system as well as to facilitate international expansion". [SP=0.46 Cap=3m]
◄Electric Guitar (ELEG)► £250k loan 6 mth loan to be repaid mostly in shares. 10% fee + 10% fee on drawdowns! Down to £95k cash. Will be used to fund RTO of 3radical. [SP=2 Cap=1m]
◄RC365 (RCGH)► MoU with with Malasian co (Koperasi Usaha Maju Kuala Lumpur Berhad) to establish a collaborative platform for offering co-branded international and domestic fintech solutions. [SP=15.75 Cap=20m]
◄Northern Bear (NTBR)► guides H1-Sep op profit £1.7-1.8m (prior to amortisation and one-off costs), a significant improvement on the very strong prior period. Refers to Sept's in line RNS so suspect this is still in line. [SP=59.6 Cap=11m]
◄BATM Advanced Communications (BVC)► $3m cyber security order. Delivery of most of the order within six months. [SP=19.5 Cap=85m]
◄Infrastructure India (IIP)► extension to the maturity dates of all its debt facilities, but only to Dec. [SP=0.56 Cap=3m]
◄Frasers (FRAS)► sells IP of Missguided to SHEIN. FRAS will retain Missguided's real estate and employees. [SP=795 Cap=3605m]
◄Solid State (SOLI)► guides FY-Mar rev and adj pretax marginally ahead of forecasts. H1 rev-organic up 35% in constant currency. [SP=1090 Cap=123m]. I hold.
◄Tissue Regenix (TRX)► approval to set up a logistics hub in Ireland for the distribution of its allograft products in EU. Appoints distributor for allograft products in Spain. [SP=54 Cap=38m]
◄Avation (AVAP)► sells one ATR 72-500 aircraft to Nepal. [SP=122.5 Cap=87m]
◄Quantum Blockchain (QBT)► £2m placing at 1.5p, a 17% discount, for R&D, ongoing legal claims and working cap. [SP=1.83 Cap=21m]
◄Heiq (HEIQ)► FY-Dec22 at last. Also H1-June. Outlook - "expect the trading conditions for our commercialized product range to continue to be challenging into 2024, we have significantly reduced our cost base...re-assess strategy and resource allocation...we are seeing increasingly positive trends within our markets." Expects to get unsuspension. [SP=19.28 Cap=28m]
In line: D4T4, SPEC
The excellent news from Ascential (LON:ASCL) (I Hold) is more evidence of value in the UK market. This is despite a disclosed process that was in play. Business sales raises £1.2bn with £850m being returned to shareholders (current mkt cap £960m) and the balance paying down debt and used for taxes etc. The rump events business will have EBITDA of £85m (pre central costs) should be worth a £1bn (EV) alone.....
Thanks RDHOWARTH,
This does indeed look a remarkable deal at Ascential (LON:ASCL) - £850m return to shareholders, from a £960m mkt cap company is very striking, as you say.
We've never looked at ASCL here before, as its market cap was always just above our upper limit.
Looks like shareholders are in for an exciting day!
And as you correctly point out, this is more evidence of value in the UK market, where an imbalance of demand & supply for shares is causing widespread mis-pricings - which means exciting upside for those of us who have gritted our teeth and continued holding decent, undervalued companies in this 2 year UK small caps bear market.
Also, rich pickings for those clever enough to be holding cash, to deploy snapping up bargains before they're either bid for, or the market generally rebounds. I tend to find few people holding cash have the nerve to deploy it at the right time (when things are cheap), and often miss the best part of a recovery as they're anticipating another downturn which doesn't happen.
Regards, Paul.
I can imagine breakup being a lot more fashionable as management teams get more aggressive to "out" perceived value...and improve performance. This could be a significant differentiator between then UK and the US for obvious reasons. Admittedly less of a small cap thing and more a mid/large cap trend. Corporate brokers will be looking at this thinking who else has got something we can sell for the mkt cap ?
Great weekend podcast Paul - it’s early arrival very welcome.
“the oven permanently flashes 00:00 all year round” - ha ha, brilliant, pure gold!
Paul’s flashes of humour and exasperation provide welcome levity during the challenging times in the market endured by us all