Small Cap Value Report (Mon 30 Sept 2024) - LTG, HEAD, ITIM, DOCS, AMS, DUKE, SPSY, BGO

Good morning! Paul & Graham with you today.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
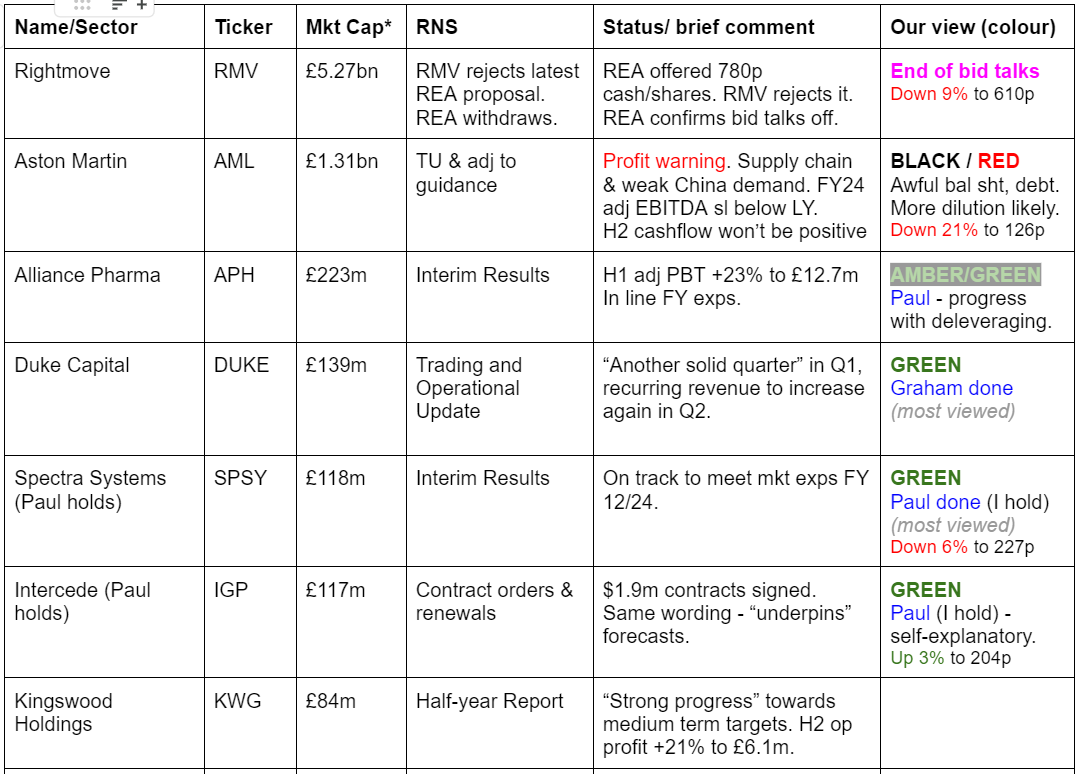
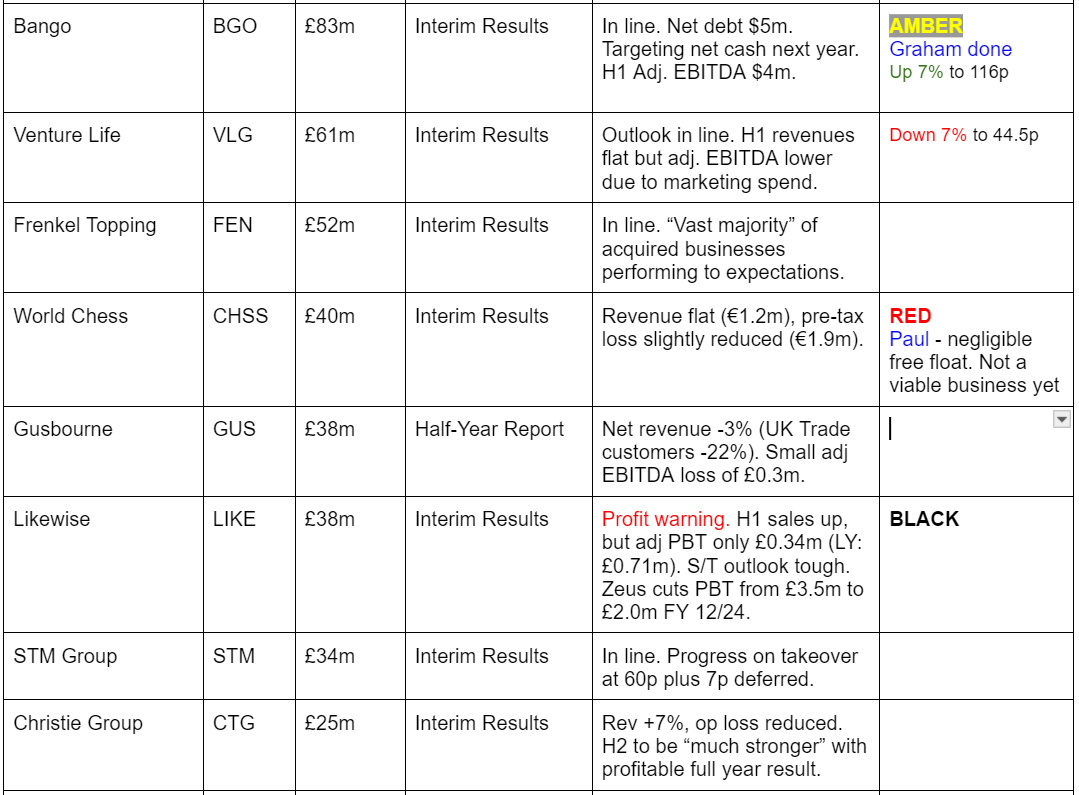
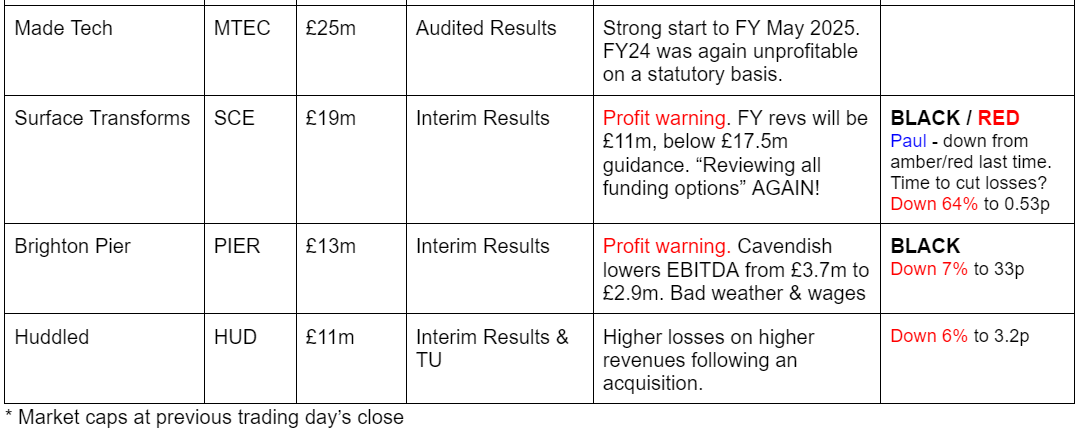
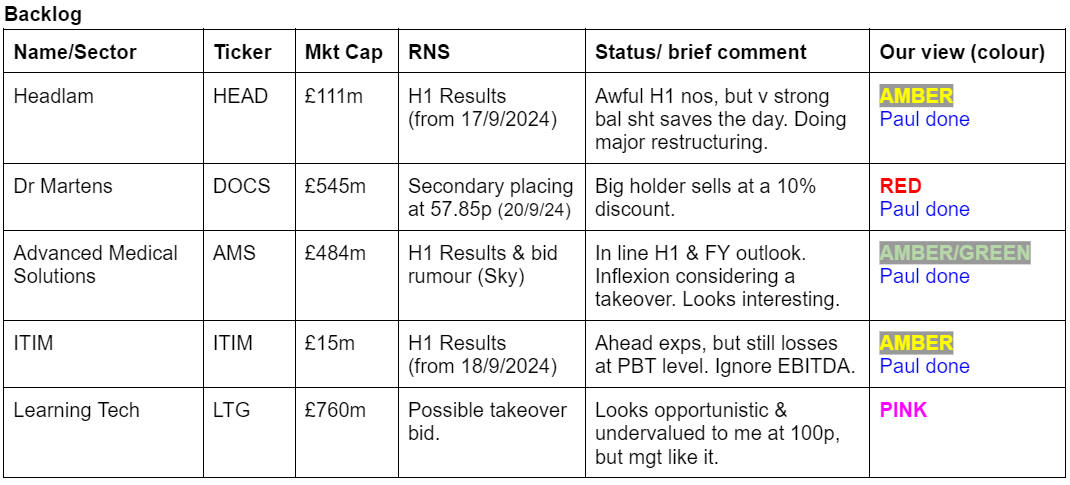
Summaries
Spectra Systems (LON:SPSY) (I hold) - down 2% to 235p (£115m) - Interim Results [in line] - Paul (I hold) - GREEN
A modest increase in H1 profit, and upbeat outlook says FY 12/2024 should be in line with expectations. FY 12/2025 should see profit double from a major contract kicking in. I'm happy with all the numbers, and think this is a very interesting growth company, still reasonably (modestly even) priced.
Learning Technologies (LON:LTG) - 95p (£760m) - Statement re possible offer - Paul - PINK
Announced late on Friday that it has received a 100p cash possible bid approach from General Atlantic, and mgt are minded to recommend it. Not a generous price at all, in my opinion, which makes me wonder what motivates mgt to want to do this deal?
Dr Martens (LON:DOCS) - 57p (£545m) - Secondary Placing - Paul - RED
A secondary placing on 20/9/2024 was done at a 10% discount. I re-assess whether bombed out shares are cheap, but conclude it's a mess with serious over-stocking, so I'm steering clear until that's resolved with a fire sale of product.
Advanced Medical Solutions (LON:AMS) - 223p (£484m) - H1 Results & takeover rumour - Paul - AMBER/GREEN
Another backlog item, which put out in line interims, and press reported rumours of a bid approach. It looks quite good to me, so worth a closer look.
ITIM (LON:ITIM) 47p (£15m) - Interim Results [ahead exps] 24/9/2024 - Paul - AMBER
Ahead of expectations update last week, but it's not very exciting when you dig into the detail, it's essentially trading around breakeven. There might be something interesting here, if the business can scale up.
Headlam (LON:HEAD) 141p (£114m) - H1 Results - Paul - AMBER
Awful H1 results, but it's got so much surplus freehold property that selling it more than pays for a major restructuring about 3x over. Can trading recover, or are the problems too deep-seated? I'm not sure either way, but the massive balance sheet NTAV gives it time to attempt a proper turnaround.
Duke Capital (LON:DUKE) - up 2% to 33.5p (£142m) - Trading and Operational Update - Graham - GREEN
A good update from Duke with steady recurring revenue that continues to grow at a modest pace with much of it sent out to shareholders in the form of a regular dividend (yield c. 8.5%). With the shares still trading at a discount to balance sheet equity, I can stay positive here although I will be quick to reduce my stance above c. 40p.
Bango (LON:BGO) - up 6% to 115p (£89m) - Interim Results - Graham - AMBER
Solid “in line” update. BGO remains loss-making but core products, customer wins and momentum are intriguing. Staying neutral on basis it has the potential to succeed and track record of managing its balance sheet is OK.
Paul's Section:
Spectra Systems (LON:SPSY) (I hold)
Down 2% to 235p (£115m) - Interim Results [in line] - Paul (I hold) - GREEN
Spectra Systems Corporation ("Spectra Systems" or the "Company"), a leader in machine-readable high speed banknote authentication, security printing, brand protection technologies and gaming security software, is pleased to announce its interim results for the six months ended 30 June 2024.
The acquisition of Cartor in Dec 2023 has kicked in for the full 6 months of the group H1 results to 30 June 2024, and it has changed the shape of SPSY’s group numbers by considerably raising revenues, but diluting profit margins. For reference, Cartor ‘s results for FY 9/2023, pre-acquisition by SPSY were: revenues £16.2m, EBITDA £2.53m, and PBT £436k.
Hence it looks like SPSY group (now including Cartor) H1 revenues of $22.7m are up 96%, but I reckon almost all the increase has probably come from Cartor’s c.$11m half year revenues (assuming revenues unchanged from its previous year, and adjusting sterling into SPSY’s reporting currency of US dollars).
Given that it’s a significant sized acquisition, it’s worth recapping on what Cartor does, and why SPSY acquired it. This was explained in this RNS from 4/12/2023. Cartor is a security printer, operating from factories in the UK & France, making postage stamps for over 180 administrations globally. It also makes high security tax stamps, vouchers, coupons & certificates. It has state of the art technology apparently. SPSY had already worked with Cartor for several years, and combining the two businesses looks set to produce good opportunities for both. So I like the look of this acquisition, although as mentioned it does dilute SPSY’s group numbers - much higher revenues, but not much change in profit, thus lowering SPSY’s quality measures somewhat. It also put SPSY’s cash pile to good use.
Back to SPSY’s H1 key numbers -
Revenue up 96% to $22.7m due to Cartor acquisition.
Operating profit up 16% to $6.2m
Note that having spent the cash pile on this acquisition, finance charges go from a net income ($172k H1 LY) to a charge of $308k H1 2024.
PBT up 7.5% to $5.89m
Adj EPS up 4% to 11.2 US cents = 8.36p, double it to annualise, is c.16.7p (PER 14.1x, hardly demanding for a growth company)
Note that the share count has been static at SPSY for years, at 49m, so it’s pleasantly averse to dilution, funding occasional acquisitions from internally generated cashflows. Note SPSY is quite a generous dividend payer for a growth company, yielding about 4.0% currently.
Forecast - Zeus gives a detailed update, very useful, thanks. This has revenue of $46m for FY 12/2024, and adj PBT at $12.0m - which looks credible since c.half is already in the bag from today’s H1 numbers.
Note the forecast for FY 12/2025 is more than doubling adj PBT to $25.4m, as a large & high margin sensors contract kicks in. So the results are likely to be spectacular in 2025, which seems to have largely been ignored by the market so far. Hence a nice catalyst here for a re-rating I suspect.
Adj EPS is forecast at 38.2 US cents next year, or 28.5 pence = 2025 PER of just 8.2x - although this earnings figure might not necessarily be repeatable.
Outlook - lots of interesting irons the fire, and management sound upbeat. They’ve delivered in the past, so I take this commentary seriously -
"The combination of the sensor contract award, the continued strong covert material sales, the boost in optical materials, and the significant advancements in our polymer substrate initiative including being asked to advise on a new series of polymer notes is all pointing towards an even more sustainable and growing profitability in the future. While all of this business growth is underway, we continue to be the most innovative company in the authentication sector with machine readable sustainable polymer substrate using circular certified polymer and new breakthroughs in smartphone technology which we are confident has the potential to reenergize this part of our product offering.
"The Board therefore believes that the Company is on track to achieve record earnings and meet market expectations for the full year."
Balance sheet - has changed shape, with the cash pile now mostly spent on the acquisition, and working capital build up for the large sensors contract underway. That should turn into cash (plus profits) in 2025, so there’s nothing of any concern to me.
Absorbing Cartor means fixed assets and goodwill have increased. Again, as expected, not a concern.
Debt of $4.8m was taken on as part of the Cartor acquisition.
Gross cash of $4.4m is slightly more than offset by Cartor’s debt of $4.8m. So it’s in a slight net debt position of $0.4m. That’s absolutely fine, given the strong profitability and cash generative nature of the business, and it’s large sensors contract underway that should provide a bonanza of cashflow in 2025. No concerns here from me.
Cashflow statement - the main feature is that operating cashflow has almost all been (temporarily) absorbed into working capital, due to inventory build-up for its large sensors contract. Note that the acquisition-related cashflows were recorded late in the 2023 financial year.
SPSY doesn’t seem to capitalise any development costs, which is nice prudent accounting. Yes, I’ve just confirmed that in the 2023 Annual Report -
“Internal research and development costs are expensed as incurred.”
[within note B, accounting policies).
The other big item is divis paid of $5.6m in H1, which is a single annual divi payment, there’s no interim divi.
Put all that together, and the cash pile has dropped from $16.6m in June 2023, to $4.4m June 2024. Expect this to rebuild in 2025.
Paul’s opinion (I hold) - this all looks fine to me, so I’m a happy holder.
I remain of the view this is an under-appreciated growth company, doing a lot of very clever stuff, and generating impressive contract wins, profits & cashflows. I suppose the main risk is possibly from large, lumpy contracts - there’s always a chance of the occasional fallow year.
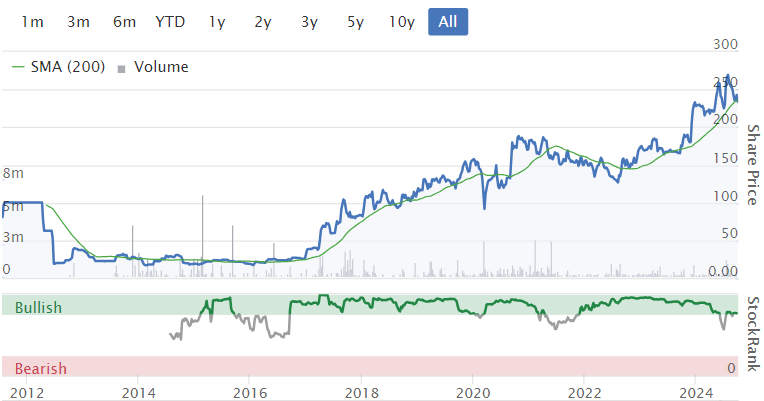
Things seemed to drop into place from 2017, and it hasn’t looked back since -
Learning Technologies (LON:LTG)
95p (£760m) - Statement re possible offer - Paul - PINK
This announcement slipped through the net at 4pm on Friday, giving LTG shares a boost.
LTG confirms it had a conditional approach from General Atlantic, a US investment firm focused on growth companies ($71bn AuM according to Google).
Possible all-cash offer at 100p. Alternative offer for equity in unlisted holding co, for LTG shareholders who don’t want to sell out.
Subject to due diligence & paperwork.
LTG Board say they’re minded to recommend the 100p offer, so is engaging with GA.
Paul’s view - it’s hardly generous, as LTG (with most of the bid premium now in the 95p share price) is only rated at a fwd PER of 12.7x
Although note that LTG broker forecasts have been in steady decline for some time. Guidance with H1 results (issued 17/9/2024) was FY 12/2024 results would be at the lower end of broker forecast range. Last balance sheet was adequate, NTAV slightly negative, but doesn’t matter as it’s a very cash generative business, making good margins, and with majority recurring or long-term contracted revenues.
Overall, I think they’re selling it too cheaply, and would be better off rejecting this bid. Maybe management might prefer the upside for themselves under P/E ownership?
Another quality UK business being taken out by Americans on the cheap?
Dr Martens (LON:DOCS)
57p (£545m) - Secondary Placing - Paul - RED
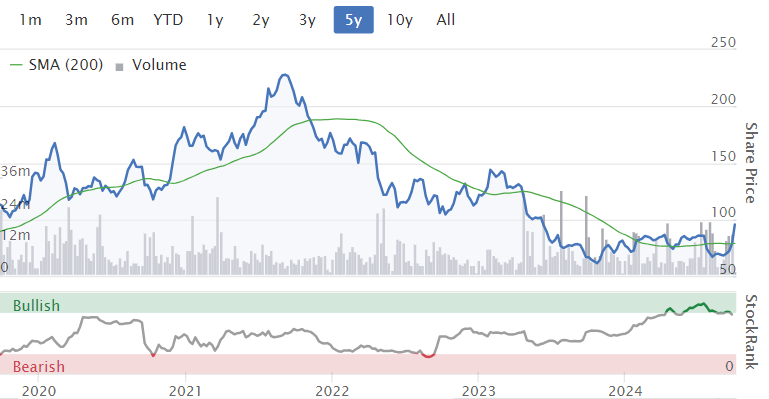
DOCS took a sharp fall from 65p to 52p on 20/9/2024 (since bounced a bit to 57p) on news that Goldman Sachs was dumping 70m shares (c.7.3% of the total) in a secondary placing on behalf of a client. It looks like Fidelity took most of them, but at a painful 10% discount.
We’re seeing quite a few secondary placings at the moment, where market liquidity is inadequate for a large holder to exit through normal trades, and buyers demand a hefty discount. Whilst these sound bad, sometimes they can be buying opportunities. A recent example of that was a sharply discounted secondary placing in TI Fluid Systems (LON:TIFS) which has since shot up about 50% due to a subsequent takeover approach.
Is DOCS a buying opportunity? I would say not. See my notes here on 30/5/2024 where I marked DOCS shares as RED at 89p, viewing it as a big mess, and looking set up for another profit warning in H2. The main problem is that the 31/3/2024 balance sheet shows huge inventories of £255m at cost (which compares with cost of sales for a whole year of £302m). So it has warehouses full of boots that it can’t sell. Hence the only solution has to be clearing them at discounted selling prices, which means future profits take a bath from low margin clearance sales. The brand is also likely to be damaged from having to take this overdue action. So expect more profit warnings from DOCS I think. Presumably the big seller was prepared to take a discounted profit for their shares because they’ve come to a similar conclusion?
At what point do DOCS shares become cheap? Difficult to say, it depends, but the current £545m market cap doesn’t look sensible to me, for a business that I think is in a big mess. It was another ludicrous, opportunistic & overpriced 2021 float, that has amazingly lost almost 90% of its peak 2021 valuation. I suspect divis are likely to be cancelled too, with bank debt reduction looking more important. Could get worse before it gets better, maybe. I’m generally of the view now that fashion sector risk isn’t worth taking - eg look at how volatile profit & share price has been at Burberry (LON:BRBY) (which I think is another awful share incidentally).
Advanced Medical Solutions (LON:AMS)
223p (£484m) - H1 Results & takeover rumour - Paul - AMBER/GREEN
H1 results were out on 18/9/2024 which we very briefly commented on, being in line H1, and in line FY outlook. It’s quite a nice company, which I last properly looked at on 10/1/2024, concluding AMBER/GREEN at 213p. At the time it said strong growth was lined up for 2024. AMS had a nice cash-rich balance sheet, although it looks as if that has now been spent on a “transformative” acquisition of Peters Surgical, which completed 1 day after the H1 period end, initially costing c.£110m. So it will now have net debt. The plot thickened on 17/9/2024, when (as always) Sky News revealed that Inflexion is considering a possible takeover bid for AMS, along with other private equity firms. Market excitement rapidly fizzled out, after a spike to 254p on 18/9/2024 disappeared and it ended last week at 223p/share.
Paul’s view - I think this looks a decent quality business, at a reasonable price (fwd PER of 18.2x), so I think it could be worth some closer investigation. There doesn’t seem to have been any comment from the company re the takeover rumours. It looks quite an interesting potential punt to me, so I’ll stick at AMBER/GREEN.
ITIM (LON:ITIM)
47p (£15m) - Interim Results [ahead exps] 24/9/2024 - Paul - AMBER
itim Group plc (AIM:ITIM) a SaaS based technology company that enables store based retailers to optimise their businesses to improve financial performance, is pleased to announce its unaudited interim results for the six months ended 30 June 2024.
Very small and illiquid, with 5 large shareholders holding about 75% of the shares, including the founder with 38%.
I’ve briefly commented on ITIM several times this year, AMBER each time. That’s because the newsflow on contracts (eg Quiz, Majestic Wine) has been good, but it remains loss-making after you reverse out the capitalised development spend, and I’m not keen on the balance sheet. Not a bad little business, but can it scale up?
H1 saw revenue up 19% to £8.8m, and ARR hit £13.2m. Not bad.
H1 adj EBITDA moved from a £(0.2)m loss last year, to £1.2m positive this time, but of course it’s a nonsense number due to capitalised development costs.
Real world PBT is c. breakeven, at £(73)k loss in H1 - much improved on the £(1,090)k loss in H1 LY.
So we have a small business, trading at breakeven - not every exciting really.
Balance sheet - nothing much, with £11.4m NAV being almost all intangible assets of £11.2m, so just £0.2m NTAV - that that should be OK for a small software company, since they get paid up-front usually. Cash looks fine at £3.0m.
Cashflow in H1 was good, mainly thanks to collecting in receivables well (a £1.4m cash boost). Note that £0.8m of intangibles were capitalised. Overall then, it’s operating around cashflow breakeven in the real world, the way I view the numbers.
Outlook - is positive -
"As a consequence of the positive momentum, including new contract wins, in addition to encouraging trading since the beginning of H2, the Board anticipates delivering full year results ahead of current market expectations."
Broker forecast - Zeus helps us out with revised numbers. I reject EBITDA for companies which capitalise internal costs, so it’s PBT only for me. This is still loss-making, but forecast improving from £(1.0)m to £(0.7)m for FY 12/2024.
Strangely, Zeus actually reduces FY 12/2025 forecast revenue from £19.0m to £18.0m, which seems odd, given talk of a strong pipeline. Profit forecast for 2025 is left unchanged at £0.4m adj PBT.
Paul’s opinion - I’m a little underwhelmed (why does nobody ever have the correct amount of “whelm”?!) by the detail, which doesn’t sound as exciting as the ahead of expectations headline. What we have here is a very small business (probably too small & illiquid to be listed), trading around breakeven in real world terms. Not very interesting. That said, there are some aspects of this share that get my antennae slightly moving, if not fully twitching. So I’d like to learn more about the company, and if it has the potential to properly scale up or not? There are so many small EPoS software companies, that often have loyal, locked in clients, but never really go anywhere. ITIM won an interesting contract in Brazil, which seems unusual for a small UK software company - what was that all about? Client concentration worries me a bit, as I think Quiz is in trouble, and I’m not sure about Majestic Wines. Might it de-list, if the costs & hassle of an AIM listing become a bore to management? It was I’m afraid another overpriced and opportunistic 2021 float.
I’ll keep an open mind on ITIM, much the same as the StockRank which has been creeping up from the red into the middle ground (currently 55). My view is not dissimilar - there could be something here, possibly, but only time will tell. What we really need to do, is talk to a big client that actually uses ITIM’s software & services, and ask them what they think. That’s true of all software companies - ignore everything the company itself says, and find out what the customers really think. I’ve heard (and experienced myself) some horror stories, where you’re locked into using some dreadful, but mission-critical software, where the listed company’s version of events in its RNSs bears no relation whatsoever to the customer experience. Hopefully that’s not the case at ITIM. How can we find out? Do any readers know anyone that uses this software? Retail isn’t a great sector either, so I’d be a bit worried about the potential for ITIM’s customers to go bust.
Headlam (LON:HEAD)
141p (£114m) - H1 Results - Paul - AMBER
Headlam Group plc (LSE: HEAD), the UK's leading floorcoverings distributor, today announces its results in respect of the first six months of the year to 30 June 2024 (the 'Period')...
Ambiguous wording there, which would have benefitted from adding a comma. What they mean is this is the first six months results of FY 12/2024.
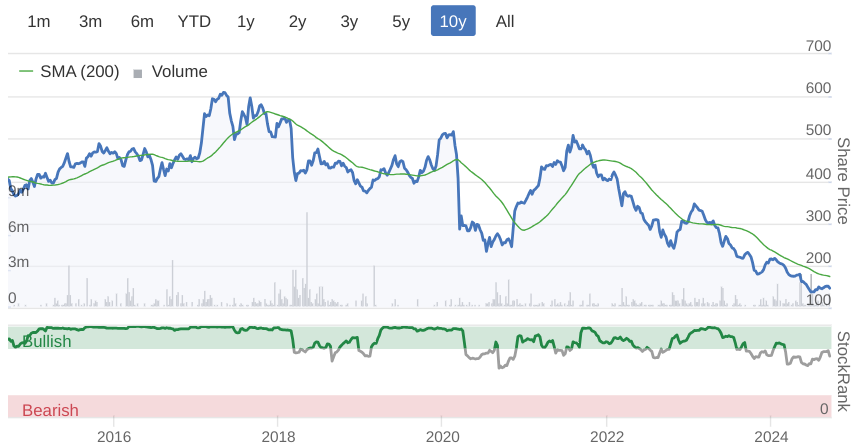
My view of HEAD was a good business, fairly reliably churning out c.40p EPS pre-pandemic, which was then obviously heavily disrupted in 2020 and 2021, but it got back to that level of earnings in 2022.
However, looking at the chart below, something’s clearly been going badly wrong since.
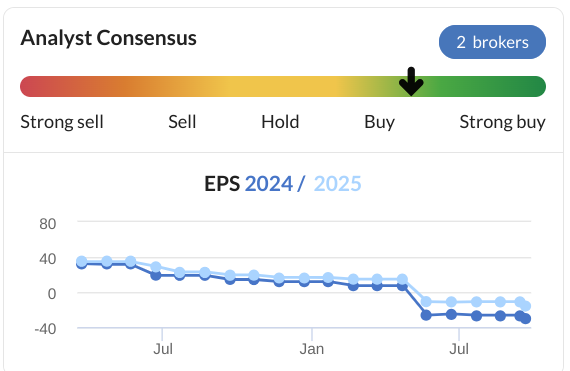
The deteriorating fundamentals are vividly depicted by the invaluable broker consensus graph below. As an aside, it’s interesting how brokers are sometimes reluctant to forecast losses. So when I see a downward direction in consensus forecasts, that flat-lines just above zero, it’s often best to assume that they’re desperately trying to remain positive, but the reality is that losses are actually becoming more likely. Then you often get a sudden lurch into forecast losses, as the restraining forces are snapped like old knicker elastic, probably.
H1 results to June 2024 are really bad - and remember these are the favourable, adjusted numbers too. Statutory PBT is £4m worse, due to £7.4m “non-underlying” costs (mainly restructuring), partially offset by a £3.2m profit on property disposal. Remember that HEAD has an unusually strong balance sheet, with loads of freehold property.
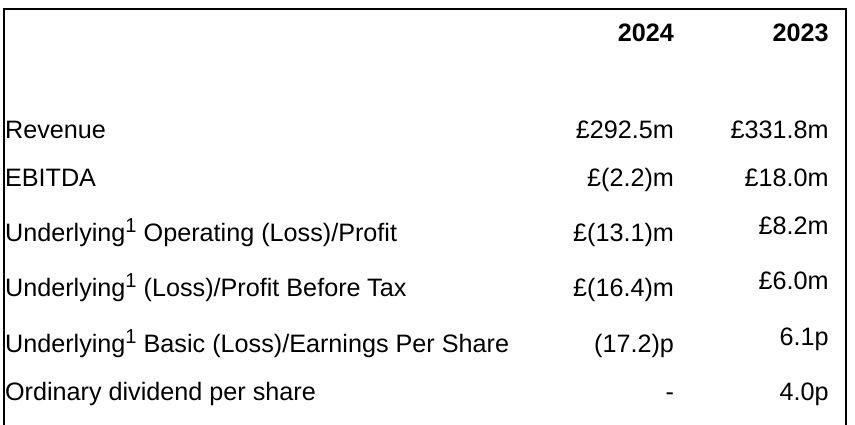
If H2 is equally bad, then we’re looking at a business making possibly £30m+ annual loss, which raises the question whether this is still a viable business, or is it doomed to go bust?
Also why has performance deteriorated this badly? Obviously subdued demand, but it’s being squeezed from all sides - revenue down 11.8%, but lower margin too, with gross profit down 14.3%. Then both distribution and administrative costs rose vs H1 LY. Hence why a £6.0m H1 profit last year became a £(16.4)m loss in H1 2024.
HEAD breezily comments -
“Results in line with expectations; acceleration of strategy through a two-year transformation plan”
It’s been restructuring for several years already, so it’s clearly not working so far.
Strategy -
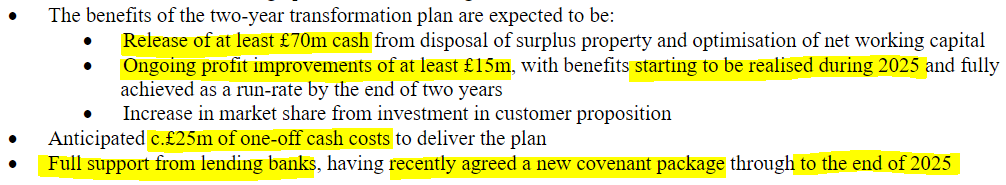
“launches the acceleration of its strategy through a transformation plan to simplify the business and enhance the customer offer, generating at least £15 million of annual profit improvement and £70 million of one-off cash benefits.”
That’s a strikingly large cash benefits (one-off) figure.
Balance sheet - this is not a reason to buy HEAD shares, but it does provide considerable downside protection, that the business should be able to trade through this downturn, without coming under dilution or insolvency pressure (probably, it depends how bad things get - even well-financed companies can be overwhelmed if trading is bad enough) -
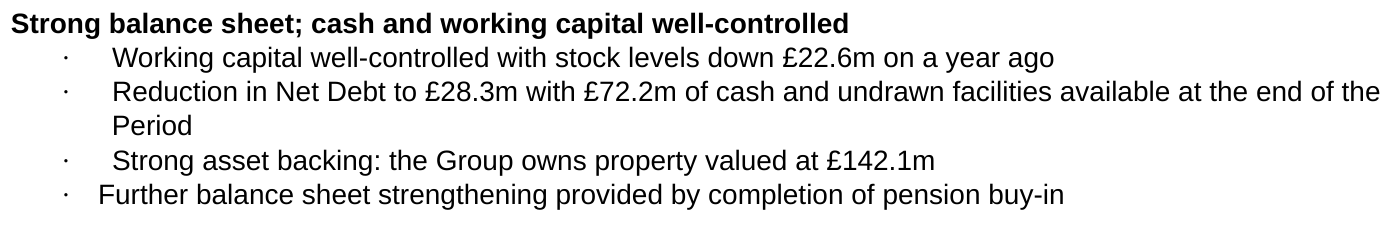
Pension scheme funding of £1m pa has now stopped, thanks to a deal with Aviva, which cost £1.1m (plus fees). That removes risk, so is good.
NAV is £200m, less intangibles of £19m, giving NTAV of a remarkably strong £181m. That’s much higher than the market cap of £114m. Although a cynic might say that all these assets are unproductive, since HEAD is now loss-making.
Net debt (excl leases) is modest at £28.3m, although covenants could now be a concern.
There’s plenty of liquidity, with £72m of cash & undrawn facilities (assuming facilities continue to be available).
Going concern statement is clean.
Restructuring - this strikes me as an extensive reorganisation of the business. Its current hotch-potch of 32 businesses (built through acquisitions) being consolidated into a single national business, called “Mercado” (strikes me as a dreary name, why choose that?! It means “market” in Spanish & Portuguese according to Google).
Broader, unified product list.
Reorganised sales teams.
Closing its big Ipswich distribution centre (freehold), which is to be sold.
Combining 2 Scottish warehouses into one (freeing up the other for sale).
Faster stock-turn, freeing up working capital.
Centralising back office & support.
Operational cost savings.
Restructurings normally consume cash, but in this case, the freehold property disposals pay for it almost 3-times over, which I find very encouraging, so insolvency/dilution risk should be minimal, assuming it’s able to sell its surplus properties as planned -
Property disposals -
“Headlam owns both the Ipswich and Uddingston properties, and both sites have recently been put on the market. We are actively engaging with buyers and offers are already being received. Collectively these properties were valued in January 2023 at £20.7 million.”
Property & bank debt - since they have security over freeholds, I’m not worried about the bank pulling the rug here -
“The Group continues to have strong asset backing; as at 30 June 2024, after the sale of the Stockport property in June 2024, the Group owned property with a market valuation of £142.1 million, and also had inventory and receivables of £124.9 million and £104.3 million respectively. The banks have a legal charge over six of the Group's properties, with a combined market valuation of £84.6 million; broadly equivalent to the size of the revolving credit facility.”
Longer-term outlook it still thinks is positive. It’s striking how much lower the market size is, so it does seem reasonable to assume that there could be a general market recovery as the housing market begins to pick up -
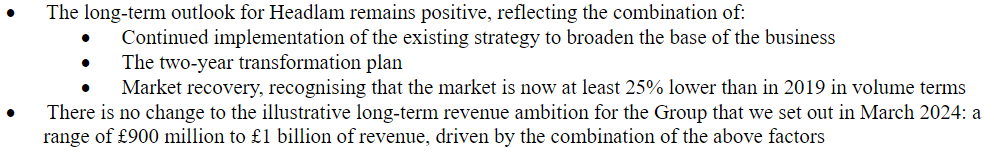
It seems to be the case that there was a surge of household improvements during the pandemic, as people spent surplus disposable income on making their homes nicer, during the enforced incarceration of lockdowns, and working from home. Home improvements have a long life, so it stands to reason that after the boom, there would be a lull. Although I don’t think anyone expected the lull to be this bad.
Market leader in furniture retail, DFS, mentioned last week that is was seeing “record low market demand”, on top of pressure from higher interest rates and Red Sea shipping delays. However, it also forecast a “gradual market recovery” in the pipeline. So perhaps investors should be positioning ourselves for that recovery, if we can find favourable risk:reward situations. DFS is so horribly over-geared that I can’t get comfortable with its diabolical balance sheet, but that might provide leveraged upside for punters who accept the financial risk (look at what happened with MCB when it pulled off a stunning turnaround, with the leveraged benefit flowing to equity holders). Could the same sort of thing happen here? DFS is the risky, geared option, whereas HEAD is effectively ungeared once you take into account its large freehold property assets & forthcoming disposals. So a bull case could be argued for either share, depending on how you see a recovery & the differing risk:reward.
Competition - HEAD says little about this, other than that it’s up against distributors lowering prices to protect market share. Up & coming competitor LIKE (TYO:2462) said on 19/6/2024 that sales are growing, and are expected to continue growing in the seasonally busier H2. So it’s obvious that HEAD is losing market share to LIKE. Although LIKE shares are also in the doldrums, because it’s only making a very modest profit margin, so seems to be chasing revenues for the sake of it - not an appealing business model from my point of view. I like businesses with at least some pricing power, or super-efficient operators, with both HEAD and LIKE seeming to be neither.
Outlook & current trading - very little to get excited about here, it sounds pretty gloomy to me -
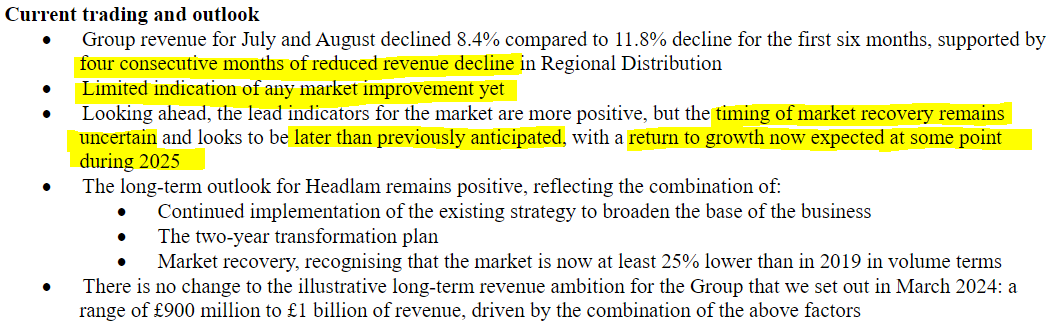
Paul’s opinion - such a tricky share to assess. H1 trading was a disaster, but it’s got a radical restructuring underway, which is fully funded from its own surplus capital, and a supportive bank that has the security of substantial freehold properties. So I don’t see risk of dilution or insolvency here. That buys it time to execute the turnaround.
There should be at least some recovery in demand, as the consumer begins to recover, and residential property markets improve. So this could be the low point in the cycle for earnings. However, I also think HEAD is probably facing much tougher competition now from growing competitor LIKE.
It all now hinges on how much upside can be squeezed out of the restructuring (turning 32 independent businesses into 1 sounds a huge task).
On balance I feel moderately negative about the business itself. However the asset backing is so strong, that a lot of the risk is removed. Hence I’ll stick at AMBER, which is where we’ve been previously all this year to date. Although I’m very much losing patience with this share, and another profit warning would mean we’d have little choice than to shift down to amber/red. We’d already be there, if it wasn’t for the big balance sheet support, now well above market cap.
EDIT: Competitor Likewise (LON:LIKE) has issued a profit warning today, with Zeus lowering forecast adj PBT from £3.5m to £2.0m FY 12/2024. 25 and 26 forecasts left unchanged though.
Graham’s Section:
Duke Capital (LON:DUKE)
Up 2% to 33.5p (£142m) - Trading and Operational Update - Graham - GREEN
Let’s check in on Duke. We last reviewed it back in April.
As a brief reminder, Duke invests in medium-sized businesses and receives payments that are linked to the growth of the revenue of those businesses.
Key points from today’s update for Q1 (April to June 2024)::
Recurring revenue of £6.3m, up 5% year-on-year.
For Q2 FY25, recurring revenue of £6.4m is anticipated - this will be a new record high but only a modest c. 3% increase on Q2 FY24.
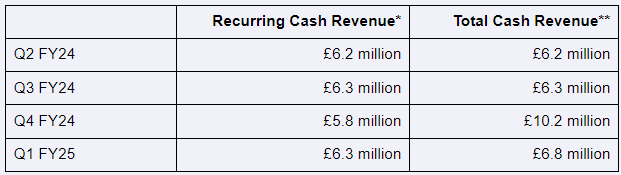
Operational update - details on two follow-on investments in existing portfolio companies. At one of these companies (United Glass Group), Duke now owns 74% of the equity.
Their tendency to buy equity stakes is something that previously affected my conviction in Duke, as I was far more interested in their “royalty” investments than in a private equity strategy.
CEO comment: Neil Johnson welcomes the August rate cut from the Bank of England.
The chart below shows the Duke share price since September 2021, when the Bank of England’s rate increases began. I’m not suggesting that the Bank of England is the only variable that counts here - but I do think it makes sense that in general, the value of Duke’s investments should fall as rates increase, and vice versa:
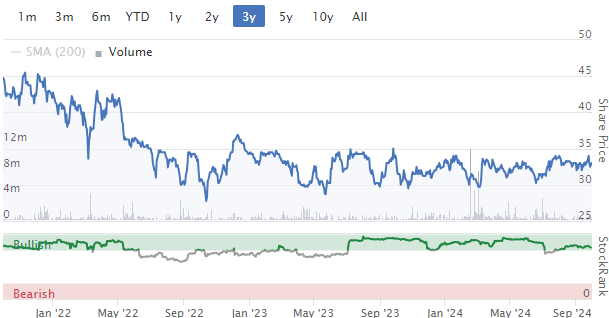
CEO comment concludes:
"Despite the macro headwinds, it is pleasing to report that Duke's diversified portfolio across the UK, Ireland, Canada and the United States continues to deliver reliable returns resulting in a strong dividend stream being paid out to its shareholders."
Graham’s view
As noted above, my conviction in the DUKE investment thesis has weakened a little over time, as some of their investments have seemed very high-risk to me, and with their growing private equity portfolio putting them first in line to take any losses at some of their portfolio companies.
However, I’m going to maintain my positive stance on these shares for the same reasons as before.
Duke has so far successfully avoided taking big losses, even when its portfolio companies have struggled. With a large, diversified portfolio that has been running for several years at this stage, it’s quite an achievement. The standout example here is Temarca, a Dutch riverboat operator crippled by the Covid crisis, which Duke exited in 2021 for only a very small loss.
Duke continues to trade at a discount to its balance sheet NAV (£142m market cap vs £165m net assets as of March 2024).
If Duke trades at or above its NAV again, I’ll revise my stance and perhaps switch to AMBER or AMBER/GREEN.
For now, I’m happy to stay positive. If I was still a shareholder here, I’d be inclined to reinvest the dividends back into DUKE until the shares trade at a higher level:
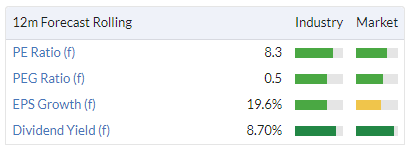
Bango (LON:BGO)
Up 6% to 115p (£89m) - Interim Results - Graham - AMBER
A mixed bag of results here, with revenues and adj. EBITDA improving, but with the company still loss-making. The main point is that trading is in line.
I’ve covered Bango a couple of times this year - see coverage in April and in January.
The main product is the “Digital Vending Machine” (DVM), a place where telcos, banks and retailers can connect to content providers and bundle their content into a package for consumers.
There is also a payment processor for app stores and merchants.
Today’s financial headlines are:
H1 revenue +19% ($24.1m)
H1 adj. EBITDA moves from breakeven to a $4m profit
The pre-tax loss improves from a $4.9m loss in H1 last year, to a $3.4m loss.
Net debt is $5m.
Customer wins/operational highlights are positive including various new customer wins and contract extensions achieved by the DVM, and new content providers signing up.
CEO comment:
"The first six months of 2024 have gone to plan and are in-line with the Trading Update issued in July. The payments business continues to deliver growth, providing cash to fund expansion of the Digital Vending Machine® (DVM), which continues to be adopted as the defacto standard platform for subscription bundling by the world's largest companies. The addition of Disney+ to the Bango eDisti program is further evidence of this and will help accelerate time-to-revenue from DVM deals. With 4 new DVM wins in the 1H and a further 3 in Q3, the pipeline built over the past years continued to deliver results and provides confidence in meeting market expectations for the full year…
Outlook: H2 will benefit from all of the new customer wins in H1 and also from Amazon Prime days, Cyber Monday, Black Friday, Christmas, etc.
Graham’s view
I continue to find the product interesting, with a convincing rationale. Bango’s CEO points to the lower churn rate enjoyed by Verizon after it started bundling 3rd party services using Bango’s DVM. Consumers like the simplicity of buying multiple products with one subscription.
Combine that with a confident self-description (Bango’s DVM is “the defecto standard problem for subscription bundling by the world’s largest companies”) and it starts to look like a very compelling investment.
So why have I been stuck on neutral? Simple: the company hasn’t been generating much by way of profits yet. Value investing tends to be a little impatient: it want’s profits today, when growing companies often can’t provide this.
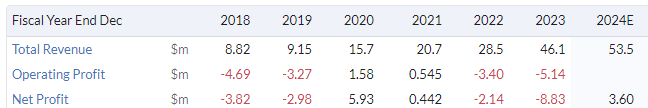
Looking at today’s income statement, we again have a large and uncomfortable gap between adjusted EBITDA and the operating loss.
The left-hand side is H1 2024; the right-hand side is H1 2023:
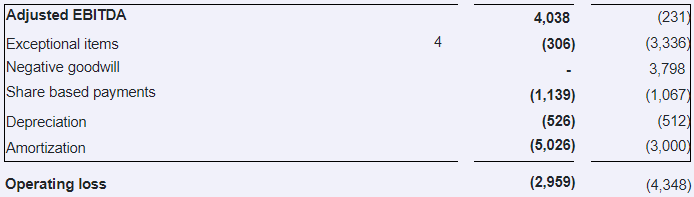
I should note again that Bango capitalises a great deal of development spending, i.e. puts the spending on its balance sheet as an asset, instead of counting it as a cost as it goes along.
In H1 2024, Bango capitalised $7.6m of development spending. At the same time, it only counted a corresponding amortisation expense of $5m. So it could be argued that the “real” operating loss was nearly $3m worse than what was recorded.
But I don’t want to be too gloomy: the numbers are moving in the right direction and I am inclined to believe the commentary which says that H2 will be a big improvement.
Therefore, I’ll continue to resist the urge to take a negative view on this unprofitable but interesting growth story.
One important factor is that Bango’s share count hasn’t increased much in recent years: it’s only up by 10% since 2018. When I see an unprofitable growth company that is constantly raising fresh equity, I’m far more inclined to be sceptical about its investment prospects. But that’s not the case here.
Bango does carry some net debt but if H2 is as good as is promised, it will have little difficulty servicing that debt. Therefore I’m happy to stay neutral here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

113 comments
Eenergy (LON:EAAS) - "Pipeline growth highlights commercial progress" - new note: https://www.equitydevelopment....
eEnergy’s interims confirm a period of strong commercial progress, underpinning confidence in revenue growth prospects for H2’24 and into FY’25. As previously reported, H1 trading was subdued but the sales pipeline is showing genuine momentum (+25% in H1) with >£6m of contracted orders scheduled for the remainder of the year. We note an element of caution over the timing of project delivery, given the strong Q4 pipeline, but this should not detract from the underlying progress that is increasingly evident. Following the disposal of the Energy Management business, eEnergy has a strong balance sheet and, in our view, is well placed to play a leading role in the Net Zero transition.
H2 has started well, with a quarterly revenue record in Q3 (£9.2m). Revenue expectations for the remainder of FY’24 are underpinned by a contracted order book of £7.6m at the end of September, £6.4m of which is expected to convert to revenue in the current year. The Board has maintained its revenue guidance of between £25m and £26m. We trim our forecast to the bottom of this range (previously £25.5m) and apply an element of caution to margins and cash generation, noting some risk over timing. As a reminder, our forecasts do not include the potential benefit of deferred consideration from the EM disposal, which management estimates at between £8m and £10m over the next two years.
Hi Yiannos1,
Do you have any thoughts on the audited results of Made Tech (LON:MTEC) out today?
I thought the results were pretty good. Revenue was only down very slightly, adjusted EBITDA was significantly up 56%, reflecting an increase in gross margin. Strong balance sheet and NO debt.
Only negatives; they've written down the investments made to date in the Housing products and they need to keep growing and investing in developing scalable SaaS solutions to address challenges in the Local Government market.
The share price was down 7.5% today on good results.
A good top up opportunity or a signal that the're over valued?
I have a small holding and am tempted to top up. So would welcome your thoughts as I'm sure you've said you hold or have held?
Kind regards, Graham.
Hi Graham,
Made Tech (LON:MTEC)
I still hold a full position.
Results were OK but already known. The company continues to bid and win big contracts and I expect more to come. There is no debt and will be cash generative for FY25. I am very sure that there is a big seller in the market (probably one of these Fund managers that haven’t got a clue or they have redemptions).
The new CFO knows his trade very well and I do not get distracted from daily price moves. Another big contract in the region of £20-£30m and the price will probably go much higher.
However, overall the UK small cap market seems to be heading for further heavy losses and most companies will be affected.
All parties involved will have to take immediate action and these daily discounted placings that some have privilege and knowledge in advance should stop. A maximum of fundraisings should be imposed on all companies. Surface Transforms (LON:SCE) was recently funded but now they need more money and more and more……. I can name many companies where investors lose their money and there is no liquidity in the market.
It seems that AIM has an expiring date and I find the spread on the bid/ask price as criminal.
DYOR of course.
All the best
Thanks Yiannos1,
I'm going to do some more research on this one and continue to monitor the share price with a view to buying more on further falls. The company seems to have a pretty good order book so far but needs a few more decent contracts and it will fly.
Thanks again for your time and comments.
Graham.
Hello Paul
I've just tries to set up your Good(Best) - Minervini2(2017) - RS +growth+fc upgrades screen and its says No results found.
Have I set it up wrong ?
I think sales growth should be rank top 50%. not 50% overall
Hi Fluffyredsheep,
Yes a couple of the fields are different to mine. You had:
The highlighted ones are different to mine, which are -
To change it, here is the way to select ranks -
Hope that helps!
Regards, Paul.
Thanks Paul I have now found the advanced rule feature
Hi Paul,
As someone new to investing (less than a year with skin in the game) just wanted to say that I find the SCVR daily updates great value and the weekly podcasts a fine accompaniment for a long dog walk. Thanks for all the analysis. Re your request for feedback on whether to cover just the good rather than the bad and the uglies too I would say "the ones to avoid" are just as important as those that might look interesting.
My tip would be that Hargreaves Lansdown allows investing in Junior ISAs for 0% commision. This has allowed me to create a well diversified portfolio for my kids at low/no cost (still have to pay stamp duty on non-AIM shares). To date, I'm over 5% up over the FTSE All Share for the last 8 months so am currently enjoying some beginner's luck.
Keep up the great work!
Thanks ROCE Balboa (great username!)
Useful feedback, thank you.
Someone else said a similar thing, so think I'll stick with the current format of mentioning all the companies, good bad & ugly!!
Regards, Paul.
Government has for 100% sure already alienated every single entrepreneur in the country . Rest assured this an agile group of people who will not wait and give anyone the benefit of doubt .
It’s not been an auspicious start but I think you are greatly exaggerating the resultant actions. You know I’m speaking from a similar level of experience to you so the reality will likely be somewhere in between our diverging views. My view is that entrepreneurs like to grumble about the regime but they adapt and carry on doing their thing. Taxes go up and taxes go down and the best choice is just to ignore them and make good operational decisions. Are you suggesting that every business owner is about to up sticks and reincorporate in Europe? That’s just nonsense. Never underestimate the power of inertia nor the ability to adapt.
Bnb
You miss some key metrics and timings .
Many entrepeneurs were borne out of the 80s and 90s .
This generation is hitting their 50s / 60s and now have generated their wealth .
They are the ones who will not continue with both work shy mental health obsessed workforce that are so hard to manage, expect everytbing and commit nothing .
There is no new wave coming through.
I never suggested every budiness owner would relocate to europe that is of course nonsense .
My point true owners plan in advance and dont wait for the train to crash, they will have changed direction well before and its nonsense to “give the benefit of the doubt”
“Control the controllables” is what you do .
Some bald headed friend of mine said that .
Hello Planetx
Really enjoy your posts and insights on here. It would be a poorer place without you, no doubt.
Totally understand your frustration with the current pre budget void but do wonder if its a bit over the top and a bit as doom-laden as your own criticisms of our new pm and chancellor.
Theres a few sweeping generalities in your posts that I believe you would be very quick to criticise as an investor responding to an RNS from a business doing the same in one of your own portfolio companies.
Personally Im prepared to give them the benefit of the doubt so far. Its very early days. They cannot say everything is ok if it is not. And who knows - they may even say that they gave everyone plenty of notice about what may be in the budget to give those who wanted it time to take action beforehand.
Lots of the fundamentals seem to be pointed in the right direction. Get the budget out of the way and maybe the future could be bright.
Businesses managenent v Entrepeneurs and wealth creators .
One thinks and moves in advance with their strategy and one sits and waits
There have been some contradictory comments today on the attitude of business to the current state of the nation .
Government has for 100% sure already alienated every single entrepreneur in the country . Rest assured this an agile group of people who will not wait and give anyone the benefit of doubt .
Business leaders on the other hand are employees of a corporation , they in many cases will wait and give the benefit of the doubt . They lack agility .
When government alienate entrepreneurs and true wealth creators it is a huge huge problem and taking the opinions of the slow moving corporates over agile leaders with true skin in the game is just madness .
There is literally no point at all to start or develop a business in the UK and every single entrepreneur in the UK knows this. Do not underestimate their ability, willingness and speed witn which they are going to act .
Creo Medical (LON:CREO) have just announced a fund raise at 15:45.
Creo Medical Group plc ("Creo", the "Company" or the "Group")
Proposed Placing to raise a minimum of £12 million. Launch of Accelerated Bookbuild
Proposed Retail Offer to raise up to approximately £5 million (issue price 24p)
Bit of a niche post but there's a research report on Research Tree today on one of my favourite businesses - The International Stock Exchange Group or TISE for short. It's a stock exchange based in Guernsey, CI. It's 10 bagged in the last decade, shows excellent topline growth, pays a high, growing dividend with specials thrown in and is available on a forward p/e of < 10. Rock solid balance sheet and a cash cow with fantastic moat qualities. Main reason co's list there is for tax reasons so regulatory risk is real but hasn't happened yet. It's got a relatively new dynamic mgt team with big plans for expansion and a US exchange has recently become largest shareholder with @ 30% holding so might be takeover target. I don't own but wish I could. I can't buy it in my ISA. A stock exchange that exists to trade shares and I can't buy any - oh the irony ! Liquidity is a problem but I'm sure it would be possible to buy some shares but I think you have to contact exchange directly to buy. Just a really interesting business imo and shows the power of moat type financial exchanges imo.
Couple of interesting acquisition announcements today from two small caps I hold
Anpario (LON:ANP) $7.3m purchase of Bio-vet in Wisconsin, USA - manufacturers compatible products to ANP to the US dairy market, from a 25000 sq ft facility. Opportunities to export sell through ANP existing global sales channels. Personally I still think ANP spread themselves very thinly ( which this will add to) so am not totally convinced by the continued diversification strategy but I cant knock the ambition with this acquisition, which is good to see
Luceco (LON:LUCE) Much chunkier purchase of CMD, Rotherham based manufacturer and supplier of office/workplace wiring and cableing products. £30m purchase price, not cheap at all for a £23m turnover business and it appears the price is all payable up front/no earn out. The RNS refers to ebitda of £4m but that doesnt make any sense as a price multiplier to me for a manufacturer. No doubt LUCE know all about CMD and they have had a good record so far with their acquisitions so hopefully not too much risk in this.
Good to see some small caps just getting on with things whilst their share prices take a bit of a bashing !
Hi Whitbourne
As per Damian, I have been on a few Spectra Systems (LON:SPSY) calls...
Just to confirm that:
- the interest rate is locked in at 0.3%
- nothing gets factored into an Spectra Systems (LON:SPSY) broker forecasts unless its contracted income. "Future sales prospects" are not something that would ever make it into a broker forecast. Spectra Systems (LON:SPSY) management believe that broker forecasts should always be met... ...then any additional business will lead to them being increased.
Touch wood, its one of those unusual companies which doesn't like to risk keeping people awake at night... ...unless one is pondering just how much additional good news there might be.
AML Aston Martin down 22%. "warned of lower annual core profit and said it no longer expects to achieve positive free cash flow in the first half, citing supply chain disruptions and weakness in China."
AML reported a net profit for y/e Dec 2017, and floated in Oct 2018. If you thought this heralded to return to profitablity for the company, then you would have been sorely mistaken. It's the only time in the last decade that it reported a profit.
Bonuses all 'round.
Just finished listening to the podcast, don’t have time to read all the detail in these updates so it’s ideal . Happy for it to be as long as it takes.
Bidder has pulled out of Rightmove (LON:RMV) offer. This is one of those where it really pays to have taken some off the table near the bid price. I had little faith that REA would end up offering a high enough price and sold the lot around 700p, although selling half is often a better strategy. Depends on your conviction in the takeover.
I hope holders heeded Paul's suggestion to top slice.
Sadly I bailed earlier in the year but the 50% uplift since last week's results at Ceres Power Holdings (LON:CWR) got top sliced today.
Hello Paul, in response to your question from the podcast over the weekend, I personally find it useful that you cover both the weaker companies as well as the stronger ones. Some of your commentary in the past has saved me some mistakes (and money) so certainly adds value as far as I'm concerned. Sorry, but I couldn't help laughing when you announced the mystery share and then immediately gave the ticker (FNX). It's always top of my list of podcasts for both the learnings and entertainment so thanks for the effort you put into these every weekend. Huw
Hi Huwster,
Great, thanks for the podcast feedback.
"Sorry, but I couldn't help laughing when you announced the mystery share and then immediately gave the ticker (FNX)."
Oh I know, I cringed when listening back to it, to check for errors. This one was a particular howler!! LOL. So very much me being the muppet on that occasion :-)
Regards, Paul.
The CEO of SRT Marine Systems (LON:SRT) (I hold) gave a 15min update on Company operations and activities this morning which is now on the website. He gave it from the Middle East and it included comments on 4 major contracts plus the launch of their new NEXUS system at METSTRADE in Amsterdam in November. The SP is up 20% this morning which is probably not a reaction to his bad hair day 8-)
SRT Marine Systems (LON:SRT) I too hold so not entirely impartial.
The web cast recording is here
https://srt-marine.com/about/n...
As well as drawing attention to the number of contracts expected to be signed off this calendar year, Simon T mentioned one with a new customer which has been progressed very rapidly by the customer. He said it was worth in excess of $200m. Rumour has it that it could be Kuwait but he didn't say. The rise in the SP seems to be a result of the reminder that quite a few important pieces of news may soon be released. I certainly hope so.
Very positive from Simon (once again) however they do sound close to signing deals. I did a shallow dive on them and think they have to be worth a start position now. Director remuneration is relatively low with management options spread over 50p, 75p 125p, 150p, 200p 250p and 300p. Project delays impacting System sales but the other business seem in good health
They raised £10m in December which I think will see them through to April 2025 excluding any milestone payments.
Paul - you previously mentioned current debt of £9.6m, actually that is part of the Secured Loan facility from LGB Capital Markets which has a 3 year term but as they were in breach of covenants at that time they had to show it as current, they subsequently got a covenant waiver and until the retest on 30/09/23 (which I assume it passed)
Gulf Marine Services (LON:GMS) I note some substantial selling here over the last couple of days and consequent fall in the price. I am in the process of building a stake here and trying to decide whether this represents an opportunity or a warning. Things I am aware of are likelihood of Seafox continuing to sell (and what do they know that don't?) and also oil pricings declining a little. Is there anything else? Does anyone here have a view? Many thanks.
Hi Robert,
Paul sees Gulf Marine Services (LON:GMS) as a cash machine longer term; like you I am building a position, and added another 20% this morning (upon which the SP immediately dropped another 1%, so my usual curse applies!). I will pause there and see where the price goes over the coming days.
I think we are seeing continued sell pressure from the Seafox shareholders (who were granted GMS shares, and I guess are selling down), but exacerbated today by the increased middle east problems.
It looks like Seafox disposed of another 14 million shares around the 15p mark today which could explain the drop though the price now seems to be recovering. We may get another RNS summarising their position.
Tinkering at the edges.
I have added a few Kier (LON:KIE) this morning at 139p. The demise of ISG, the once listed Interior Services Group, I believe is hardly an endorsement of the construction industry, but will hopefully concentrate the mind of clients that going with the cheapest price is not a prudent approach. It also creates a £4.1 billion pick up the pieces exercise for what I expect will be tier 1 contractors.
Construction will always be a low margin business, but the art of risk management has in large part be learnt by the likes of Kier (LON:KIE) and Galliford Try Holdings (LON:GFRD) . The debt reduction at the former is gathering pace and should be eliminated by 2026 according to Panmure Gordon. Progressive deleveraging should see the shares re-rate from a PE of <7. Galliford Try Holdings (LON:GFRD) which I previously held having bought a few years ago, trades on a PE of 12/13, so a PE of 10 for Kier gives a price well north of 200p, but this is surmise at present.
Facilities by ADF (LON:ADF) I have bought a modest opening position post the recent acquisition and improving outlet for the industry, having read Paul and Graham's comments and the recent interims. The shares are cheap assuming current forecasts are met. I also note that Harwood has taken a sizeable position, although in fairness and just to show no one gets it right all the time, the Harwood stable has recently had the setbacks with Hostmore and Flowtech. Still they get many more right than wrong. Also Judith Mackenzie of Downing was positive on the shares.
Just my meanderings.
Facilities by ADF (LON:ADF) I have bought a modest opening position post the recent acquisition and improving outlet for the industry, having read Paul and Graham's comments and the recent interims. The shares are cheap assuming current forecasts are met.
There was something on the BBC News website at the weekend that wasn't entirely positive about the film & streaming TV industry. It basically said that assumptions about the number of productions returning to 2022 pre-strike levels were looking very optimistic. There is a useful research website that seems to get used by the media that looked quite interesting: https://prodpro.com/blog/q2-20...
There was something on the BBC News website at the weekend that wasn't entirely positive about the film & streaming TV industry
I read the article and concluded that it was very focused on the situation in Hollywood, where film and TV production is as steel is to Port Talbot. My sense is that we can take the peak of streaming production to be well and truly in the past, but the UK is actually one of Hollywood’s challenges, with its preferential tax incentives and deep reservoir of production resources and acting talent. They love a British bad guy!
Notwithstanding the mobile nature of talent, I hope for a return to steady rosters in UK production. Steady is all it will take to deliver Facilities by ADF (LON:ADF)’s targets, in which eventuality, shares should gain good traction. Of course, I could be wrong, but my TV production friends and family (directing, acting, editing) are all busy working and the streets of Hebden Bridge are blocked with film crews on the latest Sally Wainwright production.
I read the article and concluded that it was very focused on the situation in Hollywood
The BBC article was the usual lame puff piece about some poor struggling bloke that films drone sequences for film & TV in California, but of more interest was the source which is the Prod Pro website I linked to. I would have a good poke around on there if I held Facilities by ADF (LON:ADF). I have no dog in the fight as the company has awful gross margins and has never generated anywhere enough free cashflow to be of any interest to me. Good luck with it.
Thanks for your thoughts and the link
The film and TV sector in the UK has 3 main elements:
1. Movies - returning to a strong normality post strikes, UK appears to be gaining market share
2. Streaming (aka scripted or high end TV) - streamers have cut commissioning budgets but UK is gaining market share.
3. Unscripted - this is the largest in terms of employment and is mostly for BBC, ITV, C4, C5. This remains in the doldrums. BBC has less money because inflation has eroded the real value of the license fee. The others are impacted by subdued advertising.
So Facilities by ADF (LON:ADF) business tally depends on the sub sector it serves.
Facilities by ADF (LON:ADF) There’s a current mantra in the industry amongst freelancers, survive to 25….
As most of us suggest - there still appears to be great value on offer in UK smallcap land.
Thing about AIM is that the fwd PE is 12.7, but TTM PE is 17.5. Forecast EPS growth is 21.16%, which seems unlikely. TTM EPS growth was 4.9%, which is actually pretty good. If you were to strip out a lot of the dross - let's say somewhere between 60% to 80% of companies listed there - you're likely to have companies growing much faster than that.
In FT250, TTM PE was 16. Actual growth was 7.7%. I'm very surprised. Forecast growth is 13.3%. So, again, I think analysts are overestimating. I assume that another 7.7% is the most one could hope for. It seems a bit high.
In FT100, TTM EPS growth was 1.9%, forecast 11.2%. Yet again, analysts are far too optimistic. Somewhere between 2-3% would be more realistic.
I'm not sure it is helpful to look at markets in this way. Who cares? I can't talk for anyone else, but I have no interest in investing in "the market" and only come here to find companies that can easily outperform all indices. The FTSE 250 is a complete joke of an index that is no use to anyone, heavily weighted to Investment Trusts, REITs and Infrastructure funds.
Agreed. That might account in part to the disproportionate falls in price on reasonable results.
Yep, quality companies will perform in any market.
MUL It looks like handbags at dawn for luxury good manufacturer Mulberry.
On Fri 27 Sep at 4.44pm it released it prelims. Cheeky beggars. You know it's going to be bad when there's a Friday after-hours update. What delights lie therein, I wonder.
Group revenue down 18% for a start. Group's debt facilities increased with renegotiated convenants. Hmm, that sounds ominous. Interest cover is 1.9 according to latest stats on Stocko, so that'll explain that. And, well, analysts expect losses for 2024 and 2025. Who would have thought that flogging overpriced bags would be so difficult?
It's not all bad news though. They did win a certificate for "the brand's sustainability journey" (their words). It reminds me of the film Rain Man. Tom Cruise finds he has been cut out of a substantial inheritance, but he had been awarded a rose bush.
But wait, there's more. The company decided to do a capital raise of £10m at a discount of 14.9% (but not 15%) of the share price. Shares are down 12% to 103p. Market cap is currently £71m.
"Mulberry's design teams continued to read the market well". Um, OK. Nevertheless, they made a pretax loss of £34m (2023: profit £13.2m), although some of that are wrte-downs.
FRAS owns a 37% stake in MUL, and issued an RNS today saying that they are not happy bunnies. "Frasers was not aware of the Proposed Subscription until immediately prior to its announcement ... Frasers would have been willing to underwrite the subscription in its entirety, potentially on better terms for the Company. Given this total lack of engagement, we believe the status quo to be an untenable position for Frasers and the other minority holders of Mulberry shares." They want to make an offer of 130p for the company. It is contingent on Mulberry's board recommending the offer, the largest shareholder (Challice) vote in favour of the offer, and a few other things.
Fraser's announcement does not constitute a firm intention.
Plenty of excitement today. Stay safe.
Ocean Wilsons Holdings (LON:OCN) on the move this morning. Perhaps there's a leaky ship on expected offer?
About time. The share price always seems too low and inconsistent with good results.
I really want to invest in Avacta. I get what they are trying to do and recently I have had a friend who has been through Chemo and radiation and been rather shocked by the severity of the treatment and its outcomes. So I am totally onboard with what they are doing. But every time I look at them they are just uninvestable. Struggling for money. They raised £32m in March and appear to be burning through a not dissimilar amount every year. So investors can look forward to another raise next year. Although the company also mentions wanting to join NASDAQ so more dilution anyway. They still have to work through phase 2 and maybe 3 for their first treatment. I cannot help thinking that something isn't working right when such a helpful and worthwhile object is not funded to completion. Of course they recently replaced their CEO and CFO so perhaps the answer is management. The only real solution is for a big pharma to buy it and I remain interested that they haven't...........what is missing? Anyway I remain on the sidelines believing sooner or later I will be disappointed as one of the big boys buys it for peanuts. But a treatment that removes many of the side effects of chemo ... what an outcome that would be.
Avacta (LON:AVCT)
Personal opinion is that you will have more chance making money by trying to pick the Grand National winner.
Most companies fail in Stage2.
It is clear that (by looking to list over the pond) they have difficulty raising more money in the UK. Probably local investors had enough of their stories.
All the best
The recent downgrade by Deutsche Bank didn't help but it's a very jam tomorrow biz.
its been a jam tomorrow business for years!!
It seems at Made Tech (LON:MTEC) the new CFO is bringing a far more prudent approach to their Y/e reporting, with a £4.3m impairment to intangibles, making the whole balance sheet more credible. Without that impairment charge, there would have been a statutory profit, so prospects are good going forwards.
Paul. Headlam (LON:HEAD) Adding to your comment "Restructuring - this strikes me as an extensive reorganisation of the business. Its current hotch-potch of 32 businesses (built through acquisitions) being consolidated into a single national business" It strikes me that the management has been hopeless. They should have properly integrated the acquisitions shortly after acquiring each one, instead of waiting until they are forced to integrate them because profits have turned into losses as the result of a downturn.
My understanding is that Headlam (LON:HEAD) acquired a series of 'strong' regional businesses over the years. Unlike Greggs, who grew similarly, they never had a good enough Marketing Director or at least anyone who could stand up to Tony Brewer....who is now the boss at Likewise (LON:LIKE) . Similarly too many in the business were happy to copy the patterns of past success with regional depots. It's always easier to go with an existing model that works isn't it? That is, until it doesn't.
To my mind there is huge scope here for operational savings, faster stock turn and freehold sales but I'd like to see them start delivering before investing. The efficiency buzz has been in the AR for several years. Time to deliver?
FNX our mystery share of the week, that was funny
Great podcast as always Paul!
Duke Capital (LON:DUKE)
Trading update today, hoping Paul or Graham give it the beady eye :-)
Not sure who it was who originally mentioned this, but it continues to do me proud. A great company and pays a handsome yield quarterly. I bet even Daisy would stick her earnings here!
Here we go again?
Japan's Nikkei dived 4.8% earlier today as the incoming prime minister (Shigeru Ishiba) said he supports the Bank of Japan raising interest rates.
Unwinding of the Yen carry trade 2.0?
There were elections on Friday!
New prime minister!
Nothing to do with what you are suggesting
All the best
Reassuring results from Spectra Systems (LON:SPSY) this morning, spoiled only by much lower cash balances than we have been used to. They explain that this is because they had to buy in stock to fulfil future orders, which is a positive reason. The key point is that they expect to meet 2024 forecasts which puts them back on a PER of 15-16 where they have traded historically. The detail on trading momentum and future prospects is impressive.
The 2025 forecasts suggest that earnings will more than double from 2024. That is really eye-catching. I'm sure it is too soon for the company to comment, but those estimates must be based on analysis of future sales prospects and pipeline contracts. Will be fascinating to see what develops.
A final snippet - borrowings (which came with the acquired company) at an average rate of 0.3%. Unless I have misunderstood, that's remarkable and suggests a switched-on CFO who locked in near-zero interest rates at just the right time. No need to repay any of that debt, since the cash on deposit will be earning much more.
RE: Spectra Systems (LON:SPSY)
A final snippet - borrowings (which came with the acquired company) at an average rate of 0.3%. Unless I have misunderstood, that's remarkable and suggests a switched-on CFO who locked in near-zero interest rates at just the right time. No need to repay any of that debt, since the cash on deposit will be earning much more.
I assumed the interest rate was a typo. I still think it must be. Even when BoE interest rates were at the low I don’t know how a small business would be able to borrow at those kind of rates from a UK bank. It would be interesting to find out who the lender is. Perhaps it includes monies provided by the government over Covid that have not been repaid?
I agree that it surely must be a typo in the Spectra Systems (LON:SPSY) RNS. In the Cartor accounts for y/e 30/9/23 filed at CH, the following was the loan balance:
Interest paid was:
That suggests to me that the average rate might have been around 6%. This is purely a guess but possibly they have divided the interest paid for 6 months by the average loan balance and then put the decimal point in the wrong place.
That suggests to me that the average rate might have been around 6%. This is purely a guess but possibly they have divided the interest paid for 6 months by the average loan balance and then put the decimal point in the wrong place.
Thanks for digging into the Cartor accounts. A 6% rate sounds much more plausible!
Spectra Systems (LON:SPSY) is legendarily uninterested in willing disclosure, it would be a major (but welcome) change if they were to comment on this apparent error. I hold, but with an uneasy understanding that I can never know very much about the details of this business
Hmm I'm not sure that can agree with this as I've been part of quite a few calls with Spectra Systems (LON:SPSY) management and they've spend a lot of time explaining the various parts of the business. This was also the case with the Cartor acquisition and certainly the question of the low interest rate on the debt came up. AIUI the interest rate really is 0.3% which why they didn't just pay it off. Equally the interest charge in these results (and the prior Cartor) results doesn't seem in-line with this. Looks like I have a question for this Friday's call!
Apologies to them if I have not been paying enough attention to Spectra Systems (LON:SPSY) communications and I will go back over what I can find. Interesting to hear what comes of your Friday call.
Hi Damian,
It would be super if you can post any thoughts on Spectra Systems (LON:SPSY) following your investor call on Friday. Is this call open to other shareholders, said as this is an important holding for me.
Hi OldSchool05,
As far as I can tell the call is open to all shareholders as it's being run by their Nomad Zeus Capital. I'm loath to paste an email address here but you could try getting in touch with Laetitia Bradamante at Zeus to see if you can join the call at 10am this Friday.
HTH
As far as I can tell the call is open to all shareholders as it's being run by their Nomad Zeus Capital. I'm loath to paste an email address here but you could try getting in touch with Laetitia Bradamante at Zeus to see if you can join the call at 10am this Friday.
Hi Damian,
I can't make the call on Friday but would be very interested to hear how they have achieved such a low interest rate (0.3%) on the debt if you get time to pop the question.
All the best, Si.
Huddled (LON:HUD) results interesting. Looks like they will be at a run rate closing in on revenues of £15-20m by year end (looks like £14m currently growing at around 15% qoq).
So the real question is can they get the operating leverage now to start flowing through and generating profitability. If they can then it’s very cheap in my view. But that’s why the share price is where it is - the jury will be out until it does.
Paul….a polite suggestion.
With respect, calling our Chancellor a Muppet, less than 3 months into the government’s tenure, and ahead of their first budget, is premature at best.
Business is overwhelmingly positive on this govt. Housing CEOs for example are all over them. Hardly surprising after Pepper Pig World, vroom vroom, Truss, fifteen Housing Ministers in 14 years etc etc etc…
Give them a chance. If they PROVE to be muppets, go for it. But so far I think it looks likely that Business and therefore the Economy can look forward because we finally have a government with a plan. It’s a very long time since there was any discernible plan from central govt. It’s also quite likely that our stable political environment puts the UK in great shape compared to our European friends and neighbours. Just look at the mess France, Germany and now Austria are getting themselves into.
Onto our day jobs…what on Earth holds the SP of hVIVO (LON:HVO) back? Good news after good news, Octopus increasing their holding rapidly, amazing recent results, a govt who wants to see new technology and innovation prosper, and yet still their SP going nowhere. Welcome your view about why, if and when the market will turn positive on them.
And thank you. Feel free to tell me to sod-off after my mild rebuke.
Well, let's hope you're right. I can only go on the actions & statements so far, which have done measurable damage to consumer, business, and investor confidence. Hence my remark.
Paul, Andrew, I think you’re both right. On the one hand, we have a sense that the government actually wants to try to make things better for the sake of the nation rather than themselves. On the other, there have been some leadership errors in talking down the economy and making poor choices in the handling of perks, undermining their mission. Let’s hope they learn from that and we can look forward to some stable, sensible government.
Right. Enough politics. I’ve bought Fonix (LON:FNX) this morning, agreeing wholeheartedly on your mystery share. And I’m passing the rule over MPAC (LON:MPAC) and Zotefoams (LON:ZTF. The latter feels more like a gamble on Rezorce (spelling?). What are people’s thoughts on these two? Neither has a great record of free cash flow generation, and the latter is particularly weak historically.
Rachel Reeves and HVO both requiring patience I think. I'm more confident of the latter coming good but time will tell.
I liked the Muppets, leave them out of this. I asked Copilot which Muppet would RR be most like and it came back with Miss Piggy! My wife says I'd be one of those guys in the balcony, Statler of Waldorf.
BnB, I have been thinking of getting into Fonix (LON:FNX, so have been looking at the balance sheet. We only have the 2023 Annual Report in detail, but I am struggling to understand Accrued Income of £13,174k plus trade debtors of £22,658k against 2023 revenue of £64,916k. If they are holding cash on behalf of their customers, why would these numbers be so high? Accrued income at 20% of revenue seems high to me. Anyone understand this?
Well done for looking. On my ventures into Company Accounts I have seldom given an unconditional thumbs up. I recall many years ago being hugely impressed by the clear Accounts of Coca Cola.
I found this in the admission document and think it probably explains the high level of receivables.
"Trade receivables includes gross Mobile Payments amounts due from MNOs that are payable to customers. These amounts are not recognised as revenue as detailed in note 2.5 above."
Basically Fonix acts as an intermediary, collecting the full amount from the network operators but only recognises net revenue from their portion of the transaction. However the full amounts due from the network operators are included in trade receivables until the payment is made to the end customer.
I think that makes sense.
BnB Zotefoams (LON:ZTF) looks like a free bet on the success or otherwise if ReZorce to me. The underlying business supports the share price and if and when the capex for developing ReZorce stops it will be significantly more profitable. I think Paul has commented to this effect previously.
ReZorce seems to be taking a long time to get these field trials through. Volumes weren't particularly substantial so not relevant to revenue. Could be final step in demonstrating efficacy. Hopefully we'll get an update at next quarterly. Meanwhile they keep picking up innovation and recycling awards across Europe,. The media launch was well received and supported by the former head of Unilever if I remember correctly. That led the bounce to 570p and now we're back around the £4 mark. As ever you pay your money and make your choice.
Really? ever heard of Lord Alli?
Really? ever heard of Lord Alli?
Has he got shares in Facilities by ADF (LON:ADF), then?
I’m a CEO of a tech business with 6 million ARR, the overwhelming feeling I get, is that business and the wealth creators are seen as the enemy to pay the bills ran up in CV-19, and fund public services blighted by zero productivity for decades.
It’s pie in the sky thinking, all the signs are business will invest elsewhere if the risk reward is skewed. Corp tax + dividend tax mean profits I want to take out are already taxed at 64.34%.
You decide if that feels like an environment suited to economic risk taking.
It’s pie in the sky thinking, all the signs are business will invest elsewhere if the risk reward is skewed. Corp tax + dividend tax mean profits I want to take out are already taxed at 64.34%.
first up marginal top rate of tax you are talking about is 54.5% not 64.34% so lets not create fake stats here - and there is plenty of opportunity to not pay those marginal rates if you dont actively need the funds personally in your pocket right now.
in that respect should your ire not mainly be aimed in the rear view mirror. Statements i have seen - suggest to me labour are more trying to equalise tax rates paid rather than raise them for the people who are already paying top whack tax at 50% plus.
Note I don't disagree that anything over 50% (posibly lower) is probably too high and clearly a disincentive for people to work or an incentive for people to leave or try and cheat the system.
An efficient government would work on getting rid of the dead wood in the economy of which there is far too much hitting productivity but as for "Statements i have seen - suggest to me labour are more trying to equalise tax rates paid rather than raise them for the people who are already paying top whack tax at 50% plus." this is a rediculous thought rmillaree, with respect, how much more can the low PAYE workers be put upon?
Yes, Sunak missed an open goal here, failing to let zombie companies die during the pandemic, instead handing out bounce back loans with minimal checks and overly generous furlough payments.
Because of the suddenness and depth of the business stoppages, combined with massive size of the problems, there is absolutely no doubt in my mind that the comprehensiveness of the furlough program was a daring and brilliant decision . For businesses good and bad time was of the essence if the economy was not to be utterly destroyed (particularly smaller less well capitalised businesses). There was not structure, data or staffing to do a separation of wheat from chaff in the time available. There were, of course , abuses but I have no doubt at all that the decision to save now and sort later was the right one and far more opportunity was saved for the future than was wasted on fraud.
It is instructive to feel this pressure if you look back to the Stocko SCVR comments at the time. One of Paul Scott’s comments threw serious and justified doubt on whether the program could be carried by a Civil Service that has not been covered in glory, and I think they deserve considerable credit for getting the support in place so quickly.
I will stick up for the furlough program and the Bounceback loans - that doesnt mean that there wasnt large mistakes made along the way. For example paying cash fulrough handout that suited them and perhaps the employer - and at the same time letting them go out and find another job on top - was not a sensible use of taxpayers cash in any respect. Ref bounceback loans - the problem here was twofold -s bank lent to anyone without checking at the time - and the government did not demand rigorous checks were made to stop the stupid loans. In principle though these handouts were necessary and certainly kept the lights on even if they were poorly implemented from common sense point of view - that sums up the government and banks in a nutshell.
Eg for bounceback loans they could have simply banned all companies paying dividends till loans were repaid.
imho thats the job of government civil service to do stuff like this - i would give them a 5/10 as they did the basic job that was needed - but almost zero common sense shown to protect us taxpayers who doubly scored or who had an easy job syphoning cash off with few questions being asked. With any benefits or freebies handed out the receipients should always really be signbing on the dotted line to say they will not unduly gain and act ethically. Do we ever hold or expect high stanbards high standards - rarely and that will allow fair comment from those that have seen others pocket large sums that made no sense.
Ref the furlough program - that was actually 95% run by employers and their acountants - they had to make sense of very poorly worded instructions and they did all the calcs and submissions to hmrc. All the powers that be did was do similar to what they already did anyway when reimbursing maternity pay to employers - yes extra manpower was needed but they have a huge pool of employees and budget to work with. They did their job and most of the payouts were processed reasonably quickly but for an organisation that exists to process stuff like that lets not over egg the job they did.
I have to concur with you Paul. Delivery in office significantly fails to meet expectation raised in the election campaign. Some may be surprised.
" ... fails to meet expectation raised in the election campaign "
This is the stuff that baffles me - they didn't say anything in the campaign, so what were people expecting?! Their entire strategy appeared to be 'say nothing and keep our heads down - if we don't say anything much then we can't say anything wrong, and everyone hates the previous lot so we'll win'. As we all know, this proved to be spot-on as a strategy and resulted in them winning despite having a record low support amongst the general population. Winner by default as the marginally least hated party, by refusing to really have a clear policy on anything at all so that nobody could dislike it. The only 'clear' message was a negative statement of not doing something rather than a positive policy - i.e. not imposing taxes on 'working people' (which is causing chaos as everyone is still trying to figure out the consequences of what this means and what will in fact be taxed as we approach this budget).
There were several polls run after the election in which the public were asked to name their top 5 biggest moments of the election campaign season - 4 of them were about the Tories and one about the Lib Dems. Labour didn't get a single spot for doing anything remotely memorable. People didn't vote for this government, they voted for not having anything else. It's all very depressing that this is the best the country can muster.
What about the previous muppets we have had to endure?! Wasn't it BJ who said F*** Business and don't get me started on Liz Truss.
Things can only get better....
I don't agree, things can get worse. Labour have robbed from the elderly and given in to the unions. Rishi and Hunt were a safe pair of hands and I wish they were back in control.
"Labour have robbed from the elderly and given in to the unions"! Well that's what the Daily Mail thinks. Aren't the Unions demanding that the Winter Fuel Payment be maintained for all pensioners? I think it's a pity that the Blair Govt didn't make it means tested when they introduced it. Personally I'm happy to give it up and see benefits increased for those who need it (none of whom I suspect are in a position to be reading this website).
You are wrong there Roger. I'm retired and part of my reason to be here is to try and maintain the standard of living I had before, it's also a hobby that keeps my mind active. You might be aware but let me remind you that Gordon Brown removed the tax-free stus of pension funds' dividends leaving a big funding problem for future retirees. Also in 1997 it was decided to change rules regarding inflation and yearly increases, the effect being companies tending to ignore conributions made before when it came to inflationary increases. So for anyone in my position with part or all of service before 1997, a final salary scheme means just that. I'm better off than some in that a good part of my income was in extra payments for out of hours working and on-call which I invested, a large number of my ex-colleagues are not. Now at nearly 80, I still am looking over my shoulder in case those in power decide they need to steal my modest capital to support those whose votes they depend on.
Yes, to send out dire forebodings of increased taxes and being told to wait two months before the extent of the damage is disclosed is hardly the action of responsible government. The low level of shares traded shows that people are very concerned and don’t want to enter the market. As for Starmer, he is a self-confessed devotee of the WEF and its Sustainability Policies which carry the seeds of destruction for businesses generally. You will own nothing and be happy.
Andrew
“Business is overwhelmingly positive on this govt.”
I dont know which businesses you are talking to but I know a lot of business owners and this is 1000% absolutely not the case
I would also muppet is a most generous assessment .
As I understand it, business are broadly positive, because there's at least some adults in the room offering some level of stability and working toward developing a long term plan.
There's been a few missteps which they have to learn from which they helpfully will. Maybe we all should exercise patience in the same way we do with CEOs, and allow them time to execute their plan. Patience for the new administration seems to be lacking in way that it wasn't when the last one were in.
File under Fiction.
hVIVO (LON:HVO) I held this company until a while ago, as the numbers looked good. Decided to sell because my conscience wouldn’t allow me to hold a company that is testing mRNA technology on people. Absolutely no judgement of course, as I’ve held tobacco and gambling stocks in the past. Merely offering up a possible explanation for the lagging share price, as rightly or wrongly some investors may be looking to avoid the increasing controversy around these things.
RBG Holdings (LON:RBGP) profit warning for FY24 "Accordingly, the Board now expects that the Group performance for FY 2024 will be significantly below market expectations." However signs of recovery in September and the pipeline give some cause for optimism going forward, together with cost reductions on central London property and staff costs which will benefit FY25. The share price has been bombed out anyway so a 32% fall today seems over-done. They are within banking covenants but debt is too high, this is my main area of concern and I will listen carefully to their Investor Meet Company presentation at 10:00 today. If they are credibly able to reassure on this then, at this cheap price, they could be a turnaround opportunity.
RBG Holdings (LON:RBGP) feels like a binary bet on whether it can survive. With the shares near worthless they won't be able to compensate fee earners with share rewards, which is going to make it very difficult to keep staff (let alone attract new staff). Add to that the reputational damage from all the recent shenanigans, I'd imagine they're also finding it hard to keep clients. Then you have the very high levels of debt which they'll struggle to reduce.
Venture Life (LON:VLG) interim results out today.
It irritates me when companies say that full year will be inline with "management expectations" because we don't know what they are. We do know what market expectations are and the outlook there is a big miss because Cavendish have just slashed eps by 16% from 5.5p to 4.6p.
Yes, always feels disingenuous when management say in-line and yet the broker drops by more than 10%. Given management generally guide brokers and their analysis is in the public domain forecasts should be captured.
I agree David. I'm increasingly finding that some companies sound reassuring in their TU, but then the broker reduces forecasts. So if any doubt creeps in, with a vague outlook statement, I now go straight to research tree to see if the broker has changed the forecasts, and only then flag it as a profit warning (which usually wasn't obvious from the RNS). Likewise was a good example of that today.
All too often I'm afraid the PRs make interpreting RNSs a game of cat & mouse. They try to hide the bad news, we have to unearth it. It's one of the reasons why I'm not worried about so-called AI making my role redundant! It needs experienced humans to untangle the web of lies & deceit that we are often presented with at 7am each weekday ;-)
Hi Paul
"I agree David. I'm increasingly finding that some companies sound reassuring in their TU, but then the broker reduces forecasts"
A fantastic way to identify untrustworthy management teams. If they pull this stuff once, they can be virtually guaranteed to do it again and IMHO can reasonably be immediately and permanently blacklisted... ...until said team is replaced.
Sharw. Thank you for making a good point about which party is referenced in expectations statements. This leads me to think that, as well as having to consider how good the expectations appear, I now also have to consider which party is referenced. So I will have four classes of this: 1) Expectations not specifically mentioned 2) Reference made to market expectations (being quite reliable) 3) Reference made to managements' expectations (being quite unreliable) 4) Reference only made to "expectations" with no reference as to whose expectations they are. This may be due to sloppiness, or maybe due to deliberate obfuscation. Either way, I am tempted to assume that these are management expectations and are thus unreliable. Please can you let us know what are your, and other peoples thoughts, on this last point? Is it valid to assume that expectations of unknown origin are nearly always expectations of the management? In any event I will always be looking on Research Tree to see what is happening to EPS forecasts.
Last week HM Treasury announced a change in expense exclosure for investment trusts. I think it is worth reading the statement put out by the Association of Investment Companies (AIC).
Richard Stone, Chief Executive, said: “This leap forward on cost disclosure is great news for investment companies and their investors. The temporary suspension of the rules paves the way for a permanent solution to this long-standing and damaging problem.
“It’s good that the Treasury and FCA have recognised that the current cost disclosure regime is not working. The AIC has lobbied tirelessly on this issue and it’s encouraging that the Labour government has acted so swiftly.
“We look forward to working with the FCA as it consults on the new Consumer Composite Investments (CCI) regime. It’s vital that these new rules recognise the unique characteristics of investment companies, permanently end misleading cost disclosures which distort the market, and enable investors to make better informed decisions.
“Investment companies are a great UK success story and have a vital role in bridging the gap between private assets and public markets. Ending misleading cost disclosures will enable us to continue delivering for investors and make a critical contribution to the economy as the government drives forward its ambitions for growth, investment and wealth creation.”
Investment trusts had a good day last Friday and I suspect the positive momentum will continue. (Bold is my highlighting.)
Mr Contrarian, I think someone has just stubbed out your fag end - ouch!
My morning smallcap tweet: Surface Transforms - turnaround projections turn out to be a work of friction
Surface Transforms (LON:SCE) Mercantile Ports & Logistics (LON:MPL) Versarien (LON:VRS) Kromek (LON:KMK) Chill Brands (LON:CHLL) Cirata (LON:CRTA) Concurrent Technologies (LON:CNC) STM (LON:STM) Intercede (LON:IGP) Keystone Positive Change Investment Trust (LON:KPC) Triple Point Social Housing REIT (LON:SOHO) XLMedia (LON:XLM) £EEAS Brighton Pier (LON:PIER), 4Global (LON:4GBL), Marlowe (LON:MRL), Avacta (LON:AVCT)
◄Surface Transforms (SCE)► H1-June. The serial-disappointer warns FY rev c.£11m which cf market expectations of £17.5m due to "delays to enhancing capacity and yield improvement projects". "The impact of delays to the pace of growth has led to operational inefficiencies and cash constraints. We continue to manage cash flows carefully and are reviewing all available funding options." [SP=1.44 Cap=19m]. I hold a fag-end.
◄Mercantile Ports & Logistics (MPL)► H1-June. Usless tinpot warns of FY miss. [SP=2.1 Cap=7m]
◄Versarien (VRS)► sells subsidiary, AAC Cyroma for £550k to be paid over 4 years, starting 3 months after completion! A terrible deal for a co running on fumes. [SP=0.06 Cap=2m]
◄Kromek (KMK)► FY results delayed to second half of Oct. [SP=5.87 Cap=36m]
◄Chill Brands (CHLL)► has "secured new banking provisions and is working to resume normal financial operations including the completion of its audit". Update on its fistful of calamities. [SP=2.15 Cap=11m]
◄Cirata (CRTA)► $983k one year contract renewal with HSBC. [SP=28.22 Cap=38m]
◄Concurrent Technologies (CNC)► contact with a large US defence prime contractor for an initial $255k; potential lifetime value c.$5m. Customer also placed a $133k initial contract for systems related electronics. [SP=113 Cap=97m]
◄STM (STM)► Malta Financial Services Authority minded to approve takeover of STM. Long Stop Date extended to end Oct. [SP=55.55 Cap=33m]
◄Intercede (IGP)► wins $1.9m of contract orders and renewals. These "further underpin the Group's revenue for FY25 and contracted revenue backlog for FY26". [SP=202 Cap=118m]
◄Keystone Positive Change Investment (KPC)► proposes a scheme of reconstruction and winding-up. Holders can opt for shares in the Baillie Gifford Positive Change Fund or an uncapped cash exit at a modest discount to the formula asset value. [SP=230 Cap=136m]
◄Triple Point Social Housing REIT (SOHO)► selects Atrato Partners as new investment mgr. Co expects this "will deliver significant cost savings whilst maintaining the existing high levels of service provision". [SP=64.6 Cap=254m]
◄XLMedia (XLM)► H1-June. Guides FY adj EBITDA-cont only broadly in line. Blames slow start to customer acquisition at the start of US NFL season. [SP=10 Cap=26m]
◄eENergy (EEAS)►H1-June. Guides FY in line but "exposed to adverse weather conditions in the short-term". [SP=NA Cap=NA]
◄Brighton Pier (PIER)► H1-June. Warns of FY miss if trading continues in line with the last few months. [SP=35.8 Cap=13m]
In line: 4GBL, MRL, AVCT
"turnaround projections turn out to be a work of friction"
I think it was Joel Greenblatt who said "Companies tend to run out of money before management runs out of turnaround plans."
"Positive trading, discount-to-NAV being addressed" - link to new research:
https://www.equitydevelopment.co.uk/research/positive-trading-discount-to-nav-being-addressed
In its AGM statement of 26th September, Mercia Asset Management (LON:MERC) has confirmed that trading has been positive to date in FY25 (1 Apr 24 – 31 Mar 25), it is encouraged by current deal pipelines, and it is “optimistic for continuing profitable progress” in H2.
We remind readers that Mercia is scaling rapidly, with FUM more than doubling over two years to >£1.6bn. This was boosted by record net inflows in FY24 of >£0.5bn, including a string of new mandates from British Business Bank.
Mercia has also confirmed a net cash position of over £43m (30% of its market cap), a few days before the end of H1-25. With no debt, its balance sheet remains exceptionally strong. With our fair value of 51p, we maintain our position that there is potential for a significant share-price rerating.
Funny goings-on at Thor Explorations (LON:THX). Governmental accusations of tax evasion, firmly refuted. Anyone have greater intel??
Paul, Graham, anyone fancy donning a pair of those overstocked Dr Martens and giving XLmedia a good kicking? We still hold waiting for that promised cash return to shareholders.
Capita: A better business is taking shape Capita (LON:CPI)
https://www.yellowstoneadvisor...
Morning Paul, if you have time, would appreciate a review of MTEC's results please.
I've thought they are quite good actually, despite what can be viewed as a challenging year, and orders looking forward are good to see. Profitability is up, money in the bank and no debt shouldn't be sniffed at.
Obviously the fall in bookings this year, which should have been factored could be seen as an issue; however, it meets market expectations so recent weakness should dissapate?
I like their sector dependency unlike others as for a business this size - I'd prefer them to focus on government contracts. A little negative mark on the software division not getting upto speed as this could bring new revenue streams in quickly.
Hi HH,
I didn't have time for MTEC today, and it didn't appear on the subscriber "most viewed" widget, I'm afraid.
But by all means post your thoughts on the numbers here, if you wish to.
Regards, Paul.