Small Cap Value Report (Mon 31 Oct 2022) - CRPR, ARB, ESP, SAG, TPG, LOK

Good morning from Paul & Graham!
Paul's weekly recap podcast went up on Saturday evening, the audio is here (and on podcast platforms). Also, for Stockopedia subscribers only, I've typed up a written summary, which is here.
Mello Chiswick - I'm looking forward to seeing many friends old & new at the resumption of this in-person event. I hope people support it, as it would be such a pity to see everything go online, and lose the important social aspect of investing.
Edmund’s article on Market Musings - this is a very interesting series of articles, which you might not have seen, so do check them out.
Agenda
Paul's Section:
James Cropper (LON:CRPR) - a profit warning for H1 (breakeven), but better results expected in H2. Reasons given are sensible - a 20% hike in raw materials, plus the energy spike, and time lags in passing this on to customers. The trouble is, this is now looking to be the 3rd consecutive year of EPS around 15p. So a share price of 995p looks crackers to me. There's also some net debt, and a pension deficit. Cropper looks very significantly overvalued, in my view. Edit: the price has been marked down c.20% this morning, but hardly any trades printed (so far), it's very illiquid.
Science (LON:SAG) - has been circling TP (LON:TPG) for a while now, and a deal has been struck for SAG to acquire the 72% it doesn't already own. SAG has impressed us here at the SCVR for a while, so let's hope it makes a success of this acquistion.
Graham's Section:
Argo Blockchain (LON:ARB) (£35m) - this looks like it may be reaching some sort of conclusion. The equity investment that the company hoped for has not come through, and it has resorted to selling newly-purchased bitcoin computers that it has not yet taken out of the box. Bitcoin mining is an inherently leveraged activity and Argo has combined it with financial leverage, making for a toxic combination. Energy costs are up, crypto prices are down, and there’s a very real chance that these shares are worthless.
Empiric Student Property (LON:ESP) (£504m) - this REIT has issued two statements today. The first one is a dividend declaration (0.625p per share), and the second is a business update. Empiric’s properties are “effectively full” despite rents rising by 5.2% on a like-for-like basis for the new academic year. Further rental price increases of 5% are targeted for next year. The balance sheet here appears to be conservatively managed, and the company is behaving cautiously given the economic and interest rate environment: its development and acquisition pipeline has been “largely paused”. I think it could still generate respectable and reasonable returns for investors from the current valuation, despite running a cautious strategy.
Lok'n Store (LON:LOK) (£270m) - terrific results from this AIM-listed self-storage company. All the metrics are up sharply, having been boosted by “sale and manage back transactions” that have taken a huge chunk out of the company’s outstanding debt. It is now almost debt free and has great flexibility with how it wishes to plan its future strategies. The founder of the company is still the largest shareholder and is running it as Executive Chairman. While the shares aren’t cheap by any means, I think the company has done more than enough to justify this valuation.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
James Cropper (LON:CRPR)
783p (down 21% at 08:25, but on hardly any volume so far)
Market cap £75m
In advance of its interim results announcement due on 15 November 2022, James Cropper plc ('CRPR', the 'Company' or the 'Group'), the leading advanced materials and paper products group, today issues an update on trading for the half year ended 24 September 2022.
'Unprecedented inflationary headwinds impact the half year; the Group continues to prepare for growth'
Strong Q1 (revenues up 36% vs LY)
Growth rate slowed to +26% for H1, implying Q2 might have been somewhere around +16% (my rough calculation)
Wholesale gas prices +148%, mitigated by energy surcharges to customers.
Raw materials price inflation up 20%
Margins “temporarily squeezed” due to time lag in passing on price rises.
Overall result for H1 is breakeven.
H2 outlook sounds better -
The second half of the year shows a recovery through aggressive pricing actions and surcharges, supported by the recently announced Government support on energy prices. Each division is projecting volume growth over the second half. Order books are full and the Company is focused on a range of enabling actions to build a solid foundation for continued future growth.
Profit guidance for FY 3/2023 -
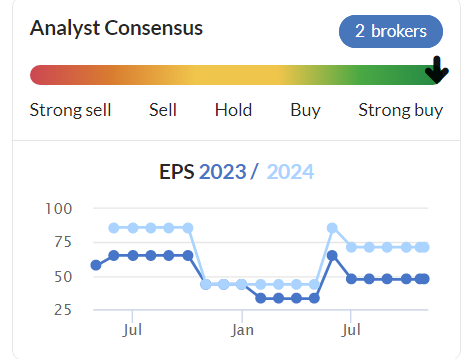
As a result of the current unprecedented macro-economic environment, management expectations for FY23 have been reduced with a year-end adjusted PBT of £2.0m against previous market expectations of adjusted PBT of £5.4m.
Clearly that’s a big drop in profit expectations, but the reasons given shouldn’t really be a surprise to the market, surely? Although the company doesn’t seem to have guided brokers down in recent months, which seems surprising, given known cost headwinds.
These forecasts are going to be slashed now, probably by about two-thirds for FY 3/2023 -
.
Management commentary sounds more upbeat for the medium term -
"Overall, despite the short term setback in profitability, growth prospects for the Group as a whole remain significant in the coming years."
My opinion - as management says, this is an energy-intensive business, so I’m struggling to understand why they didn’t manage market expectations down earlier? The big spike in energy costs was several months ago now.
It made £4.0m adj PBT in both FY 3/2022 and FY 3/2021. So a drop to £2.0m this year isn’t a disaster, and the reasons look perfectly fair - due to unplanned external factors, not internal mistakes.
With EPS now likely to be around 15p for the 3rd consecutive year, why on earth is the share price anywhere near 995p? (pre market open) That’s a PER of 66. We’ve questioned the high valuation here before. These may be temporary factors announced today, but I think far too much of the valuation rests on future hopes of improved performance, rather than historic numbers, which are now looking weak, if you take into account this year’s reduced profitability.
Note there’s also net debt, and a pension deficit.
I think this looks way overvalued.
.
Science (LON:SAG)
388p (up 2% at 09:01)
Market cap £175m
Recommended Cash Acquisition of TP Group
For anyone not aware, “recommended” means that both sides have agreed the terms of the deal, so it’s highly likely to go ahead.
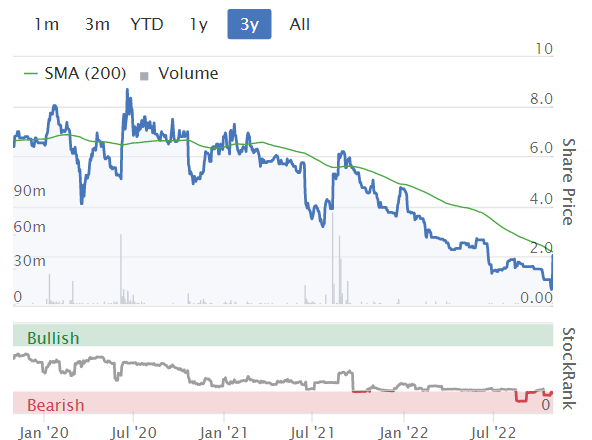
The price is 2.25p cash for TP (LON:TPG) shares, a striking 190% premium. That is until you look at the chart for the last 3 years of TPG -
.
Still, a nice trade for anyone who was lucky (or naughty!) enough to have bought TPG shares in the last 3 weeks.
The deal is valued at £17.5m in total (this is about 10% of SAG’s current market cap).
Although because SAG already owns 28% of TPG, it will only need to buy the 561m TPG shares it doesn’t currently own, so a cash cost of £12.6m.
SAG will take on £7m debt from TPG.
Onerous contracts within TPG’s Maritime division.
SAG made a takeover approach at 6.5p in 2021, so today’s 2.25p offer reflects a worsening position at TPG.
Only one institution, Hargreave Hale with 11.7% has backed the deal so far, so with SAG’s 28% that makes nearly 40% - so not necessarily a done deal yet, but probably heading that way.
My opinion - I do wonder why SAG has been so intent on acquiring TPG, when its performance over many years has been so poor? It talks about synergies, but even so.
On balance though, SAG should know TPG very well by now, due to having Directors on its board, and SAG itself has established a very good track record of being well managed, and doing good deals. I recall we’ve reported positively on SAG here many times.
Graham’s Section:
Argo Blockchain (LON:ARB)
Share price: 7.5p (-52%)
Market cap: £35m
The SCVR has only occasionally covered this bitcoin miner. In late August, with a market cap of nearly £200m, I suggested that it was worthy of giving the bargepole treatment, on the basis of its levered balance sheet and (in my view) overly aggressive growth strategy.
Here we are two months later. The pre-open market cap has fallen to just £73m, and that’s before this disastrous RNS:
The contents of today’s announcement:
- The equity investment of £24m that the company was hoping for, is apparently not happening.
- The company sold nearly 4,000 freshly delivered bitcoin mining computers that it hadn’t taken out of the box.
And then the hammer blow (emphasis added):
Should Argo be unsuccessful in completing any further financing, Argo would become cash flow negative in the near term and would need to curtail or cease operations. The Company is endeavoring to complete such financing transactions to provide the Company with working capital sufficient for its present requirements, that is for at least the next twelve months from the date of this announcement.
If it wasn’t so heavily indebted, the prospect of curtailing or ceasing operations would not be so unsettling. Because without its debts, it would be more feasible to have the crypto equivalent of “care and maintenance” - preserving its operational capabilities and simply waiting for prices to become favourable again.
However, its debts are significant. As of June 2022, they were:
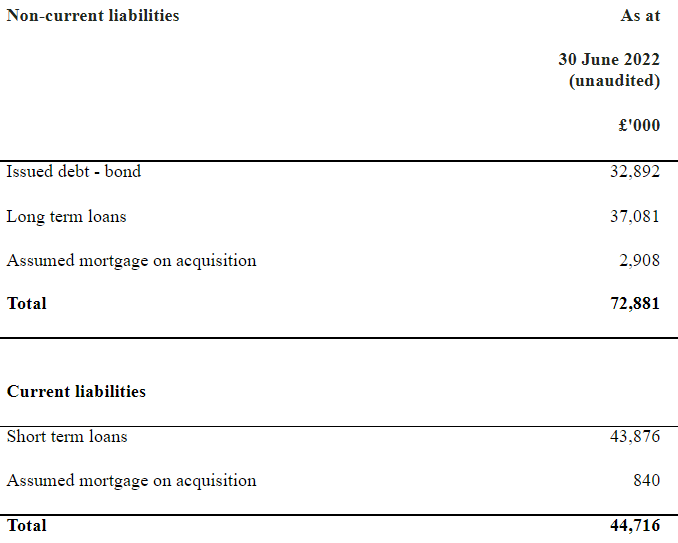
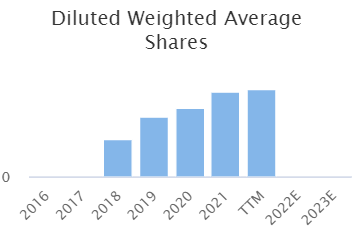
Note that even if the company gets the working capital it needs for its “present requirements”, there’s every chance that it will need more from investors after that. The share count has only gone in one direction at this stock:
My view
This looks like it could be headed for a wipeout of existing equity. I avoid saying that sort of thing with certainty, because there is always the possibility of a white knight turning up and giving a struggling business the funds it needs, before it goes bust.
Betting on that sort of thing is of course extremely risky. And without a white knight, these shares look destined for an ignominious ending.
Empiric Student Property (LON:ESP)
Share price: 83.5p
Market cap: £504m
It has been quite a while since we looked at this one.
Empiric Student Property plc (ticker: ESP), the owner and operator of premium student accommodation across the UK, is pleased to provide a business and trading update.
FY 2022 earnings will be “broadly in line with consensus at 3.2 pence share”. The Stockopedia EPS estimate is 3.23p.
Key points:
- Revenue occupancy 98% for the new academic year (it was only 86% last year).
- Like-for-like rents are up 5.2%, and minimum growth of 5% is targeted for 2023/2024.
- Disposal of a non-core property for £13m, above book value.
The CEO says that they are “effectively full” at this record-high occupancy level. Reaching 99% or 100% is in practical terms impossible, I imagine.
He continues:
"The wider economic outlook remains uncertain, however the higher education sector is known for its resilience and we expect UK universities to remain attractive to both domestic and international students. We are firmly focused on our premium accommodation offering and believe our approach to high quality customer service delivered through our Hello Student brand places us in a strong position."
Developments - the economic environment is not conducive to expansion:
Given the current market volatility we have largely paused our development and acquisition pipeline.
Indeed, the Empiric share price reflects the uncertainty in the broader property market.
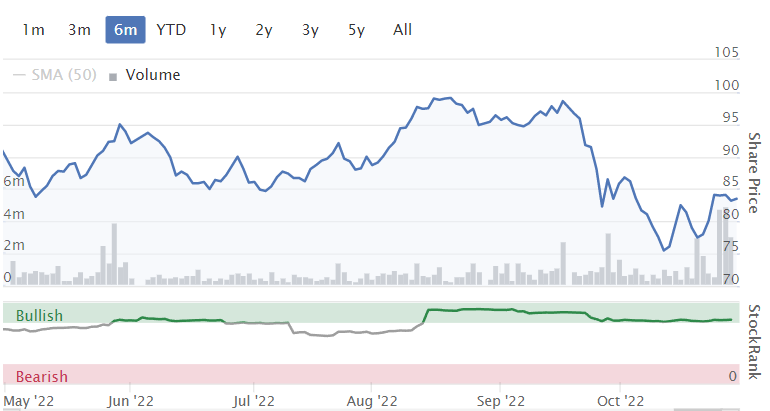
Note that net tangible assets per share, calculated in accordance with the rules for real estate companies, was reported at 117.8p for June 2022.
This compares with a share price of just 83.5p as of this morning:
Debt - the share price reflects its financial risk too, of course. Fortunately, Empiric’s financial situation appears to be sound: The LTV and the cost of debt are both low:
As at 30 September 2022, LTV was 29.7 per cent (based on 30 June 2022 valuations) with a weighted average cost of debt of 3.7 per cent, and a weighted average term to maturity of 4.8 years. Two thirds of our debt is fixed and one third floating. Cash and undrawn committed facilities totalled £100.6 million.
With an average term to maturity of 4.8 years, there will be a little bit of work to do with respect to refinancings in the years ahead. They say they are “in active and constructive discussion with lenders in respect of refinancing requirements.”
My view
I like the overall theme here. Premium student accommodation tends to find tenants easily, even if most of them come from abroad.
Empiric does say that after “targeted marketing during the pandemic”, it has raised the share of UK students to 50% of bookings. After a couple of years of normal international travel and normal marketing efforts, maybe this will head back to its historical average?
29% of bookings are from China and I suppose any strain in UK-China relations could impact this very large and important segment.
But overall, I like what this share is offering: a discount to NAV, a property niche that tends to find tenants quite easily, modest leverage ratios, and foreign customers whose spending power is somewhat immune to local considerations.
This share is unlikely to shoot the lights out but barring exceptional circumstances, it should generate a reasonable return for its investors, hopefully including both a dividend stream and a reduction in the share price discount to book.
Lok'n Store (LON:LOK)
Share price: 900p (+8%)
Market cap: £270m
Let’s check in on this self-storage company and see how it performed in FY July 2022:
- Revenue +22.9% to £26.9 million
- Adjusted operating profit +49.8% to £11.4m
- Operating profit +130% to £17.2m
- Adjusted NAV per share up 33% to £9.72.
It’s an amazing set of numbers.
Lok'nStore managed to sell four of its stores at a nice premium to their book value, in deals that it calls “sale and manage back transactions”. It is now generating revenues from managing these properties that it used to own.
As a result of this strategy, net debt has collapsed to just £20m, for an LTV of 6.6%. At this level, we can think of it as virtually debt-free.
The growth ambitions are still there, however: it currently has 40 stores (24 owned and 16 managed), and has 10 sites in its “secured store pipeline”.
The strategy is “unchanged” - “increase revenue from existing stores and open more new Landmark stores”.
The comment from Exec Chair Andrew Jacobs is brimming with confidence:
We aim to build more Landmark stores in the under-supplied UK market. We are growing the business from a strong financial platform that gives us great flexibility to respond to market circumstances. We have multiple levers to allocate our capital in ways which are most accretive to our shareholders through the economic cycle, and we are confident that we will continue to increase net assets, cash flows and dividends."
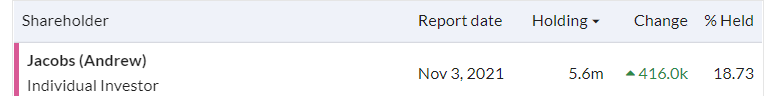
Note that Mr Jacobs is the founder of the company and still owns 19%, making him the largest shareholder by some margin:
Aside from the very rare family business that we occasionally come across, this is the ideal situation. It doesn’t get much better than being able to co-invest with a successful founder who still owns and manages his or her business.
Valuation: properties are valued each year by Jones Lang La Salle.
There’s some alchemy here involving discount rates and exit yields, but the valuations shouldn’t be too far wrong. So I would give some weight to the adjusted NAV of £9.72 per share.
Outlook statement
Here’s an excerpt:
This year's results are excellent with all metrics sharply higher, and trading since the period end is good. The continued strong demand and high occupancy levels across our stores give us pricing opportunities in the coming year.
Lok'nStore continues to experience strong year to year revenue growth on a same store basis and this will be enhanced by the three stores opened this year and the opening of four new stores opening over the coming year.
My view
Self-storage is an outperforming niche in the property market, and I think the positive underlying drivers are here to stay (increasing population density and lack of space!).
And within this niche the large, specialised self-storage companies provide a level of service that I presume the independent, smaller operators can’t guarantee.
These shares aren’t available cheaply but investors are getting a lot included in the price: excellent financial performance, a rising stream of dividends, great underlying growth prospects, and aligned management. These things are rarely priced at bargain levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Have held and done well out of Argo Blockchain (LON:ARB) in the past but have never held long term I learnt back in dot com boom that investing in small and large tech firms in high growth but risky areas is certainly not for widows or orphans and only to risk money you can afford to loose and to take profits quickly same is the case with biotech
More like gambling really normally stick to tech biotech investment trusts and private equity nowadays namely HgCapital Trust (LON:HGT) International Biotechnology Trust (LON:IBT) Harbourvest Global Private Equity (LON:HVPE) £PCT
Just my opinion if you pick the right small cap tech/bio tech you can make a lot of money the vast majority aren’t the right one
"Edmund’s article on Market Musings - this is a very interesting series of articles, which you might not have seen, so do check them out."
These are very good and I try to remember to read them but don't always manage to.
I have asked Stocko why we cannot have an email reminder when published as one gets with the SCVR but for some reason this is not possible, which is a shame.
Regards
Michael
Not sure if this will help Michael, but I leave my browser on the SCVR page, but whenever I come back I will immediately click on the "Discuss" option down the menu on the L/H side - this immediately takes you to the summary page so you can see a) any new posts and b) how many new entries to the SCVR (or any other post) since you were last on the page.
This way I normally see Edmunds article at a weekend soon after its posted and also allows me to re-visit any past articles that have new commentary - then I just scan down the entries looking for the latest time stamps.
For example, I hadn't been on the SCVR since mid-afternoon until 5 minutes ago and it told me there were 8 new posts, so I just scrolled down the SCVR until I found anything with a time-stamp after about 5pm tonight.
Sorry if that's of no help.
City in shock as £1.3 trillion is wiped off value of UK bonds in record sell-off
https://www.cityam.com/city-re...
Paul, over the weekend I read your transcript of your podcast with Paul Hawkins which I found was very thought provoking. I also listened to Tamzin Freeman`s podcast with Paul Hawkins from June 2020.
It reminded me of a period between May 2009 and April 2010, after the banking crisis, when I bought 5 building society PIBS (Permanent Interest Bearing Shares) in Nationwide, Coventry, Skipton, Newcastle and Principality, all of which still exist today. I held the PIBS in my SIPP.
I held them for varying periods between 2 years and nearly 8 years. The highest coupon with the Newcastle was 12.625% and the lowest was 6.092% with the Coventry. They were a terrific investment at the time making me a capital gain of £31k on an investment of £36k over 86% return. In addition I received half yearly interest.
At the time I did not perceive they were high risk as all societies were run prudently with only one or two exceptions and the vast majority of their mortgages were granted to home owners.
The best performer was Newcastle BS where I bought 5000 at 80p in Aug 2009 and held them until April 2017 when I sold at 185p for a capital gain of 131% plus interest received.
I used my broker HL for the transactions and 4 of the societies are quoted by HL today.
Thank you so much for reawakening me to the potential to diversify my portfolio which is currently 100% equities and cash.
I also bought PIBs at the same time but Principality is no longer available.
I hope this isn’t an inappropriate place to post this, but following on from the discussion last week about high income investing and corporate bonds etc, some might want to follow up by checking out some high income paying Investment Trusts. I hold this mix of very high dividend yielders.
SMIF. TWENTY FOUR SELECT MONTHLY INCOME FUND. 74p.
Small 1% premium to NAV. 9% dividend paid monthly. Dividend has been 0.5p a month for a while with one higher payment a year depending on affordability. This time it was 0.889p.
Until this bear market the share had traded around 90p so perhaps up to 20% or share price upside potential too.
Dividend paid monthly.
NBMI. NB GLOBAL MONTHLY INCOME. 74p.
8% discount to NAV. Dividend 8.2% paid monthly.
NOTE THIS, There are regular dividend increases! The latest increase from previous increase to 0.467p to 0.507p is from this month.
Here’s their explanation about the their dividend policy:-
“Dividends
In January 2022, the Board was pleased to announce a Target Distribution for the financial year 2022 at a rate of 5.25% of Net Asset Value per annum (net of fees and expenses) which equated to a dividend per share of £0.00415 paid monthly. This distribution represented a 6.41% increase on the total dividend for the 12 months ended 31 December 2021.
In April 2022, the Board announced a further increase to the Target Distribution for the remainder of 2022 to a rate of 5.8% of Net Asset Value per annum (net of fees and expenses). This equated to a target monthly distribution for the remainder of 2022 of £0.00443 per share paid monthly, or £0.05316 per share, per annum.
In July 2022, the Board again announced an additional increase to the Target Distribution for the remainder of 2022 to a rate of 6.75% of Net Asset Value per annum (net of fees and expenses). This equates to a target monthly distribution for the remainder of 2022 of £0.00467 per share paid monthly, or £0.05602 per share, per annum.
This latest increased Target Distribution represents a 5.4% increase on the Target Distribution announced on 28 April 2022. The new Target Distribution will, for the remainder of the year, represent a level which is 19.7% higher than the total dividends paid in 2021.
These dividend increases reflect principally the Company's exposure to rising short term USD rates and not changes to the portfolio risk exposure or portfolio composition. The Board expects that the increased dividends will remain fully covered by net revenues earned”
Like SMIF it sticks around 90p share price in normal market conditions, so similar possible 30% capital gain in time on top of that big dividend.
Again dividend paid monthly.
HENDERSON HIGH INCOME HHI 153p
Discount 3%. 7% dividend paid quarterly. No dividend increase so far this year.
AA4. AMADEO AIR FORCE PLUS. 34p
It’s much higher risk than the other 3. Leasing aircraft to Thai Airways and Emirates.Too high risk?
16% dividend AND they’ve just INCREASED it!
Here’s their explanation on that increase:-
AMEDEO AIR FOUR PLUS LIMITED (the "Company")
Dividend Declaration
The Board is pleased to announce an interim dividend of 1.5p per ordinary share. The shares will be marked ex-dividend on 13 October 2022 and the dividend will be paid on or around 31 October 2022 to shareholders on the register as at the close of business on 14 October 2022.
The Directors have noted the continued improvement in hours flown by the Company's aircraft operated by Thai Airways, resulting in the power by the hour rental receipts being higher than anticipated. In addition, with the power by the hour rent from Thai Airways switching to fixed monthly rent from 1 January 2023, the Directors believe an increase in the dividend is appropriate.
Note that AA4 is on a whopping 63% discount to NAV. Despite that the share price is up 60% over 1 year.
Dividend paid quarterly.
VPC SPECIALITY LENDING INVESTMENT TRUST VSL 82p
23% discount to NAV. 9.75% dividend paid quarterly. Share price down 3% over 1 year but up 45% 3 years.
Dividend paid quarterly.
I also hold several Commercial Property Trusts that have fallen heavily in the recent turmoil and are also paying dividends up to 10% and are on discounts as high as 45%! While Property Unit Trusts have to resort to locking in their investors when too many want to sell, Commercial Property Investment Trusts never have to do that and instead simply go to extreme discounts that can provide great buy opportunities. Unit Trusts are SO inappropriate for investing in Property.
The aic website is superb for all Investment Trusts. This is a link for VSL and for the other Trusts in the sector. Easy access to latest announcements/fact sheets, dividends, top holdings and performance info etc. Easy to check all of them in each sector too.
https://www.theaic.co.uk/companydata/0P00015JML
and this link for the likes of Twenty Four Income:-
https://www.theaic.co.uk/compa...
This is very useful and definitely not inappropriate. Thanks.
Thank you, this is great food for thought for mum's Pension (ISA), only challenge I have is that IWeb took Twentyfour Select Monthly Income Fund (LON:SMIF) off their dealing list, as they said it was inappropriate for individual investors. I only found out when trying to top up at lower values that they had stopped this.
Same applies for NB Global Monthly Income Fund (LON:NBMI) and Amedeo Air Four Plus (LON:AA4)
Maybe need to move the money to somewhere better with more range...
Cheers
Tommy
Tommy
Apologies for the late reply. That’s nonsense. Investment Trusts are generally much safer investments than single shares. Every competent broker lets their clients buy and sell them, and trade them exactly the same way and with the same dealing charges as for single shares.
The biggest Investment Trust is in the FTSE100 and several are in the FTSE250.
Also, look at the Stockopedia scores for each Trust, including Twenty Four Income and see that they often score well.
Yellow Cake (LON:YCA) statement an interesting read for anyone following nuclear / Uranium developments. The current Yellow Cake (LON:YCA) price of 436 compares to an assets value of 471.
@RDHowarth. What do you make of the broker forecast (per Stockopedia) for Yellow Cake (LON:YCA) of a £5m loss in 2024?
Not much tbh I think the numbers look a little rogue. Given that all the company does is buy U3O8 mainly from NAK Kazatomprom AO (LON:KAP) Id say trading numbers will obviously reflect NAV movement. Im not sure where this negative number comes or whether its relevant. There are rinky dinks in the way commitments roll off with guarantees etc that can affect NAV negatively from time to time....but Im afraid my approach is just to focus on the price of U3O8 and the NAV discount/premium.
At the moment the market has strategic value and this isn't reflected in a discount. In the future Sprott and Yellow Cake (LON:YCA) will be sellers....I figure they will start to recycle old stock to utilities when demand is there. They have pretty much mopped up the spot market in terms of surplus thus far. My personal thinking is I don't need to worry too much until U3O8 price is north of 100... in $ .... since that still offers decent upside Im in the sit and wait camp. Geiger Counter (LON:GCL) (illiquid) and NAK Kazatomprom AO (LON:KAP) (Russia risk) have lagged a fair bot this year but the U3O8 has been steady.
I will just alert you to the fact that Sprott have said they will NOT be selling Uranium into a rising price. Their strategy is simply to accumulate uranium at NAV and earn management fees from it while hoping that the price will go parabolic if a point arises when demand outstrips supply. The management were unable to articulate an 'endgame' and I would speculate that if they were preventing the operation of nuclear power stations one might expect the US Goverment to intervene.
Can't vouch for Yellow Cake (LON:YCA) but Sprott are probably permanent hoarders (at least for any investment horizon)...its the constitution of the fund and they do the same with their other physical asset funds...
...buy hey, I'm a uranium bull with a significant exposure to area (mainly equities but some SPUT and Yellow Cake...I prefer the former as got more dynamic liquidity mgt). Very volatile and cyclical space and not an area to own forever...but I've been in for 5 years, and with scale since the covid sell-off and I believe the opportunity is only in early innings. High risk tbc!
Both Sprott and Yellow Cake have no economic purpose other than to squeeze the market. This may get you to $100/lb but probably no more and it would be best to sell into that rise. The Kazaks are able to produce at <$10/lb ( and are still 10% below their previous output). Nextgen (NXE.TO) will hit the market later in this decade with 30m lbs and will produce at about $10/lb. McArthur River produces about 15m lbs. So the biggest producers would be producing at about $10/lb but the bulls think the previous high of $140/ lb can be taken out. One has to set that figure against the fact that every other potential project in the world is economic at $75/ lb. The bull case rests on either a mania gripping the market or a very big fund throwing say $2bn at Sprott and being able to get out at a profit in the aftermath. You also have to remember that the Kazaks can get an ISR into production in about a year so are able to ramp up quickly to meet demand.
There will be a lot of crap junior miners that could rise if the price increases, but you would still be left with an asset designed to mug you off rather than a productive resource. The whole area is spiv central.
Yellow Cake (LON:YCA) is not a trading company, it merely holds physical uranium. Profits or losses not applicable so wouldn't pay too much attention to that.
Sylvania Platinum (LON:SLP) anyone, (obvs not Paul or Graham, come back Jack)
Results out today, and if my phone calculator plus my working out are correct, I find
Production up 1.8%
Net Revenue up 23%
EBITDA up 57%
Cash in bank up 14.26% , $138m in bank for a $270 market cap
Just over 8% dividend on its way next month
What is not to like, what have I missed?
could also add that the price retreat since it went ex-div makes for an attractive entry point on a likely yield of 9%+. Broker TP of 150p also in the mix.
I've long been a fan of Sylvania Platinum (LON:SLP) and bought some more before it went ex div. Nice set of results today which will likely see the share price reach 100p again soon
Seems like the management of Sylvania Platinum (LON:SLP) are doing all of the right things - medium and longer-term expansions/explorations to keep the company growing whilst also navigating well through the shorter-term raw-material price fluctuations and production challenges.
We got a lot of this info a couple of weeks back on the TU, but it's great to see the numbers in greater detail and their commentary.
I really like the long-term prospects and suspect that last years rapid rise to £1.50 and subsequent decline was short-term trading.
I see them as a long-term holding with a great dividend and took the opportunity to top-up a couple of times recently on the down days.
I also hold Jubilee Metals (LON:JLP) but I don't hold them in as high regard. Whilst they are expanding much more into copper (which could be a positive) they don't provide any dividend and I am slightly more wary of their short-term results.
I appreciate much of this is dependent for both companies on the price of their key material output prices, but I see a big upside once we can get through the current global challenges and am happy to hold through the short-term gyrations.
I hold but one always have to worry about South African politics.High crime and frequent strikes.Oh hold on am i taking about the New UK going back to the 70's?
Am a long term holder of Sylvania Platinum (LON:SLP) and over the last year or so have transferred all my holdings into my ISA and is one of my biggest holdings think they are a well run company with a very good management who have done a good job over the last few volatile years they throw Off lots of cash have a large cash balance and are willing to return money through large dividends both regular and one offsand their webinars on investor meet the company are well worth watching for anyone holding or looking to hold the company https://www.investormeetcompan...
Also as others have mentioned are also looking in the medium term and longer term on increasing production
So agree with you Bob can’t see anything not to like myself
Sylvania Platinum (LON:SLP) I hold. it is my largest holding at about 18% of portfolio. And have held since November 2019 though I have sold some along the way including in my March 2020 meltdown.
You haven't missed anything in my opinion GloucesterBob and you state all the salient points.
There was a good note out this morning from Liberium (available through Research Tree), which is helpful in seeing future likely figures.
ST in the IC is a fan (I often take this as a negative but will go with him in this instance).
The stock is up 3.95% this year (which puts in a small group in the small cap space) and will have received 10.25p in divis this calendar year.
The share price tends to be driven to some extent by the Rhodium price and that has been soft since the peak back in early March. See images attached.
New car sales have impacted the demand but Liberium is of the opinion that new car production is about to pickup.
Against this you have to weigh the possible political uncertainty of a country like South Africa, enviromental issues will hold back some ESG types (not me), and the possibility that they will run out of raw material and it is the latter which weighs, IMO unfairly, on the price.
I won't be topping up for obvious reasons but if I was younger I could see me putting a 1/3rd of my pf into this. Sorry if this seems rampy, it is not meant to be.
Regards
Michael
Sylvania Platinum (LON:SLP) Against this you have to weigh the possible political uncertainty of a
country like South Africa, enviromental issues will hold back some ESG types (not me), and the possibility that they will run out of raw material and it is the latter which weighs, IMO unfairly, on the price.
You also have to weigh:
In the end it's a small mining related stock. No matter how good it looks, it's high risk.
timarr
Sorry if this seems rampy, it is not meant to be
Not rampy at all. Simply comes across as rather rose tinted.
For me Sylvania Platinum (LON:SLP) holds little attraction due to country risks and is in a volatile sector I'd rather avoid.
The South African economy is weak, politicians are corrupt and they have an energy crisis much worse than Europe.
I have friends in Cape Town where they continue to have multiple daily power cuts (known as 'load shedding') and has become a way of life. Basket case country.
Hi Michael,
Sylvania is a great company that will generate amazing free cash flows for many years and any expansion will easily be funded from these flows (very important for any company).
Do not listen and do not get carried away about people claiming that South Africa has political uncertainty ( it is certainly more stable than the UK’s ).
Hold on to it and enjoy the future dividends, the special dividends and the share buybacks.
Yiannos
I also hold a significant (for me) amount of Sylvania Platinum (LON:SLP) in my portfolio and have been very happy with its performance. It's risky of course but I think achieved and prospective returns are a very fair reward for accepting that risk. Realised profits, in the form of dividend distributions, have more than covered my initial outlay ... in addition to substantially greater paper gains. The company continues to perform well and I am very happy to continue to hold as one of my largest investments.
That said, your tolerance of concentration risk is clearly much greater than mine. Sylvania Platinum (LON:SLP) represents about 8% of my total portfolio and if this rises above 10% I will trim and take some profits to invest elsewhere when things look propitious. I am pretty confident about SLP but I still don't want to keep too many eggs in any one basket. Experience tells me that my own confidence level is a somewhat imperfect indicator of how any stock will actually perform.
Shoe Zone
How disappointing for a management to fail to engage with PI .
That’s the biggest red flag of all and makes them totally uninvestable .
Probably a good buy, but there are plenty of good buys and does anyone actually want to own and support part of a company that doesn’t want to talk fo you ?
It’s not a company that remotely interested me anyway but why would anyone want to support s company that acts like this .
Shoe Zone (LON:SHOE) going ex-dividend this week, Stocko likes it. I see a wide spread but reducing debt and look forward to seeing an SP of 200 p+ . I hold.
I’m invested quite heavily and have luckily seen this investment make up for a lot of other losers so I would have loved to hear what the management have to say. That said I’m fairly sure a couple of brothers are in charge and family style investments seem to be fairly secret squirrel…
Shoe Zone (LON:SHOE) management are odd. I remember being struck in the depths of the pandemic, they hid a trading statement in a "Notice of Results" announcement. And also released it at 11am. Looking back at my notes, it was in Feb 2021.
My gut still tells me that the business isn't worth investing in, despite the good trading over the last few months.
And when I say "trading statement" I actually meant a profit warning, so it wasn't an innocuous burial of important info.
What are you talking about?
SHOE is one of the best run retailers in the UK with a highly focused super impressive management that own 60% of the stock, it is one of the best performing small cap shares of the year.
Just because they decide to spend their time not promoting the company on a relatively new and unknown podcast makes them 'uninvestible' and 'the biggest red flag of all'?
Sorry, is it Halloween or April Fool's Day today?
For me yes totally .
I have 8 positions in companies that are all significant .
As a company owner I expect to be able to have engagement with that company .
If a company and its senior management do not want to engage with PI then I am not interested .
It’s my new golden rule and it also I find makes investing more rewarding as you start to act and feel like a company owner .
I am putting my hard earned pennies into long term investments and I want to understand the company and have the opportunity and openness to engage with it .
So it’s not Aprils fools day and I think it’s a perfectly valid thought process .
I have 8 positions in companies that are all significant
I completely support your discipline in excluding from your investment universe any company that does not make you feel like an owner. But, look at this the other way round: is a position size that is “significant” to you in percentage terms also significant to the board of every small- and mid-cap?
I invest in mid and large caps chiefly and have to sit in line waiting for analysts to parse their privileged access into reports. I have no expectations of extra access to their boards.
For me a negative is being too keen to drum up support for a jam tomorrow story. Getting on with managing the business rather than trying to talk it up is a positive. If you want to know more you can ask and see what reply you get or buy a share or two and turn up at the AGM and seek to know more.
Hi planet x,
That's a bit over the top!
I've found with lots of companies which are owner-managed, they often ignore small shareholders, and just get on with running the business. So I wouldn't read anything particularly negative into it. They're not interested in promoting the shares, which can be seen as a good thing, or a bad thing, depending on your point of view.
Ultimately what matters are the numbers, and SHOE is performing very well indeed, so I remain positive about its shares. Them not wanting to do a podcast is mildly disappointing, but nothing more than that.
Regards, Paul.
Completely agree, I wouldn't read to much into it. Different people take different approaches....
Well it might be disappointing that they don't want to engage with me but it's more important that they make money for investors. I've had investments in the past where I had very interesting and informative email correspondence with the founder CEO. Sadly, the companies went bump.
Everyone is free to apply whatever criteria they want .
There are thousands of companies to invest in so pick and choose as you see fit .
I had questions of Wynnstay a few months ago regarding a fund raise at slight discount so I wrote with my concerns . The CFO wrote back sane day out of hours with a measured , respectful and considered response . Box ticked .
I was also CEO of a not insignificant business so I understand that day to day interactions with shareholders is not possible in many cases but equally investing in s business where there are large founder holdings come with risks so very important to establish management work for shareholders and not a micro cap l lifestyle business for themselves .
Can’t see anything wrong with the criteria I apply and with such a tight number of holdings (8) in companies on AIM I think it important .
For example I’m over 10% of holders technology and if the majority shareholder / founder wanted to take it private or strip it of cash in excessive pay I’d be pretty screwed, so I asked him some very direct questions at AGM which he answered perfectly , so box ticked .
Anyway each to their own, I’m actually holding my own this year to date so it is working ok for me .
Just because they turned down an interview with Paul doesn't necessarily mean they 'fail to engage with PIs' , so I wouldn't be that dismissive. They probably get all sorts of requests and can't accept all of them. That said, I don't think I've seen them on Investor Meets Company or similar sites, so perhaps they do need to up their game on that front.