Small Cap Value Report (Mon 4 Dec 2023) - ITM, CRL, TON, CSFS

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Thin pickings today -
Summaries
ITM Power (LON:ITM) - up 8% to 55.5p (£342m) - Trading Update (in line) - Graham - RED
A confident update from this renewable energy company. Expectations for FY April 2024 were very low to begin with, but the company says it does expect to meet those expectations and should finish with £200m (maybe more?) of net cash. But it remains highly speculative.
Creightons (LON:CRL) - 22.5p (pre-market) £15m - Interim Results - Paul - AMBER
H1 results reveal a modest profit and fairly sound balance sheet, so will probably come as a relief to existing holders, after the shock sacking of its long-serving CEO last week. There's still a lot to do, to rebuild to anything near previous levels of profitability. So no strong view either way from me.
Titon Holdings (LON:TON) - unchanged at 80p (£9m) - Trading Update (in line) - Graham - AMBER
This nano-cap provides ventilation systems and window and door hardware. It has a remarkable track record of dividend payments stretching back over 30 years. Current trading is poor, however. I like the story but the underlying quality of the business seems limited.
Cornerstone FS (LON:CSFS) - up 30% to 15p (£9m) - Trading Update - Paul - GREEN
My first look at this tiddler, a payments/forex company. What's interesting, is that a series of out-perform updates have set it up to report a real profit this year, and hence should reduce the risk of a placing to raise more cash, as it looks a bit tight. I like turnarounds, and this looks promising, after its over-priced float flopped in 2021.
Paul’s Section:
Creightons (LON:CRL)
22.5p (pre-market) £15m - Interim Results - Paul - AMBER
Creightons manufactures branded shampoo, conditioners, fake tan, and lots of other products here which are a mystery to most men.
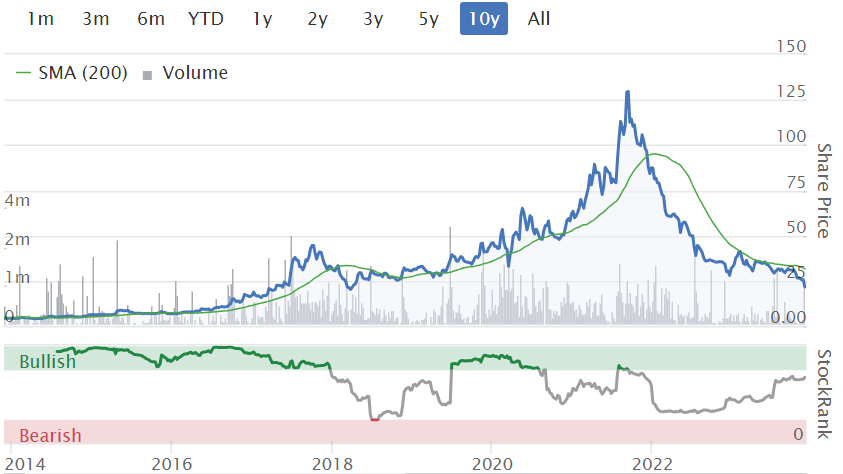
Shares were a stunning, and major multibagger as you can see below on the 10-year chart.
This has unravelled in the last couple of years, with the strong track record of profit growth coming unstuck, blamed on the energy crisis, supply chain constraints and input price increases. Surely there must be more to it than that? Some investors have questioned the acquisitions strategy, which doesn’t seem to have worked.
Most other companies are recovering from these temporary supply chain problems (eg McBride (LON:MCB) ). The abrupt sacking of the long-serving Managing Director last week (who was not thanked) is another signal that something’s not right here.
Although I’m also intrigued as to whether performance could recover back to previous highs, in which case suffering shareholders might have a renewed bull run to look forward to maybe?
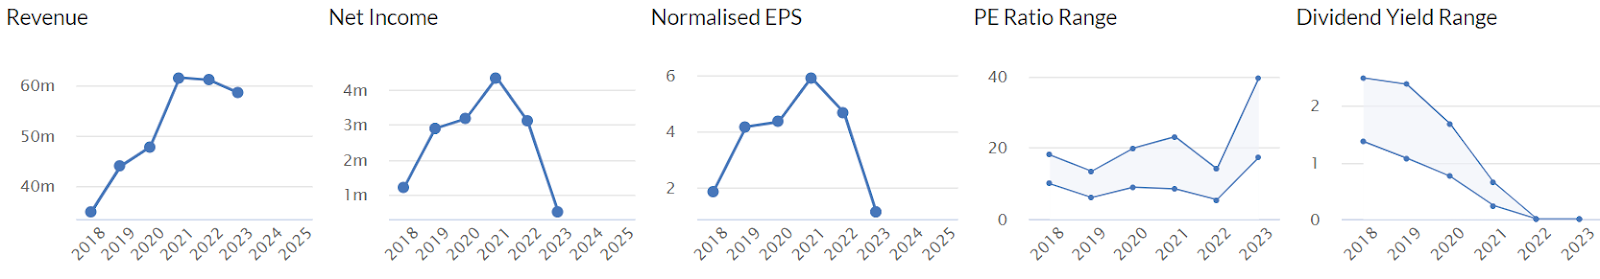
As you can see below, profitability has crashed, after a previously good track record. Things are not helped by the fact that Creightons doesn’t get any broker forecasts out to the market, so we’re in the dark. Maybe the new CEO could address that as a first step? Chairman William McIlroy is shown as being Chairman and Chief Executive now.
Interim results - 6 months to 30 Sept 2023.
Revenues - did alright at the larger Private Label division, up 10% to £12.3m, but a large 37% fall at the Contract division saw the total negative 7% to £27.6m group revenues.
Gross profit margin increased to 42.2%, from 40.4% in H1 LY - supply chain problems easing maybe? This is consistent with historic, pre-covid gross margins, which were in a range 39-42%. So further margin increases could be difficult to achieve.
H1 EBITDA of £1.4m and £0.5m pre-exceptional operating profit are both improved but still quite low.
Profit before tax is only £302k, although improved from the £(359)k loss in H1 LY.
Historically, there doesn’t look to be any obvious H1:H2 bias to profitability.
Going concern statement is clean, saying it could survive even in a downside scenario.
Balance sheet - looks OK to me - no evidence I can see of financial distress.
NAV £25.9, less intangibles £13.8m and deferred tax of £2.9m, gives my adj NTAV of £15.0m.
It has £6m of bank borrowings, less £1.7m cash = net bank debt of £4.3m, which seems reasonable. Note that £2.4m of the debt is a mortgage, so there will be an offsetting freehold asset, which makes me much more comfortable about the bank debt. I wonder when the freehold property was last valued? Maybe some upside there?
Inventories £10.4m and receivables £12.5m are tying up a fair bit of working capital.
Cashflow statement - it’s generating enough cash to pay for the modest capex, but there’s nothing left over to pay any divis.
So the business needs a significant improvement in cash generation before it can pay meaningful divis again. This is my main concern with this share.
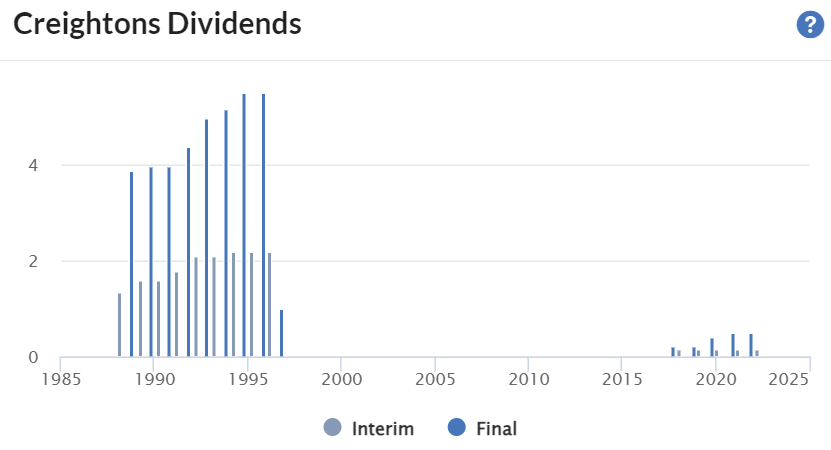
As you can see above, meaningful divis stopped in the late 1990s, and only returned on a small scale more recently.
New management need to decide if this is a growth company, or if it will focus on paying divis in future (once debt has been repaid, I hope)?
Share options - just to flag that these are excessive. The notes show 68.4m shares in issue, and 9.14m of potential dilution re share options. Personally I don’t like to see anything over 5% in dilution from share options, so this 13.4% is completely over the top, and indicates (former?) management focused on themselves rather than outside shareholders.
Outlook - there’s no separate section, but plucking some forward-looking comments from other sections -
The Branded division has been challenged in the current year. There has been a significant decline in a key export market which has suffered a sharp economic downturn. We anticipate this will start to recover during the second half as orders are starting to flow through again.
As highlighted last year, the Contract side of the business continues to see reductions in order demands. This is due to brands being overstocked and therefore, requiring less manufactured stock during 2023. However, both the Private label and Branded divisions continue to gain momentum.
We remain committed to seeking further cost and overhead reductions and to restoring margin and overall profitability to previous levels…
Once the financial stability has been successfully achieved, the Group's focus will be to pursue new growth opportunities through continuing to invest in research and development, improving manufacturing efficiencies and expanding into new markets.
The margin recovery and pro-active cost reduction measures we have taken will continue to deliver an improved performance in the second half of the year.
Paul’s opinion - I think this depends on whether you’re an existing shareholder (in which case I would be feeling relieved at these numbers, which show the business stabilising), or a potential new shareholder (where I’m not seeing anything much of interest to make me want to get involved).
It sounds like a business that’s not been very well managed, hence why profitability has crashed in the last couple of years, as supply chain problems hit. There’s not a lot of evidence from today’s numbers that these issues have been satisfactorily resolved - despite all the remedial action, H1 profitability is negligible.
So for me, I’m neutral on CRL shares, AMBER. I don’t see any particular downside risk, with an OK balance sheet. Upside might come from new management. But is it a great business? No.
£CSFS
Up 30% to 15p (£9m) - Trading Update - Paul - GREEN
As it’s quiet today, and this share is up 30%, I’ll take a quick look at it (we’ve not covered CSFS before here).
It’s one of many forex/payments companies, which I find difficult to distinguish between, as they all seem to make similar claims about having proprietary tech, offering great customer service, etc.
CSFS floated in April 2021, and predictably has been a poor IPO, losing about 90% of its float value by end 2022, although it's put in a partial recovery this year.
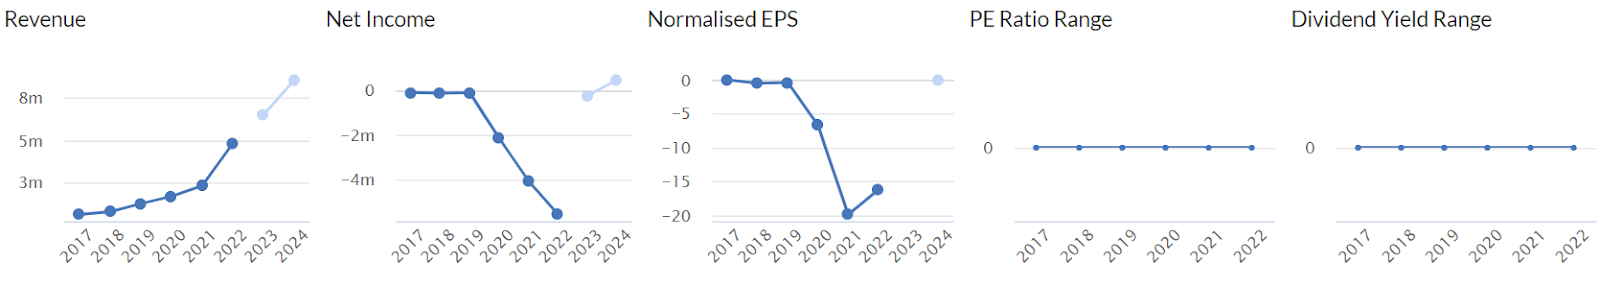
The revenue growth below has been impressive, but that came with heavy historic losses. Note that the lighter blobs below, indicating a move to breakeven, are only broker forecasts, so could be pie-in-the-sky, as they often are at this end of the market.
Reviewing the recent newsflow -
11/7/2023 - Positive TU, expects maiden EBITDA profit. New sales team doing well.
12/9/2023 - InvestorMeetCompany webinar from mgt (recording available).
12/9/2023 - Interim Results - big improvement, now c.breakeven. Cash tight, but claims to have enough. Note £2.2m loan notes. Ahead exps FY.
24/10/2023 - Ahead expectations trading update.
4/12/2023 (today) - another ahead (“materially above”) of expectations update.
The CEO sounds pleased, and I like the use of “operational gearing” -
James Hickman, CEO of Cornerstone, said: "I am pleased to be able to report that we are continuing to experience excellent trading momentum. This reflects the actions that we have taken during the year to enhance our sales team and expand our offer, such as by broadening the range of currencies and countries where we can transact.
With a highly scalable platform, along with careful management of our cost base, we are now benefitting from the operating leverage within our business as the increase in sales is driving even stronger growth in adj. EBITDA. Accordingly, the Board continues to have great confidence in the future of the Group."
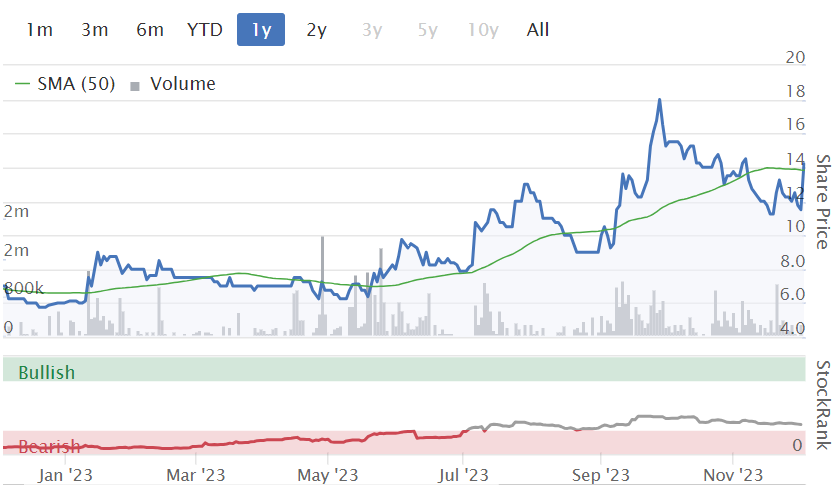
Broker update - many thanks to Shore Capital, which issues a nice update today. EBITDA here is actually quite close to PBT (proper profit). It has significantly upped forecast PBT for FY 12/2023, from £0.1m to £0.7m. That’s a very significant upgrade, I think we might have spotted something interesting here - although the market got there first, with a decent rebound in the share price in the last year -
Paul’s opinion - I like turnarounds, and moving from persistent losses into a worthwhile profit this year FY 12/2023, strikes me as very much worthy of more detailed investigation. So I’m flagging it up here, so you can take a more detailed look yourself.
This year’s numbers are assisted from a £200k profit on a dormant subsidiary, but even so, there should be a clean profit this year.
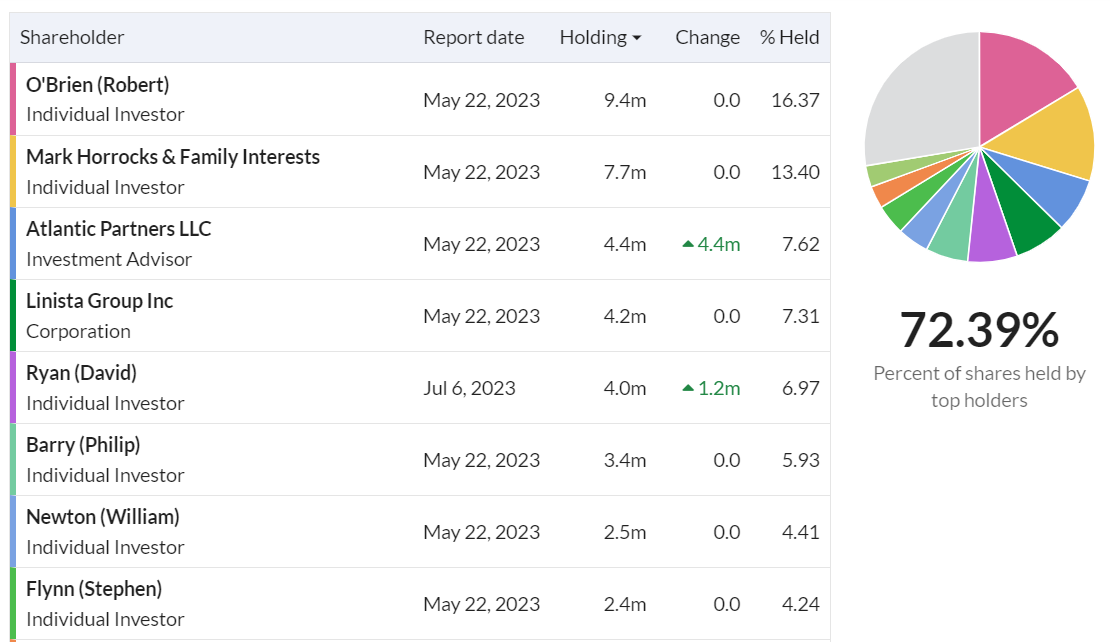
Shareholdings look mainly individuals - management maybe?
Overall, dare I go green, given the weakish cash position? Yes, I think so, as the latest forecasts show it profitable & cash generative now, and we’ve just been told that it’s trading well. So the risk of a placing could be receding. Overall then, although it’s small and illiquid, I’ll push the boat out with GREEN, due to the series of out-perform updates, and a financial position that looks OK now that it’s moved into profit & cash generation. Any views from readers, as it’s a new one for me?
Graham’s Section:
ITM Power (LON:ITM)
Share price: 55.5p (+8%)
Market cap: £342m
The flurry of news updates this morning isn’t too thick, so I’ll take a quick look at the trading update from this one.
ITM Power is not a company I write about or study regularly; here are its headline numbers for recent years:
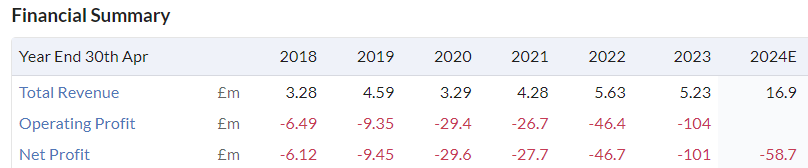
Losses twenty times larger than revenues don’t usually make for “value” investments!
Company description:
Headquartered in Sheffield, England, ITM Power designs and manufactures electrolysers based on proton exchange membrane (PEM) technology to produce green hydrogen, the only net zero energy gas, using renewable electricity and water.
If you know what any of this means, please let me know. I’ll stick to the financial figures.
Here are the bullet points from today’s H1 trading update:
“Revenue of £7.5m (well on track for full year guidance of £10m-18m)”
Note the very wide range of possible revenues.
“Adjusted EBITDA loss between £22-23.5m (trending well against lower end of full year guidance of £45-55m)”
“Net cash at the end of the first half of the year of £253.7m (against full year guidance of £175-200m), with an outflow in H1 of £28.8m, already reflecting the very early effects of the significant progress against our 12-month plan in H1”
And so:
Given this reassuring performance we confirm our full year guidance.
I agree that the performance seems to be very good, relative to guidance. However, I’m not sure that’s really saying very much!
CEO comment excerpt:
The first 6 months of the financial year from May to October already paint the early picture of a new ITM, surpassing the full year revenue of each of the last two years by about 50% in just the first half of this year. We are pleased with the improvements achieved across all areas of the company, many of which have a positive effect on how we manage cash and scrutinise capital spend.
Graham’s view
I recommend taking a look back at Paul’s comments in August on ITM’s full-year results.
In those results, the company took provisions for “inventory and contract losses”, but still finished the year with inventory of £59m, a remarkable figure given the current rate of revenue generation.
Consensus forecasts suggest that revenues will leap higher in FY April 2025. I would say that revenues need to leap higher very soon, or this inventory balance surely will have to suffer more writedowns?
FY April 2023 results recognised £23m of inventory losses, with the explanation:
The losses originate from continued iterations of product designs during manufacturing, together with some manufactured products being considered obsolete.
More positively, the company will hopefully finish the current financial year with net cash in the region of £200m, or over half the current market cap.
Given the cash balance, this is certainly not a stock that I would consider to be suitable for shorting. So I wouldn’t say that I am outright bearish on this one. But I’ll maintain Paul’s RED stance, as we know from experience that blue sky stocks rarely succeed.
Titon Holdings (LON:TON)
Share price: 80p (unch.)
Market cap: £9m
This is “a leading manufacturer and supplier of ventilation systems and window and door hardware”. It sometimes crops up in discussions among nano-cap investors.
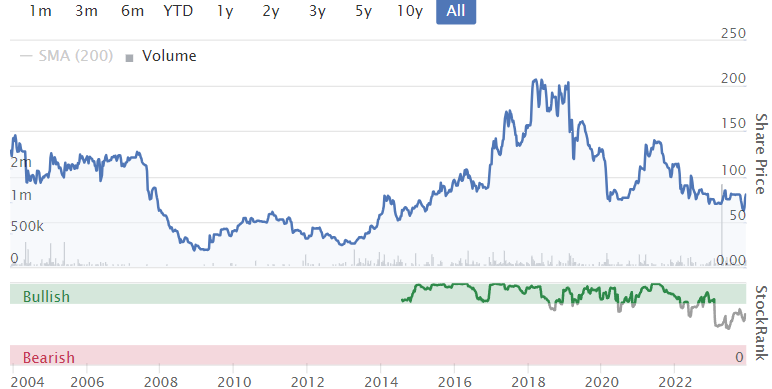
Long-term performance has been mixed:
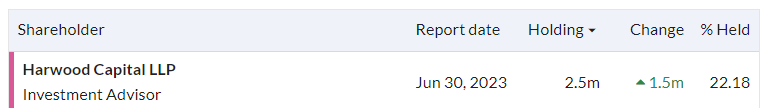
And I see that Harwood is now a major shareholder:
Today we have an update for FY Sep 2023 and an outlook for FY Sep 2024.
Sep 2023:
Trading in UK and Europe through to the end of FY22/23 surpassed the Group's expectations most recently set out in its interim results on 19 May 2023. However, Titon's South Korean business has reported to the Group a further decline in statutory profitability for FY22/23, due to year-end taxation and other provision adjustments, which will increase the reported FY22/23 Group loss before tax compared to the Board's prior expectations once Titon's share of the losses of the Group's associate, Browntech Sales Co. Ltd, are taken into account.
According to Titon’s investor relations website, the joint venture in Seoul “has captured over 75% of the market share for natural ventilation in the new build market in South Korea”.
The taxation “adjustments” in Korea that have impacted profitability for Titon could really use a fuller explanation. I presume we will get that in the full-year results.
A little bit of digging tells me that corporate tax rates in Korea have in fact been cut this year.
But Titon’s Korean business seems to be loss-making, and so tax cuts wouldn’t help it - and could even hurt its statutory results.
Balance sheet - cash of £2.2m, no debt.
Sep 2024 outlook:
Trading in the UK and Europe in the first two months of FY23/24 has been in line with the Board's expectations. Titon currently expects the UK and European business to report a loss before tax for H1 FY23/24 due to the impact of the decline in new build activity in the construction market on the Group's first quarter trading. However, the Group expects to return to profitability in the UK and Europe from the second quarter of FY23/24.
Titon Korea is expected to remain loss-making in FY23/24 due to the continuing challenging conditions in that market, and the Group is taking steps to progress its plan to streamline the Korean corporate structure and operations.
Not a very encouraging outlook statement, it must be said. But hopefully a realistic one!
New CEO: joining in April 2024.
Graham’s view
I want to like this one but it has been around for a long time and the best that can be said about it is that it’s a steady performer. It doesn’t dilute its shareholders, and it has relatives of its founder on the shareholder register, plus one on the Board (a son). So you would hope and expect to see good continued stewardship of shareholder value.
It also seems that Titon has paid a dividend every year for several decades, which is remarkable for a company of this size. Although the last one (0.5p) was really just a nominal payment to keep the record going, I think.
So yes, I think it’s worth researching this stock, for anyone interested in nano-caps.
However, I’m not sure about the company’s growth prospects and quality. Revenues seem to be stagnant, and margins and returns have been modest. So I’m neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
There's a high volume of trading this afternoon at Oxford Metrics (LON:OMG). The recent TU (Oct 25) said the results would be out tomorrow (Stockopedia still says 11/12/23). The TU said
"The Group expects to report revenues of £44.0m and an Adjusted PBT* of £6.3m, both ahead of current market expectations* for the financial year. The Group finished the year with a robust cash position of £64.8m and no debt.
Following the Group's strongest-ever first half performance, momentum continued into the second half driven by a particularly strong contribution from the Engineering and Life Sciences segments. Vicon continues to see ongoing demand for smart sensing into yet more applications from new and existing customers alike and the new Vicon Valkyrie system launched late last year continues to stimulate
demand.
The Group as a whole remains in a strong financial position which enables the business to pursue its organic growth and M&A objectives in the year ahead.
The Group starts a new financial year with a solid order book. More detail will be provided when Oxford Metrics announces its Preliminary Results for the financial year ended 30 September 2023 which is expected on Tuesday, 5 December 2023"
OMG subsequently bought IVS for about £8m of their 68m cash and 1,000,000 shares on November 1st. That still leaves OMG's net cash around 50% of their market cap.
Today's trading suggests that some investors anticipate further good news tomorrow (I hold).
Hope so, should be 100p at least
Link for Plexus pos grip technology that stops methane emissions, greenhouse gases:-
https://www.plexusplc.com
Anyone have any thoughts on Cake Box Holdings (LON:CBOX) rising by 5% ish this morning on an enormous volume 360,000 compared to average 85,000. Australian a big buyer. Is there a bid in the offing (sorry no pun intended!). They obviously like cream cakes down under after their world cup win!!
Braemar (LON:BMS) Not from today, but the webinar given by management last week. FY23 & H124 results presentation & Q&A. Video & podcast.
It strikes me as very difficult to guess which will be a winner in a field of alternative green technologies. I hear good things about ammonia usage due its transportability, its energy density, and wide availability but as ever with these things there is always a catch.
Also, I note there is talk of the world entering a period of peak emissions after which it will start to fall (though its not certain whether the projected Global target 1.8c increase will be breached enroute) and China despite opening more coal powered stations, also reaching peak emissions, after rapidly 'greening' its environment infrastructure.
So quite a confusing background, but generally encouraging despite much overblown language heard from time to time.
Effect of dilution:
https://x.com/chriswmayer/stat...
Nasty stuff, dilution. Must double-down in timely steps.
Avation (LON:AVAP) For those interested in the aviation sector, Alaska Air (NYQ:ALK) is planning on taking over Hawaiian Holdings (NSQ:HA) (announced this morning).Who knows if antitrust is an issue now and with Biden in power..?So more potential consoIidation in the US aviation market.Seems like a pretty good deal for Alaska Air (NYQ:ALK) .
I see everybody(?) chasing the rainbow (Plexus Holdings (LON:POS) ) which I don't hold. Meanwhile, gold miners in general are rising on the back of the price of gold.
https://www.nytimes.com/2023/1...
Plexus Holdings (LON:POS)
Hopefully Plexus Holdings (LON:POS) will be a big beneficiary of the commitment made by 50 countries at COP28 to reduce their methane gas emissions. Article in the FT at the weekend, just in case you missed it.
Plexus Holdings (LON:POS) sorry if i missed it but where on the Red/Amber/Green scale does this beaut go?
All colours
Take your pick.
Good one .... raised a chuckle here anyway.
If you had been to Mello last week, you would know that Paul considers Plexus Holdings (LON:POS) gold, and that was before the weekend's news!
Feels like quite a few sheep blindly following Paul on this one. Don't get me wrong, I wish everyone the best of luck, but be honest and ask yourself how well do I really understand this company?
There is nothing worse than people just pumping up their holdings without any meaningful financial analysis or future numbers in front of them to show or share with us.
There was a post in the morning about Biden’s new plans BUT why on earth will they choose Plexus? And if they do what numbers are we talking about?
There are far bigger and more well established AMERICAN companies offering exactly the same product. They have also the financial means to execute any big orders as they are in billions their market cap.
My calculations and on a best revenue scenario of £30-£35m this company will not be making any meaningful profits to distribute to shareholders!
I can’t even imagine if the price of oil falls even more as well what are the impacts on the whole industry.
The way some people are talking about this stock is that they have inside information and this is not acceptable by any means.
But as you say and as I have said before, this is not for me, but good luck to all holders.
Perhaps Plexus Holdings (LON:POS) would be better on a separate thread, as it seems a bit specialist for the small cap report?
I think this is the correct thing to do, but this is up to the management to decide.
The point I think with Plexus Holdings (LON:POS) is that they have the best technology in the world to stop methane emissions, greenhouse gases with their pos grip technology.
No other company worldwide has this technology.
Link to it:-
https://www.plexusplc.com
You might well be right, but unless I really understood the technology (eg I worked as an engineer in the oil industry) then I wouldn't want to put any money on this, so definitely not for me but hope it works out for you.
It's not difficult to understand Bouden54. Start with reading about it on the link above.
Actually Johnnycomelately Plexus Holdings (LON:POS) is v difficult to understand….they’ve got no money..they’ve sold off their Jack-up business years ago…& with that the vast bulk of their rental assets that represented over 90 % of their income back in the day..but somehow we are supposed to believe they have the *only* solution to wellhead methane emissions….it’s possible..but I’d suggest a sceptical mindset might be appropriate
Best of luck to shareholders obvs
But that’s a Plexus Holdings (LON:POS) website link.
What do you expect them to say?
That they have the worst technology?
Hi Johnnycomelately,
As I posted the other day, their technology relates to wellheads. There are many other sources of emissions that personally, if I was in charge, I would address first on the basis of achieving more (greater emissions reduction) for less ($$$).
It doesn't mean their product isn't part of the solution, but it most certainly isn't the entire solution.
Regards, Jon
Plexus pos grip technology is the entire solution.
Let me explain with a simple analogy. Your kitchen cupboards and drawers get loads of wear and tear so the screws, etc., come lose. This is what happens with conventional equipment used by oil and gas companies hence methane emissions, greenhouse gases. Conventional equipment needs loads of maintenance shutdowns to overcome these problems.
With plexus pos grip technology this doesn't happen at all. Pos Grip technology equipment doesn't need any maintenance at all.
So, all oil and gas companies need to be using Plexus pos grip technology.
Plus, Plexus are back in the Jack up business with help from SLB, Schlumberger.
The link to the plexus holdings website page is to help you understand their pos grip technology.
Here it is:- https://www.plexusplc.com
Plexus Holdings (LON:POS)
Never the less, the pos grip is a solution specific to wellheads. What about the rest of the piping, separators, pumps, compressors, sampling systems, instrumentation, valves, etc. which are all possible sources of leaks and therefore methane emissions?
Then, we could talk about artificial lift wells. Beam pumps (nodding donkeys) have a rod that passes through the top of the wellhead connected to the subsurface pump. It is sealed of course, but I doubt pos grip technology is applicable in this case. The rod has to move.
Regards, Jon
Graham, re your question on ITM (LON:ITM) I may be wrong but my idiot's guide is..........Proton Exchange Technology splits water(H2O) Into water and hydrogen. The power to do so (since the process uses a lot of power) comes from renewables when the wind blows. The effect is to store the power (unlike electricity) in the form of hydrogen.
You then use the hydrogen instead of fossil fuels, where it is far more effective than electricity in powering things like buses and Lorries and the waste product is water.
And you don't need to dig up any Lithium
Blue sky ...yes, but who doesn't need a little blue sky in their portfolio, for a tiny punt on the future ? Of course it's a gamble, but some blue skies are better than others, this one has survived and is progressing
The big game changer from the basic electrolysis that we saw in basic school science is according to this Wikipedia article, that at an industrial scale operating at high currents and high gas pressure, you need to ensure that hydrogen and oxygen , like wives and girlfriends in the naval toast, never meet. The results of both can be explosive. The anode and cathode are separated by a solid electrolye which allows the flow of protons ( the nucleus of a hydrogen atom is one proton) which combine with electrons from the electrical input to produce hydrogen at the cathode. The anode produces oxygen.
https://en.wikipedia.org/wiki/...
ITM Power (LON:ITM)
"Graham, re your question on ITM (LON:ITM) I may be wrong but my idiot's guide is..........Proton Exchange Technology splits water(H2O) Into water and hydrogen"
I think you mean splits water into OXYGEN and HYDROGEN.
Yes I do !
ITM Power (LON:ITM) I'm pleased to see the progress being made here today which I think is down to the departure of the previous CEO, Graham Cooley, and the replacement with Dennis Schulz who came from Linde (ETR:LIN) having dealt with the company in the past. The presentation on Investor Meet Company website on 17th August 2023 gave us a taste of things to come, with a streamlining of product line and cost cutting measures. A telling statement on slide 11 of the presentation said 'In the last 6 months more products have left the ITM factory than in the previous 22 years combined', giving a taste of the direction of travel. This CEO has definitely given much more focus and discipline going forward and a skim of the slide deck is definitely worth while for anyone interested in this share. (I hold).
ITM Power (LON:ITM)
Cheers for the pointer to Investor Meets. Seem a professional bunch, and encouraging to look at the list of shareholders. 16% held by Linde, a large industrial gas supplier who own British Oxygen. Big chunks held by Lord Bamford of JCB who make a hydrogen powered digger and Peter Hargreaves of Hargreaves Lansdown who make money. Ceo said company is in transition from an R&D company to a multi national manufacturing company. They seem to have a following wind.
The perfect stock DOES exist! The much-discussed Supreme (LON:SUP).
Paul and Graham,
Could you please put the Green colour coding definition back as it was. The SCVR is coded based on company financials so now making it based on opinions of value, turnarounds, overdone etc makes it of less value. You always put these kind of views in the write up anyway but please just not in the colour coding. Just my view but if others agree then please like.
Best Regards Andy
Thanks Andy,
Point taken, we're having a ponder.
Regards, Paul.
Colefax, illiquidity and value traps and buy backs .
Had a rethink on Colefax.
Mentioned it to Lisa Sanderson of SDG who pretty much said good “family” company .
Looks like zero ambition in this company albeit a well run steady state asset backed nice company .
I always like the share buybacks here too but just dawned on me this is reducing sharecount and liquidity in an already very illiquid stock with family members who never sell and rubbish free float
No rush really but going to be a long slow process to slowly reduce without freaking out the share price .
Schoolboy Lesson learned that liquidity is important .
There are many awards I am sure you will be nominated for this year Paul but just a heads up that you've already won the crown jewel... First place in my Spotify Wrapped 2023 for your podcast. I've heard the FT are devastated to hear they have been pipped.
On a serious note, the podcast has become a part of my weekends now and I love the balance of humour and great content. Keep them coming, ad free, throughout 2024!
Thanks BenHazz, that gave me a good chuckle, and it's nice to be appreciated!
I'm amazed that I've managed to create the podcasts every weekend this year, but they're really enjoyable to do, and (sounds conceited!) I actually enjoy listening back to them myself! It's a good way to recall the good stock ideas of the week, which can otherwise quickly be forgotten.
The number of listens is going up, and has reached about 2,000 per week, which I'm delighted with, given that it's niche and rather dry content (hence a bit of silliness to perk it up a bit!), and given that we've endured a 2+ years savage bear market in small caps.
Thanks again for your encouraging message, much appreciated!
Also, I would encourage anyone else to make your own podcasts if you have some interesting ideas & content you want to share. It's dead easy - I downloaded a free audio recording programme called Audacity. Then I publish the audio (unedited) via a free account on Acast - which then distributes them to all the podcast platforms. Then you need to publicise it a bit, eg on X, to get some listeners. The more the merrier, I love listening to people talking about shares.
Best wishes, Paul.
I think you’re being too modest Paul, firstly you have accountancy knowledge from first hand experience in industry, secondly you have c20 years of investing and punting and thirdly you’re a born entertainer! All in addition to doing your day job Mon-Fri, keep up the great work!
Well as modest as anyone can be who says they enjoy listening to their own podcast :)))
Hi Paul - Great to catch you for a couple of beers at Mello - The podcasts are great and much appreciated - We discussed Zane briefly during our quick chat and perhaps a mention of that every 2 or 3 episodes would help the cause and just be a gentle reminder to listeners that they can show the Ad Free appreciation in a slightly different way now and again should they wish - All the best!
the Vesuvius (LON:VSVS) Share buyback announcement this morning looks promising for more rises in its hare price as eps should go up
Sanderson Design (LON:SDG)
Close Brothers increase holding from 5% to north of 10%.
Interesting, I hold.
At a tangent, Close bros were the seller of c3.5m Vertu Motors (LON:VTU) last week presumably part of Nivag Holdings purchase on the same day.
Close Asset just announced a 3.98% holding.
Cause they sold 1.5%;
They were 5.5% before.
They failed to notify there previous position then.
That was the announcement saying they’d sold c3.5m
Can you add the RNS link re the Close Bros sale. Cannot see it on the Vertu Motors (LON:VTU) Investor site or the London stock Exchange.
May23 they had 5.5%
Now they have 3.98%.
That have cut down their position.
Re: Sanderson Design (LON:SDG)
The note at the end of the Close Brothers RNS says "On the 22nd November 2023, Close Brothers Asset Management bought 35,390 shares in SANDERSON DESIGN GROUP PLC ORD 1P. This brought our shareholding to 10.03% of the shares in issue. This is based on the shares in issue figure of 71,706,225 as at 22nd November 2023. This is the required notification that the holding has crossed 10% of the shares in issue."
35390 shares should presumably have been 353,900 shares! I'm surprised it hasn't been corrected
Avingtrans (LON:AVG)
American distributor announced for Magnetica portable MRI scanner.
"Avingtrans plc (AIM: AVG), which designs, manufactures and supplies critical components, modules, systems and associated services to the energy, medical and industrial sectors, is pleased to announce that its subsidiary, Magnetica Limited, has signed a new strategic partnership with Televere Systems, LLC, a leader in radiography product distribution. This agreement appoints Televere as the official US distributor for Magnetica's products.
Commencing immediately, this partnership was officially unveiled at the RSNA (Radiological Society of North America) 2023 annual event in Chicago. It marks a significant achievement in Magnetica's expansion strategy, reinforcing its commitment to providing advanced MRI solutions to the U.S. market. Magnetica is developing state-of-the-art technology using ultra-compact superconducting magnets in an MRI technology that will operate without liquid helium. Magnetica plans to seek FDA clearance for the product by mid-2024."
Another stepping stone towards commercialisation. I hold.
Interesting acquisition by Spectra Systems (LON:SPSY) announced this morning, spending £5.5m in cash and up to a further £5m in shares to acquire Cartor, a security printer specialising in stamps.
Key point from the announcement: there are currently only two suppliers of polymer substrate to central banks and "Spectra's research and dialogues with central banks has clearly shown the desire of the banks to have another supplier of ready to print bespoke polymer substrate." This is clearly a significant opportunity, reflected in the fact that £2m of the consideration becomes payable "in the event that Spectra has qualified its FusionTM polymer substrate for tender submissions with a central bank customer." This is moving Spectra Systems (LON:SPSY) into the big league, up against De La Rue (LON:DLAR).
Apart from this strategic case, is it good value and will it be earnings-enhancing? Well, Cartor generated PBT of £1m in FY2022 so on that basis yes. However profits more than halved in FY2023 just ended, to £435K. We can't tell which of these numbers is more representative so we basically need to trust that Dr Nabil Lawandy knows what he is doing, which is something on which we can each take a view. NAV is said to be £5m but we don't know if that includes intangibles.
My assessment is positive: the two companies have been working together previously, there are clear synergies and a long-term strategic opportunity to challenge much larger competitors. I would imagine that size matters in this market and the sales of the combined group will be more-or-less double the sales achieved by Spectra Systems (LON:SPSY) last year (£16m for Cartor, $20m for Spectra).
About time Spectra Systems (LON:SPSY) puts its cash pile to use! This acquisition seems complimentary as well as low-risk (existing commercial relationship).
I'm surprised there was no mention of cost synergies. Yes, its different products, but surely could rationalise some of the sales force, manufacturing facilities, buying raw materials at scale? At the moment, regardless of whichever EBITDA number you take for Cartor, the multiple isn't that cheap if the full earn-out is paid.
The polymer banknotes is interesting, but as the RNS mentions, there are already two BIG players in the market. Can it support a third upstart? Clearly lucrative if Spectra can get a few central bank contracts. But these are very, very slow burn. And so far, Spectra seems to only have one in the pipeline in trial stages. Even if they get another Central Bank to sign a trial agreement tomorrow, it is probably only 2025, 2026 before production revenues start.
I like the underlying defensiveness and organic growth at Spectra. So if this acquisition is successful and adds more, that's great. They can certainly afford the acquisition without risking the balance sheet.
New broker forecasts with revised EPS should push this past 200p easily, I reckon.
(I hold in the Boon Fund)
Re: Spectra Systems (LON:SPSY)
Boon, On the question of whether there’s room for another supplier in the polymer substrate market, today’s announcement seems to suggest there’s a demand.
The international polymer substrate market currently has only two suppliers,
CCL Industries in Canada and De La Rue International in the UK. Spectra's
research and dialogues with central banks has clearly shown the desire of the
banks to have another supplier of ready to print bespoke polymer substrate.
Titon Holdings (LON:TON)
Very clear statement including above market expectations, in line, and pretax worsening!
Titon Holdings (LON:TON) [I hold an opening position at 78.75 as of this morning] - 'The Board of Titon remains confident in the long-term prospects of the Group'. Normally those words would be a huge red flag to me but the contrary view from planetx is here and here. I expect this is going to be a loss-making position for at least 6 months, the new CEO doesn't arrive until April.
Michael
I hope you dont blame if it goes to pot .
I had hoped for a bigger drop this morning but looks like no sellers around I mopped up all the 78.75 / 79 / 80 and it’s spiked to 85.
At sone point next year presumably Keith Ritchie will unload some stock .
I think Rockwood are trying to add more .
The first big play is divest South Korea and saLvage any value . I got the impression that they would sell it for free and the prioroty is get rid .
It’s got increased cash (2 mill), Stock , freehold .
I’m happy enough and will keep adding at the 80p level but hard work to build a stake .
Of course no blame, we all make our own decisions. And I only have an opening position ATM. But I definitely will owe you a beer if all goes well. Any ideas what the exit from South Korea looks like? I haven't yet found anything about the terms of the JV (but have only just started looking).
Nanoco (LON:NANO)
There is a lot of value here.
Recently won a litigation against Samsung for using their IP.
Market cap is less than FEB24 cash!
They are returning 10-12p back to shareholders (1:3 tender offer at 35p is the best option for me).
They have also started their first ever commercial production and they are self funded until 2025 when they will be generating free cash flows.
Many other (about 19!) infringers of their IP identified as well.
DYOR
The South Korean exit is prioroty
Richard Staveley indicated that someone would very shortly be on a plane out there armed with bottles of whisky and to just come back with a deal done.
Ideally I think it’s a few million quid but I think will do anything just to get it out of their hair .
At one point a few years ago they were receiving if my memory serves circa 500k a year .
Personally I think they are happy to just walk away and anything extra is upside .
It’s a bad historic agreement with no control so best is just cut and run and move on .
Hope the Koreans aren’t reading this .
Next step is surely close the offices and get everyone into one location .
planet X
sold out of Titon Holdings (LON:TON) a while ago (probably to Rockwoood) - so I have no current position. I don’t understand why there should be any rush to “get rid” of the Korean assets - particularly at zero value. The parent has put no cash into the Korean asset for many many years - only received money out as upstreamed dividends. So while it might be a drag on the P&L the Korean business is no drag on cash and as far as I understand (I may be wrong) Titon has no obligation to fund any losses in Korea - worse case, it could let Titon Korea and Browntech go insolvent.
The other difficulty in selling quickly is I assume there is only one plausible buyer - the Korean JV partner.
I think if there is a turnaround to be done they do need to get on with it .
Remember also Rockwood will want an exit at sone point and the South Korean arrangement is almost certainly of zero interest to any buyer
So clear focussed strategy is simplify , and extract value .
John Molton of better capital I think once said something along these lines
“The key to change management
- if there are 10 things need changing then change all 10
- and be prepared to get a few wrong
As opposed to tackle them one by one “
And don’t forget with legals etc and back and forth it’s still at least 6-12 months ?
it took Crestchic years to divest itself of its Middle East and Australian jv , look what happened there .
So for me get on with it and get it out the door .
My morning smallcap tweet: Cashaholics Anonynmous
600 (LON:SIXH) Titon Holdings (LON:TON) Verditek (LON:VDTK) Petrofac (LON:PFC) Oxford BioMedica (LON:OXB) Arecor Therapeutics (LON:AREC) Deltex Medical (LON:DEMG) AFC Energy (LON:AFC) ITM Power (LON:ITM) Cornerstone FS (LON:CSFS) Spectra Systems (LON:SPSY)
◄600 Group (SIXH)► cash crisis worsens as potential disposal of a majority interest in the TYKMA Electrox and Control Micro Systems industrial laser businesses falter. Only laser biz may be sold to the US counterparty. FY-Mar accounts further delayed to end Feb. Trading conditions have remained difficult. Still in talks on extending $5.5m debt facility. [SP=2.76 Cap=3m]
◄Titon (TON)► warns FY-Sep pretax loss worse than mgmt expectations due to worseninng at South Korean biz. UK and Europe above exp. Current trading in UK and Europe in line but guides pretax loss for those regions due to decline in new build activity in the construction market in Q1. Expects to return to profitability in Q2. How is trading in line then? [SP=81.38 Cap=9m]
◄Verditek (VDTK)► GM motion to hose existing holders with dilution. Motion to "approve authority to allot up to 100% of share capital on a non-pre-emptive basis". [SP=0.22 Cap=1m]
◄Petrofac (PFC)► warns won't meet FY FCF target. Blames delays in securing advance payment guarantees. Co has "as continued to maintain liquidity above its financial covenant...considering the sale of non-core assets, and is actively engaged in discussions with financial investors to take a non-controlling position in certain other components of the business portfolio". Having trouble getting Performance Guarantees for EPC contracts. Talks with credit providers to secure the guarantees. [SP=17 Cap=89m]
◄Oxford Biomedica (OXB)► signs agreement to acquire ABL Europe for €15m (including €10m of pre-completion cash funding from Institut Mérieux in ABL Europe for, amongst other things, development capex). [SP=166.6 Cap=161m]
◄Arecor (AREC)► co-development and exclusive licence option agreement with a leading global medical products company for a high-value, ready-to-dilute oncology product. "Arestat enabled product is potentially first ready-to-dilute liquid formulation of a high-value oncology therapy." [SP=191.54 Cap=59m]
◄Deltex Medical (DEMG)► initial orders for new TrueVue monitors. Co expects strong start to the new year as larger quantities are shipped. [SP=0.16 Cap=3m]
◄AFC Energy (AFC)► world first modular ammonia cracker system as co commences largest ammonia to hydrogen modular cracker demonstration in operation worldwide. Engineering will start in 2024 to containerise the ammonia cracker platform. [SP=13.88 Cap=104m]
◄ITM Power (ITM)► guides H1-Oct rev £7.5m, in line. Net cash £253.7m (FY guidance £175-200m). [SP=51.48 Cap=318m]
◄Cornerstone FS (CSFS)► guides FY-Dec rev and adj EBITDA materially ahead of market expectations. [SP=11.48 Cap=7m]
◄Spectra Systems (SPSY)► buys Cartor Holdings, a leader in the security printing industry, for £10.5m max. £5.5m cash and rest in shares. Takes on up £4.5m of Cartor's external debt [SP=177 Cap=82m]. I hold.
◄Notes► SP & cap are 20m delayed
#POS - Possible game changer for Plexus? Extracts below from a WSJ article published today.
"On Saturday, the Biden administration announced a final methane rule for U.S. oil and gas producers, requiring them to plug methane leaks and stop burning excess gas with flares. The regulations also mandate regular inspections of facilities to make sure the planet-warming compound isn’t escaping into the atmosphere.
Administration officials say the methane rule—which will be phased in over the next two years after two years of contentious debate—will cool the planet and improve public health. Industry groups say it will put some well owners out of business.
European Union officials used the same playbook, announcing proposed rules in November that would clamp down on methane emissions from production facilities, as well as requiring imports and exports to track and report methane beginning in 2027.
The EPA rule will require new wells to cap flares at production facilities that burn gas waste that the industry says isn’t economical to sell.”
“The EPA estimates the new methane rule will prevent 58 million tons of methane emissions from 2024 to 2038.” Methane is an odorless, colorless byproduct of oil and gas drilling operations. Once it reaches the atmosphere, methane is 86 times more potent than carbon dioxide at trapping the sun’s energy.
In addition to curbing climate-warming methane, the rule will also eliminate 6 million tons of unhealthful volatile organic compounds by 2038, along with 590,000 tons of toxic air pollutants like benzene and toluene.
BP America Chairman and President Orlando Alvarez said he welcomed the new methane rule and its application to existing oil and gas facilities. “A well-designed rule will help drive material methane emission reductions this decade and beyond,” Alvarez said.
News coming out on cop28 and the methane pledge from oil majors and countries. Good news for plexus https://www.nbcnews.com/news/amp/rcna127496
Thanks for Sharing. Jumped in on the bell based on this news having been tempted a few times previously but not pulled the trigger. I'd always liked the concept of plexus but surely this hugely enhances it's upside potential.
I have a theory that the major Plexus Holdings (LON:POS) contract is with the BP Seagull project in partnership with Neptune Energy. The last contract win was through Neptune so it could be a good partnership there growing nicely with future work.
If that’s correct it means there could be potential for the other 6 fields under BP BP (LON:BP.) that produce through the Eastern Trough Area Project ETAP.
The RNS the other day reads relating to the 8million contract……..management believe this will further enhance the reputation and reach of the Company and should help with securing more standard and routine work amongst the other operators involved.
"The key word is "other operators" involved which would be BP, Neptune and JAPEX.
Take a read up as it looks like it could mean more contracts in Q1 with the next phase which is Murlach project. Murlach, a future tieback to the ETAP CPF, received government and regulatory approval in September 2023 with production expected in 2025. I could be completely wrong but this is where my research has taken me! :-)