Small Cap Value Report (Mon 4 Jan 2021) - ENT, SFOR, SAA

Good morning, it’s Paul here with the first SCVR for 2021. I trust you had a relaxing break over Christmas & New Year, such as it was. Plenty of repeats to watch on TV anyway, we were spoiled for choice!
Stockopedia NAPS
Ed has recently published his 7th annual Stockopedia NAPS (no-admin portfolio system) article here, well worth a read. This system (based on StockRanks) delivered an excellent +27% in 2020, and has also significantly out-performed its benchmark in the previous 6 years. It demonstrates very well that a well-thought-out mechanical stock-picking system is a good way to beat the market, if you are time poor, or don't have confidence in your own stock-picking ability.
Trading updates in January
Out of curiosity, I looked back at last year’s SCVRs to see what companies I wrote about in the first half of January 2020. It was mostly Xmas trading updates from retailers. Given that, late last year so many non-essential shops were forced to close, plus the hospitality & travel sectors were largely locked down again too, in many parts of the country, then I’m not sure how things are likely to pan out this year.
Newsflow is likely to be short term grim, but the market is already looking beyond covid, since the positive vaccine news came through, rightly so I think. Will the big rally of late 2020 hold? Answers on a postcard - I haven't got a clue, as it's not my role to guess at short term market sentiment, anything can happen.
Some things (especially companies perceived as growth shares) do look pricey now though, and have maybe gone up too much? Tesla & Bitcoin, plus plenty of other areas of the US market are clearly now in euphoria or even mania, bubble territory. It's only a matter of time before things go pear shaped in the frothiest part of the market. We've seen all this many times before, and it always ends the same way.
.
.
Given that short term company trading is likely to have been awful in some sectors, then balance sheet strength is the most important thing to me. Can companies survive, without having to do another placing, until conditions return to something like normal (best estimate on that seems to be some time in April, once enough vulnerable people have been vaccinated)?
Will investors baulk at the huge debts some companies have run up during the pandemic? Or will that be ignored, as people focus instead on rising earnings?
IFRS 16 adjustments
... are likely to cause more chaos. I was talking to the CFO of a bars group, who explained to me how it works at the moment. The asset side of the IFRS 16 entries are likely to be based on awful current trading at balance sheet dates (i.e. heavily written down). That's likely to make balance sheets look horrendous in the short term, for multi-site retail & hospitality.
However, the key point to remember, is that once trading returns to normal, hopefully in Q2 2021 onwards, then those leasehold assets are likely to be greatly increased in value again, as sites return to profitability. Hence the IFRS 16 entries are particularly problematic, and it's more important than ever to completely disregard them, in my view.
This hopeless accounting standard really does need to be repealed as soon as possible. It's messed up P&Ls, by moving some rental costs into finance costs, rendering operating profit meaningless. Ditto for EBITDA. The whole cashflow statement is largely useless now, as it doesn't reflect reality. Finally, balance sheets include a mish-mash of some future years' liabilities (but not others, such as business rates, staff costs, utilities, for future years etc), and highly volatile notional assets which are not real. It's a complete mess.
EDIT - as an example, Revolution Bars (LON:RBG) (I hold) will show awful IFRS 16 balance sheet entries probably until the 30 June 2021 balance sheet is published, whereupon the IFRS 16 leases deficit should vanish (i.e. leasehold assets should be re-rated back up to roughly match lease liabilities). This is because RBG has ditched all but 1 of its loss-making sites, by renegotiating problem leases, re-gearing (longer new lease, in return for lower rent, making it profitable again), and a disposal of a batch of problem leases with one landlord. The way IFRS 16 works, the 31 Dec 2020 H1 balance sheet, when published, will reflect the situation as at that date, i.e. showing huge liabilities & not much in the way of assets. That will not reflect the future at all, so will be highly distorted & very unhelpful. End of edit.
.
Brokers & PRs please note - trading updates
I know that a lot of city advisers read these reports, which is great, and I have constructive relationships with many people in the city. They sometimes ask me what information investors need? I can’t answer for everyone, but thought it might be useful for me to publish a list of things that would be useful to include in forthcoming trading updates, in no particular order;
- Gross cash, and net cash (as recent as possible)
- Stretched creditors - many companies are reporting unusually high cash, because they’ve taken advantage of extended payments terms. That's fine, but investors need to know how much, and when are stretched creditor payments due (e.g. extended VAT, payroll taxes, rents, and any other extended creditors). This information needs to be specific, and should be provided even if it’s a zero amount, because omitting it arouses suspicion that liabilities are being hidden to overstate cash.
- Combining the above 2, what is normalised net cash now?
- Bank facilities - how much drawn down, headroom remaining? Expiry date of facilities, and headroom on covenants - are covenants likely to be breached (going concern type notes are very useful on this, e.g. severe but plausible scenarios - I think auditors have done a good job insisting on this info in 2020)
- Profit guidance, for companies with Dec 2020 year ends should be provided - subject to audit adjustments. If not sure, then give a range of possible outcomes. Something is better than nothing.
- Profitability versus market/Director expectations - NB must include a footnote as to what those expectations are, because this information is particularly hard to find at the moment with smaller caps, due to lack of market forecasts, or some brokers withholding that information from private investors
- Outlook - assuming that business can return to normal at end Q1, then it should be possible to give some meaningful guidance for 2021. Saying it’s too uncertain is not helpful! Estimates can always be revised in future, if things chance, so just give us your best current base case estimate for 2021 please. Again, a range of numbers is good, if being precise is too problematic.
- Tables of numbers are far easier to interpret than waffly text explanations - I’m a big fan of tables, let’s have more of them please
- Abbreviations - if you must use them, please include a footnote to say what they mean, as it’s not always obvious to people outside a company’s sector
.
What to avoid - rambling, imprecise text.
Above all - please make trading updates clear, and balanced - giving a realistic overview of performance & outlook. It’s not an exercise in PR, to embellish the truth. People can usually see through that sort of thing. Investors just need the straightforward truth, which is what builds trust in companies & their management.
I hope that helps.
What else is happening today? Very little, almost nothing in small caps. A couple of larger companies;
Entain (LON:ENT)
This company used to be called GVC, it's a betting & gambling company. Mid cap or large cap, depending on what figures you use (mkt cap now £8.4bn) - it's up 26% today, on news of a possible takeover bid from MGM Resorts, "its partner in the US market".
The proposal seems to be using MGM shares not cash, and values Entain at a 22% premium, 1383p per share (which will fluctuate in real time, as the price of MGM changes). A "limited partial cash alternative would also be made available".
Note that Entain's share price is now above this possible offer price, at 1434p - suggesting that the market sees potential for a higher bid(s).
Entain has informed MGMRI that it believes that the proposal significantly undervalues the Company and its prospects. The Board has also asked MGMRI to provide additional information in respect of the strategic rationale for a combination of the two companies.
We were recently discussing here the likelihood of a tsunami of takeover bids being likely, now covid vaccines are being rolled out, and most of the Brexit uncertainty has been removed. This approach from the USA for Entain seems to confirm this trend.
Expect a lot more takeover bids. This could make US mid caps an interesting area to trawl through, in addition to small caps.
.
S4 Capital (LON:SFOR)
Mkt cap £2.7bn
This is a great story - Sir Martin Sorrell (who created ad/marketing giant WPP) is now creating a rapidly expanding "new age/new era" digital marketing group. It puts out an in line with expectations update today, which is dressed up to sound breathlessly exciting.
It expands its pretentiously named Content practice. Further moves will be announced shortly, how exciting.
I find the update today really rampy & over-excitable.
It tries to steer us towards gross profit as a key performance measure, which is laughable.
Acquisitions - note that S4 doesn't use earn-outs, which is interesting. Instead it buys companies half in cash, and half in S4 shares, with a lock-in. That's quite interesting as it challenges conventional wisdom that management at acquired companies need to be motivated with earn-outs to keep producing strong growth. I suppose if you can convince acquired companies that S4 shares will be rocket-fuelled, and show them a strongly rising share price chart, then that could work well, and builds loyalty to the larger group (or "family" as it's slightly nauseatingly called in today's announcement).
Liquidity sounds good;
Even after allowing for the cash consideration paid and due in respect of Decoded Advertising and Metric Theory, the Company will still maintain significant net cash balances.
My opinion - investors are lapping up the story here, and the share price has been strong. I suspect the published results might throw a bucket of cold water over excited punters here. Whilst respecting that Sir Martin knows his stuff, how much of a premium are people prepared to pay for that, given his advancing years?
Looking back at the last interims, it made paltry profit before tax (statutory) of £118k (bear in mind the market cap is £2.7bn!). This was massaged into an H1 £13.9m adjusted profit (see note 13 of interims). However, £6.1m of the adjustments relate to "share based compensation", which in a people business, I would just regard as payroll costs, as it's likely to be ongoing, to retain the brightest talent. Adjust that back in again as a cost, and H1 profit was really only £7.75m, the way I look at things.
Hence it seems a significantly over-valued share at the moment. Maybe the figures will grow into the valuation in future, but for now it's clearly over-hyped. You only have to read today's announcement to see how frothy it all sounds. Whether the market will know, or care, is another matter.
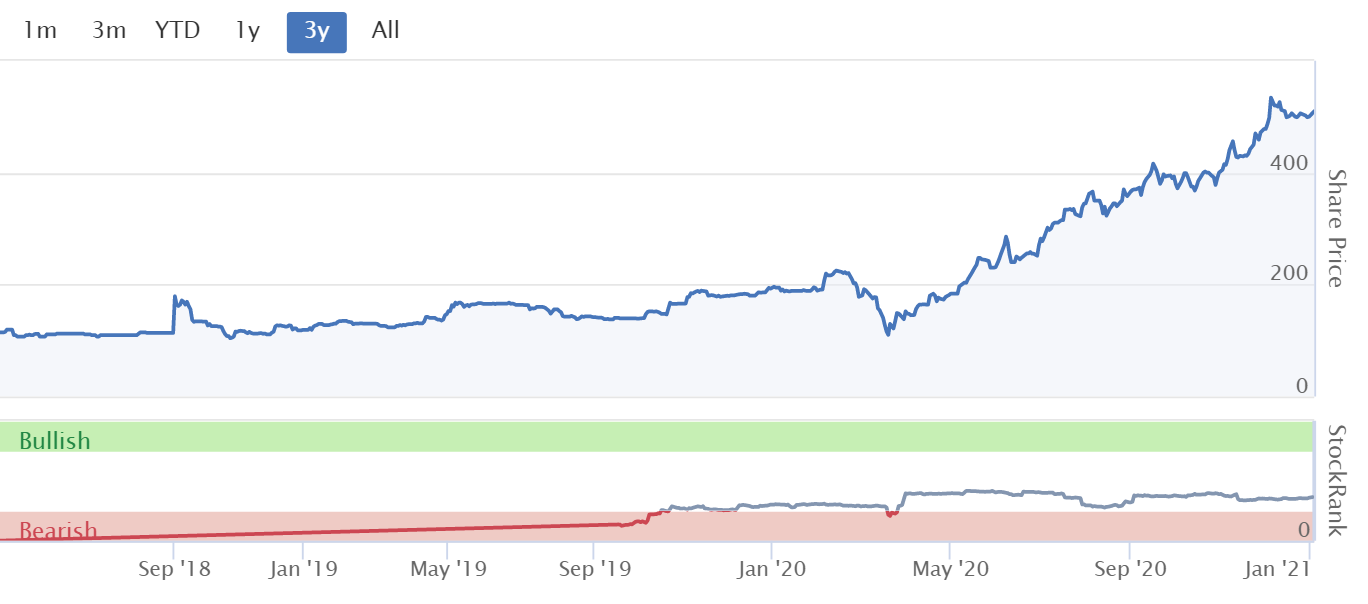
Note that the StockRank system is also sceptical (below), so it's not just me being a grinch!
If I wanted to back digital marketing, the obvious way to go is buying Facebook shares, which owns the two platforms that are most in demand for advertisers, because they deliver the best results, namely Facebook and Instagram. Why buy anything else in the sector, when $FB trades on a forward PER of 26, and is sitting on pots of cash, and should deliver strong growth for years to come? Break-up & regulatory risk is an issue though with FB.
.
.
M&c Saatchi (LON:SAA)
New CEO appointed. Moray MacLennan is a long-serving internal candidate. That's a wonderfully Scottish sounding name, so I had to google it! "Moray" means sea, apparently, and is also a type of fish. "MacLennan" is apparently a Highland Scottish clan, historically populating the north-west of Scotland.
Personally I'm giving SAA shares a wide berth for now, due to accounting problems, and some nasty dilution potential from poorly structured options-based acquisition payments. Although advertising & marketing are obviously good cyclical sectors in an economic recovery.
.
I've probably scraped today's thin news barrel as far as humanly possible, so will leave it there for today. See you tomorrow!
Thanks for the thumbs ups, it really does help motivate the writers here, when we see people like our work.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Trading Updates - Sorry I missed this yesterday & only just catching up but.....! By far the biggest bug bear and totally unacceptable is the term ???? “with market expectations!” How is a private investor expected to know, yet alone calculate, “market expectations.” These should always be qualified with numbers as it feels the company is speaking only to a restricted group of investors I.e. excluding private investors! Totally agree with cherry picked waffle Paul. There should be an agreed general format IN TABLES (yes, meaningful tables). Adjectives (above, below etc) replaced by numeric ranges!
Thank you for listening.....
Pineapple Power (LON:PNPL) - is this where we are heading? First list a vehicle that investors perceive as hot (SPAC) then find an even hotter area to invest the IPO proceeds (renewable energy) and voila - SP spikes up nearly 80% in a few trading days. That's was easy wasn't it!!! (I don't hold)
****! LOCKDOWN III
Like a bad cliché movie franchise, here we go again.
Pop Quiz:
A. Big sell off.
B. Small sell off and short term bear market.
The key reason I ask is, is market history going to repeat itself?
My biggest concern: there is no certain end date and many businesses are now definitely going to lose money, furlough, take emergency handouts, effectively killing 2021 Q1.
To sell off or to sit it out?
Personally I would go for C minor market bounce.
The only people who did not already know that this was the outcome were :
The market negative would have been if he prevaricated and pretended for a further day that this was not going to happen.
Think you will find Boris knew all along... Nation been sleepwalking into lockdown for a while now. As with the first lockdown, people now ready. Brexit queues at the Ports? Don't think so. Canny fella I think...
Having spent most of my career in digital, i agree with your comments re £SFOUR. However, google is a much higher proportion of every major company's budget.
Kape Technologies (LON:KAPE) has been doing some good stuff lately with some news but i dont think youve covered it. Why is that? or have i missed it (which is quite possible)?
Keep up the good work and hope your dog is still on the mend....
Hi Andy
You will know if Kape Technologies (LON:KAPE) is covered if you type "KAPE" into the search function and then click onto Discussion link.
Paul - I'm sure we always like and appreciate your work. It's just that by the time we've scrolled down through all your writing it's so easy to then make a start on reading all the following comments and by then we've forgotten to move back up to the top of the page to give you a well deserved thumbs up.
I know that I'm frequently guilty.
Maybe the Stocko team could enable an automatic thumbs up for those like me ;-)
This system (based on StockRanks) delivered an excellent +27% in 2020
In a word: wow!
Has anyone seen the Ienergizer (LON:IBPO) special dividend today? Must admit I read it as 4.9p at first, then read it again later on and it's 49p per share, incredible!
Ienergizer (LON:IBPO) Yeah it's good news I guess (who knows what will happen to the SP when it goes XD, mind). Of course, though, one should be aware of the fact this is basically the CEO using company cash and debt to give himself £75m. Make of that what you will.
Be interested to know if Paul has any thoughts on this and whether it's a prudent use of cash/debt. I'm undecided.
I've just had a look at the Ienergizer (LON:IBPO) numbers, because Ben Button's post above raised my curiosity. Big special divis are often a sign of a business trading its socks off.
In this case though it looks borderline crazy to me, to pay such a large special dividend, mainly funded by new borrowing facilities. Highly imprudent. Although I suppose the argument would be that software companies have recurring revenues.
Remember when Topps Tiles (LON:TPT) did something similar a few years ago, and the company almost went bust shortly afterwards, when a recession hit.
Regards, Paul.
£IBPO. Back in Oct 19 the trading update said Aggarwal had been talking to institutions about selling a small stake to improve liquidity but decided against it due to adverse UK market conditions. The RNS mentions they are now an Aim 100 Company so they may again have institutions knocking at the door. If so he could be looking to extract value before selling a stake.
certainly seems a reasonable theory, grazza. Does seem very convenient timing with the AIM100 promotion. You’d think there’d need to be additional share liquidity just for the institutions with AIM100 tracker funds to take stakes, otherwise there really would be nothing left for PIs.
Ienergizer (LON:IBPO)
If I held I would run a mile. Such a small float, such a large percentage owned by Mr Aggarwal. The dividend will be Christmas all over again for him. I have seen this kind of situation before now.
Silver
I hold Ienergizer (LON:IBPO) brought in few weeks ago as looked solid business with growing revenues but cant seem get my head round such a large divi funded via debt.
Exactly - Anil holds 83% - he can literally do what he wants - pass all ordinary / special resolutions.
This isn't true, actually. There is an agreement that Anil does not exercise the voting rights of his shares for as long as he holds 30% or more of the shares.
For IFRS 16:
If there is a change in consideration of the lease (e.g. the vendor/lessee is paying less), it should just be accounted for between the lease liability (dr) and the RoU asset (cr) - not P/L.
This is the same treatment for extending a lease or adding additional leased space.
If you are removing the lease or shortening it, both the RoU Asset and the lease liability would be reduced proportionally and the difference taken through P/L.
The ‘right of use asset’ should reflect the lease payments which would be equal to the lease liability but would include the following amounts, where relevant at recognition:
A one-sided write-off on a lease RoU asset after it has been recognised seems like strange treatment and doesn't really reflect the nature of the lease. It doesn't seem fair to say my leased property isn't doing well, so write-down the asset (which is determined by being equal to lease payments minus depreciation but don't write-down the liability of payments).
In other words, the RoU asset shouldn't reflect whether the business is doing well or not, it should just show the obligation to pay the lease and the net impact between depreciation and payment. Unless the depreciation term has suddenly been changed but that is also irregular and would also require adjusting the term of the lease obligation.
With this in mind, the EBITDA wouldn't include the depreciation of the asset and would only include the lease payments, so should provide a good indictor of the profitability of the underlying business.
Paul wrote: "Tables of numbers are far easier to interpret than waffly text explanations - I’m a big fan of tables, let’s have more of them please"
Amen! Everyone knows that tables are how information is delivered internally to managers, especially on something as basic as Sales revenue, so this info is readily available. (In fact, looked at this way the trading update is deliberately obfuscated - not really in line with building trust!)
When difficult to calculate data like carbon footprints are now routinely calculated, perhaps the time has come for a light touch minimum mandated reporting plus a legal requirement that mgt provide either a spelled out link to external expectations or provide an internal forecast.
No doubt weak companies estimates would be very broad but standard (table) formats would no doubt help. Again if mgt don't already have monthly updated forecasts at a listed company, fire them immediately!
The following 'looking back at last year' headline reminds me why I do not short:
Short sellers lost $38bn betting against Tesla in 2020, higher losses than those triggered by any other company.
As a relatively new investor, the whole shorting and betting thing is a mystery to me, so I hope I will be forgiven for a very stupid question, which my wife and I pondered over our lunch. Every loss must have a corresponding gain, so where does this humongous sum end up?
In the shorter's pocket.
I fear I may have inputted a downtick for the article instead of the intended uptick. There's no indication about what was inputted and nothing seems to change what was done.
Pretty well all newspapers allow fat finger corrections in their comments and the better ones show what has been entered.
I had intended to thank Paul for his list of cash flow best practice reporting and repeating the issues with the destructive IFRS 16.
If you tick up or down the wrong way you can cancel it by clicking in the other direction. You then need to click again in the direction you want for it to register.
Tried, but no effect on numbers.
So either my uptick was simultaneous with two downticks or the attempt to revise had no effect.
I could try to see if a downtick changes the numbers, but I'd feel uncomfortable doing it.
OK tried it and that worked, so false alarm. And there must have been two simultaneous downticks. Entirely beyond me why anyone would that.
Don't worry, because I don't see thumbs downs at all (using the new site they're completely invisible, and are always outweighed by up ticks). Happy days! :-)
If you ever read Factfulness by Hans Rosling, you will see that sets out that demographically Africa and Asia are the future drivers of world demographic related statistics, which will include economic growth, and with it their people's elevation from poverty.
Hard perhaps to imagine when you look at Zane's effort to support older people in Zimbabwe, and despair at the quality of certain types of Govt Africa often offers.
Its not going to be easy for democracy's to relate these countries, when their Govts are often so poorly managed and corrupt. It maybe a case of using a long spoon when we deal with them.
.....and fight to keep our own democracy well managed and largely corruption free. These last few years and the last 12months especially have seen a huge reduction in the competence and cleanliness of our politics. Our standing as a country has dropped hugely.
For the first time in my life, I fear for the future of the UK in this regard. So many many of characteristics i see today (obfuscation, cronyism, bypassing scrutiny, internal party decisions becoming key) are exactly what I saw living & working in the failing countries of Africa and Asia. We are so lucky in this country, democracy and justice are not the norm and easily lost.
Sadly, your observation: "For the first time in my life, I fear for the future of the UK in this regard. So many many of characteristics i see today (obfuscation, cronyism, bypassing scrutiny, internal party decisions becoming key) are exactly what I saw living & working in the failing countries of Africa and Asia." applies not only to the UK.
Here in Berlin such characteristics seem to be just as widespread, in particular amongst those in positions of influence. And to those characteristics you mention I would add that of corruption. The challenge is how to root out such practices when so many people in authority have skeletons in their own cupboard.
I suspect that what it actually happening is reporting and whistleblowing are becoming more common / newsworthy and that public expectations and tolerance of wrong doing are lower.
I find it almost impossible to believe that skullduggery is higher now than in the 1970s and 80s
I also find it slightly ironic you fear for our democracy right at the point we finally achieved a result for a democratic decision taken 4+ years ago that was delayed because the losing side refused to accept the result and used all kinds of non democratic means to prevent its enactment such as standing on false tickets, resorting to law to resolve political decisions, an obviously partisan speaker etc.
I also find it slightly ironic you fear for our democracy right at the point we finally achieved a result for a democratic decision taken 4+ years ago that was delayed because the losing side refused to accept the result and used all kinds of non democratic means to prevent its enactment such as standing on false tickets, resorting to law to resolve political decisions, an obviously partisan speaker etc.
The UK is a constitutional democracy which means that sovereignty vests in Parliament where the representatives of the constituents - MPs - sit. Only Parliament can decide that other entities may make sovereign decisions on its behalf and in the case of the Brexit referendum it decided not to, by not making the referendum binding (unlike the previous referendums on proportional representation and Scottish independence).
The upshot of that was that the only way of democratically deciding how Brexit should be achieved was through a majority vote on a Bill in Parliament. As "Brexit" is not one thing it could have been achieved in a number of ways - Theresa May's Brexit Bill was blocked by Brexiters because it wasn't hard enough, but no one on the Leave side complained about that.
It made the process a nightmare but it was entirely democratic. In fact the only non-democratic decision made was the attempt by the current Prime Minister to prorogue Parliament to avoid democratic scrutiny. Given that Johnson, Gove and co went to great lengths to make the referendum about the UK taking back its sovereignty from the EU it's a matter of very deep irony that they then attempted to deny Parliament its sovereign right to vote on the issue.
While I'd completely agree that the process was a mess and an affront to the governance of the country it was absolutely democratic. MP's represent their constituencies and their consciences and are not obliged to accept a non-binding referendum result. However, it does rather point up the issue of using a non-binding national referendum to decide issues in a constitutional democracy. Hopefully the lesson has been learned.
timarr
Whilst we’re in danger of rehashing old arguments here, I will add one more comment then drop it.
I find it interesting you offer no criticism of MPs standing on pro Brexit tickets and then voting against those manifesto commitments, some would say misleading voters, but offer criticism for the PM for using powers in his gift which got taken to court to resolve a clear judicial interference in political matters imv, despite the Speaker offering Remainers unprecedented access to set the governmental agenda against 400 odd years of parliamentary precedent. Those MPs could’ve collapsed the government on any day Parliament sat, that they chose not to because they knew the electorate would bin them is the antithesis of democracy.
I guess both sides see their own narrative and I accept that I see the world though my own prism. Thank you for your courteous and considered response .
I guess both sides see their own narrative and I accept that I see the world though my own prism. Thank you for your courteous and considered response .
You're welcome. I'd note I don't see Brexit in itself as either good or bad. I'm not convinced the disruption was worth the pain, but it is what it is.
timarr
I find it interesting you offer no criticism of MPs standing on pro Brexit tickets and then voting against those manifesto commitments
You presumably would include the ERG and hangers on in that? Those who supported Brexit but blocked the detailed solution worked out by their party leader, and in doing so blocked Brexit. The mess and delays were inevitable once Cameron decided it was smart to go for a yes/no referendum with no serious prior resolution of what Brexit would mean (Jacob Rees Mogg got it right at one point in 2016 where he suggested a 2nd referendum might be needed on an actual deal - though he changed his tune on that one!). And of course it was all made far worse by May's insanity in signing art 50 before anyone had agreedwhat sort of deal the UK wanted - given it was already clear that Brexit had as about as many meanings as voters.
The decision to leave the EU was a democratic decision - and the new PM (May) was then a Remainer who consistently tried to deliver this and work through parliament. This is not directly meant to be a party political or Brexit outcome comment
Indeed, most of my complaints related to the current Johnson administration who consistently shows a reluctance to face scrutiny (remember him a hiding in a fridge in the GE campaign, the ban on Ministers appearing on Today radio, parliament's perogation). The COVID laws have resulted in much loss of scutiny/debate and led to (poor) govt by decree. Independent bodies sidelined (Patel's bullying, House of Lords appraisal committee). Statistics bodies writing public letters about misleading use of data; slow and incomplete release of data. Internal Markets bill overturning elements of international law. - I could go on.
Why all this on an investment not a political column? Having seen how it impacts business and prosperity elsewhere and trying to see where the UK has a competitive advantage in the future, keeping society rules based and transparent is a critical point of difference and advantage - never more so now we have chosen to leave the EU. Most of my international contacts thought Brexit was a mad/bad idea. We need to attract retain trade and investment. Democracy and the rule of law was one of our strongest cards. All these actions work against us and help explain (in part) why the UK stock market remains relatively poorly valued.
It takes a lifetime to build a reputation; much less time to lose it.
Not sure which direction you are arguing in the middle there IGPJ - surely 'expectations' and 'tolerance' are not both lower?
It does seem to me though, that in the past greater efforts were made to conceal the skulduggery. Perhaps this is the result of spin-doctory.
Why bother to conceal stuff that the electorate appear not to care about?
The polls suggest that Boris would win an election tomorrow and a significant proportion of Americans (including some Democrats) believe Trump's delusions.
I often despair, but then console myself that I chose not to go into politics. It is political suicide to imply that the a significant proportion of the electorate are a bunch of impressionable idiots.
bad England.
I think the electorates expectations for standards of behaviour amongst public officials is higher, and that the tolerance level of what is seen as unacceptable is lower. That sounds like the same thing phrased in different ways but it’s subtlety different - they would expect less bad apples in a barrel and that standard which constitutes whether an apple is good or bad apple is made tougher.. Not seen any research, it’s gut feel.
The reason I say this is the democratising power of the internet which makes it easier to shine light into dark corners.
I take your point about the electorate, political apathy is reported to be rising amongst the young and they’re less likely to have a negative view of the Chinese system according to a BBC show I listened to this morning (might have been the Amol Rajan one).
I'll give you the benefit of the doubt and think of "bad England" as a bon mot ;-)
I actually thought you were pointing in the opposite direction to your clarification, and would probably have agreed, but actually you have made me think there might be a different thing going on :
Propensity to express public outrage :
Likelihood to impact voting intentions :
On reflection though there may well be a causal link to propensity to use social meeja.
Yes, the socials are definitely a double edged sword - good for exposing genuine grievance, abused for petty political point scoring over trivialities.
‘Bad England’ comes from a film, but I forget which one. One of my friends used to use it all the time :)
Happy New Year to you all, and wishing you every success in 2021!
Here are my heat maps for today (prices as at ~9:45am). Lots of big movers today, especially miners.
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volatility - volume / ATR up; moving more than a 20d EMA of the ATR):
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Big movers today (not restricted to small caps):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments. I define Small Cap using the Stockopedia Small Cap Size Group definition: Market Capitalisation between GBP 50 million and GBP 350 million.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap tile, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR related ones here in the hope that others may also find them interesting or useful. I aim to post sometime in the morning when I can, but sometimes work / family and other priorities get in the way.
greensiax
Reneuron (LON:RENE) Sudden jump today - but I cannot see any news to explain it.
Some backing on Twitter from a few decent posters
https://twitter.com/sharesearc...
Case of following the money - did research during weekend - found out that Sir Chris Evans + Richard Griffiths - 2 prolific investors had invested into the co. This news was probably spread around.. Was busy with jostling with my positions during morning due to news of tighter lockdown + S.African strain....come to investing time - SP had shot up 15%. What to do :( Decided to sit it out.
I have been a subscriber for 6 years or so and I do not post very often.
On the first trading day of 2021 I wanted to thank Paul, Jack and all the Stockopedia team for their diligence and quality of content which I and so many subscribers find invaluable.
I must apologise to Paul in particular that for 5 years I did not appreciate the significance of the thumbs up and I actually ignored it. This was a big mistake on my part but last year the penny dropped as I now realise that Paul and Jack rely on us to use the thumbs up to signify our support for what they write.
I particularly enjoy Paul`s comments on family, his beloved dog and occasionally Bournemouth a town I remember well from the 1980`s.
2020 saw some extreme volatility in the market and at the end of March my portfolio was 34% down. Thanks to some spectacular gains in the second half of the year from GAN, ITV, FXPO, TSL, SLP and FRES I finished the year up 17%.
Happy New Year to you All
Portugull
Happy new year all, one bit of news that seemed to escape the british press was while we elected to stand alone, the african continent has just created the worlds largest free trade block, 54 countries. While i'm sure that it will take them a while to get their act together, any thoughts on whether this will be good or bad for us or will it just benefit the chinese who seem to building most of the infrastructure they are going to need to make it a reality.
DJLJ23 - I worked in Consumer Goods for Nigerian companies for more than 12 years and I can tell you we are losing our foothold there very fast. Bluntly, I personally benefitted from a desire for a trustworthy white face at the top of business, managing capital for owners (both Nigerian and Expat) who wanted to live or have assets in Europe and trained talent like me was scarce so paying for 1 or 2 'British' expats was a price worth paying to minimise corruption etc. In turn I/we looked to our home market for services like design or consultants.
However, globalisation over the last 20 years now means that a vast army of well trained, globally experienced and relatively cheap middle managers from India/Gulf are available squeezing down expat salaries (good even if it did for me) but re-orientating trade flows. Secondly, in the SME space (in which I also worked for Indian and Lebanese owners), there are so many Indian and Chinese expats willing to start business and live above the shop in upcountry cities the West has never heard of to establish business. They run these businesses ruthlessly using capital from extended family as seedcorn and from these seeds the next generation of market leaders is going to come - exactly where the market of the future is. On top of this there is Chinese govt investment in ports, roads, everything long term and govt to govt. We have huge assets (vaccines?) and reservoirs of goodwill (charities) but execute remotely; the govt and business needs to facilitate British commercial boots on the ground.
Nigeria had 125mn people when I first went there in 1997; now it is 206Mn; by 2050 it is forecast at 400mn!!!
I was against Brexit but if it is to work, this has to be the opportunity area on our doorstep not the old 'White' Commonwealth of Australia and NZ or hyper competitive local relationship and far away markets of China & Asia. Yes the Africa free trade zone is/will remain largely a mirage but the world is changing forward and I fear we are looking backward.
Which British company has a clearly articulated sub-Saharan Africa strategy (excluding someone like £NXR which is really focused on South Africa) despite the fact we now have a small but rising class of black and brown British managers available and relatively good multi-cultural engagement in commerce (these things matter, word gets back) and there are significant opportunities for trade.
Rant over - subject close to my heart!
Hi Peter,
I am looking to get some exposure to African growth especially in telecoms and e-commerce. So far I have Airtel Africa (LON:AAF) and intend to add Jumia, "The Amazon of Africa" or perhaps more accurately the AliExpress of Africa. Do you have any views on these and other options?
FWIW IMHO DYOR etc etc ..... Jumia are very interesting and in my eyes, a 'proper' company. Whilst it is a rapidly moving area and I am 2 years out of the market, I think they are in a great place with the type of brand recognition/logistics lead that Amazon established in the West 15 years ago. It is their game to lose. The whole cost structure/operational reality in Nigeria is so different that I think there is a good chance for them to develop unique final mile services and approaches that will build them a moat vs global players (one of whom will ultimately buy them as the mid term potential is so large).
Online will be huge in Nigeria, especially as solar rapidly brings widespread electrification in the next 5 yrs (you only need a very little to run a cheap smartphone, I am not talking lights let alone A/C or an EV!). Prepayment/visible online prices eliminates corruption/middlemen issues and delivery centres exist to collect your parcel. Lots of potential to monetise other services over time. Because the marketplace is so decentralised and diverse it is also difficult for the govt to control - a real benefit! I have never looked in detail at Jumia as a company to invest in.......but I consistently rejected Amazon & (mistake!) am now UK centric in my investing.
In contrast, Airtel is deeply in bed with govt /regulations and thus liable to corruption/mis-allocation/co-option of resource issues. There were also internal cultural issues. Personally, I would never trust them with any of my capital ! I hope you see a very good risk/return.
Good luck.
Integrated Diagnostics Holdings (LON:IDHC) came up in my screen recently and looks really interesting to me. They provide consumer-facing medical diagnostics in Egypt (mostly). Also Sudan, Jordan, Nigeria. They have a low capital, cash-generative scalable model that looks to me like it could be appropriate for multiple African countries and also for more growth in existing countries. To be aware of: large quoted spread (although I haven't tested it yet), report in Egyptian pounds (80+% of current revenues), trade in dollars (not sure why when they trade on LSE). I need to free up some money..... If there are any holders out there: did you manage to trade inside the spread?
Interesting to see further evidence for my view that the CCP is indeed pursuing a strategy of getting multiple tiny footholds on the ground in Africa, without anyone seeming to notice, in addition to the headline investments - but even these are largely ignored by the UK press.
IMHO China will control sub-Saharan Africa within 50 years. The continent is such a mess that they will find it easy to take it over and run it, in salami-slices, slowly at first, then all at once.
I was born in West Africa and my father did a lot of business there. I have not seen any opportunities for a small cap investor for a long time.
Even more controversial is my view that China will take Australia eventually, as suggested in the E.M. Forster short story of 1909 'The Machine Stops'.
The belts and roads programme gets regular coverage in the quality press.
What’s actually missing is people caring - I spoke to my colleagues about their company cars saying don’t get Polestar or any Chinese brand in support of Hong Kong and the Uighurs - they looked at me like I was an idiot
I would wish everyone an happy new year. Something nice and also a little scary about resetting our stock performance (whether good or bad) back to zero at the start of the year and trying to guess what's in store for the year ahead.
Clearly there's cases for the bear and the bull and which way it'll go is anyone's guess but that's the fun of investing. For this year I am planning on trying to do less quick fire decisions and try to evaluate things better, last year I made too many panic buys/sells which I want to avoid. I'm going to try and stick with buying growing, mainly profitable companies in markets that are growing and overtime they will hopefully do well.
What I also think I need to learn to do better is to give up some longer term stocks which I have become emotionally attached that really don't have the long term ability to grow.
iEnergizer (LON:IBPO) Special dividend of 49.4p announced this morning - Nice start to 2021.
Paul - Keep up the great work, it's really appreciated.
Happy New Year all.
Happy New Year Paul
My morning smallcap tweet: Quiet start to 2021
Allied Minds (LON:ALM) Georgia Capital (LON:CGEO) IDE Group (LON:IDE) KKV Secured Loan Fund (LON:KKVL)
Allied Minds (ALM) update on investments. Net cash $24.6m. "The Board currently believes that if the portfolio was liquidated in the near-term, it would likely be at a significant discount to their last funding round valuations and thus to the detriment of shareholders. It believes the best way to fully realise the potential value of the portfolio will be through future exits which require more meaningful progress and investment at each of the companies." [SP=32.5 Cap=78m]
Georgia Capital (CGEO) water utility tariffs hike mean 38% growth in allowed water rev in next 3 years. [SP=540 Cap=258m]
IDE Group (IDE) wins 'significant' contract with an existing customer, worth £22.5m tot over 3 years in addition to current £5m PA. [SP=0.79 Cap=3m]
KKV Secured Loan Fund (KKVL) suspended since results late. [SP=17.28 Cap=112m]
how about giving advance notice of when trading updates are coming out ?
Happy new year Paul. Anytime in the future that a comment here gets you down just go back and read the SCVR for Christmas Eve and all the praise and positive comments that were made about your work here.
Hi Martin , I know not all companies, especially small ones, do provide dates for investors, but a lot do have a Financial Calendar on their company website in the investor section . AIM cos are not so good at doing so though for sure.
IG have a Week Ahead newsletter which gives this type of info. But it does not cover all companies. Often small caps are omitted. This week:
Constellation Brands,
Bed Bath & Beyond,
Walgreens Boots Alliance,
Micron Technology,
ConAgra Brands
Morrisons,
Next
Greggs
Marks & Spencer
The London South East site (LSE!) has a financial diary that includes all scheduled updates / reports notified in advance. It can be displayed daily, weekly or monthly (past and future).
URL: https://www.lse.co.uk/share-pr...
Sharecast seems to have identical info, just in a different format....
Sharecast Company Diary
greensiax
Thank you, that is very useful, i thought that site was a paid for resource so didnt bother looking.
Richard
For companies I am particularly interested in, I'll look back to see when they published updates last year and stick an entry in my own calendar for this so I know roughly when to expect them.
Hello Paul, and a very happy New Year to you.
"Abbreviations - if you must use them, please include a footnote to say what they mean, as it’s not always obvious to people outside a company’s sector."
I 100% agree with this. My other real bugbear is people who use non-English phrases, for example Latin or French, because they think it makes them sound clever. It doesn't. This is an English language website so let's talk in English.
Very best wishes for 2021,
Steve
Kleiner englander!
Englander surely!
Happy New Year Paul. May most of your speculative positions deliver great outcomes, and may you continue to entertain and inform us for many years to come.
Jon
Thanks Jon. Although I'm rather hoping that my investments perform well, not just my speculative positions!
Happy New Year Paul, hope you and paddy have a great 2021. I always enjoy reading your general views/thoughts as well as the company reports. The SCVR is essential every day reading for me, I feel I have learnt so much from you since becoming a member. So thank you for all your efforts and I look forward to it continuing in 2021.
Ps please do keep up your excellent in depth coverage of Boohoo (LON:BOO) and Saga (LON:SAGA)
Paul, In my excitement I forgot to wish you a Happy New Year!
Entain (LON:ENT) 2021 off to a bang!
https://www.wsj.com/articles/m...