Small Cap Value Report (Mon 4 Mar 2024) - RENX, VTU, TTG, SHOE, RDT, SONG, QTX, CRW

Good morning, it's Paul & Graham here!
The Week Ahead - today's article from Megan is an interesting read. Looks like Graham and I will be very busy Tue-Thu this week, with loads of results coming out, and of course the Budget on Weds (see Tuesday's papers for details!)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Mid-morning movers (with news) -
Shoe Zone (LON:SHOE) - up 7% to 260p - tipped in Times (persuasive article, it does look cheap!) & SCSW over weekend.
Rosslyn Data Technologies (LON:RDT) - down 28% to 11.75p (£3m) - another year of heavy losses expected, due to contract signing delays. Only £800k cash left, so another fundraise or delisting now look inevitable. “confident of securing further sizeable contracts in the near-term.”. Looks very high risk, and a stale story (v poor track record), but it’s in a sexy sector - could sentiment turn on contract win announcements maybe? Claims that its new AI module, “offers a transformational opportunity”. One for optimists only!
Hipgnosis Songs Fund (LON:SONG) - down 10% to 56.8p - bombshell from the new Board. Says its songs catalogue NAV is worth a third less than previously advised. Dividends stopped “for foreseeable future” to focus cashflows on reducing debt - the 8.3% yield was the main reason to own the shares, so this looks bad.
Summaries of main sections
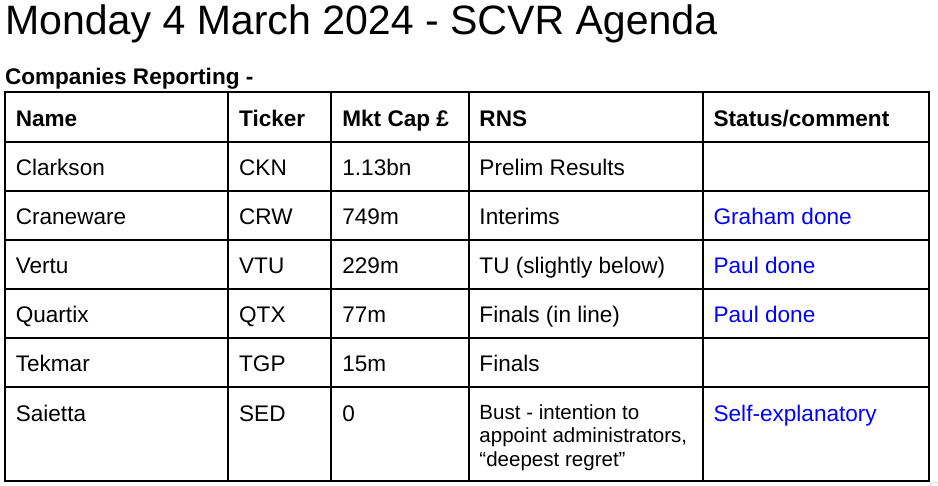
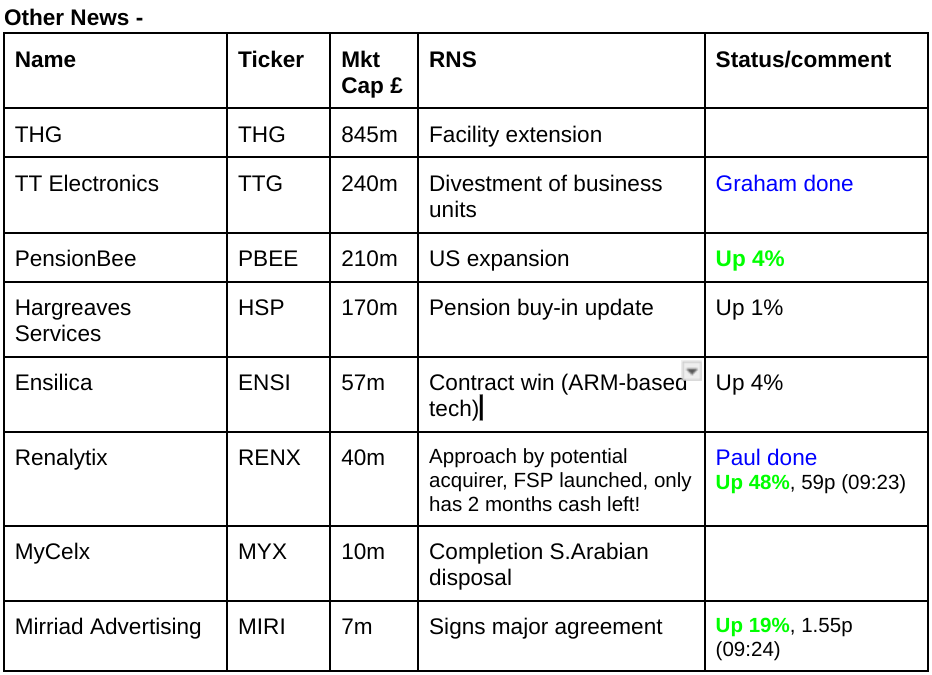
Renalytix (LON:RENX) - up 58% to 63p (08:48) (£63m) - Possible bid, FSP, funding - Paul - RED
Trying its best to sound positive, but this almost-bust heavy cash-burner admits it only has 2 months' cash remaining. So potential bidders might be motivated to try to buy it from an administrator, rather than existing shareholders? It remains very high risk until fresh funding raised and/or bid talks held. Yet another blue sky project that has destroyed an immense amount of shareholder value, and run out of cash.
Vertu Motors (LON:VTU) - 68p (pre-market) £228m - Trading Update - Paul - GREEN
Slightly below expectations update for the 11-months to 31/1/2024, within FY 2/2024. Shares are slightly up in early trades, so looks like traders are reassured that things are not any worse after a profit warning in Dec 2023 (caused by a sharp fall in used car prices). I'm happy to go back up to green, as uncertainty removed from the previous PW. Shares are at par with NTAV, so 100% asset-backed (mainly freehold property).
TT electronics (LON:TTG) - up 0.6% to 136p (£241m) - Divestment - Graham - GREEN
TTG accelerates its deleveraging process with the £20.8m disposal of some business units. In combination with healthy profits in 2023 (even if they are at the lower end of the previously forecast range), I’m looking forward to a very meaningful reduction in its £139m net debt.
Quartix Technologies (LON:QTX) - up 2% to 163p (£79m) - Final Results - Paul - AMBER/GREEN
In line with expectations audited numbers for FY 12/2023. Confident outlook for 2024, and I wonder if the reduced forecasts might be beaten later in 2024? Some problems, but these are being dealt with by the Exec Chmn/founder who has come out of retirement to sort things out in a back to basics strategy that looks simple common sense to me. Overall I'd like it a bit cheaper to buy some myself, but I see more upside than downside, so let's go with AMBER/GREEN.
Craneware (LON:CRW) - unch. at £21m (£743m) - Interim results - Graham - AMBER
Solid numbers from Craneware today as they report 8% revenue growth in H1, an improvement on the growth number reported at the most recent full-year results. The outlook for the year is unchanged. An impressive software success in the US healthcare sector.
Paul’s Section:
Renalytix (LON:RENX)
Up 58% to 63p (08:48) (£63m) - Possible bid, FSP, funding - Paul - RED
I mentioned this share recently, pointing out that despite positive-sounding operational news, the figures showed that the company was almost bust, having run out of cash. So it's highly precarious until refinanced.
Today news says -
Possible bid approach -
“Renalytix has received an unsolicited approach from a large and well-capitalised publicly listed strategic diagnostics company, which is in the process of evaluating an acquisition of the entire issued, and to be issued, share capital of the Company.”
Great, but on what terms, given that the company is in such a weak financial position?
Formal Sale Process (FSP) launched, to drum up more potential interest. Might decide to remain independent & stock market listed (mentions AIM and NASDAQ).
Takeover panel has given a dispensation from 28-day PUSU rule, and that potential bidders will not have to be publicly named.
Stifel is being appointed adviser for FSP.
Cash position - admits it’s almost out of cash -
As part of a review of funding options currently being explored, the directors of Renalytix (the "Board") are considering possible sources of funding, including equity and debt. The Company is in advanced discussions with certain existing shareholders as well as potential new equity and debt providers.
The Company has cash on hand of $2.3 million and marketable securities of approximately $1.4 million as at 3 March 2024. As reported on February 15, 2024, operating cost reductions commenced during the fiscal second quarter continued with a fiscal third quarter cash burn target approximately 33% less than in the prior quarter and approximately 50% less than in the first quarter of fiscal 2024. The Company expects existing cash resources to finance the business through April 2024, foregoing the possible Sale of the Company and/or its assets, or successful completion of the advanced financing activities noted above.
Paul’s opinion - an interesting project, with some impressive shareholders (Harwood has 10%), but cash burn has been large, and it’s been obvious for some time that the cash was running out - hence terrible shareholder value destruction.
It’s now just a lottery, to see if anyone is either prepared to buy it (at what price though?), or refinance it. RENX is in such an obviously weak position, it would only have any bargaining power if several parties are prepared to compete to buy or refinance it. So a fairly good chance that small shareholders get hung out to dry, I'd say, but anything could happen.
Yet another blue sky project that has been a disaster for shareholders, and inadequately financed.
Vertu Motors (LON:VTU)
68p (pre-market) £228m - Trading Update - Paul - GREEN
Vertu Motors, a leading UK automotive retailer with a network of 188 sales and aftersales outlets, is pleased to announce the following update with regards to the five-month period to 31 January 2024 (the "Period") ahead of its preliminary results for the year ended 29 February 2024 to be announced on 15 May 2024.
It packs a lot into this headline below! -
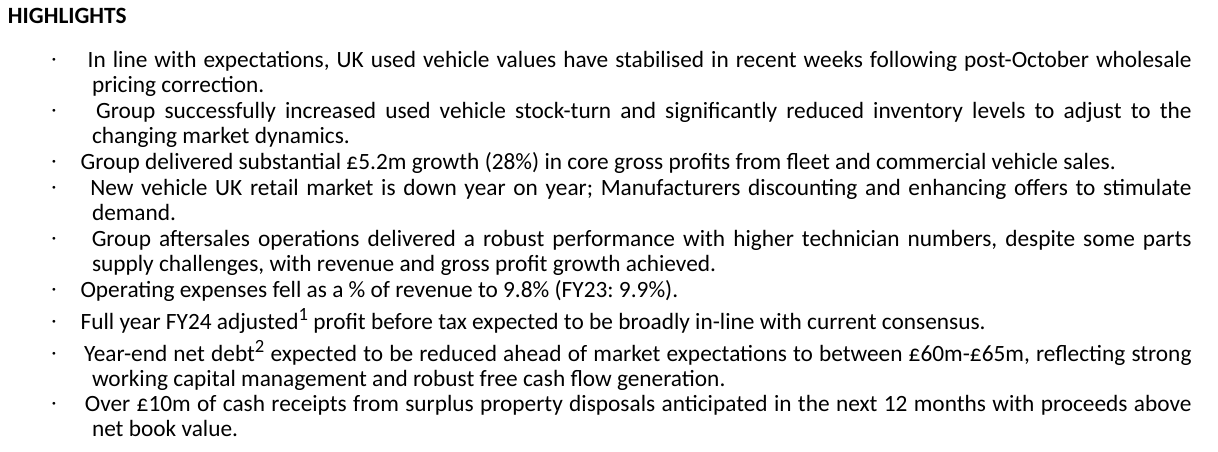
Used car prices stabilised; new vehicle market uncertain; aftersales robust. Strong year-end cash position
Key point is this -
Full year FY24 adjusted1 profit before tax expected to be broadly in-line with current consensus.
1 Adjusted for exceptional items, share based payments charges and amortisation.
How much below then?
I’ve not yet seen any updates from brokers. Zeus downgraded FY 2/2024 forecast EPS by 17% to 8.2p back in Dec 2023, in reaction to news that secondhand car prices had plunged unexpectedly quickly and by a significant amount. We had similar news from Motorpoint (LON:MOTR) too so it’s a sector thing, and should be a temporary impact.
“Broadly in line” probably means something like 8.0p EPS maybe? I’ll have to wait for broker updates to feed through.
EPS of 8.0p would mean a PER of 8.5x
Other points - I’ll copy this to save typing -
Valuation - Stockopedia stats are based on the forecasts, which is 10.0p EPS for FY 2/2025, hence the PER below being lower than my figure above for FY 2/2024.
Also note the very strong asset backing (mostly freehold property) which we’ve mentioned here many times before. Despite this, Vertu is one of the few car dealers that didn’t receive a takeover bid!
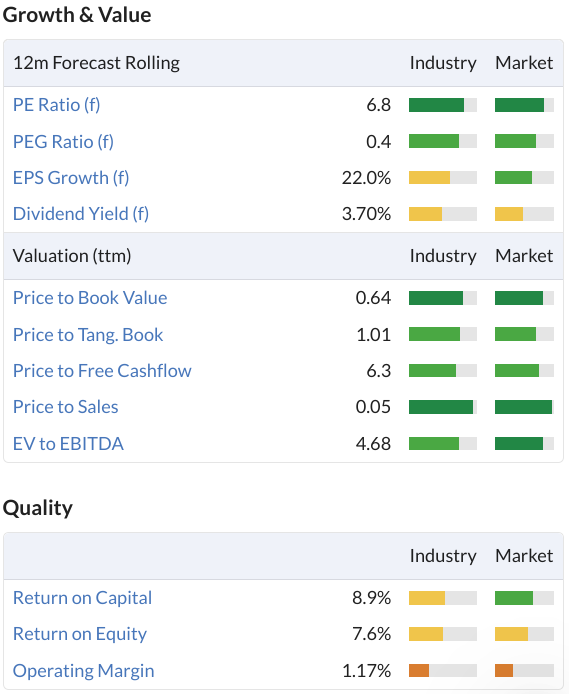
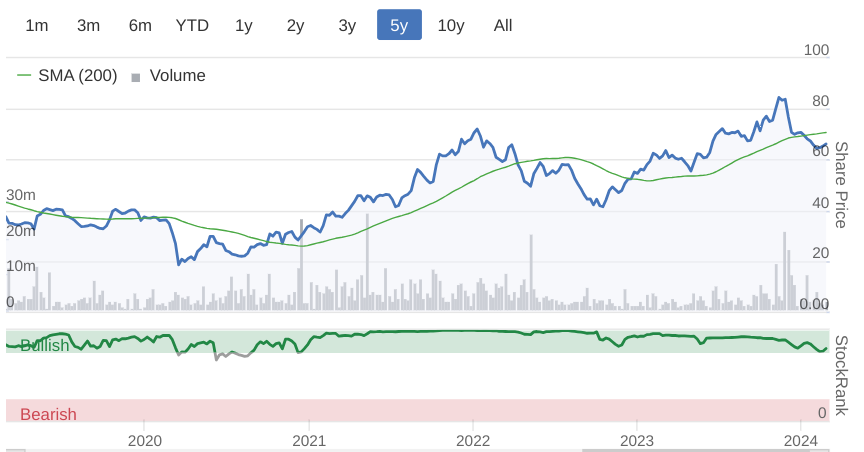
Paul’s opinion - the share price reacted badly to the profit warning late last year, and now looks into attractive value territory again.
Questions are also being asked about the imminent Chinese invasion of something like 20 new electric car brands, which surely must do some damage to European makers? Although there also seems reluctance from the public to buy electric cars.
With a share price now at par with NTAV, I see VTU as an attractive each way bet (part car dealer, part property company). Last time in Dec 2023 I went down to amber, due to uncertainty over the profit warning and used car values. Now that we know trading has stabilised, I’m happy to see it as GREEN again.
Quartix Technologies (LON:QTX)
Up 2% to 163p (£79m) - Final Results - Paul - AMBER/GREEN
Quartix Technologies plc (AIM:QTX), a leading supplier of subscription-based vehicle tracking systems, analytical software and services, is pleased to announce its audited results for the year ended 31 December 2023.
This 10-minute video from Quartix’s Exec Chairman (and founder) Andy Walters is a good summary, with useful slides, outlining the main points.
Revenue up 8.6% to £29.9m
(revenue growth of 10.6% in the core fleet business has been partially masked [over several years] by a wind-down of its small insurance telematics division, now almost eliminated)
Adjusted profit before tax decreased by 12.2% to £5.1m (2022: £5.8m) - mostly blamed on operating losses from a failed acquisition (Konetik) made by former mgt.
Statutory loss (first in the company's history) of £(0.9)m caused by £3.8m provision to replace old 2G boxes in France, and a £2.7m goodwill write off re Konetik.
Adj diluted EPS down 20% to 8.74p = PER 18.6x
Dividends cut to a total of 3.0p, down from 10.15p (incl specials) for 2022.
What went wrong? Well explained previously, and in today’s results - former management are blamed for a poor acquisition, which is now being dealt with. So that’s a temporary issue, which doesn’t worry me. Secondly, former management lost focus on the core business.
What’s being done about it? The founder returned, and is implementing a straightforward back to basics strategy -
Accelerate growth
Konetik acquisition - eliminate future costs
Lower manufacturing costs to improve gross margin on kit
Improve product features
Stop price erosion with RPI increases in contracts
That all sounds completely sensible to me, and should allow profit to recover, and divis to return to the previously generous levels of the past.
Outlook - sounds confident -
We have started the new financial year positively, with new installations in January approximately 10% ahead of the same period in 2023. This, alongside the opportunities for continued growth in all territories, and particularly in Continental Europe, underpins our confidence for 2024 and beyond."
The Company believes that market expectations for 2024 are as follows: revenue: £32.1m ; free cash flow*: £3.4m ; adjusted EBITDA: £5.4m
* Note excludes expected cash expenditure of £2.5m on 4G upgrade programme during the year.
Balance sheet - only £2.3m NTAV, but it’s an asset-light, and cash generative business that pays out cash generated as dividends. Maybe it should keep a bigger cash buffer, for any future unforeseen problems?
Paul’s opinion -
Bull points
- High recurring revenues
- Sticky customers (SMEs) with long lifetime
- Historically high margin, and cash generation, with generous divis - unusual for a tech co
- Owner-managed still
- Large Director buy recently
- Turnaround plan looks highly likely to succeed, just going back to basics
- Bear points
- Price erosion & (low) customer attrition combined can offset new customer wins
- Loss of focus and a poor acquisition - but these are now being corrected
- EPS has been declining for 5 years - can this be reversed into growth?
- Valuation is still not cheap, despite big share price falls
- Substantial costs of mobile network changeovers, has hit profits several times
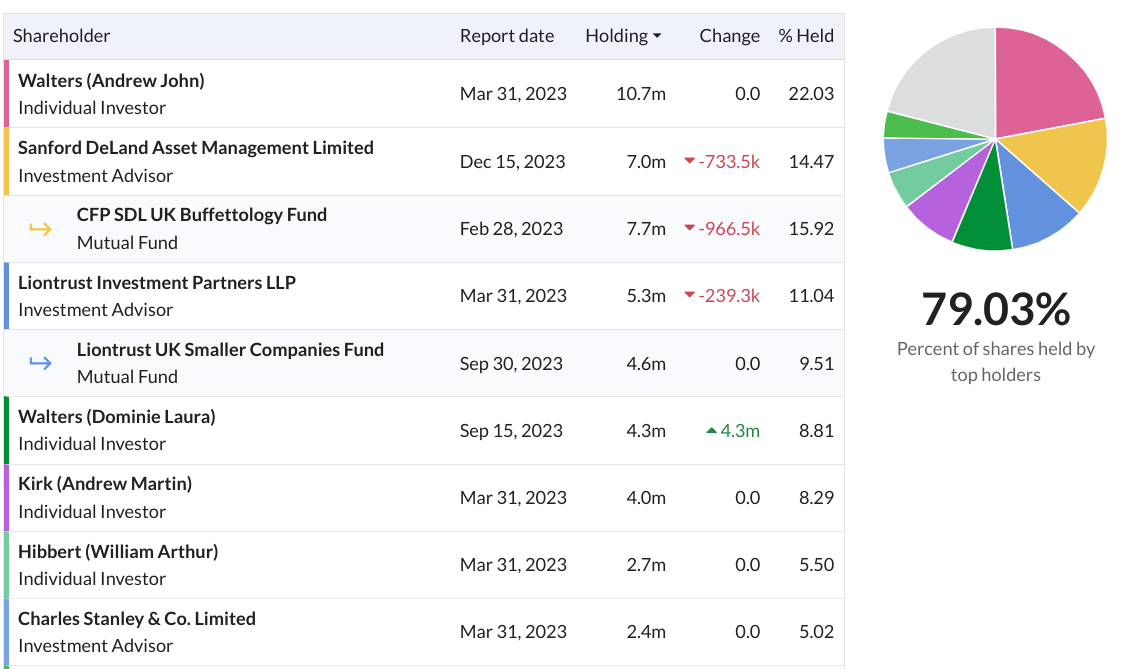
- Possible selling overhangs from institutions?
Overall, I suspect QTX shares could be getting near to the low point, although I like things to be astonishingly cheap, and sentiment on the floor, to coax me into buying. So I’m not sure risk:reward is quite good enough to make me a buyer, but I can certainly see a good turnaround here being the most likely outcome in the next few years. If growth in international markets really starts to take off, then this share could get a decent upward re-rating.
I’ll stick with AMBER/GREEN for now - moderately positive overall.
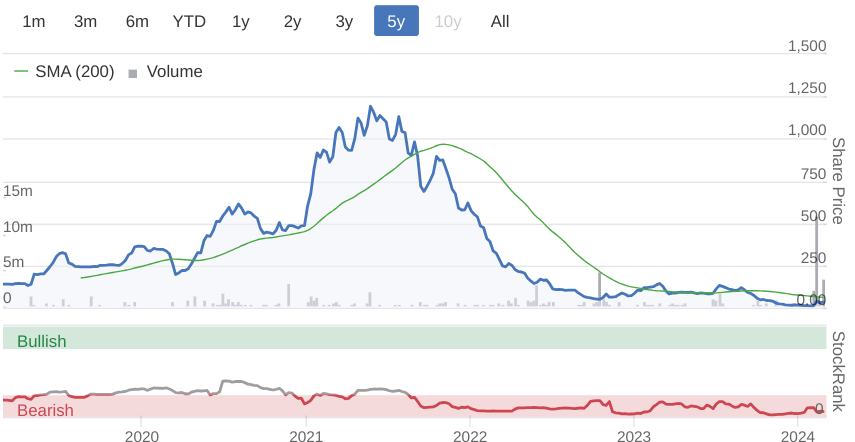
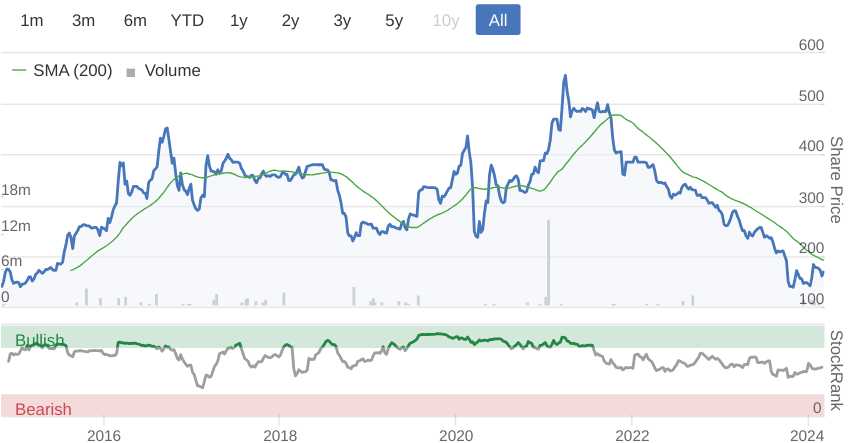
Shares have almost done a 10-year round trip, albeit with shareholders collecting generous divis along the way -
Not much free float, so QTX shares tend to be illiquid with a wide spread - note 2 instis seem to be sellers, especially SDL which has had a problem with redemptions -
Graham’s Section:
TT electronics (LON:TTG)
Share price: 136p (+0.6%)
Market cap: £241m
For over a year, I’ve been positive on this “global provider of engineered electronics for performance critical applications”.
But the market hasn’t been too impressed by it:
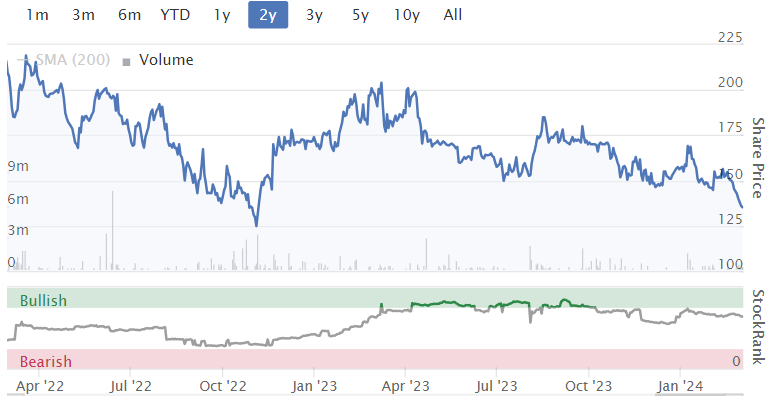
Things weren’t helped by a profit warning which we covered here in November. Adjusted PBT for 2023 would hit the lower end of the range (c. £43m), due to the breakdown of some machinery in its “Sensors and Specialist Components” division.
The investment thesis at TTG is that the company will successfully deleverage (net debt last seen at £139m), and this will get its valuation back to a more respectable level:
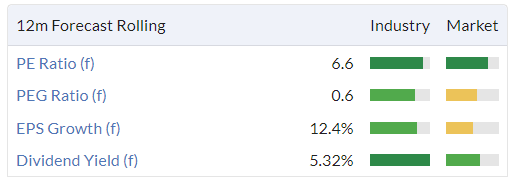
Today’s news should be positive from that perspective. The company has:
…reached an agreement to sell three business units within the GMS (GN note: Global Manufacturing) and Power and Connectivity divisions to the Cicor Group for a cash consideration of £20.8 million on a cash and debt free basis, subject to normal completion account adjustments.
Two of the units being sold are in the UK, while the third is in China.
The buyer is listed on the Swiss Exchange (ticker: CICN) and is not actually bigger than TTG, either in terms of revenues or market cap. But its balance sheet is probably much safer!
The benefits of the disposal to TTG are:
£20.8 cash consideration will be used reduce TT’s existing debt
“Expected operating margin enhancement of c. 50-70 basis points”
“Simplified operational footprint”
Comment by TTG CEO:
"We are focused on being a more profitable and resilient business underpinned by a strong balance sheet and operating in attractive growth markets.
This simplification of our portfolio will further improve our financial profile and allows TT to focus on delivering value to our stakeholders by focusing on our core growth markets, strengthening the balance sheet and driving margin progression. Today's announcement demonstrates our disciplined approach to our portfolio and provides a good home for our colleagues transferring to Cicor.
Graham’s view
As a general rule, stock market investors should be pleased when their CEOs choose to make principled divestments. Incentives for management teams usually guide them away from reducing the size of their empire.
Secondly, as disclosed in today’s RNS, the units being sold by TTG haven’t been contributing much towards profitability. For a start, their disposal will increase the operating margin of TTG as a whole. And in 2022, they contributed a small pre-tax loss despite aggregate revenues of £72.5m. So I’d hope that this disposal might help to improve TTG’s quality metrics in 2023 and beyond.
I was hoping that TTG would deleverage by itself, using its own profitability, but I can’t really complain about a c. £20m disposal to help speed the process up. Especially as it seems the units being sold weren’t contributing much to the financial performance of the group as a whole - hopefully they can be improved in the hands of their new owner.
So I’ll keep my positive stance on these shares. With c. £43m of PBT in 2023 and now with the help of this disposal, I’m hoping for a very meaningful reduction in net debt. Perhaps the market will then start to treat these shares with a bit more respect?
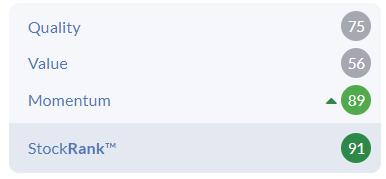
Craneware (LON:CRW)
Share price: £21 (unch.)
Market cap: £743m
Craneware (AIM: CRW.L), the market leader in Value Cycle solutions for the US healthcare market, is pleased to announce its unaudited results for the six months ended 31 December 2023 (H1 FY24).
I’ve had a call with the management at Craneware this morning so my thanks to them and to their advisors at Alma for setting this up.
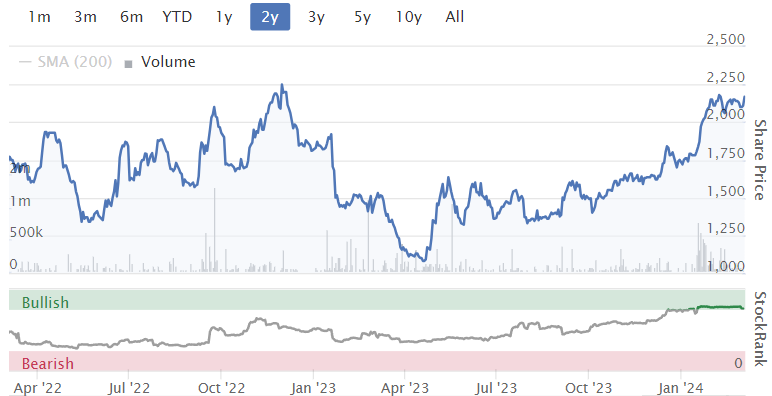
Craneware is a highly rated stock whose valuation has more than doubled from the low it was at last year:
Before giving you the bullet points from my management Q&A, here are the interim results highlights:
Revenue +8% to $91.2m
ARR +3% to $171.4m
Adjusted PBT +8% to $17m
EPS +4% to 42.8 cents per share (33.8p per share)
As for cash and debt, the company reports cash reserves of $64m vs. total bank debt of $59m.
I asked the company about its cash/debt strategy in my previous Q&A with them. They signalled at the time that they were comfortable with the small net debt position they were carrying, but that they may seek to pay down some of their debts early - which they have now done.
Operational highlights summary:
Positive response to new "Optimization suites” for hospitals.
Customer retention over 90%
Partner programme contributing to revenue growth (3rd parties now using Craneware’s data platform Trisus).
Outlook is in line with expectations.
“Market backdrop strengthening with US healthcare and hospital customers re-focusing on their future”.
“Continued and growing high levels of contracted recurring revenue”.
CEO comment:
"Our growth in the first half of the year is tangible evidence of the return of healthcare providers' focus to their strategic priorities and their increasing investment in technology to provide the insights to achieve them.
"Through our investments in the Trisus platform, Craneware is well positioned to support our customers in this transformation of the business of US healthcare, providing us with a sizeable opportunity and growth lasting for the long term.
"We have entered the second half of the year with good sales momentum and focus. We remain confident in the delivery of results for the year in line with current consensus, further growth acceleration over the near term, and our ability to create further long-term value for all stakeholders."
Management Q&A
Many thanks to Keith Neilson (KN) and Craig Peston (CP) for answering some questions for me.
Sales momentum - KN pointed out that “sales”, revenue and ARR are growing at different rates in accordance with the accounting rules and revenue recognition. Sales agreements might grow quickly, but then revenue and ARR will be lagged as it takes time for the revenue to be recognised and for it to be recognised within recurring revenue. The argument being made is that while ARR growth was 3% and revenue growth was 8%, the underlying sales momentum points to these growth rates picking up in future periods.
Revenue from 3rd party businesses using Craneware’s platform - Craneware has collected a vast amount of data on its platform (“200 million unique patient encounters”) and it has recently found new ways to monetise this. Examples given include pharmacy businesses reconciling cash movements, distributors using the platform to solve logistics problems, and other software companies plugging into it with their own solutions. This is still early-stage but the company is keen to continue growing this source of revenues.
Healthcare customers, current economic conditions - the US healthcare system is now in a post-Covid environment and while the effects of that era haven’t completely lifted, more than half of Craneware’s customers are now thought to be profitable again (and therefore in a position to invest for the future).
Growth profile - about 80% of sales growth is sales of new products to existing customers, whereas 20% of sales growth is from new customers (who in future periods will contribute to that 80% growth). The Optimisation Suites are an important source of growth: this is where individual products are packaged together to solve particular problems.
Competition? KN acknowledged that individual products have competitors, but said that the overall Craneware platform did not have competition. In terms of market share, the company estimated that 40% of US hospitals have been reached as a “landing point”. In terms of individual product categories, Craneware is thought to be the largest in the three core categories of Strategic Pricing, 340B and Pricing Integrity.
Financial strategy - with investors in mind, management were keen to point out that the company has reduced its debts and offers a modest but well-covered progressive dividend yield (yield is 1.3% according to Stockopedia).
Graham’s view
My personal stance on this company has been neutral, on valuation grounds. I would normally expect higher revenue growth from such a highly-rated company:
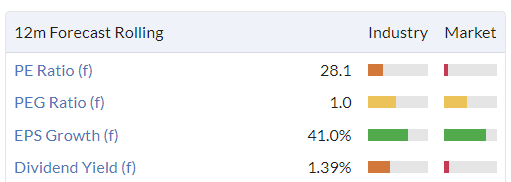
The share price gains over the past 12 months suggest that I’ve been too cautious, but what of the future?
I think the company could generate upside for investors if:
Double-digit sales growth translates to sustainable double-digit revenue/ARR growth. Maybe a boom in healthcare spending, after a relatively quiet period over the past few years, stimulates demand for new and existing products from Craneware?
Other businesses could become highly profitable customers as they seek to use the enormous Craneware dataset and platform.
Valuation: the market cap translated to dollars is c. $940m.
Net cash is approximately zero so let’s use this figure as the enterprise value.
With an ARR of $171m, the company is therefore trading at about 5.5x ARR.
In a US context, I think that this would be considered quite ordinary, i.e. still offering plenty of upside if the company outperforms or turns out to be of higher quality than the average software stock.
Personally, I would look for better bargains than this, but I remain impressed by Craneware’s progress.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Looking at Rosslyn Data Technologies (LON:RDT) Stocko / Paul last commented in March '...but it’s in a sexy sector - could sentiment turn on contract win announcements maybe? Claims that its new AI module, “offers a transformational opportunity”. One for optimists only'
I think that optimism could be about to pay off. They've recently announced a "Major new client win" with Amazon! But surprisingly to me the market has yet to pick up on the story.
This is not just as a supplier, but with AMZN funding a JV technology development. This was the result of a 9 month extensive competitive tender process.
"This initial contract is with the Customer's central procurement division and, upon successful deployment, has potential to expand to at least a further ten departments." Cavendish actually say it would be expanded to include a further 15 to 20 divisions.
Plus more contracts at advanced stage.
This is surely transformational stuff for £2.4m valuation RDT. If it works out then this will surely multiply from here.
Good volume on TT electronics (LON:TTG) Microlise (LON:SAAS) and Likewise (LON:LIKE) today. Some buyers in Treatt today also.
Market seems to have given up on TTG, too much debt stands out but todays news will help. Share count is the same as it was 30 years ago. If you believe EPS forecasts then its about as cheap as its been for 14 years
Microlise (LON:SAAS) was added to the SCSW portfolio in Feb, so readers following them I guess. Big trades today
Ahh that would explain the early volume in SAAS, not sure the 1,000,000 buy/sell is a subscriber but you never know :)
On a quiet day, does anyone have any insight regarding Renold (LON:RNO), and the fact their Employee benefit trust has again announced an increase in their holding?
They are now at 27.3m shares (12.13%), making them the 2nd largest holder. Quite a significant increase from a few months ago:
The benefit trust "satisfies awards made under various employee incentive schemes when issuance of new shares is not appropriate".
I'm just wondering why they need to significantly increase their holdings by that much. Are they rapidly expanding their incentive schemes? Or has employee performance been so good they need to reward more than they thought? Are they just 'stocking up' while they think they are getting a good price?
Maybe I'm trying to read too much into it...
Renold (LON:RNO) let’s hope it’s because they’re stocking up because the price is too low ;)
Renold (LON:RNO) if the employee benefit trust owns over 12 % its likely that Robert Purcell is going to do well…unfortunately dividends for shareholders aren’t pari-passu
Hi Paul, thanks for the podcast. Just a thought but Paul Hill attaches a time to each company covered in his videos. So I know if I want to hear about a certain stock I can quickly find it. I have no idea how you do this (useful!) however if it is fairly straightforward and not time consuming could you have a look at it? It has the advantage of saving time. Sometimes also as I listen I am also doing other things and I miss the name of the stock you are discussing so have to track back. All my own inefficiencies I am sure but any help appreciated.
Yet again, a thoroughly entertaining and informative podcast on Saturday. The really important lesson for investors, spend quality time with Mum.
Reference in the podcast how the greens and reds performed, and Paul wasn’t exactly sure of the figures, here are my observations on the greens:
Since 26 October until end of last week, there have been 145 greens on SCVR. I further researched (as opposed to blindly following Paul and Grahams greens) and bought approximately £1000 of 32 of these companies (22% of greens).
Results to end of last week:
17 winners, average return 13.1%
15 losers, average return -5.4%
Overall return, 4.4% exc dividends
Benchmarking each purchase against FTSE 100 (perhaps I should benchmark to AIM or small cap, but I have not). If I would have purchased FTSE 100 index rather than individual companies, I would have been 2.0% up. Thus the Greens I selected have outperformed FTSE 100 by 123% (4.4% v 2.0%) so far.
5 best winners:
RNO +36%
BVXP + 35%
BMY +31%
JET2 +24%
KITW +22%
5 worst losers
IPF -15%
CGS -9%
MSI -9%
SOLI -8%
BAG -7%
As yet, I have not sold any “green” buys. I am likely to sell if Paul/Graham move downwards from Green. I am also likely to sell if any go to -20%, or if any share after six months of holding hasn’t beaten the FTSE100.
I heard about a fund manager from decades ago. He ran a US university fund, I believe. He absolutely trounced the indices. His strategy was simple. He looked at Goldman Sachs buy recommendations, and if the company was rated its highest rank, he bought.
Another interesting story is by Robert Kirby, former portfolio manager at Capital Group, who talked about the performance of a client's husband, and the strategy he adopted. https://www.diywealth.com/blog...
Interesting Orval, to compare to a simple low fee passive investment, say the HSBC FTSE All World (I hold) which I think has gone up about 14% over that period so somewhat better than the 4.4% of the basket of Green rated stocks.
It's nice to have the likes of Renold (LON:RNO) (I hold) etc. which have performed so well but, overall, the duds can really bring the average down so that the, no research required, passive investment can out-perform.
Paul, thanks as ever for the great podcast.
re the change of mgt at Tortilla Mexican Grill (LON:MEX). i would have thought it would be the ideal business to have a 'bean' counter in charge'
Re Tortilla Mexican Grill (LON:MEX)
Yes I agree, and think I mentioned that in one of the 3 podcasts this weekend (audio quality on part 2 was so bad, I had to re-record it from scratch on Sunday), Tortilla (I hold) is an established brand and format, and all the CEO really needs to do is not make any big mistakes by signing terrible leases, etc. So a bean counter who focuses on squeezing the margin up without ruining product, keeping tight control over the branches and all the operations, and doing a sensible roll-out of new sites with attractive economics, is all I'm looking for. Andy Naylor should be a safe pair of hands I think.
Meanwhile I think the recent clear out of an overhang with some large trades going through, from Luke Johnson & Matthew Peacock both going above 3%, could be a turning point, possibly? Time will tell. Neither has enough to impose their will on MEX, and they've not committed significant money into it (only c.£530k from LJ), so I'm not getting over-excited about things yet, but its good to see something happen anyway.
in case you missed i meant 'bean' counter for mexican food
Ah I just spotted that, doh! Very droll! :-D
I asked ChatGPT to invent some mexican-themed puns for me to reply with, but after 60 attempts, I had to tell it to stick to the day job of replacing call centre workers.
As a long term (small) shareholder of Quartix Technologies (LON:QTX) I was interested to read the results today and your commentary Paul. Not much surprise in the loss results due to advance notice of costs of replacing the obsolete 2G and 3G kit and the write down of the disastrous acquisition in September 2023 which cost the previous CEO his job. Now the founder and former CEO is back there is hope for a turnaround.
The reduced dividend was forewarned so no surprise and explanation given in the results for the deviation from the stated dividend policy.
Encouragement for me is that the founder is back in charge and knows the business well. Also revenue is up and sales looking encouraging in the early part of 2024.
Concerns are the notes in the accounts talking about price erosion. I've also learnt more about the market and it is a very competitive space, Quartix isn't even in the top 10 players so I don't see any moat they have. The only things that keep me here are the quality metrics and the turnaround potential.
I monitor ten investment trusts. The average discount to NAV was 9% at the end of 2023, 10% at the end of January increasing to 11% at the end of February. I regard this as another illustration of the negative sentiment towards the UK stockmarket.
Stevenlondon3 - The Money Makers weekly podcast shows the average investment trust discount (excluding 3i) every week. It's currently 16% and has been 19% in October/November 2023. Jonathan Davis is well worth listening to every weekend. He's excellent.
https://money-makers.co/
Hi Topvest; Is Jonathan Davis related to the John Davis , excellent Editor of the past Magazine "Investment Trusts" Published by Flaxdale Printers. Certainly miss that source of information and advice.
Hi.
I bought into Vertu Motors (LON:VTU last week. I have been monitoring them for a while and have held in the past. Cinch have increased their stake to 9% and I my hunch is that something is brewing in the background.. Stifel were appointed broker and advisor on Friday.
Otherwise I like the business and the strong asset backing and low valuation and see it either as a sitting duck for a takeover or a incremental buy and build car empire!
Love to hear other thoughts, I'm not sure of the significance of Stifel being involved but it has been noted here that their USP is acquisitions and mergers ?
TT electronics (LON:TTG) is another I've been monitoring, so will do some research today.
bsharman - I must say I used today as a buy signal and opened a position in Vertu Motors (LON:VTU) . The change in broker last week was a hint at a possible buyout, I contemplated a buy but was worried about the impact of another profit warning. When this was followed the next day by a trading update... what a lovely coincidence. I waited to check there was no significant move down this morning which their wasn't and then opened a position. I don't expect the share to drift down any further from here, a GREEN from Paul gives confidence around the balance sheet and when I watched the CEO's pre recorded talk about the company released this morning he seemed positive, particularly around reducing the debt and the stabilisation of the used car market. Risk reward seems good, a stabilising market that could improve with the potential of a bid thrown in for free.
Vertu Motors (LON:VTU)
Love to hear other thoughts,
had a quick look through news today - good news was the lack of any specific bad news really , with used car prices dropping one might have been slightly worried that expectations would be moved down . Note perhaps the following statement does confirm that perhaps brokers will make a modest reduction overall ref expectations but imho broadly in line isnt really a miss (probably more at bottom range of expectations)
OUTLOOK
Full year FY24 adjusted7 profit before tax expected to be broadly in-line with current consensus.
TT electronics (LON:TTG)
had aquick look here and whilst it does look cheap on pe basis - but debt is material and they also have material supplier payables owed out. So whilst it does look good value on p/e i can see why it is on a a cheapo rating . Hey ho just have to look at mcbryde at what can happen if companies start to up up profits and get debt expectations reducing. Not sure if future cashflow is expected to be better than their patchy recent history of failing to turn profits into matching positive cashflow. Just look at the tragedy at xpp where they had trading issues at the same time debt had materialy risen - doesnt take much to go wrong for sharepirce to be hammered whne they have so much on the owed out side of the balance sheet.
At a quick look net debt and suppliers owed are both materially high than "back in then day" of say 2014 - so does look like this company has soemwhat struggled to stand still over the last 8-10 years. Not sure if its investment in working capital or acquisitions that has sucked up the cashflow here over the years ?
Georgia capital and Bank of Georgia
Very much remains a “special situation” almost arbitrage situation now .
Bank of Georgia still rising on the back of its acquisition now valued at 2.35 billion
G. Cap owns 20% of bank of Georgia so that’s 470 million
G Cap market cap 542 million
So 72 million for the non B o G assets .
Let’s say in terms of recognising a blue chip asset there should be no discount to the B of G holding as it would be veasy to realise for cash .
So calculations
40736526 share count
Bank of Georgia underpinned vakuation now 470 million
470 million divide by no shares says 11.53 pounds of “value “ is from bank Georgia
Share price is 12,78 , So 1.25 is the share price attributed to the non B of G holding
Last valuation for non B of G assets was 53.8% of the NAV so 14.57
So if you are so bold as to not apply a discount rating to B of G then you are getting 14.57 of unlisted assets for 1.25
This is a 91% discount to NAV .
I’ve checked my numbers a couple of times and think I’m right so if you are prepared to vakue B of G at 100% of book then it’s an anamolous. Special situation .
And G Cap have been realising assets at above NAV in past year or so .
Market is fast asleep to this, as I think there is a rule that B of G holding can only be a certain % they will be “forced” to realise that for cash .
It’s currently in top of the pops number one position in all my holdings .
So as you know planetx I also have both as high conviction holdings for me so also see plenty of value here.
However, I would say that the BoG stake should not be valued at par from a Georgia Capital (LON:CGEO) perspective as there is no way they could realise that value at no discount. Let’s say they did an institutional placing (secondary sale) you’d expect maybe a 10% discount to price. So maybe the BoG stake is realisable at circa 1000p worth of CGEO share price.
Still, an 80% discount to the private assets NAV looks anomalous - particularly given the type of assets they hold. None of these are blue sky cash hungry businesses - quite the opposite, so I’d have much more confidence in the valuation reasonableness.
Doesn’t change your numbers materially of course but prob worth noting
Or they could get a premium for such a large stake ?
Hargreaves .
Lovely move to take out the pension deficit and stop yearly annual payments of 1.8m
Max cost to do this 6.6m
I this now opens the way up for them to start to realise assets and value and spit out significant amounts of cash to shareholders .
I’m not an expert but presumably with a pension deficit there are certain restrictions on returning cash to shareholders .
Rock solid for me now and despite being near the top of its trading range this it’s likely to breakout into a new range soon .
Massive asset backing, makes money, pays good dividend and an understated wind farm value that should get upside by my fag packet circa 10 million .
DYOR as my fag packet is not a legally binding document .
Hi planetx
No specific restrictions on returning cash to shareholders when there is a pension deficit.
That said management are expected to be prudent and not jeopardise the company and thereby the pension obligations through such returns.
However, pension deficits usually have an agreed annual funding requirement that clearly comes out of cash so that restricts returns unless a management go into debt to do so. Nothing to stop a company agreeing with the trustees to restrict dividends but usually companies won’t do that.
Hargreaves Services (LON:HSP) agree with all the above - and remember current forecasts assume no meaningful recovery in the German commodity trading division, so you have a lot of potential upside thrown in for free.
If you think interest rates are likely to fall from here over the next few years, (i do) this is a smart move.
Paul and Graham,
Thanks as always for your great work on this site. I'm a regular reader of your daily musings but a very irregular contributor.
I hope you won't mind me introducing a book that I've just published. It's very difficult to get noticed in the world of publishing, especially with the explosion of self-published works these days, but I think that many of the people on this site may find it interesting. It's a work of fiction that I started during the Covid pandemic and the story centres on the world of private investing in the UK. When I was writing it, it felt like this was the community that I was writing it for and I'm sure that anyone who chooses to read it will recognize the world that I've tried to re-create. I'm not expecting to make any money out of this, in fact, getting to break-even would be a great result! I would though, like as many people as possible to read the book.
I was thinking perhaps, that I could donate half of any royalties to our favorite charity Zane over the next month as a means to encourage people to read it and leave a review on Amazon. If anyone from the Stockopedia team wants a free copy, I think I'm able to do this if there's an email address. Paul, I even made an audiobook, but you may want to try the sample before subjecting yourself to 9+ hours!
Hope you enjoy it.
Book:
https://mybook.to/PigsGetSlaughtered
Audiobook:
Pigs Get Slaughtered by A.D. Vaughan | 2940191660875 | Audiobook (Digital) | Barnes & Noble® (barnesandnoble.com)
What a great idea! I might well have a listen to your audiobook.
Very kind of you to offer some royalties to ZANE, as I know they're really struggling to raise the funding needed at the moment, and have a long waiting list of destitute pensioners they would like to help but don't currently have adequate funding to support.
Paul, it would be great if you could give it a read/listen. Like all these things, it needs someone with a following to review the book to stimulate a bit of interest. I’d be delighted if it means that Zane gets some much needed help. Here’s hoping.
Ordered for reading over my Easter holiday. Glad its raising some money for charity too.
I’ve just ordered the book from Amazon. Looking forward to a good read. Hope it’s successful for you.
Am up to Chapter 4 and it's a great read. Well done!
I don't like to get competitive, but ... started it yesterday and just finished... unputdownable, private investor thriller... loved it .... very well done indeed ....
Sigmaroc (LON:SRC) : Notice issued of exercise of the call option to acquire CRH's UK Lime
operations.
This confirms they are going ahead with second of 3 purchases of CRH lime operations, funded by previously announced facility. No specifics on performance of initial purchase (German, Czech and Irish operations), other than they will be given with year end results. The 3rd option is for CRH's Polish operations by 30 September 2024.
Profit forecasts show how much this acquisitive group is expected to grow. I hold.
Sigmaroc (LON:SRC)
The company has exercised the call option to acquire the UK lime producing assets. The integration of the German, Czech and Irish lime businesses acquired last November appears to be going to plan. Eventually these acquisitions should enable Sigmaroc (LON:SRC) to generate significant free cash flow, reduce debt and hopefully re-rate.
I hold.
Glad to hear your mums on the mend Paul. You had a busy Sunday releasing numerous podcasts I see :)
Keep up the great work Paul and Graham, its much appreciated.
The cash burn at Renalytix (LON:RENX) has been insane for a business that has had all its tech in place for years. They take a draw of blood from someone, check a few things, and have snazzy AI algorithms work out whether that person is at risk of kidney disease so it can be diagnosed at an early stage. It is bizarre to me that it managed to spend tens of millions a year after it has got all of that in place, while generating zero sales.
But as I tweeted last week about Avacta (LON:AVCT) , if you think that you have identified a UK listed company in the healthcare space with revolutionary technology that is going to solve a major problem, and that company is overlooked by the market and a potential 10/100 bagger, you are almost certainly wrong.
The best minds in science are trying to solve these problems, and a lot of them work for big pharma and are on the hunt for acquisitions. Unless you are a real expert, the chances that you have identified something that everyone else has overlooked is pretty close to zero. I've learned that the hard way. And come to the conclusion that any investment in the UK pharma space (other than in the established giants) is really just a gamble where the odds are heavily against you.
Yes donald I think your views about investing in the healthcare/biotech sector are also true for those investing in US companies in these sectors. Despite having academic and work experience in this sector it remains a moderately small part of my portfolio and I have learnt to base my investment decisions on the financial performance of biotech companies, with their technology(ies) being a secondary consideration. I have found that a portfolio of larger US biotech companies with plenty of cash and high ROICs has provided good results in the long term and I think the quality of such companies is perhaps not recognised by some people who shun the sector. I rarely invest in speculative companies in this sector, although if you regard PureTech Health as speculative, I do hold this one.
Eenergy (LON:EAAS) - "New £40m facility to drive growth in Energy Services" (new research report accessible here: https://www.equitydevelopment....)
eEnergy has announced (1st March) a new £40m project funding facility, which will support the Group’s public sector customers with their energy transition projects over coming years. It is an innovative arrangement, which will see eEnergy retain an interest in the economics of each completed project, enhancing margins and driving growth in Energy Services revenue.
A brief year-end trading update indicated that trading in the 6-months to Dec ‘23 was impacted by balance sheet constraints (prior to the c.£30m disposal of the Energy Management division). This had already been signalled in January and we update our forecasts accordingly.
The disposal of Energy Management leaves the Group in a strong net cash position and wholly focused on its high growth Energy Services business. Our confidence in growth prospects is strengthened by the new project funding facility. We therefore reiterate our Fair Value/ Share estimate of 13p, before factoring in potential contingent consideration from the Energy Management disposal, which could be material (£8m to £10m on management estimates).
My morning smallcap tweet: Electro-motive farce
Saietta (LON:SED) RC365 Holding (LON:RCGH) REGTECH OPEN PROJECT (LON:RTOP) Bridgepoint (LON:BPT) Digital 9 Infrastructure (LON:DGI9) Hipgnosis Songs Fund (LON:SONG) EnSilica (LON:ENSI) Renalytix (LON:RENX) Rosslyn Data Technologies (LON:RDT) Mirriad Advertising (LON:MIRI) Vertu Motors (LON:VTU) Hargreaves Services (LON:HSP), Quartix Technologies (LON:QTX)
◄Saietta (SED)► electric motor innovator blows its windings as it fails to secure additional funding of the scale and form required and no buyer for biz. [SP=0.62 Cap=1m]
◄RC365 (RCGH)► £4m max convert " for the continuing development of the Company's existing operations". Convert at 20% discount. Smels like a death spiral. [SP=9 Cap=12m]
◄RegTech Open Project (RTOP)► guides FY-Dec rev down c.£0.5m from £1.1m due to large additional one-off, project-based revenues in FY22. Current trading: £0.4m booked so far. FY24 sales pipeline is at £1.3m. Strategy update. Still not getting all fubnds promised under Shareholder Loan Agreement. [SP=3.31 Cap=2m]
◄Bridgepoint (BPT)► delay to adding Energy Capital Partners to the platform due to rejection by the Federal Energy Regulatory Commission. "Bridgepoint is also working with the relevant shareholder to address the points raised in the FERC order." [SP=265 Cap=2104m]
◄Digital 9 Infrastructure (DGI9)► Revolving Credit Facility lenders OK the Verne Global disposal. Remaining hurdle is merger control approval in Iceland and on Foreign Direct Investment approval in Finland. [SP=18.84 Cap=163m]. I hold.
◄Hipgnosis Songs Fund (SONG)► independent valuation gives catalogue value of $1.74-2bn after deducting contingent catalogue bonuses of $60m cf $2.55bn previously. Makes SONG NAV $1.17/sh from $1.7392 in Sept. [SP=63.1 Cap=765m]
◄EnSilica (ENSI)► wins order worth €3.8m over this and next FY. [SP=67 Cap=55m]
◄Renalytix (RENX)► gets takepover approach and launches Formal Sale Process. Also "advanced discussions with certain existing shareholders as well as potential new equity and debt providers". [SP=42 Cap=50m]
◄Rosslyn Data Technologies (RDT)► warns FY-Apr likely to be only £2.8-£3m and adj EBITDA loss c. £2.6-£2.8m. Blames "extended timeframes for interactions with partners" due to size and nature of contract opportunities. Has £800k at hand. [SP=16.13 Cap=3m]
◄Mirriad Advertising (MIRI)► 2 yrs agreement with a leading US media and entertainment co that will enable the Partner "to identify virtual product placement opportunities and introduce in-content advertising into its content." "Virtual product placement"? Crickey! [SP=1.25 Cap=6m]
◄Vertu Motors (VTU)► guides FY-Fec adj pretax broadly in-line with mkt exp. UK used vehicle values have stabilised. [SP=67.5 Cap=228m]. I hold.
◄Hargreaves Services (HSP)► agrees a pension buy-in to get short of deficit funding. Will cost £6.6m max and will likely take 12 to 24 months. [SP=518 Cap=169m]. I hold.
In line: QTX
While "AI" and "Product Placement" might get eye-rolls and cynicism, it might be closer than one thinks!
Imagine watching a TV show, a scene in an apartment at a kitchen counter. This TV show is on Netflix, so they know who you are.
In the seconds before the scene starts, Netflix decides what branded item is paying the highest to be shown in the scene to YOU specifically, against your profile. It is a can of Heinz baked beans. AI then regenerates the video frames, to have that can sitting prominently on the kitchen counter.
Your neighbour, watching the same TV show on Netflix, might see a jar of Hellman's mayonnaise.
Pipe-dream? Maybe for now. I certainly wouldn't invest in this blue-sky at the moment. But it will happen, in the future. This area (product placements, native advertising) has always been held back by the lack of personalisation and high cost of creative production/editing. But AI changes both...
Yes I would agree. A lot closer.
Smart TVs have been collecting information via Automated Content Recognition (ACR) for a number of years.
Once data has been handed over willingly it is virtually impossible to reverse.
Saietta (LON:SED) - it's all over. Suspended and intention to appoint administrators. Hope no one here got wiped out.
https://www.investegate.co.uk/...
I sold around 35p, for a small loss, following the red reporting by Graham. So getting out then pays for my subscription many times over. Thanks Graham (and Paul)!