Small Cap Value Report (Mon 5 Dec 2022) - FCRM, BAG, EQLS, LTI, RBGP

Good morning from Paul & Graham!
Apologies for the lack of a podcast this weekend, the creative juices dried up I'm afraid.
Agenda
Paul's Section:
Fulcrum Utility Services (LON:FCRM) - a disastrous convertible loan refinancing, which effectively means the shares are now worth 0.5p or less. The market price of 3.4p should therefore require an immediate ditching of this share, for anyone holding. I'm reporting on this, because it's a warning of what might happen at other companies which need funding at a time when the market is not interested in funding anything that isn't performing well.
Equals (LON:EQLS) - another positive trading update, from this forex services business, with FY 12/2022 forecasts now likely to be beaten c.10% at the revenues line, which could have a nice operationally geared boost to profits. Although I question the adjustments to profit, and large capitalised development spending, so this area needs further research. Overall though, looks well worth a closer look.
RBG Holdings (LON:RBGP) - a profit warning, but from a specific division called LionFish. The core business is performing well. So should we look through this warning as an isolated problem (the best type of profit warning)? Possibly, but a £20m loan on RBGP's balance sheet seems to be specifically linked to LionFish, and it might take time to wind down this operation, which sounds like it's on the cards. Overall, it's difficult to assess risk:reward without more information. So I'm neutral for now, but will keep an eye on it, as there's a possibility of a recovery.
Graham's Section:
A G Barr (LON:BAG) (£560m) - Barr’s announces a £20m acquisition, possibly rising to £32m in two years. It picks up a small Leeds-based drinks company, Boost, that includes the well-known Boost Energy drink. Although the RNS doesn’t tell us the exact conditions required in order for the full £32m to get paid, this still strikes me as a good deal for Barr’s, whose strong balance sheet enables them to use their own cash to fund the deal.
Lindsell Train Investment Trust (LON:LTI) (£213m) - this trust confirms that H1 was a difficult period. It outperformed the MSCI World Index in terms of total return, with the help of a dividend, but its major holding (Lindsell Train Limited, the fund management company) continued to suffer outflows and a reduction in AuM. Manager Nick Train admits that he “must work harder than usual to maintain my native optimism”. I like the investment approach here and wouldn’t worry too much about temporary underperformance. The investees, including LTL, look like great companies to me and I would sleep soundly at night owning them.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Fulcrum Utility Services (LON:FCRM)
3.4p (pre market open)
Market cap £14m
Convertible Loan Facility Agreement
The warning signs were previously communicated to the market, which I covered here on 24 Oct 2022 - an admission that the company needed more funding and was in talks with its major shareholders (Harwood Capital, and Bayford & Co, combined owning 58%).
Today’s £6m convertible loan looks onerous, and with a conversion price of a maximum of 0.5p, this could lead to up to 1.2bn of new shares being issued (quadrupling the share count, currently at 399m).
Interest is at 20% p.a., and there are other fees.
Minority shareholders are assured they will be given an open offer at the conversion price.
My opinion - this is a disaster, and an admission that the existing equity is almost worthless.
For that reason, if I held, I’d ditch the lot (if possible) on the opening bell.
It’s another reminder (which is why I’m reporting on it here) that the funding window has slammed shut for small, problem companies. Therefore major shareholders can do what they want, and provide funding on onerous terms, which destroy the value in the existing shares. Hence it makes sense to sell this type of share, salvaging whatever you can, before a bombshell refinancing on onerous terms is announced. Or worse of course (insolvency).
I think it’s a good idea to have a rule that, whenever a company reports it needs more funding, immediately hit the sell button. Conditions are now very bad for small companies needing refinancing.
Harwood Capital often de-lists shares too, so I imagine that could be the next bombshell facing FCRM. It hasn’t worked, so time to just move on. This is a reminder to all of us, to review our portfolios for companies which might need extra funding - the terms of any funding could be disastrous for existing small shareholders, as FCRM looks to be.
It's a reminder that having one or two major shareholders that control the company, increases risk for small shareholders. Harwood Capital seems a particularly aggressive fund that I'm increasingly wary of, if I see it with a large % shareholding at any company.
Equals (LON:EQLS)
97p (up 3% at 08:32)
Market cap £174m
I know there’s a fair bit of reader interest in this company, providing forex services. Its shares have been in an impressive bull run for almost 3 years now, fuelled by positive trading updates.
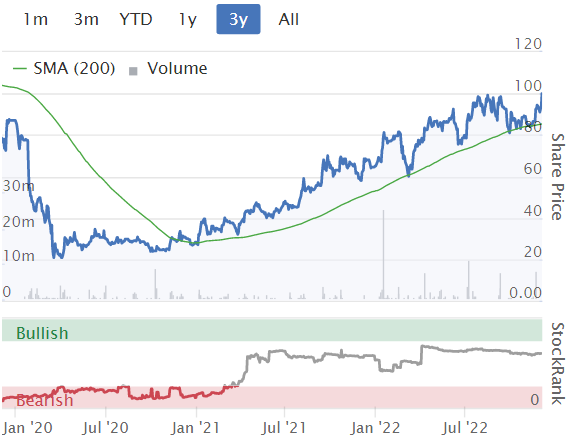
I reviewed EQLS here in July 2022, following reader requests, and came away impressed.
Here’s today’s update -
Equals Group plc (AIM:EQLS), the fast-growing payments group focused on the SME marketplace, is pleased to provide a trading update for the 11 months ended 30 November 2022 (the 'Period').
Various impressive-looking figures are presented, but cutting to the chase -
…the Board expects the Group´s full year results to be ahead of current market expectations.
Ian Strafford-Taylor, Chief Executive Officer, said: "We are extremely pleased to see a 61% increase in our revenues in the 11 months ended 30 November with all segments performing strongly.
Our revenue growth has continued in the face of difficult macro environments and this augurs well for 2023 and beyond.
We continue to invest in people, products and technology to drive our growth strategy and look forward to updating the market in early January with our full year trading statement."
As I mentioned here in July, EQLS seems to be in a sweet spot, and that clearly remains the case.
Broker update - many thanks to Zeus, for providing some numbers in an update note today. Although it hasn’t actually updated its model, but Zeus comments that FY 12/2022 revenues are now likely to beat forecast by about 10%. That could have nice operational gearing to the bottom line, because the gross margin is close to 50%. Hence the extra £5-6m revenues above forecast, would produce c.£3m of extra gross profit. Assuming that all costs remain unchanged, then feasibly this could double forecast profit before tax from £3m to £6m.
Ignore EBITDA here, because it’s inflated by the considerable development spending which is capitalised. Hence any valuation metric based on EBITDA will give an excessive valuation.
A complicating factor is that the broker notes seem to adjust profit before tax to a much larger figure than the £3m statutory PBT (forecast), to c.£10m adj PBT, a huge difference. The forecast EPS of 4.6p is calculated using the larger c.£10m adj PBT figure (less tax). So the main area for further research on this share, is to clarify what the larger adjustments to profit are, and are they reasonable or not?
It seems to be related to the large amount of payroll costs (about 20%) which are being capitalised onto the balance sheet. So I’m raising a flag here that these adjustments to profit need to be properly researched, to justify the current valuation.
My opinion - this looks a bit more complicated that I initially thought. So I’d like to see the full year numbers before forming a definite view on it. The key question concerns the large adjustments to profits, and if they’re reasonable or not? That drives EPS, so determines whether the share price is reasonable or not.
Overall though, I really like the growth that EQLS is producing, and another positive trading update today is really encouraging. It could beat profit forecasts considerably, given the operational gearing. Well worth a closer look, in my view.
There are results presentations recordings on the InvestorMeetCompany website, I might have a watch of the most recent later.
RBG Holdings (LON:RBGP)
66p (down 21% at 10:33)
Market cap £63m
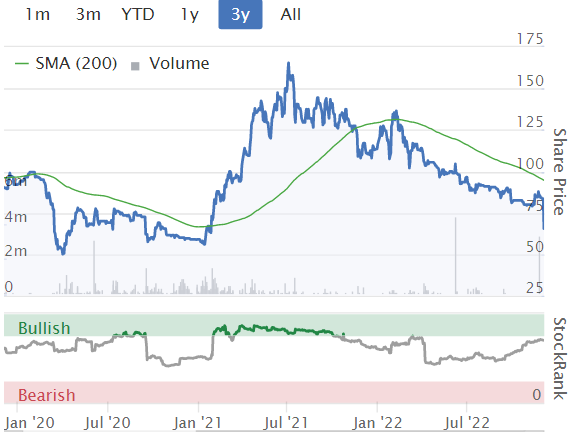
Bad luck to holders here, with a profit warning coming on top of a declining share price trend for the last 18 months or so. As you can see below, it’s now given up almost all the bull run, and is back down near all-time lows again. Could this be a buying opportunity, or are things going badly wrong?
.
RBG Holdings plc (AIM: RBGP), the professional services group, today publishes an update on current trading and outlook.
Looking at its various divisions -
Rosenblatt and Memery Crystal (legal firms) - trading well, and exceeding expectations.
Convex - some revenue deferred into Q1 2023.
Together, these businesses combined have traded “marginally ahead” of expectations. So that looks fine.
LionFish Litigation Finance - this is where the problems have occurred. It’s lost 2 cases, resulting in a £4m write-off. Hence the expected divisional profit of £2.3m for FY 12/2022 will now presumably be a loss of £1.7m .
It sounds like they might wind down this division, reading between the lines. That might be a good idea, as it’s been a flop so far. But I suppose the nature of litigation funding is that some cases will inevitably be lost due to unforeseen reasons. Maybe RBGP bit off more than it could chew, setting up this division and taking on cases that are perhaps too big?
Dividends - sound safe, with confirmation that a second interim divi will be paid.
Balance sheet - reassuring noises are made about financial strength & liquidity. Although looking at its last interim results, I can’t say I’m impressed with the balance sheet, it looks a bit thin, once intangible assets are written off. After the write-off required today, it seems as if NTAV would only be modest. So I’m not sure prioritising dividend payments is the right thing to do.
The £20m loan seems to be from a “large alternative investment firm”, so a key point is that investors need to research the terms (and any covenants) of this facility, which seems to be specifically linked to LionFish, the problem part of the business. That would be a good question to ask management on any webinars or calls - is there any risk to the £20m loan for LionFish funding from the failure of the 2 cases announced today?
Outlook - I wish companies wouldn’t quote EBITDA. It’s so annoying, because the various changes to accounting standards (esp. IFRS 16) mean that we cannot rely on EBITDA as necessarily being a sensible profit benchmark -
RBGLS continues to trade robustly and Convex has a strong pipeline of deals which remain in process. As a result of the case losses in LionFish, the Group now expects adjusted EBITDA to be materially behind current market consensus expectations for 2022 and in a range of between £11.0m-£12.0m. The Board is confident in the medium and long-term outlook of the business.
Broker update - many thanks to Singers, for its revised forecasts, which are now showing £10.1m adj EBITDA, £6.9m adj PBT (note the significant difference, hence why I dislike EBITDA so much!), which is 5.8p adj EPS. This is taking into account the losses at LionFish, so hopefully it might be a low water mark, providing there are no further losses at LionFish. This gives a FY 12/2022 PER of 11.5 - it's difficult to justify anything higher than that right now, and professional services businesses don't tend to attract high PERs, due to the inherent conflict of interests between staff and outside shareholders.
My opinion - the core business seems to be performing well, which is the main thing.
LionFish seems to have gone wrong with 2 cases, so I think we need an update on how the remaining cases are looking (it invested in 12 cases in total). This business was launched in May 2020, and I would imagine it might now be wound down, which would take time, several years probably, and require continuing funding for ongoing cases.
The CEO comes across very well on webinars, but obviously will now need to eat some humble pie, and properly explain to investors what has gone wrong, and what she's doing to sort it out, and reassure investors that the problems won’t worsen.
There have also been questions about excessive rewards for Directors at this company, which is often a problem with professional services businesses.
Wasn’t there an issue about the cost of licensing the Rosenblatt brand name? Something has stirred in the back of my mind about that.
All in all, I’ll keep an open mind on this one. It could be a good recovery candidate, but for now the bull case is looking somewhat tarnished, and the reduced share price does look justified I'm afraid.
Graham’s Section:
A G Barr (LON:BAG)
Share price: 500p (-1%)
Market cap: £560m
This is the Scottish drinks group that includes IRN-BRU, Strathmore water, a UK/EU licence from Dr. Pepper to sell Snapple, and a range of other brands.
Today it announces the £20m acquisition of Boost Drinks, to be bought from the founder of Boost and his wife. An additional £12m might be paid, depending on Boost’s revenue and profits over the next two years.
Boost was founded 20 years ago and the existing management team don’t look like they are ready for pipe and slippers just yet. So it’s good to read that they “will continue to lead the business, operating within [A.G. Barr] as a standalone business unit”.
A description of what’s being bought:
The Boost brand, founded in 2001, primarily operates in the high growth functional beverage category spanning energy, sport and protein, with a strong market position in the UK independent retail channel
I don’t believe I have ever drunk their flagship product, which is an energy drink priced at just 65p. I’ll have to keep an eye out for it next time I’m thinking about getting some Lucozade!
They also sell isotonic sports drinks, protein shakes and iced coffee.
And they have “an asset light business model outsourcing production, warehousing and logistics”.
As for the historic financial performance:
For the year ended 31 December 2021 Boost's unaudited statutory revenue and profit before tax were £42.1 million and £1.9 million respectively with gross assets of £12.5 million
My view
I’ve not seen anything to dislike about this deal.
The price tag when measured against earnings is perhaps slightly above average for a company of this small size. A.G. Barr is paying at least 10.5x last year’s PBT, rising to nearly 17x trailing PBT if the full contingent amount is paid in two years. But given that this is the branded drinks sector, perhaps this is reasonable.
Also, if we look at the deal in terms of revenues being bought in, it doesn’t look expensive to me. A.G. Barr is paying less than 0.8x trailing sales, even if the full contingent amount gets paid.
A.G. Barr itself trades at nearly 2x sales.
And within A.G. Barr, I would expect Boost’s profitability to improve. In the words of today’s RNS, Boost will be able to “leverage the Group's established scale and capability”, using all of A.G. Barr’s various resources including their operational infrastructure.
So this deal gets the thumbs up from me.
A.G. Barr reported cash balances of £61m at its most recent interim results, so there is no question about it being able to afford today’s deal.
I had a fresh look at Barr’s in August, with their share price at 543p, and came away with a positive view on the company and its valuation. I retain that view today. Stockopedia gives it a QualityRank of 98.

Lindsell Train Investment Trust (LON:LTI)
Share price: £1062.85 (+1%)
Market cap: £213m
We rarely cover investment trusts in this report but on a day when the RNS feed is quiet, I hope you’ll excuse me for covering this one.
Nick Train, fund manager at Lindsell Train Limited, is someone whose approach I believe in: buying high-conviction stakes in excellent businesses and holding them permanently.
For example, if you check out the shareholders at Burberry (LON:BRBY) (in which I have a long position), you’ll find that Lindsell Train Limited is the second-biggest shareholder there with the best part of 6% of the company. It’s not so often you find a medium-sized investment manager with such a meaningful stake in a FTSE-100 stock!
LTL also owns 4.4% of London Stock Exchange (LON:LSEG) and 1.5% of Diageo (LON:DGE) .
The Lindsell Train Investment Trust has been designed in such a way that investors can use it both to own a stake in Lindsell Train Limited (the fund management company) and to own stakes in LTL’s favourite businesses. A very nice combination, if you believe in their approach to doing business. The trust also provides seed money for new fund launches at LTL.
Here are the trust’s top ten holdings. You’ll see that A G Barr (LON:BAG) makes the cut:
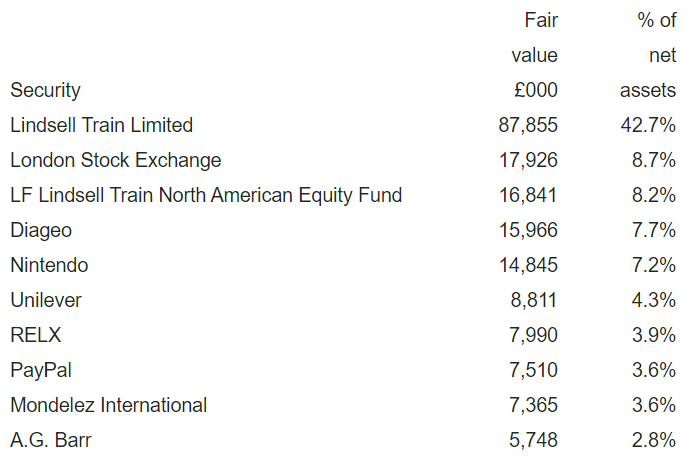
The goal of the trust is “to maximise long-term total returns with a minimum objective to maintain the real purchasing power of Sterling capital.” This doesn’t imply any particular benchmark except perhaps inflation as a lower bound.
It expects to have ”a concentrated portfolio of securities with the number of equity investments averaging fifteen companies”. I like investment managers with the courage of their convictions!
Performance: the six months to September were tough for the trust. It had a negative total return (-3%) but thanks to its dividend payment to shareholders, it did outperform the MSCI World Index (an index of stock market returns in the developed countries).

Lindsell Train Limited: assets under management at LTL fell by 10% to £18.6 billion in H1, mostly due to redemptions.
Some commentary explains that LTL’s investment approach is under pressure at the moment:
LTL has suffered from more than two years of disappointing relative performance across all its four equity strategies which, together with widespread outflows from equity funds generally, underlies this loss of FUM. The experience of recent years illustrates the investment risk inherent in a fund management business that has a singular approach to investing... LTL and the Company’s Directors strongly believe that this approach will outperform in the long term, given the Investment Manager’s concentration on companies that should generate consistently higher returns on capital over time. However, the strategy can fall out of favour when it is seen to be generating inferior short-term returns compared with alternative strategies.
Although it increases the risk over short periods of time, I still much prefer fund managers, such as LTL, who have what they describe as a “singular approach”. Instead of trying to be all things to all people, they have a particular strategy and a particular style and they stick to it.
They also note that listed fund managers are on average now being valued at 1.4% of AUM, versus 3.2% a year ago. In round numbers, this means that you now get £70 of AUM for every £1 you invest in a fund manager, versus £30 a year ago. The entire space has been devalued and derated at the same time that AUM has fallen.
This is the basis for my contrarian investment thesis: whenever AUM starts rising again, I also expect that fund manager valuation multiples will revert back towards normal, and for their share prices to make some excellent recoveries.
My view
The trust’s Net Asset Value, as of November 25th, was £1018.46. As with many trusts, the LTI share price seems to be a lot more volatile than the NAV, trading at a discount or a premium depending on the market’s mood:

Since I like their investment style, I wouldn’t mind paying a small premium for this trust but a discount would of course be nice too!
Their top holdings probably did get overvalued to an extent, so a period of underperformance may have become inevitable. London Stock Exchange (LON:LSEG) , for example, was trading at silly PE multiples:
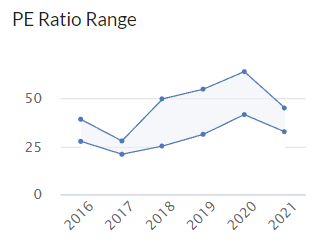
The “quality” investing style favoured by LTL has become a crowded space and it’s about time that “value” outperformed for a while. But over a period of many years, I would still expect LTL, the trust and its investee companies to do well. Thumbs up from me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
I share a surprising position with Lindsell Train -> Celtic (LON:CCP)
I believe they are second biggest holder at near 18% (disclosure of it a bit messy as a few different funds hold and then there is personal holding I think) - I've spoken to Nick Train about it. He says he would own more but the company is too small (approx £105m mkt cap I think) relative to his AUM. He's held for years and years. In his view he's waiting for the franchise value to be realised...
I hope he's correct. I have been for a while too (small tucked away holding)
thanks for doing the podcast Paul. Always an enjoyable listen.
Thanks Bert! Sorry it was late this time, but we're up-to-date now :-)
Anyone know why Shoe Zone (LON:SHOE) jumped up today? (I hold)
New share buyback without a price limit? Dunno....
Shame about the podcast - it's become a regular listen on my Monday morning walk. But completely understand. It's a huge amount of effort to do something every weekend without a break. I personally enjoy the macro commentary as it's good to get another viewpoint on what's happening.
Re Fulcrum. Paul, thanks for the info and heads up. I thought it was a possible turnaround Co, as the shareprice had crashed so much, but the business seems interesting. I've been watching them for months but the shareprice just continued to full. I thought 3p or just under would be the bottom. Luckily I held off buying any. Very narrow escape for me. Sorry to anyone in this. what a mess.
Equals (LON:EQLS) I've met and spoken with them on the tech/product side of their biz. Smart...however...
Whilst I get that they make product and make money I am unable to understand why this is a durable sort of franchise with real durable moats etc. There seems also a fairly speculative or 'entrepreneurial' feel to sources of future profits...nothing wrong with that but better suited to venture backed business rather than a small public company? Give a fairly healthy valuation premium to stock that looks like risks may have potential for some nasty skew to the downside?
I'm unsure of the above and welcome counterpoints to adjust my ignorance...
HI Paul.
Paul Hill of Vox Markets did an interview with Equals (LON:EQLS) CEO this morning to discuss the trading update and recent acquisitions.
https://www.voxmarkets.co.uk/a...
Hi All,
Is there a way to find share prices for shares that have been taken over. I specifically need to know closing prices for StageCoach (SGC) and Meggitt (MGGT) as at 31st March 2022.
Any help appreciated.
Thanks
Dan
£SGC The UT on that day was 106.2p
£MGGT The UT on that day was 760.2p
Thanks SlopsJon much appreciated , do you have a website link
Prices are from Sharepad.
This is the paid-for service which I believe is usually the source for probate/inheritance tax and capital gains tax valuations.
https://www.londonstockexchang...
I think the FT used to do this, but that was 30 years ago and I don't have a current subscription.
But slopsjon may have another source.
Try these https://www.sharedata.co.uk/sh...
Hi Paul,
thanks for covering the LTI, an investment trust I like and it is was a core holding some years ago. It was priced at more than 40% premium and has had some correction since!
I like your comments and I am happy to hold along with Caledonia.
Lindsell Train Investment Trust (LON:LTI) remember that the fund management company (42% of NAV) - the AUM is essentially one concentrated fund (technically a few funds but very similar holdings and strategy) under a single manager who is in his 60s. This makes valuing it quite tricky - you certainly can't treat as a more mainstream fund management company, which will have dozens of funds and managers.
Isn't the biggest worry with Lindsell Train Investment Trust (LON:LTI) that 41.5% of assets are an unquoted company?
Yes this relates to the Lindsell Train fund management company which is unquoted. Normally FM companies are fairly straightforward to value (percentage of AUM or simple earnings multiple) so being unquoted not a particular issue, but in this case the FM company is essentially Nick Train, and not clear what will happen to the business when he retires. Will the funds be wound up and money returned to investors? There isn't really any diversification either, so if his funds underperform there isn't much else to pick up the slack (I think there is Japanese fund, but fairly small last time I looked).
There's also a Lindell Train N American Fund - and 856% of the I.T. is in that!
Good to cover Lindsell Train Paul as I'm always a fan of investment trusts and investment managers.
I've held Lindsell Train Investment Trust for a decade or so, albeit with a smaller holding now. Its a unique investment trust as its really an outsized equity holding in Lindsell Train Limited, the super successful fund manager. As you say, this fund manager is experiencing a sticky patch, but should continue to do well long term.
If investors want exposure to Lindsell Train Limited equity this is the only place to go. However, it might be worth pointing out that if you want exposure to the underlying equity portfolio then Finsbury Growth and Income Trust is run by the same manager and have an almost identical portfolio less the equity holding in the manager, so is lower risk.
Glad you appreciate the coverage, topvest! Thought I'd throw it into the mix on a quiet news day. Cheers. Graham
£INHC. Oh dear, hardly the excited statement I'd hoped for; with a big drop in the price - again. Is this the ultimate story stock? But - cash is OK, sluggish growth continues, the duff CFO is gone ( unthanked), so I've no doubt I'll hang on 'til death do us part.
£RBGP Singer has significantly reduced its outlook for earnings.
"Group earnings downgrades are significant (-46% for FY22 and -35% for FY23) with no further contribution from LionFish assumed."
Singer may off course be wrong, but in the short term they are likely to known much more than me. I have therefore decided to take my medicine and exit at an unpleasant loss, rather than fixate on the share price.
I know we don't do resource stocks here (although Serica Energy (LON:SQZ) has rightly had a mention already today), but the take-over of Wentworth Resources (LON:WEN) can't go without coment. I am not blown away by the 30% premium, but the acquiror is the most obvious one (majority holder of WEN's main asset). I, for one, will miss the candid briefings from the engaging CEO on IMC.
Hi Paul,
Will you being doing an audio summary/podcast of last week? I for one find it very useful.
Thanks
RBG Holdings (LON:RBGP) ouch! Such is life and investing. Lionfish, the Group's litigation finance subsidiary loses two cases.
"As a result, LionFish will now have a non-cash write-off of £4.0m in 2022 and will, therefore, miss the Board's previous expectations of £2.3m profit. The actual cash loss associated with these cases amounts to £1.1m over the life of the investment."
"RBGLS continues to trade robustly and Convex has a strong pipeline of deals which remain in process. As a result of the case losses in LionFish, the Group now expects adjusted EBITDA to be materially behind current market consensus expectations for 2022 and in a range of between £11.0m-£12.0m. The Board is confident in the medium and long-term outlook of the business."
The Board reaffirm commitment to its dividend policy of distributing 60% of retained profits. I hold. Time for reappraisal. The damage is already done to the share price and need to avoid overreacting and possibly throwing the baby out with the bath water. Decisions!!
Observations welcome.
Jonno
Commiserations on RBG however does it really affect the long term investment case ? They simple lost 2 cases .
The big red give up flag was the self serving incentive plan issued to the FD who if memory serves correct received a million shares at zero cost for simply driving to work .
You don’t need to accept that nonsense .
Many thanks planetX.
As you will see above I have pulled the plug. Lesson for the learning.
Some consolation in that I have a decent holding in Crestchic (LON:LOAD) and enjoy reading your updates on the company. Her is hoping for what I expect will be a positive trading update this month.
All the best
I'm holding ... Nicola Foulston wouldn't want her reputation trashed, so I hope will focus on getting back to growth and hopefully paying herself a bit less ... from memory she was taking out over £500k pa.
I sold out of RBG Holdings (LON:RBGP) a while ago - having previously been quite positive on the company, I was put off by the massive share option packages for management. Fair enough for the CEO perhaps, but when they awarded a seven figure sum (from memory) to the newish CFO I lost patience. More generally, I just don't think specialist legal firms lend themselves to be stock market companies - the lawyers will always want the lion's share of the profits, and if they don't they could easily move elsewhere. That's why most are still partnerships.
On the litigation finance side, this was a fairly new sideline but having seen them present a couple of times, I just didn't really feel they had the expertise or experience - contrast with the likes of Burford and Manolete (I hold both), where you definitely get the impression they are deep experts in their fields (even if their profits are still looking pretty thin - I'm fairly optimistic these will come good and they know what they are doing).
Boohoo (LON:BOO) - Shorts closing here. Down from over 10% to 6.24%
SCS (LON:SCS) - price now over 200d SMA and nicely over 50d SMA.
Saga (LON:SAGA) and others - A major OTA says cruises next year will “remain at the same price as an equivalent sailing a decade ago” despite inflation hitting a 41-year high of 11.1%.
Tony Andrews, deputy managing director of Cruise.co.uk, backed up the prediction during a media briefing on Tuesday (November 29) following analysis by the agency of sailings from “multiple” cruise lines.
Presumably things are more expensive (and profitable) once they have got the customers on board?
Fulcrum / Harwood
To be fair to Harwood /Bayford didn’t they back a big fundraise about 6 months ago at circa 12p a share .
So haven’t they have been shovelling cash into fulcrum to keep it afloat ?
I actually spoke to Bayford himself and the CEO a couple years ago about investing at around 50p a share. Just was not convincing and as it’s a Sheffield company I also did not hear great things .
As for Paul’s comments on Harwood that’s a bit worrying I think they own part of nearly all my holdings - oops better have a quick sense check .
Harwood (Christopher Mills) are very astute at buying low and selling high. He also gives some great interviews on Vox Markets. In my view, they are often good to follow but they, like everyone, do make the odd mistake. As an active holder they do sometimes muscle in and take the spoils, so its best to be invested in their funds. Curtis Banks is working out much better, for example. I would suggest they have a c80-90% success rate. I'm invested in North Atlantic Smaller Companies and Oryx amongst other Harwood vehicles. North Atlantic has delivered stellar returns over 30 years, but always trades on a discount for those interested.
Yes I have to agree with Topvest, Harwood vehicles (Christopher Mills) have a good long term record even if the proprietor can occasionally have corporate buccaneer tendencies. In some cases it make sense to take companies private to reduce overheads and then re-list them when the time is right. Harwood has done this before and I am expecting to see this for SourceBio International where I topped up my holding on news it was going private. This is not a distressed company and going private is a strategic move, particularly as the benefits of listing are somewhat reduced when market sentiment for smaller companies is so poor. Where the company is distressed, as in the case of Fulcrum, going private would be much more of a concern.
I should make it clear that the companies where going private may be attractive, do of course provide an option for shareholders to retain their stakes when they go private.
My commiserations for anyone else who got into Fulcrum Utility Services (LON:FCRM) like I did. It has been a total disaster. And the warning signs were there; I knew Harwood like the turn the screws and extract their pound of flesh in funding deals. But hey ho, wasn't really paying attention to my Fulcrum holding for the past month or so, and let the opportunity to exit slip by.
Anyways, I am lucky that I only decided to put in c1% of my portfolio into Fulcrum, so even though I am sitting on an almost total loss, it hasn't been terminal to my performance.
Looking back, I ignored all the usual bargepole signs I use. Core business struggling. Sexy new industry touted (but no firm orders, revenues yet). Very weird third party agreements (the gas meter sales). But I looked at Harwood and Bayford and their keen interest here, as well as deep investment, and thought those red flags could be ignored.
(I hold in the Boon Fund)
Serica Energy (LON:SQZ) North Eigg well result is disappointing ....was a 30% chance valued at 60p risked.
In the rest of the statement production is inline and hedges are now much reduced such that Serica Energy (LON:SQZ) cashflows in H2 will be strong. The gas price has thus far averaged higher than the first half ... 209p/th Vs 175p/th. Net realisable to Serica Energy (LON:SQZ) should come in higher than 135p H1 ... which will offset the hit today.
The shares have increased from 295 to 317 ... and could fall back to 260 today but suspect they level out nearer 300 due to cashflow benefit of unhedged production and strong balance sheet. Weather looking much colder now for a month or two so a big adverse move today is the opportunity IMO.
Question RD - I can't quite get my head around how Serica Energy (LON:SQZ) should have net cash of more than half the market cap this year and trades on a PE of between 2 & 3. That just seems bizarre to me. As I understand it these fields will produce for some time considerably longer than that even without new discoveries. I understand the tax grab from the UK Govt isn't helpful though it also limited the net cost of the current well discovery (that isn't as good as hoped) to just £13m which is beneficial. But nonetheless the cashflow should be prodigious even at much lower gas prices for some time so a PE of 2 just looks wrong.
Anything I am missing in your opinion that limits the shares?
PE not much use for a short life asset like Serica Energy (LON:SQZ) .... most of your value is in two fields and its gas, Rhum and Bruce. This is discounted as its Gas and due to concentration. The total NPV incl cash 150p = 372p .... so the shares are cheap. You could then add 60p for Eigg which we take back out now... but maybe not zero. Obviously any reasonable Gas price forecast has it falling significantly in 2024.... and beyond. SO in 2025 Peel Hunt have 75p/th in for the UK. Who knows if this is true. Stronger for longer? or faster back to normal? Either way the gas price will fall again after the winter. It has always been very volatile esp in the UK, because we use it as baseload ( after persuading Drax to burn wood pellets from Canada instead of coal).
The cash is always a funny one.... mkts tend to discount cash unless it is given back. Why? Well until they give it back the potential for it to be wasted on drill bit.. aqns... etc Of course these "could" be positive. None of this is helped by ESG ruling out investing in Oil and Gas.
So you are right that the shares are cheap... but not 5x territory. Given the potential production cash profile for H2 to be better than H1 ... there is upside to nos... and some upside therefore to the NPV. Then each year you beat the broker gas price profile you add value to the NPV. With a massive drill programme off the cards the likelihood is that they do a buyback. This also improves the NPV by reducing share count.
So with the potential bad news out of the way, you have decent trading and cold weather, which can push up gas prices. Strong H2 results after reducing hedging and a buy back... could offer 20% - 30% upside and possibly more if things get silly. So I think it can ride out a possible wobble in the market and would still run for a month or two. (I own).
Mr Contrarian must be a fisherman to know how to flounder but all praise to you sir, all anglers are optimists.
Fulcrum Utility Services (LON:FCRM)
"The cold grip of Christopher Mills" got my thumbs up.
The RNS includes "Although Fulcrum is not a company that is subject to the UK Takeover Code...." Why? Stocko shows it as a company in Sheffield. Delve into company website and the registered address Stocko should be showing is Ugland House PO Box 309 Grand Cayman KY1-1104, Cayman Islands.
So that's Mr. C thumbs up Stocko thumbs down.
Wentworth Resources (LON:WEN) An offer of 32.5p has been made, board recommends.
Would be absolute daylight robbery at that price! The Dick Turpin award is standing by.......
"The Acquisition represents a material increase to the initial indicative offer price proposed by M&P on 23 September 2022"
Looks like they made a lower offer.
Re £WEN
Away on hols but from memory my fair value estimate for this share is north of 50p. I hope shareholders reject it
Would be absolute daylight robbery at that price! (Wentworth Resources (LON:WEN))
I've normally been underwhelmed by takeover prices, but clearly the market hasn't seen WEN as being worth a lot more than a 30% premium, or they'd have been buying, and the starting SP would have been higher. Realistically, 30% is a adequate, if not outstanding, premium, even it it's dissapointing for those seeing higher potential value.
Wentworth Resources (LON:WEN) The share price has gone nowhere in five years, even the share buyback did nothing to move the price. It's a shame to lose a 9% dividend, but I will take this offer.
I hold Wentworth Resources (LON:WEN) and will be happy either way. The General Public seems to have 51% of its market cap so we shall see when it comes to a vote.