Small Cap Value Report (Mon 6 Nov 2023) - KITW, GMS, AEP, TNT, MSYS

Good morning from Paul & Graham!
Weekend podcast (from Paul) - was fun to record as usual, with a bit of silliness thrown in as usual. I do try to make them shorter, but there's masses of material to cover each week. I went through the profit warnings and takeover bids for Oct 2023 that we've covered, as well as the usual summary of the daily SCVRs.
Here's the link for Graham's youtube show today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Not an exciting day I'm afraid, but we'll do our best with this hotch-potch -
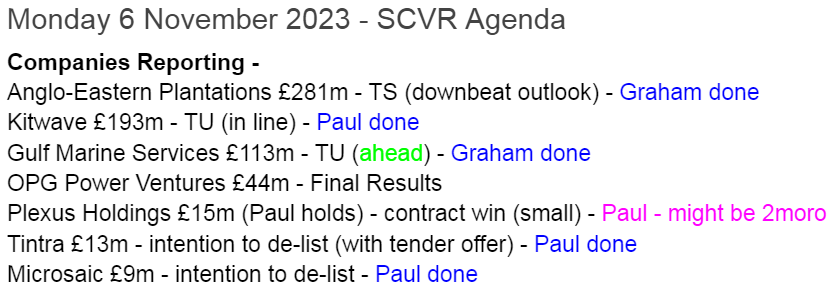
Summaries
Kitwave (LON:KITW) - 265p (pre-market) £186m - FY 10/2023 Trading Update - Paul - GREEN
The founder CEO is finally hanging up his boots in the spring next year, after a remarkable 36 years at the helm. Today's trading update for FY 10/2023 shows strong earnings growth (in line with increased forecasts), and it reassures on other points too. This share looks attractive to me as value/income/GARP, so it's another thumbs up.
Gulf Marine Services (LON:GMS) - up 5% to 13.15p (£132m) - Trading Update (ahead) - Graham - AMBER
A nice update from this operator of support vessels for the oil, gas and renewable energy industries. EBITDA will be at the top end or perhaps slightly above the previous range. Leverage remains significant but much safer than before. A high-risk, high-reward situation.
Anglo-Eastern Plantations (LON:AEP) - up 2% to 695.5p (£272m) - Trading Statement (downbeat outlook) - Graham - GREEN
This agricultural stock produces palm oil in Indonesia and Malaysia. It’s pessimistic on the short-term outlook for the palm oil price, but shareholders can take comfort in the extraordinary cash balance and the very long track record of dividend payments.
Brief comments from Paul below on proposed de-listings of Microsaic Systems (LON:MSYS) and Tintra (LON:TNT)
Paul’s Section:
Kitwave (LON:KITW)
Down 2.5% to 259p (£181m) - FY 10/2023 Trading Update - Paul - GREEN
Directorate Changes - this is all self-explanatory, with the founder (in 1987) CEO retiring in the spring -
Kitwave Group plc (AIM: KITW), the delivered wholesale business, today announces that Paul Young, Chief Executive Officer, will be retiring and stepping down from the Board at the end of the Company's Annual General Meeting ("AGM") to be held in March 2024.
Ben Maxted, the Group's Chief Operating Officer, will become Chief Executive Officer following Paul's retirement. A handover period between Paul and Ben will commence immediately to ensure a seamless transition of Chief Executive Officer responsibilities prior to the next AGM…
… post my departure, I look forward to being a long-term shareholder in the Company."
That seems to suggest no immediate plans to do a secondary placing, to get rid of his 11m shares. The Director dealings page here suggests 3 individuals with his surname (presumably connected) have together banked £7.6m between 2021 and 2023 from sales.
Investor sentiment was rattled when 5 Directors took £3.3m off the table on 4 Jul 2023 at 324.5p. That certainly dented my view of the company somewhat, which had previously been more positive.
Having said that, checking our previous notes, I’ve been positive overall on KITW -
2/5/2023 - GREEN - H1 TU slightly ahead exps. Good GARP share.
4/7/2023 - GREEN - Good H1 numbers, and outlook. Canaccord ups forecast.
Trading update - for FY 10/2023.
Kitwave Group plc (AIM: KITW), the delivered wholesale business, today announces a pre-close trading update for the year ended 31 October 2023 ("FY2023").
This sounds fine -
Following a strong performance in the first half of FY2023, positive momentum continued across all of the Group's divisions. As a result, and following the significant upgrade in July 2023, the Board expects the full-year financial results to be in line with current market expectations.
Other points - all sound encouraging -
Macro/inflation - challenges have been mitigated effectively.
Acquisition of W.Country Food Holdings - integrating well, and trading in line.
Growth - both organic and more acquisitions sought.
Web platform for suppliers & customers is going well (taking 47% of orders online)
Valuation - nice cheap value scores, and good quality measures too.
Although not much asset backing, with a high Price to Tang. Book - this measure is better when smaller, and bad once it turns negative. This is the quickest balance sheet check you can do - if this field is denoted with a “n/a”, that means NTAV is negative, so the balance sheet a needs careful check.

Broker forecasts - as you can see below, a very strong trend here, helped by acquisitions no doubt, but even so these are large increases in forecast earnings (during a tough macro period, doubly impressive) -

Many thanks to Canaccord and Research Tree for an update this morning. It confirms the above figures, with 29.0p adj EPS for FY 10/2023, which is a lovely 31% increase on LY.
PER of 9.1x is attractive, and that's historic now, so if earnings rise again this year, then the PER would drop even further.
Forecast for FY 10/2024 looks beatable, at 29.3p.
KITW is a rare success from 2021’s otherwise awful stable of stock market floats.
So the founder CEO certainly seems to be leaving on a high, having delivered a considerable success over many years here.
Paul’s opinion - I think KITW shares look very good indeed. Modest PER, good divis, and strong earnings growth.
The last balance sheet was a bit thin - only c.£10m NTAV, with some bank debt (although not excessive), so I wouldn’t want to see debt go much higher, hopefully the new CEO strikes the right balance between acquisitions, shareholder returns, and financial prudence.
A good thing about this group is that it sticks to its knitting, so the companies it buys are simple and it will already know them inside out, I imagine - hence low risk of it buying a dud, probably.
Running this type of business is all about keeping a tight control over all the detailed day-to-day operations - quite similar to retailing really. As we saw a few years ago at Conviviality, if management over-reach on acquisitions, and lose control over the basics, then implosion can be quite rapid. No sign of that here, this looks a well managed business, and so far the acquisitions seem to have been very good.
Thumbs up from me again, this looks a nice value/GARP/income share.
Stocko likes it too - see the very high StockRank, and it's a "Super Stock"
A couple more companies announce today they’re intending to de-list - I'm only mentioning them here, so that we can get them into my spreadsheet as de-listings.
Tintra (LON:TNT) - £13m - intention to de-list (with tender offer) - a change of tack here. Tintra was going to be taken over by an acquirer at 150p per share. That has now changed, as major shareholders didn’t agree with that plan. Instead the acquirer is trying to buy 29.9% through a tender offer. It’s also planning to de-list the shares, and says -
The Board considers that Tintra would be better able to raise the capital it needs to develop the business as a private company.
Paul’s opinion - this is not a share we’ve covered in the last 5 years, as it looked rubbish (from a value investment perspective). This deal reinforces my view that AIM is simply not the right place for tiny, jam tomorrow companies. Brokers need to stop floating things like this - they’re better off in private hands. Float some decent, profitable, cash generative companies please brokers! Although as one broker said to me a while back, why would you want to float if you have a great business in private ownership?! In some cases it can help raise a company’s profile by being listed, but it makes future fundraises a complete lottery, dependent on fickle market sentiment. Private ownership is much better for most small, speculative companies. So I’m pleased that lots of similar companies are now leaving the stock market.
Microsaic Systems (LON:MSYS) - £9m - intention to de-list.
This is another one we’ve never covered in the SCVRs, for the same reason - the figures were bad. It announces today that it’s going to de-list, but continue trading despite getting rid of all its staff, through the use of consultants. So shareholders might salvage something if it works out better as a private company maybe?
Graham’s Section:
Gulf Marine Services (LON:GMS)
Share price: 13.15p (+5%)
Market cap: £132m / $164m
This company operates “a modern fleet of highly versatile self-propelled lift boats''. Its headquarters have an address in Abu Dhabi.
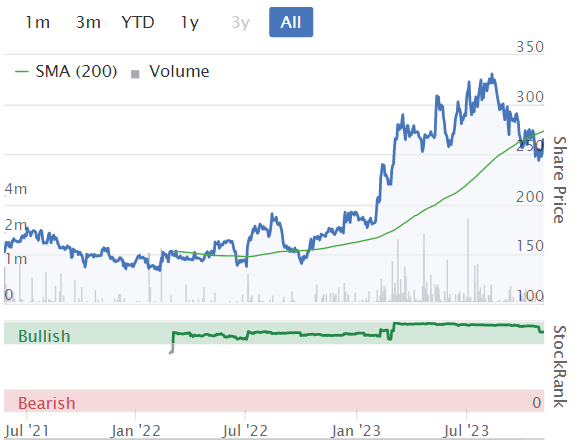
It is a multi-bagger so far this year:

Paul has covered it before (see the archives), but on a quiet news day I thought I would take a look at it for once.
Today it has published another good news update: 2023 EBITDA is now expected to be in the range of $83m to $86m (previously $77m - $85m). So in other words EBITDA will be at the top end of the previous range, or possibly just above the top of that range.
As a reminder: EBITDA is a rough estimate of operating cash flow and should certainly not be confused with profitability!
In the interim results, depreciation and amortisation were about a third of this company’s EBITDA, and finance charges were even larger. So real profits were only a fraction of EBITDA.
The real value of EBITDA - or operating cash flow - is that it can help to prevent insolvency in the short-term, as it gives the company the flexibility to maintain its assets or to pay down debt instead.
GMS does have some balance sheet questions, with net debt of $299m in the interim results (for June 2023).
But first, here is the explanation for the upgrade to the EBITDA forecast. Comment by the Executive Chairman:
Given significant improvement in backlog visibility and market outlook evidenced in the recently announced contract awards, alongside future opportunities we're bidding for, we are confident to increase our market guidance for 2023 and to provide an even higher initial guidance for 2024. We continue to see strong interest for our vessels to support maintenance projects as well as new initiatives to meet growing energy requirements, for Oil and Gas as well as for renewables, and across different geographies.
Oil and gas markets do seem to be robust at the moment: Shell (LON:SHEL) reported Q3 adjusted profits of $6.2 billion last week, in line with expectations, and expanded its share buyback programme.
And now for the debt news from today’s GMS update:
2023 net debt/EBITDA is expected within a range of 3.2x to 3.3x.
2024 net debt/EBITDA is expected within a range of 2.3x to 2.7x
These forecast multiples are much safer than the multiples the company has had in recent years, but I would suggest that they are still on the high side for a capital-intensive company in the oil and gas sector, where there are so many factors that are out of its hands.
But there’s no denying that the company has made significant progress. So far in 2023, it has prepaid $30.2m of bank debt. A fine achievement.
Graham’s view
I tend to avoid commenting on oil and gas stock, for a variety of reasons, but I can see why this one might be interesting. It has a StockRank of 90 and is trading “cheaply”:

Needless to say, it’s unlikely to be a sleep-sound-at-night type of stock. This is more of a multi-bag-or-bust type of deal, with multi-bag being the outcome that is winning so far.
Best of luck to all holders. Of course I am staying neutral on it.
Anglo-Eastern Plantations (LON:AEP)
Share price: 695.5p (+2%)
Market cap: £272m / $338m
Anglo-Eastern Plantations Plc, a major producer of palm oil and some rubber across Indonesia and Malaysia, today announces a trading update covering the nine months to 30 September 2023.
Here’s another stock that rarely gets a look-in at the SCVR. But with a market cap at this level, it deserves a brief look on a slow news day.
Its website describes a company that floated on the LSE in 1985. It looks as if the company has paid a dividend pretty much every year since then (though the payments in 2019 and 2020 were minimal).
Here are the key points from today’s Q3 update:
Production of fresh fruit: down 2% year-to-date, due to the felling of old palm trees over the last two years.
External crop purchases: down 5% due to “intense competition” for external crops.
Crude palm oil production: down 4% for the above reasons.
As for pricing, the benchmark price of crude palm oil is down 33% this year, on average, compared to 2022. “Prices remain volatile”, with other key benchmark prices also significantly lower.
Balance sheet is “strong”, with no bank loans and net cash of $226m - wow! That’s over two thirds of the market cap. That cash balance is actually lower than it was before, due to a variety of investments, dividends and a share buyback.
Development - the company has a landholding of 90,667 hectares of which 68,414 hectares are planted. A portion of planting and replanting takes place every year, and a new mill in Indonesia is “nearing completion” and is expected to start processing external crops by Q1 2024. Another planned mill is however seeing “little progress”, “as we await the relevant government authorities to approve the environmental impact assessment study”.
Outlook is pessimistic for the crude palm oil price:
CPO prices are expected to be weak for the remaining part of the year as the industry enters traditional period of more robust crop production. The reported high palm oil inventory, together with the abundance of other competitive vegetable oils, coupled with a lower demand from the major importers are likely to suppress any upward movement in CPO prices for the last quarter of 2023.
Graham’s view
I do have a soft spot for agriculture stocks, and I’m tempted to go green on this one.
The Stockopedia computers wouldn’t blame me for doing so: this stock passes no fewer than seven bullish stock screens! Let’s list them for fun:
Ben Graham Defensive Investor (Bargain Stocks)
Ben Graham Enterprising Investor (Value Investing)
Ben Graham Deep Value Checklist (Value Investing)
Best Dividends (Income Investing)
Dreman Low Price to Book Screen (Value Investing)
Philip Fisher Growth Screen (Growth Investing)
The Screen of Screens (Quality Investing)
Yes, there is the foreign country risk: few of us will be experts in the local economic and political situation in Indonesia and Malaysia.
Offsetting that, you have AEP’s very long track record of operating profitably in these jurisdictions.
The company has a controlling shareholder: a Hong Kong-headquartered holding company which I understand to be owned by certain relatives of the Malaysian Chinese billionaire Lim Goh Tong.
So that’s another important point to be aware of: a 51% shareholder. It can sometimes be risky to invest in businesses where one entity has control over it like this.
Still, I’m going to stick my neck out and take a positive stance on these shares. What can I say? The cash balance and dividend track record have intrigued me! And the yield is currently 4.7%, according to the StockReport.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Hi Gudge58, I haven't got much to add on JIM. My view isn't changed by the departure of the FD, who had a long career with the company. In the circumstances, a change is probably not a bad idea (though I note that the new FD is already "Head of Finance" at JIM). G
Hi Roger, I hope my review of GMS didn't disappoint! Best of luck with it. Cheers, Graham
Hi Mark, nice to hear from you again. Re: AEP I did cover it again in today's show. Regarding TSLA there is an awful lot to say... but I'm keeping quiet for the moment. G
XP Power (LON:XPP) why on earth would anyone be interested in buying new shares at a premium, in a bear market?
I guess the expectation is that tomorrow the shares will open a good deal higher now that debt has been reduced by 20-25% and banking covenants presumably unbreached. Personally I’m happy to wait to see where it opens and then walk away no matter how good the price. There are too many superior companies with far better management on offer to chase this crock for an eventual bounce.
Hi Paul, enjoyed the podcast as always.
QQ what are your thoughts on XP Factory (LON:XPF), have you reduced your holding a lot?
It's getting on my wick now, tiny volume today and it's dropped 6% to a 52 week low..
Hi NewInvestor1972,
As mentioned in my podcasts, I'm mainly focused on Plexus Holdings (LON:POS) at the moment, by far my largest position. So yes, I've reduced position sizes in everything else, including XP Factory (LON:XPF) . in order to provide funds to buy my increased POS position size.
As regards XPF itself, I still very much like the concept, management, etc. The sector looks good for a recovery. As you say though, it's frustrating when shares just drift down on no news - something we're probably all struggling with. What to do? It's tough.
Regards, Paul.
Thanks for the reply Paul, appreciated
I should add my own portfolio decisions are very much hit & miss over the years, as nobody can predict the future reliably. If they pretend they can, you know for sure they're full of dung! (a nice word, more wholesome than other more modern alternatives)
Interesting news just out on XP Power (LON:XPP) .
First they are raising around £45M, mainly by a placing. The indicative price mentioned for the placing is 1150p, above recent market levels. After the fresh capital is injected, debt levels will be at the upper end of the Company's target range.
Second there has been by the sound of it offers to take over the company. From the RNS:
" Since the trading update of 2 October 2023, a small number of parties have expressed indicative, non binding interest in acquiring the Company at prices which the Board considers fundamentally undervalue the Company and its long-term prospects. Having considered each of these unsolicited expressions of interest, with its advisers, the Board does not believe that any of them are at a value which merits further engagement with any of those parties and has had no hesitation in unequivocally rejecting them."
Overall this makes XP Power (LON:XPP) rather more investable. My guess is the shares will open above the placing price tomorrow morning.
Personally I have no current position and no need to chase the shares as so many other opportunities right now. I have admired the Company for a while and recent events were am unwelcome surprise - almost shocking - and the demand for the Company's products is clearly not a consistent or resilient as it seemed.
On the up side, the shares could re-rate if sales resume and the recent debt crisis ebbs away. The downside risk is that today's fund raise is not quite enough, sales stay subdued and the company and share price both get stuck in no man's land.
XP Power (LON:XPP) have announced a £45m placing with Primary Bid retail offer. Placing price is at small premium to closing price tonight.
I saw that, got a message from Primary Bid - why on earth would anyone be interested in buying new shares at a premium, in a bear market??? Seems crackers to me!
I saw that, got a message from Primary Bid - why on earth would anyone be interested in buying new shares at a premium, in a bear market??? Seems crackers to me!
I have absolutely no idea. They’ve indefinitely cancelled the dividend too. I used to have a position but sold on the first sign of the IP infringement legal case which looked very bad news to me. They were clearly bang to rights. Slightly unfortunate to acquire a company with that issue unknowingly lurking, but the subsequent poor state of the balance sheet can only be down to poor management, especially the excessive inventory position they find themselves in.
Hi Paul,
I think the answer is the hint in the RNS that there are parties out there interested in buying the whole of XP Power (LON:XPP) . At a usual takeover premium that would equate to 1300p or more, so that 1150p becomes a 'bargain'.
Who knows?! Too much smoke and mirrors for me, but it sounds like someone out there has been persuaded to part with cash for new shares at a premium to Monday's closing price.
Well the shares are 21% today.
The majority (ie 52%) of Wall Street economists now seem to believe the US will avoid a recession over the next 12 months - ie following Friday's 'Goldilocks' jobs report.
if so, then this should be a net positive for smallcaps, as many are already pricing in a 'hard landing'.
Ouch.Microsaic.. I have to admit gives me a bad feeling and bad memories.Does anyone remember Deepverge (LON:DVRG) (to be honest i'm kinda surprised they're still around)?They were called something else before merging with Modern Water i think.They were trying to get involved and a product done with Avacta (LON:AVCT) 's technology and/or another now listed company that had similar biological technology for wasteater testing during Covid.
They had a very enthusiastic and rather engaging CEO called Gerrard who used to pop up and answer questions on another less retail investor friendly in my opinion stock bulletin board only at one point........Polar Capital were invested in them at one point pre-the whole merger etc... and totally sold out during one of their very popular virtual investor presentations totally decimating the all time high share price.
Well getting around to my point... the CEO wanted to buy Microsaic at one point and somehow integrate it.I think it produced spectometers for chemistry or something from memory.And i won't go any further but if anyone does remember the heady days... they took out a couple of massive convertibles from Riverfort Global Opportunities (LON:RGO) if memory serves... and that ended all the excitement pretty much after a couple of years when they came due.There was certainly a lot of stories going on around there.And glad i've moved on in investing style since.......Onwards and upwards... i hope!
Vertu Motors (LON:VTU) I hold - possibly a good sign for VTU?
The Times reports:
"The SMMT is forecasting that in total, the UK will register 1.886 million cars in 2023, which would be a year-on-year rise of 16 per cent, although still significantly down on the 2.3 million registered in 2019 and 2.7 million in 2016.
It expects new registrations to further rise in 2024 to 1.97 million. However, for both 2023 and 2024 the SMMT is expecting electric take up to be slower than previously forecast: 17 per cent of the total market in 2023 and 22 per cent in 2024."
I'm not a Boohoo (LON:BOO) fan nor am I promoting it as I do think its competitive position looks pretty shaky (and my negative post about it from near 3 yrs ago has played out reasonably - https://www.stockopedia.com/co...)...
...BUT its notable that its not down on more bad news/PR.
Graham, I have been listening to your podcast, and I would be interested to hear your views on AEP and TSLA.
Since ASC was mentioned, I thought I'd add my own observation. In Phil Oakley's book, How to Pick Quality Shares, he defines the capex ratio as capex divided by the operating cashflow. He advises to look for a capex ratio less than 30%. If you look at companies like ASOS (LON:ASC) and Boohoo (LON:BOO), you will see that they routinely spend significantly more than that. Both companies turned out to be disasters.
TSLA - I wonder if Graham has changed the view he so succinctly expressed - despite a microphone problem - at the investors meeting in London about four or five years ago? The market can really make fools of us all however honest and rational we try to be.
Avation (LON:AVAP)
Interesting stake building by Rangeley Capital LLC owned by Christopher DeMuth
Up to 22% now. A few months ago they had nothing I think. Bought a large stake from an exiting shareholder. Wonder what the end game is here - will they get to 29% and make an offer perhaps? Or just a value play for him.
With TNAV at over 275p you’d imagine the other 70% shareholders wouldn’t be minded to sell at less than 200p which would still be a roughly 25-30% discount to NAV.
could be in play. Interesting one to watch - hope management aren’t planning on accepting a low ball offer though, particularly as they’ve gone through the toughest possible period and are now growing again.
Boohoo (LON:BOO) I see Boohoo are in for a kicking today by the BBC for 'not cleaning up its dirty practices despite promises to do so'. Good start to the week.
My SCVR summary spreadsheet is now up-to-date here.
As you can see, the new BLACK colour coding for profit warnings is working well, thank you to the reader who suggested this -
I hope everyone enjoyed the rally last week, im not about to poor cold water on it. The small cap X IT index is down 1.6% YTD....this is better than the midcap index which remains down 4.6%...and the FTSE 100 just down 0.5%. This is just index levels... We have to wait for next week for inflation data when CPI is released.
In the UK October was the crunch time re the energy crisis ...so expect news that is supportive of the rally from the UK. The January number won't help much but Feb, March, April should be tailwind numbers too....in the UK. These months were the strongest CPI months of 2023...and Gas prices will need to triple to take away this positive catalyst in Q1...."If" the mkt plays this as it did last week then you would expect it to be rather positive for UK rate victims. However there is little evidence to suggest this means the rate cycle has turned rather than paused....so I am happier personally, not jumping into the rate sensitive areas...possibly to my detriment .... since the short closing cycle will run hard in these sectors.
In the US ...this month CPI should be ok, since the comp is 0.4% mth on mth. In November and December CPI data is not going to be helpful...since the comps were negative. Yet as this is known.....I would argue a monthly number above 0.5% would be needed to be taken very badly...and most likely nos in the range 0.2-0.4%...will be judged neutral. Why? Well in January the strongest number of 2023 falls out and so you "should" see a positive drop in CPI again... and thus it will be data in the months that follow that potentially rock the boat.
Jobs data was strong last January also .... so it looks to me like the backdrop is benign now for a few months consistent with markets drifting up during a pause. What follows will depend how quickly things deteriorate. Or not. Some fairly high profile GOAT investors seem to be buying US 2 year Treasuries which is a play on deterioration..not higher for longer ...but other equally talented managers are arguing the reverse. Who is right? crikey...only time has that answer.
Equity market volatility at 15 seems crazy low to me esp when judged relative to bond volatility at 120. This would suggest that although the CPI data is behaving there is huge sensitivity to it still. And with this seeming window in the data into Q1 24 opening up.... maybe that's the play as Druck sees it..but im guessing.
However you decide to play the next few months ... it will not be plain sailing in 24 since we need the economy to slow to tame inflation. So one eye on tougher market conditions returning before we really take off...in a sense enjoying rallies and reshaping if needed, I know that's a little boring, but boring is winning at the moment....
M&A plus Decoupling could really make a difference to the UK however...patient investors can definitely buy quality cyclicals... happy hunting everyone.
Hello,
Good post. Not convinced at all this rally will mean anything more meaningful.
Hope I'm wrong!
Kitwave (LON:KITW) I hold.
Regarding the CEO departure, worth watching the most recent presentation on InvestorMeet if you're interested in the co and haven't done so already. I was really impressed with the three senior management on the call (CFO, CEO, COO), including how tight a grasp / knowledge the COO had on the operations (as you'd hope/expect...!) I remember thinking the purpose of having all three on the call was probably for succession planning as the COO answered a number of questions/presented a good chunk of the meeting (i.e. they were walking out the COO to give comfort if/when the CEO leaves.)
Kitwave (LON:KITW) looks potentially interesting after 20% dip so will need to look at this in more detail. From a very brief look a few months ago, my only reservation was whether they had any sort of competitive advantage/pricing power given there are dozens of wholesalers providing similar services. In other words is there anything that makes them stand out from the crowd?
Yeah a very important question for this type of business (and any business I guess) but, as you say, given it's low margin and there's a lot of competition you've got to be confident in the answer. From my research my understanding is:
I used to be a general manager of a smallish theatre in London and I can pay testament to how important the above qualities are. We used Booker and they were consistently late, out of stock, had very moan-y underpaid delivery drivers and we had zero relationship with them (i.e. no relationship manager who helped us out, upsold things etc. etc.) If we could have gone with a reliable, personable, affordable wholesaler who supplied local product we would have bitten their hand off but we could never really find one.
I've decided to sell out, and for me it boils down to three things.
1) Owner/Operator walking away risk, will the COO (he very well might tbf) be able to navigate the waters ahead. It looks a decent business will he be able to keep it that way. Will the current CEO start selling his holding and weigh on the share price.
2) Food inflation appears to have peaked, which will have been a tailwind to its sales and profit growth - if inflation flat lines so does the business' growth to a certain extent.
3) Its level of debt will hold back its growth by acquisition strategy in the short term and instead a focus on organic growth may well weigh on margins. But growth will be slower and harder no doubt to come by.
I feel (and I'm happy to be wrong - I will be :) ) that its a cheap well run business but will it stay well run going forwards, and growth now appears to be off the cards with lack of inflation boosting results and lack of firepower for acquisitions. All the best to Kitwave (LON:KITW) and its holders
Interesting and valid points - thanks for sharing them. I'm going to try and wait until the final year results in Feb before reassessing a) to see how much debt they've been able to pay down, b) to see how their forecasts are impacted by lower food inflation (I imagine there may even be a deflationary risk here, albeit offset by contribution from acquired companies and their reported growth in volume) and c) because they're cheap and a more benign market may value this on a modestly higher PE (my entry is about £2.80)
Oxford Metrics (LON:OMG) I’ve always been wary that this company’s technology moat is vulnerable to disruption by technologically superior competition. And today I learn from a BBC article that Football Manager 2024 has begun the process of “removing motion capture technology, instead using a new technique called "motion matching". This analyses data from actual football matches and transforms the movement of real footballers into action in the game itself.”
Perhaps someone can correct me to explain that OMG are in fact the providers of this new technology. Otherwise, holders should be concerned, notwithstanding the broader range of applications beyond gaming.
Markerless tech update from Oxford Metrics (LON:OMG) earlier in the year:
OXFORD, UK – 1st August 2023 – Vicon today marks a new era of innovation in the field of motion capture, announcing that it will debut its machine learning (ML) powered markerless technology at SIGGRAPH 2023 in Los Angeles, in collaboration with Artanim, the Swiss research institute and the award-winning VR group, Dreamscape Immersive.
The announcement follows nearly three years of research and development focussing on the integration of ML and artificial intelligence (AI) into markerless motion capture at Vicon’s renowned R&D facility in Oxford, UK. The project has been undertaken by a new dedicated team, led by CTO Mark Finch, and leverages nearly four decades worth of Vicon innovation to enable a seamless, end-to-end markerless infrastructure, from pixel to purpose.
That might be encouraging. Although the glass-half-empty read would be that OMG only debut-ed their version of the tech AFTER others had already seen theirs implemented commercially. Good luck to holders, I’m not short the name - just cautious.
Half-full read - Oxford Metrics (LON:OMG) is a world leader in real time motion capture technology with extensive capabilities in machine learning and AI, trading on a single digit forward PE if you exclude the £60 plus million in cash they are sitting on :-)
Agreed. Though still not particularly cheap relative to the small cap market. It’s all cheap!
Looking forward to reading Graham's views on Gulf Marine Services (LON:GMS) which I am pleased to hold following Paul's reports a couple of years back. Big thanks to Paul - your argument was compelling for those of us not put off by your consistent "Speculative" warnings c 6p.
Hi Roger Baron,
Well remembered! Yes, a friend flagged Gulf Marine Services (LON:GMS) to me a few years ago as an interesting special situation, and I covered it here in some depth. The story was very interesting - high cashflows from specialist ships for the oil industry, where there was under-investment and a long lag to replace them, and early signs of rising daily hire rates. The big question was whether it could survive, and repay a big debt burden.
Looks like things seem to be progressing well, which is nice to see!
I had to warn on the high risk from the debt, a few years ago. When interest rates rose, I lost interest in it, so quite good to see it seems to be coping despite that.
Best wishes, Paul.
Any thoughts on Jarvis Securities (LON:JIM)? They dropped 10% on Friday for no apparent reason and are now at 52-week low. Graham reviewed the last trading update on 10th August when the shares were 125p and said “the latest market cap of £56m looks overly pessimistic”. The stock is now down to 80p with a market cap of only £36m. Looks good value at the current price or am I missing something?
Delayed reaction to them bulleting their FD???
Volume looks to have significantly jumped on Friday (compared to their usual daily volume) and is continuing today, so guessing a larger shareholder is selling out.
Jarvis is due to announce its quarterly dividend by Thursday 9 November. The amount announced (let's hope it's not cut!) should give an idea of how the company is trading. Jarvis do not normally issue a trading update at same time, but they did last quarter. I would hope given the recent share fall, that the new Jarvis FD will give a trading update, as well as details of the next dividend.
Slightly off topic but if anybody is interested, tonight 8pm BBC1 Panorama is about Boohoo and the renewed pressure it is facing to slash costs. I don't hold.
David.
Thank you for another fantastic podcast Paul
"I'm not a Tea leaves guru!! - Brilliant.
Yes a stand-out moment
Ditto Paul thoroughly enjoyable and informative as usual…re Frasers (LON:FRAS) and Shein, possibly a case of “keep your enemies closer”….
Tintra (LON:TNT) ...more grimtech bs in payments...
BBC News app is carrying a piece criticising Boohoo (LON:BOO) ethics again.
BBC News app is carrying a piece criticising Boohoo (LON:BOO)ethics again.
Without once mentioning the pressures on Boohoo from Shein et al. It’s the wrong story at the wrong time.
Is there currently anything going through the legislative process targeting the Chinese shops (Shein, Temu, Ali express, etc)?
And it is just so odd that over the last two decades, there has been strong consumer and media pressure against UK companies, and there supply chains (whether local or overseas). This has, positively, made the UK companies clean up their act to some degree. But absolutely no pressure on the overseas companies.
Shein, Temu etc - It’s bizarre isn’t it? My hunch is that, during a cost of living crisis for consumers, the government is not comfortable restricting the supply of low-cost slave-made fashion even when it would likely allow UK companies to raise prices, improve working conditions and ease pressures on their local supply chains. Either that, or it’s a long while since they gave up running the country for anyone’s benefit than their own.
I have just been buying some stuff on Temu. Many of the items you can buy on Amazon and ebay but the prices are far higher. Prices on Temu do vary, ie go up and down a lot. But if price reduces after you buy, then they refund the difference. Some things are ridiculously cheap, for example, 10m of garden green binding twine, cost 27p. A brush for washing and cleaning trainers, cost 18p. Gloves that I have seen sold in UK online for over £10, 67p. Some stuff is rubbish though but then they refund you, if it is low cost, you don't even need to return it.
Goods are sent by air, take around 5 days to arrive. Can't see how they make any money. They even have service staff who answer your questions.
Why should I buy on ebay and Amazon?
This sounds like dumping. Pity the consumer industries don't have the lobbying power of the steel industry has against product dumping in the UK.
I suppose because UK opinion nowadays has absolutely no influence on the Chinese , so the mighty BBC targets British companies ———a much easier and, too them , rewarding task
The BBC are a bit of a joke atm. Constantly putting the UK down.
Boohoo is a big ZERO in the making and has nothing to do with what BBC thinks.
Don't get me started on this again, I got into trouble previously for questioning why the UK media is so keen to destroy UK company Boohoo, whilst ignoring all the abuses of its Chinese direct competition that air-freight in cheap tat at uneconomic prices. "Unconscious bias" I think is the polite version of what the UK media might be guilty of. And the usual let's destroy our own country, self-absorbed negative mentality that I rant about in most of my podcasts.
I think it is a major piece on Panorama tonight.
SDI (LON:SDI) acquisition of Peak Sensors in Chesterfield for £2.4m. It will join the Sensors and Controls division
SDI has rather fallen from grace and the shares (like so many other small caps) are -27% over the last 6 months. Their policy of buy and build complementary businesses seems to have slowed as it has been 12 months since their last. Director sales didn’t help and it would be good to see Ken or Mike put their hand in their pocket and buy a few shares imo (I hold)
SDI has rather fallen from grace
While director sales have been very unhelpful to the share price - unless one sold immediately on the news - the real problem is the enduring bear market in suppliers to the biotech sector. Life science tool providers are well down right across the spectrum. I think patience will be rewarded when the market revives, but there are superior businesses than SDI to ride the eventual recovery. They just aren’t UK-based.
Some time ago I sold Judges Scientific (LON:JDG) at about £13 because having bought at £6 the price had increased to £24 and then dropped to £13 - I think I hit the low point! The reason was the same; no deals had been done for a while. In retrospect it is easy to understand management would not overpay just to get a deal done and, in due course another excellent deal emerged, The rest, of course is history.
As it happens, I vaguely remember David Circurel telling me he had done something similar with SDI! I don't hold but its on the watchlist.
Judges Scientific (LON:JDG) I hold and have for over a decade
There was a 1:5 consolidation in May 2023 which complicates comparison of historic and current SP's
Other buy and build companies are doing fine such as Teqnion AB (STO:TEQ) and Lifco Ord (STO:LIFCO B) but they are not in the biotech sector, like SID, and the sector is struggling. I own both and also remain a long term holder of Judges Scientific (LON:JDG). I am afraid I sold my SDI (LON:SDI) shortly before the recent pop ..... just not convinced by the CEO.
DX (Group) (LON:DX.) bid deadline extended again. Market seems sceptical. Perhaps it's time to ditch and pick up the shares cheaper when bid does not materialise. Any holders here? Views?
Re DX (Group) (LON:DX.) are they struggling to get the backing of the board and/or other institutional shareholders at the offer price?
We've gone from...
"The Letters of Intent state that it is the intention of both Gatemore and Lloyd Dunn to provide hard irrevocable undertakings in support of any cash offer of at least 45 pence per DX Share made by H.I.G, subject to a unanimous unqualified recommendation of the DX board on or before 31 October 2023."
To...
"The New Letters of Intent state that it is the intention of both Gatemore and Lloyd Dunn to provide hard irrevocable undertakings in support of any cash offer of at least 48.5 pence"
So if the offer price has actually been nudged up even though the two parties that have provided irrecoverable undertakings were willing to accept 45p then there must resistance from elsewhere? (unless of course we are actually just in a process of extended due diligence)
The "possible cash offer" has always been 48.5p per share (see 11/9 announcement). I suspect that the original irrevocable undertakings were given when HIG were pitching 45p per share to the Board, which the Board subsequently negotiated up to 48.5p The more recent irrevocable undertaking announcements have just played catch up.
But why nudge it up in the first place? If the board has negotiated the offer up to 48.5p then why haven't they recommended it? Do they need a "firm" offer from HIG before they can do so?
No other institutional holders appear to be supporting the bid- you'd think Marlborough (who backed DX alongside Gatemore at 10p in 2017) would've been approached but nothing from them as yet- the question for me is why not?
Deadline only extended by 2 weeks this time, which strikes me as a good sign that they just need to dot some I's and cross some t's.
Dear eParo
DX Group (I hold)
The company appears to have strong momentum and, judging by analysts’ forecasts for the next two years (Liberum and Finncap), there will be decent percentage increases in sales, profits and earnings. In addition, the business is highly cash generative with net cash estimates at £31m for the year-ending June 2024 and £45m for the year-ending June 2025.
Assuming the offer succeeds at 48.5p, the exit Price to Earnings Ratio for June 2024 would be 11.7, falling to 11.1 for June 2025. At the same time, the forecast dividend yield would be 3.5%, rising to 3.8%. The exit market capitalisation at 48.5p would therefore be approximately £296 million (I have not allowed for any share options which are yet to be included) but in any event it does not appear to be an overly generous offer given the significant cash the company is currently generating. However, these are difficult times for investors and a cash offer significantly in excess of where the share price stood prior to the November announcement would clearly be welcomed as two of the major shareholders have given their support.
I will continue to hold come what may, as I feel this is a good business model. However, if you are concerned that the offer may fail, it would be perfectly reasonable to sell at least half your holding so as to provide protection with a view, as you have already stated, to repurchase at a lower level.
Kind regards
Phillip
My morning smallcap tweet: Quid Sin
Loopup (LON:LOOP) Tintra (LON:TNT) Ten Lifestyle (LON:TENG) Allergy Therapeutics (LON:AGY) Anglo-Eastern Plantations (LON:AEP) Plexus Holdings (LON:POS) Gulf Marine Services (LON:GMS) Harland & Wolff group (LON:HARL) Powerhouse Energy (LON:PHE), Aptamer (LON:APTA), Kitwave (LON:KITW)
◄LoopUp (LOOP)► will exit its Hybridium business, bought in Oct 2021, to focus on "strongly growing Cloud Telephony business, and not compromised by the requirements of the earlier stage Hybridium business". Exit to save c.€1m and cut debt by same. At the time of the acquisition co said it "brings premium hybrid technology for large scale hybrid communications that is primed for material commercial growth". Hey, ho. Trading broadly in line. [SP=1.9 Cap=4m]
◄Tintra (TNT)► mooted 150p offer rejected by majority of holders. Offerer LRB will now tender for 29.9% of co at 150p. Proposed delisting because it "would be better able to raise the capital it needs to develop the business as a private company". [SP=72.06 Cap=13m]
◄Ten Lifestyle (TENG)► contract expansions, new contracts and new partnership agreements. [SP=87 Cap=73m]
◄Allergy Therapeutics (AGY)► won't need additional funding until end Dec as co cuts costs to eke out cash. Trading broadly in line. [SP=1.45 Cap=69m]
◄Anglo-Eastern Plantations (AEP)► Q1-3 own production of fresh fruit bunches (cont) down 2% by vol. CPO prices are expected to be weak for the remaining part of the year. [SP=680 Cap=268m]
◄Plexus (POS)► £175k contract for commencement and completion during Q2 2024. [SP=15 Cap=15m]
◄Gulf Marine Services (GMS)► hikes FY-Dec EBITDA guidance to $83m to $86m (previously: $77m-$85m). FY24 hiked to and $87m to $95m. [SP=12.4 Cap=126m]. I hold.
◄Harland & Wolff (HARL)► wins £8.5m barge contract extension from Cory for delivery by H1 2025. [SP=14.4 Cap=25m]
◄Powerhouse Energy (PHE)► another company challenges PHE's EU patent granted 15 Sept. Co considers the Claim to be entirely without merit. [SP=0.27 Cap=11m]
In line: APTA, KITW
Next - Answers on a postcard
Morning Paul. In your weekend podcast (great commentary as always – big thanks), you briefly asked why Next was doing better in online fashion than rivals like ASOS or Boohoo.
Here it appears #NXT (see below H1'23 slides) is performing well both overseas (via licensing, wholesaling & using 3rd party aggregator sites) and with their new “Total Enterprise Platform (TEP)”.
Whereby they’re trying to become a viable UK competitor to the likes of Amazon marketplace for fashion. Offering external/non-NXT brands (eg Joules, Laura Ashley, Reiss, GAP & Victoria's Secret) all the logistics, website, back-office systems & importantly returns too (I believe) that 3rd parties need on an out-sourced model.
Re: 'Total Entreprise Platform'........ Yes i noticed that and thought i had got one of my EVRI return delivery slips mislabelled when querying a GAP return (i clearly buy too many clothes online!) that hadn't been credited to back to my card.And thought darn!.. i've mislabeled everything as the tracking came up as NEXT and was just about to say to the online agent/AI (not always sure which!).. 'sorry i must have made a mistake'.
And then realised that NEXT do all the backend logisitcs work for GAP over here now.Interesting model as they own or part own a lot of brands that became troubled now including Joules, Reiss, Fat Face i think.
I never even knew our local Fat Face on the highstreet had gone bankrupt during covid.They're 'doing a Mike Ashley'... or either Mike Ashley is doing a Next.