Small Cap Value Report (Mon 7 Oct 2024) - CAV, BKS, FDP

Good morning from Paul & Graham!
That's it for today, we've covered everything.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
Summaries
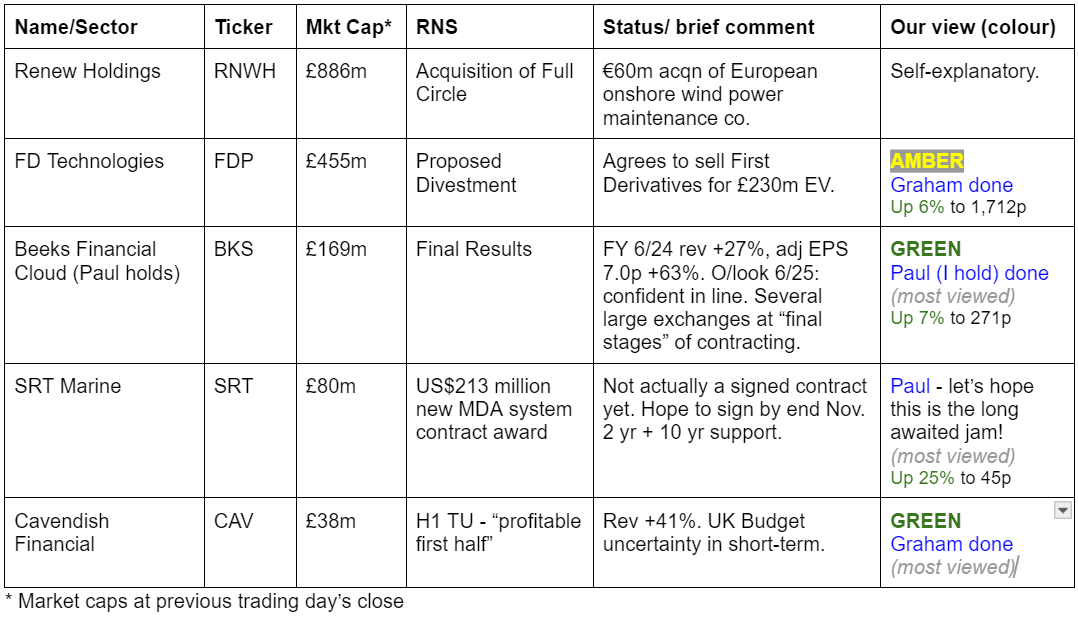
Cavendish Financial (LON:CAV) - up 3% to 10.05p (£39m) - Half Year Trading Update: Profitable First Half - Graham - GREEN
It’s a positive update with like-for-like revenues up 41% and the company back in the black. Some patience may be needed before we see truly meaningful profits but I like the risk:reward on offer with the enterprise value here currently just £22m.
Beeks Financial Cloud (LON:BKS) [Paul holds] - up 6% to 268p (£179m) - Final Results - Paul (I hold) - GREEN
I run through the numbers, which show good growth and positive free cashflow for the first time. Strong growth expected to accelerate in FY 6/2025, and the NASDAQ contract isn't even in the forecasts yet, so likely to beat expectations. Plus more large exchange deals are close to signing. BKS shares look pricey, but I continue to believe this is an almost unique commercial opportunity for a UK small cap, that's taking off. So personally I can tolerate the lofty valuation metrics.
FD Technologies (LON:FDP) - up 6% to £17.06 (£481m) - Proposed Divestment - Graham - AMBER
FDP proposes to sell off what was its core asset, in order to focus on its software business KX. It hopes to receive £230m which will pay off its debts and enable a return of capital. I’ve always shared the bears’ scepticism on this stock and am most comfortable with a neutral stance at this time.
Paul’s Section:
Beeks Financial Cloud (LON:BKS)
Up 6% to 268p (£179m) - Final Results - Paul - GREEN
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its final results for the year ended 30 June 2024.
Revenue up 27% to £28.5m - this seems to be a little behind forecast (of £29.2m, and was £30.0m a few months ago), but it doesn’t really matter, as +27% organic revenue growth is more than enough. It’s due to timing of a new contract, which slipped past the year end date, but now boosts FY 6/2025 numbers.
Canaccord points out in a helpful update note today that this makes BKS one of the UK market’s fastest growing mostly recurring revenues businesses. Further significant (faster) growth is pencilled in for FY 6/2025, due to a large contract kicking in (still under a non-disclosure agreement, but it’s NASDAQ - investors found a document online proving this, there’s a link in a previous report of mine somewhere in our archive).
Canaccord has £39.6m revenues pencilled in for FY 6/2025, a rise of 39%, all organic and mostly recurring, so this share is going to attract a premium rating, and PERs are largely useless for rapid growth companies. Hence investors tend to use valuations linked to multiples of sales or EBITDA, which personally I’m not terribly comfortable with, but you’ll get nowhere fighting the market - standing on the sidelines saying it’s overvalued has already meant missing out on a bagger here.
Various profit measures for your perusal -
Underlying EBITDA £10.7m (up 27%), the most aggressive measure that ignores a lot of costs.
Underlying profit before tax is more sensible to my mind, at £3.9m (up 68%).
Statutory PBT is the most prudent measure, and it’s a maiden profit of £1.5m. This includes the cost of employee share options, which in this case particularly are used as a form of remuneration, so I think it’s right to expense them, not adjust them out.
Underlying diluted EPS is 6.36p (up 61%) - that’s helped heavily by adjusting out the share options, and a negative tax charge. So the PER of 42x FY 6/2024 numbers is high, and based on a fairly aggressive EPS number. Hence this share clearly won’t appeal to value investors looking in the rear view mirror!
On valuation metrics BKS shares are clearly expensive. However, given the rapid organic growth valuations at this type of growth company can move things from expensive to attractively cheap. Over the years I’ve missed out on a lot of multibaggers by refusing to pay a high PER early on. Concentrating on low PER shares is an important investing lesson to unlearn - sometimes, in carefully selected cases, paying a high PER is necessary, and justified. I think that applies to BKS, hence why I’ve made this my 2nd largest personal position (for full disclosure, as required for writers here).
Note that the PER is high, but the PEG is quite reasonable, due to rapid earnings growth -
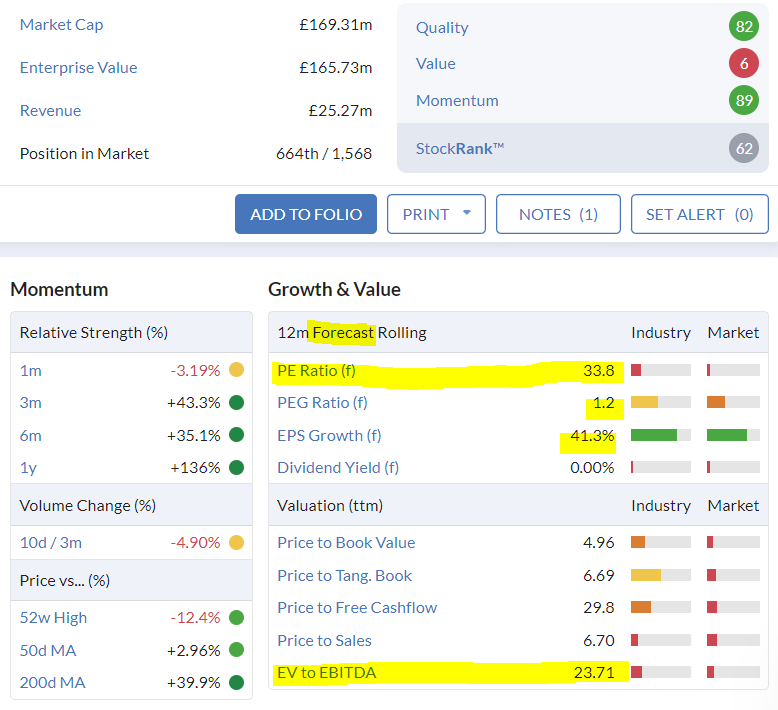
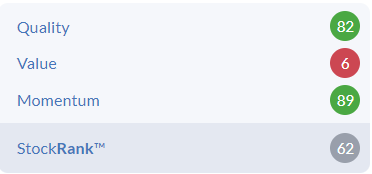
The value score is only 6, and obviously the risk is that if growth conks out, the shares would have a long way to fall.
Thankfully, BKS has excellent visibility due to most of its revenues being recurring, and management are confident the rapid growth in the forecasts is realistic.
I don’t think there’s anything to be gained by over-analysing the historical numbers. This share is all about continuing (accelerating, even) growth, so let’s look at that.
Some good points in this operational section -
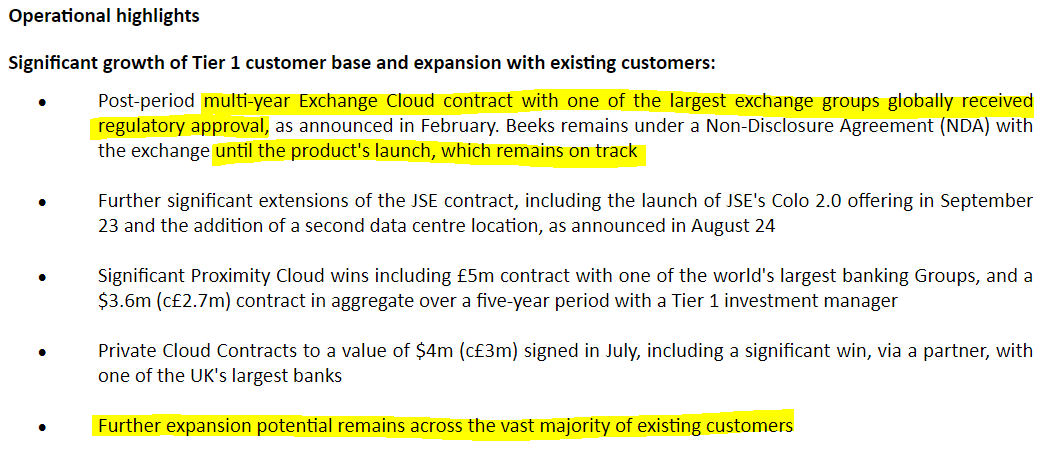
Note that the big contract (NASDAQ) is NOT currently in the forecasts. I confirmed that again today with the company, but I phrased it as the "large exchange", since they are not allowed to confirm the identity of the client, but I can mention it here because I independently, and from a public document, found out the client identity.
We’re nicely set up here for positive newsflow over the next year, as more big contacts get announced, and forecasts are raised to reflect the NASDAQ contract coming online. That’s already known of course, so you could argue some of the upside is already baked into the share price.
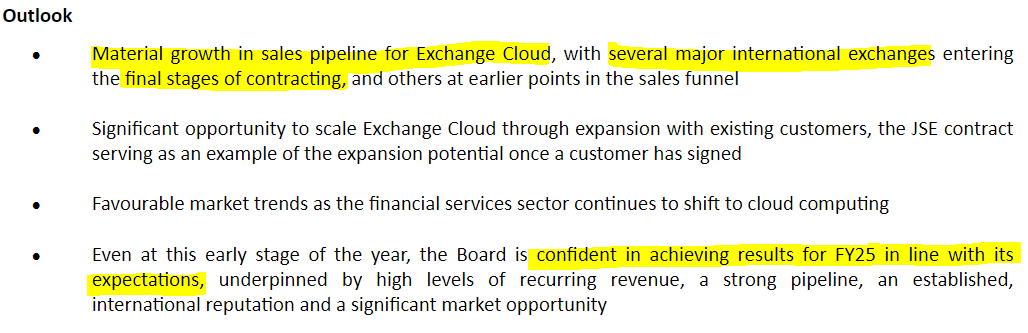
The words “final stages of contracting” above really stood out to me, and I think it’s probably that point which has driven the positive market reaction to today’s news. I tried to get more colour on this, but management won’t be drawn on the timing, as decisions from clients are outside their control, and there are often delays when dealing with large organisations.
Balance sheet - NAV £37.5m, less intangible assets of £9.4m gives NTAV £28.1m - a decent amount for the size of company, but remember it has to spend a fair bit (up-front) on servers and cabling, so it’s more capital-intensive than most small IT companies. Property plant & equipment have a NBV of £16.7m, including £2.9m freehold property. Computer equipment has a NBV (net book value, ie cost less accumulated depreciation) of £10.7m, so it’s not huge amounts by any means.
Cash is almost flat vs LY at £7.7m, and note £1.8m “Borrowings” have been repaid in the year.
It all looks fine to me. Risk of further dilution is now negligible, and I confirmed with the company today that it doesn’t intend raising any more equity, as it’s now self-funding. Unless an M&A opportunity came up, but it’s not an M&A focused company, so that’s probably not likely.
Cashflow statement - is the best so far from BKS. It’s genuinely cash generative now, about £2m free cashflow the way I look at it (taking off all real world costs, including £3.9m capex and £2.9m capitalised development costs). The cash generated was used to repay the £1.8m debt as mentioned above. No divis yet, as it’s a growth company.
So I think criticism from bears in the past about poor cash generation has now fallen away as an issue, with BKS now demonstrating maiden positive free cashflow, although it has been helped a bit by working capital movements.
The business model is that it puts in all the infrastructure, and then earns a long, sticky, and growing revenue stream from it, probably over many years, even decades.
Call with management - a few key points from our Q&A this morning, and remember this is just my recollection/interpretation of what was said, which might not be totally accurate, especially as I cheerfully admit that I don’t really understand IT.
Q. I’ve never really understood what moat BKS has, what is special about the company?
Highly specialised technology. Most cloud computing just sends information from A to B. Whereas exchanges require that all members receive the same information (prices, news, I assume) at precisely the same time. Beeks doesn’t really have any competition in this area.
Partnership business model - once BKS system is installed, exchanges earn a significant amount of money from white-labelling it to their customers. Hence business is sticky.
Everything is bespoke, tried & tested. So why would any exchange reinvent the same thing using another IT company, with the risk that it might not be 100% reliable, when BKS already has a proven system with major reference clients, that can be quickly installed & switched on.
Snowball effect - BKS is becoming the standard for exchanges, which are geographically based and don’t compete. They talk to each other, and word has got round that BKS is reliable & generates profits for the exchanges - a substantial & growing moat (my words).
Emerging markets are exciting growth opportunities, not just the major Western exchanges, because it’s harder to do business in emerging markets, so there can be strong demand as has been proven by the JSE (Johannesburg Stock Exchange), where annualised revenues are now a lot larger than originally planned - proving up the “land & expand” principle.
Other points -
Building out a new AI product, for real-time data analysis. Customer-driven request. Not spending a huge amount on it, don’t yet know if this will become significant or not.
No need to raise any more equity.
Have you seen any Budget-related, tax selling from BKS shareholders? A bit, yes. Plus some funds have had to sell, due to redemptions.
Paul’s opinion - I’ve mentioned previously that I don’t fully understand the services that BKS provides, but I can see that the very impressive organic growth and snowballing size of contract wins shows that there’s something special here. Hence management explaining to me on a call today, in simple layman’s terms, what is special about BKS was really helpful. I’ve invited the CEO to do another audio interview with me, which was well received last time, and will try to focus on the overview of the business model, rather than the technical detail.
BKS is not a value share, but I think it’s one of a handful of exciting growth companies on the UK market, and I feel the big rise in share price is justified by very good newsflow. So I’m staying bullish on it. That’s not just because I own some shares personally. It’s actually a comfortable hold for me, because I think the fundamentals are getting better. As I’ve mentioned before, I’m in this for a potentially big longer-term opportunity, so am not top-slicing my position despite a big rise. That does mean having to sometimes look away from the screen when it goes through a volatile, profit-taking patch, but I don’t think I can predict those moves, so I don’t even try.
Hence for me it’s a continuing GREEN (I hold).
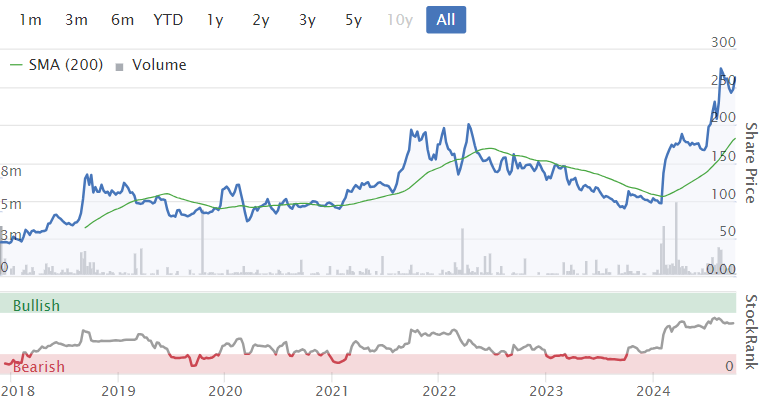
Chart since listing -
Cavendish Financial (LON:CAV)
Up 3% to 10.05p (£39m) - Half Year Trading Update: Profitable First Half - Graham - GREEN
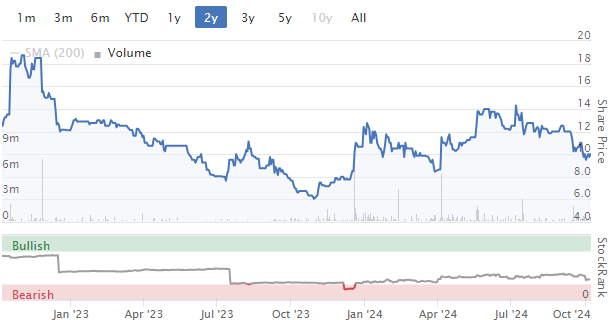
This small-cap broker has been on my best ideas list for two years running. The share price hasn’t cooperated with me yet:
But today’s H1 trading update to the end of September has some encouraging news:
Like-for-like revenues (taking into account the merger of Cenkos/finnCap in Sep 2023) are up by an impressive 41% to at least £27.5m.
H1 is described as “profitable” but for now I would assume that profits are small and much closer to breakeven than to anything more meaningful. Still, it’s an improvement on recent losses that have been posted.
Cash is at £17m which the company describes as a year-on-year improvement; however, this is the same cash balance as of November 2023 and is down from what it had reached by March 2024. So I don’t really feel that much progress has been made on that front in reality.
Forthcoming activity sounds promising although this paragraph doesn’t leave us with anything too concrete:
We have a solid pipeline of both public and private transactions in train including a number of potential IPOs and ongoing public M&A activity. We have increased our share in the public markets in terms of the number of AIM clients (rank 1st) and by adding clients on the Official List to meet our ambition of increasing the average market capitalisation of our client base.
Outlook refers to Budget uncertainty and “adjustments” that may be needed post-Budget. Come the end of this month, I guess there’s a strong possibility that we’ll be figuring out the implications of lost inheritance tax relief?
Graham’s view
This is a positive update, with the main points above all being that CAV has broken back into profitability and has seen a substantial increase in like-for-like revenues.
However, it is still far too soon for bulls (like me) to declare victory. I have always said that I see breakeven as the basic requirement for companies in this sector: bankers get paid well enough when things go right, and their pay should be flexible enough so that shareholders don’t have to take the hit when markets are quiet.
In the case of Cavendish, I did make an exception for FY March 2024 (discussed here). My reasoning was that during a merger, when there was a great deal of change, I thought it made sense for the company to pay bonuses to reward and retain staff even if that meant that there was a modest operating loss.
However, moving forward, I do expect CAV to be profitable even when markets are quiet. After all, the merger is supposed to have unlocked £7m of cost synergies. Now they just need salaries and bonuses to be linked to revenues in a reasonable way, as they have always been (Cenkos was particularly good at this).
Today’s update is a step in the right direction. For this stock to really take off, we need the UK small-cap market to take off again. Once the Budget is out of the way, perhaps that will provide the clarity that is needed?
Please note that the enterprise value here (market cap minus cash) is only £22m. In a bull market, I think CAV's EV to earnings multiples would be incredibly low at this valuation. But of course no one can predict with any certainty when that will happen!
FD Technologies (LON:FDP)
Up 6% to £17.06 (£481m) - Proposed Divestment - Graham - AMBER
Like Paul, I’ve been sceptical of this stock. For as long as I can remember, it has always traded at very rich valuations, and its financial performance hasn’t seemed to match up with its valuation.
Back in 2018, I discussed the attempt by short seller Matthew Earl to carry out a bear raid on it.
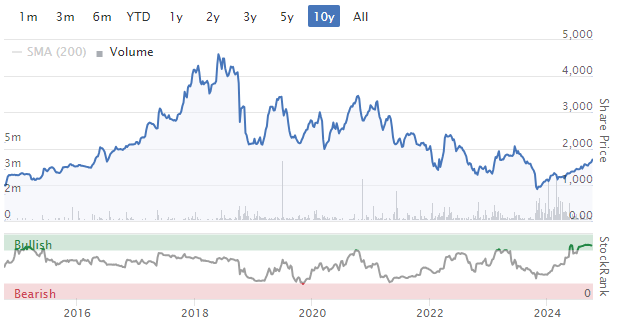
Here’s the 10 year chart. It has been quite a ride:
Figuring out what the company does has never been terribly straightforward.. The first line of the description on the StockReport reads: “FD Technologies plc is a group of data-driven businesses that unlock the value of insight, hindsight and foresight to drive organizations forward”.
The argument from bears was that FDP was a consulting business with some software investment thrown on top.
Today’s news is about a major simplification:
FD Technologies… announces that it has entered into an agreement to sell the Group's First Derivative Business to EPAM Systems, Inc… for an enterprise value of £230m (the "Divestment"). The Divestment is expected to complete in the fourth quarter of 2024, subject to shareholder approval, amongst other things.
The proposed sale will provide “the optimal organisational structure” and “enable the company to focus on KX, the part of the Group with the largest value creation potential”. It will also pay off FDP’s net debt (£20m) and bring about a return of excess cash to FDP’s shareholders.
KX is a US-based software company - homepage and Wiki article.
The proposed buyer of First Derivative is a software services company that is already in a partnership agreement with KX, and will enhance this partnership after the deal goes through.
New Trading update: H1 is in line with expectations for both KX and First Derivative. For FY25, KX is targeting to add annual contract value (an important metric in the software industry) of £16-18m.
CEO comment on the sale of First Derivative:
This Divestment is positive for all stakeholders, benefitting our shareholders and the customers and employees of KX and the First Derivative Business. For shareholders it enables the Group to focus on KX, and provides the resources to deliver on our exciting growth plans while also enabling us to return excess cash…
Graham’s view
KX has an impressive online presence but I wouldn’t want to make any suggestion as to what it might be worth. I can say with some confidence that FDP probably wouldn’t qualify as a “value investment” even if we assume that this proposed deal goes ahead.
After receiving £230m (net of any cash/debts at First Derivative), £20m will go to FDP’s debt repayment.
Let’s suppose we have roughly £200m left after costs. That leaves an enterprise value of £280m for FDP based on the current market cap.
KX generated revenues of £79m last year (FY Feb 2024).
When those results were released, FDP said that KX was targeting “positive cash EBITDA for FY27”. So there’s a few years to go before we can expect decent financial results from this entity.
Could this be worth a number like £280m? Perhaps, but it’s not a value investment.
I’ll just stay neutral on this for now.
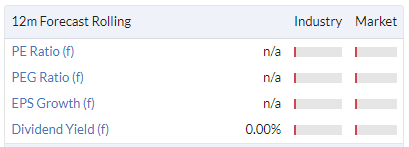
FDP enjoys a high StockRank of 81 thanks to high Quality and Momentum scores, and despite offering poor value:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Paul,
Sorry this late in the day but
Beeks Financial Cloud (LON:BKS) . Excellent write up.
My question is if Beeks offers a point to all points immediate service what did the exchange do before Beeks Financial Cloud (LON:BKS) came along or is it just the white label aspect that's so appealing to the exchange??
Thanks. I'll look at the webinar on IMC tomorrow as well
Disclosure I hold a small position
New broker note for Games Workshop (LON:GAW)
https://www.edisongroup.com/research/sigmar-the-fourth/34021/
Hopefully this is not too off topic but I think Googles NotebookLM is interesting - it's generated a podcast based on todays SCVR below - it's very generic and mentions no contributors names so hopefully I've not broken any rules here by giving it a PDF of todays report and obviously I've no intention of distributing this more widely. Google also state that they don't take ownership of any uploaded data for further training or distribution themselves.
I downloaded it and made available on Drive so it shouldn't need any further login to access it:
https://drive.google.com/file/d/1hwb7o_2j0_KaSydshyxydbgmHvsJ9FK3/view?usp=share_link
Unsurprisingly this is not a patch on the real deal - for example there are no amusing ambient noises or commentary (apart from the pronunciation of NASDAQ aka NAS-DAY-Q) and they didn't say byeeee which is a dealbreaker.
It's not completely unlistenable though - there's a half decent albeit simplistic explanation of the traffic light system at the start followed by high level commentaries that brings in the concerns about the budget. Some of the points made were a bit off the mark and I can see the podcasting style getting a bit annoying after the novelty has worn off but it's quite impressive given how quickly it came up with it which was within minutes - I just let it get on with it in the background
I also tried it using the latest research tree reports and company statement for BKS - they compared the different angles taken by the two reports so it wasn't just taking high level headings and padding them out. This might not a bad way to just get a quick view of things - an alternative screen reader - while working on something else or out for a walk where the conversational style is suited to the drifting in and out of focus while navigating roads, dog walkers, squirrels etc.
You pays your money, you takes your choice. I guess whatever format works for you - as long as the value of paying sp membership is not compromised.
One of the best bits of advice I was ever given, 35 odd years ago, was by an American tutor. “Where-ever you are, be there “.
Nature, dogs, weather, neighbours and fellow walkers. its peoples personal choice if they wish to be cocooned against all of these - cant feel its healthy for anyone in the long run though imo.
Nature, dogs, weather, neighbours and fellow walkers. its peoples personal choice if they wish to be cocooned against all of these - cant feel its healthy for anyone in the long run though imo.
Yes Lochinver it's good to unplug - I do occasionally stop listening and take in the wondrous splendour of my local park and co-op but doing the DYOR without a screen is handy since I have to sit in front of one for most of the day
Wow, that is remarkable!
It embellishes things a little, and turns the SCVR into a CNBC-style interview format. But it got the main points right. Amazing what AI can do, I might become a convert at this rate!
Paul,
Great work on the podcast this weekend. Brilliantly informative as well as being very funny and entertaining. But I think you shouldn't hold back when you said a company (can't recall the name) was a 'crock of shit!' Say what you mean. LOL :-)
Graham.
The podcasts are superb and I listen every week. I wouldn't change the format, works brilliantly. Just one small comment if I may - if you could keep it to around 1hr then that would be great. When it gets over 1hr then I find it harder to fit it all in with everything else to do. Thanks.
We all have different perspectives but many subscribers and listeners would happily listen for longer, particularly say where there was quite a bit of general macro or other observations
“many subscribers and listeners would happily listen for longer “
Did I miss out on your survey of subscribers ?
Nice analysis / review on Beeks Financial Cloud (LON:BKS) Paul. Thanks. I concur that this is a special company and is one of my top holdings. Here's hoping at least one of those Exchange contracts get signed by the end of the calendar year. Significant upside risk to FY25 and FY26 me thinks.
Yes if you are looking for a moat when investing in a company then Beeks Financial Cloud (LON:BKS) has got one of the best. In a domain where millisecond discrepancies can cost millions then their technology is essential. Typically the public cloud providers(Google, Microsoft, AWS) operate what they call ‘eventual consistency’, the information will be routed from A to B but there is no guarantee on order or timing. Beeks Financial Cloud (LON:BKS) systems once installed will take a pretty big effort to remove and client stickiness is going to be high. I missed the early meteoric rise in share price but got in at low 200’s and happy to sit back and watch the next few years.
Good point. Hazy memory but remember article in news how a hedge fund built a cable between New York and Chicago over ten years ago to shave milliseconds off trading . Holding Beeks Financial Cloud (LON:BKS) as seems to have something special against competition.
Thank you to Paul Scott for podcasts. Must take a lot of mental energy to do a hour long one with economics and politics more entwined than generally in the past.
GM,
I have also seen this same thing before, where traders have installed ultra fast cables and internet to be able to shave mili-seconds off trading times so that they can be the first to execute a trade. If this is your game and the way you do things, ultra fast and rock solid secure connections and cloud used or storage must be fundamental. That's about the extent of my knowledge and understanding on these issues.
I hold Beeks Financial Cloud (LON:BKS) so DYOR.
Graham.
I thought of you and your locked out predicament on Saturday, Paul.
I was outside the front of my house doing a bit of painting and I had a phone call from my wife to say that she couldn't open the front door. I tried from the outside and no luck so went in via the back door and found the multi-point locking was retracting but the latch wasn't releasing. Luckily my wife uses a neighbourhood page on FB and she found the name of a recommended local locksmith. I rang him and explained that the only door with a wheelchair ramp for my wife wouldn't open. He dropped everything and came round within half an hour. Within 10 mins he had applied his gentle persuader which looked like a thin stainless spade to the gap between the door and frame (which has a full length window so not rigid) and bobs your uncle. Nothing broken, a hardly noticeable scratch and 5 minutes to swap the mechanism that sits between the lock, the latch and multi-point hooks. £155 for a self employed expert who lives by recommendations and I was well pleased. So you know where to look, everybody, next time you want to get any help. Make sure you use the full locking too and don't leave a spade around :-).
Renew Holdings (LON:RNWH) , today's announcement it has
"acquired Full Circle Group Holding B.V. ("Full Circle" or the "Company"), a specialist provider of repair, maintenance and monitoring services for onshore wind turbines in the UK and Europe for a total cash consideration of €60.0m (£50.5m), funded from the Group's existing cash resources and banking facilities"
Acquisition Highlights
· Entry into the highly fragmented onshore wind services market which is forecast to grow at 7.7% CAGR from 2024 to 2030 as both the UK and Europe seek to deliver on their commitments to achieve Net Zero 2050 targets
· Technology-enabled platform providing 24/7 remote maintenance across nine countries from a centralised control centre in Amersfoort, the Netherlands
· Attractive servicing model built on strong customer relationships, with long-term, recurring full-scope contracts (c.7 years average remaining contract duration with c.95% renewal rate)
· Strong financial profile: FY21-23 revenue CAGR of 25%, delivering 14%+ EBIT margins which will be accretive to Group margins
· Excellent revenue visibility for FY25 and beyond with c.85% of Operations and Maintenance (O&M) contracts already secured and a strong pipeline of additional opportunities which gives overall revenue visibility for FY25 of c.75%
· Trans-European presence with c.75% of revenue currently generated through UK operations
· Experienced and committed management team in place to execute growth strategy
· The Acquisition is expected to be earnings enhancing to the Group in the first full year of ownership, with ROIC in excess of the Group's cost of capital by the third full year of ownership
This follows last week's small disposal and recent acquisition of UK electricity infrastructure contractor. It will be their first investment into Europe, so additional challenges but with their track record to date has been solid with the SP 10 bagging over the last 10 years.
I know Paul is a fan but recently highlighted that he thinks the price is up with events. The price has not moved on the news but after going sidewise for the year, the budget could give the stock a boost. I topped up this morning.
Well they're always breaking down..!Siemens Energy AG (ETR:ENR) almost went bust because of the parts 'falling off'.. the Gamesa division.. and had to be bailed out with a guarantee by the German government.The share price has multibagged since, but you had to be brave to buy anywhere near the recent lows.
I feel a bit sorry for whoever writes (I believe it is the Chair) the trading updates at Cavendish Financial (LON:CAV) (I hold) as visibility is very limited at any brokerage business. Every investment banker I have ever spoken to has a “great pipeline” of future deals - but as well as the need to remove the rose-tinted glasses, management knows that if the market falls 10% tomorrow, many of the IPOs /M&A deals that are supposedly “in train” will be derailed. On top of that the budget in 3 weeks time could then deliver a more structural damage to Cavendish’s main market (AIM). Therefore, I conside that the “outlook” statement can do little more than talk about the recent past.
Yet looking again at the (July) outlook statement in the FY24 results, the (September) AGM statement and today’s TU, I would infer that the April-June quarter was considerably stronger that the July-September quarter.
Ahead of the budget, I have generally been selling AIM stocks that I feel are likely to be held in IHT AIM funds. (My criteria is solid dividend paying AIM stocks that Investor’s Champion says are likely to be IHT exempt). Being a financial company , my understanding (DYOR) is that Cavendish Financial (LON:CAV) is not eligible for an IHT fund. Yet its business model means that it will be one of the most exposed (upside and downside) to the IHT decision in the budget.
Does look like people of taking advantage of the good results to sell Cavendish Financial (LON:CAV)
I think they will be ok, if not UK market as a whole is bang in trouble..
Waited ages for a bit of stability in government and Labour go and cause more instability in the markets...
donuts
Goodwin (Goodwin (LON:GDWN)), the highly successful Midlands-based engineering group, has long operated below the radar screens of all but its most loyal fans. It has never courted investor attention before. So what should be made of its appointment of Berenberg as its Joint Corporate Broker with immediate effect, alongside Shore Capital?
According to Stockopedia, Goodwin is trading on a p/e of 31 and a yield of 1.9% so it cannot claim to be heavily undervalued as is the case with other quoted family controlled businesses. It does not need to raise capital since it bought back a hefty chunk of its shares at £48 a year and a half ago. So what is the point of adding a second corporate broker?
The next generation of Goodwin's (no relation) want a higher profile for the firm?
Goodwin (LON:GDWN)
'So what is the point of adding a second corporate broker?'
Others will know more than I do - Suspect it may be related to the recent inclusion in FTSE indices and the FTSE250 specifically where I understand that liquidity rules can be an issue?
I'm pleased that Shore Capital has not been replaced - as they tend to be more private investor friendly than the 'big brokers' like Berenberg? Remains to be seen what if anything they will achieve?
Intriguing that there are no institutions on the top shareholder list? This may be a part of the puzzle? In the medium term perhaps we will see broker forecasts emerge? Hard to do in the short term with so many moving parts to the business right now?
cheers
Mark
I think you may have misread the RNS sparkler. It says:
"The contract includes the turn-key delivery of the system within 2 years, followed by a 10 year support and maintenance package."
The major element of this contract is the system and associated equipment. We're talking about software (which already exists). servers, display screens, radar, AIS transceivers (made by SRT), control towers, drones, etc. Whilst some equipment is bought in, such as display screens and servers, the software and AIS transceivers should generate a good net margin and be operational within the first two years. There will be milestone payments at frequent intervals as various aspects are delivered. I understand that SRT does not develop different versions of the software for different customers, all users have the same system but each will use whichever features they need.. As new requirements or enhancements are added, a new version is released, roughly three times a year.
By contrast, support and maintenance, which includes regular software updates which add new features, will be lower revenue and it distorts the picture if you simply divide the total value by 12 years.
One aspect not mentioned in the RNS is how acquisition of data is to be priced. SRT can provide data about boat movements outside the reach of land based stations. This is achieved from satellite monitoring and how it is charged is written into the contract. If there is to be satellite data provided, then it will create a recurring revenue stream. I hope to find out more at the AGM.
Thanks for the additional info rwh3ue. Yes, I agree that my division by twelve was simplistic. However, what you say does just raise more questions e.g. how much of the total contract value is for equipment supplied by others with presumably a straight 'pass through' by SRT and why don't they try and split out this figure from the headline number for us?
I suppose that essentially this investment comes down to whether you trust the management or not and I don't. However, I don't disagree that the numbers are potentially compelling if they can deliver - so good luck to holders.
SRT Marine Systems (LON:SRT) , I think you have hit the nail on the head sparkler, it does come down to trust. In my case I have spent years invested here and fully appreciate the caution of others resulting from false dawns. I think when it comes to trusting management, there are two ways to look at it. Are they honest and are they capable? For me, the answer to both is "yes". Simon Tucker is very open, he was one of the first CEO's to hold regular webcast updates, long before it became a normal practice. AGMs also included a tour of the site, allowing visitors (who incidentally did not have to be a shareholder to gain entry) in which one was able to speak to any member of staff or management and see demonstrations and products.
Capability is multifaceted. There is no doubt in my mind that SRT have some of the best products on the market. They have also developed a comprehensive system to analyse the data coming in to the system. In early implementations, the operators in Bahrain were overwhelmed by the sheer volume of data being reported and SRT responded by adding ways of recognising suspicious as opposed to innocent behaviour and the automation of requests for action eg, send out a patrol vessel.
Capability also includes the ability to deliver and I freely concede that SRT have been shown to unable to predict when things might happen. ST himself has admitted to being overoptimistic but one has to have some sympathy here. dealing with foreign governments can be tortuous. I recall a conversation with Simon where he had visited a country in the middle east and had spoken to the head of the civil service who was responsible for signing off a contract. This man had many thousands of staff across multiple departments. Each of these needed to review the draft contract and approve it before he could sign. He said to Simon that he hoped it would be done in the next couple of months and added "inshalla" (if God wills). Needless to say, it took another year or so.
So is SRT a trustworthy company? There biggest failing has been their inability to forecast when revenues would flow and the knock effect of having to pass round the "begging bowl". with the benefit of hindsight, we may be able to see these things as naivety but I honestly don't think anyone could have done a better job of building a British company we should be proud of.
My understanding is that this latest contract is with a Middle Eastern country beginning with a K. SRT already have an ongoing contract with Saudi Arabia and as Bahrain is due to order a small upgrade to its system, it's clear to me that this is an area where the need to know what's happening in their waters is driving this interest in doing business with SRT. This is the same as is happening in the Philippines and Indonesia plus the added dimension of fishing which has enormous implications for the populations.
You asked why SRT doesn't split out the ancillary costs of infrastructure. I suspect if you ran a company seeking to win business elsewhere, you would be coy about revealing just how much you are charging your existing customers. for each aspect of the contract. This is not Tesco selling tins of beans after all.
I don’t think everyone appreciates the complexity and scale of the System division’s offerings nor understands the issues around the financing when it comes to inter- governmental contracts.
Also overlooked is the Transponder division contribution which ST reckons has 85-90% of the market. Their new NEXUS offering which will be launched next month has already received advance orders.
FWIW I also hold Beeks Financial Cloud (LON:BKS) and feel it’s potential is way below SRT Marine Systems (LON:SRT).
SRT Marine Systems (LON:SRT)
Exactly Jim McLad. I just re-watched last week's webcast and ST emphasised that countries do not buy these systems on a whim. It takes a long time to precisely define what they need and develop mutual trust. Some countries have long memories of being shafted by large corporations in the West and have become very circumspect about committing to spending very large sums and tying themselves in for the foreseeable future.
Incidentally, ST also said SRT had sold over half a million transceivers so far, over 90% of global sales.
I am not sure there is much value to take from that comparison. These (Beeks Financial Cloud (LON:BKS), SRT Marine Systems (LON:SRT)) are very different companies operating in very different markets. Both will add value to a well-balanced portfolio. There's not much point in setting one up against the other.
Cavendish Financial (LON:CAV)
A very vague statement from the company and I believe this should not be green.
Revenues have fallen here from H2 of last year as these were about £35m and now for this financial year H1 are only £27.5m.
Cash has fallen as well.
All the best
Another vague update from Cavendish Financial (LON:CAV) today and I’m looking forward to reading Paul’s take on it.
“Profitable.” That’s it on profits. 1 word!
Looks as though they are getting enough business to bump along with minimal profit. Useful info on their deals are in this link from their website:-
https://www.cavendish.com/deal...
BIG plus is the market cap is only £37 million. IF IPOs ever get going again, with these including AIM newcomers, then cash could flow in along with rapid profits growth, and the current share price of 10p would be a steal. BUT that potential optimism is not covered in the vague Outlook comment. Seems they are for now under promising. I prefer Companies that under promise and outperform (like Next (LON:NXT) does.
A good chance that there will be something in the Budget to give a boost to smaller Companies and to Cavendish Financial (LON:CAV) ? If there is maybe it will pay off buying Cavendish Financial (LON:CAV) ahead of the Budget?
I’m holding at a loss.
It all comes down to where they can get the comp ratio at Cavendish Financial (LON:CAV)
Based on the H1 revenues, I have three scenarios:
- Comp ratio stays at 73% (same as the elevated FY24, unlikely). Operating profit likely £0.4m/H1.
- Comp ratio goes to 68% (maybe a bit ambition in 6 months, but surely doable longer term). Operating profit of £1.8m/H1. Not bad on a £37m market cap.
However, my investing here is that I think they could get the comp ratio down to close to 60%. This was achieved within the last 5 years, so its not blue-sky, it is actual comp ratio. This, of course, probably also involves more activity/revenue (ie people kept very busy, absolute bonus goes up, but a lower ratio).
At this ratio, we're looking at £5m+ operating profit in a half year. £10m+ yearly. And there's very little to adjust to get to PBT.
Couple this with maybe 20%, 30% revenue growth if things pick up, and you can see how a £37m market cap could plausibly become a £100m+ market cap within 12-18 months.
(I hold in the Boon Fund)
Love the podcasts, and this week enjoyed listening on the beach in Kefalonia. Keep them coming. I want to big up the English wine industry. There are so many vineyards across the south of England - Mainly Kent, Sussex, Surrey and Hampshire along the South Downs. I understand that you don't rate the wines but i think that they need to be compared to the champagnes of the champagne region of France - the sparkling wines produced in England are exactly the same grape varieties and the 'terroir' of the south downs in particular is exactly the same geology as in the champagne region - chalk and flint and the climate is perfect. Many French champagne houses are buying up land in the south to produce English Sparkling because the climate in the champagne region is becoming to warm. In conclusion, if you don't like champagne you probably won't like English Sparkling as it is exactly the same stuff and reflected in the price. There are now over 1000 vineyards in the UK. Gusbourne (LON:GUS) Chapel Down (LON:CDGP) are just two of the bigger producers.
In conclusion, if you don't like champagne you probably won't like English Sparkling as it is exactly the same stuff and reflected in the price. There are now over 1000 vineyards in the UK. Gusbourne (LON:GUS)Chapel Down (LON:CDGP) are just two of the bigger producers.
Surely the conclusion should be drink the product, don’t buy the shares? That’s what I do! I can’t invest in something that requires so much capex and then requires lots of marketing and ultimately depends on something as unreliable as the weather. Some of these vineyards are in frost pockets and they sit there praying every spring that the weather doesn’t wipe out the coming years vintage. Good luck to them.
I agree. The good news for sparkling wine, is you don’t need fully ripe grapes - it’s all about acidity, not flavour. Most sparking wine is drunk far too you, without any flavour development, so you don’t need the flavour compounds and development that only comes with a few years of bottle age. Most people will only buy English sparkling wine on offer, sub £30 and for the same money, also on offer, you can get decent 1er Cru champagne. Additionally, the UK still wines are just not up to scratch. Grapes like Bacchus and Rondo really are pretty poor and they just cant command any sort of premium, yet as has been said by Simoan, the fixed costs are high and rising. I cannot see any value in buying shares in English wine companies.
They're harvesting near me at Denbies, Dorking in Surrey currently.Got the machinery ou today.I'm not a huge fan of the one wine i've tried but that's personal and i know nothing about wine to be fair and just grabbed one of the ones in the sale.Worth a visit though to uk vineyards as they're beautiful places all seasons right next to Box Hill; and there's an attached hotel at Denbies, which is a lovely idea and perhaps more profitable for them as the vineyard is big, but i doubt big enough or well known enough to churn out large, regular profits.
Sigmaroc (LON:SRC)
Incoming CFO acquires 92,000 shares at a little under 69p. A reasonable size purchase.
Always good to see senior management make a good size purchase rather than being gifted shares or otherwise depending on options or waiting for LTIPs.
Seems to be a requirement …
Hi rhomboid1. The print in the Renumeration Committee Report you have copied is a bit too small to read, does it relate to Sigmaroc?
Yes…bigger version
Re Sigmaroc (LON:SRC) and Board requirement to build a stake in the company they run to align Board and shareholder interests (and this applies to many other companies).
A shareholder-friendly reform would be to add by when the shareholding must be built up by - many have the target but never reach them. Typical board tenure is often only a few years so 25% of LT each year until complete seems reasonable!
An alternate methodology would be to require 2% of salary each year for the first 4 years to be used to buy shares at the market rate on a given day and be held in trust Treasury until vesting.
I would ban also ban 'free shares' at the same time ie require a cash contribution to any shares awarded to management - say 50% of market value at time of issue. No requirement of course to take this up and these could be sold after 1 year. This could be finessed to exclude start-ups with a market capitalisation under say £30Mn
These sorts of changes are financially cost free to the government and I'm sure Stockopedia readers could give a load more suggestions, all with pros and cons.
However, in totality they could help AIM upgrade and as its quality improved, attract more money and/or direct relief to genuinely new and innovative businesses.
Rachel Reeves backs down on pension tax raid
Chancellor is warned that reducing the 40% tax relief for higher earners would disproportionately hit public sector workers of relatively modest incomes.
It could, for example, lead to a nurse earning £50,000 facing an additional tax bill of up to £1,000 a year. One senior government figure said it would be “madness” to inflict large tax rises on public sector workers, having just given them a pay rise.
https://archive.ph/bv6Sw
The reduction of the max tax free cash of £268k still on the cards, hence the rush to withdraw currently before 30th Oct.
This seems very obvious from the start the 40% tax rate isn’t that high. The gov can’t surely imagine that people in the public sector won’t be impacted. If they didn’t realise this from the outset then I’m deeply worried about their understanding of the rest of the economy which is significantly more complex. I also don’t really see how the economy would benefit short term from reducing the tax free cap. If anything it will hold back spending (people not withdrawing and spending it). Plus they’re changing the rules when people are about to retire which could be very damaging/risky. There will also be a lag from announcement to putting it into law so the mad rush will start post announcement wouldn’t it? Anyway Reeves better know what she is doing I’m increasingly sensing a Truss catastrophe!
The mad rush to sell is happening now. The cap on max tax free pension amount would have to commence on Budget day otherwise there would be a big sell off. I understand the Chancellor can announce the change to take immediate effect and then get it through parliament.
Personally think unlikely to happen tax free cash is already capped at something like £268k, yes they could reduce it but everytime they have in the past they have put protection certificates in place so those affected get a period of time to apply for one so that they still fall under the old rules.
I thought the whole point of giving wage rises was to take it back in taxes.
If there are significant changes to pensions or pension tax relief, that affect imminent retirees, it will have to be phased in over many years. People plan ahead for decades to plan retirement so changing the rules (such as lump sum tax free) would be grossly unfair with no notice.
Im not saying this government worry about fairness but changing the rules for imminent retirees with no notice would be immoral.
SRT Marine Systems (LON:SRT) I hold
As a long time suffering shareholder, who has heard all the Jam tomorrow comments, today's news fills me with pleasure. The SRT team have created a class leading set of products which are clearly superior to anything major defence companies can offer, whether that is on cost but also because it gives the customer ownership of their own data. The absence of outside interference is hugely important to sensitive countries and SRT knows this. It also knows that taking time to earn the trust of a customer is far more important than making a quick buck.
Once a customer is signed up, there will be many more, additions and upgrades plus the holy grail of recurring revenues.
I am a cynic, particularly around SRT Marine Systems (LON:SRT) , and my hat has not yet been thrown in the air as I read in the announcement “The award is subject only to completion of the formal contract and associated performance bond which are now underway and expected to be completed prior to the end of next month, with implementation commencing immediately thereafter.” It would be a cruel disappointment for things to be delayed from here, but when it comes to disappointment this company has form.
Cavendish Financial (LON:CAV) - Profitable 1st half. Decent cash pile.
"We have a solid pipeline of both public and private transactions in train including a number of potential IPOs and ongoing public M&A activity. We have increased our share in the public markets in terms of the number of AIM clients (rank 1st) and by adding clients on the Official List to meet our ambition of increasing the average market capitalisation of our client base."
https://newsfile.refinitiv.com...
My morning smallcap tweet: I've been to the mountaintop and I've seen the promised jam.
SRT Marine Systems (LON:SRT) FD Technologies (LON:FDP) Futura Medical (LON:FUM) Cavendish Financial (LON:CAV) ValiRx (LON:VAL) Hellenic Dynamics (LON:HELD), Beeks Financial Cloud (LON:BKS)
◄SRT Marine Systems (SRT)► on $213m order with 2 yr delivery and 10yr support 'subject only to completion of the formal contract and associated performance bond which are now underway and expected to be completed prior to the end of next month'. [SP=36 Cap=80m]
◄FD Technologies (FDP)► sells First Derivative Business for for an EV of £230m. £205m cash expected. Co will focus on KX. Trading in line. [SP=1612 Cap=455m]
◄Futura Medical (FUM)► milestone payment of $5m from Haleon. [SP=33.75 Cap=102m]
◄Cavendish Financial (CAV)► H1-Sep 'profitable' with rev up 41%. Vague outlook. [SP=9.5 Cap=38m]
◄ValiRx (VAL)► co-marketing agreement to provide Inaphaea's high throughput drug screening services and Patient Derived Cells to Italy's BioRep's network of clients. [SP=1.34 Cap=2m]
◄Hellenic Dynamics (HELD)► receipt of the €1m loan has been further delayed due to procedural matters pertaining to the lender. [SP=0.99 Cap=1m]
In line: BKS
Would someone be kind enough to reveal Paul’s mystery share for last week? My wife chose the French Revolution over Paul when yesterday’s long journey called for a podcast.
Hi BnB,
I didn't do a mystery share for the weekend just gone.
Regards, Paul.
The mystery share is a mystery………. ;-D
The mystery of the mystery share is a mystery.
Brilliant comments David & Camtab & many thanks. Provided me with a welcome chuckle.
Hi BnB,
I didn't do a mystery share for the weekend just gone.
Thanks Paul. There is one you covered that I’m buying. I expect to complete the first tranche purchase before the week is out and will add to the UK edition of the BnB Fund when I publish that to universal indifference given everyone knows the UK quality names. Expect few surprises!
My wife chose the French Revolution over Paul when yesterday’s long journey called for a podcast.
Has no one taken the hint? Off with her head!!
Oh……..I thought she was offering cake ;)
At last, a company intending to float ...https://appliednutrition.uk/
https://www.londonstockexchang...
Looks a high quality float with FY23 financials showing a c£18m PBT on £61m turnover. No debt. £28m clean net assets. Sports nutrition. Growing strongly. One to look at when the prospectus lands.
To add to the above, the COO is called Steven Granite - a cracking bit of nominative determinism!
Indeed
Zoe Hamburger is McDonald's uk chief restaurant officer which also tickled me
While a new listing is to be welcomed, looking at the financials you extracted, does it look a bit small to be listing on the main market rather than AIM ?
fyi https://www.morningstar.co.uk/... topvest
SRT Marine Systems (LON:SRT) well these guys have had some false starts but a $200m+ contract is enormous!!
Assuming the other one waiting on the inter-govt loan also comes through then this appears as though it may be the step change SRT Marine Systems (LON:SRT) have long promised. Let’s see.
SRT Marine Systems (LON:SRT) - "these guys have had some false starts" is probably the best understatement I've heard in a long time! 20+ years I have been watching this company promise and then fail to deliver. Maybe, just maybe, it is all about to come good but I wouldn't bank on it! Obviously the headline numbers in these contracts always look compelling but firstly remember that they are spread across TWELVE years so $18m a year is not quite as exciting as it first sounds. Next, we have absolutely no idea what kind of margins to expect on this business nor what the execution risks might be. Finally, what about the working capital implications? I hope everyone is ready for the next share placing.
I have to agree on the placing, they have enough cash until April 2025. Unless these contracts come with advance and milestone payments they will have to raise again, which I would expect them to do on the back on the other $200m contracts near signing. If the SP stays around 50p / £108m they could raise at a premium.
Then the fireworks may start (of course there's always a (large) element of execution risk
Has the jam finally started to arrive for SRT Marine Systems (LON:SRT) (I hold) where today's news https://www.investegate.co.uk/... would seem to cement its world-leading position in the provision of Marine Domain Awareness systems (MDA).
Congratulations to Simon Tucker and his team with having had the vision and persisted for so many years to deliver.
Rachel Reeves has been warned that tapping record deposits in Isa accounts by curbing tax reliefs risks suppressing much-needed investment.
Analysis of data published by the Bank of England showed that savers hold £375 billion in individual savings accounts, the highest level since the product was launched in 1999.
In the past year alone Isa deposits have climbed 17 per cent, or £54 billion, from £321 billion, with monthly inflows reaching a record of £11.7 billion in April partly due to the tax year deadline falling in the month.
https://archive.ph/UXmSZ#selec...
That’s great but how much of that is in cash ISA which is not really an investment. The government needs to encourage real investment. Will they impose a limit on cash ISA holdings?
Cash ISA contributions are still helping people save for the future, I think a limit would be unfair. Just IMO though.
I would imagine the cost of tax lost to Govt on cash ISA's would have been relatively pitiful over the last few years
I can imagine a threshold being introduced for Higher Income Earners on Stock based ISA's, just .....because!
Beeks Financial Cloud (LON:BKS) ”Material growth in sales pipeline for Exchange Cloud, with several major international exchanges entering the final stages of contracting, and others at earlier points in the sales funnel”
Nothing signed yet. But I like the tone and the breadth of possible new wins.
Also massive jump in Broker forecast from 260 to 335 cannacord.
Also massive jump in Broker forecast from 260 to 335 cannacord
I don’t read too much into these, more likely it’s just rebasing 20% growth after recent price gains. In July CG implied an upgrade was already due but would be postponed until full results today.
Yes - and the sensitivity analysis for Beeks Financial Cloud (LON:BKS) which shows a jump of 20% eps for every £5m revenue.
So on the basis of Nasdaq to come EPS could happily jump to 15p+ next year or so. These types of business trade with a much higher multiple as the revenue is long term sticky, so looks very interesting. Don’t think I will be selling any!!
Don’t think I will be selling any!!
No indeed. I’m hoping for a poor reaction in order to buy more. Can’t see it though
Beeks Financial Cloud (LON:BKS) Just had a look at the figures, there are £2,326k of share based payments excluded from underlying profit, which is material against reported underlying PBT of £3,903k. Personally I have less problem than many here re large rewards for excellent performance, but I like to see the charge left in the figures, it shows a recognition that it is a real cost.
Beeks Financial Cloud (LON:BKS)
Add to that the capitalised costs and there is no FCF generated here.
Crazy awards but then again they do love to pocket every year a couple of millions.
All the best
I'm looking forward to Paul's analysis of Beeks' finals and hope he can shed some light on something I find confusing.
According to Stocko, the eps estimate for YE 6/24 was edged up to 5.3p after the July TU.
Today's results report underlying diluted eps of 6.4p but basic eps of 3.33p.
As martinck1 says, £2.3m “of share based payments [are] excluded from underlying profit” but if we subtract £2.3m from underlying PBT of £3.9m and divide by the number of shares (c. 66m) we get 2.4p, and that's before tax.
AAARRGGHH!
Beeks Financial Cloud (LON:BKS) Not a fan. Been listed 7 years and still bouncing around break even. Growth in sales is absorbed by growth in costs. There is little in the way of economies of scale. As martinck1 notes management take a very large chunk of profits when they are made.