Small Cap Value Report (Mon 8 April 2024) - IGP, MIRI, TGP, CBOX, BGO

Good morning from Paul & Graham!
I updated my SCVR summary spreadsheet last night, and would you believe that Graham & I have already covered 370 unique companies here in 2024 to date! Also with Grahams 2024 share ideas up a stunning 16%, and mine up a not-too-shabby 11%, we're absolutely thrashing our benchmark of FTSE AIM All Share Index (FTSE:AXX) . Who said it was all doom & gloom in UK small caps? Not here it isn't!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
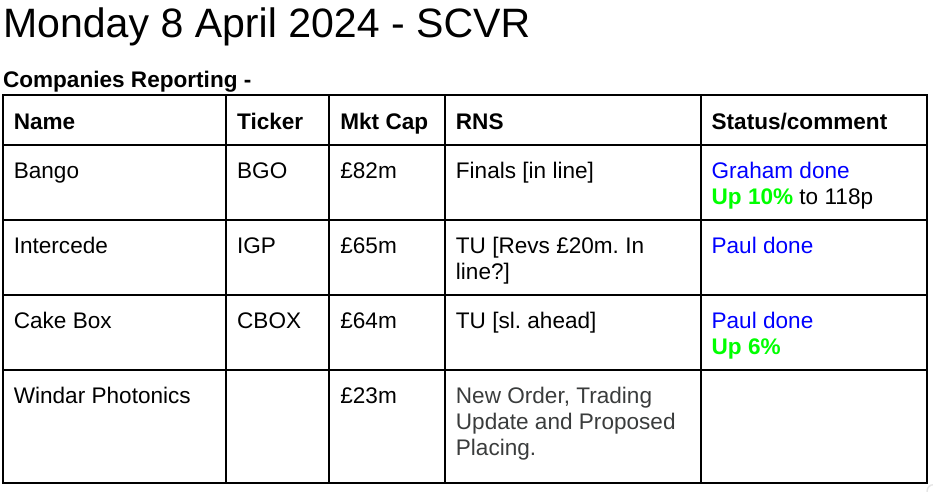
Other mid-morning movers (with news) -
Tekmar (LON:TGP) - up 14% to 10.0p (£14m) - Contract Wins - Paul - AMBER
Tekmar Group (AIM: TGP), a leading provider of products and solutions for the global offshore energy market, is pleased to announce it has recently secured a number of contract awards, with a cumulative value of approximately £6 million… These contract awards support order intake of approximately £23 million in the financial year to date.
Paul’s view - interesting company, but a very erratic track record. No forecasts available, so I can’t assess it properly. Note overdue receivables, and £18m CLN facility.
Mirriad Advertising (LON:MIRI) - up 29% to 2.25p (£11m) - Partnership with TripleLift - the market seems to like this.
Dismal historical performance with large accumulated multiyear losses. Only achieved £1.8m revenues in 2023. Cash of £6.1m remaining at Dec 2023, so the big question is can it achieve a commercial breakthrough before running out of cash again? The company suggests tantalising potential. I’ll watch from the sidelines I think, as it looks high risk at this stage.
Summaries of main sections
Intercede (LON:IGP) (Paul holds) - 111p (pre-market) £65m - Trading Update - Paul - GREEN
This year end trading update seems to be implying results in line with (increased) expectations - so why not just say so? Superb growth, helped by a large one-off contract win in FY 3/2024. Year end cash has risen greatly, to about a quarter of the market cap, helped by up-front payments by customers. Let's hope the growth continues.
Cake Box Holdings (LON:CBOX) - up 6% to 171p (£68m) - Full Year Trading Update - Paul - GREEN
FY 3/2024 turned out slightly ahead (c.3%) of expectations. With a generous dividend yield, continued roll-out of stores through franchisees, and a sound balance sheet, I remain positive on this share (despite the historical problems, which now seem resolved).
Bango (LON:BGO) - up 14% to 122.25p (£94m / $119m) - Final Results - Graham - AMBER
These results are below original expectations, as flagged by the company in January’s profit warning. The 2024 outlook is reiterated with the promise of good top-line growth and continued operational progress. Financials now need to catch up with the narrative.
Paul’s Section:
Intercede (LON:IGP) (Paul holds)
111p (pre-market) £65m - Trading Update - Paul - GREEN
Intercede, the leading cybersecurity software company specialising in digital identities, today announces the following trading update for the financial year ended 31 March 2024 ("FY24").
We get a rather strangely worded update today from one of my favourite shares (I hold), that leaves us scratching our heads over whether this is in line with expectations, or above? Confusion is best avoided at this time of day, wherever possible.
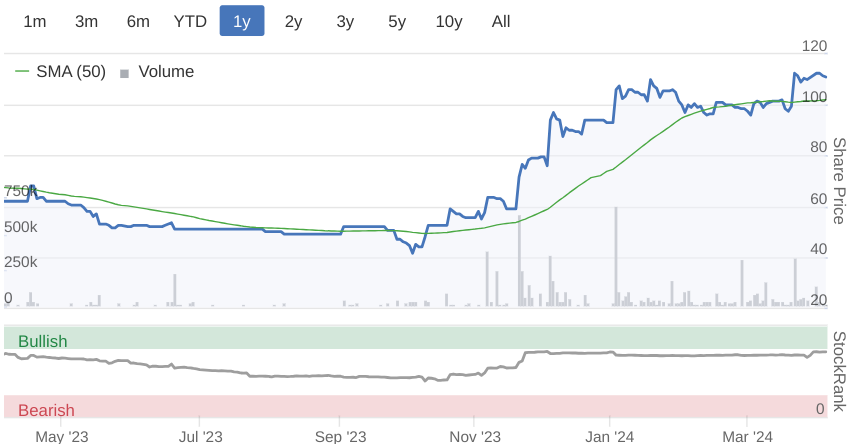
There have been a series of positive updates from IGP, as it has demonstrated excellent contract wins over the last c.six months, reflected in a doubling of the share price -
Today it says -
FY 3/2024 revenues c.£20m (Cavendish says this is in line with its latest forecast), and up a highly impressive 66% on the previous year.
On profit it says, rather bizarrely -
The combination of higher revenues and the high operational gearing present in the business is expected to result in improved profitability.
Well yes, I think we’d worked out that profit is going to improve when revenue rises 67%! Why not just tell us profit is going to be in line with expectations? Dodging that makes me wonder if something might have gone wrong?
Cavendish doesn’t seem to have changed its EPS forecast today, which is 7.7p, so it’s probably OK. Remember that contains a one-off large contract win, so we need to use the FY 3/2024 figures with caution.
Cash has come in ahead of Cavendish’s forecast - and this latest figure is about a quarter of the market cap, although some of it will be customers making up-front payments before the services have been delivered -
As at 31 March 2024, gross cash balances totalled £17.2m (2023: £8.3m). The Group has no debt.
Paul’s opinion - I’m hoping that the FY 3/2025 forecasts are set cautiously, as a step back from 7.7p to 3.7p (as currently forecast) would obviously leave little if any scope for the share price to continue rising from its current 111p.
My hope is that IGP could now be establishing a pattern of new contract wins (through resellers), hence rising earnings and a stronger share price. Time will tell if that’s right or not.
I think it’s better if companies stick to a standard format for trading updates, just stating if they’re in line, behind, or ahead of market expectations. Messing about with that format, as we’ve seen today, introduces confusion and probably unnecessary worry.
Cake Box Holdings (LON:CBOX)
Up 6% to 171p (£68m) - Full Year Trading Update - Paul - GREEN
Cake Box Holdings plc, UK's largest retailer of fresh cream celebration cakes, is pleased to provide a trading update for the 12-month period ended 31 March 2024.
Strong growth across the business resulting in full year profits slightly ahead of market expectations
Revenues up 9% to £38m (remember that it’s a franchising business, so this figure understates the revenues actually generated by the shops)
Shops delivered LFL revenue growth of +4.4%
Raw materials costs have “stabilised”
Efficiency gains.
Overall - profits slightly ahead of expectations.
Stores - 20 new sites opened by franchisees, total stores now 225. Long-term target is 400.
Net cash has improved by £1m in the year, to end at £7.3m.
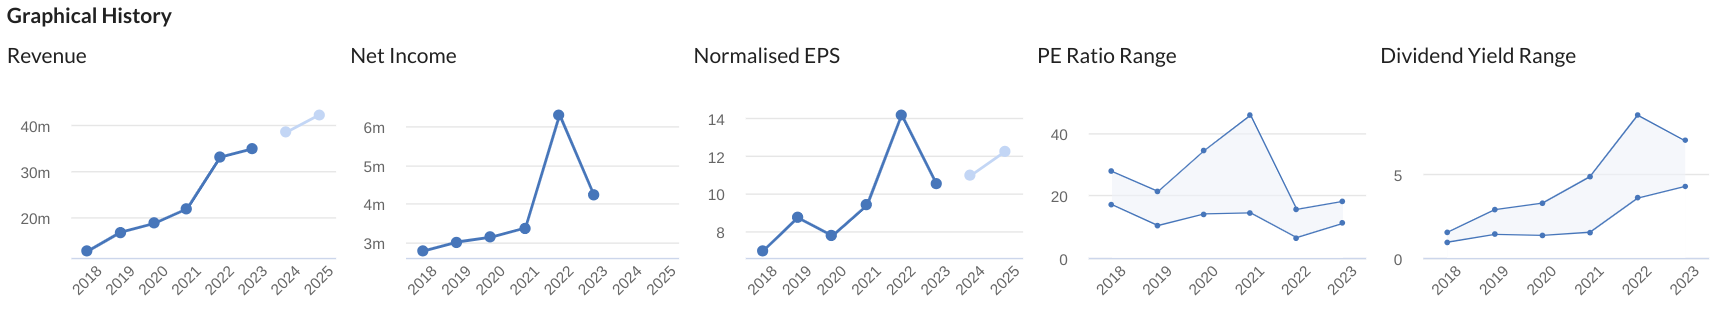
Broker forecasts - many thanks to Shore Capital for updating us today. It slightly raises forecast profit by c.3%, for 11.3p, giving a PER of 15.1x - that looks a fair price to me.
Note that a particularly good thing about the franchise model, is CBOX can expand its store estate whilst paying out almost all earnings as divis. So shareholders enjoy a dividend yield of c.5.2%. That should grow over time, as the store roll-out continues.
Paul’s opinion - CBOX has had problems in the past, but I think it’s now earned back my trust. On a PER basis it doesn’t look particularly cheap any more, but the generous dividend yield does remain attractive.
Also I should note that the market will now be valuing it on FY 3/2025 forecast of 12.1p, so the PER drops to 14.1x, and it also has a bit of net cash.
For a successful roll-out, with an attractive business model, which could also enjoy improved trading from a consumer recovery this year, I’ve talked myself into staying GREEN.
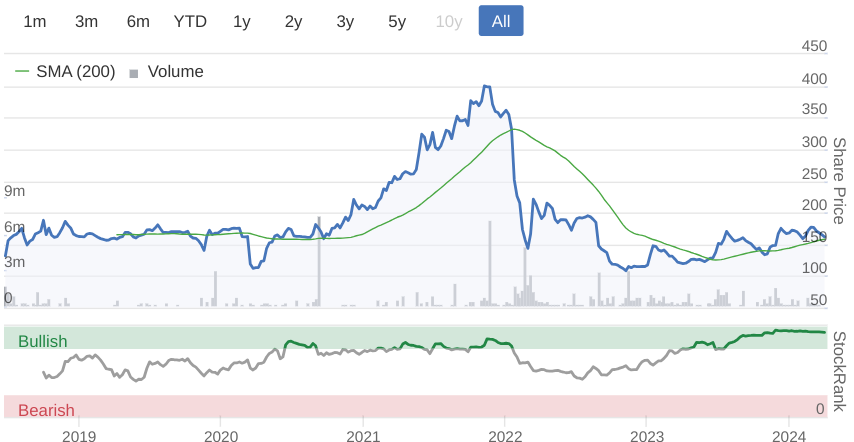
Shares are only at a similar price to 5-years ago, despite good growth. Although EPS hasn't increased that much, despite many more stores being opened.
Graham’s Section:
Bango (LON:BGO)
Up 14% to 122.25p (£94m / $119m) - Final Results - Graham - AMBER
We already covered the full-year update from Bango in January that missed expectations and saw a 30% fall in the share price.
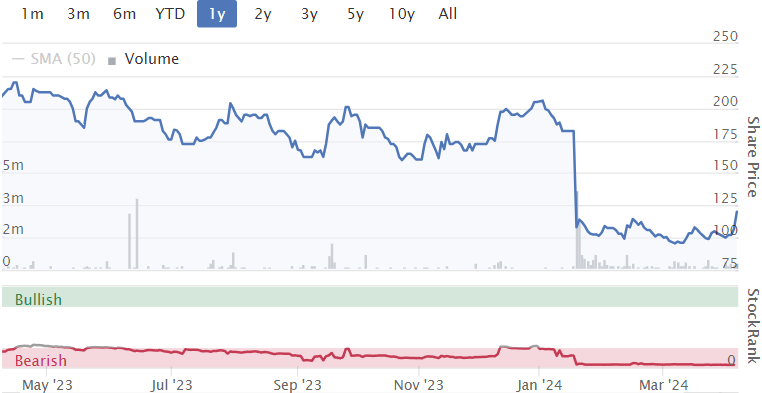
Today we get confirmation of full-year numbers, showing strong growth as expected despite not hitting original forecasts:
Revenue +62% to $46.1m
ARR +77% to $8.8m
Adj. EBITDA +29% to $6.4m
Pre-tax loss c. $9m (last year c. $2m).
The company moves into a net debt position of c. $4m.
As we discussed last time, the most important product from Bango is the “Digital Vending Machine”, a single place where consumers can manage their content subscriptions.
The DVM product is sold to and used by telecoms companies, and had 93 content providers at the end of 2023 - mostly streaming video services such as Netflix and HBO Max.
Outlook: Bango reiterates guidance for 2024.
Q1 revenue up 20% year-on-year.
ARR already reached $11m at the end of March 2024.
CEO comment excerpts:
Our technology is trusted by some of the largest companies in the world who rely on Bango to help them acquire and retain customers….
One major area of focus in 2023 was the ongoing integration of the acquired DOCOMO Digital business, which has materially accelerated our growth. The complexity of the integration was reflected in the low initial purchase price. The integration went well with all $21M of cost synergies realized. With the end of year integration challenges having now been identified and addressed, we have a clear pathway to deliver further operational and cost synergies in 2024…
As consumers add subscriptions in all aspects of their lives, it drives the need for a solution to manage these subscriptions and the opportunity for the Digital Vending Machine to become the standard industry platform for subscription bundling.
More information about the DOCOMO acquisition is available here; the price was only EUR €4m so it is indeed remarkable if $21m of cost synergies have flowed from that deal - it implies an enormous shift in profitability.
Some points to be aware of:
Long sales cycle - selling to telcos on large, multi-year contracts is a lengthy process.
Marketing challenge - Bango helps telcos with their marketing strategy as the Bango bundling proposition ultimately has to be sold to the end-users. A new customer user interface has been developed.
While the sales cycle can be long and a new marketing strategy is required, Bango is still “the simplest and fastest way for telcos to connect to content providers”. For example, Bango provides ready-made commercial terms for telcos to start doing business with all of the content providers immediately.
Financial health?
With the company moving into net debt, I’m curious to see how management feels about this. The Chair’s review of 2023 says:
The Board also determined that it was prudent to carefully manage the pace of investment, given current market conditions. As migrations complete and the free cash flows from the payments business rise, a priority is to use these to build cash reserves, repay any debt and invest in the rapid growth around the DVM.
Bango has one main loan (c. $8m) charging interest at 6%, and it must be repaid over two years, starting in Sep 2024. There is also an undrawn £3m RCF with Barclays.
Graham’s view
I continue to find this one interesting, although it continues to have a lot to prove.
The core product seems to be working very well, and gaining traction with major telcos, and for me that is the main source of excitement. The concept of a single platform where consumers can pick and choose their streaming services makes perfect sense to me. The percentage growth numbers here seem to demand respect.
Where am I less certain?
Firstly, the financials haven’t caught up with the story yet.
Here is the bridge between adjusted EBITDA ($6.4m) and the operating loss ($5.1m):
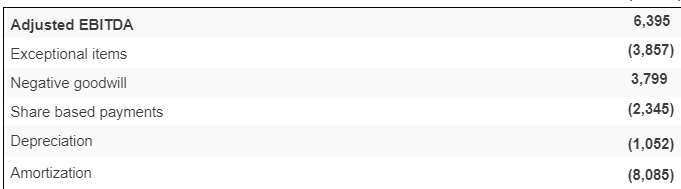
Personally, I view the share-based payments as a real cost for shareholders, as the dilution is very real.
Amortisation of $8m is also a real cost. Some people argue that it isn’t, when the only assets being amortised are those acquired during the course of M&A.
However, that argument is much more difficult to make when the company is in the process of adding new intangible assets to its own balance sheet.
Bango’s 2023 cash flow statement shows that $18m of development costs were capitalised, a remarkable figure for a company of this size.
The previous year, nearly $10m of costs were capitalised.
In other words, the company’s reported losses would be significantly higher without this accounting treatment of intangibles.
Overall, then, the financial performance in 2023 is far from good. I’m expecting a huge improvement in 2024, but it’s unfortunate that the 2023 numbers don’t give more to cheer about when it comes to profitability.
(Estimates for 2024 from Singers suggest revenue growth to $53.5m and an adj. PBT of nearly $6m.)
I’m also a little concerned about the company’s headroom.
At year-end, the company did have cash of $4m and an undrawn facility for GBP £3m.
However, its $8m loan will require a $1m principal repayment every quarter, starting later this year.
Given the amount of development spending involved, and possible exposure to swings in working capital (Bango had $22m+ of receivables and $30m+ of payables at year-end), the financial situation does not seem to be as strong as a defensive investor might wish it to be.
We can only trust that with $21m of cost synergies, and with higher payments from telcos likely to hit the company’s coffers over the next 12 months, that the company will be able to avoid any financial stress.
In conclusion: I’m intrigued by the core product at Bango and impressed by the growth achieved so far. However, I’m not ready yet to start giving it the thumbs up.
The StockRanks would be disappointed if I did:
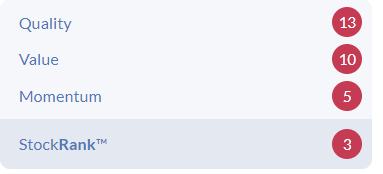
At a market cap equivalent to $119m, it’s currently trading at an ARR multiple of nearly 11x. This would be pricey, even for American investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Cornerstone FS (LON:CSFS)
ST coverage in his Alpha Report today with an initial target price at 50p.
I hold
Maybe that's why it's up 13%.Good volume today especially towards the end of the session.Wish i hadn't sold half but live and learn.
Revolution Bars (LON:RBG) Revolution Bars is close to finalising an emergency fundraising that would provide a stay of execution as it cobbles together plans that will result in the mass closure of its venues.
https://news.sky.com/story/rev...
Some SDI discussion in here today. I've long been a SDI sceptic. Looking back I’m having trouble reconciling data and statements from the FY22 report. Overall borrowing for the year is up by c.£6m on balance sheet, but financing as reported in cash-flow statement shows only a £1m increase. The CFO statement claims a net cash position of c.£1m….not born out by balance sheet that says £6m net debt. Am I being stupid? Can someone here explain?..
From cash-flow statement:
CFO report:
Are leases included in the borrowing figure? SDI (LON:SDI)
Yup. Doh! I was being stupid. In looking quickly (I've been skimming SDI (LON:SDI) ) stuff today I thought I had accounted for leases. So there is nothing wrong with reporting to be clear
Any particular reason why MCB - McBride is down around 8% today. Cant see any RNS that may have caused this
McBride (LON:MCB) did go up about 15% on Thursday and Friday, last week, guess some profit taking. It does not take much selling to move the price down, in this market.
Teleios sales have put the mockers on McBride (LON:MCB) . The same thing happened with Card. As soon as the share price got to a decent amount, they offloaded some shares. People can see the same process happening now with McBride
Telios need to be careful or people will start avoiding shares they are heavily invested in. I personally would avoid anything they are in deep on at the moment.
Frontier Developments (LON:FDEV) is having a nice 'recovery' run over the last week since it's last rns update.Here's hoping it holds as i'm finally just back in profit after 'averaging down' a few months ago.I always felt it was still pretty shorted like Synthomer (LON:SYNT, but too a lesser degree and under the reporting level..Anyway someone's buying.. perhaps a fund or 2..?Could more money be coming into the UK market lately,. especially for potentially oversold shares\future potential of previously profitable companies\fallen stars?Here's hoping it doesn't sell off again.
Could be forming a bowl, as well.
https://www.hl.co.uk/shares/st...
Paul congratulations to both you and Paul on your performance so far this year. It continues to confirm in my mind that you are both excellent stock pickers. I remember some years ago now an attempt to categorize fund managers under Information Ratios. The idea was that you could divide active risk by active return and identify the skill of the manager over time. Theoretically it was an excellent idea. Unfortunately to capture skill you need more data inputs than the career duration of most fund managers. That said I would imagine yours and Graham's information ratio would be quite high!!
My "criticism" (which it isn't really) is your benchmark. I don't think the FTSE AIM should be your benchmark. I think the small cap or even mid cap indices are more suited to what you are trying to do.
Hi Camtab,
I don't think the FTSE AIM should be your benchmark. I think the small cap or even mid cap indices are more suited to what you are trying to do.
We only use AIM as the benchmark because that's numerically where most of the companies we report on are actually listed.
Or we could make a hybrid index weighted say 70% AIM, 25% SMXX and 5% MCX? I included a field in our 2024 share picks spreadsheet for each share, stating which index it is listed on, so it would be fairly easy to calculate the weightings.
Regards, Paul.
Paul, on Intercede (LON:IGP) I suspect that the reason for the strangely worded TU is that they are need to discuss with the auditors how much of their sales should be booked in FY25 rather than FY24 and that the TU should therefore be read as FY24 is "in line with or better than" revenue and EPS forecasts.
This is because: (i) Cavendish has maintained its revenue and EPS forecasts; (ii) the net bank cash figure at year end of £17.2m is £2.2m more than Cavendish's (previously raised) forecast; whilst this may be a larger customer paying an invoice early, it more probably represents up front payments for more orders (and therefore raises the question of whether the revenue should be booked in FY25 rather than FY24); and (iii) the company is not being valued on its FY24 earnings - it has very clearly guided that the forecast £20m revenue / 7.7p EPS are a consequence of the unusually larger order and the market has discounted these figures - so there's no real benefit to IGP in reporting more revenue and higher EPS in FY24 unless the accounting rules require, since there will be no / little valuation uplift and the decline (if there is one - which time will tell) into FY25 will be more marked.
IGP have consistently reported deferred revenue and I would be surprised if it was any different this time .
Of more interest is the trading statement on 22 march
The Group is pleased to announce an order for a new licence test environment for an existing US Federal Agency, which, combined with anticipated additional conversion of our existing pipeline, means that the Group now expects financial performance to be ahead of market expectations for FY24 and creates further contracted revenue backlog for FY25. With this momentum coinciding with the launch of our new product release, MyID MFA v5, the Group is in a robust position to execute on its forthcoming plans for FY25 and beyond.
It should not be forgotten that Intercede are looking for bolt on acquisitions to provide better return than the cash pile.
Agreed. I’m sure Intercede (LON:IGP) are waiting on their auditors to try and defer as much profit as possible into the future.
I note the Department of Defence has now appeared on their website as a customer. No prizes for guessing who the $8mm contract award was from. That means they now secure most of the US Government (DoD, State, Homeland Security, TSA, SSA, FAA, White House).
Hi Paul, just a comment on something you said on your podcast about Renew Holdings (LON:RNWH) and how can you tell / judge the quality of management and / or a business which could become a multi bagger.
For me there is a clear way to judge the quality of a companies management just by looking at the numbers and its a metric which is much more reliable a judge of management quality than listening to a webinar, speaking to management directly or reading a report. The key metric to look for is ROCE (return on capital employed) a business which can consistently show over a long operating period (say at least 5-10 years) the ability to earn a high return on capital employed in the business (i would say at least 20% +) is the single best metric to assess the quality for the management in a business.
Equally a business which can then deploy incremental capital in the business and then continue to return high returns on that incremental capital then become compounding machines and i would argue are the types of businesses which can become 25+ baggers.
I personally don't know much about Renew holdings, but looking at their results over a period of time, it looks like the sort of business which fits this bill. it delivered high levels of ROCE and through acquisitions was able to deploy incremental capital at high levels of return and compounded over time.
But my main point was ROCE is the key metric i think which we should use to judge the quality of a companies management. As it clearly shows their ability to deliver a high return on the capital employed in the business.
Obviously outside of that you need to have an understanding of the industry, competetive forces etc, moat etc..
And how do you mitigate the risk of an unknowbale future? you pay a conservative price for those businesses, based on the previous years earnings (not next years earnings).
And how do you mitigate the risk of an unknowbale future? you pay a conservative price for those businesses, based on the previous years earnings (not next years earnings).
With you up to this point. But, if management and the business they run are that good, you won't get a conservative trailing multiple - absent major market dislocations. Better to be sure that the quality is there, pay up, and come back in five years to a 50-100% gain. This won't shoot the lights out, instead it'll keep your jewels twinkling nicely - and that's what quality growth investing is about.
Flowtech Fluidpower (LON:FLO)
I hold.
I watched the investor meet company presentation of the recent prelims by the newish CEO Mike England and CFO, Russell Cash and admit to being impressed with the changes, both actioned and proposed. As I have mentioned in previous posts, despite the at times, somewhat flowery management speak, Mike England has certainly shaken the company up. Early days but the new strategy seems to be slowly taking effect
Chris Mills and his colleagues Richard Staveley and Stuart Widdowson hold some 30% of the company and they certainly won't let it go on the cheap. The share price becalmed for sometime at around 80p, despite the profit warning contained in the trading update of 30th January appears to gaining some traction, although it is early days. I remain underwater with a buy price of 109p but shall sit and watch and depending on share price momentum and availabilty of funds would not be adverse to adding, on the view that the long awaited turnaround is starting to happen
Hi Jonno, Flowtech Fluidpower (LON:FLO) I watched it too and thought the CEO was super impressive. He's been there a year now and it looks likes his operational improvements are under way, integration of all previous acquisitions, margin improvement, debt reduction etc etc. Looks very good on the chart too, feeling very positive but i would say that having just bought in the last couple of weeks!
Hi Burnt Onions,
Flowtech Fluidpower (LON:FLO) I very much agree but as you know I am biased. I managed to buy a few for my daughter's ISA at 80p and subject to funds, which is always a limiting feature would like to add a few more.
All the best
Cockney Rebels “bowl” strategy / ECOR resources
Been following this for a while and he seems to get good results .
Something he really looks for is strong director buying / skin in the game at the base of the bowl .
I generally avoid resource stocks as seens that external influences control your destiny and you need a big brain to understand these external factors .
However as I have sone excess cash I’ve put a small % aside to test the bowl theory and have widened my reach to include anything
Having read Edmunds copper article stumbled onto ECOR resources thanks to sone good reader comments from illiswilgig and oldschool05 so had a decent look and lo and behold it seems to have formed a nice bowl .
There’s nothing like learning a lesson or testing a theory than jumping in head first and getting it totally wrong so that’s my first “bowl trade”
Bizarrely I’m up 2% in 60 minutes so that’s a good start though I may have caused that .
Could be a bowl, could also be an upwards movement within a continuing downtrend. I think Cockney Rebel doesn't normally buy until it looks like a stock has pretty much bottomed. Maybe you have found the bottom with Yorkshire luck. Time will tell.
I’ll check my cupboard
I though it looked like a bowl
Hi planetX.
I'm with Rog. I don't think this is a bowl (yet). If you want to see a bowl, look at Liontrust Asset Management (LON:LIO)
Now that's a bowl (I hold).
Cheers
Chris
Lionttrust - definitely on the 3 year chart it’s not a bowl that’s in my cupboard .
Just for clarity I also did the research on ECOR and liked the fundamentals which is basically huge discount to NAV , looks oversold , limited downside and rising tide on its commodity soace .
I’ll never invest in asset manager on principle .
MPAC (LON:MPAC) and Wise (LON:WISE) on 3 year charts. Intercede (LON:IGP) also. Kier (LON:KIE) maybe the best bowl over 3 years.
hVIVO (LON:HVO) quite flat on a 3 year chart but look at it on a longer time chart. ME International (LON:MEGP) on a 6 month chart.
Eleco (LON:ELCO) maybe worth considering? Also Avon Protection (LON:AVON), Bodycote (LON:BOY) and Synthomer (LON:SYNT) ?
IG Design (LON:IGR) maybe beginning to form a bowl. Cake Box Holdings (LON:CBOX) as well.
On Beach group (LON:OTB) looking "Bowlyish" if that's even a word
Also abrdn Equity Income Trust (LON:AEI) , which is currently yielding 7.9%
Serica Energy (LON:SQZ.) maybe one for your "bowl" strategy. I hold.
If you're interested in Ecora Resources (LON:ECOR) it's worth watching the Investor Meet Company interview from after the FY results a week or two ago. Not sure about the bowl but the CEO purchase in February looks well timed.
I think Atalaya Mining (LON:ATYM) is better personally if you’re keen on copper but that’s just my view.
Bowl theory - CR finds a bowl but then wants to see Director buying and ideally a change of board with new mgmt he can check out track record/history. So I don’t think he just buys the bowl - he is looking for certain characteristics that he associates with a likely recovery.
There has been some director buying Ecora Resources (LON:ECOR)
I’ll add my own magic dust and remove sone of CR
Director buying yes
Change of board not being essay for me (you often get Hope increase on change of board but no board can effect change quickly so that falls away so I don’t get that )
Sector strength / rising tide - I’m looking for change in sector strength
NAV support - looking for NAV support that limits downside , ask myself “would I buy this business” even if to strip and chop .
It’s by no means a formulated plan so all this may well change depending on which way the wind blow .
My Monthly "Bowls" Substack for any that are interested - https://briefedup.substack.com...
SDI (LON:SDI) caught a bid, along with the rest of the life science industry, when evidence came through in the last US earnings season of a potential end to the de-stocking that has dogged the sector post-Covid. But, in contrast to other names, who have shown continued strength of late, the SP has fallen back to multi year lows, beyond the low reached on the shock departure of the CEO. I think that current price movements fairly accurately reflect the uncertainty around unproven leadership, and the potential for the company’s previously successful buy and build program to be derailed by the absence of its architect. I also note that the company has been more successful with the “buy” portion of that strategy than the “build”. On the other hand, we have a PER in single figures in a sector where multiples 3x as high are not unusual. 50p looks a good entry on the chart but it may not transpire if life science names confirm the industry inflexion during the forthcoming earnings season.
What do others think?
BnB SDI (LON:SDI) does look interesting but not seeing the catalyst for change in direction of sp yet. Some revenue growth but lower margins post that COVID boost. New CEO sounds a good choice but needs to show his mettle. Green shoots with new order for Atik division?
Have traded these successfully previously but they were then seen as the new mini Judges Scientific (LON:JDG) . Not sure what you'd compare with them now. Limbo continues. Perhaps need to see a spike in volume per Wolf's indicator of change. Or wait for the Cockney 'bowl' to firm? Definitely on the watch list. Thanks for flagging.
SDI
I just took a look and it sucks .
Chart is terrible .
But what’s sucks the most and is offensive and morally repugnant is what you find when you look at director buys and sells going back 2 years .
Moriarty himself aka Ken Ford the chairman (I’d rename chiefthief) sold consistently at the top pocketing circa 2.2 million quid .
And in the past year despite the bombed out share price and “recovery” situation that he as chairman will be overseeing , he is so confident in this recovery he has bought , wait for it . Drum roll ……
Dec. 23 - 10,000 at 87p
Nov 23 - 10.000 at 121
July 19 - 50,000 at 55
Feb 19 - 100,000 at 36
His sells were
oct 22 - 160,000 at 160
Jan 22 - 200,000 at 195 (options granted at 1p)
sept 21 - 250,000 at 188 (options granted 28p)
match 21 - 500,000 at 221
Dec 19 - 250,000 at 78
So here you have a senior player on the board putting over 2 million quid in his back yet has some little confidence in the company and his team that he only invests 1% of his (well earned / I’ll gotten gains depending on your viewpoint) in a company valued at 25% of what it was .
The options appear to be
- run for the hills
- wait to see at what point if any good old Ken starts making significant director buys which would be at least in 100k chunks
Though he probably doesn’t need to does he as I suspect he has several million options in his bag given to him by the “indeiebdabtjy” renumeration committee which he of course hired .
I just don’t think this is a company being run for its investors .
Thanks for your comments, PlanetX. I do agree with what you say and I took particular umbrage at Creedon's final disposal. Or rather his mendacious explanation for cashing in. The other side of the coin, of course, is that management helped me treble my money - assisted by Covid demand - and Creedon's sale alerted me take excellent profits.
And SDI (LON:SDI) will go on another run if management are to be able to properly cash in again on their latest options giveaway. The signs of an upwards inflexion in demand are already there in reports from numerous comparators. Now management has to execute, hoping that the group's constituent companies still have relevance in the post-Covid world.
BnB
I understand that .
But why bother if management are there way inclined to use the company as a cash cow for their personal enrichment . I could never invest even if thought it was going to 10 bag .
One thing for certain if the company goes south those type of directors will be on their bike to the next pay check .
I’d just look for something else and sleep better knowing you haven’t broken the golden rule we had at px .
One concern with SDI is that the company appears to be in denial. There does not seem to be any acknowledgement that it has failed to grow some of its companies and that this has resulted in a circa 75% shares price fall since the start of 2023 (it is not all due to a Covid hangover). There are no signs that the company has learnt any lessons and the internal promotion of the COO to CEO probably means that no changes will be made, indeed he has already indicated that it will be business as usual. This is a shame as my guess is that the business could regain its former glory if the necessary corrective actions were taken.
Morning Paul, just wanted to say thanks to you and Graham for the continued effort you put in on these write ups. Really enjoying your weekly podcast as well which just adds that extra little bit of context and personality.
Thanks unbelievablejeff,
Positive feedback much appreciated! :-)
Best wishes, Paul.
Schroeders increased its holding in ECO Animal Health (LON:EAH) .
My morning smallcap tweet: If you keep napping you'll get a knee-capping
Intercede (LON:IGP) Cake Box Holdings (LON:CBOX) Windar Photonics (LON:WPHO) Batm Advanced Communications (LON:BVC) Mirriad Advertising (LON:MIRI) Aurrigo International (LON:AURR) Narf Industries (LON:NARF) Aptamer (LON:APTA), Bango (LON:BGO)
◄Intercede (IGP)► guides FY-Mar rev c.£20m up 66% and 'improved profitability'. In line? [SP=109.04 Cap=65m]
◄Cake Box (CBOX)► guides FY-Mar rev up c.9% and adjusted profits slightly ahead of market expectations due to cost control and improved efficiency. [SP=161 Cap=64m]
◄Windar Photonics (WPHO)► guides FY-Dec rev c.€4.8m up over 150%. Adj EBITDA c.€0.4m. Also guides FY24 rev growth similar to FY23. £4m placing at 35p up 6%, to keep the photons on. [SP=33 Cap=23m]
◄BATM Advanced Communications (BVC)► wins 2 yr Edgility contract extension. No £££. [SP=18.19 Cap=83m]
◄Mirriad Advertising (MIRI)► agreement with TripleLift to scale in-content advertising. "TripleLift's SSP will facilitate automated selling of in-content inventory from Mirriad's growing number of supply partners into leading media buying platforms such as Google's DV360 and the Trade Desk." [SP=1.71 Cap=9m]
◄Aurrigo International (AURR)► partnership with Aviation Solutions (part of Royal Schiphol Group), to support the roll-out of Aurrigo's autonomous solutions to the global aviation sector. [SP=95 Cap=42m]
◄Narf Industries (NARF)► wins c.$500k cybersecurity contract for the US Department of Energy Program. [SP=1.25 Cap=22m]
◄Aptamer (APTA)► files patent application to protect the recently developed Optimer binder sequences for novel applications in fast moving consumer goods generated as part of its partnership with Unilever. [SP=0.62 Cap=3m]
In line: BGO
Morning all, Jim Durkin bought 4% of the company just before the trading update. Great timing from the ex Cenkos CEO, one would think maybe too good. Cavendish Financial (LON:CAV)
Cavendish Financial (LON:CAV)
The reason given for Durkin's notification was: INCREASE IN ISSUED SHARE CAPITAL
I believe that this means he did not increase/decrease his holding, but is updating the percentage of the company he owns due to the increased share count.
Thanks Laurie!
Agree