Small Cap Value Report (Mon 8 Jan 2024) - CMCX, SCE, CLBS, PLUS

Good morning from Paul & Graham! We're ready & raring to go, for a massively busy month from this point onwards with trading updates galore. We'll try to cover as much as humanly possible!
This (below) was how busy Jan 2023 looked on my spreadsheet here, which is a quick reference tool to compare with this year's imminent RNSs if you wish (hover over any cell in the spreadsheet for a summary - as you can see I'm hovering my pointer over TM17) - and please do remember that our view on shares is only on that particular day, using the facts, figures, and forecasts available at that time. These will obviously change considerably over a year, hence we subsequently change our opinions in response to later changes in the facts, figures & forecasts. So remember this is mostly reactive, rather than predictive -
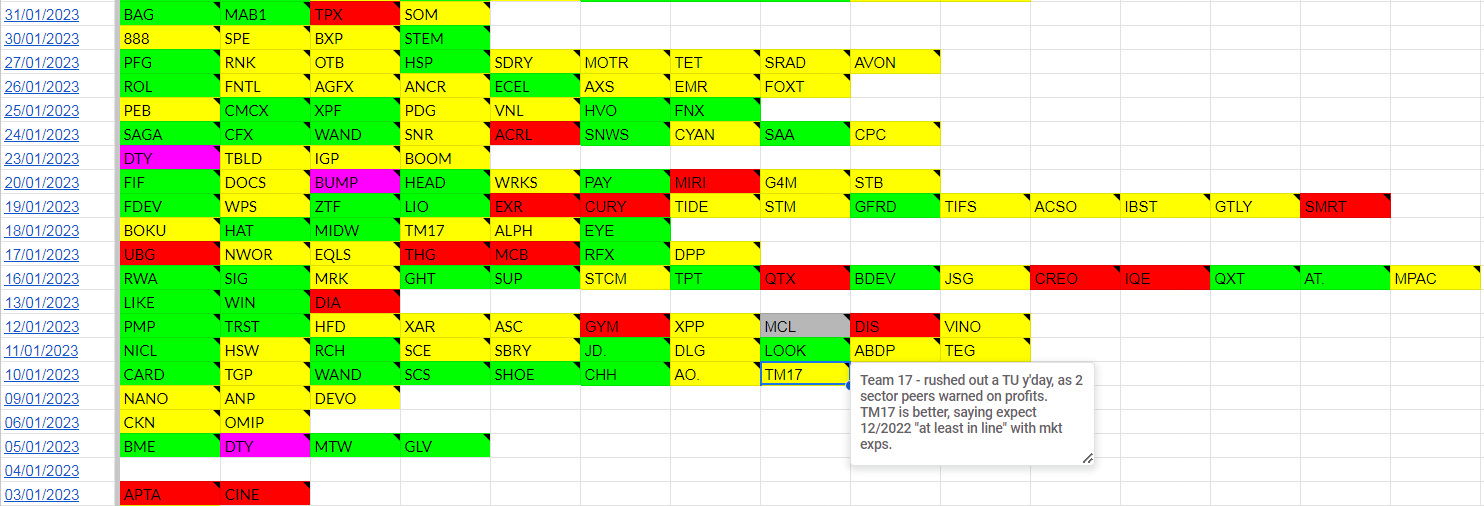
(In case you're unaware, as with any image, you can enlarge this by right-clicking your mouse, and selecting "Open link in new tab", or similar)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Live prices tracking spreadsheet for Paul & Graham's 2024 share ideas (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs) - search on any podcast provider for "Paul Scott small caps", or web link here.
Summaries
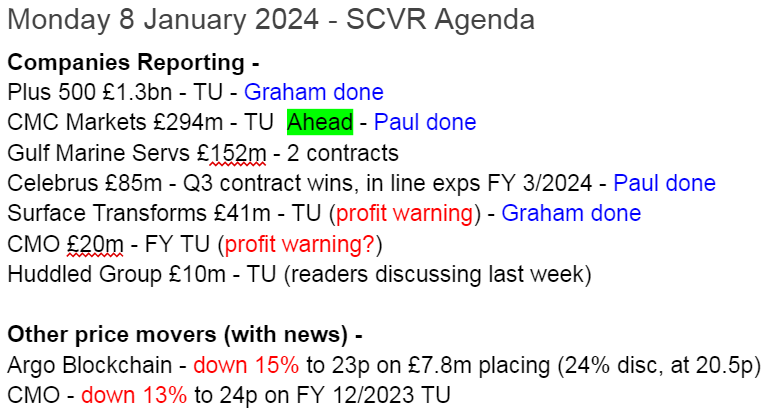
CMC Markets (LON:CMCX) - up 23% to 135p (£379m) - Trading Statement - Paul - GREEN
I rushed out a quick view below before 8am, of an ahead of expectations update. As suspected, this CFD/spread betting company's share has risen strongly in early trades today. We need more information, but it looks as if a sharp improvement in trading in Q3 (Oct-Dec) is likely to have a big operationally geared benefit to profits. Both Graham & I have this share on our top ideas for 2024, as we liked the full liquid asset backing from its bulletproof balance sheet, and the geared trading upside in for free.
Surface Transforms (LON:SCE) - down 3% to 11.16p (£39m) - Trading update (profit warning for 2023) - Graham - BLACK (profit warning), AMBER/RED
I’m giving this one a moderate thumbs down after the company fails to meet previously downgraded 2023 forecasts which were issued as recently as mid-November. It is at least funded for the short-term. I hope shareholders can avoid further dilution but would not like to bet on it.
Celebrus Technologies (LON:CLBS) - Up 10% to 236p (£94m) - Contract Update - Paul - AMBER/GREEN
Contract updates means management are confident of hitting FY 3/2024 forecasts. Looks interesting company, but it's already had a big rally of late, so less attractive value.
Plus500 (LON:PLUS) - up 4% to £17.32p (£1.38bn) - Trading Update (ahead) - Graham - GREEN
I’m taking an outright positive stance on this for the first time. The company has answered critics by buying back shares and significantly beating forecasts for 2023. Some concerns may linger but PLUS is more credible than ever before and remains attractively priced.
Paul’s Section:
CMC Markets (LON:CMCX)
Up 23% to 135p (£379m) - Trading Statement - Paul - GREEN
CMC Markets Plc ("CMC" or the "Group"), a leading global provider of online retail ("D2C") and institutional ("B2B") platform technology, today issues a trading update for FY 2024.
The current financial year is FY 3/2024, so this is a Q3 update.
It’s a financial trading (spread betting, CFD, etc) company, which isn’t obvious from the vague self-description above! 59% owned by Peter Cruddas.
At an initial look, today’s trading update looks very good -
Trading Update
The Group delivered a strong performance in the third quarter of FY24.
This was driven by an improvement in market conditions led by an increased contribution from the B2B and institutional business with the Group benefiting from the long-term investments in this area. As a result of this strong performance the Group now expects to generate FY24 net operating income of between £290-£310 million from the previously guided range of between £250-£280 million.
The next scheduled update to the market will be the FY24 pre-close update on 9 April 2024.
That’s really helpful that they include both revised, and previous guidance. All companies should do this, as it’s transparent, and saves us all time to dig out previous guidance.
Taking the mid-point of the above ranges, that’s a 13% uplift.
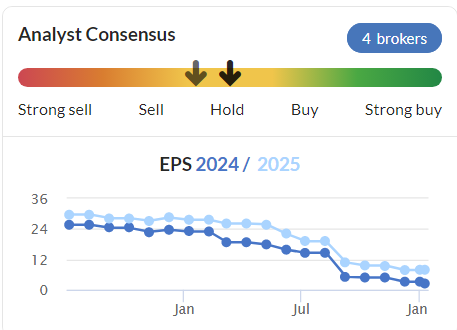
Quite a turnaround, as last time we reviewed CMCX here on 16 Nov 2023, it said trading was subdued, with a small loss in H1. Broker consensus forecasts continued declining, so I’m quite surprised to read this ahead of expectations update today. Presumably there’s now likely to be a jump up in the graph below, when it updates later this week. There aren’t any broker notes available to me on CMCX, which is a pity. Surely they can fix that?
I’m trying to work out how “net operating income” compares with profit before tax.
In H1, £122.6m net operating income turned into a £(2.0)m loss before tax! So it seems to be a revenue-type figure, not profit.
Last year, CMCX reported net operating income of £288m, and a PBT of a whopping £52m! So does today’s indication of £290-310m net operating income imply a similar level of profitability?
We’ll have to wait and see, but it seems likely to me that we might see a large increase in forecast profits after today’s update - since the business has big operational gearing - largely fixed costs, which means much higher profits when trading volumes rise.
Paul’s opinion - I need more information to be certain, but on a first look, this sounds very positive.
Both Graham and I (coincidentally, as we didn’t discuss it at all) picked CMCX for our top ideas for 2024. The reason was that valuation was completely (and more) underpinned by net working capital on the balance sheet. So any trading recovery was in for free.
I don’t think either of us expected a big trading recovery to happen immediately, so the timing at least looks lucky for us!
I’m typing this at 07:55, so it will be interesting to see how the share price reacts, I suspect a strong upward move could be about to happen.
If any readers have access to revised broker forecasts, please do share them in the comments below.
Celebrus Technologies (LON:CLBS)
Up 10% to 236p (£94m) - Contract Update - Paul - AMBER/GREEN
Celebrus Technologies plc (AIM: CLBS, "the Group", "Celebrus"), the AIM-listed data solutions provider, is pleased to announce several software contract wins made during the financial quarter to 31 December 2023. These wins demonstrate the appeal of the Celebrus platform across a range of industry sectors, as well as illustrating the deepening relationships with existing customers who recognise the importance of our new features and differentiators.
There are vague points about 4 contract wins or renewals, but I copied these snippets below because they contain a rough idea on contract size, which sound quite good -
The second win is an existing global top 10 banking customer, which has renewed its multi-million dollar annual license for a further three years, incorporating an uplift in Celebrus session volumes and increasing ARR to the Group by 19% from the original contract…
The third win is a UK bank which has been using a light, bespoke version of Celebrus that is no longer supported. The bank has signed a three-year multi-million dollar contract for the full Celebrus platform…
Outlook - overall, this sounds in line with expectations for FY 3/2024 -
…reinforce the Board's confidence in both achieving full year market expectations* and continuing to drive growth in ARR, with customers across a wide range of industry sectors…
* For the purpose of this announcement, the Group believes market consensus for FY24 to be revenue of £32.1m, and adjusted profit before tax of £5.4m.
Yes! They’ve quoted adj PBT, the figure that most of us want, not the meaningless EBITDA figures that far too many companies seem to wrongly think is the standard. Great to see that one or two companies are listening to what investors want. Why can’t companies give both EBITDA, and adj PBT at the same time? Then everyone will be happy!
Broker updates - both Cavendish and Canaccord put out notes, thank you.
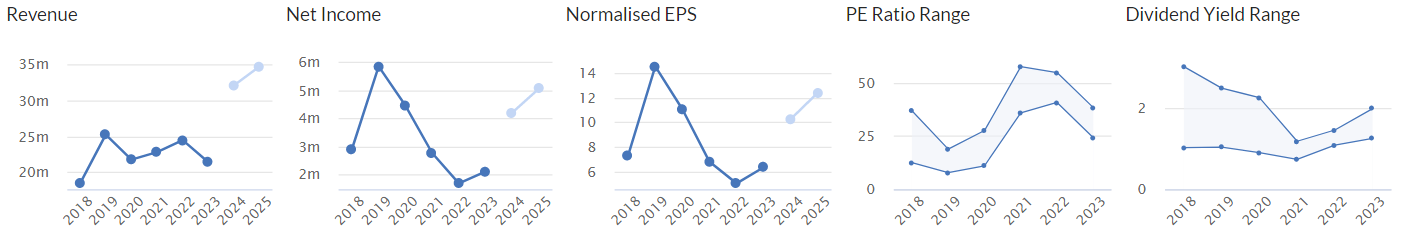
Canaccord has 10.7p adj EPS for FY 3/2024, then 13.0p for the year after.
Cavendish is somewhat lower, at 9.8p and 11.8p.
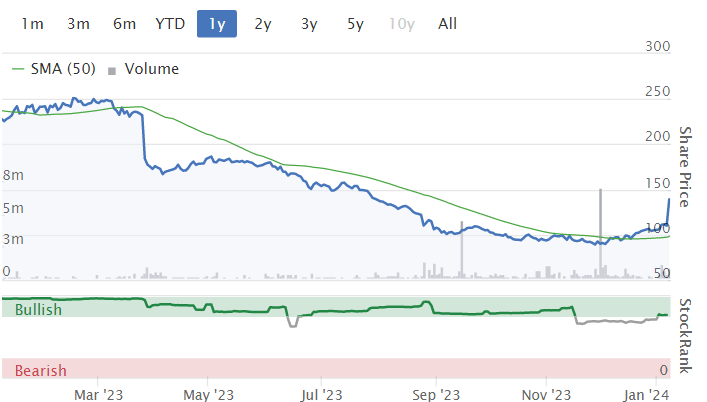
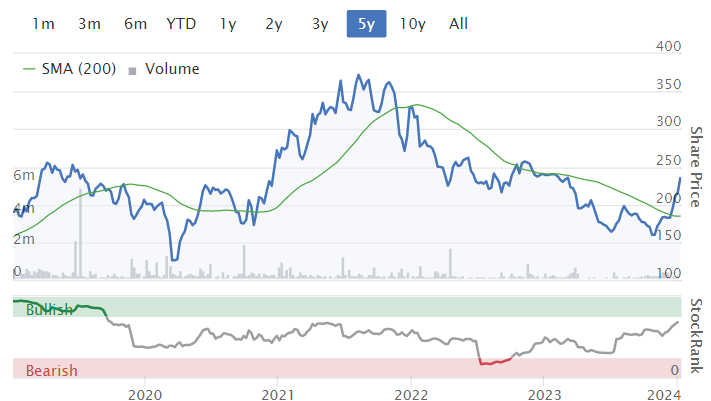
Earnings growth actual & forecast looks impressive when taken in isolation since 2020 to now, but if you look further back, the bullish forecasts are only taking it back to earnings in the 2018-2020 level. So I think we need to be a bit careful about chasing this share price too high - it’s had a very good run already - up over 50% since the lows just 2 months ago, on reassuring rather than forecast-changing news -
Paul’s opinion - well done to patient holders, I think the rally of the last 2 months looks justified - this is a decent company, well financed, and operating in a very interesting area.
There are modest divis too.
What we need to see is an acceleration of growth, I think it needs that to get a more serious re-rating. This company always looks poised for great things, but doesn’t quite seem to reach escape velocity in terms of growth or profitability. That could change, who knows? I’d want to see “significantly ahead” of expectations and broker forecast rises to get me interested again.
It could attract a takeover approach though, as companies in this sector are often popular with buyers, and they’re happy to pay a premium multiple very often.
There was a query from the last interims, where receivables were unreasonably high, so I need to see that resolved in the next balance sheet.
I’ll stick with my moderately positive view, AMBER/GREEN, despite the share price having risen a lot since my last review on 27/11/2023, so it’s not good value any more really. Still an interesting, profitable company though, with interesting potential.
Share price is back to where it was 5 years ago -
Graham’s Section:
Surface Transforms (LON:SCE)
Share price: 11.16p (-3%)
Market cap: £39m
Surface Transforms (AIM:SCE), manufacturers of carbon fibre reinforced ceramic automotive brake discs, is pleased to provide the following pre-close trading and operations update for the year to 31 December 2023 ("FY23")
This stock has been a difficult hold:
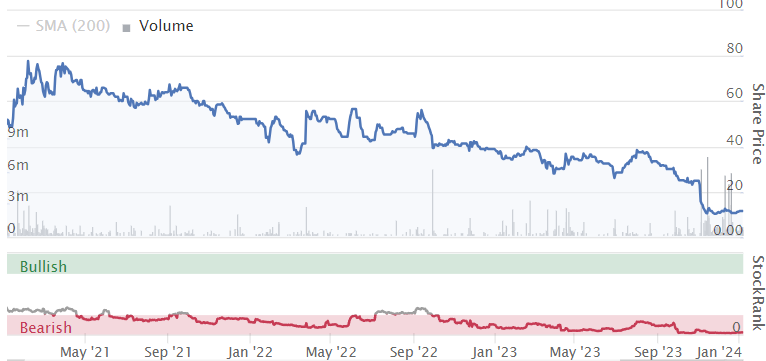
Today we learn that the company’s 2023 revenues are up 63% to £8.3m.
Revenues have been growing every quarter and Q4’s £3m were a nice jump on Q3’s £2m.
However, the full-year result is still a revenue miss against previously downgraded expectations, and the RNS doesn’t spell this out for shareholders who may not know or might forget the full-year forecast (around £8.6m).
Similarly, the company says that capex for the year was £9m, as previously forecast. But it doesn’t spell out that the full-year profit figure for 2023 is likely to be poor - you have to read the broker reports to see that.
Cavendish are forecasting an adjusted pre-tax loss of £10.3m (previously £8.5m) while Zeus have suggested an adjusted pre-tax loss of £10.4m.
I note in passing that revenues for the year are smaller than the probable pre-tax loss. This is something I keep an eye out for with early-stage companies, as a sign that a company is still very far from generating a respectable financial performance!
Funding: as previously announced, the company has secured a £13m capex loan, none of which had been drawn down at year-end. Scouring previous RNS announcements and broker notes, I don’t see any disclosure of the interest rate attached to this loan - perhaps a reader can enlighten me, if they have found this information?
On top of that loan, the company raised equity of £8.3m (gross) in November, shortly after a terrible profit warning which Paul reported on here. The placing price was 10p. Gross cash had fallen to £6.1m by the end of 2023.
Operational update
There’s an impressive ramp-up in capacity coming:
No new technical problems have arisen in recent months. Accordingly, focus remains on delivering further operational improvements, capacity installation to remove potential single points of failure, upgrading internal manufacturing processes and further strengthening operational management and supervision.
The Company continues to expect to complete the installation of £50m p.a. sales capacity by mid-year 2024 and £75m p.a. sales capacity by the end of 2025, to support existing contracts, expected growth and to build manufacturing resilience.
As a reminder of the purpose of this company, Surface Transforms is “the UK’s only manufacturer of carbon-ceramic brakes for automotive use”.
2024 outlook
The Company is maintaining its revenue guidance for 2024 at £23m. Overall, the outlook for 2024 to 2027 continues to remain very positive reflecting contracts in series production and recent new business announcements, with capacity being installed to fulfil these awards.
A note issued by Hardman & Co. in November did suggest revenues of £23m for 2024. It also suggested that pre-tax profit would break even in H2 of 2024.
CEO comment excerpt:
We continue to be capacity constrained not demand constrained, so our factory expansion remains a crucial task in positioning the Company for the future. It is therefore pleasing that the recent debt facility provides the foundation for the programme to continue apace. At the same time we are continuously improving operations to enhance productivity, thereby driving increased output in 2024, with the new senior leadership team in place to deliver these ongoing improvements in a timely manner.
Graham’s view
I’m looking for any reasons to not give this company the thumbs down.
Paul has given this share some detailed analysis not just around the time of the profit warning in November (here and here) but then again in December.
Two major positive points:
Access to a loan and a recent equity raise should stave off the need for another fundraising in the short-term.
Customer demand is thought to be strong, with revenues forecast to surge to £23m in 2024 thanks to increased capacity.
But also quite a few sources of concern I can immediately think of:
The causes of the November profit warning - manufacturing difficulties - are likely to crop up again as the company expands.
Financial risk levels will be elevated by the use of debt. Additionally, the interest rate attached to the capex loan has not been disclosed yet, to my knowledge. The lender is Liverpool’s Urban Development Fund so perhaps it’s a reasonable rate?
As an early stage manufacturer, it’s too soon to be able to predict its performance metrics such as ROCE/ROA.
The reporting style could be better. I would like it to clearly outline if it is hitting or missing expectations for revenues and profits.
My main concern is that the company might need to raise more equity, sooner or later. If you agree that the company can reach breakeven by H2 of the current year, you might be willing to bet that no more equity will be needed, and that the latest cash balance (£6m) plus the £13m loan will be enough.
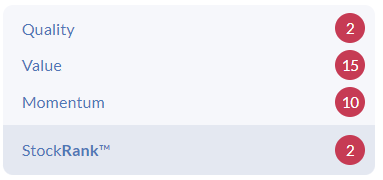
However, from a value perspective, based on achievements to date, I think it’s perfectly reasonable to give this one a moderate thumbs down. The StockRanks agree, seeing no signs of quality here and very little value, either:
So this one gets the thumbs down from me, although for the purposes of SCVR continuity we might call it AMBER/RED (see Paul’s December coverage).
Plus500 (LON:PLUS)
Share price: £17.32 (+4%)
Market cap: £1.38 billion ($1.75 billion)
Plus500, a global multi-asset fintech group operating proprietary technology-based trading platforms, today issues the following trading update for the financial year ended 31 December 2023.
This is topical considering that Paul has covered CMCX today, and CMCX was on both of our top ideas lists for 2024.
It’s a short update.
Key financial results for 2023::
Revenue $725m, EBITDA $349m, both significantly ahead of current market expectations.
Cash balance at the end of the year was $900m.
Market expectations (via Liberum) were for revenues of $645m and EBITDA of $300m. So both line items have been beaten by c. 12-13%.
Shareholder returns: the company reminds investors that it made $350m of shareholder returns in 2023, with a combination of dividends and buybacks.
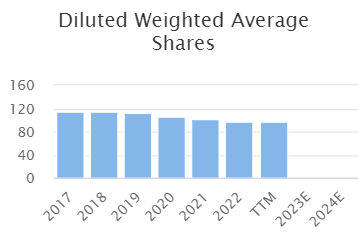
The company’s share count has been on an attractive downslope, and is now only around 80 million:
The company also has plenty of operational achievements to crow about: “the expansion of the Group's US futures businesses, the launch of a localised retail trading platform in Japan and further progress in the significant UAE market… Additionally, the Group added a regulatory licence in the Bahamas, which means it now holds 13 regulatory licences globally, representing a key competitive advantage for Plus500.”
Outlook statement doesn’t give anything away.
Graham’s view
I last covered this one in the SCVR back in February 2023, and took a neutral stance on it then (the share price was £18.80 that day).
Historically, I had concerns with certain aspects of Plus500’s operations. Firstly, its hedging practices didn’t match up with what I expect from a company in this sector (note: I hold IG group (LON:IGG) shares). I also had a perception that the company’s customers were churning very quickly, creating an inherent instability in the business model that was worse than its competitors.
Years have passed and I think it’s fair to say that Plus500 has performed admirably well. It has grown up, it has expanded, and it now has more credibility than ever before.
And I must say that I applaud the company’s use of buybacks. If sceptics like myself are refusing to buy the shares, and the stock is trading too cheaply, then buying back whatever shares it can afford is a smart move. $130m of buybacks in 2023 was a fine way to answer critics.
The stock remains “cheap” today:
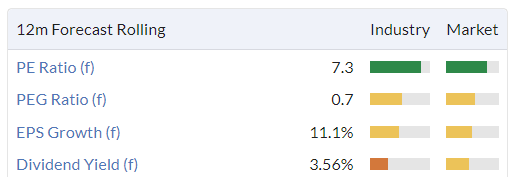
Note also that that company’s cash balance still covers more than half of its market cap.
If I was going to invest here, I’d have to make peace with the apparent reality that the company sees its cash balance as a primary risk buffer, and that this cash balance could be vulnerable to market movements in a worst-case scenario. But with that buffer approaching $1 billion, perhaps I could still sleep easily at night.
While I still prefer others in this sector, I think it would unfairly penalise Plus500, and be somewhat contradictory, if I were to remain neutral on it, given that I am so positive on its competitors. I am therefore going to tentatively give this stock the thumbs up at the current level. My prior concerns have been answered by a string of many years of high profitability, a ballooning cash balance, and a reducing share count. The 2023 result is particularly impressive given low market volatility that limited interesting trading opportunities during the year.
You may wish to bear in mind that this is not a domestic UK stock; group international headquarters are in Israel.
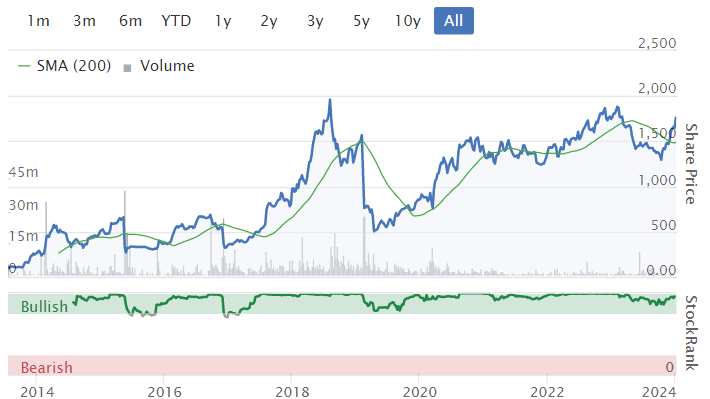
Chart since listing in 2013 -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Graham,
Had a very poor experience with Plus500 (LON:PLUS) trading platform. In my personal experience their excellent financial results reflect how they take cash from punters (mugs like me perhaps!!), not always strictly fairly, and redistribute it to shareholders via market cap growth, dividend and share buy backs. A much better share to own rather than trade through their platform. I only wish I had continued to hold the shares and not used the trading platform!
I am not surprised to hear you say that ACounsell. Thanks for sharing your personal experience. Concerns linger!!
I tried the trading platform on Plus500 (LON:PLUS) a few years back as well and gave it up immediately when I realised just how much they would take from me in spreads and financing charges alone. That said I made good money on the shares but haven't traded them for a long time since I sold despite them looking persistently cheap. I always wonder just how long that can persist. It seemed excessive compared to others like IG (at least at the time).
CMC Markets (LON:CMCX) very encouraging trading update - they are now guiding to net operating income of £300m, which means they expect around £180m in H2 (having done £120m in H1). Operating costs in H2 are excepted to be flat at around £120m, which by my very rough estimates would translate to around 15p EPS for H2 - if they are able to maintain this level of income then they could be earning 30p on an annualised basis, which would put it on around 5x earnings. Obviously trading performance is extremely volatile so impossible to say what the actual figure will be.
Remember they effectively have £237m in net cash (i.e. cash in excess of regulatory requirements), so in theory this should put a floor on any renewed share price weakness. I can't see it falling much below 100p for any sustained period given this cash buffer, so I think the risk/reward profile looks pretty good from here.
Excellent post on Wynnstay (LON:WYN) . I hold. In my view, it's not a turnaround at this stage, just a cyclical. Profitability is volatile through the cycle. After an exceptionally strong year last year they are suffering a very weak year, as the commodity price tailwind became a headwind. Adverse weather can also be an issue as was the case in October, which was just bad luck ahead of year-end.
Much of the feed business effectively works on a cost mark-up basis. Gleeson, the fertiliser business, is the one that is more volatile: massive stock gains last year has led to stock losses this year...but this will taper out. Volumes will bounce back in feed, but always weather dependent. The only thing that concerns me a bit are some comments around inflationary cost issues at the stores. They had a real problem with their pet store chain a few years back and had to put it into administration. Anyway, using a simple Gordon growth model approach - 340p with 5% dividend growth (which is what it has historically achieved) is a 10% annual return. Good enough for me as the business is relatively low risk. I agree that trading is possibly still weak, so might test the lows. £3 is a stunning entry point, in my view, if we ever see it and nothing has permanently changed.
I am looking at NWF (LON:NWF) as well, which looks really good at the right price. Took a look at Carr's (LON:CARR) , but didn't like that one as much despite Harwood holding.
"...spending hours researching a stock and then waiting for a dip in SP which doesn't come and then watching the graph carry on up to the right without ever buying"
Sounds very familiar. But last Friday was an exception, when I decided to take the plunge at the last moment before market close and bought a chunk of CMC Markets (LON:CMCX)
A combination of research, luck combined with some pluck I guess.
I'm also slowly getting better at being patient, taking heed from Warren Buffet when he reminds us “the stock market is a device for transferring money from the impatient to the patient.”
Also feeling a bit more confident with my purchase of of Eurocell (LON:ECEL) last month and plan to hold for longer term.
Interesting that Liberum who are corp broker to MPAC (LON:MPAC) have just released an in depth note pointing to the under valuation and a target price of 500p with 25p, 38p and 45p eps on a 2 year forward basis.
Given we are due a trading update in the next few days I can only assume this wasn’t entirely blind / unsanctioned. Does that suggest we can expect a relatively positive update?
I hold so I obviously hope so.
MPAC (LON:MPAC) I also hold and would just like to add those eps numbers do not include any upside from the electric battery work. I agree the timing is a bit strange but the tone is overwhelmingly positive. Tried to buy more last week but the price kept going up and up on very thin volumes, clearly a tightly held stock.
Yes - the Freyr opportunity should be treated as jam tomorrow as far as I am concerned. I ignore it completely personally. If it develops great but if not I want to know what I’m left with. As I understand it current Freyr work is a very small % of revenues and order book so core business is what we need to focus on.
Cookies are being phased out as new privacy regulations come into force. Google Chrome has started the process and will completely phase them out sometime later in the year:
https://www.bbc.co.uk/news/tec...
Silver Bullet Data Services (LON:SBDS) has devised an AI solution for marketing and Ads which was launched in November after 100 campaigns:
"Silverbullet, a provider of digital transformation services and products, is pleased announce the launch of its 4D AI Powered Insights Platform based on the accumulated knowledge and client feedback from more than 100 campaigns in FY23.
The 4D AI Insights Platform leverages AI models to combine proprietary 4D contextual intelligence with client first party data to improve video, display and YouTube campaign performance. In three recent individual digital advertising campaigns, 4D AI Insights managed services delivered +174%, +244% and +407% improvement respectively on client measured KPIs/benchmarks.
The Board has confidence in the 4D model and pipeline into FY24 based on 4D performance and the increasing demand for privacy first AI driven capabilities as the cookie is forecast to be finally deprecated in 2024. Clients are increasingly seeking innovative ways to use AI to combine available privacy safe data assets to drive marketing performance and ROI. Silverbullet, with its established 4D product and the new platform, is well positioned to help clients to unlock this global business opportunity."
US media giant Omnicom 's(NYQ:OMC - $17 Billion MC!) Media Services division has been using 4D. Programmatic Director at Omnicom Media US, commented:
"We have been delighted with the power of 4D, which has been delivering outstanding results for our clients and exceeding KPI benchmarks. 2023 has been a great year utilising 4D's AI driven, privacy safe marketing platform, and we look forward to building and using learnings from 2023 into 2024 and beyond."
A recent placing at 70p raised £1m:
The net proceeds of the Placing will be principally used to provide the working capital required to facilitate the significant recent growth in new contract wins and further accelerate the expansion of the Company's new 4D AI Powered Insights Platform. As announced at its recent interim results, Silverbullet has experienced strong revenue growth this year, with revenue having increased by 79% and overall operating costs reduced by 8% in H1 2023 versus H1 2022, as it moves towards a position of positive EBITDA in early FY24. The Company is witnessing significant demand for the AI-driven insight capabilities the 4D AI Platform can provide, with clients increasingly seeking innovative ways to utilise AI in conjunction with privacy-safe data assets to drive marketing performance and ROI.
Mkt Cap is around £20m. More info on products and services here:
https://wearesilverbullet.com/
I took an opening position recently.
hi eParo
Silver Bullet Data Services (LON:SBDS)
Simply looks another high risk jam tomorrow share but good luck.
Snazzy
Look again Snazzy
This is now profitable as I understand it. I completely agree it was way overpriced at IPO but is actually a good business. The losses were primarily funding development of the 4D product. Those costs have now been removed as dev is complete.
Look at the quality and growth of its client base. The funding was always coming as the gap between cash flow b/e and funding runway was tight (they did have just enough but too tight for any margin of error). That uncertainty has now been removed and as I understand it they are currently cash flow profitable.
Not a share for investors that don’t do their homework though - but that is where the opportunity lies, so people need to do their own research properly.
A single wealthy smart investor took all of the placing at 70p btw. That fact alone should tell one to look a bit further under the covers.
I am also long Silver Bullet Data Services (LON:SBDS) but a bit higher than this. I spotted the turnaround to break even down at about 20p but didn’t average down which has really annoyed me given it has 6 bagged since.
However, I can see this being multiples of current share price over next few years. Has very high quality customer base and should now be profitable. When it IPO’d it was too expensive. I told the CEO that who told me he felt otherwise. It went from 300p to 20p. I then thought it ludicrously cheap but was a bit concerned they might do a fundraise so held off….DOH!!!! They did but at 70p - a single investor took the whole lot.
As all the development has now been done on the 4D product the tech team has been reduced considerably. That, combined with big growth in US with blue chip clients means they should now be profitable both on a PBT and cash flow basis and that probably underpins current share price. However, upside here is potentially enormous. Risk/reward down at £3m market cap was bonkers - why I didn’t trust myself to take a large position is beyond me but hey ho!!!
Not UK, not value and not particularly small, by UK measures, though certainly tiny in US terms, Axonics (NSQ:AXNX) is to be purchased by Boston Scientific (NYQ:BSX https://www.prnewswire.com/new...
But I couldn’t think where else to post the news and I thought it would be helpful for those with an international bent as indicative of activity in small-cap medtech, which I see as unusually reasonably valued, thanks to the excitement over weight-loss drugs “weighing” on valuations. The price offered is a 40% premium to the undisturbed price pre-negotiation but a less exciting 23% from Friday’s close. It’s my second takeover offer in the last 2 weeks so activity is still high.
Hi Paul
I was the guy who put up the Einstein quote on Friday.
I just wanted to thank you for your in depth piece on Plexus Holdings (LON:POS) on your weekly Podcast. It is only a small position for me but it really helped me to better understand the situation after the very confusing RNS.
Good to know your Podcasts are now attracting 2,500 listeners. I now have a slot in my Diary to listen at 10am every Sunday!
Ah great, thanks for the Einstein quote! My mother, Sylvia, also thought it was really good, when I had her round for Sunday lunch I mentioned it :-)
Really enjoying your podcasts too Paul and new to Spotify too!I always get there eventually.....Keep up the great work there too.Are we going to get one live from Wetherspoons one day..?I've been a big fan of Spoons' food & drink offerings for a few years now after being introduced by a mate.And did you ever snap up any J D Wetherspoon (LON:JDW) 's shares in the end?
Careers at MSI-DS - MSI Defence Systems (msi-dsl.com)
MS International (LON:MSI)
I am sure many MS International holders will have seen this and it is not a surprise considering the recent news flow but they are having a large recruitment drive .
Thanks for that Helvellyn!
Another suffering New Year Blues, one i'm keeping a close eye on to add.
800-820p maybe?
Maybe, MS International (LON:MSI) is around 847p now to buy. I bought some Friday, too early but will add if goes down some more.
Looks like most PI's are selling after a good run back end of last year. Hard to blame i suppose. On the flipside, opportunities may be presented...
Yes the Santa rally, ended abruptly at New Year, quite a few high fliers are nose diving now.
Frustrating as it maybe, need to keep focused on any opportunities that arrive!
Yes I'm waiting for some to fall back, after strong run ups in November and December.
hVIVO (LON:HVO) Regarding Paul's excellent podcast and being able to sit with stocks without getting bored I decided to look at the winner in the Stockchallenge competition. Starting in January the average of the five stocks peaked at ~+36% before going mildly negative in May. How many people would have sold in May (and gone away) after being up so much? The stocks finished the year at 171% with all the heavy lifting happening from the end of August. With regard to hVIVO (LON:HVO) itself, I had written "looking for a retrace <16p". Didn't do it - "when it's time to buy you wont want to". What a chump!
We have all done it, myself especially, after spending hours researching a stock and then waiting for a dip in SP which doesn't come and then watching the graph carry on up to the right without ever buying. Apart from my trading pot I am looking for shares that I think can double or better within a 12 - 24 month timeframe so why am I bothered about + or - 5%? I now have a note on my desk ''if you are going to buy it £***!!! buy it''. As we all know buying is easy its the selling that is the hard bit.
Hi Helvellyn
I recollect a quote from Peter Lynch which seems appropriate to the situation you describe, if you like a stock and think it represents good value don't 'nickel and dime' it. After all if one is right a couple of pence here or there on the entry point will make no difference in a year or two.
For what its worth I have just added a few more Bloomsbury Publishing (LON:BMY) at 476p slightly higher than I would wish, but from my research I wouldn't be surprised to get another ahead of expectations update prior to the finals. Irrespective the shares are hardly expensive at present and there is £39m cash looking for appropriate acquisitions.
All the best
Bloomsbury Publishing (LON:BMY)
"I wouldn't be surprised to get another ahead of expectations update prior to the finals"
I agree.
Maas had 5 books in the Amazon.com top 20 most sold books list last week, and one of those books isn't even available until the end of this month.
https://www.amazon.com/charts/...
That's not happened in the last 2 years that I've monitored the list.
At the time of the Positive Trading Update released last month, Maas had 3 books in this list, which was already unprecedented as far as I could see. In the previous 2 years the most she ever managed was 2 top sellers in one week.
Fingers crossed.
A
Positive update from Celebrus Technologies (LON:CLBS) this morning. I hold - and recently have become something of a bull on these shares. I'll try to explain why. On the face of todays update is not that interesting - perhaps seems more a puff piece - as it's just confirming in-line expectations. The company has gained something of a reputation for not quite delivering on its promised potential and being quite highly rated tends to be uninteresting to private investors. Which is the kind of thing that gets me interested. There are a few things worth noting in todays update:
[1] In-line is a big rise of 62% in eps for the current year (not accounting for adjusted forecast figures and FY22 was disappointing) But mainly as it provides confidence in the further 21% eps growth forecast for the year to end March 25 - and why that might continue into the future.
[2] The established sales channel via mainly US software system companies is extremely sticky but highly constrains CLBS sales to what their channel partners want to sell. Breaking into direct sales required investing in product development and sales teams. Update confirms that the recently established direct sales channel is now working - and very likely to be working faster than the established partner channel, but from a low base. And also that the new product development is also proving attractive through the established sales channel. So the direct sales is additive rather than substituting.
[3] The private cloud implementation is attractive and speeds up direct channel sales with implementation in days not months, and up-selling with overnight implementation.
[4] Shows sales in new verticals possible with direct sales channel.
[5] Customers are sticky which is good for CLBS - but also makes gaining customers from the competition more difficult. Current shift in technology 'emptying the cookie-jar' driven by regulators provides an ability for direct sales team and private cloud to switch customers painlessly to CLBS. Potentially a large one-off opportunity for CLBS to gain customers that otherwise would not consider switching right now.
It's been hard to really understand what Celebrus software does for its customers. Worth watching the 2hr capital markets presentation on IMC or here via Youtube for a much better understanding of the technology (CTO webinar and demonstration from 29mins) and presentation from UK head of Merkle on why they benefit from recommending Celebrus to their customers (around 1hr 24 mins). I'd be interested to know what others think?
&t=6s
[6] Celebrus shares are not cheap judging by 18x forecast P/E for the current year. I usually prefer to look for much more lowly rated turnarounds. it's likely that the costs of implementing the product developments and setting up the new sales team is hiding the true profitability. It's a classic case where the ARR licences are at around 80% gross margin, but to begin with a low part of the sales value. Consistent growth in ARR will create large operational leverage.
None of this guarantees success. Turning companies around tends to take a couple of years longer than management expect, and much longer than investors expect or patience will last. Probably why CLBS shares fell from their 400p heights and more recently fell to 150p in the recent derating. Today's update confirms that management is delivering on the start of the runway.
Not sure I'll be adding at the current prices as it's already my 3rd largest holding after MS International (LON:MSI) and Macfarlane (LON:MACF) . I'd prefer the shares back at 150p to keep adding but it seems unlikely I'll get that opportunity on today's update? I generally find it hard to add as the share price climbs, prefering the depths of value and safety of margin (whoops ed - margin of safety? or maybe both)
That might prove to be a mistake? Anyway it promises to be an interesting ride from here?
Looks iike a new note from Cannacord is on research tree this morning which I can't view, also a morning brief from Cavendish which is free via research tree - which says what I've just said in far fewer word, albeit with less detail.
cheers
Mark
Celebrus Technologies (LON:CLBS)
Agreed Mark - a much misunderstood company and business model. At an inflection point here in terms of ARR. their land and expand strategy starting to accelerate.
In case you missed it, Paul has posted an excellent article about his recent experience of the laundry machines operated by ME International (LON:MEGP). Thank you Paul, I found this both informative and entertaining. You're great at this stuff!
(I hold)
Jet2holidays reports ‘record’ demand since peak campaign launch | Travel Weekly
Jet2 (LON:JET2) reporting record demand in this morning's Travel Weekly, should be a good read across for airline/travel companies/agents not least On Beach group (LON:OTB)
Very upbeat commentary from the CEO, Steve Heapy. Without wishing to be overly optimistic one would expect the increase in bookings to be reflected in the next trading update, which should be at the end of the month. Needless to say I hold.
"In the period between Boxing Day and January 5, the operator said it saw bookings increase by 150% compared to pre-Christmas, with late winter holidays and summer 2024 bookings proving popular."........
"Steve Heapy, Jet2holidays chief executive, said: “This time of year has traditionally been the peak period for holiday bookings and this is most definitely the case so far this year.
“We are seeing record levels of demand via independent travel agents as customers jump at the chance to lock in their holidays and we are expecting this demand to be even stronger over the coming weekend.
“There is no doubt that our track record of providing industry-leading customer experience is fuelling this demand, with new and existing customers responding to our award-winning proposition."
The 150pc increase sounds impressive, but who buys a holiday pre-Christmas? That's a normal booking pattern, people book holidays after Christmas, not before. This 150pc more bookings the week after Christmas should not be news.
Heapy is also just talking about agent bookings (as he talking to industry rag Travel Weekly), nothing about direct bookings. There should be record bookings as well as they have more seats (and beds) to sell than before. What's as important is what yields they are getting, anybody can get record sales selling too cheaply.
I see nothing negative in the report, but I also don't see anything to be excited about, seems Heapy was just being wisely vague, and shall await the trading update.
Jet2 (LON:JET2) was my largest holding in January 2020 (when it was DTG, and yes I did get out before share price collapsed). Started buying back over last couple of months, I am wary as really lost touch with airline industry. I hired Channel Express aircraft many times, but that was now 25 years ago, and been out of industry for 13 years now.
CROMA
Toddler Croma nice little RNS
Buying two “mom and pop” shops to add to their portfolio
Takes them to 16 “security centres”
Super simple strategy to build their network with acquisitions underpinned by freeholds as effectively zero goodwill .
Today 430k purchase underpinned by 350k of freehold so that’ 80k for two businesses including their stock .
There will be lots of independants easy to buy with owners wanting to retire and so gives them an exit and easy bolt one .
More in the pipeline I’m sure I read a target of 24 stores by year end .
All usually underpinned by freehold .
Quick fag packet
Let’s say 30 stores achievable within 24 months
Turnover 10 million easily achievable
1-2 million profit
Loads of freeholds
More cash to come from sale of security system
Sort of ok I guess though not sure going to blow the doors off but should be circa a quid a share .
have to say compared to the Wynnstay analysis done by Bob that is a pretty bad summation but it is a Monday morning
Planetx,
Yes 2 cheap locksmith acquisitions by Croma.
When I watched the CEOs last video presentation I was struck by his assertion that there is virtually no competition from others when buying up privately owned locksmiths, hence the cheap purchase price. However considerable synergy when acquired and grouped together in a buy and build strategy. Reminds me of a mini early stage Judges Scientific.
The terms of these acquisitions would seem to support the Croma Security Solutions (LON:CSSG) CEO's assertation. Combined £500k revenue for a cost (net of freehold property value) of just £88k.
Assuming that these run at a similar operating ratio to the existing locksmith shops (or, at least, will do post-acquisition), we are looking at a PE ratio for the acquisitions of about x2.
That'll do nicely!
Re Croma Security Solutions (LON:CSSG) - I think a closer parallel is Dignity, or Angling Direct (LON:ANG) where a relatively obscure, unfashionable retail niche with local Mom&Pop operations can be bought up cheap and have their economics transformed through centralised purchasing and back office and getting locations to focus on sales.
However, the issue is scale. They have just 16 stores now - how many can they absorb each year? They have the cash themselves already to fund up to 5 or 6 what do they need access to a capital market for. It looks a cracking business idea but the risk of de-listing must be high although I guess if they hang around for a few years then they will look for a takeover target.
Delisting is certainly a valid concern for Croma Security Solutions (LON:CSSG), Zipmanpeter, but I do not get any sense that it is on the agenda. Shareholder engagement was zero under the old regime but has stepped up following the divestment of Vigilant, with several Investormeetcompany presentations. Also, they are finally going to get some analyst research published, probably this quarter. This is not behaviour that is consistent with management considering delisting.
Thank you for the heads up on this one: Croma Security Solutions (LON:CSSG)
There are literally thousands of little privately-owned locksmith shops, burglar alarm/security companies around and the idea of consolidation in this industry seems compelling and I imagine could be highly profitable if done judiciously. The managment certainly come across as diligent and experienced in their niche.
People will always spend money to ensure their family's and business' safety and security. One to tuck away I feel...
I've just bought a small position (had to do it via fill or kill on HL's site). Cheers!
Hi mjfgs
What exactly is Kill of Fill?.
I have a HL account and never really understood
The order will either be placed or cancelled. Say I order to buy 1,000 ME International (LON:MEGP) shares at 122p, if HL can place that order, it will go through, otherwise it is cancelled.
It does seem more effective than leaving limited orders. Because they have to actively try to place it. You can snag a bargain sometimes.
Threepeat.
Adding to Rusty’s reply. H/L or whoever get the best price then available. e.g if you do a fill or kill buy order for ME International (LON:MEGP) at 130p and the H/L can get 120p or whatever, that’s the price the deal is done.
In my experience a limit order will not necessarily be triggered, even though you can get a get a better price quoted to you while the limit order is on. I imagine market makers will be disinclined to fill a limit order if they can't match it. A fill or kill order forces them to deal or not deal.
Transense
Interesting update on their tyre monitoring translogic system .
This is a monitoring device for truck / fleet companies to check their tyres that has become a regulatory requirement and they are rolling out the product .
RNS harps on about hiring sales director but mentions 6 new staff hired which is quite a lot for them.
Looks a very easy to product to sell into trucking / fleet who are obligated to check their tyres , will save them time and money and stop them going to prison for negligence .
Good thing with Transense and translogic is any idiot can understand the usage so appeals to me .
Valuation on paper is not super cheap but factor in the that the forward earnings from Mitsubishi cover the entire market cap then it feel a bit of a no brainer and in snooker parlance a “shot to nothing” .
Quick thank you for your spreadsheet Paul, it's a great sense check for new buys/sells.
I only have two stocks that are not green and I should have sold them a long time ago: Eneraqua Technologies (LON:ETP) Polarean Imaging (LON:POLX)
Eneraqua Technologies (LON:ETP) I believed the CEO BS, Polarean Imaging (LON:POLX) I just got far to attached to their 'game changing technology' Which turns out doesn't mean a thing if they can't commercialise it and run out of money.
"That’s really helpful that they include both revised, and previous guidance. All companies should do this, as it’s transparent, and saves us all time to dig out previous guidance."
I agree with you Paul.
But if companies don't put it then people have to go looking, which means there can be bigger moves as the information isn't as widely known. So for traders it can be beneficial!
Sigmaroc (LON:SRC) tipped by Midas yesterday:
SigmaRoc is set to become a top-tier lime and limestone producer, following an audacious deal announced late last year. Quicklime is used as a purifier to create products as wide-ranging as glassware, crockery, kettles, ovens, milk and sugar. It is also deployed to create steel bridges, buildings and roads. It is an essential component of paper production, ensures water is pure enough to drink and acts as a fertiliser, making soil less acidic and grass tastier for cattle. The shares are 57p and should move considerably higher as the transaction beds in and the business grows.
https://www.thisismoney.co.uk/...
Well hopefully Midas is right. Difficult to avoid confirmation bias, but I have a reasonable holding in Sigmaroc (LON:SRC) having added when the shares fell below the recent fund raising price. Midas also tipped Porvair (LON:PRV) yesterday that I also hold.
Time will tell if we are both right.
Not strictly small cap but I'm surprised by the strength of UK housebuilders this morning especially Crest Nicholson Holdings (LON:CRST) given current 'think' re interest rate path . What have I missed ?
Broker u/g Barclays I think
Ah yes just seen it, thanks Ox . SP target upped from 200 to 258 ;-))
Took a look into Wynnstay (LON:WYN) group over the weekend as a potential turnaround play and thought I’d share my thoughts (worth noting the sector is pretty alien to me so there are likely some misconceptions or mistakes within in my research!).
A lot of shares saw 10-20% rises towards the tail end of 2023, Wynnstay started by following the same pattern, rising from 360p in mid-October to 430p at the end of November. They then released a trading update on 30th November downgrading FY23F forecasts based on a poor H2. They stated the following key issues:
A couple of months on from the update the share price is currently languishing at around 340p, lows not seen since the end of 2020. There is still a couple of weeks left until the full-year results announcement penned for the end of January. In terms of FY24F, the recent statement highlighted the following: “Looking ahead, with uncertainty over milk and other farm-gate prices, farmer sentiment is likely to remain cautious in the short-term, but with a strong market position and balanced business model, the Board still anticipates that the next financial year will show an improvement over FY23.”
Farm gate prices:
Milk was highlighted as a key driver in a lack of confidence of farmers, the table below shows that UK farmgate milk prices are starting to recover in current projections -
Other farm price changes between October end and most recent data (typically December end):
Beef - 480 p/kg increased to 490 p/kg (+2.1%)
Pigs - 219 p/kg decreased to 214 p/kg (-2.3%)
Sheep -570 p/kg increased to 590 p/kg (+3.5%)
This data seems to suggest that the significant price drops in farm gate prices seen earlier in the year have stabilised. It would be generous to say that there was any meaningful growth in the recent figures but they are generally moving in the right direction.
Weather - Rainfall remained high at the start of November but then fell off significantly resulting in a slightly lower monthly rainfall than average for the month, December was the 9th wettest on record and there was a lot of flooding. One article I read stated it is the wettest winter in 130 years. It is hard to predict without knowledge of the sector the impact this might have but it is more likely to be negative than positive I’d guess. ChatGTP states – “While heavy rainfall can lead to shifts in the types, formulations, and timings of fertiliser purchases, the overall sales volume might not see a substantial increase or decrease, but rather a redistribution based on the specific needs arising from the weather conditions”.
When it comes to winter seed products Wynnstay were previously negative on the impact of the wet weather so I’d expect that narrative to continue and sales would be hit quite hard as growth would be strong with warm temperatures and high rainfall. A lot of seed may have been washed away and need to be repurchased potentially, I read some articles about farmers claiming compensation. The following article paints a poor picture of UK agriculture: https://www.fwi.co.uk/news/persistent-wet-weather-taking-its-toll-on-uk-farmers
Inflationary pressures – This seems to be easing, a lot of companies stating improvements.
Cash – Shore Capital noted a significant increase in net cash due to working capital increasing by 7.2 million, from 12.8 to 20 million. I hope that this will have been used to generate some additional cash not currently in the figures.
Fertiliser Prices - Fertiliser price drops seem to have stabilised as shown in the graphic and might even be moving very slightly higher.
Methane reduction – I wasn’t previously aware that Wynnstay is also involved in a study into the use of daffodils in feed to reduce methane release in cattle by up to 50%. Longer term this is something that could see benefits if governments introduce any new legislation.
Summary –
I still have some concerns that Wynnstay could warn further on profits later this month and I am not sure if I would be comfortable owning the share until after the next update. Surely a lot of the potential further downside is already in the price. I would be disappointed to see management point the finger at further declining farmer sentiment as that seems to be stabilising/starting a recovery according to farm gate prices. My concern is that the weather, specifically the high levels of rainfall and flooding are going to have a detrimental impact on sales and push profits even lower. It is worth noting that Dec 2015 was the wettest on record and when I checked back to their end of year results there was no mention of weather at any point. If there is there anyone with any sector experience that could shed more light on the impact of the wet weather to Wynnstay it would be much appreciated. Apologies for the lengthy post for those not interested in the share (I do not currently hold).
We live in an area where almost all farming is arable. And most fields have not been able to be worked on for 3 months. I would think that sowing of summer wheat will be well down this year, and many of the crops currently in the ground are beyond salvation.
Wynnstay (LON:WYN) Excellent post Ben. I think your caution regarding the upcoming TU is probably justified but I opened a slightly larger than half sized position recently, wanting to get established in the name and happy to fill out if a better price is offered. I was attracted by the asset backing and also by study of international comparisons, whose charts all look very similar, suggesting that Wynnstay’s current difficulties are not idiosyncratic. Have a look at wide moat Corteva (NYQ:CTVA, which I also bought recently, and FMC (NYQ:FMC, which I am reviewing for purchase - although I might sell puts on this at a strike in the mid 50s. In the case of Wynnstay, the almost 5% yield is historically a sign that the bottom is near, and the fact that the company has such an unblemished record of growing the dividend might be supportive of the SP above 300p. The other datapoint to watch is bond yields. If they fall, Wynnstay should benefit as it could be regarded as an unconventional bond proxy. Ultimately your caution may well be warranted. Interested to hear what you decide eventually.
Good post, thanks. Wynnstay (LON:WYN) have a good profile in this area - Herefordshire/ Shropshire and are well used by local farmers and other rural dwellers. Milk prices are certainly recovering a bit of ground, Wynnstay produce emailed various news sheets for farmers for poultry, arable, milk, beef etc and are well worth signing up for, as an investor, don't need to pretend to be a farmer!
A conservatively run company with little debt and make sensible acquisitions. I wonder if the new FD will have properties revalued? I recall the previous FD said a year or so ago that freehold property if revalued to market would add around 50p per share to asset values, but he preferred to be conservative. That was valuing then of course.
The fields are very wet in places but they often are in those places. Lambing is getting under way. Spring is coming! I hold.
Thanks for your responses grumpy, BnB, dropside and TopVest. I've decided to wait for the update in the hope a poor update could force the SP further south, I agree BnB anything around 300p would be bargain territory and I'll be jumping aboard feet first. Interesting comments around the asset value of properties that I hadn't considered. Corteva (NYQ:CTVA) is certainly interesting, I would certainly like some exposure to food production, as mid/long term it has a lot of growth potential.
My morning smallcap tweet: The Man With No Gain
CMC Markets (LON:CMCX) CMO (LON:CMO) Huddled (LON:HUD) Gulf Marine Services (LON:GMS) Surface Transforms (LON:SCE) Arecor Therapeutics (LON:AREC) Celebrus Technologies (LON:CLBS) Phoenix Spree Deutschland (LON:PSDL) Elixirr International (LON:ELIX) Mediazest (LON:MDZ) DG Innovate (LON:DGI)
◄CMC Markets (CMCX)► guides FY24 net operating income £290-£310m vs prev guidance £250-£280m. [SP=110.4 Cap=309m]
◄CMO (CMO)► warns FY-rev only broadly in-line at c. £71.5m (£83.1m), adj EBITDA c. £1m (£2.1m), below previous guidance. Blames lower average orders values. [SP=26.56 Cap=20m]
◄Huddled (HUD)► guides FY-Dec rev-cont £2.2m, almost all from Discount Dragon acquisition. Latter has exceeded mgmt expectations. [SP=3.91 Cap=13m]. I hold.
◄Gulf Marine Services (GMS)► contract extension for one small class vessel and a new contract for another small class vessel. Improved rates. [SP=15 Cap=152m]. I hold.
◄Surface Transforms (SCE)► guides FY-Dec rev £8.3m. Doesn't say if in line but F/C is £8.6m. No new technical problems have arisen. [SP=11.35 Cap=40m]. I hold.
◄Arecor Therapeutics (AREC)► expansion of its ongoing, exclusive formulation study collaboration with large pharma co. [SP=175 Cap=53m]
◄Celebrus Technologies (CLBS)► several software contract wins. Guides FY24 in line. Mkk exp are for £32.1m rev, adj pretax £5.4m. [SP=213.75 Cap=85m]
◄Phoenix Spree Deutschland (PSDL)► terminates forward funding commitment to a portfolio of development properties in Brandenburg due to decline in property values and and interest rates. Will lose initial payment of €5.5m. [SP=171 Cap=157m]
◄Elixirr (ELIX)► guides FY-Dec in line. Will move to pay two dividends PA. Interim div 5.3p xd 18 Jan. [SP=615 Cap=291m]
◄MediaZest (MDZ)► £120k placing at 0.04p, a 6% discount. Trading: ARR now c.£700k. [SP=0.04 Cap=1m]
◄DG Innovate (DGI)► Lloyd's Register 'Approval in Principle' for Pareta e-drive system design following feasibility study. CO expects to get further grant funding to move towards a full demonstration vessel project. [SP=0.17 Cap=17m]
Brief RNs from CMC Markets (LON:CMCX) raises guidance by approx 10%, hopefully a blue day.
CMC Markets (LON:CMCX) and Plus500 (LON:PLUS) both reporting significantly ahead this morning. Looks like the positive market at the end of the year is having a geared effect on trading related financials. Hopefully more to come.
CMC Markets (LON:CMCX) very positive update. my analysis suggests a long-term fair value share closer to 400p. see the graph below.
As always DYOR
BSV
Hi BSV long time no charts hope that things are good with you? Tommy