Small Cap Value Report (Mon 9 Jan 2023) - FDEV, BWNG, NANO, DEVO, ANP

Good morning from Paul & Graham!
Today's report is now finished.
Weekend podcast is here. Also the typed version is here for Stockopedia subscribers. Thank you for all the feedback, much appreciated! Most people seem to like them, and it's a useful process for me too, collecting my thoughts after each week's busy report writing.
My top 20 small cap ideas - I've also written another post here, which lists my top 20 watchlist ideas for small caps (with a value/GARP focus). I'll also publish another article with my top 20 speculative small/micro cap ideas, for more adventurous punters, next weekend.
When I spot good share ideas writing these reports, I add them to a watchlist, so I can monitor them, and consider a purchase. This weekend, I reviewed my watchlist, and thought it might be helpful to readers if I distilled it down to my best 20 ideas for companies that I think have solid finances, low risk of dilution or insolvency, are trading well, and look cheap or reasonably priced. These are listed in this article.
As always, I have no idea what the share prices will do, because facts, and market sentiment change in real time. Some shares on the list could do well, others won't - again, that is completely normal. But I hope it's an interesting list with some ideas for readers to research further, with explanations from me as to why the shares could be interesting. I'm hoping that about 60% might do OK to well, and 40% probably won't do well. As we're going into a recession, there's a heightened risk of profit warnings, so I'm fully expecting some to disappoint on earnings, especially in the first half of 2023. So it's not a list of trades, it's more solid companies that I think should do well medium to longer term, with some bumps along the road expected. There are also plenty of good dividend payers in my top 20 list. Anyway, check it out, and do leave your feedback, and your own lists (top 3, top 10, top 20, whatever you like!) of favourite shares (with explanations as to why) in the reader comments, so we can all share our best ideas.
As always our approach here is to do your own research & take responsibility for your own portfolios. So we're not recommending anything, just sharing ideas and opinions. I know it's tiresome to have to keep endlessly repeating this, but we get a handful of people who, for reasons only known to themselves, seem to have a conspiracy theory that somehow we're secretly recommending things (why on earth would we want to do that??!), which of course is complete nonsense. We want everyone to DYOR, that's the whole point! (not just mindlessly follow tips).
By the way, you don't need to "request access" from me to any of my spreadsheets (which a few people have been doing). Just clicking on the link opens it as a viewer. I obviously won't be granting editor access to anyone, as they could then change things in the spreadsheets. But you can download your own copy locally, and change anything you like within your own copy - or add information & your own notes in new columns, sort by different criteria, etc. The live price formulae in column K can sometimes be temperamental, but are the correct syntax.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
Paul's Section:
N Brown (LON:BWNG) - my review below looks at the balance sheet in particular, with the shares trading at a huge discount to NTAV. Opportunity, or signs of problems? It announces today a £50m settlement (cost) of the big legal case with Allianz, over mis-sold PPI. That's not a good outcome, being about double the provision on the balance sheet, but it does remove a major uncertainty. There seems enough liquidity to pay it. I think it's a poor quality business, so doesn't interest me, although the huge discount to NTAV, and controlling family shareholdings, might make it a candidate for a takeover bid by the Alliance family. Why would they be generous though?
Nanoco (LON:NANO) [quick comment] (41.25p down 26% at 11:06) - this news has been handled badly I think. Friday’s triumphant announcement about reaching agreement with Samsung (with no specifics) is tempered by an update today saying, “the value and terms of any final agreement are not yet certain”
Also, it’s now guiding us towards expecting a one-off settlement (with “no forward royalties”), and “at the lower end of the range of expectations” than from a jury trial.
This is a much more cautious tone today, and blows a hole in the argument that NANO might have seen major royalties as part of the settlement, which I’ve seen some bulls suggest. Although effectively winning the case through a compromise in its favour could mean negotiated royalties on future sales perhaps? I also very much like that NANO has fought and seemingly won, defending its IP, with a huge organisation Samsung. Why makes me wonder why Samsung doesn’t just buy NANO? Overall - still quite an interesting situation, but I have no way of valuing the company until we get details (which might take a while, as subject to confidentiality, so might have to be gleaned from future accounts). Today's update sounds like NANO is trying to temper investor expectations on the settlement deal. Time will tell! I'm neutral, as I can't value the share without more information.
Anpario (LON:ANP) - profit warning means it looks set to miss FY 12/2022 forecasts by about 25%, by my calculations (I can't find any broker updates, so worked the numbers out myself). Lovely balance sheet. Shares look significantly overpriced now, so I have to give it a thumbs down based purely on lack of growth, and excessive valuation. It could improve in future of course, but why pay up-front for growth that hasn't happened?
Graham's Section:
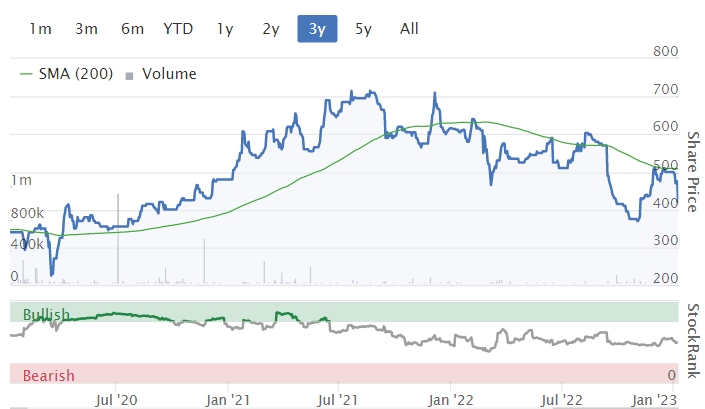
Frontier Developments (LON:FDEV) (£240m) - a huge profits and revenue warning from this video game designer and publisher. The key F1 Manager title has failed to sell as many titles as expected, and the company slashes its full-year revenue estimate (for FY May 2023) from £135m to only £100m. The operating profit estimate for the year is reduced from £20m to £2m. I still like this company but it’s concerning to see such a massive cut in estimates with only four full months left in the financial year. Ultimately, what this proves is that the stock remains a concentrated bet on a small number of key titles. With the share price now down by over 80% from its peak in January 2021, I remain neutral, leaning towards a positive view. The enterprise value is around £200m and it’s conceivable that operating profit can get back into the £10-20m range over the coming years.
Devolver Digital (LON:DEVO) (£249m) (-5%) [no section below] - continuing the video game theme, this US company listed at 157p in November 2021. As I noted in September, it was not the most promising IPO (it was organised by Zeus, mostly for the purpose of giving existing shareholders an exit). It is now down 60% from the IPO price.
Today’s update for FY December 2022 confirms that revenue recovered in H2, as anticipated. However, “Normalised Adjusted EBITDA” has missed expectations due to the “ongoing cost impact of three underperforming titles”. This EBITDA measure is now expected to come in at $20-22m (previous estimate: $27-32m). That strikes me as quite a large profit warning to suffer after the end of the financial year, especially considering that the prior estimate was reiterated in late September. On top of the weak adjusted EBITDA performance, the company is also expecting “material” cuts to the carrying value of its capitalised development costs, i.e. impairments as previous work turns out to be less valuable than previously assumed. Unfortunately I can’t find any attractions here, as it looks like a poor-quality IPO where maybe not all of the cockroaches have been revealed to shareholders yet?
Paul's Section:
N Brown (LON:BWNG)
27.7p (up 10% at 08:23)
Market cap £129m
This relates to a large, and long-running dispute between BWNG’s subsidiary JD Williams, and insurance company Allianz Insurance, over who is responsible for costs related to mis-selling of PPI.
Good news - a full and final negotiated settlement has been agreed, so this should be the end of the matter - a major uncertainty resolved.
Bad news - the cost is a lot more than expected, at £49.5m that BWNG needs to pay to Allianz (almost double the £25.5m provision in BWNG’s balance sheet as at 27 Aug 2022). Although this is less than the £70m (including interest & costs) that Allianz was claiming.
Can BWNG afford to pay it?
The answer sounds like a firm yes - this sounds positive -
The Company has sufficient liquidity to meet the cash flow requirements of the Settlement, including unsecured net cash of £82.9m as at 31 December 2022 as well as access to a RCF of £100m and overdraft of £12.5m, which are both fully undrawn as at 9 January 2023. Payment is expected to be transacted before the end of January 2023. After satisfying the Settlement the Company will retain a strong unsecured net cash position with material additional liquidity facilities remaining undrawn.
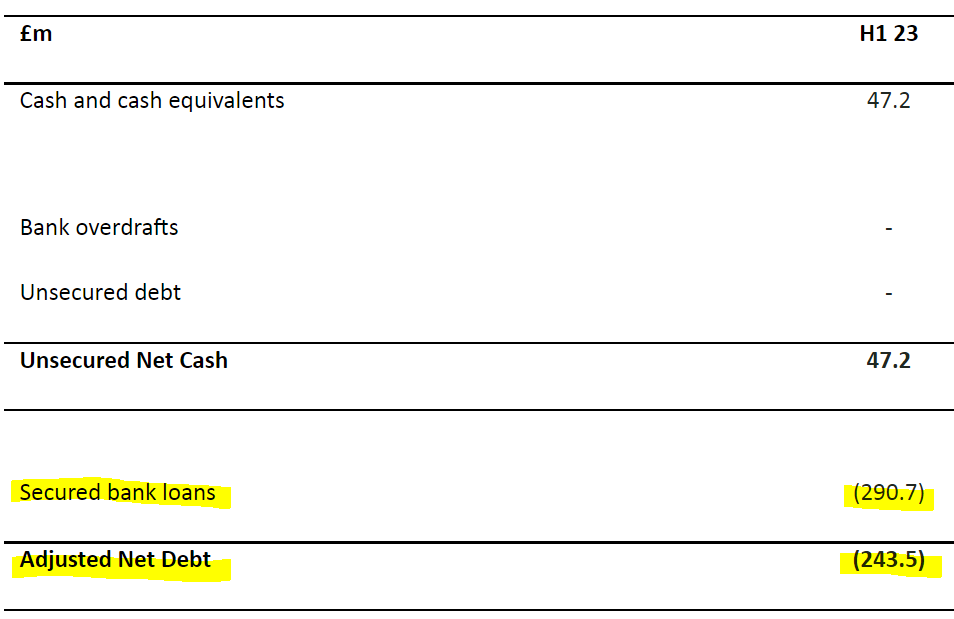
Hang on a minute though! I thought BWNG had substantial borrowings, to fund its extended payment offer to customers? Checking the last accounts (interims - 26 weeks to 27 Aug 2022), the full picture on net debt is this -
.
Today’s announcement doesn’t mention the large secured bank loans at all, which is selective reporting I would say! Although to be fair, today’s update is just talking about liquidity, not overall net debt.
The customer receivables book at BWNG was £492.0m, so it’s important to recognise that the net debt is just under half of the money receivable from customers (in instalments).
I’m not comfortable with this business model though, as the expected customer receivables losses are gigantic - many of them default - eg, just in H1 this year, the net impairment charge was £59.3m. As we saw with Studio Retail (which went bust) the actual numbers can be nothing like the published numbers, since a huge receivables book from customers who routinely default in large numbers, is very sensitive to whatever assumptions are made in the bad debt provisions - especially during an unprecedented disposable income squeeze, I would guess.
Balance sheet overall, when last reported at 27 August 2022 had NAV of £440.8m. I would delete the £108.3m intangible assets (which is all described as “software”) so has zero resale value I would suggest, so should be written off. Clunky legacy software could even be seen as a liability for this type of company, due to the cost of maintaining it.
This brings NTAV to £332.5m - which is massively above the market cap of £129m. So the stock market is effectively saying it (a) doesn’t think the net assets are completely real, and need a hefty write-off, or (b) the shares are woefully undervalued, or ( c) somewhere in the middle of those two extremes.
This balance sheet is very much stronger than rival Studio Retail (which went bust), so I suspect BWNG is probably in little danger of going bust, unless there’s a huge black hole in the accounts (as there turned out to be at Studio Retail).
Ownership - BWNG is controlled by the family of Lord Alliance of Manchester, who seem to own over half the shares. Hence I would say there could be a good chance of them taking it private - after all, why bother with a listing, when the shares are so woefully valued, at a >60% discount to NTAV?
The question is whether the Alliance family would be generous in a takeover bid, to take it private? I can’t see why they would be generous, but that’s guesswork.
My opinion - BWNG isn’t really making any profits or cashflows at the moment. It’s not a good business in my view - selling things online, in order to make profits providing expensive instalment credit to customers that often don’t repay the debt. Forecasts are for minimal profit this year, and a loss next year.
Next (LON:NXT) recently said that, due to full employment, it doesn’t see any reason to expect increased defaults on its customer receivables book. But Next sells things to more affluent people, and it’s well managed. BWNG sells to people who are financially struggling (why else would they want to use expensive credit instalments?), who we know are bearing the brunt of the cost of living crisis, since food & energy makes up a much higher % of the spending for poorer households. Therefore, I would expect defaults at BWNG to significantly increase. That could easily tip it into losses worse than forecast.
I can see why investors might be attracted to the huge discount to NTAV, but that in itself is telling us something about the quality of the net assets.
Getting the Allianz (not Alliance!) issue out of the way is a relief, but it’s not a good outcome, costing almost £50m in cash. I don’t think this threatens solvency, as liquidity is fine. Although investors should carefully check the bank covenants for the secured loans, and anticipate what might happen if BWNG started reporting big losses from receivables write-offs later this year.
It’s not for me, but good luck to holders.
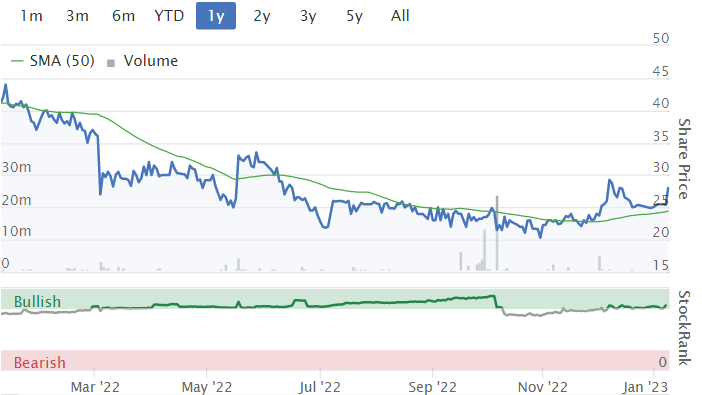
The chart's looking quite nice now, as do lots of shares, so it could be of interest to traders, as well as investors who like deep discounts to NTAV maybe?
Anpario (LON:ANP)
420p (down 12% at 12:01)
Market cap £100m
Anpario, the independent manufacturer of natural sustainable animal feed additives for health, nutrition and biosecurity, provides the following trading update for the year ended 31 December 2022.
Q4 weaker than expected.
Not helped by delays in shipments which missed year-end cut-off.
Inflation - higher raw materials & logistics costs reduced margins (but H2 improved on H1)
Reduced volumes of product sold - blames cost pressures at clients.
Costs re aborted acquisition (announced in Sept) - will be adjusted out, it was £0.2m.
Revised guidance for FY 12/2022 - revenues at least £33m, adj EBITDA at least £5m.
FY 12/2022 revenues of ££33m means that H2 is identical to H1 at £16.5m.
Adj EBITDA was £3.0m in H1, so H2 is £2.0m, a significant deterioration.
H1 gross margin was down heavily at 42% (previously 50%). So we are now told there’s some recovery in H2, but not how much.
Put that together, and it must mean admin costs rose considerably in H2 vs H1. Otherwise static revenue but higher gross margin would have led to increased H2 profits, when it's actually lower by £1m.
Depreciation is only about £0.5m pa and there shouldn’t be any finance charges, so I reckon £5m EBITDA turns into real world PBT of about £4.5m. Take off normalised future corporation tax of 25%, and we get PAT of £3.4m. Divide it by 24.0m shares, and I’m arriving at 14.2p per share. That’s well below the 20.3p that the StockReport shows for broker consensus. Even if I use 19% corp tax, it’s 15.2p EPS, well below forecast.
So this is a significant profit miss of about 25%.
Valuation - using my reworked estimates above, I’m getting a PER of almost 30 - that looks way too high.
Outlook - sounds mixed -
We expect the global economy to continue to be challenging, however, we are encouraged by the improvement in our gross margins in recent months as a result of our actions to increase sales prices and are experiencing an easing of raw material price inflation, both of which are helping the Group to rebuild its margins. We continue to invest in our global sales teams and product development which will help deliver profitable growth of the Group.
Cash is healthy at £13.6m, and could improve further from planned de-stocking. Balance sheet overall I described as superb when last reviewed here in Sept 2022 when interim results were published.
Diary date - 22 March 2023.
My opinion - I’ve never understood why this share attracts such a high valuation, and today's update strongly reinforces that view.
Profits for 2022 now look to be giving up all the (modest) growth of the last 2 years, and back to c.2019 level.
Shareholders have to hope that the company can get growth, and margins moving upwards. Without that, the current valuation doesn’t look sustainable. I think this share looks significantly over-valued right now.
Graham’s Section:
Frontier Developments (LON:FDEV)
Share price: 613.7p (-38%)
Market cap: £241m
This games designer and publisher has issued a horrible profit warning today.
Note that H1 ended in November, and its full financial year ends in May.
Summary
Frontier generated revenue of £57m in H1, a poor performance compared to prior full-year revenue forecasts of c. £135m.
F1 Manager
This is currently Frontier’s flagship title, and 600,000 units have been sold. But it hasn’t met its sales targets:
Player engagement at release in August 2022 and during the initial period after release was strong, and broadly in-line with original expectations. Unfortunately, sales performance during key holiday season price promotions fell materially below original expectations, potentially due in part to increased player price sensitivity related to worsening economic conditions.
As this is the flagship title for the company, it’s a major disappointment to see it missing expectations.
Also, I’m not sure we can lay the blame on economic conditions, as the company suggests.
The video game industry has its own business cycle that is in many ways distinct from the economy as a whole. When quality hardware and quality software are released, people tend to buy it, regardless of the latest trends in GDP.
Or as the Washington Post puts it, video games are “sort-of” recession-proof, because the value of a game, in terms of hours of entertainment, is much better value than many other forms of entertainment (e.g. eating out, cinema).
So I wouldn’t allow the economic conditions to excuse much of the performance here.
F1 Manager received good reviews from critics and from audiences alike, but clearly did not generate enough of a buzz to see it fill as many Christmas stockings as Frontier wanted it to.
One point worth mentioning is that it’s a multi-year franchise and the game will be developed and improved upon in future years. Hopefully Frontier will learn from any shortcomings the original title may have.
Existing portfolio
The existing portfolio of other titles performed in line with expectations in H1 (up to November), but then fell below expectations in December.
Economic conditions are mentioned again, with “some evidence of increased player price sensitivity”.
3rd-party publishing (“Foundry”)
In recent years, Frontier has been publishing titles for other studios, but it seems unsure if it wishes to continue doing so:
Given our mixed experience of third-party publishing in terms of financial success to date, we are assessing our strategy for Foundry in light of such experiences and competitive trends in the market. In particular, we are reviewing the return on investment achieved by Foundry.
Perhaps it wouldn’t matter too much if Frontier stopped publishing 3rd-party titles, as most of these games do look very niche and small-scale. There are no new 3rd-party titles planned for release in FY 2024.
Note that Frontier has recently bought the studio behind the successful Warhammer game it publishes, so I guess that is not a 3rd-party title any more!
Outlook
Excerpts from the outlook statement:
…the Board no longer expects to achieve the FY23 market consensus forecasts for revenue and IFRS operating profit, being £135 million and £19 million respectively.
The Board believes it is still possible to surpass last year's record revenue performance of £114 million, particularly if one of the upcoming Foundry titles is a conspicuous success. However, given the number of variables and the more challenging economic outlook, the Board's revised expectation is to deliver revenue of not less than £100 million in FY23.
What a disaster! The new revenue estimate is 25% lower than previous guidance.
Furthermore, the company explains that with only £100m of revenue, operating profit would fall to c. £2m.
My view
I’ve gone back over my notes from September, the last time I covered this stock in the SCVR.
The share price at the time was over £12.
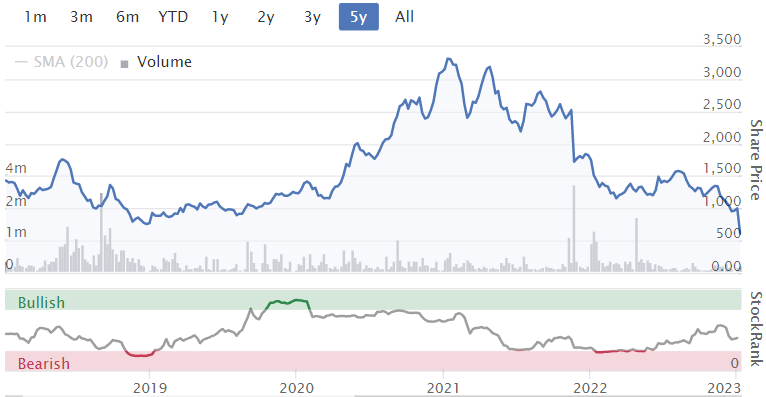
Having already fallen from a peak of £33, and with the company seeming to trade well, I viewed the company as a “weak buy”, saying “the valuation still requires the company to achieve a lot in the next two years. In particular, it requires the Formula 1 game to be a big success, and it requires a long stream of paid-for expansion packs from existing titles.”
Unfortunately, the F1 game has not been the hoped-for success yet, and the other titles aren’t picking up the slack.
So where do we go from here, with the shares down by over 80% from their peak?
Firstly, I don’t think we need to have any balance sheet concerns as the company’s cash pile at the end of H1 stands at £42.6m.
As for profitability, the company is looking for revenue growth of 5% in FY 2024. Operating leverage is significant here and I would expect that a large percentage of future revenue growth should find its way to the bottom line, particularly in F1 Manager since the base game has already been developed.
The company’s broker, Liberum, expects EBIT to improve from £2m in FY 2023 to £5m in FY 2024.
Compared to those earnings estimates, the stock might still seem very expensive at an enterprise value of around £200m. But I have to emphasise the operating leverage: each incremental £1 of revenue produces around an additional 60p of operating profit, based on the scenarios laid out by the company today.
Overall, I’m going to leave my stance on this stock unchanged. I’m broadly neutral, leaning towards a positive view. The positives:
Net cash
F1 Manager is a multi-year franchise, and can be improved over time.
The games portfolio covers a variety of genres, so there is some level of diversification.
The negatives:
The diversification achieved so far is not yet enough to reduce reliance on a small number of key titles.
The huge sales miss suggests that F1 Manager has a lot of work to do to capture the imagination of its potential fan base.
Blaming the economy for missing sales targets is a red flag in the video games industry.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Hi Paul
Thank you for your 'My top 20 small cap ideas'. Very useful indeed.
However, unless I've got it wrong (more than likely!) there's something wrong on the Wicanton row. Mid price at start of 331 doesn't compute?
Crestchic
Samson Rock have just taken their holding to over 10% .
Bit strange wonder what they are up to .
Above my pay grade .
Anyone got any insights .
Hello Planetx.
I am also wondering what Samson Rock Capital's plans are with regard to Crestchic (LOAD).
For some time now they have been mopping up any shares sold every day. I tried to find out more about them but their website requires a login.
For the takeover by Aggreko to go ahead 75% of votes must be in favour so I think if Samson get more than 25% or combine with others in a group of over 25%, they can prevent the takeover going through. Maybe they could agitate for a higher price than 401p or push for a different buyer.
I asked Peter Harris about the Aggreko offer. He told me they have a lot of irrevocables so there is a high bar for another bidder. If there was a higher bid, the board would of course consider it.
I have not sold any of my Crestchic shares so far. They are almost 20% of my portfolio.
I am also interested to hear any additional info on this.
Michael
It could just be that Samson Rock is an arbitrager, where they capture the discount during takeovers?
If you search their RNSes, they have built stakes in the last year in several acquisition targets, like Appreciate (LON:APP) as well. In Appreciate's case, they have also taken a short position in the acquirer (Paypoint).
However, Appreciate might be where they are planning to be more active, in trying to squeeze a higher offer price. They have built up a 20% stake. To my knowledge, Paypoint has only secured irrecoverable support from very few shareholders, so their 20% stake might be big enough to force Paypoint to up their offer. They have largely bought at around 5-8% discount to Paypoint's offer price.
(I hold Appreciate in the Boon Fund)
For any Team17 (LON:TM17) holders, this was released around 14.50 hrs, presumably in response to their 10% sp drop in response to the Frontier Developments (LON:FDEV) news this morning.
The Team17 (LON:TM17) price has recovered around half of it's losses so far.
Investegate |Team17 Group PLC Announcements | Team17 Group PLC: Trading Update
I think this shows just how bonkers market followers and traders are. The update said that everything was at least going to be as expected, so this means no downside to forecasts and there may even be an upside. But the lemmings dive. I wish I could take advantage and accumulate some more shares - maybe I will be able to in the near future. Opportunities come to the prepared mind. Just another example of the futility of predicting markets in the short term. Mental. Good though :-)
I think you’ve misinterpreted the price movements on Team17 (LON:TM17) . The TU is a rushed missive issued mid-session to counter a sell-off prompted by this morning’s Frontier Developments (LON:FDEV) profit warning. And it looks to have worked to settle any nerves.
I know the businesses are related but an understanding of both shows them to be quite different. Such a large reaction on the news of another's business is mental, but that's just the market. I was a little sad that I couldn't take advantage. Another time maybe.
Lord Lee's currently declared shareholdings (from HoL website)
Forgive my ignorance who is lord Lee ?
Lord Lee of Trafford,
Google his name, lots of stuff there. Also try:-
https://www.stockopedia.com/co...
Thanks
Seems to know his onions .
Holding titon holdings which is the share I’m liking these days though that’s a definite long term one to unwrap it’s value
Wasn't Lord Lee first to become an ISA millionaire? I hold Titon Holdings (LON:TON) and wish I didn't.
So it is claimed Silver Moon.
Ditto re Titon - everytime it seems to be rising towards a fair value I then realise in hindsight was my missed opportunity to exit.
He's written articles for the FT about his small cap investing for over 20 years.
These give interesting insights on his own portfolio companies (historic and current) and more generic issues, such as companies needing to publicly announce sooner when receive an approach about a possible bid (which Paul S raised concerns on just last week).
Sadly these are less frequent that they once were and appear quarterly, next one due end Feb/beginning March.
RE: Lord Lee
He must be sitting on staggering gains on some of these - I remember he bought Cerillion (LON:CER) when they IPO'd. He's held Treatt (LON:TET), Nichols (LON:NICL), Lok'n Store (LON:LOK), and FW Thorpe (LON:TFW) for years, plus Videndum (LON:VID) (Vitec, as was).
Interestingly he's moved more towards large caps in the last few years - I wonder if that's an age related thing or simply a reflection of the mispricing of some of these stocks?
timarr
Reading his articles the shift is about an increasing focus on his income needs but in companies which can delivery this and growth.
John Lee is a big fan of dividend and the three sisters: Legal and General, Aviva and MNG have provided plenty of that over the recent years.
Lord Lee has bought so many of his holdings over so many years ago that current prices may not justify.
I remember he bought Treatt and Anpario under £1 .
In his talk at Mello in November he described the Treatt and PZC at current levels attractive.
Paul - I don't hold N Brown (LON:BWNG) but what I would say is that the receivables book vs the debt is around 50% LTV and I believe that is after what they consider to be a conservative credit loss provision. In previous statements they also talked about tightening credit conditions so I suspect their loan book is better quality than it might have been previously. Certainly we have seen the book (and associated debt) shrink.
I actually think there is good value in them at the moment. My issue is more when that value becomes realisable and I think there are better opportunities out there, so my cash is unlikely to go in their direction but I think your view is over pessimistic.
Taken private is certainly possible but I suspect that if that was the plan it would have happened by now. The loan book is probably the rationale. ie they wouldn't want to take on personal liability for it when they don't have to. As very long term owners they can afford to wait.
N Brown was taken from main market to AIM market and saw the Alliance family put in over £100m. Given the age of Lord Alliance the biggest of the Alliance family share holders I would think this is just good inheritance tax planning and they remain committed to being listed.
Wynnstay
Nice little price correction continues looks like there’s a concerted seller .
At 530p that’s now below NAV , and following recent acquisitions NAV surely higher.
As acquisitions were earnings enhancing another positive .
Maybe some headwinds and maybe sone investors feel more upside elsewhere ?
Next “stop” on the decline 500p and if breaks that could slip to 450, If it gets sucked down that low it will be a great buy .
Wynnstay (LON:WYN)
I agree a great company though now sat at a loss, and having that eternal debate on whether to exit and buy back, or hold and double up.
Obviously reading on a phone so answer will not be today.
Tommy
If you still think it’s a great company then surely just sit and hold .
Pretty hard to time the market and jump in and out of AIM shares and with spreads I suggest hold unless you believe the investment case has changed .
Investing versus trading mentality .
I’m happy with Wynnstay though I’m going to have a good look at the numbers again today / tomorrow .
A lot of wild price swings in my portfolio at the moment Avingtrans, Somero, Hargreaves , Wynnstay and Sureserve are all bouncing around like crazy (most on the upswing apart from Wynnstay ) .
Luckily I added to avingtrans , Hargreaves and Sureserve at the bottom of the lows but not to trade just to top up .
I've been considering themes and how best to play them for 2023 along with a couple of examples.
Theme 1 is that there are quite a few bombed out stocks with high asset backing that haven't really recovered. Avation (LON:AVAP) is about 100p with a NAV closer to 300p and should be back into profitability. If one assumes air travel is generally robust then this should see a big re-rate at some point.
I could see Gear4music Holdings (LON:G4M) doing well in the next 12 months. It is very bombed out but probably a longer term structural winner across UK and Europe. Absolutely hated right now but often those are where opportunity lies. ie avoid the crowded trade. I have struggled to pull the trigger though as I can't decide the right time to buy. I'd like to see a small uptick in a poor retail market first but annoyingly it is up 12% today so someone has got there first.
Theme 2 : I see a number of Asset Managers in same boat. Sitting on large cash piles with good dividends and once AUMs increase with markets and inflows manifest there should be a re-rating in many of these. Average PER tends to be 12-14* across a cycle (1-2% of AUM is another metric) and when I look forward a number of AMs are sitting well below.
Theme 3 : Resource stocks still look decent to me. Atalaya Mining (LON:ATYM) has been marked down on the cost of power but this will go away for a variety of reasons (not least own solar power generation) and I can see them doubling, particularly as I like copper as a longer term commodity market anyway.
Petrotal (LON:PTAL) appears to manage the geo-political environment in Peru very well and as I see oil in the $80-$100 p/b range for the foreseeable future at a production rate of 22,000 bopd this could have net cash close to its market cap over the next 18 months. Expect dividends too.
Edit - just realised I meant to post this in a different thread but will leave it here too. I'd be interested to see peoples thoughts on overall themes rather than stock specific.
Just a personal experience if it could add some value: as someone who has been a client of Thomann throughout the years (I reckon I made more than 10 orders in total) I struggle to see how G4M could increase its market share substantially in the long term with such a tough competition. My experience with Thomann has always been top notch: fast shipping, excellent after-sales service, huge catalog, competitive prices (including own brands with great value and ridiculous prices - ideal for beginners). The level of automation in their warehouse is also quite remarkable, I see them as the Amazon of music equipment. In terms of revenue Thomann is about 10 times bigger than G4M's.
Still, you won't find everything in Thomman, I ended up buying guitars in andertons.co.uk I couldn't find elsewhere, so maybe the market is big enough and it's growing fast enough for other participants to flourish, I don't know.
Gear4music Holdings (LON:G4M) is now up over 20% today. Was there a tip in the weekend papers?
Frontier Developments (LON:FDEV) has deep problems ... IMHO
Fundamentally they have mediocre launches pretending to be AAA.
1) they launched games that are behind the curve. Shows bad management, tech and creative people - can't create AAA, but management forced to release it.
2) They will struggle to sign up new blockbuster franchises. No-one wants to get a bad game linked to their brand. They are done until they get something 10/10.
3) Talent will move/be poached selectively:
a) With only 200 staff - that isn't much to "pull one out of the bag". This will be heavily dependant on the 10-15 key people.
b) This is a "hot" or "not" industry with a globally mobile workforce and reputation is key.
c) Options will be underwater - with a long time before they look like they might recover, so cut losses for a sign on bonus elsewhere.
d) Bonuses: "we can't afford to pay bonuses, even if you personally performed well, Sorry!".
e) New cost cutting initiatives will take flesh with the fat.
f) Even paying £1m to acquire each of the top 10 -20 people is a lot cheaper than buying the whole package in a takeover.
4) Usual delays and cancellations in development - well to be honest this is in every studio.
5) Can Elite go anywhere? I think they cancelled further Odyssey dev in Mar '22
6) Top personal (inc founder) change Summer last year - loss of vision and execution ability (new CEO was creative director over last 10 years - which just get to show failure gets rewarded!)
7) Acquiring brand and talent after failing to execute internally. (Warhammer)
8) and obviously the general economy and cut back in discretionary spend will hit them
It's got a way to go before being a T/O target ... £400m MCap to get up to £20m profit company but now with a damaged brand. That isn't good value.
Franchises may have exit clauses in the event of a takeover, reducing the value further.
I can't see growth or positive news from this company in the next couple of years as they retrench.
I think this will slide a lot further. 6 months time we'll see another crash. I think we'll now see £3 before £10.
I agree. EBIT of 5m FY'24 against a current market cap of 200m, 40 times!!
Even half that would be generous! On my short list...
No position.
Regards,
Frontier Developments (LON:FDEV)
Shocking to see this update. It seems the company has not learnt from past mistakes. Back in 1995 David Braban released the title Elite Frontier-first encounters which was full of bugs and later was pulled from sale. David Braban took GameTek to court saying the company forced an early release of the game before it was ready. This was later settled out of court. So who will be blamed now for the bugs in their latest game F1 and also for the latest released Elite game?
Personally I may be tempted to buy at a lower price but for now, all I see it doing is a slow decline in the sp. I can see this dropping over the next 6 months to about 350p. I see no reason to catch a falling knife atm and why would anyone really want to buy into it until a positive update is released.
Anyone got thoughts on the Tortilla Mexican Grill (LON:MEX) update?
My thoughts: revenue growth is great and clearly they have been able to create a good brand and formula for site rollouts. But company needs to demonstrate they can turn adjusted EBITDA (£5mln) numbers into similar (or at least significantly above zero) net profit. Although Jan-23 recommends trading is in-line with expectations; significant headwinds exist (food inflation and utility cost) and current working capital / liquidity position is precarious.. and the company could quickly have to reassess its growth plan if key assumptions change. It would have been nice to hear about CFFO / FCF / cash position in the update. One benefit is that Tortilla products are priced low: so may benefit from customers switching to lower cost options or they may have the ability to raise its prices.
In summary, good to hear that they are still on their growth path but there are a few too many uncertainties (company profitability, macro picture) to enable an investment at the moment.
Paul, just wanted to second the praise for your ideas list. With a full time job the hardest thing about investing I find is just getting and maintaining a watchlist so this is great for my to then do my own research on :-)
Nanoco (LON:NANO)
The announcement today states
"The gross settlement value should be expected to be towards the lower end of the range of expectations for a successful jury trial outcome as previously guided by the Company."
I can't for the life of me find any previous guidance other than to say they can't provide guidance due to uncertainty. Is anyone else aware of guidance issued by the company when they were expecting a jury trial outcome?
In case anyone else is interested, I sort of have an answer. I emailed investor relations (MHP) and they got back to me extremely quickly (points for that, at least). They are saying that the guidance was "a multiple" of Nanoco's market capitalisation at the commencement of litigation in Feb 2020.
Market cap on 17 Feb 2020 was about £60m. I'm assuming we can take "lower end" of "a multiple" as being 2x market cap., so about £120. Nanoco's market cap today (after 20% fall) is £180m.
Interesting, but certainly risks. Samsung may just be playing games, although the momentum in the litigation was certainly with Nanaco.
Additionally a more cynical reading of "a multiple" could be 1x.
Will be interesting to see how it plays out I hold some from my early investing days when I used to fall for these 50-1 shots.
Personal feeling is given near zero revenues and fact its loss making theres at least 100 mil hope value in the price already and the backers are on 50% of any payout up to x (and no one seems to know what the x threshold is).
So i am thinking if the payout isi n the 100-200 mil area once you knock off the hope value already priced in and the backers taking their 50% we could be back to 30-35p level.
Its interesting on the advfn board some staggering examples of confirmation bias by some of the biggest believers on the run up to the recent announcements and even now they are trying to spin a positive outcome to themselves.
There will be some absolute scenes on their if this does end up in the 25-40p pay out range.
Morning Paul, happy Monday.
Can I just say your level of output of reports/analysis is ridiculous (in a very positive way). The amount you get through, and the extra work and information/analysis, above the SCVRs, produced over the weekends is incredible.
Cheers, we all owe you several pints, and one day I intend to actually pay that debt.
Chris
That's very kind, thanks Chris!
Yes, we're cooking on gas at the moment! Hopefully this is making up for my lamentable performance in Sept 2022 in particular. Swings & roundabouts hopefully :-)
This is an older article but thought I would share as I know a number of readers have shares in the likes of M P Evans (LON:MPE) Anglo-Eastern Plantations (LON:AEP) and the like. (I don't Hold)
PARIS, Dec 8 (Reuters) - The share of palm oil in biodiesel and in food in the European Union is expected to fall significantly within the next 10 years, leading to a sharp drop in imports, the European Commission said on Thursday.
In its 2022-2032 Agricultural Outlook, the Commission projected palm oil would account for 9% of total biodiesel output by 2032, down from an average 23% for 2019/2021.
Under the EU's renewable energy directive, palm oil-based fuels, accused to be linked to deforestation, are to be phased out progressively by 2030. The move raised outcry from the world's two largest palm oil producers Malaysia and Indonesia.
Thank you for sharing
I am an ex-holder of Anglo-Eastern Plantations (LON:AEP)
Paul can you look at Keller (LON:KLR) reported fraud in 3% of revenue in Australia affecting past results but future outlook and dividend all ok, a buying oppertunity?
Although I sold my shares in Keller years ago, they have always remained interesting to me, but this announcement is, imo, very disappointing for a company which has an ex finance director as CEO (iirc).
I'm aware of two similar frauds in Australia, one of which was a very major contributor in the downfall of John Mowlem about 12 years ago, I believe. That particular situation with a Mowlem Australian subsidiary was pointed out to me by my brother after his dealings with them on behalf of one of their subcontractors, about 18 months before Mowlem senior UK management spotted it. Surprising failure, I would think, on the part of senior management to investigate properly an ever widening gap between declared figures and cash generation.
My morning smallcap tweet: Line of Booty
Devolver Digital (LON:DEVO) Induction Healthcare (LON:INHC) Anpario (LON:ANP) Nanoco (LON:NANO) Kromek (LON:KMK) Batm Advanced Communications (LON:BVC) Deepverge (LON:DVRG) Kazera Global (LON:KZG) Venture Life (LON:VLG) Iofina (LON:IOF) Poolbeg Pharma (LON:POLB) Renalytix (LON:RENX) N Brown (LON:BWNG), Tortilla Mexican Grill (LON:MEX), Osirium Technologies (LON:OSI)
◄Devolver Digital (DEVO)► guides FY-Dec rev in line but adj EBITDA $20m to $22m, below expectations (whose?). Also write downs of capitalised development costs, and acquisition IP and goodwill. Outlook "negative global economic outlook and reduction in consumer spending to continue into 2023, which may affect sales volume" [SP=65 Cap=278m]
◄Induction Healthcare (INHC)► CEO resigns, becomes adviser. "Board is clear on the need to tightly manage costs and execute a plan ensuring the Group is correctly sized and on target to deliver a cash breakeven position during FY24." [SP=22 Cap=21m]
◄Anpario (ANP)► warns FY-Dec only £33m+ and adj EBITDA £5m+. Blames CHina covid, some port shipping delays. Customers tightening belts. Outlook: "encouraged by the improvement in our gross margins in recent months as a result of our actions to increase sales prices and are experiencing an easing of raw material price inflation, both of which are helping the Group to rebuild its margin". [SP=462 Cap=114m]
◄Nanoco (NANO)► more on mooted settlement of litigation with Samsung. "Gross settlement value should be expected to be towards the lower end of the range of expectations for a successful jury trial outcome...likely to be a one off payment." [SP=56.11 Cap=181m]
◄Kromek (KMK)► repeat order, worth $0.8m, from a US government customer for its D3S ID wearable nuclear radiation detector. [SP=10 Cap=44m]
◄BATM Advanced Communications (BVC)► $26m government cyber security order, to be delivered over 5 yr max. [SP=31 Cap=137m]
◄DeepVerge (DVRG)► guides FY22 rev c.£17.2m, slightly below market expectations. Restructuring expected to deliver considerable cost savings in 2023 of up to £2m. [SP=1.9 Cap=14m]
◄Kazera (KZG)► further payment from Hebei Xinjian Construction of c. $716k. A further $1.9m is expected to be paid by Xinjian by the end of Jan. [SP=0.85 Cap=9m]
◄Venture Life (VLG)► licensing of an internally developed oral care range to an existing long term customer and that it has signed a further distribution agreements for Gelclair & Pomi-T. [SP=34.22 Cap=44m]
◄Iofina (IOF)► guides production of 282MT vs f/c 255-275MT. Iodine spot price moved from $50/Kg at the start of the year and remained at approximately $70/Kg towards the end of 2022. [SP=22.64 Cap=42m]
◄Poolbeg Pharma (POLB)► initial trial analysis shows POLB 001 "demonstrated a marked reduction in both systemic and localised inflammatory response compared to volunteers who received placebo". [SP=7.3 Cap=37m]
◄Renalytix (RENX)► agreement with U.S. Veterans Health Administration to install the KidneyIntelX solution inside their Cloud Infrastructure and interface it with the VA Electronic Health Record Systems.Will be implemented on a phased basis over c. 18-months. [SP=94.9 Cap=82m]
◄N Brown (BWNG)► settles ongoing legal dispute with Allianz Insurance re claim issued against subsidiary JD Williams. Latter will pay the Insurer £49.5m. Insurer claimed over £70m but co provided only £25.5m for it. Co has sufficient liquidity to pay. [SP=26 Cap=117m]
Frontier Developments (LON:FDEV) Mkt Cap £393m until 8am, then possibly much lower - bad profit warning. Fc Revs down from £135m to £100-114m. Ouch. Effect on profitability even worse - down from £19m to between £2m and £10m.
Update - down >40%
“We’ve gone from the low-return world of 2009-21 to a full-return world, and it may become more so in the near term. Investors can now potentially get solid returns from credit instruments, meaning they no longer have to rely as heavily on riskier investments to achieve their overall return targets. Lenders and bargain hunters face much better prospects in this changed environment than they did in 2009-21. And importantly, if you grant that the environment is and may continue to be very different from what it was over the last 13 years – and most of the last 40 years – it should follow that the investment strategies that worked best over those periods may not be the ones that outperform in the years ahead.
That’s the sea change I’m talking about.”
Howard Marks - oaktreecapital.com - it’s well worth 15 mins of your day.
Happy hunting.
Thank you, will read later
I guess what is a return, so getting 3-4% for a 1 year bond versus 1% a year ago is good news to savers and to most the will think that is good, though when last looking ISA rates were still a lot lower (especially when transferring). My wife who is cash heavy (she equates buying shares to going to the local bookies and putting money on the 3:30 at Doncaster Races whilst blindfolded and wearing ear muffs), this is a very good thing as we move products over at expiry.
But when some of our main costs are going upwards at >10%, food and energy in the day to day bucket, petrol has come down a bit but still that gets eaten very quickly, and when you think about what university, weddings (kids not ours), care costs are going to be like it makes for a more nervous outlook.
As for investment yes I hold some fixed income things already and might slowly increase this year as a structured approach.
Tommy