Small Cap Value Report (Mon 9 Nov 2020) - EKF, GYM, WGB, CWD, OTB

Good morning, it's Paul and Jack here with the SCVR for Monday.
Mello
This evening Jack will be joining the panel for Mello BASH (Buy, Avoid, Sell, Hold), with 5 new investment opportunities up for discussion. It’s part of the popular virtual Mello Monday event that runs from 6-9 pm and includes a variety of insightful presentations.
If you are interested in attending, Stockopedia subscribers can get 50% discount from their tickets by using the coupon code MMStocko21 at the checkout. You can register here or see the full lineup here.
Pfizer vaccine news
Breaking News - I’ve just heard on the BBC TV that Pfizer has announced positive results from its covid-19 vaccine trial, with c.90% effectiveness in preventing the disease apparently. It is already in production, with a stockpile being built up, to hopefully be released once it finishes testing, and has hopefully got all the necessary regulatory approvals.
Coincidentally, I commented here last week, that I think we’re overdue another rally on shares that have been hit hard by covid. The market is meant to look forwards 6 months, and it seems that we should have made substantial progress against covid in 6 months’ time, with better testing, and vaccines possibly. We’re spoiled for choice in terms of bargain small caps that are priced almost to go bust, yet have strong recovery potential. I reckon a lot of money could be made from buying the right shares around now.
Also look at all the takeover bids happening now. That’s another indicator that there are pockets of value in the UK market. I do think small cap investors generally seem to be far too cautious at the moment, not looking beyond the current situation of temporary lockdown & rising covid cases. There’s a good chance that this thing could be under control quite quickly, which means we’re being offered some terrific bargains by Mr Market. Sorry if it’s unfashionable to sound upbeat, but rightly or wrongly, that’s how I see things right now.
Wow - The Dow futures are up c.1300 points to 29,600, and FTSE 100 up 240 pts to 6140 (around noon). It will be interesting to see if those levels stick, or if we’re just seeing shorters carried out on a stretcher?! Clearly the market is taking this news from Pfizer very positively.
.
Agenda
Here are today’s most interesting small cap updates that we're writing about here;
Ekf Diagnostics Holdings (LON:EKF) - Trading update (Jack, done)
Gym (LON:GYM) - Operations & trading update (Jack, done)
Walker Greenbank (LON:WGB) (Paul holds) - Licensing agreement with NEXT (Paul, done)
Countrywide (LON:CWD) - Statement re possible offer (Paul, done)
On The Beach (LON:OTB) - Full year trading update (Paul, done)
Smiths News (LON:SNWS) - Refinancing (Paul, to do)
Dignity (LON:DTY) - Trading update (Paul, to do)
.
Timings - Jack has done the morning shift, I (Paul) will be working this afternoon, so 4pm finish.
** This section written by Jack **
EKF Diagnostics Holdings (LON:EKF)
Share price: 78.75p (+1.61%)
Shares in issue: 454,993,227
Market cap: £358.3m
(Jack writing)
The strong Ekf Diagnostics Holdings (LON:EKF) share price sees the company enter mid cap territory in recent weeks, so congrats to holders on spotting the opportunity and the outstanding performance. The shares were as low as 17p in March but are now pushing 80p, driven in part by booming COVID-related business.
EKF is a global medical manufacturer of point-of-care (POCT) devices and tests for hemoglobin, glycated hemoglobin (HbA1c), glucose and lactate. It focuses on three core areas:
- EKF Point of Care (POC) analyzers are used in doctors' surgeries, clinics, hospitals and laboratories to provide fast, accurate, and affordable results.
- EKF Central Laboratory division manufactures reagents for use in hospital laboratories.
- EKF Life Sciences specializes in producing enzymes and contracted custom products for use in medical diagnostics, pharmaceuticals and industry.
It’s a sweet spot right now. You can clearly see the uptick in buying volume this year - a sign that the investment case has been transformed.

Today’s trading update sees the shares up another 1.8% to a new all-time high of 78.75p, so let’s see what it’s saying.
The group kicks off confidently with: ‘Full year performance to further exceed market consensus’ thanks to a record October and high expected orders for the remainder of the year. Market expectations have already been revised upwards several times this year.
Trading has improved ‘significantly’ in the core business in the final quarter, thanks in large part to continued orders for the PrimeStore MTM COVID-19 sample collection device.
This device was invented in 2006 in preparation for a worldwide pandemic and is designed to de-activate pathogens rapidly and stabilise the RNA for up to four weeks with no requirement for cold storage.
It also allows samples to be tested by a greater number of laboratories, as the handling risks for the deactivated virus are reduced.
Conclusion
It’s a short but confident update and confirms EKF as a company worth looking into more closely.
Expectations are currently set at £60m for revenues and adjusted EBITDA of £23m. The group suggests it will be comfortably ahead of these. Add 10% to both - which is hopefully very conservative - and you get revenue of £66m and adjusted EBITDA of £25.3m. That values EKF at 5.4x sales and 14.2x adjusted EBITDA.
No doubt what holders are hoping is that the company can blow current estimates out of the water.
We can see that forecasts have been upgraded considerably - when that happens, there’s always potential for a further beat as analyst estimates can prove conservative in these instances as they ‘anchor’ to obsolete historic numbers.

And at this valuation, EKF does probably need to confirm blockbuster trading figures. The statement today is so brief that it’s impossible to have an informed view on that right now.
The company has net cash on the balance sheet and looks in good shape but the forecast PE ratio (which can’t be trusted given the ongoing growth) puts EKF at 41.2x earnings. If top line growth can exceed expectations and translate into margin expansion, then this could fall in short order.
Primestore MTM has recently been successfully evaluated by Public Health England in a peer-reviewed comparative study, which concluded it was the only commercially available sample collection device where no residual virus was detectable out of 23 tested.
And of course global demand for the PrimeStore MTM sample containment device has increased significantly due to COVID-19.
We all know governments around the world are throwing silly amounts of money at COVID testing right now. So if EKF has one of the best devices on the market, there’s every chance it can continue to surprise to the upside.
At 79p I’m priced out currently but tempted to do more research - there is always the possibility that current forecasts are just way off base.
** This section written by Jack **
Gym Group (LON:GYM)
Share price: 139p (+1.31%)
Shares in issue: 165,941,580
Market cap: £230.7m
Gym (LON:GYM) operates 183 low cost gyms nationwide.
At some point winning Leisure and Retail stocks will have an almighty comeback. Not right now, though, and in the meantime it can be stubbornly difficult to find stocks in the sector that are marked down enough to provide sufficient risk:reward.
A couple of pub groups perhaps, Restaurant Group if it makes it through, and I’m seeing a few property companies like Town Centre Securities (LON:TOWN) trading at steep discounts to net asset value. But then there are some other operators whose share prices have not sufficiently adjusted to the new reality, IMO.
I’d put the Gym Group in the latter category for now - a great roll out story in normal markets - but one whose share price does not reflect the risk of prolonged trading disruption or a possibly permanent shift towards more at-home exercising.
Counter arguments are welcome, but even if that’s an overstatement and Gym Group immediately reverts to 2019 trading levels in 2021, that would still price it at 21.5x normalised EPS and 1.5x sales.
The update confirms that GYM closed its 167 gyms in England on 4 November 2020, following the introduction of the 4-week lockdown announced by the UK Government on 31 October.
The Company's three gyms in Wales closed on 26 October as part of a 2-week lockdown announced by the Welsh Assembly but its 13 gyms in Scotland remain open.
It expects monthly cash burn during closure to be around £6m.
Net debt actually reduced in the period to £32m ( 31 July 2020: £35.7m) versus £100m of total borrowing capacity. So it looks like close to a year’s worth of liquidity. GYM is also in discussions with its lending banks about resetting future covenant tests.
In addition, £4.5m of the £9.4m of rent deferred from H1 2020 has now been repaid.
What’s more, GYM traded profitably and cash generatively after re-opening, which shows that it can bounce back quickly.
Conclusion
New sites are expected to open in Q1 2021 and the group ‘continues to see an opportunity to access attractive potential new sites and is building a pipeline for new openings in 2021.’
On balance it looks like GYM is in reasonably good shape - certainly not in panic mode, although circumstances are far from ideal. It’s likely that the sites that do go bust are independents, while larger entities with better access to capital should be able to protect themselves and invest for the recovery.
These are exceptional times though, and it is uncertain to what degree the market will recover. Have people’s habits changed for good? Maybe we are a nation of runners and cyclists now. Or maybe those concerns are overstated.
Given ongoing uncertainties, I would want a bigger margin of safety here.
.
** This and all subsequent sections written by Paul **
Walker Greenbank (LON:WGB)
Share price: 68p (up 12%, at 12:36)
No. shares: 71.0m
Market cap: £48.3m
(Paul holds)
Walker Greenbank PLC (AIM: WGB), the luxury interior furnishings group, is pleased to announce that its Sanderson, Sanderson Home and Morris & Co brands have signed a licensing agreement with major retailer NEXT for an extensive range of clothing, homeware and accessories for an initial term of two and a half years. This agreement follows the successful collaboration between NEXT and the Company's Scion brand announced earlier this year.
With the Morris & Co brand, NEXT will produce apparel, including womenswear, men's shirts and childrenswear, with an anticipated launch date of June 2021….
All of the products under the licensing agreement are expected to become available, once launched, both online at NEXT.CO.UK and in selected NEXT retail stores.
Simon Wolfson, NEXT Chief Executive, said: "We are delighted to be working with Walker Greenbank to develop new products for these wonderful brands. We believe that the combination of their exceptional design work with NEXT's product development, online and retail infrastructure can deliver some new and very exciting product ranges."
My opinion - clearly this is good news, but we’re not given any financial details, so at this stage it’s impossible to work out how this might help WGB’s future profitability.
Some clues - I like the choice of wording for an “extensive range of clothing, homewares, and accessories” - suggesting that this could be a decent sized deal.
Initial term of 2.5 years suggests it could become an ongoing partnership, long term, if it works. It also suggests there’s significant commitment to the ranges, because if it was just a trial, then it would only be for a few months, or maybe one year.
“Selected” stores, gives us no indication of how many stores will receive these ranges, nor how they are deciding which stores to send it to.
Overall then, a lot of question marks, we’ve no option but to wait until next summer, and see how the new ranges perform. Plus monitor broker notes, who are given more detail by companies.
Two points from me;
- This deal highlights the value of WGB’s extensive, historic back catalogue of designs & prints, especially classic arts & crafts styles. I’ve always thought these have considerable value, not reflected in the current valuation.
- The obvious next step would be for NEXT to buy WGB, to fully exploit its valuable brands & back catalogue. So there must be a higher chance of a takeover bid, hopefully at a decent premium.
I think there’s considerable potential in WGB, and to my mind, the shares still look cheap (I hold).
.
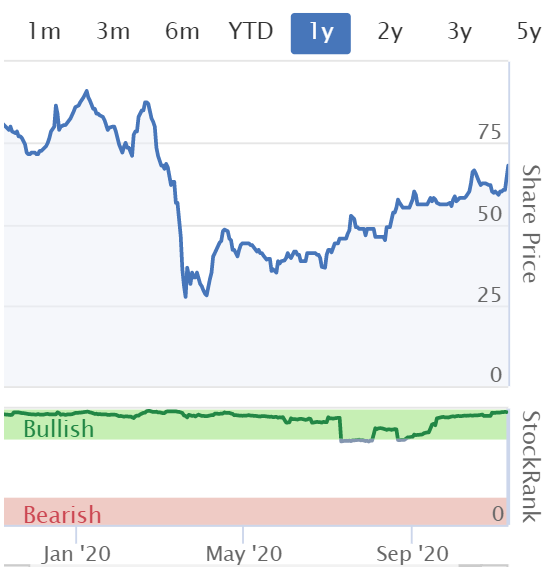
.
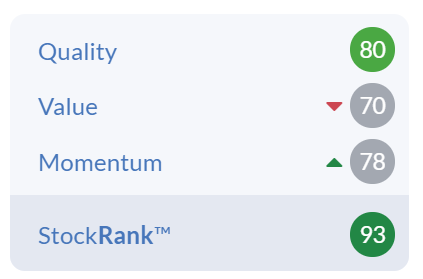
Stockopedia likes it too, and the broker forecasts seem to have been updated, so we can probably rely on this;
.
Countrywide (LON:CWD)
Share price: 202.3p (up 40% today)
No. shares: 50.6m
Market cap: £102.4m
Statement re Possible Offer and Postponement of General Meeting
Countrywide plc ("Countrywide" or the "Company") has received an indicative approach from Connells Limited to acquire the entire issued and to be issued share capital of the Company, in cash, at a price of 250 pence per Countrywide share (the "Approach"). The Approach is at an early stage and Connells Limited has indicated that any offer is conditional upon, amongst other things, completion of confirmatory due diligence and the recommendation of the Board of Countrywide.
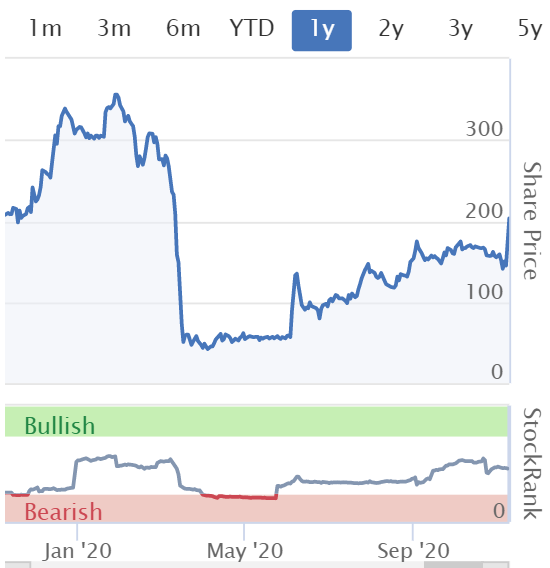
Things are certainly getting interesting here! I last reported on Countrywide with its proposed refinancing with Alchemy, at 135p per share, here on 22 Oct 2020. Clearly the takeover approach today from Connells is much more attractive, at 250p. Although obviously with a takeover, the upside is capped at your exit price. Whereas with a refinancing, the longer term upside could be greater. A bird in the hand, and all that?
The meeting to approve the previous Alchemy deal has been put on hold, which makes sense if a better alternative is available, and the company is consulting with shareholders. Generally, private investors are frozen out of these things, but there’s no reason why you cannot write to, email, or telephone the company. I think letters addressed to the Chairman are best, because they receive so few physical letters these days, it’s a very good way to get through to the key people.
My opinion - there’s not really a lot I can add to this. The company now seems to be in play, and we’ll just have to wait and see how events pan out. It's an interesting reminder that having a weak balance sheet need not be an impediment to bidding interest. It could even make companies more vulnerable to opportunistic approaches?
.
.
On The Beach (LON:OTB)
Share price: 330p (up 24% today, at 14:17)
No. shares: 157.4m
Market cap: £519.4m
On the Beach Group plc (LSE: OTB.L), the UK's leading online retailer of beach holidays, today provides an update on trading for the 12 months to 30 September 2020 ("FY20") ahead of announcing its Preliminary Results on 10 December 2020.
There’s been a stunning rebound in share price in the last week, particularly today, after the positive-sounding news on Pfizer’s covid vaccine;
.

.
We’re seeing some staggering, coiled spring type share price surges today, for travel, hospitality & retailing shares, on the Pfizer vaccine news. I’m also noticing some plunges in WFH shares, like Loopup (LON:LOOP) (I hold). It’s really surprising that such big moves are happening so suddenly, on news that isn’t exactly unexpected - the big pharmas have been saying for a while that promising progress is being made.
Also, I see that some of the fashionable covid testing shares are down by about a third today - e.g. Synairgen (LON:SNG) , Novacyt Sa (LON:NCYT) , Avacta (LON:AVCT) - I hope readers trading these things had stop losses in place.
Prior to covid, OTB seemed to be growing revenues strongly, but profitability levelling off;
.

.
Here’s what OTB says today, summarised by me;
Year ending 30 Sept 2020
- Short-lived boost to trade over the summer
- New restrictions on travel, and winter seat capacity “significantly reduced”
- Booking volumes down 75% in Q3 (April, May, June), and 53% in Q4 (July, Aug, Sept)
- Adjusted profit before tax is around breakeven for FY 09/2020 - not too bad, in the circumstances in my view
- Cancellations - worse than expected over the summer, at >90% - similar rate expected over the winter
- Exceptional costs are large: £10m in H2, taking it to £45m full year
- Customer funds fully ring-fenced - I very much like this, as it’s more ethical, and is a strong selling point, it also means OTB is well set up to survive downturns when it has to refund customers
- Substantial delays in getting refunds from airlines
- Cash & liquidity looks fine: £44m cash on 6 Nov, and undrawn £75m credit available
- Cash burn is up to £2m per month (at zero revenues) - which looks easily survivable - no insolvency risk here, in my view
My opinion - this travel company has got through the crisis so far, with plenty of liquidity (following a fundraising earlier this year).
Investors are now clearly looking beyond covid, to a resumption of the travel/holiday sector in 2021, probably with a lot of pent-up demand, I reckon.
With the share price now back up to nearly its pre-covid level, I don’t see enough upside to want to buy OTB.
I see much better upside elsewhere (my top pick for travel-related companies is Saga (LON:SAGA) which is now one of my largest positions. Once its 2 brand new cruise ships sail again, they’re forecast to generate £40m p.a. EBITDA each. Plus the resumption of its travel agency business, on top of the profits already being made by its insurance division. The current mkt cap makes no sense at all to me (i.e. far too low), since it’s just been refinanced). That one looks like a potential long-term 5-bagger to me, whereas OTB doesn't.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

166 comments
After digesting some of the recent news regarding the vaccine, it looks inevitable that there will be a priority order for the treatment. This is some basic information from gov website:
This interim ranking of priorities is a combination of clinical risk stratification and an age-based approach, which should optimise both targeting and deliverability. A provisional ranking of prioritisation for persons at-risk is set out below:
Therefore this vaccine could be double catalyst for Saga (LON:SAGA) as I imagine majority of their travelling customers will be fall under some of the first priority groups to be vaccinated. Obviously this is will take a lot of time to work through the system, but it looks like their share price could re-rate quicker than some sectors i.e. nightclubs.
The question is - are cruises still risky economically for Saga, if they can't vaccinate their staff?
Presume even if all their passengers are vaccinated, but crew aren't. If there is an outbreak, then the cruise is cancelled - as staff will have to isolate, who will serve the passengers! That would be refunds all round.
Plus even if all passengers were vaccinated, as long as staff have the virus, because the vaccine is only 95% effective, then 5% of passengers would still be at risk of catching COVID
I'm sure cruise liners, can arrange for staff to be vaccinated, if they have not been already.
If the passengers have been vaccinated, then the virus will be about as deadly as flu?
One issue could be visiting ports if there are cases on board. Many countries will not have had the vaccine until later than the UK or some other western countries.
Why can’t the crew be vaccinated?
One big plus for Saga compared with the likes of Carnival (that bb posters sometimes ignore) is that Saga also have their insurance business and where they led the way with innovative and successful (so far) 3 year fixed price policies, and a big general travel business. So it is not dependent just on their 2 new state of the art cruise ships. But demand for those, with forward bookings is large, and during 2021 the survivors in the Travel and Hospitality sectors should be envisaging a much brighter future.
The share prices have to some extent anticipated that recovery and hence some have rocketed already, but arguably Saga has lagged so far. Potential for a significant relating?
Who would have thought that Boohoo (LON:BOO) is now seen as a covid play. Lots of crazy moves today..mostly on AIM.
Wonder if price moves were in part triggered by inability to trade on various sites. AJ BELL a complete disaster once the vaccine news broke. Amateurish.
Wow. I read on here a a good few comments about bombed out sectors could be ripe for an upswing. I particularly liked Paul's write up on saga. I actually made a list yesterday that included jet 2 and saga to do a bit of digging. Get home turn my computer and boom! Unbelievable moves today. I avoid all news sources recently as I just can't take the misery so I didn't hear the vaccine news.
Question is what now. As gromley says above some of this seems to be an overreaction in my view.
I found this on line
https://www.sciencemediacentre.org/expert-reaction-to-pfizer-and-biontech-reporting-interim-results-from-phase-3-covid-19-vaccine-trial/
The main points seem to be
the large majority of us even rolling into next summer won't be vaccinated. So lockdowns, WFH extended well into next year.
There are still large question marks over it's effectiveness on the older age groups.
Will general populations be willing en masse to actually take the vaccine.
This vaccine requires very cold storage (-70c) which apparently many uk health centres don't currently have a facility to do on this scale. (Possible picks and shovel investment here?)
Length of protection unknown.
2 doses are needed. 1st one the another 2 weeks later and immunity a week later - so a month here.
This is hot off the press, so early safety evaluations are due the end of this month and long term evaluations take 2 years. Obvious issues could arise here.
On the whole I personally think this is very encouraging and my guess is this is a turning point in the whole saga. Apparently if this vaccine works others have a high chance too and may be easier to make/transport. The question is what does this mean for share prices and the economy. Paul Are you still looking at saga today thinking its cheap. It seems to me a lot of these companies are going to have to go through an extended period reporting negative numbers for a good few quarters yet. With the expected market gyrations following vaccination news flow. What happens if negative side effects are found etc.
I do think some uk shares look good value at the moment e.g. compass group, jet2, Saga if you look long term.
Would like to know other readers thoughts and look forward to Paul and jacks scvr tomorrow.
Yes, I think SAGA could be a 5-bagger from here, once its travel division & owned cruise ships are operating again in 2021, and the rest of the business benefits from new mgt back to basics approach. This is a tarnished, but incredibly valuable brand. The insurance division is highly profitable.
Debt is fine - the c.£550m cruise ship debt costs 4.3% pa and has covenant waivers until June 2021, I cannot see any reason why that wouldn't be extended. Ships should generate £40m EBITDA pa each, there are 2.
Recent fundraising paid off most of the bank debt. Plenty of liquidity.
What's left? a £250m bond, which is cheap, and not repayable for several years. SAGA reckon they can pay it off from cashflows.
I see SAGA worth 500p+ based on likely earnings in future, once travel resumes.
The founder's son paid 405p in new money for most of his recent investment.
It's a steal, in my view. DYOR obviously, as always.
Best wishes, Paul.
I hear what everyone's saying but I managed to complete 4 buys today on HL without any problem. Mind you they
were all timed between 11.00am and 11.30am so I guess I got just under the wire.
iDealing also running pretty normally all day.
Not problems with HL after 1.50pm upto 16.20, only share I could not get a trade price but even that was available a few minutes later.
Have had no problem myself logging in to HL and using the website today. I didn't attempt to trade.
I was alright too until about 14.00. I did two trades first thing and all fine. It reminded me of Brexit day.
Thank you FREng,my wife has just popped out will refer her to your post when she gets back,thanks again very informative,.
Wow, some of these drops seem like further opportunity. LoopUp especially, considering it's not entirely a Covid share. Ways of working have changed and will be here to stay at least for most of 2021 even if this vaccine is entirely successful. Secondly, most companies will now definitely consider working with reduced office capacity as benefits and ability to work remotely has already been demonstrated.
Keeping a clear mind and reverting back to the initial investment thesis will help - I think this is a top up opportunity if anything else!
ATB
P.
x-o worked
iweb - didnt work - pretty bad
"I hope readers trading these things had stop losses in place"
I don't use them (or at least the automated variety) as, once when I did, the share price crashed down so quickly that my holding was sold at way below the stop price and at what ended up being near the bottom.
With the way things have gone today I wonder how many suffered similarly?
i wonder if pre set stops and buy orders will work today ??
I would be causing a lot of trouble for HL if mine didnt.
Just to be crystal clear, I talked about people TRADING, not investing.
Personally I never use stops on my investments, just on occasional (usually terrible!) trades :-)
I try not to trade on days like this with all the short / long panic selling. But I cant even get into the HL site to see where I am.
Same with IWeb and AJ Bell for me today - total gridlock and collapse - very frustrating...
Pretty shocking that HL cant even open. interactive is open.
Hi kgb1953 - Re HL Trading - I think we should blame everyone TFH today rather than WFH!
Thats Trading and Working From Home to make it clear
I managed to log into HL Ok all afternoon, however response times and data updates were abysmal. Interactive charts frequently impossible
It will be interesting to see days Total volumes compared to a "normal" day
Same for ii and Halifax. Are there any websites that have been accessible?
ii is working for me. Just bought some £OCDO
AJ Bell not accessible. I think a class action lawsuit is needed against AJB. When this happened in September they reassured me the problem with site accessibility was management top priority.
iDealing has been up and running all day, Occasionally quotes were a bit mean but I guess the MMs were having to work hard to get their profits.
got on Halifax about 4pm poor wide spreads too
IG works fine - it does take a few seconds to get a quote (which usually is instantaneous) but other than that you can trade OK.
Halifax on the other hand is 'currently unavailable'...
Yeah same iweb issues here
I logged into iWeb at 13 14 today anxious to sell one of my holdings. It took dozens of attempts resulting in a number of variations of "service not available" messages until I eventually sold at 14 17. Comments on HL, ii and AJBell on here suggest all were in the same difficulty.
No problem with HL, I managed to do a trade.
Same here HL site not working
What a terrible state of affairs
I will not be using them anymore
I would just like to make my experience with OTB available to investors, this is not Coniston's views but my wife's,
I booked a full package holiday on behalf of my son and his 8 friends to go away after doing their A-Levels as an extra protection I paid the deposit and subsequent instalments via my Master card, due to the outbreak of Covid I was notified that OTB were cancelling the holiday and that I would receive all payments back in two instalments the first being any money I had paid for hotel and transfers and that the flight money would be paid back when OTB received it back from the flight company.
I waited several months checking to see if any repayment had been paid back into my account but nothing had so I contacted OTB through the my message booking page on several occasions to see when refunds were being paid back, eventually after E-mailing their CEO Simon Spooner and still getting no response I emailed customer services several times and I was told that the refund for the hotel and transfers had been paid back into the card that was used I checked with my bank several times but they said no money had been refunded so I phoned customer service only to get an automated message, the next time I heard from OTB was to say my refund was there waiting for me to collect I checked and sure enough it was imagine my disappointment when I saw it was for £9.00 only when I had in fact paid nearly £1,700, I sent several more messages to OTB with no replies at first then I got an email saying the £9.00 was what was paid towards the flight and that they had already paid back the hotel and transfer money But I Still hadn't had it, then another representative from OTB contradicted what their colleague had said and they said it was for the hotel and transfers, they have removed all my messages off my booking page that I had with them and now almost a year later I am still waiting for my refund I have been so stressed with this and will never ever book with this company again and my friend who has had several holidays booked at the same time as me and had them cancelled with Jet2 has had All her money refunded within a week, the customer service at OTB is dismal and I know I am not the only one experiencing this with them.
Coniston
Has your wife tried asking her CC company to raise a chargeback? If that's too late now, a letter to the company secretary "ahead of proceedings", giving them 10 working days before you use the online small claims court process, might lead to some action. If not, use the court process. You can claim back your court fees. I'm not a lawyer but these recommendations appear often in the money pages of the better newspapers.
I wasn't very happy with my own experience of On The Beach (LON:OTB) either coniston. Due to travel in September, paid £1,350 up front. Jet2 cancelled the flights in July: On The Beach sent us cancellation notice saying they would refund their proportion immediately, but airline may take longer. Well Jet2 sent us £1,250 directly almost immediately, but nothing from OTB so I messaged them a couple of weeks later. Today's update reminded me I still hadn't received my £95 from them, so I sent them a grumpy message this morning and they say it's now finally been refunded today - although £20 deducted. I reckon they would have just kept it, if I hadn't chased again.
Its a great day for fitting realities to one's chosen narrative...either in an offensive or defensive way (the latter probably takes the prize today with the covid wonder stocks).
Best thing is to do nothing, think and go another day.
I'm not in the covid plays very much but sadly I do have c.27% in gold miners so I feel that side of the pain too.
Someone mentioned K3 Capital (LON:K3C) ....its probably going to surprise meaningfully FY2021. Historic earnings are reasonably depressed given first brexit and then covid (took our last 2 months of FY2020 for M&A) and still looks alright for the price. They've set 2021 expectations very conservatively using pretty prior years performance for 3 businesses. And for the M&A biz they have have pretty much excluded expectations of juicy transaction fees and just assumed retainer fees. As for acquired randd (R&D tax credits) and Quantuma (insolvency, restructuring) they assumed little YoY growth despite both businesses having a strong growth trajectory, particularly Quantuma.
Implicit in their forward assumptions are that neither M&A or insolvency and business restructuring work picks up. Trading update for Q1 implies both M&A and randd tracking ahead in first quarter when annualised. This is particularly good for M&A as the first month was a fallow period really with lockdown still in place and so retainers not being recognised in earnings and the shutdown means they had not had a chance to build new client retainers back up for the July and August when they were back to the office and trading more fully.
There's probably been a bit of an overhang for a couple of reasons. Quite a lot of PIs bought around the huge profits seen in 2018 and perhaps got tired of the robust but not immediately fruitful underlying growth. Then the equity issued to acquire in May this year was quite chunky and so probably some repositioning going on after that.
M&A and insolvency will bring some revenue volatility but its probable that the quantum of earning over next c 5years is being significantly underpriced....plus in 2 years time this stock could easily have a 10% yield on current price if trading conditions decent.
What a strange world only took the dog for a walk and this year's losers are starting to look like wins. See we have vaccines and life might be getting back to normal soon fingers crossed.
I hope others are enjoying the ride today.
BSV
P.S. Thanks god I closed the FSTE100 short before the walk.
There’s a good chance that this thing could be under control quite quickly, which means we’re being offered some terrific bargains by Mr Market.
Hi Paul/Jack
Excellent summaries as always. You mention here about terrific bargains currently in the market. Any pointers as to which companies you mean, so can delve a little deeper and have a look...? I think Saga (LON:SAGA) suddenly has my attention, given the levels we've seen recently. Just wondering if you had any other pointers to research into??
re Heatmaps
For those interested, I produce daily weekly, monthly and YTD heatmaps that can be sliced by index and are full interactive so you can drill down by index to sector and constituents: they are sized by cap and coloured by price change in the time interval chosen (it's "inspired" by FinViz in the US) ..
these are end-of-day data only and are included as part of a market sentiment dashboard which aggregates key data on sentiment scores like the VIX, AAII investor sentiment, Fear and Greed Index , UK shares making new highs/lows as well as price moving averages based sentiment readings etc
these and the other plots on https://runprofits.com
They are ostensibly trading tools and use data visualisation and data mining to give quick insights
end of blatant plug .....
Todays market is probably a bit of a traders dream - but a bit harder to look through the mist if you're more of an investor.
Vaccine news is clearly good news generally but the key here is the massive switch out of anything deemed as being covid related and into bombed out recovery stocks. This was always likely to happen - you only had to look at the bottled up sentiment to realise this.
From a trading perspective that offers some significant contrarian opportunities as stocks have more than halved on the news but at an investing level becomes more interesting. As we know vaccines are likely to only last a year and will need constantly updating to stay relevant. That is why drug companies are booking up quarantine facilities around challenge studies years in advance. Someone like Open Orphan (LON:ORPH) has been hit 20% today yet only a small part of its business relies on covid. Similarly Tiziana Life Sciences (LON:TILS) which fell 40% at one point earlier. These businesses are based on longer term macro trends, it's not binary. Thus these falls seem an over reaction to me. Similarly I don't see demand for PPE, disinfectants, sanitisers etc disappearing overnight. That demand is likely to be sustained long into the future in my view, so these stocks have also been hit too hard.
Others down 15-20%.....online demand for music Gear4music Holdings (LON:G4M) or Loopup (LON:LOOP) also probably not going to change much. Same could be said for Boohoo (LON:BOO) and ecommerce businesses, so probably also an opportunity as they are in positive macro trends. Covid has helped these businesses forward by a year or two but I don't see a shift in dynamic.
Testing is a trickier one - it won't disappear but it could get rapidly scaled back. Not today but in 6 -9 months potentially and as we know the market is (well is supposed to be) forward looking. Not quite sure of the read across here. My suspicion is that companies like Novacyt Sa (LON:NCYT) will be the winners as they are first movers at scale but possibly pared back from existing expectations. I'm watching this one - if it drops back towards 400p I think I'd buy as net cash will offer some protection there longer term.
Definitely an interesting market today offering up some opportunities I think.
’Know what you own’ is once again going to be put to the test today, as it was in March. If anyone is panicking - stop; revisit your investment thesis; check the valuation; have a full thought process before doing anything. Knee jerk reactions should always be avoided.
Excellent advice Nebraska. If I may add at the risk of tautology "Know what you"...and why?
Can that be true, a sample of 94, look at the reactions on reuters interesting
https://uk.reuters.com/article/idUKKBN27P1FX
You have to remain a little sceptical though, not that i think the markets will, most data , outside of whitty, shows the pandemic is in decline so hope of a virus, numbers falling & new Biden stimulus, woosh.
https://en.m.wikipedia.org/wiki/RNA_vaccine
Although mRNA vaccines have entered clinical studies (anti-cancer vaccines) in the late 90s for DC-based vaccines (https://pubmed.ncbi.nlm.nih.gov/11828001/) and in the early 00s for the direct injection of mRNA (https://pubmed.ncbi.nlm.nih.gov/18481387/), currently, there are no RNA vaccines approved for human use.
I am heavily down in my covid testing stocks today Avacta (LON:AVCT) Novacyt Sa (LON:NCYT) and Synairgen (LON:SNG) but in case people have not picked up on the detail in the Pfizer vaccine announcement the sample size of the test was 94.
I leave people to draw their own conclusions.
Regards
Michael
The sample size was 43,538 of which only 94 contracted the virus.
Just to explain the 94 figure - tens of thousands of people were involved in the trial. Half were given the vaccine and half were given a placebo. Neither those involved in the trial nor those conducting the trial knew which patients were in which group. 94 of the people involved contracted Covid, and of those 90% were in the group which received the placebo rather than the vaccine. So it's not an infallible solution, but it does reduce the danger by 90%.
It has previously been suggested that the best course of action may well be to be treated with more than one vaccine.
I only hope the Pfizer one doesn't give me an unwanted erection.
Love the final sentence :-)
That is not right. 94 people got infected with Covid during the trial and of those infected over 90% did not receive the vaccine which is strong evidence that the vaccine works in reducing infection. We will still need testing but not sure exactly what to level. E.g. if you are travelling you may need to have proof of having had the vaccine and a negative test.
MichaelFBS
but in case people have not picked up on the detail in the Pfizer vaccine announcement the sample size of the test was 94.
Thats 94 postives not sample size of 94 - I would agree though the sample size is smaller than i would like and obviously its not peer reviewed info so we just have to take it at face value that the news is as good as they want us to believe (cough) - i would say though i am guessing they have passed the necessary statistically significant threshold they need even with this at face value small sample size - with a proper double blind trial its highly unlikely that they would get such positive results by chance alone even with such a small sample size .Toss a coin 100 times and you are down to less than 3% chance of getting 60+ heads by chance - so the quoted numbers do look very statistically significant to me despite the low total count from which the numbers are derived. Anyway today i think i will only be taking the positives out of the news, hopefully its further progress to proving that the doomongers "no working vaccine this year or next" are likely to be wrong.
I am missing that small print - could you point us to it?
£NCYT Novacyt
People who sold testing stocks today: The world doesn't need testing?! Just turn off your screen, and think for a minute about reality! No testing? Over?! Come on.
Novacyt Sa (LON:NCYT) I agree, testing will still be needed. However Phase Two of the contract with the DHSC which is optional might not be won (or only partially won) if a vaccine is found and distributed quickly enough? How much of this Phase Two contract is/was already baked into the shareprice?
Novacyt Sa (LON:NCYT) I added more today below 600p. They have a ton of cash. But some of the other testing stocks do not even have a product yet. Launch first or second quarter of 2021! Too late. They could halve again and still look expensive.
BP. up 18% today. That may be a first. Loads of bombed out stocks look real value now.
I attended Mello Monday for the first time, last month. I don't have a particularly long attention span and was wondering how I would manage a 3 to 4 hour conference (after work had finished). However, I signed up with a positive attitude "if you don't try things, you can't form an opinion. I love investing so there is bound to be something there of interest etc" The time flew by! David Shredder does an excellent job of hosting and keeps conversations moving. Each section is fairly short. Its clear to see a lot of thought has gone in to the content as each section covers different areas of interest, from business presentations, to balance sheet red flags to the excellent BASH panel. I have now signed up for a yearly pass, which was a snip at £95. Amazing value with excellent and interesting content. Thank you Stockopedia for sharing its existence :)
Is this the start of tech to value trade? If inflation eventually comes along that would be another catalyst for value. Interesting times.
Wow - novacyt down 35%, Loopup down 16% (of course I added this morning before fall!!)
On the other hand On the beach up 25% and Air partner up 15%.
The question remains will the COVID stocks lose growth post the vaccine
AJ Bell site crashed again.
Not great for a £1.72BN market cap company given the nature of its business.
Appreciate it's a busy trading moment, but surely that's the purpose of a "large" platform - to provide for trades.
Time to move lock stock n barrel to another provider.
if its any consolation HL was incredibly slow too.
If you wanted or needed to sell it would be a real p@@??r
I've been using both throughout the day, AJ Bell was much worse!
Don't try IWEB utterly useless. They are always down when the market gets busy. IG seems to be working normally
I don't trade that often but over the past year IWEB has been absolutely fine for me. It has never been down when I have gone on. Having said that I am not on every day or for that matter every week.
I absolutely agree re AJB and am totally sick of their site with its down times and very limited value and functionality. I would dearly love to see no more of the sad lady holding a red cup of tea who greets you every time you log on too. This morning I traded for the first time with IG - not CFDs as I am not brave enough but normal share trading. What a revelation. Live pricing, intuitive lay out and extremely fast minimum share search and trading. IG is still up as I write despite huge trading levels, whilst AJB is unobtainable! Chalk and cheese comes to mind! Only downside was my first trade which was Loopup (LON:LOOP) which immediately lost 20% - oh dear!
I absolutely agree re AJB and am totally sick of their site with its down times and very limited value and functionality. I would dearly love to see no more of the sad lady holding a red cup of tea who greets you every time you log on too. This morning I traded for the first time with IG - not CFDs as I am not brave enough but normal share trading. What a revelation. Live pricing, intuitive lay out and extremely fast minimum share search and trading. IG is still up as I write despite huge trading levels, whilst AJB is unobtainable! Chalk and cheese comes to mind! Only downside was my first trade which was Loopup (LON:LOOP) which immediately lost 20% - oh dear!
Did you not know the AJ Bell trading platform still runs on a 1990's Intel Pentium PC in Andy Bell's back bedroom? They must have missed that from the marketing blurb. I've always wondered what broker Russ Mould uses. I bet he doesn't eat his own cooking...
All the best, Si ... who will probably be offloading his Pfizer shares this PM using IG.
I could have written your post word for word. This has got to be the final straw for AJ Bell. On such a significant market day, to be unable to even login - never mind buy or sell is wholly unacceptable. I've been trying to buy since 11.30am and estimate the delay has already cost me a significant chunk of cash - watching the share price of your target go up while being unable to take any action is not a pleasant place to be. Can anyone recommend an alternative provider? Preferably one that has proven able to stay active and tradeable even on busy days.
That's not HL, then, who have also crashed to the point of not being able to login.
Thanks all - think you've reconfirmed immediate reaction. Am waiting to see what the complaints dept comes back with ("sorry, the fact that people might want to trade during busy times took us completely by surprise and the ZX Spectrum (48k) couldn't cope" or "sorry, we messed up, here's £500" !) and currently, am anticipating moving across to ii, where trading always seems to have dealt with the busy times.
It appears that I am not alone in my AJB experiences then. Not sure whether to just incur the cost of transfer to IG or trade them out? The final straw for me was the IPO of Verici Dx (LON:VRCI) out of Renalytix Ai (LON:RENX) which I hold. I topped up my subscription of the .20p goodies and have yet to find out if I have any a week later - they are just sitting with zeros in my portfolio. Anyone else waiting for news? I also understand that with AIM traded shares we have to wait a year before we get our share for share allocation - anyone know if this is right? I think I will go back to playing my piano as Mozart is far less frustrating.
Telephone Execution Sevice level with Charles Stanley. Been using them for years, never been unavailable. Might cost more than an automated system, but you can get to know the dealers, 'work the order', know that instructions will be followed, etc. I reckon it's not cost me any more than internet-only service in reality, and it works!
and the opposite side of the coin, Covid trade unravelling fast with some eye watering drops in moments
as well as the obvious CV19 plays unwinding like Remote Monitored Systems (LON:RMS), Novacyt SA (LON:NCYT) ... Ocado (LON:OCDO) £LOOP also joining the rout
Very interesting to see how that news has had the polar opposite effect on £Boo and Asos (LON:ASC)
I understand the broad-brush negative reaction to pure play online shares but I can only see covid-19 free future being beneficial for Boohoo group/ Asos. Their respective target markets will need more clothes to go out and about in and these are still the most cost effective and choice effective ways of achieving that.
There really can't be much change in the near term as only 50m doses available worldwide this year with concerns around duration of immunity. In my opinion additional lockdowns accompanied with this vaccine will still be required to draw a line under it. Also, who are these 10% of people it doesn’t work on? Sorry sods.
Long term the shift to online is as clear as ever with the only potential for derailment being greater online revenue taxation- which I 'm sure is imminent. Alternatively the fabled British High Street is destined to become a series of automated warehouses clustered around a handful of hairdressers and cafes.
Great response, thank-you!
What's happened to £EKF - priced dropped 15% at 12 noon today despite a good trading update this morning?
What's happened to Ekf Diagnostics Holdings (LON:EKF) - priced dropped 15% at 12 noon today despite a good trading update this morning?
Well, it's perceived as being reliant on the continuation of CV19 for its growth and Pfizer just announced a working vaccine ...
timarr
Vaccine or not (and my quick take on the Pfizer news is that it still has a couple of more hurdles before regulatory approval for emergency use), my judgement (which could well be wrong) is that volume testing will continue well into 2021 and probably beyond. So specifically with regards to EKF Diagnostics Holdings (LON:EKF) I believe the current forecasts are wide of the mark.
The forecasts for 2020 were upgraded by house broker N+1 Singer today to £63m revenue (from £60m) and EPS to 3.5p (from 3.25p). At a share price of 70p (currently 66p) that puts EKF on a 2020 PE of 20. The 40+ PE that Jack quotes in his piece above refers to the forward forecast for 2021 which remains unchanged at £49.5m revenue and 1.65p EPS. N+1 Singer have said they will be updating 2021 forecasts once EKF have issued their year end trading update (late December or early January). My view is that 2020 is far from a flash in the pan and 2021 forecasts should reflect that in due course.
This logic prompted me to top up at 59p and 63p earlier when the shares dipped violently - so clearly there is also some volatility risk with this share.
Cheers
Simon
Thanks for your thoughts Simon, bought on the news at market opening only to see it tank later, anyway im holding for now
Thank you - I should have realised! - I hold.
The Pfizer vaccine news is excellent. Some notes of caution though:
We don't know whether the vaccine stops severe cases of COVID that will cripple the health system or the more mild cases;
We don't yet know if the vaccine prevents people from carrying SARS-CoV-2, the symptom-free cohort
We DO know that Pfizer deliberately designed their study to ensure it was one of the first to read out
In short, I wouldn't pile-in to Pfizer on the back of this news, but it bodes very well indeed for the suite of other vaccine candidates in development, particularly mRNA vaccines. Great news!
Agreed, we also don't know how long the immunity will last for or whether there would need to be regular injections
Yes, good news but how long will it take to produce enough and vaccinate everyone, I'm thinking at least 6 months and probably more like a year?
Indeed, the market seems to be reacting as if "it will all be over by Christmas" , but that strikes me as premature.
They want to fast track approval , but how long does that take?
Pfizer say they can manufacture 50m doses this calendar year (is that 25m treatments at 2 doses each). UK Gov say they have ordered £30m (again doses or treatments?). It does not follow from that the will have 30m available in the UK before Christmas.
Doses are 7 days apart to achieve immunity.
It is difficult to distribute as needs storing at -80 degrees c
It is potentially great news, but I cannot really see it having a material impact on restrictions and controls before next year.
IMHO obvs
I think the technology is replicable so other vaccines may work too. Thats what they seem to be saying on CNBC.
I think the technology is replicable so other vaccines may work too. Thats what they seem to be saying on CNBC.
The main point is that a vaccine does work - there was always a residual concern that CV19 would be totally vaccine resistant - you can't overcome the science. Once you've proven you can block it then it becomes an engineering issue as to how to scale up and deploy - which is something we can definitely achieve.
Obviously lots of issues to overcome and no visibility as to how it will work in future - but 90% effectiveness is way beyond the wildest wet dreams of immunologists, so if this stands it's fantastic news.
As for the market reaction - well, it's hard to know whether to be amused, bemused or confused. Hardly anything has really changed yet just in my portfolio I have 10 stocks up more than 10% but Novacyt Sa (LON:NCYT) down 40% and Loopup (LON:LOOP) down 20%. Just another manic Monday ...
timarr
it's hard to know whether to be amused, bemused or confused.
It's as simple as ABC then.
Thx Gromley really good points.
Because it is an RNA vaccine it has to be stored on dry ice.
UK govt. had ordered 40m doses which is enough for 20m persons, as you need to 2 doses. No doubt most of the early production will be going to the USA.
{Vaccine}
Yes Herbie,
I picked that up later and I think there was a later figure somewhere around about how much the UK might get in the first tranche.
Numbers aside I thought the UK Gov press conference was much more on message. JVT was precise (and adorably prickly) as ever and even Boris avoided the hyperbole.
The takeaway for me was - encouraging but does not make a difference before spring at the earliest - it was not that difficult so why the Journo question "does this mean we can hug granny at Christmas" - strewth!!
I still feels to me that the markets over-reacted somewhat today (even accepting that the markets are supposed to look 6-9 months ahead).
I constantly fail to read the short-term mood of the market, so my opinion means little, but I am not rueing any stocks that "got away" today - they will either come back to me or they wont.
Yes, but aren’t markets looking ahead and quickly pricing in the likelihood of a return to more normal times next year? Some of the gains today for bombed out travel and hospitality shares are over 20%.
FT article on Saturday showed UK shares at their lowest relative to other markets since 1973 and some of the extreme fallers are back to the prices they were then too. So though part of the gains today could well be shorters desperately closing positions, isn’t there a high chance we’ve seen the bottom now for the sectors worst hit by covid?
One big concern still is if the mink cases spread, as there are fears the vaccine will not work for that mutated version. So as always with investing there’s always something for us to worry about.
THE big plus about vaccine news imo is not the investment gains likely but a chance for a return to normality for hospitals and for those waiting for vital tests and operations. So much focus on covid has seen cancer and other life threatening illnesses take second stage.
some of the short squeezes going - off
the blue indicates short interest, the green is the price jump
what is this platform you're using? Looks excellent!
Nice platform ! What is it please ?
thanks, they are at https://runprofits.com
I think you make an excellent point re Gym (LON:GYM) Paul by asking 'Have people's habits changed for good' In my view it is not simply a matter of these companies surviving financially, but also transforming their offering to meet the new reality, especially in the cities. I was a member of a huge Gym Group on the ground floor of our riverside development in London where our beautiful apartment sits unvisited for the last 9 months and it was packed at the start of the working day and going home time. Of course there will still be gyms and everyone won't work from home all the time, but also the mass purchase of exercise equipment noted on this site at the start of the lockdown must have made a significant impact on workout routines. Gyms make their money from huge sign ups after Christmas with many not attending past the first visit but not cancelling subs either. Will this still happen? Maybe it is a multitude of smaller more local gyms which are required plus possibly more home visit personal coaching as well? Who knows? What is more certain is that the thumping humping max capacity workouts in vast high cost properties in city centre locations which GYM still rent, might be a thing of the past?
Chriskay,
Re Gym (LON:GYM) I think that whilst it used to be true most "Gyms make their money from huge sign ups after Christmas" this is much less true of the low cost no contract gyms like The Gym Group & Pure Gym that have emerged in last 5 years. These were already growing sharply (vs public and premium gyms which were stagnant). Many of these were young (ie <30 years old) and either wont have the space/money to invest in home gym (unlike an older, wealthier demographic). They probably like the cheap social outing of gyms. For £20/month you can go say 1-2 times week at an effective cost of 20/7= <£3/visit - about the same as a cup of coffee or a drink.
Anyway, in contrast say (my worst case guess) of say a loss of 1 in 10 former Gym Group users to 'home gyms or cycling/running (in a cold wet Britain?), I would concentrate on the millions of gym goers who who have previously paid much more for the fixed contracts you reference, either with cash strapped local authorities or premium price premium service health clubs. Many of these will tiptoe back to gyms via a no-frills no contract route, lured by big Marketing budgets, from the national low cost chains. I see this effect as the bigger in the medium term.
Gym's issue now is that it has been trying to open near transport hubs where possible and in the big cities these might suffer a long term effect from home working. However, they are fully invested so whilst they may become less profitable, they are unlikely to have to close (mature EBITDA has been >30%!) and by standing will mostly keep their members (who get a less crowded gym!) and so prevent competitors getting going nearby even if rental costs reduce since they will lack scale. It has demonstrated its willingness to drop prices in 2018/19 in contested areas to retain membership before being agile and putting prices back up 3 months later
Meanwhile, the Gym Group's own roll out plan IS helped by lower rental costs. With its relatively fixed central costs for technology upgrades and purchasing scale plus established property teams, it should be well placed to accelerate. its growth.
Clearly I am optimistic for it on a 2-3 year basis and hold a decent sized position in £GYM.
Funny that, Biden declared president, Vaccine announced, CNN drop the Covid project fear onslaught.
Crazy reaction in the market in the last 30 minutes. All the beaten up airlines and business intrinsically to those settings linked have begun their march :-)
Whoosh! Pfizer announce breakthrough on vaccine. Dow futures up a thousand points plus. Ftse100 up 260 points with travel, airlines and such racing up. Edit; make that 300 points up.
"A great day for science and humanity" Pfizer CEO "The biggest medical breakthrough in over 100 years". Live now on CNBC.
Hi Peter
It is based on a sample size of 94 so I think a bit early to count chickens?
Regards
Michael
Indeed. They have not managed to produce a reliable flu vaccine yet. Personally I prefer to build up my own immune system instead of relying on questionable drugs.
Where did you see the 94 number Michael?
The Pfizer CEO is talking abou thousands of participants.
This is a great victory for humanity, and one that could not have been accomplished without the almost 44,000 people who selflessly raised their hands to participate in our trial and help our scientists and clinicians advance this important breakthrough.
.
Today, piworld have launched a new idea Deep Dive into ... different tech themes. So today: Deep Dive into Silicon Carbide for investors. By Dr Peter Gammon of Warwick University. Video or Podcast.
It's quite technical, but as the title, it's a deep dive to understand how silicon carbide is evolving in industry, and the implications for investors.
Do give us your feedback, good or bad. If good, we will provide more of these. If it's just too technical ... we won't!
Viday
A most interesting presentation. more deep dive tech themes please
Jack,
One point to note and not commented on by EKF Diagnostics Holdings (LON:EKF) today is this new COVID testing collaboration announced last month....
EKF will have exclusive rights to market and distribute COVID-SeroKlir , Kantaro's quantitative SARS-CoV-2 IgG antibody test kit in the UK and Germany and non-exclusive rights in Europe. For the research market, EKF will have non-exclusive rights to distribute COVID-SeroIndex across the UK and Europe.
.....The agreement follows the receipt of the CE Mark certification approving the use of COVID-SeroKlir and COVID-SeroIndex for detecting the presence and the precise titer (level) of IgG antibodies. Measuring the level of neutralizing antibodies in addition to other antibodies a person produces as part of their immune response to COVID-19 virus exposure provides important information in assessing any likely protection against future re-infection.
I have just topped up in the expectation that there will be a PEAD effect whilst the market re-adjusts expectations and that COVID test kits will provide a further growth catalyst.
Apologies, my heatmap post earlier has been 'queued for review'.
Here's a slimmed down version in case it's the length that triggered the review.
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than 20d ATR EMA):
Big movers today (moving more than 20d ATR EMA against either yesterdays close, or today's open - not limited to small caps):
Hi
Is there some trick to reading this heatmap - in terms of getting it to a size that I can read? For me it is a jumble of colour and not a lot else. Maybe that is the idea?
Not meaning to be critical - I really appreciate all the input made contributors - just I don't think I'm getting the most from this and I wonder if I am missing out?
Try right clicking and select "Open in New Tab"
Thanks Glorenfeld :)
@dfs12 Yes, your browser will re-size the images to fit your available screen space so popping them out into a new tab as Glorenfeld suggests should improve things if they aren't legible for you.
Warm regards,
Greensiax
Even so, I have to click four times in Google Chrome's browser to achieve a readable-sized layout. Being honest, it's not really my scene. Sorry about that,
Silver
@Silver Moon, no need to be sorry...
I produce them primarily for myself and share them in the hope that others may also find them useful. If you don't then that's cool, if no-one does then I'll stop. No ego to hurt ;)
Cheers,
Greensiax
Hi Greensiax, to keep things neat and tidy could i suggest you start a separate thread called something like: 'Greensiax's Heat Maps' and post updates daliy/weekly (as & when you can) in the comments, then those who like them can use and those who don't won't get upset with it appearing in SCVR comments.
Forbsy.
Fits on my screen fine so it must be your device.
The heat map is a graphic so you can right click on it and download then view on your computer.
Even on my 24" screen they are still not really legible. However a couple of clicks with CNTR+ remedies that. Thanks for the new tab idea - I will study them now.
I don’t understand, I can read on an iPad which is about 8 inches and on my computer screen which is about 20 inches. But I’m using the old site.
I can read them on my iPad but they are very unclear on my 32" main PC screen - I don't understand either.
That’s seems odd. Clear on my PC monitor, on the iPad they are a bit small but I can still read the share names even with my dodgy eyesight. Maybe it’s a new site issue?
Here are my heat maps for today (prices as at ~9:45am).
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than 20d ATR EMA):
SVCR unfiltered (limited to top 80):
All Instruments (filtered to 'interesting', limited to top 80):
All Instruments (unfiltered, limited to top 80):
Big movers today (moving more than 20d ATR EMA against either yesterdays close, or today's open - not limited to small caps):
And finally the key to the heat map contents:
All heatmaps are ordered by Stock Rank™ .
PS: If you don't find a particular heatmap of interest or useful please let me know and I'll stop posting it. Similarly if there is a view that you'd particularly like to see please comment and if I can, I will.
Cheers, and stay safe,
Greensiax
[Edited to add PS]
Any thoughts on Pelatro (LON:PTRO) ? This morning's RNS goes all round the houses to avoid the dreaded phrase "substantially below market expectations" but revenue 4.0m IS below expectations of 7.4m. Cenkos (afaics the only one covering) has dropped eps forecasts from 2,2c to -5.7c this year and from 2.4c to -3.1c next. That is substantial.
Used to be a holder of £PTRO but sold up earlier in the year with a loss of about 30%. Its in a very interesting line of the business but I tired of what seemed to be continuous drops in forecasts. Its starting to more look like a jam tomorrow company. I remember someone flagging that management decided they needed some expensive cars to drive around in on the company and I guess that was the final straw for me.
It still has some significant potential but not sure they will ever realize it.
Read the notes to the accounts in Pelatro (LON:PTRO) ....they're a bit 'interesting'.
There's more but this is what I can recall re Pelatro from memory and don't want to go digging back in
£PTRO - I do not hold - looked into this one in some detail before - just saying it as it is 1/ Spread is big so hard to trade 2/ Management have failed to deliver on their expectations now at least 3 times 3/ Obvious that moat is weak given that their shift to ARR has not worked 4/ recent rebound in SP was due to Simon Thompson ramping it 5/ Today's RNS really was a fine display of damage minimization and a lot of excuse making. Coincidental timing of contract award with annoucement of lower rev? mmmmm...
hi
Re: CWD and the approach this morning from Connells? Does that mean the recapitalisation deal with Alchemy is off the table for now?
Countrywide (LON:CWD) I don't think the position is clear at all. Ever thus with this company. I posted here in April that I had taken a mad punt on this because it owned so many top brands despite the debt. The specialist press has reported a lot of quiet stake building over the last few months. The suggested offer of 250p in cash was made on 26 October i.e. a week before the Alchemy prospectus was issued.....and what did the Board of Countrywide say or do? Nothing much or so it seems.
It is clear from the wording today from Connells that they want all of the management out...".Connells believes that Countrywide needs a new management team, with real estate agency expertise..". Blunt, rude even or what! Almost a football chant; "you don't know what you are doing". Mind you, I fully agree with them. The rather cosy arrangement with Alchemy will now need to see a lot more money on the table. I have to wonder if the directors of Countrywide have to be reminded that their main role is to work for the benefit of the shareholders rather than hang on to their very well paid positions.
I must say I am very surprised that Foxtons (LON:FOXT) is not a lot stronger today. Added a few more today.
Countrywide (LON:CWD) the Alchemy bid is off the table as it as 135p and the Connells bid is at 250p. Don't need to wait for board support to choose between those. Connells must have as good visibility as most to market potential. Paying 5x 2020 op profit not a stretch. Long and buying more
While Connells understand the market - my reading of the Connells RNS is that they have not (as yet) been able to do any due diligence. The board postponement of the GM, will presumably allow this due diligence now to take place. Given the financial predicament at Countrywide (LON:CWD), it cannot be ruled out that the details of the financing will be found that makes the Connell bid not workable - as well just with time, Connells might decide not to go ahead as it sees the housing market develop into the end of the year. With Countrywide trading at a large discount to the 250p indicative offer, there are risks priced in.
Am I being particularly stupid? but The offer is 250, todays shareprice only hovered around 210 all day. Why didn't the price jump to 250 and sit there? Does the market not think that Connells will go ahead with the takeover?
Countrywide (LON:CWD)
Am I being particularly stupid? but The offer is 250, todays shareprice only hovered around 210 all day.
I think with takeovers thjere is always a material % chance the takeover may get pulled by either party - but particularly the buyer if for example due diligence uncovers a can of worms.
the following indicates there is work to do yet for buyer to be in position to proceed
The Approach is at an early stage and Connells Limited has indicated that any offer is conditional upon, amongst other things, completion of confirmatory due diligence and the recommendation of the Board of Countrywide.
ok lets do some basic estimates
Lets say 75% chance takeover goes ahead at 250p and 25% chance deal collapses completely and we are back where we were before todays news 145p.
So 250 * 0.75 + 145 * 0.25 = fair current shareprice of 224p
We probably need to reduce to 60% success chance of takoever going ahead to factor in current shareprice. In summary the market appears to rather skeptical that shareholders will receive 250p in cash.
I guess the following section summarises how uncertain everything is ref this announcement.
There can be no certainty that an offer will be made, nor as to the terms of any such offer, should one be made.
Note if you compare the wooliness of this approach to the one for revolution bars back in 2017 Revolution Bars (LON:RBG) (24/8/2017) which was board approved (and still failed !) - it seems fairly clear there is very little certainty given today that this transaction will go ahead - so hence the shareprice is only slightly over halfway towards the exit price depsite the promising spin coming from Connells.
MaanA
On £CWD I don't think it is quite clear. If Connells can formalise their bid at 250p - then it is clear. But for the moment the Board has only "postponed" (not cancelled) the GM to approve the Alchemy offer.
The 22 Oct RNS said that the Alchemy proposals conditions had the following conditions (among others):
* the Resolutions having been passed by Shareholders at the General Meeting;
- Admission having become effective by not later than 8:00 a.m. on 22 February 2021 (or such later time and/or date as Countrywide may agree).
As Admission of the new shares were only due to be on 17 December (under the original period), this would appear (as I read the situation) that the Board could hold Alchemy on the back burner for upto 2 months, while it sees if Connells can firm up its offer. [This obviously depends on Alchemy having some other out that I am not aware of and the banks not being able to withdraw funding before then.] This would be my initial read of the situation but DYOR.
I totally agree with Barnetpeter's point that Connells seem to have a low opinion of the CWD management and their criticism seems to chime with Robin Paterson's views.
Hi Paul/Jack,
I keep seeing investment groups shorting Codemaster-since the announcement-any thoughts as to why?
Thanks
Mark
Maybe there is an expectation that major share holders will refuse the offer and the offer will be withdrawn although it could go that other way, I would not want to be short Codemaster.
Mark, there is an arbitrage in CDM as it is a stock and cash offer. The terms are 120p cash plus .02834 Take Two shares for every Codemaster. Therefore you can theoretically buy CDM and simultaneously short sell 0.2834 Take Two shares. Using an exchange rate of £=$1.32, an example would be to sell .02834 Take Two at $165 , that would be $4.676 received, converted to £ = £3.57 plus £1.20p = £4.77. If you can buy CDM in the market below £4.77 you lock in a profit and benefit from an improvement in the offer or a counterbid. You close the position by delivering the Take Two you receive against your short position. The risk is the deal falls apart and you have to sell your CDM lower and buy back your Take Two in the market.
I see Take Two shares were down nearly 9% yesterday, so this offer is even worse than the original price. I’m waiting for a better offer,
Could I get your views on Codemasters £CDM. The bid price seems low given the momentum and new lockdown which should help this gaming share. Lockdown may also be more likely in the US over Christmas/New year given the change in administration.
Im holding off on codemasters as theres no real game portfolio and they seem to be relying on 1 game Dirt5.
Morning Paul and Jack; with a trading update from lon:TW. - is there anything to be read into the housing sector generally which could assist investors in smaller builders/agencies?
Paul, any chance of checking out the full year trading update for On the Beach (OTB), the UK's leading online retailer of beach holidays. Prior to Covid it was emerging as a fast growing disruptive internet star. It raised £50m in May, is just about breaking even and has cash of £44m on its balance sheet plus a £75m undrawn credit facility. The group says that its 'zero revenue cash burn' is £2m a month, so it has the capacity to survive the current pandemic.
Jet2 versus OTB. Which is the best long-term recovery play assuming that we ever escape from this ghastly global pandemic.
you really in Darwen? (Im a Darrener)
Sadly not. Brought up there but moved away for work. "Between those hills so bleak and barren there lies a town called dirty Darren". Still miss the place.
theyre building houses all over it now. Sad for us. Old Bailey's fields, Cranberry lane and all the adjacent ground on Pole lane. Green belt land grab.
£Jet2 versus £OTB. Which is the best long-term recovery play assuming that we ever escape from this ghastly global pandemic.
Both are excellent companies - both have ringfenced customer funds so that the vast majority of customers have received refunds rather than endless deferrals, forced offers of vouchers and incoherent responses. Quite how most travel companies think they can screw their customers on one hand and persuade them to hand over more money on the other is beyond me. Desperation I suppose.
On The Beach (LON:OTB) notes that some refunds have been paid before they've received the cash themselves, so the net cash position is better than it looks. The trade off is between Jet2 who control the whole value chain - but bear the costs and the capex - and OTB who are a pure play online platform with very low levels of cashflow requirement but rely on third-parties to handle the actual execution of the holidays. It's a difficult question to answer.
Looking around the world the only countries and economies that are doing OK are those that have controlled CV19 both inside and at the borders - Taiwan, South Korea, New Zealand ... for example, reports suggest that about 50% of the CV19 cases circulating in the UK now came from a variant in Spain over the summer. So a reasonable surmise is that under all circumstances overseas travel will be the last sector to resume.
One one hand, OTB will sail through barring complete and permanent shut down while JET2 may in extremis need to come back to the market for more cash if the issues extend into 2022. On the other, JET2 can control and make Covid-safe (well, as much as that's possible) the whole end-to-end holiday experience. Both will do way better than most travel companies, but you may need to be very patient.
timarr
For airline stocks, may be worth looking at Eurocontrol's November recovery projections to 2024 under 3 vaccine scenarios, this being the key chart https://www.flickr.com/photos/...
https://www.eurocontrol.int/si...
I haven't read the presentation in detail but sense it paints a slower picture than many expect. Also I'm unclear if there's a breakdown between business and leisure travel - reasonable to expect the latter to be faster as many businesses will conclude they can function well remotely, saving huge amounts of £££££ and time.
Alas patience turned out to only be a 3 hour wait!
Smiths News (LON:SNWS), previously Connect Group has managed to refinance its existing financial obligations without having to raise new equity. Despite the more stringent conditions attached by lenders this is very much a positive development in my view. Given its free cashflow and other lowly metrics plus the recent trading update the company is increasingly looking like a viable turnaround candidate.
Totally agree jonno - the Smiths News (LON:SNWS) refinancing looks good to me.
For me this is the main uncertainty lifted (the possibility of dilution) so I am surprised at the muted reaction thus far.
Although perhaps we well get a better view with prelims on Thursday which include more detail on the refinancing.
Simec Atlantis seems an interesting little company. It has made an announcement re a new £1m grant this morning. They are involved in creating energy from waves which has for sometime been an interesting and achievable objective. They also make a fuel pellet to burn in empty coal power stations. The pellet is made from plastic and biomass. Again in a more environmentally conscious world I wonder if this hasn't got legs. Valuation as you would expect looks stretched.
Sorry I forgot to mention I have a small holding in SAE (Simec Atlantic), but not intended as a ramp. It seems to me that if we are going to do anything about Global Warming, and if we don't all the money in the world is not going to help us, we need t rebase our infrastructure. I did well out of ITM the hydrogen business on this thinking. Just a thought.....recognising high risk and balance sheet isn't very good.
Hello Camtab
I agree that SIMEC Atlantis Energy (LON:SAE) is an interesting company and used to hold it. I sold out at a loss a while after their tidal power project at Meygen failed to get the subsidies they had been hoping for.
The difficulty is several fold. The cost of wind and solar energy has come down so far that tidal power (being several years behind in development) is significantly more expensive. One of the main advantages of tidal power is its predictably whereas wind and solar are much less certain. However, this advantage has also diminished as the wind farms in particular are so widespread now that, as the wind tends to be blowing somewhere all the time, the power from wind is less erratic than it was.
They are now much more diversified with some tidal projects in other areas of the world and the waste to energy project at Uskmouth and they have also been working on reducing costs. But these are all early stage projects and carry not necessarily money spinners.
They are also part of the opaque GFG Alliance group these days which makes them hard to analyse.
So, my feeling right now is that I really hope that they are successful because we need all the help we can get fighting climate change but the investment case is insufficiently strong. Hopefully, it will all come good.
Useful input Graham thanks for taking the time.
I also am wary. Tidal power devices have been in development for as long as cold fusion. The reality is that the cost of wind and solar is going down ever more, with years more of cost reduction likely, and their intermittence can be addressed by utility scale batteries. This is starting to happen: see £GRID.
saw the news this morning from Countrywide (LON:CWD), maybe worth mentioning any read-across to Foxtons (LON:FOXT) where I think you might own shares Paul?
According to Stockopedia, Foxtons (LON:FOXT) is expected to make a small loss this year and next on sales of around £100m. It's last great year was 2015 (pre-Brexit of course) when the company reported sales of £150m and a net profit of £35m. Stockopedia says today's enterprise value is £115m.
Foxtons (LON:FOXT) shares up around 5% this morning on the Countrywide (LON:CWD) news.
Asagi (long Foxtons (LON:FOXT))
Hi Paul. I agree with matylda with K3 capital. I bough some in the offer couple of months ago. I thought it was a little like Games Workshop a few years ago having plenty of cash, good dividend and high returns on it's assets. I also would appreciate your thoughts. By the way, particularly in these dreary times, I enjoy your dedicated research checking out pubs and eating places!
I am pleased to see that Countrywide (LON:CWD) has postponed the GM to approve the issuance to shares to Alchemy at 135p (below market), which would have allowed Alchemy to gain control, without paying a premium. There is now an indicative proposal from Connells at 250p. Opposition to Alchemy’s proposals by major shareholders (Robin Paterson at Catalist) seem to be paying off (for now - Connells proposal needs firming up). (I have only a token holding).
Morning Paul - You last commented on K3 Capital (LON:K3C) in February this year saying it was maybe "worthy of a closer look".
The integration update today seems positive as does the recent 1% buy by the co-founder - Net Cash, Good yield and a PER of around 10.
Appreciate if you have time for a closer look, on the surface, looks cheap with 2022E EPS forecasts set to be higher than 2018 (when the share price was well over 2x current).
Wondering what I and the market has perhaps missed here - Apart from the fact it's not a particularly exciting sector!
Sounds promising:
"Two transformational, earnings enhancing acquisitions
completed since the period end, creating a group of complementary
professional services business with a greater degree of predictability"
Not as interesting as WGB, CWD, OTB, SNWS and DTY :)
40% agreement there from me.
But
matylda
How did you sneak back in?
Have you not heard that we have left the EU now?
Seriously though, good to see you back posting. I am struggling now to remember why you left us, but I think it was something family related - I hope that all went well?
If all goes well - maybe catch up with you in Chiswick in a year or so.
Yes, welcome back - and here is a reminder for Gromley:
https://www.stockopedia.com/content/i-read-the-news-today-oh-boy-8-nov-2019-527471/
My morning smallcap tweet: Countrywide (CWD) bid approach
Pelatro (LON:PTRO) Walker Greenbank (LON:WGB) Mirriad Advertising (LON:MIRI) Countrywide (LON:CWD) Invinity Energy Systems (LON:IES) Amigo Holdings (LON:AMGO) Dignity (LON:DTY) GYM (LON:GYM) Smiths News (LON:SNWS) EKF Diagnostics Holdings (LON:EKF) Plant Health Care (LON:PHC) Zaim Credit Systems (LON:ZAIM) Totally (LON:TLY)
Pelatro (PTRO) wins 3 year contract worth $1m-$1.8m depending on the customer's take up of additional services. Guides FY rev only $4-4.2m. Blames lower than scheduled implementation of projects. Rev would have been $7.6m on old rev model, down 35%. Co "expects any contract wins before the end of this year to be for recurring revenue. Whilst the Company will, therefore, benefit from the smoother and higher quality earnings from this contract profile, it is unlikely that any further contracts won this year will result in significant additional revenue being recognised in 2020." [SP=39.9 Cap=15m]
Walker Greenbank (WGB) signs licensing agreement with Next for an extensive range of clothing, homeware and accessories over 2.5 years. Expected launch June. [SP=59.5 Cap=42m]
Mirriad Advertising (MIRI) launch of the 'Music Alliance' to place high profile brands into music content. "These partnerships bring brands immediate access to over a thousand global artists." [SP=34.2 Cap=73m]
Countrywide (CWD) 250p bid approach by Connells. Postpones GM. [SP=145 Cap=73m]. I'm short.
Invinity Energy Systems (IES) 1.8MWh sale to Orkney Flow + Tidal + Hydrogen project worth c.£1.2m if I read it right. [SP=105 Cap=75m]
Amigo (AMGO) CFO scarpers, leaves Nov 30. He is thanked. [SP=6.45 Cap=31m]
Dignity (DTY) Q3 rev up 4% but U/L op profit down 8%. Also "restructure of certain operating assets to enable their profits to be included in our securitisation covenants." to give more covenant headroom. Cost cuts of over £8m from Mar 2021. [SP=555 Cap=278m]
Gym (GYM) passed Q3 covenant test but Q4 looking tricky. since they assumed gyms remained open. Talking to lenders. "The business has traded profitably during the period and we are confident that our strong financial position, with very low levels of net debt and close to £70 million of unused facilities, will provide the platform to resume our growth path." [SP=137.2 Cap=228m]
Smiths News (SNWS) refinances existing senior finance agreement fro 3 years at 5.5% to 6% over LIBOR. This is higher than before "but remains competitive, and is reflective of the tightened credit markets at this time." [SP=25 Cap=61m]
EKF Diagnostics (EKF) guides another FY beat. Current F/C is rev £60m and adj EBITDA £23m. [SP=77.5 Cap=353m]
Plant Health Care (PHC) oint-Development Agreement for PREtec products with Wilbur-Ellis Agribusiness. It's "an important validation of the commercial value of PREtec as we move to the first product launches." No £££. [SP=8.1 Cap=20m]
ZAIM Credit Systems (ZAIM) Q3(Sep) amount funded up 42% over Q2, 4.3% YoY. [SP=2.76 Cap=11m]
Totally (TLY) H1 rev up 10%, pretax £0.1m (-£2.6m). Div 0.25p. "Continues to see increases in demand for some services as a direct result of COVID-19 and expect this to increase during the second National lockdown." [SP=17.4 Cap=32m]
In line: One Media IP (LON:OMIP)
Also: Aukett Swanke (LON:AUK) warns on FY, expects a small loss.
// Third Quarter Trading Update
// Like-for-like gross profit up 23% in third quarter and 16% year-to-date reflecting client conversion at scale
// Trading Update
// Despite the ongoing Covid pandemic, trading continues as expected.
// Q3 Report to 30 September 2020
// If of interest
// Trading Statement
// Revenue for the first nine months was £1,378m and only 1% lower than the prior year
// Statement re covenant amendment and liquidity update/
/ As previously indicated in the trading update of 15 September 2020, FirstGroup plc ('FirstGroup' or the 'Group') expects to report a small adjusted operating profit for the seasonally weaker first half of the current financial year.
// Full Year Trading Update and Notice of Results
// As a result of the travel restrictions in place and low levels of consumer confidence, the Group experienced a varied trading performance through Q3 and Q4 with booking volumes down 75% and 53% respectively YOY.
// Trading update
// Strong trading in October, combined with expected orders for the remainder of the year, will result in full year performance ahead of market expectations, which have already been revised upwards several times this year.
// Third quarter update
// In the first three quarters of 2020 the Group conducted 61,700 funerals (September 2019: 52,100) in the United Kingdom.
// Operations and Trading Update
// Membership grew from reopening until the second half of September, when the emergence of a second wave of Covid-19 meant member levels started to decline with total membership on 31 October 2020 of 639,000. Despite this, over the three-month period ongoing paying members were up 2.4% at 588,000 compared to re-opening
// Interim results
// Group turnover of £54.1 million (H1 2019: £49.2 million)
// Half-year Report
// Plant Health Care and Wilbur-Ellis sign Agreement/
/ Plant Health Care® and Wilbur-Ellis® Agribusiness enter into Joint-Development Agreement for PREtec products
// Contract Win and Trading Update
// Revenue is expected to be between $1m and $1.8m, depending on the customer's take up of additional services which are currently under discussion.
// Trading Update
// Countering the ongoing wider macro challenges, the Company continues to trade in line with market expectations and expects to report revenues for year of circa £4m and EBITDA of £1.4m, an increase of 14% and 30% respectively on the prior year. One Media retains a healthy cash position with an unaudited cash balance of £6.7m as at 31 October 2020.//
// Third quarter 2020 trading update
// Zaim saw a recovery in amounts funded back to almost pre-pandemic levels with a 42.3% increase in the amount funded in Q3 2020 compared to Q2 2020 mainly due to the expansion of its online business platform (a dip of 9.5% vs Q1 and an increase of 4.8% on Q3 2019).
// Launch of Nuvec® Oncology Treatment Programme
// announce that it has appointed Nanomerics Limited ("Nanomerics") to investigate the potential utility of Nuvec® in cancer therapy.
// Trading Statement
// Continued to operate through a pre-booked appointments model and have achieved a good sales rate of 0.76 homes per outlet per week in the second half of the year to date (2019: 0.93)
// Interim Trading Update
// Our total revenue increased by 12% compared with the first nine months of 2019.
Thanks Holland,
The Tp Icap (LON:TCAP) is an interesting stock, full disclosure: I know this company as I used to work there. MY personal view is that tonnes of mgt flab that could be cut -but you could say that at most large corps. However, at this price it looks cheap. It has triggered bargain investing screen light. But then is it a value trap. Tks for the updates as always.....
Morning, Would it be possible for Jack to comment on the Codemasters Group (LON:CDM) Codemaster takeover proposal that came out late Friday, appreciate he has covered before. Not much of a premium yet it has a healthy institutional shareholder base, will they have been consulted?
Codemasters Group (LON:CDM) Not much of a premium yet it has a healthy institutional shareholder base, will they have been consulted?
I believe holders include Andy Brough, Mark Slater and Keith Ashworth Lord (through Free Spirit). Together they have more than enough clout to challenge the low ball take over proposal for Codemasters?
Free Spirit holds but doesn't make the top ten. It's 4.2% of their total NAV of £28.5m so they have £1.2m out of the CDM market cap of £716m.
Hi Andy,
We hold Codemasters Group (LON:CDM) in the Investment Club (pitch found here), so we're following the the proposal too. It's fair to say we view the premium as too low and would vote no here. It's a bit of a surprise... CDM has great proprietary tech in its racing-optimised video game engine and some powerhouse game franchises like F1.
I would have thought Slater et al would view this offer as cutting off material medium to longer term upside so we'll see if institutional holders challenge the bid or a rival offer materialises. They've got to be looking for more of a premium... I'm disappointed to see the board intends to recommend the offer.
Seriously need to review the rules around what management have to disclose in terms of what gets offered to them post takeover....
While, as a holder, I am also disappointed that Codemasters Group (LON:CDM) is looking like it is giving up some upside, I am also acutely aware that the last time shareholders overturned a management recommended bid was £RBG. That takeover, turned down at 205p, looks so dreamily far away from todays 11p that I am going to be very cautious indeed about messing up Codemasters