Small Cap Value Report (Mon 9 Oct 2017) - ACRL, YOU, XPP, IPX, CPX

Good morning folks!
Accrol Group (LON:ACRL)
- Share price: 132p (pre-suspension)
- No. of shares: 93 million
- Market cap: £123 million (pre-suspension)
Paul speculated last week that this tissue supplier would not be put into administration over its net debt, which was last reported at £19 million.
Today we have confirmation that directors think a solution will be found:
The Directors believe that the current challenges facing the Company relate largely to FY18 and are likely to have less of an impact on the Company's trading performance in FY19. The Board are therefore confident that, whilst there can be no guarantee, a solution will be found to the Company's short term funding requirements.
Certainly, this is comforting. What is the probability of a solution being found, then? 60-70%. perhaps?
If a solution can be found, it then becomes a question of how much dilution is needed to steady the ship.
The PE outfit which floated Accrol is still on the register. I'd strongly suspect they are more interested in continuing to divest rather than increasing their stake. So it will be up to the nearly half a dozen other institutions involved, in cooperation with the bank, to figure it out.
If we assume that earnings will return to an approximately "normal" level next year (PBT c. £8 million), but then apply a discount for loss of trust over this incident, and for the debt level, and for the potential HSE fine, then existing equity looks worth maybe 40% of the level it was at pre-suspension?
YouGov (LON:YOU)
- Share price: 300p (+2.6%)
- No. of shares: 105.1 million
- Market cap: £315 million
Some nice results from this market research firm, suggesting that I've been too harsh on it in the past. Although valuation remains a concern.
Current trading is in line with expectations.
For the year ending July:
- Group revenue increased by 21% (9% on a constant currency basis)
- Data Products and Services revenue up by 37% to £47m (24% on a constant currency basis); now represents 44% of Group total (2016: 38%)
- Cash generated from operations (before paying interest and tax) increased by 37% to £19m (2016: £14m)
Excluding the currency tailwind arising from US/international sales, the constant FX growth is stronger than the market as a whole and it has been for 3 three years now. Bear in mind that the growth is being achieved organically, which is always encouraging and actually not very common!
Organic growth has had the side-effect of leaving the company's cash balance to grow, another bonus for shareholders.
Staff numbers are up by 87 to 779 - very important to keep track of this. Staff costs are 50% of revenue.
My opinion: I'm increasingly impressed by YouGov as a business. From what I can gather, it is a true market leader, with excellent international growth opportunities.
My main gripe is with the accounts. I think the accounting rules are there for good reasons, and the amortisation of intangibles (which YouGov ignores for its adjusted profit measurements) are an important part of the accounts. YouGov spent £7 million on intangibles according to these figures, including £3.5 million spent on recruiting people for its international panel.
These costs need to be accounted for, not ignored, so I would trust the £4.6 million net income figure before I trusted the adjusted numbers. On that basis, I still can't justify the market cap here!
XP Power (LON:XPP)
- Share price: £30.825p (+7.4%)
- No. of shares: 19.2 million
- Market cap: £591 million
Thank you to readers for the requests for coverage of this stock.
I last covered this supplier of power components at the half-year report in July.
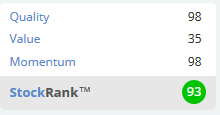
It was a Greenblatt "Magic Formula" stock at the time, although the Magic Formula Ranking has deteriorated a little since then due to a declining earnings yield (i.e. the valuation has increased). Return on capital is still excellent.
These attributes are encapsulated very well in the breakdown of its high StockRank:
So let's take a look at today's Q3 trading update:
Trading in the third quarter has been robust. Revenues for the nine months ended 30 September 2017 increased by 34% over the prior year to £123.9 million (2016: £92.6 million). In constant currency the increase in revenues was 21%.
Regular readers will know that I always focus on constant currency changes whenever possible. In this case, 21% is a fine result.
That's organic growth but the company is also looking to make acquisitions and indeed has already made a £17 million acquisition (announced last week). It used a new debt facility to complete the deal, so net debt is now c. £11 million.
XP pays quarterly dividends and increases the next dividend to 49 pence, up 9%.
Outlook is excellent and the full year looks set to be ahead of expectations:
We are encouraged by another quarter of strong order intake with our end markets remaining buoyant.
The Group believes it is continuing to take market share as its portfolio of industry-leading power technology products is increasingly designed-in to new equipment by our target customers. These design wins will translate in to orders as our customers’ projects move to production phase over the coming years.
My opinion: It's hard to find any faults here. XP is designing most of its own products, so it's got control of the intellectual property which is generating so much of the value here. It's enjoying real underlying business momentum and the acquisition strategy doesn't look too aggressive.
A premium rating is deserved and so in my opinion it's quite possibly still a buy at current levels.
Impax Asset Management (LON:IPX)
- Share price: 150.5p (+7%)
- No. of shares: 127.7 million
- Market cap: £192 million
It's a Q4/full-year update for this environmental asset manager.
AuM increased by another 9% in Q4 to £7.3 billion. That's pre-closure of the recently-announced US acquisition, which is set to take total group assets over £10 billion.
The movement can be broken down as 6% increase from flows and 3% increase from growth in the existing assets.
That's another fine result. The full-year result is 46% increase from flows and 15% increase from growth in existing assets.
I think it's worth adding a bit of caution that a small number of additional mandates can make a huge difference to the flow results. These are large and potentially one-off transactions.
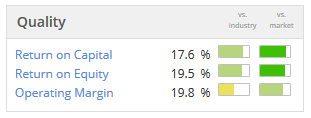
The market cap to (pre-acquisition) AuM ratio is now 2.6% which is fairly average among asset managers as a whole, although arguably still inexpensive against active or specialist asset managers. Schroders (LON:SDR), for example, is trading at 2.3% of AuM. I would argue that Impax is a lot more specialised, although you could also argue that it's a lot riskier compared to its larger rival.
On balance, I'm still positive on Impax. I expect these quality ratios to improve in the years ahead, with increased scale.
CAP XX (LON:CPX)
- Share price: 15.125p (-2.4%)
- No. of shares: 298 million
- Market cap: £45 million
Audited results for the year ended 30 June 2017
Thanks to readers for the suggestion to cover this one, too!
I haven't looked at it before, and note that it is headquartered in Sydney. Accounts are denominated in AUD.
It's still early-stage:
Sales revenue of A$4.1 million (2016: A$5.0 million) and EBITDA loss of A$1.2 million (2016: A$0.7 million) in line with guidance announced on 7 June 2017
Royalty revenue of A$0.7 million (2016: A$0.2 million) up 177%. Q4 Murata royalty up over 50% on prior quarter, following major new product launches during the year. Introduction of additional product ranges by AVX during the year
Despite the worsening overall result (pre-tax loss is A$1.7 million, widening from A$1.3 million), the Board reckons that the IP/patent portfolio is in "strongest position ever".
The results published are for the year ending June. There is a lot happening at the company which might improve future results, e.g.:
- New licensing deals ("at least some of these to successfully close").
- Sales inquiries for prismatic supercapacitors are "at record levels". First large volume design win already announced.
- High-volume orders are expected in current financial year in relation to further IoT design wins.
- Negotiating with manufacturers over automotive opportunities which currently with customers for evaluation.
Cash is A$3.9 plus A1.5 million tax rebate expected.
The tone, as you might have guessed, is very positive. Interest in the small product range is "sharply on the increase" from the IoT (Internet of Things) market.
My opinion
I rarely go for "blue sky" shares although I try to keep an open mind as to whether or not they might eventually succeed.
In the case of Cap-XX, it does have a partial explanation for the fall-off in sales, as its manufacturing plant produced nothing for 7 weeks.
But I think scepticism is the right stance to take. It's not a new listing. Indeed, it listed all the way back in 2006, with the same founder-CEO in charge. At the time, it said:
'Floating on AIM is a real milestone for CAP-XX and is pivotal in our Company's aim to become the number one supplier of supercapacitors into the mobile devices market.'
'We believe that there is a fantastic opportunity in this market, as mobile handset providers seek to provide increasingly power hungry applications, such as quality flash photography. At present there is a widening gap between the power these applications require and the power current battery solutions provide. The attributes of the CAP-XX solution means we are ideally placed to capitalise on this by providing an immediate and easily accommodated solution to the issue of power in mobile devices.'
As you can see, back then it said that its products were going to revolutionise the next generation of mobile phones. Today, it says it is going to revolutionise the Internet of Things.
Anything is possible but scepticism is the correct stance, especially in the absence of confirmed sales.
That's all I've got time for today. Thanks for the requests and I'll see you again later this week!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
38 comments
If Accrol sell the Bentleys and Lambo's that would be a start back on the right road!
Without repeating to much what others have already contributed regarding Accrol Group (LON:ACRL). This for me was a little bit out of the blue. This was on my watch list for a while as expansion plans looked promising, however carrying out my due diligence reading Pauls reviews, the cards seemed stacked against me and I never took a position.
So I would like to say thanks again Paul for your efforts, I dodged a bullet with this one.
Sean
I think Stonegate will have to up the bid price for RBG. It's too low. Artemis pulling out just confirms that. Deltic is a distraction - but confirms that Stonegate are taking the piss at 203p.
P.
Stonegate would have done the rounds of big shareholders and I think if they don't believe they have the votes at 203p, will of course be silly not to up their bid and secure some binding vote commitments ahead of the EGM.
XP Power (LON:XPP) while I have done well out of this. I first bought 2012 and 4 times subsequently all below £17 and have received 16% of my investment back in dividends. That said I have been guilty, as Buffett would put it, of thumb sucking because I should have bought more of this stock, as I was convinced of its quality/prospects. But with the reason parabolic rise I find it difficult to buy some more at £31 or am I guilty of price anchoring!?
May well make a small purchase on a pull back from today's rise.
I'm a great supporter of XPP and wish it well. You do have to understand that the IP is not that valuable, basically they make power "bricks" and while they own the design, making new designs is not that difficult, their real "moat" is the Vietnamise very low cost factory they have built over the last 10 years or so.
Interesting announcement from DX (Group) (LON:DX.) this morning. Significant new funding (albeit expensive) and very experienced new management who will be putting substantial skin in the game (albeit on preferential terms).
Still very high risk, but enough to tempt me to take a punt.
Effortless Cool
Did I get this right that if the £24 m loan notes in £DX are converted in 3 years, withthe PIk interest, there will be another 297 million shares issued?
That looks about right, which clearly restricts the upside, to an extent. But if the new directors want to make serious money out of this, they need to get the share price significantly above 10p.
My speculative investment is based on the belief that Gatemore has headhunted executives with strong records and relevant sector experience and the fact that those executives are willing to back themselves with material risk capital.
Hopefully the new DX (Group) (LON:DX.) management team will be less accident prone than the old guard. I bought into the company after its catastrophic profit warning in 2015 took 80% of the share price and it has been downhill ever since with failed planning applications for a new distribution centre, the strategic asset combination with John Menzies hitting a brick wall and the underlying business falling off a cliff. Amazed that Gatemore still keep pumping in fresh capital. The new deal will dilute the existing shareholders significantly but at least gives them/us one last roll of the dice. Today's 20% or so share price rise illustrates just how desperate things had become.
Picking up on an earlier comment, yet another high quality IPO from Zeus!
Gus.
Re DX (Group) (LON:DX.) Gatemore appear to be exhibiting a classic case of 'escalation of committment' - faced with increasingly negative outcomes from a prior investment they are choosing to plow on rather than alter course.
There's a great ten-part BBC4 series 'The Vietnam War' currently being broadcast on Monday evenings. As early in the conflict as 1965 the Americans similarly displayed an escalation of commitment rather than walk away:
Possibly, but some successful turnarounds look like that too -- to keep the war metaphor, look at the behaviour of the British government in 1940 just after Dunkirk, why not choose to become a quiet and orderly German province, instead of that escalation of commitment policy they chose in the face of what was, at the time, a formidable opponent?
But I suspect your view will be widespread, among PIs in particular, in the short term, so that it seems highly likely the price will languish down for a year or two before the actual turnaround. Also the principals don't seem interested in convincing PIs -- the announcement seems intended to fulfil regulatory requirements rather than convince, as there's little details on plans and strategy, which will reinforce this effect. So far, it looks like one for the watchlist.
Accrol looks a complete disaster - but is there a chance it could become a takeover candidate in a recapitalized form (assuming that will happen?)
I'd second you taking a look at CAP XX (LON:CPX) Graham, just a small position for me and very forward-looking. Ta!
I have always had some reservations about ACRL but a company with £135M of turnover, apparently up-to-date production lines and a product that is needed by the discounters/supermarkets must have some value. If it comes back to the market it could be that the initial fall will be overdone.
Bit of a discussion on XP Power (LON:XPP) here:
https://www.stockopedia.com/content/i-read-the-news-today-oh-boy-9-oct-2017-226378/
It would be good to hear the pro's views on it too.
Graham,
I applaud your optimism on ACRL.
Over many years investing there are two statements that fill me with dread:
'...the Company is engaging with its major shareholders and its bank.', and
'...pending clarification of its financial position.'
Both have been deployed by ACRL and I fear the worst. If you were a banker faced with management incompetence from lack of hedging and foresight as to the effect of a falling pound, failure to admit to a major H&S failure and plunging profits, would you want to increase your exposure? I for one would not.
And if I were to be persuaded, a bank appointed Chairman, CEO and CFO would be my starting point.
Yes I would tend to agree Jasperthedog and I have a nasty feeling that some of Accrol's major customers may also want to eliminate exposure to the company, particularly if there is any suspicion of unethical behaviour over the H&S failure. I think there is still a chance the company may go down the pan.
Accrol's major customers are only interested in getting their product at the lowest price possible. Anything they say to the contrary is totally divorced from reality.
The announcement by Digital Barriers (LON:DGB) of the proposed sale of its main business contains some financial details. Has anyone managed to do a rough estimate of the post-disposal enterprise value for the residual Thruvision business? (which is in a growing market, though I don't know what their competitive position is, or their patent protection).
Hi Graham, I would be grateful if you have time to run your slide rule over CPX results today. They manufacture supercapacitors. Starting to look very interesting now upon reading today's results...
Regards DH2.
Hi DH2, I've taken a look at it! Ta.
Hi Graham, much appreciated.
DH2.
May I please add another vote for XP Power (LON:XPP) if you have the time Graham? (disclosure: I hold)
Hey Astongirl, I've added XP Power (LON:XPP). Thanks for the suggestion!
Regards
Graham
XP Power (LON:XPP) Thank you Graham :-)
Like purpleski I felt I was price anchoring having been holding since 2015. Whilst I haven't had the phenomenal 15x gains of some respected investors who have held for longer, I did add a few more in August using the 'fresh eyes' investment case.
I also like to add on an ahead of expectations statement so I too shall be watching the price closely this week.
Well done to all holders.
Hi Graham. I expect I'm not alone waiting with bated breath on Paul's latest RBG instalment especially with tomorrow being deadline day for Deltic. Would also be great to hear a view on XPP after another stellar update this morning. Many thanks as always to you both for such great insights.
You're not alone indeed.
Exciting times. Can we expect an increased offer from Stonegate? Here's hoping we do.
I can't see Stonegate unilaterally upping their bid for Revolution Bars (LON:RBG) without some pressure being put on them by Deltic (or another bidder for that matter).
Meanwhile, Revolution Bars (LON:RBG) 's existing management seem to have run up a white flag and surrendered to Stonegate without much gumption. This morning's rebuttal RNS of the Deltic merger proposal by RBG reads as though it was written by Stonegate (perhaps it was?) so absent a funded cash offer from Deltic - which seems unlikely without a significant third party backer - I fear the current 203p is all we're likely to get.
Gus.
Hi Graham
Do you have time to cover Impax asset management or XP power ?
Thanks
Thanks for mentioning XPP (and Astongirl too), to me this update looks VERY good with a substantial increase in trade/orders, and they still look pretty good value; hopefully the recent acquisition will boost numbers further in time.
I wish I'd bought IPX after the half-year update... but with the share price now up 50% in about a month I have to question the amount of frothy euphoria in it now and wonder if an amount of the portfolio rise is just due to general positive market movements...?
BTW, I notice IMO are up 12% on relatively heavy buying volume all of a sudden, after days and days of selling, with no announcement. Has anyone heard a rumour...?
Hi Jesse, covered them both. Thanks for the request!
Graham
Thanks Graham and for making me aware of Impax in the first place . heard the CEO present recently and he did mention that Impax shouldn’t be expected to trade on the same rating of AUM as fund managers that have a higher percentage of funds directly from retail investors . A high percentage of impax AUM is from institutions on an average fee of around 0.5%
Hi graham re. Accrol Group (LON:ACRL) you suggest a post suspension price of around 40% of 132 = 53p.
My fag packet calc goes like this. The directors say earnings will be significantly less. So let's say half 2017's = 5p.
Pre suspension PE was 10. With a debt loading and distressed status, let's say appropriate PE = 6. That makes post suspension share price = 30p
Of course, this is a guestimate as there are huge variances in the underlying numbers and assumptions.
Personally if I wanted to take a punt I would start being interested in taking a long position at a price below 35.
Ram,
Accrol Group (LON:ACRL) are dubious on 3 points - The forgotten H & S issue, not sufficiently covering forward purchases and not informing the market sooner about their higher paper price with its likely squeeze on margins. There is now virtually no price at which I would take a punt on their competence, or honesty.
The article below was written only 16 months ago what I have learn from this sorry affair is that company like Zeus who promoted this particular IPO should be treated with caution I am not blaming them entirely but surely somebody must have know something about the accounts where was the due diligence ? It is also interesting that since the founding family exited it appears that the only director that own shares in the company is Stephen Crossley (NED) around 130k based on pre suspension value which he acquired one year ago it would appear no other directors hold any significant position hardly a vote of confidence makes me very wary of IPOs at present .
Peter Cheung, Executive Chairman at Accrol Group Holdings, says: “We are delighted by the level of interest and support we have received from high quality institutional investors and I would like to thank the team at Zeus Capital for delivering a seamless transaction. We are a very well invested company with an attractive and progressive dividend policy and we look forward to creating value for all of our shareholders in this new and exciting stage in Accrol's development.”
Dan Bate, Director at Zeus Capital, says: “It is a pleasure to advise Accrol Group Holdings plc on its admission to AIM, GBP63.5 million fundraising and new GBP38 million debt facilities. The Hussain family has built up a successful business since it was founded in 1993 and will be stepping back as part of a managed hand over process to the executive team. I am confident that with the support of its new institutional investors, Accrol will go from strength to strength as a public company. I am delighted also to have supported NorthEdge on the successful completion of the first exit from its maiden fund.”
Dan Wright, Head of Portfolio at NorthEdge Capital, says: “We are delighted to have partially exited our first investment from Fund I by way of IPO. We believe Accrol will go from strength to strength on AIM as a public company, thanks to the strong shareholder base, management team and underlying operations of the business. We look forward to a new chapter in Accrol’s development.”
My morning smallcap tweet:
Earthport (LON:EPO), Digital Barriers (LON:DGB), City of London Investment (LON:CLIG), Accrol Group (LON:ACRL)
Earthport (EPO) wins first contract in Germany from ECB Swiss Euro Clearing Bank ("SECB"), a major euro payment clearing hub for Swiss banks, to provide SWIFT payments. I am short.
Digital Barriers (DGB) sells its main business for £25.5m + £2m earn-out, following the disappointing financial performance of the Existing Group. A review confirmed that the unpredictable nature of the sales cycles the Group faced was unlikely to change in the near to medium term, and larger sales would exacerbate the lumpy nature of revenue streams. Leaves Thruvision, a people-screening business. Cap at 18.875p is £31.2m.
City of London (CLIG) AGM: Q1 Trading Update. FuM $5.0bn (£3.7bn) up by $0.3bn in the Q. Q1 pretax £2.5m (£2.3m, after an unrealised profit on seed investments of £0.2m).
Accrol Group (ACRL) "The current challenges facing the Company relate largely to FY18 and are likely to have less of an impact on the Company's trading performance in FY19. The Board are therefore confident that, whilst there can be no guarantee, a solution will be found to the Company's short term funding requirements."
The City of London Investment (LON:CLIG) update was encouraging this morning and it now has its highest ever funds under management in terms of US dollars if not British pounds. I think this is an excellent fund management company which is trading relatively cheaply at about 11-12 times last year earnings. Just to flag to readers it goes ex-dividend on the 12th October which equates to about 3.7% so this is quite a good time to get in. Although there is usually a bit of a drop on ex-divi day which may be preferable to wait for depending on how fussed you are by the income. The main risk with City of London Investment (LON:CLIG) is if you think the outlook for emerging markets looks poor. I am long.