Small Cap Value Report (Mon 9 Oct 2023) - SCS, VLX, MCON, VTU, MIND

Good morning from Paul & Graham!
Today's report is now finished.
Podcasts - it was too hot here in Gozo for me to feel motivated to do anything energetic over the weekend, so I stayed in and recorded podcasts instead! Here we are, there are 2 for this weekend, with loads of (hopefully interesting) small caps news & views.
The burning issue this morning will be what happens at Metro Bank Holdings (LON:MTRO) - press reports are giving sketchy details of a deal having apparently been done, with an existing shareholding injecting more equity to take a controlling stake (at what price/dilution?) and apparently one level of bondholders taking a haircut. We'll look into the details once they are announced. Why anyone would want to be a small shareholder in a precarious bank, is beyond me - way too high risk. I discussed this one in the weekend podcast. What does impress me however is how fast regulators are now forcing refinancings at troubled banks - so far, preventing wider contagion. EDIT: apparently new shares will be issued at 30p, so not a bad outcome at all for existing shareholders, at first sight - but why did any small shareholders take the enormous risk, when they didn't have to?
Graham went into more detail on MTRO refinancing in his daily youtube show (recording here), flagging that he went AMBER on MTRO last week, because he thought the balance sheet numbers weren't bad enough for it to be a zero. Since a solvent solution for equity does seem to have been agreed over the weekend, thanks to a white knight investor buying new equity in what will be a controlling stake, then I suppose Graham's view has been vindicated! However, I maintain that risk:reward was terrible, since the positive outcome has only resulted in (at time of writing) a 16% gain in share price to 53p, which in order to have achieved this gain, shareholders ran a very big risk of a 100% wipeout. So regardless of outcome, risk:reward was terrible on this trade!
Reminder for Mello Monday - starting 17:00 tonight - 2 interesting companies presenting, both of which we've reviewed recently, Equals (LON:EQLS) and accesso Technology (LON:ACSO) . Also a guest interviewee, who David tells me has lots of interesting insights.
Graham's Youtube channel - I think it's fine to promote this here, as it's free, and Graham has confirmed he does NOT take any fees to promote individual companies (of course neither do I!) - our views are totally independent and honest, which can't be said of everyone giving views on shares out there. Graham's channel is a live show at 11:30 each weekday - not sure how long he'll be able to keep that up, sounds like a lot of work to me, to do straight after co-writing the SCVRs. It looks complementary to me, so I'll check it out myself when it starts shortly. He's going to mention MTRO in more detail I think, which saves me a job here! I think anyone putting out decent quality, independent content deserves our support & encouragement.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries -
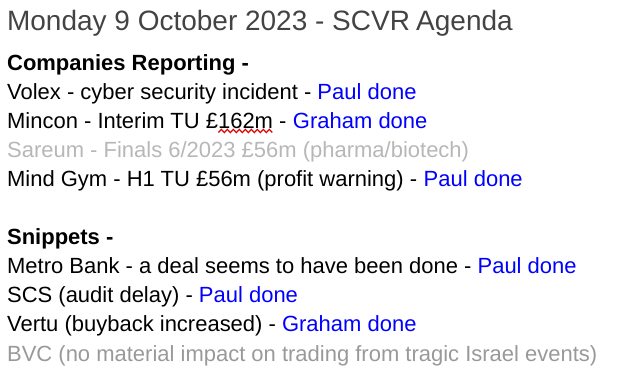
SCS (LON:SCS) - 167p (pre market) £56m - Audit delay - Paul (I hold) - GREEN
Audit delayed by a fortnight, but confirms results will be in line with previous trading update. So probably not a concern, but might trigger an attack of the vapours in this nervous market, who knows?! As audit delays are commonplace, and results in line, I'm sticking with my positive view from 3 August.
Volex (LON:VLX) - 310p (pre market) £563m - Cyber incident - Paul - GREEN
Reveals it has been hit by hackers, but reassures it's not impacted operations, and financial impact not material. So at this stage I'll give it the benefit of the doubt, although obviously unimpressed with IT security not being up to scratch.
Mincon (LON:MCON) - down 5% to 72p (£158m/€183m) - Interim Trading Update (profit warning) - Graham - AMBER
This is down by just 5% despite the 2023 EBITDA forecast being slashed by nearly 30% (the prior EBITDA forecast is not included in today’s RNS). Weak mining demand and some other issues are hurting performance; I still think this has long-term potential and I remain neutral.
Vertu Motors (LON:VTU) - down 0.7% to 70.8p (£243m) - Share Buyback programme - Graham - GREEN
Just a quick note to say that Vertu is again enlarging its buyback programme. It originally announced a £3m buyback in May, then in June announced a further £3m. Today it announces another £3m! Paul observed recently that they had bought back 14% of the whole company in 7 years; the share count has fallen from a high of almost 400 million in 2018 to 341 million today. The stock trades at a PER of about 7x; I love to see companies at cheap valuations calling the market’s bluff and ploughing cash flow into their own stock. If they can keep this up, it has great long-term implications for EPS (so long as their underlying earnings power doesn’t fall off a cliff!). See Paul’s detailed comments for a longer discussion of the factors at play here.
(Paul adds - although bear in mind VTU took on a fair bit of debt to acquire Helston, so I'm a little surprised it's effectively using debt to fuel the buybacks, but it depends how you view it!)
Mind Gym (LON:MIND) - down 38% to 34.5p (£34m) - H1 Trading Update - Paul - RED
This looks a right can of worms! A big profit warning today, and scrutinising the last accounts, I see it's capitalising almost £5m of internal costs onto the balance sheet as development spend, with only a £740k amortisation charge! So the previous profits are not real (in cashflow terms). It's now set to burn through the rest of its cash pile by March 2024, according to Liberum. I would deploy my bargepole for this one. Pity, as it traded well pre-pandemic, but clearly has problems now.
Paul's Section:
SCS (LON:SCS)
167p (pre market) £56m - Audit delay - Paul (I hold) - GREEN
Says today that its FY 7/2023 results will be delayed from 10 Oct to 25 Oct.
It doesn’t give a satisfactory reason for the delay, but does reassure that the numbers will be in line with the FY TU (full year trading update), and that the board has “no concerns whatsoever”.
Paul’s view - audit delays seem commonplace at the moment, probably an overhang from the effect of lockdowns, with not enough trainees going through the system, I’m guessing.
Since ScS has specifically stated that the results are in line with expectations, then I’ll stick with my GREEN view, explained here on 3 August, with an in line TU, reassuring on order intake, and a cash pile larger than the market cap (which continuously rotates, it’s not a seasonal spike). I concluded it looked remarkably cheap, and has remained so! At least ScS shareholders can relax, knowing that they can ride out any downturn in demand, if one arises. Unlike DFS, with its crazily geared balance sheet (but much better brand and market share). [no section below]
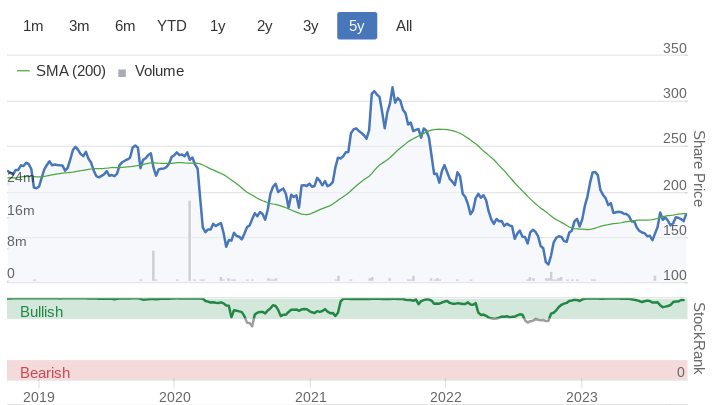
Is the chart forming a base I wonder? Note the consistently high StockRank -
Volex (LON:VLX)
310p (pre market) £563m - Cyber incident - Paul - GREEN
Another all-too-common problem is companies being hacked - I assume by fraudsters who demand ransoms in bitcoin maybe? Although I’ve heard some IT people say that successful attacks expose poorly managed, insecure IT systems, so it doesn’t reflect well on the company’s IT people.
Consultants have been brought in to investigate. Actions taken to stop unauthorised access. All sites remain operational. “Minimal disruption”, and “Group continues to trade…” (I should hope so!).
Key point is, “At this stage, any financial impact resulting from the incident is not expected to be material”.
It might cause a markdown in share price today, I imagine, but I don’t see anything serious enough to change my GREEN view of this expanding group, with shares reasonably priced, and its key sectors seemingly enjoying industry tailwinds - so hopefully we can avoid a profit warning here, but I can’t be sure about that.
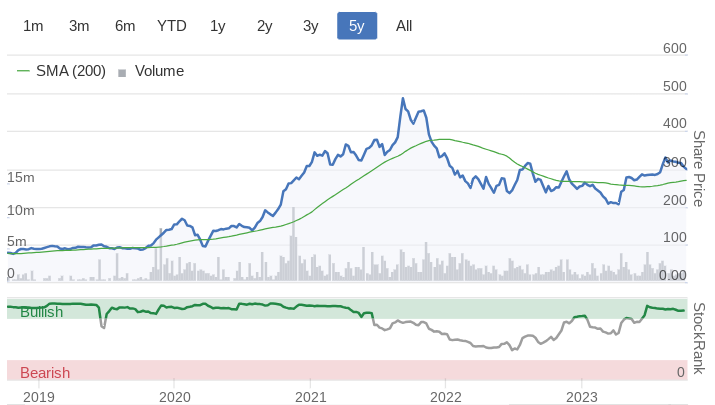
Another one with a high StockRank -
Mind Gym (LON:MIND)
Down 38% to 34.5p (£34m) - H1 Trading Update - Paul - RED
Mind Gym (AIM: MIND), the global provider of human capital and business improvement solutions, provides a trading update for the six months ended 30 September 2023 and updated outlook for the year ending 31 March 2024 ("FY24").
H1 trading has been below expectations.
Blames customers delaying or cancelling spend, due to macro factors.
Cost-cutting is underway, to reduce overheads.
Capex in H2 also being reduced - I’m surprised to hear capex mentioned for a services business, so it looks like they’re maybe capitalising internal costs? Oh blimey, yes they are, big time! I’ve just checked the last accounts, and it capitalised c.£5m in each of the last 2 years of development spending, whilst only amortising £740k in FY 3/2023. This means profits turn into negative cashflow, in both of the previous 2 years. That’s enough to rule it out for me, so by all means skip the rest of this section, as I’m going to conclude negatively.
Revised guidance -
As a result, the Group expects to report H1 FY24 revenues of c. £21m, (H1 FY23: £26.8m) and a loss at EBITDA level. The Group now expects FY24 revenues and profits to be significantly lower than current market expectations even though we have seen an improvement in market activity reflected in increased bookings for Q3 versus the comparative period in the prior year. Our H2 performance is expected to be stronger than H1 with revenues broadly similar to, and underlying EBITDA margins ahead of, the respective levels in H2 FY23.
Liberum update - many thanks for crunching the numbers. It’s really bad.
FY 3/2024 revenue forecast drops from £62.6m to £48.4m
Adj EPS goes from 4.7p positive, to (2.0)p negative.
Forecast year end net cash revised from £8m to just £1m for March 2024.
Paul’s opinion - this is really bad. Before investing or holding here, you must look at the cashflow statements. These show the profits are not real! It’s capitalising a ton of payroll (development spending) onto the balance sheet. This is why it’s burning through the cash pile, despite reporting adj profits. With Liberum forecasting almost all the cash will be gone by March 2024, I suspect this share could have much further to fall.
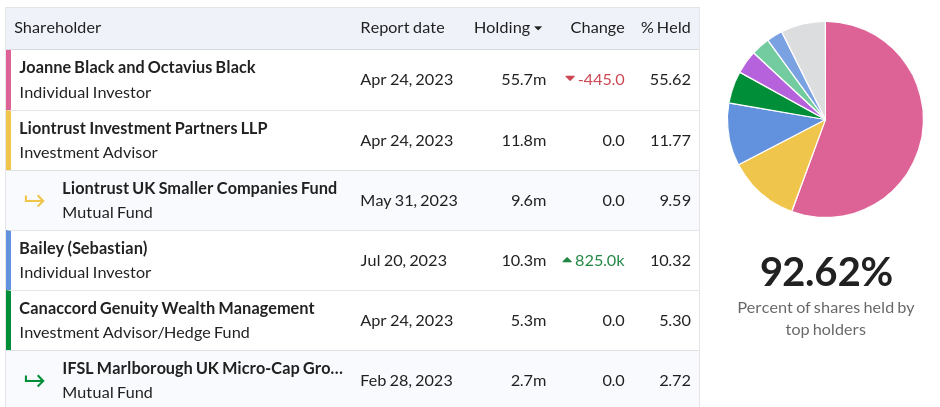
It’s owner-managed though, which usually means resilience, but it could also mean delisting risk, since the CEO owns 56%, with 2 other large shareholders meaning that the free float is small.
Historic performance before the pandemic was good though, so it’s not clear what’s since gone wrong. I’m not going to stick around to find out, as the numbers look dreadful to me, it’s a bright RED I’m afraid.
Note that Canaccord are known for brutally ditching stuff that they lose faith in, so I'd be worried to see them on the major shareholder list here -
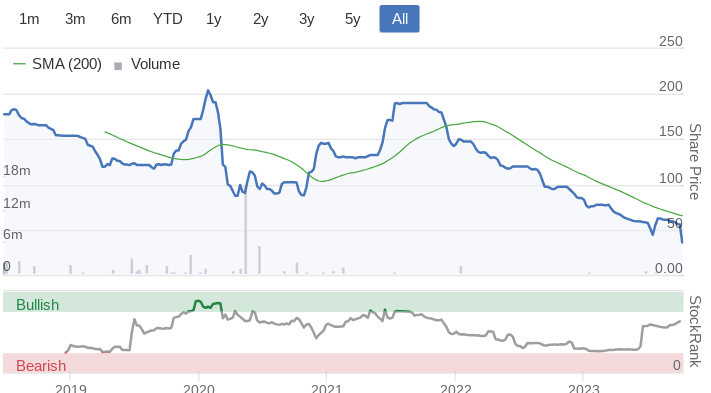
A very poorly performing & disappointing float, to date -
Graham’s Section:
Mincon (LON:MCON)
Share price: 72p (-5%)
Market cap: £158m (€183m)
Mincon Group plc (Euronext:MIO; AIM:MCON), the Irish engineering group specialising in the design, manufacture, sale and servicing of rock drilling tools and associated consumable products, today provides a trading update for the period from 1st January 2023 to date, incorporating the nine months to 30th September 2023.
I last looked at this one back in May, taking a neutral stance as the company attempted to overcome some company-specific and macro challenges.
Unfortunately, this morning’s announcement is a profit warning. Revenues have “contracted” again in Q3. Year-to-date revenues (first nine months of 2023) are down 7% year-on-year.
The macro challenge posed by weakness in the mining sector is mentioned as an ongoing challenge. Additionally, “two large scale construction projects in North America… will no longer take place as planned”.
Other points:
Working capital position has improved, leading to an improved cash position.
Gross margin falls to 30.4% year-to-date (corresponding figure for last year: 32%).
Exceptional cost of €0.8m to implement a cost reduction programme.
Outlook:
In light of the above, looking ahead to the remainder of the year we now expect to deliver full year EBITDA of approximately €20 million. Our outlook for the medium term is positive, we will continue to invest, to improve our competitiveness within our current industries, and focus on delivering new opportunities in current and new industries to deliver better returns for the Group.
Estimates: according to a note published by Shore Capital in August, the 2023 EBITDA forecast at the time was €28 million. So the new EBITDA forecast of around €20 million is almost 30% lower.
The adjusted PBT forecast for 2023 falls from €17 million to only €8.8 million.
(It would be helpful if the RNS included the prior forecast in addition to the new forecast, as companies are increasingly doing these days.)
Graham’s view
Many thanks to Shore Capital for publishing their updated forecasts today. I’ve been neutral on this stock, admiring its long-term profitability while remaining cognisant that the company has had some difficulties over the past year or so.
Here’s a brief financial summary:
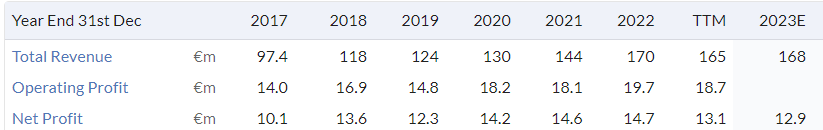
And here’s a summary of the difficulties faced by the company:
Supply chain: I think this is now resolved, with the company reporting today that it has been able to reduce inventory (although seemingly at the cost of some gross margin).
Freight conditions: Mincon previously resorted to using expensive air freight. There is no mention of this today and I believe it has been resolved.
Greenhammer project: this project ran into difficulties earlier this year. The interim results in August mentioned a new test being planned to take place in the United States. This is not resolved.
Demand from the primary market served by Mincon, the mining industry, remains in a slump and this problem is not resolved (but there is little that Mincon can do about it).
Net debt should improve thanks to the inventory reduction; it was last seen at €15m. This is partially resolved.
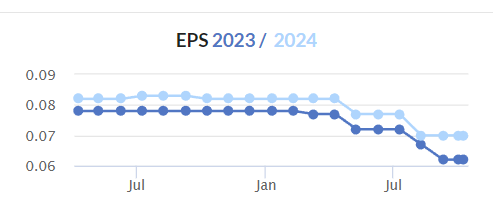
As you can see, it’s a mixed bag. Earnings momentum has been negative:
And valuation still isn’t as cheap as many other small-caps:

So for me, this is a name where I have to remain neutral. If it overcame its challenges, or if the stock ever fell into deep value territory, I think it would be very interesting, but I’m neutral for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Hi
Are there any holders of NB Global Monthly Income Fund (LON:NBMI)
I have just gone through the corporate actions last month and I am missing about 5% of my holding following the recent corporate action. I have just followed this up with AJ Bell today to query what has gone on. Just wondering whether everyone else had the transaction go through fine or not?
I also went back through the previous actions in March, May and July and the balance pre/post redemption was correct for all three, including the fractional.
Thanks
Tommy
Tommy. I hold and the payment looks spot on to what I was expecting. (Do not hold with AJ Bell).
Any followers / investors in SDI (LON:SDI) here? Graham last reviewed them on 8th August (AMBER) when price was 122p. SP has cratered by 35% since with Mkt Cap dropping to around £87m now. There were big insider sales in Oct last year but no meaning buys this year.
ESG Funds and Investment Trusts
Today's fall in the shares of IPX (down 12% to 397) is a reminder of Fashion Investing!
Two year ago you could not buy enough of them at three times the price.
How quickly the table has turned among the investing community small and big. The sentiment has changed massively against ESG but the science behind it has remaind as solid as it was then. It is interesting that the ESG has now become the dirty word but Energy, Tobacco, Weapon manufacturers and the Booz makers have become acceptable investment now.
I have very little doubt that the scientific foundation of ESG (E in particular) has not gone away and sooner or later it will regain it's status as the way forward. Look no further than Nissan decision to discontinue with the combustion engines by 2030 despite the government postponing the ban to 2035. The future is green and investing in that future will be profitable .
Wether now is the time to invest or not is beyond my limited knowledge .
I thought Impax Asset Management (LON:IPX) had done a pretty decent job at limiting their outflows - certainly way better than the Fund Manager I work for has :-(
J D Wetherspoon (LON:JDW)
Interesting to see that Pauls comments friday that he thinks J D Wetherspoon (LON:JDW) is probably overvalued.
JDW shares overshot on the rebound in recent months I think, so seem fully priced for now. But I’m still going to enjoy reading his commentary! [no section below]
If we look at 2025 forecasts for the company they are expectinmg to do 50p eps. This could end up being jackanory stuff but thats pe of under 13. So if they can hit that target i think the shares look reasonable to cheapish rathe rthan being toppy.
Its tricky taking viewpoint here so i dont disagree that its not dirt cheap at present but historically this company has traded at a bit of a premium probably due to the fact its earnings history has been more reliable than others in the sector who tend to struggle more when times are tough.
I went in my local wetherspoons mid saturday afternoon - it was raining and we are into quieter winter season but it was chokka full which i didnt quite expect. I suspect their value ref pricing is ensuring trading is tickety boo.
I feel other than debt being slightly toppy they really are potentially in a sweet spot now. They have certainly concentrated on cash preservation recently so one would hope longterm debt could come down nicely and interest rates being paid long term should be less than now if that does happen and rates paid come down.
What they have done over the last few years is massively up then % of pubs that are freehold - so in some respects high debt and interest payments come with decent extra tangible asset value of property they own outright that they didnt own 12 years go.
In the last 12 years, the company has increased the ratio of freehold pubs it owns from 43% to 70%, as a result of investment in freehold reversions and opening freehold pubs.
ref book value of estate their commentary seems to suggest that the accounts book value might not reflect the true value of the property.
Although there have been a number of impairments over the years in respect of individual properties, the book value of the company's assets is £1.38 billion, which is approximately eight times the company's EBITDA of £170 million. There are many pubs in the estate where expected future cash flows would result in a valuation which is considerably in excess of book value. However, accounting rules do not take account of these potential valuations.
This historical cost accounting approach can also create anomalies in pub valuations.
On the flip side if we look at current year eps estimates of closer to 40p - the company doesnt look so cheap. So i would say on where we are now one may take the viewpoint that one doesnt give them the benefit of higher 2025 expectations. Note i have always though that J D Wetherspoon (LON:JDW) tell it how it is so if they are projecting better times for 2025 i for one am happy to believe what they arte saying.
If anyone is worried about future lockdowns this is completely the wrong share to own with their high debt !!!
I concur with your view that J D Wetherspoon (LON:JDW) is currently undervalued. I have recently turned up at some pubs expecting to have a civilised pre lunch drink only to find that the pub can't be bothered to open until noon. This is clearly not a problem with JDW as they always seem to be open.
My main reasons for thinking the share price is undervalued are:
a. The share price is currently languishing at £6.35 whereas it's pre Covid share price was £16 plus, and I believe that the share price will revert to the mean.
b. Tim Martin the Chairman of the company has bought £18m plus worth of shares this year at depressed prices which suggests to me that he has a lot of faith in the company.
c. JDW shares its scaled economies with customers.
d. Two pubs a day are closing in Britain and I think that those entities that survive will do very well.
e. The gradual return to working in the office should enhance sales.
On a recent visit to London I had to walk out of a Wetherspoons because the the pub was so crowded and I couldn't find a spare table even though it was a Thursday.
I think investors will need to be patient though as the Business Cycle is turning very slowly.
J D Wetherspoon (LON:JDW)
This is clearly not a problem with JDW as they always seem to be open.
I was a little upset last year when trains to london were delayed when i was going to see Pearl Jam at Hyde park and they refused to sell beer before 9 am unless i also bought a full monty breakfast. Perhaps thats just policy in Newcastle keeping the drunks out first thing. Hey ho they were happy to let us sit there and have a coke.
a. The share price is currently languishing at £6.35 whereas it's pre Covid share price was £16 plus, and I believe that the share price will revert to the mean.
Unfortunately you need to factor in the extra shares in issue compared to pre covid - there is 20% plus more shares now in circulation so on lfl basis if they hit 80% of prior highs thats probably pre covid peak equivalent if you are expecting that they will revert to mean. I also think with higher interest rates they currently have to work harder to stand still ref debt - hopefully rates will come back down but no sign they will get as low as they were previously.
Hi rmillaree,
Interesting to see that Pauls comments friday that he thinks J D Wetherspoon (LON:JDW) is probably overvalued.
Except I didn't say that it was "probably overvalued"!
I just said it looks fully priced, i.e. price is up with events, in my view.
As you discuss in this thread, if you think earnings are set to strongly rise, then that could justify paying up for it.
Regards, Paul.
J D Wetherspoon (LON:JDW)
apologies for this misquote there - in my defence i had at first copied your exact comments but somehow lost the contents of my post and made a hash of it the second time around.
Amazing that Mind Gym (LON:MIND) broker retained profit forecasts (wildly optimistic as it turned out) in June, todays profit warning couldn't have been a total surprise, the markets been pricing it in for over a year. Does the company not speak to the broker?
Now you have a company and broker who no one believes, tanked share price, 15% spread, cash spent, poor outlook. Will be crap results in Dec, no doubt with the carrot of better trading to come, but if history is a guide no new update until the end of April. Who wants to be holding this for maybe 5 months with no news. If a company is going to float at least know how to play the game! Maybe the CEO 56% holding means he couldn't care less about the shareprice or informing the market as he'll just look to take it private when it falls low enough. Pathetically amateur state of affairs really.
Mind Gym (LON:MIND) And the auditors are happy with capitalising payroll, are they? And just what is "human capital" anyway?
My simple rule is not to invest in companies that haven't been listed for at least 7 years. This has been listed for 5. It is a mitigation strategy against such ticking timebombs that have been lobbed into the market. No wonder AIM is down nearly half from its peak and below where it was 20 years ago.
Some big movers down today
Impax down 12% (looks like a 5% outflow in the last quarter - but they say year on year is still slightly positive - so perhaps an over-reaction as they appear to have performed better than many competitors over the last year or so - of course the share price was sky high and so the deep sell off may now bring this into buying territory)
Sdi down 7% (sell off continues - perhaps 60p is on the cards)
Shoe Zone down 7% (seems unknown as to why the drop - but retailers have been volatile in this market)
Cerillion down 10% (Actually down almost 20% in about a week - perhaps connected to the profit warning from Spirent)
TT electronics (LON:TTG) probably of no significance but two sizeable trades recorded this morning, off book. Both are shown as buys going through at 170p, in two tranches of 500,000 and 600,000.
I hold; hence my interest. TT electronics (LON:TTG) has been trading well, but the market is completely disinterested as is the case with most small caps
Metro Bank Holdings (LON:MTRO) I gambled on Friday ....and won .Closed out 8:00am.Rarely make such binary bets but felt that a rescue could be achieved and shorts would close....I got lucky. this bank and this sector need to be treated with caution for the time being
Well done! Braver man than me.
Believe me Bouden54 .....it was a long weekend LOL !
For me too much talk of takeover going on. I think if you are building a portfolio of shares on the hope they may get taken over it is a dangerous road. Accepted there are a number of takeovers going on. But to my thoughts you buy good companies, and it may be a potential purchaser agrees with you, but that is not THE REASON to buy a share.
But to my thoughts you buy good companies, and it may be a potential purchaser agrees with you, but that is not THE REASON to buy a share
This is the principle I work to. And it has delivered well on the takeover front, though less well on capital appreciation. Thank you central banks.
Takeovers are irritating...as is the speculation about them :)
If I own the target I relish a takeover - generally 30%+ boost in one day ,how is that irritating ?
I’d never buy for a mere 30%…if I own I expect way more than that. I never buy for value as never a good enough reason in micro/small cap (I like value obvs) and always for duration growth. If someone makes me accept a mere 30% then it’s coercion and close to robbery.
That seems a fair and reasonable view of many a takeover. Right? Very irritating and very unhealthy investment approach to focus on takeovers. Again, right?
I don’t need the validation of others.
And if I’m happy to be taken out…well that means my stock selection has failed and I’m caught in a rather ho-hum company.
So…I think you’ll find I’m right and you probably need to completely overhaul your approach ;)
Have I just found a bot on Stockopadia ?? this cannot be a rational human response LOL !!
Does not compute. Logic failure. Filed under human error 001
That’s one of the values of mojo’s contributions. He seems to always have a unique take on stocks. Which you could love or hate but differing opinions helps fight group think. I’m always interested in mojo’s comments even if I disagree with them ;)
There is absolutely no need to be rude here, It demeans you.
Because of the amount of time spending due diligence - which can be weeks, even months to find that a company you expect to hold for years gets taken out a few weeks after you have bought it. I find this profoundly irritating. I am not a trader - some shares I have owned for more than 10 years
Fair comment James, but I cannot be told "I need to overhaul my approach" when I have been successful over a long period (long and short). Nobody is aware of my risk appetite or capacity for loss.Everybody needs to work within their own comfort zone
Get a grip man SaarfLondon. I'm amazed with your chippiness! I thought you were just messing rather than being upset but turns out you were upset. So, with that hindsight, turns out you were the only one being rude. It was pretty clear that I was giving a view and then jesting a bit and exaggerating about it. At no point were you told to overhaul your approach...I was stating I don't follow it and don't like it (for reasons given).
Maybe discussion and disagreement isn't for you until you've built your confidence a bit more ;)
(NOTE: the last sentence is a subtle dig...tho its not subtle anymore as I've explained it and owned it for the plodders in here...I expect a bit of pearl clutching outrage from somewhere)
U crazy rascal - I thought I was back on Twitter
Takeovers of quality companies are a scourge on the UK stockmarkets. The LSE is not replacing the delisted companies with fresh 'good' stuff.
As a result the pool of 'good' stuff on the LSE is reducing, and we're fishing in ever lower quality waters.
Ask yourself this. Would you rather have Cadburys Schweppes in your portfolio now, or have received cash for the takeover with 30% premium (or whatever) a couple of decades ago? Same could be said of ARM , Reuters etc etc.
But in an unloved market like the UK where there are many undervalued companies... takeovers are one way to unlock that value.
This does not apply if your investment strategy is not to look for undervalued companies. If one is focused on finding companies that can deliver above-average EPS growth in the future, then yes - takeovers is not THE REASON to buy. In fact you want to purposely avoid companies that have a high chance of a takeover - as often they get taken out before their true, future EPS growth story is realised, and thus get taken out at too cheap a price.
Nice spike for Beeks Financial Cloud (LON:BKS) this morning. Rumours of takeover interest or just belated positive reaction to the latest investor presentation?
Re Beeks Financial Cloud (LON:BKS)
I blame Paul's Saturday podcast! Just bought some myself although I fear it may pull back a bit after the initial surge this morning
Hi Westway001,
Well my weekend podcast certainly convinced one investor to buy more Beeks Financial Cloud (LON:BKS) (I hold) this morning - me! I put in buy orders today, but HL dealing platform kept rejecting it, and I had to put in a fill or kill order at 2p above the ask price, to get a fill, on quite a small order. So it seems the overhang of shares that was evident in the market last week (I bought several clips easily during the IMC webinar) seems to have cleared, for now anyway. It's anybody's guess what backed up sellers there might be, so today's rise may not hold, who knows?
Another point is that the recording of the IMC webinar went up, I think, on Friday, so probably would have been viewed by lots of people over the weekend. It's very bullish I think, and was the reason I wanted to buy more, so looks like others have taken the same view.
Regards, Paul.
In my humble opinion it's probably just the forward looking nature of the markets. FY23 figures are now history and given the fact that Beeks Financial Cloud (LON:BKS) missed FY23, FY24 growth forecasts look even better.
What I was pleased about with the presentation was the confirmation that they had not lost the 2nd Exchange opportunity that they mentioned in the H1 presentation. Hopefully we will see it booked this financial year.
Cheers Andy
Beeks Financial Cloud (LON:BKS)
I was encouraged by the IMC presentation broadly because the exchange deal with the JSE is going so much better than expected.
Management say they anticipate £5-20m from each exchange deal and the JSE was pencilled in at the lower end of that. However, demand is now pointing to it being much higher. That’s a very good reference point because it likely points to management being on the conservative side of sales expectations.
Financial institutions are being encouraged by regulators not to be overly reliant on AWS or Azure as cloud providers. This means that something like the Beeks offering should be well received and will offer a significant moat as it is adopted.
Businesses that have sticky infrastructure type deals with financial institutions tend to be very well rated (PER wise) - ie 20 to 40 * as these clients change provider very infrequently and are high quality credits.
Ultimately it come down to whether you think the exchange cloud is going to continue to take off. If it does then shareholders should do very well as operating leverage kicks in. Resilience is a big thing in regulators rhetoric at the moment and Beeks Financial Cloud (LON:BKS) straddles that narrative as well as providing speed/latency which is why I like them. I know how difficult and long drawn out it is to do those deals though so the fact the JSE is signed and working well should act as a strong reference and likely accelerate other negotiations. It’s an interesting space.
Re SCS (LON:SCS)
I don't think necessarily a 'hack' reflects badly on the IT team in a company, though of course depending on the form of the hack, it can.
The weakest point in an organisation is the human element, and opening an email with a link or a document attached can be the route to allowing types of virus/bugs etc into a system.
Its quite hard to defend against all of these, though with training it can be preventable, but be aware those 'phishing' attempts are getting cleverer, and take many guises to fool individual users.
SCS (LON:SCS) Hi Trident, I assume your comment refers to Volex (LON:VLX) ?
Whoops. You're right, shame I can't blame a hacker for it!
Yes the weakest link is always human: e.g. those C-suite managers that are forever clicking on spear-phishing links despite all the training you give them !
However IT know all that, and they have to plan for it and plan mitigations for it.
In the case of Volex it sounds like they were pretty successful: no operational impact suggests whatever happened was contained, and if they did need to recover any critical systems they were able to do so from immutable / offline backups. Many companies are not so successful.
Re: Volex (LON:VLX)
Another all-too-common problem is companies being hacked - I assume by fraudsters who demand ransoms in bitcoin maybe? Although I’ve heard some IT people say that successful attacks expose poorly managed, insecure IT systems, so it doesn’t reflect well on the company’s IT people.
Surely this is a not unlikely consequence of a company making acquisitions though? I assume very few acquisitions would be turned down based on poor IT security alone if all other financial metrics make it worthwhile. Especially where the acquired companies are in low cost labour countries such as Turkey and Mexico. The main issue here is to detect the hack and limit damage which they seem to have done.
@simoan
You make a valid point; but we don't (yet) know the extent and damage of this hack (beyond loss of face and fall in share price ). Unless it turns out that the compromise has in fact been contained with no ongoing compromise of the parent company I suggest that it might show that insufficient care &/or resources were given to IT.
In the US companies are obliged to make public any hacks (as Volex (LON:VLX) has done) so we will probably see more acknowledged as time goes by. www.sec.gov/news/press-release/2023-139
Hi Paul,
Just a quick note to say that I am really appreciating your weekly podcasts both SCap and Macro. They are a definite compliment to the SCVR.
Not sure I would like to be holding Israeli stocks this morning, such as MTI Wireless Edge (LON:MWE) , a former holding of mine. Dreadful events which are already having repercussions on oil & gas markets.
Energean absolutely hammered.....down nearly 18%. Their off shore infrastructure must be a vulnerable and tempting target for hezbollah, should their Iranian Quartermaster instruct them to start another front. Gas and oil prices are up after a difficult week. We have two sets of family friends in Israel and this is horrific.
Stinker of an update from Mind Gym (LON:MIND)
Liberum cut PBT forecasts from 6.8m (2024) to -2.8m and 7.9m (2025) to 2.0m
Net cash drops from 7.6m to 0.9m
Moved from buy to under review.
Market cap down to only 33m now so getting into punt territory, tho a lot of businesses seem to be showing all the resilience of a jellyfish. If the US enters a recession next year could see more pain.
Morning Wolfie!
Thanks for flagging those massive broker cuts at Mind Gym (LON:MIND) - I'm about to look at that one next.
Regards, Paul.
Fantastic podcasts this weekend Paul. Loved the accent and really love Part 2 - so interesting. You have a real talent for this - thanks!
How kind, thanks stockorocko! I really enjoy creating the podcasts, and as you know, my silliness gene can kick in at any time, without warning!! :-D
Good morning.
I own a shareholding in Severfield (SFR-LON) and emailed the FD following the government’s recent announcement of its intention to severely cut back on the HS2 project. My concern was whether Severfield’s involvement in the scheme would result in the need for write-offs. With the permission of Adam Semple, the FD, to allow his answer to be reproduced, here is my question and his response:
My morning smallcap tweet: holders exercised by Mind Gym warning
Chill Brands (LON:CHLL) Volex (LON:VLX) IQ-AI (LON:IQAI) Batm Advanced Communications (LON:BVC) Graft Polymer (UK) (LON:GPL) Narf Industries (LON:NARF) DX (Group) (LON:DX.) Mind Gym (LON:MIND) Ilika (LON:IKA) Hercules Site Services (LON:HERC) Assura (LON:AGR) Mincon (LON:MCON) SCS (LON:SCS), Sirius Real Estate (LON:SRE)
◄Chill Brands (CHLL)► Chill ZERO products enter an initial 150 of WHSmith's. Total UK retailer orders £350k. [SP=5.15 Cap=15m]
◄Volex (VLX)► certain IT systems and data at some international sites have been hacked. All sites remain operational.Financial impact expected to be minimal. [SP=306.75 Cap=554m]. I hold.
◄IQ-AI (IQAI)► FDA grants orphan status to Gallium Maltolate for treating atypical teratoid rhabdoid tumour. [SP=3.73 Cap=7m]
◄BATM Advanced Communications (BVC)► does not expect attacks in Israel to have a material impact on trading. [SP=25.9 Cap=112m]
◄Graft Polymer (GPL)► agreement within European consortium to explore scope for addressing electromagnetic wave pollution. Co will prepare samples of shielding for testing. The project is due to last until autumn 2025. [SP=1.5 Cap=2m]
◄Narf Industries (NARF)► wins $1.8m US gov't contract to work on the Digital Health Security programme. [SP=0.7 Cap=12m]
◄DX (DX.)► PUSU Deadline extended to 6 Nov. [SP=42.49 Cap=256m]
◄Mind Gym (MIND)► warns FY-Mar rev and profit significantly lower than market expectations despite improvement in market activity reflected in increased bookings for Q3. Blames clients deferring orders. [SP=56.25 Cap=56m]
◄Ilika (IKA)► to get £400k grant to scale-up its Goliath pilot production. [SP=30 Cap=48m]
◄Hercules Site Services (HERC)► get 5 yr contract to provide Balfour Beatty with contingent labour resource. [SP=25.4 Cap=16m]
◄Assura (AGR)► confident trading stmt for H1-Sept. [SP=41.86 Cap=1241m]
◄Mincon (MCON)► guides FY-Dec EBITDA only c. €20m. Q1-3 rev down 7%. Two large scale construction projects in North America expected in Q4 will no longer take place as planned although the larger will commence in 2024. [SP=72 Cap=158m]
◄ScS (SCS)► FY results delayed 2 weeks to 25 Oct. Will be in line. "Apart from the short delay, the year-end process has been as expected and the Board has no concerns whatsoever in this regard." [SP=167 Cap=56m]. I hold.
In line: SRE
Staggering how you manage to process so much information, so quickly! Awesome stuff :-)
It's the dry humour I love.
Metro Bank Holdings (LON:MTRO) shareholders to be heavily diluted and some bondholders set to lose over 40%.
This may well be a rescue deal but stakeholders have suffered pain.
Reputational damage will weigh heavy for some time.
Dog bowls still available in store.
While I am glad that market disruption is saved by the “rescue” of Metro Bank Holdings (LON:MTRO) , I continue to be baffled by what makes Metro think that they can make success of having a large high street presence when every other bank has found that they cannot make the formula work. My local Metro has a large smart facility but, as with the other banks, I only see the most desultory level of traffic.
Maybe some others here can tell me of their reason why Metro is a key and much used part of their life. And would it make any difference to them if it was on a, cheaper, first floor level?
I don’t hold Metro (or any bank - I used to work for one) but there must be a trick here that I am missing.
I have several friends that use Metro Bank Holdings (LON:MTRO)
For personal - they like that they have branches that are convenient, and that they can walk in and get service, and not have to book like 3 weeks in advance. Also it is open the hours they want (ie evenings, weekends). Apparently their call center customer service is also good.
For business - I have friends who run/own SMEs and they say the service is better than other banks, more features/functionality for free or cheap that other banks charge a lot for. Easier to get in-person service. Also easier to get loans.
All this, of course, cost a lot of money.
But the bull case for Metro bank is whether they can pull in loads of new Current Accounts (personal and business) where customers are happy to earn 0% because of the service levels they can't get elsewhere. And therefore, with 0% cost of funding and high interest rates, their Net Interest Margin should be much higher than a traditional high street bank, who now have to compete on current account interest rates, having stripped back service to barebones and offering identikit commoditized current accounts.
You only have to look at the Current Account switching bonuses now on offer (£200+) from the major banks to see that none of them offer current accounts that is a level above commodity, that they have to bribe for switching, because they're churning customers (to other banks that offer switching bonuses).
With all the major high street banks closing down branches at a quick rate, inevitably there will be some customers in those branches that value it, and so is a ripe customer for Metro to poach. Indeed, we have seen in the last few quarters that the new customer growth rate at Metro is pretty healthy, in what is a mature, low-growth market.
Thank you for the response Boon, regarding MTRO. I will cheer from the sidelines as I just don't see enough demand for their street front services, but maybe if they really are the last man standing they can mop up enough to cover what I consider unnecessarily high overheads. Especially if they are the last resort I can see no reason for them to be at street level in a high footfall high street.
I am probably biased against their chances since on a personal basis I don't believe I have been into a bank more than once a year for the last decade.
Morning all,- two potentially negative Monday morning RNS this morning at 7am.
SCS (LON:SCS) preliminary results delayed and Volex (LON:VLX) a cyber security incident. I am Not sure the market will like either of these announcements. Would appreciate comments.
Morning Bristolian, SCS (LON:SCS) say their results are in-line with the trading update issued in August, whilst Volex (LON:VLX) say that the incident will not result in a material financial impact (presumably being the cyber consultants' fee). One can imagine both will be immediately marked-down though on open, so there could be a chance for a top-up on any spike down (I hold both).
Hi StrollingMolby and Bristolian,
Both audit delays and cyber-incidents seem fairly commonplace these days, and don't seem to do lasting damage to share prices, unless some more serious effects emerge.
But as you say, market makers are likely to mark down the prices at the open, just in case.
Regards, Paul.